
- Home
- »
- Medical Imaging
- »
-
Dermatology Imaging Devices Market Size Report 2026-2033GVR Report cover

Dermatology Imaging Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Modality (Digital Photographic Imaging, OCT, Dermatoscope, High Frequency Ultrasound), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$7.5BCAGR, 2026–2033
12.2%Dermatology Imaging Devices Market Summary
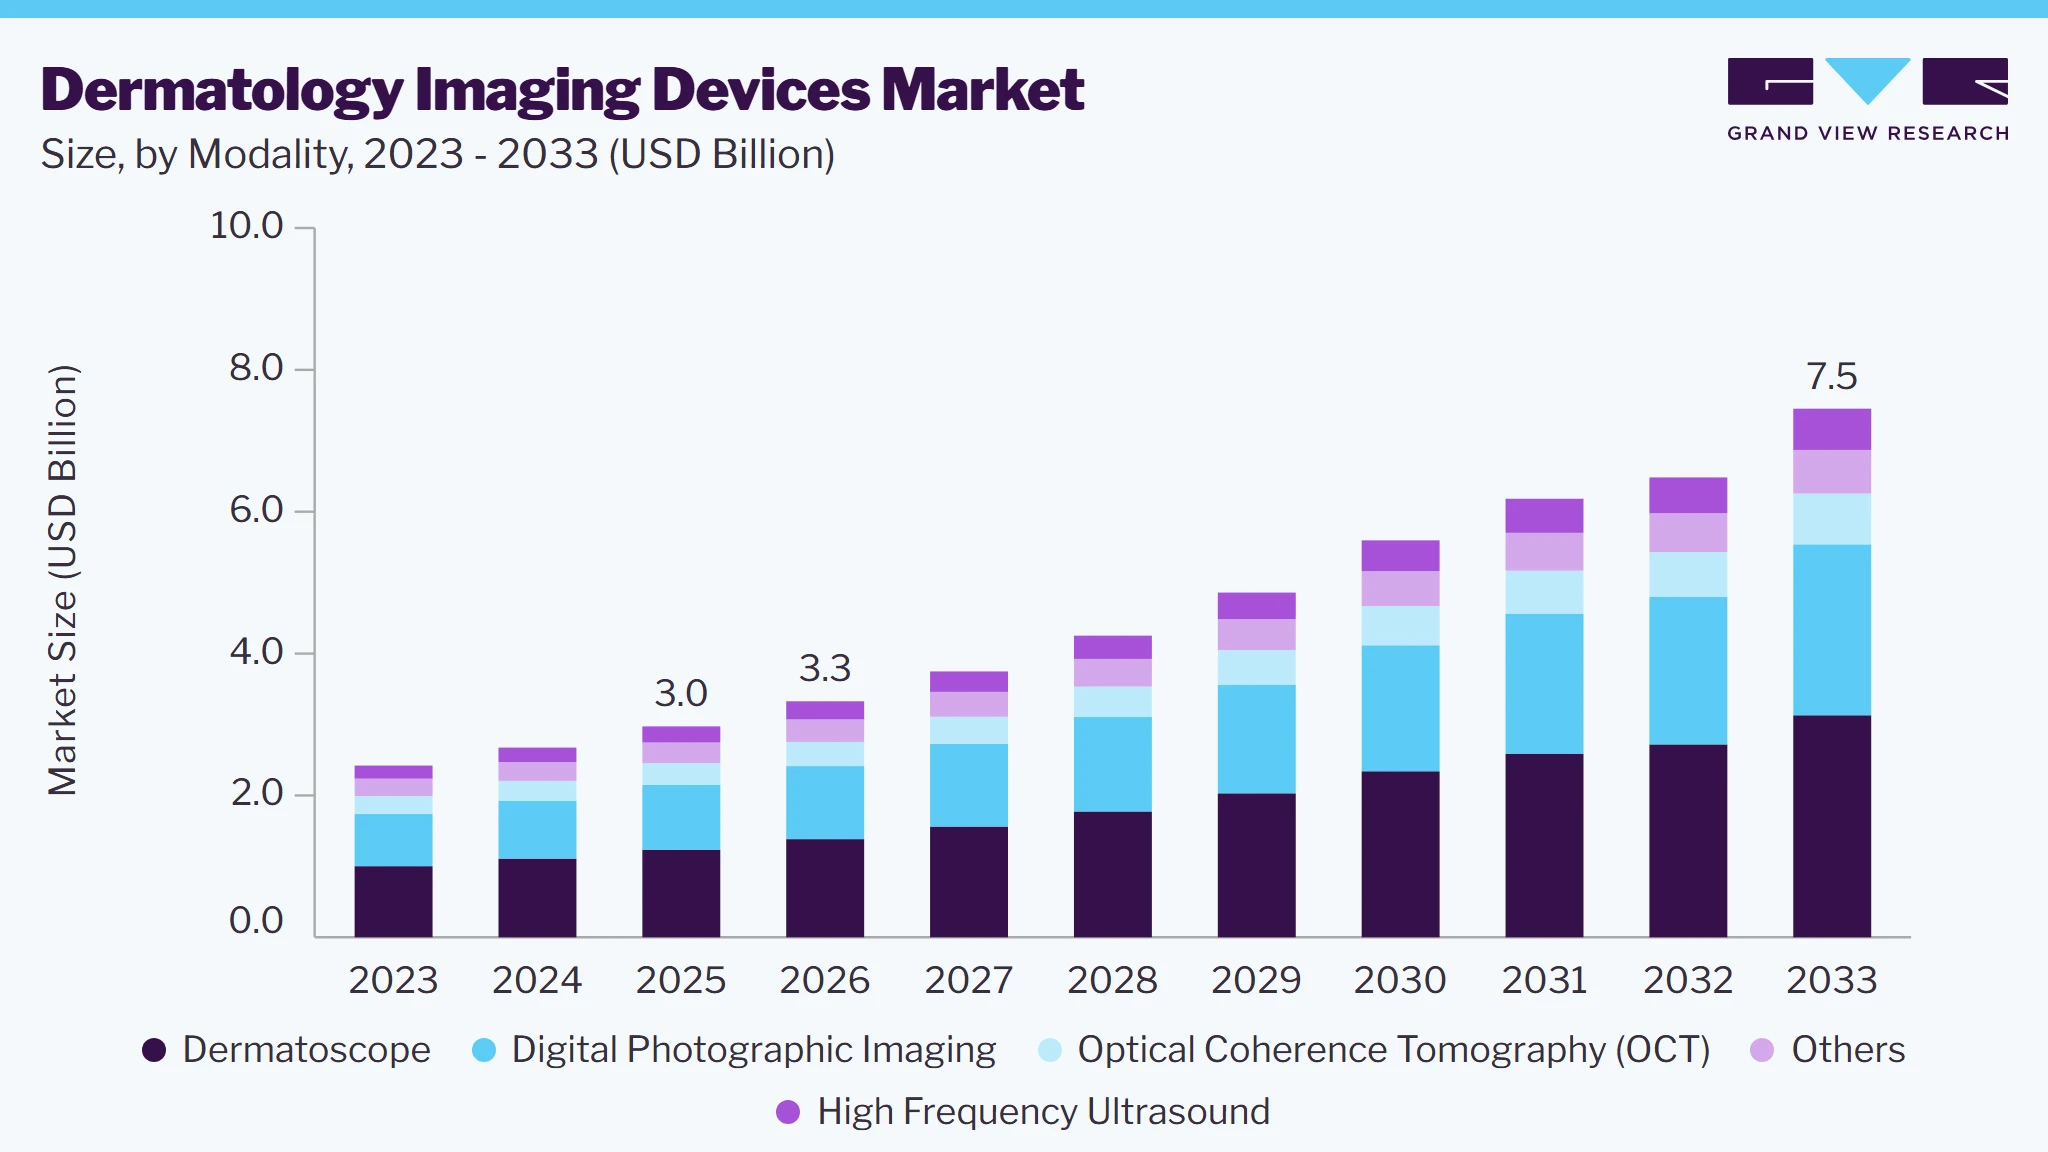
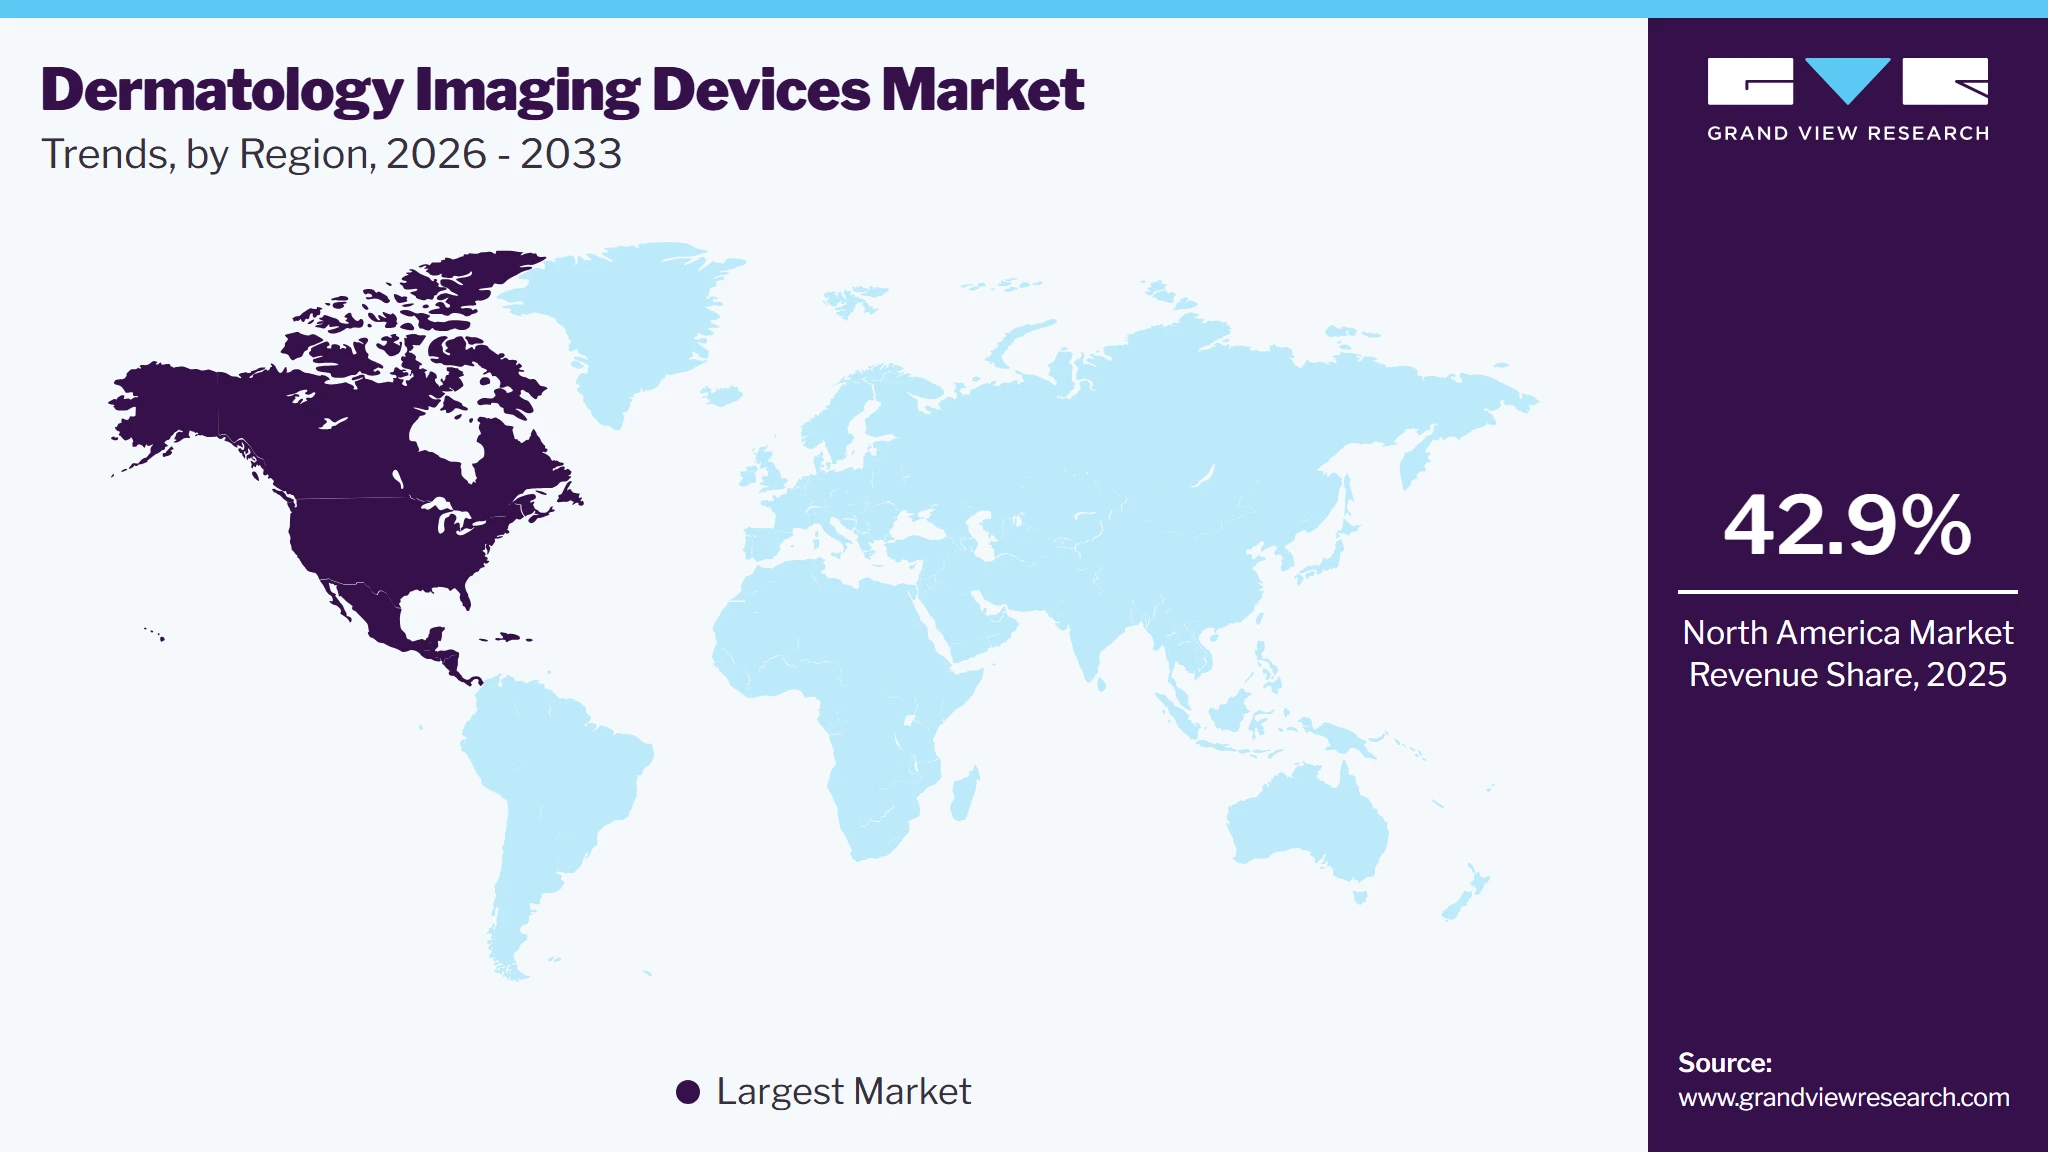
The dermatology imaging devices market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 7.5 billion by 2033, at a CAGR of 12.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.9% in 2025. The growing prevalence of skin disorders, rising awareness about skin cancers, and the growing demand for non-invasive diagnostic procedures are some of the major factors anticipated to boost the market growth over the forecast period.
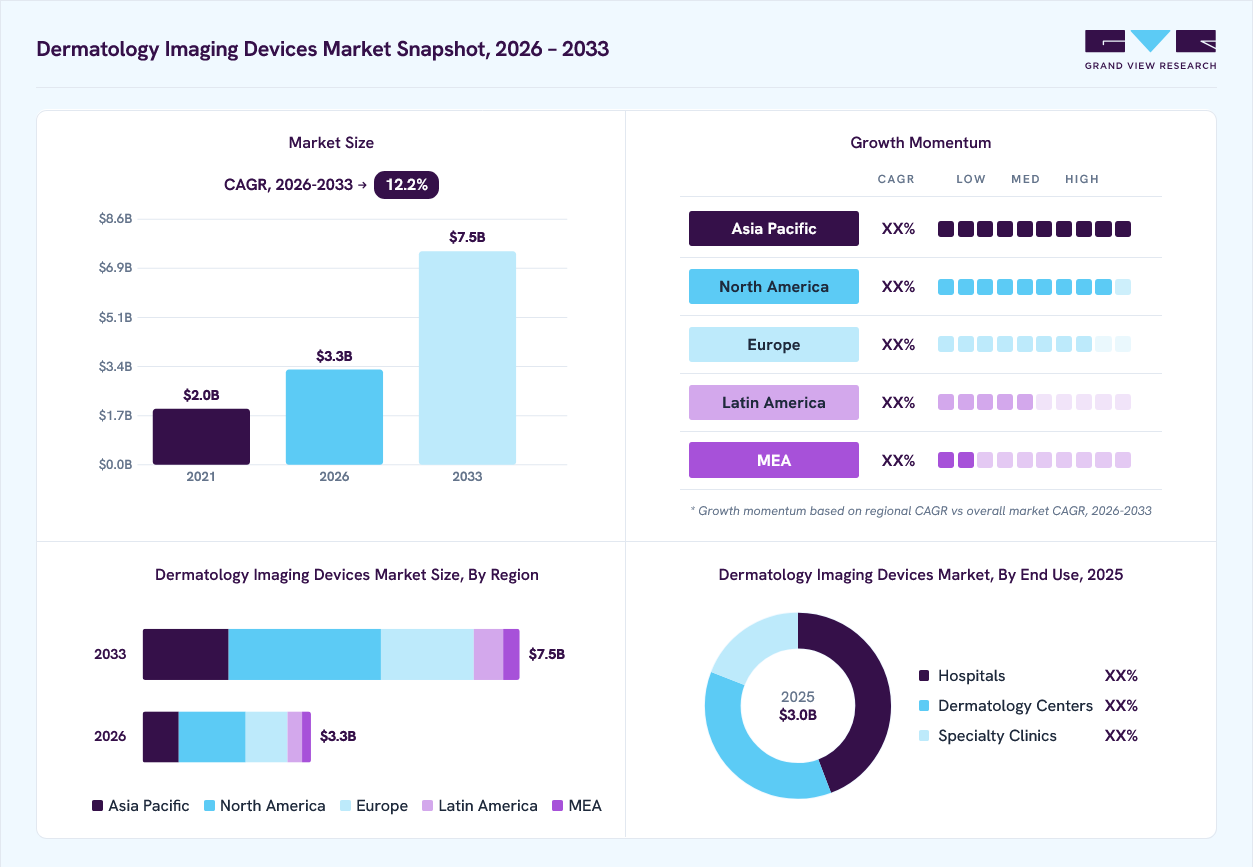 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
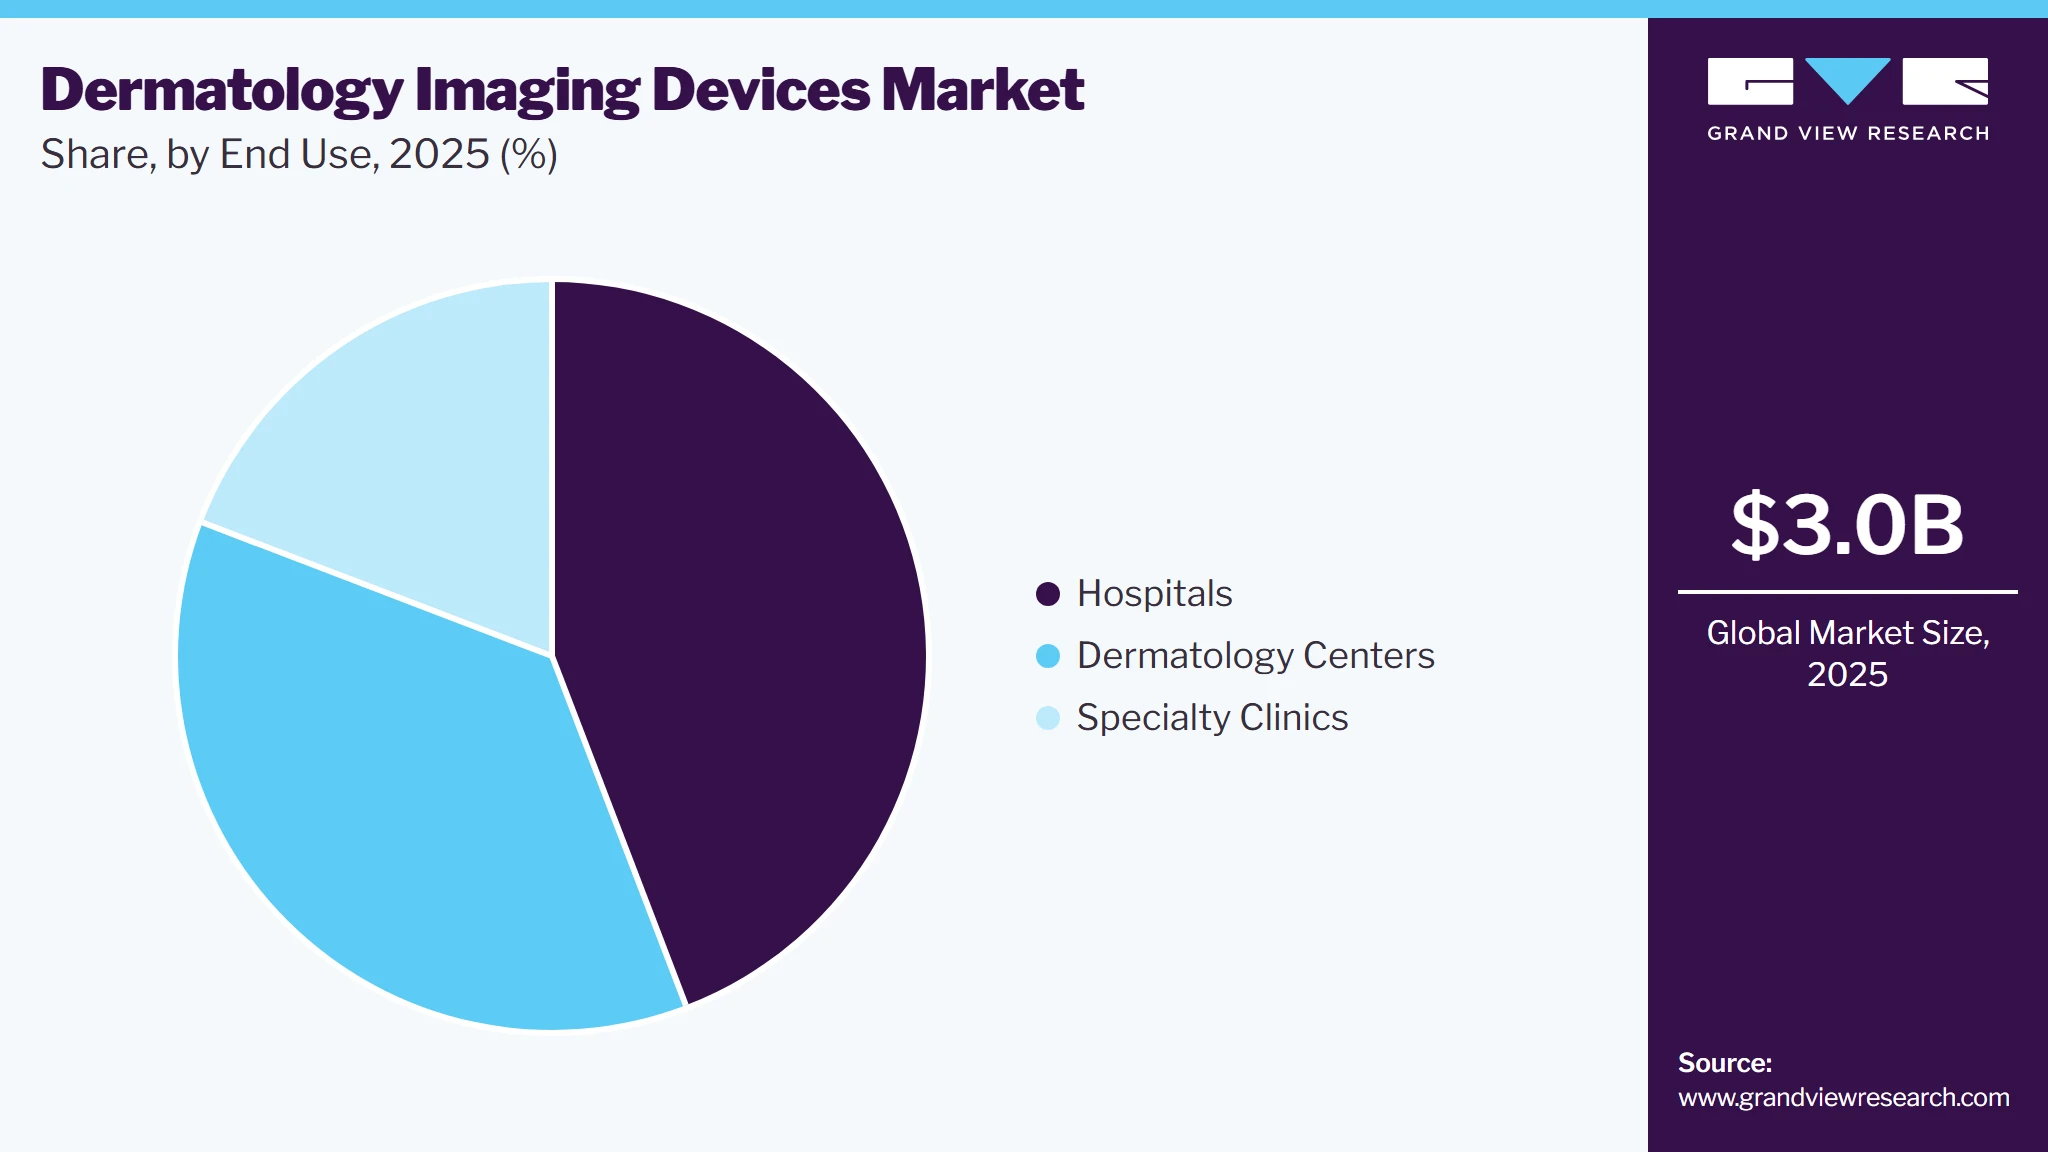
- By end-use: Hospital segment led the market with the largest revenue share of 44.2% in 2025.
- By modality: Dermatoscope segment led the market with the largest revenue share of 41.5% in 2025.
- By application: Skin cancers segment led the market with the largest revenue share of 48.8% in 2025.
Regional Highlights
- Largest regional market: North America (42.9% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 7.5 Billion
- CAGR (2026-2033): 12.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, technological advancements have developed advanced dermatology imaging devices with higher accuracy and faster results. For instance, the introduction of optical coherence tomography (OCT) and confocal microscopy has transformed the diagnosis of skin disorders by providing high-resolution images of skin layers in a non-invasive procedure.The increasing prevalence of skin cancer worldwide has created a strong demand for market in the forecast period. According to the American Academy of Dermatology Association, skin cancer is most prevalent in the U.S.; around 9,500 people get diagnosed with skin cancer daily, and above 1 million are currently suffering from melanoma. As per the estimates, around 197,700 new cases of melanoma will be diagnosed in 2022, among which non-invasive methods diagnose 97,920 and 99,780 are diagnosed by invasive procedures. Skin cancers are predominantly found in women than in men below age 50, but it is significantly higher in men above age 50. It can be attributed to the differences in recreation and work-related UV exposure. According to the estimates, around 1 in 27 men and 1 in 40 women are expected to suffer from melanoma. Melanoma holds only 1% of all the skin cancers found in the U.S., whereas it leads to the highest number of deaths from skin cancer. According to the American Society of Clinical Oncology (ASCO), it is evaluated that around 7,990 deaths, among which 5,420 are men and 2,570 are women from melanoma, will occur in the United States in 2023.
 To learn more about this report, Download Free Sample Report
The field of dermatology has seen significant technological advancements in imaging devices in recent years. Several companies have launched new products that utilize innovative partnerships to improve patient outcomes. These new technologies have allowed for more accurate diagnoses and better treatment options for skin conditions. For instance, In August 2023, BioActor, a Solabia subsidiary, and Pixience, a manufacturer of digital dermatoscope technology, have collaborated to develop a new skin imaging technology to test and validate nutritional bioactives used for skin health. Pixience has developed a skin image-capturing device called C-Cube and image analysis software called QuickScale, which can evaluate various skin health parameters, including 3D image evaluation.
The demand for noninvasive imaging tools for diagnosing and treatment of skin cancers and other skin-related disorders is expected to create lucrative growth opportunities in the forecast period. Patients and physicians prefer noninvasive technologies, as they are less painful, have minor risks, and require less recovery time. According to an article published by Memorial Sloan Kettering Cancer Center, Early detection of skin cancer can be challenging. Traditionally, dermatologists use biopsies to examine skin cancer, but this can be invasive and cause scarring.
However, Memorial Sloan Kettering’s Dermatology Service offers noninvasive approaches to detect, diagnose, and even treat skin cancer. One such approach is reflectance confocal microscopy (RCM), which uses a low-power laser to scan skin lesions. This laser can penetrate slightly below the skin’s surface and collect information about the cellular elements in a lesion. The reflected information is collected in still and video images and sent to expert doctors for examination and diagnosis. Since RCM is noninvasive, doctors can repeatedly reexamine the same area without damaging the tissue. This contrasts with taking multiple biopsies, which can damage the tissue and make it harder to study later.
Market Dynamics
The dermatology imaging devices market is experiencing strong growth, driven by the increasing prevalence of skin disorders, rising incidence of skin cancer, growing demand for early and accurate dermatological diagnosis, and continuous technological advancements in non-invasive skin imaging technologies. The market is further supported by increasing awareness of preventive skin examinations, expanding adoption of digital imaging solutions in dermatology practices, integration of artificial intelligence (AI) into skin lesion analysis, and the growing preference for objective, image-based clinical decision-making across both developed and emerging healthcare markets. Dermatology imaging devices enable hospitals, dermatology clinics, cancer centers, aesthetic clinics, and specialty diagnostic centers to visualize, document, monitor, and assess a wide range of skin conditions using high-resolution, non-invasive imaging technologies. These devices improve diagnostic accuracy, facilitate longitudinal monitoring of lesions, support treatment planning, and enhance teledermatology and digital patient management. Dermatology imaging devices are widely used for the detection, diagnosis, and monitoring of melanoma and non-melanoma skin cancers, atypical pigmented lesions, psoriasis, eczema, atopic dermatitis, rosacea, acne, vitiligo, vascular lesions, fungal skin infections, pigmentary disorders, inflammatory dermatoses, hair and scalp disorders, nail diseases, and other chronic dermatological conditions. The increasing emphasis on early skin cancer detection, AI-assisted image analysis, digital dermoscopy, total body photography, and advanced optical imaging technologies is expected to further accelerate market growth over the forecast period.
The rising global burden of skin disorders and skin cancers is one of the primary factors driving the growth of the dermatology imaging devices market. The increasing incidence of melanoma, basal cell carcinoma, squamous cell carcinoma, psoriasis, eczema, acne, rosacea, vitiligo, and other chronic dermatological conditions has significantly increased the demand for accurate, non-invasive diagnostic technologies that enable early detection and continuous disease monitoring. Early diagnosis is particularly critical for skin cancer, where timely identification of suspicious lesions greatly improves treatment outcomes and survival rates. Consequently, healthcare providers are increasingly adopting advanced dermatology imaging devices, including digital dermatoscopes, total body photography systems, reflectance confocal microscopy (RCM), optical coherence tomography (OCT), and high-frequency ultrasound, to improve diagnostic accuracy while reducing unnecessary biopsies. In addition, growing public awareness of skin health, expanding skin cancer screening programs, increasing exposure to ultraviolet (UV) radiation, aging populations, and improved access to dermatology services are further accelerating the utilization of imaging technologies in both clinical and outpatient settings. The integration of artificial intelligence (AI) with dermatology imaging platforms is also enhancing lesion detection, image interpretation, and longitudinal monitoring, enabling clinicians to make faster and more accurate diagnostic decisions. As the global prevalence of dermatological diseases continues to rise, the demand for advanced imaging solutions is expected to increase steadily, supporting sustained growth of the dermatology imaging devices market.
Limited awareness regarding the clinical benefits and diagnostic value of advanced dermatology imaging technologies remains a significant restraint on the growth of the dermatology imaging devices market. In many developing and underpenetrated healthcare markets, both patients and primary care providers continue to rely predominantly on conventional visual examinations and clinical assessment, resulting in the underutilization of advanced imaging modalities such as digital dermoscopy, total body photography, reflectance confocal microscopy (RCM), optical coherence tomography (OCT), and high-frequency ultrasound. Insufficient knowledge about the ability of these technologies to facilitate early skin cancer detection, improve diagnostic accuracy, monitor disease progression, and reduce unnecessary biopsies limits their adoption in routine dermatological practice. Furthermore, inadequate training among healthcare professionals, limited availability of specialized dermatologists, and a lack of standardized screening programs in several regions contribute to slower implementation of imaging-based diagnostic workflows. Budget constraints in smaller hospitals and dermatology clinics, combined with uncertainty regarding the return on investment for advanced imaging systems, also discourage procurement, particularly in emerging economies. Although increasing educational initiatives, technological advancements, and growing awareness of skin cancer prevention are expected to improve adoption over time, the current lack of awareness and limited understanding of the long-term clinical and economic benefits of dermatology imaging continue to restrain market growth.
Market Concentration & Characteristics
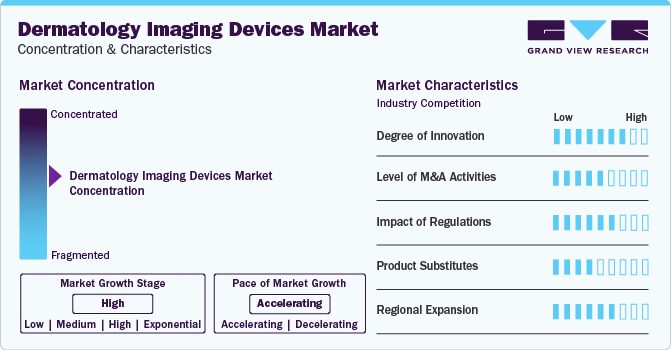
The market growth stage is high, and the pace of the market growth is accelerating. The market has witnessed a high degree of innovation, marked by several instances of regulatory approvals, partnerships, and collaborations. In recent years, the market has seen a surge in the number of new product launches, making it increasingly challenging for market leaders to sustain themselves in the ever-changing market. However, leading players are investing heavily in R&D activities to develop advanced imaging technologies, which is expected to fuel market growth. For instance, Canfield Scientific, Inc. launched VISIA Skin Analysis, a facial imaging device in December 2023. VISIA is an AI-integrated device used to capture high-quality standardized images to analyze the results.
 To learn more about this report, Download Free Sample Report
Technological advancements and product launches drive the market growth. Startups like MetaOptima are leading the way in developing innovative AI-powered solutions for skin cancer detection. MetaOptima's DermEngine platform utilizes AI algorithms to analyze images of skin lesions, enabling dermatologists to accurately diagnose and manage skin cancer cases at an early stage. With the growing demand for early skin cancer detection and other dermatological conditions, these startups are poised to revolutionize the market growth.
The market has been characterized by a high degree of innovation. These devices are designed to aid dermatologists in diagnosing and treating skin conditions more accurately and efficiently. For instance, in June 2023, FotoFinder Systems GmbH, a prominent manufacturer of medical imaging systems for dermatology, unveiled two cutting-edge innovations: the meesma, a portable imaging solution for aesthetics, and the fourth-generation FotoFinder ATBM master, equipped with an AI assistant called AIMEE for Total Body Dermoscopy. These state-of-the-art systems are showcased for the first time to experts at the "25th World Congress of Dermatology" (WCD) in Singapore, scheduled from 3rd to 8th July 2023.
Several market players in the market are engaged in a moderate level of merger and acquisition (M&A) activities. For instance, in July 2022, EMZ Partners, a private equity firm based in Europe, entered into a legal agreement the acquire a majority stake in FotoFinder. GmBH. This acquisition was completed in Q2 2022.
The market is highly impacted by strict regulations. For instance, the U.S. Food and Drug Administration (FDA) has strict regulations regarding the approval of medical devices. For instance, in January 2024, DermaSensor Inc. announced the FDA approval of its DermaSensor, non-invasive skin cancer evaluation system.
Product substitutes have a moderate impact on the global market. For instance, the advancement of telemedicine and teledermatology has led to the development of innovative devices that allow dermatologists to diagnose and treat patients remotely. These substitutes could disrupt the market for traditional dermatology imaging devices. In October 2022, Y Combinator launched Northwind, the Teledermatology platform for Psoriasis and Eczema in the U.S. Northwind offers customized treatments and continuous support from the panel of certified dermatologists
Regional expansion is anticipated to have a moderate-to-high growth impact on the global market. Regional expansion provides market players with an opportunity to tap into previously untapped customer bases. This strategy enables them to strengthen their position in the market and increase their market share. For instance, In Hanoi, Vietnam, the Dr. Hoàng Tuấn Medical Center recently installed the VECTRA WB360 whole-body imaging system by Canfield Scientific, Inc. in January 2024.
Analyst Perspective
The global dermatology imaging devices market is driven by the increasing prevalence of skin cancer and chronic skin disorders, along with growing demand for early, accurate, and non-invasive diagnosis. Rising awareness of preventive skin screening, expanding dermatology services, and advancements in imaging technologies are accelerating market growth. The increasing adoption of digital dermatoscopes, total body imaging systems, reflectance confocal microscopy (RCM), optical coherence tomography (OCT), high-frequency ultrasound, and multispectral imaging devices is enabling improved lesion assessment, enhanced diagnostic accuracy, and better clinical decision-making while reducing unnecessary biopsies.
End-use Insights
Based on end use, the hospital segment led the market with the largest revenue share of 44.2% in 2025. Dermatology imaging devices are extensively used in hospitals due to the availability of specialized equipment and trained professionals. The availability of advanced technology and skilled professionals in hospitals ensures accurate diagnosis and effective treatment of skin disorders. Patients diagnosed with cancer are more likely to visit hospitals for advanced diagnosis and treatment. Also, the easy availability of specialized doctors in hospitals aids in convenient cancer diagnosis and treatment.
 To learn more about this report, Download Free Sample Report
The dermatology centers segment is expected to grow at the fastest CAGR during the forecast period. Dermatology centers have become increasingly popular among patients seeking treatment for skin-related issues. Patients often prefer going to these centers rather than hospitals for reasons such as the specialized care they offer. Since dermatologists focus solely on skin-related issues, they have greater expertise in this field. This often translates into better diagnoses and treatment options for patients. Another reason is the convenience. These centers are often located in easily accessible areas, and patients can typically get an appointment quickly. Furthermore, dermatology clinics are often equipped with state-of-the-art imaging equipment, enabling more accurate diagnoses and treatment plans.
Modality Insights
By modality, the dermatoscope segment led the market, accounting for the largest revenue share of 41.5% in 2025. Dermatoscopes are specialized tools used in dermatology to examine the skin and detect any anomalies or changes in growth patterns. These devices are designed to magnify the skin surface in order to provide a more detailed examination. Their non-invasive, painless examinations, accuracy in diagnosing skin conditions, and ease of use for re-examining skin lesions over time have contributed to their popularity among physicians. Dermatoscopes are also used to detect skin cancer and other skin diseases at an early stage. Additional features such as polarized and non-polarized lighting options, adjustable magnification levels, and the ability to capture images for further analysis are expected to remain dominant in the forecast period.
The digital photographic imaging segment is expected to witness the fastest CAGR during the forecast period. Digital photographic imaging uses digital cameras to capture and store images electronically. Digital photographic imaging has become essential for diagnosing and monitoring skin conditions in the global market. Dermatology imaging devices use high-resolution digital cameras to capture images of the skin, allowing dermatologists to identify and track changes in the skin over time. Some available products in this market include MoleScope, FotoFinder, and Canfield VISIA. Additionally, the development of total-body photographic imaging systems for capturing high-resolution images of the entire body is expected to fuel market growth during the forecast period. For instance, VECTRA WB360, IntelliStudio, and DermaGraphix are the total body photography systems developed by Canfield Scientific, Inc. The DermaGraphix body mapping solution is designed to provide dermatologists with a comprehensive view of a patient's skin condition by capturing high-resolution images of the entire body. The system uses advanced software to analyze the images and create a detailed map of the patient's skin, allowing dermatologists to identify and track changes over time. It offers a range of features, including measurement tools, guided imaging, and image comparison, which make it an indispensable tool in the diagnosis and monitoring of skin conditions.
Application Insights
Based on application, the skin cancers segment led the market with the largest revenue share of 48.8% in 2025, owing to the higher prevalence of skin cancers across the globe. In 2022, the Global Cancer Observatory recorded approximately 331,722 new cases of Melanoma worldwide, accounting for 3.2% of all cancer cases. Out of these cases, 58,667 people lost their lives due to Melanoma. Dermatology imaging devices help diagnose and treat skin cancers at an early stage. For instance, the MoleMax HD system, developed by Derma Medical Systems, uses digital dermoscopy to capture high-resolution images of the skin, enabling dermatologists to detect early signs of skin cancer. Additionally, the Vivascope 1500 by Caliber Imaging and Diagnosis uses confocal microscopy to capture cellular-level images of the skin, allowing dermatologists to identify abnormal cells that may indicate skin cancer.
The plastic and reconstructive surgery segment is expected to grow at the fastest CAGR during the forecast period. Plastic and reconstructive surgeries are growing rapidly owing to the rising prevalence of minimally invasive surgical procedures and technological advancements in devices and techniques. Thus, growth in cosmetic surgeries leads to an increased need for accurate imaging to achieve optimal results. Availability of products specific to plastic and reconstructive surgeries is expected to fuel the market in the forecast period. For instance, the VISIA Complexion Analysis System by Canfield Scientific, Inc. uses multispectral imaging to provide a comprehensive view of the skin, and the Canfield Vectra 3D imaging system creates a 3D model of the face or body to aid in treatment planning.
Regional Insights
North America dominated the dermatology imaging devices market with the largest revenue share of 42.9% in 2025, owing to factors such as rising prevalence of skin conditions and skin cancer in the region, rising awareness of early disease detection and treatment, and the availability of advanced technologies and imaging modalities that make it easier for dermatologists to diagnose and treat skin disorders. This has further boosted the demand for market in North America.
 To learn more about this report, Download Free Sample Report
U.S. Dermatology Imaging Devices Market Trends
The dermatology imaging devices market in the U.S. held the largest share in the North America region in 2025, owing to the presence of major market players such as Canfield Scientific, Inc., e-con Systems Inc., Longport, Inc., GE HealthCare, and Caliber Imaging and Diagnosis. Moreover, the increasing number of healthcare facilities and hospitals in the U.S. has also played a vital role in the market growth. The easy availability of specialized doctors and medical professionals has led to better diagnosis and treatment of skin diseases, driving the demand for dermatology imaging devices.
Europe Dermatology Imaging Devices Market
The dermatology imaging devices market in Europe is expected to grow at a lucrative CAGR during the forecast period, driven by the increasing prevalence of skin diseases, rising awareness of skin cancer, and the growing demand for minimally invasive procedures. According to the Global Cancer Observatory, 146,321 new cancer cases were reported in the European region in 2022, out of which 26,180 deaths were recorded. The five-year prevalence of melanoma is 571,712 cases. Thus, the aforementioned statistics suggest that the European market is anticipated to boom in the forecast period.
The UK dermatology imaging devices market is characterized by a robust dermatology infrastructure, with many NHS hospitals and clinics providing skin care services. According to the British Association of Dermatologists, there were approximately 626 consultant dermatologists in the UK as of 2021, followed by 250 specialists. The National Institute for Health and Care Excellence (NICE) provides guidelines for diagnosing and treating various skin conditions, which helps ensure that patients receive high-quality care. Private dermatology services are also available nationwide for those who prefer to receive care outside of the NHS.
The dermatology imaging devices market in Germany has captured the dominant position in the European market owing to robust healthcare infrastructure, increased spending on the healthcare, and rising prevalence of skin conditions. According to recent data published by the OECD, Germany had the highest healthcare expenditure among all EU countries in 2021, with an average of EUR 5,159 per person. Public funding for healthcare was also higher than the EU average, accounting for 85.5% of the total funding. Furthermore, out-of-pocket payments were relatively lower in Germany, which accounted for only 12% of the total healthcare expenditure, whereas it was 15% in the EU on average.
The France dermatology imaging devices market is anticipated to grow at the fastest CAGR during the forecast period, owing to the rising prevalence of skin conditions and skin cancers. According to estimates from the Global Cancer Observatory, more than 483,568 new cases of cancer were marked in 2022 in France, out of which 15,729 cases were melanoma. The five-year prevalence rate is 61,520 melanoma cases.
Asia Pacific Dermatology Imaging Devices Market
The dermatology imaging devices market of Asia Pacific is expected to grow at the fastest CAGR of 14.1% from 2026 to 2033. The driving factors include the rising prevalence of skin diseases, increasing awareness about skincare, and technological advancements in dermatology imaging. In addition, the increasing disposable income of people in the Asia Pacific region is expected to increase the demand for dermatology imaging devices. The rise of medical tourism in countries such as India, Singapore, and Thailand is also expected to contribute to the market growth of the Asia Pacific region.
The China dermatology imaging devices market is driven by technological advancements and the expansion of healthcare infrastructure. Technological advancements have led to more advanced imaging devices with greater accuracy and resolution, while rising healthcare expenditure has enabled more patients to access dermatology services. In addition, the country's growing middle class and rising awareness of the importance of skin health have driven a surge in demand for dermatology services.
The dermatology imaging devices market in Japan is growing at the fastest CAGR during the forecast period. This growth can be attributed to factors such as an aging population, the increasing prevalence of skin diseases, and technological advancements. In addition, rising demand for non-invasive diagnostic procedures, growing awareness about skin cancer, and increasing adoption of digital imaging technologies. In addition, the Japanese government's supportive policies for healthcare and the increasing number of dermatology clinics and hospitals in the country are also contributing to the market growth.
Latin America Dermatology Imaging Devices Market
The dermatology imaging devices market in Latin America is an emerging market and is anticipated to grow at a significant CAGR during the forecast period, owing to factors such as the growing prevalence of skin diseases, increasing awareness of early diagnosis and treatment, and the rising demand for non-invasive procedures.
The Brazilian dermatology imaging devices market is the largest, as the country has a large patient pool with various skin diseases, leading to increased demand for advanced diagnostic tools.
The dermatology imaging devices market in Mexico is expected to grow at a steady CAGR during the forecast period, driven by the Mexican government's initiatives to expand access to healthcare services, which has increased demand for dermatology imaging devices.
The dermatology imaging devices market in Argentina is developing due to a high incidence of skin cancer, which has increased demand for advanced diagnostic tools. Additionally, the growing economy and increasing healthcare expenditure are expected to contribute to the market growth in Argentina.
Middle East & Africa Dermatology Imaging Devices Market
The dermatology imaging devices market in the Middle East & Africa is growing steadily and is driven by various factors, including government investments in the healthcare sector. In recent years, many countries in the Middle East & Africa have increased their healthcare budgets, increasing the demand for advanced medical devices and technologies, including dermatology imaging devices. Moreover, emerging players in the Middle East & Africa compete globally by introducing innovative, cost-effective products.
The UAE dermatology imaging devices market has witnessed a surge in the demand for dermatology imaging devices owing to the high prevalence of skin cancer and other skin diseases. The country is also home to several hospitals and clinics that offer advanced dermatological treatments and services, which has further boosted the market growth.
The dermatology imaging devices market of Saudi Arabia and South Africa has also seen significant CAGR over the forecast period in the market due to the increasing awareness about skin health and the availability of advanced medical facilities.
The Kuwait dermatology imaging devices market, on the other hand, is smaller. Still, there is a high demand for dermatology imaging devices due to the high incidence of skin cancer.
Key Dermatology Imaging Devices Company Insights
The major market players operating in the global market include GE HealthCare, VisualSonics, Koninklijke Philips N.V., Canfield Scientific, Inc., FotoFinder Systems GmbH, e-con Systems Inc., and others. These players are focusing on enhancing their product offerings through upgrades, strategic collaborations, and M&A activities. Additionally, the emerging players operating in the market include Metaoptima, DermaSensor, Courage+Khazaka electronic GmbH, Longport, Inc., Cortex Technology, DRAMIŃSKI S. A., Clarius, Michelson Diagnostics Ltd (MDL), Caliber Imaging and Diagnosis, DermLite, and others.
Key Dermatology Imaging Devices Companies:
The following key companies have been profiled for this study on the dermatology imaging devices market.
- Canfield Scientific, Inc.
- FotoFinder Systems GmbH
- e-con Systems Inc.
- Courage+Khazaka electronic GmbH
- Longport, Inc.
- Cortex Technology
- DRAMIŃSKI S. A.
- GE HealthCare
- VisualSonics
- Clarius
- Koninklijke Philips N.V.
- Michelson Diagnostics Ltd (MDL)
- Caliber Imaging and Diagnosis
- DermLite
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Canfield Scientific, Inc., FotoFinder Systems GmbH, e-con Systems Inc., Courage+Khazaka electronic GmbH)
- Focus on expanding AI-enabled dermatology imaging platforms, digital dermoscopy systems, and total body photography solutions for early skin cancer detection.
- Strengthen product portfolios through continuous software upgrades, regulatory approvals, strategic acquisitions, and partnerships with hospitals, dermatology clinics, and teledermatology providers.
- Strong global brand recognition, extensive distribution networks, and established relationships with dermatologists and healthcare institutions support market leadership.
- Broad product portfolios combining dermoscopy, multispectral imaging, AI-assisted lesion analysis, and digital imaging provide comprehensive diagnostic solutions.
- High R&D and product development costs, coupled with stringent FDA, CE MDR, and other regulatory requirements, increase commercialization timelines.
- Premium pricing limits adoption among small clinics and healthcare facilities in price-sensitive markets.
Emerging Players (Michelson Diagnostics Ltd (MDL), Caliber Imaging and Diagnosis, DermLite)
- Focus on AI-powered skin lesion assessment, smartphone-compatible imaging solutions, cloud-based dermatology platforms, and affordable digital dermoscopy devices.
- Prioritize innovation through AI algorithms, machine learning, teledermatology integration, and strategic collaborations with research institutes and digital health companies.
- Faster innovation cycles enable rapid introduction of AI-driven diagnostic features and software enhancements.
- Flexible product development and digital-first business models facilitate quicker adaptation to evolving clinical needs.
- Limited financial resources, smaller sales and distribution networks, and lower brand recognition restrict market penetration.
- Clinical validation, regulatory approvals, and reimbursement challenges can delay commercialization and customer adoption.
Recent Developments
-
In June 2026, FotoFinder expanded its European presence by bringing Vienne Medical, its long-standing distribution partner in France, into the FotoFinder Group. The development strengthened FotoFinder's local market presence and distribution capabilities for its dermatology imaging portfolio, including digital dermoscopy and automated total-body skin mapping systems.
-
In March 2026, Canfield Scientific launched the next-generation VISIA Facial Skin Analysis system, integrating 2D and 3D imaging capabilities with AI-driven skin analysis. The platform combines Canfield's VECTRA 3D imaging technology with VISIA's established facial analysis capabilities, strengthening standardized skin assessment, treatment planning, and patient consultation workflows.
-
In February 2024, the European Society of Radiology (ESR) and GE HealthCare announced their continued partnership for the upcoming European Congress of Radiology (ECR), scheduled from February 28 to March 3 in Vienna. The congress will focus on the theme of "Next Generation Radiology”
-
In January 2024, GE HealthCare announced its acquisition of MIM Software, a leading provider of AI-based solutions for medical imaging analysis. MIM Software offers innovative solutions for radiation oncology, molecular radiotherapy, diagnostic imaging, and urology across various healthcare settings. GE HealthCare aims to use MIM Software's advanced imaging analytics and digital workflow capabilities to drive innovation and enhance patient care in different care areas across the globe.
Dermatology Imaging Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.3 billion
Projected market size by 2030
USD 7.5 billion
Growth rate
CAGR of 12.2% from 2026 to 2033
Base year
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2024 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Modality, application, end-use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; China; Japan; India; Australia; Thailand; South Korea; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Canfield Scientific, Inc.; FotoFinder Systems GmbH; e-con Systems Inc.; Courage+Khazaka electronic GmbH; Longport, Inc.; Cortex Technology; DRAMIŃSKI S. A.; GE HealthCare; VisualSonics; Clarius; Koninklijke Philips N.V.; Michelson Diagnostics Ltd (MDL); Caliber Imaging and Diagnosis; and DermLite
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional, and segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dermatology Imaging Devices Market Report Segmentation
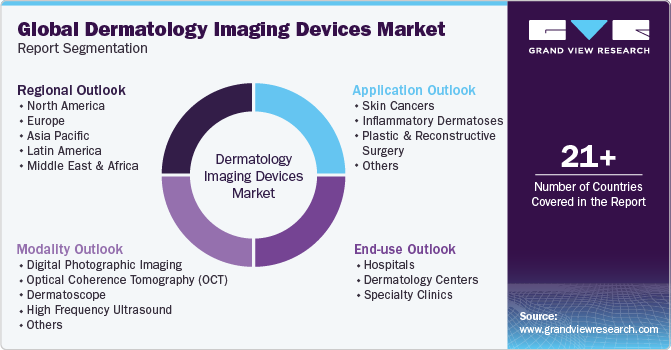
This report forecasts revenue growth at global, regional, & country levels as well as provides an analysis on the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dermatology imaging devices market report on the basis of modality, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Modality Outlook (Revenue, USD Million, 2021- 2033)
-
Digital Photographic Imaging
-
Optical Coherence Tomography (OCT)
-
Dermatoscope
-
High Frequency Ultrasound
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021- 2033)
-
Skin Cancers
-
Inflammatory Dermatoses
-
Skin psoriasis
-
Eczema (Atopic dermatitis)
-
Others
-
-
Plastic and Reconstructive Surgery
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021- 2033)
-
Hospitals
-
Dermatology Centers
-
Specialty Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021- 2033)
-
North America
-
U.S.
- Canada
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dermatology imaging devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dermatology imaging devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Modality
Revenue capture definition
Digital Photographic Imaging
Revenue is generated through the procurement of capital for high-resolution, medical-grade clinical camera systems, specialized total-body mapping rigs, and automated 2D/3D skin imaging workstations. Manufacturers derive upfront income from hardware installation and specialized lighting peripherals, which are consistently supplemented by multi-year software-as-a-service (SaaS) subscriptions for integrated AI lesion tracking, cross-polarized imaging software, cloud-based data storage, and electronic medical record (EMR) integrations.
Optical Coherence Tomography (OCT)
Revenue flows from the commercialization of premium, non-invasive optical imaging systems that deliver real-time, cross-sectional micro-structural views of skin layers at cellular resolution. Market participants capture substantial upfront capital revenue from these advanced diagnostic consoles, along with high-margin recurring income from single-use or modular handpiece optical windows, calibration kits, and specialized premium software licenses tailored for non-invasive optical skin biopsies.
Dermatoscope
Revenue is captured through the high-volume distribution of portable, handheld diagnostic optical tools utilized by clinicians for magnified skin surface inspections. Device manufacturers generate steady income through direct sales of pocket dermatoscopes, as well as recurring revenue from interchangeable contact plates, charging docks, smartphone/tablet mounting adapters, and single-use protective sanitary lens caps.
High Frequency Ultrasound
Revenue is derived from the sale of high-resolution, skin-optimized ultrasound systems engineered to map tumor margins, skin thickness, and subcutaneous structural layers. Income is driven by the upfront capital purchase of the main control console, paired with steady aftermarket sales of specialized high-frequency transducers/probes, software upgrades for multi-modal tissue elastography, and recurring consumption of conductive acoustic gels.
Others
Revenue encompasses alternative and emerging cutaneous imaging technologies, including confocal laser scanning microscopy (CLSM), hyperspectral imaging tools, multispectral lesion analyzers, and custom software maintenance extensions or legacy trade-in hardware upgrade packages.
Segment - Application
Revenue capture definition
Skin Cancers
Revenue is generated by positioning advanced diagnostic and mapping modalities for the early detection, documentation, and border monitoring of malignant lesions, including melanoma, basal cell carcinoma, and squamous cell carcinoma. Device suppliers capitalize on high-volume diagnostic activities, driving recurring software usage fees, total-body photography updates, and high-precision margins for tools that eliminate unnecessary physical skin biopsies.
Inflammatory Dermatoses
Revenue flows from the deployment of high-resolution tracking and imaging platforms to objectively grade, document, and monitor the progression or treatment response of chronic skin diseases.
Plastic and Reconstructive Surgery
Revenue is derived from high-end 3D surface imaging platforms and skin elasticity mapping tools utilized for pre-operative volumetric planning and post-operative outcome simulation. Medtech developers command premium pricing models in this segment by offering advanced structural morphing software, vascular perfusion imaging add-ons, and volumetric analysis tools that directly enhance patient consultation conversion rates and surgical precision.
Others
Revenue includes secondary clinical and cosmetic applications, such as tracking cosmetic treatment efficacy, wound-healing progression, and trichoscopy, as well as academic dermatological clinical research protocols.
Segment - End Use
Revenue capture definition
Hospital
Revenue is generated through large-scale capital budget allocations, multi-site institutional tenders, and long-term group purchasing organization (GPO) supply networks. Device manufacturers secure high-value bulk sales of comprehensive imaging packages, multi-room total body mapping suites, and institution-wide enterprise software licensing agreements, backed by robust multi-year technical maintenance and service SLA contracts.
Dermatology Centers
Revenue flows through targeted professional sales structures supplying dedicated, mid- to large-scale dermatological practices. Income is anchored on a balanced mix of mid-tier capital imaging hardware, combined with predictable, recurring revenue from software-as-a-service (SaaS) clinical licenses and modular device accessories.
Specialty Clinics
Revenue is captured through nimble aesthetic, cosmetic, and multi-specialty private clinics via competitive device leasing options, direct-to-physician sales, and independent provider buying groups. Hardware providers maximize value in this space by deploying space-saving, highly versatile, and mobile diagnostic systems, predominantly handheld dermatoscopes and smart camera attachments, that optimize patient room turnaround times and support fast, point-of-care private consultations.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What constitutes the Dermatology Imaging Devices Market?
Define the product scope by including imaging devices.
Segment the market by modality, application, and end user.
Define end user categories.
Establish geographic scope and align on base year & forecast horizon (2020-2030).
FDA, EMA, research publications, regulatory agencies, industry publications
Build the Product Base
What is the total addressable demand for dermatology imaging devices?
Estimate the global patient pool suffering from skin cancer, psoriasis, acne, eczema, melanoma, and other dermatological disorders.
Analyze the installed base of hospitals, dermatology centers, and specialty clinics.
Assess dermatologists, skin cancer specialists, and other end users. Evaluate procurement patterns, replacement rates, and imaging device adoption trends.
ECRI reports, distributor sales data, dermatology clinic surveys, beauty industry reports
Estimate Penetration
What is the current and future adoption rate of dermatology imaging technologies?
Evaluate penetration of imaging technologies across hospitals, dermatology clinics, beauty centers, and diagnostic laboratories.
Assess adoption by imaging modality and AI-enabled imaging platforms.
Analyze technology diffusion across developed and emerging healthcare markets.
Evaluate clinical application adoption, including skin cancer detection, mole mapping, and lesion detection programs.
Clinical trials, dermatologists, aesthetic physicians, skin professionals, beauty retailers
Revenue Conversion
How is the market value calculated and validated?
Collect average selling prices (ASP) for each imaging modality across major regions.
Estimate annual unit shipments based on installed base, replacement rate, and new installations.
Calculate market revenues by modality, application, end user, and region.
Cross-check market estimates with company financials and industry sales reports.
Sales statements, investor presentations, company annual reports, government export databases, industry reports
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Porters Analysis
Conducted a comprehensive Porter’s Five Forces assessment of the global dermatology imaging devices market to evaluate the competitive intensity and long-term attractiveness of the industry. The study analyzed the bargaining power of suppliers of imaging components, optical sensors, AI software, and diagnostic platforms, as well as the bargaining power of dermatology clinics, hospitals, specialty diagnostic centers, and aesthetic practices. It further assessed the threat of new entrants considering regulatory approvals, technology development costs, intellectual property barriers, and clinical validation requirements. The analysis examined competition from substitute diagnostic approaches such as conventional visual skin examinations, histopathology, and emerging AI-assisted diagnostic solutions while evaluating competitive rivalry among manufacturers based on product innovation, pricing strategies, distribution networks, regulatory compliance, technological differentiation, strategic collaborations, mergers & acquisitions, and global market expansion initiatives.
Enables stakeholders to understand the competitive structure and profitability potential of the dermatology imaging devices market. The assessment supports strategic decision-making by identifying market entry barriers, competitive threats, supplier and customer influence, and technology-driven competitive advantages. It also helps manufacturers formulate pricing and distribution partnerships, identify investment opportunities, and develop sustainable long-term strategies across medical dermatology and aesthetic imaging applications.
Modality Analysis
Conducted a detailed modality assessment of the global dermatology imaging devices market by evaluating key imaging technologies including dermatoscopes, digital dermatoscopes, confocal microscopes, optical coherence tomography (OCT), high-frequency ultrasound, and hyperspectral imaging systems. The study analyzed the adoption trends, clinical advantages, diagnostic accuracy, and cost-effectiveness of each modality across dermatological applications, including skin cancer detection, lesion monitoring, and aesthetic evaluation. The analysis also examined technological advancements, including AI integration, image enhancement algorithms, and compatibility with teledermatology.
Enables stakeholders to identify the most commercially promising imaging modalities and understand their adoption trends across dermatology clinics, hospitals, and aesthetic centers. The assessment supports product development strategies, technology investment decisions, and clinical validation planning. It also helps manufacturers and investors prioritize high-growth modalities and align R&D efforts with emerging diagnostic technologies.
Geographic Analysis
Conducted a regional analysis of the global dermatology imaging devices market covering North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The study evaluated regional market size, growth potential, regulatory frameworks, reimbursement policies, and competitive landscape. It analyzed country-level adoption rates of dermatology imaging technologies, presence of key manufacturers, and distribution networks. The analysis also assessed macroeconomic factors, healthcare infrastructure, and technological readiness influencing market penetration.
Enables stakeholders to identify high-growth regions and understand geographic variations in market dynamics. The assessment supports regional expansion strategies, partnership development, and resource allocation planning. It also helps manufacturers and investors prioritize target markets, optimize distribution networks, and align product positioning with regional demand patterns.
Frequently Asked Questions About This Report
Some key players operating in the dermatology imaging devices market include Canfield Scientific, Inc., FotoFinder Systems GmbH, e-con Systems Inc., Courage+Khazaka electronic GmbH, Longport, Inc., Cortex Technology, DRAMIŃSKI S. A., GE HealthCare, VisualSonics, Clarius, Koninklijke Philips N.V., Michelson Diagnostics Ltd (MDL), Caliber Imaging and Diagnosis., and DermLite
Key factors that are driving the dermatology imaging devices growth include growing prevalence of skin disorders, rising awareness about skin cancers, and the growing demand for non-invasive diagnostic procedures.
North America dominated the dermatology imaging devices market with a share of 42.9% in 2025. This is attributable to rising awareness of early disease detection and treatment, availability of advanced technologies and imaging modalities that makes easier for dermatologists to diagnose and treat skin disorders.
Based on modality, the dermatoscope segment led the market with the largest revenue share of 41.5% in 2025.
Based on application, the skin cancers segment led the market with the largest revenue share of 48.8% in 2025.
The global dermatology imaging devices market size was estimated at USD 3.0 billion in 2025 and is expected to reach USD 3.3 billion in 2026.
The global dermatology imaging devices market is expected to grow at a compound annual growth rate of 12.2% from 2026 to 2033 to reach USD 7.5 billion by 2033.
Based on end-use, hospital segment led the market with the largest revenue share of 44.2% in 2025.
About the Author(s)
Medical Imaging Research Team
Healthcare · Medical ImagingThis report was authored by the medical imaging research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical imaging segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


