
- Home
- »
- Plastics, Polymers & Resins
- »
-
Dicyclopentadiene Market Size, Share & Trends Report 2033GVR Report cover

Dicyclopentadiene Market (2026 - 2033)
Size, Share & Trends Analysis Report By Grade (Polyester / UPR Grade, High Purity Grade), By Application (Unsaturated Polyester Resin, Hydrocarbon Resins), By End-use (Automotive, Marine, Packaging), By Region, And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.3BMarket Forecast, 2033
$1.8BCAGR, 2026–2033
5.2%Dicyclopentadiene Market Summary
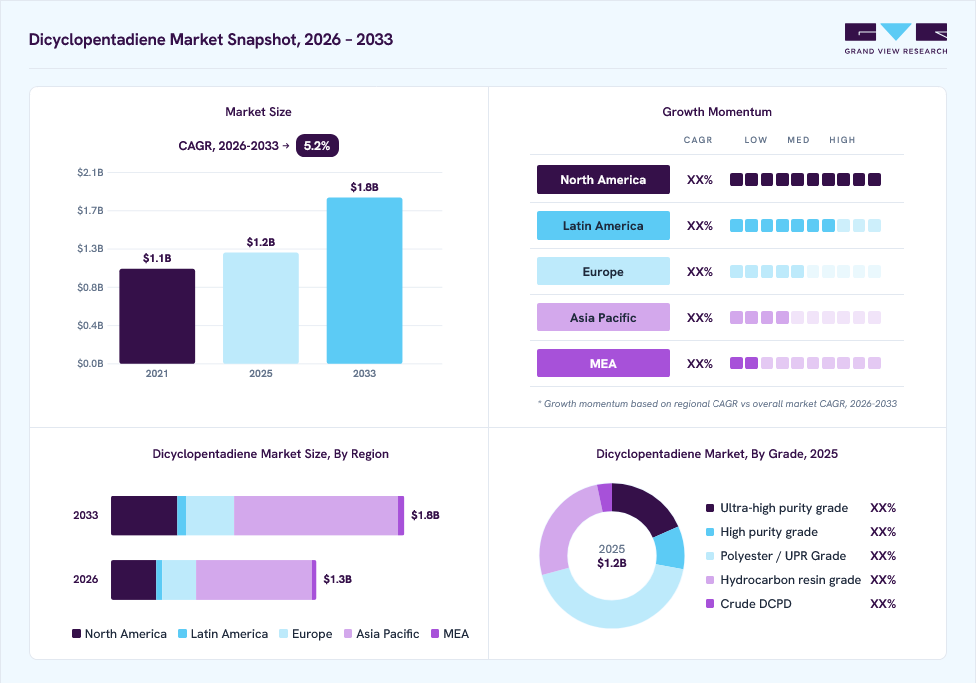
The global dicyclopentadiene market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.3 billion in 2026 to USD 1.8 billion in 2033, at a CAGR of 5.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 56.5% in 2025. The market growth is supported by increasing demand for DCPD-based unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, and specialty polymers across automotive, construction, marine, electrical and electronics, and industrial applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By grade: Polyester/UPR grade held the largest revenue share of 40.4% in 2025.
- By application: Unsaturated polyester resin held the largest revenue share of 41.6% in 2025.
- By end-use: Construction is expected to grow at the fastest CAGR of 5.6% from 2026 to 2033
Regional Highlights
- Largest regional market: Asia Pacific (56.5% revenue share, 2025)
- Fastest-growing regional market: North America (fastest CAGR, 2026-2033)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market Size in 2025: USD 1.2 Billion
- Estimated Market Size in 2026: USD 1.3 Billion
- Projected Market Size by 2033: USD 1.8 Billion
- CAGR (2026-2033): 5.2%
GVR research-powered AIAsk Prism AI about the dicyclopentadiene marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗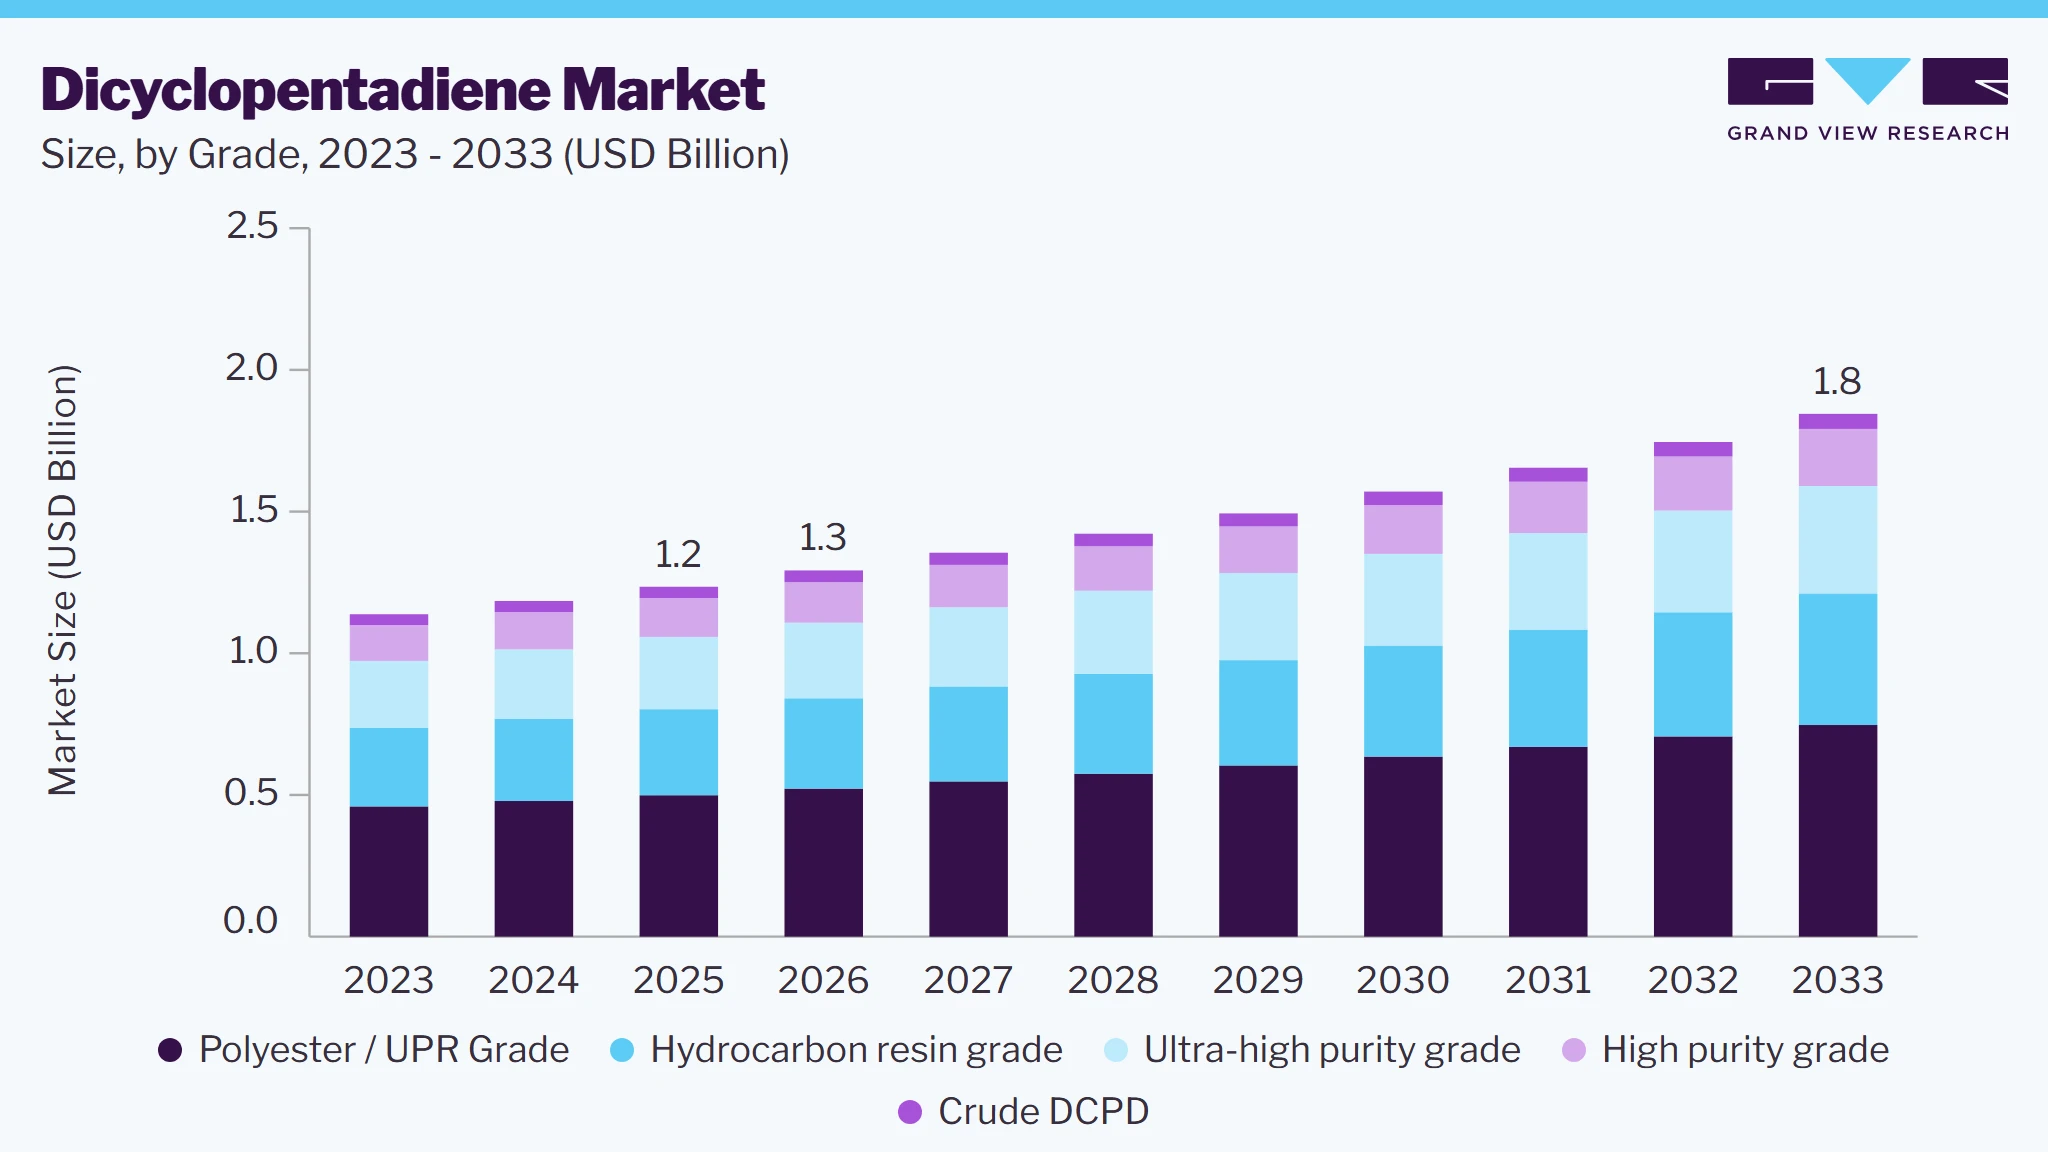 To learn more about this report, Download Free Sample Report
Growing consumption of engineered materials is strengthening demand for dicyclopentadiene (DCPD), particularly as a feedstock for unsaturated polyester resins, hydrocarbon resins, and specialty polymers. Its ability to improve impact resistance, chemical durability, thermal performance, and dimensional stability makes DCPD relevant to composite structures, coatings, adhesives, and molded components. Increasing production of vehicles, boats, construction components, storage tanks, pipes, and electrical equipment is supporting downstream consumption. The shift toward lightweight and longer-lasting materials is also encouraging formulators to use DCPD-derived systems where conventional materials may offer lower durability or corrosion resistance.Market Dynamics
The dicyclopentadiene industry is influenced by the performance requirements of downstream resin and polymer industries as well as the availability of C5 hydrocarbon feedstocks. Demand is closely linked to manufacturing activity in construction, transportation, marine, infrastructure, and industrial goods, where DCPD-based materials are used to produce durable composite and polymer components. Market development is also shaped by petrochemical operating rates, feedstock economics, resin production capacity, product purity requirements, and the emergence of higher-value specialty applications. Increasing investment in composite manufacturing and specialty chemical production is creating opportunities for suppliers with reliable production and consistent-quality grades.
Growing use of fiberglass-reinforced and other composite materials is supporting DCPD consumption in applications where low weight, corrosion resistance, strength, and durability are important. DCPD-modified unsaturated polyester resins are used in products such as vehicle components, marine structures, sanitary ware, pipes, tanks, and construction panels. Automotive manufacturers are also increasing the use of composite materials to reduce component weight and improve fuel efficiency or vehicle performance, while infrastructure and industrial users seek materials with longer service lives and lower maintenance requirements.
The expansion of composite manufacturing capacity and continued development of resin systems with improved mechanical and thermal characteristics are supporting broader adoption of DCPD-derived materials. Growth in transportation infrastructure, recreational marine products, and industrial equipment is expected to provide further demand opportunities for DCPD-based formulations.
The availability and cost of DCPD are closely connected to C5 hydrocarbon streams generated during steam cracking and related petrochemical operations. Changes in ethylene production, cracker utilization, crude oil and naphtha prices, and refinery operating conditions can affect the quantity and economics of recoverable DCPD. Periods of lower petrochemical operating rates may tighten availability and increase procurement costs for downstream users.
Feedstock fluctuations can also influence production planning and pricing for resin manufacturers that rely on stable DCPD supplies. Producers therefore need effective recovery, purification, storage, and supply-management systems to maintain consistent output and meet the specifications required by different downstream applications.
The development of higher-value applications offers an opportunity for DCPD producers to reduce reliance on conventional resin markets and strengthen margins through differentiated grades. High-purity DCPD can serve applications requiring tighter chemical specifications, while specialty grades can be developed for advanced polymer, resin, and composite systems with specific performance requirements.
Increasing demand for high-performance coatings, adhesives, specialty polymers, and engineered composites is encouraging manufacturers to improve formulation efficiency and material performance. Expansion into these applications, supported by technical collaboration with downstream formulators, can increase the value generated from DCPD and create new avenues for market growth.
Market Concentration & Characteristics
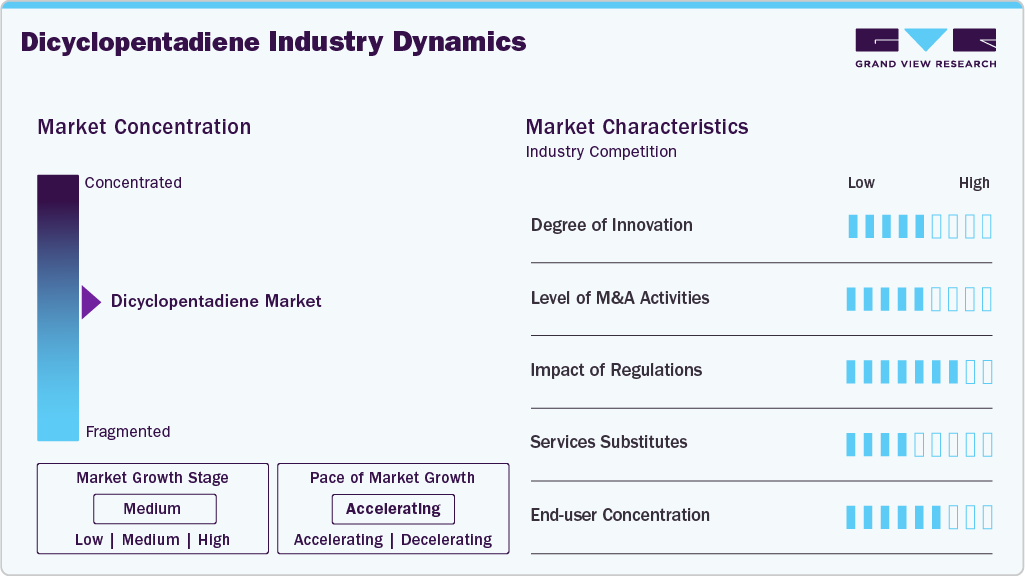
The DCPD market includes integrated petrochemical producers, hydrocarbon stream processors, specialty chemical companies, and regional suppliers. Competition is shaped by production scale, access to C5 feedstock, purification capabilities, product purity, supply reliability, pricing, and technical support. Producers with integrated feedstock positions can benefit from greater control over raw-material availability and production economics, while specialty suppliers can differentiate through high-purity grades and application-focused solutions. Market participants are strengthening their positions through capacity optimization, process improvements, feedstock integration, purification technologies, and closer relationships with resin and polymer manufacturers. Geographic supply coverage and dependable delivery are also important competitive factors because downstream customers require consistent material specifications for large-scale production. As specialty applications expand, competition is expected to increasingly focus on quality consistency, operational efficiency, supply security, and the ability to meet customized technical requirements.
 To learn more about this report, Download Free Sample Report
Leading companies are strengthening their positions in the dicyclopentadiene industry through production capacity enhancements, process optimization, feedstock integration, and the development of differentiated grades for downstream applications. Greater emphasis on high-purity material, consistent specifications, efficient recovery and purification processes, and dependable supply is expected to intensify competition over the forecast period. Producers are also building closer technical relationships with resin, polymer, and composite manufacturers to develop application-specific solutions and improve customer retention. Expansion of distribution networks and regional supply capabilities is further enabling companies to serve growing demand while reducing supply-chain constraints across key end-use markets.
Analyst Perspective
The DCPD market is expected to gain from continued expansion of composite materials, specialty resins, and high-performance polymer applications across transportation, construction, marine, and industrial sectors. Increasing demand for lightweight components, corrosion-resistant structures, and materials with extended service life is likely to sustain consumption of DCPD-derived products. Producers are also expected to pursue higher-purity grades and application-specific formulations as downstream manufacturers seek improved material performance and greater processing efficiency. Capacity additions, stronger feedstock integration, and broader regional supply networks may further support market penetration, while growth in advanced composites and specialty chemical applications is likely to create additional opportunities for DCPD suppliers in both established and emerging markets.
Grade Insights
The polyester / UPR grade segment dominated the dicyclopentadiene market, accounting for 40.4% of total revenue in 2025 reflecting the important role of DCPD in unsaturated polyester resin production. DCPD is used as a raw material or modifier in polyester systems that are subsequently incorporated into products such as boats, sanitaryware, tanks, panels, and other composite components. NOVA Chemicals identifies DCPD as a feedstock for polyester resins, while LOTTE Chemical lists UPR among the principal applications of its DCPD product.
The hydrocarbon resin grade segment is expected to grow at a CAGR of 5.5% during the forecast period. Demand is supported by the use of DCPD as a feedstock for hydrocarbon resins used in applications such as coatings, adhesives, inks, and specialty materials. ORLEN Unipetrol specifically identifies hydrocarbon resins among the downstream products manufactured using DCPD, including applications such as colored asphalt and reinforcing paints.
Application Insights
The unsaturated polyester resin segment dominated the dicyclopentadiene industry, accounting for 41.6% of total revenue in 2025. DCPD is incorporated into polyester resin systems used to manufacture reinforced composite products with properties such as corrosion resistance, dimensional stability, and mechanical durability. Expanding use of these materials across transportation, marine, construction, and industrial applications supports the segment's leading position.
The hydrocarbon resins segment is expected to grow at the fastest CAGR of 6.1% during the forecast period. Increasing consumption of hydrocarbon resins in adhesives, coatings, inks, rubber compounds, and other specialty formulations is driving demand for DCPD as a key feedstock. Growth in packaging, construction, automotive, and industrial manufacturing is expected to further increase consumption in this application.
End-use Insights
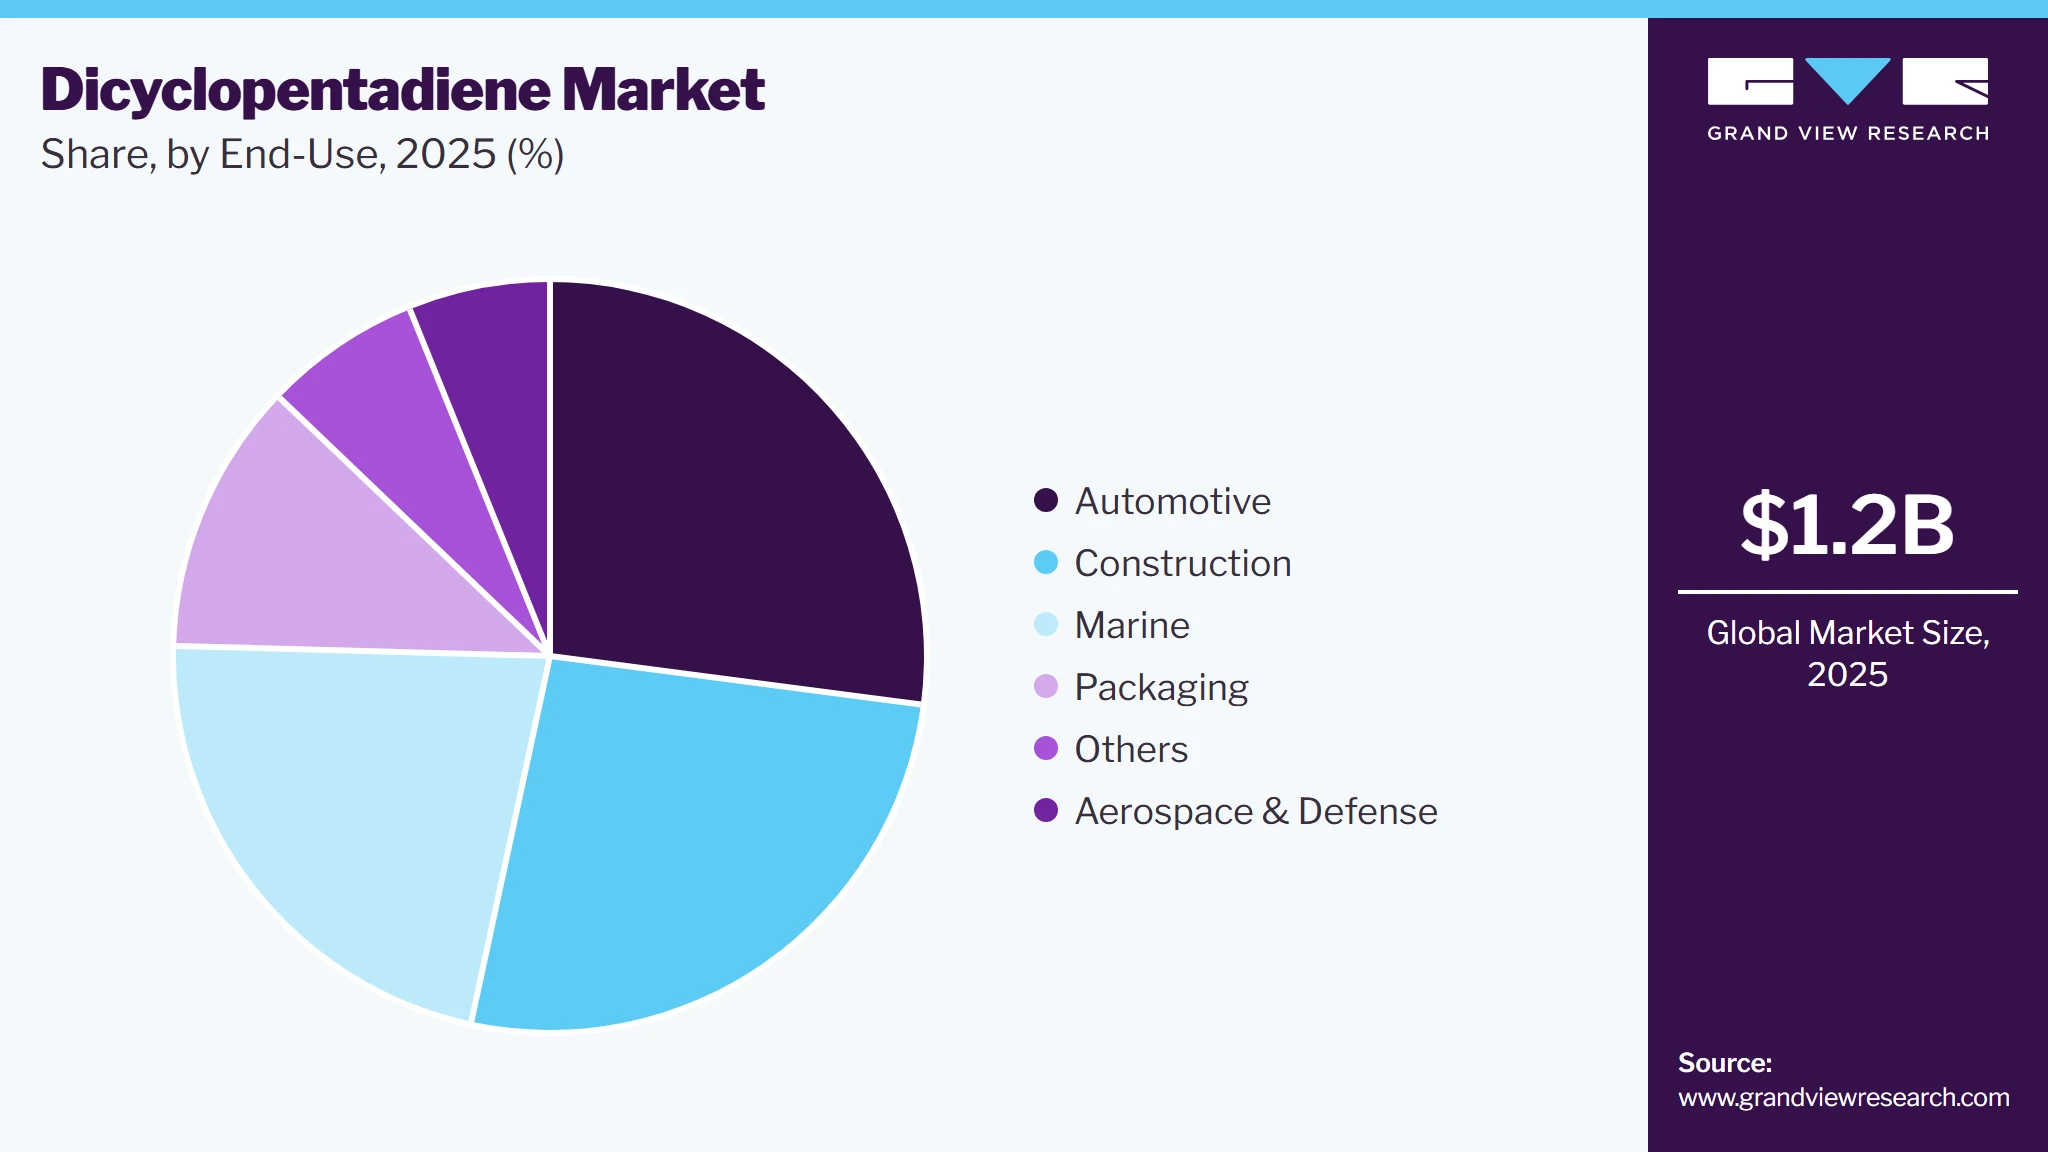
The automotive segment dominated the dicyclopentadiene market with a revenue share of 27.1% in 2025, supported by the incorporation of DCPD-derived materials into automotive components and related polymer systems. DCPD is used in materials serving requirements such as dimensional stability, durability, and lightweight construction. Increasing demand for lightweight composite materials and high-performance molded components is supporting DCPD consumption in the automotive sector.
 To learn more about this report, Download Free Sample Report
The construction segment is expected to grow at a CAGR of 5.6% during the forecast period. DCPD-based resins and composites are used in products such as pipes, tanks, panels, sanitaryware, roofing components, and other construction materials. Infrastructure development and the growing preference for durable, corrosion-resistant, and lightweight composite materials are expected to sustain demand for DCPD in construction.
Regional Insights
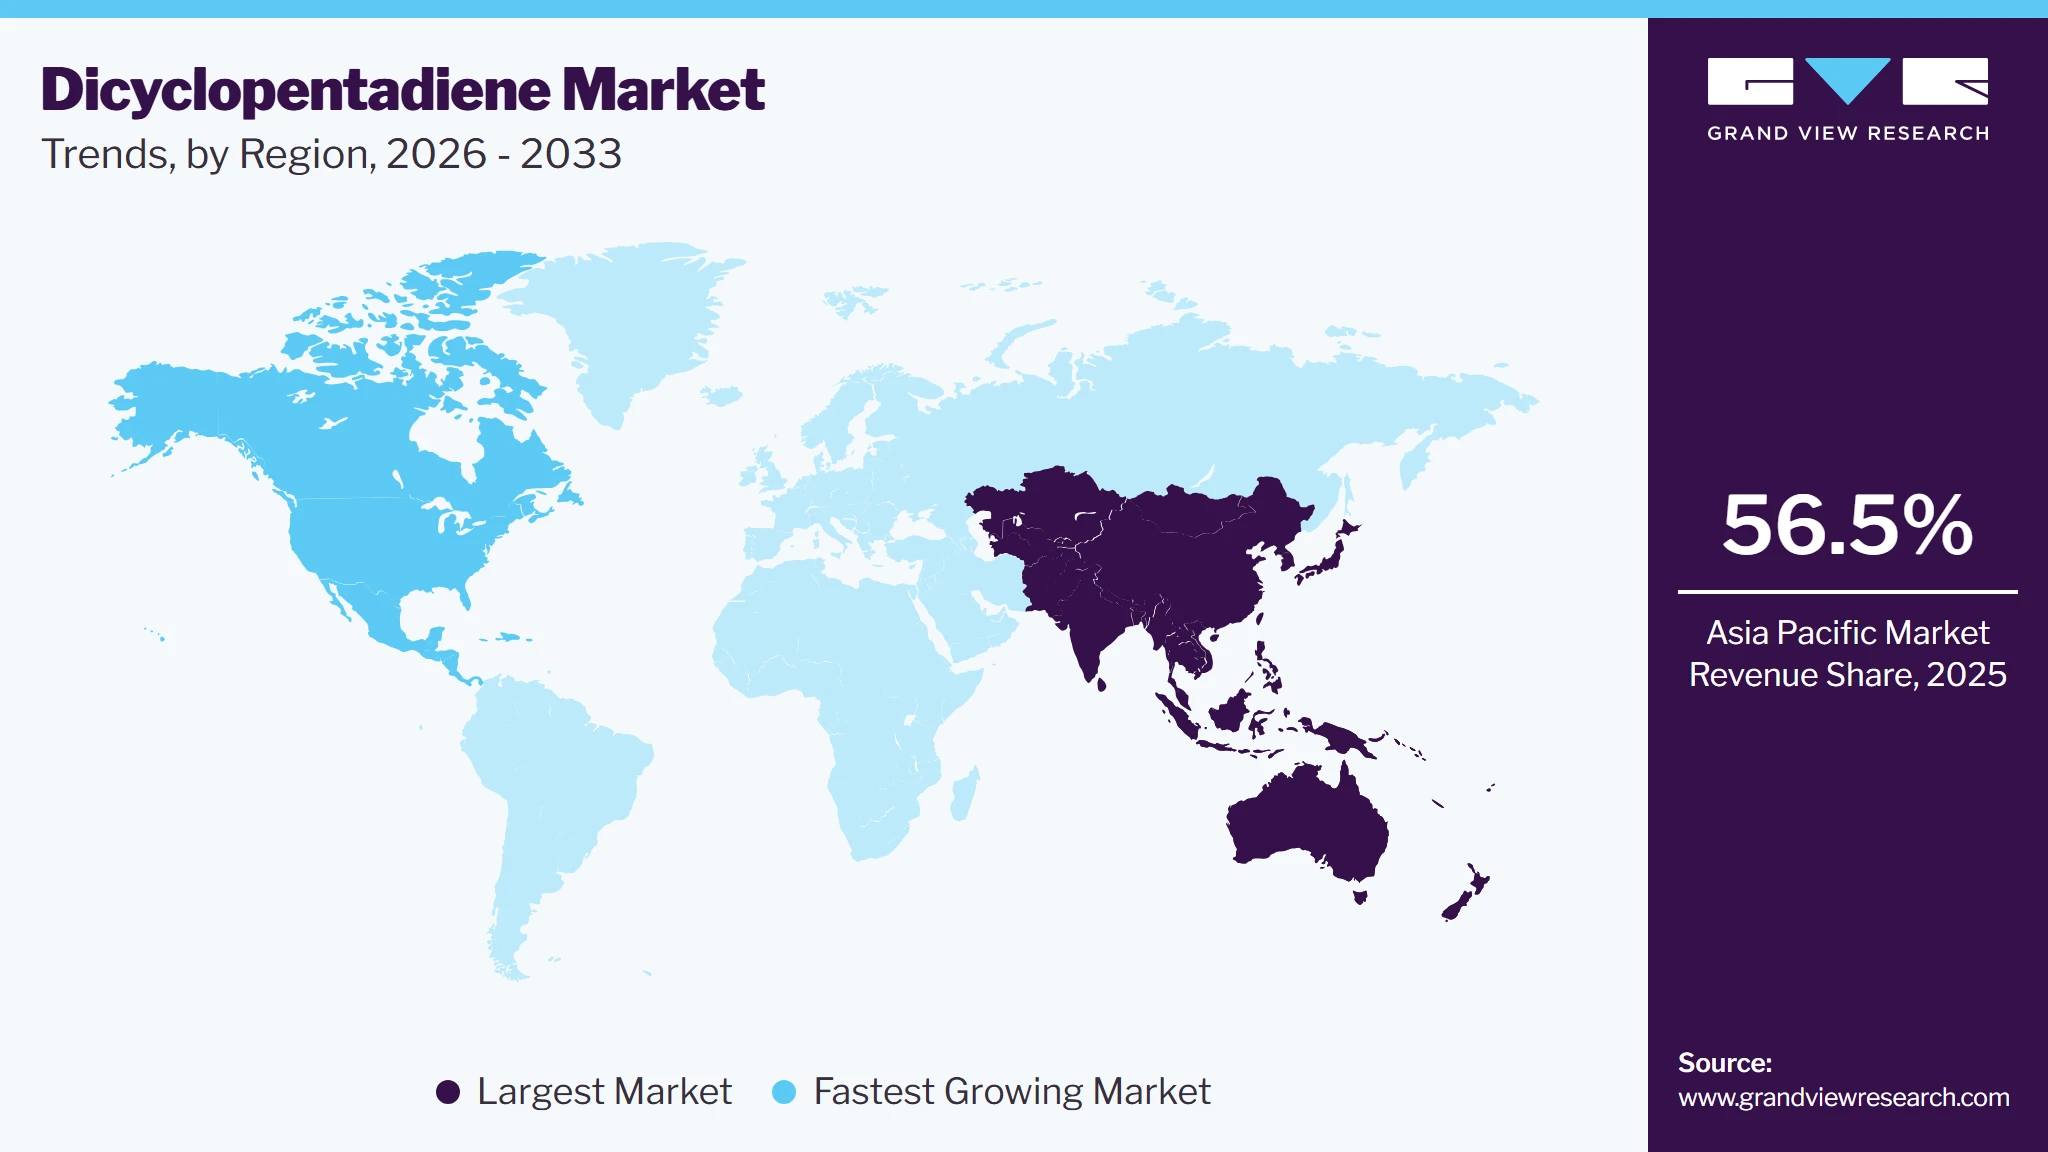
The Asia Pacific dicyclopentadiene market dominated with a revenue share of 56.5% in 2025. The region benefits from a strong petrochemical manufacturing base, substantial C5 hydrocarbon feedstock availability, and extensive downstream production of resins, elastomers, composites, and specialty polymers. China, Japan, and South Korea remain important markets due to their established chemical industries and demand from automotive, construction, marine, and industrial applications.
 To learn more about this report, Download Free Sample Report
China Dicyclopentadiene Market Trends
The China dicyclopentadiene market is the largest in Asia Pacific, supported by its large-scale petrochemical and chemical manufacturing infrastructure. Demand is closely linked to the production of unsaturated polyester resins, hydrocarbon resins, synthetic rubber, and specialty polymers. Expanding automotive production, infrastructure development, and composite-material manufacturing are expected to sustain DCPD consumption, while domestic production capacity helps strengthen regional supply.
North America Dicyclopentadiene Market Trends
The North America dicyclopentadiene industry is expected to grow at the fastest CAGR over the forecast period has a well-established DCPD market supported by integrated petrochemical operations and access to C5 hydrocarbon streams generated through cracking activities. The region benefits from established production of DCPD-based resins, elastomers, and specialty polymers, with demand coming from automotive, construction, marine, and industrial applications. Continued investment in manufacturing efficiency and specialty chemical production is expected to support regional demand.
The U.S. is the key market within North America, supported by its extensive petrochemical infrastructure and presence of major DCPD producers. DCPD consumption is driven by applications in unsaturated polyester resins, hydrocarbon resins, EPDM, poly-DCPD, and other specialty materials. Demand from automotive manufacturing, infrastructure, composites, and industrial applications is expected to provide steady opportunities for market expansion.
Europe Dicyclopentadiene Market Trends
Europe's dicyclopentadiene industry is supported by established petrochemical production, specialty chemical manufacturing, and demand for high-performance polymer materials. Automotive, construction, coatings, adhesives, and composite applications represent important consumption areas. Increasing emphasis on resource efficiency, circular feedstocks, and lower-carbon chemical production is also encouraging producers to explore bio-circular and mass-balance approaches for DCPD supply.
Latin America Dicyclopentadiene Market Trends
Latin America's DCPD industry is supported by growing chemical and polymer manufacturing activities, particularly in Brazil and other industrial economies. Demand is associated with unsaturated polyester resins, hydrocarbon resins, composites, and specialty materials used in construction, transportation, and industrial applications. Expansion of infrastructure and manufacturing activity is expected to gradually increase regional consumption.
Middle East Dicyclopentadiene Market Trends
The Middle East dicyclopentadiene industry is benefiting from the region's expanding petrochemical sector and increasing efforts to diversify into higher-value chemical products. Availability of hydrocarbon feedstocks and integrated chemical complexes provides opportunities for DCPD production and downstream processing. Growing investment in construction, infrastructure, automotive-related manufacturing, and specialty chemicals is expected to create additional demand for DCPD-derived resins and polymers.
Key Dicyclopentadiene Company Insights
Companies operating in the dicyclopentadiene market are strengthening their competitive positions through product portfolio expansion, production capacity enhancement, feedstock integration, purification technology, and investments in high-quality DCPD products. Leading manufacturers are focusing on improving DCPD purity, product consistency, process efficiency, supply reliability, and application-specific grades while expanding their presence across unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, cyclic olefin polymers, poly-DCPD, and other specialty applications.
-
Chevron Phillips Chemical Company is a major participant in the dicyclopentadiene industry, leveraging its integrated petrochemical operations and C5 hydrocarbon processing capabilities to produce and supply crude DCPD. The company focuses on reliable feedstock availability, efficient hydrocarbon separation, product quality, and consistent supply to downstream customers. Its DCPD production capabilities support applications including hydrocarbon resins, unsaturated polyester resins, elastomers, and other specialty chemical products, strengthening its position in the global DCPD value chain.
-
Shell Chemicals is a prominent participant in the dicyclopentadiene market, leveraging its integrated petrochemical infrastructure and C5 hydrocarbon processing capabilities to manufacture and supply DCPD. The company emphasizes consistent product quality, reliable supply, production efficiency, and technical support for downstream applications. Its DCPD portfolio serves applications across resins, polymers, elastomers, and other specialty chemical formulations, while its broad manufacturing and distribution network supports its competitive position in global markets.
Key Dicyclopentadiene Companies:
The following key companies have been profiled for the study on the dicyclopentadiene market.
-
Chevron Phillips Chemical Company
-
Shell Chemicals
-
Braskem
-
LOTTE Chemical
-
NOVA Chemicals Corporation
-
LyondellBasell Industries
-
ZEON Corporation
-
YEOCHUN NCC (YNCC)
-
ORLEN Unipetrol
-
Shandong Qilong Chemical
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Chevron Phillips Chemical Company, Shell Chemicals, Braskem, LOTTE Chemical, NOVA Chemicals Corporation, LyondellBasell Industries
- Invest in C5 hydrocarbon recovery, DCPD separation, purification, and processing technologies to improve product quality, production efficiency, and yield.
- Expand DCPD portfolios across crude, high-purity, polyester/UPR, and hydrocarbon resin grades to address diverse downstream requirements.
- Strengthen feedstock integration and production capacity to improve supply reliability and respond to growing demand from resin, elastomer, composite, and specialty polymer manufacturers.
- Develop application-specific DCPD grades with controlled purity, composition, and performance characteristics for UPR, hydrocarbon resins, EPDM, COC/COP, and poly-DCPD applications.
- Strong petrochemical infrastructure and C5 feedstock integration supports efficient DCPD production.
- Established production capabilities and broad geographic presence provide large-scale supply and distribution advantages.
- Extensive product portfolios allow manufacturers to serve multiple downstream applications and purity requirements.
- Strong technical expertise in olefins, C5 processing, polymer intermediates, and specialty chemicals supports product development and process optimization.
- Established relationships with resin, elastomer, polymer, automotive, construction, and industrial customers strengthen market access.
- High dependence on C5 feedstock availability and cracker operating rates can affect DCPD production volumes and supply conditions.
- Capital-intensive petrochemical production and purification facilities require substantial investment for capacity expansion and modernization.
- Exposure to fluctuations in crude oil, naphtha, energy, transportation, and other petrochemical input costs can affect production economics.
- Large-scale integrated operations may provide less flexibility than smaller specialty producers when addressing highly customized requirements or small-volume orders.
Emerging Players: ZEON Corporation, YEOCHUN NCC (YNCC), ORLEN Unipetrol, Shandong Qilong Chemical
- Expand DCPD purification and production capabilities to increase availability of high-purity and application-specific grades.
- Improve C5 fraction recovery, separation, distillation, and purification technologies to enhance yield, product quality, and manufacturing efficiency.
- Focus on competitive pricing and reliable supply to strengthen relationships with regional resin, polymer, elastomer, and composite manufacturers.
- Develop higher-value DCPD products targeting UPR, hydrocarbon resins, poly-DCPD, specialty polymers, and elastomer applications.
- Strong technical capabilities in C5 hydrocarbon processing, DCPD purification, and specialty chemical production.
- Regional production facilities can provide competitive access to major Asian and European downstream markets.
- Greater flexibility in product development and regional customer servicing compared with some global integrated producers.
- Integration with petrochemical complexes can provide access to C5 streams and improve feedstock utilization.
- Ability to compete on pricing and offer regionally optimized supply solutions can support penetration into cost-sensitive markets.
- Smaller global footprint and distribution networks compared with the largest multinational petrochemical companies.
- More limited financial resources may constrain large-scale capacity additions and international expansion.
- Greater exposure to regional feedstock availability, cracker utilization, energy costs, and logistics conditions.
- Dependence on regional customers and distributors may limit direct access to certain global markets.
Recent Developments
-
In September, 2023 Shell Chemicals Europe entered into a strategic collaboration with OQ Chemicals to supply ISCC PLUS-certified bio-circular dicyclopentadiene (DCPD) based on a mass-balance approach. The DCPD is used as a precursor for OQ Chemicals’ Oxbalance TCD Alcohol DM, supporting applications in technical polymers, coatings, adhesives, food packaging, electronics, and automotive products. The collaboration strengthens Shell’s sustainable DCPD offering and supports reliable supply of lower-carbon feedstock for downstream specialty chemical production.
Dicyclopentadiene Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026
USD 1.3 billion
Projected market size by 2033
USD 1.8 million
Growth rate
CAGR of 5.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Grade, application, end-use, region
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Chevron Phillips Chemical Company; Shell Chemicals; Braskem; LOTTE Chemical; NOVA Chemicals Corporation; LyondellBasell Industries; ZEON Corporation; YEOCHUN NCC (YNCC); ORLEN Unipetrol; Shandong Qilong Chemical
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dicyclopentadiene Market Report Segmentation
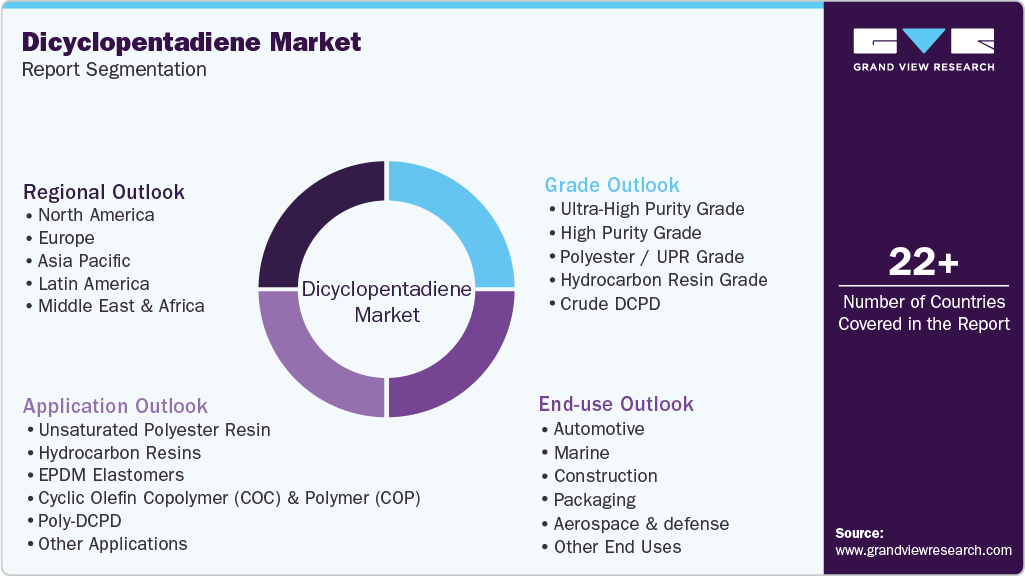
This report forecasts revenue & volume growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dicyclopentadiene market report based on grade, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Grade Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Ultra-High Purity Grade
-
High Purity Grade
-
Polyester / UPR Grade
-
Hydrocarbon Resin Grade
-
Crude DCPD
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Unsaturated Polyester Resin
-
Hydrocarbon Resins
-
EPDM Elastomers
-
Cyclic Olefin Copolymer (COC) & Polymer (COP)
-
Poly-DCPD
-
Other Applications
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Marine
-
Construction
-
Packaging
-
Aerospace & defense
-
Other End Uses
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The dicyclopentadiene market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dicyclopentadiene segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Grade
Revenue capture definition
Ultra-high purity grade
Revenue is generated from DCPD supplied at very high purity levels for applications requiring stringent control of composition and impurities. Demand is supported by specialty polymer, advanced resin, and high-performance material applications where consistent chemical characteristics and purity are critical.
High purity grade
Market revenues arise from high-purity DCPD used as a specialty chemical intermediate in applications such as hydrocarbon resins, specialty polymers, and advanced thermoset materials. Revenue is influenced by purity, consistency, dimer content, and suitability for specific polymerization and formulation processes.
Polyester / UPR Grade
Revenue is captured from DCPD supplied for the production of unsaturated polyester resins (UPR). This grade is used to modify polyester resin formulations and improve properties such as chemical resistance, toughness, dimensional stability, and processing performance in molded and composite products.
Hydrocarbon resin grade
Sales are generated from DCPD used as a feedstock for hydrocarbon resin production. Demand is driven by applications in adhesives, coatings, printing inks, rubber compounding, and other formulations where DCPD-based resins provide tack, compatibility, thermal stability, and chemical resistance.
Crude DCPD
Revenue is generated from crude DCPD recovered from C5 hydrocarbon streams and supplied for further purification, fractionation, or downstream chemical processing. Demand is influenced by availability of C5 feedstock, DCPD concentration, purity requirements, and integration with downstream resin and polymer manufacturing.
Segment - Application
Revenue capture definition
Unsaturated Polyester Resin
Sales are generated from DCPD used as a reactive modifier and raw material in unsaturated polyester resin production. DCPD-based UPRs are used in fiberglass-reinforced plastics, construction materials, automotive components, tanks, pipes, and other composite applications.
Hydrocarbon Resins
Market revenues arise from DCPD supplied as a feedstock for DCPD-based hydrocarbon resins. These resins are used in adhesives, coatings, printing inks, rubber compounds, road-marking materials, and other applications requiring enhanced tack, compatibility, and durability.
EPDM Elastomers
Revenue is captured from DCPD used as a diene comonomer in the production of EPDM elastomers. DCPD contributes to the crosslinking characteristics and performance of EPDM, which is used in automotive seals, hoses, roofing membranes, wire and cable insulation, and other rubber products.
Cyclic Olefin Copolymer (COC) & Polymer (COP)
Sales are generated from DCPD used as a comonomer or monomer component in the manufacture of cyclic olefin polymers and copolymers. These materials are used in optical, medical, pharmaceutical packaging, laboratory, and specialty applications requiring high transparency, low moisture absorption, and dimensional stability.
Poly-DCPD
Revenue is derived from DCPD used in ring-opening metathesis polymerization (ROMP) to produce poly-DCPD. The material is used for lightweight, impact-resistant molded components in automotive, industrial, infrastructure, and specialty applications.
Other Applications
Revenue is generated from DCPD used in specialty chemical intermediates, coatings, adhesives, flame-retardant materials, fragrances, and other niche chemical and polymer applications.
Segment - End Use
Revenue capture definition
Automotive
Sales are generated from DCPD-based materials used in automotive components, including body panels, structural parts, bumpers, hoods, fenders, seals, hoses, and other lightweight molded components. Demand is supported by requirements for weight reduction, impact resistance, durability, and corrosion resistance.
Marine
Market revenues arise from DCPD-based unsaturated polyester resins and poly-DCPD materials used in boats, marine structures, panels, housings, and other components. Demand is influenced by requirements for lightweight construction, moisture resistance, durability, and corrosion resistance.
Construction
Revenue is captured from DCPD used in polyester resins, hydrocarbon resins, and poly-DCPD materials incorporated into construction products such as pipes, tanks, roofing components, panels, sanitary products, and composite structures.
Packaging
Sales are generated from DCPD-derived polymers and resins used in selected packaging-related applications, particularly specialty packaging and materials requiring chemical resistance, dimensional stability, transparency, or enhanced barrier performance.
Aerospace & defense
Market revenues arise from DCPD-based specialty polymers, composites, and resin systems used in selected lightweight structural and protective components. Demand is influenced by requirements for high strength-to-weight ratios, impact resistance, durability, and dimensional stability.
Other End Uses
Revenue is derived from DCPD supplied for electrical and electronics, industrial equipment, consumer products, adhesives, coatings, rubber products, and other specialty applications where DCPD-derived resins and polymers provide targeted performance characteristics.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms is the supply base?
Examine the availability and processing of C5 hydrocarbon streams, primarily generated as by-products of naphtha or other hydrocarbon cracking processes. The assessment covers C5 fraction recovery, DCPD concentration, separation, fractionation, purification, hydrogenation where applicable, storage, production capacity, plant integration, quality-control practices, and supply-chain management. It also evaluates feedstock availability, cracking activity, recovery efficiency, purity levels, energy requirements, production technology, and capacity expansion that influence DCPD quality, consistency, cost, and scalability.
Form Adoption Layer
Where is dicyclopentadiene utilized?
Evaluate the adoption of DCPD across its major downstream applications, including unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, cyclic olefin copolymers and polymers, poly-DCPD, and other specialty chemical applications. Demand is influenced by DCPD purity, reactivity, compatibility with polymer systems, processing characteristics, performance requirements, and the expansion of resin, elastomer, composite, and specialty polymer applications.
Consumption Intensity Layer
How much dicyclopentadiene is consumed?
Assess DCPD consumption across major end-use industries, including automotive, construction, marine, packaging, aerospace & defense, electrical and electronics, and industrial applications. The analysis considers downstream production volumes, DCPD incorporation rates, grade requirements, resin and polymer formulation ratios, manufacturing intensity, replacement demand, and capacity additions to estimate annual consumption across key markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production, purification, and sale of DCPD in crude, high-purity, ultra-high-purity, polyester/UPR, and hydrocarbon resin grades. Revenue growth is supported by demand for DCPD-based unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, cyclic olefin polymers, poly-DCPD, and other specialty materials. Pricing and revenue realization are influenced by DCPD purity, feedstock availability, production capacity, energy and processing costs, downstream demand, product specifications, and regional supply-demand conditions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation
The assessment provides detailed cross-segmentation of the dicyclopentadiene market across grade, application, and end use. The analysis evaluates crude DCPD, high-purity, ultra-high-purity, polyester/UPR, and hydrocarbon resin grades; applications including unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, COC/COP, poly-DCPD, and other applications; and end-use industries such as automotive, construction, marine, packaging, aerospace & defense, and other industrial sectors.
Enables identification of high-growth opportunities across specific grade-application-end-use combinations. Supports product development, feedstock sourcing, capacity planning, distribution, and market-entry strategies by highlighting application-specific purity requirements, performance characteristics, demand intensity, and growth potential.
Opportunity Assessment
Detailed evaluation of growth opportunities arising from increasing demand for DCPD-based resins, elastomers, specialty polymers, composites, and advanced molded materials. The assessment covers expansion of unsaturated polyester resin production, hydrocarbon resin applications, EPDM demand, poly-DCPD adoption, specialty polymer development, production capacity additions, technological advancements, feedstock integration, and geographic expansion.
Enables identification of attractive investment opportunities across the DCPD value chain, from C5 hydrocarbon recovery and purification to downstream resin and polymer production. Supports decisions related to capacity expansion, purification technology, feedstock integration, product development, regional market entry, and strategic partnerships by highlighting high-potential applications and evolving downstream demand.
Competitive Benchmarking
Comparative assessment of leading DCPD producers and petrochemical companies based on product portfolios, DCPD purity grades, production capacity, feedstock integration, manufacturing technologies, geographic presence, plant footprint, R&D capabilities, distribution networks, and strategic initiatives. The benchmarking evaluates product quality, production efficiency, supply reliability, grade availability, application coverage, vertical integration, and commercialization strategies.
Supports benchmarking against key DCPD producers while identifying opportunities to strengthen product differentiation, purity and quality consistency, production efficiency, feedstock security, and geographic coverage. The analysis assists strategic decisions concerning capacity expansion, purification technology, downstream integration, portfolio development, partnerships, and long-term competitive positioning.
Frequently Asked Questions About This Report
The market is driven by increasing demand for DCPD-based unsaturated polyester resins, hydrocarbon resins, EPDM elastomers, and specialty polymers. Growing automotive production, infrastructure development, marine construction, and demand for lightweight and corrosion-resistant composite materials are supporting consumption.
North America is the fastest-growing region over the forecast period.
The dicyclopentadiene market size was valued at USD 1.2 billion in 2025 and is expected to reach USD 1.3 billion in 2026.
The dicyclopentadiene market is expected to grow at a CAGR of 5.2% from 2026 to 2033 to reach USD 1.8 billion by 2033.
Unsaturated polyester resin dominated the market with a 41.6% revenue share in 2025, while hydrocarbon resins segment is the fastest-growing segment.
Key players include Chevron Phillips Chemical Company, Shell Chemicals, Braskem, LOTTE Chemical, NOVA Chemicals Corporation, LyondellBasell Industries, ZEON Corporation, YEOCHUN NCC (YNCC), ORLEN Unipetrol, Shandong Qilong Chemical. These companies compete through DCPD production capacity, product quality, feedstock integration, purification capabilities, application-specific grades, and regional supply networks.
Asia Pacific dominated the market, accounting for the largest revenue share of 56.5% in 2025.
The polyester / UPR grade segment dominated with revenue share of 40.4% in 2025, while hydrocarbon resin grade segment is the fastest-growing grade.
The automotive segment dominated the market with a revenue share of 27.1% in 2025, while construction segment is the fastest-growing end-use.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


