
- Home
- »
- Plastics, Polymers & Resins
- »
-
Engineering Plastics Market Size & Share Report, 2026-2033GVR Report cover

Engineering Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin Type (ABS, LCP, PA, PET, PC), By End-use (Automotive & Transportation, Electrical & Electronics, Building & Construction, Industrial, Aerospace), By Region, And Segment Forecasts
Market Size, 2025
$158.3BMarket Estimate, 2026
$170.6BMarket Forecast, 2033
$288.6BCAGR, 2026–2033
7.8%Engineering Plastics Market Summary
The global engineering plastics market size was valued at USD 158.3 billion in 2025 and is projected to grow from USD 170.6 billion in 2026 to USD 288.6 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of approximately 45.0% in 2025. Industry growth is primarily driven by rising demand for engineering plastics across diverse end-use sectors, such as packaging, automotive, and construction, due to their attributes, including low weight, high durability, and cost-effectiveness.
Key Market Trends & Insights
- By resin type: Styrene copolymers (ABS and SAN) segment held the largest market share of approximately 34.0% in 2025.
- By end use: Automotive & transportation segment dominated the market with largest revenue share of over 35.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (Approximately 45.0% revenue share, 2025)
- By country: The China dominated Asia Pacific with the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 158.3 Billion
- Estimated market size in 2026: USD 170.6 Billion
- Projected market size by 2033: USD 288.6 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In recent years, there has been significant demand for products that replace alloys and metals in various industries, such as industrial machinery, automobiles, and consumer goods. The critical importance of the industry lies in technology, as ever-increasing end-user demands for versatility, and product specifications gradually tend to overshadow consumption dynamics.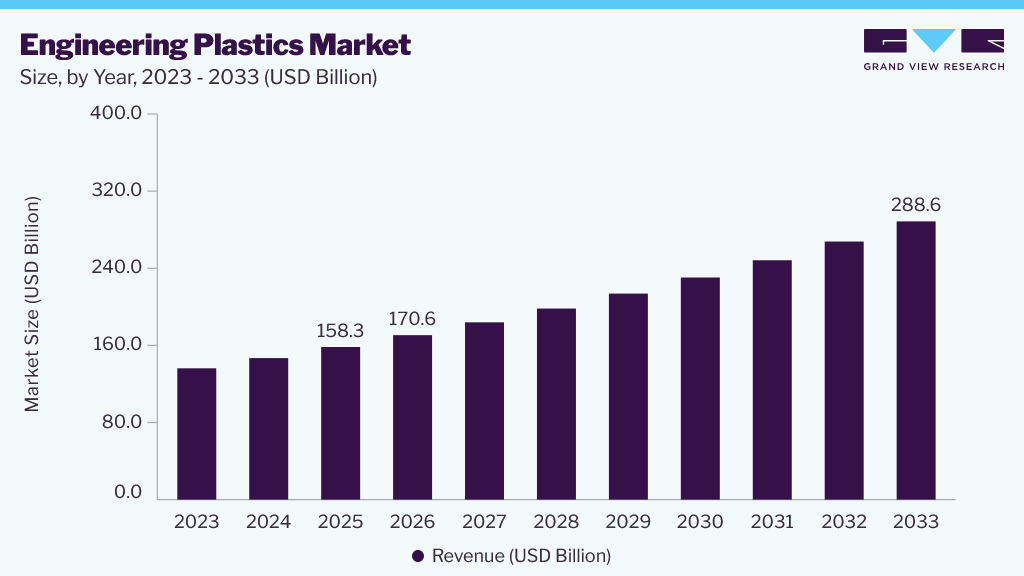 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Other factors, such as production processes, raw material availability, and socio-political events, also significantly influence industry trends. Rapid industrial growth and the expanding machinery industry across the region create opportunities for manufacturers to enhance their machinery and automation solutions.
In addition, encouraging investments in expanding engineering plastics production capacity to support rising industrial demand. For instance, in May 2025, DOMO Chemicals announced the expansion of its compounding operations in Mumbai, India, to meet the growing demand for high-performance engineering plastics, strengthening regional production capabilities for polyamide-based and other engineered resins used in automotive, electronics, and industrial applications. This strategic expansion reinforces the availability of advanced engineering plastics required by the modern manufacturing and automation industries.
Analyst Perspective
The global engineering plastics market is evolving from a conventional material replacement to a key driver of lightweight, high-performance, and sustainable manufacturing across industries. Styrene copolymers (ABS and SAN) remain the leading resins due to their widespread use in automotive, electrical & electronics applications. The automotive and transportation sectors continue to drive the highest demand. Investments in advanced materials, recycled-content plastics, and expanded regional production are accelerating innovation and strengthening supply chains, especially in the Asia Pacific and North America. Increasing electrification, industrial automation, and sustainability regulations are expected to drive long-term growth, prompting manufacturers to focus on high-performance materials, circular economy initiatives, and localized production to remain competitive.
Resin Type Insights
The styrene copolymers (ABS and SAN) segment led the market with the largest revenue share of 34.0% in 2025. Acrylonitrile butadiene styrene (ABS) finds major applications in the electrical & electronics industry. However, the growing application scope of these compounds in the automotive industry is expected to provide the segment with growth opportunities. The product is used in bumpers, interior components, and automotive trims, and its usage scope is expected to increase, considering the high production of lightweight passenger cars, especially in North America and Europe.
Ongoing innovations in sustainable ABS and SAN materials continue to support this trend in high performance applications. For instance, in June 2024, Trinseo PLC introduced MAGNUM ECO+, MAGNUM CR, and TYRIL CR, new ABS and SAN resins with 60% chemically recycled content that offer drop-in solutions for automotive, industrial, and consumer goods while reducing product carbon footprints. These innovations are expected to further drive the market.
The demand for polycarbonate (PC) has risen substantially, particularly in electrical and automotive applications, indicating potential growth in recent times. The innate malleability and flexibility of this polymer make it an exceptional candidate for thermoforming applications. Setting itself apart from its thermoplastic counterparts, polycarbonate exhibits a remarkable ability to undergo substantial plastic deformation without fracturing or cracking.
End-use Insights
The automotive & transportation segment led the market with the largest revenue share of approximately 35.0% in 2025. The increasing product usage in automotive components, such as bumpers, interior trims, and dashboards, as opposed to alloys and metals, has been a major factor driving the segment's growth. In recent years, there has been a significant rise in automotive production, mainly driven by the growth of the manufacturing sector. For instance, in April 2025, Covestro AG introduced a new portfolio of TÜV Rheinland-certified post-consumer recycled (PCR) polycarbonates made from scraped automotive headlamps. Developed in collaboration with partners including Volkswagen and NIO, the materials are designed for new automotive applications, supporting lightweight vehicle manufacturing while advancing circularity in the automotive industry.
The electrical & electronics segment is anticipated to grow at a significant CAGR from 2026 to 2033, driven by increasing demand for household electrical & electronics products, including wires, cables, sockets, and circuit breakers. Several market players are tapping into a variety of polymer products and filler technologies to address new design challenges in the electronics industry. Increased investment in advanced engineering plastics supports high-growth manufacturing industries. For instance, in May 2025, BASF announced the commercial launch of Ultramid Advanced, a new polyphthalamide (PPA) grade for electric vehicle power electronics, with production and supply focused on meeting the growing demand.
Regional Insights
The North America engineering plastics market is expected to grow at a significant CAGR during the forecast period. The recent surge in production utilizing shale gas and increasing exploration activities has enabled North American consumers and producers to obtain an unprecedented level of cost-effectiveness, which, in turn, has bolstered the demand for engineering plastic compounding in the region.
U.S. Engineering Plastics Market Trends
The engineering plastic market in U.S. held a substantial market share in North America in 2025. The demand for engineered plastic compounds in the country is mainly generated by the expanding automotive industry, coupled with rising construction activities.
Asia Pacific Engineering Plastics Market Trends
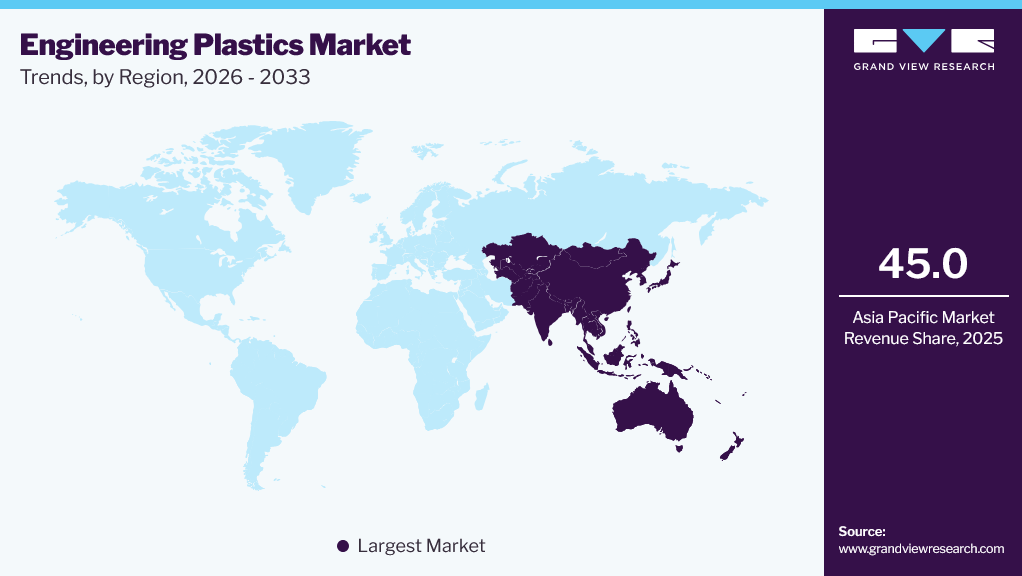
Asia Pacific dominated the global engineering plastics market with the largest revenue share for over 45.0% in 2025 and is projected to grow at the fastest CAGR during the forecast period, due to the high availability of skilled labor at a low cost, as well as easily accessible land. The region is a major hub for rapidly expanding industries like construction, automotive, and electronics, offering significant potential for engineering plastics manufacturers.
 To learn more about this report, Download Free Sample Report
The engineering plastics market in China accounted for the largest market revenue share in the Asia Pacific in 2025. The automotive and transportation segment captured the largest revenue share of approximately 35.0% in 2025. Continuous infrastructure investments are expected to sustain economic growth, and the automotive, aerospace, and construction sectors are expected to benefit from reforms, including regulatory changes, policy adjustments, and structural enhancements.
The India engineering plastics market is anticipated to grow at a lucrative CAGR during the forecast period. The automotive, aerospace, and construction sectors in India are poised for robust growth in the coming years, thereby supporting overall market growth. This projection is underpinned by escalating consumer demand and a notable uptick in disposable income levels.
Europe Engineering Plastics Market Trends
The engineering plastics market in Europe is anticipated to grow at a moderate CAGR of 6.2% from 2026 to 2033. The regional market is shaped by stringent environmental regulations enforced by entities such as the European Chemicals Agency (ECHA) and the European Commission, along with other federal-level agencies, further influencing industry dynamics.
The UK engineering plastics market is anticipated to experience a gradual growth trajectory, influenced by multiple factors, including muted industrial output amid economic uncertainties, potential supply chain disruptions, and evolving regulatory conditions, which collectively shape the market's landscape and growth potential.
The engineering plastics market in Germany is anticipated to grow at a lucrative CAGR during the forecast period. Germany was the leading manufacturer of engineering plastics in Europe. The country is self-sufficient in terms of engineering plastic production, with an adequate number of plants and production capacities to fulfill the local demand.
The France engineering plastics market is anticipated to grow significantly on account of improvements in socioeconomic conditions and an ease in the high-price perception among households, which are likely to spur investments in the consumer electronics industry in France.
Central & South America Engineering Plastics Trends
The engineering plastics market in Central & South America has significant growth potential as it offers opportunities for investors to increase the domestic production of these plastics. Changes in consumer preferences, low production costs, rapid industrialization, and an increase in disposable income in the region are anticipated to drive economic growth over the next few years.
The Brazil engineering plastics market is expected to grow at a significant CAGR of over 7.0% from 2026 to 2033, owing to increasing GDP and high demand for Brazilian & other exports. Passenger cars make up a substantial portion of the total automobile sales in the Central & South American region.
Middle East & Africa Engineering Plastics Trends
The engineering plastics market in the Middle East & Africa is anticipated to grow at a moderate CAGR from 2026 to 2033. GCC countries have ongoing infrastructure projects, including railways, roads, and bridges, that require engineering plastic products, such as pipes and tubes. This is expected to boost product demand in the region.
Key Engineering Plastics Company Insights
Key companies are adopting several organic and inorganic expansion strategies, such as mergers & acquisitions, new product launches, capacity expansion, and joint ventures, to expand and maintain their market share. For instance, in October 2025, Daicel Corporation plans to acquire Polyplastics Co., Ltd.'s business and the integrate Polyplastics' engineering plastics business into its High Performance Polymers (HPP) Strategic Business Unit to strengthen its engineering plastics operations and improve global competitiveness.
Key Engineering Plastics Companies
The following key companies have been profiled for this study on the engineering plastics market:
-
Grand Pacific Petrochemical Corporation
-
Mitsubishi Engineering-Plastics Corporation
-
Wittenburg Group
-
Piper Plastics Corp.
-
Chevron Phillips Chemical Company LLC
-
Daicel Corporation
-
Evonik Industries AG
-
Eastman Chemical Company
-
Ascend Performance Materials Holdings Inc.
-
Ravago Group
-
Teknor Apex Company
-
Trinseo PLC
-
Polyplastics Co., Ltd.
-
Ngai Hing Hong Company Limited
-
Ginar Technology Co., Ltd.
Recent Developments
-
In February 2026, Evonik Industries AG expanded its VESTAKEEP i4 PEEK filament portfolio for industrial additive manufacturing by introducing new grades for high-performance applications in aerospace, automotive, and medical sectors, strengthening Evonik's position in advanced engineering plastics for demanding industries.
-
In October 2025, Daicel Corporation and Mitsui Chemicals announced a strategic partnership to strengthen their engineering plastics businesses. Under this agreement, Polyplastics will market Mitsui Chemicals' high-performance resins, ARLEN and AURUM, to meet rising demand for advanced engineering plastics in the automotive, electrical & electronics industries.
Engineering Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 158.3 billion
Estimated market size in 2026
USD 170.6 billion
Projected market size by 2033
USD 288.6 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin type, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; China; India; Japan; Australia; Brazil; Saudi Arabia
Key companies profiled
Grand Pacific Petrochemical Corporation; Mitsubishi Engineering-Plastics Corporation; Wittenburg Group; Piper Plastics Corp.; Chevron Phillips Chemical Company LLC; Daicel Corporation; Evonik Industries AG; Eastman Chemical Company; Ascend Performance Materials Holdings Inc.; Ravago Group; Teknor Apex Company; Trinseo PLC; Polyplastics Co., Ltd.; Ngai Hing Hong Company Limited; Ginar Technology Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Engineering Plastics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global engineering plastics market report based on resin type, end-use, and region:
- Resin Type Outlook (Revenue, USD Billion, 2021 - 2033)
- Styrene Copolymers (ABS and SAN)
- Fluoropolymer
- Ethylene Tetrafluoroethylene (ETFE)
- Fluorinated Ethylene-propylene (FEP)
- Polytetrafluoroethylene (PTFE)
- Polyvinyl Fluoride (PVF)
- Polyvinylidene Fluoride (PVDF)
- Liquid Crystal Polymer (LCP)
- Polyamide (PA)
- Aramid
- Polyamide (PA) 6
- Polyamide (PA) 66
- Polyphthalamide
- Polybutylene Terephthalate (PBT)
- Polycarbonate (PC)
- Polyether Ether Ketone (PEEK)
- Polyethylene Terephthalate (PET)
- Polyimide (PI)
- Polymethyl Methacrylate (PMMA)
- Polyoxymethylene (POM)
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Automotive & Transportation
- Electrical & Electronics
- Building & Construction
- Consumer Goods & Appliances
- Industrial
- Aerospace
- Medical
- Others
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Asia Pacific
- China
- Japan
- India
- Australia
- Central & South America
- Brazil
- Middle East & Africa
- Saudi Arabia
- North America
Frequently Asked Questions About This Report
The global engineering plastics market is expected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 288.6 billion.
The styrene copolymers (ABS and SAN) segment accounted for the largest revenue share of approximately 34.0% in 2025.
Key players in the market include Grand Pacific Petrochemical Corporation, Mitsubishi Engineering-Plastics Corporation, Wittenburg Group, Piper Plastics Corp., Chevron Phillips Chemical Company LLC, Daicel Corporation, Evonik Industries AG, Eastman Chemical Company, Ascend Performance Materials Holdings Inc., Ravago Group, Teknor Apex Company, Trinseo PLC, Polyplastics Co., Ltd., Ngai Hing Hong Company Limited, Ginar Technology Co., Ltd., and others.
The global engineering plastics market size was valued at USD 158.3 billion in 2025 and is estimated at USD 170.6 billion for 2026.
Asia Pacific dominated with approximately 45.0% revenue share in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


