
- Home
- »
- Healthcare IT
- »
-
Fitness Tracker for Sleep Monitoring Market Report, 2033GVR Report cover

Fitness Tracker For Sleep Monitoring Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Smart Watches, Smart Bands, Smart Clothing) By Distribution Channel (Online, Offline), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$7.0BMarket Estimate, 2026
$8.3BMarket Forecast, 2033
$23.1BCAGR, 2026–2033
15.8%Fitness Tracker For Sleep Monitoring Market Summary
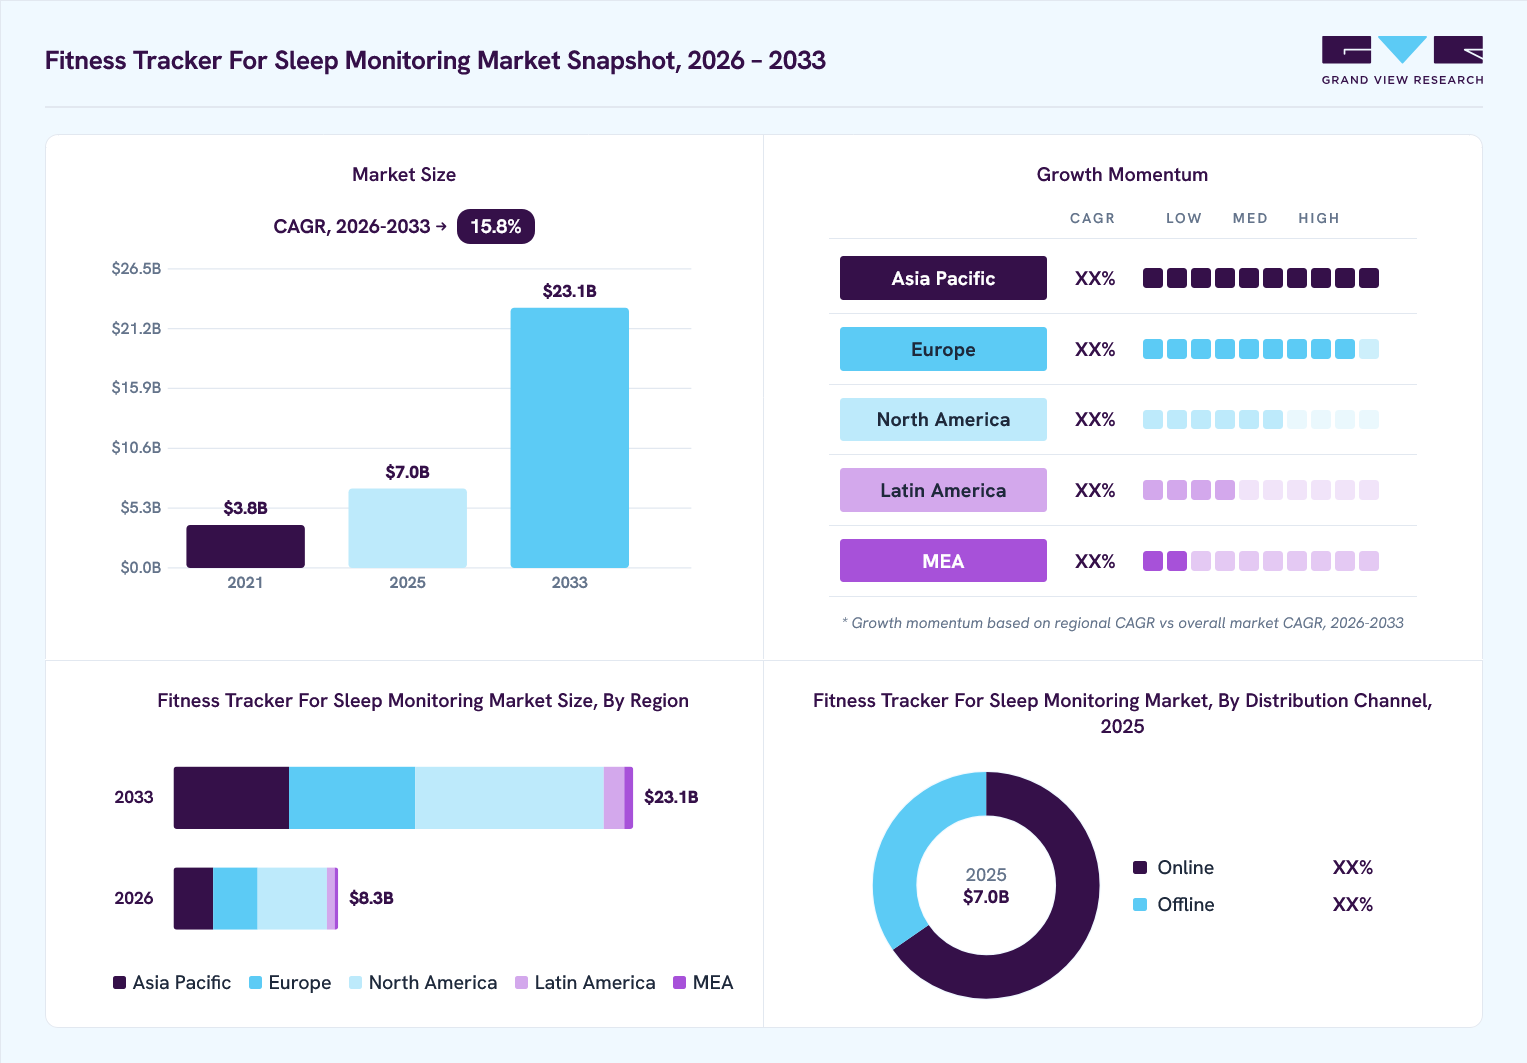
The global fitness tracker for sleep monitoring market size was valued at USD 7.0 billion in 2025 and is projected to grow from USD 8.3 billion in 2026 to USD 23.1 billion by 2033, growing at a CAGR of 15.8% from 2026 to 2033. North America dominated the fitness tracker for sleep monitoring market with the largest revenue share of 42.2% in 2025. The growth is attributed to factors such as lifestyle shifts, rising health consciousness and preventive healthcare, growing adoption of smart devices, technological advancements in wearables, and a growing geriatric population.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Smart watches segment held the largest market share of 47.9% in 2025.
- By distribution channel: Online segment held the largest market share of 65.3% in 2025.
Regional Highlights
- Largest regional market: North America (42.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 7.0 Billion
- Estimated market size in 2026: USD 8.3 Billion
- Projected market size by 2033: USD 23.1 Billion
- CAGR (2026-2033): 15.8%
Prism AI by Grand View Research Free to tryAsk a question about the fitness tracker for sleep monitoring marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →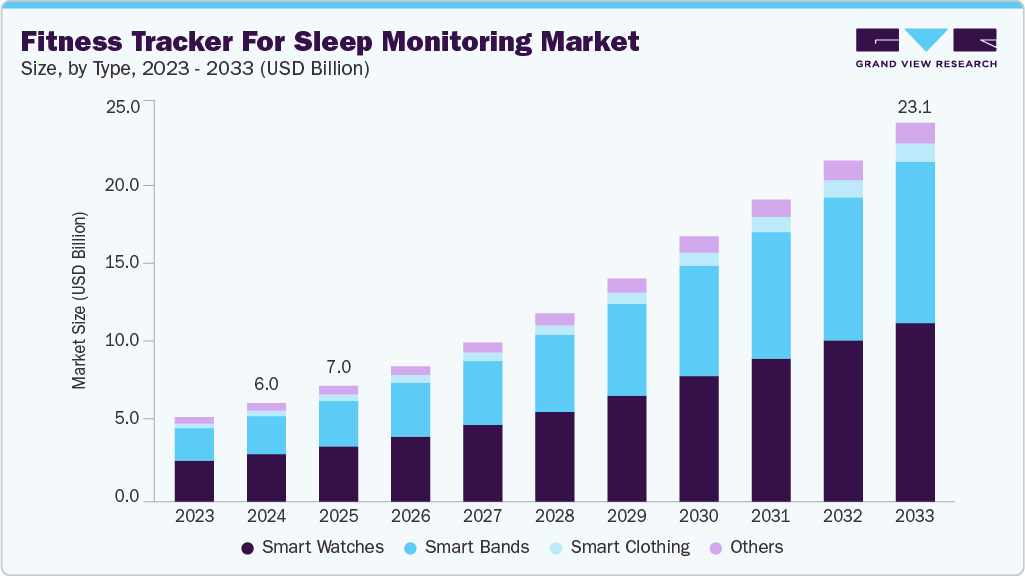 To learn more about this report, Download Free Sample Report
Market Dynamics
The fitness tracker for sleep monitoring market is experiencing steady growth, driven by the rising prevalence of sleep disorders, increasing stress-related fatigue, and growing awareness of sleep as a fundamental component of overall health and well-being. The increasing burden of chronic conditions such as obesity, cardiovascular diseases, and diabetes, which are often associated with poor sleep quality, is further accelerating the adoption of sleep-tracking wearables for preventive health management. The expansion of digital health ecosystems, advancements in AI-based sleep analytics, and the growing adoption of remote patient monitoring are enhancing the accuracy and clinical relevance of sleep insights, supporting both consumer wellness and healthcare applications. Wearable devices such as Apple Watch, Fitbit devices, and WHOOP bands are widely used for sleep stage tracking, recovery scoring, and personalized sleep coaching, reinforcing the role of fitness trackers in sleep health management.
Consumers are increasingly shifting from reactive healthcare to preventive health management, with sleep emerging as a fundamental pillar of overall wellness alongside physical activity and nutrition. Growing awareness of the health risks associated with inadequate sleep is encouraging the adoption of fitness trackers that provide continuous sleep monitoring, personalized insights, and long-term health management.
Key Global Statistics on Sleep Disorders and Sleep Health, 2026
Sleep Statistic
Data
Adults getting insufficient sleep
More than one-third of adults sleep less than the recommended 7 hours per night.
Adults experiencing insomnia symptoms
Up to two-thirds of adults occasionally experience insomnia symptoms.
Prevalence of chronic insomnia
10-15% of people suffer from chronic insomnia.
Older adults with insomnia
Up to 75% of older adults experience symptoms of insomnia.
Sleep difficulties due to stress
54% of adults report stress and anxiety as the primary reasons for difficulty falling asleep.
Insomnia and mental health
40% of people with insomnia have a diagnosable mental health condition.
Depression and insomnia
83% of adults with depression experience at least one symptom of insomnia.
Sleep loss due to pain
95% of adults lose at least one hour of sleep each week because of pain.
Technological advancements are further driving the market growth by improving the accuracy and clinical relevance of sleep monitoring. Artificial intelligence, advanced biosensors, physiological signal analysis, and digital health integration enabling fitness trackers to deliver more comprehensive sleep assessments, recovery scores, personalized coaching, and longitudinal health insights. The growing integration of wearable devices with digital health platforms and remote patient monitoring solutions is also shifting to preventive healthcare and clinical support applications. The following are some of the recent developments in the fitness tracker for sleep monitoring market.
- In May 2026, Apple introduced an advanced health features across Apple Watch and AirPods Pro, enhancing sleep monitoring, physiological tracking, and wellness insights through deeper integration within its health ecosystem, thereby advancing consumer wearable capabilities and personalized digital health management solutions.
- In May 2026, Google launched Fitbit Air, a wrist strap powered by artificial intelligence for continuous health tracking, expanding Fitbit’s ecosystem with advanced sensing capabilities for sleep, activity, and wellness monitoring within consumer wearable technology markets and global adoption trends.
- In February 2026, NextSense launched Smartbuds, the world’s first truly wireless EEG-enabled earbuds, integrating brain-sensing technology designed to monitor and actively improve sleep quality through real-time neural and auditory feedback systems for enhanced restorative rest outcomes in clinical healthcare applications.
The fitness tracker for sleep monitoring market is restrained by the limited clinical accuracy of consumer wearables compared with polysomnography (PSG), the gold standard for sleep assessment. Most fitness trackers estimate sleep stages using accelerometers and optical heart rate sensors rather than directly measuring brain activity, eye movements, and muscle activity. As a result, their ability to accurately detect sleep disorders such as obstructive sleep apnea, insomnia, and narcolepsy remains limited, restricting their use for clinical diagnosis and encouraging healthcare professionals to rely on validated sleep studies. In March 2026, the National Sleep Foundation published a scientific position statement stating that while consumer sleep technologies can enhance sleep awareness and encourage healthier sleep behaviors, they should not replace comprehensive clinical evaluation for suspected sleep disorders due to variability in device performance and inherent technological limitations.
The integration of artificial intelligence (AI) and machine learning into fitness trackers presents a significant opportunity for the sleep monitoring market. AI-powered algorithms enable wearable devices to deliver personalized sleep insights, recovery scores, bedtime recommendations, and behavioral coaching based on users' sleep patterns, heart rate, stress levels, and activity data. As consumers increasingly seek individualized health guidance rather than basic sleep metrics, manufacturers are expanding AI-enabled features to improve user engagement and long-term wellness outcomes. The growing integration of sleep data with digital health platforms, corporate wellness programs, and telehealth services is further broadening the market potential. In March 2026, Fitbit[SK1] enhanced its AI-powered Personal Health Coach with improved sleep tracking capabilities, enabling more accurate detection of sleep onset, sleep stage transitions, interruptions, and naps.
The following are some of the top fitness trackers for sleep monitoring
Device
Type
Key Features
Ideal For
Oura Ring (Gen 3+)
Ring
Monitors HR, HRV, SpO₂, body temp, sleep stages, menstrual cycle; requires tagging habits.
Users focused on women’s health & trend tracking
Whoop Strap 4.0
Wrist‑band
Tracks HR, HRV, SpO₂, skin temp, respiratory rate, strain, sleep stages, recovery score; no display.
Serious athletes needing in‑depth health insights
Google Pixel Watch
Smartwatch
Built‑in ECG/GPS, HR, SpO₂, sleep stages, skin temp, cycle tracking; deep metrics via Fitbit Premium
Android users seeking smartwatch + sleep tracking
Ultrahuman Ring AIR
Ring
Measures HR, HRV, body temp; offers in‑depth sleep data and cardio‑age insights; no subscription needed.
Users wanting detailed sleep metrics without fees
Elemind Sleep Headband
Headband
EEG‑based acoustic stimulation to aid sleep onset; tracks brainwaves, sleep stages, efficacy.
Those struggling to fall asleep, needing active assistance
Market Concentration & Characteristics
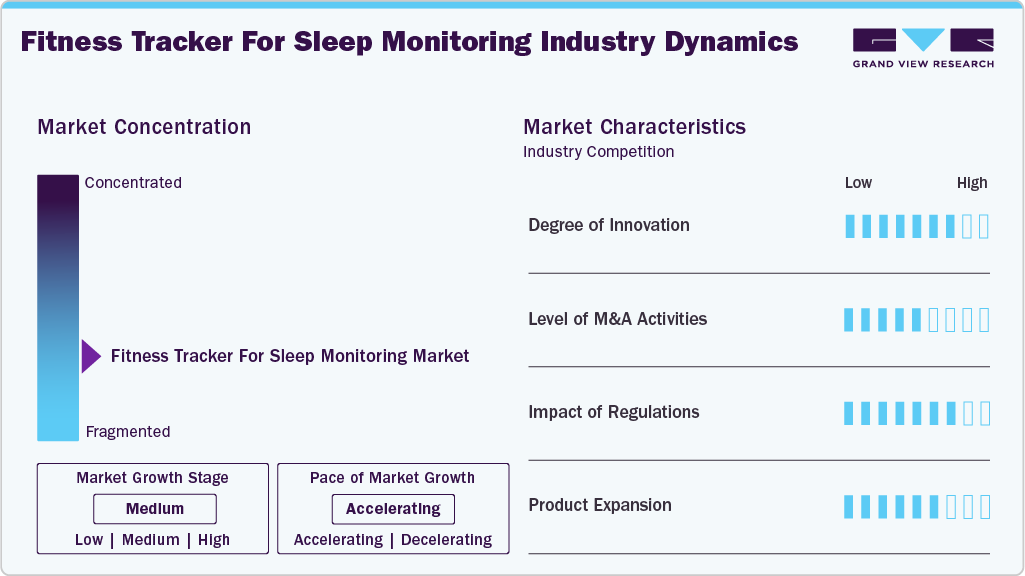
The degree of innovation in the fitness tracker for sleep monitoring industry is high, driven by rapid advancements in sensor technologies, artificial intelligence, and user-centric design. Manufacturers are continually improving sleep tracking accuracy by integrating advanced biometric sensors capable of measuring heart rate variability, blood oxygen levels, skin temperature, and movement with minimal latency. The ongoing technological developments are improving user engagement and positioning fitness trackers as viable tools in preventive healthcare and remote patient monitoring, marking a strong industry innovation trajectory.
 To learn more about this report, Download Free Sample Report
The level of mergers and acquisitions (M&A) in the fitness tracker for sleep monitoring industry is moderate as companies seek to expand their capabilities, product offerings, and market reach. Key players in the wearables and digital health space are acquiring startups with niche technologies in sleep analytics, AI-based health monitoring, and sensor innovation. For instance, larger firms such as Google’s acquisition of Fitbit reflect a trend of consolidation aimed at strengthening the ecosystems and overall presence. In addition, collaborations between tech companies and healthcare firms are becoming more common, signaling a growing interest in leveraging sleep data for broader health and wellness applications. This M&A activity is helping companies accelerate innovation, enter new regional markets, and enhance competitiveness in a rapidly evolving landscape.
The market operates within a complex regulatory landscape that influences innovation, consumer trust, and market access. Most devices are classified as general wellness products, which avoids the rigorous premarket approval required for medical devices. However, as wearables increasingly include advanced features such as sleep apnea detection or EEG-based staging, many manufacturers are pursuing FDA clearances and adhering to frameworks such as the U.S. Digital Health Software Precertification Program. For instance, in September 2024, Apple received FDA approval in the United States for sleep apnea detection on its Watch Series 9, Series 10, and Ultra 2 models. The feature used accelerometer‑based “breathing disturbance” metrics to alert users of potential issues and facilitate healthcare provider consultations.
The market continues to expand through diverse product lines and innovative form factors, catering to a wider range of user preferences and use cases. For instance, in July 2024, Samsung expanded its wearables portfolio with the global launch of the Galaxy Ring, Galaxy Watch7, and Galaxy Watch Ultra-integrating Galaxy AI-driven sensor capabilities to deliver 24/7 wellness support, including advanced sleep analysis, heart-rate monitoring, energy scoring, and personalized health insights. These varied expansions reinforce market competitiveness and enable brands to target specific demographics, from fashion-conscious users to wellness seekers and those needing integrated sleep solutions.
Analyst Perspective
The fitness tracker for sleep monitoring market is driven by the increasing prevalence of sleep disorders, stress-related sleep disturbances, obesity, cardiovascular diseases, and diabetes, all of which are closely linked to poor sleep quality and a growing need for continuous health monitoring. Rising consumer awareness of sleep as a critical pillar of preventive healthcare, combined with the increasing adoption of wearable technologies for monitoring sleep, recovery, and overall wellness, is driving market growth. Technological advancements in AI-powered sleep analytics, advanced sensor technologies, and digital health integration are further accelerating the adoption of fitness trackers by enabling more accurate sleep assessment, personalized insights, and actionable recommendations that support long-term health management and sustained user engagement.
Increased Accessibility and Mass Adoption Through Affordable Smart Devices
The widespread availability and affordability of smart devices, such as smartphones, smartwatches, and fitness bands, have made health tracking more accessible. Sleep monitoring has become a standard feature in many wearable devices, fueling mass adoption. Integration with mobile apps allows users to visualize sleep data, set goals, and receive personalized insights, enhancing user engagement and effectiveness. For instance, in February 2025, Apple introduced sleep tracking on Apple Watch and iPhone, enabling users to set personalized sleep schedules, monitor sleep stages, respiratory rate, daytime battery, and heart rate, and adjust wind‑down routines via Health and Sleep apps to enhance wellness.
Growing Focus on Holistic Wellness and Preventive Healthcare
As mental health-related issues such as stress escalate globally, awareness around holistic wellness is rising, prompting more individuals to proactively invest in preventive healthcare tools. Sleep, being a critical component of overall well-being, has gained significant attention. Fitness trackers that monitor sleep duration, quality, and patterns enable users to detect potential issues early and encourage healthier habits. This transition from reactive to preventive health management is a key driver of market growth. Companies are integrating more advance features into their wearable devices in response to this growing demand for advanced health monitoring. For instance, in September 2024, Apple launched the Watch Series 10 in the U.S., featuring advanced health capabilities, including a sleep apnea detection tool.
Lifestyle Shifts (Impact of Remote and Hybrid Work Models on Sleep Patterns)
The shift to remote and hybrid work models has significantly altered daily routines, including sleep patterns. Due to this shift, many individuals are experiencing irregular sleep schedules and increased screen time, leading to sleep disturbances. Fitness trackers with sleep monitoring capabilities help users become more aware of their sleep hygiene and make data-driven adjustments to restore balance, making these devices essential in the post-pandemic lifestyle. For instance, in June 2022, Garmin launched the Vivosmart 5 fitness tracker in India, offering comprehensive health monitoring features including sleep, stress, hydration, heart rate, SpO₂, women’s health, and Body Battery energy tracking.
Technological Innovation and Enhanced Device Capabilities
Continuous innovation in wearable technology has significantly improved fitness trackers' accuracy, comfort, and functionality. Modern devices are equipped with advanced sensors that measure heart rate variability, blood oxygen levels, body temperature, and movement during sleep. Incorporating AI and machine learning allows for more precise analysis and tailored recommendations, making sleep trackers smarter, more reliable, and more user-friendly. For instance, in June 2024, Apple previewed watchOS 11 in the U.S., introducing a powerful Vitals app for sleep and health metrics, cutting-edge sensor technology, advanced algorithms, and a science-backed approach to deliver groundbreaking insights into users' health and fitness, offering an unprecedented level of personalization, a training load feature, customizable activity rings, enhanced smart stack and photos watch faces, translate integration, and sleep apnea notifications.
Type Insights
Based on type, the smart watches segment led the market with the largest revenue share of 47.9% in 2025. The dominance is attributed to the widespread adoption of smartwatches due to their multi-functionality, combining sleep monitoring, fitness tracking, heart rate analysis, and smartphone connectivity in a single device. Brands such as Apple, Samsung, Fitbit, and Garmin have led the segment with feature-rich wearables that offer advanced sleep tracking capabilities, including sleep stage analysis, SpO₂ monitoring, and AI-driven sleep scores. For instance, in May 2023, Samsung introduced One UI 5 Watch in South Korea, previewing its upcoming Galaxy Watch series. The upgrade enhanced sleep features, including sleep scores, snoring duration, SpO₂ metrics, infrared‑based sleep mode, guided sleep coaching, and personalized fitness and safety tools.
The smart bands segment is expected to dominate the market with the fastest CAGR over the forecast period, owing to their affordability, lightweight design, and growing popularity among first-time users and fitness beginners. These devices offer essential health-tracking features, including sleep duration, sleep stages, and heart rate monitoring, at a significantly lower price than smartwatches, making them accessible to a wider consumer base. In September 2023, Google launched the Fitbit Charge 6 globally. This smart band features sleep monitoring, heart‑rate tracking, built‑in GPS, ECG and EDA sensors, SpO₂ monitoring, and other integrated Google services. In addition, improvements in battery life, comfort, and syncing capabilities with health apps have enhanced the user experience. The segment also benefits from increasing adoption in emerging economies, where cost-effective health monitoring solutions are in high demand.
Distribution Channel Insights
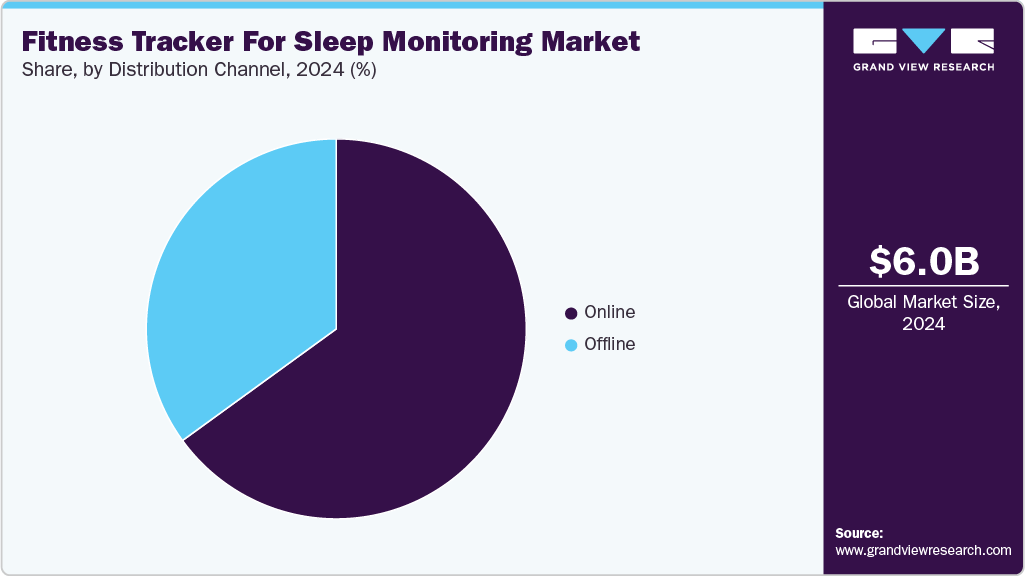
Based on distribution channel, the online segment led the market with the largest revenue share of 65.3% in 2025. The growing preference for e-commerce platforms that offer a wide variety of fitness trackers at competitive prices, along with easy comparison of features, customer reviews, and doorstep delivery, contributes to the segment's dominance. The rise of direct-to-consumer sales by leading brands such as Fitbit and Amazfit through their websites and partnerships with major online retailers such as Amazon and Flipkart has further accelerated online sales. In addition, the post-pandemic shift toward digital shopping behavior, along with attractive discounts, exchange offers, and EMI options, has made online channels the preferred mode of purchase, especially among tech-savvy and health-conscious consumers.
 To learn more about this report, Download Free Sample Report
The offline segment is anticipated to grow at a moderate CAGR over the forecast period, owing to the continued consumer preference for hands-on product experience, personalized assistance, and immediate purchase gratification. Physical retail outlets such as electronic stores, brand showrooms, and health and wellness chains allow customers to try on devices, assess comfort and fit, and receive in-person demonstrations, which is especially important for wearable products such as fitness trackers. Moreover, growing retail expansion in tier-2 and tier-3 cities and strategic placement of products in multi-brand outlets and tech malls are boosting offline visibility. Many consumers still rely on offline channels for trusted recommendations and after-sales support, which helps drive purchases in certain demographics, particularly among older and less tech-savvy buyers.
Regional Insights
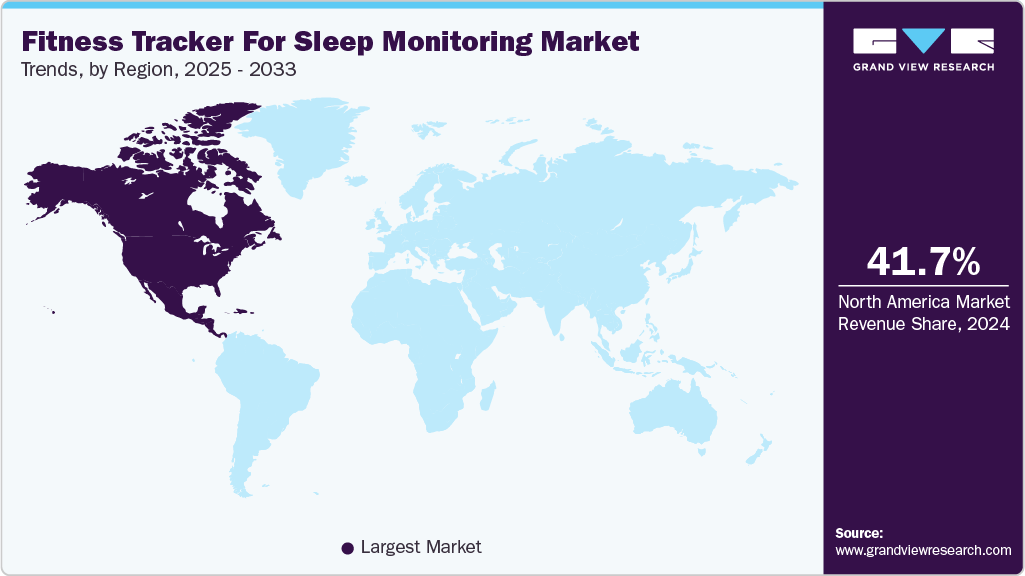
North America dominated the fitness tracker for sleep monitoring market with the largest revenue share of 42.2% in 2025, driven by high awareness of sleep health, widespread adoption of wearable technology, and a strong healthcare infrastructure. Increasing cases of lifestyle-related disorders such as sleep apnea, obesity, and stress have made sleep tracking a key component of preventive care. Moreover, corporate wellness programs, health insurance incentives, and robust integration with mobile health platforms have accelerated adoption across the region.
 To learn more about this report, Download Free Sample Report
U.S. Fitness Tracker for Sleep Monitoring Market Trends
The market in the U.S. held the largest share in the North America region in 2025, the presence of leading brands such as Apple and Fitbit, and strong consumer interest in self-health management. According to a report by NIH from 2023, an estimated 50 to 70 million people in the U.S. experience sleep disorders, and approximately one-third of adults consistently fall short of getting the uninterrupted sleep necessary to maintain good health, driving demand for devices that track sleep patterns, heart rate, and SpO₂ levels. Smart healthcare investments, digital health policies, and increasing partnerships between tech companies and healthcare providers also support the growth.
Europe Fitness Tracker for Sleep Monitoring Market Trends
The fitness tracker for sleep monitoring industry in Europe is expected to grow at a significant CAGR over the forecast period, owing to increasing government focus on digital health initiatives, chronic disease management, and healthy aging. Sleep health awareness is rising due to studies linking sleep deprivation with cardiovascular and metabolic disorders. Countries such as Germany, France, and Italy are witnessing high demand for fitness trackers as part of lifestyle improvement efforts, supported by insurance reimbursements and partnerships between wearables brands and wellness service providers.
The UK fitness tracker for sleep monitoring industry is anticipated to grow at a significant CAGR due to rising obesity rates and increasing cases of insomnia and mental health issues, prompting consumers to adopt wearables for sleep monitoring. The National Health Service (NHS) and private insurers are increasingly open to integrating wearable data for preventive care. Tech-savvy youth, high smartphone penetration, and strong retail and e-commerce channels further fueled the adoption of smartwatches and fitness bands with sleep monitoring features.
Asia Pacific Fitness Tracker for Sleep Monitoring Market Trends
The fitness tracker for sleep monitoring industry in Asia Pacific is anticipated to grow at a significant CAGR over the forecast period due to rapid urbanization, growing middle-class income, and increased smartphone and wearable usage. Sleep disorders are rising due to hectic work-life schedules and digital screen exposure. Consumers in countries such as India, Japan, South Korea, and Southeast Asia are becoming more health-conscious, and governments are supporting digital health solutions.
China fitness tracker for sleep monitoring industry is expected to register a significant CAGR over the forecast period, driven by tech innovation, government support for digital health, and a large base of digitally connected consumers. Growing concern over stress-related sleep disorders among the working population has increased demand for sleep monitoring features in wearables. Domestic companies dominate the market with AI-enabled, affordable smart bands and watches. E-commerce platforms and social commerce further amplify reach and consumer engagement for the devices.
Latin America Fitness Tracker for Sleep Monitoring Market Trends
The fitness tracker for sleep monitoring industry in Latin America is anticipated to grow at a significant CAGR over the forecast period because of increasing health awareness, particularly among urban populations. Countries in the region are witnessing a rise in chronic conditions related to sleep, leading to a greater focus on personal health tracking. Adoption is fueled by smartphone growth, improving internet access, and brand expansions into Latin American markets. Collaborations between health-tech companies and local distributors are also helping expand product availability.
Brazil fitness tracker for sleep monitoring industry is anticipated to grow at a significant CAGR over the forecast period, driven by its urban population, increasing digital health literacy, and government initiatives to promote active lifestyles. Rising stress and poor sleep hygiene among young professionals have fueled demand for affordable, feature-rich wearables. The local presence of international brands and strong e-commerce platforms, and retail networks supports continued market expansion in Brazil.
Middle East and Africa Fitness Tracker for Sleep Monitoring Market Trends
The fitness tracker for sleep monitoring industry in the Middle East and Africa is expected to grow at a significant CAGR over the forecast period, owing to increasing disposable incomes, growing awareness about sleep health, and government-backed wellness campaigns. The Gulf Cooperation Council (GCC) countries are investing in digital transformation and health tech, making them prime markets for fitness wearables. Meanwhile, in parts of Africa, rising smartphone penetration and falling wearable prices are slowly making sleep trackers more accessible.
Saudi Arabia fitness tracker for sleep monitoring industry is forecasted to grow at a significant CAGR over the forecast period, driven by factors such as its Vision 2030 health initiatives, which emphasize personal wellness and digital health adoption. The government actively promotes fitness and health-tracking devices through campaigns and incentives, especially among the youth and working-class populations. High smartphone penetration, increasing urbanization, and a cultural shift toward health-conscious living are key drivers for the rising adoption of sleep-monitoring wearables in the kingdom.
Key Fitness Tracker for Sleep Monitoring Company Insights
The key market players’ adapting to the rapidly changing technology and innovations presents tough competition in the market. The market players are focusing more on research and development to provide efficient products to cater to the rising demand. The increasing number of brands offering fitness trackers for sleep monitoring with advanced technology, continuous development of features offering the best customer experience, and at prices suiting different earning groups, and the growing e-commerce sector support the market growth.
Key Fitness Tracker for Sleep Monitoring Companies:
The following are the leading companies in the fitness tracker for sleep monitoring market.
- Fitbit (Google)
- Garmin Ltd.
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Xiaomi Corporation
- Huawei Technologies Co., Ltd.
- Withings (Nokia Health)
- Amazfit (Zepp Health / Huami)
- Polar Electro
- WHOOP Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Apple Inc., Fitbit (Google), Garmin Ltd., Samsung Electronics Co., Ltd., Huawei Technologies Co., Ltd.)
- Focus on expanding premium wearable portfolios by integrating advanced sleep monitoring, AI-powered health analytics, ECG, SpO₂, and continuous heart rate monitoring. Invest in proprietary health ecosystems, software updates, and strategic collaborations to enhance personalized sleep insights and preventive health capabilities.
- Strong global brand recognition, extensive R&D capabilities, large installed user base, robust ecosystem integration with smartphones and health platforms, and advanced sensor technologies. Strong distribution networks and high consumer trust support premium market positioning.
- Premium pricing is adopted in price-sensitive markets. High dependence on proprietary ecosystems may reduce interoperability, while battery life constraints and limited clinical-grade accuracy remain key challenges.
Emerging and Value-Focused Players (e.g., Xiaomi Corporation, Amazfit (Zepp Health), Polar Electro, WHOOP Inc., Withings)
- Focus on affordable or specialized wearable solutions with advanced sleep tracking, recovery analysis, AI-driven coaching, and subscription-based health insights. Emphasize innovation in sensor technology, long battery life, and expansion into emerging markets and niche fitness segments.
- Competitive pricing, rapid product innovation, specialized sleep and recovery analytics, longer battery life, and strong appeal among fitness enthusiasts and price-sensitive consumers. Ability to quickly adopt new AI-enabled health features.
- Smaller global market presence compared to leading brands, limited ecosystem integration, lower marketing reach, and greater reliance on third-party platforms or subscription revenues. Some brands have limited penetration in enterprise and healthcare applications.
Recent Developments
-
In June 2025, Garmin announced the plan to launch the Index Sleep Monitor this year. This upper arm, screenless sleep tracker with advanced sensors for sleep staging, SpO₂, heart rate, and HRV will reinforce Garmin's commitment to precision health tracking and wearable innovation.
-
In January 2025, Samsung expanded the Galaxy Ring offering by introducing two larger sizes (14 and 15) and rolling out new Samsung Health sleep features, Sleep Environment Report, Sleep Time Guidance, and a Mindfulness Tracker, reinforcing its focus on sleep wellness innovation.
-
In September 2024, Apple introduced a health feature, enabling sleep apnea notifications via the Watch’s new Breathing Disturbances metric and transforming AirPods Pro 2 into an all-in-one hearing health solution, including hearing tests, active protection, and over‑the‑counter hearing aid support.
-
In February 2024, Samsung launched the Galaxy Ring in Spain at Mobile World Congress, showcasing its inaugural smart ring. It featured continuous sleep, heart‑rate, and respiration monitoring alongside sensor‑driven biometric insights and integrated Samsung Health app support.
-
In September 2022, Google Cloud and Fitbit launched the "Device Connect for Fitbit" solution, enabling healthcare providers to securely access consenting patients' wearable data, such as sleep, heart rate, SpO₂, temperature, and activity, for enhanced remote monitoring, chronic disease management, and research.
Fitness Tracker for Sleep Monitoring Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.0 billion
Estimated market size in 2026
USD 8.3 billion
Projected market size by 2033
USD 23.1 billion
Growth rate
CAGR of 15.8% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Fitbit (Google); Garmin Ltd.; Apple Inc.; Samsung Electronics Co., Ltd.; Xiaomi Corporation; Huawei Technologies Co., Ltd.; Withings (Nokia Health); Amazfit (Zepp Health / Huami); Polar Electro; WHOOP Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fitness Tracker For Sleep Monitoring Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fitness tracker for sleep monitoring market report based on type, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Smart Watches
-
Smart Bands
-
Smart Clothing
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online
-
Offline
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The fitness tracker fFor sleep monitoring market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each fitness tracker fFor sleep monitoring segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Smart Watches
Wrist-worn wearable devices that combine fitness tracking, sleep monitoring, health sensors, and smartphone connectivity to provide comprehensive health and lifestyle insights.
Smart Bands
Lightweight wearable fitness bands are designed primarily to monitor physical activity, sleep patterns, heart rate, and other basic health metrics.
Smart Clothing
Apparel embedded with sensors and smart textiles that continuously monitor physiological parameters, including sleep, movement, respiration, and body temperature.
Others
Includes other wearable sleep monitoring devices such as smart rings, sleep-tracking patches, smart earbuds, and clip-on wearable sensors.
Segment - Distribution Channel
Revenue capture definition
Online
Sales of fitness trackers through e-commerce platforms, brand-owned websites, online marketplaces, and digital retail channels.
Offline
Sales through physical retail outlets, including electronics stores, specialty fitness stores, supermarkets, department stores, and authorized brand retailers.
Estimation Model
Section
Key Summary
1.1 Research Approach
Hybrid study using secondary and primary research. Market estimated through wearable device shipments, sleep monitoring adoption rates, consumer health awareness, pricing trends, and technological advancements. Inputs from wearable manufacturers, distributors, retailers, healthcare professionals, and industry experts validate findings.
1.2 Market Estimation Framework
Uses three models: (1) wearable adoption and shipment model, (2) average selling price (ASP)-based revenue model, and (3) vendor revenue validation model to triangulate total market size.
1.2.1 Demand Model
Estimates demand for fitness trackers with sleep monitoring based on wearable device shipments, consumer adoption of sleep-tracking features, prevalence of sleep disorders, health awareness, replacement cycles, and regional penetration of wearable technology.
1.2.2 ASP Model
Market value derived from the average selling price (ASP) of smartwatches, smart bands, smart clothing, and other wearable devices with sleep monitoring capabilities, considering product category, feature set, brand positioning, and regional pricing variations.
1.2.3 Vendor Model
Cross-validates market size using revenues of key fitness tracker manufacturers, shipment volumes, product portfolios, regional sales performance, and annual financial reports of leading wearable technology companies.
1.3 Forecast Development
Based on increasing prevalence of sleep disorders, rising health and wellness awareness, growing wearable adoption, advancements in AI-powered sleep analytics, sensor technologies, digital health integration, and expanding preventive healthcare initiatives.
1.4 Segmentation Method
Weighted index based on wearable adoption rates, product innovation, consumer spending patterns, sleep monitoring feature penetration, distribution channel performance, and regional digital health maturity.
1.5 Scope & Assumptions
Market measured in USD based on revenues generated from fitness trackers equipped with sleep monitoring capabilities, including smartwatches, smart bands, smart clothing, and other wearables. Estimates incorporate blended ASPs, shipment volumes, replacement rates, online and offline sales channels, and regional variations in consumer adoption and pricing.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client request
Customization delivered
Value adds
Sleep Health & Consumer Adoption Analysis
Developed a comprehensive assessment of global sleep health trends, prevalence of sleep disorders, wearable adoption, consumer behavior, and demand for sleep monitoring technologies across different age groups and regions. The study evaluated sleep-related disease burden, lifestyle patterns, and penetration of fitness trackers for sleep monitoring.
Enables stakeholders to identify high-growth consumer segments, assess market demand, optimize product positioning, and prioritize investments in regions with rising adoption of sleep monitoring wearables.
Wearable Technology & User Journey Analysis
Conducted an end-to-end assessment of the user journey, including device selection, onboarding, sleep tracking usage, AI-powered sleep coaching, mobile application engagement, subscription services, and long-term device retention. The study also evaluated consumer preferences, pricing trends, and distribution channels.
Provides actionable insights for improving user engagement, increasing customer retention, optimizing pricing and go-to-market strategies, and enhancing the overall consumer experience.
Advanced Sleep Monitoring & Technology Assessment
Conducted an in-depth evaluation of emerging wearable technologies, including AI-powered sleep analytics, advanced biosensors, SpO₂ monitoring, heart rate variability (HRV), skin temperature sensing, and cloud-based health platforms. The study benchmarked product innovations, regulatory developments, and competitive positioning across leading market participants.
Helps stakeholders identify innovation opportunities, accelerate product development, strengthen competitive differentiation, and capitalize on emerging trends in AI-enabled sleep monitoring and digital health ecosystems.
Frequently Asked Questions About This Report
The global fitness tracker for sleep monitoring market size was estimated at USD 7.0 billion in 2025 and is expected to reach USD 8.3 billion in 2026.
The global fitness tracker for sleep monitoring market is expected to grow at a compound annual growth rate of 15.8% from 2026 to 2033 to reach USD 23.1 billion by 2033.
Some key players in the market are Fitbit (Google); Garmin Ltd.; Apple Inc.; Samsung Electronics Co., Ltd.; Xiaomi Corporation; Huawei Technologies Co., Ltd.; Withings (Nokia Health); Amazfit (Zepp Health / Huami); Polar Electro; WHOOP Inc.
The market is driven by factors such as shifting lifestyles that emphasize wellness, the growing focus on preventive healthcare, and increasing health consciousness among consumers.
North America dominated with a 44.2% revenue share in 2025 owing to the high prevalence of sleep disorders, widespread adoption of wearable health technologies, strong consumer health awareness, and increasing focus on preventive healthcare and digital wellness.
Asia Pacific is the fastest-growing region over the forecast period owing to the rising prevalence of sleep disorders, increasing adoption of wearable devices, expanding smartphone penetration, growing health awareness, and rising disposable incomes across emerging economies.
The online segment led with a 65.3% revenue share in 2025, and is the fastest-growing segment.
The smart watch segment dominated the market and held the largest revenue share of 47.9% in 2025. The dominance is attributed to the widespread adoption of smartwatches due to their multi-functionality, combining sleep monitoring, fitness tracking, heart rate analysis, and smartphone connectivity in a single device, while smart bands is the fastest growing segment.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


