
- Home
- »
- Consumer F&B
- »
-
Food Colors Market Size & Share Report, 2026-2033GVR Report cover

Food Colors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Natural, Synthetic, Nature-Identical, Caramel), By Form (Powder, Liquid, Gel & Paste), By Source (Plants, Microbes), By Application, By Region, And Segment Forecasts
Market Size, 2025
$3.5BMarket Estimate, 2026
$3.7BMarket Forecast, 2033
$5.9BCAGR, 2026–2033
5.9%Food Colors Market Summary
The global food colors market size was valued at USD 3.5 billion in 2025 and is projected to grow from USD 3.7 billion in 2026 to USD 5.9 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 31.6% in 2025. The market in Europe dominated with a revenue share of 29.9% in 2025. Market growth is primarily driven by increasing demand for visually appealing food products across the bakery, confectionery, beverages, and dairy categories.
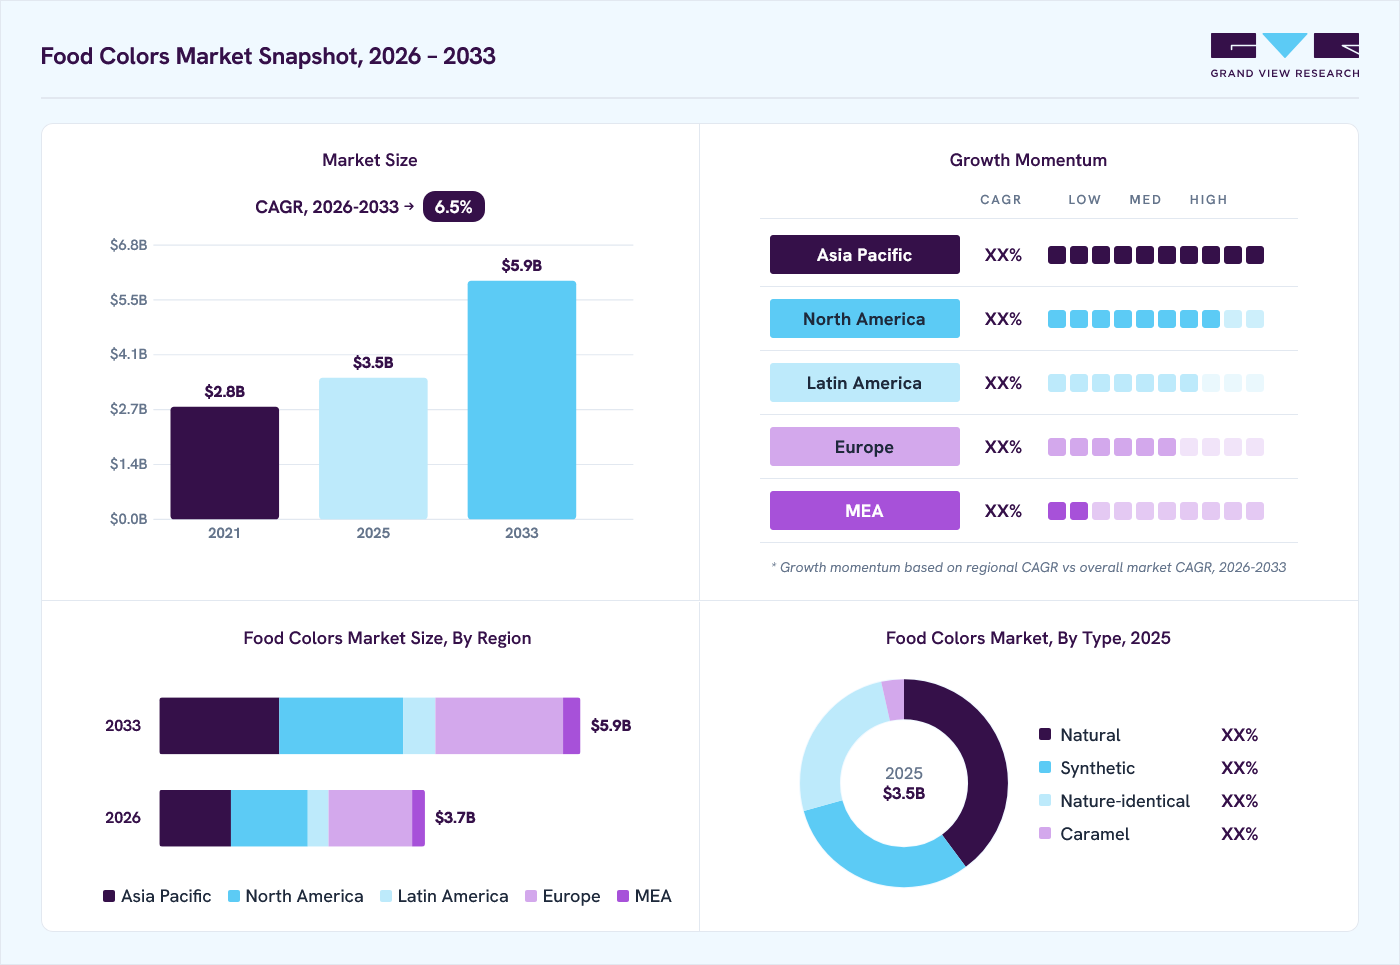 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Natural segment held a dominant position, with a value share of 39.8% in 2025.
- By form: Powder segment held a dominant position, contributing 51.6% of total revenue in 2025.
- By source: Plant, animal, & insect segment held the largest revenue share of 60.2% in 2025.
- By application: Dairy & frozen treats dominated the market with a revenue share of 29.4% in 2025.
Regional Highlights
- Largest regional market: Europe (31.6% revenue share, 2025)
- By country: The Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.5 Billion
- Estimated market size in 2026: USD 3.7 Billion
- Projected market size by 2033: USD 5.9 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Color plays a critical role in shaping consumer perceptions and purchasing decisions, particularly in packaged foods, where visual differentiation is essential. Food manufacturers are therefore incorporating advanced coloring solutions to enhance product appearance and maintain brand consistency.
The rising consumer preference for clean-label and natural ingredients. As awareness of health and wellness continues to grow, consumers are increasingly avoiding artificial additives and seeking products formulated with plant-based or naturally derived colors. This trend has encouraged manufacturers to invest in natural pigments such as carotenoids, anthocyanins, and chlorophyll extracted from fruits, vegetables, and botanical sources
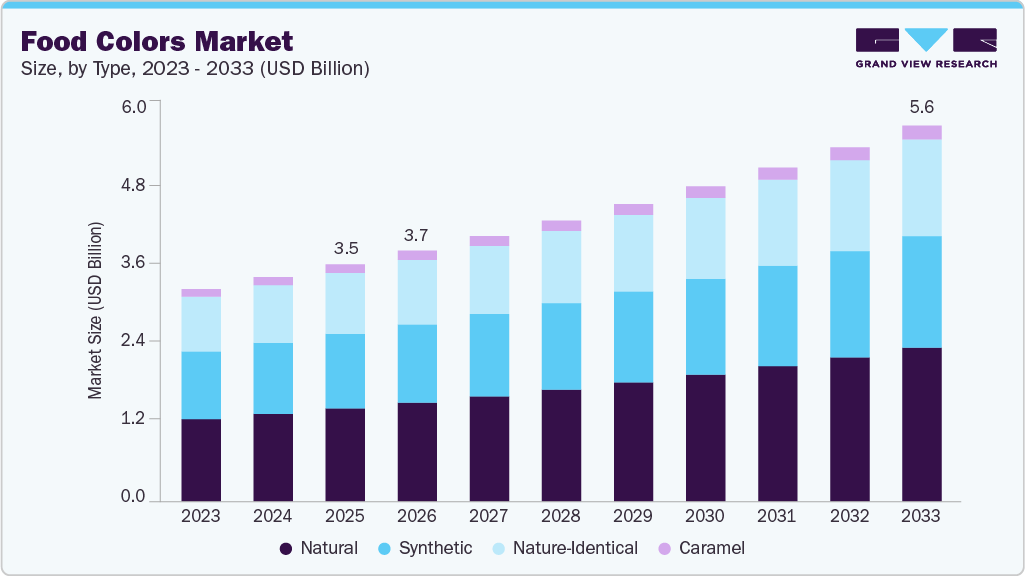 To learn more about this report, Download Free Sample Report
The expansion of the global processed food and beverage industry is supporting steady demand for food colors. Rapid urbanization, changing dietary patterns, and increasing consumption of convenience foods are driving product innovation in packaged food categories. Food colors enable manufacturers to maintain product stability and aesthetic appeal during processing, storage, and transportation, further strengthening their role in modern food formulations.
Market Dynamics
The food colors market is expanding as food manufacturers increasingly focus on enhancing product appearance while meeting evolving consumer preferences for clean-label, naturally sourced ingredients. Rising demand for visually appealing packaged foods, beverages, bakery products, dairy items, and plant-based alternatives has encouraged manufacturers to expand their portfolios with stable and application-specific color solutions. At the same time, stringent food safety regulations and labeling requirements are accelerating innovation in natural, nature-identical, and low-impact coloring technologies. Companies are investing in advanced extraction methods, fermentation processes, and formulation capabilities to improve color stability, heat resistance, and shelf life without compromising product quality. Emerging economies are contributing to market expansion through increasing consumption of processed and convenience foods, supported by urbanization and rising disposable incomes. The ongoing product innovation, strategic partnerships, and sustainability initiatives are reshaping competitive dynamics, enabling manufacturers to differentiate their offerings and address the growing demand for safe, high-performance, and environmentally responsible food coloring solutions across diverse applications.
The increasing consumer preference for clean-label food products is a primary driver of the food colors market. Consumers are becoming more conscious of ingredient transparency and are actively seeking products formulated with recognizable, naturally derived ingredients. This shift has encouraged food and beverage manufacturers to replace synthetic colorants with plant-based, microbial, and other naturally sourced alternatives that align with clean-label positioning. The trend is particularly evident across bakery, confectionery, dairy, beverages, and plant-based food categories, where visual appeal remains a critical purchasing factor while ingredient authenticity has become equally important. As a result, manufacturers are investing in advanced extraction technologies and formulation capabilities to deliver natural colors with improved stability, consistency, and application performance.
The transition toward natural food colors is also being reinforced by retailers and global food brands that are reformulating product portfolios to meet evolving consumer expectations and strengthen brand credibility. Companies are expanding research and development efforts to improve the heat, light, and pH stability of natural pigments, enabling their use across a broader range of processed foods and beverages. This ongoing innovation is creating long-term demand for premium coloring solutions, encouraging strategic collaborations between ingredient suppliers and food manufacturers.
The restraints affecting the food colors market is the relatively high production cost and performance limitations associated with natural food colors. Natural pigments are typically extracted from fruits, vegetables, spices, algae, and microorganisms, making their production more resource-intensive than synthetic alternatives. Seasonal variations in raw material availability, agricultural dependency, lower extraction yields, and extensive purification requirements contribute to higher manufacturing costs. Many natural colorants exhibit reduced stability when exposed to heat, light, oxygen, or varying pH conditions, making it difficult for manufacturers to maintain consistent product appearance throughout processing and shelf life. These technical challenges often require additional formulation expertise, encapsulation technologies, or stabilizing ingredients, increasing overall production expenses. For price-sensitive food manufacturers, particularly in emerging markets, these higher costs can limit the adoption of natural colors despite growing consumer demand, thereby slowing market penetration and creating operational challenges for both suppliers and end users.
The rapid expansion of plant-based foods and functional beverages presents a significant growth opportunity for the food colors market. Consumers increasingly associate these products with health, wellness, and sustainability, creating demand for color solutions that complement natural ingredient positioning. Manufacturers of plant-based meat alternatives, dairy substitutes, fortified beverages, and nutritional products require specialized food colors that replicate the visual characteristics of conventional foods while maintaining clean-label compliance. This has accelerated the development of innovative natural pigments capable of delivering enhanced color intensity, stability, and processing performance across diverse formulations.
The growing popularity of premium, organic, and fortified food products is encouraging ingredient suppliers to develop customized coloring solutions tailored to specific applications. Advances in biotechnology, precision fermentation, and botanical extraction are enabling manufacturers to produce more stable and sustainable natural pigments with improved scalability. These technological developments, combined with rising investments in product innovation and strategic partnerships between ingredient suppliers and food manufacturers, are creating new commercial opportunities across developed and emerging markets. As consumer demand for healthier and visually appealing products continues to grow, the expansion of plant-based and functional food categories is expected to generate substantial long-term opportunities for the global food colors market.
Market Concentration & Characteristics
The global food colors industry is moderately consolidated, with a few multinational ingredient manufacturers dominating global supply, alongside several regional producers specializing in natural pigments. Leading companies maintain strong market positions through extensive product portfolios, proprietary extraction technologies, and well-established distribution networks across the food and beverage industries. Large ingredient suppliers also benefit from long-term partnerships with food manufacturers, enabling consistent demand and product innovation.
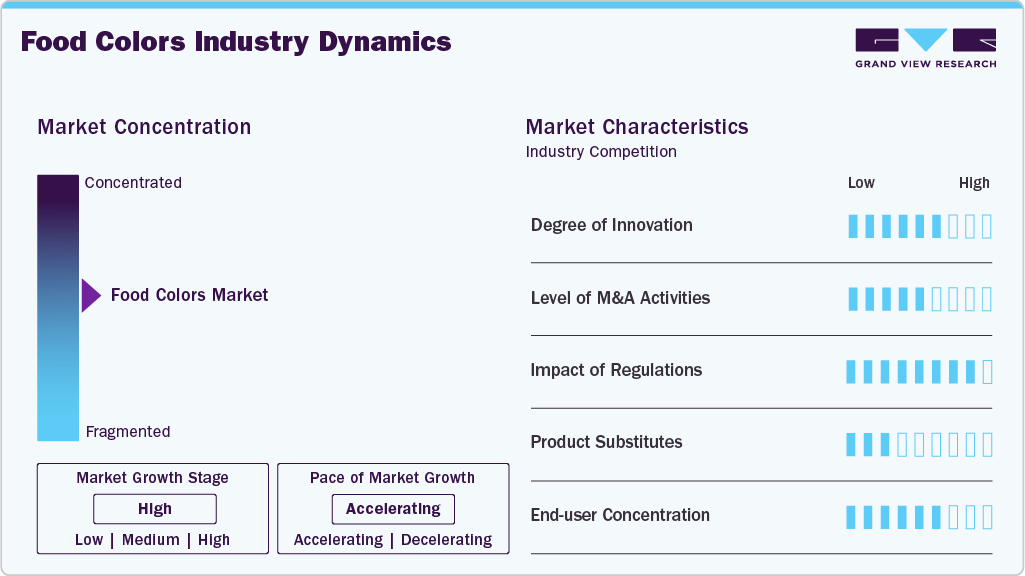 To learn more about this report, Download Free Sample Report
Competitive intensity within the food color industry is driven by increasing investments in research and development, particularly for natural and plant-based coloring solutions. Companies are focusing on developing stable natural color formulations that can withstand heat, pH variations, and light exposure during food processing. Strategic acquisitions, collaborations with food manufacturers, and expansion of production capacities are also common strategies used to strengthen global presence and capture emerging market opportunities
Analyst Perspective
The food colors market is undergoing a structural shift as consumer demand moves from synthetic additives toward clean-label and naturally sourced color solutions. While natural colors are becoming the preferred choice, improving their stability, consistency, and cost-effectiveness remains a key focus for manufacturers. Innovation in plant-based extraction, fermentation, and formulation technologies is expected to reshape the competitive landscape over the coming years. Companies that can balance regulatory compliance, sustainability, and application performance will be better positioned to capture premium opportunities. Emerging food categories, particularly plant-based foods, functional beverages, and premium packaged products, are expected to remain the primary engines of long-term market growth.
Product Insights
Based on product, natural segment held a dominant position, with a value share 39.8% in 2025. This growth is due to the strong shift toward clean-label and plant-derived ingredients. Consumers increasingly prefer natural colors extracted from fruits, vegetables, and botanical sources as alternatives to synthetic additives. Regulatory pressures and labeling transparency requirements in several regions have also encouraged food manufacturers to reformulate products using natural color solutions. As a result, natural systems have gained widespread adoption across beverage, confectionery, and dairy applications.
The caramel segment is expected to grow at a significant CAGR of 6.2% during the forecast period. This is due to its widespread use in beverages, bakery, and savory food applications. Caramel color is valued for its stability, versatility, and cost-effectiveness compared to many natural pigments. It is commonly used in carbonated soft drinks, sauces, confectionery products, and baked goods. The growing demand for dark-colored beverages and processed foods continues to support the expansion of this segment
Form Insights
In 2025, powder segment by form, held a dominant position, contributing 51.6% total revenue. The growth is primarily driven by its longer shelf life and ease of storage compared to liquid forms. Powdered food colors offer better stability and are widely used in dry food formulations such as bakery premixes, confectionery coatings, and snack seasonings. They are also easier to transport and handle in large-scale manufacturing environments. These advantages have made powder-based formulations the preferred choice for many food processors.
The liquid segment is expected to grow at the fastest CAGR of 6.2% during the forecast period, due to its convenience in beverage and dairy applications. Liquid colors offer superior dispersion and uniform mixing, making them suitable for ready-to-drink beverages, syrups, and liquid food products. They also allow manufacturers to achieve precise color intensity during production. Increasing demand for colored beverages and functional drinks is supporting segment growth.
Source Insights
In terms of source, plant, animal, & insect held largest revenue share of 60.2% of total market in 2025. driven by growing consumer demand for natural and plant-derived ingredients. Colors extracted from sources such as beetroot, turmeric, paprika, spirulina, and berries are increasingly used as alternatives to synthetic dyes. Plant-based pigments align with clean-label trends and regulatory preferences for naturally derived food additives. Their compatibility with organic and vegan food products further supports market leadership.
The microbes segment is expected to grow at a significant CAGR of 5.4% during the forecast period, as biotype advances enable the production of stable natural pigments through microbial fermentation. Microbial pigments offer advantages such as controlled production conditions and consistent quality. They also reduce dependence on agricultural raw materials, which are subject to seasonal variability. Increasing research in fermentation-based color production is expected to expand this segment.
Application Insights
By application, dairy & frozen treats dominated with a revenue share of 29.4% in 2025. due to the extensive use of colors in cakes, pastries, candies, and decorative toppings. Visual appeal is a critical factor influencing consumer purchase decisions in these product categories. Manufacturers use food colors to enhance product aesthetics and differentiate flavors. The popularity of premium confectionery and artisanal bakery products further supports segment demand.
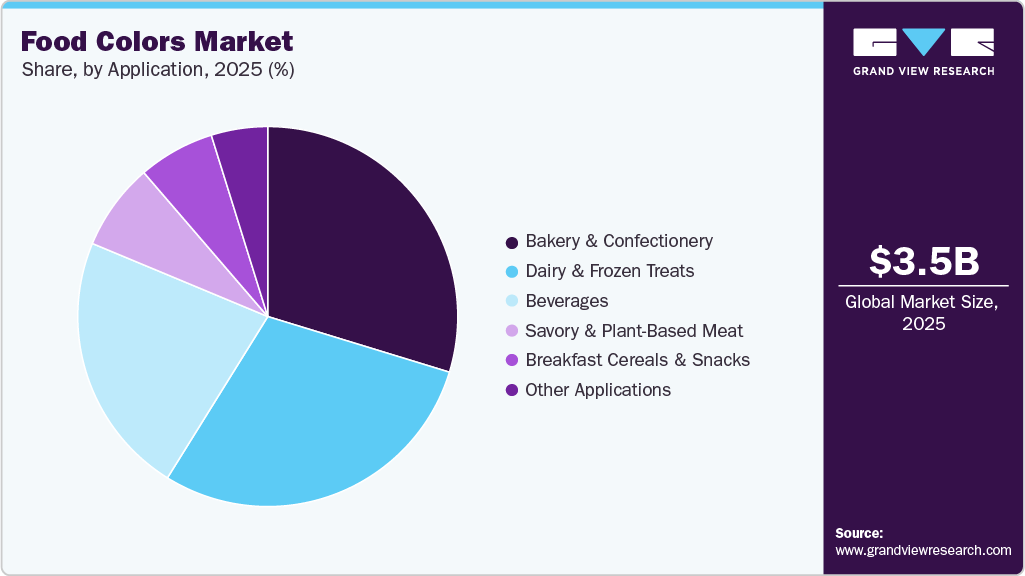 To learn more about this report, Download Free Sample Report
The dairy & frozen treats segment is expected to grow at a significant CAGR of 6.3% during the forecast period. Increasing consumption of flavored yogurts, ice creams, and frozen desserts is driving the demand for natural and vibrant colors. Food manufacturers are incorporating fruit-derived pigments to enhance product appeal while maintaining clean-label positioning. Rising innovation in premium dairy products is further accelerating segment growth.
Regional Insights
The food colors market in North America is driven by high consumption of processed foods and beverages. Food manufacturers in the U.S. and Canada are actively reformulating products to meet clean-label requirements. Rising demand for natural and organic food products is encouraging the use of plant-based food colors. Innovation in functional beverages and premium confectionery also supports market growth.
U.S. Food Colors Market Trends
The food colors market in the U.S. held a significant share in North America in 2025, due to its well-developed food processing industry. Rising consumer demand for natural and organic food ingredients has encouraged manufacturers to shift toward plant-based color solutions. Strong innovation in beverages, snacks, and confectionery continues to drive market growth.
Europe Food Colors Market Trends
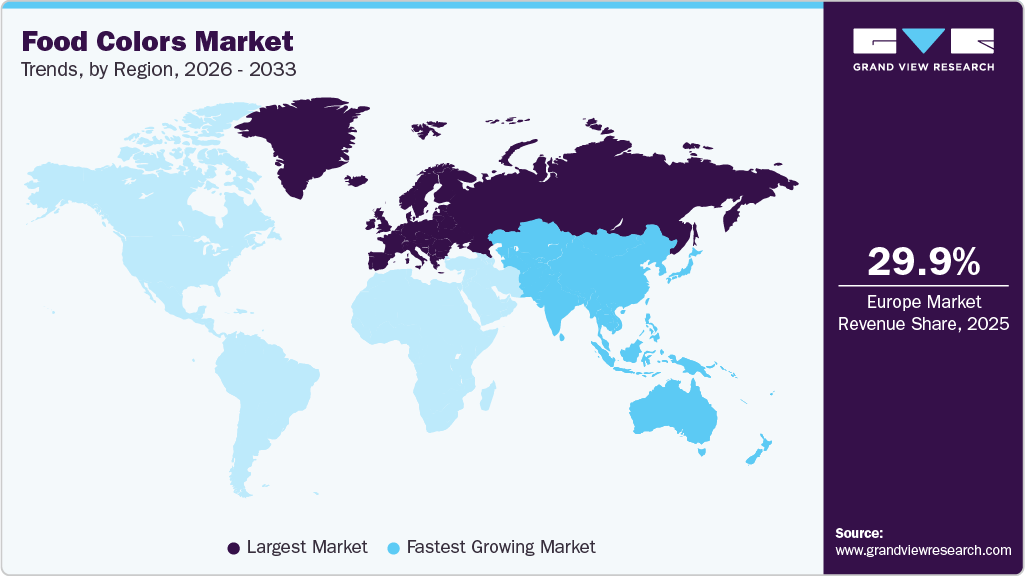
Europe dominated the food colors market with the highest revenue share of 31.6% in 2025. The growth is supported by strict regulations regarding synthetic additives and strong consumer demand for natural ingredients. The region has a well-established food processing industry that increasingly relies on natural color solutions. Growing adoption of plant-based and organic foods further drives demand for natural food colors across European markets.
 To learn more about this report, Download Free Sample Report
Germany dominated the Europe food colors market in 2025. supported by strong regulatory frameworks and consumer preference for natural ingredients. The country’s well-established food manufacturing sector continues to adopt natural color solutions in bakery, dairy, and beverage products. Innovation in clean-label and organic food products further supports market growth.
Asia Pacific Food Colors Market Trends
The food colors market in the Asia Pacific is expected to grow at the fastest CAGR during the forecast period, due to expanding food processing industries and increasing disposable incomes. Countries such as China, India, and Japan are witnessing rising demand for packaged foods and beverages. The region’s large population and changing dietary habits are driving increased consumption of food color across multiple food categories.
The China food colors market held a significant share in the Asia Pacific in 2025, driven by rapid industrialization and increasing consumption of processed foods. The country’s expanding beverage and confectionery industries are major contributors to food color demand. Government regulations and rising consumer awareness are also driving the use of natural colorants.
Latin America Food Colors Market Trends
The food colors market in Latin America is emerging, with growth supported by expanding bakery and beverage industries. Brazil and Mexico represent key markets due to their strong food manufacturing sectors. Increasing urbanization and growing demand for convenience foods are encouraging the adoption of food coloring ingredients.
Middle East and Africa Food Colors Market Trends
The food colors market in the Middle East & Africa is experiencing gradual growth, driven by rising demand for processed and packaged foods. Expanding retail sectors and increasing consumption of confectionery and beverages support market expansion. In addition, the tourism and hospitality industries drive demand for visually appealing food products.
Key Food Colors Company Insights
Naturex, Roha Dye Chem Pvt. Ltd., Chr. Hansen, Sensient Technologies Ltd., Doehler, and Diana Naturals are the key players in the global food colors market. These companies have a global presence with manufacturing facilities and sales offices spread across the globe. Chr. Hansen and Naturex are the leading manufacturers and are highly active in the natural food colors industry. Naturex exclusively manufactures products derived from natural sources, which include natural ingredients, dietary supplements, and natural colors & flavors.
- BASF SE manufactures and distributes chemicals for a range of applications. The company operates 390 production sites across Europe, Asia, North America, Latin America, Africa, and Australia, producing industrial chemicals through seven business segments that cater to a wide consumer base. These segments include chemicals, performance products, plastics, functional materials & solutions, biotype, oil & gas exploration, and agricultural solutions. It has an employee base of over 100,000, of whom over 53,000 are based in Germany. BASF Polyurethane is a division of the company. It manufactures polyurethane for a variety of applications and offers a comprehensive polyurethane portfolio, including polyols, polyether, TDI, MDI, and specialty elastomers. The company is involved in the production of food colorants, which are supplied to the consumers through direct and third-party distribution networks, thereby making the company one of the notable forces in the food colors industry.
Key Food Colors Companies
The following key companies have been profiled for this study on the food colors market.
-
Cargill, Incorporated
-
Oterra
-
BASF SE
-
Danisco
-
DD Williamson
-
DSM
-
Naturex
-
FMC Corporation
-
ADM
-
Lycored Ltd.
-
GNT Group
-
SAN-EI GEN F.F.I. Inc.
-
Sensient Technologies Corporation
-
Roha Dye Chem Pvt. Ltd.
-
Symrise
-
Synthite Industries Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cargill Incorporated, Oterra, BASF SE, Danisco, DD Williamson, DSM, ADM, GNT Group, Sensient Technologies Corporation, Symrise, SAN-EI GEN F.F.I. Inc.)
- Invest heavily in R&D to develop clean-label, high-stability, and application-specific color solutions.
- Strengthen global manufacturing and distribution networks to ensure supply reliability and regulatory compliance.
- Expand portfolios through acquisitions, strategic partnerships, and integration across the food ingredients value chain.
- Focus on long-term contracts with multinational food and beverage companies while providing technical formulation support.
- Extensive global presence with diversified customer bases across multiple food and beverage categories.
- Broad product portfolios covering natural, synthetic, nature-identical, and specialty color solutions.
- Strong financial resources enabling continuous innovation, capacity expansion, and regulatory compliance.
- Established brand reputation supported by comprehensive technical service and application expertise.
- Large organizational structures can slow product development and response to changing consumer preferences.
- High operating and compliance costs associated with maintaining global production and regulatory standards.
- Dependence on complex international supply chains increases exposure to raw material and logistics disruptions.
- Premium pricing strategies may reduce competitiveness in highly price-sensitive markets.
Emerging Players (Naturex, FMC Corporation, Lycored Ltd., Roha Dye Chem Pvt. Ltd., Synthite Industries Ltd.)
- Focus on niche segments such as botanical extracts, regional color solutions, and customized formulations.
- Expand production capabilities to address growing demand for natural and sustainable food colors.
- Build partnerships with regional food manufacturers and distributors to increase market reach.
- Invest selectively in process optimization and fermentation or extraction technologies to enhance product competitiveness.
- Greater flexibility in developing customized products for specific customer requirements.
- Strong specialization in natural pigments, botanical ingredients, or region-specific raw materials.
- Faster decision-making and shorter product development cycles compared with larger competitors.
- Ability to capitalize on emerging clean-label and sustainable ingredient trends with focused product offerings.
- Limited global manufacturing footprint and distribution capabilities compared with industry leaders.
- Lower investment capacity for large-scale R&D, marketing, and international expansion.
- Greater reliance on regional markets and a narrower customer base, increasing business concentration risk.
- Smaller production volumes may limit economies of scale and reduce pricing competitiveness in large-volume contracts.
Recent Developments
-
In January 2025, ROHA introduced its next-generation natural food colors tailored for cream fillings and compound coatings in the confectionery sector, addressing the surging demand for clean-label and plant-based ingredients. Sourced from fruits, vegetables, flowers, and algae, these colors, offered under the NATRACOL brand, combine vibrancy, stability, and sensory appeal.
-
In February 2025, Oterra inaugurated a new color blending and application center in Kochi, Kerala, India, to serve the growing demand for natural colors in the Indian, Asia Pacific, and Middle East food and beverage markets.
-
In April 2025, DIC CORPORATION's U.S. subsidiary, Earthrise Nutritionals, inaugurated a state-of-the-art edible algae cultivation facility in California to support sustainable smart farming. The new plant, which produces Spirulina-derived LINABLUE, a natural blue colorant, reinforces DIC's expansion into eco-friendly, food-grade colorants using advanced technologies and renewable energy.
-
In June 2025, Oterra, formerly known as Chr. Hansen Natural Colors A/S announced its intention to acquire the natural food coloring division of Diana Food, a move that underscores its rapid growth in the global food colorant market. Diana Food is part of Symrise AG, a leading global supplier of ingredients for food, nutrition, cosmetics, and fragrances.
Food Colors Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.5 billion
Estimated market size in 2026
USD 3.7 billion
Projected market size by 2033
USD 5.9 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
product, form, source, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Spain; Italy; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia.
Key companies profiled
Cargill; Incorporated; Oterra; BASF SE; Danisco; DD Williamson; DSM; Naturex; FMC Corporation; ADM; Lycored Ltd.; GNT Group; SAN-EI GEN F.F.I. Inc.; Sensient Technologies Corporation; Roha Dye Chem Pvt. Ltd.; Symrise; Synthite Industries Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Food Colors Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global food colors market report based on type, product, application, and region.
-
Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Natural
-
Carotenoids
-
Anthocyanin
-
Annatto
-
Other Naturals
-
-
Synthetic
-
Tartrazine-E102
-
Sunset Yellow FCF-E110
-
Brilliant Blue FCF
-
Other Synthetic
-
-
Nature-Identical
-
Mixed Carotenes
-
Canthaxanthin
-
Riboflavin
-
Other Nature-Identical
-
-
Caramel
-
-
Form Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Powder
-
Liquid
-
Gel & Paste
-
-
Source Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Plants
-
Microbes
-
Petroleum, Other Minerals & Chemicals
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Bakery & Confectionery
-
Dairy & Frozen Treats
-
Breakfast Cereals & Snacks
-
Savory & Plant-Based Meat
-
Beverages
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The food colors market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each food colors segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product
Revenue capture definition
Natural
Market expansion is driven by rising demand for clean-label food products, increasing regulatory preference for naturally derived ingredients, and expanding adoption across premium beverages, dairy, bakery, and confectionery applications.
Synthetic
Commercial performance is sustained through widespread utilization in high-volume processed foods, confectionery, beverages, and snacks, where superior color consistency, processing stability, and cost efficiency support large-scale production.
Nature-Identical
Value creation is generated by manufacturers seeking a balance between natural positioning and functional performance, enabling reliable color delivery while meeting evolving formulation and labeling requirements.
Caramel
Business growth is supported by extensive use in carbonated beverages, sauces, bakery products, alcoholic drinks, and ready-to-eat foods, where distinctive brown shades and excellent heat stability enhance product appeal.
Segment – Form
Revenue capture definition
Powder
Income generation is strengthened by its extended shelf life, simplified storage, and compatibility with dry mixes, bakery premixes, confectionery, seasonings, and instant beverage formulations.
Liquid
Market momentum is fueled by increasing application in beverages, dairy products, syrups, and liquid food processing, where rapid dispersion and precise dosing improve manufacturing efficiency.
Gel & Paste
Sales growth is reinforced by expanding use in bakery decoration, confectionery fillings, icings, desserts, and specialty food products requiring concentrated pigmentation and controlled application.
Segment – Source
Revenue capture definition
Plant
Demand acceleration is driven by increasing extraction of pigments from fruits, vegetables, flowers, and spices to satisfy consumer preference for naturally sourced, clean-label food color solutions across diverse food categories.
Microbes
Industry value is strengthened through advancements in fermentation-based pigment production, enabling scalable manufacturing, consistent quality, and sustainable sourcing for next-generation natural food colors.
Petroleum
Economic contribution is maintained by continued demand for synthetic colorants in cost-sensitive food applications where high color intensity, formulation stability, and production efficiency remain key purchasing considerations.
Other Minerals & Chemicals
Profitability potential is reinforced by the use of mineral- and chemically derived coloring ingredients in specialized food formulations requiring enhanced processing performance, color durability, and compliance with application-specific standards.
Segment – Application
Revenue capture definition
Bakery & Confectionery
Market demand is propelled by the need for vibrant, heat-stable colors in cakes, pastries, candies, chocolates, and decorative toppings, enabling manufacturers to enhance product appeal and support premium product differentiation.
Dairy & Frozen Treats
Commercial value is reinforced by expanding use in flavored milk, yogurt, ice cream, frozen desserts, and dairy alternatives, where visually appealing formulations strengthen consumer preference and product innovation.
Breakfast Cereals & Snacks
Sales performance is accelerated by increasing incorporation into ready-to-eat cereals, cereal bars, chips, extruded snacks, and children's snack products, helping brands improve shelf visibility and strengthen product positioning.
Savory & Plant-Based Meat
Business momentum is driven by rising adoption in sauces, seasonings, meat substitutes, ready meals, and savory snacks, where authentic color development enhances product realism and overall consumer acceptance.
Beverages
Income potential is supported by extensive utilization in carbonated soft drinks, juices, energy drinks, flavored water, alcoholic beverages, and functional drinks, enabling manufacturers to create distinctive visual identities and reinforce brand recognition.
Other Applications
Growth prospects are strengthened by expanding usage in sauces, dressings, nutraceuticals, pet food, dietary supplements, and specialty food products, creating opportunities for customized color solutions across emerging food categories.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Raw Material & Production Layer
What forms the supply base?
Evaluate the production of food colors using naturally derived and synthetic feedstocks, including fruits, vegetables, spices, algae, microorganisms, petroleum-based intermediates, and mineral-derived compounds. Assess manufacturing technologies such as solvent extraction, fermentation, enzymatic processing, chemical synthesis, spray drying, encapsulation, and blending. The analysis also covers raw material procurement, pigment stabilization, quality assurance, production capacity, processing efficiency, regulatory compliance, and regional manufacturing hubs influencing the global supply landscape.
02
Application Adoption Layer
Where are food colors consumed?
Examine food color adoption across bakery & confectionery, dairy & frozen treats, breakfast cereals & snacks, savory & plant-based meat, beverages, and other processed food applications. Market expansion is supported by increasing demand for visually appealing products, clean-label formulations, premium food offerings, and differentiated product aesthetics that enhance consumer appeal and brand positioning.
03
Consumption Intensity Layer
How much food colors are utilized?
Analyze consumption trends by evaluating processed food production, beverage manufacturing volumes, bakery output, confectionery demand, dairy processing, product launches, and ingredient usage across major food categories. The assessment considers purchasing patterns of food manufacturers, beverage producers, ingredient formulators, contract manufacturers, and private-label brands to determine regional and global consumption intensity.
04
Revenue Layer
How is market revenue generated?
Market value is generated through the commercial supply of natural, synthetic, nature-identical, and caramel food colors to food and beverage manufacturers, ingredient processors, private-label producers, and foodservice operators. Industry expansion is supported by continuous product innovation, growing demand for clean-label ingredients, investments in sustainable color technologies, regulatory-driven product reformulation, strategic collaborations, and the increasing adoption of application-specific color solutions across global food and beverage industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study delivers detailed country-level analysis across major food colors production and consumption markets. It evaluates raw material availability, natural and synthetic color manufacturing technologies, production capacity, supply chain dynamics, import-export trends, pricing outlook, food safety regulations, consumer preference shifts, and downstream demand from bakery & confectionery, dairy & frozen treats, beverages, breakfast cereals & snacks, and savory & plant-based food applications.
Enables stakeholders to identify high-growth regional markets, evaluate manufacturing ecosystems, optimize sourcing strategies, understand regulatory requirements, and prioritize investments based on consumer demand, production capabilities, and supply chain resilience.
Competitive Benchmarking
The report provides a comprehensive benchmarking assessment of leading food color manufacturers, covering product portfolios, natural and synthetic color offerings, manufacturing capabilities, innovation pipelines, geographic presence, distribution networks, sustainability initiatives, quality certifications, operational excellence, and recent strategic developments.
Supports organizations in evaluating competitive positioning, identifying product portfolio strengths, benchmarking innovation initiatives, establishing strategic partnerships, and strengthening market differentiation through advanced color technologies and sustainable ingredient solutions.
Opportunity Assessment
The study evaluates emerging growth opportunities across clean-label formulations, plant-based pigments, fermentation-derived colorants, functional foods, premium beverages, natural ingredient innovation, and sustainable manufacturing technologies. It also examines opportunities arising from evolving consumer preferences, regulatory shifts, and advancements in extraction and formulation techniques.
Assists companies in identifying high-potential growth areas, aligning product development with evolving consumer expectations, accelerating innovation strategies, expanding application portfolios, and strengthening long-term competitiveness through differentiated and sustainable food color solutions.
Frequently Asked Questions About This Report
Market growth is primarily driven by increasing demand for visually appealing food products across the bakery, confectionery, beverages, and dairy categories.
The natural segment led with a 39.2% revenue share in 2025, and is the fastest-growing type.
The powder segment led with a 51.8% revenue share in 2025, while the liquid segment is the fastest-growing.
The plant segment led with a 59.4% revenue share in 2025, while the microbes segment is the fastest-growing.
Bakery & confectionery segment held the largest share (over 29.0%) in 2025, while the dairy & frozen treats segment is the fastest-growing.
The global food colors market size was valued at USD 3.5 billion in 2025 and is estimated at USD 3.7 billion for 2026.
The global food colors market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 5.6 billion by 2033.
Europe dominated with a 29.9% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Key players include Cargill; Incorporated; Oterra; BASF SE; Danisco; DD Williamson; DSM; Naturex; FMC Corporation; ADM; Lycored Ltd.; GNT Group; SAN-EI GEN F.F.I. Inc.; Sensient Technologies Corporation; Roha Dye Chem Pvt. Ltd.; Symrise; Synthite Industries Ltd.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


