
- Home
- »
- Pharmaceuticals
- »
-
General Anesthesia Drugs Market Size Report, 2026-2033GVR Report cover

General Anesthesia Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug (Propofol), By Route Of Administration (Intravenous), By End Use (Hospitals, Ambulatory Surgical Centers), By Application, By Region, And Segment Forecasts
Market Size, 2025
$5.5BMarket Estimate, 2026
$5.6BMarket Forecast, 2033
$7.2BCAGR, 2026–2033
3.6%General Anesthesia Drugs Market Summary
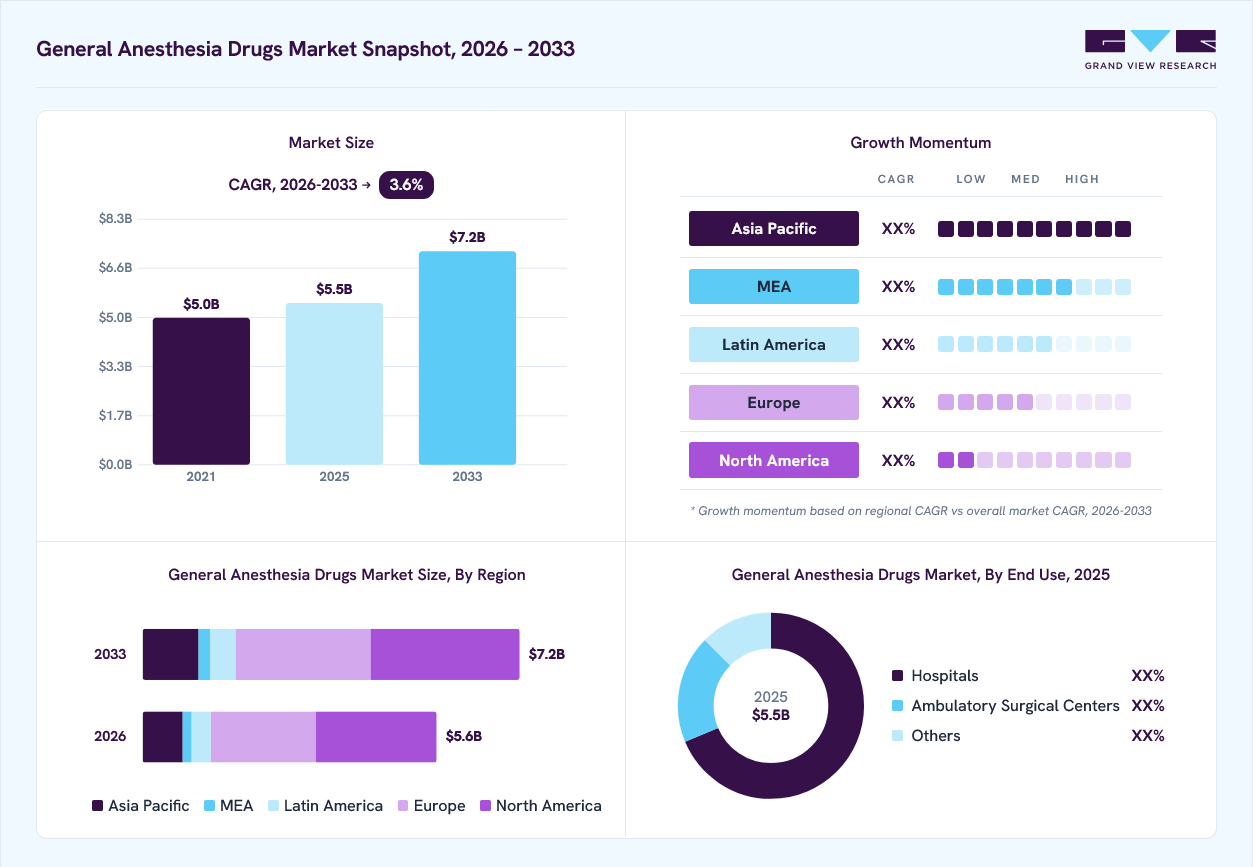
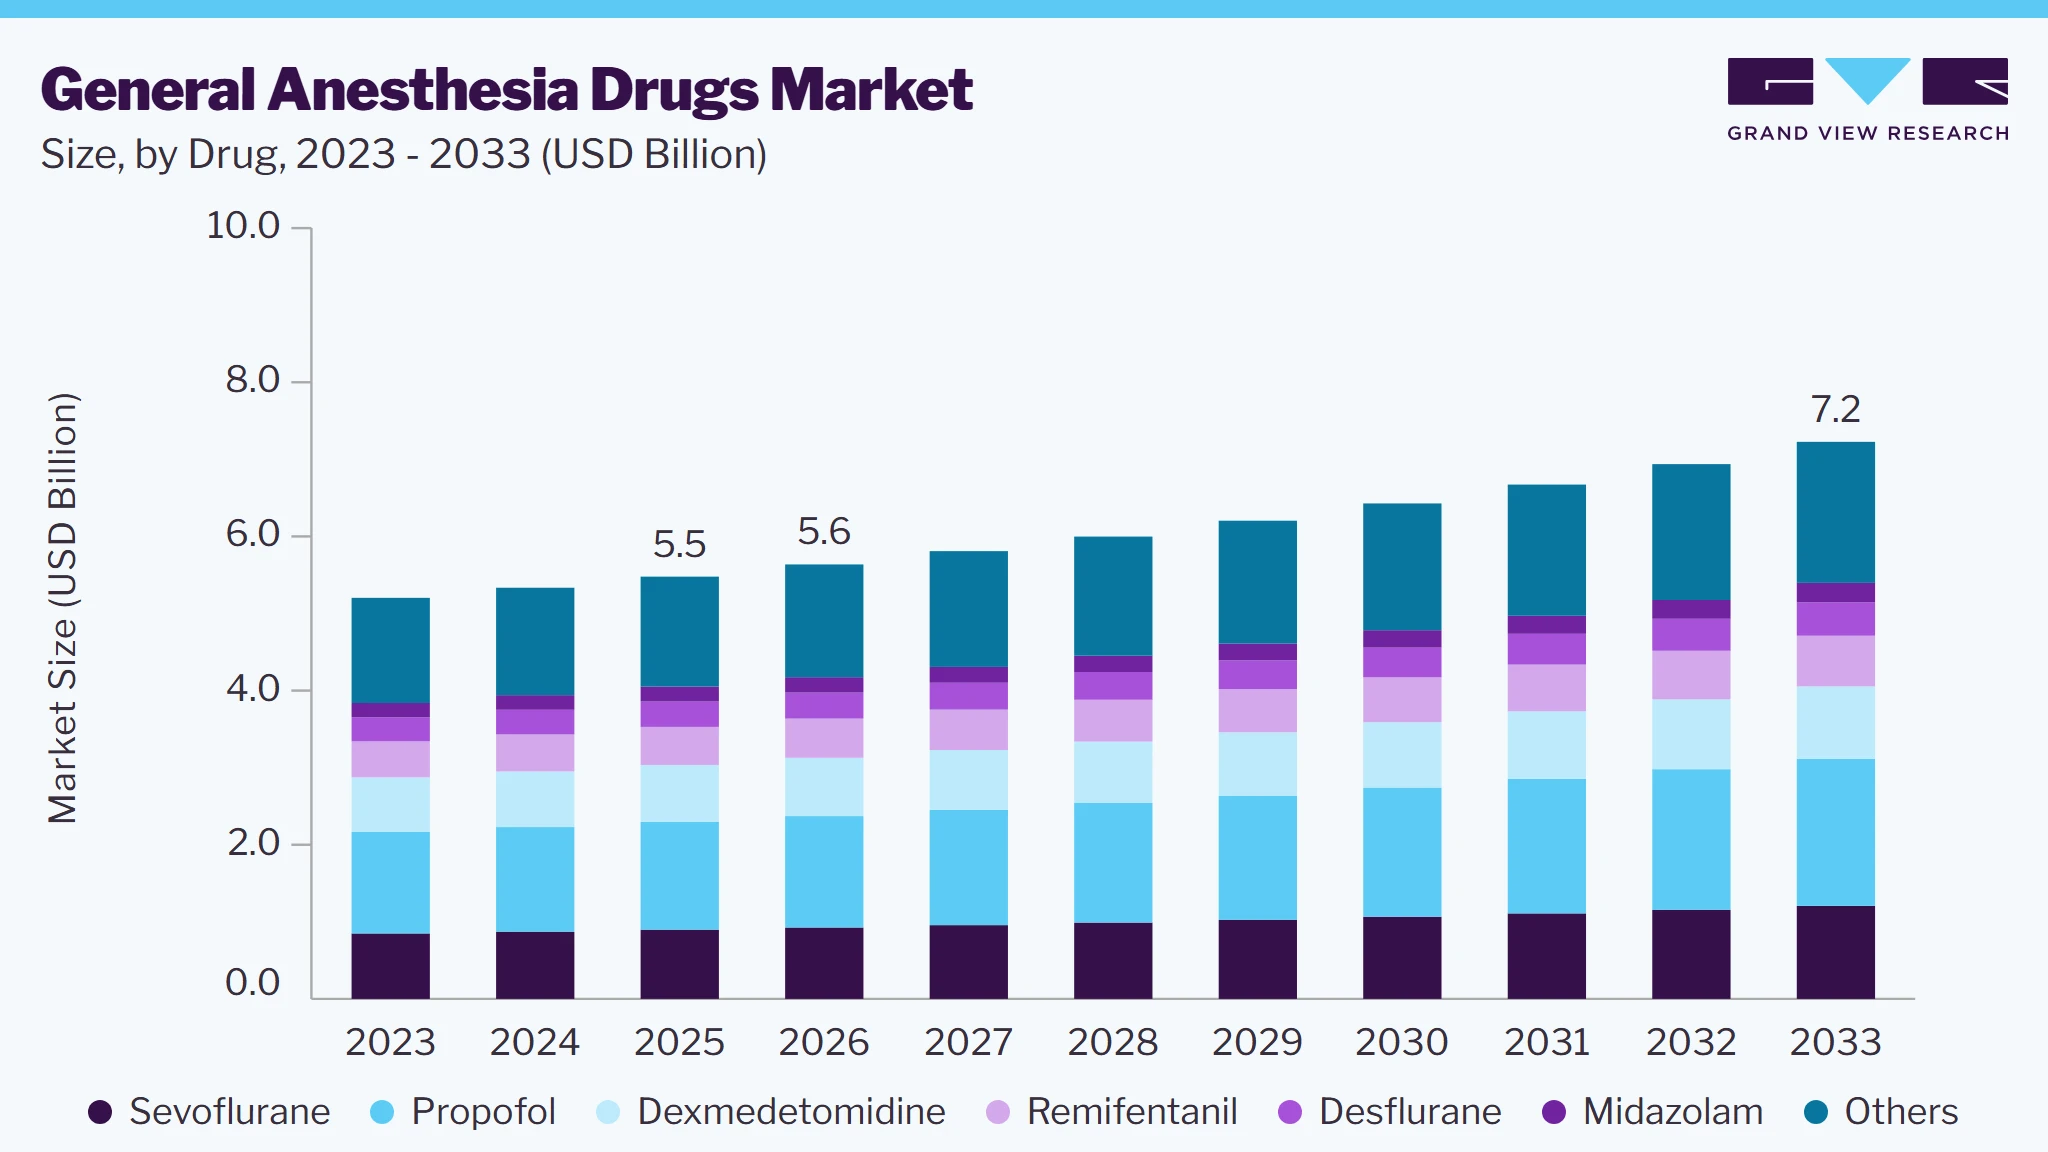
The global general anesthesia drugs market size was valued at USD 5.5 billion in 2025 and is projected to grow from USD 5.6 billion in 2026 to USD 7.2 billion by 2033, at a CAGR of 3.6% from 2026 to 2033. The market in North America dominated with a revenue share of 41.2% in 2025. This growth is primarily fueled by the increasing volume of surgical procedures, advancements in anesthesia technology, and the rising prevalence of chronic diseases.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug: Propofol segment held the largest market share of 25.5% in 2025.
- By route of administration: Intravenous segment held the largest market share of 64.1% in 2025.
- By end use: Hospitals segment held the largest market share of 68.6% in 2025.
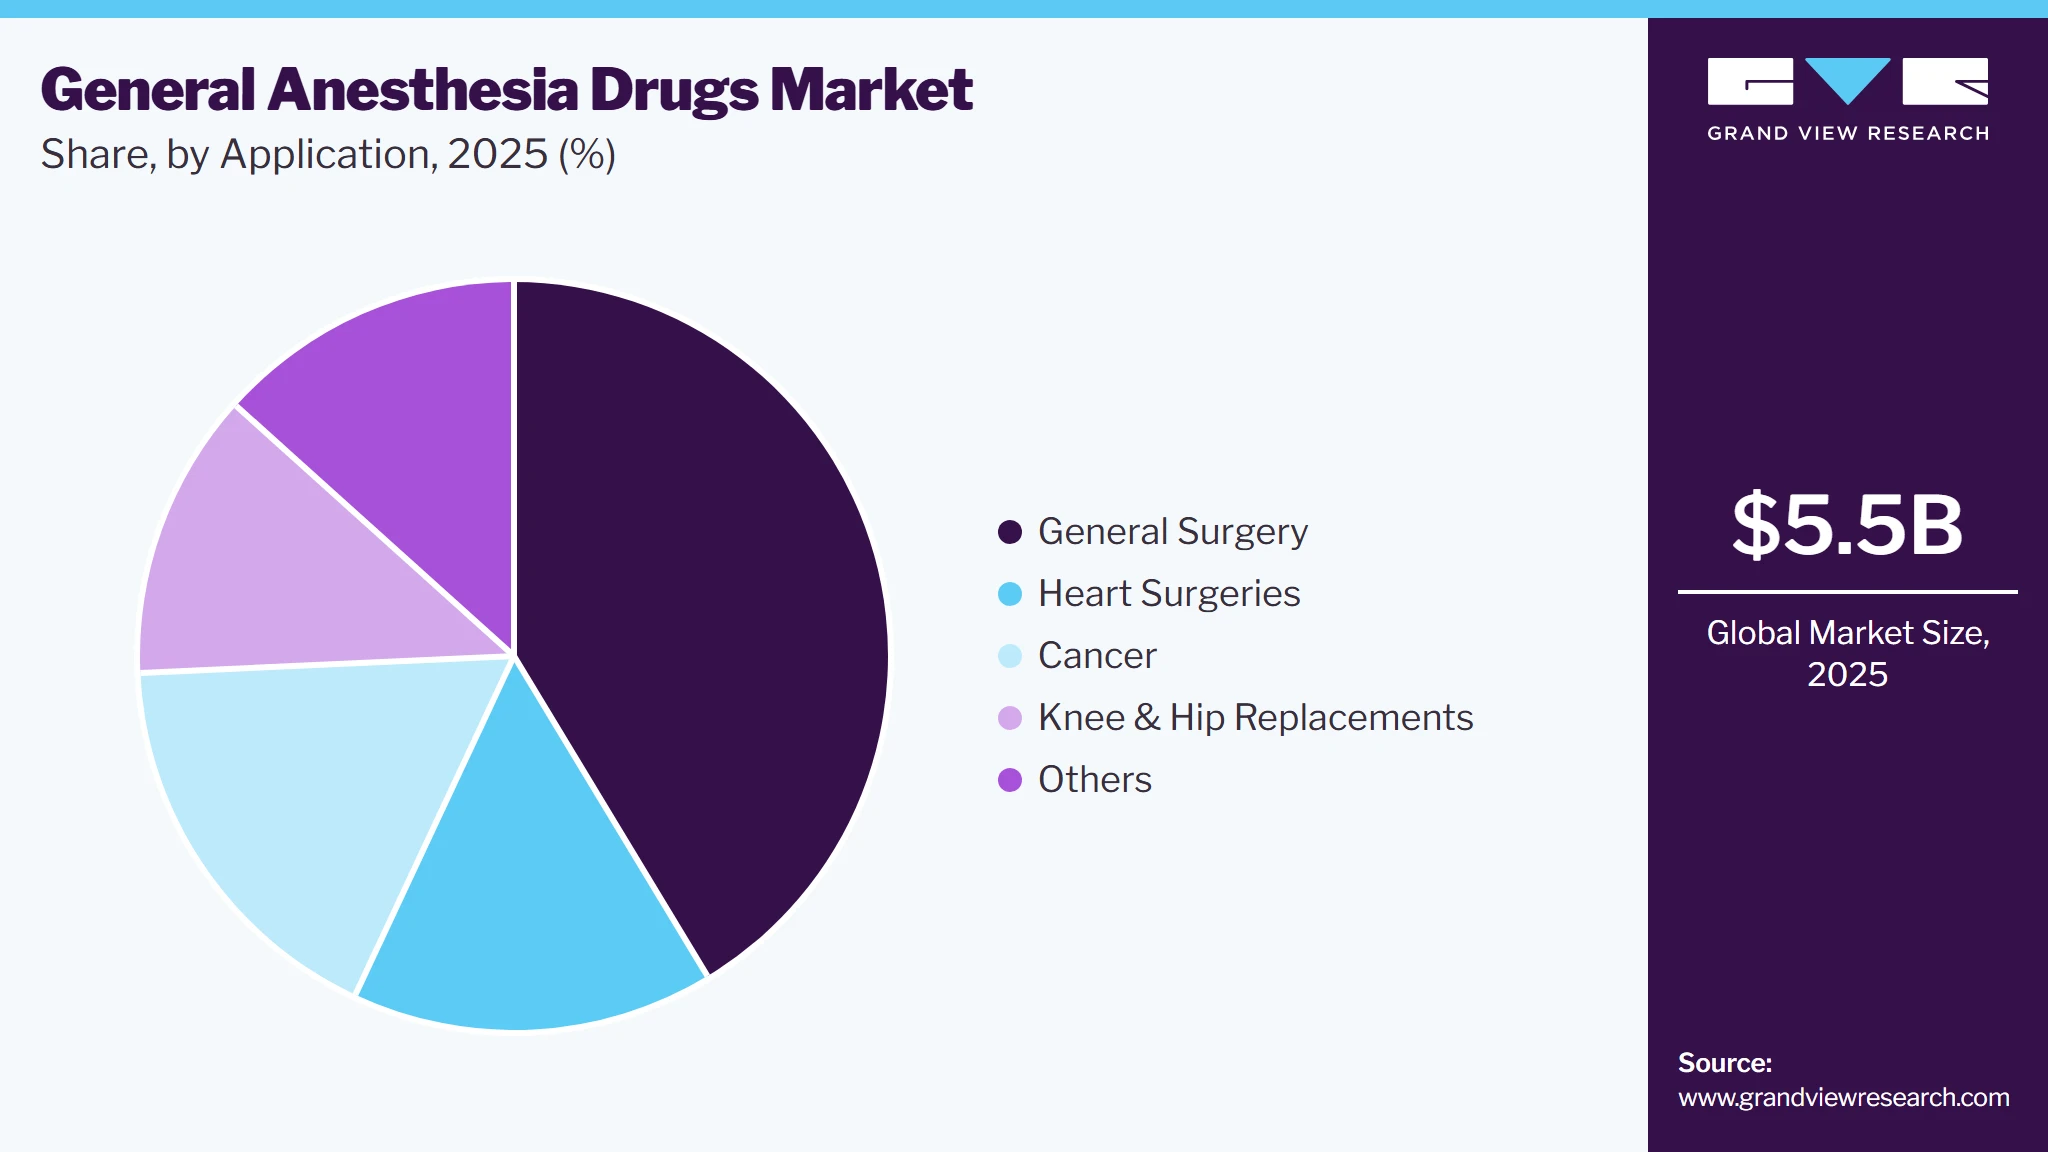
- By application: General surgery segment held the largest market share of 41.3% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.5 Billion
- Estimated market size in 2026: USD 5.6 Billion
- Projected market size by 2033: USD 7.2 Billion
- CAGR (2026-2033): 3.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As per the World Health Organization (WHO), the global surgical volume is rising due to increased incidence of chronic diseases and aging populations. The National Library of Medicine also estimates that over 313 million surgical procedures are conducted annually worldwide, underscoring the expanding demand for effective anesthesia solutions.A primary driver for market growth is the increasing prevalence of chronic diseases & surgical procedures. Chronic conditions such as CVD, cancer, and obesity are on the rise globally, leading to a higher volume of surgeries and medical interventions. For instance, cardiovascular diseases (CVDs) kill approximately 10,000 people in the WHO European Region every day. In addition, the American Cancer Society reports that nearly 2,001,140 new cancer cases are projected in 2024 in the U.S., highlighting a robust demand for surgical interventions and, consequently, anesthesia drugs.
 To learn more about this report, Download Free Sample Report
Furthermore, the aging population is a significant demographic factor driving the market's growth. With the aging population across the globe, there is an increasing need for medical procedures, many of which require anesthesia. According to WHO, the number of people aged 60 and older is expected to reach 2.1 billion by 2050, representing a substantial portion of the population that will require surgical interventions and anesthesia. The changing demographics highlight an increasing need for anesthesia medications and services designed with the elderly in mind.
Technological advancements in anesthesia delivery systems are also contributing to market growth. Innovations in anesthesia drugs and equipment have led to enhanced safety profiles, improved efficacy, and reduced side effects. For instance, the development of new anesthetic agents and delivery systems, such as target-controlled infusion systems and advanced monitoring devices, have revolutionized how anesthesia is administered and managed. For instance, in February 2024, Hikma Pharmaceuticals PLC launched Fentanyl Citrate Injection, USP, in the U.S. This medication is designed for short-duration analgesia during anesthesia, premedication, induction, maintenance, and immediate postoperative recovery. These advancements are supported by R&D efforts from major pharmaceutical companies and academic institutions, leading to the introduction of new products that meet the evolving needs of healthcare providers and patients.
The rise in outpatient and minimally invasive surgical procedures influences market dynamics. Advances in surgical techniques, such as laparoscopic and endoscopic procedures, often require different anesthesia approaches than traditional surgeries. The demand for short-acting and rapid-recovery anesthesia agents has increased, leading to innovations and growth in this market segment. Outpatient surgeries, which are less invasive and often performed under general anesthesia, are becoming more common, driving the need for effective and efficient anesthetic solutions.
Market Dynamics
The general anesthesia drugs market is supported by the steady increase in surgical procedures, growing demand for safe anesthetic agents, and continued improvements in perioperative care. Hospitals and ambulatory surgical centers are adopting anesthetic drugs that provide rapid induction, predictable recovery, and improved patient safety across different surgical specialties. The increasing number of elderly patients and the rising prevalence of chronic diseases requiring surgical intervention continue to support the use of general anesthesia drugs. At the same time, healthcare providers are focusing on balanced anesthesia approaches that combine intravenous and inhalation agents to improve clinical outcomes and optimize drug utilization. The market is also supported by ongoing product approvals, expanded manufacturing capacity, and efforts by pharmaceutical companies to strengthen the supply of essential anesthetic medicines. These developments help healthcare facilities maintain consistent access to general anesthesia drugs for both routine and complex surgical procedures.
The increasing number of elective, emergency, and minimally invasive surgical procedures is a major driver for the general anesthesia drugs market. Growth in orthopedic, cardiovascular, neurological, gastrointestinal, and oncological surgeries continues to support the demand for intravenous and inhalation anesthetic agents. The growing elderly population and the rising prevalence of chronic diseases have also increased the need for surgical interventions that require safe and effective anesthesia. Hospitals and ambulatory surgical centers are focusing on anesthetic drugs that provide rapid induction, stable hemodynamic control, and predictable recovery, helping improve surgical workflow and patient management. In addition, healthcare providers are maintaining adequate inventories of essential anesthesia medicines to reduce procedure delays and ensure uninterrupted patient care. Pharmaceutical companies are also expanding the availability of injectable anesthetics to support increasing procedural volumes. For instance, in April 2025, Avenacy announced the U.S. launch of Propofol Injectable Emulsion, USP following U.S. FDA approval. The product was introduced as a therapeutic generic equivalent to Diprivan and was made available in 200 mg per 20 mL, 500 mg per 50 mL, and 1,000 mg per 100 mL single dose vials for induction and maintenance of general anesthesia and sedation. This launch strengthened the availability of an essential anesthetic drug used across a wide range of surgical procedures.
The availability of general anesthesia drugs remains affected by manufacturing complexity, supply chain disruptions, and shortages of sterile injectable medicines. Many intravenous anesthetics require specialized manufacturing processes, strict quality standards, and reliable access to pharmaceutical ingredients. Any interruption in production or distribution can affect hospital inventories and procedure scheduling. Healthcare facilities often need to manage limited supplies of essential anesthetic agents, particularly propofol and other injectable products used in routine surgical care. Regulatory inspections, manufacturing upgrades, and raw material constraints can further extend supply timelines. These factors increase procurement challenges for hospitals and may require healthcare providers to use alternative anesthetic protocols depending on product availability. Supply shortages can also increase operational pressure on healthcare facilities by limiting drug choices during surgical procedures. As a result, hospitals are strengthening inventory planning, qualifying multiple suppliers, and maintaining strategic stock levels to reduce the risk of treatment disruptions. Pharmaceutical manufacturers are also expanding production capacity and strengthening distribution networks to improve the availability of essential anesthesia medicines and support uninterrupted surgical care.
Continued product development and regulatory approvals are creating opportunities for the general anesthesia drugs market by increasing the availability of new anesthetic agents and expanding treatment options for healthcare providers. Companies are investing in intravenous anesthetics with rapid onset and recovery profiles while also developing products that support improved safety during surgical procedures. Regulatory approvals encourage broader adoption of newer therapies and increase competition within the market. Growing investments in research and manufacturing are also supporting product availability across hospitals and ambulatory surgical centers. As healthcare systems continue to perform a higher number of surgical procedures, the need for additional anesthesia options is likely to support future market growth. For instance, in May 2026, the U.S. Food and Drug Administration approved Cypsedo, containing cipepofol, for the induction of general anesthesia in adults undergoing surgery. The approval introduced a new intravenous general anesthetic option for adult surgical patients and expanded the range of available anesthesia drugs for clinical practice. This approval strengthened the availability of innovative anesthetic therapies and supported continued development within the general anesthesia drugs market.
Market Concentration & Characteristics
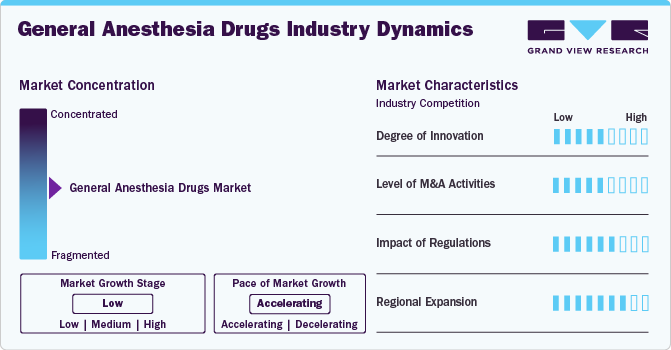
The general anesthesia drugs industry is characterized by significant innovation driven by advancements in drug development and anesthesia delivery technologies. Companies focus on creating novel anesthetic agents with improved safety profiles, faster onset, and shorter recovery times. For instance, the development of target-controlled infusion systems has revolutionized anesthesia delivery, allowing for precise control over drug administration and enhancing patient outcomes. Innovations such as desflurane and sevoflurane, which offer rapid induction and emergence from anesthesia, have become staples in modern anesthetic practice.
M&A plays a pivotal role in the general anesthesia drugs industry, facilitating market consolidation and the acquisition of new technologies. Major pharmaceutical companies frequently engage in M&A to expand their existing product portfolios and gain access to innovative technologies. M&A activities enable companies to leverage synergies, integrate advanced technologies, and streamline production processes, boosting their competitive edge and market presence. For instance, in April 2024, Baxter expanded its pharmaceutical portfolio in the U.S. with the launch of Ropivacaine Hydrochloride Injection, USP.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the market by ensuring product safety and efficacy. Regulatory organizations such as the U.S. FDA and the European Medicines Agency (EMA) enforce rigorous drug approval and monitoring standards. Recent regulatory updates, such as enhanced labeling requirements and post-market surveillance, aim to improve patient safety and drug effectiveness. These regulations help maintain high standards in the industry and foster trust among healthcare professionals, contributing to a stable and reliable market environment.
Regional expansion is a critical factor in the market's growth, with emerging economies experiencing increased demand due to improved healthcare infrastructure. In regions such as Asia-Pacific and Latin America, growing healthcare investments and rising surgical procedures drive market growth. Favorable government initiatives in India and China, focusing on enhancing healthcare access and infrastructure, contribute to this regional growth. The rise in disposable incomes and improved access to healthcare services also support the expansion of markets in these regions.
Analyst Perspective
The general anesthesia drugs market is shifting toward products that improve perioperative care through rapid induction, predictable recovery, and consistent safety profiles. The market is becoming more focused on companies with established sterile injectable manufacturing capabilities, broad anesthesia portfolios, and strong hospital distribution networks. Baxter International Inc., Fresenius SE & Co. KGaA, and B. Braun Melsungen AG continue to strengthen their positions through their established anesthesia and critical care product portfolios. At the same time, Hikma Pharmaceuticals plc, Aspen Pharmacare Holdings Limited, and other generic manufacturers are expanding product availability through new approvals and product launches, supporting a stable supply of essential general anesthesia drugs across healthcare facilities.
Drug Insights
In 2025, the propofol segment dominated this market with a substantial share of 25.5% and is also expected to grow at the fastest CAGR during the forecast period. Propofol is renowned for its rapid onset and quick recovery times, which enhance patient comfort and procedural efficiency. It is widely used for induction and maintenance of anesthesia, making it a versatile choice in various surgical and diagnostic procedures. The agent's favorable pharmacokinetic profile, including its short half-life and rapid metabolism, contributes to its popularity among anesthesiologists.
Propofol's broad acceptance in outpatient and same-day discharge procedures underscores its appeal in the growing trend of minimally invasive and outpatient surgeries. Furthermore, advances in formulation and delivery systems, such as improved intravenous administration techniques and the introduction of propofol-based emulsion formulations, have enhanced their clinical utility and safety profile.
Route Of Administration Insights
Based on route of administration, the intravenous segment led the market with the largest revenue share of 64.1% in 2025 and is also expected to grow at the fastest CAGR of 3.8% during the forecast period. Several key factors, including IV anesthesia delivery advancements, efficacy, and convenience, are primarily driving this growth trajectory. IV anesthesia is preferred for its rapid onset of action and precise control over drug administration, which are crucial for managing complex surgical procedures and ensuring patient safety. The ability to adjust dosage in real-time allows anesthesiologists to tailor anesthesia depth according to the patient’s needs and the requirements of the surgery.
Innovations in infusion systems, such as target-controlled infusion (TCI) devices, have improved the accuracy of drug delivery and patient monitoring. These systems enable precise control over anesthesia levels, enhancing overall procedural outcomes and patient comfort. For instance, the integration of smart infusion pumps with advanced monitoring systems has streamlined the administration process, reducing the risk of dosing errors and improving patient safety.
End-use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 68.6% in 2025. Hospitals are central to providing complex and high-volume surgical procedures, critical drivers for the demand for general anesthesia. As per the American Hospital Association (AHA), hospitals perform most of the country's surgical procedures, including elective and emergency surgeries. This high volume creates a consistent demand for general anesthesia drugs, as hospitals require a wide range of anesthetic agents to effectively manage different types of surgeries. The Urgent Care Association reported in May 2024 that approximately 14,714 urgent care centers nationwide provide diagnostic services and care to over 100 million patients annually.
The ambulatory surgical centers are anticipated to grow at the fastest CAGR during the forecast period. The growing preference for outpatient surgeries, where patients can undergo procedures and return home on the same day, is a significant driver of ASC growth. As per the Ambulatory Surgery Center Association (ASCA), ASCs offer a practical and affordable substitute for hospital surgeries, attracting patients and insurance providers. Moreover, the Centers for Medicare & Medicaid Services (CMS) have widened the scope of procedures that can be done in ASCs, thus enhancing their attractiveness and application. A study published in Health Affairs highlights that outpatient care settings, including ASCs, offer significant cost savings compared to inpatient hospital care, further fueling their growth.
Application Insights
Based on application, the general surgery segment led the market with the largest revenue share of 41.3% in 2025, driven by the high volume of procedures performed across hospitals and ambulatory surgical centers. The segment includes a broad range of surgical interventions requiring anesthesia for induction, maintenance, and perioperative management, supporting steady demand for general anesthesia drugs. The increasing number of elective and emergency surgeries, coupled with the growing adoption of minimally invasive procedures, further contributes to market demand. In addition, the rising prevalence of chronic diseases and an aging population are increasing the need for surgical interventions. Hospitals also prioritize anesthetic agents that offer rapid induction, predictable recovery, and stable patient management, supporting their use in general surgery. Together, these factors have strengthened the segment’s leading position in the application-based general anesthesia drugs market.
 To learn more about this report, Download Free Sample Report
The knee and hip replacement segment is anticipated to grow at the fastest CAGR over the forecast period, driven by the increasing prevalence of osteoarthritis, advancements in surgical techniques, and demographic trends. Osteoarthritis, particularly in the knee and hip joints, is a leading driver of the high demand for knee and hip replacement surgeries. According to the Centers for Disease Control and Prevention (CDC), approximately 32.5 million adults in the U.S. suffer from osteoarthritis, with knee and hip joints being commonly affected. This high prevalence results in a significant volume of replacement procedures, driving the demand for adequate general anesthesia.
Regional Insights
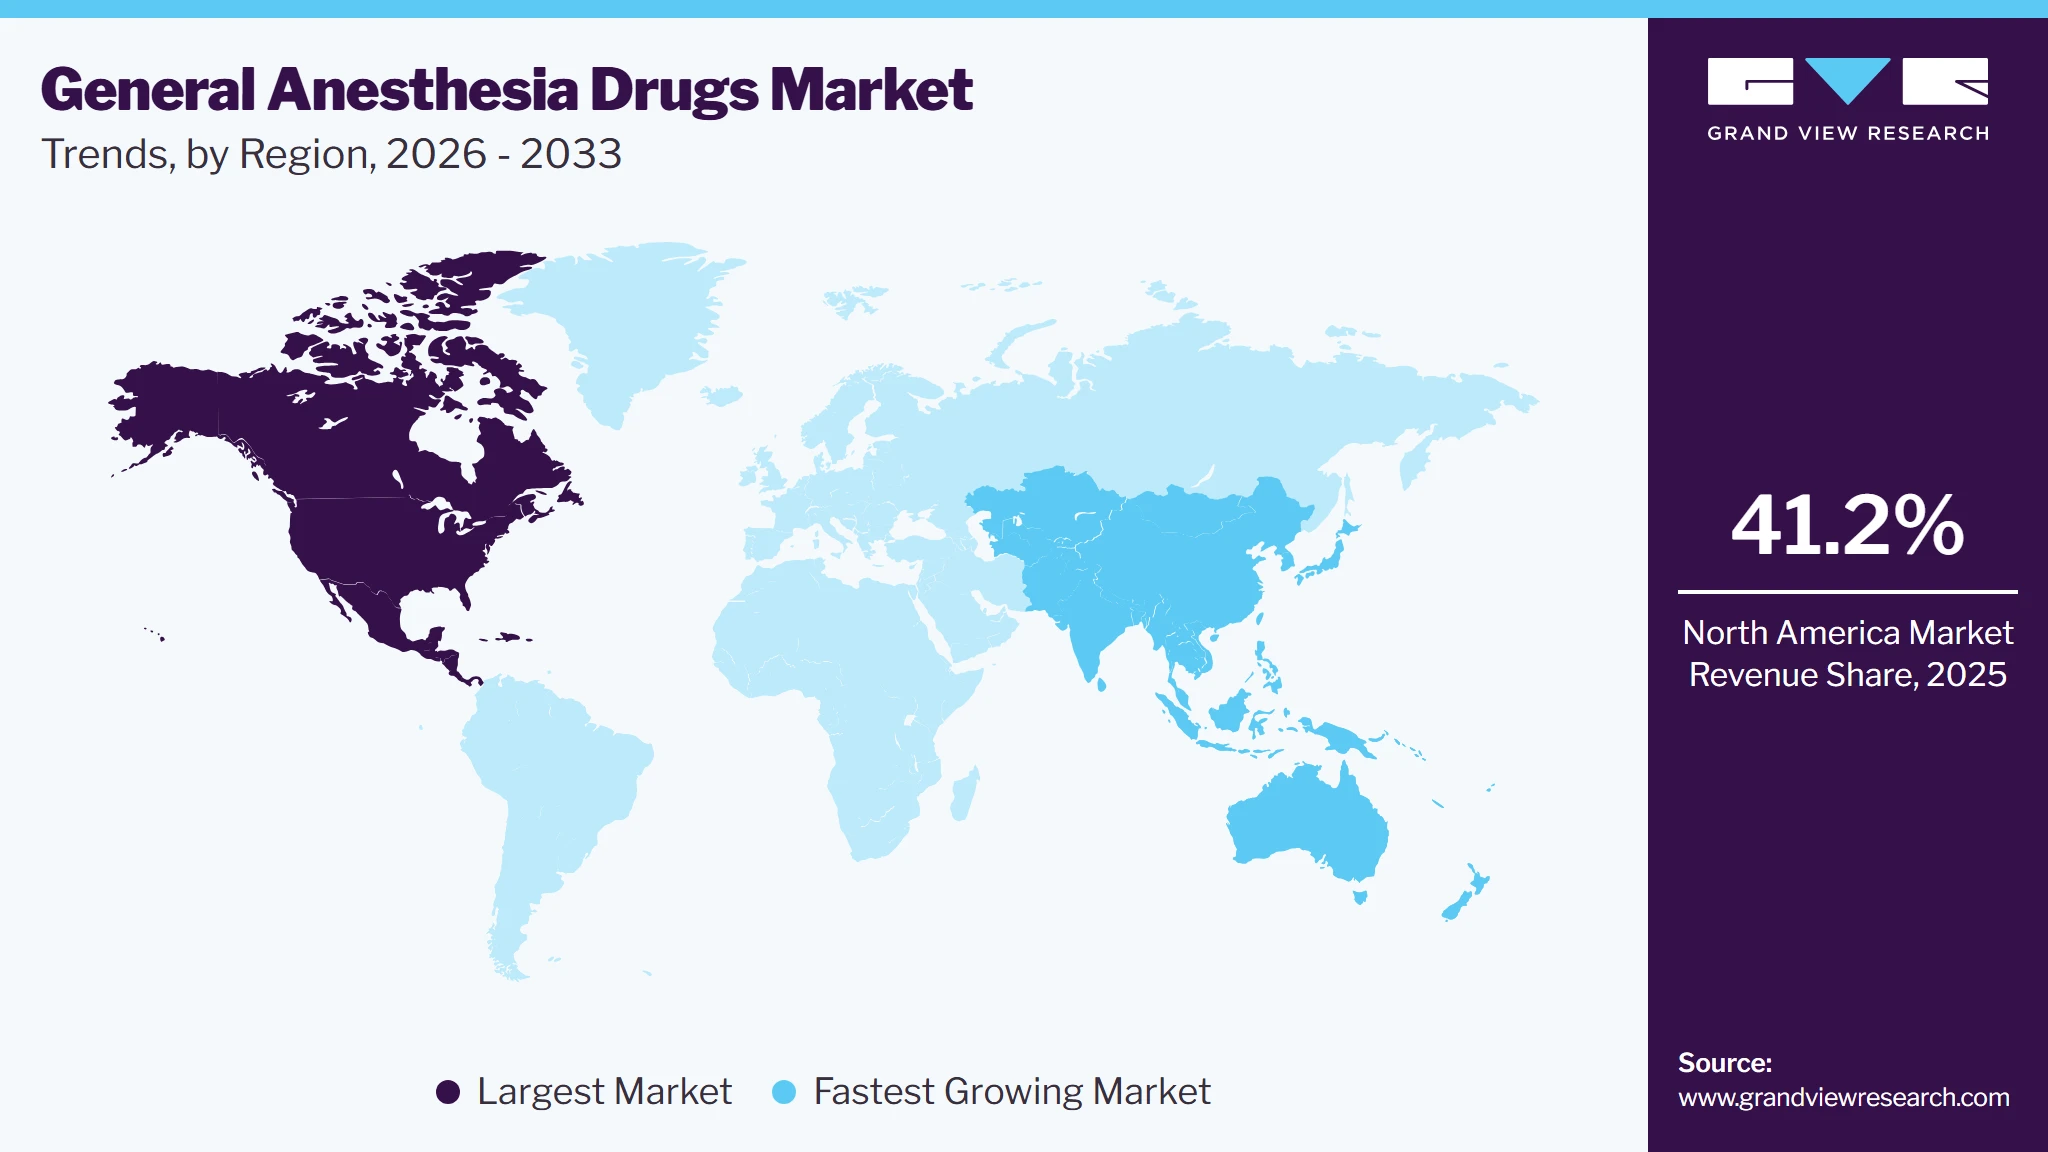
North America dominated the general anesthesia drugs market with the largest revenue share of 41.2% in 2025. The dominance is due to several critical factors, including the high prevalence of chronic diseases, technological advancements, and substantial healthcare infrastructure. The rising prevalence of chronic conditions such as CVD and cancer, which often require surgical interventions, fuels the demand for general anesthesia. According to the International Society of Aesthetic Plastic Surgery report, 26.2 million surgical procedures were conducted in the U.S. in 2022. In addition, data from the National Library of Medicine indicated that, in 2021, nearly nine significant surgeries were performed per 100 older adults, with over one in seven Medicare beneficiaries undergoing major surgery within five years, highlighting a substantial and growing demand for effective general anesthesia drugs.
 To learn more about this report, Download Free Sample Report
U.S. General Anesthesia Drugs Market Trends
The general anesthesia drugs market in the U.S. held the largest share in the North America region in 2025. It is driven by the high volume of surgeries, continuous innovation in anesthesia drugs, and a strong emphasis on patient safety and recovery. The U.S. has one of the highest surgical procedure rates globally, reflecting the high demand for anesthesia. The FDA plays an essential role in regulating and approving new anesthetic agents, ensuring safety and efficacy, which supports market expansion. According to the CDC, over 32.5 million adults in the U.S. are affected by osteoarthritis, creating a substantial demand for joint replacement surgeries.
The aging population plays a crucial role in this trend. According to a report published by the U.S. Census Bureau, the proportion of adults aged 65 and older is increasing, and this demographic is more susceptible to joint-related ailments. With the growing elderly population, the frequency of elective joint replacement surgeries, including total knee arthroplasties (TKAs) and total hip arthroplasties (THAs), is rising. These procedures often require general anesthesia for effective pain management and to facilitate a smooth surgical process.
Europe General Anesthesia Drugs Market Trends
The European general anesthesia drugs market is witnessing substantial growth driven by increasing surgical volumes, an aging population, and advancements in anesthesia technology. The aging population across Europe, as highlighted by the European Commission, results in a higher prevalence of age-related diseases that require surgical interventions, driving demand for anesthesia. According to the European Commission, Europe reports an average of around 40 million surgical procedures annually, and the European Medicines Agency (EMA) ensures stringent regulatory oversight, which promotes high standards for anesthesia drugs.
The UK general anesthesia drugs market is bolstered by the increasing number of surgical procedures, advancements in surgical techniques, and government healthcare initiatives. The National Health Service (NHS) performs a high volume of elective and emergency surgeries, creating a substantial demand for anesthesia. According to Cancer Research UK, every year, over 393,000 people are diagnosed with cancer. On average, someone in the UK is diagnosed with cancer every 90 seconds. Recent advancements in anesthesia technologies, including developing new anesthetic agents and improved delivery systems, support market growth.
The general anesthesia drugs market in Germany is thriving due to a combination of high healthcare standards, advanced medical technologies, and an increasing number of surgical procedures. Germany's robust healthcare system, supported by high standards set by regulatory bodies like the Federal Institute for Drugs and Medical Devices (BfArM), ensures the availability of safe and effective anesthesia drugs. The country's commitment to technological innovation in anesthesia and surgical techniques contributes to market growth. Furthermore, as noted by the Federal Statistical Office, Germany's aging population drives the demand for surgeries and, consequently, anesthesia drugs.
Asia Pacific General Anesthesia Drugs Market Trends
The general anesthesia drugs market in the Asia Pacific region is expected to grow at the fastest CAGR of 4.9% over the forecast period due to increasing healthcare expenditure, a rising population with growing surgical needs, and advancements in medical technology. Asia Pacific with its large and diverse population & rising incidence of chronic conditions along with the need of surgical interventions further fuels the demand for general anesthesia. Governments in China and India are investing heavily in healthcare infrastructure and medical technology, further driving market growth.
The general anesthesia drugs market in India is experiencing rapid growth, fueled by a rising burden of chronic diseases, increasing surgical volumes, and significant healthcare reforms. India’s large population, with a growing prevalence of conditions like cardiovascular diseases and diabetes, results in a high demand for surgical interventions and anesthesia. According to the National Center for Disease Informatics and Research, the projected number of new cancer cases in India was 1,461,427, with a crude incidence rate of 100.4 per 100,000 individuals in 2022. Recent government initiatives, such as the Ayushman Bharat scheme, aim to improve healthcare access and affordability, thereby increasing the number of surgeries performed.
The general anesthesia drugs market in China is experiencing robust growth, driven by several critical factors, including the increasing prevalence of chronic diseases, significant investments in healthcare infrastructure, and recent advancements in medical technology. According to the China Cardiovascular Disease Report 2022, cardiovascular diseases are the leading cause of death in China, contributing to a high volume of surgical procedures. Additionally, the growing incidence of cancer, as reported by the China National Cancer Center, further fuels the demand for effective anesthesia solutions. The Healthy China 2030 initiative emphasizes improving health services and expanding coverage, which includes increasing the availability of surgical procedures and related anesthesia services. This initiative supports developing and growing healthcare infrastructure, enhancing the overall market for general anesthesia drugs.
Latin America General Anesthesia Drugs Market Trends
The general anesthesia drugs market in Latin America is expanding due to increasing healthcare access, rising surgical procedures, and improvements in medical technology. The region’s growing population and increasing incidence of chronic diseases lead to a higher volume of surgeries, which drives demand for anesthesia drugs. Governments in Brazil and Mexico are investing in healthcare infrastructure and medical technology, supporting market growth.
The general anesthesia drugs market in Brazil is driven by increasing healthcare access, a high volume of surgeries, and advancements in medical technologies. Brazil’s expanding healthcare system, supported by government initiatives like the Unified Health System (SUS), increases access to surgical procedures, thereby driving demand for anesthesia. The country’s high incidence of chronic diseases, such as cardiovascular conditions and diabetes, necessitates frequent surgical interventions.
Middle East & Africa General Anesthesia Drugs Market Trends
The general anesthesia drugs market in the Middle East and Africa is expanding significantly due to rising healthcare investments, increasing surgical procedures, and advancements in medical technology. Favorable initiatives by the government in this region to improve healthcare infrastructure and medical technologies improve access to surgical services. The growing prevalence of chronic conditions and an increasing number of surgical interventions further drive the demand for general anesthesia drugs.
The general anesthesia drugs market in Saudi Arabia is experiencing rapid growth due to significant investments in the healthcare sector, a rising number of surgical procedures, and advancements in medical technologies. The Saudi government’s Vision 2030 initiative emphasizes enhancing healthcare infrastructure and services, supporting the growth of the general anesthesia drugs market. The rising prevalence of chronic diseases and the demand for advanced surgical procedures drive the need for adequate general anesthesia drugs.
Key General Anesthesia Drugs Company Insights
The general anesthesia drugs industry is dominated by several major pharmaceutical companies, which collectively account for a significant market share. These leading players have established themselves through extensive R&D efforts, resulting in the introduction of innovative treatment options. They have also expanded their drug portfolios through strategic collaborations, mergers, and acquisitions.
Key General Anesthesia Drugs Companies:
The following key companies have been profiled for this study on the general anesthesia drugs market.
-
Baxter International Inc.
-
AstraZeneca
-
AbbVie Inc.
-
B. Braun Melsungen AG
-
Fresenius SE & Co. KgaA
-
Pfizer
-
Hospira Inc.
-
Aspen Pharmacare Holdings Limited
-
Hikama Pharmaceuticals plc
-
Abbott Laboratories
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Baxter International Inc., AstraZeneca, AbbVie Inc., B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Pfizer, Abbott Laboratories)
- Focus on expanding anesthesia portfolios through product approvals, lifecycle management, and manufacturing capacity expansion. Strengthen relationships with hospitals, ambulatory surgical centers, and healthcare distributors through broad product availability, supply agreements, and clinical support programs.
- Strong product portfolios covering multiple anesthesia drugs and perioperative care products. Wide manufacturing capabilities, established regulatory expertise, and extensive distribution networks support consistent product availability across major healthcare markets.
- High manufacturing and regulatory compliance costs associated with sterile injectable products. Dependence on complex supply chains and large production facilities may affect operational flexibility during periods of manufacturing disruptions or product shortages.
Emerging Players (Hospira Inc., Aspen Pharmacare Holdings Limited, Hikma Pharmaceuticals plc)
- Focus on expanding generic anesthesia drug portfolios through new product launches, regulatory approvals, and geographic expansion. Target hospitals and healthcare providers by offering cost competitive injectable anesthetics and strengthening regional manufacturing and distribution capabilities.
- Ability to introduce cost competitive generic anesthesia drugs and respond to market demand with focused product portfolios. Flexible manufacturing strategies and targeted regional expansion support growth in established and developing healthcare markets.
- Limited product diversification compared with larger pharmaceutical companies. Smaller global commercial presence and distribution networks may limit access to certain healthcare markets and large procurement contracts.
Recent Developments
-
In September 2024, Eugia Steriles, a subsidiary of Aurobindo Pharma received USFDA approval for Lidocaine Hydrochloride injection. The injection is used as an anesthetic on the body to help reduce discomfort and pain caused by invasive procedures such as needle punctures, insertion of breathing tube or catheter, and surgery.
-
In August 2024, Amneal Pharmaceuticals, Inc. announced FDA approval for its Propofol Injectable Emulsion USP in three single-dose vial concentrations; it is widely used in hospitals to induce and maintain anesthesia and sedation.
-
For instance, in April 2024, Baxter expanded its pharmaceutical portfolio in the U.S. with the launch of Ropivacaine Hydrochloride Injection, USP. This new product comes in a convenient, ready-to-use, single-dose infusion bag.
-
In March 2023, Lupin Ltd's partner, Caplin Steriles, received FDA approval to market Rocuronium Bromide Injection and Thiamine Hydrochloride Injection USP. Rocuronium Bromide Injection is used to aid rapid sequence intubation and muscle relaxation during surgery. Following this, in November 2023, Lupin Ltd's stock rose by 3% succeeding the U.S. launch of Rocuronium Bromide Injection, highlighting the market impact of regulatory approvals.
General Anesthesia Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.5 billion
Estimated market size in 2026
USD 5.6 billion
Projected market size by 2033
USD 7.2 billion
Growth rate
CAGR of 3.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug, route of administration, end use, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Baxter International Inc.; AstraZeneca; AbbVie Inc.; B. Braun Melsungen AG; Fresenius SE & Co. KgaA; Pfizer; Hospira Inc.; Aspen Pharmacare Holdings Limited; Hikama Pharmaceuticals plc; Abbott Laboratories.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global General Anesthesia Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global general anesthesia drugs market report based on drug, route of administration, application, end-use, and region.
-
Drug Outlook (Revenue, USD Million, 2021 - 2033)
-
Sevoflurane
-
Propofol
-
Dexmedetomidine
-
Remifentanil
-
Desflurane
-
Midazolam
-
Others - (Sufentanil, Fentanyl, Ketamine, Isoflurane, Thiopental, etc.)
-
-
Route Of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Intravenous
-
Inhaled
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Heart Surgeries
-
Cancer
-
General Surgery
-
Knee And Hip Replacements
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The general anesthesia drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each general anesthesia drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug
Revenue capture definition
Sevoflurane
Includes sevoflurane based anesthetic formulations used for the induction and maintenance of general anesthesia through inhalation across pediatric and adult surgical procedures.
Propofol
Includes propofol based intravenous anesthetic formulations administered for the induction and maintenance of general anesthesia during surgical and diagnostic procedures.
Dexmedetomidine
Includes dexmedetomidine based formulations administered as sedative and anesthetic adjuncts during general anesthesia to support perioperative patient management.
Remifentanil
Includes remifentanil based opioid formulations administered during general anesthesia to provide intraoperative analgesia as part of balanced anesthesia protocols.
Desflurane
Includes desflurane based inhalation anesthetic formulations administered for the maintenance of general anesthesia during surgical procedures requiring volatile anesthetic agents.
Midazolam
Includes midazolam based formulations administered before or during general anesthesia for sedation, anxiolysis, and induction support as part of anesthetic management.
Others
Includes general anesthesia drugs not covered under the above categories, such as sufentanil, fentanyl, ketamine, isoflurane, thiopental, and other anesthetic or anesthetic adjunct agents.
Segment- Route of Administration
Revenue capture definition
Intravenous
Includes general anesthesia drugs administered directly into the bloodstream through intravenous injection or infusion for anesthesia induction, maintenance, or perioperative anesthetic support.
Inhaled
Includes volatile anesthetic agents administered through inhalation using anesthesia delivery systems for the induction or maintenance of general anesthesia.
Segment - End Use
Revenue capture definition
Hospitals
Includes the use of general anesthesia drugs in public and private hospitals performing inpatient, outpatient, emergency, and complex surgical procedures requiring general anesthesia.
Ambulatory Surgical Centers
Includes the use of general anesthesia drugs in ambulatory surgical centers performing same day surgical procedures that do not require overnight hospital admission.
Others
Includes the use of general anesthesia drugs in healthcare facilities other than hospitals and ambulatory surgical centers, including specialty surgical clinics, office based surgical facilities, military healthcare facilities, and academic medical centers.
Estimation Model
 To learn more about this report, Download Free Sample Report
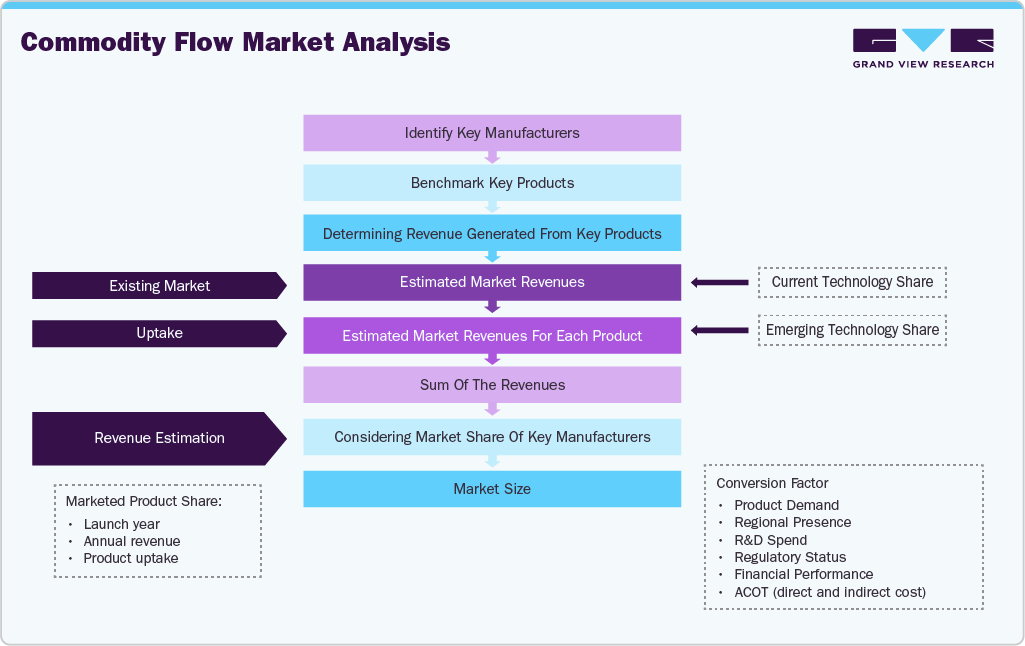
The general anesthesia drugs market was estimated using a commodity flow market analysis approach. Key manufacturers of intravenous and inhalation anesthetic drugs were identified, and their marketed products were benchmarked based on product type, route of administration, approved indications, pricing, manufacturing capacity, geographic presence, and regulatory approvals. Revenue generated from leading anesthesia drugs was evaluated using company annual reports, regulatory filings, investor presentations, procurement data, and publicly available product information. Market estimates were validated through the analysis of hospital procurement trends, surgical procedure volumes, utilization of anesthesia drugs across hospitals and ambulatory surgical centers, and product adoption by healthcare providers. Average selling prices, product availability, generic competition, and regional demand patterns were incorporated to estimate segment level market values. The estimates were further validated through primary interviews with industry participants and healthcare professionals to ensure consistency with current market conditions and purchasing practices.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
General Anesthesia Drug Portfolio & Competitive Assessment
Conducted a detailed assessment of the global general anesthesia drugs market by evaluating approved anesthetic agents, product portfolios, route of administration, clinical use, regulatory approvals, and competitive positioning. The study analyzed key companies including Baxter International Inc., AstraZeneca, AbbVie Inc., B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Pfizer, Hospira Inc., Aspen Pharmacare Holdings Limited, Hikma Pharmaceuticals plc, and Abbott Laboratories. It also reviewed market trends across intravenous and inhalation anesthesia products used in surgical care.
Helped the client identify key competitors, compare product portfolios, evaluate market positioning, and understand opportunities across different anesthesia drug categories and healthcare facilities.
General Anesthesia Product Benchmarking Study
Delivered a comprehensive benchmarking analysis of general anesthesia drugs by comparing product type, route of administration, approved indications, dosage forms, manufacturing capabilities, regulatory status, and clinical application. The assessment also evaluated product differentiation, supply capabilities, lifecycle management strategies, and geographic presence across leading manufacturers of anesthesia drugs.
Enabled the client to compare competing products, identify portfolio gaps, support product development planning, and evaluate opportunities for portfolio expansion across the general anesthesia drugs market.
General Anesthesia Manufacturing & Supply Chain Assessment
Conducted a strategic assessment of the manufacturing and supply chain for general anesthesia drugs by evaluating sterile injectable manufacturing capabilities, volatile anesthetic production, raw material availability, regulatory requirements, contract manufacturing capabilities, supply continuity, distribution networks, and regional manufacturing presence supporting hospital and ambulatory surgical center demand.
Supported manufacturing and procurement planning by identifying qualified manufacturing partners, evaluating supply chain risks, assessing regional production capabilities, and strengthening supply continuity strategies for general anesthesia drugs across major healthcare markets.
Frequently Asked Questions About This Report
The propofol segment led the market with the largest revenue share of 25.5% in 2025, owing to its widespread use for the induction and maintenance of general anesthesia.
The intravenous segment dominated the market with a 64.1% revenue share in 2025, supported by its rapid onset, precise dosing, and extensive use across surgical procedures.
Key players include Baxter International Inc., AstraZeneca, AbbVie Inc., B. Braun Melsungen AG, Fresenius SE & Co. KGaA, Pfizer Inc., Hospira Inc., Aspen Pharmacare Holdings Limited, Hikma Pharmaceuticals plc, and Abbott Laboratories.
North America dominated the general anesthesia drugs market with a 41.2% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period, driven by expanding healthcare infrastructure, increasing surgical volumes, and improving access to anesthesia services.
The global general anesthesia drugs market size was valued at USD 5.5 billion in 2025 and is estimated at USD 5.6 billion for 2026.
The global general anesthesia drugs market is expected to grow at a CAGR of 3.6% from 2026 to 2033, reaching USD 7.2 billion by 2033.
Key factors include the increasing number of surgical procedures, growing aging population, rising prevalence of chronic diseases requiring surgery, demand for rapid-acting and safe anesthetic agents, expansion of ambulatory surgical centers, and continued product approvals and manufacturing capacity expansion.
The hospitals segment accounted for the largest market share, with 68.6% of revenue in 2025, due to the high volume of inpatient and complex surgical procedures performed in hospital settings.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


