
- Home
- »
- Next Generation Technologies
- »
-
Green Data Center Market Size & Share Report, 2026-2033GVR Report cover

Green Data Center Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solution, Services), By Enterprise Size (Large Enterprises, SMEs), By End Use (BFSI, Retail, IT & Telecom, Healthcare, Manufacturing), By Region, And Segment Forecasts
Market Size, 2025
$83.9BMarket Estimate, 2026
$99.8BMarket Forecast, 2033
$296.7BCAGR, 2026–2033
16.8%Green Data Center Market Summary
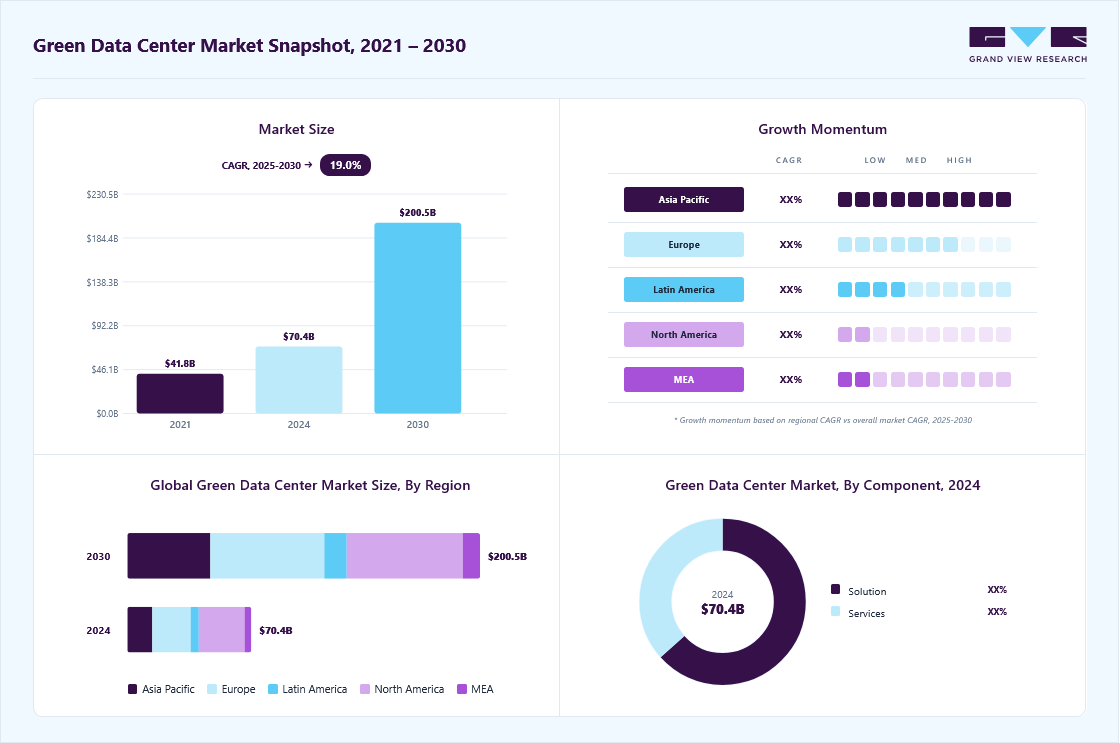
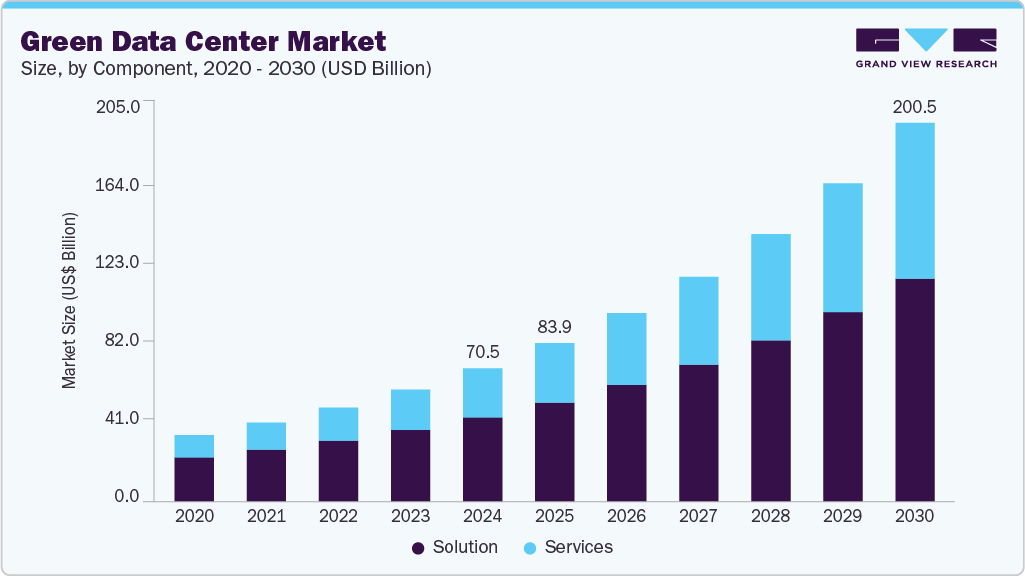
The global green data center market size was valued at USD 83.9 billion in 2025 and is projected to grow from USD 99.8 billion in 2026 to USD 296.7 billion by 2033, at a CAGR of 16.8% from 2026 to 2033. The market in North America dominated with a revenue share of 37.3% in 2025. North American data center operators are accelerating renewable energy adoption through long-term power purchase agreements (PPAs), on-site solar installations, and wind energy projects to reduce carbon emissions and meet corporate net-zero goals.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solution segment held the largest market share of 62.5% in 2025.
- By enterprise size: Large enterprises segment held the largest market share of 71.3% in 2025.
- By end use: BFSI segment held the largest market share of 23.3% in 2025.
Regional Highlights
- Largest regional market: North America (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 83.9 Billion
- Estimated market size in 2026: USD 99.8 Billion
- Projected market size by 2033: USD 296.7 Billion
- CAGR (2026-2033): 16.8%
Prism AI by Grand View Research Free to tryAsk a question about the green data center marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →These initiatives lower dependence on fossil fuels, improve energy resilience, support regulatory compliance, and drive investments in energy-efficient, sustainable green data center infrastructure. Driven by increasing energy costs, stringent environmental regulations, and growing corporate sustainability goals, pushing organizations to adopt energy-efficient infrastructure. Rising demand for cloud computing, internet of things (IoT), and big data analytics necessitates scalable and eco-friendly data centers, while advancements in cooling technologies, renewable energy integration, and modular designs enhance efficiency.
 To learn more about this report, Download Free Sample Report
The stringent government regulations and policies promoting sustainable IT infrastructure are also contributing to the green data center industry. Governments worldwide are implementing carbon emission reduction targets and energy efficiency standards, compelling organizations to adopt eco-friendly data center solutions. For instance, the European Union’s Climate Neutral Data Centre Pact and the U.S. Energy Efficiency and Renewable Energy Initiatives encourage the adoption of green technologies. Compliance with these regulations not only helps companies avoid penalties but also enhances their corporate social responsibility (CSR) profiles, attracting environmentally conscious investors and customers.
The rising awareness of environmental sustainability among corporations and consumers is also fueling market growth. Large tech companies like Google, Microsoft, and Amazon are investing heavily in carbon-neutral data centers to meet their net-zero commitments. This trend is encouraging smaller enterprises to follow suit, driving demand for green data center solutions. Furthermore, the increasing popularity of edge computing and 5G networks necessitates decentralized, energy-efficient data centers, further propelling market expansion.
The proliferation of artificial intelligence (AI) applications has led to an unprecedented demand for data processing capabilities, necessitating the expansion of data center infrastructures. This growth has intensified the focus on energy efficiency and sustainability. For instance, in December 2024, Google partnered with Intersect Power, a U.S.-based Green energy supplier and TPG Rise Climate a U.S.-based impact investing platform to develop renewable energy and storage projects alongside new data centers across the U.S. Intersect will build the clean energy assets, with Google as the main offtaker and anchor tenant, supporting its goal to add gigawatts of new data center capacity
Market Dynamics
The green data center market is experiencing robust growth as enterprises, hyperscale cloud providers, and colocation operators prioritize sustainable digital infrastructure to support the rapid expansion of artificial intelligence (AI), cloud computing, high-performance computing (HPC), and data-intensive applications. The increasing power consumption of AI workloads is driving demand for energy-efficient servers, advanced power distribution systems, intelligent energy management platforms, and high-density cooling technologies such as liquid cooling and immersion cooling to improve operational efficiency while reducing carbon emissions. Growing corporate net-zero commitments, stricter environmental regulations, and rising electricity costs are encouraging organizations to integrate renewable energy sources, battery energy storage systems (BESS), and AI-enabled data center infrastructure management (DCIM) solutions that optimize energy utilization and minimize environmental impact. The continued expansion of hyperscale and edge data centers, coupled with advancements in modular infrastructure, heat recovery systems, waste heat reuse, and smart grid integration, is further accelerating market growth. In addition, significant investments by cloud service providers, colocation companies, utilities, and governments in renewable-powered facilities, low-carbon construction practices, and next-generation sustainable data center technologies are strengthening the industry's transition toward carbon-neutral operations. Rising adoption across cloud providers, telecommunications, banking, healthcare, manufacturing, government, research institutions, and digital service providers is expected to sustain long-term growth in the global Green Data Center Market.
The growing emphasis on reducing carbon emissions and improving energy efficiency is a major driver of the green data center market. Hyperscale cloud providers, colocation operators, and enterprises are increasingly investing in renewable energy sources such as solar, wind, and hydroelectric power through power purchase agreements (PPAs) and on-site generation. Rising AI workloads and high-density computing are also accelerating the deployment of energy-efficient servers, intelligent power management systems, liquid cooling, immersion cooling, and AI-driven data center infrastructure management (DCIM) solutions. These technologies help reduce power consumption, improve power usage effectiveness (PUE), and support corporate net-zero and sustainability goals.
The substantial capital expenditure required to build or retrofit green data centers remains a key restraint to market growth. Deploying advanced cooling systems, renewable energy infrastructure, battery energy storage systems (BESS), intelligent power distribution, and energy-efficient IT equipment requires significant upfront investment. In addition, integrating sustainable technologies into existing facilities can involve operational disruptions, complex engineering requirements, and extended implementation timelines. Limited renewable energy availability in certain regions, aging power infrastructure, and rising equipment costs further increase the financial burden on data center operators, particularly small and medium-sized enterprises.
The rapid expansion of AI, cloud computing, and high-performance computing (HPC) presents significant growth opportunities for the Green Data Center Market. Increasing rack power densities are driving demand for advanced cooling technologies such as direct-to-chip liquid cooling, immersion cooling, and AI-enabled thermal management systems that improve energy efficiency while supporting next-generation computing workloads. Furthermore, growing investments in modular green data centers, renewable-powered facilities, smart grids, waste heat recovery, and carbon-neutral infrastructure are creating new opportunities for technology providers and data center operators. As governments and enterprises strengthen sustainability initiatives and digital transformation strategies, demand for environmentally responsible, energy-efficient data centers is expected to grow across cloud services, telecommunications, BFSI, healthcare, manufacturing, and public sector organizations.
Analyst Perspective
The green data center market is evolving as organizations invest in AI, cloud, edge, and high-performance computing. The expansion of hyperscale and colocation facilities and rising AI power demands are driving adoption of energy-efficient power systems, intelligent cooling, renewable energy, and AI-enabled Data Center Infrastructure Management (DCIM) solutions. Enterprises are prioritizing carbon neutrality, lower Power Usage Effectiveness (PUE), regulatory compliance, cost optimization, and infrastructure resilience. Vendors offering integrated cooling, power management, renewable energy, battery storage, modular infrastructure, and AI-driven energy optimization solutions are expected to gain a competitive advantage. As sustainability policies and ESG initiatives expand, solutions that improve energy efficiency, reduce emissions, support high-density AI computing, and enable scalable, low-carbon infrastructure will drive long-term growth in the global green data center market.
Component Insights
Based on component, the solution segment led the market with the largest revenue share of 62.5% in 2025 and is expected to grow at the significant CAGR over the forecast period, driven bythe rising demand for advanced cooling solutions, such as liquid cooling and free cooling, which significantly reduce energy consumption compared to traditional air-based cooling systems. As data centers expand and power densities increase, efficient thermal management becomes critical, pushing companies to invest in innovative cooling technologies that lower operational costs and carbon footprints. The segment is further segmented into monitoring and management systems, cooling systems, networking systems, and power systems.
The services segment is anticipated to grow at the fastest CAGR of 18.9% during the forecast period, driven by the rising demand for consulting and assessment services, as businesses seek guidance on transitioning to energy-efficient data center models. Sustainability consultants help organizations evaluate carbon footprints, optimize power usage effectiveness (PUE), and comply with environmental regulations such as the EU’s Energy Efficiency Directive and LEED certifications. As regulatory pressures intensify, companies are increasingly outsourcing these assessments to ensure compliance and maximize operational efficiency. The segment is further segmented into installation & deployment, consulting, and support & maintenance.
Enterprise Size Insights
Based on enterprise size, the large enterprises segment led the market with the largest revenue share of 71.3% in 2025. Large enterprises generate and process exponentially growing volumes of data from digital transformation initiatives, enterprise software, customer relationship management (CRM), artificial intelligence, and edge computing. This requires high-density and high-performance data centers, which often consume significant energy. Green data centers, with their optimized energy use and advanced virtualization, offer scalable solutions that balance performance and efficiency.
The SMEs segment is expected to grow at the fastest CAGR during the forecast period. SMEs are undergoing rapid digital transformation, adopting cloud-based applications, data analytics, and digital platforms to remain competitive and agile. This shift naturally increases their reliance on third-party or co-located data centers, many of which are now green-certified or marketed as energy-efficient. SMEs increasingly prefer cloud and managed service providers with strong environmental credentials, indirectly driving demand for green data centers.
End Use Insights
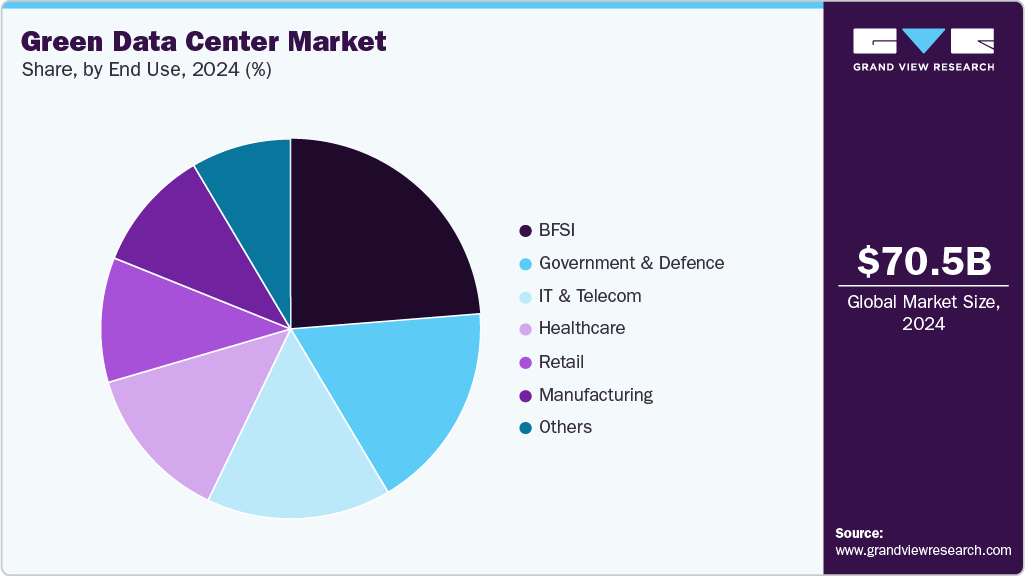
Based on end use, the BFSI segment led the market with the largest revenue share of 23.3% in 2025, driven by the growth of digital banking and fintech, which has exponentially increased data processing needs. With the rise of mobile banking, blockchain, AI-driven fraud detection, and real-time transaction processing, financial institutions require high-performance, low-latency data centers that minimize energy waste. Green data centers, equipped with advanced cooling systems, renewable energy integration, and AI-powered energy management, enable BFSI firms to handle massive workloads while reducing operational costs.
 To learn more about this report, Download Free Sample Report
The IT & telecom segment is expected to grow at the fastest CAGR over the forecast period, due to the rise of edge computing. As latency-sensitive applications (e.g., augmented reality, smart cities) proliferate, decentralized edge data centers must balance performance with energy efficiency. Modular green data centers, equipped with battery storage, solar panels, and passive cooling, for edge deployments, reducing reliance on fossil fuels in remote locations.
Regional Insights
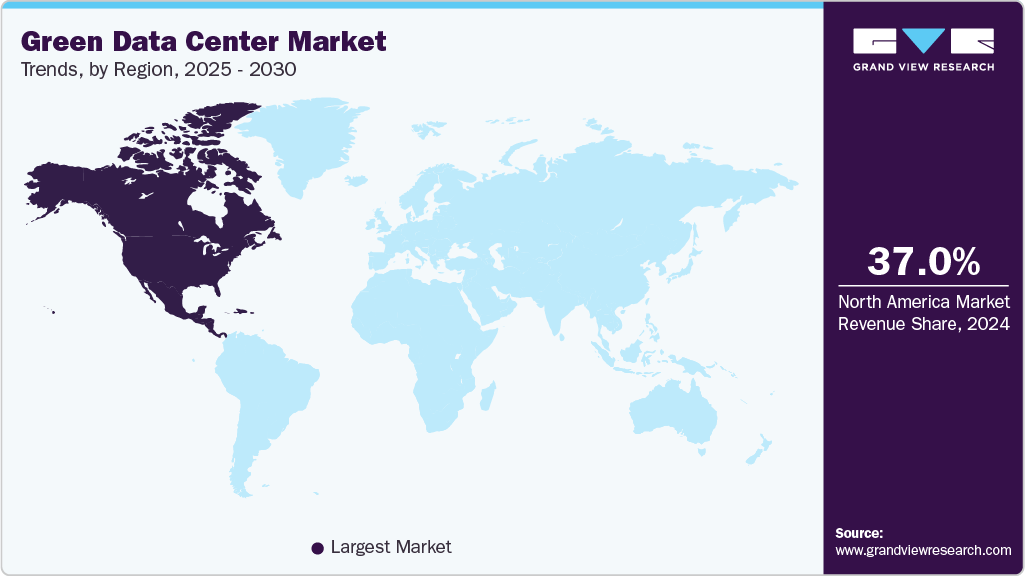
North America dominated the green data center market with the largest revenue share of 37.3% in 2025, driven by the expansion of hyper scale and cloud providers such as Amazon Web Services (AWS), Microsoft Azure, Google Cloud, and Meta, all of which are aggressively investing in green data centers. These hyperscalers are building massive renewable-powered facilities across the U.S. and Canada, setting industry benchmarks and driving economies of scale. Their commitment to using 100% renewable energy and achieving carbon neutrality is creating a ripple effect across the data center supply chain, prompting colocation providers and enterprises to follow suit.
 To learn more about this report, Download Free Sample Report
U.S. Green Data Center Market Trends
The green data center market in the U.S. held the largest share in the North America region in 2025. The U.S. government has introduced several policies that incentivize the development of green data centers. The Inflation Reduction Act (IRA) of 2022, for example, includes significant clean energy tax credits and funding programs aimed at reducing carbon emissions across industries.
Europe Green Data Center Market Trends
The green data center market in Europe is anticipated to register at a considerable CAGR from 2026 to 2033. Europe's market benefits from early adoption of smart grid technologies, AI-based energy management, and real-time environmental monitoring. These technologies allow data centers to dynamically adjust cooling systems, optimize server workloads, and reduce idle energy use.
The UK green data center market is expected to grow at a rapidly CAGR during the forecast period. Advanced technologies such as AI-powered cooling, modular data center architecture, and heat reuse systems are being rapidly adopted in the UK to improve energy efficiency and sustainability. Data centers are increasingly designed to repurpose excess heat for district heating projects or nearby residential and commercial facilities.
The green data center market in Germany accounted for a substantial market revenue share in Europe in 2025. Large German enterprises and multinational corporations are integrating Environmental, Social, and Governance (ESG) benchmarks into their IT sourcing decisions. This has led to greater demand for green-certified data centers that can help reduce carbon footprints and support climate disclosures.
Asia Pacific Green Data Center Market Trends
The green data center market in Asia Pacific is expected to register at the fastest CAGR of 19.2% from 2026 to 2033, driven by accelerating digital transformation, rising data traffic, government sustainability mandates, and a strong focus on energy-efficient infrastructure. With booming economies, increasing cloud adoption, and a push for decarbonization, countries across the region are investing heavily in eco-friendly data centers.
The Japan green data center market is expected to grow at a rapid CAGR during the forecast period. Japan aims to become carbon neutral by 2050, with interim milestones set for 2030. The government is promoting green innovation through subsidies, tax incentives, and R&D funding under programs like the Green Growth Strategy and the Digital Garden City Nation vision. Data centers, which account for significant energy use, are central to these efforts.
The green data center market in China accounted for a substantial market revenue share in Asia Pacific in 2025. China is relocating data center capacity from the energy-constrained eastern provinces to resource-rich western regions, where hydropower and wind energy are more abundant. This policy reduces strain on urban grids while supporting the green transition.
Key Green Data Center Company Insights
Key players operating in the green data center industry are Schneider Electric, Vertiv Group Corp., Equinix, Inc., Digital Realty Trust, and Huawei Technologies Co., Ltd. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals.
Key Green Data Center Companies:
The following key companies have been profiled for this study on the green data center market.
-
ABB
-
Asetek Inc.
-
Cisco Systems, Inc.
-
Dell Inc.
-
Delta Electronics, Inc.
-
Digital Realty Trust
-
Equinix, Inc.
-
Fujitsu
-
General Electric
-
Hewlett Packard Enterprise Development LP
-
Hitachi Energy Ltd.
-
Huawei Technologies Co., Ltd.
-
IBM Corporation
-
Schneider Electric
-
Siemens
-
Vertiv Group Corp.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Schneider Electric, Vertiv, Eaton, ABB, Siemens, Johnson Controls, Huawei Digital Power, Delta Electronics, Legrand)
- Established companies focus on delivering end-to-end green data center solutions, including energy-efficient power infrastructure, intelligent cooling systems, DCIM software, renewable energy integration, battery energy storage systems (BESS), and modular data center solutions. Their strategies emphasize continuous R&D, AI-driven energy management, strategic acquisitions, partnerships with hyperscale cloud providers and colocation operators, and expansion of sustainable infrastructure portfolios to support carbon-neutral data centers.
- These companies benefit from extensive global presence, diversified product portfolios, strong engineering capabilities, established customer relationships, and comprehensive service networks. Their expertise in power management, thermal management, automation, and digital infrastructure enables them to deliver reliable, scalable, and energy-efficient solutions while helping customers reduce operating costs, improve Power Usage Effectiveness (PUE), and achieve sustainability goals.
- Established vendors face challenges including high capital investments in product innovation, complex integration with legacy infrastructure, dependence on global supply chains for electrical and cooling equipment, and increasing competition from specialized technology providers. Rapid advancements in AI infrastructure, evolving sustainability regulations, and the need for continuous innovation can also increase development costs and pressure profit margins.
Emerging Players (Submer, LiquidStack, Iceotope, Asperitas, ZutaCore, Green Revolution Cooling (GRC))
- Emerging companies primarily focus on next-generation cooling technologies, including immersion cooling, direct-to-chip liquid cooling, AI-driven thermal management, waste heat recovery, and sustainable cooling infrastructure for AI and high-density computing environments. Their strategies emphasize innovation, energy efficiency, lower water consumption, modular deployment, and collaborations with hyperscalers, colocation providers, server OEMs, and research institutions to address growing AI and HPC workloads.
- Emerging vendors offer highly specialized solutions that significantly improve cooling efficiency, reduce power consumption, support higher rack power densities, and lower total cost of ownership (TCO). Their innovative technologies enable better sustainability performance, faster deployment, and improved scalability for AI-ready data centers, making them attractive partners for organizations investing in next-generation digital infrastructure.
- Emerging companies generally have limited global presence, smaller customer bases, lower manufacturing scale, and fewer financial resources than established infrastructure vendors. They also face challenges in expanding commercial deployments, building long-term customer trust, integrating with existing data center ecosystems, and competing against established players offering comprehensive end-to-end infrastructure solutions and global support capabilities.
Recent Developments
-
In December 2024, Schneider Electric announced the launch of advanced AI-ready data center solutions to address escalating energy and sustainability challenges driven by the rapid expansion of AI workloads. Central to the update is the introduction of the Galaxy VXL, a compact, high-density uninterruptible power supply (UPS) designed specifically for data centers and large-scale electrical environments.
-
In November 2024, Vertiv partnered with Compass Datacenters to introduce the Vertiv CoolPhase Flex, a hybrid cooling solution designed to streamline the adoption of liquid cooling for AI-driven data center environments. As the latest evolution of the Vertiv Lieber DSE Packaged System, CoolPhase Flex combines liquid and air cooling technologies within a single integrated unit. It allows data centers to begin with efficient air-based direct expansion (DX) cooling and built-in economization, and seamlessly transition to liquid cooling as high-density computing demands increase—offering a flexible and future-ready approach to thermal management in AI-focused facilities.
Green Data Center Market Report Scope
Report Attribute
Details
Market size in 2025
USD 83.9 Billion
Estimated market size in 2026
USD 99.8 Billion
Projected market size by 2033
USD 296.7 Billion
Growth rate
CAGR of 16.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, Enterprise Size, End Use; Region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
ABB, Asetek Inc., Cisco Systems, Inc., Dell Inc., Delta Electronics, Inc. , Digital Realty Trust, Equinix, Inc., Fujitsu, General Electric, Hewlett Packard Enterprise Development LP, Hitachi Energy Ltd., Huawei Technologies Co., Ltd., IBM Corporation, Schneider Electric, Siemens, Vertiv Group Corp
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Green Data Center Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the green data center market report based on component, enterprise size, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solution
-
Monitoring & Management System
-
Cooling System
-
Networking System
-
Power Systems
-
Others
-
-
Services
-
Installation & Deployment
-
Consulting
-
Support & Maintenance
-
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Enterprises
-
SMEs
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
BFSI
-
Retail
-
IT & Telecom
-
Healthcare
-
Manufacturing
-
Government & Defense
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
- Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
India
-
China
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The green data center market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each v segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solutions
Solutions comprise the hardware, software, and infrastructure technologies deployed to improve the energy efficiency, sustainability, and operational performance of green data centers while reducing power consumption, carbon emissions, and environmental impact.
Services
Services include professional and managed offerings that support the planning, implementation, optimization, and lifecycle management of green data center infrastructure.
Segment - Enterprise Size
Revenue capture definition
Small and Medium-Sized Data Centers
The SMEs segment, with respect to the number of employees, generally includes organizations employing between 10 and 999 employees.
Large Enterprises
The Large enterprises segment, with respect to the number of employees, typically comprises organizations employing more than 1,000 employees for multinational corporations.
Segment - End Use
Revenue capture definition
BFSI
Banks, financial institutions, and insurance companies that deploy green data centers to support secure digital banking, payment processing, risk management, and regulatory compliance while reducing energy consumption.
Retail
Retailers and e-commerce companies that utilize green data centers to support online transactions, inventory management, customer analytics, and omnichannel operations with improved energy efficiency.
IT & Telecom
Technology companies, cloud service providers, managed service providers, and telecommunications operators that implement green data centers to support cloud computing, network services, AI workloads, and digital infrastructure sustainably.
Healthcare
Hospitals, healthcare providers, pharmaceutical companies, and research institutions that rely on green data centers to securely manage electronic health records, medical imaging, telemedicine, and healthcare analytics while minimizing environmental impact.
Manufacturing
Industrial organizations that deploy green data centers to support smart manufacturing, Industrial IoT (IIoT), automation, digital twins, predictive maintenance, and enterprise resource planning (ERP) systems using energy-efficient infrastructure.
Government & Defense
Government agencies and defense organizations that adopt green data centers to operate mission-critical applications, citizen services, cybersecurity systems, and secure data storage while meeting sustainability and energy efficiency mandates.
Others
Includes education, media and entertainment, energy and utilities, transportation and logistics, research organizations, and other industries utilizing green data center technologies to improve operational efficiency and reduce environmental impact.
Estimation Model
Layer
Question
Analysis
Digital Infrastructure & Sustainability Demand Layer
Who drives demand for Green Data Centers?
Identify organizations investing in sustainable digital infrastructure, including hyperscale cloud providers, colocation operators, enterprises, telecommunications companies, government agencies, BFSI, healthcare providers, manufacturing firms, research institutions, and edge data center operators. Assess the growing adoption of AI, cloud computing, ESG initiatives, and net-zero commitments to estimate the Total Addressable Market (TAM).
Data Center Infrastructure Expansion Layer
Where are Green Data Centers deployed?
Evaluate the expansion of hyperscale, enterprise, colocation, modular, and edge data centers across major regions. Analyze investments in new greenfield facilities and modernization of existing data centers with renewable energy, energy-efficient power systems, advanced cooling technologies, and intelligent infrastructure to determine the Operationally Reachable Market (ORM) for green data center solutions.
Green Technology Adoption Layer
Who adopts Green Data Center solutions?
Analyze adoption across hyperscale cloud providers, colocation companies, enterprises, government agencies, telecom operators, BFSI, healthcare, retail, manufacturing, education, and research organizations. Assess deployment of renewable energy integration, AI-enabled DCIM, liquid and immersion cooling, energy-efficient UPS systems, battery energy storage systems (BESS), waste heat recovery, and smart power management to estimate technology penetration and end-user demand.
Revenue Generation Layer
How is revenue generated?
Assess revenue generated from green data center solutions, including cooling systems, power systems, monitoring & management platforms, networking infrastructure, and supporting equipment. Include revenue from consulting, installation & deployment, and support & maintenance services. Analyze average selling prices (ASPs), project values, deployment volumes, retrofit investments, service contracts, and recurring maintenance revenue to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Green Data Center Vendor Competitive Benchmarking
Assessed leading data center chip vendors based on processor portfolio (CPU, GPU, AI ASIC, FPGA, DPU/IPU), AI performance, memory bandwidth, networking capabilities, process node, power efficiency, software ecosystem, packaging technologies, partnerships, pricing strategies, geographic presence, innovation roadmap, and market share.
Enables stakeholders to benchmark competitors, identify technology leaders, evaluate product differentiation, assess AI and cloud infrastructure capabilities, and formulate competitive product development and go-to-market strategies.
Chip Architecture & Technology Assessment
Evaluated demand across CPUs, GPUs, AI ASICs, FPGAs, DPUs, HBM, DDR memory, networking ASICs, and interconnect technologies based on workload performance, power efficiency, scalability, AI readiness, deployment models, and total cost of ownership (TCO).
Enables semiconductor vendors, OEMs, and investors to optimize product portfolios, prioritize R&D investments, identify emerging technology trends, and align chip development strategies with evolving AI, cloud computing, and hyperscale data center requirements.
Pricing & Average Selling Price (ASP) Analysis
Assessed ASP trends by chip category (CPU, GPU, AI ASIC, FPGA, HBM, networking chips), technology generation, performance tier, and customer segment.
Helps stakeholders estimate revenue potential, optimize pricing strategies, evaluate profitability, and improve market forecasting accuracy.
Frequently Asked Questions About This Report
The global green data center market size was valued at USD 83.9 billion in 2025 and is estimated at USD 99.8 billion for 2026.
The global green data center market is expected to grow at a CAGR of 16.8% from 2026 to 2033, reaching USD 296.7 billion by 2033.
North America dominated with 37.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The solution segment led with a 62.5% revenue share in 2025, while the services segment is the fastest-growing.
The large enterprises segment led with a 71.3% revenue share in 2025, while small & medium enterprises segment is the fastest-growing segment.
The BFSI segment held the largest share (over 23.0%) in 2025, while IT & Telecom segment is the fastest-growing segment.
Some key players operating in the green data center market include ABB, Asetek Inc., Cisco Systems, Inc., Dell Inc., Delta Electronics, Inc., Digital Realty Trust, Equinix, Inc., Fujitsu, General Electric, Hewlett Packard Enterprise Development LP, Hitachi Energy Ltd., Huawei Technologies Co., Ltd., IBM Corporation, Schneider Electric, Siemens, Vertiv Group Corp.
The growing focus on reducing carbon emissions, energy consumption, and other overall resource usage is boosting the growth of the global green data center market. Growing climate change awareness and the need for environmental sustainability have heightened the demand for more enhanced energy-efficient and nature-friendly solutions around various applications, including data centers.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


