
- Home
- »
- Plastics, Polymers & Resins
- »
-
Healthcare Passive Cold Chain Packaging Market Size, Growth Report, 2026-2033GVR Report cover

Healthcare Passive Cold Chain Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Insulated Containers, Insulated Pallet Shippers, Gel Packs, Dry Ice Systems, PCM), By Temperature Requirement, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$7.7BMarket Estimate, 2026
$8.6BMarket Forecast, 2033
$18.8BCAGR, 2026–2033
11.9%Healthcare Passive Cold Chain Packaging Market Summary
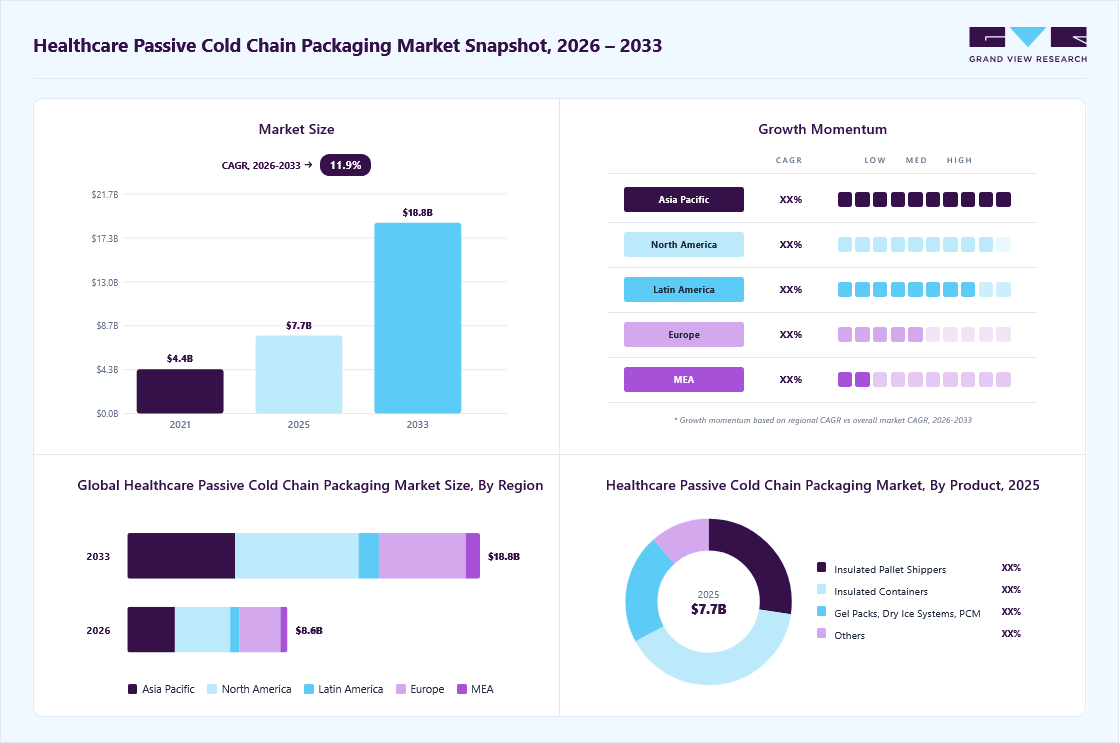
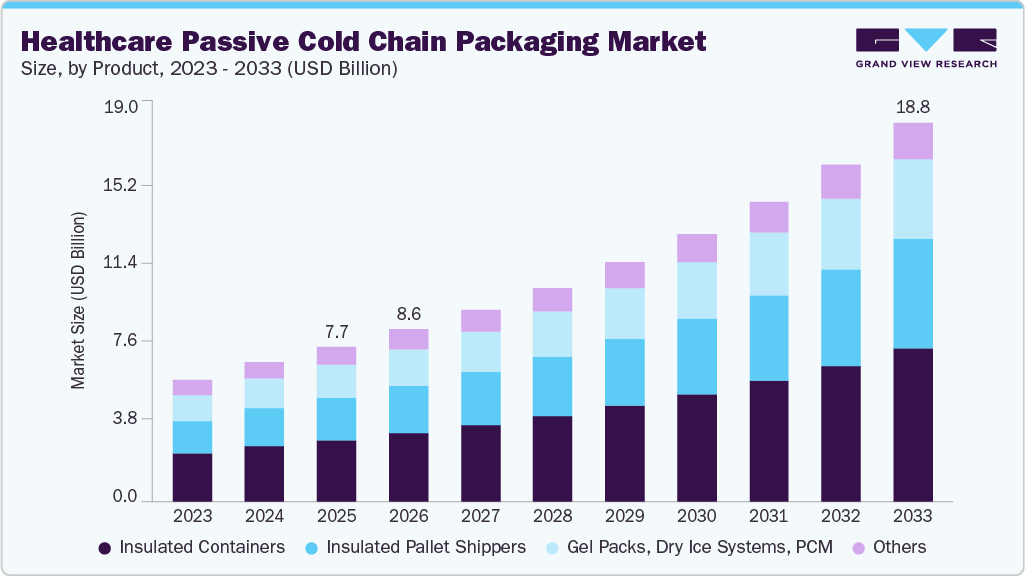
The global healthcare passive cold chain packaging market size was valued at USD 7.7 billion in 2025 and is projected to grow from USD 8.6 billion in 2026 to USD 18.8 billion by 2033, at a CAGR of 11.9% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 34.5% in 2025. Rising demand for temperature-sensitive pharmaceuticals, including vaccines, biologics, and specialty drugs, is significantly driving the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Insulated containers segment dominated the healthcare passive cold chain packaging market in 2025, accounting for 39.7% of revenue share
- By temperature requirements: refrigerated or chilled 2°C to 8°C segment accounted for 46.8% of the healthcare passive cold chain packaging market in 2025.
- By end use: Pharmaceutical and biopharmaceutical companies segment dominated the healthcare passive cold chain packaging market in 2025, accounting for 40.4% of total market share.
Regional Highlights
- Largest regional market: North America (34.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. healthcare passive cold chain packaging industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 7.7 Billion
- Estimated market size in 2026: USD 8.6 Billion
- Projected market size by 2033: USD 18.8 Billion
- CAGR (2026-2033): 11.9%
Prism AI by Grand View Research Free to tryAsk a question about the healthcare passive cold chain packaging marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Besides, the expansion of global pharmaceutical distribution networks and stricter regulatory requirements for maintaining product integrity during transit are further accelerating market growth. Products such as monoclonal antibodies, cell and gene therapies, and specialty injectables require strict temperature control, typically within 2 to 8 degrees Celsius or frozen conditions throughout storage and transportation. Any temperature excursion can compromise product efficacy and safety, making reliable passive packaging solutions such as insulated shippers, phase change materials, and thermal liners essential. The increasing global demand for these high-value therapeutics, along with large-scale immunization programs, continues to accelerate adoption.
 To learn more about this report, Download Free Sample Report
An increasing complexity of global pharmaceutical supply chains, combined with the need for cost-efficient logistics, is also boosting the market growth. Passive cold chain packaging provides operational advantages, including lower transportation costs, reduced reliance on active refrigeration systems, and improved flexibility in handling and distribution. This is particularly relevant in emerging markets where infrastructure limitations and inconsistent power supply create challenges for active cold chain systems. In addition, the rise of direct-to-patient delivery models and decentralized clinical trials is further strengthening demand for portable and reliable temperature-controlled packaging solutions.
Regulatory compliance requirements are also significantly influencing market growth. Health authorities such as the US Food and Drug Administration and the European Medicines Agency have established stringent guidelines for temperature-controlled pharmaceutical logistics, requiring validated packaging solutions and continuous monitoring. This has driven pharmaceutical companies and logistics providers to invest in high-performance passive packaging systems that ensure compliance and mitigate product risk. At the same time, sustainability considerations are becoming increasingly important, with a growing focus on reusable and recyclable packaging formats that support innovation and long-term market expansion.
Market Concentration & Characteristics
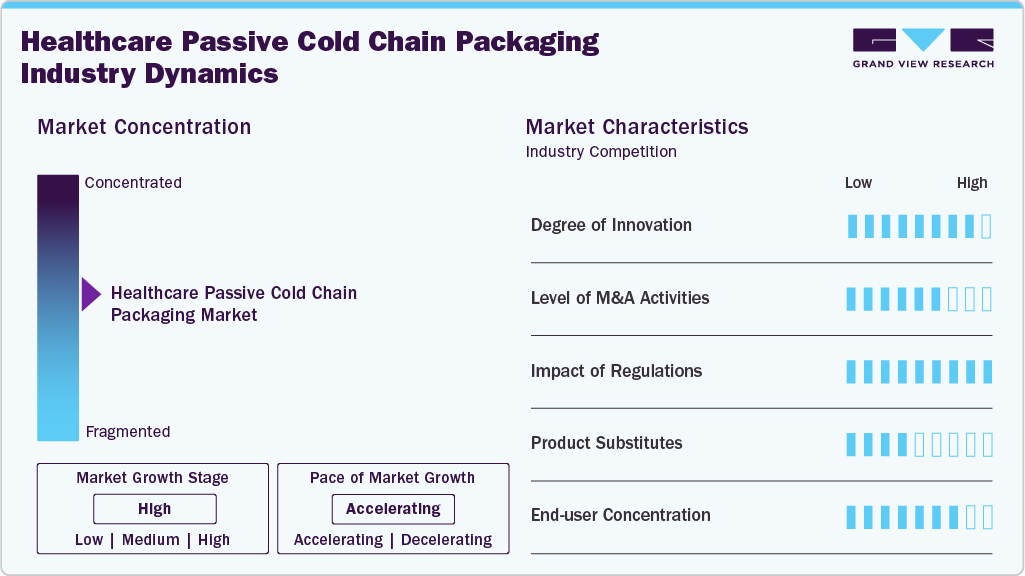
The healthcare passive cold chain packaging market is characterized by stringent regulatory requirements and high-quality assurance standards. Packaging solutions must comply with stringent global standards for temperature control, validation, and traceability, particularly for the transport of pharmaceuticals and biologics. This results in a strong emphasis on performance reliability, qualification testing, and documentation. Market participants must continuously invest in R&D and validation capabilities to meet evolving compliance standards and ensure product integrity across diverse distribution environments.
 To learn more about this report, Download Free Sample Report
The market also exhibits a service-oriented and logistics-integrated structure. Companies increasingly offer end-to-end solutions that include packaging design, testing, leasing models, reverse logistics, and real-time temperature monitoring. This integration is driven by the growing complexity of pharmaceutical supply chains and the need for reliable last-mile delivery. Additionally, demand patterns are closely tied to pharmaceutical production cycles, clinical trial activity, and global vaccination programs, making the market partially demand-driven and sensitive to healthcare industry trends.
Product Insights
The insulated containers segment dominated the healthcare passive cold chain packaging market in 2025, accounting for 39.7% of revenue share, due to their superior thermal performance and ability to maintain stable temperature ranges for extended durations across complex distribution cycles. Their reusability, durability, and compatibility with phase change materials make them a cost-efficient solution for high-value pharmaceutical shipments. Besides, strong adoption by pharmaceutical companies and logistics providers of bulk transport and long-distance shipping further supported the segment's leadership.
Insulated pallet shippers are gaining strong traction in the healthcare passive cold chain packaging market due to their ability to transport large-volume pharmaceutical shipments while maintaining consistent temperature control over extended transit durations. These solutions are designed for bulk logistics, offering high payload Temperature Requirement, robust insulation, and compatibility with phase change materials, making them suitable for long-distance and international distribution. Additionally, their reusable design and integration with standardized pallet systems improve handling efficiency, reduce overall logistics costs, and support sustainability objectives for pharmaceutical companies.
Temperature Requirement Insights
The refrigerated or chilled 2°C to 8°C segment accounted for 46.8% of the healthcare passive cold chain packaging market in 2025, driven by the high volume of pharmaceuticals, such as vaccines, insulin, and biologics, that require this temperature range for stability and efficacy. This range is widely used across global distribution networks, making it the most operationally critical segment for pharmaceutical logistics. Additionally, increasing immunization programs and the expansion of biologics pipelines have further strengthened demand for reliable chilled passive packaging solutions.
The frozen (-20°C to ±5°C) segment is driven by the increasing demand for temperature-sensitive biologics, specialty drugs, and certain vaccines that require sub-zero storage to maintain stability and shelf life. This segment is critical for long-haul and international shipments where extended temperature control is essential to prevent product degradation. Additionally, the growing pipeline of advanced therapies and the expansion of global cold chain infrastructure are supporting the adoption of passive packaging solutions for frozen temperature ranges.
End Use Insights
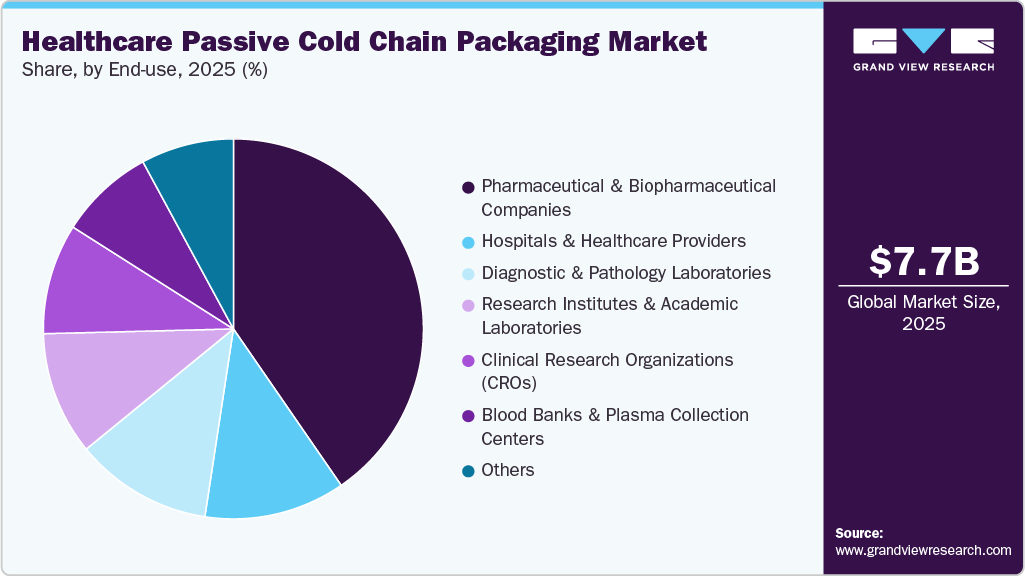
The pharmaceutical and biopharmaceutical companies segment dominated the healthcare passive cold chain packaging market in 2025, accounting for 40.4% of total market share, driven by the high production and global distribution of temperature-sensitive drugs, including biologics, vaccines, and specialty therapeutics. These companies require reliable and validated packaging solutions to ensure product integrity and regulatory compliance across complex supply chains. Additionally, increased R&D activities, clinical trials, and the commercialization of advanced therapies have further strengthened demand for passive cold chain packaging in this segment.
 To learn more about this report, Download Free Sample Report
The hospitals and healthcare providers segment is driven by the growing need for safe storage and last-mile handling of temperature-sensitive drugs, vaccines, and biologics within clinical settings. These facilities rely on passive cold chain packaging for internal transport, emergency use, and short-term storage where flexibility and reliability are critical. In addition, increasing patient volumes, immunization programs, and decentralized healthcare delivery models are further supporting demand in this segment.
Regional Insights
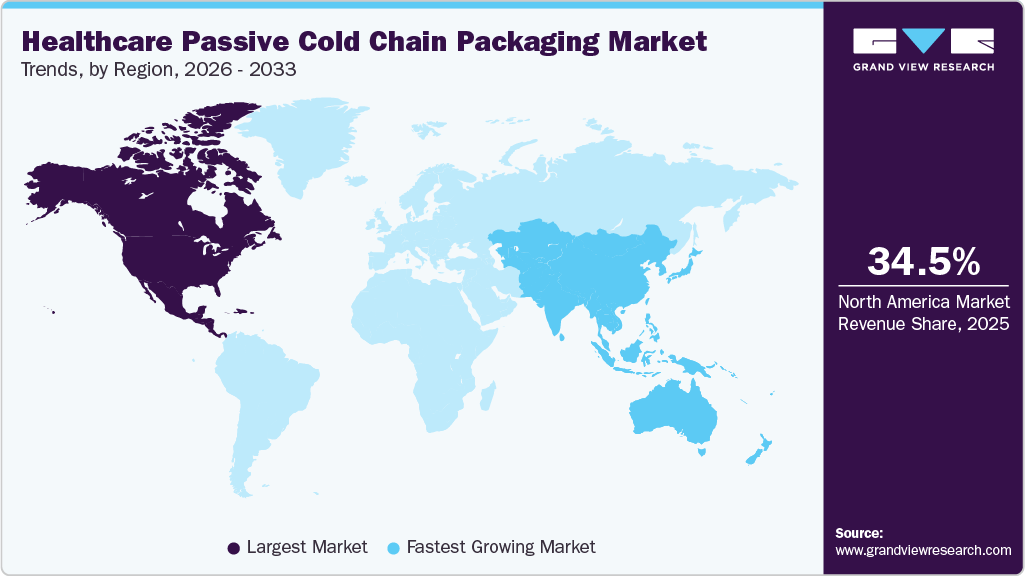
The North America healthcare passive cold chain packaging industry dominated the global market 34.47% in 2025 due to the strong pharmaceutical and biotechnology base in the U.S. and Canada, with high production and export of temperature-sensitive biologics and specialty drugs. The region benefits from advanced cold chain infrastructure and the presence of leading companies, including Pfizer, Moderna, and packaging providers Sonoco ThermoSafe and Pelican BioThermal. Additionally, stringent regulatory frameworks and strong investments in vaccine distribution and clinical research further reinforced the region’s market leadership.
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Passive Cold Chain Packaging Market Trends
The healthcare passive cold chain packaging industry in the U.S. dominated the market in North America in 2025, driven by its large-scale production and distribution of temperature-sensitive pharmaceuticals, including biologics and vaccines. The presence of major pharmaceutical companies such as Pfizer and Johnson & Johnson, along with advanced cold chain infrastructure, supports high demand for reliable packaging solutions.
Asia Pacific Healthcare Passive Cold Chain Packaging Market Trends
The healthcare passive cold chain packaging industry in the Asia Pacific is emerging as a high-growth region, driven by expanding pharmaceutical manufacturing hubs in China and India, along with increasing vaccine production and biologics demand. Countries such as Japan and South Korea are also contributing through advanced healthcare infrastructure and growing adoption of temperature-controlled logistics. Additionally, rising government focus on immunization programs, improving cold chain infrastructure, and the presence of regional players such as CSafe and Softbox Systems are supporting strong market expansion.
The China healthcare passive cold chain packaging industry is a key growth market, driven by its rapidly expanding pharmaceutical and biotechnology manufacturing base, particularly in vaccines and biologics. Strong government support for healthcare infrastructure, along with large-scale immunization programs, is increasing demand for reliable temperature-controlled packaging solutions. Additionally, the presence of domestic players such as Sinopharm and WuXi AppTec, coupled with rising exports of temperature-sensitive drugs, is further accelerating market growth.
Europe Healthcare Passive Cold Chain Packaging Market Trends
The healthcare passive cold chain packaging industry in Europe represents a mature and highly regulated market for healthcare passive cold chain packaging, driven by strong pharmaceutical manufacturing in Germany, France, and the UK. The region benefits from advanced cold chain logistics infrastructure and the presence of leading pharmaceutical companies such as Roche and Sanofi, along with packaging providers such as Envirotainer. In addition, stringent regulatory oversight by agencies such as the European Medicines Agency ensures high adoption of validated and compliant passive packaging solutions across the region.
Key Healthcare Passive Cold Chain Packaging Company Insights
The healthcare passive cold chain packaging market is characterized by a moderately consolidated and technology-driven competitive landscape, with the presence of global players such as Sonoco ThermoSafe, Pelican BioThermal, Envirotainer, and Cold Chain Technologies. Competition is primarily based on thermal performance, duration capabilities, cost efficiency, and compliance with stringent regulatory standards. Companies are increasingly focusing on innovation in phase change materials, reusable packaging solutions, and digital monitoring technologies to differentiate their offerings. Strategic initiatives such as partnerships with pharmaceutical firms, expansion of rental and reverse logistics models, and geographic expansion into emerging markets are key approaches to strengthening market position.
-
In November 2025, Peli BioThermal LLC opened an expanded service center in Allentown, Pennsylvania, to increase throughput for reusable and on-demand single-use shippers. The upgrade expands Temperature Requirement for refurbishment, testing, and Crēdo on-demand programs, shortening lead times for U.S. customers and strengthening local availability for pharmaceutical and biotech cold shipments.
-
In April 2025, Peli BioThermal LLC announced the acquisition of the Evo product line (cryogenic shipping solutions). The addition brings LN2 dry-vapor cryogenic shippers and connected monitoring to Peli’s portfolio, accelerating offerings for ultra-cold cell and gene therapy logistics used by U.S. developers and clinical trial sponsors.
-
In March 2025, Cold Chain Technologies acquired Global Cold Chain Solutions (GCCS), a specialist in passive cold chain solutions with a strong presence in Australia and India. This strategic move expands CCT's footprint in key Asia-Pacific markets, enhancing its portfolio of temperature-controlled packaging for pharmaceuticals and biotech shipments amid rising demand for reliable cold chain logistics in emerging regions.
Key Healthcare Passive Cold Chain Packaging Companies:
The following key companies have been profiled for this study on the healthcare passive cold chain packaging market.
- Sonoco ThermoSafe
- Cold Chain Technologies
- Peli BioThermal LLC
- Cryopak
- CSafe
- DGP Intelsius LLC
- TemperPack
- Taylor Corporation
- Ernest Packaging Solutions
- TEMPACK
- Insulated Products Corporation
Healthcare Passive Cold Chain Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.7 billion
Estimated Market size in 2026
USD 8.6 billion
Projected Market size by 2033
USD 18.8 billion
Growth rate
CAGR of 11.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, temperature requirement, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Sonoco ThermoSafe; Cold Chain Technologies; Pelican BioThermal; Cryopak; CSafe; DGP Intelsius LLC; TemperPack; Taylor Corporation; Ernest Packaging Solutions; TEMPACK; Insulated Products Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Passive Cold Chain Packaging Market Report Segmentation
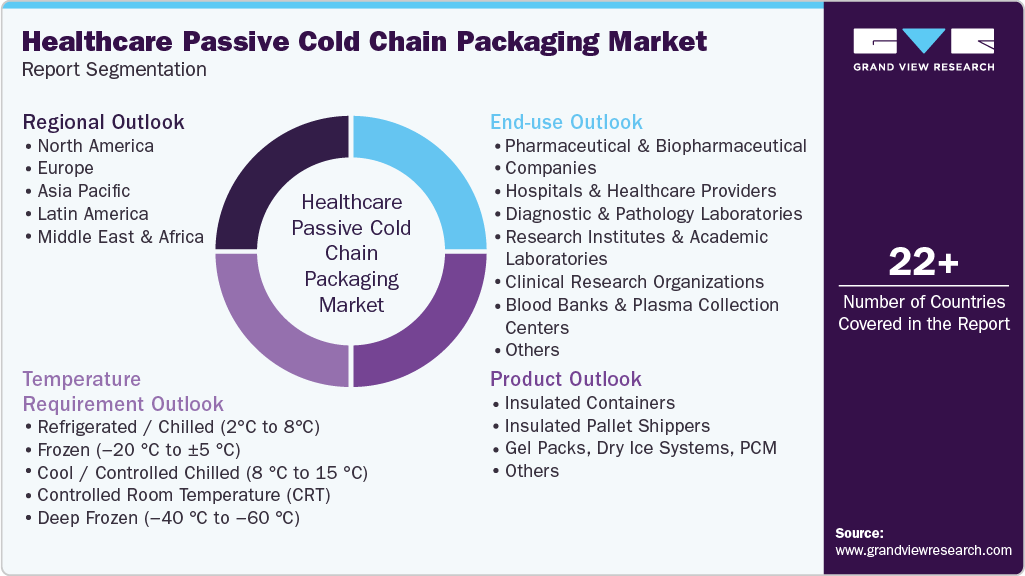
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global healthcare passive cold chain packaging market report on the basis of product, temperature requirement, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Insulated Containers
-
Insulated Pallet Shippers
-
Gel Packs, Dry Ice Systems, PCM
-
Others
-
-
Temperature Requirement Outlook (Revenue, USD Million, 2021 - 2033)
-
Refrigerated / Chilled (2°C to 8°C)
-
Frozen (-20 °C to ±5 °C)
-
Cool / Controlled Chilled (8 °C to 15 °C)
-
Controlled Room Temperature (CRT)
-
Deep Frozen (-40 °C to -60 °C)
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biopharmaceutical Companies
-
Hospitals & Healthcare Providers
-
Diagnostic & Pathology Laboratories
-
Research Institutes & Academic Laboratories
-
Clinical Research Organizations (CROs)
-
Blood Banks & Plasma Collection Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
Insulated containers segment led with a 39.7% revenue share in 2025.
Refrigerated or chilled 2°C to 8°C segment held the largest revenue share 46.8% in 2025.
Pharmaceutical and biopharmaceutical companies segment held the largest share (over 40.4%) in 2025.
North America dominated with a 34.5% revenue share in 2025.
The global healthcare passive cold chain packaging market was estimated at around USD 7.7 billion in the year 2025 and is expected to reach around USD 8.6 billion in 2026.
The pharmaceutical & biopharmaceutical companies segment led the healthcare passive cold chain packaging market in 2025 due to the high demand for temperature-sensitive biologics, vaccines, and specialty drugs requiring strict cold chain compliance throughout global distribution.
The key players in the healthcare passive cold chain packaging market include Sonoco ThermoSafe; Cold Chain Technologies; Pelican BioThermal; Cryopak; CSafe; DGP Intelsius LLC; TemperPack; Taylor Corporation; Ernest Packaging Solutions; TEMPACK; and Insulated Products Corporation.
The healthcare passive cold chain packaging market is driven by rising demand for temperature-sensitive biologics and vaccines, expansion of global pharmaceutical supply chains, and increasing regulatory requirements for safe and compliant drug transportation.
The global healthcare passive cold chain packaging market is expected to grow at a compound annual growth rate of 11.9% from 2026 to 2033 to reach around USD 18.8 billion by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


