
- Home
- »
- Smart Textiles
- »
-
Healthcare Personal Protective Equipment Market Report 2033GVR Report cover

Healthcare Personal Protective Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Hand Protection, Respiratory Protection), By End-use (Hospitals, Home Healthcare, Outpatient/Primary Care Facilities), By Region, And Segment Forecasts
Market Size, 2025
$13.0BMarket Estimate, 2026
$14.3BMarket Forecast, 2033
$28.5BCAGR, 2026–2033
10.4%Healthcare Personal Protective Equipment Market Summary
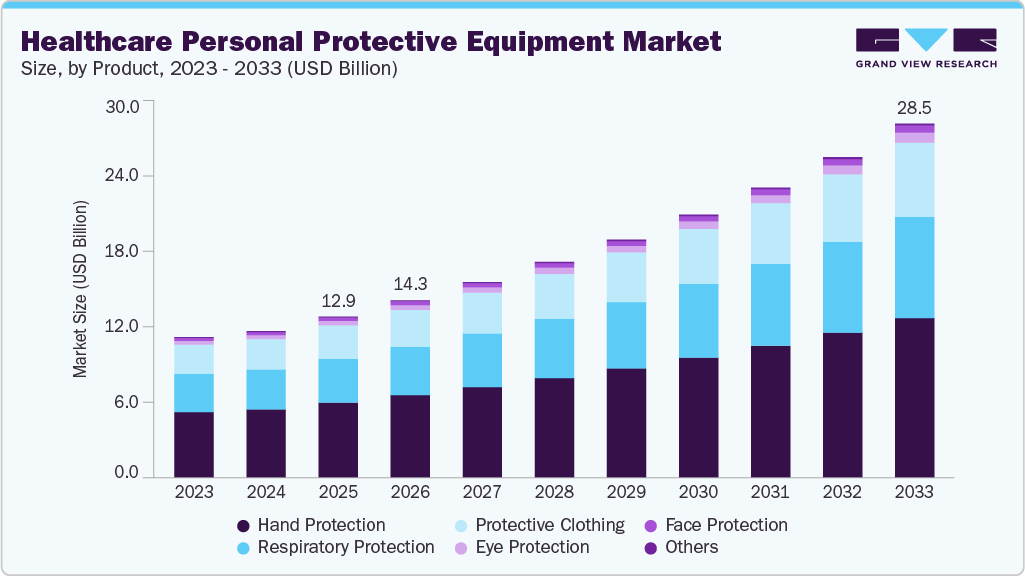
The global healthcare personal protective equipment market size was valued at USD 13.0 billion in 2025 and is projected to grow from USD 14.3 billion in 2026 to USD 28.5 billion by 2033, at a CAGR of 10.4% from 2026 to 2033. Europe dominated the global market, accounting for a revenue share of 32.9% in 2025. The rising prevalence of infectious diseases and heightened awareness of infection control are major drivers of the industry.
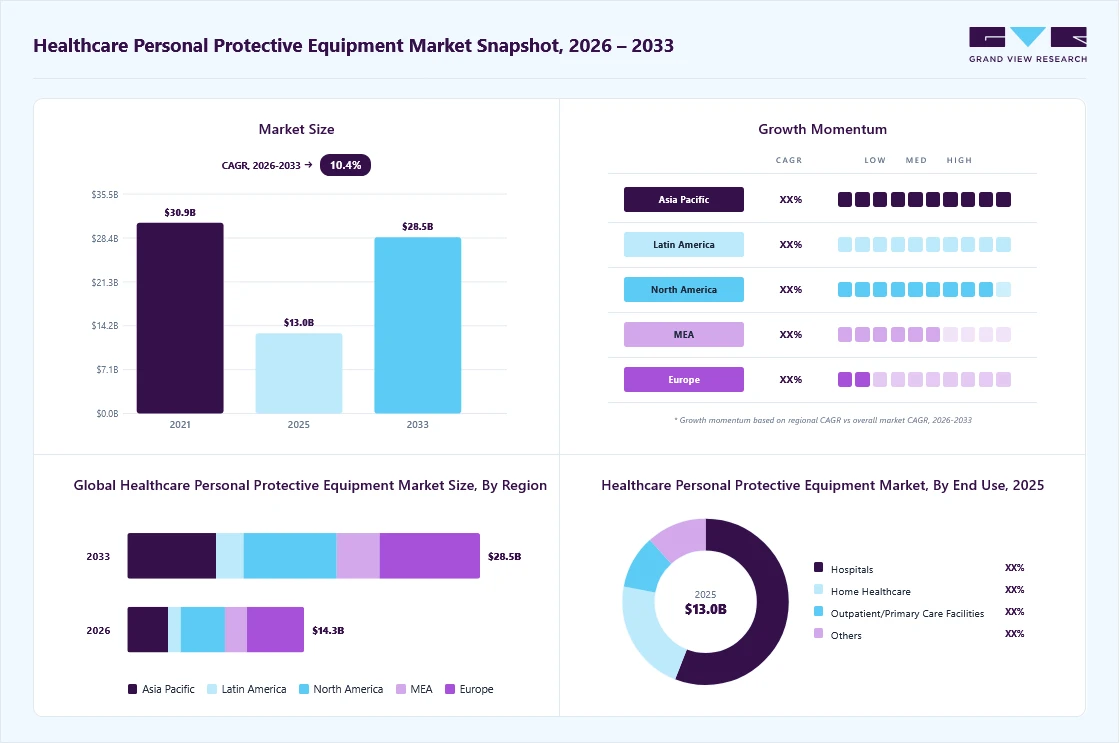 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Hand protection segment held the largest market share of 46.6% in 2025.
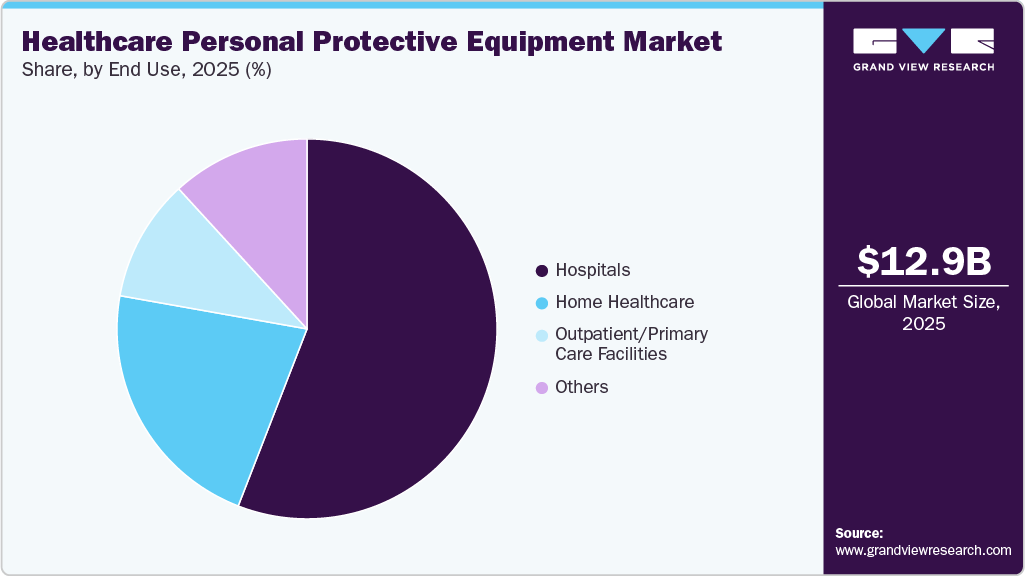
- By end use: Hospitals segment held the largest market share of 55.9% in 2025.
Regional Highlights
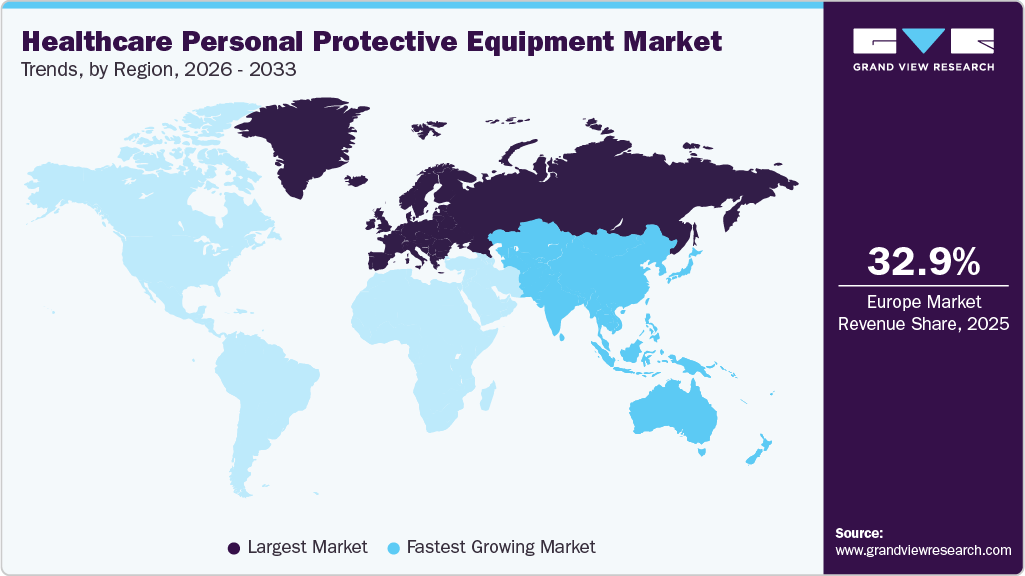
- Largest regional market: Europe (32.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Germany held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 13.0 Billion
- Estimated market size in 2026: USD 14.3 Billion
- Projected market size by 2033: USD 28.5 Billion
- CAGR (2026-2033): 10.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing demand for personal protective equipment (PPE) is supported by the continued integration of PPE into routine infection prevention and occupational safety protocols across healthcare settings. Rising Infection Prevention Requirements and Occupational Safety Standards: The persistent burden of healthcare-associated infections (HAIs), antimicrobial resistance, and infectious disease outbreaks is reinforcing infection prevention and control requirements across healthcare facilities. WHO’s 2024 global IPC report identifies HAIs as a continuing threat in hospitals and clinics and links effective IPC practices with reducing transmission and AMR.
 To learn more about this report, Download Free Sample Report
In the U.S., CDC guidance updated in 2025 continues to emphasize occupational infection prevention, while its standard precautions require risk-based use of gloves, gowns, masks, eye protection, and other PPE when exposure to infectious materials is anticipated. These requirements create recurring procurement needs across hospitals, outpatient facilities, laboratories, and other care settings, supporting a relatively stable underlying demand base beyond pandemic-related purchasing cycles.
Market Dynamics
The ongoing need for infection prevention and occupational safety across healthcare settings supports the personal protective equipment market. Persistent healthcare-associated infections and infectious disease risks continue to reinforce the need for PPE, while established infection-control protocols sustain demand beyond pandemic-related requirements. Hospitals, clinics, laboratories, and other care facilities, therefore, remain consistent sources of PPE consumption.
The expansion of healthcare delivery across hospitals, outpatient facilities, long-term care, dental practices, laboratories, and home-based care is widening the settings in which healthcare workers require occupational protection. WHO estimates that 136 million people work in the health and social work sector globally, while healthcare personnel face biological, chemical, physical, and other occupational hazards. PPE therefore represents a recurring operational requirement across a broad and increasingly distributed healthcare workforce, rather than a product limited to hospital-based acute care. This trend is particularly relevant as more complex care moves beyond traditional hospitals. NIOSH identifies hospitals, ambulatory healthcare services, nursing and residential care facilities, dental offices, clinics, and private home care as settings requiring personal protective equipment for healthcare personnel. Its 2024 targets document also notes the expanding role of non-hospital healthcare settings in delivering complex care. This diversification increases the addressable customer base for gloves, protective clothing, masks, respirators, eye protection, and other specialized PPE, while creating demand for products adapted to different exposure risks and working environments.
Healthcare PPE remains highly price-sensitive, particularly for standardized products such as examination gloves, masks, and gowns that are purchased in large volumes. Manufacturers must also manage fluctuations in raw material prices, manufacturing capacity, freight costs, and inventory requirements while meeting product quality and regulatory specifications. For healthcare providers, this creates pressure to balance protection levels and product performance against procurement budgets. The resulting emphasis on price and supply continuity can limit the adoption of higher-cost specialized PPE unless its performance advantage is clearly demonstrated.
Environmental concerns surrounding disposable PPE are creating opportunities for manufacturers to develop products that reduce material use, improve recyclability, or incorporate lower-impact materials without compromising barrier performance. WHO's PPE guidance specifically identifies environmentally responsible disposal, human-factors design, and the ability of certain PPE to withstand repeated disinfection among relevant product considerations. This creates scope for suppliers to differentiate through material selection, packaging, reuse-compatible designs, and waste-reduction strategies. Extended PPE use can lead to heat, restricted movement, communication difficulties, and discomfort, making fit and ergonomic design relevant to healthcare worker compliance. WHO recommends PPE designs that provide an unobstructed field of vision, enable communication, minimize junctions between PPE components, and incorporate human-factors considerations for sizing and comfort. Manufacturers that address these requirements while maintaining required protection levels can move beyond commodity-based competition and target higher-value clinical applications.
Market Concentration & Characteristics
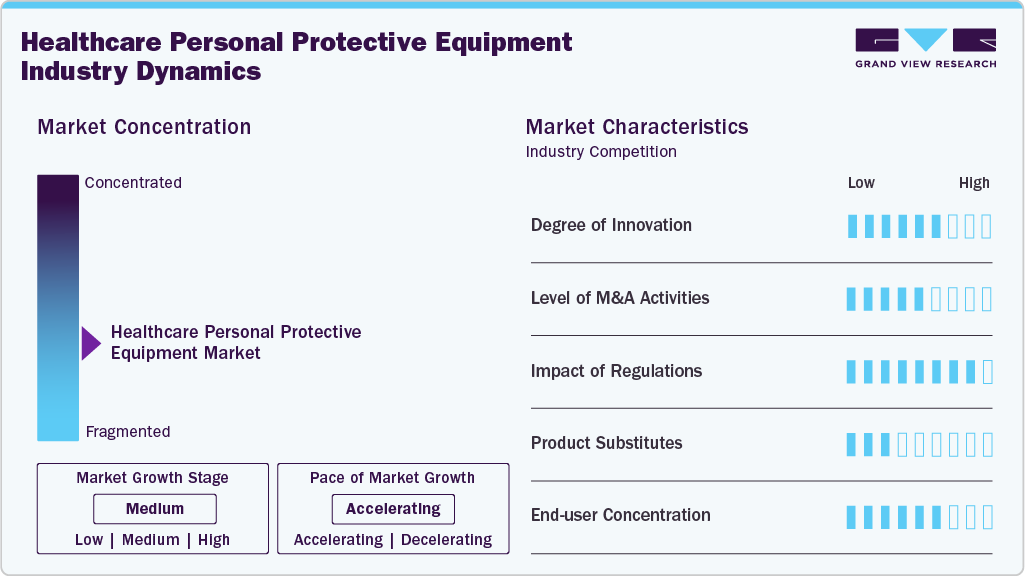
The healthcare personal protective equipment industry remains moderately fragmented, with international manufacturers competing alongside regional and specialized suppliers across gloves, masks, gowns, protective eyewear, and respiratory protection. Scale provides advantages in manufacturing capacity, distribution, quality systems, and institutional procurement, while commodity-oriented products such as basic masks and examination gloves allow competition from a broader supplier base. However, requirements become more demanding for products used in higher-risk applications, where performance testing, quality controls, regulatory clearances, and consistent supply are important considerations in purchasing.
Product innovation is largely application-driven, with manufacturers focusing on barrier performance, breathability, fit, ergonomics, and wearer comfort. Development is also shifting toward materials and designs that can improve protection without increasing heat or restricting movement during extended use. Regulatory requirements remain an important competitive filter. In the U.S., OSHA requires employers to provide appropriate PPE where healthcare workers face occupational exposure to blood or other potentially infectious materials, with selection based on the anticipated exposure and task. CDC guidance similarly calls for risk-based selection of gloves, gowns, masks, and eye protection. These requirements support recurring demand while increasing the importance of product quality, certification, and supply reliability in institutional purchasing decisions.
 To learn more about this report, Download Free Sample Report
Hospitals and large healthcare networks represent a significant concentration of demand for healthcare PPE due to their high patient volumes and large clinical workforces. Procurement decisions increasingly balance unit price with product performance, supply continuity, standardization, and supplier reliability. OSHA requirements also place the responsibility on employers to provide appropriate PPE and, where applicable, to ensure its availability, replacement, and disposal. This purchasing structure favors suppliers capable of maintaining consistent specifications and high-volume fulfillment, while group purchasing and centralized procurement can intensify price competition for standardized products such as gloves, masks, and gowns.
Analyst Perspective
The healthcare personal protective equipment market is evolving as providers place greater emphasis on infection prevention, occupational safety, and preparedness for infectious disease outbreaks. Demand spans gloves, gowns, masks, face protection, and other products used across hospitals, clinics, laboratories, and emergency care settings. Procurement is increasingly influenced by product quality, regulatory compliance, supply continuity, and inventory availability. Manufacturers are developing improved materials, ergonomic designs, and application-specific products that balance protection, comfort, and usability. Supply-chain resilience is also gaining importance as healthcare organizations seek reliable inventories and reduced supplier dependence. Future competition will increasingly center on product performance, manufacturing scalability, supply reliability, cost efficiency, and compliance with evolving infection-control and sustainability requirements.
Product Insights
Hand protection accounted for an estimated 46.6% of the healthcare personal protective equipment market revenue in 2025, reflecting the broad use of medical gloves across hospitals, clinics, laboratories, dental practices, and other care environments. CDC Standard Precautions recommend gloves whenever contact with blood, body fluids, mucous membranes, non-intact skin, or potentially contaminated equipment is anticipated, while disposable gloves should be removed between patients and changed when contamination occurs during care. This task-specific and largely single-use pattern creates a recurring consumption base, particularly for examination and surgical gloves.
Respiratory protection is anticipated to grow at the fastest CAGR of 13.9% over the forecast period, as healthcare facilities strengthen controls for airborne and aerosol-transmitted hazards. CDC's 2025 healthcare respiratory-protection guidance identifies N95 and other respirators as PPE designed to provide defined filtration and close facial fit, with selection determined by the airborne hazard, exposure conditions, and applicable requirements. Their use extends beyond pandemic preparedness to clinical situations involving tuberculosis, measles, varicella, and aerosol-generating procedures. The growing emphasis on fit testing, respiratory protection programs, and the appropriate selection of respirators is therefore expanding demand for higher-performance respiratory PPE across healthcare settings.
End Use Insights
Hospitals dominated the healthcare personal protective equipment industry, accounting for 55.9% revenue share in 2025. High patient volumes, diverse clinical procedures, and continuous exposure to potentially infectious materials create a substantial, recurring need for gloves, gowns, masks, respirators, and eye protection. CDC Standard Precautions require healthcare personnel to select PPE based on the anticipated exposure and nature of patient interaction, supporting consistent institutional consumption across departments. Large-scale procurement, centralized purchasing, and routine replacement further sustain hospitals as the largest end-use segment.
 To learn more about this report, Download Free Sample Report
Home healthcare is expected to grow at a significant CAGR of 10.4% from 2026 to 2033, supported by the broader shift toward care delivery outside traditional facilities. As more clinical and caregiving activities occur in residential settings, caregivers and home-health professionals require task-appropriate protection against exposure to body fluids and infectious materials. WHO guidance for home care emphasizes risk-based PPE selection, including masks, eye protection, gloves, and gowns where appropriate. The expansion of home-based care, therefore, broadens PPE consumption beyond institutional healthcare settings and supports faster segment growth over the forecast period.
Regional Insights
North America maintained steady growth in the healthcare personal protective equipment market, supported by its extensive healthcare infrastructure, established infection prevention practices, and stringent occupational safety requirements. The U.S. regulatory framework requires employers to assess workplace hazards and provide appropriate PPE where exposure risks warrant its use. Healthcare facilities, therefore, maintain recurring procurement across gloves, protective clothing, masks, respirators, and eye and face protection. The scale of regional healthcare activity further supports demand; U.S. healthcare spending reached USD 5.3 trillion in 2024, with hospital expenditures increasing 8.9% to USD 1.63 trillion.
The U.S. healthcare personal protective equipment market accounted for the largest share of North America in 2025, reflecting its large healthcare system, high volume of clinical services, and established workplace-safety framework. OSHA requires employers to conduct workplace hazard assessments and select PPE that appropriately protects affected employees, while healthcare-specific requirements incorporate standard and transmission-based precautions. These institutional requirements, combined with substantial hospital and clinical spending, create a broad recurring demand base for healthcare PPE.
Europe Healthcare Personal Protective Equipment Market Trends
Europe dominated the global healthcare personal protective equipment industry, accounting for an estimated 32.9% revenue share in 2025. The region benefits from established healthcare systems, extensive institutional procurement, and a harmonized regulatory framework governing PPE placed on the EU market. Regulation (EU) 2016/425 establishes essential health and safety requirements and conformity-assessment obligations for PPE, while CE marking provides evidence of compliance with applicable EU legislation. These requirements support demand for certified protective products across hospitals and other healthcare settings.
 To learn more about this report, Download Free Sample Report
The Germany healthcare personal protective equipment market accounted for a substantial share of Europe in 2025, supported by its large healthcare system and high healthcare expenditure. Germany's total healthcare expenditure reached approximately USD 580 billion in 2024, including around USD 140 billion for hospitals. This broad institutional base supports recurring procurement of protective products across hospitals, nursing facilities, and other care settings. Germany's established healthcare and distribution infrastructure further supports demand for regulated PPE products.
Asia Pacific Healthcare Personal Protective Equipment Market Trends
The Asia Pacific healthcare personal protective equipment industry is expected to expand at a CAGR of 11.8% from 2026 to 2033, supported by expanding healthcare access, rising clinical activity, and investments in healthcare infrastructure. WHO data indicate continued progress in health service coverage across South-East Asia and the Western Pacific, although substantial gaps remain. This expansion is increasing PPE requirements across hospitals, clinics, primary care facilities, and other healthcare settings. At the same time, regional manufacturing capacity and evolving medical-device regulatory frameworks are strengthening local supply capabilities and supporting the wider availability of regulated protective products.
The China healthcare personal protective equipment market dominated Asia Pacific in 2025, supported by the scale of its healthcare system and extensive medical-product manufacturing base. China recorded 10.1 billion healthcare visits and 3.1 billion hospital discharges in 2024, creating a substantial recurring requirement for infection-control products across healthcare facilities. The country's manufacturing ecosystem further supports regional supply, while the National Medical Products Administration has continued to strengthen medical-device manufacturing and quality requirements, including revised Good Manufacturing Practice requirements taking effect in November 2026. These factors support both domestic PPE demand and supply availability across the broader Asia Pacific market.
Latin America Healthcare Personal Protective Equipment Market Trends
Latin America healthcare personal protective equipment industry is experiencing moderate growth as healthcare systems strengthen infection prevention and expand access to primary and hospital-based services. PAHO reported that public health expenditure accounted for an average of 55.6% of total health resources across Latin America and the Caribbean in 2023. However, investment levels and healthcare capacity remain uneven across countries. At the same time, regional programs are strengthening infection prevention and control practices, including hospital outbreak preparedness and healthcare-associated infection surveillance. These developments are supporting more systematic PPE procurement across hospitals, primary-care facilities, and other healthcare settings.
Middle East & Africa Healthcare Personal Protective Equipment Market Trends
The Middle East and Africa healthcare personal protective equipment industry recorded growth as countries strengthened healthcare infrastructure, infection prevention and control (IPC) programs, and preparedness for infectious disease outbreaks. WHO has identified sustained investment in IPC and WASH as a priority for protecting patients and health workers, particularly in settings where resources and technical capacity remain constrained. Across the African Region, efforts to strengthen IPC governance, health worker safety, and outbreak readiness have continued, while the Eastern Mediterranean Region has expanded IPC capacity within emergency response frameworks. These initiatives are supporting more systematic PPE requirements across hospitals, clinics, and emergency-care settings.
Key Healthcare Personal Protective Equipment Company Insights
The global healthcare personal protective equipment market is highly competitive, with manufacturers focusing on portfolio expansion, manufacturing capacity, product performance, and distribution capabilities. Strategic acquisitions are also reshaping the industry. Competition increasingly centers on regulatory compliance, supply reliability, protection, fit, and wearer comfort, particularly across healthcare-specific gloves, protective apparel, masks, respirators, and eye protection.
Key Healthcare Personal Protective Equipment Companies
The following key companies have been profiled for this study on the healthcare personal protective equipment market.
-
3M
-
Alpha Pro Tech, Ltd.
-
Ansell Limited
-
Cardinal Health
-
DuPont
-
Dynarex Corporation
-
Hartalega Holdings Berhad
-
Kossan Rubber Industries Bhd
-
Lakeland Industries, Inc.
-
Medline
-
MSA Safety
-
Owens & Minor Products & Healthcare Services
-
PIP Global Safety
-
Top Glove Corporation Bhd
Recent Developments
-
In August 2026, Medline expanded its healthcare PPE offering through a dedicated PPE solution covering examination gloves, medical face masks, respirators, and medical gowns, together with facility-specific PPE recommendations and training.
-
In January 2026, Ansell launched the TouchNTuff 93-800 disposable glove, designed to provide at least 15 minutes of acetone resistance. The product expands the company’s disposable glove portfolio for applications requiring enhanced chemical protection, including healthcare and life-science environments.
Healthcare Personal Protective Equipment Market Report Scope Table
Report Attribute
Details
Market size in 2025
USD 13.0 billion
Estimated market size in 2026
USD 14.3 billion
Projected market size by 2033
USD 28.5 billion
Growth rate
CAGR of 10.4% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Russia; Italy; China; Japan; India; Australia; South Korea; Thailand; Indonesia; Malaysia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
3M; Alpha Pro Tech, Ltd.; Ansell Limited; Cardinal Health; DuPont; Dynarex Corporation; Hartalega Holdings Berhad; Kossan Rubber Industries Bhd; Lakeland Industries, Inc.; Medline; MSA Safety; Owens & Minor Products & Healthcare Services; PIP Global Safety; Top Glove Corporation Bhd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Personal Protective Equipment Market Report Segmentation
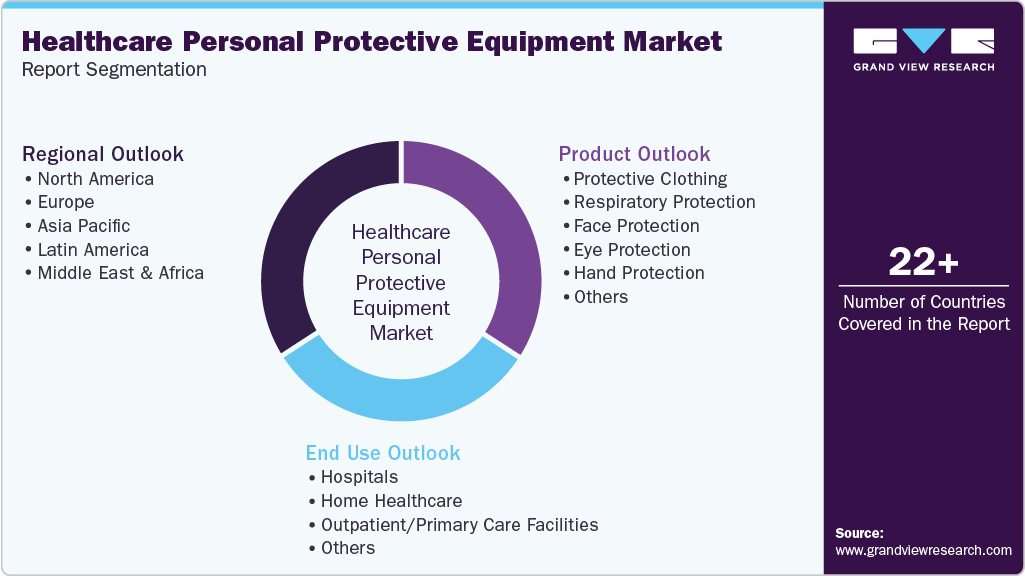
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global healthcare personal protective equipment market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Protective Clothing
-
Coveralls
-
Gowns
-
Others
-
-
Respiratory Protection
-
Surgical Masks
-
Respirator Masks
-
Others
-
-
Face Protection
-
Eye Protection
-
Hand Protection
-
Disposable Gloves
-
Durable Gloves
-
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Home Healthcare
-
Outpatient/Primary Care Facilities
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
UK
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
Malaysia
-
Indonesia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
Asia Pacific is expected to be the fastest-growing region over the forecast period.
Hand protection segment led with a 46.6% revenue share in 2025, while respiratory protection is expected to be the fastest-growing segment.
Hospitals segment led with a 55.9% revenue share in 2025.
The global healthcare personal protective equipment market size was valued at USD 13.0 billion in 2025 and is estimated at USD 14.3 billion in 2026.
The global healthcare personal protective equipment market is expected to grow at a CAGR of 10.4% from 2026 to 2033, reaching USD 28.5 billion by 2033.
Key players include 3M; Alpha Pro Tech, Ltd.; Ansell Limited; Cardinal Health; DuPont; Dynarex Corporation; Hartalega Holdings Berhad; Kossan Rubber Industries Bhd; Lakeland Industries, Inc.; Medline; MSA Safety; Owens & Minor Products & Healthcare Services; PIP Global Safety; Top Glove Corporation Bhd.
Europe dominated with a 32.9% revenue share in 2025.
The global healthcare personal protective equipment market was driven by rising infection prevention requirements across hospitals and clinical settings. Strict safety regulations and continuous PPE replacement needs further supported sustained market demand.
About the Author(s)
Smart Textiles Research Team
Advanced Materials · Smart TextilesThis report was authored by the smart textiles research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the smart textiles segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


