
- Home
- »
- Medical Devices
- »
-
Healthcare Third-Party Logistics Market Report, 2026-2033GVR Report cover

Healthcare Third-party Logistics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Industry (Biopharmaceutical, Pharmaceutical, Medical Device), By Supply Chain (Cold Chain Logistics, Non-cold Chain Logistics), By Service, By Region, And Segment Forecasts
Market Size, 2025
$279.8BMarket Estimate, 2026
$300.3BMarket Forecast, 2033
$522.1BCAGR, 2026–2033
8.2%Healthcare Third-Party Logistics Market Summary
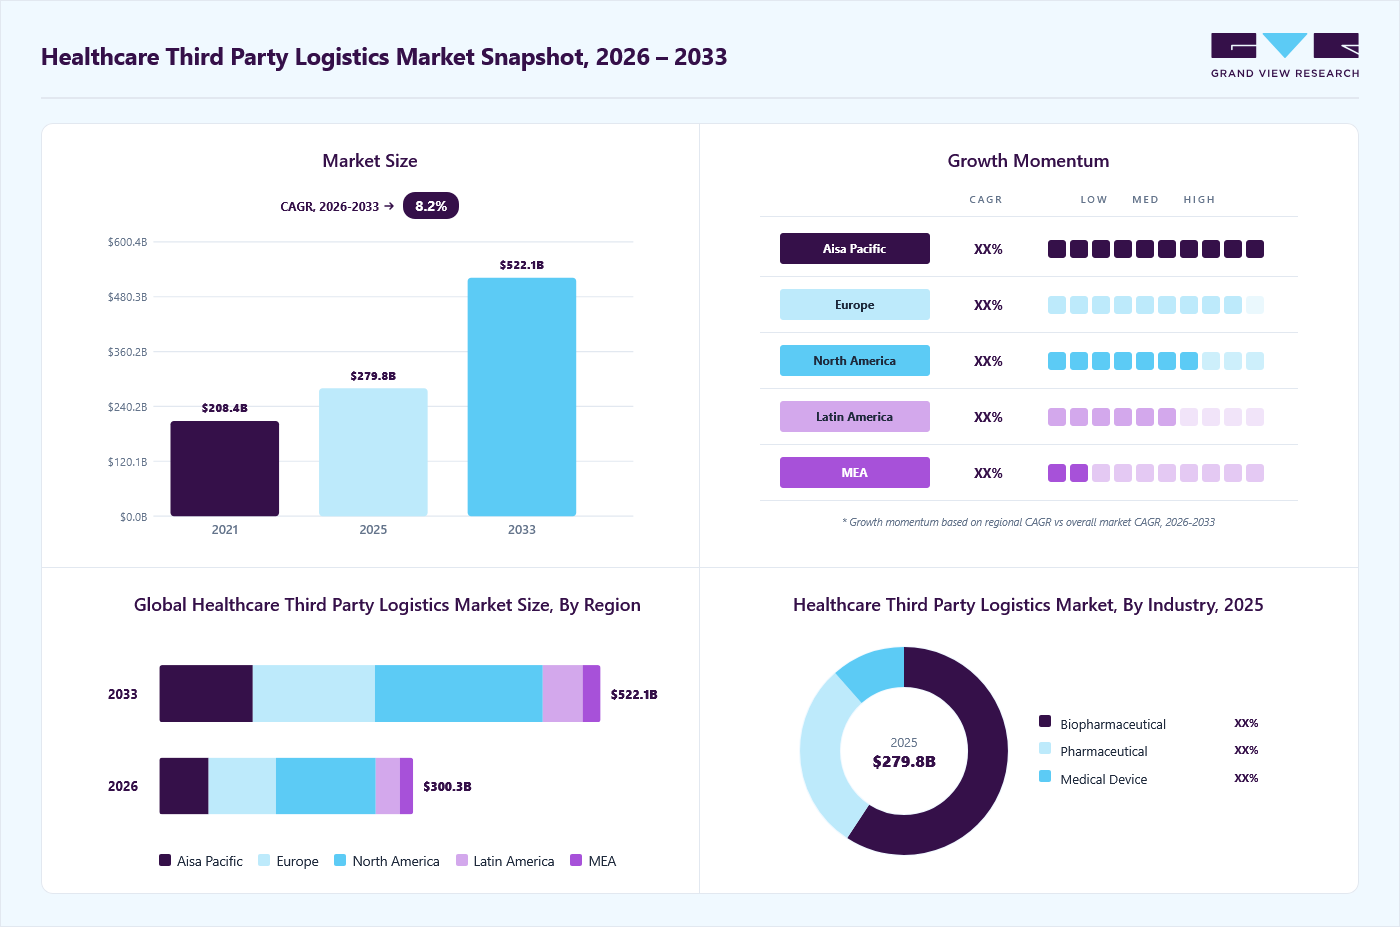
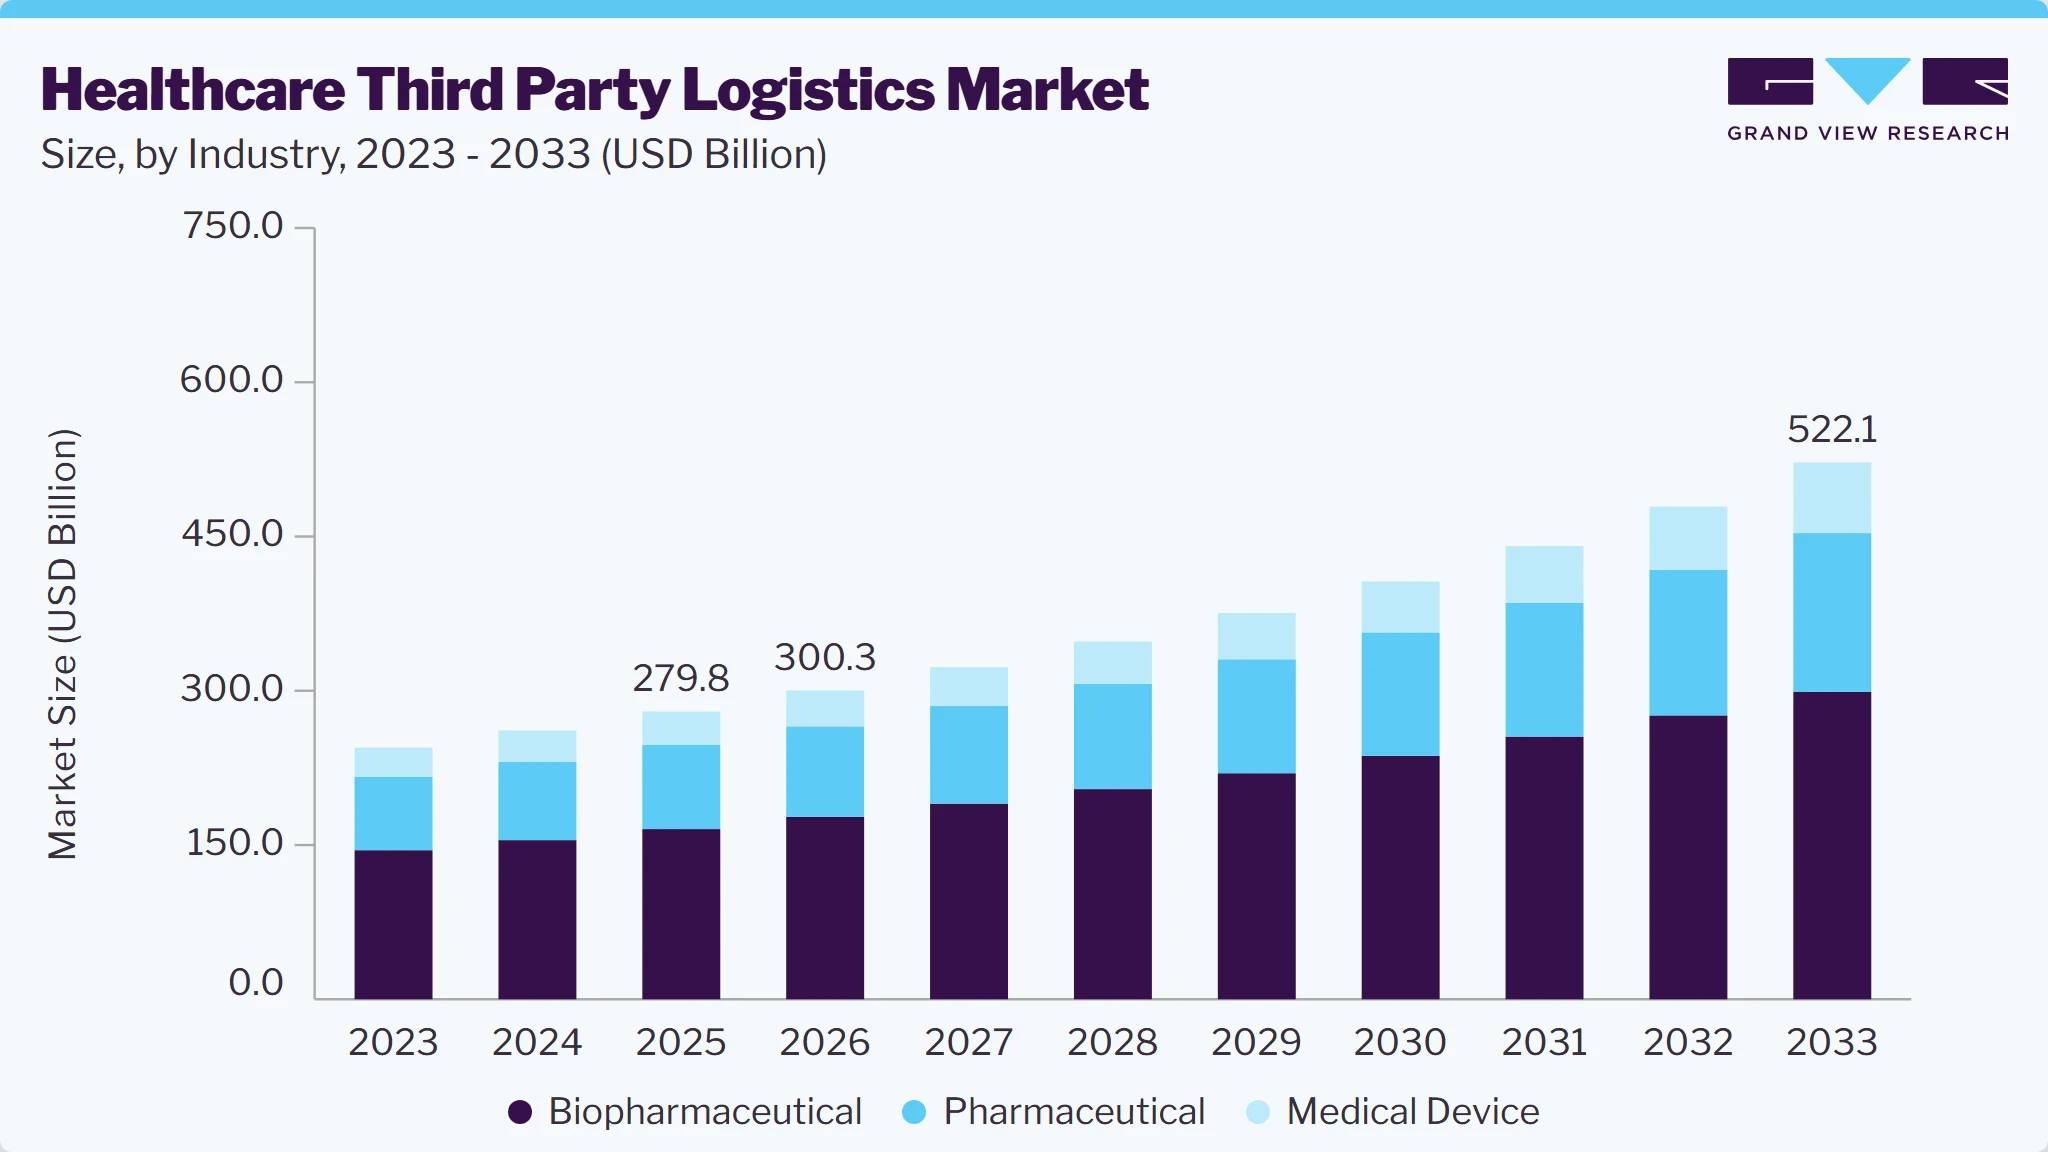
The global healthcare third-party logistics market size was valued at USD 279.8 billion in 2025 and is projected to grow from USD 300.3 billion in 2026 to USD 522.1 billion by 2033, at a CAGR of 8.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 39.4% in 2025. The demand for healthcare third-party logistics (3PL) services is driven by factors such as the growing need for healthcare products, technological advancements, and stringent regulatory compliance.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By industry: Biopharmaceutical segment led the market with the largest revenue share of 59.1% in 2025.
- By service: Warehousing and storage segment led the market with the largest revenue share of 43.4% in 2025.
- By supply chain: Non-cold chain logistics segment led the market with the largest revenue share of 75.1% in 2025.
Regional Highlights
- Largest regional market: North America (39.4% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 279.8 Billion
- Estimated market size in 2026: USD 300.3 Billion
- Projected market size by 2033: USD 522.1 Billion
- CAGR (2026-2033): 8.2%
Prism AI by Grand View Research Free to tryAsk a question about the healthcare third-party logistics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
As healthcare companies expand globally, they increasingly depend on 3PL providers to manage resources efficiently and minimize overhead costs. In addition, collaborative partnerships, such as DHL Group’s agreement with Vizient Inc., further enhance service offerings while addressing industry challenges. Healthcare manufacturers, distributors, and providers rely on specialized logistics partners to streamline operations and minimize expenses.Outsourcing logistics to 3PL providers enables companies to leverage advanced supply chain technologies, optimize distribution networks, and specialize expertise in handling temperature-sensitive pharmaceuticals, medical devices, and biologics. This reduces the need for heavy in-house infrastructure investments, lowers labor costs, and improves inventory management accuracy. Moreover, 3PL partners can consolidate shipments, improve last-mile delivery efficiency, and reduce transportation costs through strategic route planning and carrier partnerships. In a market where compliance with stringent regulatory requirements is essential, 3PL providers also help mitigate costly errors and delays by ensuring proper documentation, labeling, and storage. The combined impact of operational optimization and cost savings drives greater adoption of third-party logistics services across hospitals, clinics, pharmacies, and healthcare manufacturers.
 To learn more about this report, Download Free Sample Report
Moreover, ongoing digital transformation in healthcare logistics has been redefining operational standards, with providers steadily integrating advanced tools to handle increasingly complex and regulated supply chains. Over the past three years, the sector has moved from basic tracking systems to fully connected, data-driven platforms capable of predicting risks before they occur. For instance, the UPS Healthcare expanded its cold chain network with AI-enabled monitoring, enabling predictive alerts for temperature-sensitive biologics and high-value vaccines. The following year, DHL Supply Chain introduced IoT-based sensor technology across its global healthcare facilities. This allows end-to-end visibility for products such as cell and gene therapies, where even minor environmental deviations can impact efficacy. By 2025, these capabilities will have matured into comprehensive, real-time control towers that monitor and dynamically adjust routes and storage conditions, giving providers a significant service advantage over traditional logistics models.
Furthermore, reverse logistics is a critical growth driver in the healthcare third-party logistics industry, particularly within the biopharmaceutical sector, where product recalls, returns, and recycling processes require specialized handling. The increasing complexity of cold chain products, including biologics, cell therapies, and vaccines, has heightened the need for robust reverse logistics systems that can recover, transport, and dispose of sensitive materials in compliance with stringent regulatory standards. Leading providers invest in purpose-built infrastructure and digital tracking tools to ensure that returned products maintain chain-of-custody integrity and that disposal processes meet environmental and safety regulations. For instance, DHL Supply Chain has expanded its healthcare-focused facilities to incorporate dedicated return processing zones equipped with temperature-controlled inspection areas, enabling rapid assessment and safe reallocation or destruction of returned biopharmaceutical products. Similarly, Marken has strengthened its clinical trial logistics network to manage returns of unused investigational products from decentralized trial sites, using secure, GDP-compliant transport to prevent contamination risks.
Market Dynamics
Healthcare manufacturers, distributors, and providers are increasingly outsourcing logistics to 3PL partners to enhance cost efficiency, service reliability, and regulatory compliance. Specialized 3PLs support in minimizing in-house infrastructure requirements, optimizing warehousing and transportation networks, improving inventory accuracy, and reducing labor and distribution costs. In addition, their expertise is crucial for handling temperature-sensitive pharmaceuticals, biologics, vaccines, medical devices, and high-value therapies, all of which demand strict controls over storage, documentation, labeling, and supply chain.
The ongoing digital transformation is further driving the adoption of 3PL services, as healthcare logistics providers embrace technologies such as AI, IoT sensors, predictive analytics, and real-time control towers to navigate complex supply chains. These advancements enable temperature tracking, risk alerts, route optimization, and proactive interventions, resulting in reduced product loss and improved delivery performance. Moreover, reverse logistics is one of the major market growth factors, particularly for biopharmaceuticals, clinical trial materials, vaccines, and recalled products. As providers channel investments into temperature-controlled return processing, secure transportation, and compliant disposal systems to effectively manage recalls, returns, recycling, and unused investigational products. Thus, the market is transitioning towards integrated, technology-driven logistics models that support cost savings, ensure compliance, and drive operational resilience throughout healthcare supply chains.The growing commercialization of specialty pharmaceuticals and advanced therapies presents substantial opportunities for the healthcare third party logistics market. Increasing approvals of biologics, biosimilars, cell therapies, gene therapies, and precision medicines are generating demand for highly specialized logistics services capable of supporting complex storage and distribution requirements. Several manufacturers and developers require logistics partners with expertise in cryogenic transportation, chain of custody management, real time tracking, and patient specific delivery models, creating opportunities for service differentiation. Growing clinical trial activity across oncology, rare diseases, and regenerative medicine is further increasing demand for specialized healthcare logistics solutions. Further, expanding pharmaceutical manufacturing activities across Asia Pacific, Latin America, and the Middle East are creating new opportunities for regional distribution networks, warehousing facilities, and integrated supply chain services, allowing logistics providers to strengthen their presence across emerging healthcare markets.
Market Concentration & Characteristics
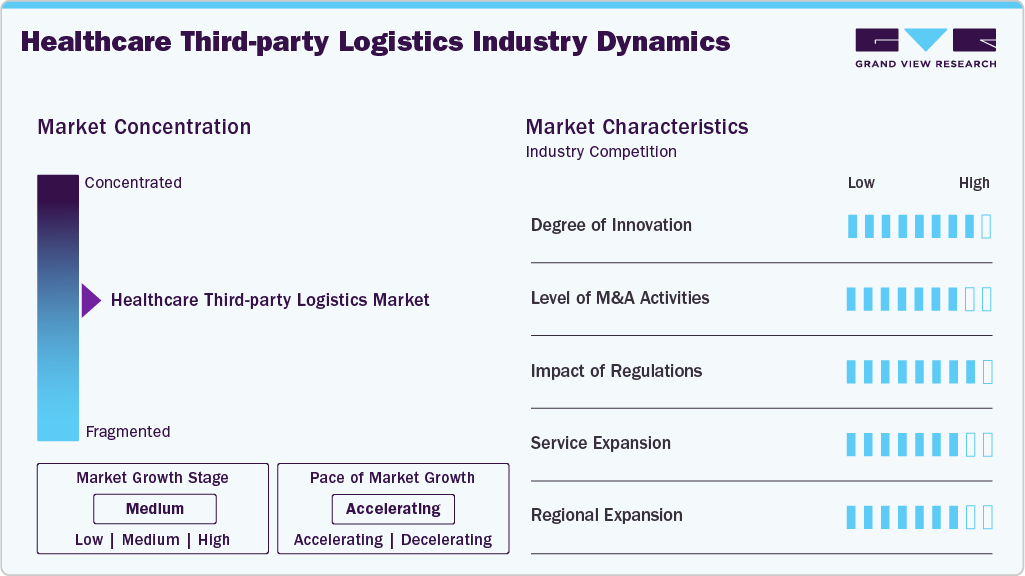
The industry growth stage is moderate, and growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion. Innovation is driven by advancements in cold chain logistics, real-time tracking, and automation. The integration of IoT, AI-driven route optimization, and blockchain for shipment verification has enhanced supply chain transparency.
The industry has witnessed high levels of mergers and acquisitions, as logistics providers seek to expand service capabilities and geographic reach. Major players such as UPS Healthcare, FedEx, and DHL Supply Chain have acquired specialized cold chain and clinical trial logistics firms to strengthen their presence in niche markets.
 To learn more about this report, Download Free Sample Report
Regulatory compliance plays a defining role in shaping the healthcare 3PL industry. Strict guidelines such as Good Distribution Practices (GDP), Good Manufacturing Practices (GMP), FDA requirements, and EU pharmaceutical logistics standards drive investments in validated storage, temperature monitoring, and serialization technologies. Compliance with evolving drug traceability laws, such as the U.S. Drug Supply Chain Security Act (DSCSA) and the EU Falsified Medicines Directive (FMD), adds complexity to logistics operations.
Leading healthcare 3PL providers are expanding their service offerings to include clinical trial logistics, specialty drug distribution, and home healthcare delivery. The rise of direct-to-patient (DTP) models and decentralized clinical trials has pushed logistics providers to develop last-mile solutions, temperature-controlled packaging, and patient-centric delivery systems.
Healthcare 3PL providers are aggressively expanding in Asia-Pacific, Latin America, and the Middle East to support the growing pharmaceutical markets in these regions. Investments in cold chain infrastructure, regional distribution hubs, and regulatory expertise are helping global logistics firms strengthen their foothold in emerging markets. The increasing outsourcing of pharmaceutical manufacturing to India and China is also driving demand for specialized logistics solutions in these regions.
Analyst Perspective
The healthcare third party logistics market is experiencing strong growth driven by increasing global demand for pharmaceutical products, biologics, vaccines, and specialty therapies that require highly specialized storage and distribution solutions. From an analyst perspective, rising outsourcing by pharmaceutical manufacturers, biotechnology companies, and medical device manufacturers is increasing demand for transportation, warehousing, inventory management, cold chain logistics, and value-added supply chain services. The growing volume of temperature sensitive biologics, vaccines, biosimilars, and advanced therapies is encouraging healthcare companies to partner with logistics providers that possess established cold chain infrastructure, regulatory expertise, and global distribution capabilities. Simultaneously, increasing regulatory requirements related to product traceability, serialization, temperature monitoring, and supply chain security are driving investments in digital tracking platforms, automated warehouses, and real time monitoring technologies. Growing pharmaceutical production across emerging markets, coupled with expanding healthcare access and rising cross border trade of healthcare products, is creating new opportunities for logistics providers. Companies with strong cold chain networks, integrated transportation and warehousing capabilities, and extensive geographic coverage are expected to secure a larger share of future healthcare logistics demand. Such factors are expected to drive market growth.
Impact of U.S. Tariffs on the Global Healthcare Third-Party Logistics Market
U.S. tariffs on pharmaceutical ingredients, medical devices, and healthcare-related imports are significantly influencing the industry. Rising trade tensions and tariff uncertainties have encouraged pharmaceutical and medical device manufacturers to diversify sourcing and manufacturing operations beyond China toward countries such as India, Vietnam, and Mexico. This geographic shift has increased demand for healthcare 3PL providers capable of managing complex multi-country transportation, customs clearance, and regulatory compliance processes.
In addition, companies are increasing regional warehousing and inventory buffering strategies to reduce supply chain disruptions caused by tariffs and fluctuating trade policies. As a result, healthcare logistics providers are expanding temperature-controlled storage facilities and distribution networks to support the uninterrupted delivery of pharmaceuticals, vaccines, and biologics. Tariff-related supply chain restructuring has also accelerated investment in regional logistics hubs and localized distribution centers, creating new business opportunities for healthcare 3PL companies. Furthermore, changing import regulations have increased the need for specialized compliance management, serialization tracking, and customs brokerage services. Thus, U.S. tariffs are reshaping global healthcare supply chains and driving greater reliance on advanced, flexible, and regulatory-compliant third-party logistics solutions across international healthcare markets.
Technological Advancements
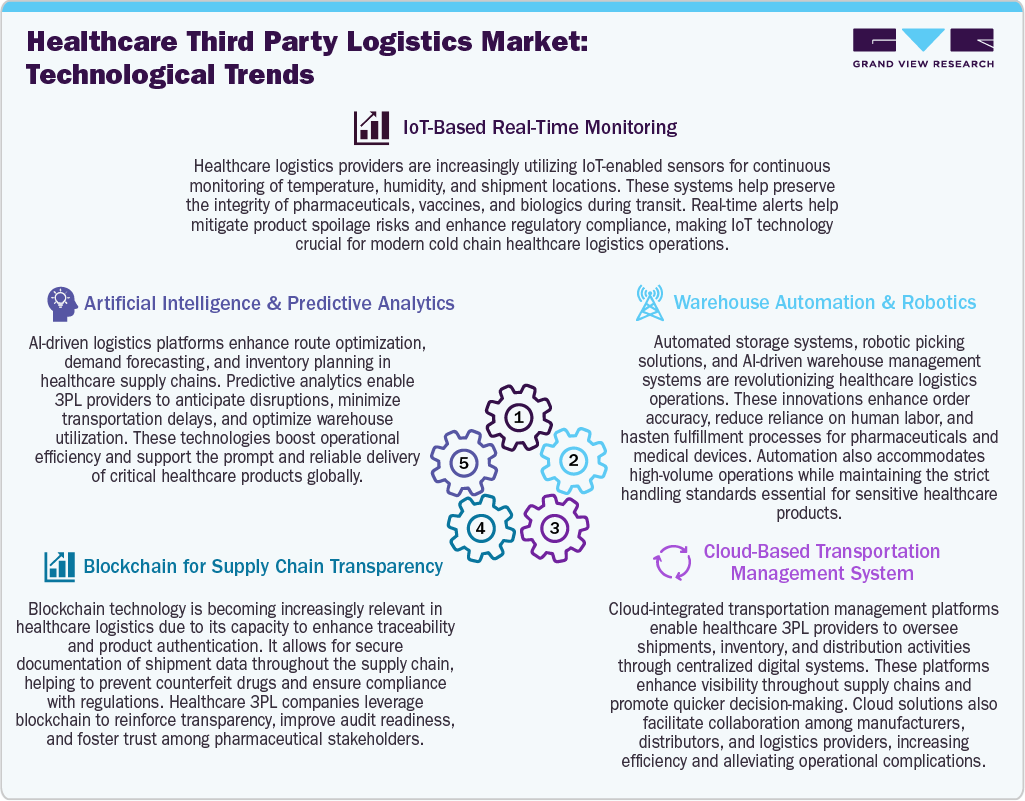
Technological advancements are significantly transforming the industry by improving supply chain visibility, operational efficiency, and regulatory compliance. Healthcare 3PL providers are increasingly adopting IoT-enabled monitoring systems that provide real-time tracking of temperature-sensitive pharmaceutical shipments, helping maintain product integrity during transportation and storage. Artificial intelligence and predictive analytics are further enhancing logistics performance by optimizing delivery routes, forecasting demand fluctuations, and minimizing supply chain disruptions. In addition, blockchain technology is improving transparency and traceability across healthcare supply chains by enabling secure documentation and reducing the risk of counterfeit pharmaceuticals.
 To learn more about this report, Download Free Sample Report
Warehouse automation and robotics are streamlining order fulfillment processes, increasing inventory accuracy, and reducing labor dependency in pharmaceutical distribution centers. Cloud-based transportation management systems are also enabling centralized control over inventory, warehousing, and transportation operations while improving coordination among manufacturers, distributors, and healthcare providers. These digital innovations are becoming increasingly important as healthcare supply chains grow more complex due to rising biologics demand, global pharmaceutical trade expansion, and stricter regulatory requirements. As a result, technological integration is strengthening the ability of healthcare third-party logistics providers to deliver safe, efficient, and compliant supply chain solutions worldwide.
Pricing Model Analysis
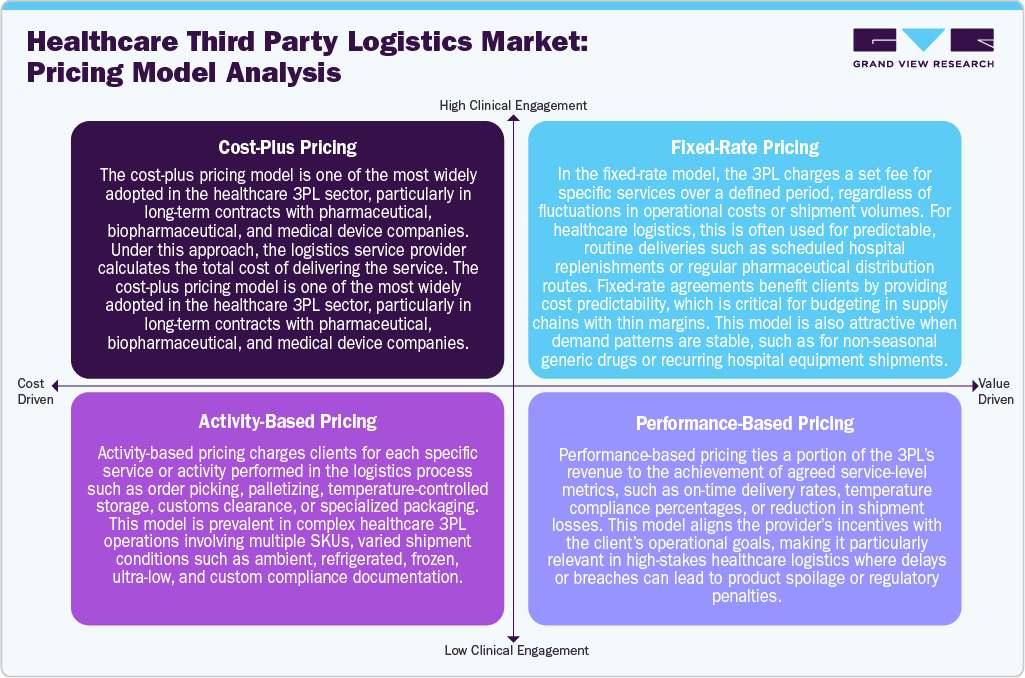
The industry employs various pricing models tailored to service complexity and customer needs. The cost-plus pricing model is prevalent in long-term contracts for pharmaceuticals and medical devices. Providers calculate operational expenses like warehousing, transportation, compliance, and packaging and add a fixed profit margin. This model offers pricing transparency but may not encourage optimization of costs.
 To learn more about this report, Download Free Sample Report
The fixed-rate model involves a set fee for distinct logistics services over a specified period, making it ideal for consistent healthcare deliveries and providing clients with cost predictability. Activity-based pricing is often used in complex logistics scenarios, where clients pay separately for services such as cold chain storage, order picking, customs clearance, and temperature monitoring. This model enhances flexibility and cost efficiency for variable shipment needs. Moreover, performance-based pricing ties a portion of the 3PL provider's revenue to service quality metrics, like on-time delivery, temperature compliance, and shipment accuracy. This approach drives accountability and promotes high standards in critical transportation for pharmaceuticals and biologics.
Industry Insights
Based on industry, the biopharmaceutical segment led the market with the largest revenue share of 59.1% in 2025. The growth is driven by increasing complexity of global supply chains, growing biopharmaceutical manufacturing, and a rising demand for efficient, compliant, and temperature-controlled distribution networks. Besides, increased focus on personalized medicines, biosimilars, and advanced biologics has led to an increased need for specialty logistics capabilities, which is expected to drive the market growth. In addition, changing regulatory frameworks in markets have increased the need for operational precision, traceability, and quality assurance, further fueling the 3PL providers. Furthermore, the globalization of clinical trials and commercial supply networks has fueled the requirement for logistic partners. Such factors are expected to drive the market over the estimated time period.
The pharmaceutical segment is driven by the globalization of pharmaceutical manufacturing, rising demand for cost-effective distribution models, and the necessity to comply with stringent regulations. Besides, increased drug consumption, the expansion of generics, and an increased focus on timely delivery are expected to drive the 3PL services in the pharmaceutical industry. Moreover, several companies increasingly focus on outsourcing logistics services to optimize efficiency, lower overhead costs, and ensure consistent service quality across various regions. In addition, evolving trade policies and intricate cross-border supply chains have increased the need for specialized logistics providers who can efficiently manage regulatory documentation, customs clearance, and distribution. For instance, the Global Pharma Logistics Summit in Mumbai demonstrates the necessity for 3PLs as key enablers of resilient pharmaceutical supply chains. Emerging themes included the importance of tracking and tracing, particularly for temperature-sensitive products such as biologics.
Service Insights
Based on service, the warehousing and storage segment led the market with the largest revenue share of 43.4% in 2025, driven by growing demand for temperature-controlled storage, regulatory compliance, and inventory management solutions. The increasing production of biologics, specialty drugs, and medical devices has led to higher investments in GMP-compliant and GDP-certified warehouses. In addition, the expansion of regional distribution hubs, automation in storage facilities, and just-in-time inventory models further strengthened the segment growth. With pharmaceutical and medtech companies outsourcing logistics to focus on core R&D and manufacturing, warehousing remains a critical component of the healthcare supply chain. Moreover, rapid growth in biologics, personalized therapies, and clinical trial supplies that require validated, temperature-controlled environments is contributing to segment growth. Besides, inventory complexity has increased with SKU proliferation and multi-channel distribution, prompting the usage of specialized storage solutions, segmented racking, and controlled access.
The transportation segment is driven by the increasing demand for home healthcare and requires reliable transportation for healthcare professionals, medical equipment, and supplies. According to WHO projections, 80% of older individuals will reside in low- and middle-income countries by 2050, prompting urgent challenges for health and social systems, particularly in enhancing access to non-emergency medical transport (NEMT) amid the rapid aging population. Moreover, increasing demand for efficient and specialized logistics solutions across biopharmaceutical supply chains is accelerating the segment growth. The growing focus on maintaining the integrity and timely delivery of high-value products, from temperature-sensitive biologics to high-demand generics, supports the market growth. Moreover, the growing demand for thorough tracking capabilities to ensure adherence to strict regulatory standards, especially in handling controlled substances and biologics, is expected to drive segment growth.
Supply Chain Insights
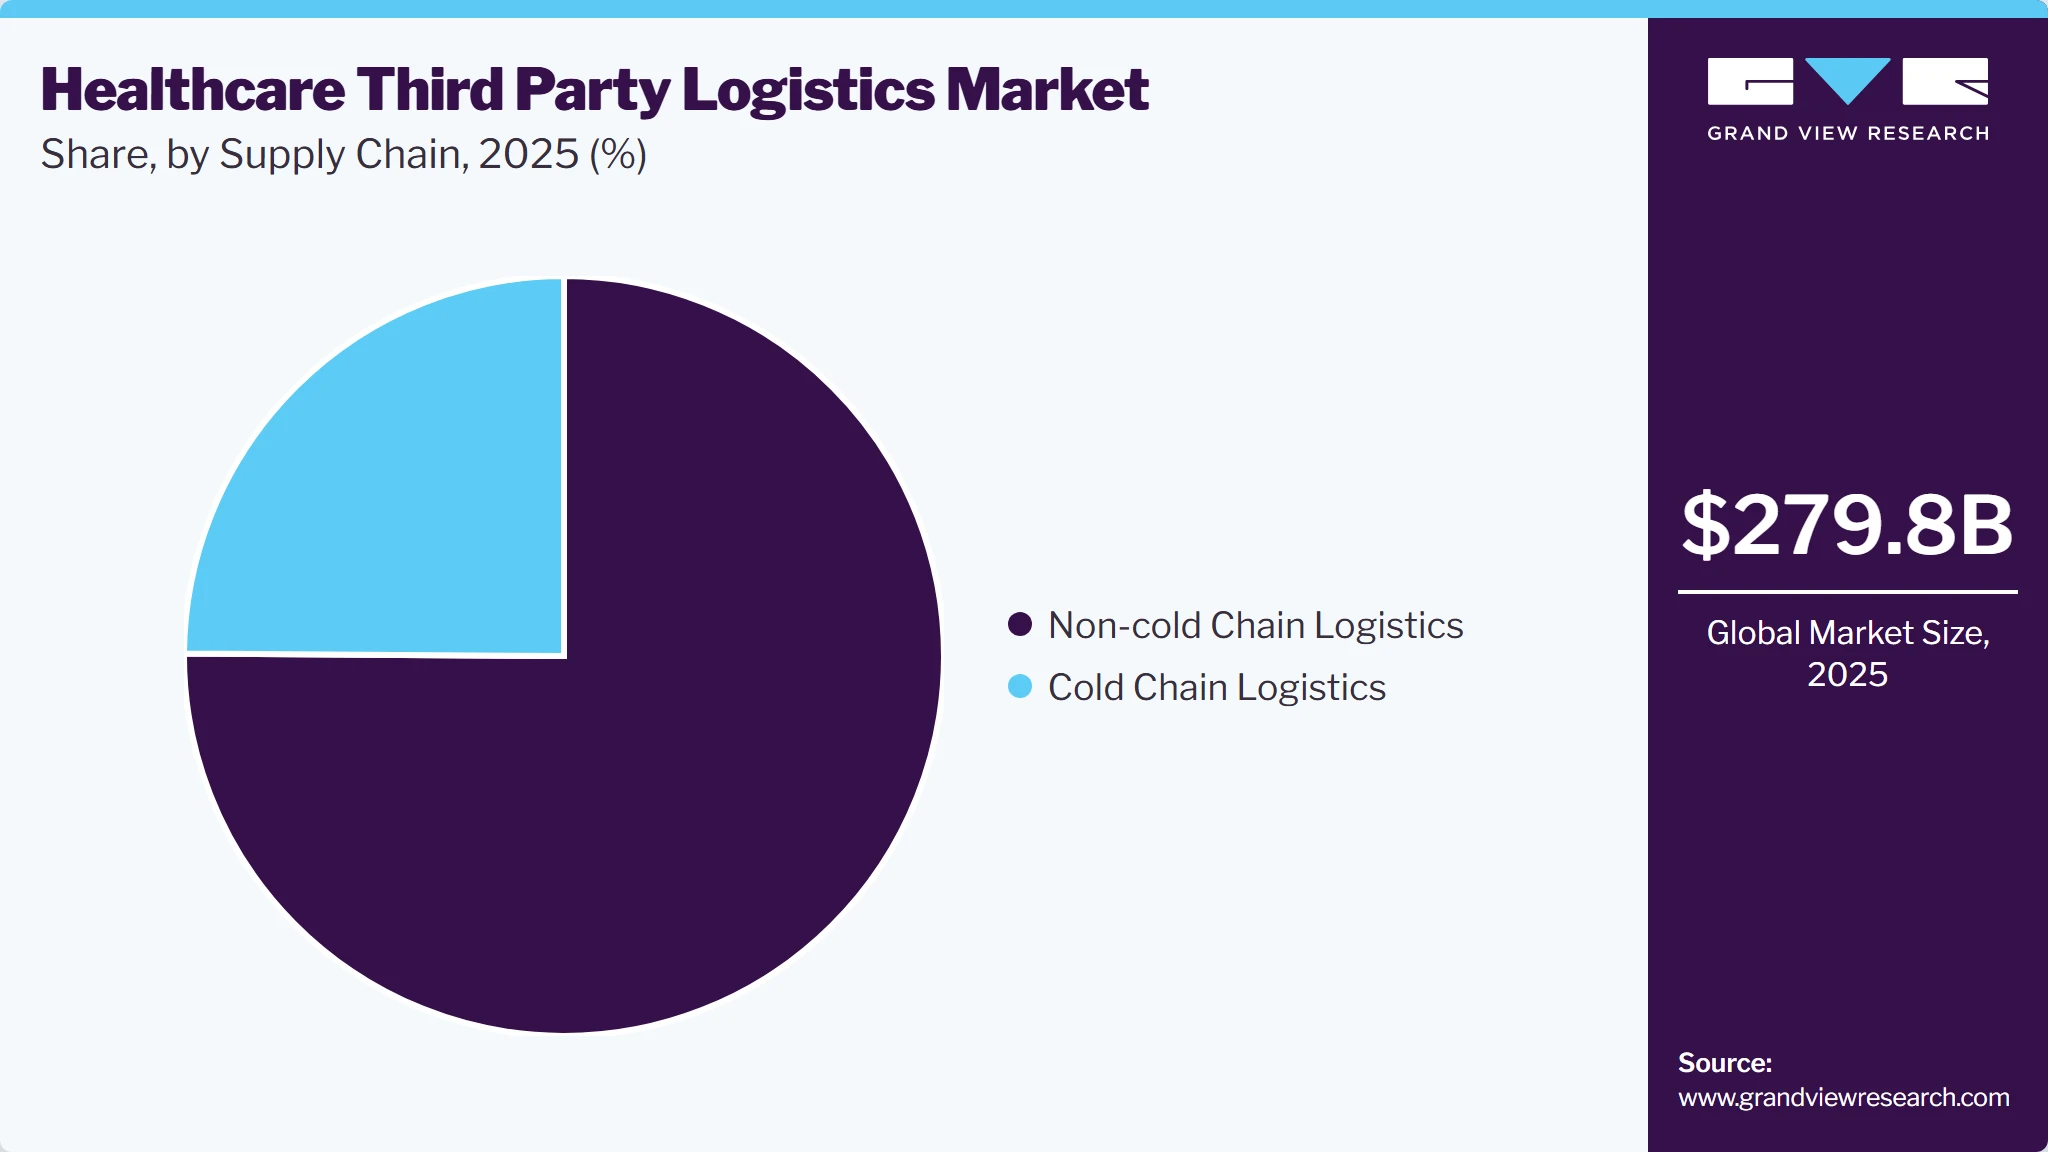
Based on supply chain, the non-cold chain logistics segment led the market with the largest revenue share of 75.1% in 2025, driven by the increasing demand for efficient pharmaceutical product distribution that does not require temperature-controlled environments. Besides, other factors contributing to market growth are rising demand for generic drugs, over-the-counter (OTC) medications, and medical supplies, combined with expanding healthcare infrastructures and retail pharmacy networks, which have increased the need for enhanced logistics solutions. Moreover, pharmaceutical companies increasingly outsource non-cold chain logistics operations to specialized 3PL providers to optimize costs, improve supply chain flexibility, and enhance operational efficiency. In addition, the rising adoption of e-commerce platforms in healthcare distribution has accelerated demand for reliable last-mile delivery solutions tailored to non-cold chain logistics.
 To learn more about this report, Download Free Sample Report
The cold chain logistics segment is driven by increasing demand for temperature-sensitive products in pharmaceuticals, biopharmaceuticals, personalized medicine, vaccines, and regenerative therapies. Besides, increased use of complex biologics, gene therapies, and cell therapies across the globe has led to a rising need for cold chain logistics services with stringent temperature control and cryogenic storage. Moreover, in pharmaceutical and biopharmaceutical products, the chemical stability and product efficacy play a significant role in product sterility during storage and transportation, further supporting market growth.
Regional Insights
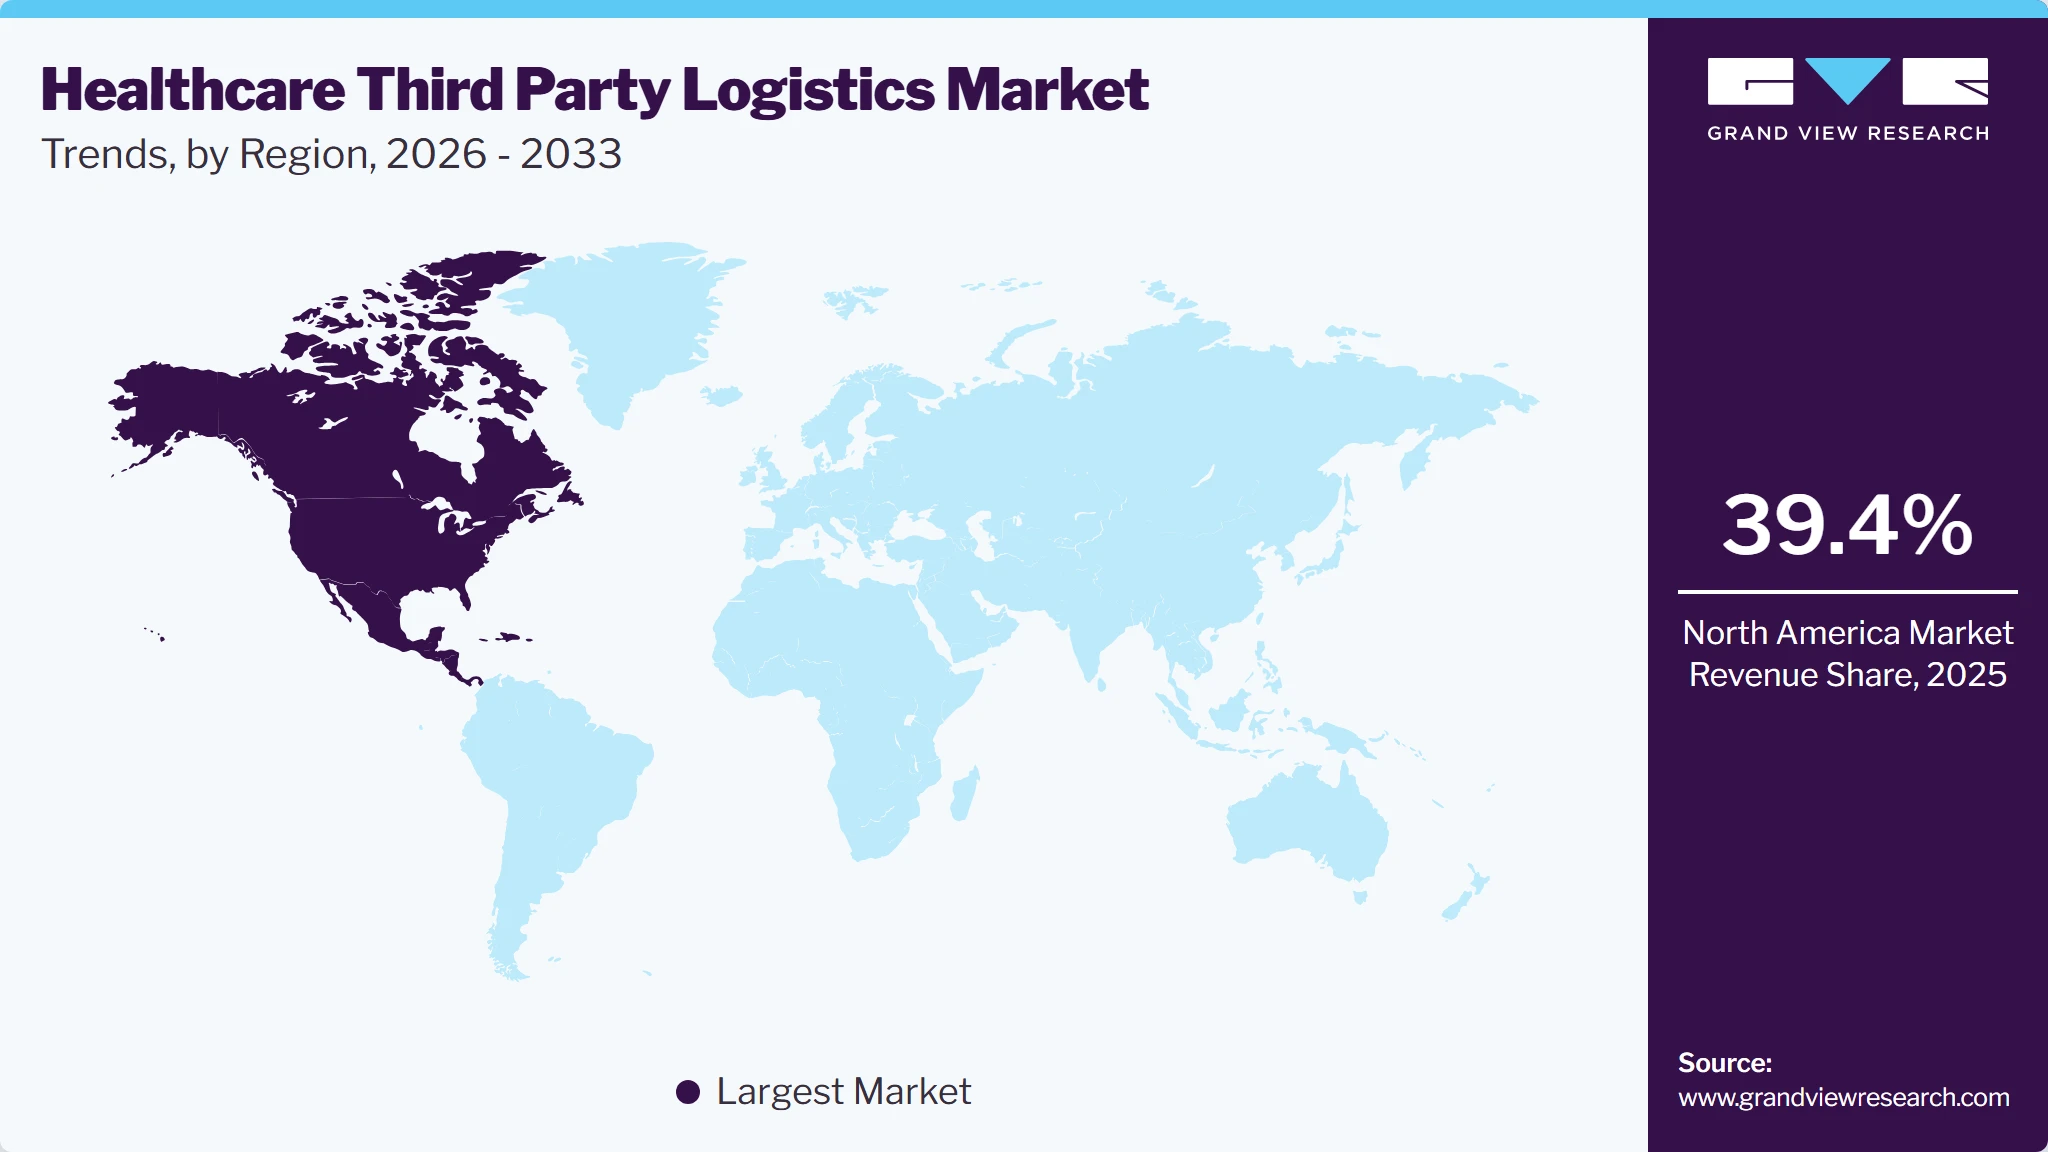
North America dominated the healthcare third-party logistics market with the largest revenue share of 39.4% in 2025, attributed to the increasing complexity of pharmaceutical and biopharmaceutical supply chains, the rising number of temperature-sensitive products, and stringent regulatory requirements. Besides, some factors contributing to the market are the rising demand for specialized logistics services due to growing requirements for personalized medicine, biosimilars, and high-value biologics. This has led many pharmaceutical and medical device companies to outsource their non-core logistics functions to reliable 3PL providers.
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Third-Party Logistics Market Trends
The healthcare third-party logistics market in the U.S. held the largest share in the North America region in 2025, owing to the increasing complexity of pharmaceutical and medical supply chains, increased demand for temperature-controlled logistics, and the need to meet stringent regulatory standards. Besides, as the healthcare industry evolves, the advancements in biologics, specialty drugs, and personalized therapies are expected to drive the logistics outsourcing to enhance operational efficiency and manage costs effectively. This trend has been further fueled by the shift toward value-based patient-centric delivery models, leading to broader adoption of 3PL services nationwide.
Canada healthcare third-party logistics market is driven by the pharmaceutical and biotechnology sectors, a growing demand for cold chain logistics, and stringent regulatory compliance requirements. Besides, the increasing imports of high-value therapeutics, rising usage of biologics, and a shift toward outsourcing non-core functions have led manufacturers to partner with specialized 3PL providers, further supporting the market growth. Besides, the need for cost efficiency and country distribution coverage, particularly in remote and underserved areas, has led to a rising requirement for third-party logistics in supporting Canada's healthcare market.
Europe Healthcare Third-Party Logistics Market Trends
The healthcare third-party logistics market in Europe is driven by the region's expanding pharmaceutical and biologics manufacturing base, rising harmonization of regulations across the EU, and the increasing demand for cross-border distribution of healthcare products. Besides, the companies are increasingly outsourcing logistics functions, which helps reduce operational complexities while maintaining compliance with strict regulations for handling temperature-sensitive and high-value medical products. In addition, changing demographic scenarios, including an aging population and a rising prevalence of chronic diseases, combined with increased spending on specialty drugs, are expected to drive the need for efficient and scalable supply chain solutions managed by specialized 3PL providers.
Germany healthcare third-party logistics market held the highest share in 2025, fueled by its strong pharmaceutical manufacturing base, increased healthcare expenditure, and a robust regulatory framework that ensures product safety and quality. Besides, the rising demand for biologics, specialty drugs, and advanced medical devices has increased the need for reliable, compliant, and time-sensitive distribution solutions. In addition, the growth of e-pharmacies, an aging population, and an increasing prevalence of chronic diseases further emphasize the reliance on specialized logistics providers for the seamless movement of healthcare products throughout the supply chain.
The healthcare third-party logistics market in the UK is expected to grow significantly over the forecast period, driven by rising advanced pharmaceutical manufacturing capabilities, robust clinical research activities, and a growing demand for specialized medicines. Besides, the increasing prevalence of biologics, personalized treatments, and high-value medical devices has increased the need for secure, compliant, and efficient logistics solutions. In addition, a growing aging population, rising chronic diseases, and the expansion of e-pharmacies have further fueled the reliance on 3PL providers to oversee complex, time-sensitive, and regulated supply chains.
Asia Pacific Healthcare Third-Party Logistics Market Trends
The healthcare third-party logistics market in Asia Pacific is expected to grow at the fastest CAGR over the forecast period, driven by the rapid expansion of pharmaceutical manufacturing, increased international trade for generics and active pharmaceutical ingredients (APIs), and the ongoing development of the healthcare industry in emerging countries. Other factors contributing to market growth are lower service costs, adherence to evolving Good Distribution Practice (GDP) standards, improved access to medicines, rising requirements for e-commerce, increasing focus on regulatory compliance for logistics, and technological advancements.
China healthcare third-party logistics market is driven by a rapidly aging population, the increasing prevalence of chronic diseases, and a rising demand for advanced therapies and high-quality healthcare products. Besides, the expansion of pharmaceutical and biopharmaceutical manufacturing capabilities, along with strong government initiatives aimed at improving healthcare accessibility and efficiency, has led to a significant increase in the outsourcing of logistics operations.
The healthcare third-party logistics market in Japan is driven by a rising aging population, the growing demand for advanced medical treatments, and the expansion of its pharmaceutical and biopharmaceutical sectors. Besides, growing chronic diseases and lifestyle-related diseases have increased the usage of prescription drugs, medical devices, and diagnostic equipment, creating a need for reliable and compliant logistics networks. In addition, government policies aimed at improving healthcare access and the country’s emphasis on quality and precision in supply chain operations have fueled the market growth.
India healthcare third-party logistics market is experiencing rapid growth, driven by expanding pharmaceutical and biopharmaceutical markets, rising demand for specialty drugs, and increased export activities to regulated and emerging markets. Besides, the government initiatives, particularly the Production Linked Incentive (PLI) scheme for pharmaceuticals and medical devices, alongside improvements in healthcare infrastructure, are expected to drive the need for specialized logistics solutions. For instance, according to an article published by the Economic Times in March 2025, the launch of modernized healthcare logistics infrastructure in India aims to enhance supply chain efficiency for pharmaceuticals, medical devices, and cold chain logistics. This initiative supports timely delivery, reduces wastage, and strengthens distribution networks, contributing significantly to the country’s healthcare sector advancement.
Latin America Healthcare Third-Party Logistics Market Trends
The healthcare third-party logistics market in the Latin America region is expected to grow significantly, due to increasing demand for pharmaceuticals & biopharmaceuticals, along with the expansion of regional drug manufacturing. In addition, government initiatives aimed at improving access to essential medicines are expected to support market growth. Besides, regulatory reforms in major countries such as Brazil and Argentina have fueled a supportive environment for developing logistics infrastructure that complies with GDP standards.
Brazil's healthcare third-party logistics market is experiencing robust growth, driven by rising demand for efficient and reliable supply chain solutions. Besides, the country’s vast geography and underdeveloped healthcare infrastructure pose significant logistical challenges, which drive the need for 3PL services among the healthcare providers. In addition, expanding healthcare access in rural and underserved areas further fuels the reliance on 3PL providers to enhance delivery efficiency and improve patient outcomes. Moreover, the key players are investing in temperature-controlled logistics, broadening their service portfolios, and forming strategic alliances. As the market evolves, intensified competition is expected to drive the market over the estimated period.
Middle East & Africa Healthcare Third-Party Logistics Market Trends
The healthcare third-party logistics market in the Middle East & Africa is growing steadily due to increased pharmaceutical product requirements, healthcare investments, and rising government initiatives to improve healthcare infrastructure. In addition, third-party logistics services are becoming crucial for distributing pharmaceuticals, biologics, vaccines, and medical devices, which play a significant role in temperature-controlled and secure handling. Besides, the market prioritizes the rising adoption of cost-effective technologies like RFID tracking, automated inventory systems, and IoT-enabled cold chain monitoring to enhance visibility, minimize risk, and adhere to regulatory standards.
The UAE healthcare third-party logistics market is rapidly growing, driven by rising demand for advanced medical treatments and an increase in pharmaceutical product consumption. Besides, the government's strategic initiative to establish the UAE as a regional healthcare and logistics hub is expected to drive market growth. In addition, increased healthcare spending, modernized regulations, and efforts to improve access to specialized therapies have increased the need for efficient, compliant, and scalable supply chain solutions. Moreover, the UAE's competitive healthcare 3PL market is fueled by key players such as DHL and Aramex, Aetna Inc., Mednet, Nextcare, GlobeMed Ltd., and Sehteq. For instance, in March 2026, Dubai South announced the launch of a new distribution facility by Hellmann Calipar Healthcare Logistics (HCHL) within its Logistics District. The expansion increases Hellmann’s UAE network to five distribution centers, reinforcing its dedicated healthcare logistics capabilities across the Middle East. The new facility addresses rising demand for reliable healthcare supply chains, driven by stricter regulations and the growing need for precise handling and visibility of temperature-sensitive medical products throughout the logistics process.
Key Healthcare Third-Party Logistics Company Insights
The global healthcare third-party logistics market is experiencing significant growth, with the major market players including Cardinal Health, DHL Group, Agility, SF Express, Kinesis Medical B.V., United Parcel Service of America, Inc., Barrett Distribution, AmerisourceBergen Corporation, DB Schenker, FedEx, KUEHNE + NAGEL, Kerry Logistics Network Ltd., and Freight Logistics Solutions. These firms offer comprehensive services from cell line development to commercial manufacturing, driving innovation and efficiency in biologic drug production. For instance, in March 2025, Barrett Distribution Centers, a recognized leader in third-party logistics specializing in e-commerce and omnichannel fulfillment, introduced the E-commerce Accelerator program. This initiative is created to support fast-growing, early-stage brands in scaling their logistics operations effectively and efficiently.
Key Healthcare Third-Party Logistics Companies
The following key companies have been profiled for this study on the healthcare third-party logistics market.
-
Cardinal Health
-
DHL Group
-
Agility
-
SF Express
-
Kinesis Medical B.V.
-
United Parcel Service of America, Inc.
-
Barrett Distribution
-
AmerisourceBergen Corporation
-
DB Schenker
-
FedEx
-
KUEHNE + NAGEL
-
Kerry Logistics Network Ltd.
-
Freight Logistics Solutions
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cardinal Health; DHL Group; United Parcel Service of America, Inc. (UPS); AmerisourceBergen Corporation)
- Established players focus on expanding healthcare-dedicated warehousing, cold chain infrastructure, GDP-compliant transportation, and integrated distribution networks.
- They invest in digital tracking, temperature monitoring, automation, and strategic partnerships with pharma, medtech, hospitals, and distributors to strengthen service reliability, regulatory compliance, and global scalability.
- Established players benefit from strong global networks, established customer relationships, advanced cold chain capabilities, regulatory expertise, and scalable infrastructure.
- Their ability to manage complex healthcare shipments, provide real-time visibility, ensure product integrity, and support end-to-end logistics makes them preferred partners for pharmaceutical, biotech, medical device, and healthcare providers.
- Established players often face high operating costs, complex regulatory exposure, and slower customization due to large-scale standardized processes.
- Their dependence on global transportation networks can increase vulnerability to disruptions, fuel cost volatility, and capacity constraints, while smaller specialized providers may offer more flexible, niche, and cost-efficient healthcare logistics solutions.
Emerging Players (Agility; Kinesis Medical B.V.; Barrett Distribution)
- Emerging players focus on niche healthcare logistics services, regional distribution strength, customized warehousing, specialty freight handling, and flexible customer support.
- They target underserved routes, specialized medical shipments, and cost-efficient logistics models while building partnerships with healthcare manufacturers, distributors, hospitals, clinics, and medical device companies to expand market presence.
- Emerging players offer agility, faster decision-making, customized service models, competitive pricing, and stronger responsiveness to specific client needs.
- Their focused operations allow them to serve niche healthcare logistics requirements, manage specialized shipments, and provide personalized support, making them attractive to small and mid-sized pharma, medtech, and healthcare providers.
- Emerging players may have limited global reach, smaller infrastructure capacity, lower brand recognition, and fewer advanced technology investments compared to established players.
- They can face challenges in scaling cold chain networks, meeting complex regulatory requirements across regions, and competing for large enterprise contracts requiring broad geographic coverage and integrated logistics capabilities.
Recent Developments
-
In November 2025, United Parcel Service of America, Inc. mentioned the completion of the acquisition of Andlauer Healthcare Group, a Canada-based provider of specialized healthcare supply chain solutions, including third-party logistics and temperature-controlled transportation services. The acquisition will strengthen UPS’s healthcare logistics portfolio and reinforce its focus on expanding specialized global capabilities in the healthcare sector.
-
In May 2025, DHL Group announced the strategic expansion of its Life Sciences & Healthcare (LSH) campus in Germany, transforming the facility into a key European pharmaceutical hub. This development is part of DHL Health Logistics’ broader global multibillion-euro investment. The campus now features a fourth state-of-the-art logistics center, bringing the total warehouse space to 100,000 square meters, an area equivalent to over 14 soccer fields. The expanded site will provide capacity for more than 140,000 pallets of pharmaceutical and medical products. Serving a diverse range of international clients in biopharma, specialty pharma, medical technology, and clinical research, the campus employs over 600 skilled professionals dedicated to supporting advanced healthcare logistics.
-
In March 2025, DHL Group and Cryoport, Inc. announced that DHL had fully acquired CRYOPDP, a prominent specialty courier specializing in clinical trials, biopharmaceuticals, and cell and gene therapies. In addition, the two companies revealed a strategic partnership aimed at enhancing their supply chain services for the global life sciences and healthcare industries.
Healthcare Third-Party Logistics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 279.8 billion
Estimated market size in 2026
USD 300.3 billion
Projected market size by 2033
USD 522.1 billion
Growth rate
CAGR of 8.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Industry, service, supply chain, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, Japan, China, India, Thailand, South Korea, Australia, Brazil, Argentina, South Africa, UAE, Saudi Arabia, Kuwait, Qatar, Oman
Key companies profiled
Cardinal Health, DHL Group, Agility, SF Express, Kinesis Medical B.V., United Parcel Service of America, Inc., Barrett Distribution, AmerisourceBergen Corporation, DB Schenker, FedEx, KUEHNE + NAGEL, Kerry Logistics Network Ltd., and Freight Logistics Solutions among others.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Third-party Logistics Market Report Segmentation
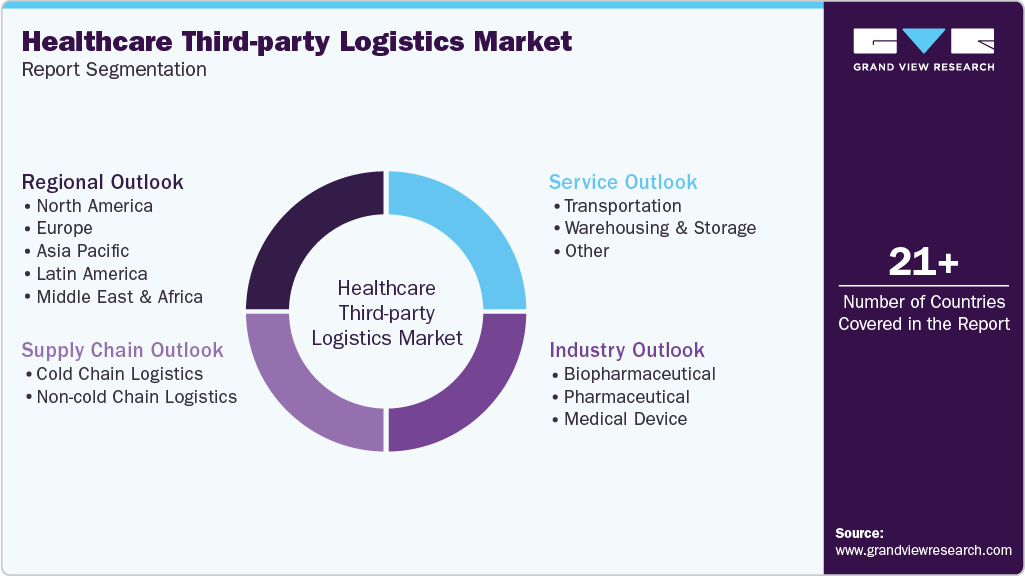
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global healthcare third-party logistics market report based on industry, service, supply chain, and region:
 To learn more about this report, Download Free Sample Report
-
Industry Outlook (Revenue, USD Billion, 2021 - 2033)
-
Biopharmaceutical
-
Vaccines
-
Biosimilars
-
Plasma Derived Products
-
Others
-
-
Pharmaceutical
-
Medical Device
-
Class I
-
Class II
-
Class III
-
-
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Transportation
-
Air Freight
-
Sea Freight
-
Overland
-
-
Warehousing and Storage
-
Other
-
-
Supply Chain Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cold Chain Logistics
-
Non-cold Chain Logistics
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The healthcare third-party logistics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each healthcare third-party logistics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Industry
Revenue capture definition
Biopharmaceutical
The segment represents revenue generated from logistics services for biologically derived therapeutic products requiring specialized handling, including temperature-controlled storage and transportation. This segment covers biologics across various therapeutic areas, supported by GDP-compliant warehousing, cold chain distribution, and regulatory documentation. It includes biological medical products derived from living organisms, such as vaccines, plasma-derived products, and other biological drugs, such as monoclonal antibodies and cell and gene therapies.
Vaccines
The segment covers third-party logistics solutions for prophylactic and therapeutic vaccines, requiring strict cold chain management, real-time temperature monitoring, and expedited transportation. Services ensure compliance with national immunization supply chain protocols and WHO pre-qualification standards.
Biosimilars
The segment captures revenue generated from third-party logistics services provided for biosimilar products. It includes cold chain transportation, warehousing, distribution management, inventory control, packaging, and regulatory-compliant handling of biosimilar biologics.
Plasma Derived
Products
This segment encompasses logistics services for plasma-based therapies, such as immunoglobulins, clotting factors, and albumin, which require ultra-cold storage, secure transport, and traceability from donor to patient. It is driven by stringent biosecurity and regulatory oversight.
Others
The segment captures revenue generated from logistics services provided for other healthcare products not categorized under biopharmaceuticals, vaccines, biosimilars, plasma-derived products, pharmaceuticals, or medical devices. It includes healthcare consumables, diagnostics, laboratory products, and related healthcare supplies.
Pharmaceutical
The segment covers logistics services for small-molecule drugs and over-the-counter medications, including temperature-controlled and ambient storage, pick-and-pack distribution, inventory management, and regulatory compliance for prescription drug supply chains.
Medical Device
The segment represents 3PL services for medical instruments and equipment, covering distribution, warehousing, reverse logistics, and compliance with device-specific regulatory classifications.
Class I
The segment includes logistics for low-risk medical devices (e.g., stethoscopes, bandages) requiring basic storage and distribution solutions, with minimal regulatory complexity but high-volume handling.
Class II
The segment covers logistics for moderate-risk devices (e.g., infusion pumps, diagnostic kits) requiring controlled environments, calibrated storage, and regulatory labeling compliance.
Class III
The segment encompasses logistics for high-risk, life-sustaining devices (e.g., implantable pacemakers, heart valves) requiring specialized handling, secure transport, and stringent chain-of-custody protocols.
Segment - Service
Revenue capture definition
Transportation
Transportation in the healthcare 3PL market involves revenue from the movement of pharmaceuticals, biopharmaceuticals, medical devices, and other healthcare products across domestic and international geographies. It includes specialized handling for temperature-controlled, high-value, and time-sensitive shipments to maintain product integrity and regulatory compliance.
Air Freight
Air freight services involve the revenue from transport of healthcare products via cargo or passenger aircraft, enabling rapid delivery over long distances. This mode is preferred for high-value, urgent, or temperature-sensitive shipments, including vaccines, biologics, and critical medical devices, where speed and reliability are paramount.
Sea Freight
Sea freight covers bulk transportation of healthcare goods through ocean carriers, offering cost-effective solutions for large-volume, non-urgent shipments. It is widely used for raw materials, medical consumables, and equipment, with containerized options for cold-chain requirements during extended transit times.
Overland
Overland services include the transportation of healthcare products via road and rail networks. This segment addresses last-mile delivery, regional distribution, and cross-border trucking, supporting cold and ambient supply chains with flexibility for short- to medium-distance logistics.
Warehousing and
Storage
It captures revenue generated from healthcare warehousing and storage services. It includes ambient and temperature-controlled storage, inventory management, stock monitoring, order fulfillment, packaging, and distribution center operations for healthcare products.
Other
Other services in healthcare 3PL include value-added logistics such as packaging, kitting, labeling, customs brokerage, reverse logistics, and supply chain visibility solutions. These services enhance operational efficiency, compliance, and product traceability across the healthcare supply chain.
Segment - Supply Chain
Revenue capture definition
Cold Chain Logistics
Cold chain logistics in the healthcare third-party logistics market refers to the transportation, storage, and distribution of temperature-sensitive healthcare products, including biopharmaceuticals, vaccines, biologics, and certain medical devices. This segment encompasses specialized infrastructure, equipment, and monitoring systems to maintain prescribed temperature ranges across the supply chain, ensuring product integrity, regulatory compliance, and patient safety.
Revenue in this segment is generated from services such as refrigerated transportation, temperature-controlled warehousing, and real-time monitoring solutions.
Non-Cold Chain
Logistics
Non-cold chain logistics in the healthcare third-party logistics market covers the handling, storage, and distribution of healthcare products that do not require temperature-controlled environments, such as pharmaceuticals, medical devices, surgical instruments, and consumables. This segment includes warehousing, inventory management, order fulfillment, and transportation services utilizing ambient storage and delivery conditions. Revenue is derived from the efficient movement of goods while ensuring regulatory adherence, timely delivery, and cost optimization within healthcare supply chains.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Service-Level Customization
Offered customized service-level agreements (SLAs) based on product sensitivity, delivery urgency, and compliance requirements. This includes dedicated cold-chain handling for biologics, same-day delivery for critical hospital supplies, and specialized packaging for temperature-sensitive pharmaceuticals. Providers may also create customized KPI dashboards, inventory visibility tools, and emergency response logistics solutions tailored to pharmaceutical manufacturers, hospitals, and medical device companies.
Customized service levels improve supply chain reliability and patient safety by ensuring critical healthcare products reach hospitals, pharmacies, and patients on time. Dedicated cold-chain handling reduces product spoilage and financial losses, while emergency delivery services minimize treatment delays. Tailored KPI monitoring and inventory management also help pharmaceutical companies improve operational efficiency, reduce stock-outs, and strengthen customer satisfaction in highly regulated healthcare markets.
Industry Outlook Customization
Customized technology integration services such as real-time shipment tracking, AI-based demand forecasting, and warehouse management system (WMS) integration with ERP platforms like SAP or Oracle. Healthcare 3PL companies also provide serialized product tracking, blockchain-enabled traceability, and automated compliance reporting. These solutions improve visibility across the supply chain while supporting regulatory compliance and reducing operational inefficiencies.
Advanced technology integration enhances real-time visibility and decision-making across the healthcare supply chain. AI-driven forecasting reduces excess inventory and prevents shortages, while serialized tracking improves product authentication and regulatory compliance. Automated reporting lowers administrative workload and minimizes human error. These capabilities help healthcare companies reduce operational costs, improve transparency, accelerate response times, and maintain higher service quality for healthcare providers and patients.
Regional Landscape
Customized distribution networks according to regional demand, regulatory frameworks, and healthcare infrastructure. This may include establishing dedicated regional warehouses, micro-fulfillment centers near hospitals, or multi-country distribution hubs for global pharmaceutical companies. Customized transportation routes, local language support, and country-specific regulatory documentation services help clients improve delivery efficiency, reduce transit time, and expand market reach effectively.
Customized distribution networks enable faster product movement and improved market accessibility, especially in remote or high-demand regions. Regional warehousing and optimized transportation routes reduce delivery timelines and logistics costs. Country-specific compliance support simplifies cross-border operations and lowers regulatory risks. This flexibility allows pharmaceutical and medical device companies to scale efficiently, improve product availability, and strengthen their competitive position in both developed and emerging healthcare markets.
Frequently Asked Questions About This Report
The global healthcare third-party logistics market size was valued at USD 279.8 billion in 2025 and is estimated at USD 300.3 billion for 2026.
The global healthcare third-party logistics market is expected to grow at a CAGR of 8.2% from 2026 to 2033, reaching USD 522.1 billion.
Non-cold chain logistics segment held the largest revenue share in 2025.
warehousing and storage segment held the largest revenue share in 2025.
North America dominated with a 39.4% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Some key players operating in the healthcare third-party logistics market include Cardinal Health, DHL Group, Agility, SF Express, Kinesis Medical B.V., United Parcel Service of America, Inc., Barrett Distribution, AmerisourceBergen Corporation, DB Schenker, FedEx, KUEHNE + NAGEL, Kerry Logistics Network Ltd., and Freight Logistics Solutions, among others.
The biopharmaceuticals segment led with a 59.1% revenue share in 2025.
Key factors driving the growth of the healthcare third-party logistics market include the growing demand for healthcare products, technological advancements, and stringent regulatory compliance. As healthcare companies expand globally, they increasingly depend on 3PL providers to manage resources efficiently and minimize overhead costs. In addition, collaborative partnerships, such as DHL Group’s agreement with Vizient Inc., further enhance service offerings while addressing industry challenges. Such factors are expected to drive the market growth.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


