
- Home
- »
- Advanced Interior Materials
- »
-
HVAC Distribution Market Size, Share & Trends Report, 2033GVR Report cover

HVAC Distribution Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Heat Pump, Furnace, Unitary Heaters, Boilers, Air Purifier, Dehumidifier, AC), By Application (New Construction), By End-use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$294.8BMarket Estimate, 2026
$312.2BMarket Forecast, 2033
$497.0BCAGR, 2026–2033
6.9%HVAC Distribution Market Size & Trends
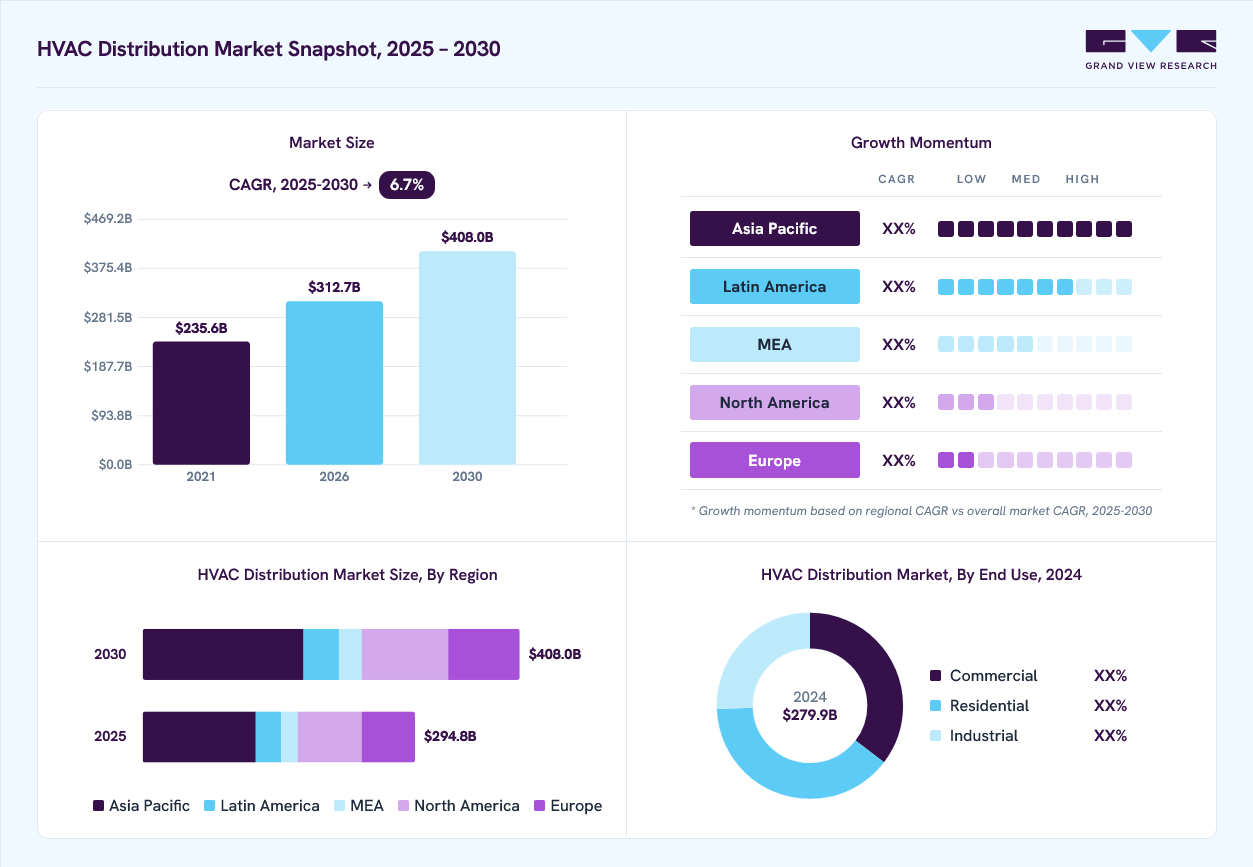
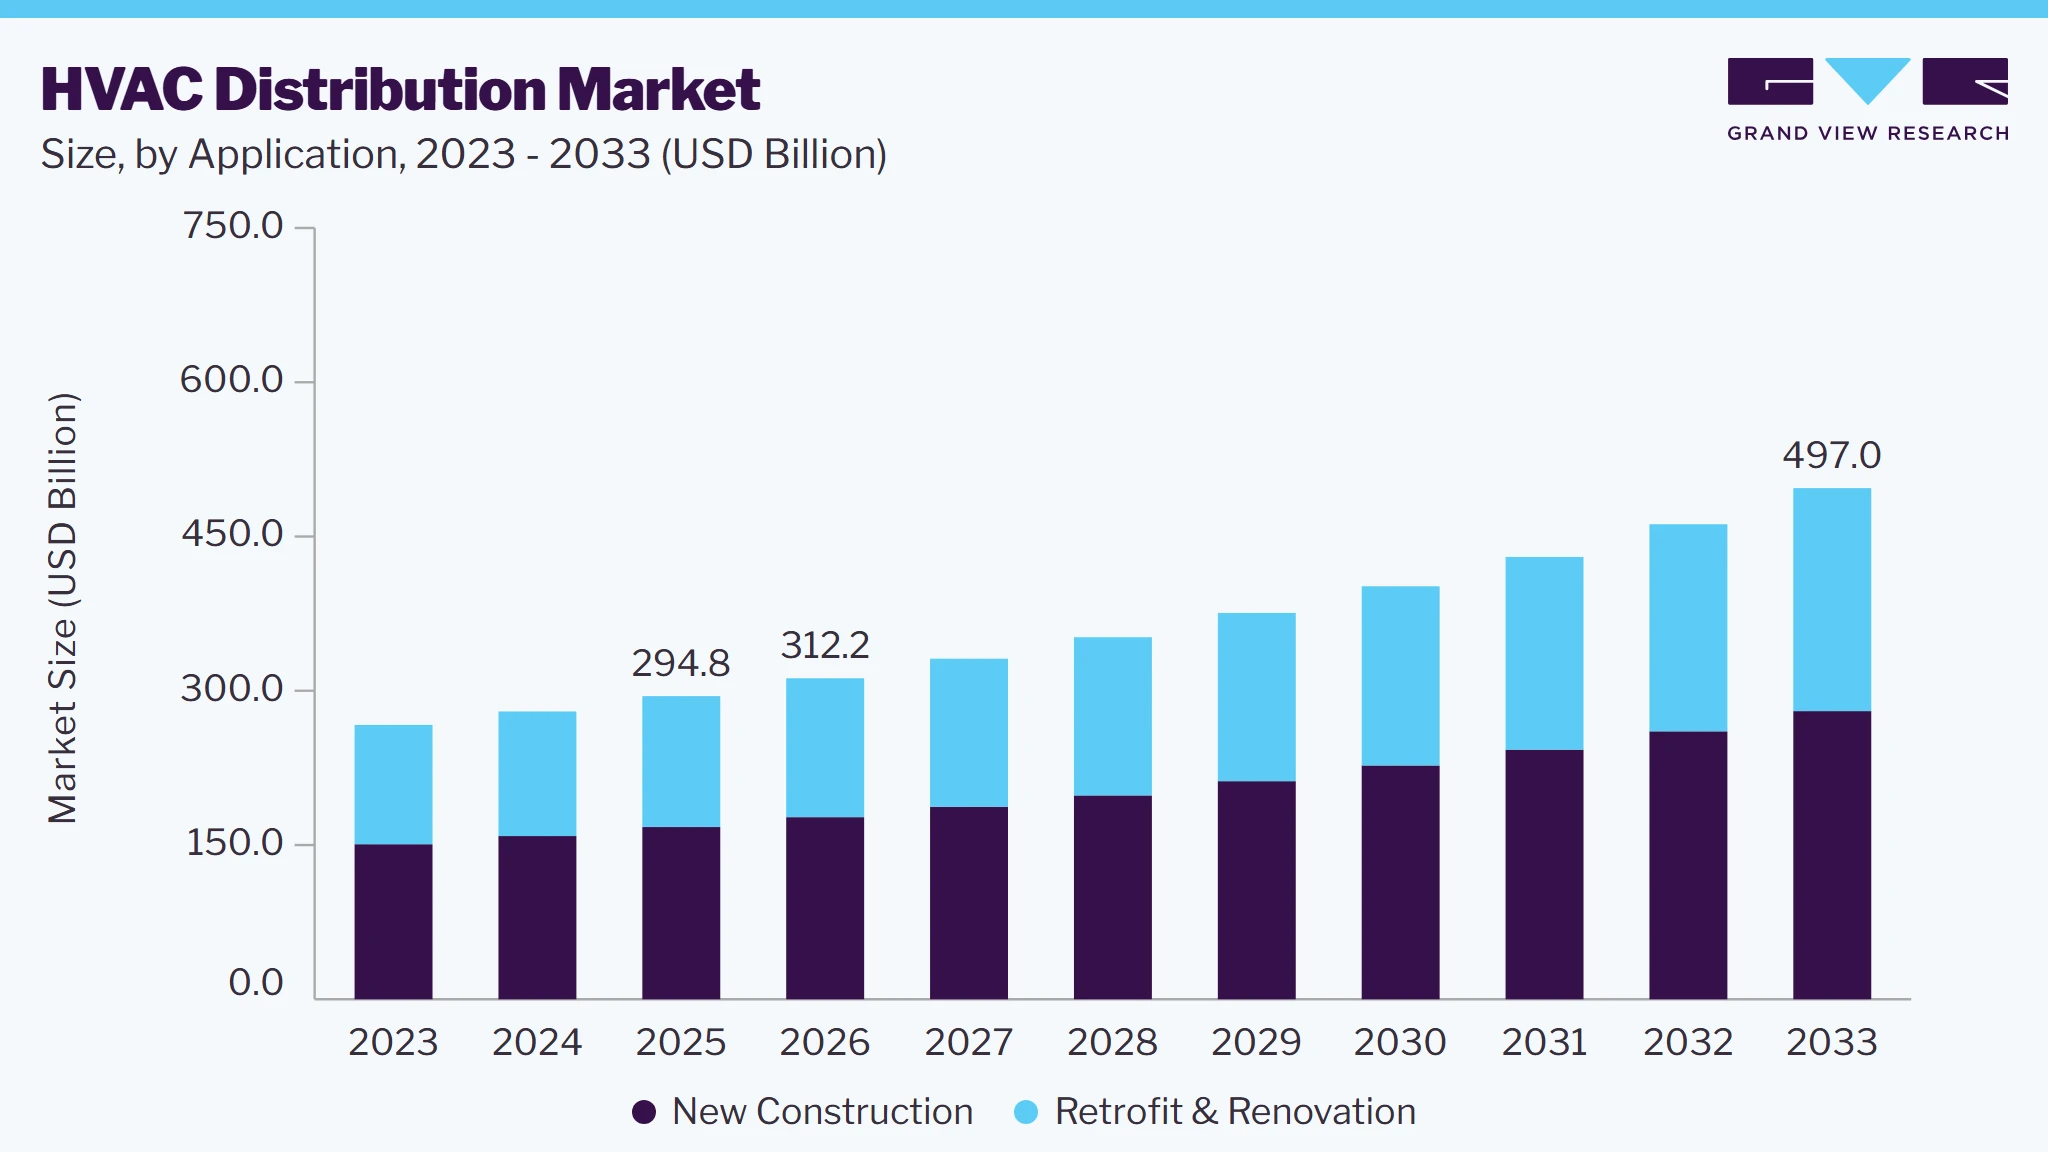
The global HVAC distribution market size was valued at USD 294.8 billion in 2025 and is projected to grow from USD 312.2 billion in 2026 to USD 497.0 billion by 2033, growing at a CAGR of 6.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 41.5% in 2025. The HVAC distribution industry plays a crucial role in ensuring the efficient delivery of heating, ventilation, and air conditioning systems across various sectors, including residential, commercial, and industrial.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Heat pump segment led the market with the largest revenue share of 35.4% in 2025.
- By distribution channel: Offline segment led the market with the largest share of 89.1% in 2025.
- By application: New construction segment led the market with the largest share of 56.8% in 2025.
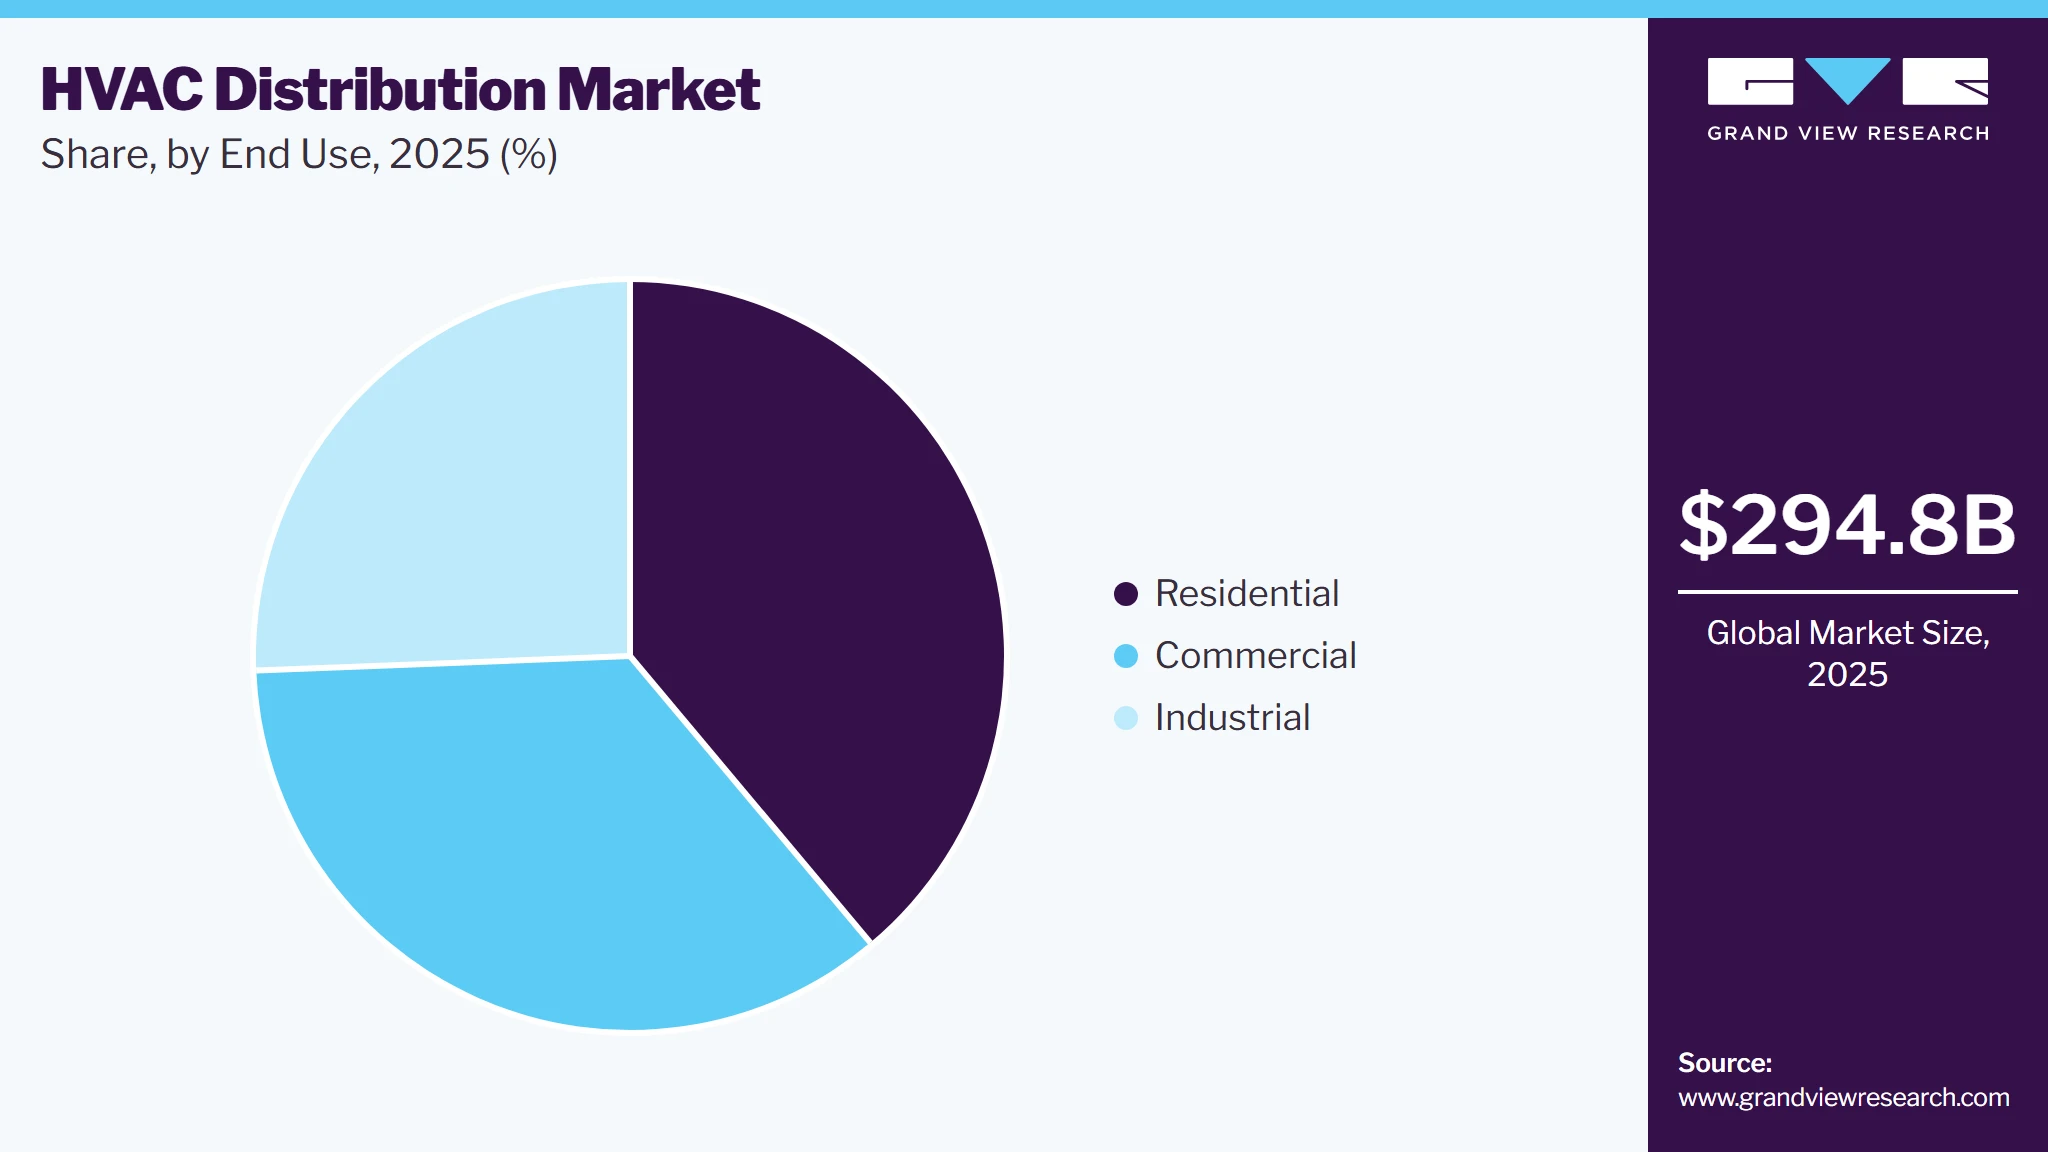
- By end-use: Residential segment led the market with the largest revenue share of 38.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.5% revenue share, 2025)
- By country: The China held the largest share of Asia pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 294.8 Billion
- Estimated market size in 2026: USD 312.2 Billion
- Projected market size by 2033: USD 497.0 Billion
- CAGR (2026-2033): 6.9%
Prism AI by Grand View Research Free to tryAsk a question about the HVAC distribution marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
This market encompasses the manufacturers, suppliers, and distributors that provide HVAC equipment and components, ensuring their availability for end users. Technological advancements influence the sector in energy efficiency, smart systems, and sustainability. As environmental concerns and energy regulations tighten, the demand for energy-efficient and eco-friendly HVAC solutions continues to grow, driving innovation and competition in the market.In recent years, there has been an increasing shift toward integrated HVAC solutions that combine heating, cooling, and air quality management, leading to a rise in demand for advanced systems. Distribution networks are evolving to meet the needs of modern consumers, who prioritize both performance and sustainability in their systems. Furthermore, with the growing adoption of smart technologies, the market is seeing a shift toward digitally connected products that offer greater control and automation. As urbanization and industrialization continue globally, the HVAC distribution market is poised for steady growth, with a focus on improving system reliability, energy efficiency, and environmental impact.
 To learn more about this report, Download Free Sample Report
The global HVAC distribution industry is influenced by dynamic trade flows, with Asia Pacific continuing to serve as the central manufacturing and export hub. Countries such as China, India, and Vietnam dominate global exports, benefiting from established production capabilities and cost advantages. At the same time, North America-particularly the United States and Mexico-has emerged as a significant manufacturing and re-export region due to increasing nearshoring trends and favorable trade agreements. Trade tensions, shifting tariffs, and supply chain disruptions have prompted key HVAC distributors and OEMs to diversify sourcing strategies, invest in localized production, and reassess cross-border logistics.
Market Dynamics
The HVAC distribution market is driven by increasing demand for energy-efficient heating, ventilation, and air conditioning systems across residential, commercial, and industrial sectors. Rapid urbanization, growth in new construction activities, and rising investments in building renovation and retrofitting are creating sustained demand for HVAC equipment and replacement components, strengthening the role of distributors in ensuring timely product availability. The market is also benefiting from stricter energy efficiency regulations, decarbonization initiatives, and the growing adoption of smart and connected HVAC systems, which require distributors to expand their product portfolios and provide greater technical support.
The HVAC distribution market is primarily driven by the growing demand for energy-efficient, sustainable, and technologically advanced HVAC systems across residential, commercial, and industrial applications. Stringent government regulations aimed at reducing energy consumption and greenhouse gas emissions, along with the phased adoption of low-global-warming-potential (GWP) refrigerants, are encouraging the replacement of aging HVAC equipment with high-efficiency alternatives.
In addition, rapid urbanization, expanding construction activities, and increasing investments in the modernization of commercial buildings and industrial facilities are generating sustained demand for HVAC products through distribution networks.
The HVAC distribution market is constrained by persistent pricing pressure, inventory management challenges, and rising operating costs across the supply chain. Fluctuations in construction activity, economic uncertainty, and changing purchasing patterns have made demand forecasting more complex, increasing the risk of inventory imbalances and excess stock.
In addition, the transition to refrigerant-compliant HVAC equipment has required distributors to manage legacy products alongside next-generation systems, resulting in higher inventory carrying costs and increased working capital requirements. Rising raw material and manufacturing costs have also contributed to higher procurement expenses, while intense competition within the distribution landscape limits the ability of distributors to fully transfer these cost increases to contractors and end-users.
The ongoing digital transformation of the HVAC industry presents significant growth opportunities for distributors seeking to improve operational efficiency and strengthen customer engagement. The adoption of digital ordering platforms, AI-enabled demand forecasting, warehouse automation, inventory optimization, and customer relationship management solutions is enabling distributors to streamline operations, reduce lead times, and improve inventory accuracy.
Furthermore, the increasing demand for value-added services, including technical consulting, contractor training, equipment commissioning support, flexible financing options, inventory management programs, and just-in-time delivery, is allowing distributors to differentiate themselves beyond traditional product supply.
Market Concentration & Characteristics
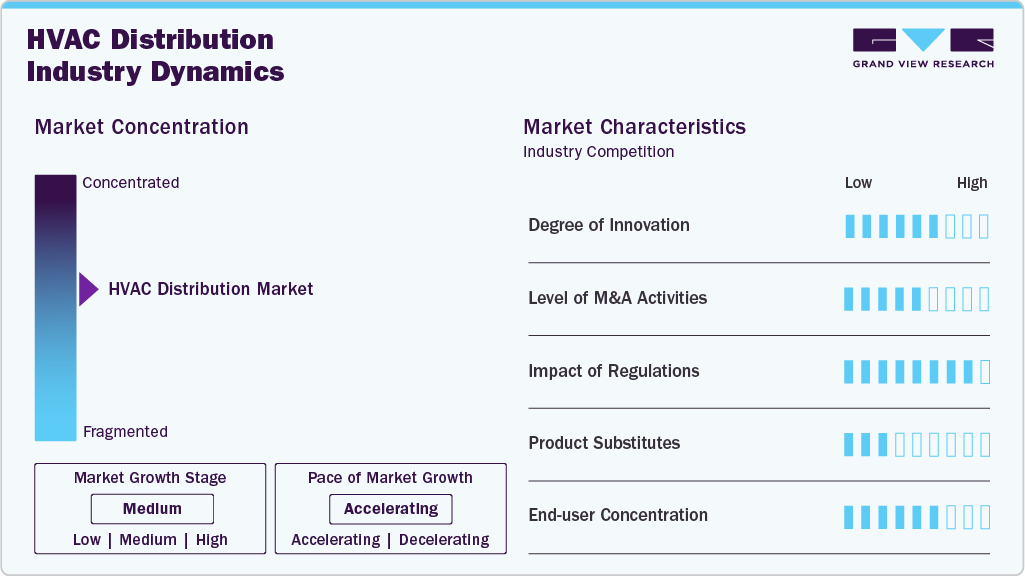
The HVAC distribution market exhibits a moderately fragmented structure, defined by the presence of established global players alongside a growing number of regional and specialized distributors. Prominent companies such as Carrier Global Corporation, Johnson Controls, Trane Technologies, Daikin Industries, and Lennox International have cemented strong market positions through comprehensive product portfolios, advanced technologies, and expansive distribution networks. In parallel, regional players and independent distributors play a vital role in serving local markets by offering tailored solutions that align with regional climate conditions, building codes, and customer preferences.
Environmental regulations and energy efficiency standards significantly influence the dynamics of the HVAC distribution industry. Governments and regulatory bodies across the globe are enforcing building efficiency codes and sustainability mandates that encourage the adoption of energy-efficient HVAC systems. Distributors are increasingly required to stock and promote systems that meet these standards, driving a shift toward environmentally friendly products. This regulatory pressure not only stimulates market demand but also encourages manufacturers and distributors to invest in innovative and compliant technologies.
 To learn more about this report, Download Free Sample Report
Technological advancements continue to reshape the HVAC distribution landscape. The integration of smart technologies, such as IoT-enabled HVAC systems and advanced building automation, is transforming how heating and cooling solutions are delivered and maintained. Improvements in energy management, remote monitoring, and predictive maintenance are becoming standard features, pushing distributors to offer products that incorporate these innovations. Additionally, the use of low-global-warming-potential (GWP) refrigerants and variable-speed compressors is gaining traction, enabling systems to achieve greater efficiency and adaptability across varying climate zones and building types.
Regionally, North America holds a dominant share of the HVAC distribution market, supported by robust construction activity, regulatory incentives for energy-efficient systems, and a strong aftermarket service industry. Europe closely follows, driven by a commitment to sustainable building practices and the widespread adoption of green technologies. The Asia-Pacific region is experiencing rapid growth, fueled by urbanization, infrastructure expansion, and rising demand for climate control in emerging economies such as China and India. These regional trends underscore the global shift toward high-performance, sustainable HVAC solutions distributed through increasingly sophisticated and diverse networks.
Analyst Perspective
The HVAC distribution market is witnessing steady growth as demand for energy-efficient heating, ventilation, and air conditioning systems continues to increase across residential, commercial, and industrial buildings. Rapid urbanization, expanding construction activities, and growing investments in building modernization are driving the need for high-performance air distribution products that improve airflow, indoor air quality, and overall HVAC system efficiency. In addition, increasingly stringent energy efficiency standards and green building regulations are encouraging the adoption of insulated duct systems, low-leakage air distribution components, and smart airflow control solutions. As building owners and contractors continue to prioritize energy savings, occupant comfort, and sustainable building operations, manufacturers offering durable, high-efficiency, and application-specific HVAC distribution products are expected to benefit from sustained long-term market growth.
Equipment Insights
Based on equipment, the heat pump segment led the market with the largest revenue share of 35.4% in 2025. The global heat pump market is experiencing significant growth, driven by increasing demand for energy-efficient and sustainable heating and cooling solutions. Governments worldwide are implementing policies and offering incentives to promote the adoption of heat pumps, aiming to reduce greenhouse gas emissions and enhance energy efficiency. Technological advancements, such as the development of low-GWP refrigerants and integration with renewable energy sources, are further propelling market expansion.
The HVAC distribution market for air conditioning systems is witnessing steady growth, driven by increasing urbanization, rising temperatures, and growing demand for energy-efficient cooling solutions. The demand for both residential and commercial air conditioning units is surging, particularly in regions experiencing extreme heat or rapid infrastructural development. In addition to traditional air conditioning units, the market is also seeing a rise in demand for smart HVAC systems that offer greater control, energy efficiency, and integration with home automation systems.
Application Insights
Based on application, the new construction segment led the market with the largest revenue share of 56.8% in 2025. In the HVAC distribution market, the new construction segment represents a significant growth driver, driven by the global expansion of residential, commercial, and industrial infrastructure. As developers prioritize energy efficiency and compliance with green building standards from the outset, demand is rising for advanced HVAC systems that integrate seamlessly into modern building designs. Distributors play a key role in supplying high-efficiency units, smart HVAC technologies, and customizable system configurations tailored to new building specifications.
The retrofit & renovation application segment is a crucial part of the HVAC distribution industry, fueled by the need to upgrade aging infrastructure and improve the energy performance of existing buildings. Building owners are increasingly replacing outdated HVAC systems with more efficient, environmentally friendly alternatives to comply with evolving regulations and reduce operating costs. This segment presents opportunities for distributors to supply compact, adaptable systems designed for retrofitting without major structural changes.
End Use Insights
Based on end-use, the residential segment led the market with the largest revenue share of 38.9% in 2025. In the residential HVAC distribution market, there is a notable shift towards energy-efficient and sustainable solutions. Homeowners are increasingly opting for systems that not only provide comfort but also contribute to environmental conservation. Rising energy costs and heightened environmental awareness drive this trend. Distributors are responding by offering products that incorporate advanced technologies such as smart thermostats, variable refrigerant flow (VRF) systems, and eco-friendly refrigerants.
 To learn more about this report, Download Free Sample Report
The commercial HVAC distribution market is experiencing a transformation with the integration of smart technologies and a focus on sustainability. Businesses are increasingly adopting HVAC systems equipped with IoT capabilities, enabling real-time monitoring and predictive maintenance. This shift enhances operational efficiency and reduces downtime. Moreover, there is a growing emphasis on energy-efficient solutions to comply with stringent environmental regulations and reduce operational costs. Distributors are expanding their offerings to include systems that support renewable energy integration and provide scalable solutions for diverse commercial applications, from office buildings to industrial facilities.
Distribution Channel Insights
Based on distribution channel, the offline segment led the market with the largest revenue share of 89.1% in 2025. The online distribution channel in the HVAC market is experiencing significant growth, driven by the increasing adoption of e-commerce platforms and changing consumer preferences. Customers now seek the convenience of browsing, comparing, and purchasing HVAC products from the comfort of their homes. Online platforms offer a wide range of products, detailed specifications, and customer reviews, empowering consumers to make informed decisions.
Despite the rise of online channels, the offline distribution channel remains a cornerstone of the HVAC market. Traditional brick-and-mortar stores, authorized dealers, and HVAC contractors continue to play a crucial role, especially for complex installations and commercial projects. These channels provide personalized services, expert advice, and immediate product availability, which are essential for customers requiring tailored solutions and professional installation.
Regional Insights
North America HVAC distribution market is experiencing a shift toward energy-efficient and smart technologies, driven by stringent environmental regulations and rising consumer demand for sustainability. The integration of smart HVAC systems, including AI-based automation and IoT connectivity, is gaining momentum in both residential and commercial sectors.
U.S. HVAC Distribution Market Trends
The HVAC distribution industry in the U.S. is expected to grow at a CAGR of 6.3% from 2026 to 2033. The U.S. market is witnessing increased demand for energy-efficient systems, particularly heat pumps, as part of efforts to reduce carbon emissions and enhance energy efficiency. Government initiatives, such as the U.S. Department of Energy's investment in heat pump manufacturing, are bolstering market growth.
The HVAC distribution market in Canada is expected to grow at a CAGR of 6.6% from 2026 to 2033. Canada's market is benefiting from robust infrastructure investments, particularly in residential and social infrastructure projects. Government funding for retrofitting and upgrading existing buildings is driving demand for energy-efficient HVAC solutions. The market is also seeing a shift towards sustainable technologies, including the adoption of low-GWP refrigerants and integration with renewable energy sources, aligning with the country's environmental goals.
Europe HVAC Distribution Market Trends
Europe's HVAC distribution industry is influenced by a strong emphasis on energy efficiency and decarbonization, with a focus on heat pump adoption. Government incentives and regulations are playing a significant role in promoting sustainable HVAC solutions. However, recent political uncertainties and changes in support schemes have impacted market dynamics, leading to fluctuations in heat pump sales across different countries.
Germany HVAC distribution market held a 32.4% share of the Europe market in 2025. A strong commitment to sustainability and energy efficiency characterizes Germany's market. The country's focus on reducing carbon emissions and enhancing energy performance in buildings is driving the demand for advanced HVAC systems. Despite challenges such as fluctuating support schemes and economic factors, the market continues to prioritize the adoption of energy-efficient technologies.
The HVAC distribution market in the UK is experiencing growth due to increasing demand for cooling solutions and the government's commitment to achieving net-zero greenhouse gas emissions by 2050. Reversible heat pumps are gaining popularity as a cost-effective and sustainable solution for both heating and cooling needs.
Asia Pacific HVAC Distribution Market Trends
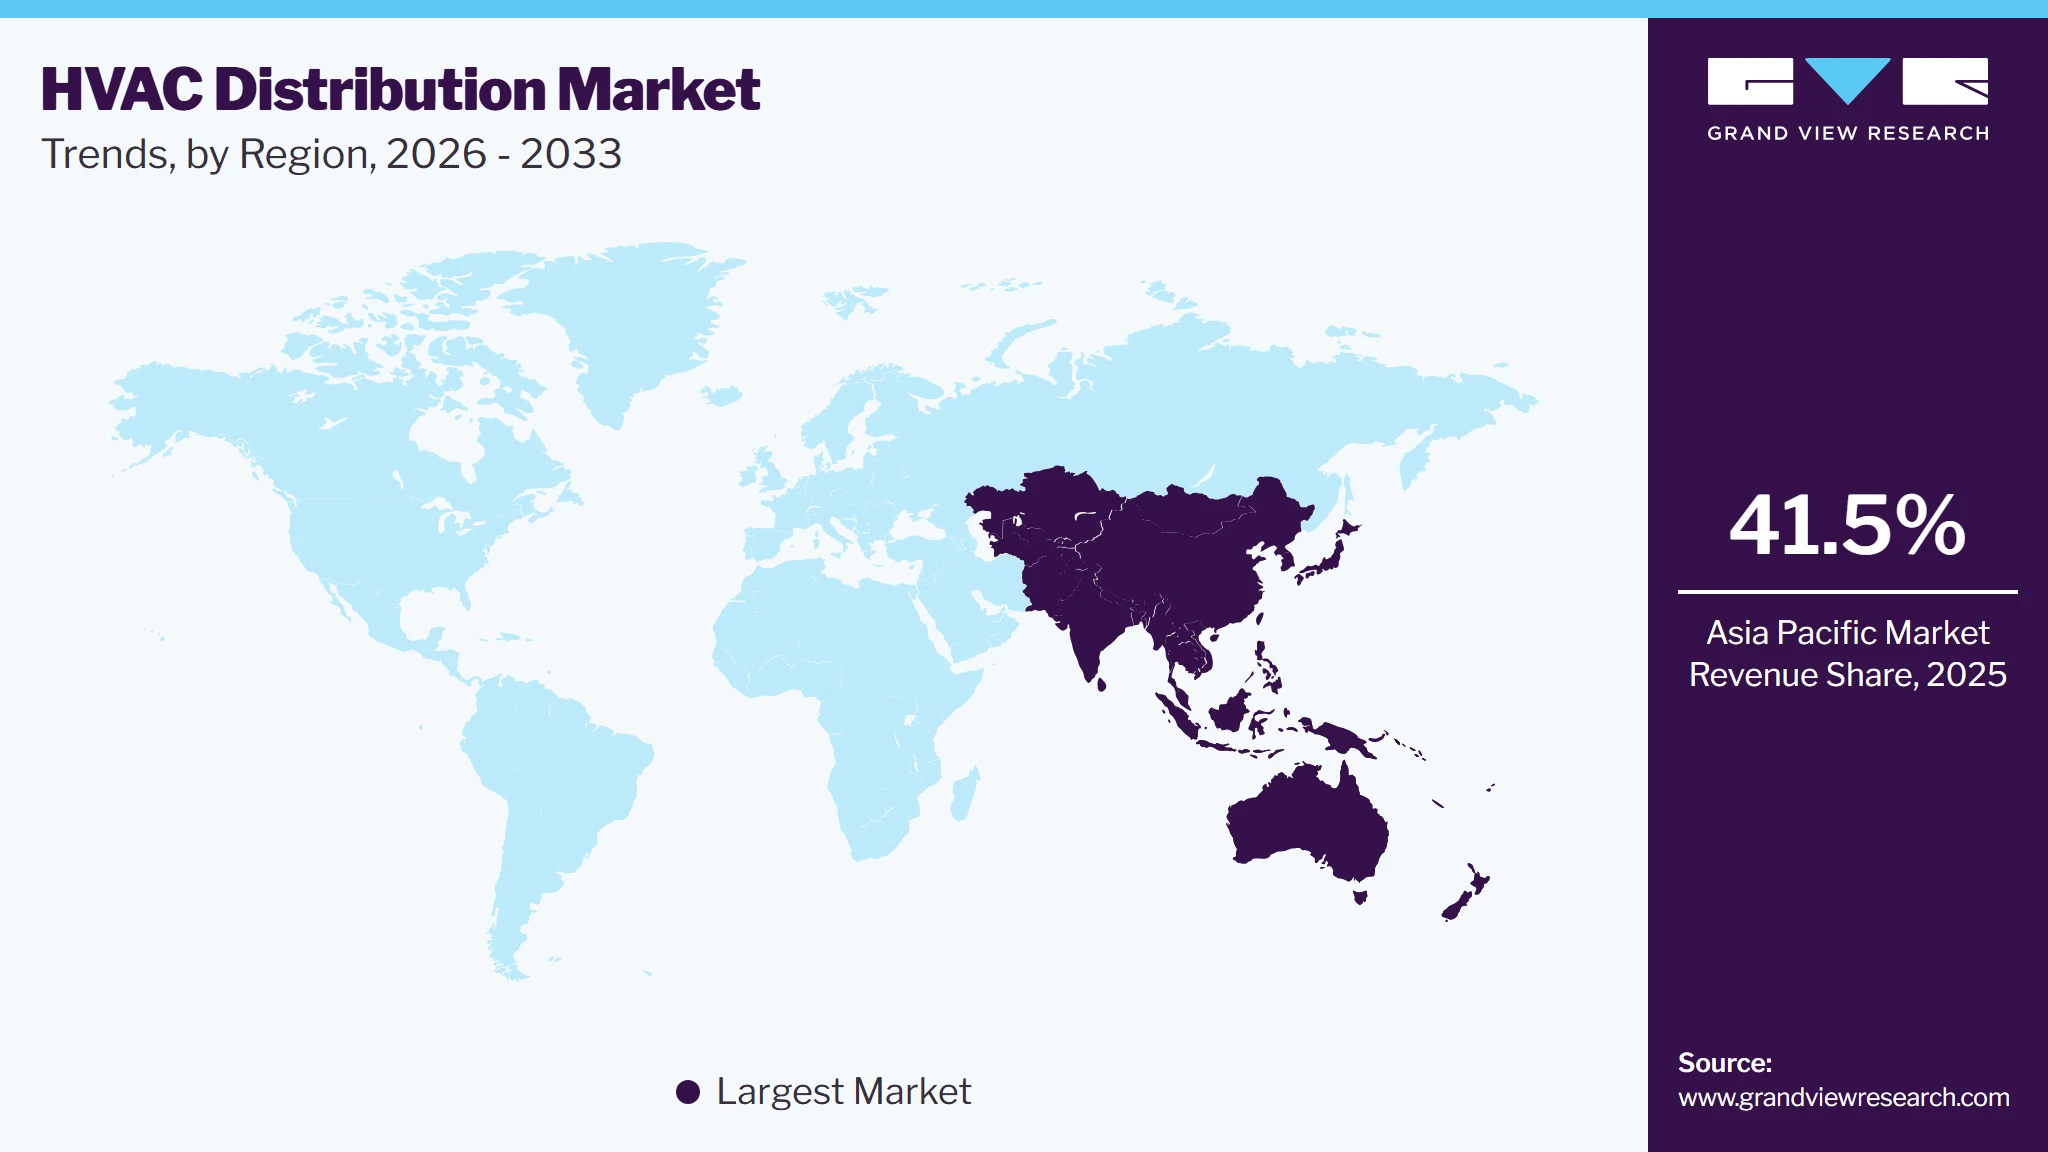
Asia Pacific dominated the HVAC distribution market with the largest revenue share of 41.5% in 2025. The Asia Pacific market is expanding rapidly, driven by urbanization, industrialization, and increasing construction activities. Countries in the region are adopting energy-efficient HVAC systems, with a focus on integrating renewable energy sources and low-GWP refrigerants. The market is also witnessing the rise of smart HVAC systems and IoT integration, enhancing system efficiency and user control.
 To learn more about this report, Download Free Sample Report
The HVAC distribution market in China held the largest share in the Asia Pacific region in 2025. China HVAC distribution market held a significant share of Asia Pacific. China's HVAC distribution industry is experiencing significant growth due to rapid urbanization and industrial development. The government's focus on energy efficiency and environmental sustainability is driving the adoption of advanced HVAC technologies. The market is also witnessing increased demand for smart HVAC systems and integration with renewable energy sources, aligning with the country's green building initiatives.
The HVAC distribution market in India is expected to grow at a CAGR of 7.2% from 2026 to 2033. India's market is expanding in response to rapid urbanization and increasing construction activities. The government's initiatives to promote energy efficiency and sustainable building practices are driving demand for advanced HVAC systems. The market is also seeing a rise in the adoption of smart HVAC technologies and low-GWP refrigerants, reflecting a shift towards environmentally friendly solutions.
Middle East & Africa HVAC Distribution Market Trends
Extreme climate conditions and growing infrastructure development influence the Middle East and Africa's HVAC distribution industry. Countries in the region are investing in energy-efficient HVAC systems to reduce energy consumption and enhance indoor comfort. The market is also witnessing increased adoption of smart HVAC technologies and sustainable solutions, reflecting a shift towards environmentally friendly practices.
Saudi Arabia's HVAC distribution market is expanding in response to urbanization and infrastructure development. The government's initiatives to promote energy efficiency and sustainable building practices are driving demand for advanced HVAC systems. The market is also seeing a rise in the adoption of smart HVAC technologies and low-GWP refrigerants, aligning with the country's Vision 2030 goals for sustainability.
Latin America HVAC Distribution Market Trends
Latin America's HVAC distribution industry is influenced by growing infrastructure development and urbanization. Countries in the region are increasingly adopting energy-efficient HVAC systems, driven by government incentives and regulations. The market is also witnessing a shift towards sustainable technologies, including the use of low-GWP refrigerants and integration with renewable energy sources.
Brazil's HVAC distribution market is expanding due to increasing demand for cooling solutions in the residential and commercial sectors. The government's focus on energy efficiency and environmental sustainability is driving the adoption of advanced HVAC technologies. The market is also seeing a rise in the use of smart HVAC systems and low-GWP refrigerants, aligning with global sustainability trends.
Key HVAC Distribution Company Insights
Some of the key players operating in the market include Watsco, Inc.; Winsupply Inc.; and Ferguson Enterprises.
-
Watsco, Inc. is the largest distributor of air conditioning, heating, and refrigeration (HVAC/R) equipment and related parts and supplies in North America. Founded in 1956 and headquartered in Miami, Florida, Watsco operates over 670 locations across the United States, Canada, Mexico, and Puerto Rico. The company serves more than 350,000 contractors and technicians annually, offering a wide range of products, including residential and commercial HVAC systems, parts, and supplies. Watsco's business strategy focuses on acquiring businesses to build density in existing markets and expand its network into new geographic areas.
-
Winsupply Inc. is a leading supplier of residential and commercial construction and industrial supplies and equipment in the United States. Established in 1956 and headquartered in Dayton, Ohio, Winsupply operates approximately 630 wholesaling locations across 45 states. The company offers a diverse range of products, including plumbing, HVAC, electrical, industrial pipe, valves and fittings, and waterworks supplies.
Key HVAC Distribution Companies:
The following key companies have been profiled for this study on the HVAC distribution market.
-
HVAC Distributors
-
Watsco, Inc.
-
CAREL Japan
-
Salvador Escoda
-
Ferguson Enterprises
-
Reece Group
-
Winsupply Inc.
-
Johnstone Supply
-
Dynamic distributors
-
Gustave A. Larson Company
-
United Refrigeration, Inc.
-
2J Supply HVAC Distributors
-
Duncan Supply Co. Inc.
-
Crescent Parts & Equipment
-
Northeastern Supply Co.
-
Guangzhou Tofee Electro-Mechanical Equipment Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Watsco, Inc.; Ferguson Enterprises Inc.; Reece Group Limited; Winsupply Inc.; Johnstone Supply; United Refrigeration, Inc.)
- Expand geographic presence through branch network expansion and strategic acquisitions.
- Strengthen distribution capabilities through digital procurement, inventory optimization, and supply chain integration.
- Enhance customer retention by offering value-added services, including technical support, contractor training, financing solutions, and just-in-time delivery.
- Extensive distribution networks supported by strong supplier relationships and diversified product portfolios.
- Significant purchasing power, enabling favorable procurement terms and high inventory availability.
- Advanced logistics infrastructure that supports efficient order fulfillment and broad market coverage.
- High operating and inventory carrying costs associated with extensive distribution networks.
- Exposure to fluctuations in construction activity and replacement demand affecting sales volumes.
- Operational complexity arising from multi-location network management and post-acquisition integration.
Emerging & Regional Players (e.g., Gustave A. Larson Company; 2J Supply HVAC Distributors; Duncan Supply Co., Inc.; Salvador Escoda S.A., regional players)
- Strengthen regional market presence through localized distribution networks and contractor-focused service models.
- Differentiate through responsive customer support, technical assistance, and specialized product availability.
- Expand product portfolios and distribution capabilities to increase market penetration within regional markets.
- Strong relationships with regional contractors, dealers, and installation partners.
- Operational flexibility that enables faster response to local market requirements.
- Specialized regional expertise and customized service offerings that support customer retention.
- Limited geographic footprint and procurement scale relative to established distributors.
- Lower investment capacity for digital transformation, automation, and distribution infrastructure.
- Greater sensitivity to regional economic conditions and competitive pricing pressures.
Recent Developments
-
In May 2025, Watsco completed the acquisition of Southern Ice Equipment Distributors, alongside two other transactions earlier in the year. In January, Watsco acquired Lashley & Associates, a U.S. based distributor specializing in custom air movement products and commercial supplies. This was followed by the acquisition of Hawkins HVAC Distributors in April 2025, a supplier of HVAC supplies and equipment with locations in North Carolina, and South Carolina. The terms of these transactions were not disclosed.
-
In May 2025, Winsupply acquired Industrial Sales Co. which serves water, gas, telecom, geothermal, landscape and equipment customers throughout the Midwest.Terms of the deal were not disclosed.
HVAC Distribution Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 294.8 billion
Market size value in 2026
USD 312.2 billion
Revenue forecast in 2033
USD 497.0 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, end-use, distribution channel, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Watsco, Inc., Ferguson Enterprises Inc., Reece Group Limited, Winsupply Inc., Johnstone Supply, United Refrigeration, Inc., Gustave A. Larson Company, 2J Supply HVAC Distributors, Duncan Supply Co., Inc., Salvador Escoda S.A.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global HVAC Distribution Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global HVAC distribution market report based on equipment, end use, distribution channel, application, and region:
-
Equipment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Heat Pump
-
Furnace
-
Unitary Heaters
-
Boilers
-
Air Purifier
-
Dehumidifier
-
Air Handling Units
-
Ventilation Fans
-
Air Conditioning
-
Chillers
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Commercial
-
Residential
-
Industrial
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Offline
-
B2B
-
B2C
-
-
Online
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
New Construction
-
Retrofit & Renovation
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Spain
-
Italy
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The HVAC distribution market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each HVAC distribution segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Equipment
Revenue Capture Definition
Heat Pump
Revenue generated from the distribution and wholesale sale of air-source, ground-source, and water-source heat pumps to contractors, dealers, commercial customers, and other end users.
Furnace
Revenue generated from the distribution and sale of gas, electric, and oil-fired furnaces through HVAC distribution networks.
Unitary Heaters
Revenue generated from the distribution of self-contained unitary heating systems supplied to commercial and industrial customers through authorized distribution channels.
Boilers
Revenue generated from the distribution and wholesale sale of hot water and steam boilers used in residential, commercial, and industrial applications.
Air Purifier
Revenue generated from the distribution of standalone and integrated air purification systems through HVAC distributors and dealer networks.
Dehumidifier
Revenue generated from the distribution and sale of residential, commercial, and industrial dehumidification equipment.
Air Handling Units (AHUs)
Revenue generated from the distribution of air handling units supplied for commercial, industrial, and institutional HVAC installations.
Ventilation Fans
Revenue generated from the distribution and wholesale sale of residential, commercial, and industrial ventilation fans through HVAC distribution channels.
Air Conditioning
Revenue generated from the distribution of split systems, packaged units, central air conditioners, ductless systems, and other air conditioning equipment.
Chillers
Revenue generated from the distribution and wholesale sale of air-cooled and water-cooled chillers for commercial and industrial cooling applications.
Others
Revenue generated from the distribution of HVAC accessories, controls, thermostats, filters, ducting components, refrigerants, replacement parts, and related products.
Segment - End Use
Revenue Capture Definition
Commercial
Revenue generated from the distribution of HVAC products supplied to offices, retail buildings, healthcare facilities, educational institutions, hospitality establishments, and other commercial facilities.
Residential
Revenue generated from the distribution of HVAC equipment and components supplied for single-family homes, apartments, condominiums, and other residential buildings.
Industrial
Revenue generated from the distribution of HVAC equipment supplied to manufacturing facilities, warehouses, power plants, data centers, and other industrial facilities.
Segment - Distribution Channel
Revenue Capture Definition
Offline
Revenue generated through physical HVAC distributors, wholesale branches, dealer networks, and brick-and-mortar sales channels, including sales to contractors, builders, OEMs, commercial and industrial customers (B2B), as well as direct sales to individual consumers through distributor-operated retail outlets and authorized dealers (B2C).
Online
Revenue generated through e-commerce platforms, distributor websites, online procurement portals, and digital marketplaces selling HVAC equipment, components, parts, and accessories to both business and individual customers.
Segment - Application
Revenue Capture Definition
New Construction
Revenue generated from the distribution of HVAC equipment and components installed in newly constructed residential, commercial, and industrial buildings.
Retrofit & Renovation
Revenue generated from the distribution of replacement HVAC systems, components, and accessories used for equipment upgrades, modernization, and renovation projects in existing buildings.
Estimation Model
Layer Name
Key Question
Description
HVAC Equipment Demand Layer
Where are HVAC distribution products required?
Analyze demand across residential, commercial, and industrial buildings. Assess new construction activity, renovation projects, HVAC equipment installations, replacement demand, and ducted HVAC adoption to establish the addressable demand for HVAC distribution products.
Construction & Building Infrastructure Investment Layer
Where is new product demand being created?
Evaluate investments in residential housing, commercial buildings, healthcare facilities, educational institutions, industrial plants, warehouses, and data centers. Assess greenfield construction, retrofit projects, energy-efficiency upgrades, and HVAC modernization initiatives that drive procurement of new HVAC distribution products.
Product Adoption Layer
Which HVAC distribution products are being deployed?
Segment demand by product type, material, distribution channel, application, and end-use industry. Apply adoption rates based on building type, airflow requirements, HVAC system configuration, energy efficiency standards, indoor air quality requirements, and regional building codes.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of HVAC distribution products by product type, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new HVAC distribution products supplied through OEMs, wholesalers, distributors, contractors, and retailers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked leading HVAC distributors and manufacturers based on product portfolio, financial performance, technology capabilities, geographic presence, and strategic positioning, distinguishing global leaders from regional and specialized players
Enabled client to evaluate market positioning, identify differentiation levers, and track competitive threats across fragmented channel landscape
Regional Segmentation
Refined regional analysis by evaluating construction activity, regulatory frameworks (energy efficiency standards, refrigerant phase-down mandates), manufacturing activity, and distribution infrastructure across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
Facilitated identification of high-growth regions, regulatory hotspots, and investment priorities to support targeted market entry and expansion decisions
Opportunity Assessment
Assessed emerging growth opportunities across retrofit installations, energy-efficient smart HVAC systems (IoT-enabled, AI-driven controls), data center cooling, residential replacement demand, and digitally enabled distribution channels
Prioritized high-potential revenue pockets including heat pump adoption, aging infrastructure retrofits, and aftermarket services to guide strategic investment
Frequently Asked Questions About This Report
The global HVAC distribution market size was estimated at USD 294.8 billion in 2025 and is projected to grow from USD 312.2 billion in 2026.
The global HVAC distribution market, in terms of revenue, is expected to grow at a compound annual growth rate of 6.9% from 2026 to 2033 to reach USD 497.0 billion by 2033.
Some of the key players operating in the HVAC distribution market include HVAC Distributors, Watsco, Inc., Ferguson Enterprises Inc., Reece Group Limited, Winsupply Inc., Johnstone Supply, United Refrigeration, Inc., Gustave A. Larson Company, 2J Supply HVAC Distributors, Duncan Supply Co., Inc., Salvador Escoda S.A.
The market is influenced by technological advancements in energy efficiency, smart systems, and sustainability. As environmental concerns and energy regulations tighten, the demand for energy-efficient and eco-friendly HVAC solutions continues to grow, driving innovation and competition in the market.
The heat pump segment accounted for the largest market share of 35.4% in 2025, driven by rising demand for energy-efficient heating and cooling systems and supportive government incentives for electrification.
The offline distribution channel held the largest revenue share of 89.1% in 2025 due to the extensive network of wholesalers, distributors, and authorized dealers that provide technical support and installation services.
The new construction segment led the market with a 56.8% revenue share in 2025, supported by increasing residential, commercial, and industrial construction activities worldwide.
The residential segment accounted for the largest revenue share of 38.9% in 2025, owing to growing demand for home comfort solutions, energy-efficient HVAC systems, and replacement of aging equipment.
Asia Pacific held the largest revenue share of 41.5% in 2025, driven by rapid urbanization, infrastructure development, expanding construction activities, and increasing HVAC adoption across residential and commercial sectors.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


