
- Home
- »
- Petrochemicals
- »
-
Industrial Gases Market Size & Share Report, 2026-2033GVR Report cover

Industrial Gases Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Nitrogen, Oxygen, Hydrogen, Carbon Dioxide), By Application (Healthcare, Manufacturing, Retail), By Distribution (Bulk), By Region, And Segment Forecasts
Market Size, 2025
$119.1BMarket Estimate, 2026
$127.3BMarket Forecast, 2033
$172.6BCAGR, 2026–2033
4.4%Industrial Gases Market Summary
The global industrial gases market size was valued at USD 119.1 billion in 2025 and is projected to grow from USD 127.3 billion in 2026 to USD 172.6 billion by 2033, at a CAGR of 4.4% from 2026 to 2033. The market in Europe dominated with a revenue share of 41.7% in 2025. The growth is primarily driven by the growing manufacturing industry in developing economies of the Asia Pacific region.
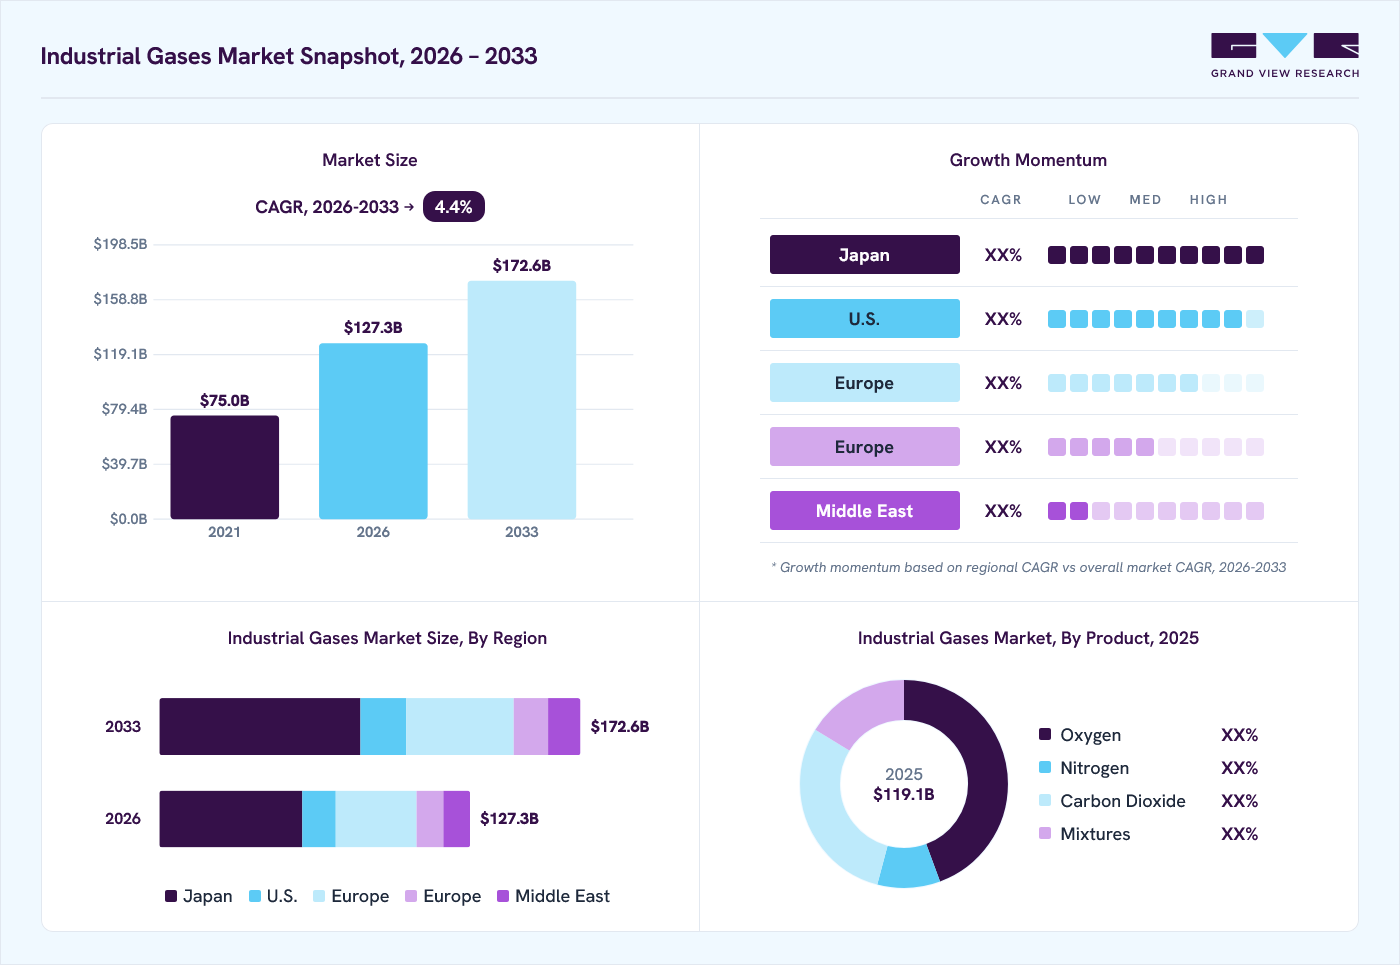 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Oxygen segment held the largest market share of 38.5% in 2025.
- By distribution: Cylinder segment held the largest market share of 36.5% in 2025.
- By application: Healthcare segment held the largest market share of 27.0% in 2025.
Regional Highlights
- Largest regional market: Europe (41.7% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 119.1 Billion
- Estimated market size in 2026: USD 127.3 Billion
- Projected market size by 2033: USD 172.6 Billion
- CAGR (2026-2033): 4.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rapid industrialization and the application of industrial gases in various industries, such as manufacturing, mining, metals, food & beverage, and healthcare, are further expected to influence the market growth in the coming years. However, environmental regulations, safety, and high gas conversion costs may hinder the industry's growth during the forecast period. The U.S. accounted for a majority share in the North America regional market and is expected to retain its leading position throughout the forecast period. The U.S. emerged as one of the major countries utilizing industrial gases, as the country has the presence of a large number of major industrial gas suppliers, such as Linde, Air Liquide, Messer, and Air Products & Chemicals. The growing healthcare industry in the U.S., coupled with growing R&D in the healthcare sector owing to the recent outbreak of the COVID-19 pandemic, is expected to propel the demand for industrial gases in the U.S.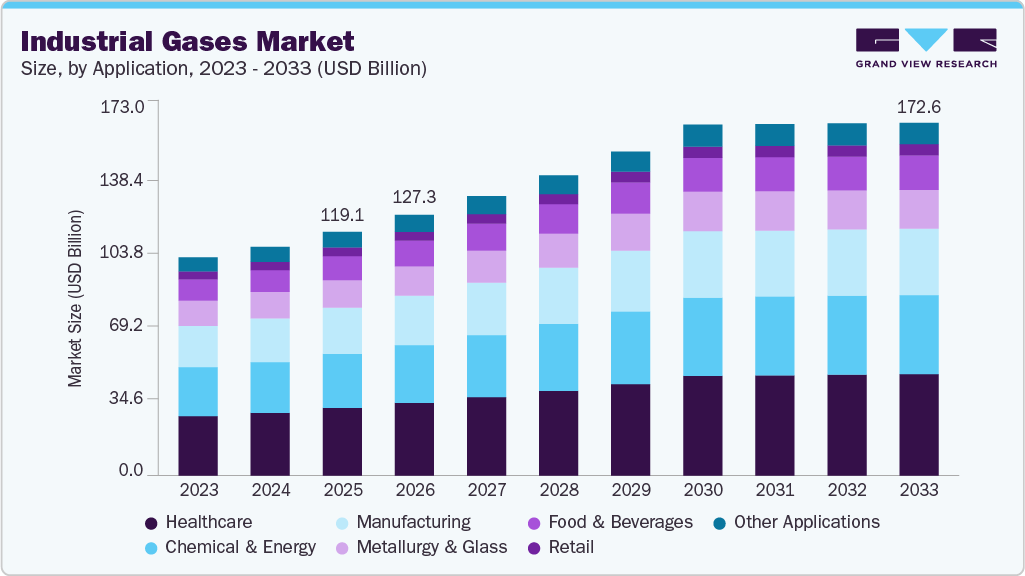 To learn more about this report, Download Free Sample Report
The dependence of the electronics end-use sector on industrial gases has provided an alternate source of opportunity for the market, given the broad range of applications from flat-panel displays and semiconductors to LED lights and solar cells. Unlike the petrochemical and metallurgy industry, the electronics end-use industry embraces suppliers to greater standards with regard to project experience, coverage, and technical specifications. Asia Pacific accounted for a significant revenue share in 2025 and is projected to continue to dominate the global market during the forecast period. The economic growth in countries, such as China, India, and South Korea, has shown strong growth and the trend is expected to continue over the forecast period. The presence of major electronics companies in the U.S. is also one of the major reasons driving the demand for industrial gases. In the U.S., the usage of electronics is increasing day by day, with an ever-growing number of electronic devices and gadgets being manufactured for the convenience of consumers. The growing healthcare and electronic industries across the region are likely to promote market growth. Expansion of the industrial sector is anticipated to further fuel the regional market.
Market Dynamics
The industrial gases market is being driven by the expansion of manufacturing, healthcare, electronics, and energy industries, where gases such as oxygen, nitrogen, hydrogen, argon, and carbon dioxide play a critical operational role. Industrial gases are extensively used in metal fabrication, semiconductor manufacturing, chemical processing, welding, food preservation, and refinery operations due to their importance in process efficiency and product quality. According to data published by the World Steel Association, global crude steel production exceeded 1.8 billion tons in 2024, supporting strong consumption of oxygen and nitrogen across steel manufacturing and metal processing activities.
Healthcare demand is also contributing significantly to market growth, particularly for medical oxygen and specialty gases used in hospitals, diagnostics, and pharmaceutical manufacturing. Industrial gas companies are increasingly investing in air separation units, hydrogen infrastructure, and on-site gas supply systems to strengthen long-term supply capabilities. In parallel, rising adoption of hydrogen in clean energy projects and semiconductor manufacturing expansion is further accelerating demand for high-purity industrial gases across advanced industrial applications.
A major restraint for the industrial gases market is the high energy intensity associated with gas production and distribution processes. Production technologies such as cryogenic air separation, hydrogen generation, and gas liquefaction require substantial electricity consumption and continuous operational stability, making industrial gas manufacturers highly exposed to fluctuations in energy prices. Rising electricity and natural gas costs continue to impact operating margins, particularly in regions facing energy supply instability and carbon reduction regulations.
Industrial gas infrastructure development involves significant capital investment in production plants, pipelines, storage systems, and transportation networks. Establishing air separation units and bulk gas distribution systems requires long project timelines and high upfront expenditure, which can limit expansion in developing and cost-sensitive markets. Compliance with industrial safety regulations, emissions standards, and hazardous gas handling requirements further increase operational complexity and maintenance costs for manufacturers and distributors.
Product Insights
On the basis of products, the global industry has been further categorized into oxygen, nitrogen, hydrogen, carbon dioxide, acetylene, and argon. The oxygen product segment dominated the industry in 2025 and accounted for the highest share of 38.52% of the overall revenue. Oxygen is utilized for fabrication, steel melting, medical applications, copper smelting, etc. Oxygen is known to improve the thermal efficiency of fuel. Thus, oxygen can be used as a methodology for obtaining better energy from fuel.
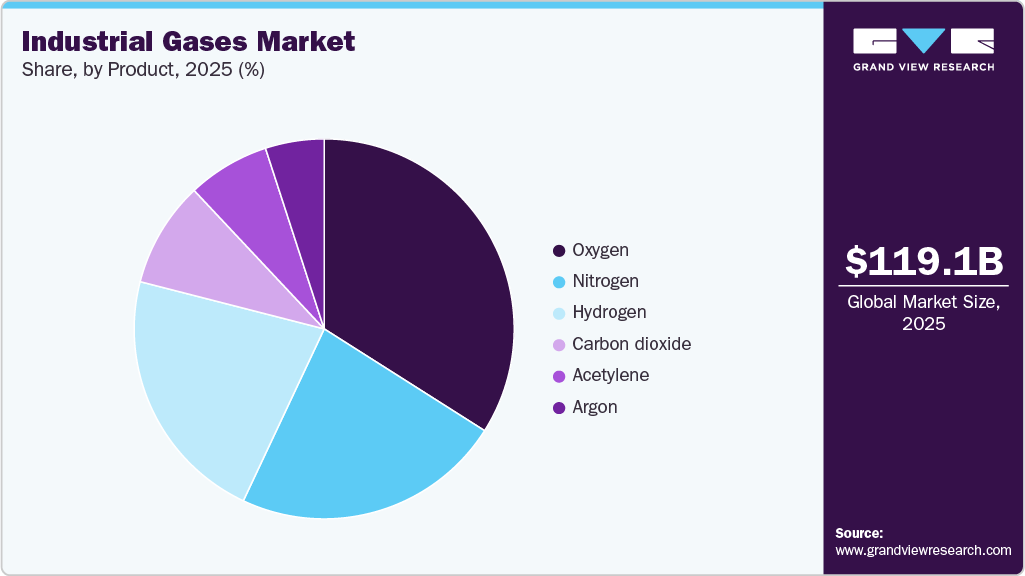 To learn more about this report, Download Free Sample Report
Similarly, it can also be used for the cleanup of hazardous, treatment of polluted water, and coal gasification systems. It is considered an alternative to chlorine in the pulp & paper industry to decrease pollution.Nitrogen has the highest growth rate and penetration owing to large-scale applications in the medical and pharmaceutical industries. The global pandemic has resulted in healthcare facilities demanding essential medical supplies and other essential life-saving devices to prevent the spread of the virus and provide optimum care to infected patients.
Distribution Insights
The cylinder segment led the industry in 2025 and accounted for the largest revenue share of 36.55%. It is the most preferred form of distribution by consumers. This type of distribution is practiced by independent gas distributors by purchasing gas from producers and compressing them in their packaging facilities. Many gases are also supplied at room temperature in the liquid state. The gases are stored at low pressure in thin-walled steel or composite aluminum cylinders. The bulk (Liquid Gas Transport) distribution segment accounted for the second-largest share in 2025. This involves the gas in a liquefied or natural state being transported by either road (dedicated trailers) or via pipelines (over long distances).
This mode of delivery is ideally opted when the demand for gases is higher than packaged gas distribution and lesser than onsite distribution. This is a more efficient form of distribution and is, therefore, more preferred than the other modes of distribution since it ensures a continuous supply of gases. The onsite form of distribution is the most conducive form of distribution for the manufacturing companies like Air Products & Chemicals, The Linde Group, Air Liquide, etc. since it reduces their transportation costs. The company’s onsite plant usually integrates onsite facilities at refueling stations to optimize its operations. The supply systems are set up around standardized components to ensure maximum cost efficiency.
Application Insights
The healthcare industry application segment accounted for the largest share of 27.04% of the overall revenue in 2025 and is projected to grow at the second-highest CAGR during the forecast period. Governments across the globe are investing in medical research as medical institutes and pharmaceutical companies are working towards developing vaccines and medicine to fight novel coronavirus. This is driving the demand for industrial nitrogen, which is used in the healthcare industry. Carbon dioxide is also widely used for cryopreservation applications, where tissues, gametes, cellular samples, and embryos are preserved at extremely low temperatures. Industrial gases also find application in various other industries including automotive & transportation, aerospace & aircraft, water & wastewater treatment, and others.
Manufacturing is estimated to be the fastest-growing segmentfrom 2026 to 2033. The demand for industrial gases in the manufacturing industry is projected to witness rapid growth owing to various applications. Carbon dioxide is frequently used in the rubber industry in the form of dry ice for the non-abrasive cleaning of rubber molds. It is commonly used by manufacturers of molded rubber products to reduce production downtime and maintenance & labor costs. The use of carbon dioxide for the cleaning of essential tools and molds in the rubber industry offers various advantages over conventional cleaning methods.
Regional Insights
On the basis of geographies, the global industry has been further categorized into Asia Pacific, North America, Europe, Latin America, and Middle East & Africa. Europe dominated the industry in 2025, in terms of revenue share. The growth and demand is strong in chemicals, healthcare, metallurgy, and electronics, with increasing focus on green hydrogen and carbon capture applications. While traditional industrial demand is relatively stable, energy costs and regulatory compliance significantly influence pricing and investment decisions. Innovation and sustainability-driven applications are key growth drivers.
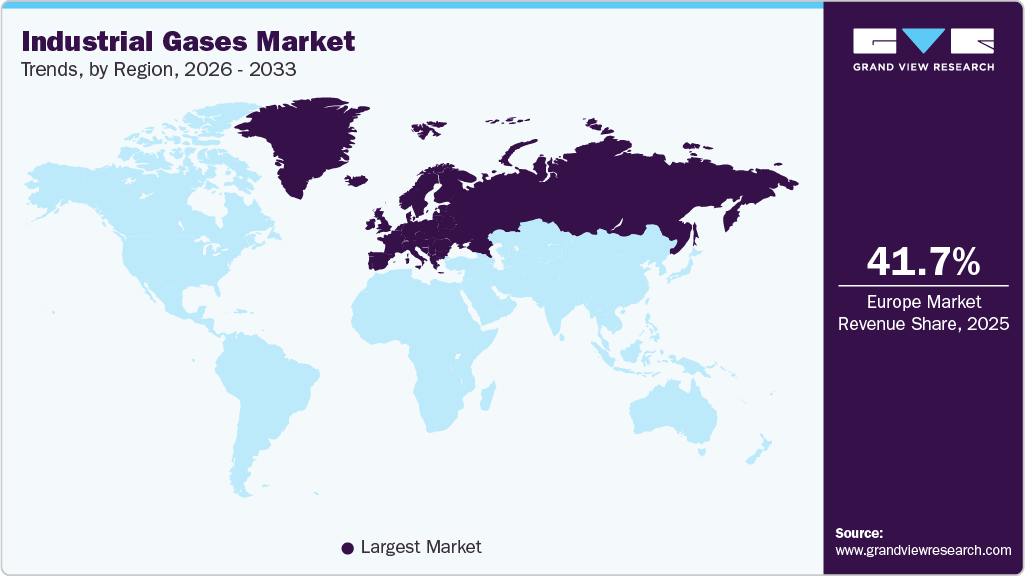 To learn more about this report, Download Free Sample Report
Germany Industrial Gases Market Trends
Germany is one of Europe’s key industrial gases consumers, supported by its strong manufacturing, automotive, chemicals, and engineering sectors. Demand is increasingly influenced by energy transition initiatives, particularly hydrogen and low-carbon industrial processes. While traditional demand is mature, investment in green technologies sustains long-term growth potential.
North America Industrial Gases Market Trends
In 2025, North America accounted for the second-largest revenue share. The growing healthcare industry and expansion of the industrial sector in the U.S. and Canada are expected to foster the demand for industrial gases in the region.
Asia Pacific Industrial Gases Market Trends
Asia Pacific’sexpansion of end-use industries in key markets like India, China, South Korea, and Japan are expected to driven by rapid industrialization, urbanization, and expansion of manufacturing across China, India, Japan, and Southeast Asia. Strong demand from steel, chemicals, electronics, healthcare, and food & beverage industries supports sustained growth. Increasing investments in electronics fabrication, clean energy, and hydrogen infrastructure further enhance market potential. Merchant liquid supply and on-site gas generation models are expanding across the region to support large industrial customers.
China is the largest country market in the APAC regional market owing to increasing demand for industrial gases in the aerospace industry for high-quality gas solutions. Growth and expansion of the food & beverage and industrial sectors in key markets like China and India are also expected to fuel the demand for industrial gases over the forecast period.
Latin America Industrial Gases Market Trends
The Latin America industrial gases market is developing and demand-driven, supported by growth in metals & mining, oil & gas, food processing, and healthcare. Countries such as Brazil, Mexico, and Chile account for the majority of consumption. Market growth is linked to industrial expansion and infrastructure development, though investment is constrained by economic volatility and limited pipeline infrastructure. Merchant liquid and cylinder supply models dominate the region.
MEA Industrial Gases Market Trends
The MEA industrial gases market is emerging but high-potential, driven by oil & gas, refining, chemicals, and large-scale infrastructure projects. The Middle East shows strong demand for hydrogen, oxygen, and nitrogen, supported by petrochemical complexes and energy-intensive industries. In Africa, demand growth is led by mining, healthcare, and basic manufacturing, though infrastructure limitations remain a constraint. Long-term industrial diversification strategies support gradual market expansion.
Key Industrial Gases Company Insights
The global industry is highly competitive due to the strong presence of many regional as well as multinational companies.Key industry participants are involved in research and development and constant innovation, which have become among the most important factors for them to perform in the competitive industry.
Key Industrial Gases Companies:
The following are the leading companies in the industrial gases market. These companies collectively hold the largest market share and dictate industry trends.
- Air Liquide
- Air Products Inc.
- INOX-Air Products Inc.
- Iwatani Corp.
- Linde plc
- Messer
- SOL Group
- Strandmøllen A / S
- Taiyo Nippon Sanso Corp.
- Matheson Tri-Gas Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: Air Liquide, Air Products Inc., Linde plc, Messer, Taiyo Nippon Sanso Corp., Matheson Tri-Gas Inc.
- Focused on long-term industrial gas supply contracts across manufacturing, healthcare, electronics, and energy sectors.
- Expanded investments in hydrogen, carbon capture, and clean energy gas infrastructure projects.
- Strengthened global production and distribution networks through on-site plants and pipeline systems.
- Maintained strong global presence with diversified end-use industry exposure.
- Benefited from large-scale production capabilities and integrated supply infrastructure.
- Demonstrated advanced technological expertise in specialty and high-purity gases.
- Faced high capital investment requirements for plant expansion and infrastructure maintenance.
- Remained exposed to energy price fluctuations and operational cost volatility.
- Experienced regulatory pressure related to emissions, safety, and environmental compliance.
Emerging Players: INOX-Air Products Inc., Iwatani Corp., SOL Group, Strandmøllen A/S
- Concentrated on regional industrial gas distribution and localized customer service.
- Expanded presence in healthcare, fabrication, and small-scale manufacturing industries.
- Focused on strategic partnerships and selective capacity expansion in high-growth regions.
- Benefited from strong regional market understanding and customer proximity.
- Demonstrated faster responsiveness to localized industrial demand changes.
- Maintained competitive pricing structures in regional markets.
- Operated with limited global infrastructure and lower international market penetration.
- Faced comparatively weaker technological capabilities in specialty gas applications.
- Higher dependence on regional industrial activity increased market concentration risk.
Industrial Gases Market Report Scope
Report Attribute
Details
Market size in 2025
USD 119.1 billion
Estimated market size in 2026
USD 127.3 billion
Projected market size by 2033
USD 172.6 billion
Growth rate
CAGR of 4.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2018 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in million SCF, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, distribution, and region
Regional scope
Asia Pacific; North America; Europe; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; The Netherlands; China; India; Japan; South Korea; Australia; Malaysia; Thailand; Singapore; Brazil; Saudi Arabia; UAE
Key companies profiled
Air Liquide; Linde plc; Air Products Inc.; Taiyo Nippon Sanso Corp.; Messer; SOL Group; Iwatani Corp.; Matheson Tri-Gas, Inc.; INOX-Air Products Inc.; Strandmøllen A/S
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional, and segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Industrial Gases Market Report Segmentation
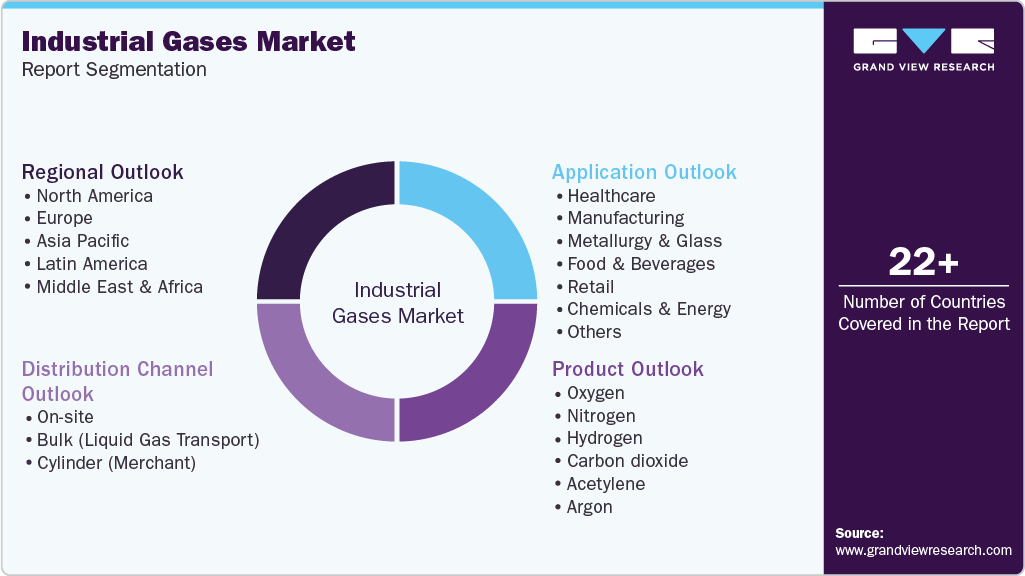
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2033. For the purpose of this study, Grand View Research has segmented the global industrial gases market report based on product, application, distribution, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Million SCF; Revenue, USD Million, 2018 - 2033)
-
Oxygen
-
Nitrogen
-
Hydrogen
-
Carbon dioxide
-
Acetylene
-
Argon
-
-
Application Outlook (Volume, Million SCF; Revenue, USD Million, 2018 - 2033)
-
Healthcare
-
Manufacturing
-
Metallurgy & Glass
-
Food & Beverages
-
Retail
-
Chemicals & Energy
-
Others
-
-
Distribution Outlook (Volume, Million SCF; Revenue, USD Million, 2018 - 2033)
-
On-site
-
Bulk (Liquid Gas Transport)
-
Cylinder (Merchant)
-
-
Regional Outlook (Volume, Million SCF; Revenue, USD Million, 2018 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
The Netherlands
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Malaysia
-
Thailand
-
Singapore
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
A detailed regional assessment of the industrial gases market was conducted across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, including country-level analysis of nitrogen, hydrogen, oxygen, carbon dioxide, argon, and acetylene demand. The study evaluated manufacturing concentration, industrialization trends, healthcare infrastructure growth, steel production activity, and energy sector demand across major consuming countries.
Enabled identification of high-demand industrial clusters and country-specific growth opportunities. Supported regional expansion planning, production localization strategies, and prioritization of end-use industries with strong gas consumption potential.
Trade Assessment
An assessment of global trade dynamics for industrial gases and related equipment was conducted, covering export-import trends, cross-border gas transportation infrastructure, merchant gas supply chains, and dependency on regional production hubs for hydrogen, oxygen, and specialty gases.
Helped identify supply chain vulnerabilities, trade dependencies, and sourcing diversification opportunities. Supported risk mitigation planning and optimization of international distribution and supply network strategies.
Opportunity Assessment
Emerging opportunities within the industrial gases market were evaluated across green hydrogen projects, healthcare oxygen demand, semiconductor manufacturing expansion, carbon capture applications, and industrial decarbonization initiatives. The analysis also reviewed increasing adoption of on-site gas generation systems in manufacturing and energy-intensive industries.
Enabled identification of long-term growth areas and technology-driven investment opportunities. Supported innovation planning, portfolio diversification, and strategic expansion into high-value industrial and clean energy applications.
Frequently Asked Questions About This Report
The global industrial gases market size was valued at USD 119.1 billion in 2025 and is estimated at USD 127.3 billion for 2026.
The global industrial gases market is expected to grow at a CAGR of 4.4% from 2026 to 2033, reaching USD 172.6 billion by 2033.
Healthcare segment held the largest share (over 27.0%) in 2025, while manufacturing is the fastest-growing application.
Key factors that are driving the industrial gases market growth include rising end-user industry growth coupled with growing manufacturing industries in developing economies.
Europe dominated with a 41.7% revenue share in 2025.
The oxygen segment dominated the market and accounted for the largest revenue share of 38.5% in 2025.
The cylinder segment accounted for the largest revenue share of 36.5% in 2025.
Key players include Air Liquide; Linde plc; Air Products Inc.; Taiyo Nippon Sanso Corp.; Messer; SOL Group; Iwatani Corp.; Matheson Tri-Gas, Inc.; INOX-Air Products Inc.; Strandmøllen A/S.
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


