
- Home
- »
- Healthcare IT
- »
-
Internet Of Things In Healthcare Market Size Report, 2033GVR Report cover

Internet Of Things In Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Medical Devices, System & Software, Services), By Connectivity Technology (Cellular, Wi-Fi, Bluetooth, LPWANs), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$65.1BMarket Estimate, 2026
$78.9BMarket Forecast, 2033
$308.5BCAGR, 2026–2033
21.5%Internet Of Things In Healthcare Summary
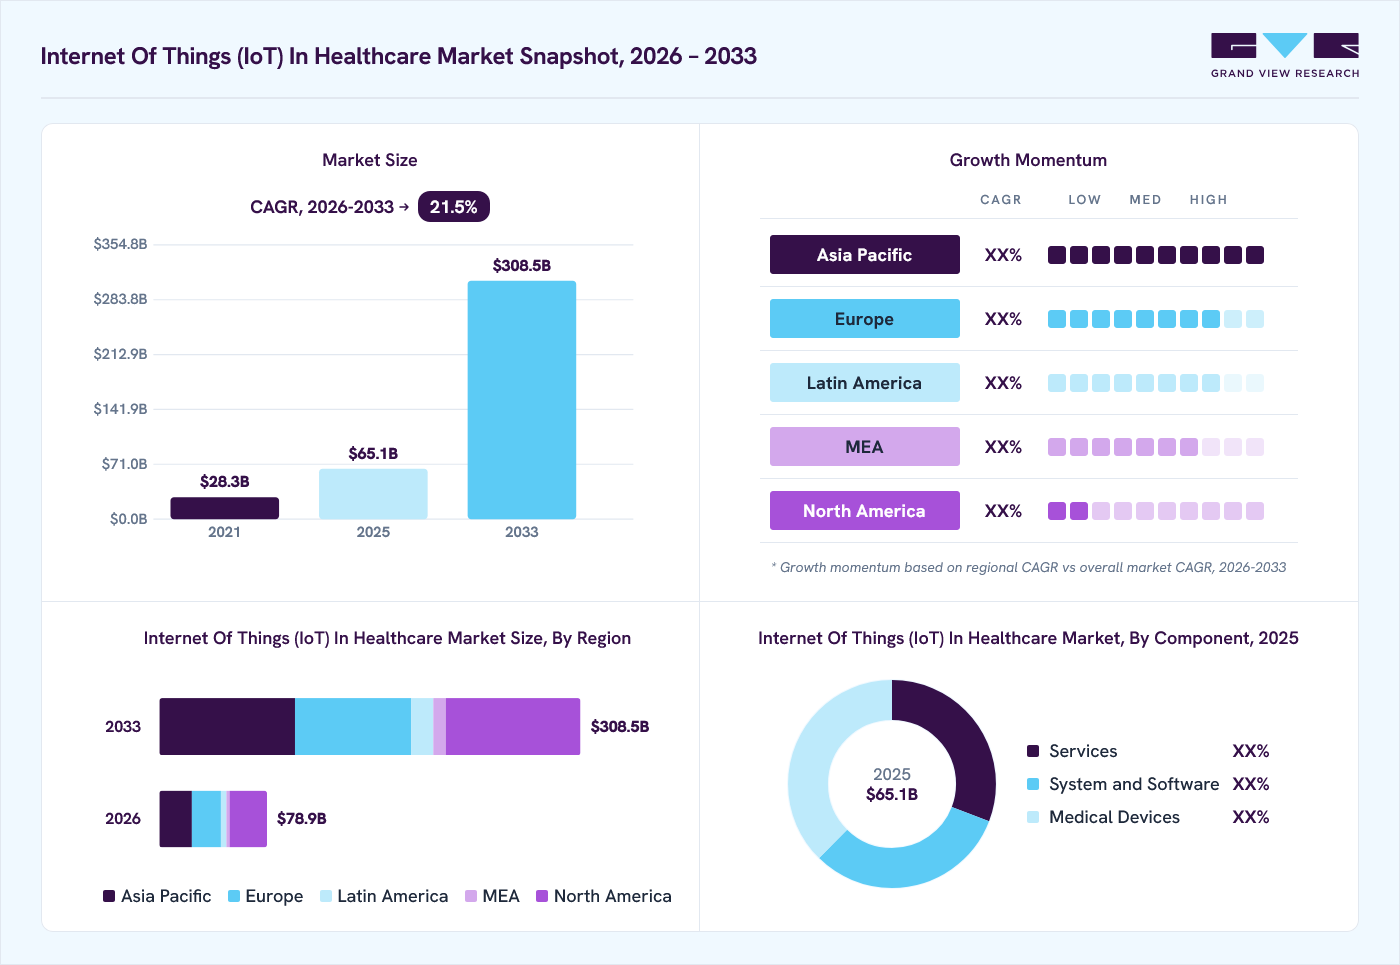
The global Internet of Things (IoT) in healthcare market size was valued at USD 65.1 billion in 2025 and is projected to grow from USD 78.9 billion in 2026 to USD 308.5 billion by 2033, growing at a CAGR of 21.5% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 34.7% in 2025. The market is driven by increasing usage of smartphones, smart devices, and wearables to monitor patients.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Medical devices segment held the largest revenue share of 37.7% in 2025.
- By connectivity technology: Cellular segment held the largest share in 2025.
- By application: Telemedicine segment held the largest share in 2025.
- By end-use: Hospitals and clinics segment held the largest share of 43.2% in 2025.
Regional Highlights
- Largest regional market: North America (34.7% revenue share, 2025)
- Fastest-growing regional market: Asia pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 65.1 Billion
- Estimated market size in 2026: USD 78.9 Billion
- Projected market size by 2033: USD 308.5 Billion
- CAGR (2026-2033): 21.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, increasing adoption of remote patient monitoring for improved out-of-hospital care boosts the market. Outbreak of COVID-19 positively impacted the IoT in healthcare market, accelerating the adoption of innovative technologies like the Internet of Things (IoT) in healthcare. With social distancing measures and concerns about in-person contact, the demand for remote patient monitoring solutions skyrocketed. IoT devices like wearable sensors, smart inhalers, and connected blood pressure monitors enabled healthcare providers to track patients' vital signs and health data remotely.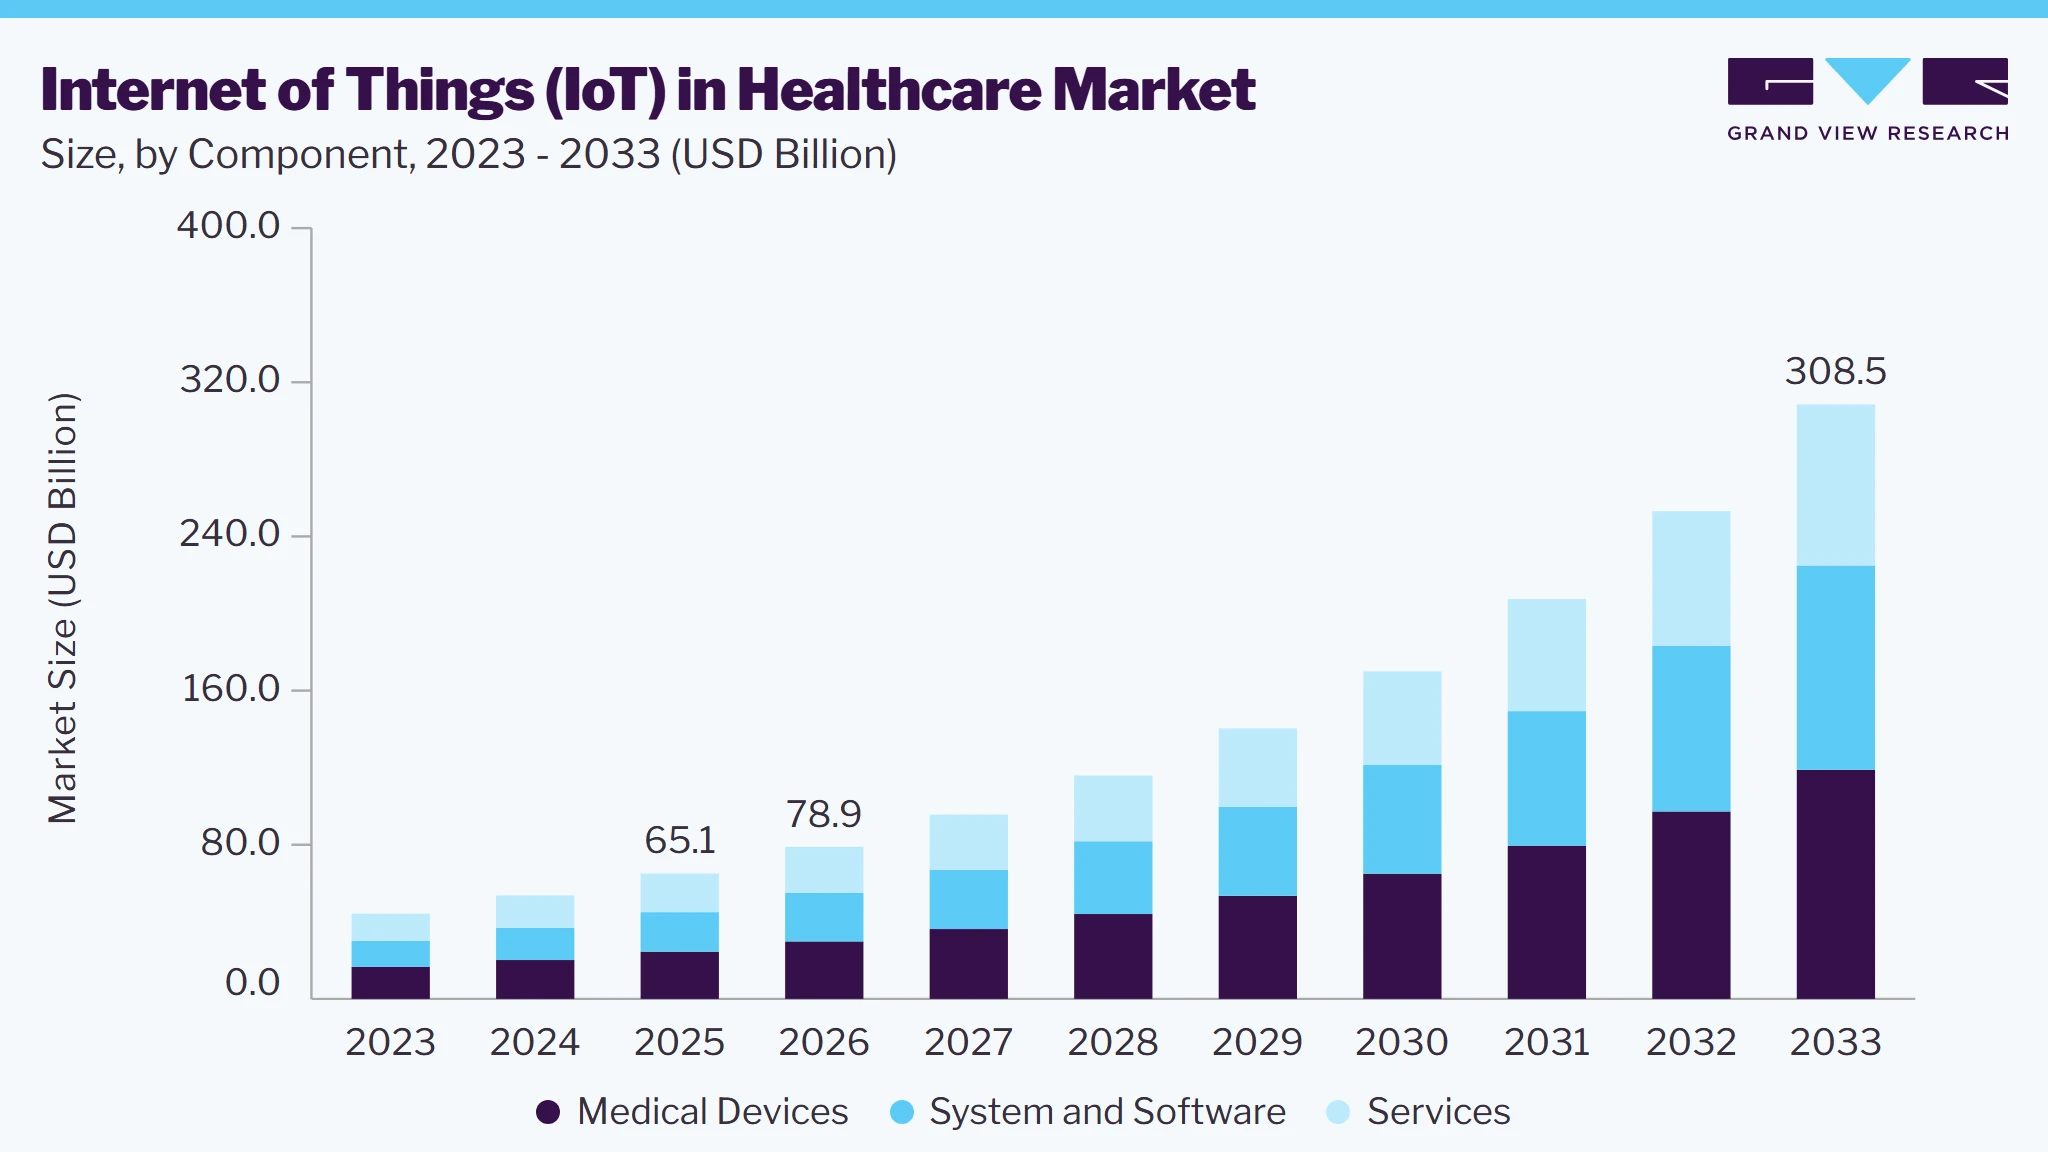 To learn more about this report, Download Free Sample Report
This helped in early detection of potential health complications, improved disease management, and reduced hospital readmissions. For instance, in February 2022 Government of India announced two projects to enhance digital health for the people to fight against the pandemic. The government has projected to launch an open platform including digital registries for doctors, and other healthcare providers, novel healthcare identities, and global access to digital healthcare facilities. Such advancements boost the global market. Moreover, after COVID-19 pandemic, there has been a surge in adoption of telemedicine in the healthcare sector, which fosters the global market.
Rising investments in implementing digital technologies in healthcare institutions and emergence of connected care are the key factors boosting industry growth. Technological advancements, a growing geriatric population, and rising prevalence of chronic conditions positively impact the market expansion. Furthermore, growing affordability and reduced costs of hardware are driving the demand for smartphones in the market, which is expected to drive the market's growth. In addition, measures are taken to improve security of the data. For instance, in December 2022, Palo Alto Networks introduced a Zero Trust Security solution for medical IoT, aiming to enhance the secure management of connected devices for healthcare providers. This cybersecurity approach ensures the protection of organizational data by systematically validating each user and device, offering a swift and secure means of handling the diverse landscape of medical devices.
Increasing applications of smart devices and wearables in healthcare, such as glucometer, tablets, smartphones, smartwatches and headphones, heartrate cuff, bands, and others, is expanding the scope of Internet of Things, especially in healthcare as they give special attention to access the patients remotely. Moreover, the tracker system in these devices enables access to emergency patients by sending emergency alerts to seek medical help. Technological advancements in smartphone technology for improving disease diagnosis are anticipated to drive the growth of Internet of Things in the healthcare market. Moreover, smartphones offer advantages such as ease of use, portability, large storage capacity, and making them an optimal solution for diagnostic and monitoring services.
 To learn more about this report, Download Free Sample Report
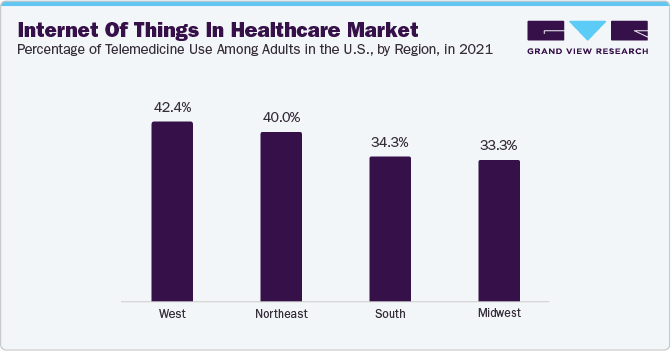
High penetration of smartphones is also one of the significant factors boosting the growth of internet of things in healthcare market. As per The Mobile Economy 2022, smartphone penetration was 67% of the global population in 2021 and is expected to reach 70% by 2025. An increase in number of mobile subscriptions is also contributing to an increase in the demand for IoT solutions. A rise in number of mobile subscriptions in emerging economies such as India, China, Indonesia, Bangladesh, and some African & Latin American countries is expected to further drive the market growth. In addition, continuous improvements in network infrastructure and growing network coverage are also creating opportunities for key players to grow in the market. Moreover, usage of mobile devices is rising among physicians.
Market Dynamics
The growing adoption of telehealth and virtual care services is increasing the demand for connected healthcare devices capable of enabling remote patient monitoring, real-time health data transmission, and continuous care management. Healthcare providers are increasingly leveraging IoT-enabled wearables, sensors, and monitoring systems to support virtual consultations, improve patient engagement, and enhance clinical decision-making outside traditional healthcare settings. This shift toward digital care delivery is driving the development of interconnected healthcare ecosystems and accelerating the adoption of IoT technologies across the healthcare sector. For instance, according to the American Medical Association (AMA), 71.4% of physicians reported using telehealth in their practices on a weekly basis in 2024, compared to 25.1% in 2018, demonstrating the rapid adoption of virtual care models and the increasing need for IoT-enabled solutions that facilitate remote healthcare delivery.
Deploying IoT-enabled healthcare solutions requires substantial investments in connected medical devices, sensors, communication networks, cloud infrastructure, cybersecurity systems, and advanced analytics platforms. In addition, healthcare organizations must invest in system integration, interoperability upgrades, workforce training, and ongoing maintenance to ensure efficient and secure operation of connected healthcare environments. The considerable capital and operational expenditures associated with these deployments can limit adoption, particularly among small and resource-constrained healthcare providers, thereby hindering market growth.
The increasing convergence of IoT, artificial intelligence (AI), and healthcare data platforms is creating significant opportunities for advanced clinical decision-making, predictive analytics, and workflow automation. As healthcare organizations generate growing volumes of data from connected devices, there is rising demand for platforms that can integrate, normalize, and transform this data into actionable insights. AI-enabled interoperability solutions are expected to enhance the value of IoT ecosystems by improving care coordination, operational efficiency, and real-time patient monitoring capabilities. For instance, in June 2026, Redox launched new AI capabilities designed to help healthcare organizations scale integration workflows and establish a robust data foundation for AI applications. The solution enables healthcare providers and technology teams to more efficiently connect, manage, and leverage clinical data, supporting the development of AI-driven healthcare solutions and improved interoperability across healthcare systems.
"Anyone can build a prototype now. What you can't replicate is 14 years of production experience with the ways healthcare data actually behaves at the last mile; the edge cases, the EHR-specific quirks, the configurations that only exist because someone hit that exact failure in the real world, that's the foundation our AI capabilities are built on, and it's why they hold up where others don't.”
-Sasi Mukkamala, Chief Technology Officer at Redox
Market Concentration & Characteristics
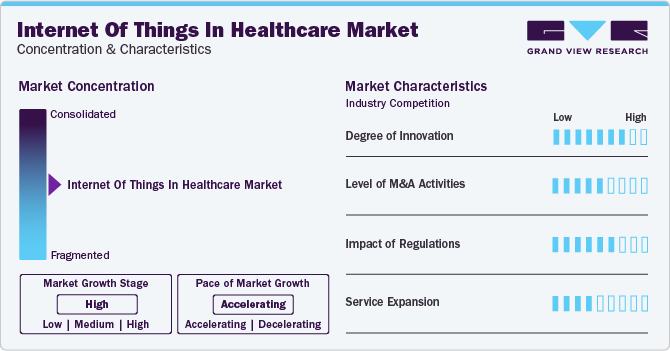
Technological proliferation and increasing investments are expected to drive the global market over the forecast period. Significant advances in telehealthcare and growing penetration of Internet and broadband services have further propelled growth of the Internet of Things (IoT) in healthcare market.
Several market players such as Medtronic, Cisco Systems, Inc., SAP SE, and Microsoft Corporation are involved in merger and acquisition activities. Through M&A activity, these companies can expand their geographic reach and enter new territories.
 To learn more about this report, Download Free Sample Report
Favorable government regulations are driving growth in the market. It is regulated by the FDA’s Center for Devices and Radiological Health (CDRH) in the U.S. In 2017, the U.S. FDA launched its Digital Health Innovation Action Plan, which provides timelines and details regarding implementation of the 21st Century Cures Act. The government in the U.S. is also focusing on issues associated with IoT in healthcare with new governance.
Analyst Perspective
The IoT in healthcare market is witnessing strong growth driven by the convergence of connected medical devices, remote patient monitoring, and real-time clinical data analytics across hospital and homecare settings. Growth is primarily supported by rising demand for continuous disease monitoring, aging population, and the shift toward value-based care models, which collectively push healthcare providers to adopt interoperable, sensor-enabled ecosystems. However, the market remains highly fragmented due to interoperability challenges, cybersecurity concerns, and uneven digital infrastructure across emerging economies, limiting large-scale integration. Over the forecast period, competitive intensity is expected to increase as incumbents, and digital health entrants focus on edge-enabled platforms, cloud integration, and AI-assisted decision support to improve clinical workflow efficiency and patient outcomes.
End-use Insights
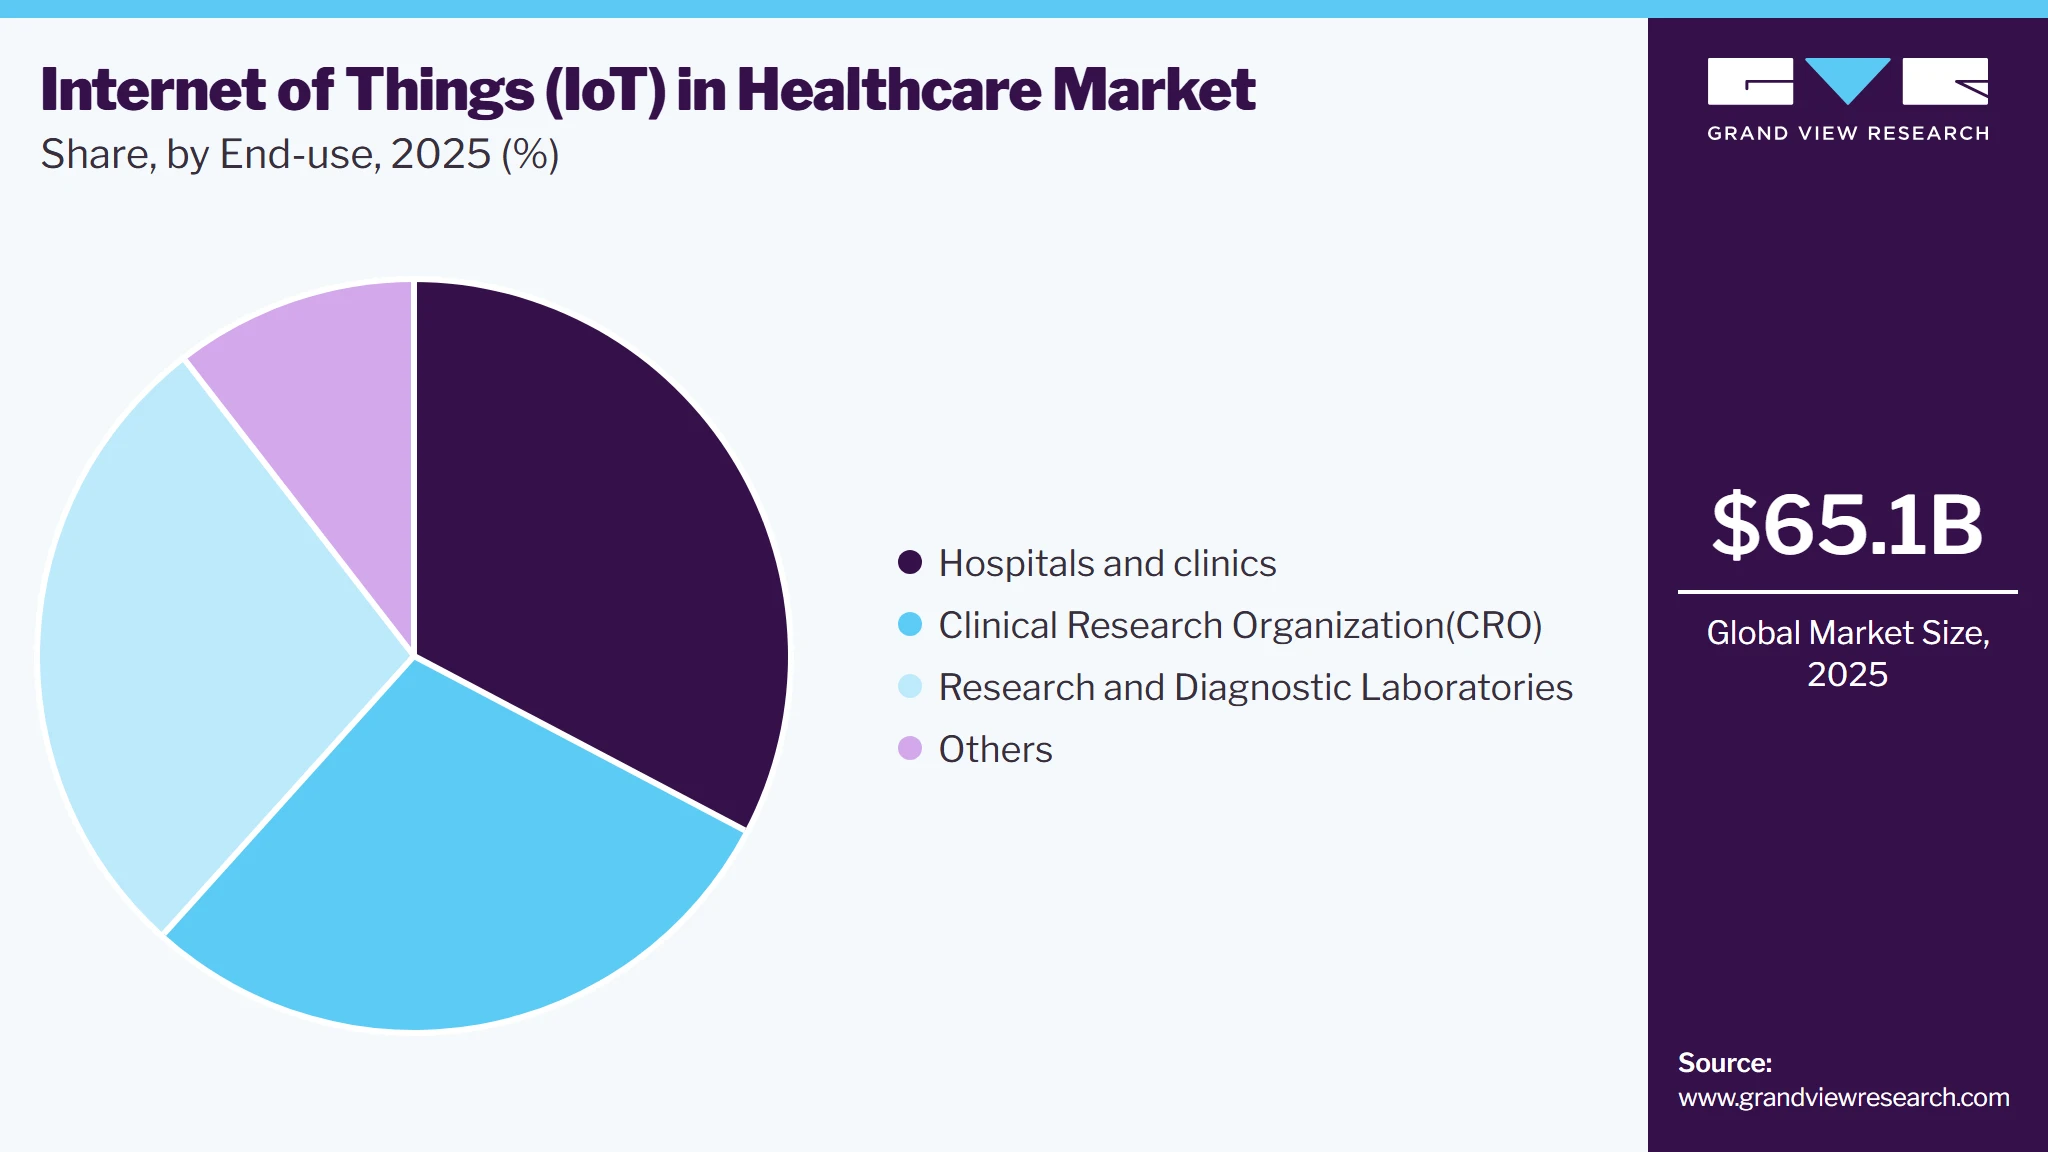
Based on end-use, the hospitals and clinics segment held the largest revenue share of 43.2% in 2025. Improved operational and functional efficiency gained by hospitals due to IoT is a key factor propelling growth of the market. For instance, these solutions help hospitals in management of real-time communication, medical records & billing, hospital workflows, and medication compliance improving overall operational efficiency. In addition, IoT solutions allow enhanced treatment outcomes, disease management, and patient experience leading to improved care delivery. Moreover, increasing investments by hospitals for accelerating the adoption of digital technology is another factor contributing to segment share.
 To learn more about this report, Download Free Sample Report
Clinical Research Organizations (CROs) segment is expected to grow with the fastest CAGR over the forecast period. Rising implementation of IoT solutions for enhancing accuracy of clinical research is a major factor fuelling the segment. CROs have augmented widespread use of these solutions for improving patient retention and recruitment process, which are potential issues in clinical research. Hence, these capabilities are estimated to drive the segment during the forecast period.
Component Insights
Based on components, the medical devices segment held the largest revenue share of 37.7% in 2025. This is attributed to large scale-adoption of medical devices owing to increasing need for efficient and cost-effective solutions for delivering healthcare services. For instance, medical devices are connected with IoT sensors to offer healthcare professionals a continuous stream of real-time health data such as glucose monitoring, heart rate, and blood pressure. In addition, the growing demand for self-monitoring devices such as wearable devices are expected to surge the demand for connected medical devices in healthcare sector. Several key players and universities are launching novel medical devices for self-monitoring of health indicators. For instance, in January 2022, Abbott introduced biowearables for self-monitoring of major nutritional health indicators. Such, initiatives are driving the medical devices segment.
System and software segment is expected to grow with the fastest CAGR over the forecast period. This growth is attributed to technological advancements and growing investments by operating players for the development of novel connected solutions for life science industry. For instance, in September 2021, McKesson launched a rapid return solution for health systems, which helps health systems and hospitals increase the amount of credit received for returned pharmaceuticals & OTC products, simplify the returns process, and expedite credit processing. Furthermore, increasing adoption of connected systems and digital technologies in the health centers may boost the segment during study period. The need for managing medical records is rising in developed economies such as the U.S., which is positively influencing the demand for software solutions.
Connectivity Technology Insights
By connectivity technology, cellular segment held the largest share in 2025. Cellular networks have wide range of applications. In healthcare, they are used for remote patient monitoring as it allows data from devices to be collected and made available to healthcare professionals in real-time. Therefore, it is regarded as a faster, safer, and conducive connectivity solution for remote monitoring. Cellular connectivity technology also improves usability, versatility, and portability for connected medical devices.
LPWANs (Low Power Wide Area Networks) segment is expected to witness rapid growth over the forecast period. This is attributed to unique characteristics of LPWANs, including low power consumption and the ability to establish long-range communication. These features make it well-suited for wireless monitoring and emerging healthcare applications. In telemedicine, where consistent data transmission is crucial, LPWANs prove advantageous, especially during adverse weather conditions that may result in increased error rates. The adaptation of modulation schemes by CR-LPWAN (Cognitive Radio LPWAN) to the appropriate frequency bands further enhances performance, making it particularly resilient during challenging weather conditions.
Application Insights
By application, telemedicine segment held the largest share in 2025, and is expected to grow with the fastest CAGR over the forecast period. Increasing prevalence of chronic diseases and rising demand for patient monitoring are the major factors contributing to segment’s growth. Recent advancements in telemedicine technology coupled with launch of telemedicine services are fueling the demand for IoT solutions. For instance, in May 2021, Lytus Technologies, a platform services company launched its telemedicine services along with a network of local health centers in India offering additional services beyond virtual care. Moreover, key players in internet of things in healthcare are focused on development of innovative telemedicine solutions or devices for improving the healthcare system. For instance, CareClix offers a broad range of telehealth and telemedicine services through high-definition video examinations and remote consultations.
Connected imaging is expected to grow at the significant CAGR over the forecast period. The market is driven by consolidation across industry, strategic initiatives by key market players, and a rising need to reduce the cost of care. The market holds many growth opportunities owing to increasing consumer demand & patient acceptance, enhanced quality of care, and growing adoption of telemedicine. For instance, in May 2021, Walmart Inc. acquired MeMD-a- a telehealth provider- to provide virtual access to urgent, behavioral, and primary care services throughout the U.S.
Regional Insights
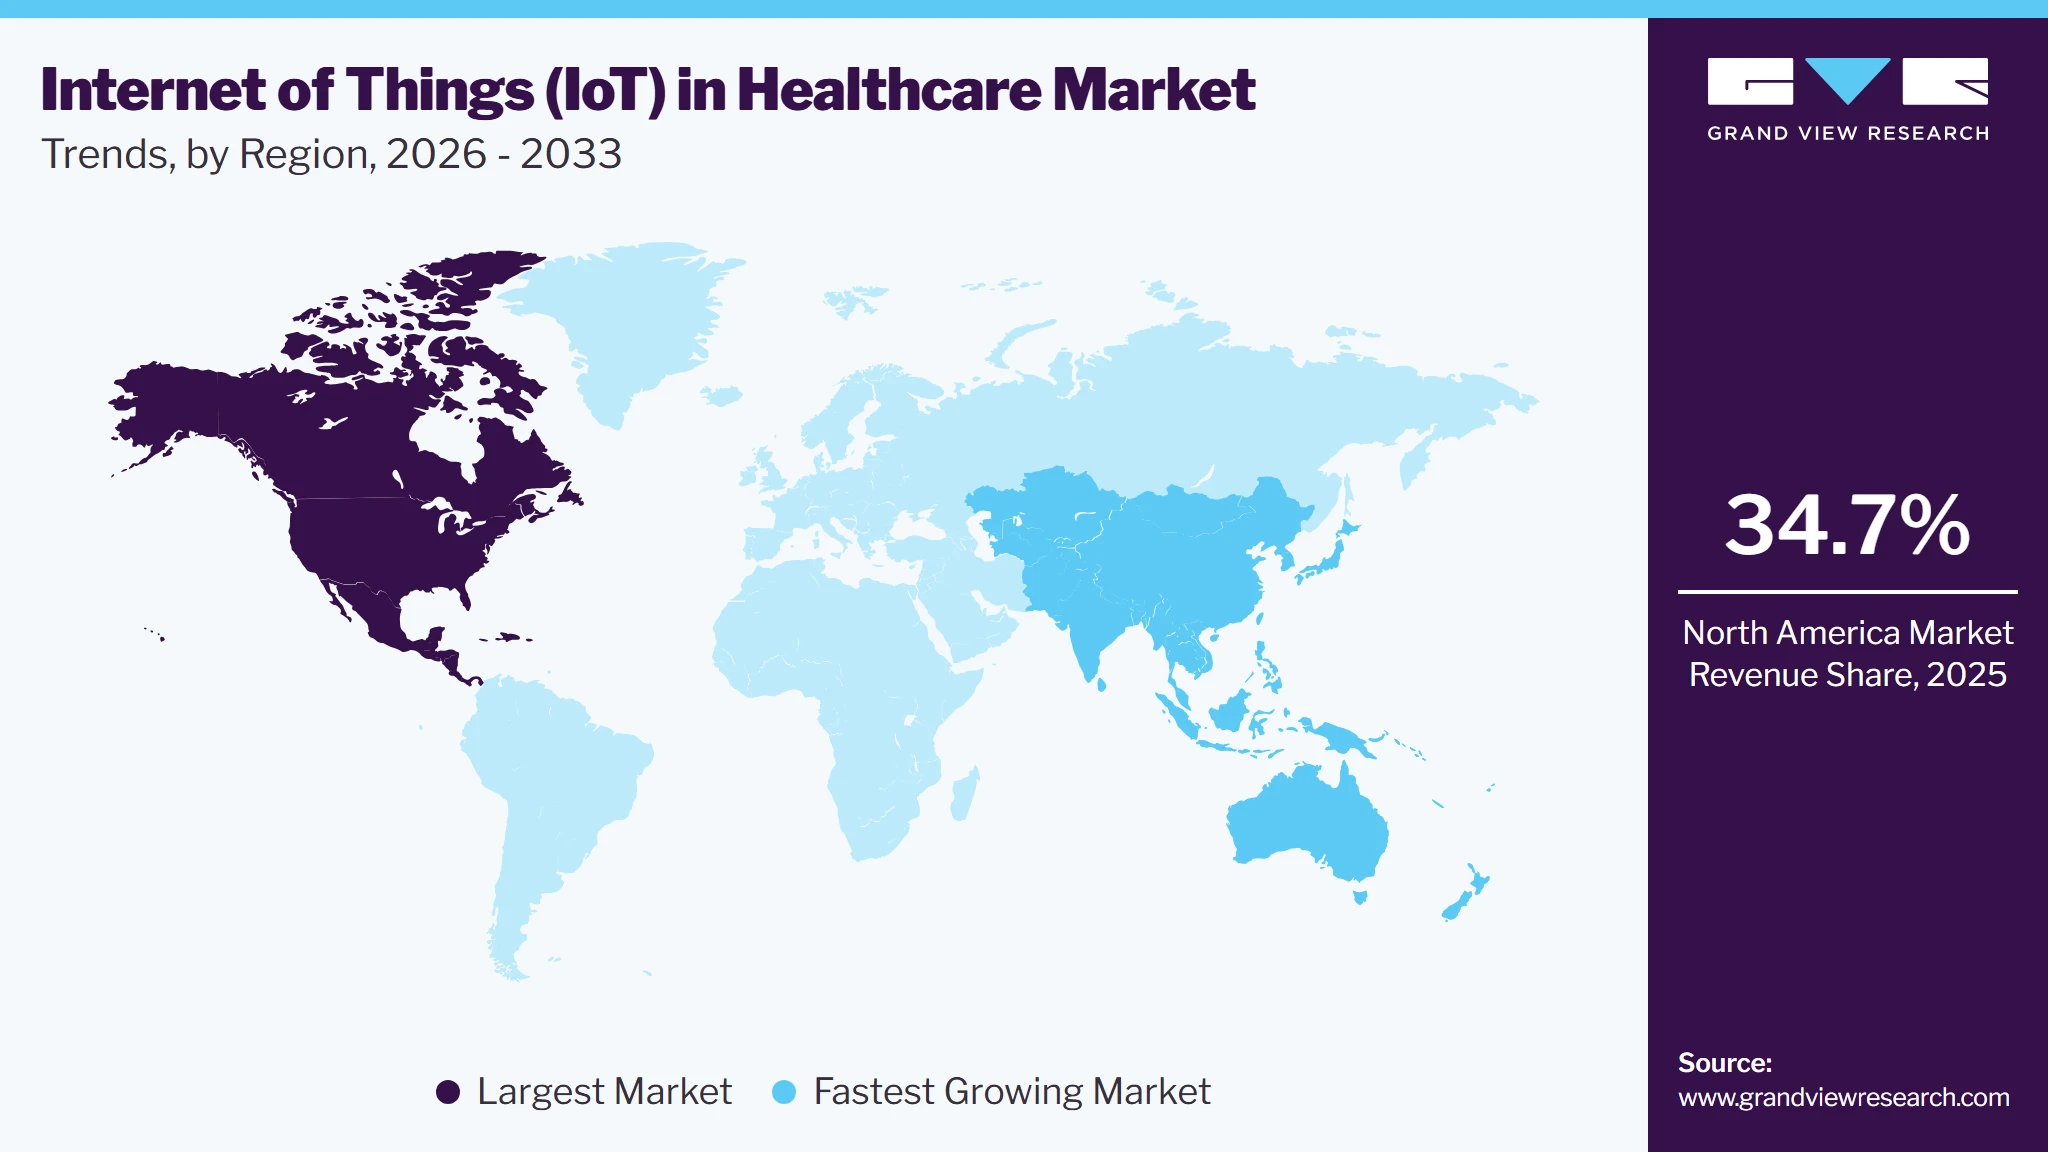
North America dominated the Internet of Things (IoT) in healthcare market with the largest revenue share of 34.7% in 2025. Increased usage of telehealth, e-prescribing, mHealth, and other HC IT technologies as a response to COVID-19, as well as increased government requirements & support for IoT solutions in healthcare, are primary growth factors driving the market. Furthermore, rise in number of hospitals, advanced research organizations, universities, and medical device manufacturers has a positive impact on market growth. Increase in adoption of electronic health records is increasing significantly in the U.S. As per the Health IT reports until 2021, nearly 9 out of 10 U.S.-based physicians have adopted EHR. Thus, high adoption rate also plays a crucial role in boosting market growth.
 To learn more about this report, Download Free Sample Report
U.S. Internet of Things (IoT) in Healthcare Market Trends
The IoT in healthcare market in the U.S. held the largest share in the North America region in 2025. Growth in the country can be attributed to increasing development & deployment of innovative & advanced healthcare management software and presence of a large number of players operating across segments, such as mobile & network operations. Moreover, rising young population, increasing awareness about health-related issues, and surging disposable income contribute to market growth in the U.S. In addition, key players in the country are increasingly focusing on developing advanced healthcare products, including innovative & secure data storing & sharing platforms for EHR, building network infrastructure, and promoting adoption of various remote health & telemedicine services in the U.S.
Asia Pacific Internet of Things (IoT) in Healthcare Market Trends
Asia Pacific region is anticipated to witness fastest growth over the forecast period, owing to the improvement in healthcare infrastructure & increase in healthcare expenditure in developing Asian countries, owing to growth in adoption of advanced technology to cut down medical costs & streamline hospital workflow, are key drivers of demand for IoT in healthcare in the region. Moreover, several government initiatives and supportive programs are also boosting the adoption of such technologies. For instance, in Australia, the state and federal government support healthcare IT at their level. State-level programs, such as HealthSmart, and nationwide programs, such as HealthConnect, are examples of government programs undertaken to increase integration of IoT solutions in healthcare.
Digital ecosystem in Japan is likely to improve communication between patients and doctors. However, digital ecosystem in the country is currently unevenly developed. The government has approved only one or two mobile applications due to safety & accuracy concerns. More research on mobile apps is required to improve approval rates. In addition, Symax and Clintal are among the key digital health startups in the country. Moreover, due to increasing government spending on healthcare, high demand for eHealth services in healthcare sector is fueling Japan’s digital health market. This is expected to drive demand in the market during forecast period.
Internet Of Things In Healthcare Market Share Insights
-
Medtronic, Cisco Systems Inc., IBM Corporation, and GE Healthcare are some of the dominant players operating in internet of things (IoT) market.
-
Medtronic has a global presence and operates from over 370 locations in approximately 160 countries.
-
IBM Corporation operates in over 170 countries. IBM serves its consumers from varied industries, such as automotive, banking, life sciences, retail, chemical & petroleum, and communication.
-
Infosys Limited, Cerner Corporation, Wipro ltd, and QUALCOMM Incorporated some of the emerging market players functioning in internet of things (IoT) market.
-
QUALCOMM Incorporated has 170 sales offices in more than 30 countries across the globe.
-
Wipro ltd caters to new age markets, network & edge providers, and utilities, as well as incumbents of the public sector.
Key Internet Of Things In Healthcare Companies
The following key companies have been profiled for this study on the Internet of Things (IoT) healthcare market.
-
Medtronic
-
Cisco Systems, Inc.
-
IBM Corporation
-
GE Healthcare
-
Microsoft Corporation
-
SAP SE
-
Infosys Limited
-
Cerner Corporation
-
QUALCOMM Incorporated
-
Amazon
-
Intel corporation
-
Wipro ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Koninklijke Philips N.V., GE HealthCare, Siemens Healthineers AG
etc.)
- Focus on end-to-end IoT healthcare ecosystems integrating devices, cloud platforms, AI analytics, and hospital IT infrastructure. Strong emphasis on partnerships with healthcare providers and expansion of digital health platforms.
- Strong global installed base, deep integration across hospital workflows, advanced R&D capabilities, and leadership in cloud, AI, and connected medical devices.
- High cost structures, complex implementation cycles, and slower innovation adaptation due to large-scale legacy systems.
Emerging Players (Robert Bosch GmbH, Infosys Limited
. etc.)
- Focus on cloud-first healthcare IoT platforms, smart hospital solutions, infrastructure enablement, and system integration services. Strong push toward partnerships and scalable digital health ecosystems.
- Strong cloud and AI infrastructure, advanced sensing and automation capabilities, and cost-effective IT services and integration expertise
- Limited direct presence in core medical device manufacturing and lower control over clinical workflows compared to established OEMs and healthcare-focused device companies.
Recent Development
-
In September 2023, Infosys announced the expansion of its strategic collaboration with NVIDIA Corporation. This collaboration aimed to generate technology and expertise needed to drive productivity with generative AI applications and solutions across various industries, including healthcare.
-
In May 2023, SAP SE collaborated with Accenture. The aim behind the collaboration was to work collaboratively on several AI-based projects and extend product portfolios.
-
In February 2023, Wipro ltd partnered with Koninklijke Philips N.V. to offer Electronic Medical Record (EMR) enterprise solutions for the healthcare industry in Saudi Arabia. The integrated solution, which is in line with Saudi Arabia's Health Sector Transformation Programme- Vision 2030, will put a special emphasis on localized practice, adjustable workflows, data, and service linkages.
-
In June 2022, GE Healthcare launched Allia platform, which was designed for minimally invasive image-guided surgery. The platform was designed through a multiyear collaboration with surgeons and interventionists. Allia was designed with the purpose of improving workflow efficiency, enhancing user experience, and increasing the adoption of image guidance in daily practice.
Internet Of Things In Healthcare Market Report Scope
Report Attribute
Details
Market size in 2025
USD 65.1 billion
Market size value in 2026
USD 78.9 billion
Revenue forecast in 2033
USD 308.5 billion
Growth rate
CAGR of 21.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, connectivity technology, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, Japan, China, India, Australia, Thailand, South Korea, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Medtronic, Koninklijke Philips N.V., Amazon.com, Inc., Oracle, IBM, GE HealthCare, Microsoft Corporation, SAP SE, Infosys Limited, Intel Corporation, Wipro, Siemens Healthineers AG, Honeywell, Robert Bosch GmbH, Cisco Systems, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Internet of Things in Healthcare Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global Internet of Things in healthcare market report on the basis of component, connectivity technology, application, end-use, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Medical Devices
-
Wearable External Devices
-
Implanted Medical Devices
-
Stationary Medical Devices
-
-
System and Software
-
Remote Device Management
-
Network Bandwidth Management
-
Data Analytics
-
Application Security
-
Network Security
-
-
Services
-
System Integration Services
-
Consulting, Training, and Education
-
Support and Maintenance Services
-
-
-
Connectivity Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Cellular
-
Wi-Fi
-
Bluetooth
-
LPWANs
-
Zigbee
-
RFID
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Telemedicine
-
Patient Monitoring
-
Connected Imaging
-
Clinical Operations
-
Medical Management
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals and Clinics
-
Clinical Research Organizations
-
Research and Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The Internet of Things in healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Internet of Things in healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Component
Revenue Capture Definition
Medical Devices
Revenue generated from connected medical devices that collect, transmit, and monitor patient health data through IoT-enabled technologies.
a) Wearable external device: Spending on wearable sensors, smart watches, patches, glucose monitors, and other externally worn devices used for continuous health monitoring and data collection.
b) Implanted Medical Devices: Revenue derived from connected implantable devices such as pacemakers, defibrillators, neurostimulators, and cardiac monitors that facilitate remote monitoring and clinical management.
c) Stationary Medical Devices: Expenditure associated with network-connected hospital-based equipment including patient monitors, imaging systems, infusion pumps, and critical care devices.
Software and systems
Revenue attributable to software platforms and digital infrastructure that enable device connectivity, data management, analytics, and cybersecurity across healthcare IoT ecosystems.
a) Remote device management: Spending on solutions used to monitor, configure, update, and manage connected medical devices remotely throughout their lifecycle.
b) Network Bandwidth Management: Revenue generated from technologies designed to optimize network performance and ensure reliable transmission of healthcare data across connected environments.
c) Data analytics: Expenditure on platforms that process, analyze, and generate actionable insights from data collected through connected healthcare devices and systems.
d) Application security: Revenue associated with software solutions that protect healthcare applications, patient information, and connected platforms from cyber threats and unauthorized access.
e) Network Security: Spending on technologies that secure healthcare communication networks, connected endpoints, and data transmission channels from cybersecurity risks.
Services
Revenue generated from professional and managed services supporting the deployment, integration, optimization, and maintenance of healthcare IoT solutions.
a) System Integration: Expenditure on integrating connected devices, healthcare IT systems, cloud platforms, and enterprise applications to enable seamless interoperability.
b) Consulting, Training and education: Revenue derived from advisory, implementation planning, workforce training, and educational services supporting IoT adoption in healthcare settings.
c) Support and maintenance : Spending on technical support, software updates, device monitoring, troubleshooting, and ongoing operational management services.
Segment- Technology
Revenue Capture Definition
Wi-Fi
Revenue generated from Wi-Fi-based connectivity solutions enabling wireless communication between healthcare devices, systems, and care settings.
Bluetooth Low Energy
Spending on low-power wireless technologies supporting wearable devices, patient monitoring solutions, and short-range healthcare data transmission.
ZigBee
Revenue attributable to ZigBee-enabled healthcare networks used for secure, low-power communication among connected devices and sensors.
RFID
Expenditure associated with RFID technologies used for asset tracking, inventory management, patient identification, and workflow optimization.
Cellular
Revenue generated from cellular-enabled healthcare devices and platforms that facilitate remote monitoring and data exchange across geographically dispersed locations.
Segment- End Use
Revenue Capture Definition
Clinical Research Organization(CRO)
Revenue derived from IoT solutions utilized to support decentralized trials, remote patient monitoring, data collection, and clinical research activities.
Hospitals and clinics
Spending on connected healthcare infrastructure, patient monitoring systems, smart medical devices, and digital care delivery solutions deployed within healthcare facilities.
Research and Diagnostic Laboratories
Revenue generated from IoT-enabled laboratory equipment, diagnostics platforms, asset management systems, and connected testing environments.
Others
Expenditure is attributable to healthcare payers, home healthcare providers, long-term care facilities, academic institutions, and government healthcare organizations.
Segment- End Use
Revenue Capture Definition
Telemedicine
Revenue generated from IoT-enabled solutions that facilitate remote consultations, virtual care delivery, and real-time patient data exchange.
Medication Management
Spending on connected systems and devices used for medication adherence monitoring, automated dispensing, and therapy management.
Clinical Operations
Revenue attributable to IoT technologies supporting workflow optimization, asset tracking, staff coordination, and operational efficiency across healthcare facilities.
Patient Monitoring
Expenditure on connected devices and platforms that enable continuous monitoring of patient health parameters in clinical and home settings.
Connected Imaging
Revenue generated from network-enabled imaging systems that support image acquisition, data sharing, remote access, and diagnostic workflow integration.
Others
Spending associated with emerging IoT healthcare applications including rehabilitation, elderly care, population health management, and preventive healthcare initiatives.
Estimation Model
Top-Down
Segmentation
Validation
Forecasting
Commodity Flow Analysis
Country-Level Segment Share Modeling
Data Triangulation & Validation Model
Forecasting & CAGR Modeling
The IoT in Healthcare Market was estimated using a top-down approach by analyzing the revenues, product portfolios, and adoption trends of the leading market participants. The top 15 companies offering connected medical devices, remote patient monitoring solutions, wearable healthcare technologies, smart hospital systems, and healthcare IoT platforms were assessed to determine the overall market size, with regional revenue contributions and technology adoption trends incorporated into the analysis.
The market was segmented by component, application, end use, and geography. Revenue allocation was conducted across hardware, software, and services offerings, as well as key applications including remote patient monitoring, telemedicine, medication management, clinical operations, and connected medical devices.
Market estimates and segment shares were validated through primary discussions with healthcare providers, medical device manufacturers, IoT platform providers, technology vendors, and industry experts. Secondary findings were cross-verified using company disclosures, regulatory publications, healthcare databases, and industry reports.
Market forecasts were developed by evaluating trends in connected healthcare infrastructure, remote patient monitoring adoption, wearable medical devices, digital health transformation, cloud-based healthcare platforms, and advancements in wireless communication technologies. The analysis also incorporated healthcare expenditure trends, regulatory developments, and investments in smart healthcare ecosystems.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation of IoT healthcare market by main segment and application
Development of cross-matrix linking Services, Systems & Software, and Medical Devices with key applications such as remote patient monitoring, chronic disease management, ICU monitoring, and emergency care workflows
Enables granular identification of high-growth segment–application intersections and supports targeted product positioning and investment prioritization
Interoperability and ecosystem integration mapping
Mapping of data exchange compatibility across IoT devices, EHR systems, hospital IT platforms, and third-party analytics tools using HL7/FHIR alignment levels
Helps identify integration-ready solutions and ecosystem lock-in risks influencing procurement decisions
Country-level IoT healthcare policy and government support mapping
Assessment of country-wise government initiatives, digital health missions, IoT-enabled healthcare programs, funding schemes, and regulatory enablers across key regions (e.g., digital health infrastructure programs, smart hospital initiatives, national telehealth policies)
Enables prioritization of favorable regulatory markets, identification of government-backed demand pockets, and alignment of expansion strategy with policy-driven growth ecosystems
Frequently Asked Questions About This Report
The global internet of things in healthcare market size was valued at USD 65.1 billion in 2025 and is estimated at USD 78.9 billion in 2026.
The global internet of things in healthcare market is expected to grow at a CAGR of 21.5% from 2026 to 2033, reaching USD 308.5 billion by 2033
Key factors that are driving the market growth include rising adoption of wearable technology, investments for implementing digital technologies in healthcare institutions, and emergence of connected care. Along with this, rising investments for implementing digital technologies in healthcare institutions, and the emergence of connected care are the key factors boosting industry growth.
Based on components, the medical devices segment held the largest revenue share of 37.7% in 2025.
North America dominated the Internet of Things (IoT) in healthcare market with the largest revenue share of 34.7% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
By connectivity, cellular segment held the largest share in 2025.
Telemedicine segment held the largest share in 2025
Some key players operating in the IoT in Healthcare market include Medtronic, Koninklijke Philips N.V., Amazon.com, Inc., Oracle, IBM, GE HealthCare, Microsoft Corporation, SAP SE, Infosys Limited, Intel Corporation, Wipro, Siemens Healthineers AG, Honeywell, Robert Bosch GmbH, Cisco Systems, Inc.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


