
- Home
- »
- Next Generation Technologies
- »
-
IoT Node And Gateway Market Size, Share Report, 2033GVR Report cover

IoT Node And Gateway Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By Connectivity (ZigBee, Wi-Fi, Bluetooth, Z-Wave), By End-use (Consumer Electronics, Wearable Devices, Automotive & Transportation), By Region, And Segment Forecasts
Market Size, 2025
$612.6BMarket Estimate, 2026
$690.9BMarket Forecast, 2033
$1,487.3BCAGR, 2026–2033
11.6%IoT Node And Gateway Market Summary
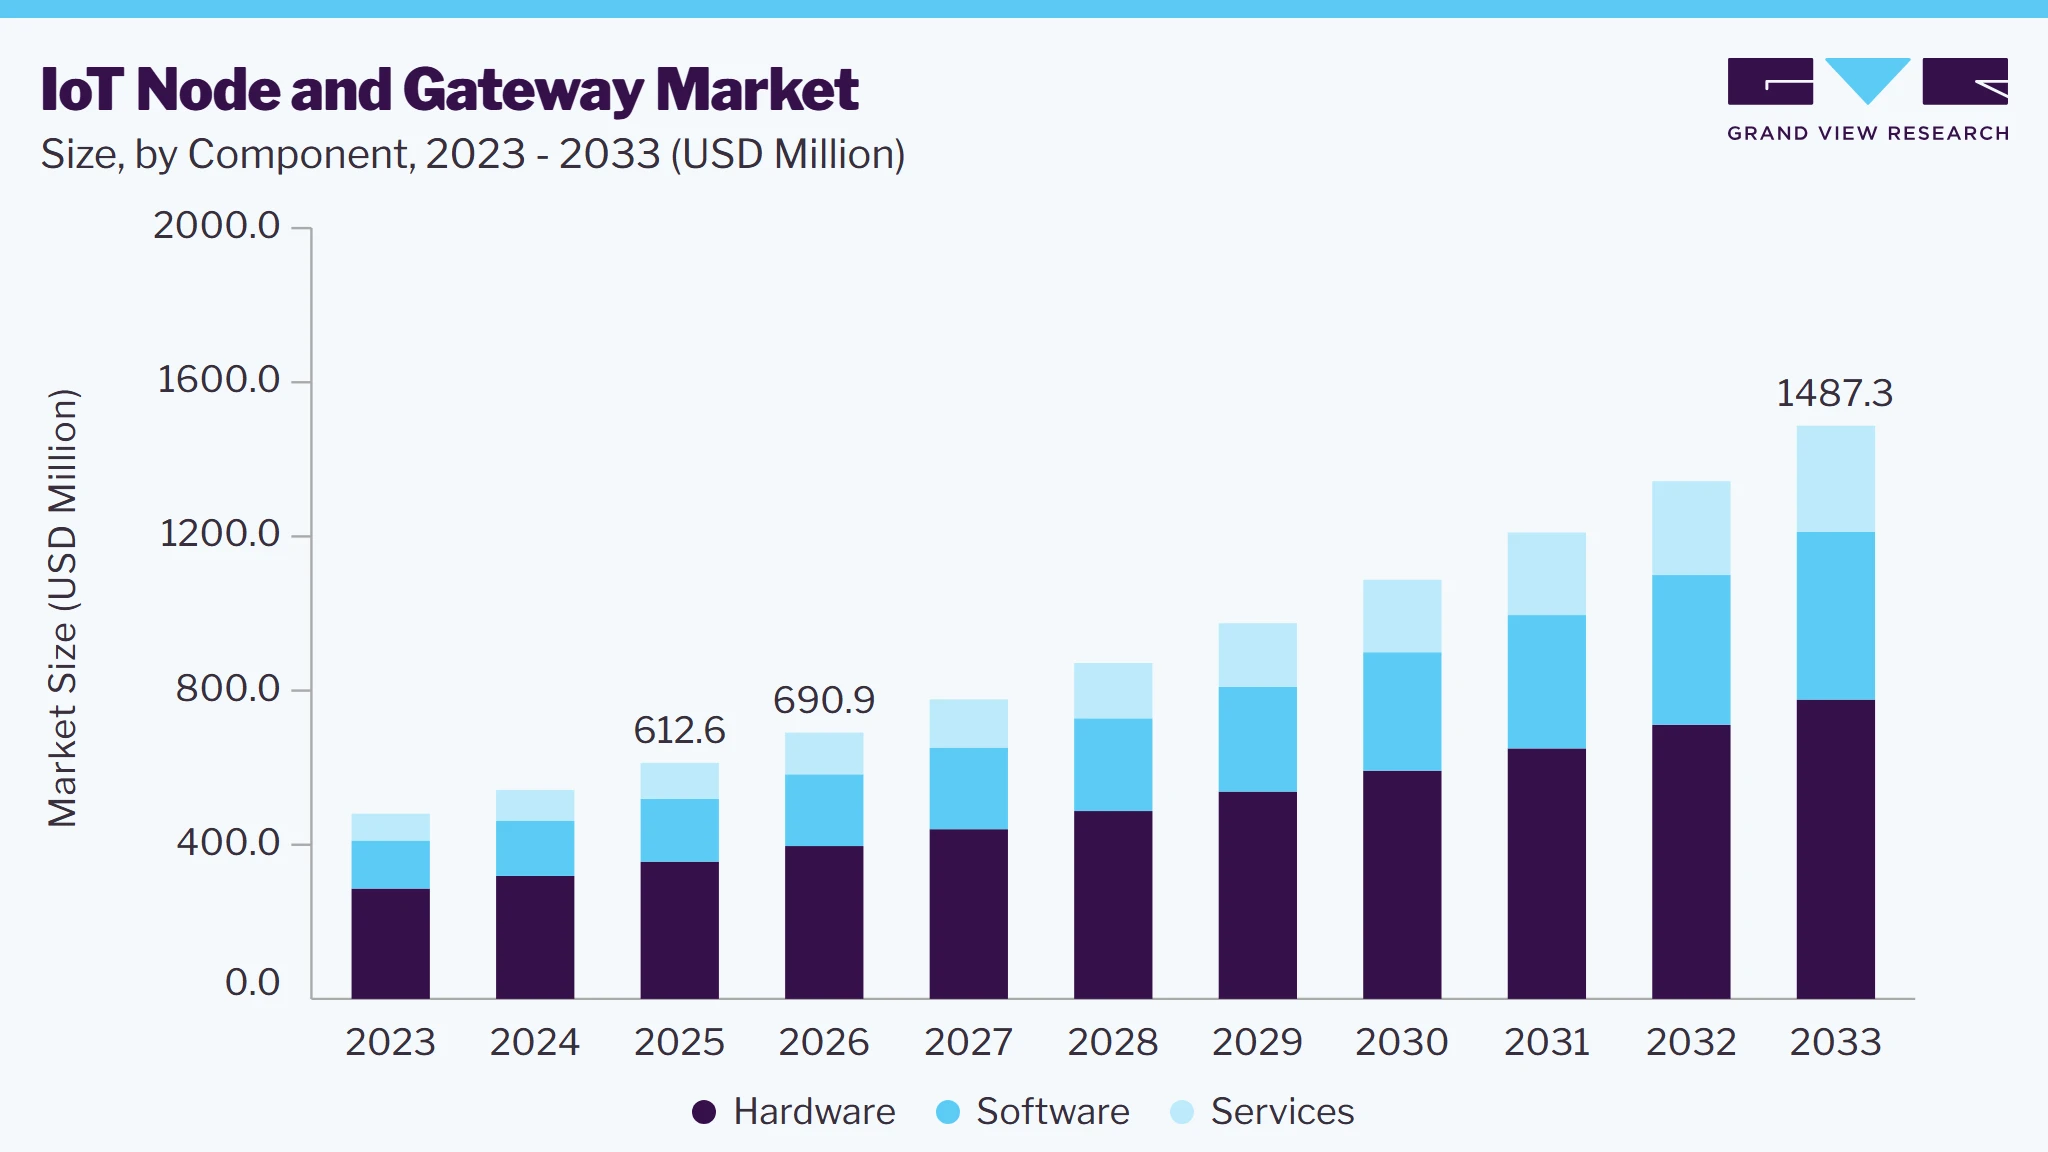
The global IoT node and gateway market size was valued at USD 612.6 billion in 2025 and is projected to grow from USD 690.9 billion in 2026 to USD 1,487.3 billion by 2033, at a CAGR of 11.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.9% in 2025. The IoT node and gateway market is primarily driven by the rapid adoption of Industrial IoT (IIoT) and smart connected devices, increasing deployment of edge computing for real-time data processing, and the expansion of smart city and Industry 4.0 initiatives.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The hardware segment accounted for the largest market share of 58.1% in 2025.
- By connectivity: The Wi-Fi segment dominated the market, with a share of 36.6% in 2025.
- By end use: The consumer electronics segment dominated the market with a share of 19.1% in 2025.
Regional Highlights
- Largest regional market: North America (36.9% revenue share in 2025)
- Fastest growing regional market: Middle East & Africa (highest CAGR 15.8%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 612.6 Billion
- Estimated market size in 2026: USD 690.9 Billion
- Projected market size by 2033: USD 1,487.3 Billion
- CAGR (2026-2033): 11.6%
Prism AI by Grand View Research Free to tryAsk a question about the IoT node and gateway marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Additionally, rising demand for low-latency data processing, improved network connectivity (such as 5G), and enhanced cybersecurity requirements in connected ecosystems are further accelerating the market growth. The need for efficient data collection, real-time monitoring, and seamless connectivity is driving the adoption of these technologies. Additionally, advancements in wireless communication technologies like 5G and AI are bolstering the capabilities of the market, enabling faster and more reliable data transfer. In June 2023, IBM Corporation announced the acquisition of Agyla SAS. The acquisition will extend IBM’s portfolio of hybrid multi-cloud services and further advance the company’s hybrid cloud and AI strategy in the region.
 To learn more about this report, Download Free Sample Report
Moreover, the market landscape is evolving with the emergence of Low-Power Wide-Area Network (LPWAN) technologies like LoRa and Sigfox, which offer extended connectivity range and lower power consumption. Across sectors from agriculture to logistics, internet of things (IoT) nodes and gateways are revolutionizing operations. Nodes with sensors gather real-time data, while gateways ensure this data reaches its destination securely and efficiently. As industries strive for efficiency and automation, the demand for these technologies is expected to rise. Recent developments include the integration of AI and machine learning into IoT nodes, allowing for more intelligent data processing at the edge. This reduces latency and enhances the decision-making capabilities of the devices.
Industries are harnessing node and gateway technology to enhance operations. Agriculture benefits from soil moisture data, manufacturing optimizes production lines, and smart cities improve infrastructure management; with 5G connectivity gaining traction, node & gateway are becoming even more instrumental in supporting high-speed, low-latency data transfer. Rapid expansion characterizes the market driven by the widespread adoption of IoT solutions. It encompasses sensors and actuators and captures real-world data, while gateways enable efficient data transfer to the central system.
Various advancements are being made in the market as the industry reshapes the landscape of connected devices and data communication. Advancements in microelectronics have led to smaller, more power-efficient IoT nodes. This enables seamless integration into various devices and environments while extended battery life reduces maintenance needs. IoT nodes now possess enhanced processing capabilities, enabling data preprocessing at the edge. This reduces latency and conserves bandwidth as only relevant information is sent to the cloud for further analysis. Integrating 5G technology offers higher data speeds and reduced latency, significantly benefiting IoT node and gateway. It enables real-time communication, which is crucial for applications like autonomous vehicles and remote healthcare. The market is advantageous due to the increasing integration of IoT in various sectors.
Market Dynamics
The IoT node and gateway market is experiencing robust growth, driven by the need for seamless edge-to-cloud connectivity and the rising deployment of intelligent edge infrastructure across industrial and commercial environments. Organizations are increasingly adopting IoT gateways and nodes to enable efficient data aggregation, local processing, and real-time decision-making in distributed systems, particularly in applications such as smart manufacturing, energy management, logistics, and connected infrastructure. This growing emphasis on interoperability, scalability, and reduced latency in data transmission is further strengthening the adoption of advanced IoT gateway solutions across global markets.
The IoT node and gateway market is primarily driven by the rapid adoption of Industrial IoT (IIoT) solutions across manufacturing, energy, transportation, and smart infrastructure sectors. Organizations are increasingly deploying connected devices to enable real-time monitoring, predictive maintenance, and automated decision-making across distributed operations. IoT nodes and gateways are critical enablers, facilitating seamless data collection from sensors and enabling efficient communication between edge devices and centralized platforms.
In addition, the growing shift toward smart factories and Industry 4.0 initiatives is accelerating demand for scalable and interoperable IoT architectures. Enterprises are integrating IoT gateways to manage heterogeneous devices, reduce data transmission latency, and support edge computing capabilities, thereby improving operational efficiency and system responsiveness.
One of the major restraints in the IoT node and gateway market is the increasing vulnerability to cybersecurity threats and data breaches. With the growing number of connected devices, the attack surface is expanding significantly, making IoT ecosystems more susceptible to unauthorized access, malware attacks, and data interception. IoT gateways, being central communication hubs, often become high-value targets for cybercriminals.
Furthermore, concerns about data privacy and compliance with stringent regulatory frameworks such as the GDPR, as well as industry-specific security standards, are limiting the seamless adoption. Organizations often face challenges in implementing robust end-to-end security across diverse IoT environments, increasing deployment complexity and slowing large-scale adoption.
The growing adoption of edge computing presents a significant opportunity for the IoT node and gateway market. Enterprises are increasingly shifting data processing closer to the source to reduce latency, optimize bandwidth usage, and enable real-time analytics. IoT gateways play a crucial role in this architecture by enabling local data processing, filtering, and intelligent decision-making at the edge.
Additionally, large-scale investments in smart cities, smart grids, autonomous systems, and connected healthcare infrastructure are creating new avenues for IoT node and gateway deployment. These applications require highly reliable, low-latency communication networks, positioning IoT gateways as essential components in next-generation digital infrastructure ecosystems.
Market Concentration & Characteristics
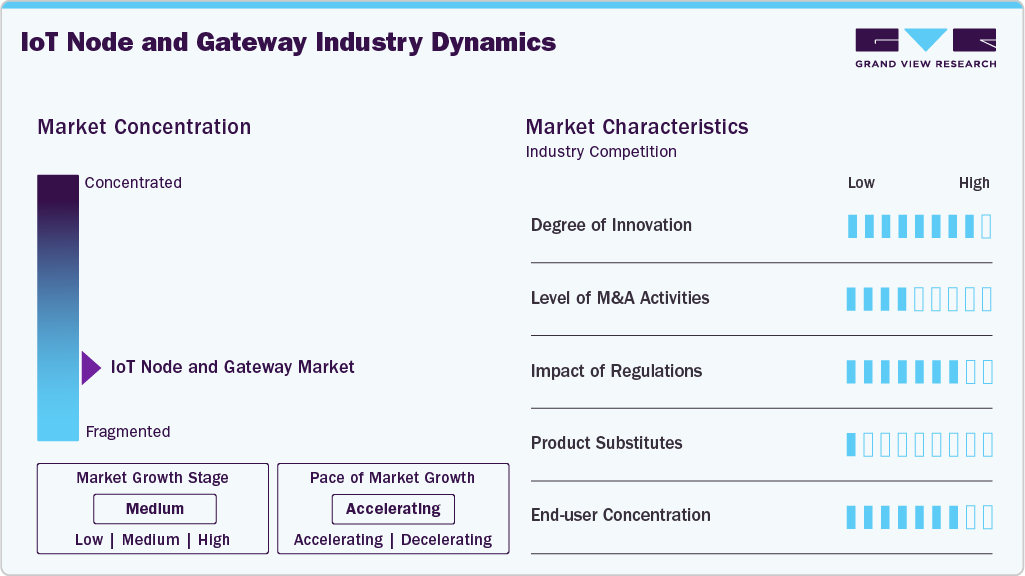
The IoT node and gateway market is moderately fragmented, comprising global semiconductor manufacturers, industrial automation companies, networking equipment providers, and emerging IoT solution vendors. The ecosystem is highly technology-driven, supported by advancements in edge computing, Industrial Internet of Things (IIoT), artificial intelligence, cloud integration, and 5G connectivity, which enable efficient device-to-cloud communication, real-time data processing, and interoperability across heterogeneous IoT environments. Mergers and acquisitions activity in the market is moderate, driven by companies seeking to strengthen edge computing capabilities, expand IoT portfolios, and enhance global connectivity solutions. Regulatory influence in the IoT node and gateway market is moderate to high, primarily shaped by cybersecurity standards, data privacy regulations, industrial safety requirements, and compliance frameworks governing connected devices across critical infrastructure sectors.
 To learn more about this report, Download Free Sample Report
Product substitution is relatively low, as IoT nodes and gateways serve as essential infrastructure components for enabling connectivity, data aggregation, and edge intelligence across IoT ecosystems, making them difficult to replace with alternative technologies. Demand remains highly diversified across industrial automation, smart cities, energy and utilities, healthcare, transportation, agriculture, and consumer IoT applications, driven by rapid digital transformation, increasing deployment of connected devices, expansion of smart infrastructure projects, and the growing need for real-time monitoring, automation, and predictive analytics.
Analyst Perspective
The IoT node and gateway market is experiencing strong structural growth, driven by the rapid expansion of connected devices across industrial and commercial ecosystems and the accelerating shift toward edge-enabled architectures for real-time data processing. Increasing adoption of Industrial IoT (IIoT) solutions is enabling enterprises to enhance operational efficiency, improve asset utilization, and implement predictive maintenance across manufacturing, energy, transportation, and smart infrastructure applications. In addition, the growing integration of advanced technologies such as 5G connectivity, edge computing, artificial intelligence, and cloud platforms is further strengthening demand for scalable and interoperable IoT node and gateway solutions, positioning them as critical enablers of next-generation digital transformation initiatives.
Component Insights
Based on component, the hardware segment led the market with the largest revenue share of 58.1% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The IoT market has been experiencing remarkable growth driven in large part by advancements in hardware components for both Internet of things node and gateway. These components are the building blocks of IoT devices, enabling them to collect, process, and transmit data efficiently and reliably. The most notable trend in IoT hardware components is miniaturization. Manufacturers are continually striving to reduce the size of sensors, processors, and other components while maintaining or even improving their performance. In May 2022, Advantech Co. Ltd. launched UNO-2271G V2. The next generation UNO-2271G V2 edge IoT gateway features a modular design and can be easily integrated with an optional second stack I/O extension module to support diverse operations.
The services segment is expected to witness the highest CAGR of around 15% by 2033. IoT landscape, node, and gateway serve as the backbone, connecting various devices and systems to the cloud or other data processing infrastructure. Sensors, on the other hand, are the important hardware component of node and gateway, providing real-time information about the physical world. In March 2022, Intel Corporation acquired Granulate Cloud Solutions Ltd., an Israel-based developer of real-time continuous optimization software. The acquisition of Granulate will help cloud and data center customers maximize computer workload performance and reduce infrastructure and cloud costs.
End-use Insights
Based on end use, the consumer electronics segment dominated the market with the largest revenue share of 19.1% in 2025. The market is particularly booming and expected to grow exponentially in the coming years. The rise in popularity of IoT technology is driven by the convenience and efficiency it offers to users. It allows users to connect and control multiple devices from a single point, making their lives easier and more efficient. For instance, people can control their home appliances, lighting, and security systems from their smartphones or other connected devices. Moreover, the trend towards smart homes and smart cities is driving the demand in the market. With smart homes, people can monitor and control their homes remotely, ensuring safety and energy efficiency.
The aerospace and defense segment is expected to witness a CAGR of 13.9% from 2023 to 2033. In the aerospace and defense industry, it has been used to monitor aircraft performance, track the movement of military assets, and improve logistics and supply chain management. This technology has provided valuable insights into equipment maintenance and usage, as well as enabling better decision-making in real-time, thereby, the growth of the market in the aerospace and defense industry is expected to continue in the coming years. For instance, in April 2022, Intel Corporation announced the signing of a memorandum with Lockheed Martin to harness innovative 5G software and hardware solutions to enable faster and more decisive actions for the U.S. Department of Defense.
Connectivity Insights
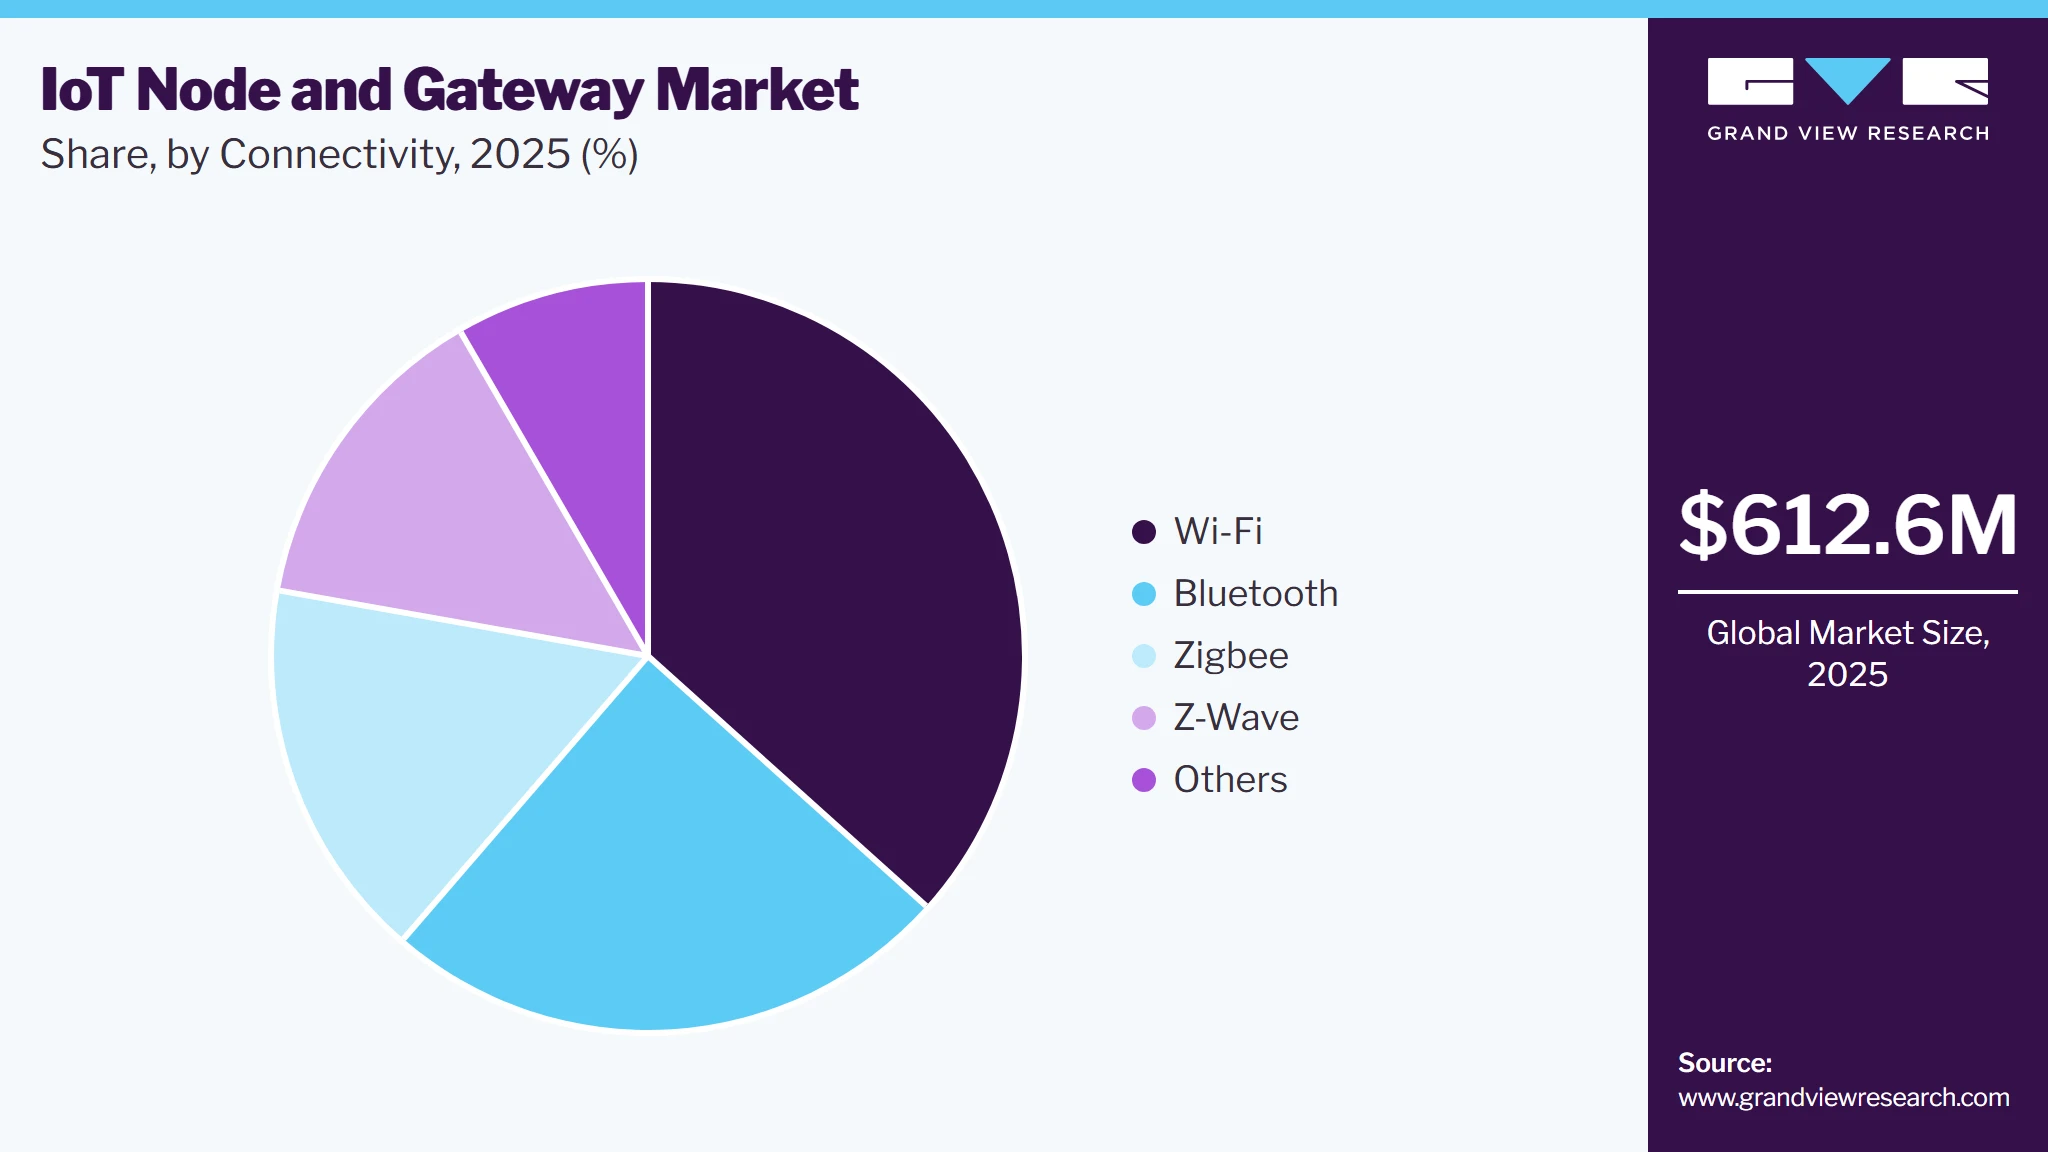
Based on connectivity, the Wi-Fi segment dominated the market with the largest revenue share of 36.6% in 2025. Wi-Fi networks are ubiquitous in homes, offices, and public spaces, making them easily accessible for IoT devices. Easily availability has led to increased adoption, as IoT nodes can seamlessly connect to existing infrastructure. Wi-Fi offers high data transfer speeds, making it suitable for applications that require real-time data transmission, such as video surveillance, industrial automation, and smart home devices. This high throughput is crucial for the success of IoT applications. For instance, in June 2023, Cisco Systems Inc. partnered with AT&T Inc. to enhance connectivity and advance the calling landscape for hybrid workforces. This partnership allows users the flexibility to take calls across multiple devices while traveling for work, running errands, and more.
 To learn more about this report, Download Free Sample Report
The Z-wave segment is expected to witness the highest CAGR of 13.4% from 2023 to 2033. Z-Wave is a wireless communication protocol that was developed with the specific goal of facilitating interoperability among various smart devices. It operates on the sub-GHz frequency band, providing superior range and penetration through walls and floors compared to its Wi-Fi and Bluetooth counterparts. In May 2023, Laird Connectivity launched the RM126x series of LoRaWAN modules. The RM126x module series comes as two variants with the RM1262 based on the SX1262 chipset and the RM1261 based on the SX1261 chipset.
Regional Insights
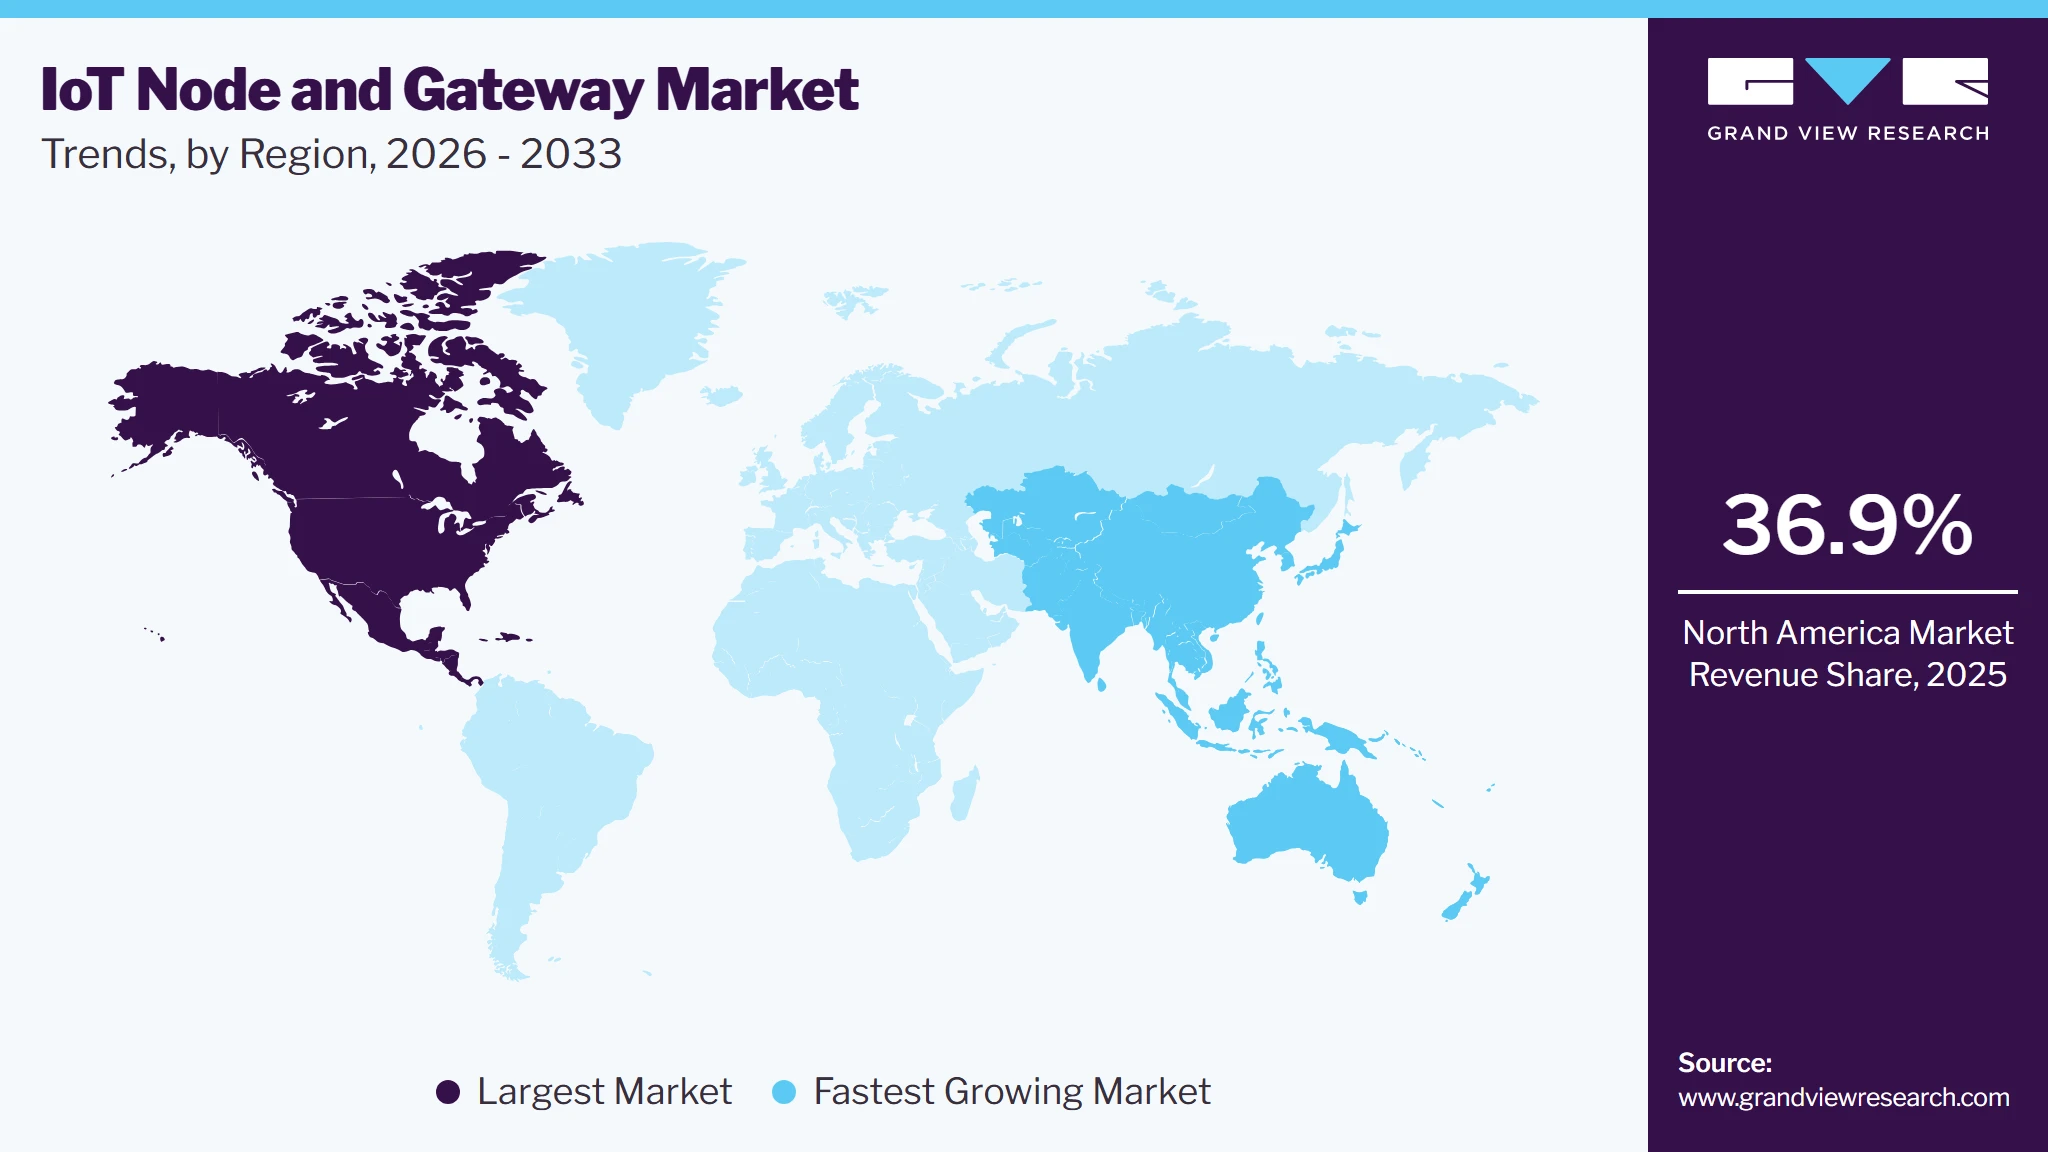
North America dominated the IoT node and gateway market, accounting for the largest revenue share of 36.9% in 2025. The IoT node and gateway market in the U.S. held the largest share in the North America region in 2025. The region has been at the forefront of technological innovation, with a robust ecosystem of tech companies, startups, and research institutions. This environment has fostered the development of cutting-edge IoT solutions, making it an ideal market for adoption. The region has been quick to embrace emerging technologies such as 5G, edge computing, and AI, which are essential for IoT deployments.
 To learn more about this report, Download Free Sample Report
The Middle East and Africa region is expected to grow at the fastest CAGR of 17.3% over the forecast period. The regional growth can be attributed to the growing focus on digital transformation and economic diversification. Several Middle Eastern countries, such as the UAE have ambitious visions for smart cities and smart infrastructure, making extensive use of IoT technology. Investments in areas like energy management, transportation, and healthcare have led to the widespread deployment of IoT node and gateway, contributing to high adoption rates.
Key Companies & Market Share Insights
The key players often include technology innovators, solution providers, and research institutions. The hardware and software provide the foundation. Still, software connectivity and security capabilities are critical determinants of value. IoT platform provides core connectivity, device management, data analytics, and integration capabilities. For instance, In May 2023, Cisco Systems Inc. announced a partnership with the United States Golf Association with this partnership the two organizations leverage Cisco’s industry-leading solutions, innovation, and expertise to strengthen the USGA’s technological infrastructure at their championships and foster innovation and inclusion in the sport of golf.
Key IoT Node And Gateway Companies:
The following key companies have been profiled for this study on the IoT node and gateway market.
-
Cisco Systems Inc.
-
Sierra Wireless
-
Intel Corporation
-
IBM Corporation
-
Huawei Technologies Co. Ltd.
-
Dell Technologies Inc.
-
Advantech Co. Ltd.
-
NXP Semiconductors N.V.
-
Eurotech
-
Particle Industries Inc.
-
Helium
-
Laird Connectivity
-
Robert Bosch GmbH
-
STMicroelectronics N.V.
-
Texas Instruments Incorporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cisco Systems Inc., Intel Corporation, IBM Corporation, Huawei Technologies Co. Ltd., Dell Technologies Inc., Robert Bosch GmbH)
Focus on delivering end-to-end IoT solutions covering hardware, connectivity, edge computing, cloud integration, and industrial platforms.
Invest heavily in AI-enabled analytics, 5G/edge infrastructure, cybersecurity, and Industrial IoT (IIoT) deployments across manufacturing, automotive, energy, and smart city ecosystems.
Strong global presence, large installed base across enterprise and industrial sectors, advanced R&D capabilities, vertically integrated ecosystems, and strong financial strength enabling large-scale deployments.
High system complexity and integration cost, slower customization cycles, heavy reliance on industrial capital expenditure, and intense competition across overlapping technology domains.
Emerging & Specialized Players (Sierra Wireless, Advantech Co. Ltd., Eurotech, Particle Industries Inc., Helium, Laird Connectivity)
Focus on niche IoT connectivity solutions, edge gateways, LPWAN networks, developer platforms, and industrial edge computing systems.
Emphasis on flexible, modular, and cost-effective IoT deployments for SMEs and specific industry use cases.
Agility in innovation, faster time-to-market, strong specialization in connectivity or edge solutions, developer-friendly ecosystems, and the ability to serve customized or niche IoT applications.
Limited global scale, weaker end-to-end ecosystem coverage, lower R&D budgets compared to established players, and dependence on partnerships with larger OEMs and platform providers.
IoT Node And Gateway Market Report Scope
Report Attribute
Details
Market size in 2025
USD 612.6 billion
Estimated market size in 2026
USD 690.9 billion
Projected market size by 2033
USD 1,487.3 billion
Growth rate
CAGR of 11.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, connectivity, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia, Brazil; Mexico; UAE; South Africa, Saudi Arabia
Key companies profiled
Cisco Systems Inc.; Sierra Wireless; Intel Corporation; IBM Corporation; Huawei Technologies Co. Ltd.; Dell Technologies Inc.; Advantech Co. Ltd.; NXP Semiconductors N.V.; Eurotech; Particle Industries Inc.; Helium; Laird Connectivity; Robert Bosch GmbH; STMicroelectronics N.V.; Texas Instruments Incorporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global IoT Node And Gateway Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and analyzes the latest industry trends and opportunities in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the IoT node and gateway market report based on component, connectivity, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Connectivity Integrated Circuited (ICs)
-
Logic Devices
-
Memory Devices
-
Processors
-
Sensors
-
Temperature Sensors
-
Motion Sensors
-
Light Sensors
-
Others
-
-
-
Software
-
Services
-
-
Connectivity Outlook (Revenue, USD Billion, 2021 - 2033)
-
ZigBee
-
Wi-Fi
-
Bluetooth
-
Z-Wave
-
Others
-
-
End-Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consumer Electronics
-
Wearable Devices
-
Automotive & Transportation
-
BFSI
-
Healthcare
-
Retail
-
Building Automation
-
Oil & Gas
-
Agriculture
-
Aerospace & Defense
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East and Africa
-
UAE
-
South Africa
-
-
Research Methodology
The IoT node and gateway market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each IoT node and gateway segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
Revenue is generated through the sale of IoT node and gateway physical components, including connectivity ICs, processors, memory devices, logic devices, and sensors (temperature, motion, light, others), which enable data acquisition, processing, and device-to-cloud communication. Revenue is captured from OEMs, industrial automation providers, consumer electronics manufacturers, automotive systems suppliers, and smart infrastructure deployments.
Software
Revenue is generated from the licensing and deployment of IoT platform software, device management systems, edge analytics tools, cybersecurity solutions, and embedded applications that enable monitoring, control, and interoperability of connected devices.
Services
Revenue is captured from consulting, system integration, installation, cloud connectivity, maintenance, managed services, and lifecycle support associated with IoT node and gateway deployments.
Segment - Connectivity
Revenue capture definition
ZigBee
Revenue is captured from low-power mesh networking solutions used in smart home automation, building management systems, and industrial control applications.
Wi-Fi
Revenue is generated from wireless connectivity solutions that enable high-speed data transmission in consumer electronics, smart homes, industrial monitoring, and connected infrastructure.
Bluetooth
Revenue is generated through short-range communication modules used for device-to-device connectivity in IoT ecosystems.
Z-Wave
Revenue is captured from wireless mesh networking solutions primarily used in residential automation, smart security systems, and smart appliance connectivity.
Others
Revenue is generated through alternative connectivity technologies such as LPWAN, NB-IoT, LTE-M, and proprietary industrial communication protocols.
Segment - End Use
Revenue capture definition
Consumer Electronics
Revenue is generated from smart, connected devices such as TVs, speakers, and home appliances that are embedded with IoT functionality.
Wearable Devices
Revenue is captured from smartwatches, fitness trackers, and health monitoring devices used in fitness, healthcare, and wellness applications.
Automotive & Transportation
Revenue is captured from connected vehicle systems, telematics, fleet management, and smart mobility solutions.
BFSI
Revenue is captured from IoT-enabled security systems, surveillance infrastructure, and smart banking branch solutions.
Healthcare
Revenue is captured from remote patient monitoring systems, connected medical devices, and hospital automation solutions.
Retail
Revenue is captured from IoT-based inventory tracking, smart shelves, customer analytics, and retail automation systems.
Building Automation
Revenue is captured from smart HVAC, lighting control, energy management, and security automation systems in buildings.
Oil & Gas
Revenue is captured from IoT-based monitoring, predictive maintenance, pipeline management, and asset tracking solutions in energy operations.
Agriculture
Revenue is captured from precision farming solutions including soil monitoring, irrigation systems, and crop analytics platforms.
Aerospace & Defense
Revenue is captured from connected asset tracking, surveillance systems, and predictive maintenance solutions in defense and aerospace applications.
Others
Revenue is captured from IoT applications across logistics, smart cities, utilities, and diverse industrial and public infrastructure deployments.
Estimation Model
Layer Name
Key Question
Description
Connected Device & Industrial Demand Layer
Who generates demand for IoT nodes and gateways?
Represents the total demand base for IoT node and gateway solutions, driven by industries such as manufacturing, automotive, healthcare, energy, agriculture, retail, and smart infrastructure. Demand is fueled by rapid digital transformation, rising adoption of Industrial IoT (IIoT), the expansion of smart cities, and the increasing need for real-time monitoring, predictive maintenance, and automation across connected ecosystems.
Connectivity & Edge Infrastructure Layer
What technologies enable IoT node and gateway systems?
Includes core enabling technologies such as sensors, processors, connectivity ICs, embedded systems, edge computing, 5G, LPWAN, Wi-Fi, Bluetooth, ZigBee, cloud platforms, artificial intelligence (AI), machine learning (ML), cybersecurity frameworks, and edge analytics that support data acquisition, processing, and transmission.
Network, Platforms & Data Management Layer
How is IoT data transmitted, processed, and managed?
Covers IoT gateways, edge devices, communication networks, cloud platforms, device management systems, industrial platforms, middleware solutions, and analytics engines that enable seamless connectivity, interoperability, real-time data processing, and integration across heterogeneous IoT environments.
Revenue Generation & Monetization Layer
How is revenue generated in the IoT node and gateway market?
Revenue is generated through hardware sales (sensors, processors, gateways), software platforms (device management, analytics, security), and services (integration, deployment, maintenance, managed services), along with connectivity solutions and subscription-based IoT platform offerings across industrial and commercial applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Assessed the global IoT node and gateway market size, historical and forecast growth trends, and detailed segmentation by component (hardware, software, services), connectivity (Wi-Fi, Bluetooth, ZigBee, Z-Wave, others), and end-use industry (consumer electronics, automotive & transportation, healthcare, retail, building automation, oil & gas, agriculture, aerospace & defense, others).
Supports market entry and expansion strategies, identifies high-growth opportunities across industrial IoT, smart infrastructure, connected devices, and edge computing ecosystems, improves investment prioritization, and enables data-driven planning for technology and product roadmaps.
Competitive Benchmarking & Strategic Positioning Analysis
Benchmarked leading IoT ecosystem providers, semiconductor companies, networking firms, and edge computing solution vendors based on product portfolio strength, connectivity capabilities, edge intelligence, cloud integration, security frameworks, and global deployment capabilities.
Supports competitive differentiation, strengthens IoT platform positioning, identifies gaps in hardware-software integration and connectivity offerings, improves partnership and acquisition decisions, and enhances long-term IoT ecosystem strategy across industries.
Regional Market Demand & Technology Adoption Analysis
Analyzed regional demand across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, evaluating factors such as Industrial IoT adoption, smart city initiatives, 5G penetration, manufacturing digitization, cloud adoption, regulatory environment, and connected infrastructure investments.
Supports geographic expansion planning, identifies high-growth regions driven by rapid digitalization and smart infrastructure development, improves localization and deployment strategies, enables region-specific partnerships, and strengthens long-term planning for global IoT ecosystem growth.
Frequently Asked Questions About This Report
Some key players operating in the Internet of things node and gateway market include Cisco Systems Inc., Sierra Wireless, Intel Corporation, IBM Corporation, Huawei Technologies Co. Ltd., Dell Technologies Inc., Advantech Co. Ltd., NXP Semiconductors N.V., Eurotech, Particle Industries Inc., Helium, Laird Connectivity, Robert Bosch GmbH, STMicroelectronics N.V., Texas Instruments Incorporation.
The Internet of Things (IoT) node and gateway market is expected to grow substantially due to several key factors, including the advent of 5G technology, the increasing utilization of wireless smart sensors and networks, a burgeoning market for connected devices, and the rising demand for data centers driven by the growing adoption of cloud platforms.
The Wi-Fi segment dominated the market, with a share of 36.6% in 2025.
The consumer electronics segment dominated the market with a share of 19.1% in 2025.
North America accounted for the largest share of 36.9% in 2025.
The hardware segment accounted for the largest market share of over 58.1% in 2025. The growth is attributed to the pivotal role played by hardware components in enabling the seamless connectivity and functionality of IoT ecosystems, reflecting the substantial demand for sensors, processors, ICs and other essential hardware elements crucial for IoT node and gateway deployments.
The global internet of things node and gateway market size was estimated at USD 612.6 billion in 2025 and is expected to reach USD 690.9 billion in 2026.
The global IoT node and gateway market is expected to witness a compound annual growth rate of 11.6% from 2026 to 2033 to reach USD 1,487.3 billion by 2033.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


