
- Home
- »
- Medical Devices
- »
-
Medical Adhesive Tapes Market Size And Share Report 2033GVR Report cover

Medical Adhesive Tapes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Acrylic, Silicone), By Adhesion, By Backing Material, By Application (Surgery, Wound Dressing), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$10.3BMarket Estimate, 2026
$10.9BMarket Forecast, 2033
$17.3BCAGR, 2026–2033
6.9%Medical Adhesive Tapes Market Trends
The global medical adhesive tapes market size was valued at USD 10.3 billion in 2025 and is projected to grow from USD 10.9 billion in 2026 to USD 17.3 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 48.7% in 2025. The growing incidence of chronic conditions, including venous leg ulcers, diabetic ulcers, and traumatic wounds, is a primary driver for the increased utilization of medical adhesive tapes. As an illustration, WHO data indicates that annually, approximately 1.2 million individuals succumb to fatalities resulting from vehicle crashes, with an additional 20 to 50 million people sustaining non-fatal injuries.
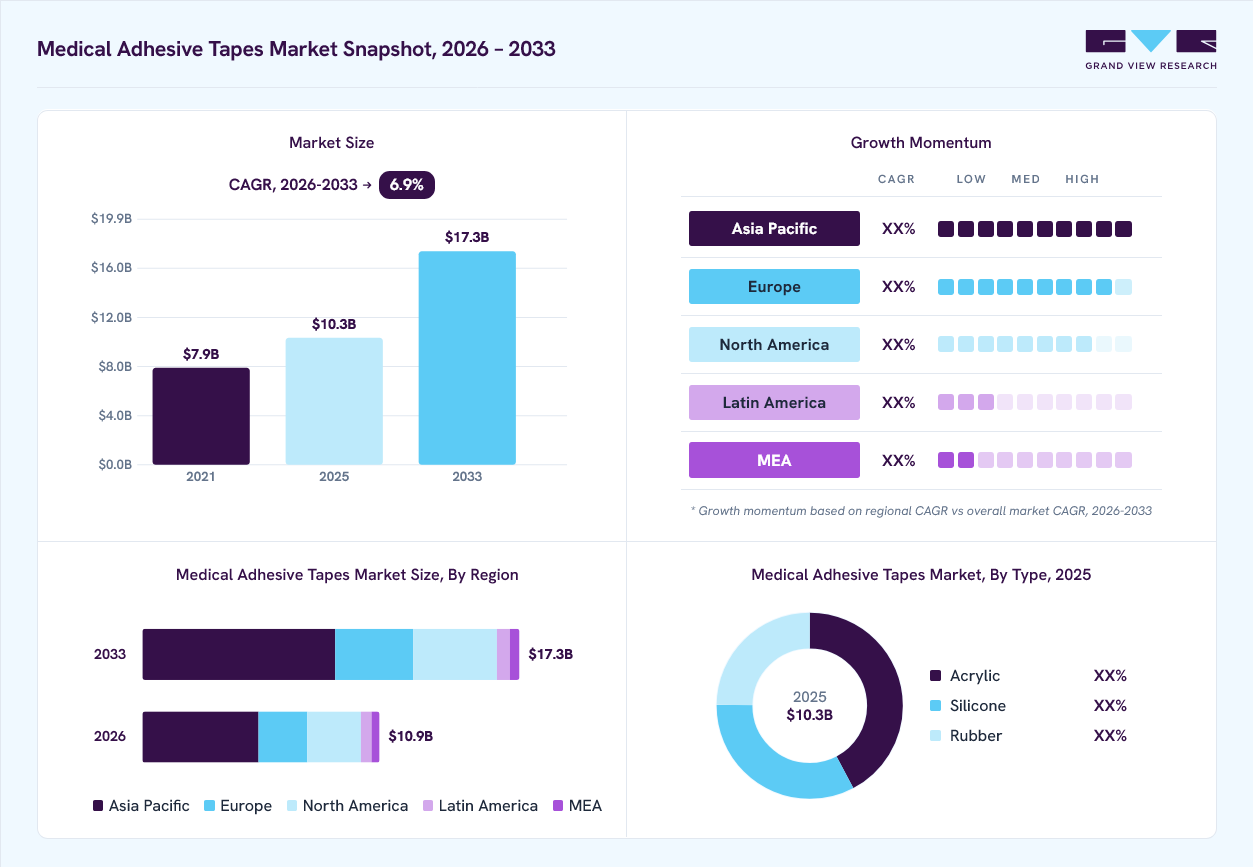 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Acrylic segment dominated the market, with a revenue share of 42.2% in 2025.
- By backing material: Paper segment held the largest market share of 43.4% in 2025.
- By adhesion: Double coated segment held the largest revenue share of 53.9% in 2025.
- By application: Surgery segment led the market with the largest revenue share of 36.9% in 2025.
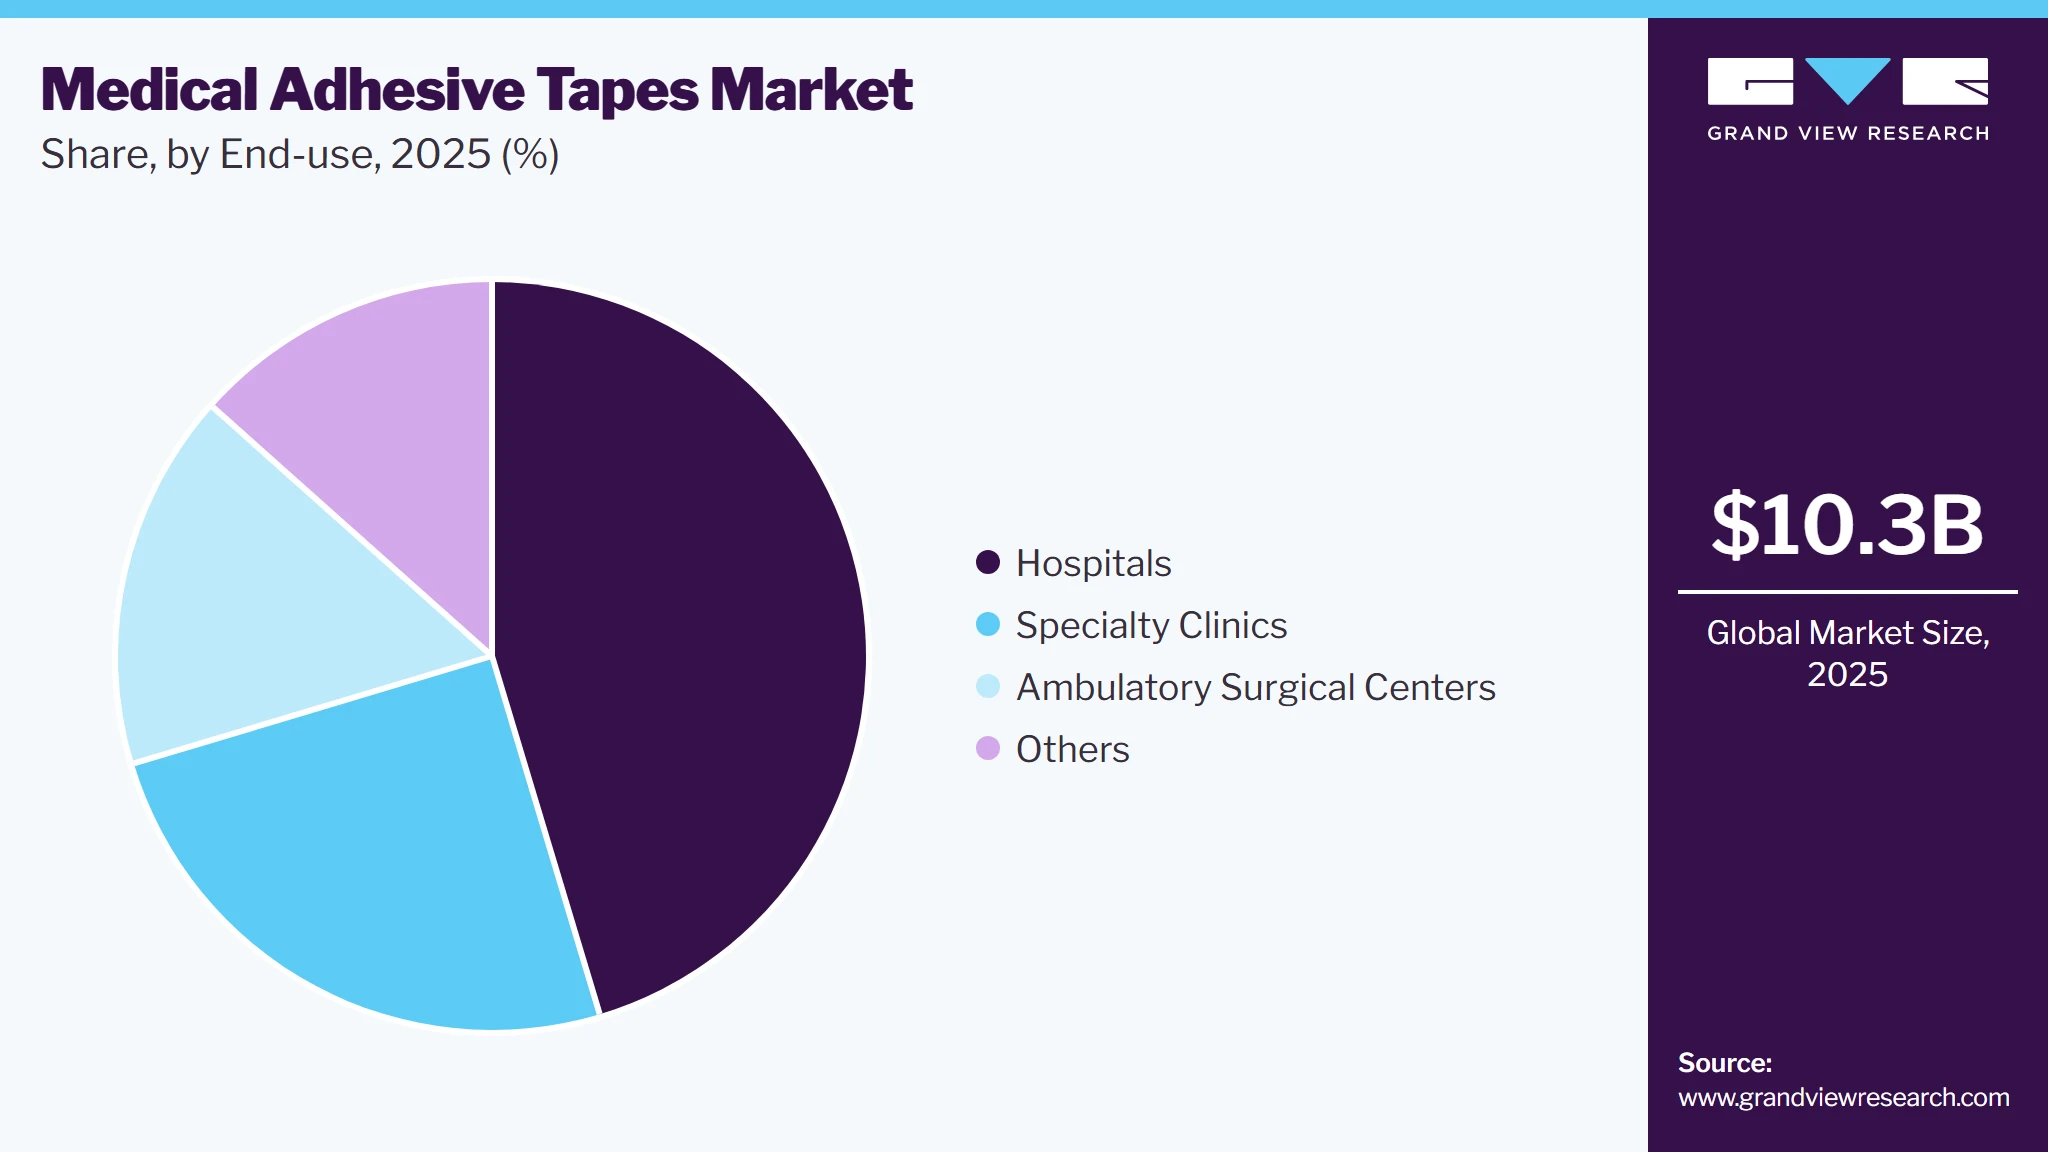
- By end use: Hospitals segment led the market with the largest revenue share of 45.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.7% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.3 Billion
- Estimated market size in 2026: USD 10.9 Billion
- Projected market size by 2033: USD 17.3 Billion
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Surgical interventions necessitate the placement of infusions, IV lines, and catheters, all of which rely on medical adhesive tapes for secure adhesion. Medical adhesive tapes play a crucial role in ensuring the stability and correct placement of catheters and IV lines. The growing prevalence of surgical procedures is expected to fuel the demand for these tapes. For instance, as reported published in 2023 by the Mass General Brigham, around 900,000 open heart surgeries are conducted every year in the U.S. In addition, AHA Journals report that roughly 40,000 children undergo congenital heart surgery annually in the U.S. These surgeries require a considerable healing period, during which wound dressing products play a crucial role in facilitating prompt recovery. Therefore, the preference for wound dressing post-surgery is expected to propel the utilization of medical adhesive tapes throughout the forecast period.
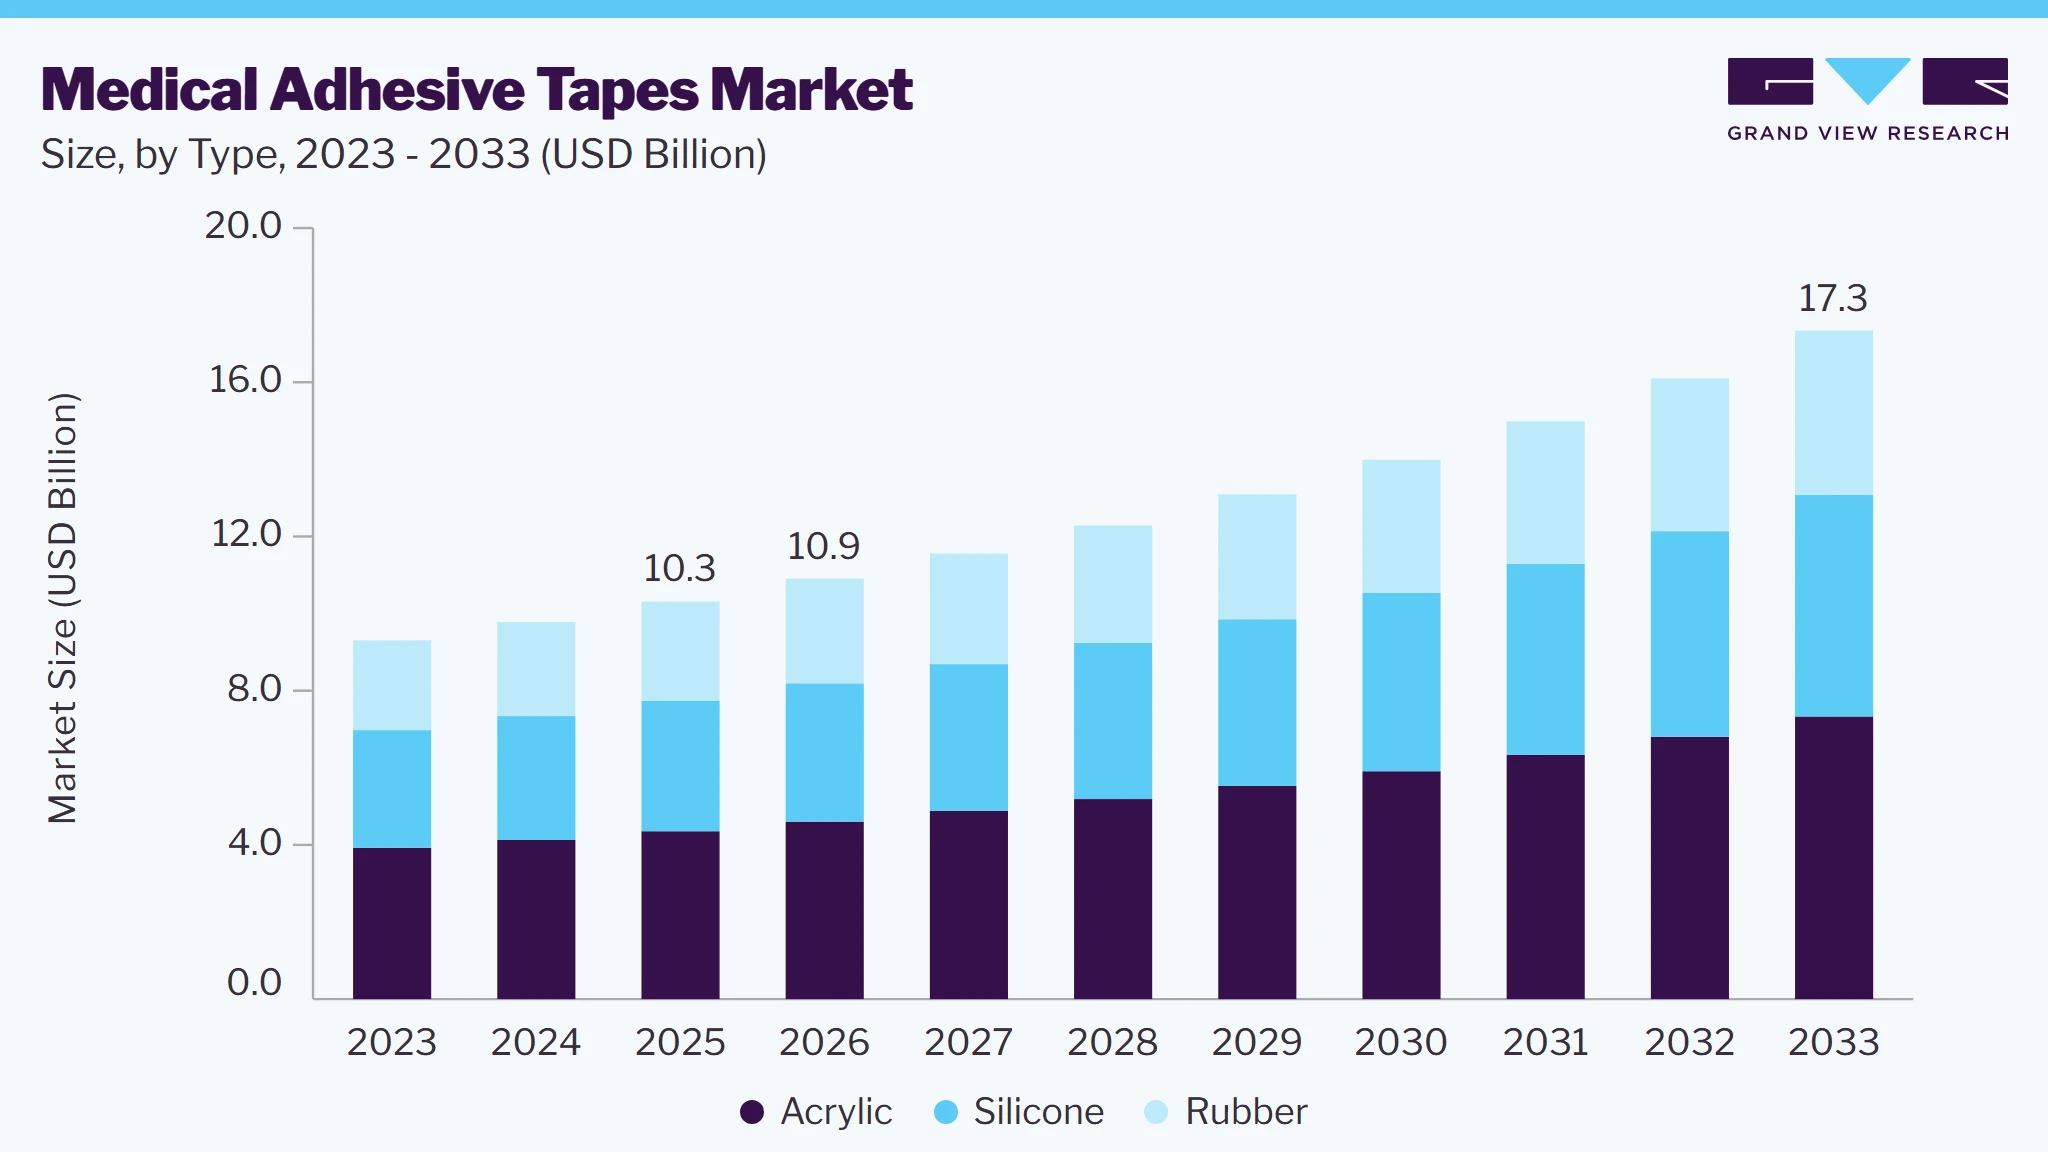 To learn more about this report, Download Free Sample Report
There is a rising trend in global road accidents and other catastrophic events. For instance, according to a 2023 WHO report , approximately 28% of worldwide road traffic fatalities took place in the WHO South-East Asia Region, followed by 25% in the Western Pacific Region, 19% in the African Region, 12% in the Region of the Americas, 11% in the Eastern Mediterranean Region, and 5% in the European Region. The majority of these deaths, about nine in ten, occurred in low- and middle-income countries, where the fatality rates are notably higher relative to the number of vehicles and road infrastructure.
Market Dynamics
The medical adhesive tapes market is experiencing significant growth, driven by rising numbers of surgical procedures, the growing prevalence of chronic wounds, and expanding demand for home healthcare and wearable medical devices. Continuous advancements in skin-friendly, silicone-based, and hypoallergenic adhesive technologies are improving patient comfort and expanding clinical applications. However, challenges such as skin injuries associated with prolonged tape use, fluctuations in raw material prices, and stringent regulatory requirements for biocompatibility may restrain market growth. Despite these constraints, growing investments in advanced wound care, an aging population, and the increasing adoption of minimally invasive procedures are expected to create significant opportunities for market expansion over the coming years.
The increasing number of surgical procedures worldwide is a major driver of the medical adhesive tapes market, as these products are widely used to secure surgical dressings, wound closures, IV lines, drainage tubes, and catheters during perioperative care. The growing adoption of minimally invasive surgeries, coupled with the rising prevalence of chronic diseases requiring surgical intervention, has further increased demand for reliable and skin-friendly fixation solutions. In addition, the expansion of ambulatory surgical centers and improvements in healthcare infrastructure are supporting higher consumption of medical adhesive tapes across healthcare settings. For instance, according to Kuwait Specialty Field Hospital 463 surgeries performed in May 2025 in Kuwait.
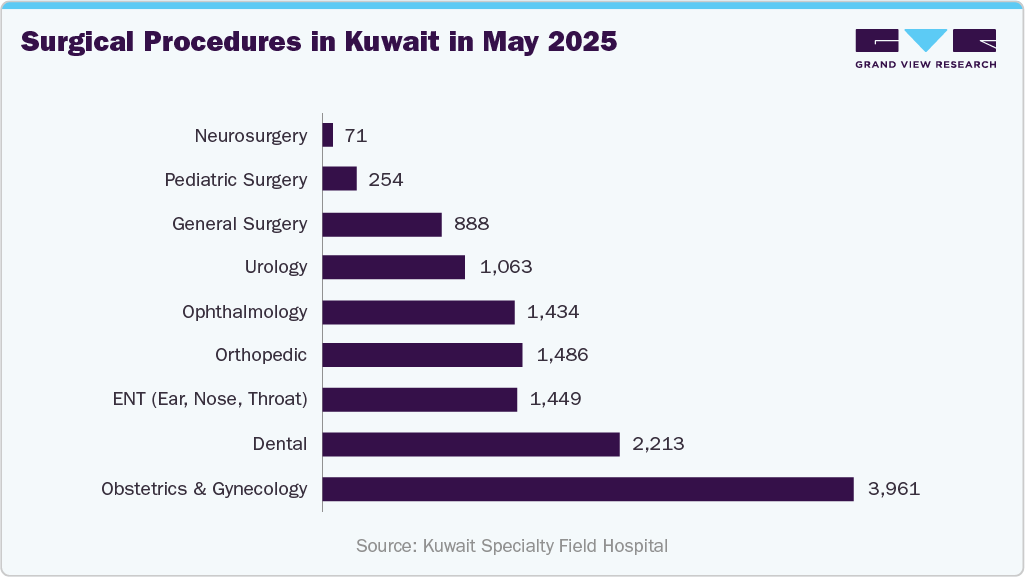 To learn more about this report, Download Free Sample Report
Medical adhesive-related skin injuries (MARSI) remain a significant restraint on the medical adhesive tapes market, as prolonged or repeated tape application can lead to skin tears, blistering, irritation, and allergic reactions. These complications are particularly common among elderly patients, neonates, and individuals with fragile or compromised skin, increasing discomfort and the risk of secondary infections. Consequently, healthcare providers are becoming more selective in their adhesive product choices and increasingly adopting silicone-based, gentler fixation solutions, thereby limiting the use of conventional adhesive tapes in certain clinical settings.
The rapid expansion of wearable medical devices presents a significant growth opportunity for the medical adhesive tapes market, as these devices require reliable, long-lasting skin adhesion for accurate monitoring and patient comfort. Increasing adoption of continuous glucose monitors (CGMs), insulin pumps, ECG patches, and wearable biosensors is driving demand for breathable, hypoallergenic, and moisture-resistant adhesive tapes. Manufacturers are investing in advanced adhesive technologies that offer extended wear time while minimizing skin irritation, creating new opportunities across chronic disease management and remote patient monitoring applications.
For instance, in July 2024, Avery Dennison Medical introduced its Medical Wearable Adhesives Center, highlighting the rapid growth of the wearable medical device segment and the increasing importance of pressure-sensitive adhesive tapes. The company emphasized that wearable devices may require adhesion ranging from a few hours to up to 30 days, depending on the application and patient needs, making high-performance, skin-friendly adhesives essential. This trend is creating significant opportunities for medical adhesive tape manufacturers to develop advanced solutions that improve device performance, patient comfort, and time-to-market for wearable healthcare products.
Market Concentration & Characteristics
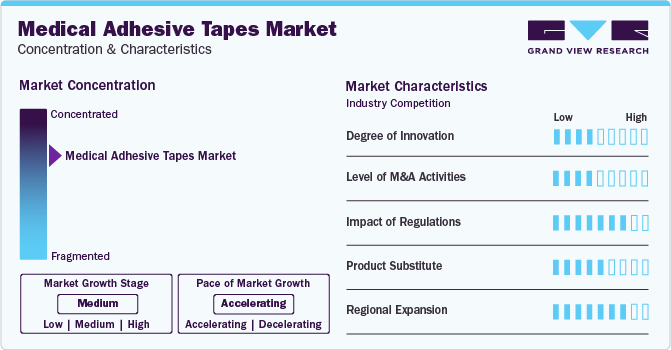
The market is witnessing a moderate degree of innovation, with companies introducing improved products with enhanced adhesion, easy removal, and reduced skin irritation. These innovations aim to enhance patient comfort, promote better wound healing, and provide healthcare professionals with more efficient and reliable adhesive solutions.
 To learn more about this report, Download Free Sample Report
Several market players such as Cardinal Health, 3M, and Smith & Nephew are involved in merger and acquisition activities. Through M&A activity, these companies can expand their geographic reach and enter new territories.
Regulations in the market have a significant impact, with changes necessitating manufacturers to adjust their products or processes accordingly. These can include regulations that promote the production of eco-friendly and sustainable medical adhesive tapes, or those that require changes in manufacturing technologies to reduce the emissions of volatile organic compounds (VOCs)
Potential product substitutes in the market include staples and sutures in wound closure and surgical procedures. Advanced wound dressings like hydrocolloids, foam dressings, and alginate dressings further serve as substitutes, particularly in wound care. Market players are expanding regionally to capitalize on growing healthcare demands, with a focus on enhancing product accessibility and addressing specific regional healthcare needs.
Analyst Perspective
The medical adhesive tapes market is expected to witness significant growth, driven by increasing surgical procedures, rising prevalence of chronic wounds, and expanding adoption of wearable medical devices. Demand is shifting toward silicone- and acrylic-based tapes that offer gentle skin adhesion, longer wear time, and improved patient comfort. In addition, manufacturers investing in skin-friendly adhesive technologies, sustainable materials, and product innovation are likely to strengthen their competitive positioning, while expanding healthcare infrastructure and home healthcare adoption will continue to create long-term growth opportunities.
Regulatory and Reimbursement Trends
As healthcare systems prioritize cost-effective wound management and standardized reimbursement pathways, regulatory compliance has become a key factor influencing the adoption of medical adhesive tapes. Manufacturers are focusing on products that meet reimbursement eligibility, quality standards, and clinical documentation requirements to improve market access.
According to the Cardinal Health 2026 Wound Care Reimbursement Coding Guide, medical adhesive tapes and related wound care products are primarily reimbursed under Medicare Part B’s Durable Medical Equipment, Prosthetics, Orthotics, and Supplies (DMEPOS) benefit using HCPCS codes. Coverage is determined by individual Medicare Administrative Contractors (MACs) based on Local Coverage Determinations (LCDs), making accurate coding, regulatory compliance, and adherence to CMS coverage policies essential for reimbursement and broader market adoption.
Type Insights
Based on type, the acrylic segment led the market with the largest revenue share of 42.2% in 2025. The prevalence of acrylic medical adhesive tape can be attributed to the benefits it offers. Specifically, this tape provides a robust initial tack, exhibits low skin sensitivity, and leaves no residue on the skin upon removal. In addition, it showcases resistance to humidity and heat, is latex-free, and can be laminated onto various surfaces, including foams and film dressings. Notably, the tape maintains its integrity throughout the wound dressing process.
The silicone segment is expected to grow at the fastest CAGR over the forecast period. The rising demand for silicone medical adhesive tapes can be attributed to several key factors. One significant reason is their repositionable nature, allowing for wound observation and examination without the necessity of replacing the dressing, thereby facilitating extended wear time. In addition, these tapes are atraumatic and easy to remove, reducing the risk of complications like secondary infections. Moreover, silicone tapes contribute to minimizing scarring and are internationally recognized as a recommended form for scar management. Consequently, the demand for silicone medical adhesive tapes is anticipated to grow in the forecast period due to these factors.
Backing Material Insights
Based on backing material, the paper segment led the market with the largest revenue share of 43.4% in 2025. Paper-based tapes are widely used in medical applications because they provide a good balance of strength, flexibility, and breathability. The porosity of paper allows for better aeration and moisture absorption, making it suitable for applications where skin contact is involved. In addition, paper tapes are easily customizable, allowing manufacturers to produce a variety of widths and lengths to meet diverse medical requirements, thereby contributing to the overall segment growth.
The fabric segment is expected to grow at the fastest CAGR over the forecast period. due to its unique combination of durability, flexibility, and excellent adhesive properties. Fabric-backed tapes are known for their high tensile strength and resistance to tearing, making them ideal for applications that require a secure and long-lasting bond. Furthermore, fabric tapes offer enhanced breathability compared to some other materials, promoting airflow and reducing the risk of skin irritation.
Adhesion Insights
Based on adhesion, the double coated segment led the market with the largest revenue share of 53.9% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The attribution of its market dominance can be ascribed to enhanced strength and superior dimensional versatility, rendering them highly adaptable for conversion. Furthermore, these tapes present breathable, hypoallergenic, and repositionable alternatives. They also offer a variety of thickness, adhesive strengths, and backing materials to cater to individual requirements, consolidating their stronghold in the market.
The single coated segment is estimated to register the fastest CAGR over the forecast period.Single-coated medical tapes comprise a substrate of foam, nonwoven, film, or metal coated with medical-grade pressure-sensitive adhesive on one side. These tapes, protected by a silicone release liner, are utilized in healthcare devices that require direct skin contact.
Application Insights
Based on application, the surgery led the market with the largest revenue share of 36.9% in 2025. The surge in the usage of medical adhesive tapes can be linked to the rise in the number of surgical procedures. For instance, an article published by 'Trauma of Major Surgery' indicates that approximately 310 million major surgeries are conducted annually. In addition, the growing trend of cosmetic surgeries has contributed to the increased utilization of medical adhesive tapes. In 2020, according to the Aesthetics Society, approximately 140,314 fat-reduction procedures were performed, further fueling the growth of this segment.
Wound Dressingis expected to grow at the fastest CAGR over the forecast period. The increase in the utilization of medical adhesive tapes can be attributed to the growing prevalence of wound dressing applications, particularly in the treatment of various chronic and acute wounds. The rising incidence of chronic wounds such as diabetic foot ulcers, venous leg ulcers, and pressure ulcers is expected to drive the demand for these tapes. For instance, as per IDF Diabetes Atlas report published in 2021, around 537 million adults are living with diabetes disorder. Furthermore, diabeticfootonline.com report published in 2020, up to 34% of individuals with diabetes are at risk of developing diabetic foot ulcers. These factors contribute significantly to the expansion of the market.
End-use Insights
Based on end-use, the hospitals segment led the market with the largest revenue share of 45.3% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The dominance of the hospital segment in the use of medical adhesive tapes can be ascribed to a surge in surgical procedures, an escalation in the number of hospitals, and a rise in accidental incidents across various countries. For instance, according to Philkotse, the number of traffic accidents rose from 63,072 in 2007 to 116,906 in 2018. This increase in accidents has led to a higher incidence of surgeries and, consequently, an elevated demand for medical adhesive tapes. Additionally, in the U.S. the National Highway Traffic Safety Administration projected that 42,795 individuals lost their lives in motor vehicle traffic crashes in the year 2022. Therefore, owing to these contributing factors, the hospital segment is anticipated to take a leading position in the end-use category.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers segment has been anticipated to witness lucrative CAGR over the forecast period. The growing incidence of chronic diseases is driving the demand for ambulatory surgical centers. Moreover, increased investments and various initiatives by public health organizations and governments, coupled with a changing preference among patients favoring ASCs over traditional hospitals, are anticipated to boost the demand for medical adhesive tapes in these ambulatory settings.
Regional Insights
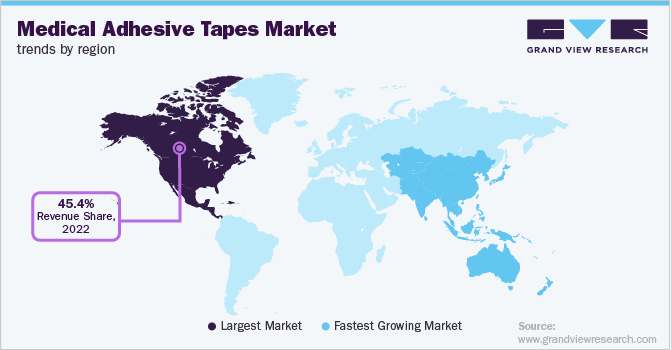
Asia Pacific dominated the medical adhesive tapes market with the largest revenue share of 48.7% in 2025. The growing prevalence of diabetes in the region can be attributed to the increasing demand for medical adhesive tapes. For instance, according to the Down to Earth organization, India had an estimated 74.2 million diabetics between the ages of 20 and 79 as of December 2021, with projections indicating a rise to 124.8 million by 2045. In the Philippines, the International Diabetes Federation (IDF) reported that 3,993,300 people out of a total population of 536,600 had diabetes in 2021. The escalating number of diabetics raises the likelihood of diabetic foot ulcers, necessitating the use of wound dressings. This, coupled with an increase in surgical cases, is expected to drive the demand for medical adhesive tapes, thereby stimulating regional market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
China held the largest revenue share of the market in the Asia Pacific region in 2025. The country's economy is one of the biggest in the world, which allows for substantial investment in the production of medical adhesive tapes. In addition, China's access to economical and readily available raw materials drives foreign investments, contributing to the growth of healthcare adhesive tapes production.
North America held a significant market share in the market in 2023. This market is driven by the advanced healthcare infrastructure, increasing public awareness, and the presence of significant industry players. Furthermore, the anticipated rise in surgical procedures in North America is expected to drive the demand for medical adhesive tapes. For instance, the Emory University Hospital estimated that approximately 441 open-heart operations were conducted in the U.S. in 2022 Similarly, according to AHA Journals, 40,000 children in the U.S. undergo congenital heart surgery annually. Given the recovery period for these surgeries, wound dressings are essential, necessitating the use of medical adhesive tapes and thereby propelling regional growth.
The U.S. accounted for the largest revenue share of the market in North America region in 2023. The U.S. boasts a robust and technologically advanced healthcare infrastructure, fostering increased adoption of medical adhesive tapes in various clinical applications. In addition, the presence of prominent market players and research institutions within the country contributes to the development and innovation of advanced adhesive technologies.
Key Medical Adhesive Tapes Company Insights
Some of the key players operating in the market include Cardinal Health, 3M and Smith Nephew. These players are continuously focusing on developing innovative medical adhesive tape products with advanced features, such as improved adhesion, breathability, and skin-friendly formulations, to meet evolving healthcare needs. Furthermore, they also focus on strategic partnerships, acquisitions, and global expansions to strengthen market presence and offer comprehensive solutions, ensuring they stay ahead in a competitive healthcare landscape.
Nitto Denko Corporation and Nichiban Co Ltd are some of the emerging market players in the market. These market players employ strategies such as technological innovation to introduce unique products, cost competitiveness to offer budget-friendly solutions, and strategic alliances for market expansion.
Key Medical Adhesive Tapes Companies
The following key companies have been profiled for this study on the medical adhesive tapes market.
-
Smith & Nephew
-
3M
-
Medline Industries, LP
-
Paul Hartmann AG
-
Cardinal Health
-
Baxter
-
Johnson & Johnson Services, Inc
-
Nitto Denko Corporation
-
Nichiban Co Ltd
-
Lohmann Technologies
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (3M, Avery Dennison Medical, Medline Industries, LP, Cardinal Health Inc.)
- Focus on product portfolio expansion across acrylic, silicone, and rubber adhesive tapes.
- Invest in R&D for skin-friendly, breathable, and wearable-device compatible adhesives.
- Strong global brand recognition and customer loyalty.
- Extensive regulatory approvals and proven clinical performance.
- Higher operating costs and complex organizational structures.
- Longer product development and regulatory approval timelines.
Emerging Players (Flexcon Company, Inc., DermaMed Coatings Company, Mactac (Medical Products))
- Focus on niche segments such as silicone tapes, antimicrobial tapes, and wearable medical adhesives.
- Introduce cost-effective and customized products for regional markets.
- Faster innovation cycles and greater flexibility in product development.
- Ability to address underserved regional and specialty application markets.
- Limited brand recognition and customer trust compared with established companies.
- Smaller manufacturing capacity and restricted global distribution networks.
Recent Developments
-
In January 2023, introducing Swift Melt 1515-I, H.B. Fuller's first biocompatible product approved in the IMEA region. This product is tailored for clinical tape applications, specifically designed for adherence to the skin in challenging climates, such as the hot and humid conditions found in the Indian subcontinent
-
In February 2023, 3M launched a new medical adhesive formulated to securely adhere to the skin for an extended period, lasting up to 28 days. This adhesive is specifically designed for use with a wide variety of health monitors, sensors, and long-term medical wearables
-
In April 2022, 3M introduced a new adhesive tape designed for securing medical devices to a patient's skin, offering extended adhesion for up to 21 days
Medical Adhesive Tapes Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.3 billion
Estimated market size in 2026
USD 10.9 billion
Projected market size by 2033
USD 17.3 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, backing material, adhesion, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
3M, Avery Dennison Medical, Medline Industries, LP, Cardinal Health Inc., Flexcon Company, Inc., DermaMed Coatings Company, Mactac (Medical Products), CCT (Coating & Converting Technologies, LLC) (An ATP Group Company), DermaRite Industries, LLC, Lohmann & Rauscher GmbH & Co.KG, Paul Hartmann AG, Smith & Nephew PLC, Gergonne Industrie, Saint-Gobain S.A. (Medical), PPI Adhesive Products, Sterimed Group
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Adhesive Tapes Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global medical adhesive tapes market report based on type, backing material, adhesion, application, end use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Acrylic
-
Silicone
-
Rubber
-
-
Backing Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Paper
-
Fabric
-
Plastic
-
Others
-
-
Adhesion Outlook (Revenue, USD Million, 2021 - 2033)
-
Single Coated
-
Double Coated
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Surgery
-
Wound Dressing
-
IV Lines
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Specialty Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The medical adhesive tapes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical adhesive tapes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue capture definition
Acrylic
Acrylic-based medical adhesive tapes accounted for a significant share of the market due to their strong adhesion, skin-friendly properties, breathability, and long wear time. Their widespread use in wound dressings, surgical tapes, wearable medical devices, and securement applications supported consistent revenue generation across both hospital and home healthcare settings.
Silicone
Silicone-based medical adhesive tapes captured a growing share of the medical adhesive tapes market owing to their gentle skin adhesion, atraumatic removal, and suitability for fragile or sensitive skin. Their increasing adoption in advanced wound care, postoperative dressings, neonatal care, and long-term wearable medical devices contributed to significant revenue growth.
Rubber
Rubber-based medical adhesive tapes held a notable share of the market due to their high initial tack, strong adhesion, and cost-effectiveness. Their extensive use in general wound care, medical device fixation, and routine clinical applications, particularly in hospitals and emergency care settings, contributed to revenue generation.
Estimation Model
Approach
Description
Bottom-Up Modeling
Regional market size was defined using country-level healthcare indicators, including the number of surgical procedures, chronic wound patient population, hospital admissions, and consumption of medical adhesive tapes across hospitals, ambulatory surgical centers, and home healthcare settings. Average selling prices (by tape type: acrylic, silicone, and rubber) were applied to estimate regional revenues.
Top-Down Revenue Triangulation
The medical adhesive tapes market was estimated by calculating its share within the broader wound care and medical consumables market. Revenue contributions of leading manufacturers such as 3M, Avery Dennison, Lohmann & Rauscher, Medline, Cardinal Health, and PAUL HARTMANN AG were analyzed using annual reports, product portfolios, investor presentations, and publicly available financial disclosures.
Demand-Side Procedure Modeling
Market demand was estimated by analyzing the annual volume of surgical procedures, wound dressing changes, catheter and IV securement procedures, wearable medical device adoption, and home healthcare utilization. These procedure volumes were combined with average tape usage per procedure and regional healthcare expenditure to determine total market demand and revenue generation.
Delivered Customizations
This report has been delivered with the following In-depth customziations
Client Request
Customization Delivered
Value Adds
Market Analysis by Segments
Delivered detailed market sizing and forecasts by adhesive type, backing material, application, end user, and region, along with country-level analysis for key markets such as the U.S., Germany, China, Japan, and India.
Enabled targeted investment decisions, regional expansion planning, and identification of high-growth market segments.
Competitive Landscape Assessment
Provided company profiling, market share assessment, competitive benchmarking, SWOT analysis, and recent product launches, partnerships, acquisitions, and regulatory approvals.
Helped identify competitive gaps, benchmark industry leaders, and support strategic positioning and partnership opportunities.
Technology Trends & Growth Opportunities
Delivered in-depth analysis of emerging technologies, innovation pipeline, regulatory trends, and opportunity assessment across advanced wound care and wearable healthcare applications.
Supported long-term product development, R&D prioritization, and market entry strategies by identifying high-potential growth areas.
Frequently Asked Questions About This Report
Key factors that are driving the medical adhesive tapes market growth include chronic diseases, a rising geriatric population, an increasing number of road accidents, and trauma cases, and surge in surgical procedures
The hospitals segment led the market with the largest revenue share of 45.3% in 2025.
The surgery led the market with the largest revenue share of 36.9% in 2025 and wound dressing segment is second fastest growing market
The double coated segment led the market with the largest revenue share of 53.9% in 2025 while single coated segment is expected to be the fastest-growing market.
The paper segment led the market with the largest revenue share of 43.4% in 2025.Paper-based tapes are widely used in medical applications because they provide a good balance of strength, flexibility, and breathability.
Asia Pacific dominated the medical adhesive tapes market with the largest revenue share of 48.7% in 2025.
The global medical adhesive tapes market size was estimated at USD 10.3 billion in 2025 and is expected to reach USD 10.9 billion in 2026.
The global medical adhesive tapes market is expected to grow at a compound annual growth rate of 6.9% from 2026 to 2033, reaching USD 17.3 billion by 2033.
Some key players operating in the medical adhesive tapes include S3M, Avery Dennison Medical, Medline Industries, LP, Cardinal Health Inc., Flexcon Company, Inc., DermaMed Coatings Company, Mactac (Medical Products), CCT (Coating & Converting Technologies, LLC) (An ATP Group Company), DermaRite Industries, LLC, Lohmann & Rauscher GmbH & Co.KG, Paul Hartmann AG, Smith & Nephew PLC, Gergonne Industrie, Saint-Gobain S.A. (Medical), PPI Adhesive Products and Sterimed Group.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


