
- Home
- »
- Advanced Interior Materials
- »
-
Medical Devices Packaging Equipment Market Report, 2033GVR Report cover

Medical Devices Packaging Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Primary Packaging, Secondary Packaging, Vision Inspection Systems), By Application (Medical Implants, Surgical Instruments, Disposable Medical Devices), By Region, And Segment Forecasts
Market Size, 2025
$1.8BMarket Estimate, 2026
$1.9BMarket Forecast, 2033
$2.8BCAGR, 2026–2033
5.8%Medical Devices Packaging Equipment Market Summary
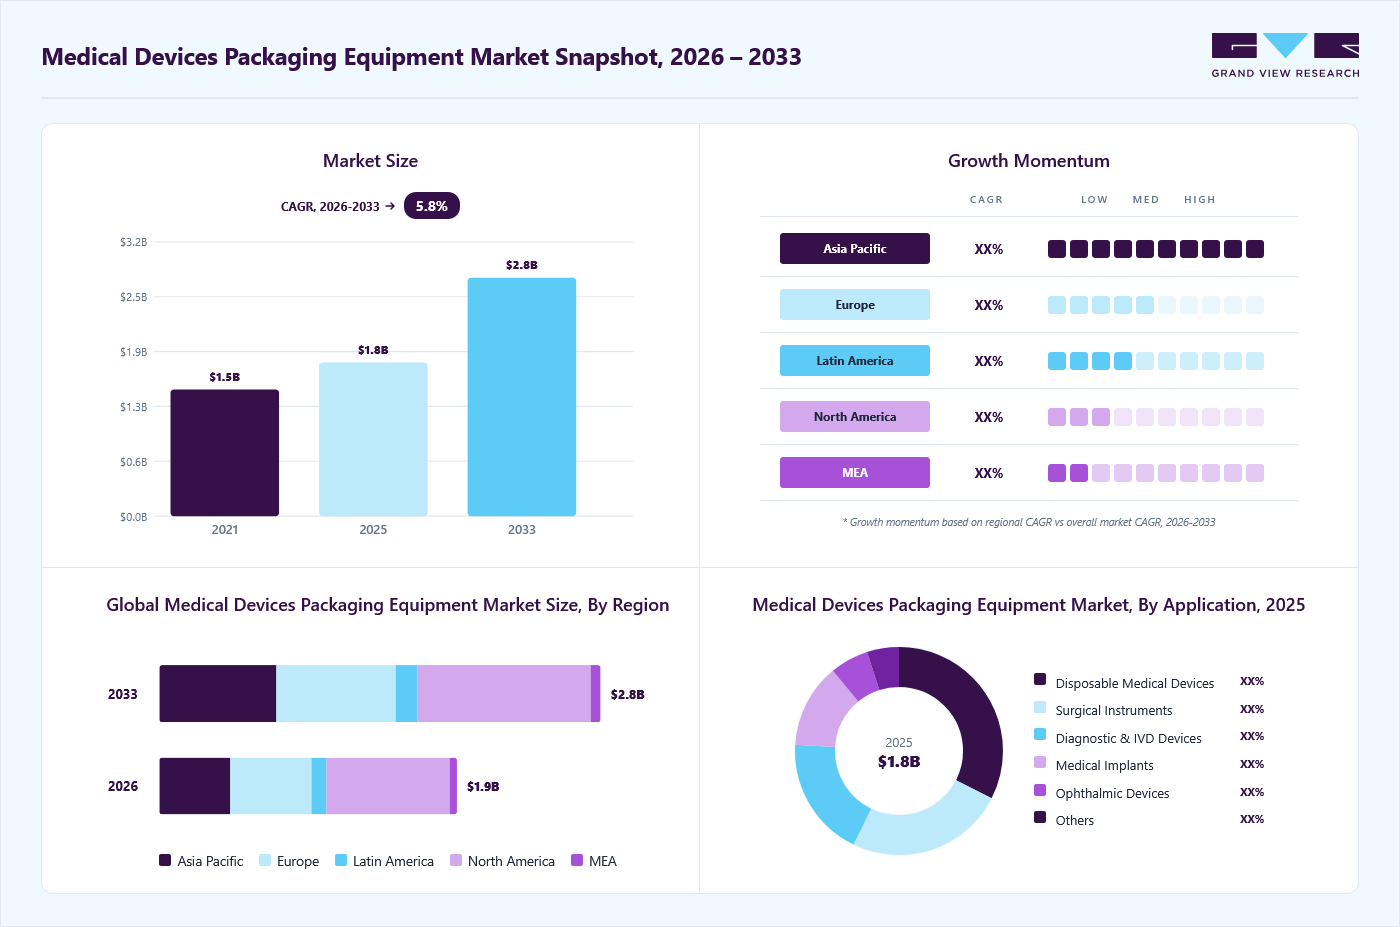
The global medical devices packaging equipment market size was valued at USD 1.8 billion in 2025 and is projected to grow from USD 1.9 billion in 2026 to USD 2.8 billion by 2033, at a CAGR of 5.8% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 41.2% in 2025. The market is driven by expanding medical device production and the growing requirement for sterile, reliable, and regulatory-compliant packaging solutions across medical and diagnostic applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Primary packaging equipment segment dominated the market with a revenue share of 55.7% in 2025.
- By application: Disposable medical devices segment dominated the market in 2025, holding 32.5% market share.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. market held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.8 Billion
- Estimated market size in 2026: USD 1.9 Billion
- Projected market size by 2033: USD 2.8 Billion
- CAGR (2026-2033): 5.8%
Prism AI by Grand View Research Free to tryAsk a question about the medical devices packaging equipment market✓Every figure cited from GVR research Prefer the report? Download free sample →
The growing adoption of single-use medical products, coupled with ongoing advancements in diagnostic, surgical, and implantable devices, has driven demand for packaging equipment capable of handling diverse product formats while maintaining product integrity and sterility. Stringent regulatory requirements for traceability and quality assurance are encouraging manufacturers to invest in high-speed packaging systems equipped with inspection, labeling, and serialization capabilities.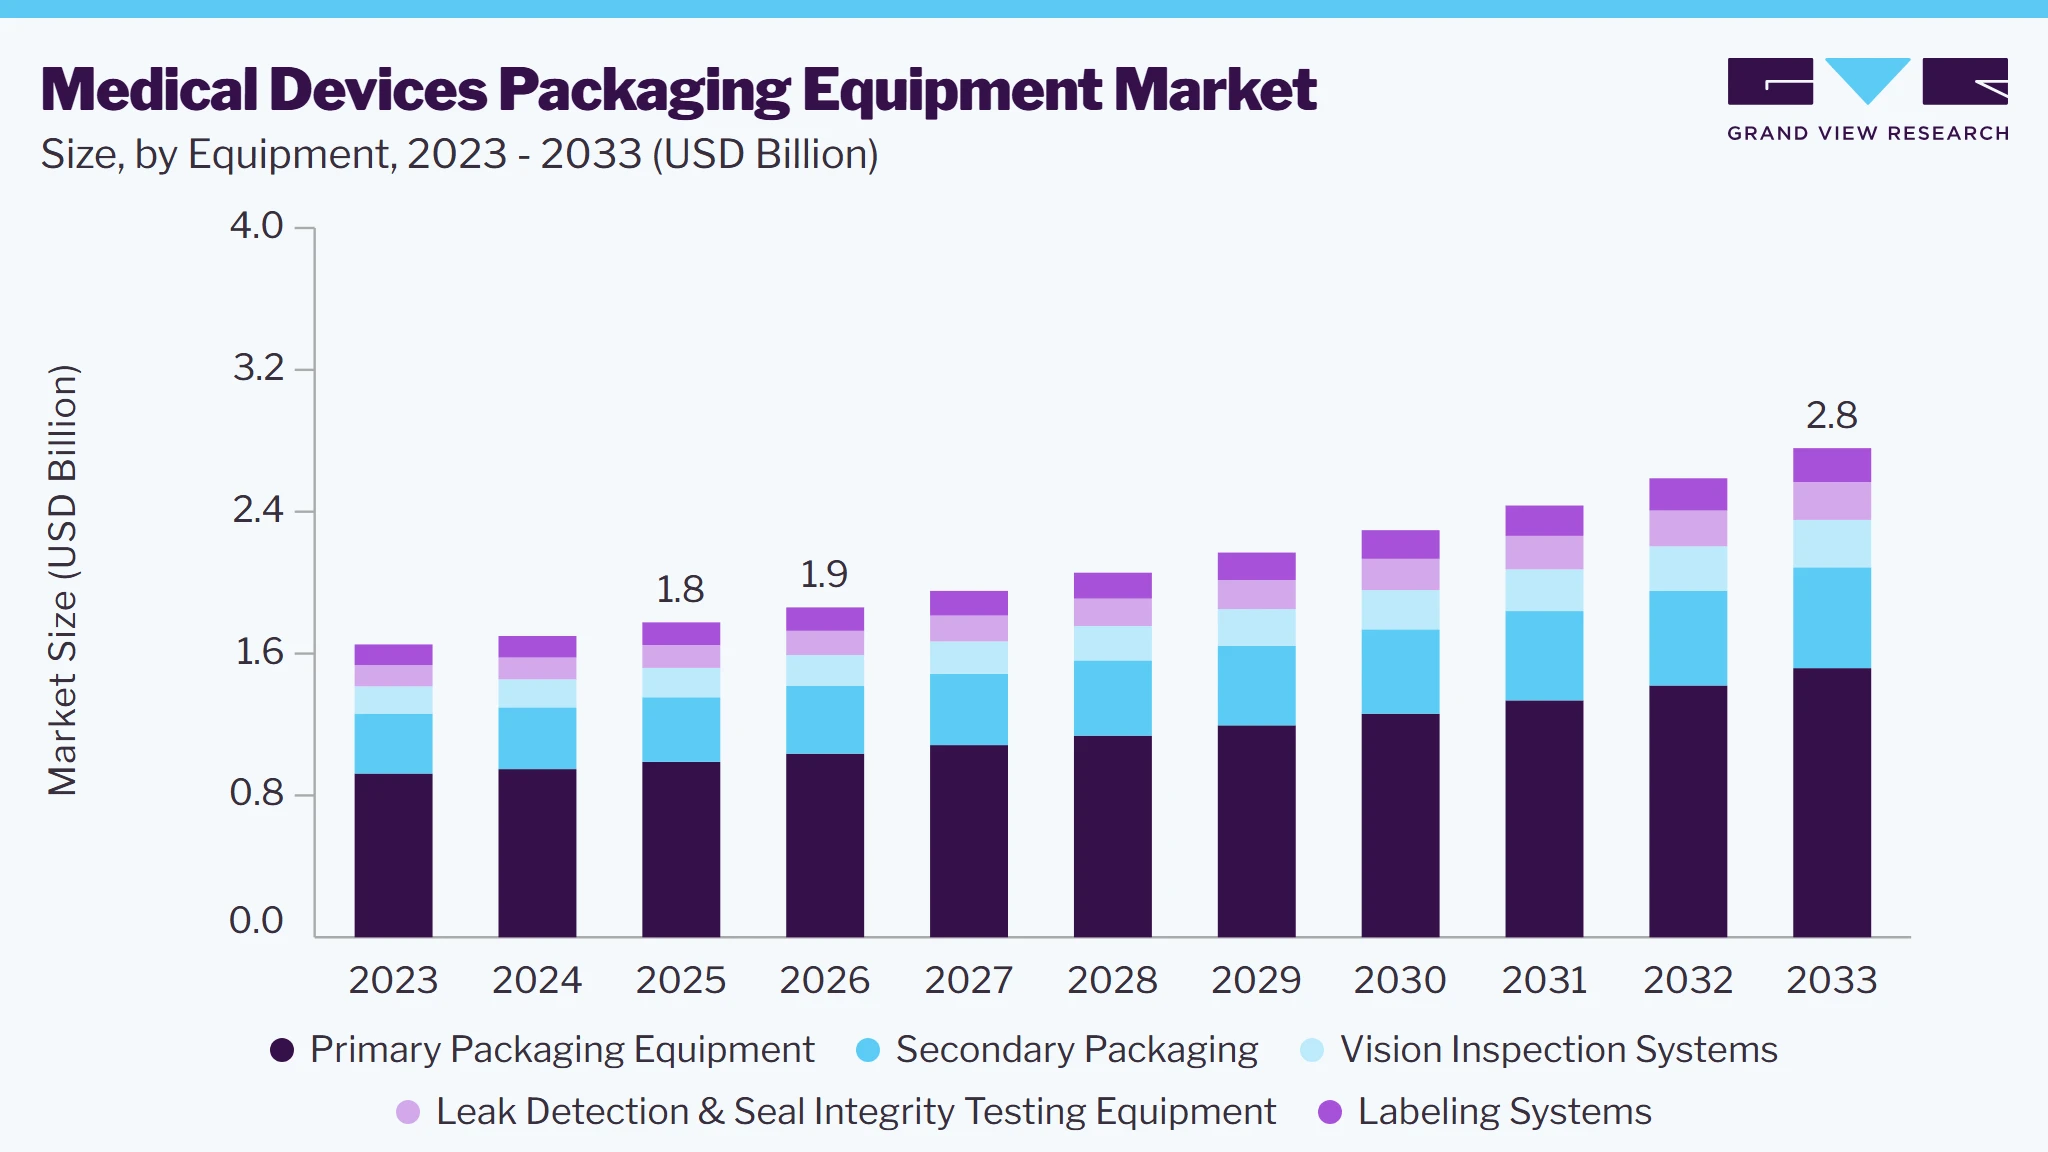 To learn more about this report, Download Free Sample Report
The expansion of contract manufacturing organizations (CMOs) serving medical device companies has further increased the adoption of versatile packaging equipment capable of accommodating multiple product configurations and production volumes. Growing demand for customized packaging solutions for implants, wearable medical devices, and combination products is prompting equipment manufacturers to develop flexible, modular systems. Digital integration, including real-time process monitoring and predictive maintenance capabilities, is improving equipment utilization and reducing production downtime.
Market Dynamics
The expanding production of medical devices across diagnostic, surgical, implantable, and single-use product categories is driving demand for advanced medical device packaging equipment worldwide. The growing emphasis on sterile barrier protection, product integrity, and regulatory compliance is encouraging manufacturers to invest in automated packaging systems that deliver consistent quality, minimize contamination risks, and improve production throughput. Increasing adoption of high-speed packaging lines integrated with inspection, labeling, and serialization technologies is further enhancing packaging accuracy and product traceability. Expanding contract manufacturing activities, increasing investments in medical device production facilities, and continued capacity expansion across established and emerging manufacturing hubs are further accelerating the deployment of advanced packaging equipment.
The high initial cost of medical device packaging equipment, along with the substantial investment required for installation, validation, and cleanroom integration, remains a significant challenge for manufacturers, particularly small and medium-sized enterprises. Compliance with stringent international regulations governing sterile packaging, equipment qualification, and process validation increases implementation complexity and extends procurement timelines. Frequent changes in packaging material specifications and evolving regulatory requirements may also necessitate equipment modifications and additional validation activities. Furthermore, the need for skilled personnel, ongoing maintenance, and integration with existing production lines can increase operational costs and slow equipment adoption, particularly in price-sensitive manufacturing environments.
Market Concentration & Characteristics
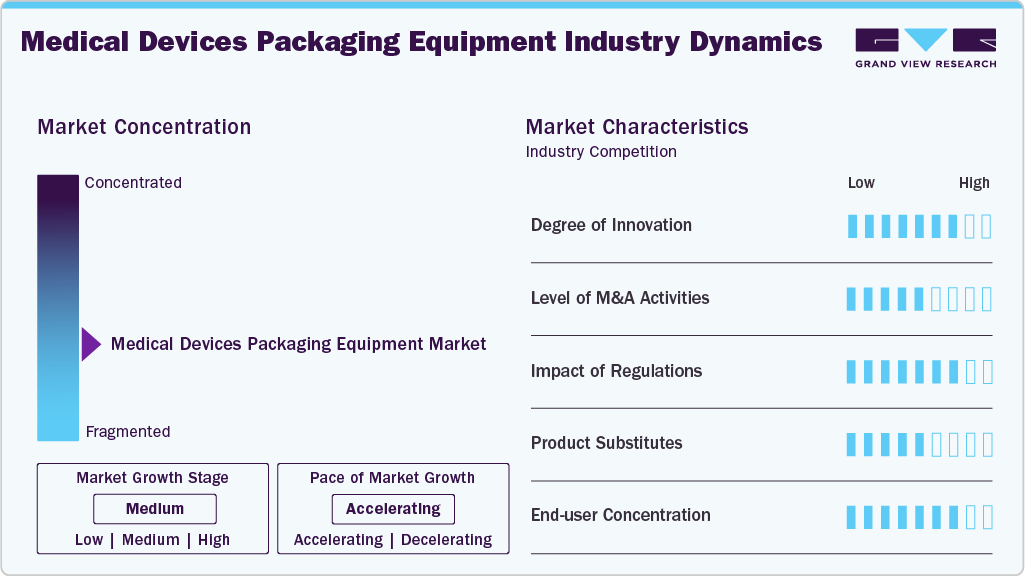
The global medical devices packaging equipment market exhibits a moderately consolidated industry structure, with a limited number of international manufacturers accounting for a significant share of global revenue, while numerous regional companies compete in specialized applications and local markets. Large participants benefit from broad product portfolios, global distribution networks, strong engineering capabilities, and long-standing relationships with medical device manufacturers, whereas regional suppliers compete through customization, shorter delivery timelines, and cost-effective solutions.
The industry is characterized by high technical and regulatory barriers to entry. Packaging equipment supplied to medical device manufacturers must comply with stringent quality standards, validation requirements, and cleanroom manufacturing practices, requiring substantial investments in engineering, testing, and regulatory documentation. Lengthy procurement and equipment qualification processes further strengthen customer retention and limit supplier switching, creating long-term business relationships.
 To learn more about this report, Download Free Sample Report
Competition is primarily based on equipment performance, production flexibility, lifecycle service capabilities, and compliance with international medical packaging standards rather than pricing alone. Companies increasingly differentiate themselves through integrated automation, modular system architecture, and comprehensive after-sales support to address evolving manufacturing requirements. Strategic collaborations, product innovation, and geographic expansion remain common approaches for strengthening market presence and expanding customer reach.
The market also demonstrates a high level of technological intensity, with continuous investments in precision engineering, digital process controls, and intelligent packaging solutions. As medical device production expands in emerging economies, both global and regional manufacturers are increasing manufacturing capacity, service infrastructure, and localized technical support, creating a competitive environment that balances technological leadership with application-specific expertise.
Analyst Perspective
The medical devices packaging equipment market is growing steadily as medical device manufacturers increasingly invest in advanced packaging solutions to ensure product sterility, regulatory compliance, and patient safety. Demand is supported by the rising production of surgical instruments, diagnostic devices, implantable devices, consumables, in-vitro diagnostics (IVD), and wearable medical devices, where reliable and contamination-free packaging is essential. The increasing adoption of automated packaging equipment enables manufacturers to improve production efficiency, reduce labor costs, maintain packaging consistency, and comply with stringent global regulatory standards. Growing demand for sterile barrier packaging, blister packaging, tray sealing, pouching, labeling, and serialization is further driving market expansion. Equipment manufacturers are investing in high-speed automation, vision inspection systems, digital monitoring, and sustainable packaging technologies to enhance operational efficiency and product quality.
Equipment Insights
The primary packaging equipment segment dominated the medical devices packaging equipment market with a revenue share of 55.7% in 2025. The segment's leadership stems from its essential role in directly packaging medical devices while maintaining sterility, product integrity, and regulatory compliance. The growing production of disposable medical devices, surgical instruments, diagnostic kits, and implantable products has increased demand for automated form-fill-seal machines, thermoforming equipment, blister packaging systems, pouch packaging machines, and tray-sealing solutions.
The leak detection & seal integrity testing equipment segment is projected to register the fastest CAGR during the forecast period. Increasing regulatory emphasis on package validation and the need to ensure sterile barrier integrity are encouraging wider adoption of advanced testing technologies. Medical device manufacturers are integrating automated vacuum decay, pressure decay, high-voltage leak detection, and non-destructive seal integrity testing systems into packaging lines to enhance quality control and minimize product recalls.
Application Insights
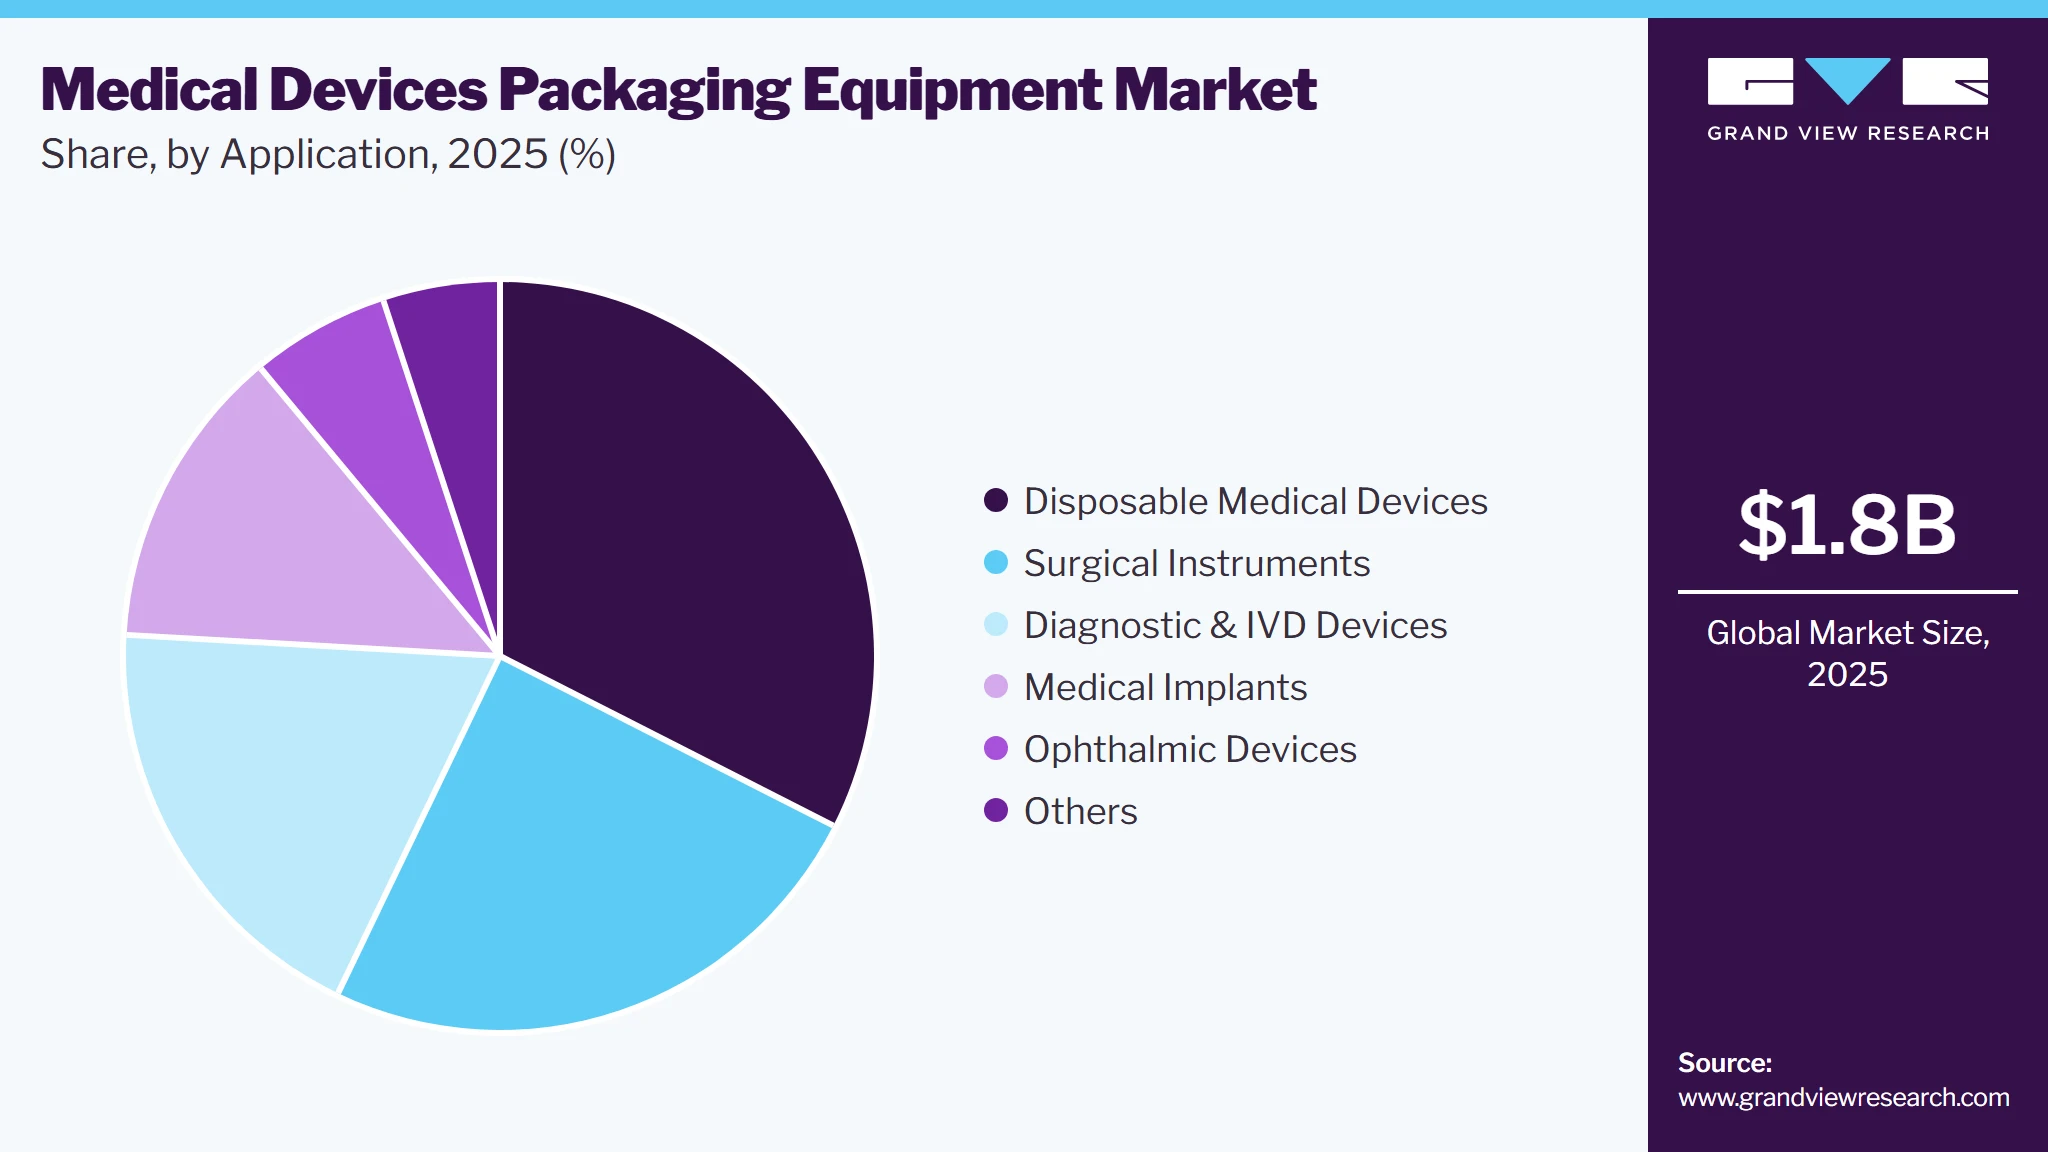
The disposable medical devices segment dominated the medical devices packaging equipment market in 2025, accounting for the largest revenue share at 32.5%. The segment's leadership is driven by the high-volume production of single-use medical products, including syringes, catheters, IV sets, gloves, gowns, and other infection prevention devices that require sterile, secure, and regulatory-compliant packaging. Increasing emphasis on infection control, growing healthcare utilization, and stringent packaging standards have encouraged manufacturers to invest in high-speed automated packaging equipment capable of maintaining product sterility, ensuring traceability, and supporting large-scale production.
 To learn more about this report, Download Free Sample Report
The diagnostic & IVD devices segment is projected to register the fastest CAGR of 6.6% during the forecast period. Growth is fueled by increasing demand for diagnostic testing, point-of-care testing devices, molecular diagnostics, and laboratory consumables, all of which require high-precision packaging solutions to preserve product integrity and extend shelf life. Expanding investments in diagnostic infrastructure, coupled with stringent quality standards for sterile and tamper-evident packaging, are accelerating the adoption of automated medical device packaging equipment for diagnostic and IVD applications.
Regional Insights
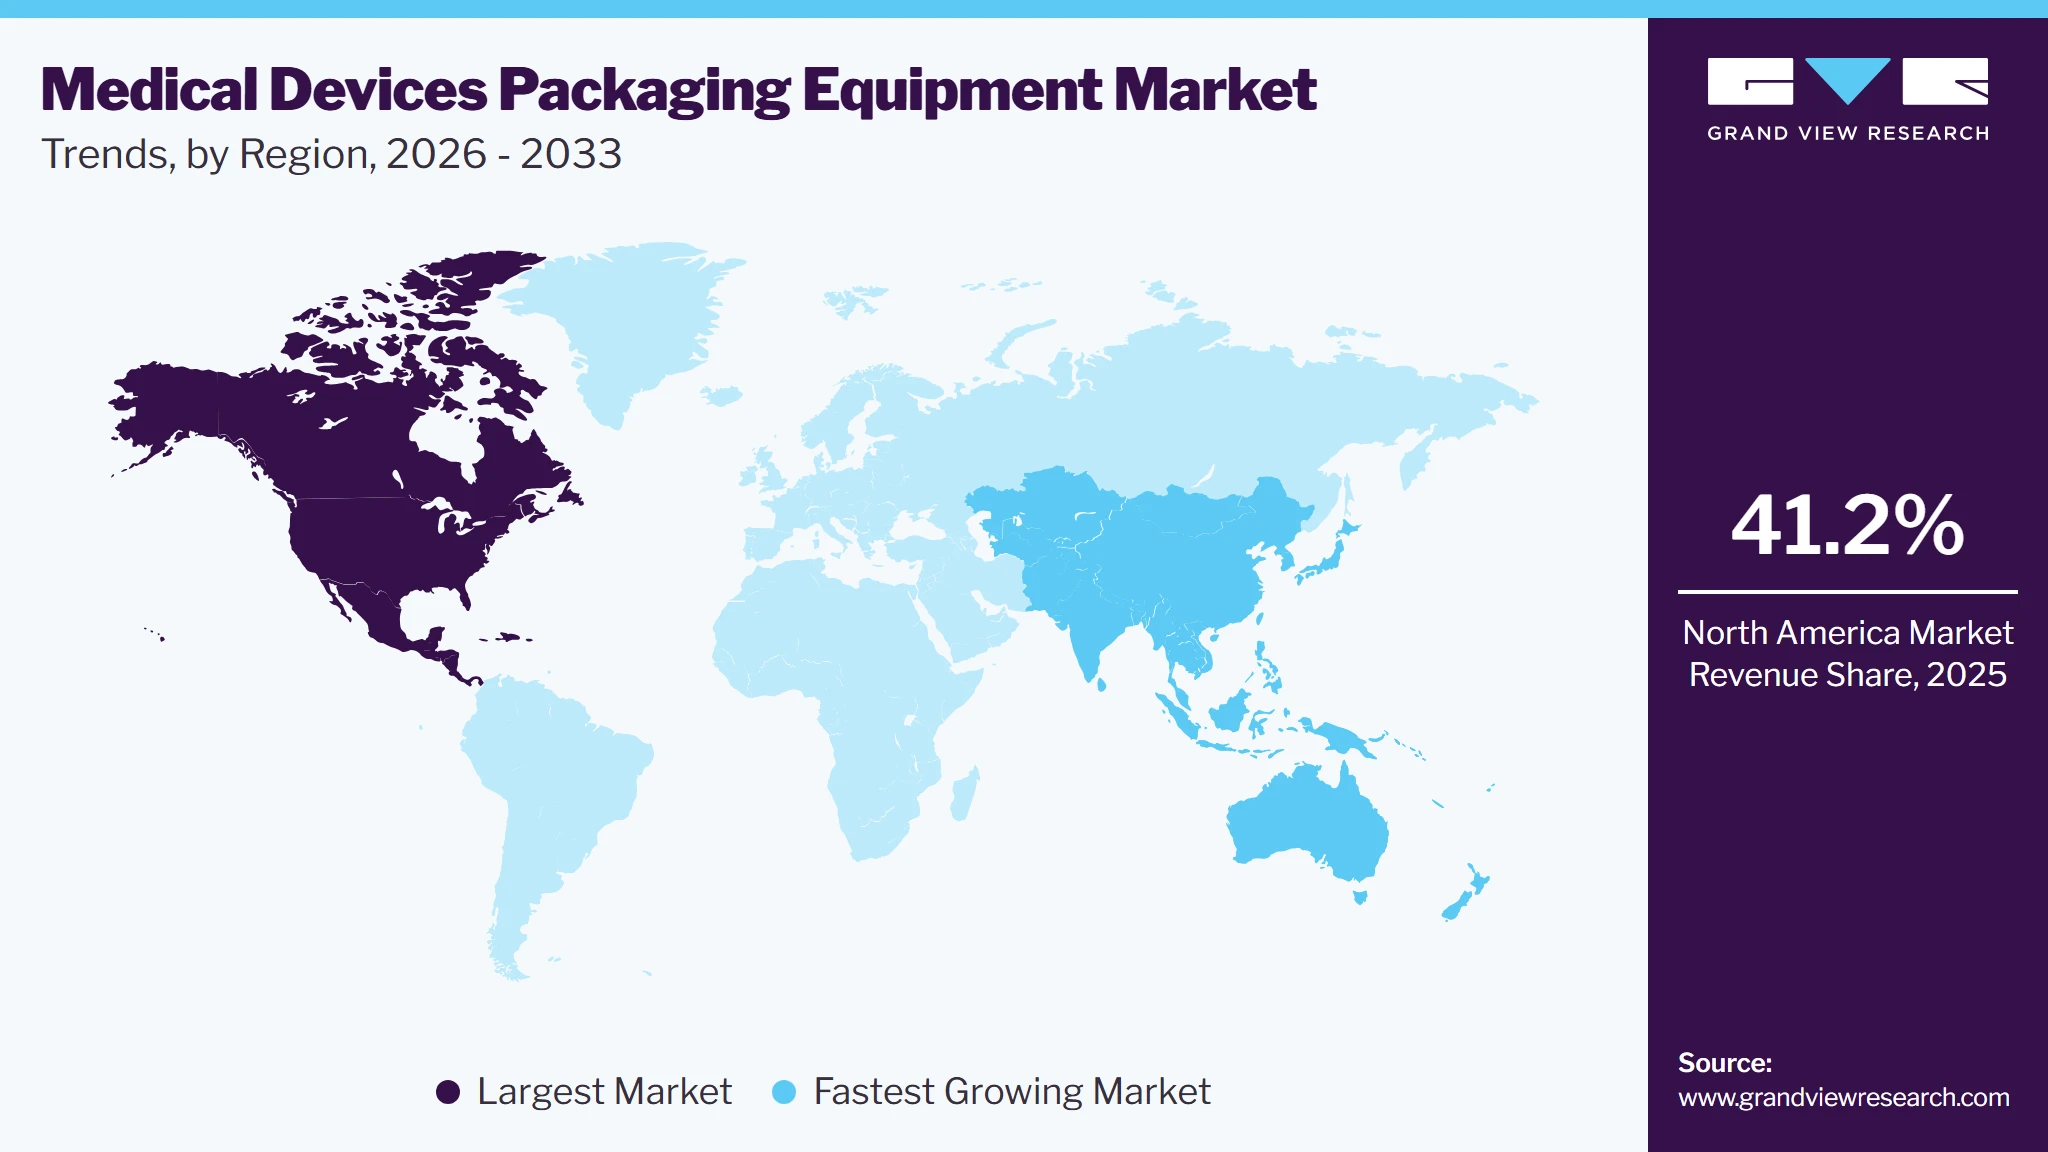
North America held a 41.2% share of the medical devices packaging equipment market in 2025, supported by its mature medical technology ecosystem and strong emphasis on product quality and patient safety. The region continues to invest in automated packaging infrastructure that delivers high throughput, precise sealing, and validated sterile barrier performance. Demand is further reinforced by increased production of high-value medical devices, expanded outsourcing among contract manufacturers, and greater adoption of intelligent packaging systems that support real-time monitoring, serialization, and traceability requirements.
 To learn more about this report, Download Free Sample Report
U.S. Medical Devices Packaging Equipment Market Trends
The medical devices packaging equipment market in the U.S. accounted for the largest share of the North American market. Its position is underpinned by an extensive base of medical device manufacturers and sustained investment in advanced manufacturing technologies. Packaging equipment demand is being shaped by greater use of robotic handling systems, vision-based inspection, and integrated validation processes that improve production consistency and meet stringent regulatory standards.
The Canada medical devices packaging equipment market is anticipated to record steady growth over the forecast period. Increasing domestic manufacturing capabilities, coupled with efforts to strengthen healthcare supply chains, are encouraging investments in modern packaging technologies. Manufacturers are adopting modular and scalable equipment to improve operational flexibility, reduce packaging errors, and support compliance with international quality standards.
Europe Medical Devices Packaging Equipment Market Trends
The medical devices packaging equipment market in Europe remained prominent in 2025, supported by ongoing innovation in medical technology manufacturing and a robust regulatory framework governing sterile packaging and product safety. Demand is being shaped by the increasing adoption of high-performance packaging systems that can handle complex device configurations, improve line efficiency, and support validated production environments. The region is also witnessing greater investment in digital process control, modular equipment platforms, and packaging solutions designed to reduce material consumption without compromising package performance.
The Germany medical devices packaging equipment market accounted for the largest share of the European market in 2025, reflecting its position as a major manufacturing hub for medical devices and industrial packaging machinery. Equipment demand is driven by the modernization of production facilities with fully integrated packaging lines that combine forming, sealing, inspection, and labeling within a single automated workflow. Manufacturers are also emphasizing equipment flexibility to accommodate shorter production runs, customized device formats, and increasingly stringent validation protocols required for high-value medical products.
The medical devices packaging equipment market in France is anticipated to expand at a steady pace during the forecast period. Growth is supported by increasing investment in advanced manufacturing capabilities and the expansion of domestic production for diagnostic, surgical, and single-use medical products. Packaging equipment procurement is increasingly focused on compact, adaptable systems that improve production efficiency, minimize downtime, and support rapid product changeovers. Greater attention to environmentally responsible manufacturing practices is also encouraging the adoption of energy-efficient equipment and packaging technologies that support recyclable, reduced-material packaging formats.
Asia Pacific Medical Devices Packaging Equipment Market Trends
The medical devices packaging equipment market in the Asia Pacific is projected to register the fastest growth during the forecast period. The expansion of medical device manufacturing, the increase in contract manufacturing activities, and the strengthening of healthcare infrastructure are creating sustained demand for advanced packaging systems across the region. Manufacturers are investing in automated, scalable equipment to increase production capacity, maintain consistent packaging quality, and comply with international sterilization and packaging standards.
The China medical devices packaging equipment market accounted for the largest share of the Asia Pacific market, supported by its extensive medical device manufacturing base and continuous expansion of production capacity. Manufacturers are increasingly deploying high-speed packaging equipment to enhance operational efficiency and meet growing domestic and export demand. Investments in intelligent manufacturing, integrated quality inspection, and automated packaging lines are enabling higher production throughput while supporting compliance with evolving international packaging and regulatory requirements.
The medical devices packaging equipment market in India is expected to witness robust growth during the forecast period. Increasing domestic production of medical devices, the expansion of manufacturing facilities, and government initiatives to strengthen local manufacturing capabilities are contributing to demand for equipment. Companies are adopting modern packaging technologies to improve product quality, reduce manual intervention, and achieve greater production flexibility.
Middle East & Africa Medical Devices Packaging Equipment Market Trends
The medical devices packaging equipment market in the Middle East & Africa is anticipated to grow steadily during the forecast period, supported by expanding healthcare manufacturing capabilities and increasing investments in localized medical device production. Demand for advanced packaging equipment is strengthening as manufacturers prioritize sterile barrier systems, automated packaging workflows, and compliance with international quality standards.
The Saudi Arabia medical devices packaging equipment market is witnessing sustained growth as the country continues to strengthen its domestic medical device manufacturing ecosystem under ongoing industrial diversification initiatives. Investments in new production facilities are creating demand for high-performance primary packaging equipment that supports sterile packaging, process validation, and automated quality inspection. The increasing production of disposable medical products, diagnostic devices, and surgical consumables, along with the adoption of digitally integrated manufacturing systems, is driving the modernization of medical device packaging operations in the country.
Latin America Medical Devices Packaging Equipment Market Trends
The medical devices packaging equipment market in Latin America is projected to grow steadily during the forecast period, supported by increasing investments in healthcare manufacturing, expanding production of medical consumables, and the gradual modernization of packaging operations. Manufacturers are adopting automated primary packaging equipment to improve sterility assurance, production efficiency, and compliance with international quality standards while reducing operational costs.
The Brazil medical devices packaging equipment market is benefiting from the expansion of domestic medical device manufacturing and continued investments in healthcare production infrastructure. Companies are upgrading packaging facilities with automated forming, sealing, labeling, and inspection systems to improve product quality, enhance manufacturing efficiency, and support regulatory compliance.
Key Medical Devices Packaging Equipment Company Insights
Some of the key players operating in the market include MULTIVAC Group, Syntegon Technology GmbH, OPTIMA packaging group GmbH, ULMA Packaging, and Fuji Machinery Co., Ltd.
-
MULTIVAC Group is a Germany-based global manufacturer of packaging and automation solutions serving the healthcare, pharmaceutical, food, and industrial sectors. For the medical device packaging equipment market, the company manufactures thermoforming packaging machines, tray sealers, chamber machines, labeling systems, inspection equipment, and complete automated packaging lines for sterile medical products. Its growth is driven by increasing demand for sterile barrier packaging, stricter regulatory requirements, and the adoption of automated packaging solutions that improve product safety and production efficiency.
-
Syntegon Technology GmbH is a Germany-based provider of processing and packaging technologies for the pharmaceutical, medical technology, and food industries. The company manufactures thermoforming machines, blister packaging systems, sealing equipment, inspection systems, cartoners, and integrated packaging lines for medical devices. Its growth is driven by expanding medical device production, increasing demand for sterile packaging, and greater adoption of automated and digitally integrated packaging technologies to ensure regulatory compliance and operational efficiency.
Key Medical Devices Packaging Equipment Companies:
The following key companies have been profiled for this study on the medical devices packaging equipment market:
-
MULTIVAC Group
-
Syntegon Technology GmbH
-
OPTIMA packaging group GmbH
-
IMA Group
-
ULMA Packaging
-
Uhlmann Pac-Systeme GmbH & Co. KG
-
Körber Pharma
-
Hawo GmbH
-
SencorpWhite, Inc.
-
Marchesini Group S.p.A.
-
ProMach Inc.
-
Fuji Machinery Co., Ltd.
-
Omori Machinery Co., Ltd.
-
TECNIMODERN AUTOMATION
-
Cama Group S.p.A.
Company categorization
Operating strategies
Competitive Edge
Weakness
Mature Players: MULTIVAC Group, Syntegon Technology GmbH, OPTIMA packaging group GmbH, IMA Group, Uhlmann Pac-Systeme GmbH & Co. KG
- Focus on advanced automated packaging equipment, continuous product innovation, and long-term supply agreements with pharmaceutical and medical device manufacturers.
- Invest in smart packaging technologies, integrated packaging lines, inspection systems, serialization, and global service expansion through acquisitions and strategic partnerships.
- Extensive product portfolios covering thermoforming, blister packaging, pouch packaging, tray sealing, labeling, inspection, and end-of-line automation.
- Strong global distribution networks, regulatory compliance expertise, validated packaging solutions, and long-standing customer relationships enhance competitive positioning.
- High capital investment in manufacturing, R&D, and compliance increases operational costs.
- Large organizational structures and complex global operations can reduce flexibility in addressing niche customer requirements and rapidly evolving packaging technologies.
Emerging Players: ALFA LAVAL, Hawo GmbH, SencorpWhite, Inc., TECNIMODERN AUTOMATION, Cama Group S.p.A.
- Focus on customized packaging equipment, flexible automation solutions, and specialized systems for sterile medical devices, diagnostics, and healthcare products.
- Strengthen regional presence through customer-specific engineering, partnerships with medical device manufacturers, and application-focused product development.
- Greater flexibility in delivering customized packaging solutions and faster adaptation to customer-specific production requirements.
- Specialized engineering expertise and shorter product development cycles enable rapid response to evolving packaging applications.
- Limited global distribution and after-sales service infrastructure can restrict expansion into large multinational projects.
- Narrower product portfolios and lower manufacturing scale may reduce competitiveness against established global packaging equipment suppliers.
Recent Developments
-
In October 2025, Shawpak launched its new LT Range of linear thermoforming machines designed specifically for medical device packaging applications. The new machinery range features cleanroom-compatible construction, modular automation, precision thermoforming, and support for robotic integration to package a wide variety of sterile medical devices. The launch expands Shawpak's portfolio of dedicated medical packaging equipment, enabling manufacturers to improve production efficiency, packaging consistency, and compliance with stringent healthcare quality and regulatory standards.
-
In August 2024, MULTIVAC Group acquired an 80% stake in Italianpack S.p.A. to strengthen its medical-device packaging equipment portfolio. The acquisition expands the company's capabilities in tray sealing, filling, denesting, and lid placement systems used for sterile medical device packaging while broadening its portfolio of automated packaging solutions. This strategic move enhances MULTIVAC's global market presence and enables it to better meet the growing demand for advanced, efficient medical device packaging equipment.
Global Medical Devices Packaging Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.8 billion
Estimated market size in 2026
USD 1.9 billion
Projected market size by 2033
USD 2.8 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, application, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Turkey; Benelux; China; Japan; India; Thailand; Indonesia; Malaysia; Vietnam; Philippines; Mexico; Brazil; UAE; Saudi Arabia; Egypt
Key companies profiled
MULTIVAC Group; Syntegon Technology GmbH; OPTIMA packaging group GmbH; IMA Group; ULMA Packaging; Uhlmann Pac-Systeme GmbH & Co. KG; Körber Pharma; Hawo GmbH; SencorpWhite, Inc.; Marchesini Group S.p.A.; ProMach Inc.; Fuji Machinery Co., Ltd.; Omori Machinery Co., Ltd.; TECNIMODERN AUTOMATION; Cama Group S.p.A.
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Devices Packaging Equipment Market Report Segmentation
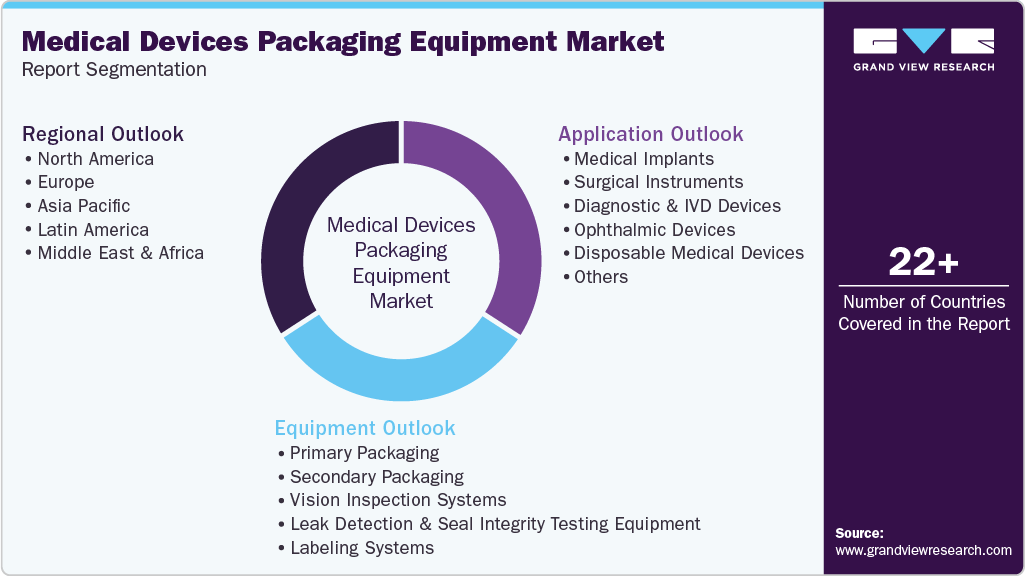
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global medical devices packaging equipment market report based on equipment, application, and region.
 To learn more about this report, Download Free Sample Report
-
Equipment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Primary Packaging
-
Vacuum Forming (Thermoforming) Machines
-
Vacuum Chamber Packaging Machines
-
Blister Packaging Machines (for medical devices)
-
Tray Sealing Machines
-
Medical Heat Sealers / Pouch Sealing Machines
-
-
Secondary Packaging
-
Cartooning Machines
-
Case Packing Machines
-
-
Vision Inspection Systems
-
Leak Detection & Seal Integrity Testing Equipment
-
Labeling Systems
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Medical Implants
-
Surgical Instruments
-
Diagnostic & IVD Devices
-
Ophthalmic Devices
-
Disposable Medical Devices
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
Turkey
-
Benelux
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Thailand
-
Indonesia
-
Malaysia
-
Vietnam
-
Philippines
-
-
Latin America
-
Mexico
-
Brazil
-
-
Middle East and Africa
-
Egypt
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The medical devices packaging equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical devices packaging equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Equipment Type
Revenue Capture Definition
Primary Packaging Equipment
Revenue is generated from the sale of primary medical device packaging equipment, including thermoforming machines, pouch sealing systems, tray sealing machines, form-fill-seal systems, integrated automation modules, replacement components, installation, commissioning, and aftermarket services supplied for sterile barrier packaging of medical devices.
Secondary Packaging Equipment
Revenue is generated from the sale of secondary packaging equipment, including cartoning machines, case packing systems, overwrapping equipment, palletizing systems, integrated conveying solutions, replacement components, installation, and lifecycle services supplied for packaged medical devices.
Vision Inspection Systems
Revenue is generated from the sale of machine vision inspection systems, optical inspection equipment, barcode and UDI verification systems, integrated quality inspection solutions, software, replacement components, installation, and maintenance services used for medical device packaging quality assurance.
Leak Detection & Seal Integrity Testing Equipment
Revenue is generated from the sale of leak detection systems, seal integrity testing equipment, vacuum decay testers, pressure decay systems, high-voltage leak detection equipment, integrated testing solutions, replacement components, calibration, and technical support services supplied for sterile package validation.
Segment - Application
Revenue Capture Definition
Medical Implants
Revenue is generated from the sale of medical device packaging equipment used for sterile packaging of orthopedic, cardiovascular, dental, and spinal implants, as well as other implantable medical devices, including primary packaging, inspection, leak testing, and labeling systems.
Surgical Instruments
Revenue is generated from the sale of packaging equipment supplied for the sterile packaging of reusable and single-use surgical instruments, including pouch- and tray-sealing, labeling, inspection, and seal-integrity testing systems.
Diagnostic & IVD Devices
Revenue is generated from the sale of packaging equipment supplied for diagnostic instruments, in-vitro diagnostic (IVD) kits, test cartridges, sample collection devices, and laboratory consumables, including primary packaging, secondary packaging, labeling, and inspection solutions.
Ophthalmic Devices
Revenue is generated from the sale of packaging equipment supplied for ophthalmic surgical devices, contact lens products, intraocular lenses, and vision care products, including sterile packaging, leak testing, labeling, and automated inspection systems.
Disposable Medical Devices
Revenue is generated from the sale of packaging equipment supplied for disposable medical devices, including syringes, catheters, IV sets, wound care products, gloves, and other single-use products, covering primary packaging, secondary packaging, labeling, vision inspection, and seal integrity testing equipment.
Others
Revenue is generated from the sale of packaging equipment supplied for respiratory devices, dialysis products, drug delivery devices, patient monitoring accessories, medical electronics, rehabilitation devices, and other specialty medical products, as well as integrated packaging, inspection, labeling, and testing solutions.
Estimation Model
Layer Name
Key Question
Description
Medical Device Packaging Demand Layer
Where is medical device packaging equipment required?
Analyze demand across medical device manufacturing segments, including surgical instruments, diagnostic devices, implantable devices, consumables, catheters, wound care products, in-vitro diagnostics (IVD), and wearable medical devices. Assess requirements for sterile barrier packaging, labeling, sealing, pouching, blister packaging, and tray packaging to establish the addressable demand for medical device packaging equipment.
Medical Device Manufacturing Infrastructure Layer
Where is demand for new equipment being created?
Evaluate investments in medical device manufacturing facilities, cleanroom expansions, contract manufacturing organizations (CMOs), packaging line automation, and facility modernization. Assess greenfield projects, production capacity expansions, regulatory compliance upgrades, and replacement of aging packaging equipment that drive procurement of new medical device packaging systems.
Product Adoption Layer
Which packaging equipment technologies are being deployed?
Segment demand by equipment type, automation level, packaging format, and end-use application. Apply adoption rates based on production volume, sterility requirements, packaging material compatibility, throughput, traceability, and regulatory compliance. Assess the increasing adoption of automated thermoforming, tray sealing, pouch sealing, blister packaging, labeling, serialization, and vision inspection systems across medical device manufacturing.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of medical device packaging equipment by equipment type, automation level, packaging format, end-use application, and region. Quantify revenues generated exclusively from the sale of new medical device packaging equipment supplied to medical device manufacturers, contract packaging companies, and OEMs. The scope excludes installation, maintenance, consumables, packaging materials, spare parts, software upgrades, rental equipment, and aftermarket service revenues.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
A region-wise demand assessment was conducted for the global medical devices packaging equipment market, with a focus on major medical device manufacturing hubs. The analysis evaluated the adoption of packaging equipment, manufacturing capacity expansion, automation investments, and regulatory compliance across key countries and regions.
The assessment helped the client identify high-growth regional markets, evaluate equipment demand trends, and prioritize expansion opportunities across medical device manufacturing locations.
Competitive Benchmarking
A comparative assessment of leading manufacturers was conducted across product portfolio, packaging technology, automation capabilities, global presence, strategic initiatives, and after-sales service in the medical devices packaging equipment market.
The benchmarking enabled the client to evaluate competitive positioning, technology capabilities, and supplier strengths while supporting partnership and investment decisions.
Opportunity Assessment
An opportunity analysis was conducted to evaluate demand for automated packaging lines, thermoforming, blister packaging, pouch packaging, inspection systems, and serialization equipment across medical device manufacturing applications.
The analysis helped the client identify high-growth equipment segments, evaluate emerging automation trends, and support long-term product development and market expansion strategies.
Frequently Asked Questions About This Report
The global medical devices packaging equipment market size was valued at USD 1.8 billion in 2025 and is expected to be USD 1.9 billion in 2026.
Key factors driving the global medical devices packaging equipment market include increasing production of medical devices, stringent regulatory requirements for sterile and compliant packaging, and growing demand for single-use and infection prevention products. Rising investments in healthcare infrastructure, automation of packaging operations, and the adoption of advanced packaging technologies are further supporting market growth.
Primary Packaging Equipment accounted for the largest share of 55.7% in 2025, while leak detection & seal integrity testing equipment is the fastest-growing segment.
Disposable Medical Devices accounted for the largest share of 32.5% in 2025, while diagnostic & IVD devices segment is fastest growing application.
Asia Pacific is the fastest-growing region over the forecast period.
The global medical devices packaging equipment market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 2.8 billion by 2033.
North America held a 41.2% share of the market in 2025.
Some of the key players operating in the global medical devices packaging equipment market include MULTIVAC Group, Syntegon Technology GmbH, OPTIMA packaging group GmbH, IMA Group, ULMA Packaging, Uhlmann Pac-Systeme GmbH & Co. KG, Körber Pharma, Hawo GmbH, SencorpWhite, Inc., Marchesini Group S.p.A., ProMach Inc., Fuji Machinery Co., Ltd., Omori Machinery Co., Ltd., TECNIMODERN AUTOMATION, and Cama Group S.p.A.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


