
- Home
- »
- Micro Molding & Microspheres
- »
-
Medical Injection Molding Machine Market Report, 2026-2033GVR Report cover

Medical Injection Molding Machine Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Plastics, Metal), By System (Hot Runner, Cold Runner), By Product Type (Hydraulic, Electric, Hybrid), By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$3.1BCAGR, 2026–2033
5.4%Medical Injection Molding Machine Market Summary
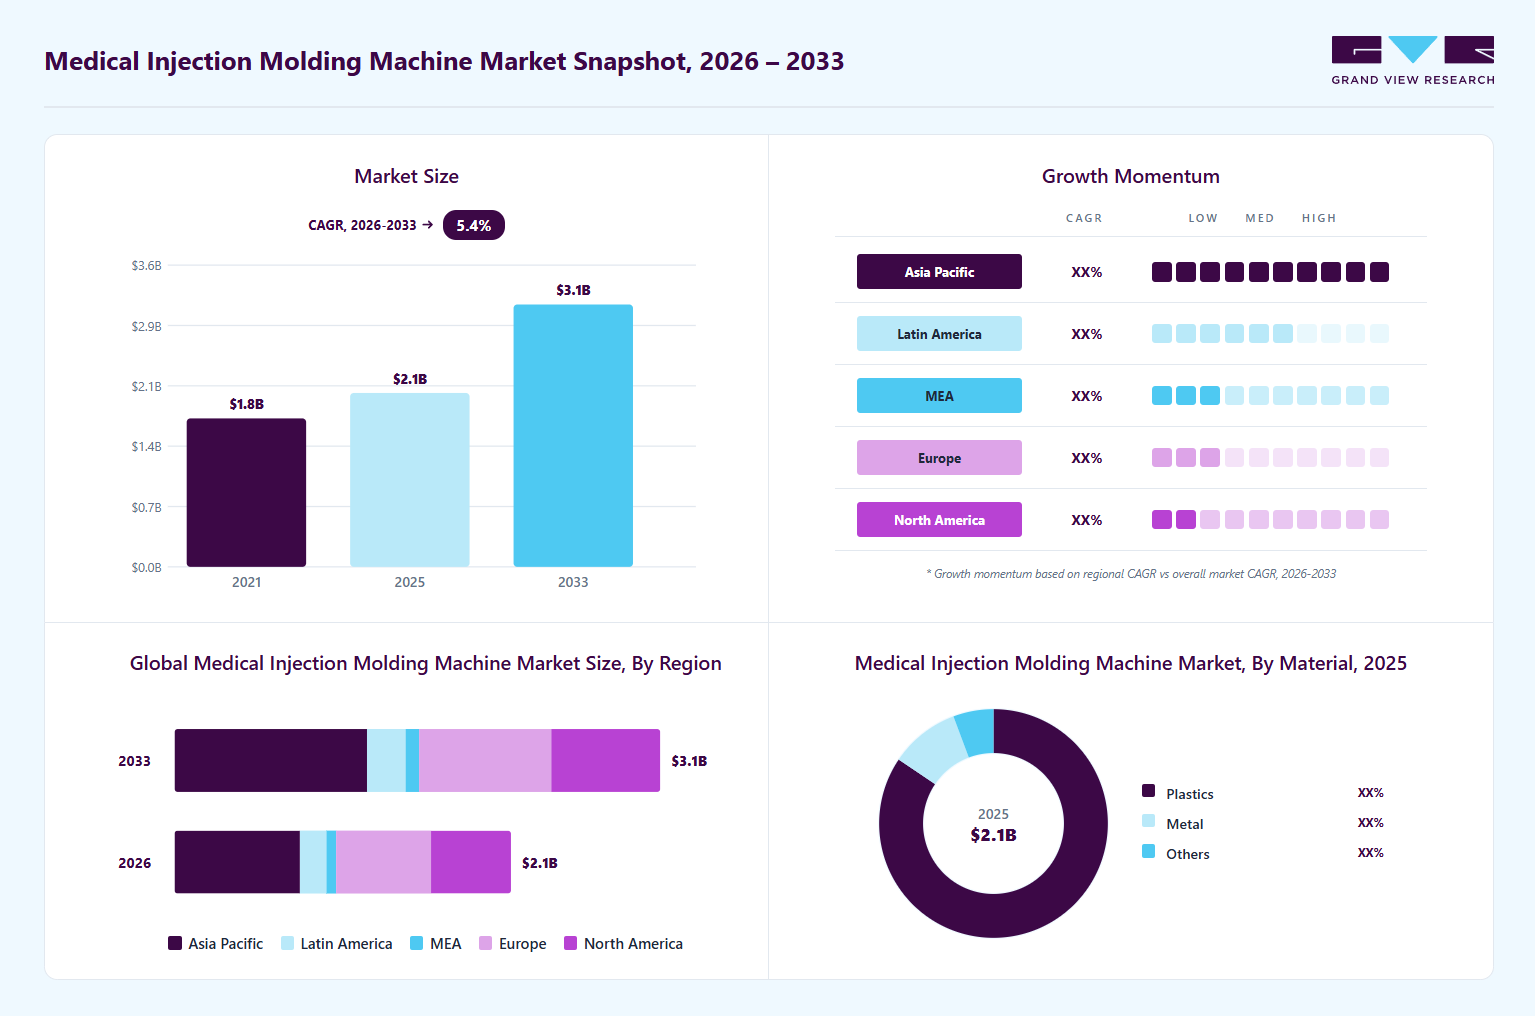
The global medical injection molding machine market size was estimated at USD 2.1 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 3.1 billion by 2033, growing at a CAGR of 5.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 37.1% in 2025. The increasing production of precision medical components, including syringes, catheters, and diagnostic parts, drives the market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Electric segment led the market with the largest revenue share of 46.3% in 2025
- By system: Hot runner segment led the market with the largest revenue share of 57.6% in 2025.
- By material: Plastics segment led the market with the largest revenue share of 84.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.1% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.1 Billion
- Projected market size by 2033: USD 3.1 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the medical injection molding machine marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Increasing demand for high-volume, contamination-free manufacturing is pushing hospitals and OEMs toward automated molding systems. The growth of minimally invasive procedures also boosts the need for complex, micro-molded parts.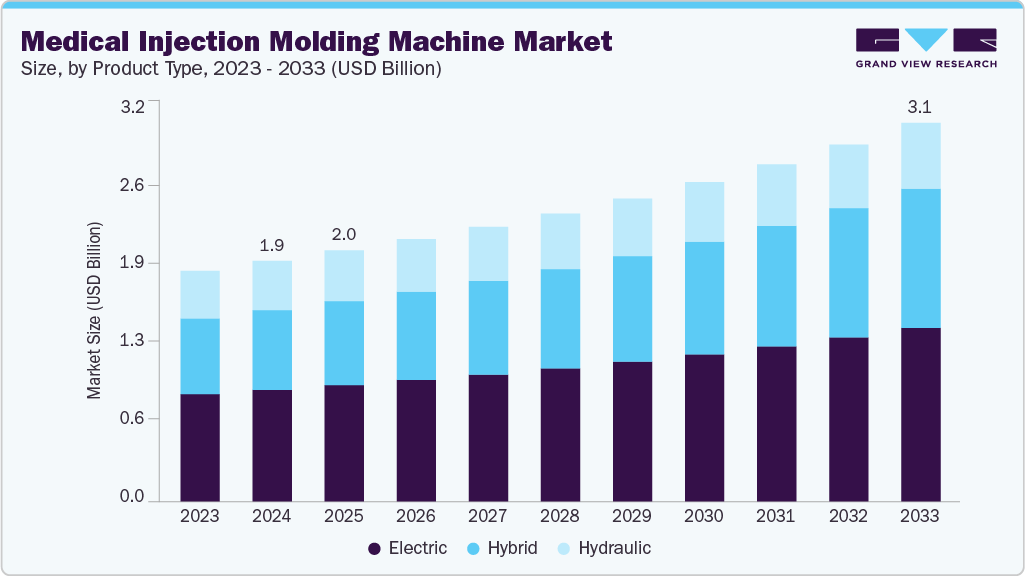 To learn more about this report, Download Free Sample Report
Stringent regulatory standards for medical device safety are encouraging manufacturers to invest in machines that offer consistency and repeatability. Technological advancements such as all-electric molding systems improve energy efficiency and reduce operational costs. The rising preference for medical-grade plastics further elevates demand for specialized molding equipment. Additionally, expanding healthcare infrastructure in emerging markets fuels steady upgrades to equipment.
Market Dynamics
The medical injection molding machine market is experiencing steady growth due to the increasing production of medical devices, rising demand for disposable healthcare products, and advancements in precision manufacturing technologies. The expansion of healthcare infrastructure, growing prevalence of chronic diseases, and increasing emphasis on infection prevention have accelerated the need for high-volume production of medical components. Additionally, manufacturers are investing in automation, cleanroom-compatible equipment, and energy-efficient molding systems to meet stringent regulatory requirements while improving operational efficiency and product quality.
The growing consumption of medical devices and single-use healthcare products is a major factor driving demand for medical injection molding machines. Products such as syringes, catheters, diagnostic kits, inhalers, IV components, and drug delivery systems require high-precision manufacturing processes capable of producing large volumes with consistent quality. The increasing number of surgical procedures, vaccination programs, and diagnostic testing activities worldwide continues to boost production requirements across the healthcare sector.
Furthermore, healthcare providers and regulatory agencies are emphasizing patient safety and infection control, encouraging the use of disposable medical products. This trend has prompted manufacturers to expand production capacities and adopt advanced injection molding technologies that offer faster cycle times, improved precision, and compliance with stringent medical standards, thereby supporting market growth.
The medical injection molding machine market faces challenges associated with substantial capital investment and strict regulatory standards. Advanced electric and hybrid molding machines, automation systems, cleanroom integration, and quality control technologies require significant upfront expenditure. Additionally, manufacturers must comply with rigorous medical device regulations and validation processes, which can increase operational complexity, prolong implementation timelines, and create barriers for small and medium-sized enterprises seeking to enter or expand within the market.
The integration of Industry 4.0 technologies, automation, and intelligent process monitoring systems presents a significant opportunity for the medical injection molding machine market. Manufacturers are increasingly adopting connected machines, real-time quality monitoring, predictive maintenance, and data-driven production management to improve efficiency and minimize defects. These capabilities enable consistent production of highly precise medical components while reducing operational costs.
Market Concentration & Characteristics
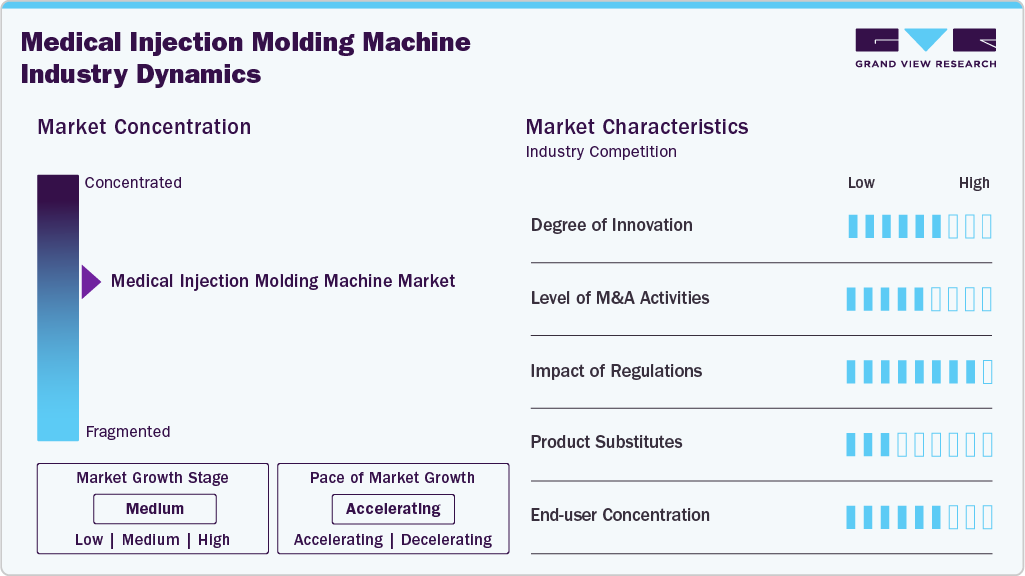
The medical injection molding machine market remains moderately concentrated, with a few global players dominating high-precision and high-capacity segments. Leading manufacturers benefit from strong technological capabilities, regulatory expertise, and long-term supply relationships with top medical device companies. However, smaller regional producers continue to compete in niche applications such as low-volume specialty components. This blend of dominant innovators and emerging specialists keeps the market balanced but competitive, creating opportunities for innovation while maintaining pressure on pricing and quality standards.
The need for extreme precision, micro-molding capability, and contamination-free production shapes innovation in the medical injection molding machine industry. Manufacturers are increasingly integrating all-electric systems, real-time quality monitoring, and automation to support the production of complex medical components. Advanced materials and digital process controls are accelerating design flexibility and production consistency. As healthcare demands evolve, innovation remains a core competitive lever for machine vendors.
 To learn more about this report, Download Free Sample Report
Regulation fundamentally drives equipment design, validation protocols, and manufacturing workflows in medical molding. Stringent standards for biocompatibility, sterility, and traceability require investment in machines that ensure consistent, verifiable output. Meeting FDA, EU MDR, and ISO directives demands high-accuracy, low-defect systems, making equipment quality a direct outcome of regulatory pressure. This intensifies entry barriers for new manufacturers.
End-user concentration is influenced by the dominance of large medical device manufacturers that rely on high-volume, automated molding solutions. These major buyers often secure long-term partnerships, creating stable but highly competitive supplier dynamics. Smaller clinics and specialty device producers contribute additional demand but represent a lower share of machine purchases. This concentration around leading OEMs strengthens pricing discipline and drives continuous performance upgrades from machine suppliers.
Analyst Perspective
The medical injection molding machine market is positioned for sustained growth, supported by rising global demand for medical devices, diagnostic equipment, and disposable healthcare products. Increasing regulatory emphasis on product quality, precision, and contamination control is driving manufacturers toward advanced electric and hybrid molding technologies that offer superior accuracy and cleanroom compatibility. At the same time, automation, digital monitoring, and Industry 4.0 integration are becoming critical differentiators as medical manufacturers seek greater production efficiency and traceability. While high capital investment and stringent compliance requirements remain challenges, continued innovation in energy-efficient machinery, miniaturized component production, and smart manufacturing solutions is expected to create significant opportunities for market participants over the forecast period.
System Insights
Based on system, hot runner segment led the market with the largest revenue share of 57.6% in 2025. This can be attributed to their ability to deliver consistent melt flow and minimize material waste. They support high-speed, multi-cavity production, which is crucial for large-volume medical consumables such as syringes and IV components. Their superior precision and reduced cycle times make them ideal for meeting the strict standards of healthcare manufacturing. As medical OEMs pursue efficiency and repeatability, hot runners remain the preferred system choice.
Cold runner segment is expected to grow at a significant CAGR of 4.1% from 2025 to 2033 in terms of revenue. The cold runner systems segment is experiencing significant growth as smaller manufacturers and specialty device producers opt for cost-effective molding solutions. Their simpler design reduces upfront equipment investment, making them attractive for low- to medium-production volumes. Cold runners also offer flexibility for frequent material changes, which benefits companies that produce a diverse range of medical components. This balanced cost-performance profile is driving steady adoption across emerging and mid-sized healthcare markets.
Product Type Insights
Based on product type, electric segment led the market with the largest revenue share of 46.3% in 2025, due to their high precision, clean operation, and superior energy efficiency. They are ideal for producing contamination-sensitive components used in diagnostics and drug-delivery systems. Consistent clamp control and repeatable accuracy support strict regulatory compliance in medical manufacturing. These advantages make electric machines the preferred choice for large-scale, high-precision production.
The hybrid machines segment is expected to grow at the fastest CAGR of 5.8% over the forecast period. Hybrid machines combine the power of hydraulics with the efficiency of electric drives. This balance supports complex medical components that require both force and precision. Their reduced energy consumption and improved cycle flexibility attract mid-to-large-scale manufacturers. The growing demand for cost-effective yet high-performance systems is accelerating the adoption of hybrids.
Material Insights
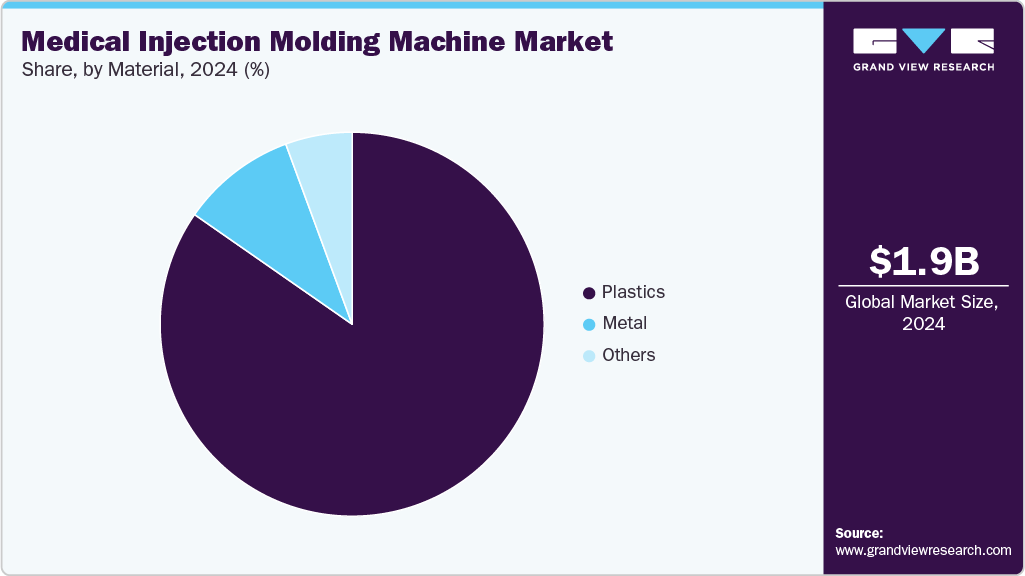
Based on material, plastics segment led the market with the largest revenue share of 84.4% in 2025, primarily due to their versatility, biocompatibility, and capacity for mass production. This dominance is further supported by rising demand for disposable devices, which has accelerated the use of plastic-molded components in hospitals and diagnostic centers. Additionally, the lightweight, sterile, and economical qualities of plastics make them essential for syringes, housings, and various types of drug-delivery products. As manufacturers continue to emphasize efficiency and safety, plastics remain the preferred material for many applications.
 To learn more about this report, Download Free Sample Report
The metal segment is expected to grow at the fastest CAGR of 6.3% over the forecast period, driven by rising demand for durable, high-strength components in surgical and orthopedic devices. Precision metal molding enables the creation of complex geometries and tight tolerances required in critical medical applications. Advancements in metal injection molding technology are improving cost efficiency and production scalability. This momentum is accelerating adoption among manufacturers seeking robust, performance-centric medical parts.
Regional Insights
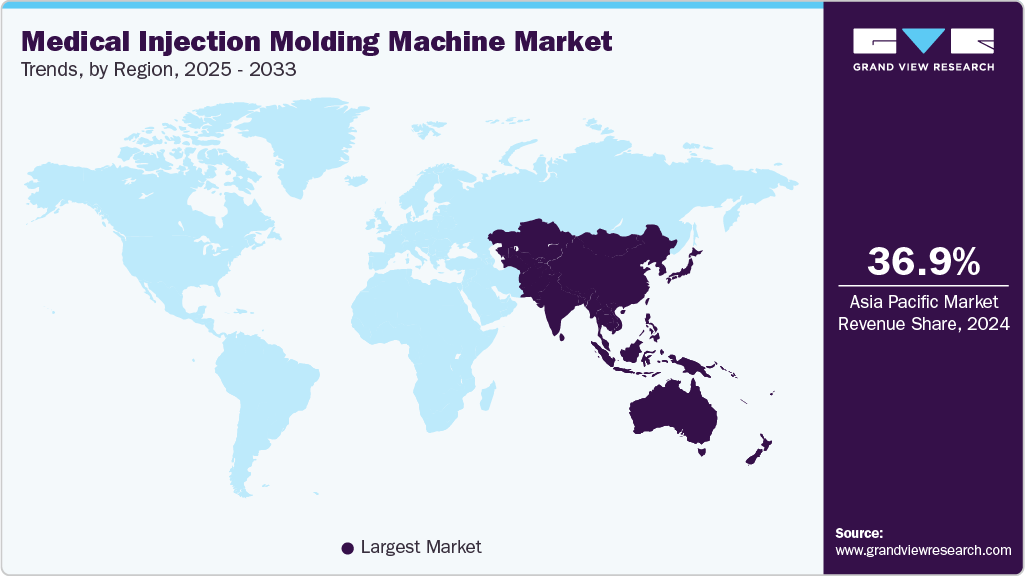
Asia Pacific dominated the medical injection molding machine market with the largest revenue share of 37.1% in 2025, owing to strong medical device manufacturing bases in China, Japan, South Korea, and India. The region benefits from lower production costs, rapid industrialization, and increasing investment in automated molding technologies. The expansion of healthcare infrastructure drives high-volume demand for disposable medical components. Government initiatives supporting medical export capabilities further reinforce the region’s leadership.
 To learn more about this report, Download Free Sample Report
The medical injection molding machine market in China held the largest share in the Asia Pacific region in 2025, due to its massive medical device manufacturing ecosystem and large-scale adoption of automated injection molding systems. Strong government support for healthcare production and export competitiveness fuels continuous equipment upgrades. High-volume demand for syringes, diagnostic consumables, and device housings drives significant machine utilization. Rapid advancements in smart manufacturing further solidify China’s leading position.
The medical injection molding machine market in India is experiencing rapid growth as local medical device production expands under initiatives promoting domestic manufacturing and reducing imports. Rising demand for affordable medical consumables encourages investment in efficient, mid-range molding machines. Improvements in healthcare infrastructure are widening opportunities for precision-molded diagnostic and patient-care product types. Increasing interest from global OEMs in Indian manufacturing partnerships strengthens the country’s upward market trajectory.
North America Medical Injection Molding Machine Market Trends
The North America medical injection molding machine market is growing steadily at a CAGR of 4.2%, as medical OEMs adopt advanced, energy-efficient injection molding machines to meet strict regulatory standards. The region’s focus on high-precision surgical and diagnostic devices drives demand for sophisticated molding capabilities. Strong R&D ecosystems encourage the adoption of all-electric and automated machine systems. Increasing preference for domestically manufactured medical product types also supports market expansion.
U.S. Medical Injection Molding Machine Market Trends
The U.S. dominates the North America medical injection molding machine industry due to its large medical device manufacturing base and strong adoption of high-precision molding technologies. Strict FDA regulations drive demand for machines that ensure consistent, validated production quality. Major OEMs are investing in automation and all-electric systems to improve output efficiency. Continued innovation in diagnostics, wearables, and minimally invasive devices further strengthens U.S. leadership.
The Canada medical injection molding machine market is growing steadily as its healthcare manufacturing ecosystem expands to support the rising demand for domestically produced medical components. Government incentives for advanced manufacturing are increasing investments in modern molding equipment. The country’s focus on high-quality medical consumables and specialty devices drives the adoption of precise, energy-efficient systems. Enhanced cross-border supply partnerships with U.S. manufacturers also support Canada’s market growth.
Europe Medical Injection Molding Machine Market Trends
The Europe medical injection molding machine industry is experiencing notable growth, driven by technological innovation and strong compliance with stringent healthcare regulations. Manufacturers prioritize high-quality, contamination-controlled production, boosting demand for advanced molding systems. The region’s leadership in diagnostic and minimally invasive medical devices further fuels the adoption of equipment. Investments in sustainable and energy-efficient machine designs add momentum to market growth.
The Germany medical injection molding machine marketdominates Europe, due to its strong medical engineering capabilities and advanced manufacturing infrastructure. The country’s focus on precision molding for surgical instruments, diagnostic systems, and high-quality consumables drives demand for machines. German manufacturers adopt cutting-edge automation and digital monitoring to ensure regulatory compliance and production accuracy. Continuous investment in R&D and export-oriented device production further reinforces its leadership.
The medical injection molding machine market in France is experiencing steady growth as medical device producers expand their capacity to meet the rising domestic and EU healthcare needs. Increasing adoption of all-electric and energy-efficient molding systems supports the country’s sustainability goals and manufacturing standards. Demand for diagnostic and patient-care consumables boosts investment in mid-to-high precision molding equipment. Strengthening collaborations between research institutes and medical manufacturers accelerates market expansion in France.
Middle East & Africa Medical Injection Molding Machine Market Trends
The Middle East & Africa medical injection molding machine industry is witnessing gradual yet consistent growth, driven by the expansion of hospital networks and rising demand for essential medical supplies. Investments in localized manufacturing are encouraging the adoption of cost-effective molding systems. Governments are focusing on reducing healthcare import dependence and creating opportunities for regional production units. As healthcare modernization advances, the demand for reliable injection molding machines remains strong.
The Saudi Arabia medical injection molding machine market dominates Middle East & Africa, due to its strong investment in healthcare modernization and the expansion of local medical device manufacturing. Government-led initiatives to reduce import dependence are driving demand for advanced injection molding machines. High consumption of medical consumables across hospitals and diagnostic centers supports steady equipment deployment. Rising partnerships with global technology providers further strengthen the country’s leading regional position.
Central & South America Medical Injection Molding Machine Market Trends
The Central & South America market for medical injection molding machines is growing as countries like Brazil and Argentina expand local medical device production capabilities. Increasing government support for healthcare manufacturing attracts foreign investments in molding technologies. Rising demand for affordable medical consumables boosts installations of mid-range injection molding machines. Enhanced supply-chain integration with North American OEMs is also accelerating regional adoption.
The Brazil medical injection molding machine market dominates Central & South America, due to its expanding medical device production capacity and strong demand for essential healthcare consumables. Growing investments in modern manufacturing facilities are accelerating the adoption of efficient injection molding machines. The country’s large healthcare network drives a consistent need for high-volume molded components. Supportive industrial policies and rising collaborations with global medical manufacturers further reinforce Brazil’s leadership.
Key Medical Injection Molding Machine Company Insights
Some of the key players operating in the market include Arburg GmbH + Co KG, Haitian International Holdings Limited, and Milacron.
-
Arburg is recognized for its highly precise injection molding systems designed for regulated medical manufacturing environments. The company emphasizes repeatability and process control for producing micro and high-tolerance medical components. Its machines support clean-room production and are widely used for syringes, diagnostics, and pharmaceutical packaging. Arburg integrates advanced digital control systems to monitor molding stability and reduce defects. Strong focus on automation and smart manufacturing strengthens its position in high-end medical molding applications.
-
Haitian International focuses on high-efficiency injection molding machines that support large-scale production of medical consumables. The company offers cost-optimized systems that strike a balance between speed, precision, and energy efficiency. Its equipment is widely adopted for the mass production of disposable medical products and basic device components. Haitian continues to expand its technological capabilities with servo-driven and hybrid machine platforms. This combination of scalability and affordability drives its strong presence in volume-focused medical manufacturing.
Key Medical Injection Molding Machine Companies:
The following key companies have been profiled for this study on the medical injection molding machine market.
-
Arburg GmbH + Co KG
-
Haitian International Holdings Limited
-
Milacron
-
Nissei Plastic Industrial Co., Limited.
-
Engel Austria GmbH
-
Sumitomo (SHI) Demag Plastics Machinery GmbH
-
Chen Hsong Holdings Limited
-
Toyo Machinery & Metal Co., Ltd
-
Husky Injection Molding Systems Ltd
-
Japan Steel Works Limited
-
KraussMaffei Group
-
UBE Machinery
-
Shibaura Machine Co. Ltd.
-
Wittmann Battenfeld
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Arburg GmbH + Co KG, Engel Austria GmbH, Haitian International Holdings Limited, Husky Injection Molding Systems Ltd, KraussMaffei Group, Sumitomo (SHI) Demag Plastics Machinery GmbH, Milacron)
- Focus on developing high-precision electric and hybrid injection molding machines tailored for regulated medical manufacturing environments.
- Expand digital manufacturing capabilities through automation, smart monitoring, and integrated production management solutions.
- Strong global customer base, extensive service networks, and established relationships with leading medical device manufacturers.
- Significant investment in R&D enables continuous innovation in machine accuracy, energy efficiency, and cleanroom-compatible operations.
- Premium pricing can limit adoption among small and medium-sized medical product manufacturers.
- Dependence on mature markets may result in slower growth compared to competitors targeting emerging economies.
Emerging & Regional Players (e.g., Chen Hsong Holdings Limited, Shibaura Machine Co. Ltd., Toyo Machinery & Metal Co., Ltd, UBE Machinery, Wittmann Battenfeld)
- Strengthen market penetration through competitively priced equipment and localized sales and support operations.
- Enhance product portfolios by incorporating automation features and improving machine performance for medical applications.
- Cost-effective solutions attract manufacturers seeking lower capital investment while maintaining production efficiency.
- Greater flexibility in addressing regional customer requirements and adapting to changing market demands.
- Comparatively lower global brand visibility and market recognition in highly regulated medical sectors.
- Limited international service infrastructure may affect large-scale project execution and after-sales support capabilities.
Recent Developments
-
In September 2025, Arburg introduced an advanced digital production cell tailored for medical technology applications. The system combines automated process control with intelligent monitoring to improve production accuracy and consistency. Its flexible design supports rapid adjustments for complex medical components and varying output needs. This development highlights Arburg’s commitment to intelligent, automated solutions for regulated medical manufacturing.
-
In September 2025, ENGEL demonstrated a virtual showcase of its advanced injection molding system to highlight smart manufacturing capabilities for precision medical production. The presentation emphasized high-accuracy molding suitable for complex medical components, as well as integrated process control technologies. This initiative reflects ENGEL’s commitment to driving innovation in automated, high-performance molding solutions for regulated healthcare applications.
-
In October 2024, Milacron introduced a new all-electric injection molding machine built for advanced manufacturing needs, including medical device production. This machine focuses on minimizing energy consumption, improving cycle consistency, and reducing maintenance demands. Its design aims to deliver higher precision and cleaner operations for molded medical components. By offering this technology, Milacron responds to rising demand for efficient, high-performance molding solutions in regulated industries.
Medical Injection Molding Machine Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.1 billion
Projected market size by 2033
USD 3.1 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, system, product type, region.
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Arburg GmbH + Co KG; Haitian International Holdings Limited; Milacron; Nissei Plastic Industrial Co., Limited; Engel Austria GmbH; Sumitomo (SHI) Demag Plastics Machinery GmbH; Chen Hsong Holdings Limited; Toyo Machinery & Metal Co., Ltd; Husky Injection Molding Systems Ltd; Japan Steel Works Limited; KraussMaffei Group; UBE Machinery; Shibaura Machine Co. Ltd.; Wittmann Battenfeld.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Injection Molding Machine Market Report Segmentation
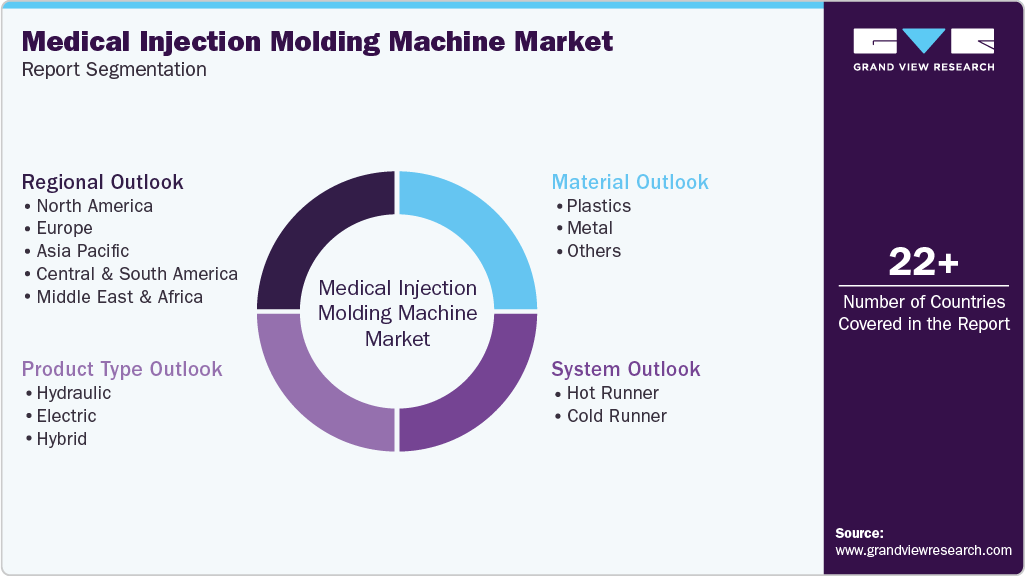
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical injection molding machine market report based on material,system, product type, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Plastics
-
Metal
-
Others
-
-
System Outlook (Revenue, USD Million, 2021 - 2033)
-
Hot Runner
-
Cold Runner
-
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hydraulic
-
Electric
-
Hybrid
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The medical injection molding machine market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical injection molding machine segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product Type
Revenue Capture Definition
Hydraulic
Revenue is captured through sale of hydraulic injection molding machines used for manufacturing a broad range of medical components requiring high clamping force and reliable performance. Market value is influenced by demand from manufacturers producing larger or technically demanding medical products.
Electric
Revenue is generated from sale of electric injection molding machines that offer high precision, energy efficiency, and cleanroom compatibility for medical device production. This segment benefits from increasing investments in advanced manufacturing technologies and stringent quality requirements within the healthcare industry.
Hybrid
Revenue is derived from sale of hybrid injection molding machines that combine hydraulic power with electric precision to optimize productivity and operational efficiency. Market growth is supported by manufacturers seeking a balance between performance, energy savings, and production flexibility in medical applications.
System
Revenue Capture Definition
Hot Runner
Revenue is derived from the sale of injection molding machines equipped with hot runner systems that enhance material utilization, reduce waste, and support high-volume medical manufacturing. Market earnings are influenced by demand for efficient production processes and superior product consistency.
Cold Runner
Revenue is generated from molding systems utilizing cold runner technology for medical component production. Demand is primarily linked to applications requiring lower tooling investment, material flexibility, and cost-effective manufacturing for specialized or lower-volume production runs.
Material
Revenue Capture Definition
Plastics
Revenue is generated from the sale and deployment of injection molding machines used for processing medical-grade plastics in the production of syringes, diagnostic devices, drug delivery components, laboratory consumables, and disposable medical products. Market value capture is influenced by production volumes, machine precision requirements, and demand for high-throughput manufacturing.
Metal
Revenue is captured through machines utilized for manufacturing metal-based medical components, including surgical instruments, implant parts, orthodontic devices, and precision healthcare equipment. Growth is supported by increasing adoption of complex and high-strength metal components in advanced medical applications.
Others
This segment captures revenue from molding systems designed for specialized materials such as silicone, elastomers, ceramics, and bio-compatible composites. Revenue expansion is driven by emerging healthcare applications requiring unique material properties and customized medical product designs.
Estimation Model
Layer Name
Key Question
Description
Medical Device Manufacturing Demand Analysis
What is the demand potential for injection molding machines from the medical device industry?
Market estimation begins by assessing global and regional demand for medical devices, disposable healthcare products, diagnostic components, drug delivery systems, and laboratory consumables that require injection molding manufacturing processes.
Technology & Product Adoption Assessment
Which machine technologies and product types are witnessing the highest adoption?
Evaluates adoption across hydraulic, electric, and hybrid machines, along with hot runner and cold runner systems, based on production efficiency, precision requirements, cleanroom compatibility, and automation trends within medical manufacturing facilities.
Revenue Mapping by Material and End-Use Applications
How is revenue distributed across materials and medical applications?
Analyzes machine demand associated with plastics, metal, and other materials used in medical production and maps revenues across key application areas such as consumables, surgical products, diagnostics, and medical equipment components.
Market Size Validation & Competitive Benchmarking
What is the validated market value and growth outlook?
Final market estimates are validated through manufacturer revenues, production capacity trends, and competitive benchmarking of leading market participants operating in the medical injection molding machine industry.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Comprehensive Assessment of the Market Across Material, System, and Product Type Segments
Delivered a detailed market analysis covering Plastics, Metal, and Other materials; Hot Runner and Cold Runner systems; and Hydraulic, Electric, and Hybrid machine categories. The study included segment-level revenue assessment, growth trends, adoption patterns, and demand outlook across medical manufacturing applications globally.
Enabled stakeholders to identify the most attractive revenue-generating segments, evaluate technology adoption trends, and prioritize investment opportunities based on evolving healthcare manufacturing requirements.
Competitive Landscape and Market Participant Evaluation
Provided an in-depth evaluation of leading manufacturers and regional competitors, including market positioning, strategic initiatives, product innovation focus, operational strengths, and competitive benchmarking. The analysis assessed the role of established multinational suppliers and emerging regional participants in shaping industry dynamics.
Offered a clear understanding of competitive intensity, market concentration, and strategic differentiation, supporting partnership evaluation, supplier selection, and competitive intelligence activities.
Strategic Market Outlook and Future Growth Opportunities
Delivered a forward-looking assessment of market drivers, restraints, opportunities, technology advancements, automation trends, cleanroom manufacturing requirements, and regulatory influences impacting future market development. The report also highlighted emerging demand areas and evolving customer requirements across the medical device manufacturing ecosystem.
Assisted decision-makers in developing long-term growth strategies, identifying high-potential investment areas, mitigating business risks, and aligning product development initiatives with anticipated market evolution.
Frequently Asked Questions About This Report
The global medical injection molding machine market, in terms of revenue, is expected to grow at a compound annual growth rate of 5.4% from 2026 to 2033 to reach USD 3.1 billion by 2033.
Asia Pacific dominated the medical injection molding machine market with the largest revenue share of 37.1% in 2025.
Some of the key players operating in the global medical injection molding machine market include Arburg GmbH + Co KG; Haitian International Holdings Limited; Milacron; Nissei Plastic Industrial Co., Limited; Engel Austria GmbH; Sumitomo (SHI) Demag Plastics Machinery GmbH; Chen Hsong Holdings Limited; Toyo Machinery & Metal Co., Ltd; Husky Injection Molding Systems Ltd; Japan Steel Works Limited; KraussMaffei Group; UBE Machinery; Shibaura Machine Co. Ltd.; Wittmann Battenfeld.
Increasing consumption of plastics in healthcare applications, technological advancements and rising demand for medical disposable products are the major factors driving the growth of the market.
The global medical injection molding machine market size was valued at USD 2.1 billion in 2025 and is expected to remain at USD 2.1 billion in 2026.
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by expanding medical device manufacturing, increasing healthcare investments, and growing demand for high-precision molding solutions.
The electric segment led the market with the largest revenue share of 46.3% in 2025.
The plastics segment led the market with the largest revenue share of 84.4% in 2025.
The hot runner segment accounted for the largest revenue share of 57.6% in 2025.
About the Author(s)
Micro Molding & Microspheres Research Team
Advanced Materials · Micro Molding & MicrospheresThis report was authored by the micro molding & microspheres research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the micro molding & microspheres segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


