
- Home
- »
- Advanced Interior Materials
- »
-
Metal Casting Market Size And Share Report, 2026-2033GVR Report cover

Metal Casting Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Iron, Steel, Aluminum), By Application (Automotive & Transportation, Heavy Machinery &Tools, Energy & Power, Aerospace & Defense), By Region, And Segment Forecasts
Market Size, 2025
$225.2BMarket Estimate, 2026
$234.6BMarket Forecast, 2033
$347.5BCAGR, 2026–2033
5.8%Metal Casting Market Summary
The global metal casting market size was valued at USD 225.2 billion in 2025 and is projected to grow from USD 234.6 billion in 2026 to USD 347.5 billion by 2033, at a CAGR of 5.8% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 56.8% in 2025. The market is driven by growing vehicle production, particularly in electric and hybrid vehicles. The demand for lightweight, durable cast metal components such as engine blocks, chassis, and transmission housings has also surged.
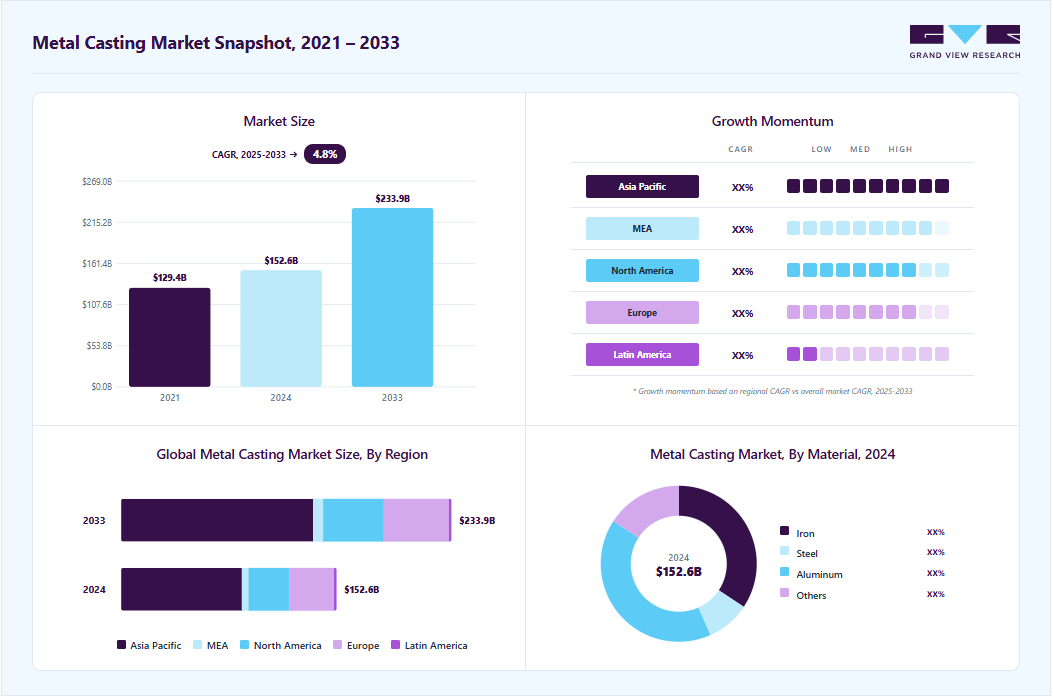 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Iron segment held the largest market share of 35.0% in 2025.
- By application: Automotive & transportation segment held the largest market share of 42.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (56.8% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 225.2 Billion
- Estimated market size in 2026: USD 234.6 Billion
- Projected market size by 2033: USD 347.5 Billion
- CAGR (2026-2033): 5.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Automakers are also shifting toward aluminum and magnesium castings to reduce vehicle weight, improve fuel efficiency, and meet emission regulations. Infrastructure and industrial development across emerging economies are other major drivers for the metal casting industry. In India, for instance, the government allocated over USD 130 billion in 2024 for infrastructure projects under the PM Gati Shakti plan, spurred demand for castings used in construction equipment, water distribution, and transportation systems. Similarly, in 2025, Saudi Arabia and the UAE ramped up investment in mega-projects such as NEOM and Etihad Rail, which required massive volumes of ductile iron and steel castings. Such large-scale infrastructure activities fuel demand for ferrous and non-ferrous cast products across construction, utilities, and public transportation networks.
 To learn more about this report, Download Free Sample Report
The renewable energy sector is contributing significantly to the expansion of the casting industry. In 2024 alone, global wind power capacity additions reached 116 GW, led by China, the U.S., and Germany. Wind turbine components such as rotor hubs, nacelle frames, and bearing housings are commonly produced using precision casting techniques due to their complex geometry and durability requirements. The scaling up of offshore wind farms in Europe and coastal Asia in 2025 further amplified the demand for corrosion-resistant metal castings, particularly stainless steel and specialized iron alloys.
Technological advancements in casting processes have strengthened the market's capability to meet high-precision industrial demands. As of 2025, more than 35 percent of mid- to large-sized foundries globally have adopted 3D printing for pattern making and rapid prototyping, reducing development time by over 40 percent. Countries like Germany, Japan, and South Korea have seen widespread integration of automated molding lines and solidification simulation software, enabling consistent production of high-performance components for aerospace, marine, and defense applications. These innovations improve quality and address labor shortages by streamlining operations.
Sustainability and environmental compliance are increasingly shaping market strategies. In 2024, over 65 percent of European metal casting facilities reported using recycled materials as their primary feedstock, aligning with EU Green Deal policies. During the same year, the U.S. also witnessed a 12 percent increase in ferrous scrap recycling for casting applications. As environmental awareness grows and regulatory frameworks tighten, the demand for cast products made through eco-friendly practices is rising. These developments position metal casting as a key enabler of circular manufacturing systems while maintaining economic viability.
Market Dynamics
The market is growing as industries such as automotive, construction, machinery, and aerospace continue to require durable and cost-effective metal components. Rising infrastructure development and manufacturing activities are increasing the demand for cast parts across a wide range of applications. Advancements in casting technologies are helping manufacturers improve product quality and production efficiency. However, fluctuations in raw material prices and increasing environmental regulations continue to pose challenges for market participants.
The metal casting industry is being driven by the automotive industry's growing focus on lightweight vehicle manufacturing and production efficiency. Automakers are increasingly using large aluminum cast components to reduce vehicle weight, improve fuel economy, and simplify assembly processes. Compared with traditional fabrication methods that require multiple welded parts, metal casting enables the production of complex components as a single piece, reducing material usage, manufacturing time, and overall production costs. As vehicle manufacturers continue to redesign platforms for electric and next-generation vehicles, demand for advanced casting technologies is rising significantly.
A recent example of this trend is the expansion of gigacasting technology across the automotive industry. At the IAA Mobility 2025 event, Volkswagen announced the adoption of gigacasting for several upcoming entry-level electric vehicles, highlighting the industry's growing shift toward large structural castings. Hyundai commenced production using its first 9,000-ton Giga Press at its Ulsan facility, supporting its hypercasting strategy for future EV manufacturing. These developments demonstrate how leading automakers are investing in advanced metal casting technologies to improve manufacturing efficiency and reduce vehicle complexity, creating strong growth opportunities for the metal casting market.
The global market is highly energy-intensive, as foundries rely on melting furnaces, heat-treatment equipment, and automated production systems that consume large amounts of electricity and fuel. Fluctuations in energy prices can significantly increase production costs and put pressure on profit margins, particularly for small and mid-sized foundries. Setting up and modernizing casting facilities requires substantial capital investment in furnaces, molding equipment, automation systems, and environmental compliance technologies. For instance, the Foundry Association of Ukraine in 2025 reported that electricity prices for foundries had increased by 10-15%. The association noted that electricity accounts for approximately 15-20% of total production costs in foundry operations, making rising power prices a major concern for competitiveness. The rising cost burden has encouraged foundries worldwide to invest in energy-efficiency initiatives, but high operating and capital costs remain a key restraint for the market growth.
The adoption of advanced manufacturing technologies is creating significant opportunities for the market. Technologies such as 3D sand printing, automated molding systems, and casting simulation software enable foundries to produce complex components with greater precision while reducing production time and material waste. These solutions also help manufacturers respond more quickly to customer requirements and improve overall operational efficiency. As industries such as aerospace, energy, and industrial equipment increasingly require customized and high-performance components, demand for digitally enabled casting processes is expected to grow. An example of this trend was reported by the American Foundry Society in 2025, which highlighted the growing use of 3D sand printing in foundries. For instance, Grede adopted 3D-printed cores to reduce energy consumption, assembly time, and tooling costs while improving casting accuracy. Such advancements demonstrate how digital manufacturing technologies are helping foundries improve efficiency and expand their production capabilities.
Analyst Perspective
The metal casting market is undergoing a transformation as manufacturers focus on producing lighter, stronger, and more complex components for industries such as automotive, industrial machinery, and construction. Demand is being supported by the growing adoption of electric vehicles, ongoing infrastructure development, and increasing investment in advanced manufacturing technologies. The foundries are embracing automation, 3D sand printing, and digital simulation tools to improve efficiency, reduce waste, and enhance product quality. While challenges such as high energy costs, raw material price fluctuations, and environmental regulations continue to impact profitability, they are also encouraging the industry to adopt more sustainable and efficient production methods. In the long term, companies that can balance cost efficiency, technological innovation, and sustainability will be best positioned to strengthen their market presence and capture future growth opportunities.
Material Insights
The iron segment led the market with the largest revenue share of 35.0% in 2025, driven by strong demand from the machinery, energy, and industrial equipment sectors, where cast iron and related iron-based alloys are widely used for their strength, wear resistance, machinability, and cost-effectiveness. Rising vehicle production and demand for engine blocks, brake components, transmission housings, and other cast components support consumption, while infrastructure development and construction activity increase demand for cast iron pipes, fittings, drainage components, and structural products.
The steel segment is anticipated to grow at a significant CAGR during the forecast period, due to rising investments in infrastructure, energy, and heavy machinery. Steel castings offer high strength, toughness, and wear resistance, making them suitable for structural and load-bearing applications. Growing construction activity across Asia-Pacific, the Middle East, and Africa drives demand for steel components such as girders, beams, and structural connectors. In the energy sector, the expansion of thermal and renewable power generation capacity is driving demand for steel castings in turbines, valves, and pressure vessels.
Application Insights
The automotive & transportation segment led the market with the largest revenue share of 42.1% in 2025. The surge in electric vehicle production significantly drives the automotive segment's rapid progress. In 2024, global electric vehicle sales surpassed 17 million units, accounting for over 14 million battery-electric vehicles and plug-in hybrids, marking a robust year-over-year increase of around 26%. This surge elevates EVs to over 14% of new light-duty vehicles worldwide, with some regions reaching as high as 22%, and rising EV sales are fueling demand for lightweight, high-precision metal castings used in battery enclosures, motor housings, and chassis components. Advanced casting processes, such as high-pressure die casting, allow manufacturers to meet the stringent weight and performance standards of electric vehicles by deploying optimized alloys and complex geometries.
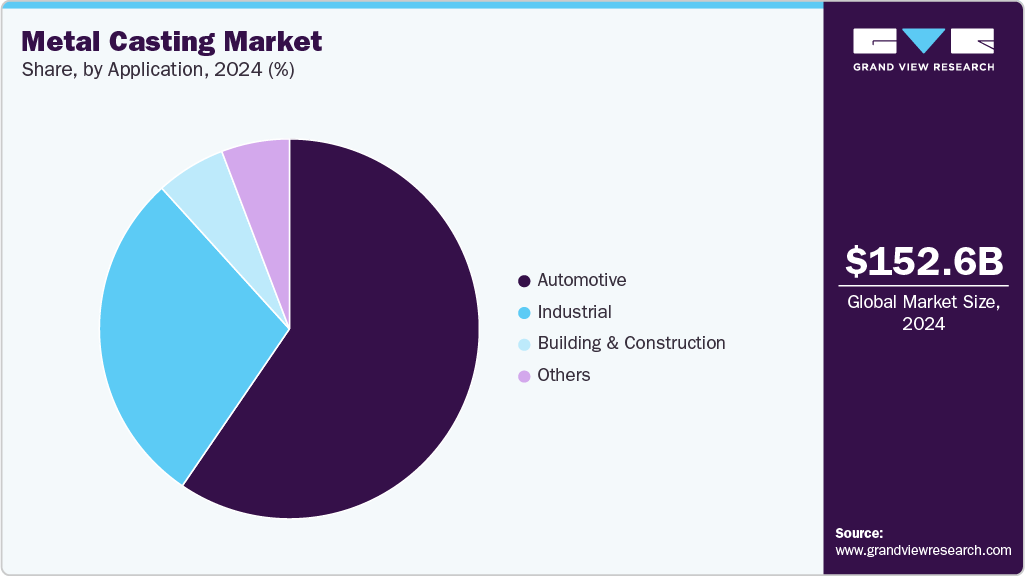 To learn more about this report, Download Free Sample Report
The energy & power segment is anticipated to grow at the fastest CAGR over the forecast period, driven by rising investments in electricity generation, transmission, and distribution infrastructure, which are increasing the demand for metal cast components such as housings, turbine components, pump bodies, valve bodies, and other structural parts. The expansion of renewable energy projects, grid modernization, and power generation facilities is further supporting demand for cast metals that offer durability, dimensional stability, and resistance to demanding operating conditions.
Regional Insights
The metal casting market in North America is growing steadily due to strong demand from the aerospace, and defense industries. These sectors require high-precision components with complex geometries, which has increased the use of advanced casting techniques such as investment casting and pressure die casting. Automakers focus on lightweight materials such as aluminum and magnesium to improve fuel efficiency, thereby supporting non-ferrous metal castings. Rising investments in electric vehicles and hybrid technology have also opened new avenues for casting applications in battery housings, motor parts, and chassis components.
U.S. Metal Casting Market Trends
The metal casting market in the U.S. is advancing due to growing demand from key sectors such as automotive and aerospace. For example, Ford and General Motors have expanded their use of aluminum castings in EV platforms to reduce vehicle weight and enhance battery efficiency. Tesla’s Gigafactories also utilize giga-casting techniques to produce large vehicle components in a single mold, streamlining production and cutting assembly time. In the aerospace sector, companies such as Pratt & Whitney and GE Aerospace rely heavily on investment casting for turbine blades and other engine components that must withstand extreme temperatures and stresses.
Asia Pacific Metal Casting Market Trends
The Asia Pacific metal casting market held the largest revenue share of 56.8% in 2025 and is expected to grow at the fastest CAGR during the forecast period. As countries like China, India, and Vietnam continue to invest in infrastructure development and urbanization, the demand for cast metal products such as pipes, valves, engine components, and structural parts has grown significantly. Rapid industrialization and government support for manufacturing, through initiatives such as "Make in India" and China's "New Infrastructure" strategy, have increased the region's foundry activity and capacity.
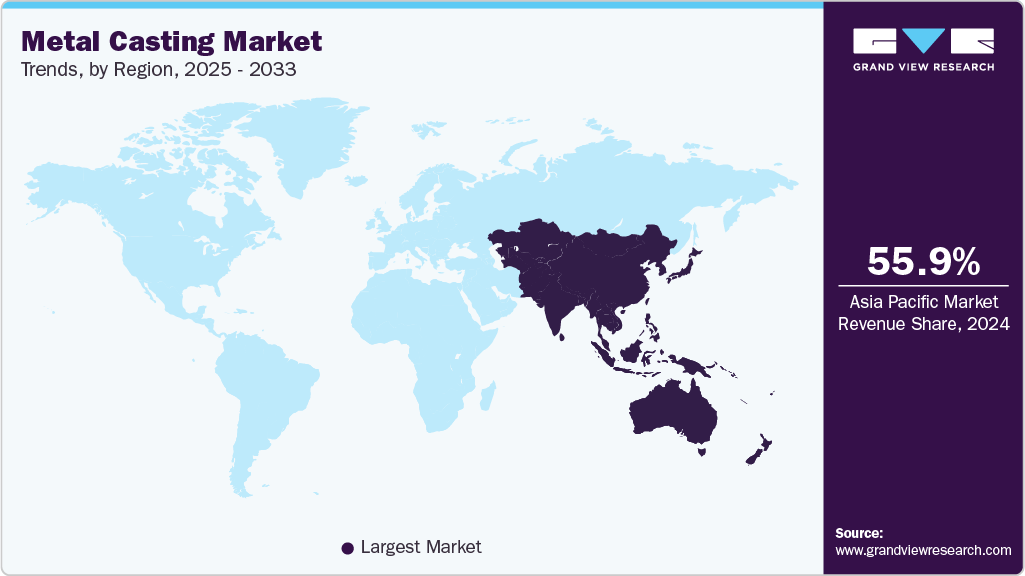 To learn more about this report, Download Free Sample Report
The metal casting market in China accounted for the largest market revenue share in the Asia Pacific in 2025, supported by the country’s large manufacturing base, particularly across machinery, industrial equipment, energy, and transportation applications. Rising vehicle production and increasing investment in industrial machinery are sustaining demand for cast components, including engine parts, housings, structural components, and precision castings.
Europe Metal Casting Market Trends
The metal casting market in Europe is expanding rapidly. Automakers across Germany, France, and Italy are increasingly adopting lightweight metal castings made from aluminum and magnesium to meet fuel efficiency standards and reduce vehicle emissions. This trend has accelerated with the shift toward electric vehicles, in which cast components are used in battery housings, motor components, and structural frames. Aerospace manufacturers such as Airbus rely on high-precision investment casting for engine components and airframe structures, supporting the growth of specialized foundries across the region.
Latin America Metal Casting Market Trends
The metal casting market in Latin America is expanding due to increasing industrial activity and infrastructure development across Brazil, Argentina, and Mexico. Construction of roads, bridges, railways, and urban infrastructure has boosted the demand for cast iron and steel components used in structural frameworks, drainage systems, and heavy machinery. Brazil dominates the regional casting landscape, supported by a strong base of iron foundries and driven by its large construction and manufacturing sectors. On the other hand, Argentina is seeing growing investment in automotive manufacturing, which supports the casting of engine blocks, chassis parts, and transmission housings.
Middle East & Africa Metal Casting Market Trends
The metal casting market in the Middle East and Africa is evolving with significant developments across sectors such as oil and gas, construction, and power generation. In the Gulf countries, especially Saudi Arabia and the UAE, large-scale infrastructure and energy projects are increasing the demand for cast components used in pipelines, pumps, valves, and heat exchangers. These countries are investing in foundry upgrades to produce corrosion-resistant, high-strength castings suited for high-temperature, high-pressure applications in oil and gas. In addition, ongoing refinery expansions and petrochemical plant developments require reliable casting inputs for complex machinery.
Key Metal Casting Company Insights
Some of the key players operating in the market include Alcast Technologies Ltd., Calmet Inc. and others
-
Alcast Technologies Ltd. is a Canada-based company headquartered in Hamilton, Ontario, known for its expertise in high-quality aluminum and zinc die casting. Established in 1994, the company serves various industries including automotive, aerospace, lighting, and electronics. Alcast is equipped with advanced vertical and horizontal die-casting machines, enabling the production of precision components with complex geometries. Alcast specializes in high-pressure aluminum and zinc castings, often using alloys such as A380, A383, and ZA-12.
-
Calmet Inc. is an international manufacturing and supply company that provides metal castings and precision-machined parts to clients across North America and Europe. With manufacturing facilities based in India and China, Calmet offers ferrous and non-ferrous castings, catering to automotive, hydraulics, agriculture, power transmission, and heavy equipment industries. Calmet’s casting offerings include grey iron, ductile iron, malleable iron, steel, aluminum, brass, and bronze. The company provides services such as heat treatment, CNC machining, galvanizing, electroplating, and painting to enhance the performance and durability of its cast components.
Key Metal Casting Companies:
The following key companies have been profiled for this study on the metal casting market.
-
Alcast Technologies Ltd.
-
Ahresty Corporation
-
Calmet Inc
-
Dynacast Ltd
-
Endurance Technologies Limited
-
GF Casting Solutions (Georg Fischer AG)
-
MES, Inc. (Metrics Holdings)
-
Proterial, Ltd
-
Rheinmetall AG
-
Ryobi Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Ahresty Corporation; Dynacast; GF Casting Solutions; Proterial, Ltd.; Rheinmetall AG; Ryobi Limited)
- Invest heavily in automation, robotics, and smart foundry technologies to improve productivity.
- Focus on long-term supply agreements with major automotive OEMs and industrial customers.
- Expand production capacity through new facilities and technology upgrades.
- Strong brand reputation and established customer relationships.
- Large-scale production capabilities resulting in lower per-unit costs.
- Access to advanced technologies and proprietary manufacturing processes.
- High operating and maintenance costs due to large manufacturing facilities.
- Significant exposure to fluctuations in automotive production cycles.
- Longer decision-making processes due to complex organizational structures.
Emerging Players (Alcast Technologies Ltd.; CALMET; Endurance Technologies Limited; MES, Inc.)
- Focus on niche casting applications and customized component manufacturing.
- Compete through cost-efficient production and flexible manufacturing processes.
- Expand presence in regional and developing markets.
- Greater flexibility in adapting to customer requirements.
- Faster decision-making and quicker implementation of operational changes.
- Lower overhead and administrative costs.
- Limited global presence and brand recognition.
- Smaller production capacities compared to industry leaders.
- Lower bargaining power with raw material suppliers.
Recent Development
-
In November 2024, CFS Foundry announced the launch of advanced metal casting and CNC machining services, elevating its capabilities to produce high-quality, precision-engineered metal components for various industries. The company specializes in diverse casting techniques, including die casting, investment casting, and stainless steel casting, leveraging state-of-the-art facilities and strict quality assurance protocols. Focusing on innovation and customer satisfaction, CFS Foundry integrates CNC machining into its processes, ensuring components meet precise specifications and are delivered as ready-to-use solutions.
Metal Casting Market Report Scope
Report Attribute
Details
Market size in 2025
USD 225.2 billion
Estimated market size in 2026
USD 234.6 billion
Projected market size by 2033
USD 347.5 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, Volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Material, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Spain; China; India; Japan; South Korea; Brazil
Key companies profiled
Alcast Technologies Ltd.; Ahresty Corporation; Calmet Inc.; Dynacast Ltd.; Endurance Technologies Limited; GF Casting Solutions (Georg Fischer AG); MES, Inc. (Metrics Holdings); Proterial, Ltd.; Rheinmetall AG; Ryobi Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Metal Casting Market Report Segmentation
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global metal casting market report based on the material, application, and region.
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Iron
-
Steel
-
Aluminum
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Automotive & Transportation
-
Heavy Machinery &Tools
-
Energy & Power
-
Aerospace & Defense
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
Spain
-
Italy
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Research Methodology
The metal casting marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachmetal casting segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Material
Revenue capture definition
Iron
Revenue is generated from the production and sale of cast components manufactured from various iron grades, including gray iron, ductile iron, white iron, malleable iron, and compacted graphite iron, for applications in the automotive, industrial, and construction sectors.
Steel
Market revenue is derived from the manufacturing and consumption of steel castings made from carbon steel, alloy steel, stainless steel, and other specialty steel grades used in demanding industrial, energy, transportation, and infrastructure applications.
Aluminum
Revenue is captured through the production and utilization of aluminum castings made from various aluminum alloys for lightweight, corrosion-resistant, and high-performance components, particularly in automotive, aerospace, industrial, and consumer applications.
Others
This segment generates revenue from cast components manufactured from metals and alloys other than iron, steel, and aluminum, including magnesium, zinc, copper, bronze, and brass, which are used in specialized industrial and engineering applications.
Application
Revenue capture definition
Automotive & Transportation
The automotive and transportation segment captures revenue generated from metal castings used in engine blocks, cylinder heads, transmission housings, wheels, brake components, suspension parts, and structural components.
Heavy Machinery &Tools
The heavy machinery and tools segment represents revenue generated from metal castings used in construction equipment, mining machinery, agricultural equipment, machine tools, industrial machinery, and other heavy-duty equipment.
Energy & Power
The energy and power segment includes revenue from metal castings used in turbines, generators, pumps, valves, compressors, heat exchangers, and other components of power generation and energy infrastructure.
Aerospace & Defense
The aerospace and defense segment captures revenue generated from metal castings used in aircraft engines, structural components, landing systems, missile systems, military vehicles, and other defense equipment.
Others
The others segment represents revenue generated from metal castings used in applications such as marine equipment, medical devices, electronics, consumer products, railways, and general industrial equipment.
Estimation Model
Layer Name
Key Question
Description
End-Use Industry Analysis
Where does demand originate?
This stage evaluates manufacturing activity and infrastructure development across key end-use sectors, including automotive, industrial, building & construction, and others. Industry production trends, capital investments, and equipment demand are analyzed to identify the primary sources of demand for metal cast components. The analysis helps determine the overall addressable market for metal castings.
Cast Component Assessment
Which components require metal castings?
This stage identifies the components that are commonly manufactured through casting processes across different industries. Demand is assessed for products such as engine blocks, transmission housings, pumps, valves, pipes, fittings, and structural components. Component production volumes are then mapped to their respective end-use applications to estimate casting demand.
Material Consumption Analysis
How much casting material is consumed?
The estimated demand for cast components is translated into material consumption across iron, steel, aluminum, and other alloy castings. Material selection is evaluated based on application requirements, performance characteristics, and industry preferences. This step quantifies the total casting volume consumed by material type and application segment.
Revenue Estimation
How much market revenue is generated?
The calculated casting volumes are converted into market revenue using average selling prices across different materials and applications. Pricing analysis considers factors such as alloy type, casting complexity, production process, and regional market dynamics. The aggregated revenue estimates are used to determine the overall market size and forecast growth.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Raw Material Pricing Analysis
Conducted a detailed assessment of key raw materials used in metal casting, including iron, steel, aluminum, magnesium, zinc, and copper alloys, covering price trends, supply-demand dynamics, trade flows, and sourcing risks across major regions.
Helps stakeholders understand cost drivers, evaluate procurement risks, and develop sourcing strategies to improve profitability and supply chain resilience.
Growth Opportunity Assessment
Conducted a comprehensive assessment of emerging growth opportunities across electric vehicles, renewable energy infrastructure, industrial automation, aerospace, and advanced manufacturing applications. The analysis included demand outlook, technology adoption trends, investment activity, and market attractiveness across key regions.
Helps stakeholders identify high-growth application areas, prioritize investment opportunities, and develop long-term expansion strategies in rapidly evolving end-use sectors.
Global Trade Flow & Import-Export Analysis
Evaluated international trade patterns for metal castings and casting materials, including import-export volumes, key trading countries, tariff structures, supply chain dependencies, and regional manufacturing competitiveness.
Enables stakeholders to understand trade dynamics, assess supply chain risks, identify export opportunities, and make informed sourcing and market-entry decisions across global markets.
Frequently Asked Questions About This Report
The metal casting market is primarily driven by rising demand from the automotive, industrial, and construction sectors, along with increasing infrastructure and manufacturing activities worldwide. The growing adoption of lightweight materials and advanced casting technologies is further supporting market growth.
The global metal casting market size was valued at USD 225.2 billion in 2025 and is estimated at USD 234.6 billion for 2026.
The global metal casting market is expected to grow at a CAGR of 5.8% from 2026 to 2033, reaching USD 347.5 billion by 2033.
Based on material, iron accounted for largest revenue share of 35.0% in 2025.
Based on application, automotive & transportation accounted for largest revenue share of 42.1% in 2025.
The key players operating in the metal casting market are Alcast Technologies Ltd; Ahresty Corporation; CALMET; Dynacast; Endurance Technologies Limited; GF Casting Solutions; MES, Inc.; Proterial, Ltd.; Rheinmetall AG; Ryobi Limited, and others.
Asia Pacific dominated the market with revenue share of 56.8% in 2025.
China dominated the Asian market with revenue share of 67.7% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 6.0% over the forecast period.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


