
- Home
- »
- Next Generation Technologies
- »
-
Military Wearables Market Size And Share Report 2026-2033GVR Report cover

Military Wearables Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Headgear, Smart Eyewear, Wrist Devices, Headset, Bodywear), By Technology (Communication), By End-user (Land Forces, Naval Forces, Air Forces), By Region, And Segment Forecasts
Market Size, 2025
$4.5BMarket Estimate, 2026
$4.6BMarket Forecast, 2033
$6.0BCAGR, 2026–2033
3.7%Military Wearables Market Size & Trends
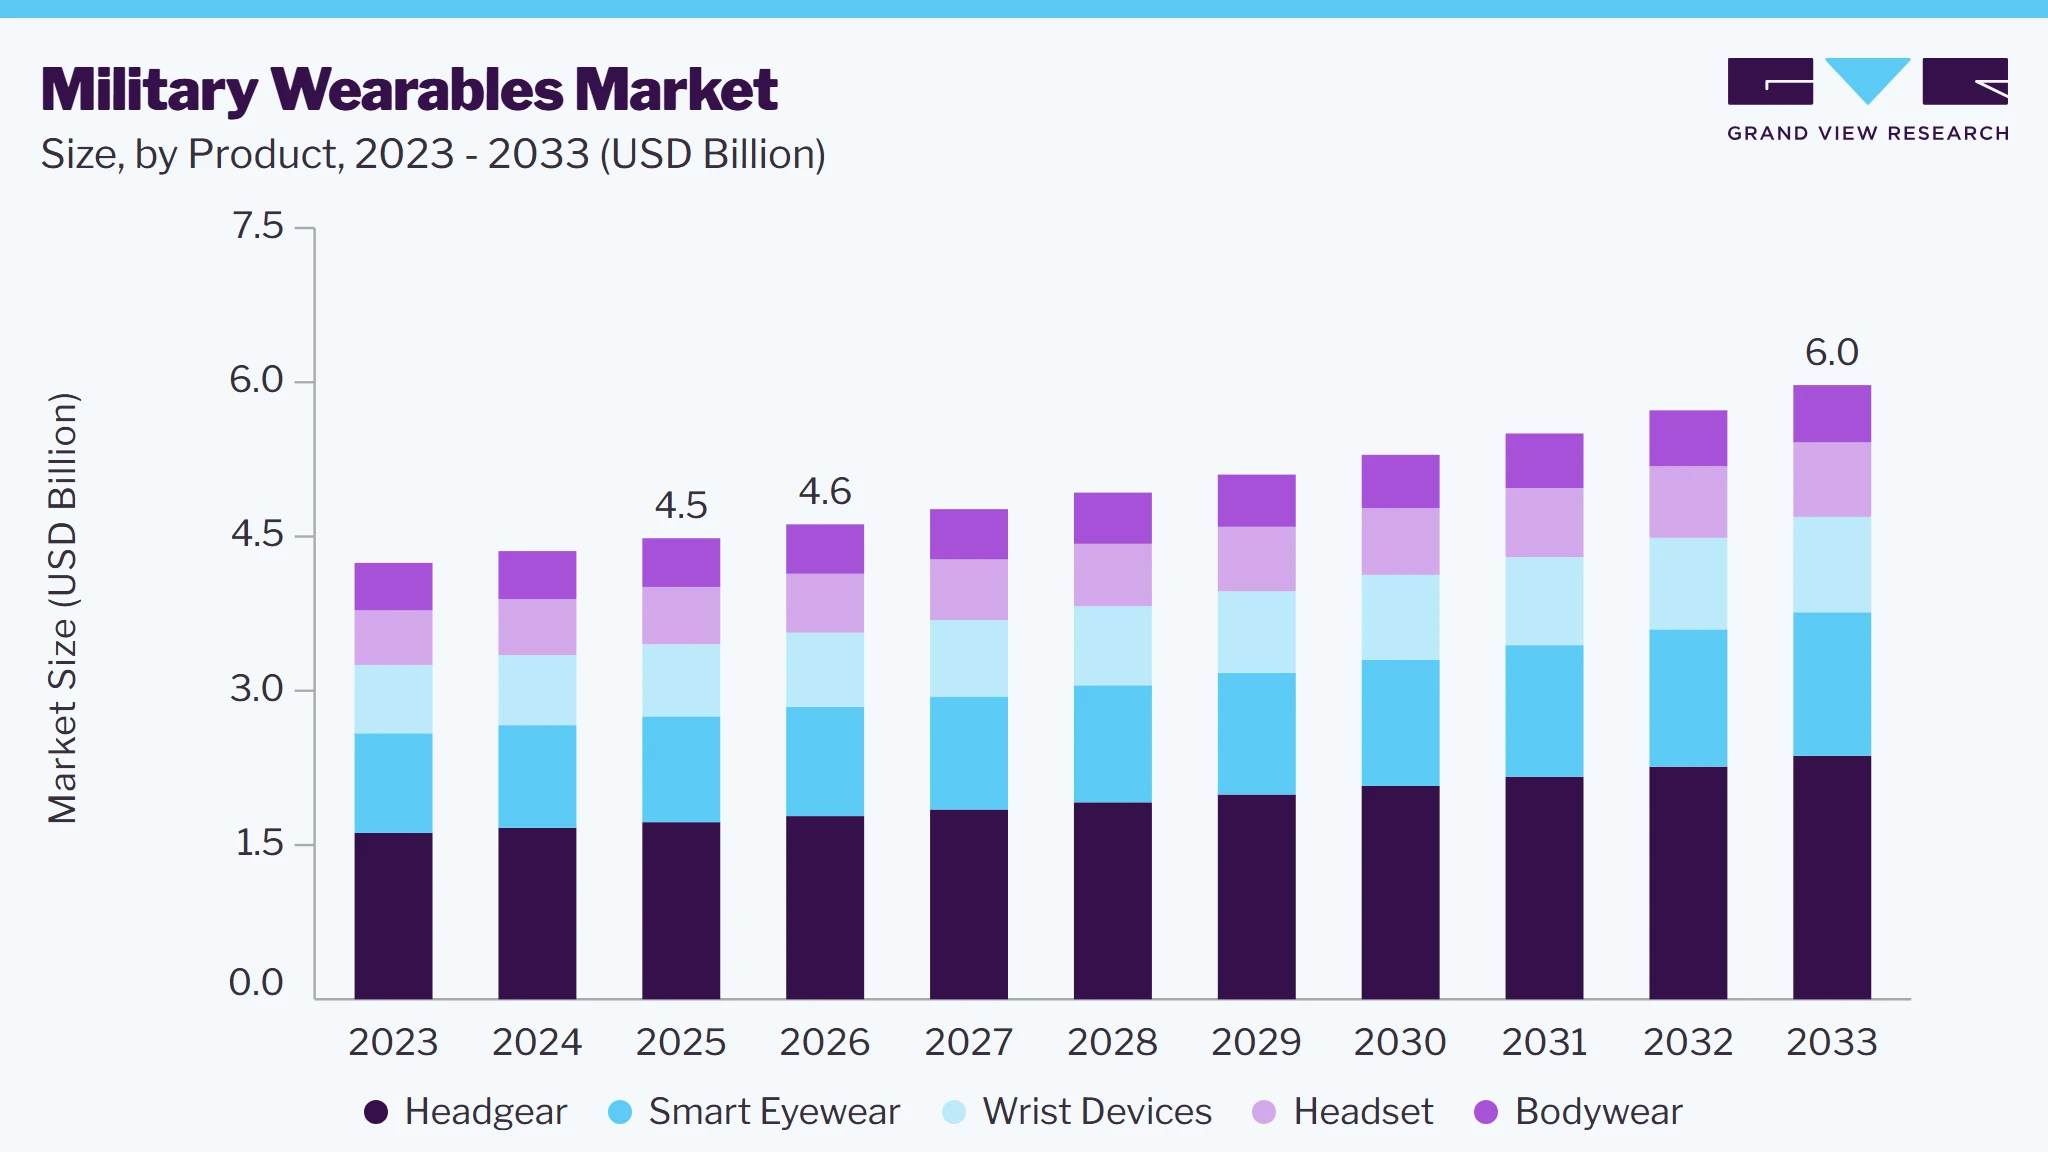
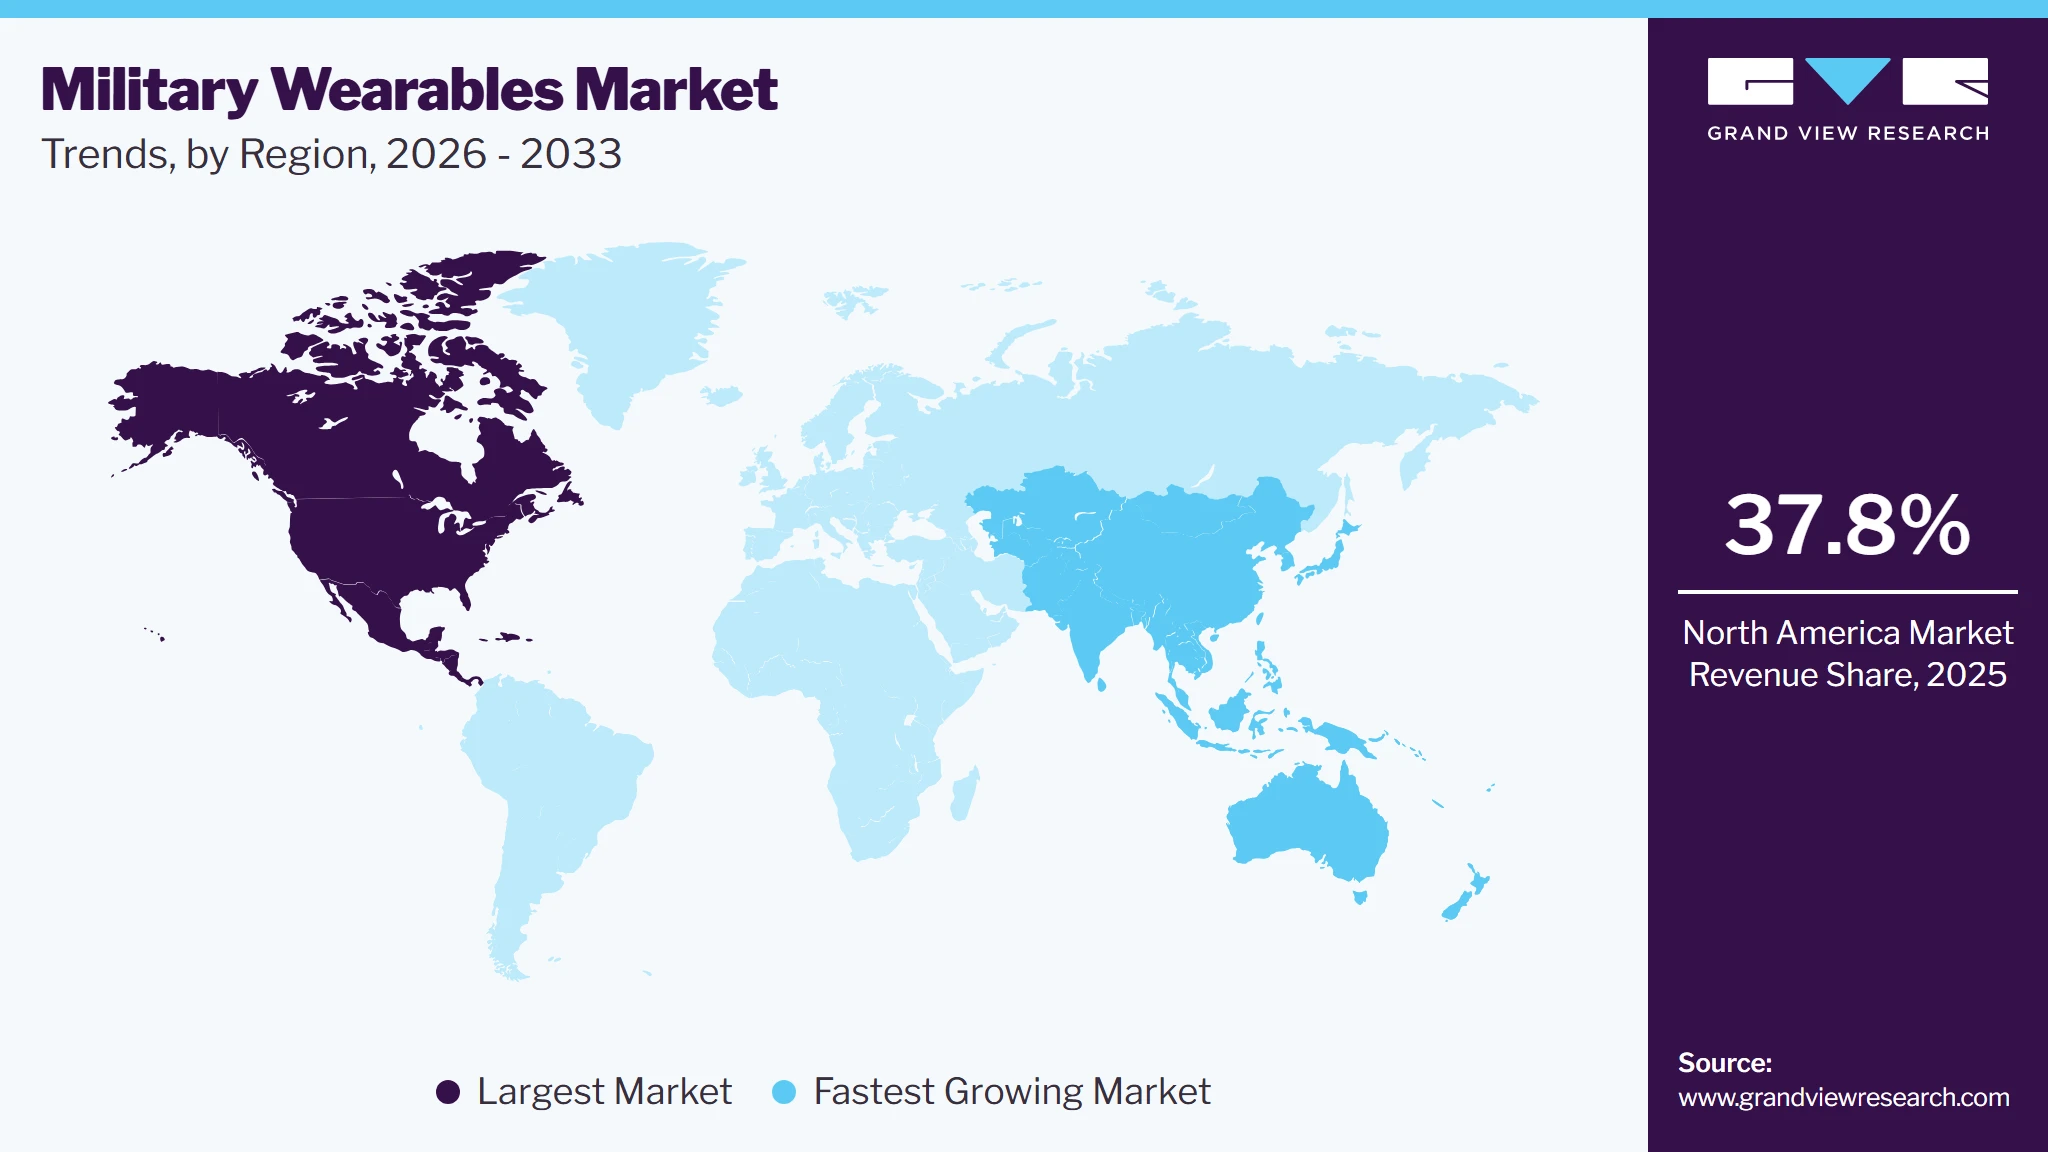
The global military wearables market size was valued at USD 4.5 billion in 2025 and is projected to grow from USD 4.6 billion in 2026 to USD 6.0 billion by 2033, at a CAGR of 3.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.8% in 2025. The military wearables market is driven by rising investments in soldier modernization programs, increasing demand for real-time battlefield situational awareness, and growing adoption of AI-enabled wearable technologies.
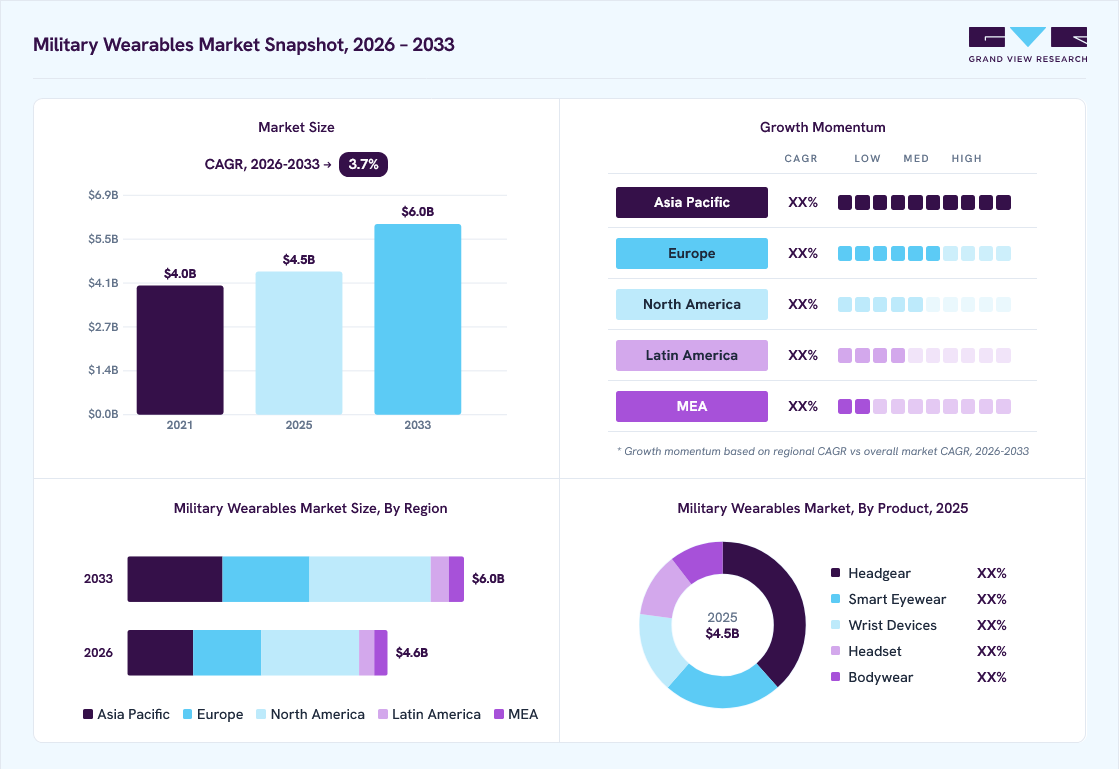 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Headgear segment dominated the market, with a share of 38.4% in 2025.
- By technology: Communication segment accounted for the largest market share of 33.6% in 2025.
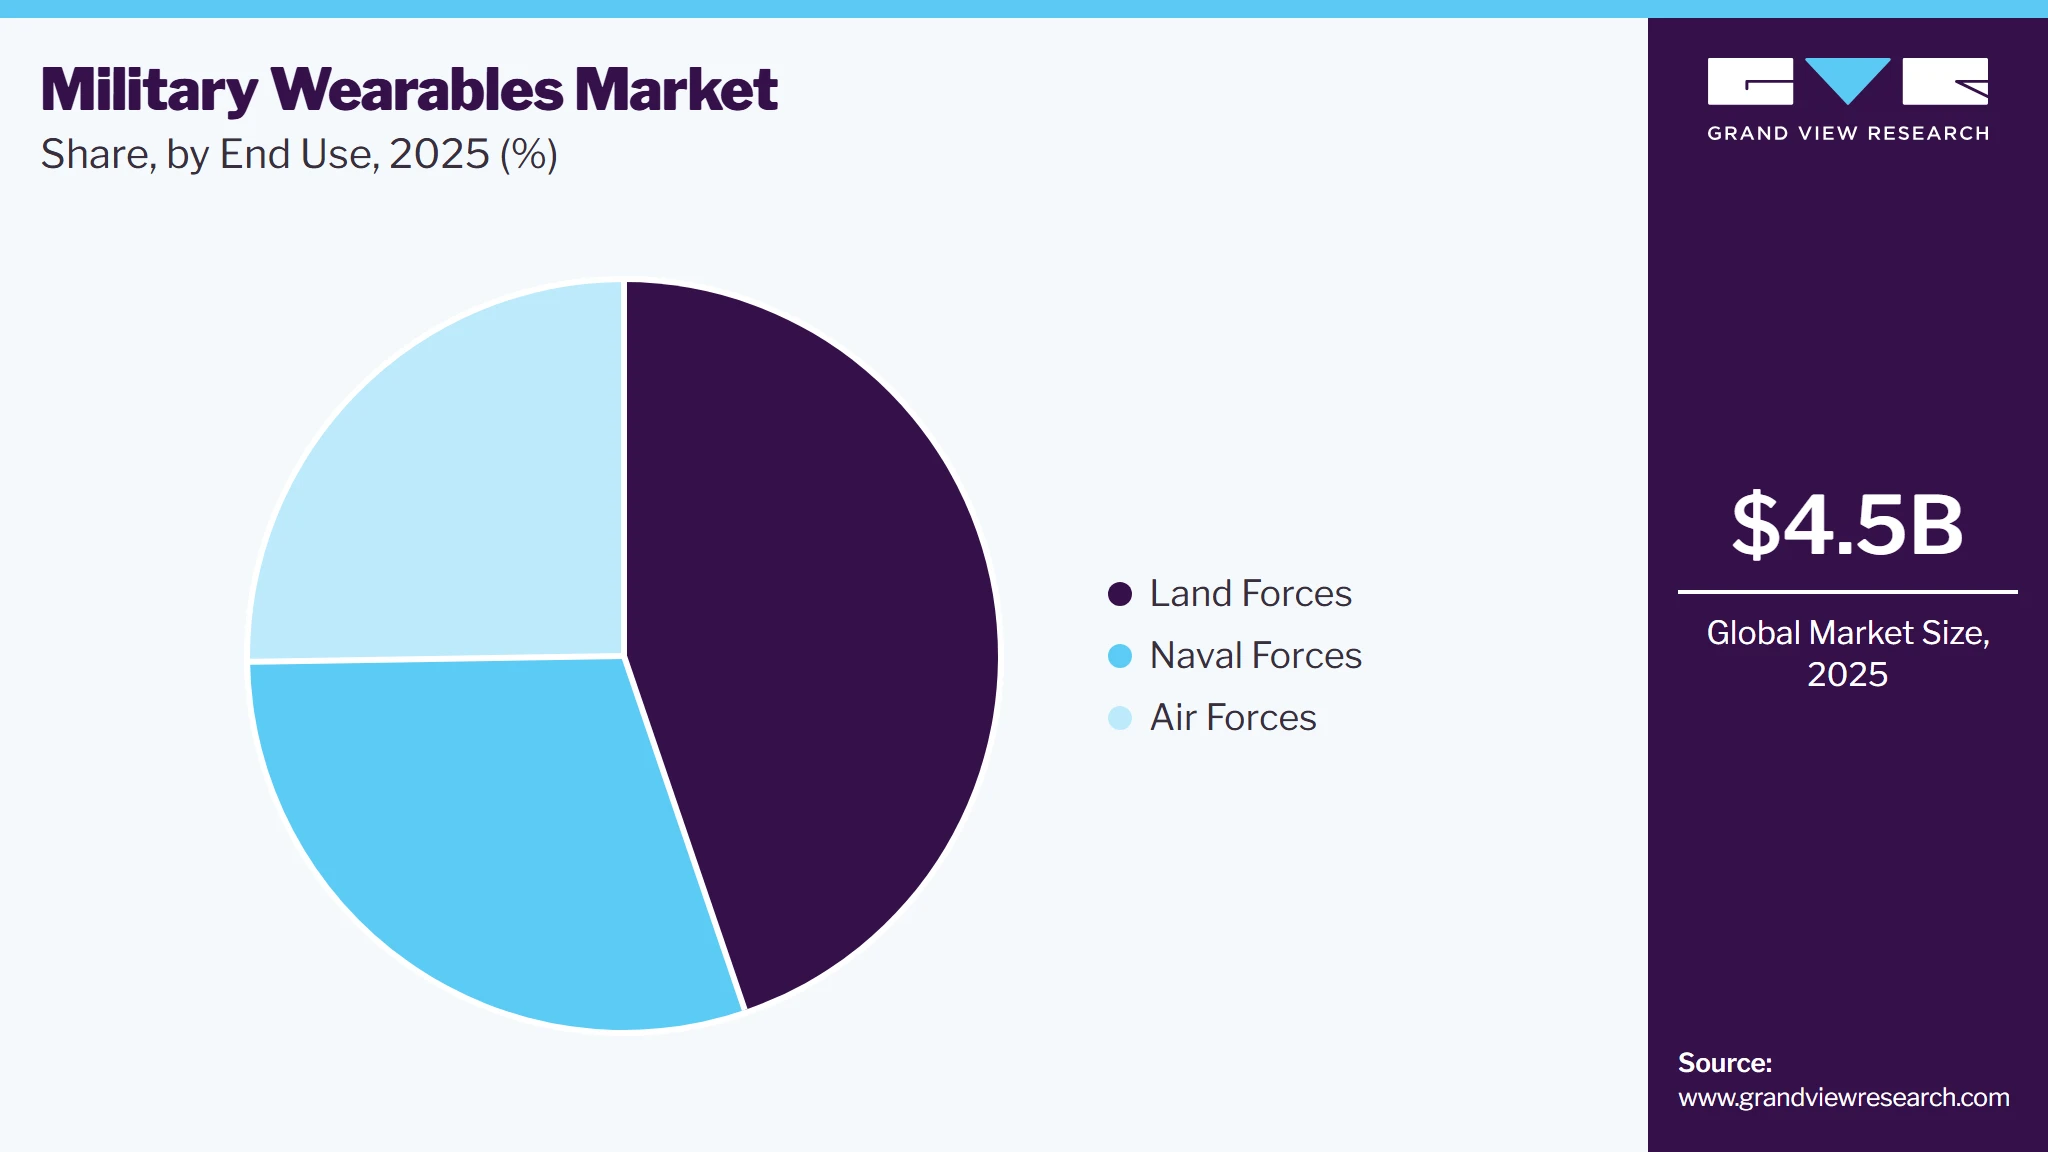
- By end use: Land forces segment accounted for the largest market share of 44.8% in 2025.
Regional Highlights
- Largest regional market: North America (37.8% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 5.4%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.5 Billion
- Estimated market size in 2026: USD 4.6 Billion
- Projected market size by 2033: USD 6.0 Billion
- CAGR (2026-2033): 3.7%
Prism AI by Grand View Research Free to tryAsk a question about the military wearables marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The expanding deployment of smart helmets, body-worn sensors, and health monitoring systems enhances soldier survivability, improves mission effectiveness, strengthens tactical decision-making, and enables continuous performance monitoring, thereby accelerating market adoption.The market growth is driven by the increasing adoption of sophisticated military wearables that enhance safety, performance, and efficiency in defense missions. Advanced wearables such as smart helmets, exoskeletons, sensor-integrated body armor, and communication systems are being integrated into modern military strategies to improve situational awareness, real-time communication, and health monitoring for personnel. The military wearables market is driven by emerging trends such as the increasing use of artificial intelligence (AI) and machine learning (ML) for predictive health monitoring, augmented reality (AR) to enhance battlefield awareness, and smart textiles with integrated sensors for tracking soldier performance. Additionally, there is a growing focus on wearable exoskeletons and sensor-enabled body armor to improve soldier resilience and operational effectiveness. With rising defense expenditures globally, particularly in North America, Europe, and Asia-Pacific, demand for military wearables is expected to grow steadily, creating lucrative opportunities for technology providers and manufacturers.
 To learn more about this report, Download Free Sample Report
The market is dominated by key players such as Lockheed Martin, Boeing, Raytheon Technologies, and Thales Group, which heavily invest in research and development to introduce innovative wearable solutions for defense applications. These companies are focusing on developing advanced wearable systems that enhance soldier capabilities, communication, health monitoring, and mission success on the battlefield. Additionally, cybersecurity integration in military wearables is becoming a priority to safeguard sensitive defense data.
Furthermore, the military wearables industry is projected to witness significant growth, powered by ongoing improvements in AI, sensor technologies, and data protection. The demand for wearable solutions is projected to increase as defense forces increasingly turn to these technologies to enhance soldier performance, decrease operational risks, and enhance decision-making capabilities. With an emphasis on mission preparedness and the delivery of real-time intelligence, military wearables will be an essential component to the success of future defense efforts, defining the future of warfare well into 2030.
Market Dynamics
The military wearables market is experiencing growth, driven by increasing investments in next-generation soldier systems, rising demand for connected battlefield capabilities, and the growing adoption of wearable technologies. The expansion of procurement for integrated soldier equipment, tactical communication systems, biometric monitoring devices, and wearable power management solutions is accelerating the deployment of advanced military wearables to enhance combat effectiveness. The integration of edge computing, AI-powered analytics, low-power sensors, secure wireless communication, and ruggedized wearable electronics improves operational coordination, soldier endurance, and force protection, creating significant long-term opportunities for the global military wearables market.
Governments are prioritizing comprehensive soldier modernization initiatives to improve combat effectiveness, survivability, and operational efficiency. Military organizations are equipping personnel with smart helmets, wearable communication systems, biometric sensors, body-worn computers, and integrated navigation devices that provide real-time battlefield information. These technologies enable faster decision-making, seamless coordination, and enhanced situational awareness during complex missions, making wearable solutions a critical component of future infantry and special operations programs.
The increasing emphasis on network-centric warfare is further accelerating investment in advanced wearable platforms that securely connect soldiers to command centers, unmanned systems, and tactical vehicles. Continuous advancements in lightweight electronics, ruggedized materials, energy-efficient processors, and secure wireless communication are improving reliability in harsh combat environments. Armed forces seek to enhance mission readiness while reducing operational risks; procurement of integrated wearable systems continues to expand across global defense organizations.
Power availability remains a significant challenge for wearable devices deployed during prolonged military operations. Many wearable systems require continuous operation for communication, navigation, biometric monitoring, and data processing, increasing battery consumption. Frequent battery replacement or recharging may not be practical in remote or hostile environments, creating operational constraints that affect mission continuity and reduce the effectiveness of connected soldier systems.
Military forces require wearable equipment that maintains reliable performance under extreme temperatures, high humidity, dust exposure, and physical impact without compromising battery life. Increasing functionality often results in higher energy demands, making compact power solutions difficult to achieve. These technical challenges increase equipment complexity, maintenance requirements, and lifecycle costs, limiting wider deployment across extended field operations.
The integration of artificial intelligence into wearable platforms is creating new opportunities for intelligent battlefield decision support. AI-powered wearables can process data from multiple onboard sensors to detect threats, monitor soldier health, identify environmental hazards, and prioritize mission-critical information. This enables personnel to receive actionable insights in real time while reducing cognitive workload during high-pressure operational scenarios.
Advancements in edge computing, secure tactical networks, and sensor fusion are enabling wearable systems to analyze information locally without depending on continuous connectivity. AI-enabled wearables can improve target recognition, navigation assistance, predictive health monitoring, and mission planning while supporting autonomous battlefield operations. These evolving capabilities are expected to strengthen operational effectiveness and encourage broader adoption of intelligent wearable technologies across modern defense programs.
Market Concentration & Characteristics
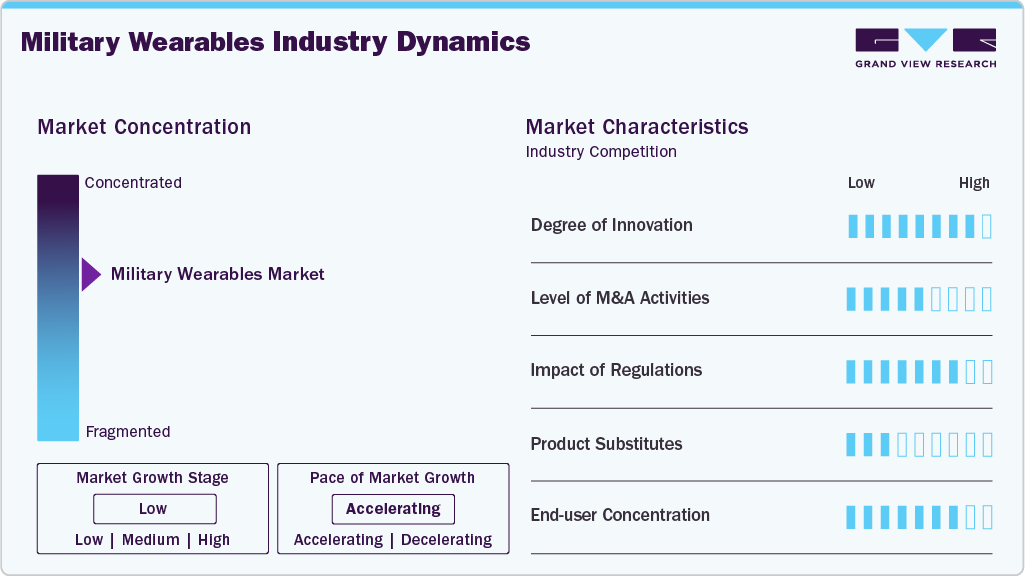
The military wearables market is moderately concentrated, with established defense electronics manufacturers, tactical communication system providers, wearable sensor developers, military optics companies, and advanced battlefield technology firms competing across soldier modernization, tactical communications, biometric monitoring, navigation, command and control, and force protection applications. Increasing emphasis on network-centric warfare, multi-domain operations, and dismounted soldier effectiveness is accelerating market expansion. Companies are strengthening their competitive positions through strategic defense partnerships, technology acquisitions, integrated soldier system development, and continuous investments in smart textiles, edge computing, energy-efficient electronics, secure tactical networking, and wearable power management technologies.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by continuous advancements in AI-assisted decision support, sensor fusion, wearable edge processors, augmented reality displays, biometric health monitoring, and secure low-latency battlefield connectivity. Merger and acquisition activity remains moderate as defense companies expand wearable technology capabilities and strengthen integrated soldier solution portfolios. Regulatory impact is significant due to military qualification standards, cybersecurity compliance, defense procurement requirements, and export control regulations. The threat of substitutes remains low because conventional combat equipment cannot deliver the integrated communication, physiological monitoring, navigation, and real-time situational awareness capabilities provided by advanced military wearable systems.
Analyst Perspective
The military wearables market is experiencing substantial expansion, driven by the increasing deployment of network-centric warfare systems, rising procurement of integrated soldier equipment, and a growing emphasis on real-time physiological monitoring during combat operations. Advancements in smart textiles, low-power electronics, secure wireless connectivity, and wearable power management are enhancing battlefield coordination, operational endurance, and mission execution. Defense technology providers are well-positioned to benefit from evolving military digitalization initiatives, reinforcing long-term market expansion and sustainable revenue generation across the global defense and security ecosystem.
Product Insights
Based on product, the headgear segment led the market with the largest revenue share of 38.4% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The tactical helmet segment is experiencing the fastest growth, driven by the increasing adoption of advanced technologies to enhance soldier safety and environmental awareness. Modern tactical helmets now incorporate augmented reality (AR) displays, built-in communication systems, and health sensors, enabling soldiers to access real-time battlefield data, maintain seamless communication, and remain operational in high-stress conditions. The growing emphasis on soldier protection, along with technological advancements in lightweight and durable materials, is fueling the widespread adoption of tactical helmets, making them an essential piece of equipment for military units worldwide. As technology continues to evolve, next-generation helmets will feature even more sophisticated capabilities, further reinforcing their importance in modern warfare.
By product type, the smart eyewear segment is the second-fastest growing category in the military wearables industry. Demand for AR goggles and smart glasses has surged as military forces seek to enhance operational effectiveness. These devices provide soldiers with critical real-time information, such as maps, target tracking, and data overlays, directly within their field of vision, making them a key component of future warfare strategies. The rising need for enhanced situational awareness, combined with advancements in AR technology, is accelerating the growth of this segment. Smart vision equipment improves decision-making, navigation, and target accuracy, making it indispensable for troops operating in complex environments. As technology continues to evolve, becoming smaller, more efficient, and more powerful, demand for smart eyewear is expected to see sustained growth in the coming years.
Technology Insights
Based on technology, the communication segment dominated the market with the largest revenue share of 33.6% in 2025, driven by the critical need for secure and efficient communication in defense operations. As military forces become increasingly dependent on real-time information sharing, integrated communication systems within wearables-such as tactical helmets and wrist devices-have become indispensable. These systems ensure uninterrupted connectivity in harsh environments, where traditional communication methods may be ineffective. Additionally, the adoption of 5G technology, enhanced encryption techniques, and satellite communication is further fueling the demand for advanced military communication solutions. The ability to securely transmit large volumes of data in real-time remains a top priority, solidifying this segment's leading position in the market.
The network and connectivity segment is projected to be the fastest-growing in terms of CAGR between 2025 and 2030. The rising demand for reliable, high-speed connectivity across a wide range of military wearables is a key growth driver. As armed forces deploy advanced wearables in complex operational environments, the supporting infrastructure must be equally sophisticated to handle high data transfer rates and seamless integration. Innovations in networking technologies, such as mesh networks and secure communication grids, are essential for maintaining connectivity among dispersed troops. Furthermore, the push for interoperability between wearable devices and broader military systems will significantly contribute to this segment’s expansion. In the coming years, advanced connectivity solutions will play a pivotal role in real-time data processing, situational awareness, and overall mission success.
End-user Insights
Based on end use, the land forces segment dominated the market with a revenue share of 44.8% in 2025, primarily driven by the rising adoption of wearable technology to enhance soldier performance, safety, and combat communication. Advanced wearables such as tactical helmets, intelligent vision equipment, and sensor-integrated body armor are significantly improving operational capabilities, real-time information delivery, and situational awareness. As warfare tactics evolve, land-based troops are at the forefront of integrating next-generation wearable technologies to gain tactical superiority, enhance mobility, and safeguard troop health in various combat environments. This segment is also benefiting from increased defense technology investments and continuous upgrades of troop equipment to meet modern battlefield requirements.
 To learn more about this report, Download Free Sample Report
The Naval Forces segment holds the second-largest market share, driven by the growing demand for advanced communication, situational awareness, and health monitoring solutions for seafarers and submariners. Wearable technologies such as communication headsets, tactical headgear, and health monitoring systems are increasingly being used to enhance coordination, crew safety, and operational efficiency in maritime missions. As naval operations become more complex, wearable devices are playing a crucial role in navigation, environmental monitoring, and secure communication. The continuous demand for rugged and technologically advanced wearables, coupled with improvements in their durability for marine environments, positions this segment for steady growth in the coming years.
Regional Insights
North America dominated the military wearables market with the largest revenue share of 37.8% in 2025. The United States, the world’s largest defense spender, is the primary driver of this growth due to continuous investments in military technology. The U.S. military is rapidly adopting wearables to enhance soldier efficiency, enable real-time communication, and improve health monitoring. Additionally, the integration of Artificial Intelligence (AI), machine learning (ML), and cybersecurity features into military wearables is further accelerating market expansion. With ongoing modernization efforts and a strong focus on technological advancement, North America is expected to maintain its market dominance from 2025 to 2030.
 To learn more about this report, Download Free Sample Report
U.S. Military Wearables Market Trends
The military wearables market in the U.S. held the largest share in the North America region in 2025, fueled by the Department of Defense’s increasing reliance on wearable technologies. The demand for tactical helmets, sensor-integrated body armor, and health monitoring devices is rising as the U.S. military seeks to enhance operational effectiveness, safety, and communication. The integration of real-time analytics, AI-driven decision-making tools, and advanced situational awareness systems is a key growth driver. Moreover, the shift toward individualized, data-driven soldier solutions, such as biometric tracking and fitness monitoring, is gaining traction. High defense spending and strategic collaborations between defense contractors and tech firms continue to drive innovation and adoption in this market.
Europe Military Wearables Market Trends
The European military wearables market is expected to grow at a CAGR of over 3.5% from 2025 to 2030, driven by increasing investments in wearable technologies aimed at enhancing soldier protection and performance. The integration of smart tactical helmets, sensor-equipped body armor, and medical monitoring systems into European defense forces is improving situational awareness, real-time data accessibility, and soldier health tracking. As defense budgets increase and NATO emphasizes technological interoperability, demand for military wearables is expected to rise across the region.
The UK military wearables market is set to witness significant growth, driven by modernization initiatives aimed at improving communication, health monitoring, and decision-making. Wearable devices that track vital signs and predict potential health risks are becoming central to the U.K. military’s strategy for maintaining soldier readiness and security. Additionally, the U.K. is leveraging AI and data analytics to customize wearable technologies to meet individual soldier demands.
The military wearables market in Germany is expanding due to ongoing defense modernization efforts. Germany is investing in smart helmets, performance-tracking wearables, and sensor-integrated uniforms to enhance soldier safety and mission success. These systems allow real-time monitoring of troop health and battlefield performance. Germany’s defense budget growth and commitment to NATO operations will continue driving military wearable adoption in the country.
Asia Pacific Military Wearables Market Trends
The Asia-Pacific military wearables market is projected to grow at the fastest CAGR from 2026 to 2033, fueled by rising defense budgets, large-scale military modernization programs, and technological advancements. Countries such as China, Japan, and India are actively adopting wearable technologies to enhance soldier performance, improve operational safety, and optimize real-time battlefield decision-making. The increasing demand for smart helmets, health monitoring systems, and tactical wearables is driven by military efforts to enhance situational awareness and reduce risks in high-threat environments. Investments in defense infrastructure and advanced wearable technologies will continue to propel market expansion in the region.
The Japan Military Wearables Market is expanding as the nation is prioritizing the development of its defense capabilities by embracing advanced technology. The Japanese Self-Defense Forces are increasingly using wearable health monitoring systems, performance-tracking devices, and real-time communication tools to enhance troop safety and battlefield efficiency. Japan’s strategic partnerships with global defense forces, along with a strong focus on technological innovation, will sustain long-term market growth.
Military wearables market in china is growing aggressively owing to the nation's strong defense modernization initiative and growing emphasis on soldier technology. China is integrating health-tracking wearables, smart helmets, and sensor-enabled body armor into its military operations to improve situational awareness and mission effectiveness. The country’s advancements in AI, data analytics, and real-time intelligence capabilities are central to enhancing soldier performance and military readiness. With a vast military workforce and an aggressive focus on technology development, China’s market for military wearables is poised for continued expansion.
Key Military Wearables Company Insights
Some of the key players operating in the market are BAE Systems, Elbit Systems, among others.
-
BAE Systems is a defense and aerospace technology company with a broad portfolio of wearable solutions for soldiers. Their wearable military solutions include intelligent helmets, tactical headsets, communication devices, and health-monitoring wearables. BAE's wearable solutions are intended to deliver real-time information, enhance situational awareness, and promote soldier safety on the battlefield. The company also deals in wearable communication solutions that enable soldiers to remain connected in harsh environments. BAE is a dominant company in North America and Europe with a robust defense contracting presence.
-
Elbit Systems offers air, land, and naval technologies for the defense sector. Elbit Systems provides smart eyewear, headmount, and body-worn sensors in the military wearables business. The wearables are aimed at enhancing soldier health monitoring, situational awareness, and battlefield communications. Elbit products are used extensively across the Middle Eastern and European defense markets, where their wearable technology is built into broader defense systems to drive mission success and reduce soldier risk.
Thales Group and Rheinmetall are some of the emerging market participants in the Military Wearables Market.
-
Rheinmetall is specializes in the development of military technologies such as smart clothing, wearable sensors, and tactical vests with health and biometric monitoring. Their wearables enable soldiers to monitor vital signs, physical stress, and communication capabilities in real-time. Rheinmetall also specializes in developing systems that combine wearable technology with weapons systems and armored vehicles. Rheinmetall's wearable solutions are becoming popular in European and Asia-Pacific markets as an integral part of holistic defense solutions.
-
Thales Group provides a diversified range of defense and security solutions with emphasis on communication systems, intelligent helmets, augmented reality (AR) glasses, and medical monitoring devices for soldiers. Thales' wearable technologies aim to enhance soldier efficiency, safety, and performance through essential information provision and situational awareness. These wearables enable real-time data gathering and communication, which is essential for effective military operations. The firm is a major player in the European and Asia-Pacific defense markets, with ongoing innovations to address contemporary soldier requirements.
Key Military Wearables Companies
The following key companies have been profiled for this study on the military wearables market.
-
BAE Systems
-
Elbit Systems
-
Rheinmetall
-
Saab
-
Rheinmetall
-
Aselsan
-
General Dynamics
-
Garmin
-
Lockheed Martin
-
Honeywell International Inc.
-
L3harris Technologies Inc.
-
Leonardo S.p.A.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BAE Systems, Elbit Systems, L3harris Technologies Inc.)
- Focus on expanding integrated soldier systems through defense partnerships, secure communications, and wearable technology development.
- Invest heavily in R&D to deliver rugged, AI-enabled wearable solutions for modern military operations.
- Strong defense portfolios, long-term government contracts, and proven battlefield technologies strengthen competitive market positioning.
- Ability to deliver secure, interoperable, mission-critical wearable systems meeting stringent military performance requirements.
- Dependence on lengthy defense procurement cycles may delay the commercialization of next-generation wearable technologies.
- Large organizational structures can reduce flexibility in responding to rapidly evolving battlefield technology requirements.
Emerging Players (Thales Group, Saab, Aselsan)
- Emerging players focus on developing AI-enabled wearable sensors through defense innovation partnerships and specialized technology collaborations.
- Invest in lightweight, wearable platforms that support biometric monitoring, tactical communications, and soldier performance enhancement.
- Agile product development enables rapid integration of advanced wearable technologies for evolving defense requirements.
- Specialized expertise in sensor innovation and smart textiles strengthens differentiation within niche military applications.
- Limited manufacturing scale and defense procurement experience restrict participation in large military contracts.
- Smaller financial resources may constrain long-term R&D investments and global market expansion initiatives.
Recent Developments
-
In December 2024, BAE Systems has signed a £133 million contract with the Eurofighter Typhoon consortium (Germany, Italy, Spain, and the UK) to continue developing its Striker II Helmet Mounted-Display (HMD). The helmet brings together cutting-edge technologies, such as digital night vision and a color display, to deliver mission-critical information to the pilot in real-time on their visor. The deal will concentrate on developing the capabilities of the helmet through flying trials and solidifying its leadership position in military wearables for flight.
-
In July 2024, Viasat launched the Secure Wireless Hub (SWH), a wearable tactical communications system for dismounted troops. Co-developed with U.S. Special Operations Command (USSOCOM), the system provides a light, single-unit tactical gateway that improves network connectivity and situational awareness for ground troops. Weighing less than one kilogram, the SWH minimizes size, weight, and power (SWaP), easily integrating with body armor. It gives interoperability between a range of devices and supplies secure VPN capability, allowing dependable connectivity and data sharing in near real-time while in combat mode
-
Thales Group partnered with the French Ministry of Armed Forces in February 2024 to provide next-generation integrated combat systems for wearable devices. This includes the creation of connected helmets, body-worn sensors, and intelligent communication systems for soldiers. These wearables are intended to enhance soldier survivability, health monitoring, and data transmission on the battlefield. The objective of the partnership is to keep the French military in the lead of wearable defense technology.
Military Wearables Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.5 billion
Estimated market size in 2026
USD 4.6 billion
Projected market size by 2033
USD 6.0 billion
Growth rate
CAGR of 3.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
BAE Systems; Elbit Systems; Rheinmetall; Thales Group; Saab; Aselsan; General Dynamics; Garmin; Lockheed Martin; Honeywell International Inc.; L3harris Technologies Inc.; Leonardo S.p.A.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Military Wearables Market Report Segmentation
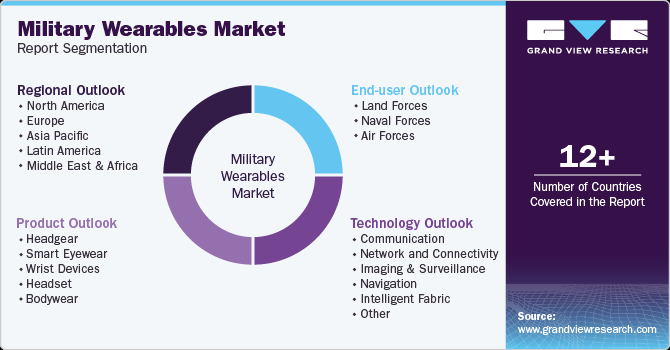
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest technology trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global military wearables market report based on product, technology, end-user, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Headgear
-
Smart Eyewear
-
Wrist Devices
-
Headset
-
Bodywear
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Communication
-
Network and Connectivity
-
Imaging & Surveillance
-
Navigation
-
Intelligent Fabric
-
Other
-
-
End-user Outlook (Revenue, USD Million, 2021 - 2033)
-
Land Forces
-
Naval Forces
-
Air Forces
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The military wearables market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each military wearables segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Headgear
Revenue is generated through smart combat helmets equipped with integrated communication modules, biometric sensors, night-vision interfaces, hearing protection, and situational-awareness systems. This segment is driven by rising soldier modernization initiatives, increasing demand for battlefield connectivity, and enhanced force protection during combat and tactical operations.
Smart Eyewear
Revenue is generated through augmented reality glasses, head-up display systems, thermal imaging eyewear, and tactical vision devices that provide real-time mission intelligence. This segment is supported by increasing demand for hands-free information access, improved target acquisition, and enhanced operational awareness in complex battlefield environments.
Wrist Devices
Revenue is derived from rugged military smartwatches, wrist-mounted GPS units, biometric monitors, mission tracking devices, and tactical data displays. This segment is driven by the need for continuous health monitoring, navigation support, secure communication, and rapid access to mission-critical information during field operations.
Headset
Revenue is captured through tactical communication headsets featuring noise cancellation, hearing protection, secure voice transmission, and wireless battlefield connectivity. This segment is propelled by increasing adoption of network-centric warfare, coordinated military operations, and the need for reliable communication in high-noise combat environments.
Bodywear
Revenue is generated through smart combat uniforms, biometric monitoring vests, wearable power systems, body-mounted sensors, and integrated soldier equipment. This segment is driven by increasing focus on soldier survivability, physiological monitoring, operational endurance, and seamless integration of wearable technologies into combat gear.
Segment - Technology
Revenue capture definition
Communication
Revenue is captured through wearable communication technologies enabling encrypted voice transmission, tactical messaging, real-time command coordination, and battlefield information sharing. This segment is driven by increasing deployment of secure military communication networks and growing demand for uninterrupted operational connectivity.
Network and Connectivity
Revenue is generated through wearable networking technologies supporting secure wireless links, mesh networking, satellite communication integration, and connected soldier ecosystems. This segment is supported by the rising adoption of digital battlefield infrastructure and real-time data exchange across military units.
Imaging & Surveillance
Revenue is derived from wearable thermal imaging systems, infrared sensors, tactical cameras, night-vision devices, and reconnaissance equipment, which provide real-time battlefield intelligence. This segment is driven by increasing demand for enhanced target detection, surveillance capabilities, and improved situational awareness during military missions.
Navigation
Revenue is captured through wearable GPS systems, inertial navigation devices, digital mapping solutions, and positioning technologies that support accurate troop movement and mission planning. This segment is propelled by growing requirements for precise navigation and operational coordination across diverse combat environments.
Intelligent Fabric
Revenue is generated through smart textiles embedded with physiological sensors, conductive fibers, environmental monitoring capabilities, and wearable electronics integrated into military uniforms. This segment is driven by advancements in textile engineering and increasing demand for lightweight, multifunctional combat apparel.
Others
Revenue is captured through wearable power management systems, exoskeleton technologies, biometric authentication devices, environmental sensing solutions, and emerging soldier support technologies. This segment is supported by continuous defense innovation and expanding integration of advanced wearable capabilities across military operations.
Segment - End Use
Revenue capture definition
Land Forces
Revenue is generated through the deployment of wearable technologies across infantry units, armored divisions, special operations forces, and ground combat personnel for communication, navigation, health monitoring, and battlefield awareness. This segment is driven by extensive soldier modernization programs and increasing investments in connected battlefield capabilities.
Naval Forces
Revenue is captured through wearable systems used by naval personnel for secure communication, operational monitoring, navigation assistance, and mission coordination aboard ships, submarines, and maritime security platforms. This segment is driven by growing maritime defense requirements and the modernization of naval combat systems.
Air Forces
Revenue is derived from wearable technologies supporting pilots, aircrew, and aviation personnel through biometric monitoring, helmet-mounted displays, flight communication systems, and mission assistance devices. This segment is propelled by increasing focus on pilot safety, mission effectiveness, and advanced aerospace operational capabilities.
Estimation Model
Layer Name
Key Question
Description
Defense Adoption Layer
Who are the potential adopters?
Identifies the primary organizations adopting military wearable solutions, including defense ministries, armed forces, special operations units, homeland security agencies, border security organizations, peacekeeping forces, and military training institutions seeking enhanced soldier survivability, mission effectiveness, force protection, and operational readiness.
Technology Enablement Layer
Who can deploy military wearable solutions?
Deployment depends on the availability of secure tactical communication networks, wearable sensors, biometric monitoring technologies, edge computing platforms, satellite connectivity, AI-powered analytics, power management systems, and integrated command-and-control infrastructure that support connected soldier operations.
Application Layer
Where are military wearable solutions actively utilized?
Military wearable solutions are deployed across infantry operations, special forces missions, border surveillance, tactical reconnaissance, combat search and rescue, command-and-control activities, military training exercises, peacekeeping deployments, disaster response operations, and battlefield medical support to enhance operational effectiveness and personnel safety.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through sales of wearable communication systems, smart helmets, tactical headsets, biometric monitoring devices, smart uniforms, wearable navigation equipment, system integration services, maintenance contracts, software upgrades, lifecycle support, defense modernization programs, and long-term military procurement agreements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Integrated Soldier Modernization Program Assessment
Conducted detailed evaluation of integrated soldier modernization programs across land, naval, and air forces, assessing smart helmets, biometric sensors, tactical communication devices, wearable power systems, and battlefield connectivity technologies to enhance operational effectiveness.
Improves soldier survivability, enhances mission readiness, strengthens battlefield coordination, and supports informed procurement decisions.
AI-Enabled Military Wearables Deployment & Battlefield Connectivity Strategy
Assessed deployment of AI-enabled military wearables across combat operations, reconnaissance missions, border security, and special forces, integrating secure communications, edge computing, biometric monitoring, and real-time situational awareness capabilities for mission optimization.
Enhances tactical awareness, improves operational coordination, enables real-time decision-making, and strengthens defense capabilities.
Smart Wearable Sensors & Tactical Health Monitoring Evaluation
Evaluated implementation of wearable biometric monitoring systems, intelligent sensor platforms, smart textiles, environmental monitoring devices, and predictive health analytics supporting continuous soldier performance assessment, physiological monitoring, and operational endurance during military missions.
Enables proactive health monitoring, improves operational endurance, reduces mission risks, and supports force readiness.
Frequently Asked Questions About This Report
The Asia Pacific is the fastest-growing region with a CAGR of 5.4% from 2026 to 2033.
Some key players operating in the military wearables market include BAE Systems; Elbit Systems; Rheinmetall; Thales Group; Saab; Aselsan; General Dynamics; Garmin; Lockheed Martin; Honeywell International Inc.; L3harris Technologies Inc.; Leonardo S.p.A.
Key factors that are driving the military wearables market growth include the increasing adoption of sophisticated military wearables that enhance safety, performance, and efficiency in defense missions.
The headgear segment dominated with a 38.4% revenue share in 2025 and smart eyewear segment is second fastest growing market
The land forces segment dominated the market with a share of 44.8% in 2025.
Based on technology, the communication segment dominated the market with the largest revenue share of 33.6% in 2025, driven by the critical need for secure and efficient communication in defense operations.
The global military wearables market size was valued at USD 4.5 billion in 2025 and is estimated at USD 4.6 billion for 2026
The global military wearables market is expected to grow at a CAGR of 3.7% from 2026 to 2033, reaching USD 6.0 billion by 2033.
North America dominates the military wearables industry, accounting for 37.8% of total market revenue share in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


