
- Home
- »
- Communication Services
- »
-
Mobile Satellite Services Market Size Report, 2026-2033GVR Report cover

Mobile Satellite Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Voice, Data), By Application (Land Mobile, Maritime, M2M Services), By End-user (Defense & Intelligence, Government, Industrial, Enterprise), By Region, And Segment Forecasts
Market Size, 2025
$6.9BMarket Estimate, 2026
$7.3BMarket Forecast, 2033
$12.0BCAGR, 2026–2033
7.3%Mobile Satellite Services Market Summary
The global mobile satellite services market size was valued at USD 6.9 billion in 2025 and is projected to grow from USD 7.3 billion in 2026 to USD 12.0 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 32.9% in 2025. Mobile satellite services utilize satellite technology to offer voice and data communication services to mobile users across the globe, regardless of their location on land, sea, or air.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Data segment dominated the market, with a revenue share of 74.8% in 2025.
- By application: Land Mobile segment held the largest market share of 35.6% in 2025.
- By end-user: Defense & Intelligence segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (32.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.9 Billion
- Estimated market size in 2026: USD 7.3 Billion
- Projected market size by 2033: USD 12.0 Billion
- CAGR (2026-2033): 7.3%
Prism AI by Grand View Research Free to tryAsk a question about the mobile satellite services marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Mobile satellite services are witnessing significant growth owing to the increasing need for global connectivity, particularly in remote and rural areas where terrestrial infrastructure is insufficient. The market is expected to continue its growth trajectory in the coming years, primarily driven by the surging usage of mobile data and the growing adoption of satellite-based Internet of Things (IoT) applications. Mobile satellite services are a means of providing communication services to mobile devices using satellite technology. Mobile satellite services are witnessing significant growth due to the increasing demand for connectivity solutions in remote, underserved, and rural areas where traditional terrestrial networks are either not functional or unavailable. One of the trends in this market is the usage of mobile satellite services during emergencies and natural disasters.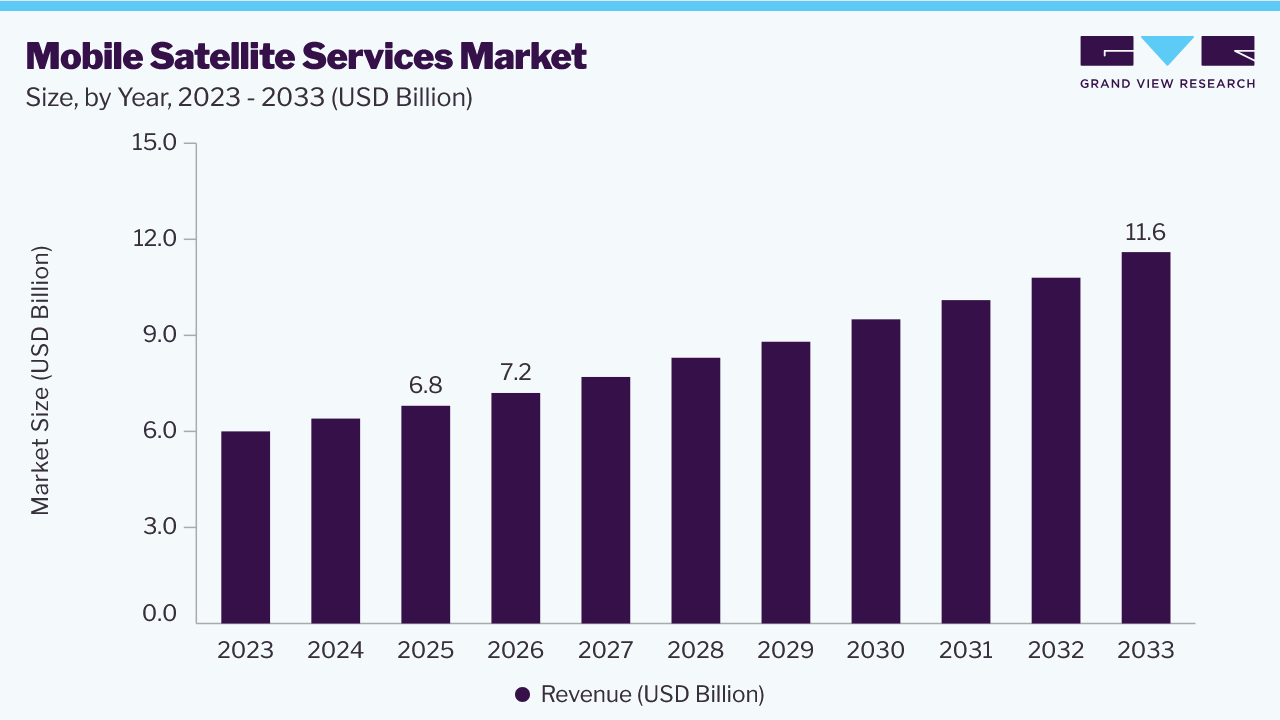 To learn more about this report, Download Free Sample Report
Telecom operators and mobile satellite service providers are joining forces to tackle the issue of inadequate network coverage in remote areas. The main objective of these partnerships is to offer network connectivity in regions where the existing terrestrial network falls short. These efforts are anticipated to close the network gap and propel the expansion of the mobile satellite services industry in the foreseeable future. In addition to personal or consumer-level network connectivity, business operations in remote locations, such as the marine, mining, oil and gas, and defense sectors, face multiple challenges due to minimal access to terrestrial networks. As a result, these industries are increasingly turning to satellite-based connectivity, which is fueling the growth of mobile satellite services.
Market Dynamics
The mobile satellite services market is experiencing steady growth driven by increasing demand for ubiquitous connectivity across remote, maritime, aviation, defense, and disaster-response environments. Advancements in low Earth orbit (LEO) satellite constellations, software-defined satellites, hybrid satellite-terrestrial networks, and satellite-enabled IoT are transforming service capabilities while improving coverage and network resilience. The growing reliance on mission-critical communications, emergency preparedness, and digital transformation across industries continue to drive market expansion.
The growing need for uninterrupted communication in regions beyond the reach of terrestrial cellular infrastructure is a major driver for the mobile satellite services market. Industries such as oil & gas, mining, maritime shipping, aviation, emergency response, and defense increasingly operate in geographically isolated environments where conventional communication networks are unavailable or unreliable. Governments are also investing in resilient communication infrastructure to improve disaster preparedness and national security, further driving demand for satellite-based mobile connectivity.
Mobile satellite services address this challenge by delivering seamless voice and broadband data communications regardless of geographical location. Modern satellite networks equipped with high-throughput satellites (HTS) and LEO constellations provide lower latency, higher bandwidth, and improved service reliability for mission-critical operations. As enterprises prioritize operational continuity and global connectivity, adoption of MSS solutions continues to expand across commercial and government sectors, accelerating overall market growth.
The mobile satellite services market faces a significant restraint due to the substantial capital investment required for satellite deployment, ground infrastructure, spectrum licensing, and specialized communication terminals. Satellite-enabled devices and service subscriptions remain considerably more expensive than conventional terrestrial communication alternatives, limiting affordability for many commercial users and small organizations.
These high costs particularly affect price-sensitive markets and developing economies where communication budgets remain constrained. Small enterprises, regional operators, and consumer applications often delay adoption due to higher equipment acquisition and recurring service expenses. Consequently, market penetration remains concentrated among government agencies, defense organizations, large enterprises, and mission-critical industries, slowing broader commercial adoption despite increasing connectivity requirements.
The rapid expansion of IoT deployments across transportation, logistics, agriculture, energy, and environmental monitoring presents a significant opportunity for the mobile satellite services market. Increasing adoption of hybrid terrestrial-satellite communication architectures enables organizations to maintain continuous connectivity even beyond cellular coverage. Advancements in smaller satellite terminals, software-defined networking, and direct-to-device satellite technologies are further supporting this opportunity.
Mobile satellite service providers are increasingly integrating satellite connectivity with 5G, cloud platforms, and IoT ecosystems to deliver comprehensive communication solutions. Vendors investing in LEO satellite constellations, machine-to-machine (M2M) communication platforms, and satellite-enabled asset monitoring are well positioned to capture new revenue streams. The strongest growth opportunities are expected across industrial IoT, smart transportation, remote asset management, maritime digitalization, and connected defense applications.
Analyst Perspective
The mobile satellite services market is transitioning from traditional voice centric communication toward high speed broadband, IoT connectivity, and integrated satellite terrestrial networking solutions. The growing demand for resilient communications across the defense, transportation, aviation, maritime, and industrial sectors continues to support sustained market expansion. Emerging technologies, including LEO satellite constellations, direct to device connectivity, software-defined satellites, and satellite-enabled 5G integration, are reshaping competitive dynamics. Continued investment in next-generation satellite infrastructure, digital mobility services, and global connectivity platforms is expected to strengthen market growth, while strategic partnerships between satellite operators and terrestrial network providers will become increasingly important.
COVID-19 Impact Analysis
The COVID-19 pandemic had a widespread impact on various industries, including the mobile satellite services sector. Although mobile satellite communications proved beneficial in facilitating uninterrupted communication in remote areas during the pandemic, global supply chain disruptions caused delays in new product and component deliveries. In addition, workforce shortages negatively affected mobile satellite services. To curb the spread of the virus, governments across the globe implemented measures such as travel and material movement restrictions, which significantly impacted industries such as marine and aviation. These industries are among the primary consumers of mobile satellite services for maritime and in-flight connectivity. Consequently, reduced demand from these sectors harmed the growth of mobile satellite services. However, as the market recovers from the pandemic's adversities, it is expected to grow over the forecast period.
Service Insights
Based on service, the data segment led the market with the largest revenue share of 74.8% in 2025. The segment is anticipated to grow at the fastest rate during the forecast period. One of the primary factors driving the growth of the segment is the increasing demand from industries such as aviation, marine, emergency response, and oil and gas, for high-capacity and high-speed data services in challenging and remote locations. These sectors require reliable and secure communication of data for various applications such as asset tracking, video surveillance, and remote monitoring. Furthermore, the need for a consistent and dependable connection is driving growth in this market segment, especially in urban and suburban areas where terrestrial infrastructure is available.
The services segment is anticipated to register substantial growth over the forecast period. The growth in this market segment can be attributed to the rising demand for dependable and secure communication services in remote areas and regions affected by disasters, where terrestrial infrastructure may not be available or damaged. This demand is driven by various industries, including maritime, oil and gas, emergency response, and aviation, where reliable voice communication is essential for operational safety and efficiency. Additionally, the adoption of 5G technology and High-Throughput Satellite (HTS) systems is fueling the growth of voice services in the mobile satellite services industry. 5G technology provides higher bandwidth and faster data rates, while HTS systems offer increased capacity and more efficient utilization of satellite resources, allowing mobile satellite service providers to offer advanced voice services, such as high-definition voice and video calls. Furthermore, the use of Software Defined Radios (SDRs) is enabling MSS providers to offer more scalable and flexible voice services, as SDRs can adapt to different network configurations and frequency bands.
Application Insights
Based on application, the land mobile segment led the market with the largest revenue share of 35.6% in 2025. The segment is also estimated to grow at the fastest CAGR during the forecast period. The growth of the segment is attributed to its extensive usage of mobile satellite services in land mobile applications that require reliable and secure connectivity in remote locations where terrestrial infrastructure is not feasible. For instance, in mining operations, MSS can be utilized for remote monitoring purposes such as equipment monitoring, asset tracking, and safety monitoring, enhancing productivity and safety while reducing costs.
In emergency response scenarios, such as natural disasters or accidents, where terrestrial communication infrastructure may be damaged or disrupted, MSS can serve as a dependable means of communication and data connectivity for first responders and emergency management organizations. By utilizing mobile satellite services, organizations can effectively coordinate their efforts and communicate with each other, which increases the adoption of MSS for land mobile applications.
The M2M segment is anticipated to witness significant growth through the forecast period. The ability of MSS to offer secure connectivity for M2M services operating in inaccessible areas, where terrestrial networks may not be available or reliable, is a major factor contributing to the segment growth. M2M services involve the exchange of data between two or more devices without human intervention, and MSS capabilities are increasingly being integrated into these devices. This allows companies to track and monitor the movement, location, and condition of assets such as containers, vehicles, and other equipment. MSS is also being used for remote monitoring and control of equipment and systems in various industries, including utilities, agriculture, and environmental monitoring. Such factors bode well for the growth of the segment over the forecast period.
End User Insights
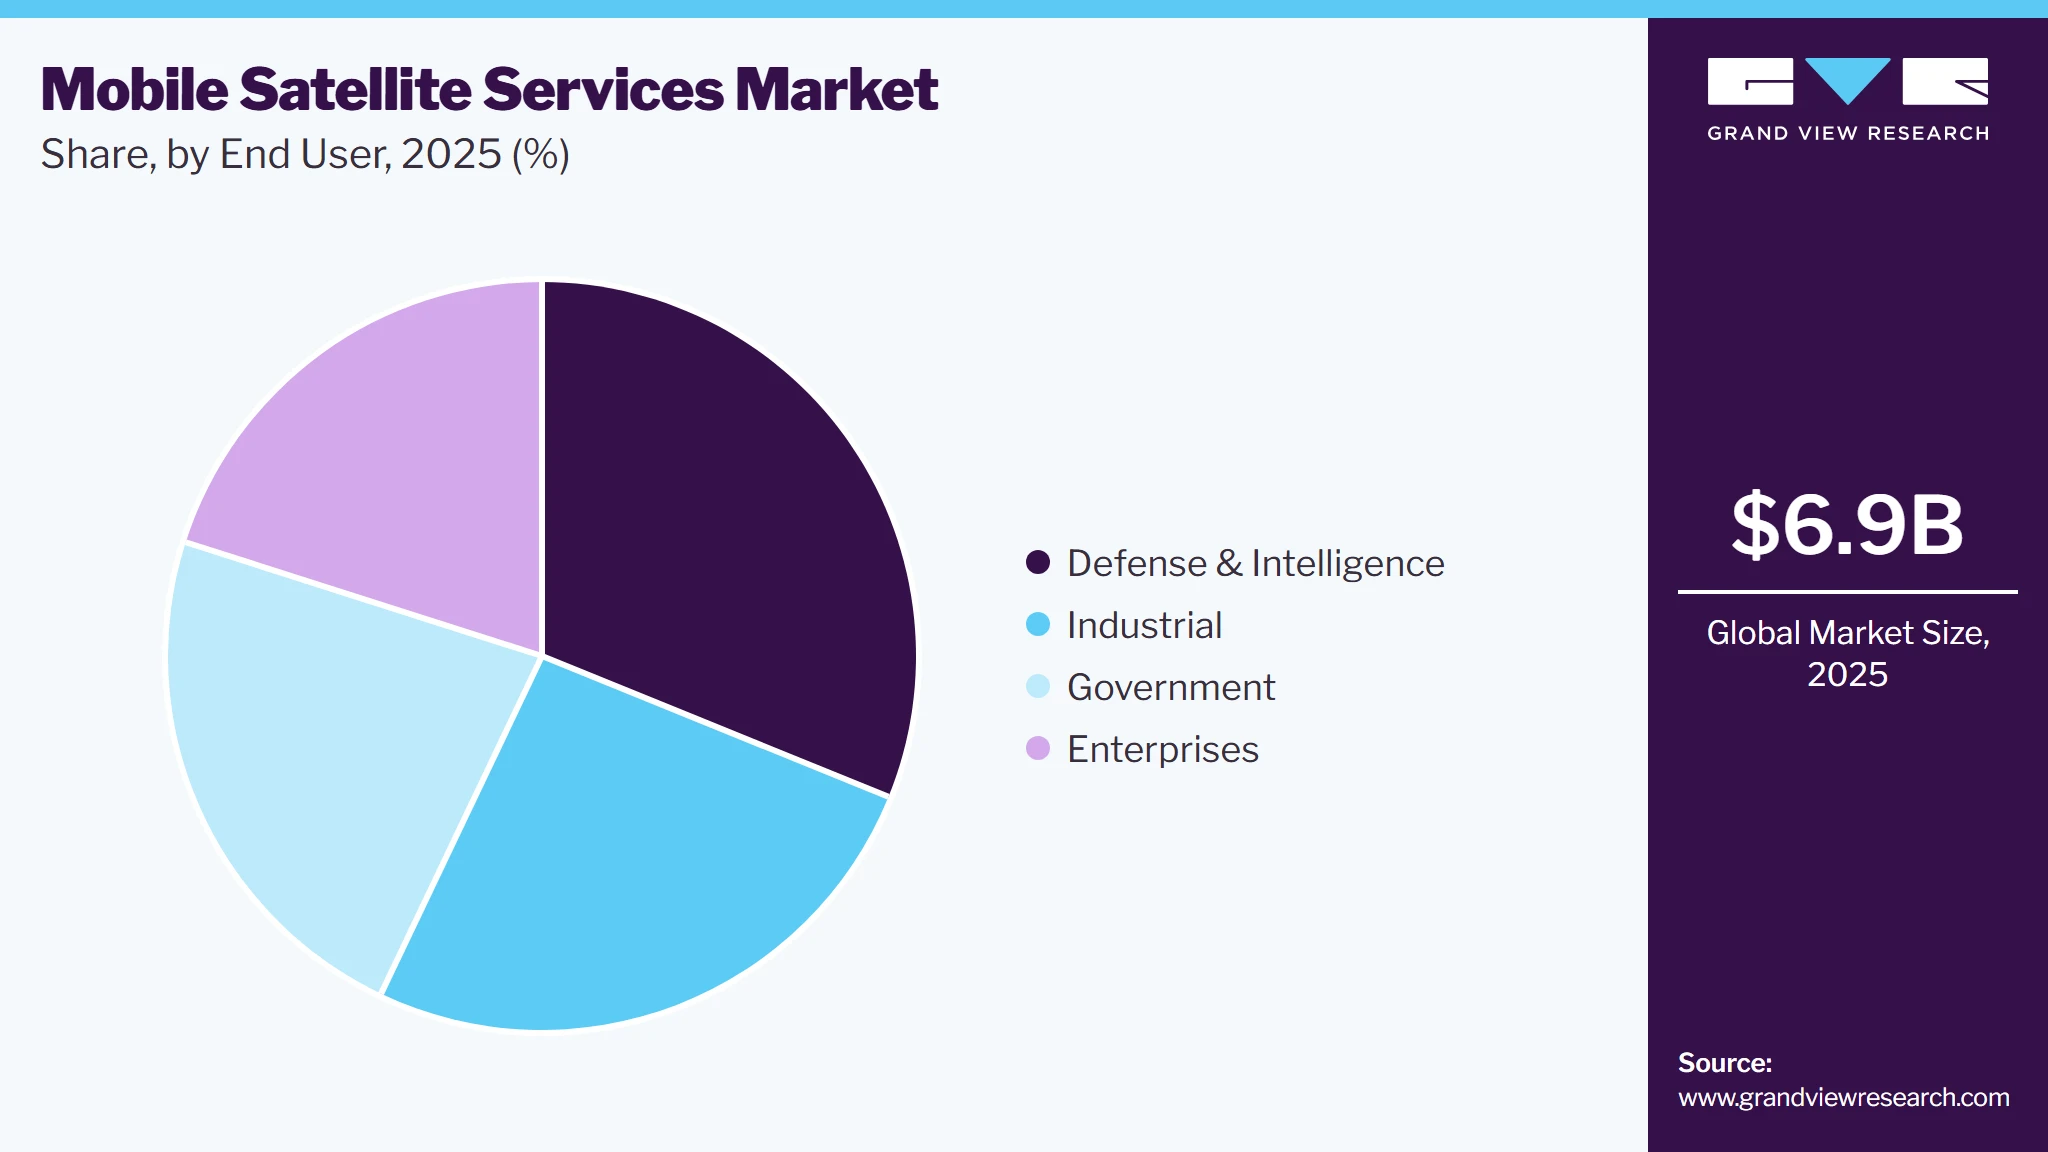
Based on end-user, the defense & intelligence segment led the market with the largest revenue share of 31.1% in 2025. The defense and intelligence sector has witnessed an increase in the adoption of mobile satellite services due to the growing demand for reliable and secure communication in remote and challenging environments. These services are employed in unmanned aerial vehicles to offer real-time Intelligence, Surveillance, and Reconnaissance (ISR) capabilities. Furthermore, the growing utilization of these services for secure data and voice communication in tactical environments enables troops to communicate effectively in areas where terrestrial networks are not feasible or dependable, which is driving the growth of this segment.
 To learn more about this report, Download Free Sample Report
The industrial segment is expected to witness the highest growth rate during the forecast period. The increased use of machine learning and IoT technologies in industrial settings is driving the adoption of MSS for remote monitoring and data transfer of devices and sensors. This enables businesses to make data-driven decisions and improve their operational efficiency.
Applications of mobile satellite services include remote asset management in the mining and oil & gas industries, where they enable companies to monitor and control equipment and facilities from afar. These services also provide reliable communication capabilities for workers in remote locations. Furthermore, the growing need for sustainable energy is boosting the use of MSS in the renewable energy sector, particularly for the remote monitoring and control of solar and wind farms.
Regional Insights
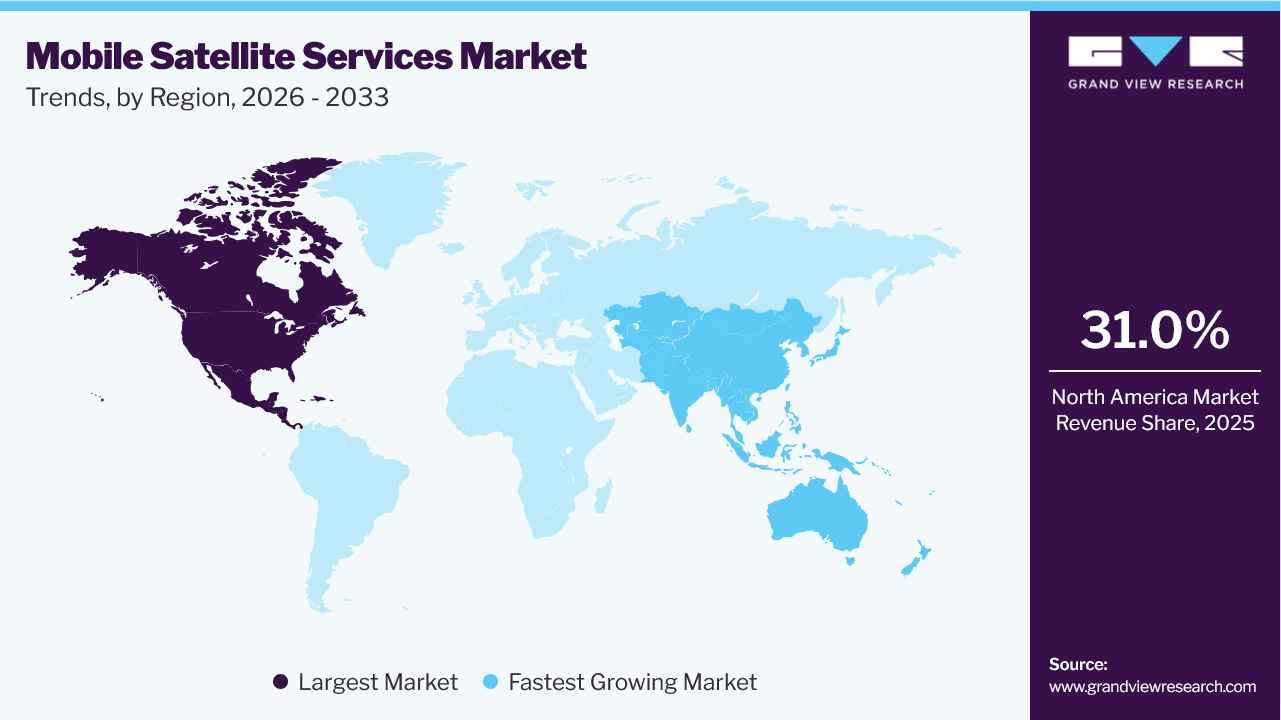
North America dominated the global mobile satellite services market with the largest revenue share of 32.9% in 2025. The increasing adoption of mobile satellite services in North America is driven by the necessity for dependable and accessible connectivity in remote regions. Several regions in North America, particularly rural and isolated areas, lack access to conventional telecommunications infrastructure. Mobile satellite services serve as a viable substitute for traditional networks, allowing individuals in these areas to remain connected.
 To learn more about this report, Download Free Sample Report
U.S. Mobile Satellite Services Market Trends
The mobile satellite services market in the U.S. held the largest share in the North America region in 2025. The mobile satellite services market in the U.S. plays significant role in the growth of regional industry. Presence of multiple key players in the country, accessibility to advanced technology assistance, and increasing investments by the U.S.-based companies in this market primarily contribute to market growth. Partnerships among key companies in the country are expected to develop further growth opportunities. For instance, in May 2026, AT&T, T-Mobile, and Verizon announced plan to launch new joint venture aimed at improving direct-to-device communications capabilities in the U.S., with the help of satellite-powered technologies. The joint venture is expected to expand mobile connectivity for wireless connection users and address coverage gaps.
Asia Pacific Mobile Satellite Services Market Trends
The Asia Pacific region is experiencing the highest growth in the mobile satellite services market, driven by several factors, including the growing proliferation of smartphones, the development of digital infrastructure, and efforts taken by regional governments to implement 5G networks. Advancements in digital infrastructure, such as high-speed internet networks, fiber-optic connectivity, and satellite communication systems, are rapidly taking place in the region. These developments are generating opportunities for mobile satellite service providers to offer dependable and high-quality communication services to underserved and remote regions, where traditional networks may be limited. The enhanced digital infrastructure is facilitating better connectivity, and mobile satellite services are being utilized to fill the gaps in coverage and provide connectivity in remote areas.
Key Mobile Satellite Services Company Insights
The mobile satellite services market can be described as a moderately consolidated market with the presence of established mobile network operators, technology providers, and startups, each with their own unique strengths and capabilities. Key market players are seeking partnership and collaboration opportunities to provide innovative solutions to their customers and gain a significant share in the mobile satellite services industry.
Key Mobile Satellite Services Companies
The following key companies have been profiled for this study on the mobile satellite services market.
-
Viasat, Inc.
-
SES S.A.
-
Intelsat S.A.
-
Iridium Communications Inc.
-
Vizocom Company.
-
Speedcast
-
Telesat
-
EchoStar Corporation
-
Thuraya Telecommunications Company
-
SKY Perfect JSAT Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Viasat, Inc., Iridium Communications Inc., SES S.A., Intelsat S.A.)
- These players are focused on investing in next-generation satellite constellations, expanding managed connectivity services, strengthening government and enterprise contracts, developing hybrid satellite-terrestrial solutions, and pursuing strategic partnerships and acquisitions.
- These players have extensive global satellite coverage, diversified service portfolios, established customer base, strong financial resources, advanced satellite infrastructure, and long-term government and defense relationships.
- Heavy reliance on government and large enterprise customers exposes providers to long procurement cycles and changing budget priorities. This can delay contract awards, slow project deployment, and affect revenue stability.
Emerging Players (Thuraya Telecommunications Company, Telesat Corporation, Speedcast)
- These players are focused on specialized regional services, enterprise mobility solutions, managed communication services, niche industry applications, and technology partnerships to expand market presence.
- These players have Strong expertise in targeted market segments, flexible service offerings, specialized industry knowledge, and growing investments in next-generation connectivity solutions.
- Limited access to satellite capacity and ground infrastructure can constrain service availability and network scalability. This may affect their ability to meet growing customer demand across diverse geographic regions.
Recent Developments
-
In March 2026, Orange, signed signing of a Memorandum of Understanding with a joint venture between Vodafone and AST SpaceMobile, AST SpaceMobile and Satellite Connect Europe for direct-to-device mobile services enhancement and complement its terrestrial coverage in underserved areas.
-
In May 2025, Iridium Communications Inc. partnered with Syniverse Technologies, LLC to facilitate the Iridium NTN Direct service rollout and enable continuous connectivity for mobile network operators (MNOs) customer base worldwide through Syniverse platform integration,.
Mobile Satellite Services Report Scope
Report Attribute
Details
Market size in 2025
USD 6.9 billion
Estimated market size in 2026
USD 7.3 billion
Projected market size by 2033
USD 12.0 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Service, application, end-user, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
Viasat, Inc.; SES S.A.; Intelsat S.A.; Telesat Corporation; EchoStar Corporation; Thuraya Telecommunications Company; Iridium Communications Inc.; SKY Perfect JSAT Holdings Inc.; Vizocom; Speedcast
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Mobile Satellite Services Market Report Segmentation
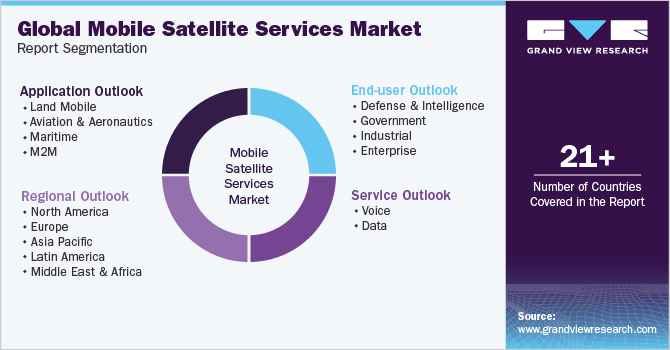
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global mobile satellite services market report based on Service, application, end user, and region:
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Voice
-
Data
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Land Mobile
-
Aviation & Aeronautics
-
Maritime
-
M2M
-
-
End-user Outlook (Revenue, USD Million, 2021 - 2033)
-
Defense & Intelligence
-
Government
-
Industrial
-
Enterprise
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Research Methodology
The Mobile Satellite Services market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Mobile Satellite Services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Voice
Revenue generated from satellite-based mobile voice communication services, airtime subscriptions, prepaid and postpaid voice plans, emergency communication services, roaming charges, secure voice services, and associated communication terminals supporting voice transmission.
Data
Revenue generated from satellite mobile internet services, internet connectivity subscriptions, bandwidth usage, IP-based communication services, satellite backhaul, IoT data connectivity, machine-to-machine (M2M) communications, managed satellite network services, and value-added data communication solutions.
Segment - Application
Revenue capture definition
Land Mobile
Revenue generated from satellite communication services used by emergency responders, military units, mining, oil & gas, transportation, utilities, forestry, humanitarian organizations, and remote field operations requiring mobile connectivity.
Aviation & Aeronautics
Revenue generated from satellite connectivity services supporting commercial airlines, business aviation, military aircraft, air traffic communication, cockpit connectivity, passenger broadband, aircraft tracking, and flight safety communications.
Maritime
Revenue generated from satellite communication solutions for commercial shipping, fishing fleets, offshore energy platforms, naval operations, cruise ships, vessel monitoring, crew welfare services, and maritime safety communications.
M2M Services
Revenue generated from satellite-enabled machine-to-machine communication services supporting IoT devices, remote asset monitoring, fleet management, smart agriculture, environmental monitoring, pipeline monitoring, industrial automation, and telemetry applications.
Segment - End-user
Revenue capture definition
Defense & Intelligence
Revenue generated from secure satellite communications, tactical communication systems, battlefield connectivity, intelligence gathering, surveillance, reconnaissance operations, encrypted communications, and military mobility applications.
Government
Revenue generated from satellite communication services used by public safety agencies, disaster management authorities, border security, emergency response organizations, law enforcement, and civil administration communication networks.
Industrial
Revenue generated from satellite connectivity solutions deployed across oil & gas, mining, energy, utilities, construction, transportation, logistics, and other industrial operations requiring remote communication infrastructure.
Enterprises
Revenue generated from satellite communication services purchased by commercial enterprises for business continuity, remote office connectivity, corporate communications, mobile workforce support, and hybrid network connectivity solutions.
Estimation Model
Layer Name
Key Question
Description
Addressable End-User Demand Assessment
Which industries require mobile satellite communication services?
This layer estimates the addressable demand across defense, government, maritime, aviation, industrial, enterprise, and IoT applications. It evaluates communication requirements in remote and underserved regions where terrestrial networks are unavailable. Regional adoption intensity, mobility requirements, and mission-critical communication needs are analyzed to establish the total addressable market.
Service & Application Adoption Analysis
Which Mobile Satellite Services are being adopted across applications?
This layer analyzes the adoption of voice and data services across land mobile, maritime, aviation, and M2M applications. It evaluates usage intensity, subscription models, bandwidth consumption, and service penetration across customer segments. Technology migration toward broadband satellite services is also incorporated into demand estimation.
Technology & Infrastructure Assessment
Which technological developments are influencing market expansion?
This layer evaluates investments in LEO and GEO satellite constellations, high-throughput satellites, gateway infrastructure, satellite terminals, software-defined satellites, and hybrid satellite-terrestrial networks. It also assesses regulatory developments, spectrum availability, and network modernization initiatives that influence service deployment. These technology investments determine future capacity expansion and service quality improvements.
Revenue Forecast & Competitive Benchmarking
How will market revenues evolve across regions and vendors?
This layer combines subscriber growth, average revenue per user (ARPU), enterprise adoption, government contracts, and industry-specific deployment trends to estimate market revenues. Competitive positioning, service portfolio expansion, geographic presence, pricing strategies, and technology investments are evaluated to forecast long-term market growth and vendor market shares.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Mobile Satellite Services Market Opportunity Assessment
- Country/region-wise market sizing and forecasts
- Analysis of demand, adoption trends, and regulatory landscape
- Identification of high-growth regions and investment hotspots
- Identified region-specific growth opportunities
- Supported expansion and go-to-market strategy
- Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Mobile Satellite Services Market
- Criss-cross market analysis by service, application, end-user
- Demand and adoption assessment across key segments
- Segment attractiveness and growth potential benchmarking
- Identified high-potential market segments
- Supported targeted product positioning and marketing strategy
- Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Mobile Satellite Services Market
- Benchmarking of key competitors across products, pricing, partnerships, and innovation
- Comparative assessment of market share, capabilities, and strategies
- Analysis of competitive strengths, gaps, and differentiation areas
- Identified competitive white spaces and growth gaps
- Supported strategic positioning and differentiation
- Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global mobile satellite services market size was estimated at USD 6.9 billion in 2025 and is expected to reach USD 7.3 billion in 2026
The global mobile satellite services market is expected to grow at a compound annual growth rate of 7.3% from 2026 to 2033, reaching USD 12.0 billion by 2033.
Some key players operating in the mobile satellite services market include Viasat, Inc., SES S.A., Intelsat S.A., Telesat Corporation, EchoStar Corporation, Thuraya Telecommunications Company, Iridium Communications Inc., SKY Perfect JSAT Holdings Inc., Vizocom, Speedcast.
North America dominated the market with the largest revenue share of 32.9% in 2025.
Land Mobile segment held the largest market share of 35.6% in 2025, and it is the fastest growing over the forecast period.
Defense & Intelligence segment accounted for the largest revenue share of 31.1% in 2025, while industrial is the fastest growing over the forecast period.
Asia Pacific held the fastest growing CAGR over the forecast period.
Data segment dominated the market, with a revenue share of 74.8% in 2025. One of the primary factors driving the growth of the segment is the increasing demand from industries like aviation, marine, emergency response, and oil and gas, for high-capacity and high-speed data services in challenging and remote locations.
About the Author(s)
Communication Services Research Team
Technology · Communication ServicesThis report was authored by the communication services research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communication services segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


