
- Home
- »
- Clinical Diagnostics
- »
-
Multi Cancer Early Detection Market Size Report, 2026-2033GVR Report cover

Multi Cancer Early Detection Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Liquid Biopsy, Gene Panel, LDT & Others), By End Use (Hospitals, Diagnostic Laboratories), By Region (North America, Europe, Latin America, Asia Pacific, MEA), And Segment Forecasts
Market Size, 2025
$1.3BMarket Estimate, 2026
$1.5BMarket Forecast, 2033
$4.6BCAGR, 2026–2033
17.2%Multi Cancer Early Detection Market Summary
The global multi cancer early detection market size was estimated at USD 1.3 billion in 2025 and is projected to grow from USD 1.5 billion in 2026 to USD 4.6 billion by 2033, growing at a CAGR of 17.2% from 2026 to 2033. The North America market held the largest share of 37.6% of the global market in 2025. This market growth is attributed to an increase in the prevalence of multiple cancers aided by the growing need to provide efficient methods to detect them at early stages to enable timely appropriate treatment.
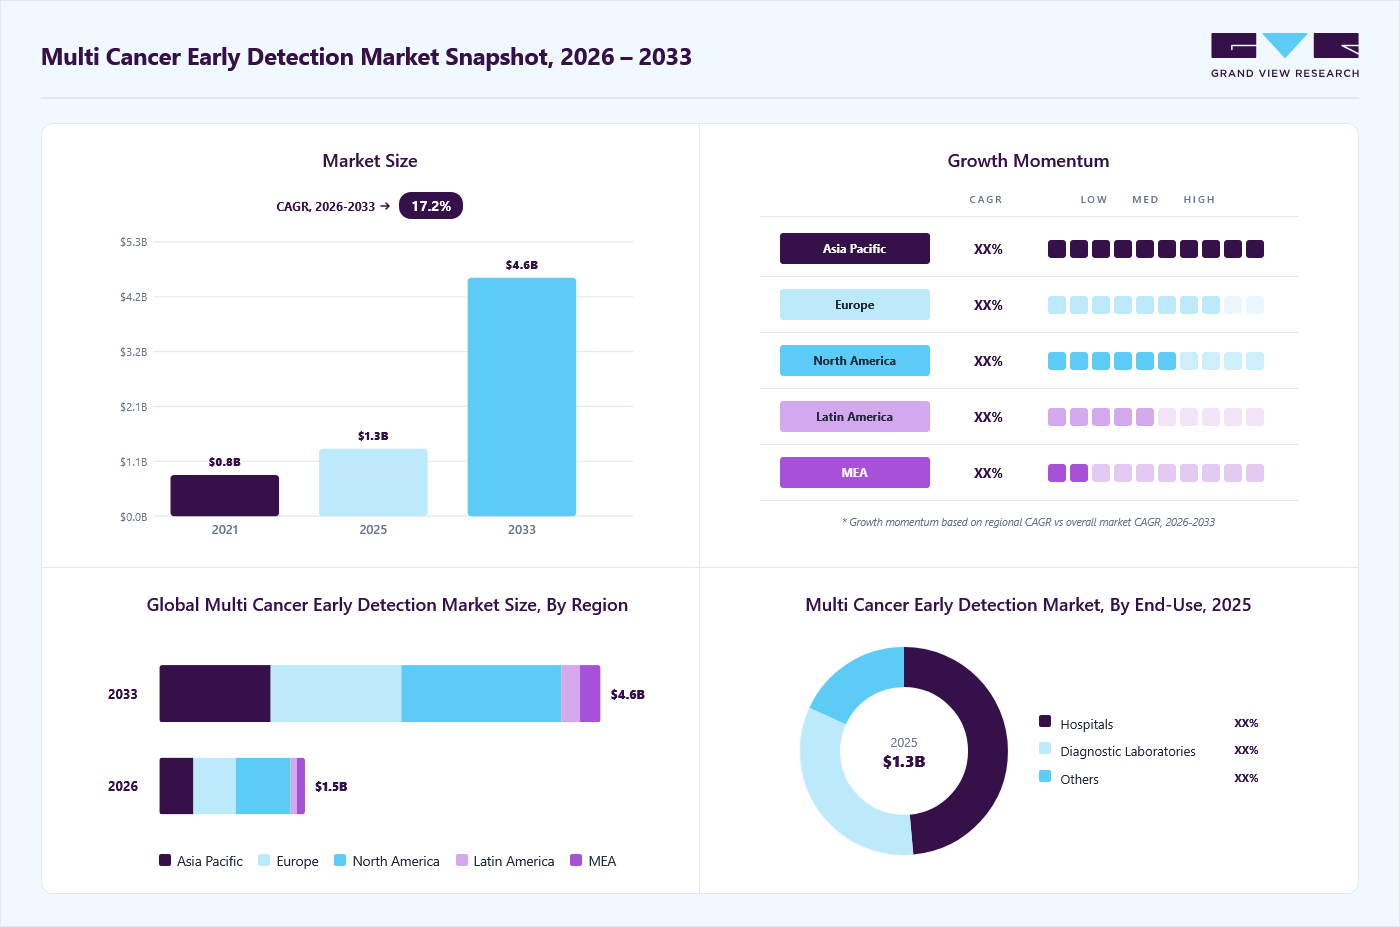 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The gene panel, LDT, and other segments led the market in 2025 and liquid biospy segment is anticipated to grow at the fastest CAGR over the forecast period.
- By end-use: The hospitals segment led the market with the largest revenue share of 48.5% in 2025.
Regional Highlights
- Largest regional market: North America (37.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Estimated market size in 2026: USD 1.5 Billion
- Projected market size by 2033: USD 4.6 Billion
- CAGR (2025-2030): 17.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, according to the International Agency for Research on Cancer (IARC), over 20.7 million new cases are expected in 2023, and over 35 million cases are predicted to occur by 2050. Moreover, early detection of cancer, particularly when it is localized and has not metastasized, significantly enhances the effectiveness and efficiency of treatment. This further enhances the need for advanced diagnostic solutions, which drives market growth. Emerging biological and informational technologies, including nanotechnology, big data analytics, artificial intelligence (AI), machine learning (ML), and genome sequencing, are revolutionizing diagnosis and therapy. These innovations drive breakthroughs in precision medicine, enabling early detection, personalized treatment plans, and improved patient outcomes.For instance, AI/ML algorithms are employed by companies like Google Health to enhance imaging diagnostics, while genome sequencing technologies by firms like Illumina facilitate the identification of genetic predispositions. Multi-cancer early detection (MCED) screening aims to expand the range of cancers detectable through screening methods and identify cancer in asymptomatic individuals. For instance, GRAIL's Galleri test makes it possible to screen for multiple types through a single blood test, targeting early-stage where treatment is most effective. These advancements hold the potential to significantly improve survival rates and reduce healthcare costs by identifying tumors at a stage where interventions can have the greatest impact.
 To learn more about this report, Download Free Sample Report
Moreover, the impact of early detection on survival rates becomes evident when examining outcomes for specific types. For instance, over 90% of women diagnosed with breast cancer at its earliest stages survive for at least five years, compared to only 15% of women diagnosed at the most advanced stages, which constitute approximately 15% of cases. Similarly, more than 80% of lung cancer patients survive for a minimum of one year if diagnosed and treated in the earliest stages. This is in stark contrast to a mere 15% survival rate for those identified at the disease's most advanced stages. These statistics highlight the life-saving potential of early diagnosis and timely intervention.
Furthermore, rising awareness about early diagnosis, available treatment options, and advancements in medical therapies have significantly improved patient outcomes. According to the OECD, approximately 2.7 million people in the European Union were projected to receive a cancer diagnosis in 2020, with countries such as Ireland, Belgium, Denmark, and the Netherlands reporting higher incidence rates. Cancer remains the second leading cause of mortality in Europe, following cardiovascular diseases, with an estimated 1.3 million deaths attributed to cancer in 2020.
Early detection plays a major role in reducing cancer-related mortality, particularly through the implementation of effective screening programs. Evidence demonstrates that early detection can improve patient survival rates by five to ten times compared to late-stage detection. For instance, the five-year survival rate is only 21% for patients diagnosed after cancer has metastasized, compared to 89% when the disease is identified early while still localized. These statistics underscore the critical importance of early diagnosis in improving survival outcomes and enhancing the quality of life for cancer patients.
However, high costs associated with advanced diagnostic technologies, such as liquid biopsy tests, genome sequencing, and AI-driven analytics, limit accessibility for a significant portion of the population, restrain market growth. In addition, the regulatory environment poses challenges, as gaining approval for new MCED technologies often requires extensive clinical trials and validation processes, delaying market entry. Limited awareness and uncertainty regarding the accuracy and reliability of MCED tests among healthcare providers and patients further hinder adoption. Moreover, inadequate healthcare infrastructure in some regions delays the implementation of comprehensive screening programs, while ethical concerns around false positives, overdiagnosis, and patient anxiety create resistance.
Market Dynamics
The multi-cancer detection market is evolving as healthcare systems seek approaches that support earlier cancer identification through minimally invasive screening methods. Growth is supported by advances in liquid biopsy technologies, increasing availability of genomic and methylation-based testing platforms, and rising interest in population level cancer screening programs. Market participants are focusing on generating clinical evidence, expanding physician access, and strengthening partnerships with diagnostic laboratories to support adoption. A notable example reflects this trend. For instance, in February 2025, GRAIL partnered with Quest Diagnostics to integrate the Galleri multi cancer early detection test into Quest's ordering network, enabling broader access through laboratory and electronic health record systems. At the same time, regulatory engagement and large-scale clinical studies are shaping market development by evaluating test performance and clinical utility. Continued investments in research, reimbursement expansion, and commercialization activities are expected to support market progression as stakeholders work to establish the role of multi cancer early detection testing within routine cancer screening pathways.
The growing volume of clinical evidence supporting multi-cancer early detection testing is a key factor driving market growth. Healthcare providers and policymakers are increasingly evaluating blood-based screening approaches that can identify multiple cancer types before symptoms appear. Large scale studies are helping establish the clinical utility, accuracy, and feasibility of integrating these tests into routine care pathways. The market is also benefiting from support from government agencies and research organizations that are investing in screening innovation to improve cancer outcomes. Such initiatives strengthen physician confidence and encourage broader stakeholder participation across healthcare systems. An important development highlights this trend. For instance, in 2025, the National Cancer Institute launched the Vanguard Study under the Cancer Screening Research Network to evaluate multi-cancer detection blood tests in individuals aged 45 to 75 years. The study supports the generation of evidence required for future adoption decisions and contributes to the advancement of screening strategies aimed at improving early cancer detection rates.
Despite technological progress, the market continues to face challenges related to demonstrating long term clinical benefits and integration into established screening frameworks. Multi cancer early detection tests must show not only the ability to detect cancers earlier but also meaningful improvements in patient outcomes. Healthcare providers and payers often require evidence that screening programs lead to reductions in advanced disease burden and support cost effective care delivery. Questions regarding follow up procedures, management of positive findings, and alignment with existing screening recommendations can slow adoption. This challenge is reflected in recent clinical findings. For instance, in 2026, GRAIL announced topline results from the NHS Galleri trial involving approximately 142,000 participants in England. While the study reported positive findings related to earlier stage cancer detection, it did not achieve its primary objective of demonstrating a statistically significant reduction in cancers diagnosed at Stage III or Stage IV, highlighting ongoing evidence requirements for widespread implementation.
The expansion of reimbursement pathways and healthcare coverage presents a significant opportunity for the multi-cancer early detection market. Broader insurance support can improve patient access to screening services and encourage physicians to incorporate these tests into preventive care strategies. As more clinical evidence becomes available, payers are increasingly assessing the value of early cancer detection in reducing future treatment costs and improving patient management. Market participants are actively pursuing reimbursement initiatives alongside commercialization efforts to strengthen adoption. Improved coverage can also support greater utilization through hospitals and diagnostic laboratories, which represent key end users within the market. A notable example demonstrates this opportunity. For instance, in 2025, TRICARE added GRAIL's Galleri multi cancer early detection test as a covered benefit for eligible individuals aged 50 years and older who are at elevated risk for cancer. This development represents a meaningful step toward expanding access and supporting broader acceptance of multi-cancer screening technologies.
Analyst Perspective
The latent tuberculosis infection (LTBI) detection market is expected to witness sustained growth, driven by increasing global efforts toward tuberculosis elimination, expanding screening initiatives among high-risk populations, and growing awareness of the importance of early identification of latent infections. LTBI detection tests serve as essential tools for identifying individuals at risk of developing active tuberculosis, supporting preventive treatment strategies and public health surveillance programs. The market is benefiting from the increasing adoption of interferon-gamma release assays (IGRAs), which offer improved specificity and operational advantages compared to traditional tuberculin skin tests, particularly in BCG-vaccinated populations. Furthermore, favorable recommendations from global health organizations, rising investments in tuberculosis control programs, and expanding laboratory diagnostic infrastructure are supporting market development. Ongoing advancements in immunodiagnostic technologies, automated laboratory workflows, and broader integration of LTBI screening into routine healthcare and infectious disease management programs are expected to strengthen the market’s long-term growth outlook.
Type Insights
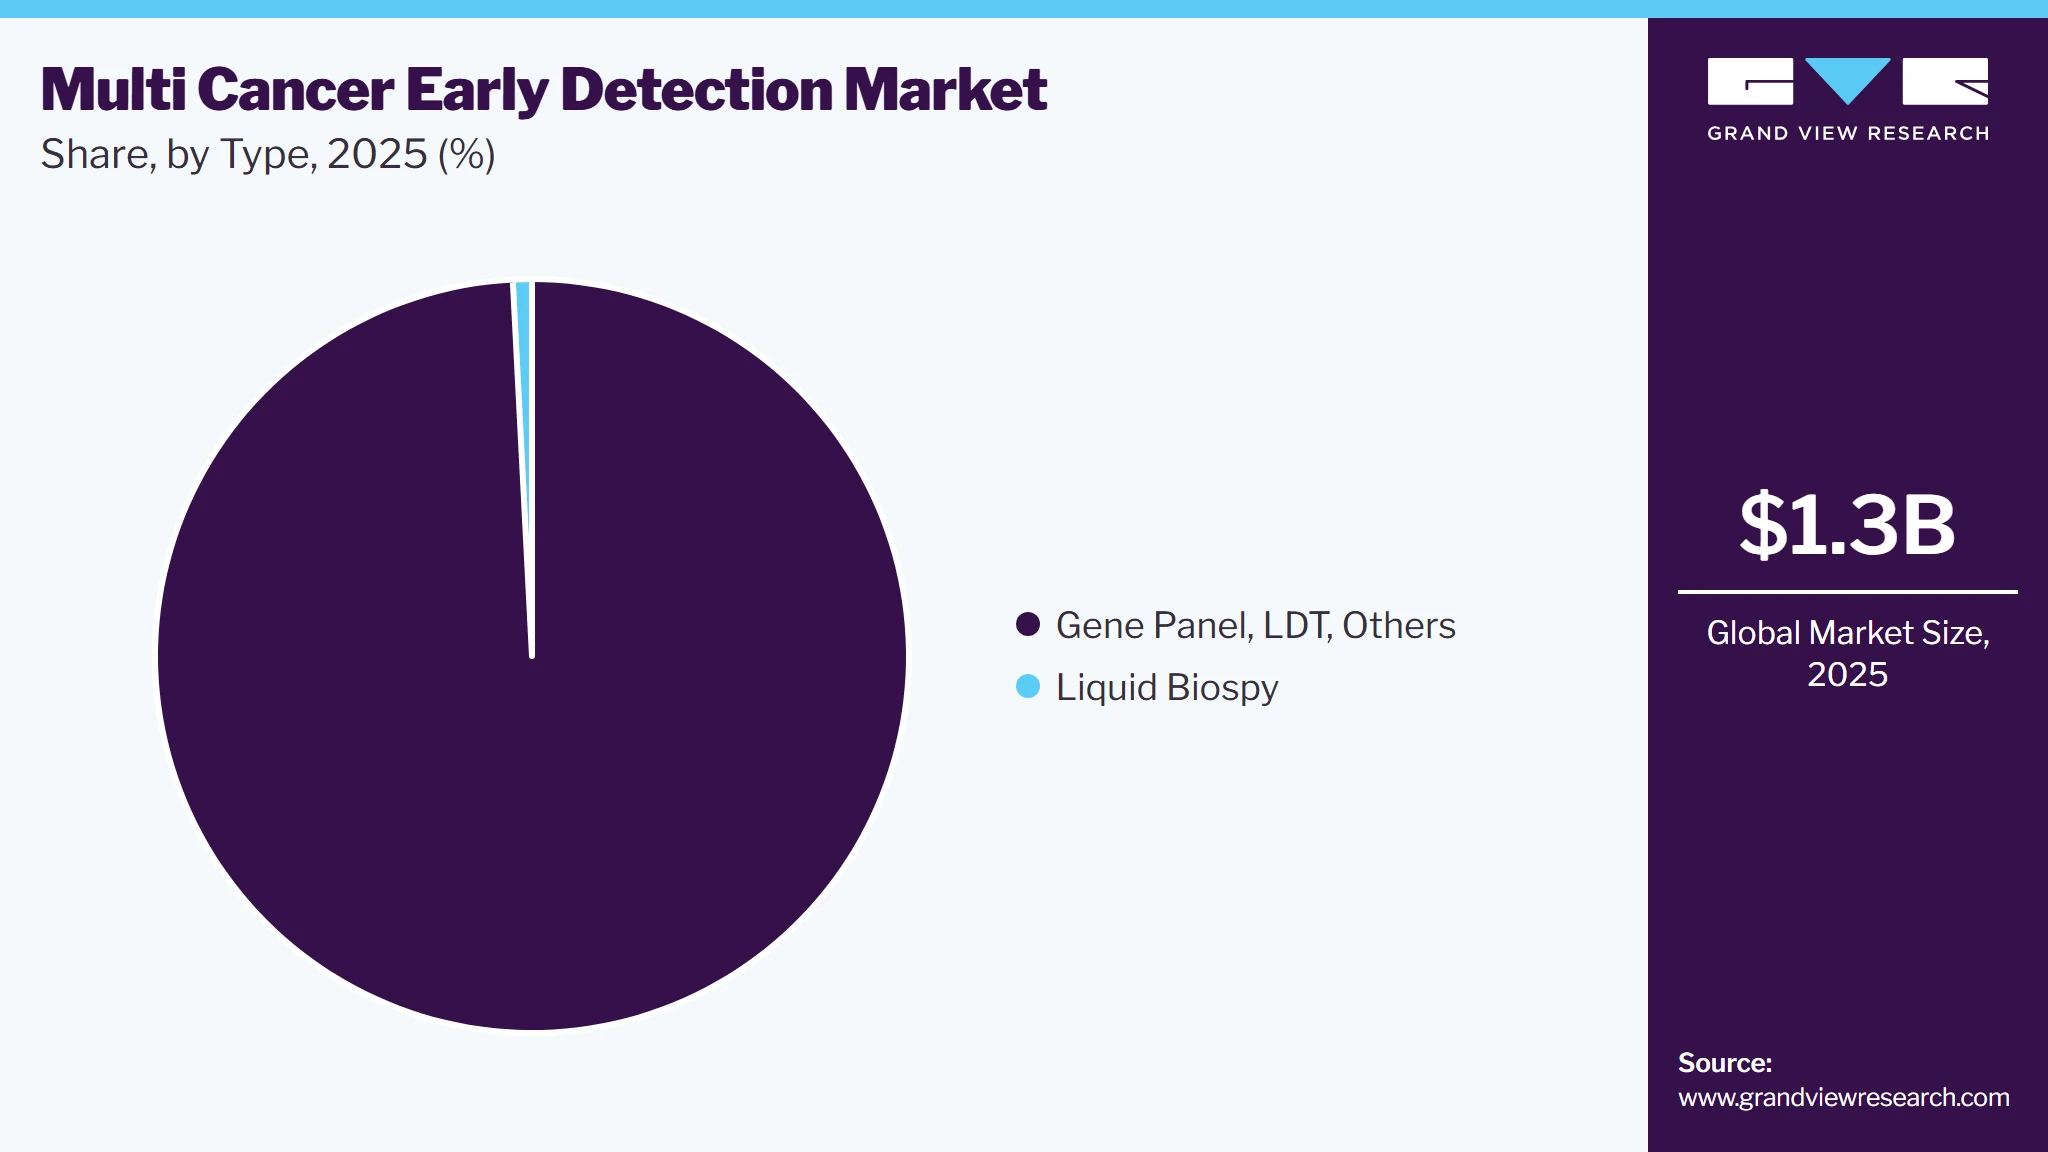
Based on type, the gene panel, LDT, and other segments led the market in 2025 and liquid biospy segment is anticipated to grow at the fastest CAGR over the forecast period. The growth of this segment is largely driven by the non-requirement of FDA approval requirements for laboratory-developed tests (LDTs) in diagnostic laboratories, allowing for faster deployment and adoption. Advancements in next-generation sequencing (NGS), or massively parallel sequencing, have transformed the landscape of genetic testing for risk assessment. These technologies enable comprehensive and efficient genetic profiling, enhancing the scope of detection. Moreover, panel-based tests, compared to traditional BRCA1/2 genetic testing, offer broader insights into inherited risks of breast and ovarian cancers while providing higher clinical value for detecting hereditary risks associated with other malignancies, such as pheochromocytoma-paraganglioma and colorectal cancer.
 To learn more about this report, Download Free Sample Report
Liquid biopsy is anticipated to grow fastest over the forecast period. The segment's growth is attributed to the increasing number of players receiving funding from investors to develop new tests. Liquid biopsy is an advanced testing technology for detecting tumor-related genetic alterations. It has also been used to stratify tumors to enable appropriate treatment through precision oncology. For instance, in July 2024, Guardant Health, Inc. announced an upgrade to its industry-leading Guardant360 liquid biopsy test. The enhanced version now analyzes biomarkers across 739 genes, ten times more cancer biomarkers than the previous duplication. This upgraded test provides the capability to detect a broad range of emerging biomarkers, allowing for a more precise characterization of cancer and offering much higher sensitivity in quantifying disease burden. The biomarkers, or gene alterations, identified by the test empower oncologists to tailor targeted treatment strategies most effective for patients with advanced cancer, ultimately improving treatment outcomes.
End Use Insights
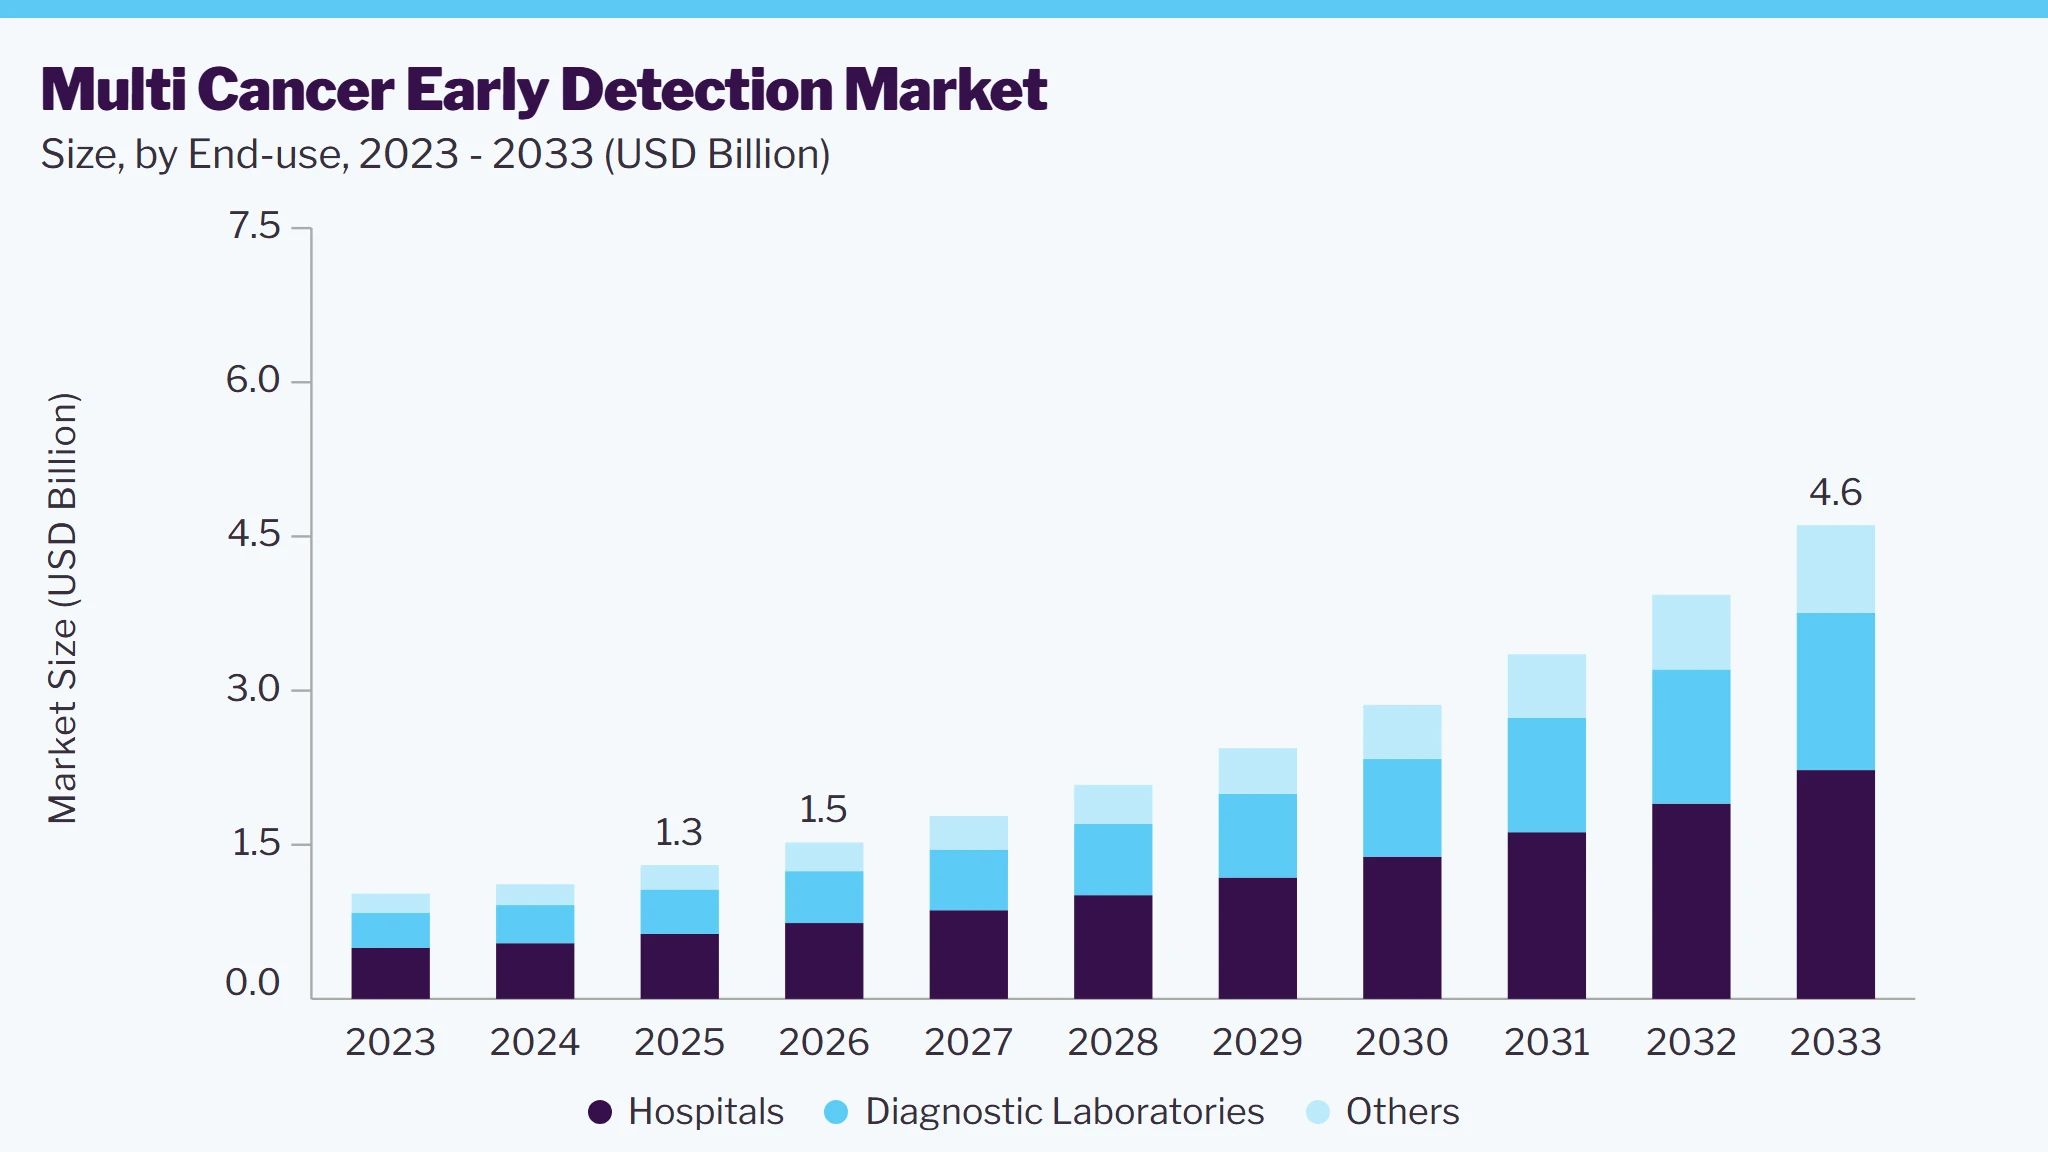
Based on end use, the hospitals segment led the market with the largest revenue share of 48.5% in 2025. The growth of this segment can be attributed to the increasing preference for hospitals that offer a comprehensive range of services under one roof. One of the key advantages of hospitals conducting multi-cancer diagnostics is the ability to provide test results even in emergencies. Advances in hospital laboratories are essential to meet the evolving needs of patients, and many hospitals are expanding their service offerings to include a broader array of diagnostic and treatment options. For instance, in May 2024, University Hospitals announced the availability of a new detecting test, the GRAIL Galleri test, that can detect 50 different types of tumors.
Diagnostic laboratories is projected to grow significantly over the forecast period. Several factors, including increased awareness of personalized medicine, technological advancements, and the growing demand for affordable healthcare services, drive the growth of the diagnostic laboratory segment. In addition, government initiatives to provide support, such as compensation for diagnostic tests, are expected to fuel market expansion further. Many healthcare institutions are also partnering with laboratories to integrate a variety of clinical tests into their services. For example, in June 2023, the Baylor Scott & White Research Institute, in collaboration with Exact Sciences Corporation, launched a multi-cancer early detection program to improve cancer interception rates in Texas.
Regional Insights
Europe multi cancer early detection market dominated and accounted for a 36.05% share in 2024, owing to rising awareness of cancer prevention, advancements in diagnostic technologies, and increased healthcare investments. Growing government-funded screening programs, such as those focusing on breast, colorectal, and cervical cancers, have enhanced the adoption of innovative diagnostic solutions. Furthermore, the growing demand for personalized medicine and precision oncology, which depend on advanced tests like MCED, further accelerates market growth. The introduction of cutting-edge technologies, including liquid biopsy and next-generation sequencing, is enhancing the accuracy and effectiveness of detection.
UK Multi Cancer Early Detection Market Trends
The multi cancer early detection market in the UK is expected to grow over the forecast period due to the presence of complex healthcare infrastructure, the launch of novel products, and collaborations between key market players.
France multi cancer early detection market is expected to grow over the forecast period due to increased government investments in healthcare and cancer prevention programs, aided byrising demand for advanced diagnostic solutions. The country's focus on enhancing early detection and personalized medicine is driving the adoption of these technologies.
The multi cancer early detection market in Germany is expected to grow over the forecast period due to the growing integration of innovative diagnostic technologies, such as liquid biopsy and next-generation sequencing, which is driving widespread adoption of multi-cancer screening solutions.
North America Multi Cancer Early Detection Market Trends
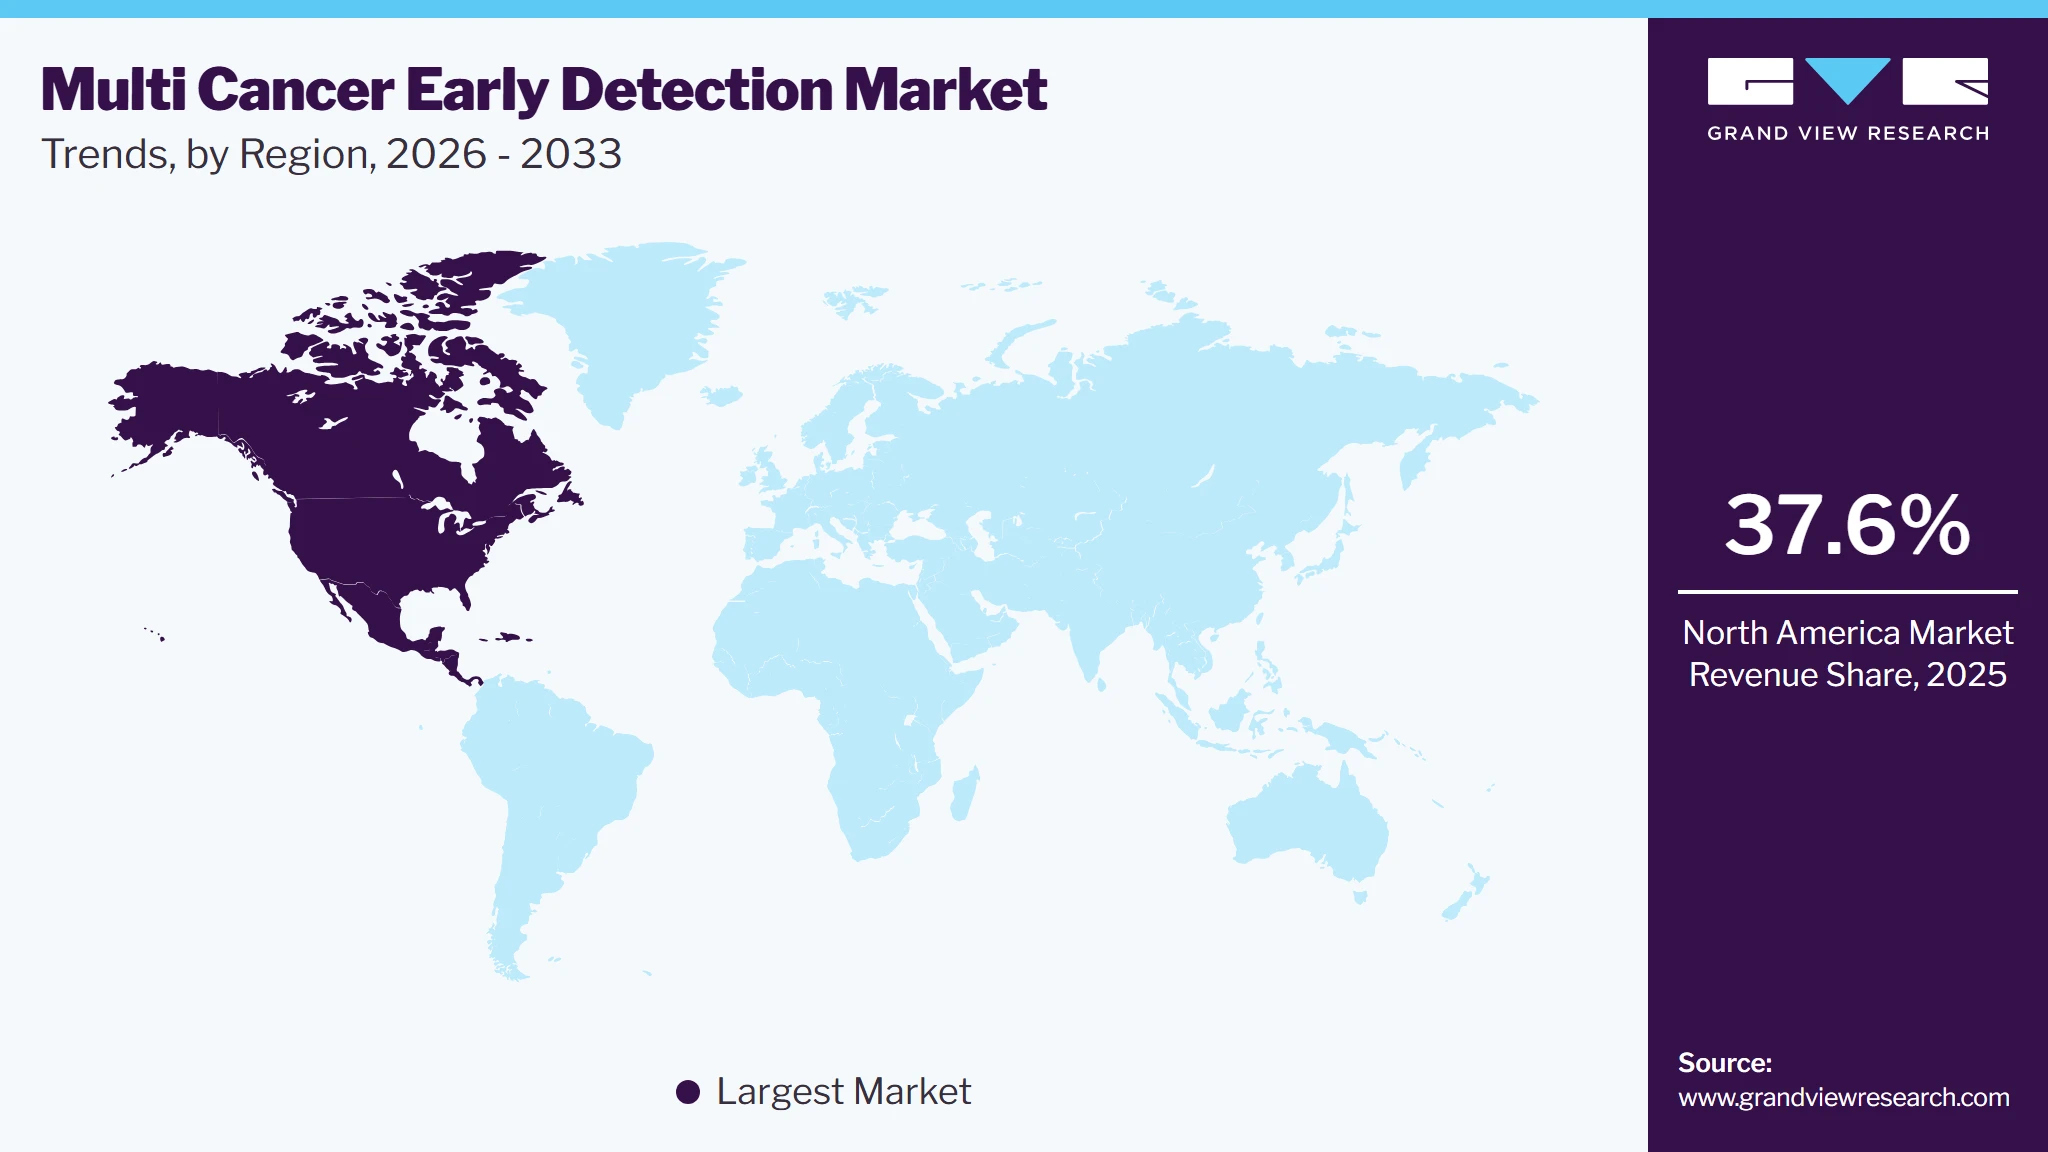
North America multi cancer early detection industry accounted for the largest revenue share of 37.6% in 2025 and is anticipated to grow at fastest growth over the forecast period. The multi cancer early detection market in North America was identified as a lucrative region in this industry owing to the high prevalence of cancer, rapid technological advancements, and increasing government initiatives supporting early detection. The U.S. leads the market, driven by significant investments and the presence of numerous biotechnology companies developing innovative MCED tests. Organizations like the American Society of Clinical Oncology (ASCO) support adopting early detection technologies, further fueling market growth. For example, in November 2023, GRAIL, LLC launched the REACH (Real-world Evidence to Advance Multi-Cancer Early Detection Health Equity) study to assess the clinical impact of the Galleri MCED test on the Medicare population, highlighting ongoing efforts to expand access and improve outcomes through advanced diagnostic solutions.
 To learn more about this report, Download Free Sample Report
The multi cancer early detection market in the U.S. held the largest share in the North America region in 2025, owing to significant investments in biotechnology and strong support from healthcare organizations like ASCO. The development and adoption of innovative tests, such as GRAIL’s Galleri, enhance early detection and improve public health outcomes.
Asia Pacific Multi Cancer Early Detection Market Trends
The multi cancer early detection market in Asia Pacific is anticipated to witness the fastest growth, driven by improving healthcare infrastructure, a large and growing population, and an increasing number of local companies entering the market. With a high prevalence, nearly half of all global cases, and 58.3% of cancer deaths occurring in Asia, according to Global Cancer Statistics 2020, the demand for early detection solutions is rising. Moreover, demographic changes such as urbanization, aging populations, and economic growth are increasing attention on cancer prevention. However, challenges such as low affordability, inadequate infrastructure, and a shortage of trained professionals may hinder the market's growth in some areas.
China multi cancer early detection market is expected to grow over the forecast period due to increasing incidence rates and rising awareness about early diagnosis. Government initiatives and collaborations with biotechnology firms are further accelerating the adoption of innovative diagnostic technologies across the country.
The multi cancer early detection market in Japan is expected to grow over the forecast period owing to increasing healthcare awareness and government initiatives aimed at enhancing cancer screening programs. Technological innovations and the integration of advanced diagnostic tools, such as liquid biopsy, are driving regional market expansion.
Latin America Multi Cancer Early Detection Market Trends
The multi cancer early detection market in Latin America was identified as a lucrative region in this industryowing to the growing adoption of innovative diagnostic technologies to address the rising cancer burden. Increasing awareness and government initiatives to improve screening are driving regional market expansion.
Brazil multi cancer early detection market is expected to grow over the forecast period. Government initiatives and partnerships with private sector players are driving the adoption of MCED solutions to enhance early cancer detection across the country.
MEA Multi Cancer Early Detection Market Trends
The multi cancer early detection market in MEA holds major growth opportunities, as most of it is untapped due to the unavailability of organized cancer screening programs in this region, especially in underdeveloped African economies.
Saudi Arabia multi cancer early detection market is expected to grow over the forecast. This market's growth is primarily attributed to the increasing government focus on healthcare innovation and cancer prevention programs. The country’s investment in advanced diagnostic technologies and collaboration with global players is driving the adoption of MCED solutions.
Key Multi Cancer Early Detection Company Insights
The multi-cancer early detection market is characterized by major players focusing on developing innovative diagnostic solutions. Key companies such as Illumina, Inc., Exact Sciences Corporation, FOUNDATION MEDICINE, INC., and Guardant Health are leading the market, leveraging advanced technologies like liquid biopsy and next-generation sequencing to detect multiple types of cancer early and accurately. These players are continuously investing in research and development to enhance the efficacy and reliability of their tests, while collaborations with healthcare providers and research institutions are aimed at expanding the reach and impact of MCED solutions. Their focus on offering high-quality, cost-effective diagnostic options has positioned them as pivotal contributors to the market's growth, enabling earlier intervention and improved patient outcomes.
Emerging players in the multi-cancer early detection (MCED) market are making significant advances by introducing innovative technologies and approaches to cancer detection. Companies like ADELA, Inc., ClearNote Health, and SeekIn are leveraging artificial intelligence, machine learning, and genomics to create more efficient and accessible MCED tests. These emerging players focus on developing comprehensive, non-invasive screening tools that can detect a wide range of tumors at earlier stages, often through blood tests. Their ability to offer personalized solutions, integrate data analytics, and collaborate with academic and healthcare institutions is helping to expand the reach of MCED technologies. While they face competition from established market leaders, these new entrants are poised to drive innovation in cancer screening, particularly in underserved markets and populations.
Key Multi Cancer Early Detection Companies
The following key companies have been profiled for this study on the multi cancer early detection market.
-
Illumina, Inc.
-
GRAIL, Inc.
-
Exact Sciences Corporation
-
FOUNDATION MEDICINE, INC.
-
AnchorDx
-
Guardant Health
-
Burning Rock Biotech Limited
-
GENECAST
-
Beijing Lyman Juntai International Medical Technology Development Co.
-
Freenome Holdings, Inc
-
Elypta AB
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (GRAIL, Illumina, Exact Sciences, Guardant Health, FOUNDATION MEDICINE)
- Focus on development and commercialization of blood based multi cancer early detection tests using liquid biopsy, genomic profiling, methylation analysis, and multiomics technologies.
- Emphasize large scale clinical validation studies, regulatory submissions, reimbursement expansion, physician engagement, and partnerships with healthcare systems, laboratories, and electronic health record providers to support adoption.
- Strong intellectual property portfolios, extensive clinical evidence, established brand recognition, advanced sequencing and bioinformatics capabilities, and broad access to healthcare providers and diagnostic networks.
- Ability to support large population screening initiatives through scalable testing infrastructure and commercial resources.
- High test costs may limit adoption among average risk populations.
- Dependence on regulatory approvals, reimbursement expansion, and long clinical validation timelines can slow commercialization.
- Significant investments in research and evidence generation increase operational expenditures.
Emerging & Regional Players (Freenome, Burning Rock Biotech, AnchorDx, GENECAST, Beijing Lyman Juntai International Medical Technology Development Co., Elypta AB)
- Focus on innovative biomarker discovery, AI enabled analytics, multiomics platforms, regional market expansion, and development of cost-conscious cancer screening solutions.
- Emphasize collaborations with research institutions, healthcare providers, and biotechnology partners to strengthen clinical validation and market access.
- Agility in technology development, growing expertise in precision diagnostics, competitive pricing strategies, and ability to address regional screening needs.
- Strong focus on novel biomarkers and differentiated approaches may support future market positioning.
- Limited commercial scale, smaller clinical evidence base, lower brand visibility, and restricted access to global distribution channels.
- Dependence on external funding, partnership support, and regulatory milestones may constrain expansion compared to established market participants.
Recent Developments
-
In October 2024, SeekIn Inc. revealed its innovative two-step multi-cancer screening strategy at the Early Detection of Cancer Conference in San Francisco. This approach aims to reduce the financial burden of population-wide screening, making Multi-Cancer Early Detection (MCED) tests more affordable and accessible.
-
In August 2024, Exact Sciences announced the enrollment of the first patient in its MCED Falcon Registry Real-World Evidence study at Baylor Scott & White, Texas's largest non-profit health system. This multi-site study aims to enroll up to 25,000 patients and evaluate the clinical performance, patient and provider experiences, and psychological impact of MCED testing over five years.
-
In February 2024, The NIH announced the Cancer Screening Research Network (CSRN) launch to evaluate new detection technologies and methods, supporting the Biden-Harris administration's Cancer Moonshot initiative. As part of this effort, the National Cancer Institute (NCI) has funded eight research groups to kick off the network.
Multi Cancer Early Detection Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.3 billion
Estimated market size in 2026
USD 1.5 billion
Projected market size by 2033
USD 4.6 billion
Growth rate
CAGR of 17.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, End Use, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Illumina, Inc., GRAIL, Inc., Exact Sciences Corporation, FOUNDATION MEDICINE, INC., AnchorDx, Guardant Health, Burning Rock Biotech Limited, GENECAST, Beijing Lyman Juntai International Medical Technology Development Co., Freenome Holdings, Inc., and Elypta AB.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Multi Cancer Early Detection Market Report Segmentation
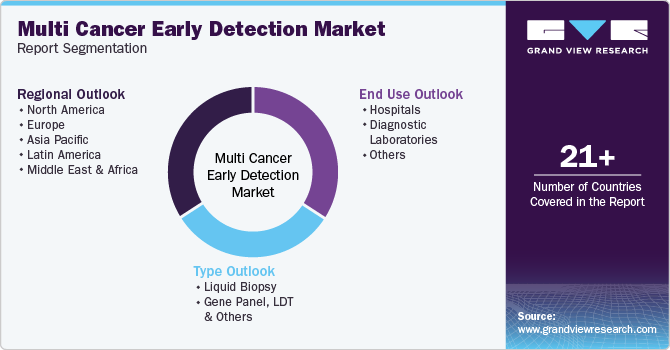
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global multi cancer early detection market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Liquid Biopsy
-
Gene Panel, LDT & Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
The multi cancer early detection market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each multi cancer early detection segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Liquid Biopsy
Revenue is primarily captured through blood based multi cancer detection tests that analyze circulating tumor DNA, methylation patterns, proteins, or other biomarkers for screening and early identification of multiple cancer types from a single sample.
Gene Panel, LDT & Others
Market value originates from laboratory developed tests, targeted genomic panels, multiomics assays, and alternative MCED methodologies that assess cancer associated molecular signatures beyond conventional liquid biopsy-based screening approaches.
Segment - End Use
Revenue capture definition
Hospitals
Revenue flows from physician ordered MCED testing conducted for patients within hospital systems, cancer centers, and integrated healthcare networks where screening results support diagnostic evaluation, referral pathways, and clinical decision making.
Diagnostic Laboratories
Market contribution comes from independent and reference laboratories performing sample processing, biomarker analysis, test interpretation, and reporting services for MCED assays ordered by healthcare providers and institutions.
Others
Revenue capture includes MCED testing utilized through research organizations, academic institutions, employer sponsored screening programs, community health initiatives, and other non-hospital or non-laboratory healthcare settings.
Estimation Model
The multi cancer early detection (MCED) market is expected to witness significant growth, driven by increasing emphasis on early cancer detection, rising cancer burden worldwide, and growing adoption of minimally invasive screening technologies. MCED tests serve as innovative tools for identifying multiple cancer types from a single blood sample, supporting earlier intervention and potentially improving patient outcomes. The market is benefiting from advancements in liquid biopsy technologies, next generation sequencing, methylation analysis, multiomics platforms, and artificial intelligence enabled biomarker interpretation, which continue to enhance test performance and scalability. Furthermore, expanding clinical validation efforts, increasing participation in large population screening studies, and growing engagement from healthcare providers and diagnostic laboratories are supporting market development. Favorable reimbursement progress, strengthening regulatory pathways, and increasing investments from both public and private organizations are further contributing to adoption. Ongoing integration of MCED testing into preventive healthcare strategies and cancer screening programs is expected to support the market's long term growth outlook while advancing the role of precision diagnostics in oncology care.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Targeted Therapy Adoption Analysis
Assessment of adoption trends across cholinesterase inhibitors, chronic immunomodulators, monoclonal antibodies, rapid immunotherapies, and emerging targeted therapies used in Myasthenia Gravis treatment.
Helps identify high growth treatment segments and investment opportunities across evolving disease management approaches.
Biologic and Pipeline Landscape Assessment
Analysis of approved biologics, late- stage pipeline candidates, FcRn inhibitors, complement inhibitors, and other immune targeted therapies under development for myasthenia gravis.
Supports opportunity identification across emerging treatment modalities and future commercialization prospects.
Clinical and Treatment Pattern Evaluation
Evaluation of treatment utilization across generalized and ocular myasthenia gravis, including therapy sequencing, biologic adoption trends, immunosuppressive treatment patterns, and acute disease management approaches.
Tracks evolving treatment practices and supports strategic planning for market entry and portfolio expansion.
Personalized Medicine and Innovation Landscape
Assessment of advancements in biomarker guided therapies, antibody specific treatment approaches, precision medicine initiatives, and next generation immunotherapies for Myasthenia Gravis.
Assessment of advancements in biomarker guided therapies, antibody specific treatment approaches, precision medicine initiatives, and next generation immunotherapies for Myasthenia Gravis.
Competitive Benchmarking and Product Portfolio Analysis
Comparative assessment of approved products, pipeline assets, clinical development strategies, regulatory milestones, partnerships, and commercialization initiatives of leading Myasthenia Gravis market participants.
Supports competitive intelligence, partnership evaluation, licensing opportunities, and market positioning decisions.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The market continues to face challenges related to demonstrating long term clinical benefits and integration into established screening frameworks.
The expansion of reimbursement pathways and healthcare coverage presents a significant opportunity for the multi-cancer early detection market.
North America multi cancer early detection industry accounted for the largest revenue share of 37.6% in 2025, owing to the high prevalence of cancer, rapid technological advancements, and increasing government initiatives supporting early detection.
The global multi cancer early detection market size was estimated at USD 1.3 billion in 2025 and is expected to reach USD 1.5 billion in 2026.
Key players operating in the multi cancer early detection market are Illumina, Inc., GRAIL, Inc., Exact Sciences Corporation, FOUNDATION MEDICINE, INC., AnchorDx, Guardant Health, Burning Rock Biotech Limited, GENECAST, Beijing Lyman Juntai International Medical Technology Development Co., Freenome Holdings, Inc, Elypta AB.
Key drivers driving the multi cancer early detection market are increasing prevalence of cancer, extensive R&D for the development of MCED and need to develop diagnostic options that can detect cancer at an early stage.
The global multi cancer early detection market is expected to grow at a compound annual growth rate of 17.2% from 2026 to 2033 to reach USD 4.6 billion by 2033.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


