
- Home
- »
- Medical Devices
- »
-
Nasal Packing Devices Market Size & Share Report, 2033GVR Report cover

Nasal Packing Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Injectable, Gel, Sprays, Dressings), By Type (Bioresorbable, Non-absorbable), By Region (North America, Asia Pacific, Europe, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$215.4MMarket Estimate, 2026
$226.3MMarket Forecast, 2033
$323.7MCAGR, 2026–2033
5.2%Nasal Packing Devices Market Summary
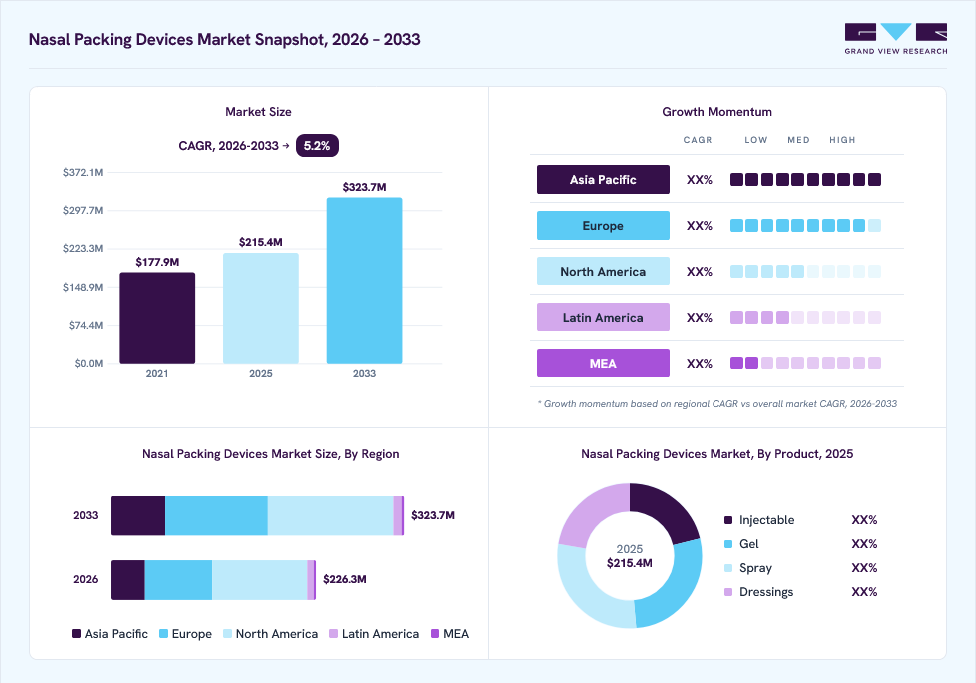
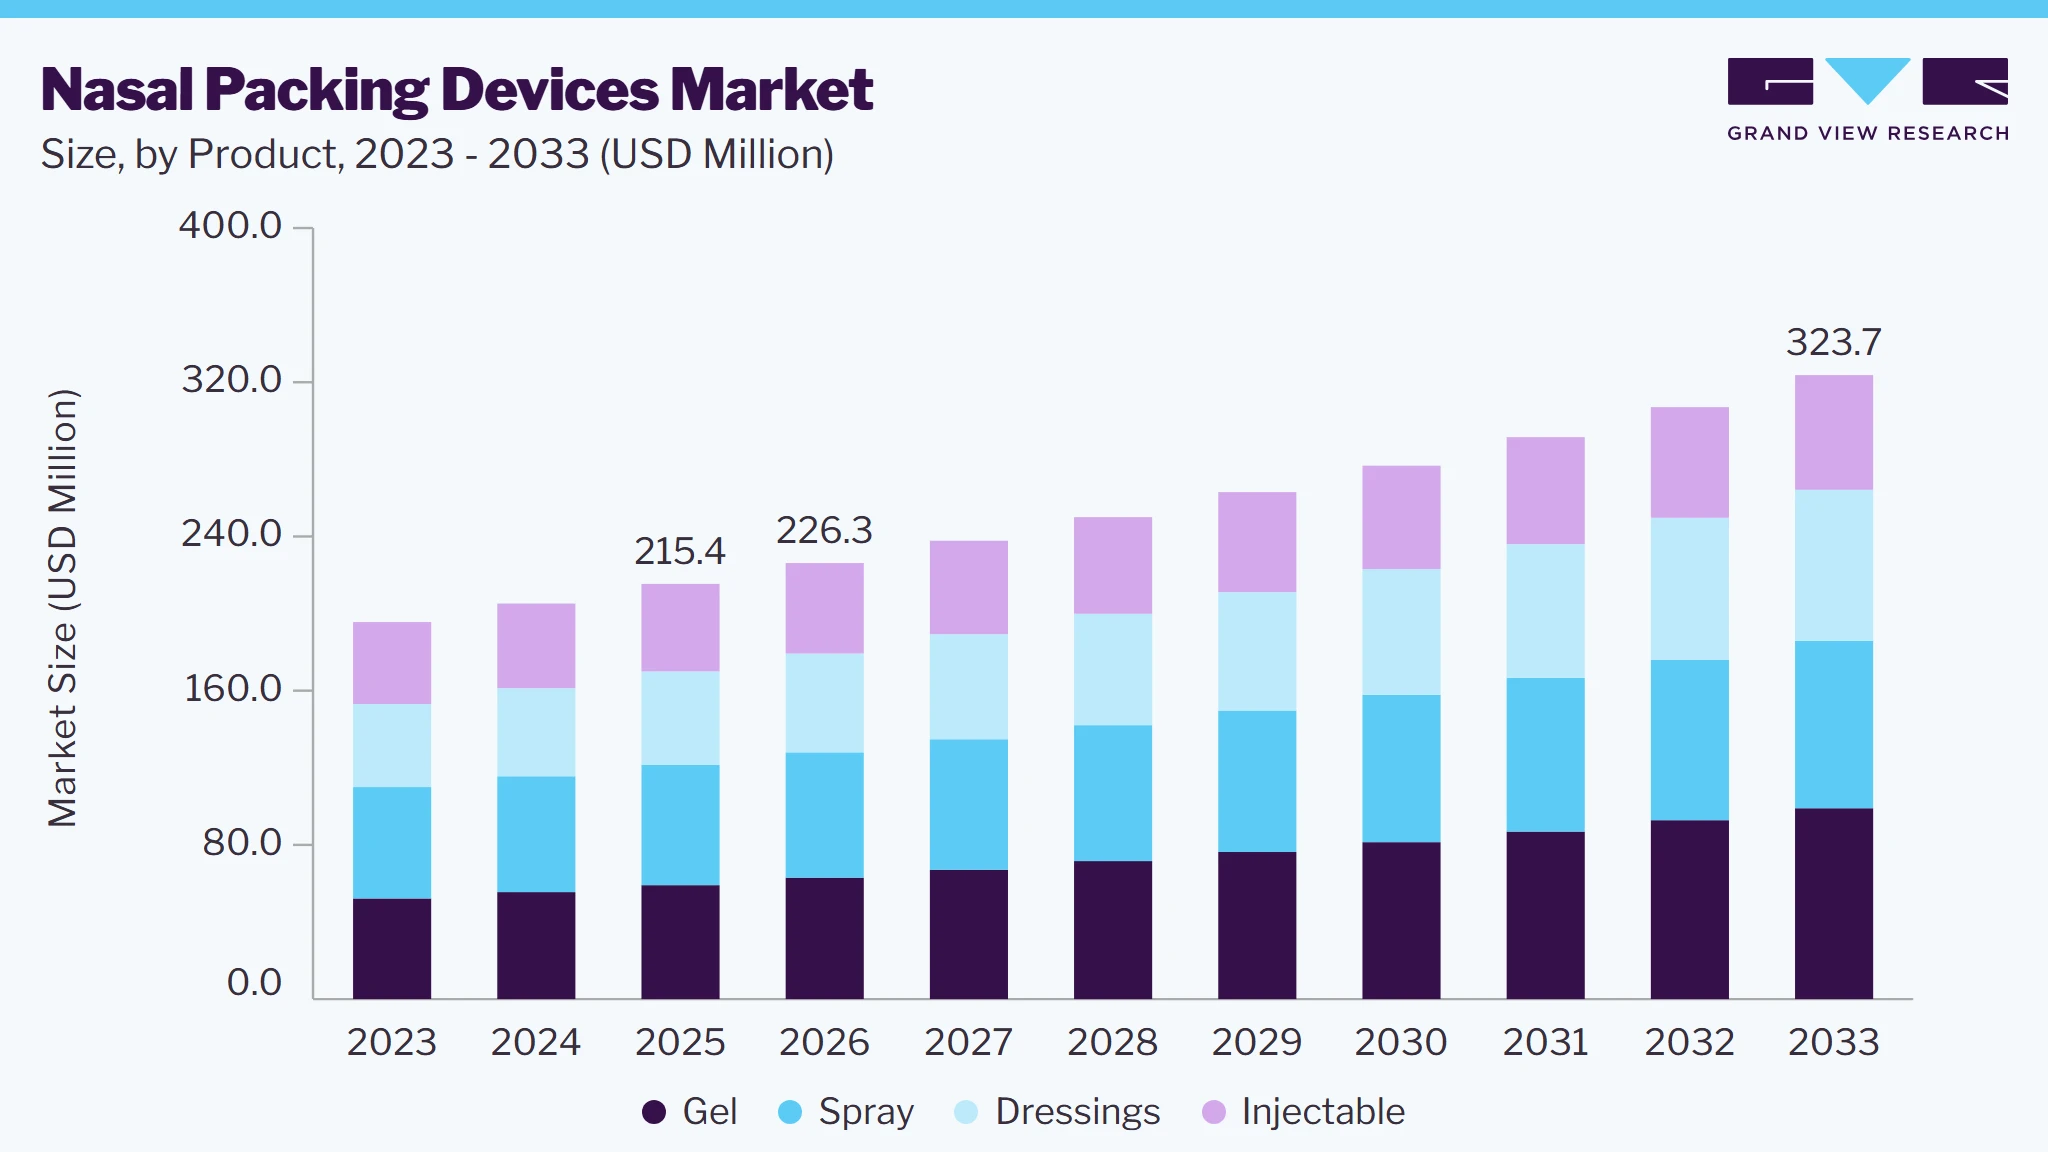
The global nasal packing devices market size was valued at USD 215.4 million in 2025 and is projected to grow from USD 226.3 million in 2026 to USD 323.7 million by 2033, at a CAGR of 5.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 46.8% in 2025. The global industry is driven by the rising incidence of nasal surgeries, including septoplasty and sinus surgeries, as well as increasing cases of nasal injuries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Spray segment dominated the market, with a revenue share of 29.0% in 2025.
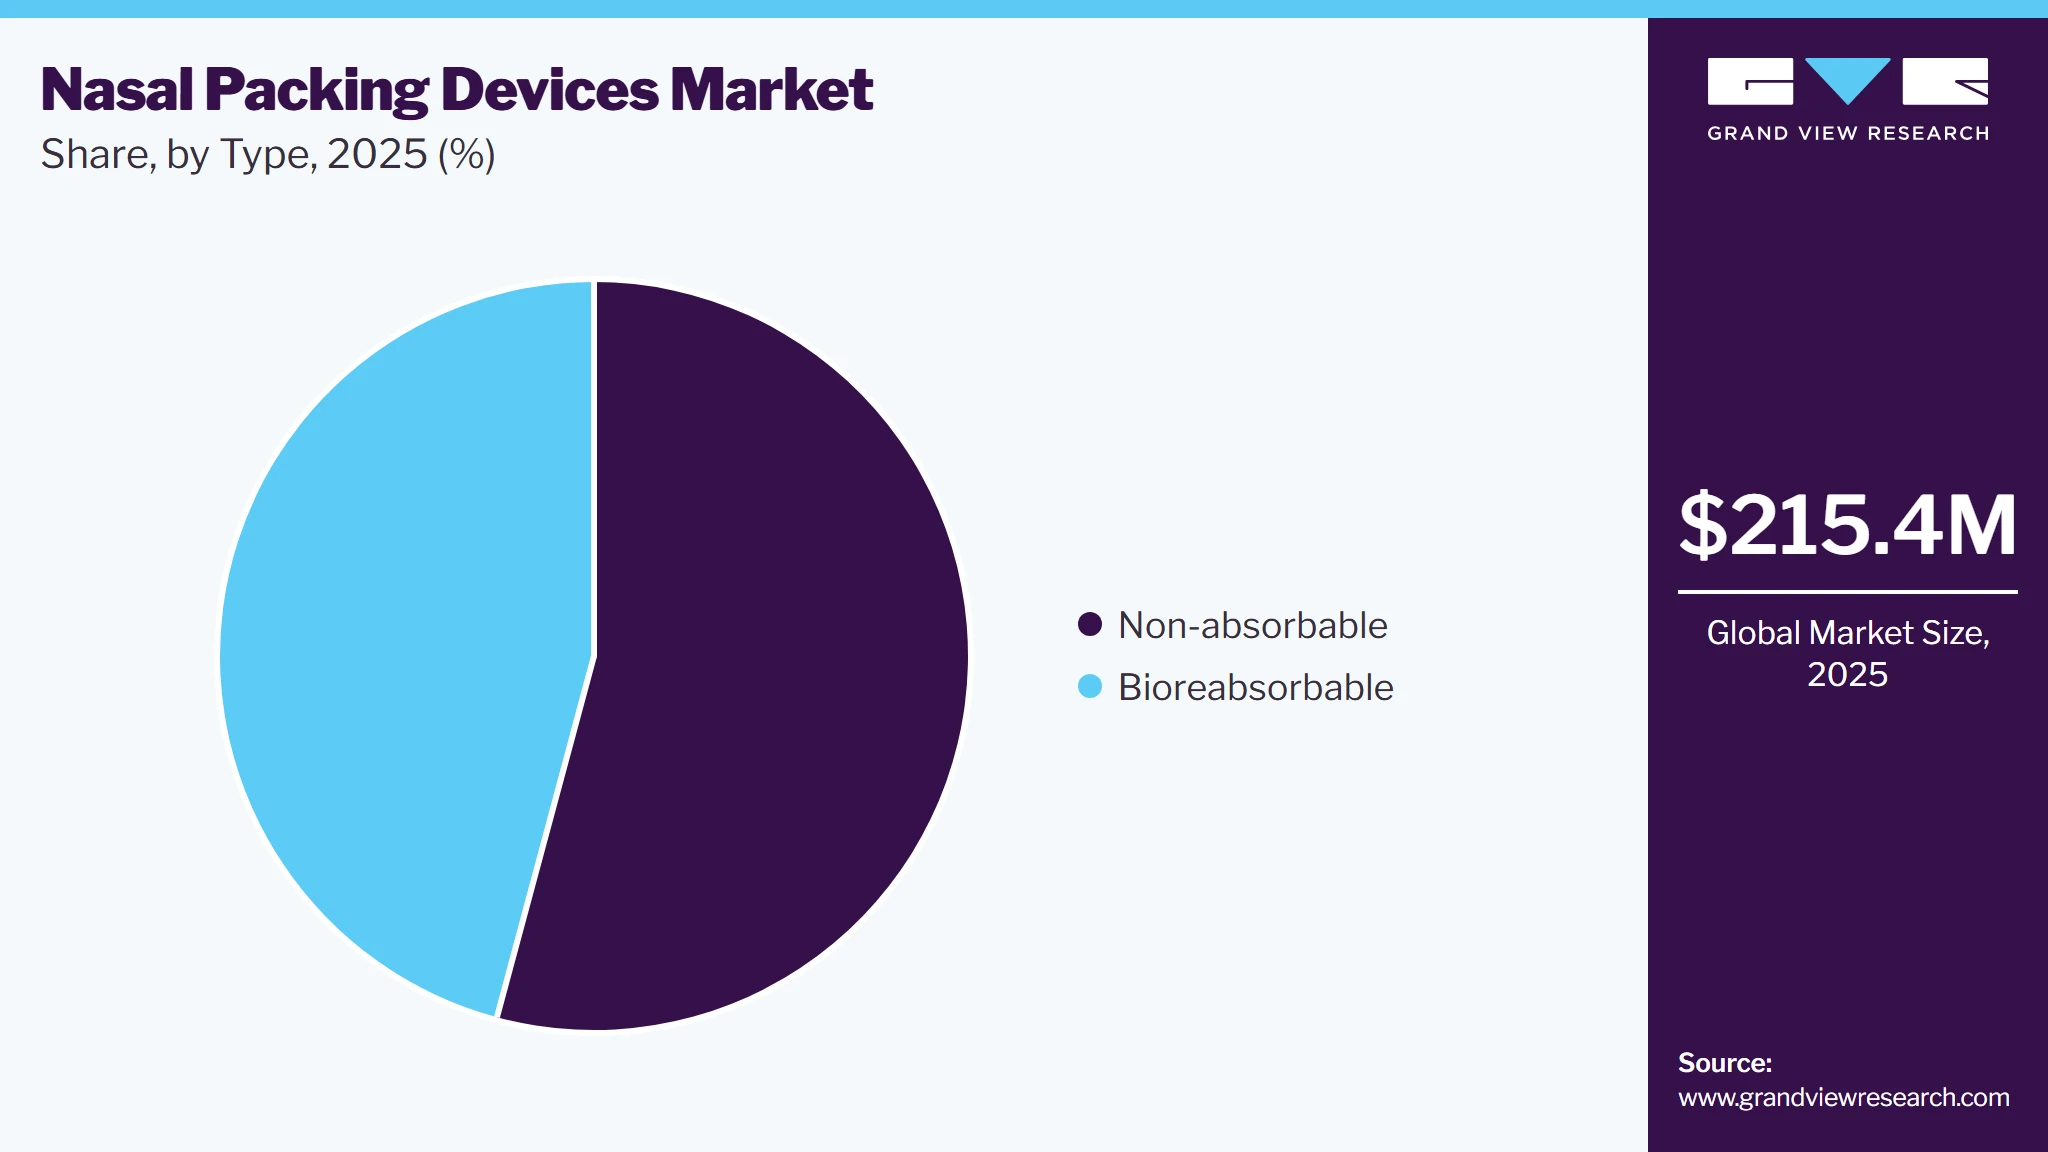
- By type: Non-absorbable segment held the largest market share of 54.2% in 2025.
Regional Highlights
- Largest regional market: North America (46.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 215.4 Million
- Estimated market size in 2026: USD 226.3 Million
- Projected market size by 2033: USD 323.7 Million
- CAGR (2026-2033): 5.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising prevalence of epistaxis, also known as nosebleeds, is the primary factor majorly responsible for the growing demand for the market. Advancements in nasal packing materials, such as bioabsorbable and hemostatic products, are enhancing patient comfort and recovery.The rising incidence of chronic nasal conditions such as sinusitis, nasal polyps, and nosebleeds has fueled the demand for nasal packing solutions. Epistaxis results from the cooperation of various elements that harm the nasal mucosal covering, influence the vessel walls, or disturb the coagulability of the blood. Nasal packing is the second line of treatment for epistaxis, after the failure of cauterization. According to a study on nosebleeds conducted in the U.S., the occurrence is most common among children between the ages of 2 to 10 and adults and elders between the ages of 50 to 80, and this age group also contributes to the majority. Hence, the increasing number of the elderly population is also contributing to market growth. According to the American Academy of Otolaryngology, chronic sinusitis affects approximately 12% of the global population, which leads to a growing need for surgeries like septoplasty, rhinoplasty, and other corrective nasal procedures. Nasal packing devices are essential in these surgeries to control bleeding, support the healing process, and prevent complications.
 To learn more about this report, Download Free Sample Report
Nasal packing can be classified according to the type of epistaxis, which is anterior, and posterior based on the location of the site of bleeding. Anterior nasal packing has more demand as anterior bleeding is more common among patients. Patients need to be admitted to the hospital for the application of posterior nasal packing. Nasal packing is suggested to be applied only when the site of bleeding is clearly identified. Nasal packing traditionally included a ribbon gauze applied with antibiotics, lubricant, or ointments. But the industry has significantly developed, the recent launches include foam-based nasal packing that can absorb liquid more than 30 times its weight. Once absorbed, the packing expands, imposing pressure on the nasal walls, which helps control the bleeding.
Over time, nasal packing devices have evolved from simple gauze-based solutions to more advanced materials such as absorbable hemostatic agents, and synthetic and bio-resorbable materials. These new innovations improve the patient's comfort and reduce the need for removal and the risk of infection. Products like Merocel, a commonly used nasal packing material, and Cutanplast, a bioabsorbable packing, offer ease of use and reduced complication rates. Such developments are contributing to the rapid growth of the market.
As the field of rhinoplasty and nasal surgeries advances, more sophisticated techniques are being used, leading to an increased focus on post-operative care. The growing demand for minimally invasive surgeries, which often require effective nasal packing to prevent bleeding and minimize complications, is also influencing the market. Devices that are easy to insert, reduce patient discomfort, and promote faster recovery are increasingly in demand.
Market Dynamics
The nasal packing devices market is experiencing steady growth as hospitals, ambulatory surgical centers, specialty ENT clinics, and emergency care facilities increasingly adopt advanced nasal packing solutions to manage epistaxis, provide postoperative support, and promote effective wound healing following nasal procedures. These devices encompass a wide range of products, including absorbable and non-absorbable nasal packs, inflatable nasal tampons, hemostatic dressings, nasal splints, and bioactive packing materials designed to control bleeding, stabilize nasal structures, and minimize postoperative complications. Nasal packing devices are widely used across various clinical applications, including epistaxis management, septoplasty, functional endoscopic sinus surgery (FESS), rhinoplasty, turbinate reduction procedures, and trauma-related nasal interventions. The growing prevalence of chronic rhinosinusitis, nasal trauma, coagulation disorders, and an aging population with a higher incidence of spontaneous nosebleeds is contributing to increased demand for these devices. Furthermore, advancements in biomaterials, bioresorbable hemostatic agents, antimicrobial coatings, patient-comfort-focused designs, and drug-eluting nasal packing technologies are improving hemostatic effectiveness, reducing pain during insertion and removal, minimizing the risk of adhesions and infections, and enhancing postoperative recovery. The increasing volume of ENT surgeries, rising preference for minimally invasive nasal procedures, expanding access to specialized otolaryngology care, and continued focus on improving patient outcomes while reducing healthcare-associated complications are expected to sustain the demand for advanced nasal packing devices across healthcare settings.
The rising incidence of nasal disorders is a key factor driving the growth of the nasal packing devices market. Conditions such as chronic rhinosinusitis, recurrent epistaxis (nosebleeds), deviated nasal septum, nasal polyps, allergic rhinitis, and traumatic nasal injuries are becoming increasingly prevalent due to factors including aging populations, increasing air pollution, allergies, upper respiratory infections, and lifestyle-related risk factors. Many of these conditions require surgical intervention or emergency bleeding management, where nasal packing devices play a critical role in achieving hemostasis, supporting postoperative healing, preventing adhesions, and stabilizing nasal structures. In addition, the growing number of patients receiving anticoagulant and antiplatelet therapies has increased the incidence of difficult-to-control epistaxis, further driving the demand for effective nasal packing solutions. As healthcare systems continue to expand access to otolaryngology (ENT) services and awareness regarding timely diagnosis and treatment of nasal disorders improves, the volume of nasal procedures is expected to rise, supporting sustained adoption of both absorbable and non-absorbable nasal packing devices across hospitals, ambulatory surgical centers, and specialty ENT clinics.
The high cost of advanced nasal packing devices is a significant restraint on the growth of the nasal packing devices market, particularly in price-sensitive healthcare systems and low- and middle-income countries. Premium products incorporating bioresorbable materials, hemostatic agents, antimicrobial coatings, drug-eluting formulations, or patient-comfort-enhancing technologies are considerably more expensive than conventional gauze or standard non-absorbable nasal packs. While these advanced devices offer benefits such as improved hemostasis, reduced pain during removal, lower risk of postoperative adhesions and infections, and enhanced patient comfort, their higher acquisition costs can limit adoption, especially in healthcare facilities operating under constrained budgets. In addition, inconsistent reimbursement policies for advanced ENT consumables and the need to balance clinical outcomes with cost-effectiveness often lead hospitals and ambulatory surgical centers to continue using lower-cost traditional alternatives. As a result, the affordability of advanced nasal packing solutions remains a key challenge, particularly in emerging markets where healthcare expenditure and access to specialized ENT care are comparatively limited.
Market Concentration & Characteristics
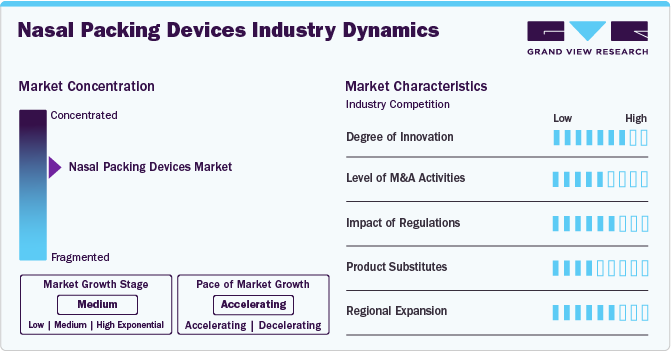
The industry is characterized by moderate industry concentration, with a few key players dominating the market, including companies like Medtronic, Smith & Nephew, and Medi-Tech. These devices are primarily used in ENT surgeries, trauma care, and to manage conditions like epistaxis (nosebleeds) and chronic sinusitis. The industry is marked by a focus on innovative, patient-friendly solutions, such as absorbable materials, non-invasive designs, and easy-to-use systems. Increasing demand for minimally invasive procedures and advancements in biodegradable materials are driving innovation, while regulatory compliance and cost pressures remain ongoing challenges.
The industry is highly innovative, driven by the demand for safer, more comfortable, and effective solutions in managing nasal surgeries and conditions like epistaxis. Key innovations include bioabsorbable materials, which eliminate the need for device removal, and advanced hemostatic agents that enhance bleeding control. Additionally, non-invasive designs and products that minimize patient discomfort are gaining popularity. There is also a focus on improving ease of use for healthcare providers with simpler application techniques. As minimally invasive surgeries rise in popularity, the industry continues to evolve, incorporating smart technologies and materials that promote faster healing and better outcomes.
 To learn more about this report, Download Free Sample Report
Regulations have a significant impact on the nasal packing devices industry, ensuring safety, efficacy, and quality. In markets like the U.S. and Europe, devices must meet strict standards set by regulatory bodies such as the FDA and EMA, which can involve lengthy approval processes and rigorous testing. Compliance with these regulations is crucial for market entry and can affect product development timelines and costs. Additionally, biocompatibility, sterility, and patient safety are key regulatory concerns that influence design and manufacturing. As the industry innovates, meeting evolving regulatory requirements remains a challenge but also ensures that products deliver high-quality outcomes for patients.
Mergers and acquisitions (M&A) in the industry are rapidly increasing as companies aim to bolster their technological capabilities and market reach. For instance, in June 2024, CoagCo LLC, a Cleveland-based medical device company, announced a partnership with CHAMPS Group Purchasing (GPO). The agreement will leverage CHAMPS' purchasing power across 20,000 U.S. member locations, enhancing the distribution of CoagCo's innovative nosebleed device while offering savings to CHAMPS members.
Alternatives or product substitutes include nasal sprays, cauterization techniques, and hemostatic agents. Nasal sprays, often used for mild nosebleeds or congestion, provide a non-invasive option, though they may not be as effective in severe cases. Cauterization, a medical procedure that uses heat to stop bleeding, serves as another substitute, especially in treating chronic epistaxis. Additionally, absorbable hemostatic agents, such as gelatin sponges or fibrin sealants, are gaining popularity for managing bleeding without the need for traditional nasal packing. These alternatives, while effective, may not fully replace traditional packing devices in more severe or surgical cases.
In November 2024, Aptar Pharma inaugurated a new manufacturing facility in Taloja, India, to enhance its production capabilities for drug delivery systems. The facility aims to meet the growing demand for innovative healthcare solutions in the region, reinforcing Aptar Pharma's commitment to providing advanced, high-quality solutions for pharmaceutical and biotechnology companies. In North America and Europe, demand for minimally invasive nasal packing devices is rising due to high rates of chronic sinusitis and nosebleeds. In Asia-Pacific and Latin America, improving healthcare infrastructure and growing nasal health awareness are boosting market growth. Regulatory support and strategic partnerships are driving the expansion and adoption of advanced solutions in these regions.
Analyst Perspective
The nasal packing devices market is driven by long-term trends in ENT care, including the rising prevalence of nasal disorders and increasing ENT surgical volumes. Growing incidence of chronic rhinosinusitis, recurrent epistaxis, deviated nasal septum, nasal polyps, and nasal trauma is supporting demand for nasal packing solutions used for bleeding control, wound healing, and structural support. Healthcare providers are increasingly adopting absorbable and bioresorbable products to improve patient comfort, reduce pain during removal, and minimize postoperative adhesions and infections. The growing use of minimally invasive procedures, including FESS, septoplasty, and rhinoplasty, is further increasing demand for specialized, procedure-specific packing solutions. Advancements in biomaterials, hemostatic technologies, antimicrobial coatings, and drug-eluting systems are improving clinical performance and postoperative outcomes.
Product Insights
Based on product, the spray segment led the market with the largest revenue share of 29.0% in 2025, driven by innovations like the approval of a nasal spray for severe allergic reactions. In August 2024, the FDA approved a needle-free nasal spray by ARS Pharmaceuticals as an emergency treatment for anaphylaxis in adults and older children. This spray offers an alternative to injectable treatments like EpiPen, providing a more convenient and effective solution for managing life-threatening allergic reactions, which include symptoms like hives, swelling, and difficulty breathing. The growing demand for non-invasive solutions further boosts the market.
The gel segment is projected to experience the fastest compound annual growth rate (CAGR) over the forecast period. Recent advancements in gel production, driven by their high patient comfort and hemostatic properties, are expected to boost segment growth. Gels and dressings are among the most effective treatments for nosebleeds, with various dressing brands available in the market. MeroGel, by Medtronic, is a leading nasal dressing. Additionally, injectable nasal packing is specifically used to prevent lateralization of the central turbinate and nasal adhesions during the post-surgery recovery period.
Type Insights
Based on type, the non-absorbable segment led the market with the largest revenue share of 54.2% in 2025. These devices are preferred in various medical procedures due to their durability and ability to provide extended support in managing conditions like nosebleeds, chronic sinusitis, and post-surgical recovery. Non-absorbable nasal packing devices are effective in controlling bleeding and preventing complications without the need for frequent replacements. Their widespread use in hospitals and clinics, along with their cost-effectiveness, contributes to the segment's growth. Additionally, their ability to maintain optimal positioning for longer periods further drives their market dominance in nasal packing solutions.
 To learn more about this report, Download Free Sample Report
The bioresorbable segment has experienced significant growth, with a notable compound annual growth rate (CAGR) during the forecast period, owing to the rapid technological advancements and the increasing introduction of newer brands into the market. Bioresorbable nasal packing devices are much more convenient to the patients as there is much less pain and have more advantages than their counterpart segment.
Regional Insights
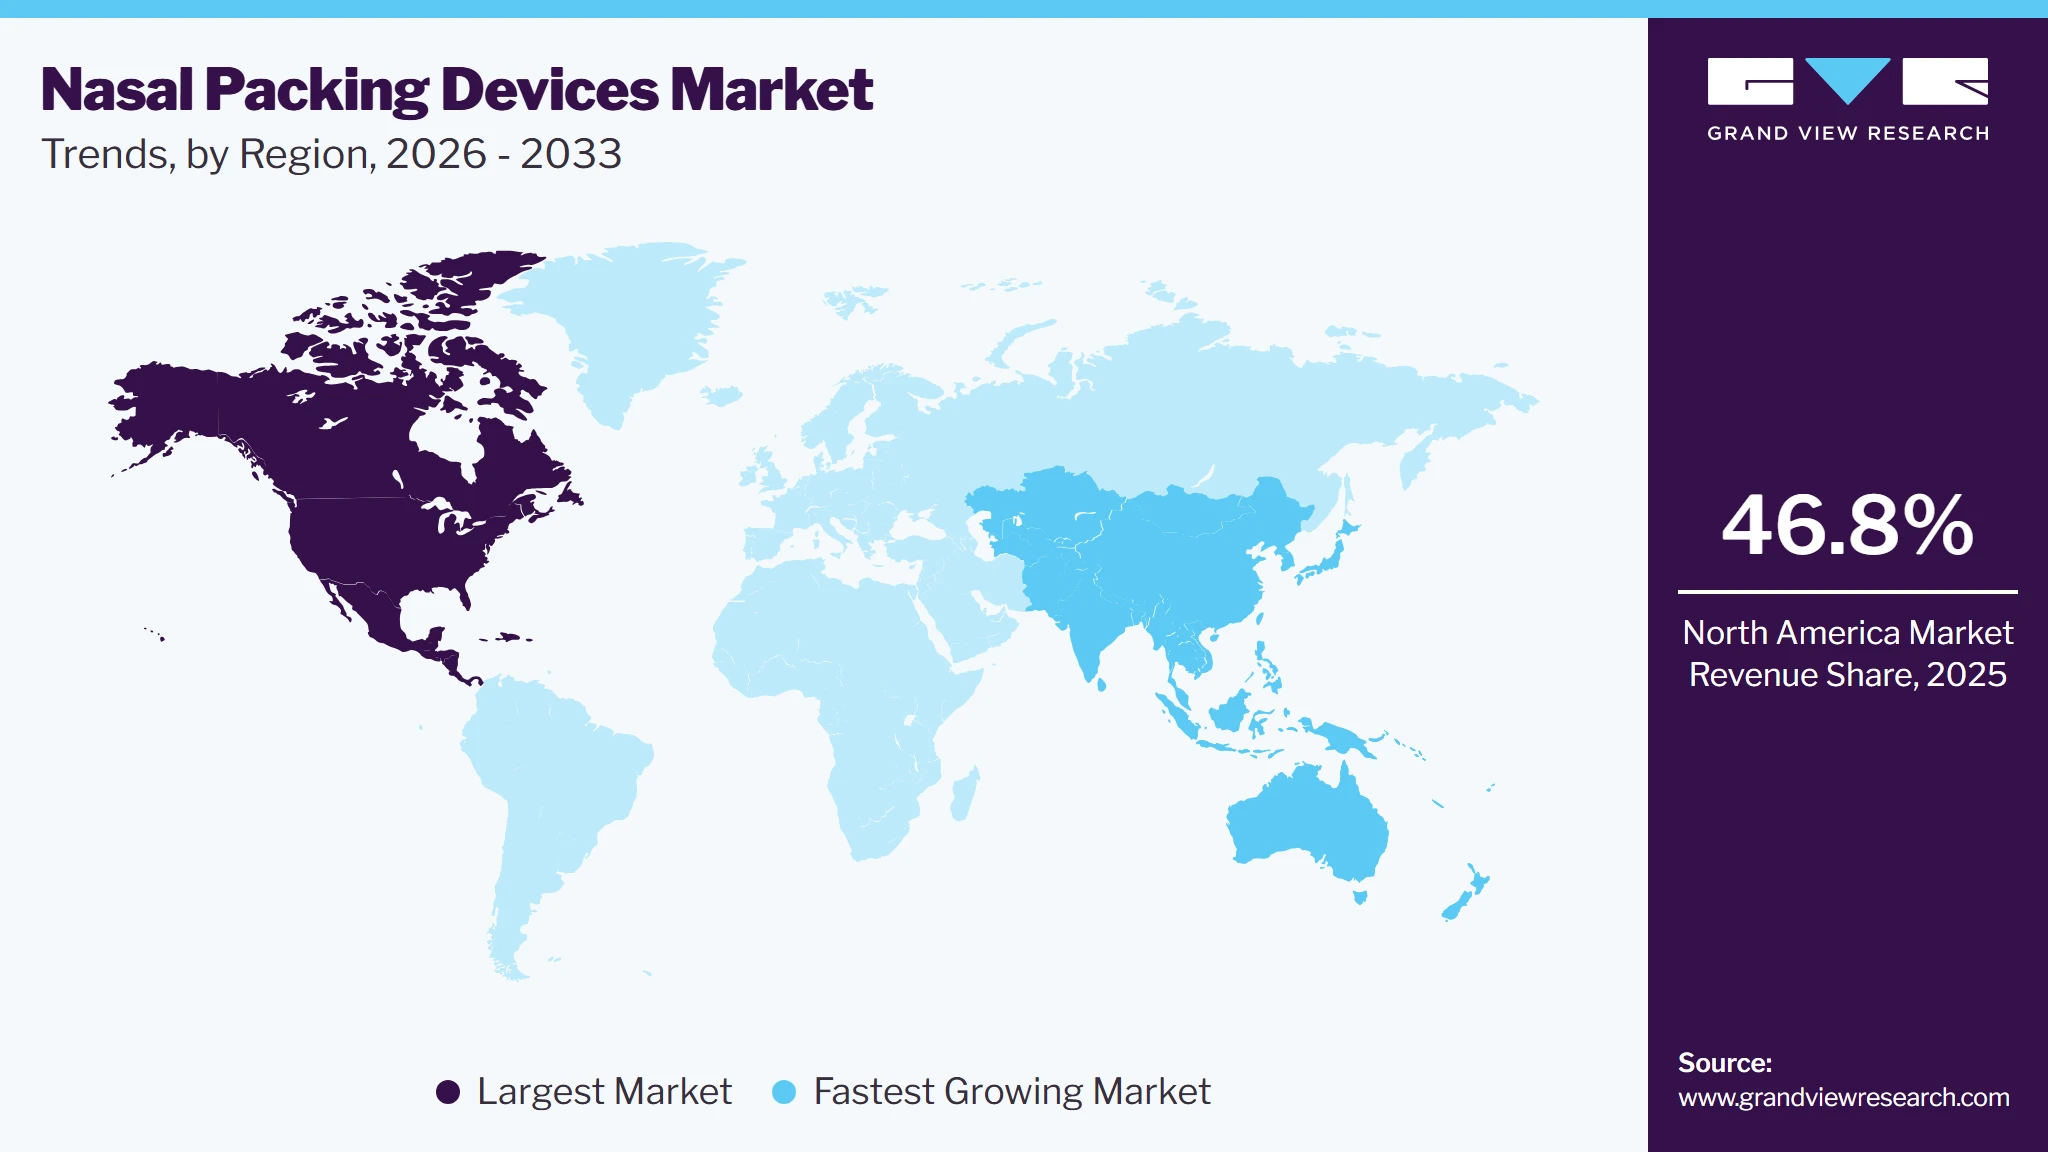
North America dominated the nasal packing devices market with the largest revenue share of 46.8% in 2025. due to the growing adoption of nasal packing solutions for treating the rising number of epistaxis (nosebleed) cases. Additionally, the presence of key market players and ongoing technological innovations in nasal packing products, such as bioabsorbable and minimally invasive devices, contribute to market growth. Strong healthcare infrastructure and a focus on patient comfort further reinforce North America's dominance in the global market.
 To learn more about this report, Download Free Sample Report
U.S. Nasal Packing Devices Market Trends
The nasal packing devices market in the U.S. held the largest share in the North America region in 2025. Each year, up to 60 million people in the U.S. experience nosebleeds, with a higher frequency during the winter months due to cold weather and indoor heating, which dry out the nasal passages. This high incidence of epistaxis drives the demand for effective nasal packing solutions. Additionally, the growing adoption of advanced, patient-friendly devices and the presence of leading medical companies in the U.S. further contribute to the market's substantial share in North America.
Europe Nasal Packing Devices Market Trends
The nasal packing devices market in Europe is witnessing growth, fueled by increasing awareness of minimally invasive treatments and the adoption of advanced technologies, such as bioabsorbable materials, which are driving demand for more effective and comfortable nasal packing solutions. For example, Olympus offers a variety of Blu and Blu Glide products, including nasal packing strips for nose surgery. These bacteriostatic and biocompatible advanced polyvinyl alcohol (PVA) sponges address the issues associated with traditional laminated packing products.
The UK nasal packing devices market is projected to expand owing to its advanced healthcare system, partnerships among major stakeholders, and the launch of novel products. Furthermore, a heightened focus on research and development for nasal packing devices designed to address diverse conditions is anticipated to be a significant driver of market growth.
The nasal packing devices market in France is expected to grow over the forecast period, driven by increasing cases of chronic sinusitis, nosebleeds, and nasal surgeries. Advancements in minimally invasive treatments, coupled with rising awareness of bioabsorbable and patient-friendly packing solutions, are further contributing to market expansion.
Germany nasal packing devices market is expected to grow over the forecast period, fueled by the high volume of ENT procedures, which totaled 239,670 in 2022. The increasing prevalence of nasal conditions like epistaxis and sinusitis, along with advancements in minimally invasive treatments, is driving market growth.
Asia Pacific Nasal Packing Devices Market Trends
The nasal packing devices industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The rise in the number of nasal packing device manufacturers, coupled with high unmet healthcare needs, is driving market expansion. Additionally, the region's booming economy and improving healthcare infrastructure, particularly in rapidly developing countries like China and India, are contributing to this growth. Growing awareness about nasal packing devices and their applications in treating conditions like nosebleeds and sinus issues further supports the market's development, as both healthcare providers and patients increasingly recognize the benefits of these advanced solutions.
Japan nasal packing devices market is poised for substantial growth. Japan’s advanced healthcare infrastructure and high demand for innovative medical solutions further fuel market expansion. The market is also benefiting from the adoption of bioabsorbable materials and improved patient comfort in nasal packing products. With Japan's focus on technological advancements and rising healthcare expenditure, the market is expected to see steady growth, offering significant opportunities for both local and global players.
The nasal packing devices market in China is expected to grow, driven by technological advancements and heightened research and development in the field of nasal packing devices. The China National Medical Products Administration (NMPA) is responsible for overseeing medical devices, including injectables, to guarantee their safety, effectiveness, and adherence to regulatory requirements.
India nasal packing devices market is poised for substantial growth, fueled by increasing healthcare access, rising incidences of chronic sinusitis, nosebleeds, and nasal surgeries, and improving medical infrastructure. Additionally, the growing awareness of minimally invasive treatments and advancements in nasal packing technologies contribute to this growth. The rising healthcare spending and the adoption of advanced devices position India as a key emerging market for nasal packing solutions.
Latin America Nasal Packing Devices Market Trends
The nasal packing devices market in Latin Americais experiencing significant growth. Increasing efforts in research and development coupled with rapid technological advancements are predicted to drive market growth in the area. Domestic firms concentrate on cost-conscious market sectors by delivering economical inspection solutions. Their familiarity with local regulations and business practices could enable them to offer more customized support and services, thereby fueling market growth.
Saudi Arabia nasal packing devices market is anticipated to expand in the forecast period. This is attributed to the government's encouragement of private sector involvement in healthcare, as outlined in the National Transformation Plan (NTP). Additionally, the projected rise in disposable income from economic expansion and urban development is expected to generate favorable growth prospects.
Key Nasal Packing Devices Company Insights
The scenario in the industry is highly competitive, with key players such as Smith & Nephew, Stryker Corporation; and Medtronic plc. holding significant positions. The major companies are undertaking various organic as well as inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Nasal Packing Devices Companies
The following key companies have been profiled for this study on the nasal packing devices market.
-
Summit Health
-
Smith & Nephew
-
Stryker Corporation
-
Medtronic plc.
-
Network medical products ltd.
-
Olympus
-
Lohmann & Rauscher
-
Meril Life Sciences Pvt Ltd.
-
FABCO
-
Aegis Lifesciences
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Smith+Nephew, Medtronic plc, Johnson & Johnson, Baxter International Inc., Stryker Corporation, Teleflex Incorporated)
- Established companies focus on expanding comprehensive ENT and hemostatic product portfolios comprising absorbable and non-absorbable nasal packing devices, hemostatic gels, sprays, dressings, injectable hemostatic agents, and postoperative care solutions.
- They emphasize continuous innovation in bioresorbable biomaterials, hemostatic technologies, antimicrobial coatings, and patient comfort while leveraging global manufacturing capabilities, hospital procurement contracts, and extensive distribution networks to strengthen market leadership.
- Extensive global distribution networks and long-standing relationships with hospitals, ambulatory surgical centers (ASCs), emergency departments, and specialty ENT clinics enable strong market penetration. Broad product portfolios facilitate bundled procurement agreements and recurring revenue from ENT procedures and epistaxis management.
- Significant financial resources support large-scale manufacturing, regulatory compliance, clinical research, and continuous product innovation.
- Dependence on global manufacturing operations and complex supply chains increases exposure to raw material price fluctuations and logistics disruptions. Premium pricing of advanced bioresorbable products may limit adoption in cost-sensitive markets.
- Large organizational structures may also reduce responsiveness to niche clinical requirements and rapidly evolving biomaterial innovations.
Emerging Players (Hemostasis LLC, Summit Medical LLC, Network Medical Products Ltd., Olympus Terumo Biomaterials Corp., SAI MedPartners LLC)
- Emerging companies prioritize innovative and cost-effective nasal packing solutions by developing bioresorbable materials, advanced hemostatic technologies, patient-centric product designs, and specialty ENT solutions.
- Many focus on expanding regional distribution, collaborating with ENT specialists, and addressing unmet clinical needs through differentiated product offerings and competitive pricing strategies.
- Agile product development enables rapid commercialization of innovative biomaterials and specialty hemostatic products.
- Competitive pricing, focused product portfolios, and flexibility in responding to physician preferences create opportunities to gain market share. Strong emphasis on niche ENT applications and expansion into emerging healthcare markets supports long-term growth.
- Limited manufacturing capacity, smaller R&D budgets, and comparatively lower brand recognition constrain large-scale commercialization and international expansion.
- Dependence on third-party distributors and challenges associated with obtaining regulatory approvals across multiple regions may slow market penetration compared with multinational competitors.
Recent Developments
-
In April 2024,Aptar Pharma announced plans to expand its manufacturing facility in Congers, New York, with completion expected by the end of 2024. The expansion will enhance the production of Unidose nasal spray systems by adding moulds and assembly lines in cleanroom environments. The facility is set to be operational by 2025.
-
In September 2024, Phillips Medisize, a Molex subsidiary, announced its agreement to acquire Vectura Group, a UK-based CDMO specializing in inhalation drug delivery devices. Vectura's expertise includes the development of dry powder inhalers and metered dose inhalers, enhancing Phillips Medisize’s capabilities in inhalation drug delivery.
-
In October 2024, Aptar Pharma acquired SipNose Nasal Delivery Systems' device technology assets, strengthening its position in the intranasal drug delivery market. SipNose’s devices, designed for targeted delivery within the nasal cavity, will enhance Aptar Pharma's patent portfolio and aid in developing new drug delivery products.
Nasal Packing Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 215.4 million
Estimated market size in 2026
USD 226.3 million
Projected market size by 2033
USD 323.7 million
Growth rate
CAGR of 5.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Thailand; Brazil; Argentina; Colombia; Saudi Arabia; South Africa; UAE
Key companies profiled
Summit Health; Smith & Nephew; Stryker Corporation; Medtronic plc.; Network medical products ltd.; Olympus; Lohmann & Rauscher; Meril Life Sciences Pvt Ltd.; FABCO; Aegis Lifesciences
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Nasal Packing Devices Market Report Segmentation
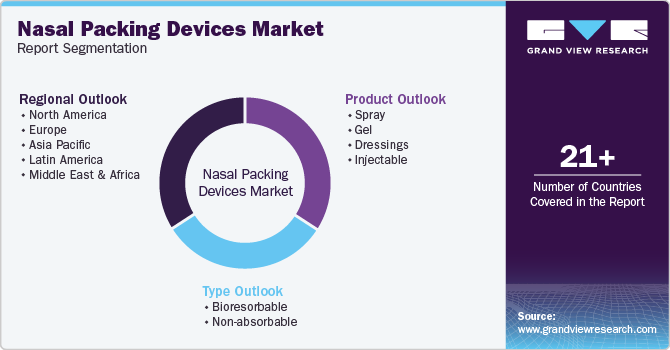
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global nasal packing devices market report on the basis of product, type and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Spray
-
Gel
-
Dressings
-
Injectable
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Bioresorbable
-
Non-absorbable
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The nasal packing devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each nasal packing devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Spray
Revenue is generated through the sale of topical nasal hemostatic sprays formulated to rapidly control epistaxis and support postoperative bleeding management. Manufacturers capture recurring revenue from procedure-based utilization in hospitals, emergency departments, outpatient ENT clinics, and ambulatory surgical centers, with increasing adoption driven by ease of application, reduced treatment time, and growing preference for minimally invasive bleeding control solutions.
Gel
Revenue is derived from the commercialization of nasal hemostatic gels used to achieve localized bleeding control, promote mucosal healing, and reduce postoperative adhesions following ENT procedures. Market participants benefit from recurring demand across surgical and emergency care settings, particularly as advanced bioactive and bioresorbable gel formulations gain wider clinical acceptance.
Dressings
Revenue flows from the sale of nasal dressings and packing materials, including absorbable sponges, foam dressings, gauze-based products, inflatable tampons, and hemostatic packing devices utilized for epistaxis management and postoperative support. Manufacturers generate value through high procedural volumes and the routine replacement of single-use dressings across hospitals and specialty ENT centers.
Injectable
Revenue is captured through injectable hemostatic agents and biomaterial-based formulations administered during or following nasal surgical procedures to control bleeding, seal tissue, and facilitate healing. Manufacturers benefit from premium-priced products designed for complex surgical interventions, supported by increasing adoption of advanced hemostatic technologies in ENT surgery.
Segment - Type
Revenue capture definition
Non-absorbable
Revenue is generated through the sale of traditional non-absorbable nasal packing devices, including gauze packs, polyvinyl alcohol (PVA) sponges, inflatable balloon packs, and nasal tampons that require removal following hemostasis. Manufacturers capture recurring revenue through widespread utilization in emergency epistaxis management and routine ENT procedures, supported by their cost-effectiveness, clinical familiarity, and broad availability across healthcare settings.
Bioresorbable
Revenue is derived from the commercialization of bioresorbable nasal packing devices manufactured using biodegradable polymers, gelatin, chitosan, hyaluronic acid, oxidized regenerated cellulose, collagen, and other advanced biomaterials that gradually dissolve within the nasal cavity, eliminating the need for removal. Market participants benefit from premium pricing driven by improved patient comfort, reduced postoperative pain, lower risk of mucosal trauma and adhesions, and increasing adoption in functional endoscopic sinus surgery (FESS), septoplasty, rhinoplasty, and other advanced ENT procedures.
Estimation Model
Phase Name
Key Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Define/Finalize Product/Device Categories
2. Scope Product, Type, and Geography
3. Define/Finalize Criteria Based on End-User Use for Estimated Replacement and Purchase per O/R Cases
4. Align procedure list for focused analysis
Annual Reports, FDA/CE approval, company product literature
Build the Product Base
How large is the total end-market universe?
1. Collect Annual Volumes of O/R Surgical Procedures and Weighted Trend and Split Assumptions
2. Evaluate Annual Package Device Utilization per Procedure and Global Indication
3. Map Product Usage Across Hospitals, Ambulatory Surgical Centers, and O/R Rooms
4. Develop Procedure Volume Forecasts
Government publications, physician blogs, hospital discharge databases, company filings/presentations
Estimate Penetration
What proportion of procedures utilized annual packaging devices?
1. Assess Adoption of Retail Package Devices Across O/R Procedures and End-User Segments
2. Evaluate Shift from Conventional to Biodegradable Retail Packaging Products
3. Analyze Utilization Split by Product Type and Healthcare Setting
4. Validate assumptions using manufacturer data and trade publications
Government publications, physician blogs, company annual reports, product literature
Revenue Conversion
How do procedure volumes translate into market revenue?
1. Determine ASPs by Product Category and Design
2. Calculate Average Device Consumption per Procedure
3. Apply Projected Pricing and Utilization Variations
4. Cross-check with Company Revenues and Trade Data
Government publications, physician blogs, hospital discharge assessments, company financial reports
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global nasal packing devices market, covering leading manufacturers of absorbable and non-absorbable nasal packing products, hemostatic gels, sprays, dressings, injectable hemostats, and bioresorbable biomaterial-based solutions. The study evaluated product portfolio breadth, technology innovations, manufacturing capabilities, distribution networks, regulatory approvals, pricing strategies, strategic partnerships, and geographic expansion initiatives across hospitals, ambulatory surgical centers (ASCs), emergency departments, and specialty ENT clinics. It also assessed innovation trends in bioresorbable materials, antimicrobial technologies, drug-eluting nasal packaging systems, and patient comfort-focused product development adopted by both established medical device companies and emerging manufacturers.
Enables stakeholders to understand the competitive dynamics, product positioning, commercialization strategies, and technology adoption trends shaping the global nasal packing devices market. Supports supplier evaluation, product portfolio differentiation, partnership development, and benchmarking of innovation capabilities to strengthen market penetration across ENT care settings.
Segment by Type Analysis
Conducted a detailed segment-level assessment of the nasal packing device market across key product types including non-absorbable and bioresorbable nasal packing devices. The study analyzed adoption trends, product utilization patterns, clinical preferences, pricing differentials, and technology advancements associated with each product type across hospitals, ambulatory surgical centers (ASCs), emergency departments, and specialty ENT clinics. It further evaluated postoperative-specific utilization by assessing environment and postoperative ENT surgical care, historical and forecast demand trends, reimbursement scenarios, and the growing transition toward bioresorbable materials driven by improved patient comfort, reduced postoperative complications, and elimination of device removal procedures.
Enables stakeholders to gain granular insights into adoption, utilization, and commercialization of absorbable and non-absorbable nasal packing devices. Supports product positioning, pricing optimization, technology advancement, and manufacturing prioritization by understanding the clinical positioning of high-growth product types associated with improved patient outcomes. Assists in benchmarking conventional non-absorbable versus bioresorbable products across global healthcare markets.
Macroeconomic Analysis
Conducted an in-depth macroeconomic assessment focused on healthcare expenditure growth, reimbursement evolution, and the shift in noninvasive ENT care paths, aging demographics, expanding access to ENT care, and hospital infrastructure investments influencing demand for nasal packing devices. The study evaluated key economic indicators including hospital infrastructure budgets, reimbursement patterns, cost pressures on medical consumables, biomedical R&D, supply chain disruptions, and international trade policies affecting nasal packing device demand. The macroeconomic study also emphasized infection prevention, outpatient surgical care, and adoption of advanced bioresorbable technologies influencing market growth.
Enables stakeholders to understand the macroeconomic environment driving the global nasal packing devices market. Supports long-term forecasting, investment planning, and supply chain management through assessment of market performance indicators and government decisions amid changing healthcare expenditure trends. Aids in adopting advanced technologies to tackle infection prevention and improve patient outcomes.
Frequently Asked Questions About This Report
North America dominated the nasal packing devices market with the highest share of 46.8% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Non-absorbable held the largest revenue share in 2025, while bioresorbable is the fastest-growing area.
The global nasal packing devices market size was estimated at USD 215.4 million in 2025 and is expected to reach USD 226.3 million in 2026.
The global nasal packing devices market is expected to grow at a compound annual growth rate of 5.2% from 2026 to 2033 to reach USD 323.7 million by 2033.
By product, the spray segment led with a 29.0% revenue share in 2025, while gel segment is the fastest-growing segment.
Some key players operating in the nasal packing devices market include Smith & Nephew, Lohmann & Rauscher, Network Medical Products Ltd., Olympus Corporation, Summit Medical Group, Entellus Medical, Inc., Medtronic, Stryker, Merocel Corp, Boston Scientific Corporation
Key factors driving the nasal packing devices market growth include an increasing number of nasal surgeries, the prevalence of epistaxis and chronic rhinosinusitis, growing geriatric population coupled with the prevalence of hypertension, favorable government initiatives along with rising per capita income.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


