
- Home
- »
- Advanced Interior Materials
- »
-
Non-ferrous Scrap Recycling Market Size, Growth Report, 2026-2033GVR Report cover

Non-ferrous Scrap Recycling Market (2026 - 2033)
Size, Share & Trends Analysis Report By Metal (Copper, Aluminum, Lead), By Sector (Construction, Automotive, Consumer Goods, Industrial Goods), By Region (North America, Europe, APAC, MEA), And Segment Forecasts
Market Size, 2025
$680.5BMarket Estimate, 2026
$696.5BMarket Forecast, 2033
$895.1BCAGR, 2026–2033
3.6%Non-ferrous Scrap Recycling Market Summary
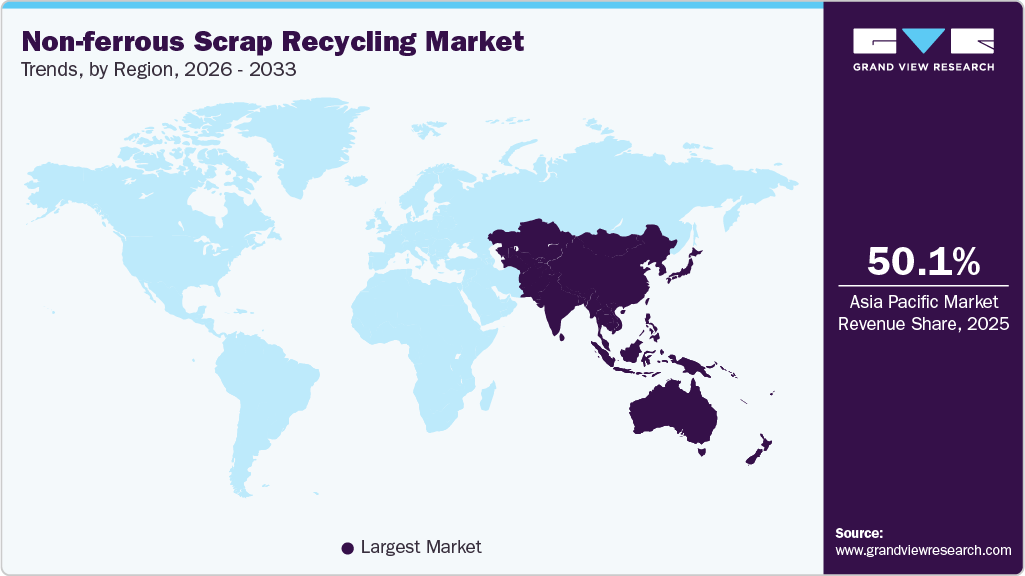
The global non-ferrous scrap recycling market size was valued at USD 680.5 billion in 2025 and is projected to grow from USD 696.5 billion in 2026 to USD 895.1 billion by 2033, at a CAGR of 3.6% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 50.1% in 2025. The growth is driven by rising demand for sustainable and cost-efficient raw materials across key end-use industries such as automotive, construction, and electrical & electronics, coupled with increasing regulatory emphasis on circular economy practices and carbon emission reduction.
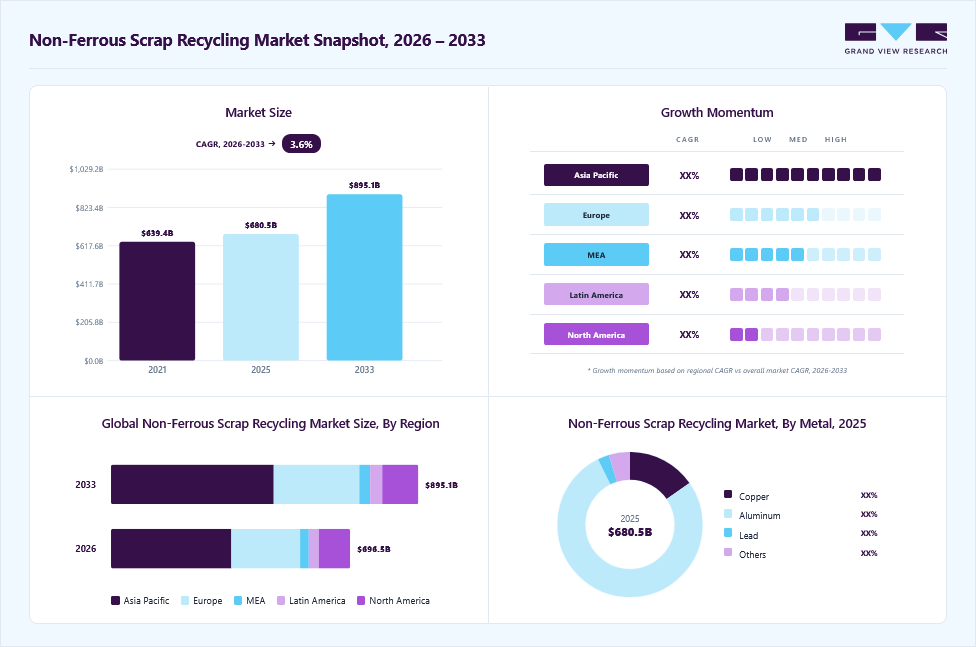 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By metal: Aluminum accounted for the largest share, contributing 77.3% of total revenue in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (50.1% revenue share, 2025)
- By country: The U.S. non-ferrous scrap recycling industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 680.5 Billion
- Estimated market size in 2026: USD 696.5 Billion
- Projected market size by 2033: USD 895.1 Billion
- CAGR (2026-2033): 3.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is being strongly propelled by sustainability-driven mandates, particularly the push to decarbonize energy-intensive metal production. Recycling aluminum, for instance, consumes up to ~95% less energy compared to primary smelting, while recycled copper saves ~80-85% energy, making secondary metals critical for achieving net-zero targets. Regulatory frameworks such as extended producer responsibility (EPR), landfill restrictions, and carbon pricing mechanisms are accelerating scrap utilization across automotive, construction, and packaging sectors. In addition, OEMs, especially in electric vehicles, are increasingly incorporating recycled aluminum and copper to reduce lifecycle emissions, while infrastructure projects are prioritizing low-carbon materials, further institutionalizing demand for recycled non-ferrous metals.
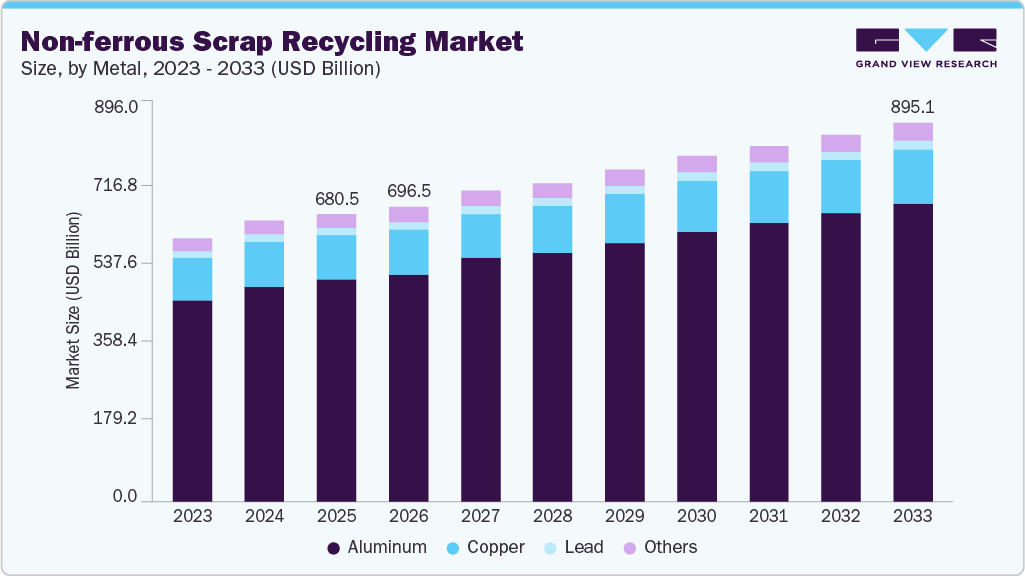 To learn more about this report, Download Free Sample Report
The industry is witnessing the rapid deployment of high-precision sorting and recovery systems to address the complexity of multi-metal waste streams. Sensor-based sorting technologies, including X-ray fluorescence (XRF), laser-induced breakdown spectroscopy (LIBS), and near-infrared (NIR) systems, are enabling real-time identification and separation of alloy-specific scrap, significantly improving yield and purity levels. Advanced eddy current separators are now capable of recovering ultra-fine non-ferrous particles, while AI-driven robotics are being used in automated material recovery facilities (MRFs) to enhance throughput and reduce manual intervention.
 To learn more about this report, Download Free Sample Report
Drivers, Opportunities & Restraints
The industry is being propelled by intensifying decarbonization targets and the need to secure a reliable raw material supply through secondary sources. Large-scale capital deployment into recycling infrastructure is reinforcing this trend. For example, in September 2025, Aurubis AG inaugurated a copper recycling facility in the U.S. with an investment of approximately USD 800 million, aimed at processing complex scrap streams and reducing dependence on primary metal imports. At the policy level, frameworks such as the EU’s Critical Raw Materials strategy, which targets a meaningful share of metals to be sourced from recycling by 2030, are further institutionalizing demand for recycled aluminum and copper across sectors such as energy, mobility, and construction.
The market is witnessing strong upside potential driven by financing support and the scaling of advanced recovery technologies, particularly for low-grade and multi-metal waste. In September 2025, the European Investment Bank approved funding of USD 232 million to support recycling capacity expansion and process optimization initiatives in Europe. Industry players are increasingly investing in integrated facilities capable of extracting multiple metals, including copper, nickel, and precious metals, from e-waste and industrial scrap. These developments are opening new revenue pools, improving recovery efficiencies, and strengthening supply chains for critical materials required in electrification and renewable energy deployment.
Market expansion is constrained by regulatory trade barriers and volatility in scrap pricing, both of which affect supply chain stability and margins. In November 2025, the European Union outlined plans to limit aluminum scrap exports starting in 2026 to retain material within the region for domestic processing. While such measures support local recyclers, they also disrupt global trade flows, particularly for countries reliant on imported scrap. Additionally, fluctuations in scrap metal prices driven by shifts in primary metal markets continue to create uncertainty in procurement and profitability, making long-term planning more complex for recyclers and downstream users.
Metal Insights & Trends
Aluminum dominated the non-ferrous scrap recycling market in 2025, accounting for the largest revenue share, and is also expected to register the highest CAGR over the forecast period. This is primarily due to its high recyclability, ability to retain properties after multiple recycling cycles, and significantly lower energy consumption compared to primary production. Strong demand from packaging, automotive, and construction sectors continues to support its leadership, while increasing adoption in electric vehicles and renewable energy applications is further accelerating growth. Technological advancements in sorting and remelting processes are also enhancing recovery efficiency, making aluminum recycling more economically attractive.
Copper and Lead also hold substantial shares in the market, driven by their critical applications and high recovery value. Copper recycling is gaining traction due to rising demand from electrical infrastructure, electronics, and renewable energy systems, where conductivity and performance are essential. Lead recycling remains well-established, particularly through the closed-loop recycling of lead-acid batteries, ensuring consistent scrap availability and high recovery rates. Environmental regulations around hazardous waste management and battery disposal further support lead recycling, while overall demand for secondary copper and lead continues to grow as industries seek cost-effective and sustainable material alternatives.
Sector Insights & Trends
The construction sector held the largest share of the industry in 2025, driven by extensive use of metals such as aluminum and copper in building infrastructure, wiring, roofing, and structural applications. Rapid urbanization, infrastructure development, and renovation activities across both developed and emerging economies are generating substantial volumes of recyclable scrap while simultaneously driving demand for cost-effective materials. The use of recycled metals in construction also aligns with green building standards and sustainability certifications, further reinforcing its dominance.
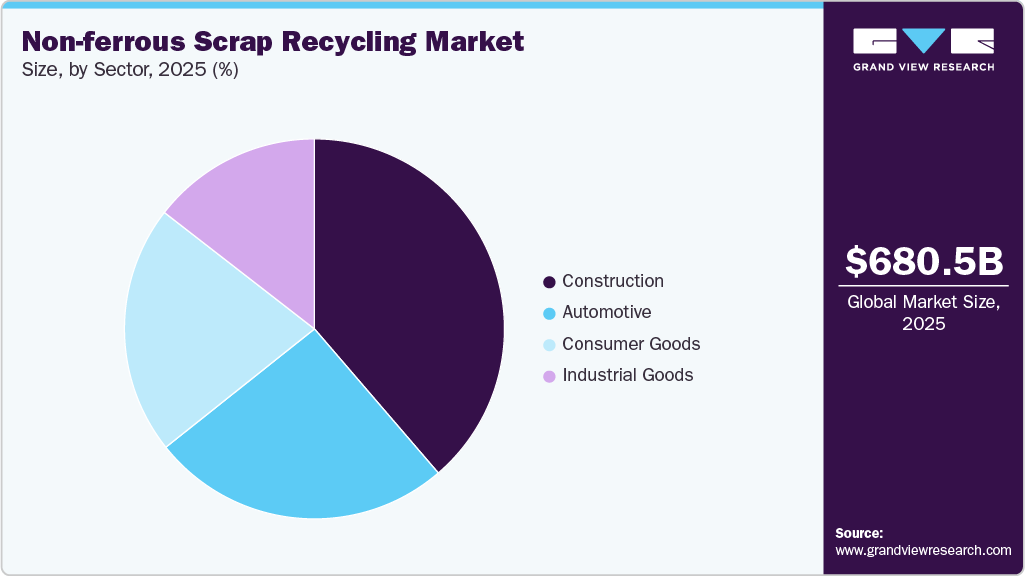 To learn more about this report, Download Free Sample Report
The consumer goods segment is expected to register the highest CAGR over the forecast period, supported by increasing production of electronics, appliances, and packaging materials. Rising consumption of electronic devices and short product life cycles are generating significant volumes of end-of-life products, creating a strong feedstock base for recycling. Additionally, growing emphasis on sustainable packaging and circular product design is encouraging manufacturers to incorporate higher proportions of recycled non-ferrous metals, particularly aluminum, thereby driving segment growth.
Regional Insights
North America non-ferrous scrap recycling market is characterized by a well-established collection and processing ecosystem, supported by stringent environmental regulations and strong demand from automotive, construction, and electrical sectors. The region is witnessing increased investments in advanced recycling infrastructure to enhance domestic metal supply chains and reduce reliance on imports. Additionally, the transition toward electric vehicles and renewable energy systems is significantly boosting demand for recycled aluminum and copper, while regulatory focus on reducing landfill waste and promoting circular economy practices continues to strengthen market growth.
U.S. Non-ferrous Scrap Recycling Market Trends
The non-ferrous scrap recycling market in the U.S. represents the largest market within North America, driven by high scrap generation, advanced recycling technologies, and strong industrial demand. The country is increasingly focusing on strengthening domestic recycling capacity, as evidenced by major investments such as large-scale copper and multi-metal recycling plants. Demand from EV manufacturing, grid modernization, and infrastructure development is accelerating the use of secondary metals. Additionally, supportive policies and sustainability commitments from corporations are encouraging the adoption of recycled materials across key industries.
Asia Pacific Non-ferrous Scrap Recycling Market Trends
The non-ferrous scrap recycling market in Asia Pacific dominates the global industry in terms of volume, led by countries such as China, India, and Japan. Rapid industrialization, urbanization, and infrastructure development are generating substantial scrap volumes while simultaneously driving demand for cost-effective raw materials. The region also benefits from a large informal recycling sector, particularly in India, although there is a gradual shift toward formalization and organized recycling systems. Government initiatives promoting resource efficiency, coupled with rising demand from electronics, automotive, and construction sectors, are key growth drivers.
 To learn more about this report, Download Free Sample Report
China’s non-ferrous scrap recycling market is evolving rapidly, supported by a strong government push toward resource efficiency, circular economy adoption, and carbon reduction goals. Recycling of key metals such as aluminum, copper, lead, and zinc is gaining momentum as industries increasingly prioritize secondary raw materials to reduce dependence on primary mining and volatile imports. Policy frameworks promoting cleaner production, stricter environmental norms, and formalization of the recycling ecosystem are accelerating the shift from fragmented, informal operations to more organized and technologically advanced processing facilities.
At the same time, rising domestic scrap generation from end-of-life products, infrastructure upgrades, and growing industrial activity is strengthening local supply streams. However, the market continues to navigate challenges such as quality inconsistency in scrap, price fluctuations, and the need for better collection and sorting systems. Overall, the sector is moving toward a more efficient, regulated, and sustainability-driven structure, with increasing integration across collection, processing, and end-use industries.
Europe Non-ferrous Scrap Recycling Market Trends
The non-ferrous scrap recycling market in Europe is highly regulated and technologically advanced, with a strong emphasis on sustainability and circular economic principles. Policies aimed at reducing carbon emissions and improving resource efficiency are encouraging higher recycling rates and investments in advanced sorting and recovery technologies. The region is also focusing on securing critical raw materials through domestic recycling, leading to strategic measures such as restrictions on scrap exports. Demand is primarily driven by automotive electrification, renewable energy deployment, and sustainable construction practices.
Latin America Non-ferrous Scrap Recycling Market Trends
The non-ferrous scrap recycling market in Latin America is emerging, supported by increasing industrial activity and rising awareness of recycling benefits. Countries such as Brazil and Mexico are key contributors, with growing investments in recycling infrastructure and metal recovery processes. However, the market remains relatively fragmented, with a mix of formal and informal players. Expanding manufacturing sectors and export-oriented metal industries are creating opportunities for scrap utilization, although challenges such as regulatory gaps and limited technological adoption persist.
Middle East & Africa Non-ferrous Scrap Recycling Market Trends
The non-ferrous scrap recycling market in the Middle East & Africa region is witnessing gradual growth, driven by infrastructure development and increasing focus on economic diversification. Countries in the Middle East are investing in recycling facilities to reduce dependence on imported raw materials and support sustainable development goals. In Africa, the market is largely informal but holds significant potential due to rising urbanization and the increasing generation of metal scrap from construction and consumer goods. Improving regulatory frameworks and foreign investments are expected to enhance market structure and growth over the coming years.
Key Non-ferrous Scrap Recycling Company Insights
Some of the key players operating in the non-ferrous scrap recycling market include Aurubis AG, Sims Metal Management Inc., and Others.
-
Aurubis AG, established in 1866 and headquartered in Hamburg, Germany, is a leading global provider of non-ferrous metal recycling and copper production. The company specializes in processing complex scrap materials, including electronic waste and industrial residues, through advanced smelting and refining technologies. Aurubis focuses on circular economy principles by maximizing metal recovery rates, reducing carbon emissions, and investing in state-of-the-art recycling facilities to ensure sustainable resource utilization across its global operations.
-
Sims Metal Management Inc., established in 1917 and headquartered in Sydney, Australia, is one of the world’s largest metal recycling companies, with a strong presence in non-ferrous scrap processing. The company operates an extensive network of collection, processing, and trading facilities, supplying recycled metals to manufacturers worldwide. Sims emphasizes sustainability through energy-efficient operations, advanced sorting technologies, and initiatives aimed at reducing landfill waste, while supporting the transition to a circular economy.
-
Hindalco Industries Ltd., established in 1958 and headquartered in Mumbai, India, is a leading aluminum and copper producer with integrated recycling capabilities. A part of the Aditya Birla Group, Hindalco has been expanding its footprint in non-ferrous scrap recycling, particularly through investments in downstream aluminum recycling and circular material solutions. The company focuses on sustainable metal production by increasing the use of recycled inputs, improving energy efficiency, and supporting low-carbon manufacturing across automotive, packaging, and construction applications.
Key Non-ferrous Scrap Recycling Companies:
The following key companies have been profiled for this study on the non-ferrous scrap recycling market.
- Aurubis AG
- Chiho Environmental Group Limited
- Hindalco Industries Ltd.
- Kuusakoski
- Matalco Inc.
- OmniSource Corp.
- Recyclex
- SA Recycling LLC
- Sims Metal Management Inc.
- TSR Recycling GmbH & Co. KG
Recent Developments
-
Aurubis AG, in September 2025, officially commissioned its new copper recycling facility in Richmond, Georgia (U.S.), with an investment of approximately USD 800 million. The plant is designed to process around 180,000 tons of complex scrap annually, enabling higher recovery of copper and precious metals from multi-material waste streams. This development strengthens Aurubis’ position in the North American recycling market, enhances supply security for secondary metals, and supports decarbonization by reducing reliance on primary mining.
-
Sims Metal Management Inc., in February 2026, announced the expansion of its advanced metal recovery operations in the U.S. and U.K., focusing on increasing processing capacity for non-ferrous scrap and e-waste. The initiative includes the deployment of AI-enabled sorting systems and upgraded shredding technologies to improve material recovery rates and operational efficiency. This expansion aligns with growing demand for high-purity recycled metals and strengthens the company’s role in supporting circular economy supply chains.
-
Hindalco Industries Ltd., in August 2025, announced an investment of approximately USD 150 million to scale up its aluminum recycling operations in India and the U.S., including capacity expansion at its downstream facilities. The initiative aims to increase the share of recycled aluminum in its overall production mix, reduce carbon intensity, and cater to rising demand from the automotive and packaging sectors. This move reinforces Hindalco’s focus on sustainable metal production and circular material usage.
Non-ferrous Scrap Recycling Market Report Scope
Report Attribute
Details
Market Definition
The market size represents the total value of scrap generated from different sectors for a particular year.
Market size value in 2026
USD 696.5 billion
Revenue forecast in 2033
USD 895.1 billion
Growth rate
CAGR of 3.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons; revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Metal, sector, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK.; Russia; Turkey; China; India; Japan; Brazil
Key companies profiled
Aurubis AG; Chiho Environmental Group Limited; Hindalco Industries Ltd.; Kuusakoski; Matalco Inc.; OmniSource Corp.; Recyclex; SA Recycling LLC; Sims Metal Management Inc.; TSR Recycling GmbH & Co. KG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-ferrous Scrap Recycling Market Report Segmentation
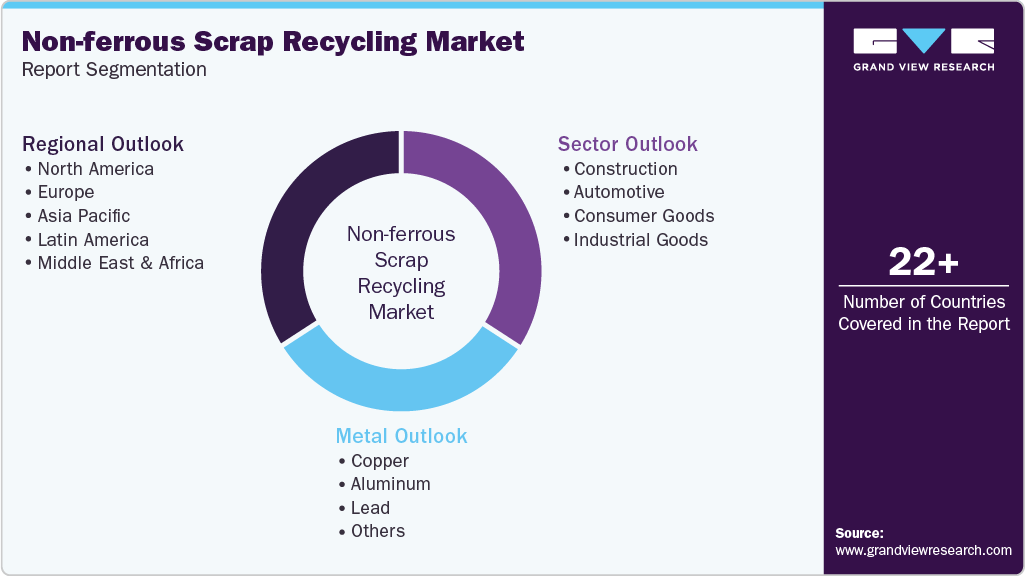
This report forecasts volume & revenue growth at the global, regional, and country levels and analyses the latest trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global non-ferrous scrap recycling market report by metal, sector, and region:
 To learn more about this report, Download Free Sample Report
-
Metal Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Copper
-
Aluminum
-
Lead
-
Others
-
-
Sector Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Construction
-
Automotive
-
Consumer Goods
-
Industrial Goods
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Russia
-
Turkey
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Frequently Asked Questions About This Report
The global non-ferrous scrap recycling market size was valued at USD 680.5 billion in 2025 and is estimated at USD 696.5 billion for 2026.
The global non-ferrous scrap recycling market is expected to grow at a CAGR of 3.6% from 2026 to 2033, reaching USD 895.1 billion by 2033.
Aluminum dominated the non-ferrous scrap recycling market by metal type, accounting for 77.3% of total revenue in 2025, driven by its high recyclability and strong demand across key industries. Its growing use in lightweight and sustainable applications continues to support its leading position.
Key players include Aurubis AG; Chiho Environmental Group Limited; Hindalco Industries Ltd.; Kuusakoski; Matalco Inc.; OmniSource Corp.; Recyclex; SA Recycling LLC; Sims Metal Management Inc.; TSR Recycling GmbH & Co. KG.
The global non-ferrous scrap recycling market is driven by rising demand for sustainable and cost-efficient raw materials across industries such as automotive, construction, and electrical & electronics.
Asia Pacific dominated with a 50.1% revenue share in 2025.
Construction segment held the largest revenue share in 2025, while consumer goods is the fastest-growing sector.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


