
- Home
- »
- Medical Devices
- »
-
On-body Injectors Market Size & Share Report, 2026-2033GVR Report cover

On-body Injectors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Spring-based, Motor Driven, Rotary Pump, Expanding Battery), By Application (Oncology, Diabetes, Cardiovascular Disease), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$6.3BMarket Estimate, 2026
$7.3BMarket Forecast, 2033
$17.3BCAGR, 2026–2033
13.2%On-body Injectors Market Summary
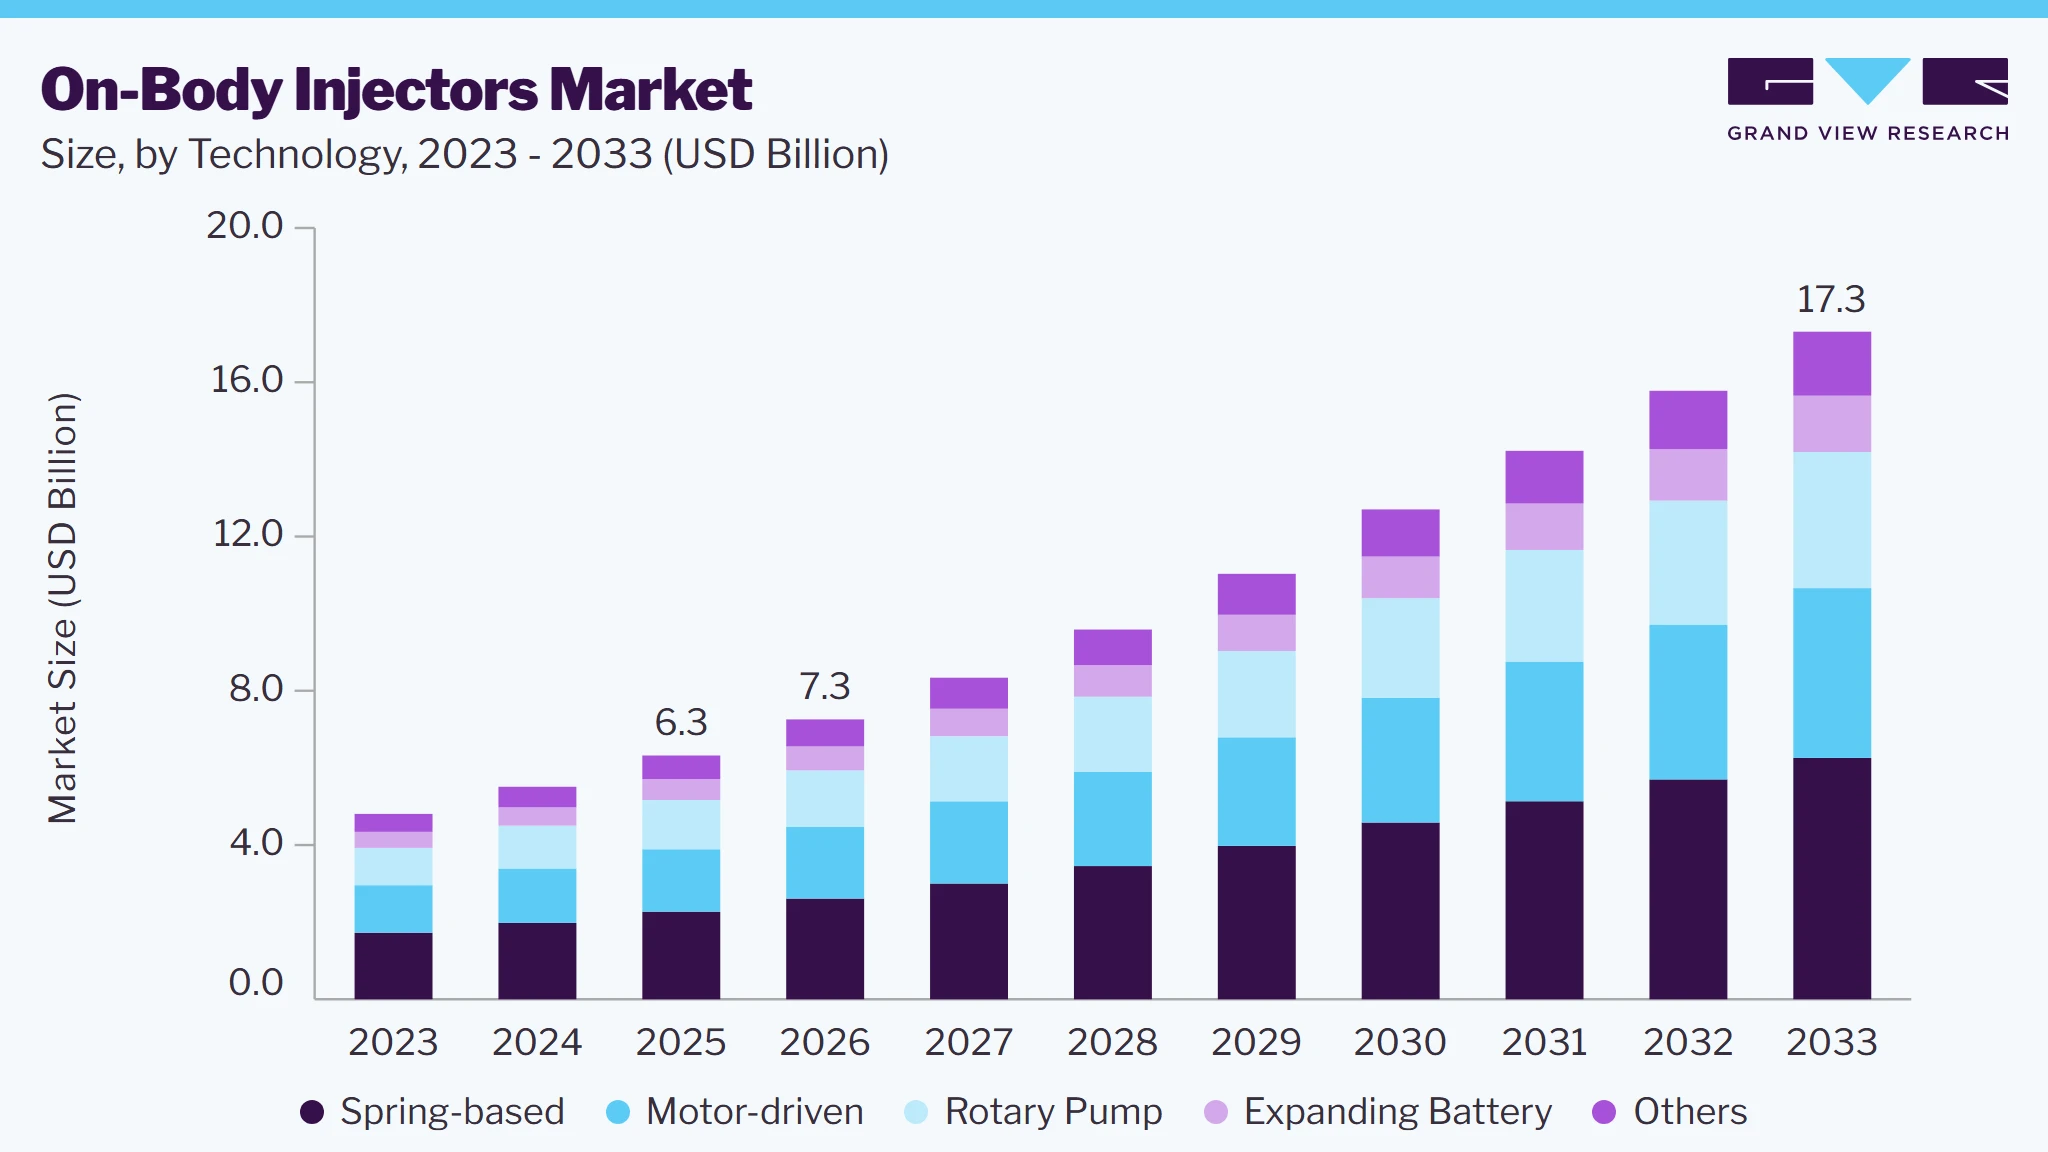
The global on-body injectors market size was valued at USD 6.3 billion in 2025 and is projected to grow from USD 7.3 billion in 2026 to USD 17.3 billion by 2033, at a CAGR of 13.2% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 33.1% in 2025. This can be attributed to the increasing prevalence of chronic diseases, technological advancements in injectors, growing focus on home healthcare, increasing concerns about needlestick injuries, and a wide range of applications of on-body injectors.
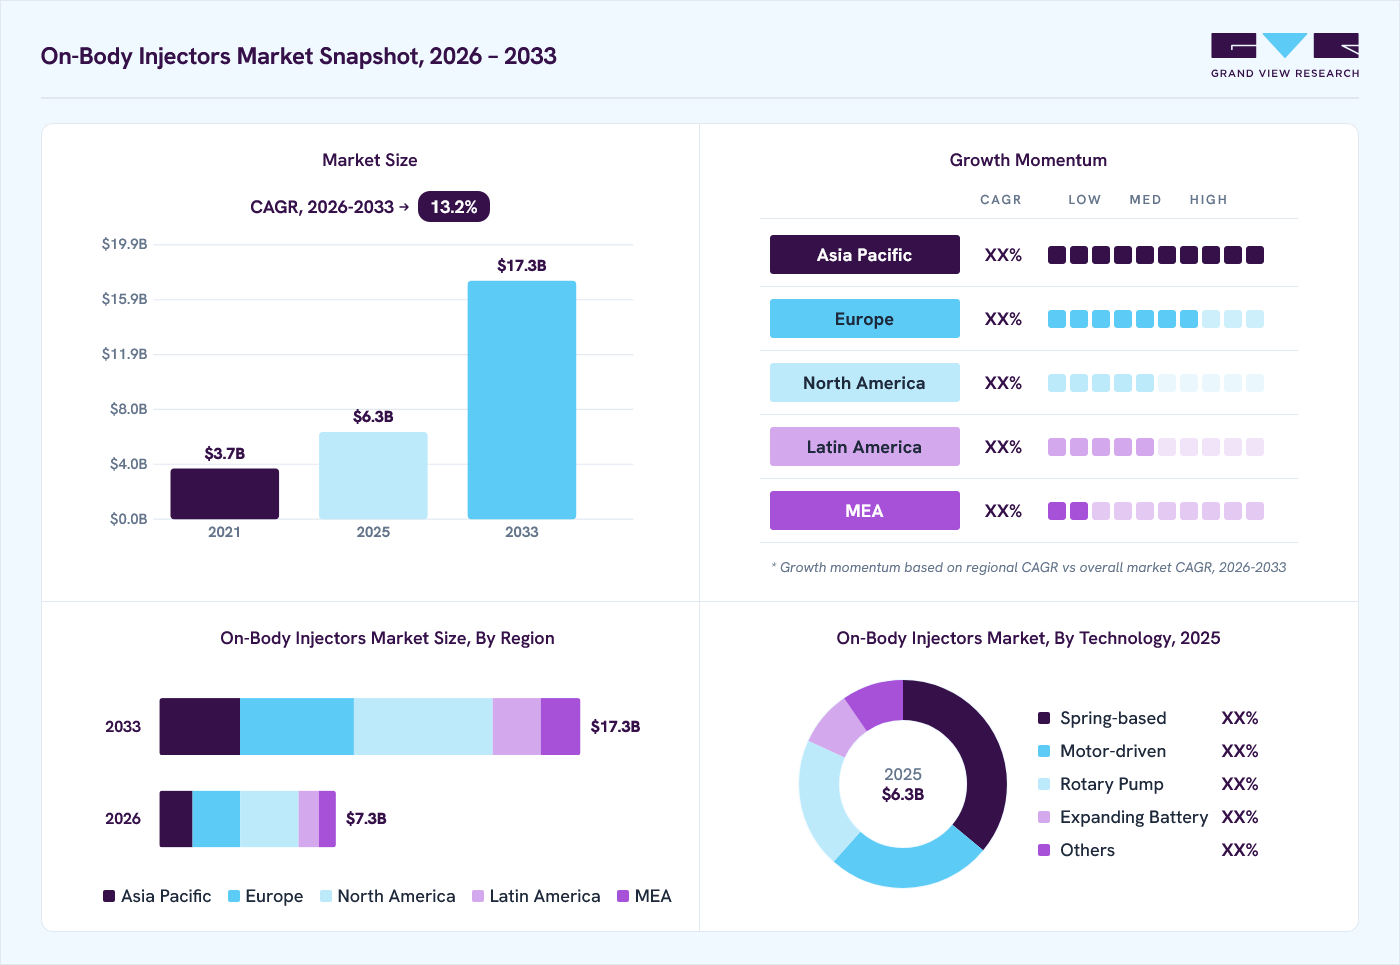 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Spring-based segment held the largest revenue share of 36.0% in 2025.
- By application: Diabetes segment held the largest revenue share of 32.6% in 2025.
- By end-use: Home care settings segment held the largest revenue share of 50.0% in 2025.
Regional Highlights
- Largest regional market: North America (33.1% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.3 Billion
- Estimated market size in 2026: USD 7.3 Billion
- Projected market size by 2033: USD 17.3 Billion
- CAGR (2026-2033): 13.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Chronic diseases such as diabetes, cancer, asthma, Alzheimer's disease, Parkinson's disease, and others often require frequent injections, and on-body injectors offer a convenient and manageable solution. According to the International Diabetes Federation, 537 million adults aged between 20 - 79 had diabetes in 2021, which is expected to increase to 643 million in 2030.The global demography is witnessing a significant shift with the increasing geriatric population. For instance, according to WHO, the global population aged above 60 is expected to reach 2.1 billion by 2050. This elderly population base is significantly vulnerable to chronic conditions and is more prone to developing chronic diseases that require regular monitoring and medication with their increasing age. For instance, according to the Commentary on Chronic Disease Prevention Report 2022, around 60% of the country’s adult population had at least one chronic disease. Moreover, around 40% of the adults were suffering from multiple chronic conditions. This elderly population prefers to receive care in the comfort of their own homes rather than in healthcare facilities. This is expected to increase the demand for on-body injectors as they allow older adults to manage their conditions at home without need.
 To learn more about this report, Download Free Sample Report
Needlestick injuries are a major occupational hazard for healthcare workers, leading to safety concerns and demand for advanced devices. As a result of the safety concerns, there has been a shift towards using more automated and hands-free drug delivery devices such as on-body injectors. According to a study published by the National Institute of Health in February 2022, an intravenous cannula (33.0%) and a hypodermic needle (18.7%) were the two most common devices responsible for needlestick injuries. The on-body injectors offer an advanced alternative to these needles and can reduce the risk of needlestick injuries during administration, which is expected to increase their demand over the forecast period.
Market Dynamics
The on-body injectors market is experiencing substantial growth driven by the increasing prevalence of chronic diseases requiring long-term biologic drug administration, including cancer, autoimmune disorders, diabetes, cardiovascular diseases, and rare diseases. The market is further supported by the growing demand for patient-centric drug delivery solutions, rising adoption of self-administration therapies, expansion of biologics and biosimilars pipelines, and continuous advancements in wearable drug delivery technologies. On-body injectors enable pharmaceutical companies, healthcare providers, hospitals, specialty clinics, and home healthcare settings to administer large-volume and high-viscosity medications through a convenient, minimally invasive, and automated delivery platform. These devices are widely utilized for oncology treatments, immunology therapies, diabetes management, and other chronic disease applications where traditional injections may be less convenient or require frequent healthcare facility visits, thereby improving treatment adherence, patient comfort, and overall healthcare efficiency.
The expanding use of biologic therapies and the growing preference for self-administration are key factors driving growth in the global on-body injectors market. Biologics are increasingly being prescribed for the treatment of complex chronic diseases such as cancer, autoimmune disorders, inflammatory bowel disease, multiple sclerosis, and rare diseases. Many of these therapies involve large-volume or high-viscosity formulations that can be challenging to administer using conventional syringes or auto injectors. On-body injectors provide an effective solution by enabling automated, controlled subcutaneous drug delivery over extended periods while improving patient comfort and mobility. Furthermore, healthcare systems are increasingly promoting home-based treatment models to reduce hospital visits, enhance patient convenience, and optimize healthcare resources.
Recent regulatory advancements further highlight the growing importance of on-body injector technologies. In 2025, Sanofi received authorization from the UK Medicines and Healthcare Products Regulatory Agency (MHRA) for the subcutaneous formulation of Sarclisa for multiple myeloma, making it the first anti-cancer therapy in the UK and globally to offer administration through an on-body injector. The approval provides patients with the flexibility to receive treatment either in outpatient settings or potentially at home, reducing the burden of repeated clinic visits while supporting patient-centered care. Such innovations demonstrate the growing integration of wearable drug delivery systems into oncology and specialty care, further accelerating demand for on-body injectors across global healthcare markets.
One of the primary restraints limiting the growth of the on-body injectors market is the high cost associated with device development, manufacturing, and integration with specialty pharmaceutical products. On-body injectors incorporate sophisticated components such as automated delivery systems, sensors, electronic controls, and connectivity features, increasing production costs compared to traditional injection devices. Furthermore, manufacturers must comply with stringent regulatory requirements related to drug-device combination products, safety validation, human factors engineering, and product reliability. Obtaining regulatory approvals often involves extensive clinical testing and documentation, which can increase development timelines and overall costs. These challenges may limit adoption among smaller pharmaceutical companies and create affordability concerns in cost-sensitive healthcare systems, particularly in developing regions where reimbursement support for advanced drug delivery technologies remains limited.
Market Concentration & Characteristics
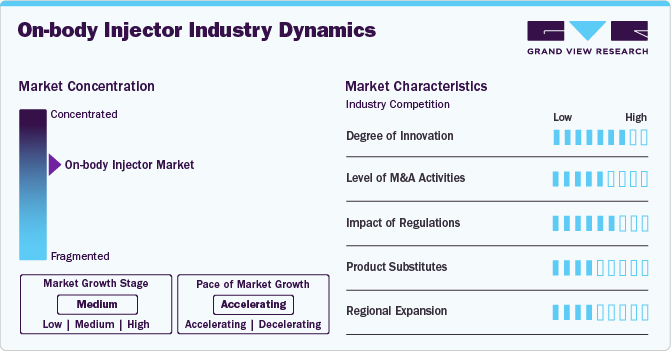
The on-body injectors industry is characterized by the increasing prevalence of chronic diseases, the development of advanced solutions by the market players, a wide range of applications of on-body injections, increasing preference for home care coupled with an aging population, focus on reducing the burden on healthcare organizations, and efforts to reduce needle stick injuries.
The market exhibits a high degree of innovation, driven by the increasing efforts of market players to develop solutions addressing different patient needs, convenience, and safety. For instance, in May 2021, Gerresheimer introduced SensAIR, a first-of-its-kind platform for on-body drug delivery to administer high-viscosity drugs such as monoclonal antibodies. Developing such innovative products to address different patient needs increases the degree of innovation in the market.
 To learn more about this report, Download Free Sample Report
Regulatory bodies such as the FDA and EMA have established clear guidelines for approving and clearing on-body injectors as medical devices. The standardization of the regulatory pathways and increasing acceptance of these devices by authorities as viable drug delivery devices offering better patient care and improving patient care are significantly shaping the market's regulatory scenario.
Mergers and acquisitions (M&A) in the on-body injector industry are rising as companies seek to expand their market share, product portfolios, and technological capabilities. For instance, in June 2023, LTS LOHMANN Therapie-Systeme AG announced the acquisition of Sorrel's wearable injection device business to expand its existing portfolio by adding large-volume wearable injector technologies.
The market faces a moderate threat from product substitutes, primarily driven by the availability of established drug delivery methods and the emergence of innovative technologies. While on-body injectors offer enhanced patient convenience and adherence, traditional options such as oral medications and manual injections remain cost-effective and familiar alternatives. However, the demand for self-administration coupled with the increasing prevalence of chronic diseases strengthens the position of these devices over other alternatives.
The expansion strategies the market players use are driven by efforts to increase the customer base and grab the opportunities offered by emerging markets such as Asia Pacific and Latin America, which have developing healthcare sectors.
Analyst Perspective
The on-body injectors market is expected to grow strongly as healthcare shifts toward patient-centric, home-based, and self-administered treatments. Rising chronic diseases and increasing use of biologics are driving demand for convenient drug delivery systems. Innovations such as wearable, connected, and automated injectors are expanding applications across oncology, autoimmune diseases, diabetes, and other therapeutic areas. Partnerships between pharmaceutical and device companies are accelerating drug-device combination products. Despite challenges such as regulatory complexity, high development costs, and reimbursement issues, growing home healthcare infrastructure, product innovation, and demand for convenient and personalized treatments are expected to support long-term market growth.
Technology Insights
Based on technology, the spring-based segment led the market with the largest revenue share of 36.0% in 2025. Spring-based on-body injectors are efficient devices that provide several advantages for patients and healthcare providers. They deliver medication with consistent pressure and speed, ensuring accurate dosing, which is crucial for treatments requiring precise amounts, such as insulin for diabetes or biologics for autoimmune conditions. This controlled delivery reduces the risk of human error with manual injections. In addition, these injectors are user-friendly, featuring automatic needle insertion and retraction, which significantly reduces discomfort and anxiety. This simplicity enhances patient compliance, as people are more likely to follow their medication regimen when the process is easy and less painful. Moreover, these devices allow patients to administer their doses with the simple press of a button, making them a preferred choice over a more complex delivery mechanism. The increasing innovation in these devices and their cost-effectiveness are expected to increase their demand over the forecast period.
The rotary pump segment is projected to experience the fastest CAGR of 13.4% over the forecast period. These pumps offer high control in dispensing medications by leveraging advanced fluid mechanics, minimizing the risk of dosing errors, and maximizing therapeutic efficacy. This increases their applicability in delivering drugs such as biologics where precise dosing is critical. Moreover, these devices can offer advanced functionalities such as wireless connectivity, customizable settings, & remote monitoring capabilities, which are further anticipated to drive their demand over the forecast period.
Application Insights
Based on application, the diabetes segment led the market with the largest revenue share of 32.6% in 2025. This can be attributed to the high and growing prevalence of diabetes globally, particularly type 2 diabetes, which requires frequent insulin administration. According to the Centers for Disease Control and Prevention data updated in May 2024, around 38 million people in the U.S. are living with diabetes, with around 90% to 95% of them suffering from type 2 diabetes-such a high prevalence of diabetes requiring regular increases the demand for on-body injectors. Moreover, on-body injectors offer a convenient solution for diabetic patients to self-manage their condition, improving treatment adherence and glycemic control, which is further anticipated to fuel the segment's growth.
The autoimmune diseases segment in the on-body injectors market is projected to experience the fastest CAGR over the forecast period owing to the rising prevalence of chronic autoimmune conditions such as rheumatoid arthritis, multiple sclerosis, and Inflammatory Bowel Diseases (IBD). According to a study published by Crohn's & Colitis UK in March 2022, around 1 in every 123 people in the UK suffer from IBD. Patients suffering from these autoimmune disorders often require frequent, long-term administration of biologic drugs and immunotherapies, making on-body injectors an ideal delivery solution and driving segment growth.
End-use Insights
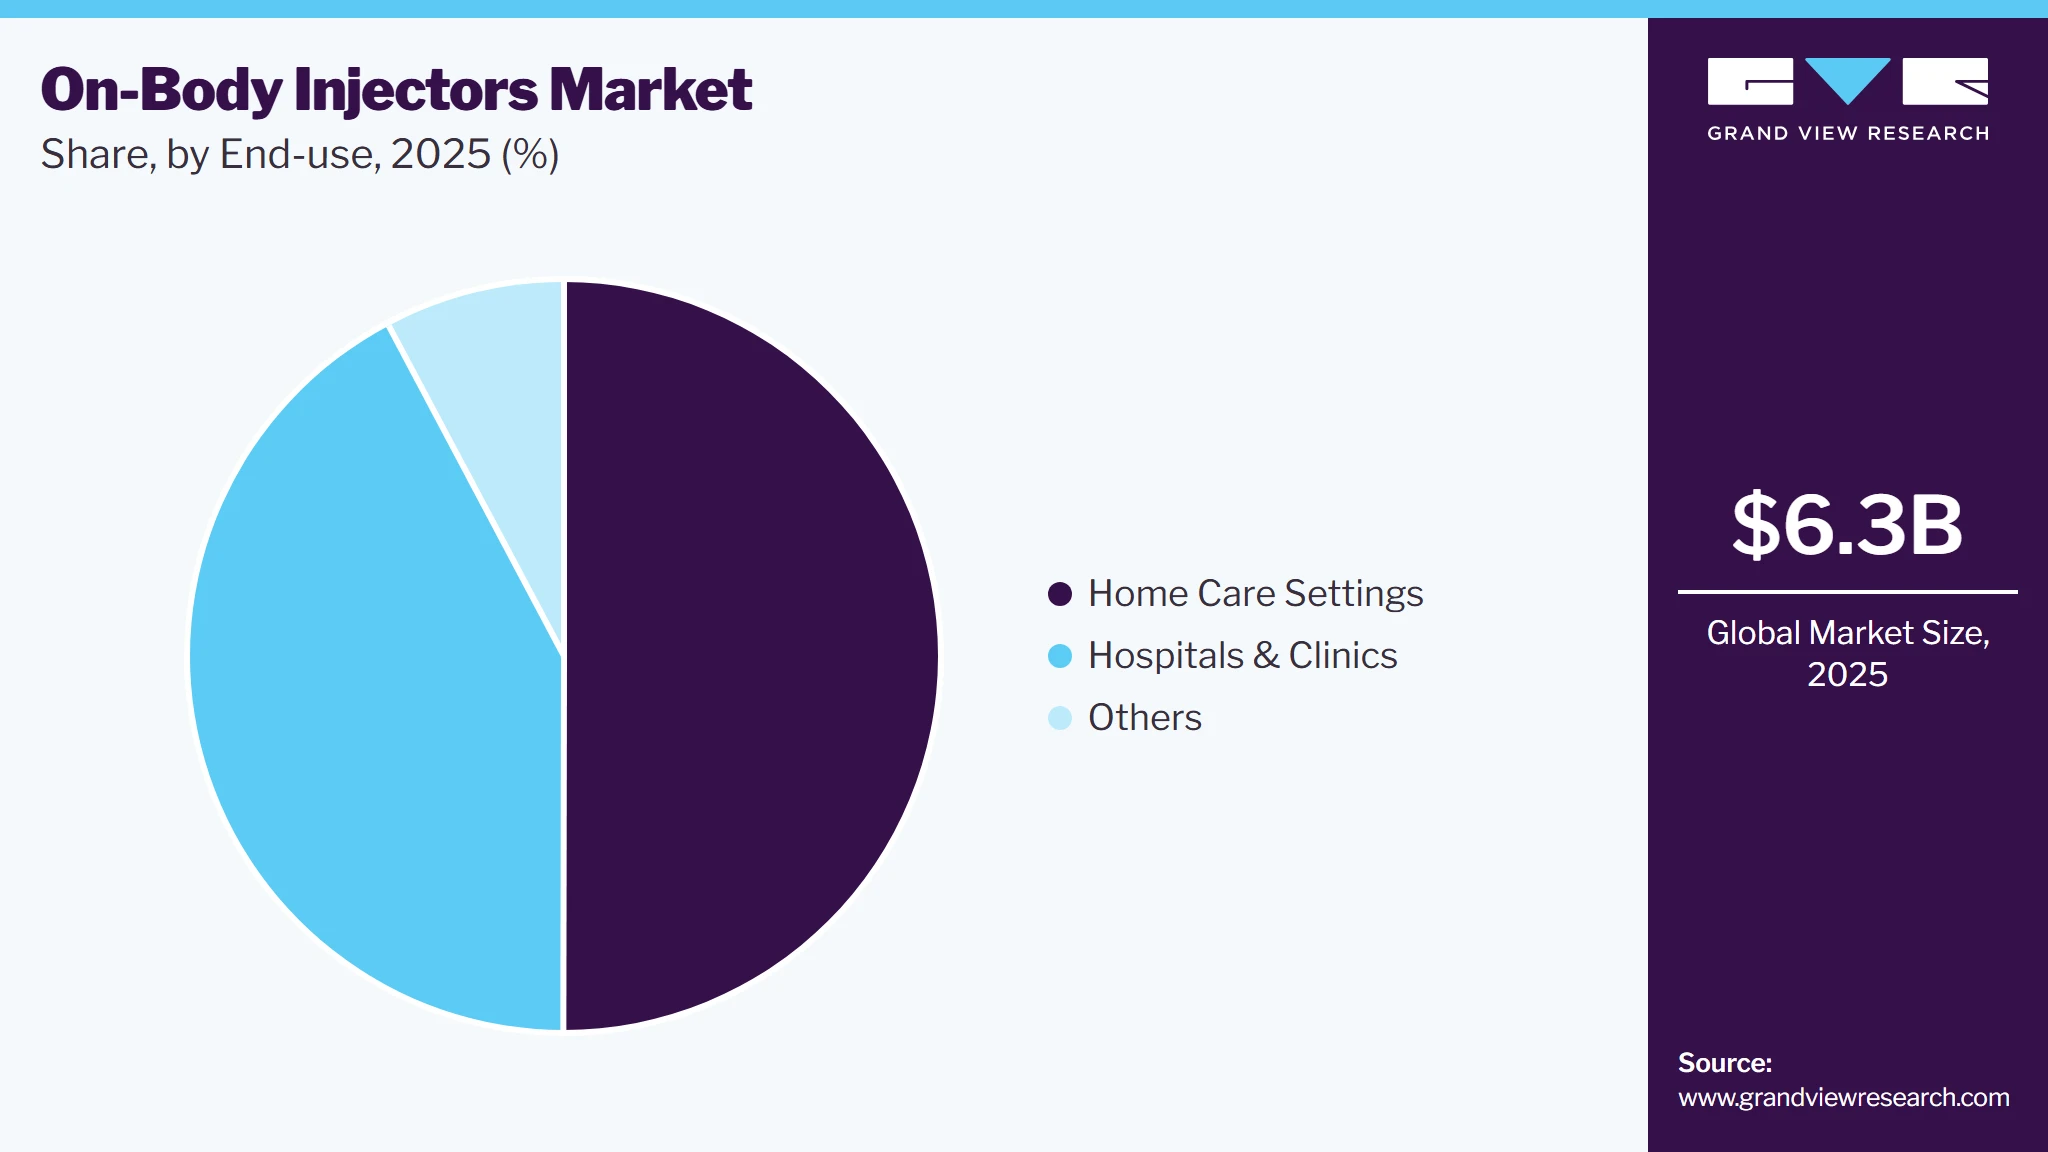
Based on end-use, the home care settings segment led the market with the largest revenue share of 50.0% in 2025. This dominance is attributable to the growing preference for self-administration of medications and the increasing adoption of on-body injectors for managing chronic conditions such as diabetes, autoimmune disorders, and cancer. Several on-body injectors enable patients to conveniently administer their medications at home, eliminating the need for frequent visits to healthcare facilities. This convenience factor, coupled with the hands-free and discreet nature of on-body injectors, has made them the preferred choice for patients seeking to integrate their treatment seamlessly into their daily lives, contributing to the high demand for these devices in the homecare settings.
 To learn more about this report, Download Free Sample Report
The hospitals and clinics segment is projected to grow significantly over the forecast period. This growth is driven by the rising prevalence of chronic diseases, such as cancer, diabetes, and autoimmune disorders, which require the administration of biologics and specialty medications. The on-body injectors offer healthcare providers in hospital and clinical settings a convenient and reliable solution to administer these complex therapies, improving patient outcomes and reducing the burden on healthcare facility staff.
Regional Insights
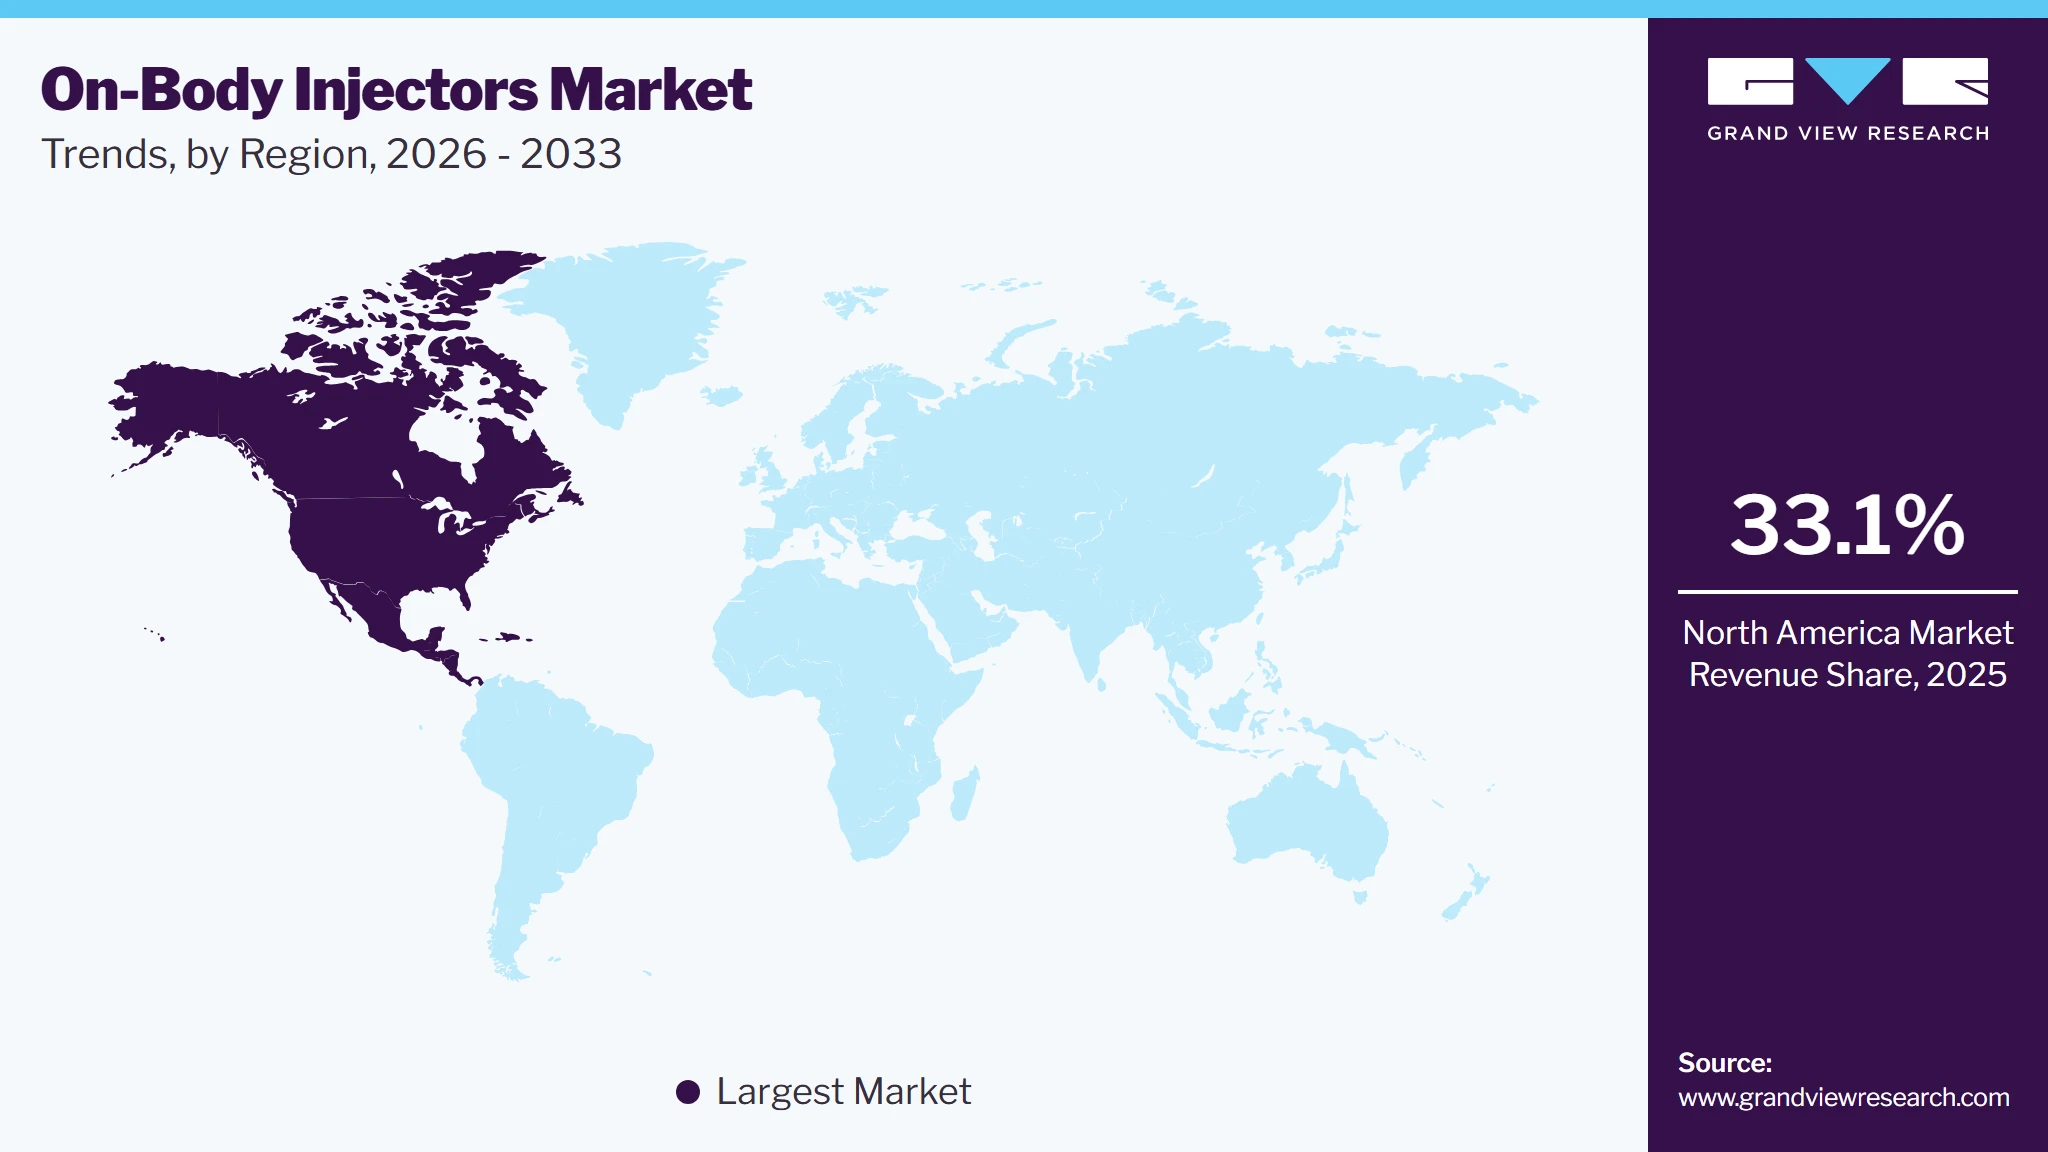
North America dominated the on-body injectors market with the largest revenue share of 33.1% in 2025. This can be attributed to the increasing prevalence of chronic diseases, the presence of key market players, the growing focus on home care, and better access to advanced on-body injectors. The North American region is witnessing a significant increase in the demand for home care owing to the region’s aging population and chronic diseases. For instance, according to Statistics Canada, 18.9% of Canada’s population was aged 65 or above in January 2023. This high share of the adult population, coupled with increasing chronic diseases and demand for home care, drives the demand for on-body injectors in the North American region.
 To learn more about this report, Download Free Sample Report
U.S. On-body Injector Market Trends
The on-body injectors market in the U.S. held the largest share in the North America region in 2025. This can be attributed to the increase in healthcare spending, supportive regulatory framework, and increasing R&D initiatives from market players in the country. The companies operating in the market are developing innovative solutions to meet the evolving market needs. Similarly, the FDA supports the innovation of on-body injectors to enhance the quality of care and utilize self-administration offered by on-body injectors. For instance, in October 2023, Apellis Pharmaceuticals, Inc. announced the U.S. FDA approval of the EMPAVELI injector. This injector is designed to enhance self-administration of EMPAVELI and is approved for adults suffering from paroxysmal nocturnal hemoglobinuria (PNH). The development of such innovative solutions coupled with a supportive regulatory framework is anticipated to drive the market growth of the country.
Europe On-body Injectors Market Trends
The on-body injectors market in Europe is witnessing growth, driven by the increasing geriatric population base in developed countries of the region, such as the UK, Germany, France, and Italy, the rising prevalence of chronic diseases, increasing demand for patient-centric medication options, and the increasing development of advanced on-body injectors in the region. According to the IDF Diabetes Atlas, around 61 million people in Europe will be living with diabetes in 2021, and this is expected to increase to approximately 67 million in 2030. This increasing prevalence of chronic diseases, with increasing access to advanced on-body injectors, is expected to drive market growth in the region.
The UK on-body injectors market is witnessing significant growth due to the increasing focus on improving patient care, reducing the risk of needle stick injuries, and increasing the availability of advanced injectors in the country. Needle stick injuries pose safety risks to healthcare workers in the UK and can lead to costly treatments and lawsuits. The Health and Safety (Sharp Instruments in Healthcare) Regulations 2013 emphasize the prevention of sharps injuries in the healthcare sector. Wearable injectors help mitigate these risks by eliminating the need for manual needle injections.
The on-body injectors market in France is witnessing significant growth owing to the growing homecare sector in the country, the increasing prevalence of chronic diseases, a supportive regulatory framework, and increasing awareness about the use of on-body injectors over traditional means of medication delivery. The benefits offered by on-body injectors, such as convenience, accuracy, and better safety, significantly increase the preference towards these devices for medication delivery, thereby driving the market growth.
Germany on-body injectors market is experiencing notable growth owing to the increasing acceptance of self-injectors, increasing geriatric population base, and focus on home care. Germany has a rapidly aging population with a high prevalence of chronic diseases such as diabetes, heart disease, and cancer. According to the World Bank, the number of people aged 65 and above in Germany has significantly increased from 17.1 million in 2015 to over 19.2 million in 2023. This growing geriatric population base, coupled with increasing chronic disease prevalence, is driving the market growth in Germany.
Asia Pacific On-body Injectors Market Trends
The on-body injectors market in Asia Pacific is witnessing significant growth driven by rising healthcare investments, an expanding elderly population, the increasing prevalence of chronic respiratory diseases, and increasing government initiatives to prioritize and promote healthcare reform and increase home care in the region’s healthcare facilities to decrease the burden of the large patient pool from the healthcare sectors.
Japanon-body injectors market is set for significant growth due to increasing concerns about patient safety and convenience and the country’s increasing geriatric population base. Japan has one of the fastest-aging populations globally. According to the World Bank, the elderly population in Japan has increased from 34.7 million in 2015 to around 37.4 million in 2023. This elderly population is further expected to increase the demand for on-body injectors in the country, thereby driving market growth.
Theon-body injectors market in China is expected to grow in the Asia Pacific in 2025. This can be attributed to the increasing adoption of on-body injectors, growing focus on developing country’s healthcare sector and decrease the burden on country’s healthcare sector. China is taking significant steps to develop its healthcare sector, which is anticipated to drive the country's demand for advanced medical devices such as on-body injectors.
India on-body injectors market is expected to grow significantly over the forecast period. Various factors, such as an increasing population base, high prevalence of chronic diseases, advancements in regulatory frameworks, and increasing availability of advanced medical devices, fuel the on-body injectors market in India. According to the India Diabetes (ICMR INDIAB) study published by the Indian Council of Medical Research in 2023, around 10.1 crore of the country’s population has diabetes. This high prevalence of diabetes is anticipated to increase the demand for advanced drug delivery solutions such as on-body injectors in the country, thereby driving the market growth.
Latin America On-body Injectors Market Trends
The on-body injectors market in Latin American is fueled by the increasing number of patients on self-health management, decreasing the burden on healthcare facilities, and growing awareness about the advantages of advanced medical devices for better health outcomes. Moreover, the countries in the region, such as Brazil and Argentina, are witnessing a rise in chronic diseases, which is further anticipated to contribute to market growth.
Saudi Arabia on-body injectors market is anticipated to expand in the forecast period. The growing geriatric population, which is highly susceptible to chronic diseases, is one of the major factors positively influencing the market growth in this country. For instance, according to the Saudi Arabian Monetary Agency (SAMA), the share of the Saudi Arabian population aged 60 years and above is expected to reach 25% of its total 40 million population in 2050. The country's increasing geriatric population base is expected to drive the market over the forecast period.
Key On-body Injectors Company Insights
The competitive scenario in the on-body injectors market is highly competitive, with key players such as West Pharmaceutical Services, Inc.; BD; Stevanato Group, Enable Injections and others. The major companies are undertaking various organic and inorganic strategies such as launches, partnerships, acquisitions, mergers, and regional expansion to serve their customers' unmet needs.
Key On-body Injectors Companies
The following key companies have been profiled for this study on the on-body injectors market.
-
West Pharmaceutical Services, Inc.
-
BD
-
Stevanato Group
-
Enable Injections
-
Nemera
-
Debiotech SA
-
AbbVie, Inc.
-
Coherus BioSciences, Inc.
-
Gerresheimer AG
-
E3D Elcam Drug Delivery Devices
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (AbbVie, Inc.,West Pharmaceutical Services, Inc.; BD; Stevanato Group; Enable Injections; Nemera)
- These companies focus on expanding partnerships with pharmaceutical and biotechnology firms, enhancing wearable drug delivery technologies, supporting biologics commercialization, and investing in large-scale manufacturing capabilities.
- They emphasize product reliability, regulatory compliance, connectivity features, and geographic expansion to strengthen their position in the on-body injectors market.
- Strategic collaborations for drug-device combination products and lifecycle management initiatives further support market growth.
- Established players benefit from strong brand recognition, extensive regulatory expertise, robust intellectual property portfolios, and long-standing relationships with pharmaceutical manufacturers.
- Their advanced engineering capabilities, global distribution networks, proven product performance, and large-scale production infrastructure enable successful commercialization of on-body injector platforms across multiple therapeutic areas, including oncology, autoimmune diseases, and cardiovascular disorders.
- Large organizations may experience slower innovation cycles due to complex organizational structures and lengthy regulatory processes.
- High investment requirements for research, development, and manufacturing can increase operational costs.
- Additionally, dependence on major pharmaceutical partnerships and increasing competition from emerging wearable drug delivery companies may create challenges in maintaining market leadership.
Emerging Players (Coherus BioSciences, Inc; Gerresheimer AG; E3D Elcam Drug Delivery Devices)
- Emerging companies focus on developing next-generation wearable injectors with improved usability, connectivity, miniaturization, and patient-centric designs.
- They prioritize innovation in large-volume drug delivery, digital health integration, and customized drug-device solutions through strategic collaborations with pharmaceutical companies and contract development partners.
- These companies gain competitive advantages through technological innovation, agile product development, and the ability to address specific unmet needs in biologic drug administration.
- Their flexible business models, specialized expertise, and focus on differentiated wearable injector platforms enable faster adaptation to evolving market demands and emerging therapeutic applications.
- Regulatory approval processes for drug-device combination products can be costly and time-consuming.
- Limited financial resources, smaller commercial footprints, and lower brand recognition compared with established competitors may restrict market penetration.
- They also face challenges in scaling manufacturing operations and securing long-term partnerships with major pharmaceutical companies.
Recent Developments
-
In February 2024, Coherus BioSciences, Inc. launched its UDENYCA ONBODY, a novel wearable injector for delivering pegfilgrastim, which reduces infection risk during chemotherapy. The device enhances patient convenience by minimizing hospital visits.
-
In October 2023, the U.S. FDA approved the Empaveli Injector, an on-body injector for the self-administration of pegcetacoplan. This device allows patients to administer their health irrespective of their location.
On-body Injectors Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 6.3 billion
Market size value in 2026
USD 7.3 billion
Revenue forecast in 2033
USD 17.3 billion
Growth rate
CAGR of 13.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Thailand; Brazil; Mexico, Argentina; South Africa; Saudi Arabia, UAE; Kuwait
Key companies profiled
West Pharmaceutical Services, Inc.; BD; Stevanato Group; Enable Injections; Nemera; Debiotech SA; AbbVie, Inc.; Coherus BioSciences, Inc; Gerresheimer AG; E3D Elcam Drug Delivery Devices
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global On-body Injectors Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global on-body injectors market report based on technology, application, end-use, and region:
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Spring-based
-
Motor-driven
-
Rotary Pump
-
Expanding Battery
-
Other
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Diabetes
-
Cardiovascular Disease
-
Autoimmune Disease
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Clinics
-
Home Care Settings
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The on-body injectors market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each on-body injectors segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
Spring-based
Revenue captured from on-body injectors that utilize mechanical spring-powered mechanisms to deliver medications subcutaneously. These devices provide controlled drug administration without requiring complex electronics and are widely used for biologics and chronic disease therapies. Revenue includes sales of spring-actuated wearable injector systems and associated components.
Motor-driven
Revenue generated from on-body injectors that employ electric motors to precisely control drug delivery rates and dosing schedules. These systems offer enhanced accuracy, programmable administration, and support for high-volume biologic therapies. Revenue includes motorized wearable injectors used across various therapeutic applications.
Rotary Pump
Revenue derived from on-body injectors incorporating rotary pump mechanisms for continuous and controlled medication delivery. These devices are designed to handle complex formulations and large-volume drug administration with high precision. Revenue includes wearable injector systems utilizing rotary pump technology and related accessories.
Expanding Battery
Revenue captured from wearable injectors that use battery expansion or electrochemical actuation mechanisms to facilitate drug delivery. These devices enable compact designs, controlled administration, and improved patient convenience. Revenue includes products utilizing expanding battery technology for subcutaneous drug delivery.
Others
Revenue generated from on-body injectors utilizing alternative delivery technologies, including osmotic, pneumatic, hydraulic, or emerging actuation mechanisms. This segment includes innovative wearable drug delivery platforms not classified under spring-based, motor-driven, rotary pump, or expanding battery categories.
Segment - Application
Revenue capture definition
Oncology
Revenue generated from on-body injectors used for administering oncology therapies, including biologics, monoclonal antibodies, supportive care drugs, and cancer treatment regimens. These devices facilitate convenient delivery of high-value cancer medications in both clinical and home-based settings.
Diabetes
Revenue captured from on-body injectors designed for diabetes management, including insulin and other injectable therapies. The segment includes wearable drug delivery systems that improve treatment adherence, dosing accuracy, and patient convenience for diabetic care.
Cardiovascular Disease
Revenue derived from on-body injectors used for administering therapies related to cardiovascular disorders, including lipid-lowering biologics, anticoagulants, and other chronic cardiovascular treatments. These devices support long-term disease management through convenient drug administration.
Autoimmune Disease
Revenue generated from wearable injectors used to deliver biologics and specialty therapies for autoimmune conditions such as rheumatoid arthritis, psoriasis, inflammatory bowel disease, and multiple sclerosis. The segment benefits from increasing biologic adoption and home-based treatment trends.
Others
Revenue captured from on-body injectors utilized in additional therapeutic areas, including rare diseases, infectious diseases, hormonal disorders, pain management, and other specialty applications requiring subcutaneous drug delivery.
Segment - End-use
Revenue capture definition
Hospitals & Clinics
Revenue generated from on-body injectors purchased and utilized by hospitals, specialty clinics, infusion centers, and healthcare facilities. These settings use wearable injectors for initiating treatment, monitoring therapy, and administering specialty medications under professional supervision.
Home Care Settings
Revenue captured from on-body injectors used in home healthcare environments, allowing patients to self-administer or receive caregiver-assisted treatment outside traditional healthcare facilities. This segment is driven by the growing shift toward patient-centric and home-based care models.
Others
Revenue derived from on-body injector utilization in alternative settings such as ambulatory surgical centers, research institutions, long-term care facilities, specialty pharmacies, and community healthcare centers. This category encompasses end users beyond hospitals, clinics, and home care environments.
Estimation Model
Scope Definition
Build the Product Base
Estimate Penetration
Revenue Conversion
What is being sized?
How large is total addressable market?
What portion transitions to Smart Connected Pens?
How does volume become revenue?
PROCESS STEPS
1. Triangulate data from pharmaceutical manufacturers, device developers, healthcare providers, and regulatory agencies.
2. Scope Product & Interoperability Specifications.
3. Set Geographic Boundaries.
4. Align on base year & forecast horizon (2026-2033).PROCESS STEPS
1. Gather patient population data.
2. Estimate annual treatment volumes and biologic utilization rates by indication.
3. Apply patient eligibility, treatment adherence, and utilization assumptions.
4. Forecast demand based on chronic disease prevalence, biologics pipeline growth, and self-administration trends.PROCESS STEPS
1. Evaluate treatment settings and identify therapies suitable for wearable subcutaneous drug delivery.
2. Map current and projected adoption rates of on-body injectors versus conventional delivery methods.
3. Analyze penetration across hospitals, clinics, and home care settings.
4. Validate estimates using manufacturer shipments, product approvals, and healthcare utilization data.PROCESS STEPS
1. Collect average selling price (ASP) data for on-body injectors and drug-device combination products.
2. Segment by Revenue Streams.
3. Apply regional pricing differences and reimbursement considerations.
4. Cross-Check with Trade Data.Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technological Advancements in On-body Injectors
Conducted a comprehensive assessment of technological innovations in the on-body injectors market, focusing on wearable drug delivery systems, large-volume subcutaneous administration, connectivity-enabled injectors, automated dosing technologies, smart sensors, and patient-centric device designs. The study evaluated advancements in biologic drug delivery, digital health integration, remote monitoring capabilities, battery-powered and mechanical actuation technologies, and emerging trends in home-based treatment solutions. Regulatory approvals, product launches, clinical developments, and strategic collaborations between pharmaceutical and device manufacturers were also analyzed.
This analysis enables stakeholders to understand evolving wearable drug delivery technologies and identify innovation-driven growth opportunities. It supports strategic product development, partnership evaluation, and commercialization planning while highlighting how technological advancements are improving patient adherence, treatment convenience, and healthcare efficiency across chronic disease management applications.
Competitive Landscape and Product Benchmarking Analysis
Conducted an in-depth competitive assessment of leading on-body injector manufacturers based on product portfolios, technology platforms, regulatory approvals, geographic presence, manufacturing capabilities, and strategic partnerships. The research evaluated differentiation factors such as dosing accuracy, device usability, connectivity features, biologic compatibility, patient comfort, reliability, and commercialization strategies. Market positioning, mergers and acquisitions, product launches, and pipeline developments undertaken by key industry participants were also examined.
This assessment helps stakeholders benchmark competitive positioning, identify market gaps, and understand strategic approaches adopted by leading companies. The analysis supports investment decisions, partnership opportunities, product differentiation strategies, and technology selection while providing insights into evolving competitive dynamics and market entry barriers.
Geographical Expansion Analysis - China and Germany Injection Pen Market
Conducted a detailed regional market assessment of the on-body injectors industry across major healthcare markets. The study examined key growth drivers, biologics adoption rates, chronic disease prevalence, reimbursement frameworks, healthcare infrastructure development, regulatory environments, and home healthcare adoption trends. Country-level opportunities, market penetration strategies, and pharmaceutical-device ecosystem developments were also analyzed.
This geographical analysis enables stakeholders to identify high-growth regional opportunities and optimize expansion strategies. The study highlights differences in biologic therapy adoption, healthcare spending, regulatory pathways, and patient preferences, supporting informed investment decisions and strengthening long-term market growth strategies across global markets.
Frequently Asked Questions About This Report
The global on-body injectors market was estimated at USD 4.8 billion in 2023 and is expected to reach USD 5.5 billion in 2024.
The global on-body injectors market is expected to grow at a compound annual growth rate of 14.9% from 2024 to 2030 to reach USD 12.70 billion by 2030.
North America dominated the won-body injectors market with a share of 33.2% in 2023. This is attributable to the rising prevalence of chronic & lifestyle-related diseases and the presence of sophisticated healthcare infrastructure.
Some key players operating in the on-body injectors market include West Pharmaceutical Services, Inc.; BD; Stevanato Group, Enable Injections and others.
Key factors that are driving the on-body injectors market growth include rising demand for round-the-clock monitoring, Increasing concern over the hazards related to needlestick injuries, and technological developments in wearable injectors.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


