
- Home
- »
- Clinical Diagnostics
- »
-
Pancreatic Cancer Diagnostic Market Size, Growth Report, 2026-2033GVR Report cover

Pancreatic Cancer Diagnostic Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, Test Type (Imaging Test, Biopsy, Blood Test), By Cancer Type (Exocrine, Endocrine), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.8BMarket Estimate, 2026
$2.9BMarket Forecast, 2033
$5.1BCAGR, 2026–2033
6.8%Pancreatic Cancer Diagnostic Market Summary
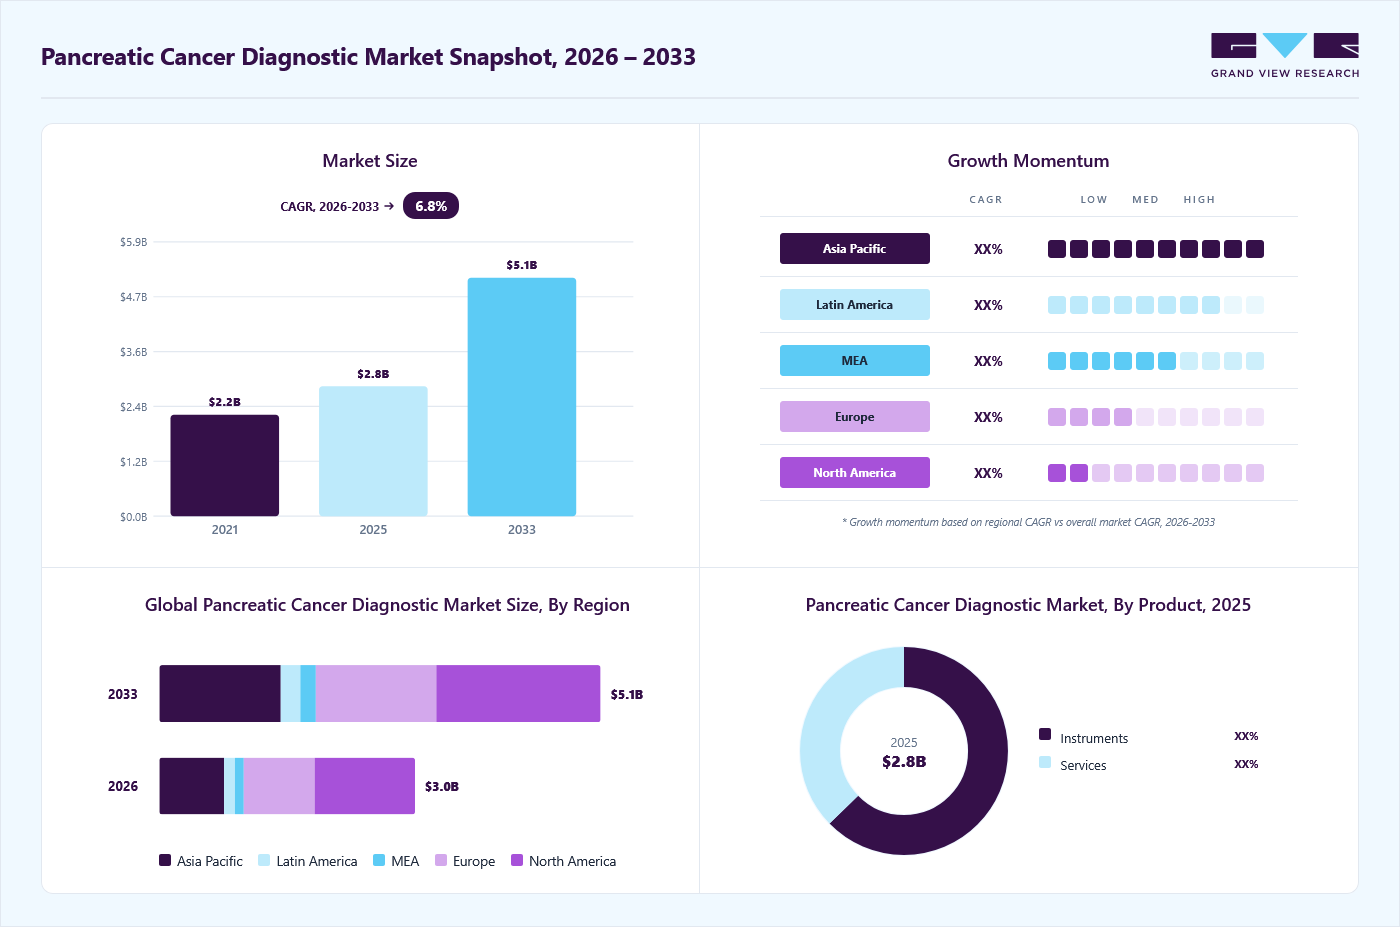
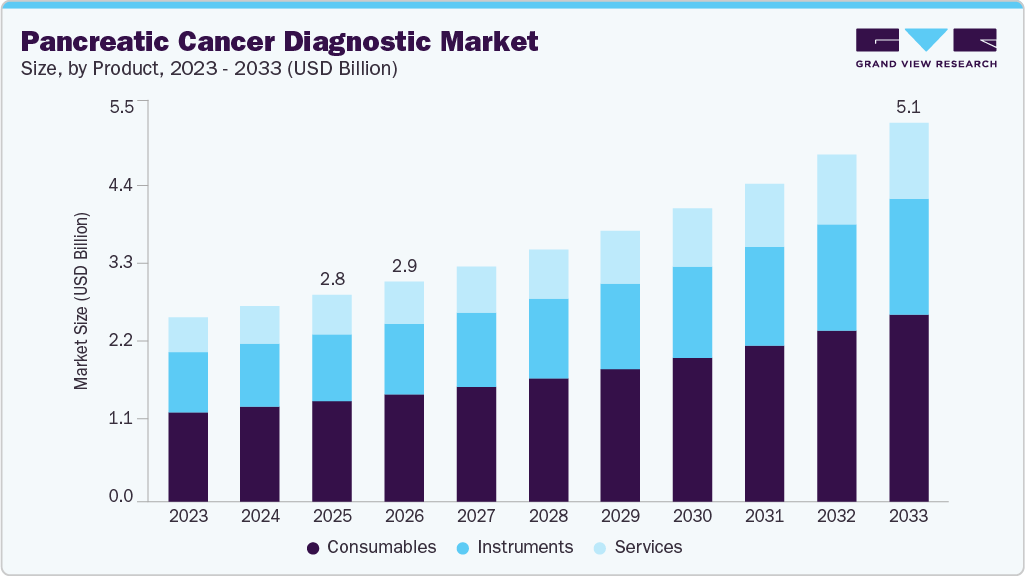
The global pancreatic cancer diagnostic market size was valued at USD 2.8 billion in 2025 and is projected to grow from USD 2.9 billion in 2026 to USD 5.1 billion by 2033, at a CAGR of 6.8% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 39.5% in 2025. The increasing prevalence of pancreatic cancer, the growing emphasis on early detection, and advancements in molecular diagnostics and imaging technologies are the key drivers of the global market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Consumables segment accounted for the largest market revenue share in 2025.
- By test type: Imaging segment accounted for the largest market revenue share in 2025.
- By cancer type: Exocrine segment accounted for the largest market revenue share in 2025.
Regional Highlights
- Largest regional market: North America (39.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. pancreatic cancer diagnostic industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 2.8 Billion
- Estimated market size in 2026: USD 2.9 Billion
- Projected market size by 2033: USD 5.1 Billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, the rising adoption of liquid biopsy and AI-assisted imaging, coupled with expanding healthcare infrastructure and oncology screening programs in emerging economies, is further supporting market growth. Pancreatic cancer is one of the leading causes of cancer-related death across the globe, and the burden of disease is escalating at a significant pace, driven by late-stage diagnosis and limited early detection options. According to the American Cancer Society’s Cancer Facts & Figures, published in January 2026, the five-year relative survival rate remains approximately 13%, underscoring the persistently poor prognosis of the disease. In 2026 alone, an estimated 67,530 new cases and 52,740 deaths are projected in the United States, making pancreatic cancer the third leading cause of cancer-related mortality despite accounting for only about 3% of all cancer diagnoses.Notably, incidence has been increasing by nearly 1% annually since the 1990s. Only about 17% of patients are diagnosed at a localized stage, where the five-year survival rate is about 44%, whereas most cases are detected at advanced stages, with significantly lower survival. These trends highlight the urgent need for improved early detection and advanced diagnostic solutions.
 To learn more about this report, Download Free Sample Report
Moreover, early disease diagnosis is critical to improving treatment outcomes. Consequently, market participants and healthcare organizations are increasingly investing in funding initiatives, awareness campaigns, and research programs to encourage routine checkups and screening practices. These strategic efforts are focused on enhancing early-stage detection rates, which remain comparatively low, and improving overall patient survival. Such initiatives are expected to support the advancement of diagnostic capabilities and drive growth in the pancreatic cancer diagnostics industry.
For instance, in November 2025, the Pancreatic Cancer Action Network announced new research grant investments to support scientists across multiple institutions in advancing early detection, addressing therapeutic resistance, and improving treatment outcomes for pancreatic cancer. These funding initiatives are specifically designed to bridge critical research gaps and accelerate innovation in diagnostic and therapeutic approaches.
The significant rise in the number of pancreatic malignancy cases is driving the adoption of screening tests and generating strong demand for novel diagnostic solutions. Currently, diagnostic modalities such as biomarker assays, liver function tests, biopsies, and advanced imaging technologies are widely utilized for disease detection. Moreover, the growing demand for advanced diagnostic solutions is prompting manufacturers to develop innovative, high-precision testing technologies. For instance, in March 2026, researchers supported by the National Institutes of Health developed a novel blood-based test combining multiple protein biomarkers that demonstrated over 90% accuracy in detecting pancreatic cancer, including early-stage cases, highlighting significant progress toward non-invasive early-detection solutions.
Moreover, the growing number of programs promoting screening for malignant tumors is driving worldwide demand for pancreatic cancer diagnostic products. Partnerships among organizations such as the World Health Organization, Centers for Disease Control and Prevention, and the Pancreatic Cancer Action Network are expected to support market growth by advancing awareness and diagnosis. In addition, multiple initiatives are encouraging early screening, risk assessment, and biomarker-based detection of pancreatic malignancies.
For instance, in October 2025, Pancreatic Cancer Action Network launched its Shine a Light campaign to raise awareness of early symptoms, risk factors, and the importance of timely diagnosis. Furthermore, global initiatives such as World Pancreatic Cancer Day 2025, which the World Pancreatic Cancer Coalition celebrated to mark 10 years of driving global awareness, have significantly increased awareness of symptoms, genetic testing, and diagnostic pathways, thereby accelerating the adoption of pancreatic cancer diagnostic technologies worldwide.
Advancements in molecular diagnostics are creating significant growth opportunities in the pancreatic cancer diagnostics industry. Molecular diagnostic tests enable the identification of specific genetic mutations and biomarkers associated with pancreatic malignancies, facilitating earlier diagnosis and more targeted treatment approaches. For example, liquid biopsy-based tests that detect circulating tumor DNA (ctDNA) are increasingly being developed and validated to support early-stage detection of pancreatic cancer.
Moreover, the integration of artificial intelligence (AI) in imaging, pathology, and biomarker-based testing is expected to enhance early diagnostic accuracy and efficiency. Recent studies published in September 2024 in leading gastroenterology and oncology journals highlight that AI-assisted endoscopic ultrasound and biomarker analysis demonstrate improved sensitivity in detecting early pancreatic lesions compared to conventional diagnostic methods, thereby supporting increased adoption of advanced diagnostic technologies.
Market Concentration & Characteristics
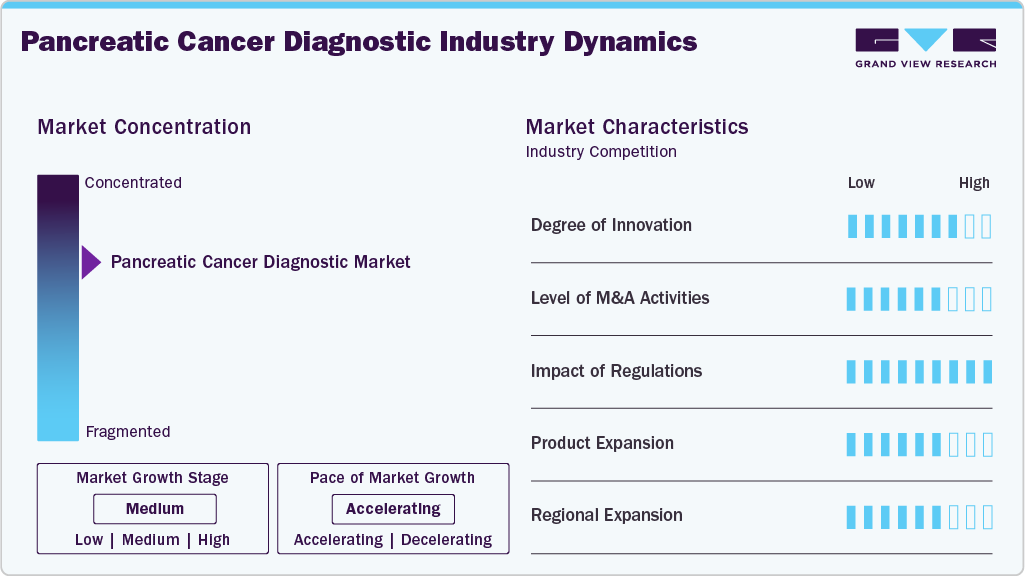
The pancreatic cancer diagnostics industry exhibits a moderate to high degree of innovation, driven by advancements in molecular diagnostics, biomarker discovery, and artificial intelligence (AI). Conventional methods, such as imaging and biopsies, remain widely used, while emerging technologies, such as liquid biopsy and circulating tumor DNA (ctDNA) analysis, are enabling earlier, non-invasive detection. AI integration in imaging and pathology is further enhancing diagnostic accuracy and efficiency. In addition, ongoing research in multi-omics and biomarker-based tests is expanding diagnostic capabilities. However, adoption remains gradual due to high costs, regulatory challenges, and the need for extensive clinical validation, indicating strong future innovation potential.
The pancreatic cancer diagnostics industry is witnessing moderate yet steadily increasing M&A activity, driven by the growing need to strengthen molecular diagnostics capabilities, expand biomarker portfolios, and accelerate the development of early-detection technologies. Strategic acquisitions are enabling companies to enhance their technological expertise, broaden product pipelines, and gain a competitive edge in the evolving diagnostics landscape. For instance, in November 2025, Abbott Laboratories announced the acquisition of Exact Sciences to reinforce its oncology screening portfolio. This acquisition is focused on leveraging the CancerGuard multi-cancer early detection test, a blood-based diagnostic platform capable of detecting over 50 cancer types, including pancreatic cancer, thereby strengthening Abbott’s position in non-invasive and early-stage cancer diagnostics.
 To learn more about this report, Download Free Sample Report
Global regulatory frameworks have a high impact on the pancreatic cancer diagnostics industry, shaping product development, approval timelines, and commercialization strategies. Stringent regulatory frameworks enforced by authorities such as the U.S. Food and Drug Administration and the European Medicines Agency require extensive clinical validation to ensure the safety, accuracy, and reliability of diagnostic tests, particularly for novel technologies such as liquid biopsy and AI-based solutions. While these regulations enhance product quality and patient safety, they often result in longer approval timelines and higher development costs. In addition, evolving guidelines for laboratory-developed tests (LDTs) and multi-cancer early detection (MCED) assays are increasing compliance requirements.
The pancreatic cancer diagnostics industry is witnessing strategic expansion as companies increasingly focus on entering new geographic markets and strengthening their global footprint. Key players are targeting emerging regions such as the Asia Pacific, Latin America, and the Middle East & Africa through partnerships, local manufacturing, and distribution agreements to improve accessibility and affordability of diagnostic solutions. In addition, companies are collaborating with regional laboratories and healthcare providers to expand their customer base and increase test adoption. Market participants are also investing in regulatory approvals and localization strategies to accelerate product commercialization in untapped markets. This expansion approach is enabling companies to diversify revenue streams, reduce dependence on mature markets, and capitalize on the growing global demand for early cancer diagnostics.
Product Insights
The consumables segment led the market with the largest revenue share of 48.65% in 2025. The rising adoption of consumables in diagnostic procedures, Increased R&D investments, and the growing launch of technologically advanced diagnostic kits and reagents are anticipated to support segment expansion. In addition, the rising need for accurate, early detection, coupled with the high cost and recurring use of specialized reagents, is further driving sustained demand and revenue growth in the consumables segment. For instance, in August 2024, Immunovia reported enhanced performance of its next-generation pancreatic cancer detection test, demonstrating approximately 85% sensitivity and 98% specificity for early-stage disease detection. The test uses advanced antibody-based biomarker analysis, underscoring the growing demand for high-performance reagents and diagnostic kits for pancreatic cancer detection.
The services segment is expected to witness at the fastest CAGR during the forecast period, driven by increasing research into advanced diagnostic methods and the integration of AI and computer-aided detection tools into imaging. In addition, ongoing efforts by healthcare organizations to improve early detection and survival rates are further supporting segment expansion. For instance, in March 2026, the Duke Cancer Institute launched a multidisciplinary pancreatic cancer center focused on early detection, high-risk patient surveillance, and integrated care delivery to improve clinical outcomes. The center combines advanced diagnostics, clinical trials, and coordinated care services, highlighting the growing role of specialized service-based models in improving pancreatic cancer diagnosis and survival.
Test Type Insights
The imaging test segment led the market with the largest revenue share of 57.03% in 2025. The growth of the segment is driven by ongoing technological advancements and their critical role in early detection and disease staging. The segment remains driven by the widespread use of computed tomography (CT), magnetic resonance imaging (MRI), endoscopic ultrasound (EUS), and positron emission tomography (PET) scans. Developments, particularly the integration of artificial intelligence (AI) and radiomics, are significantly enhancing diagnostic accuracy and early tumor detection.
Moreover, these techniques are preferred by health professionals owing to their higher accuracy in malignancy detection and their non-invasive nature. In addition, advancements in imaging technologies, such as the development of contrast agents and 3D imaging, and the application of artificial intelligence to imaging, are further improving the accuracy & efficiency of pancreatic cancer diagnosis.
For instance, in 2025, an international research team developed AI-assisted endoscopic ultrasound (EUS) models capable of real-time detection and segmentation of pancreatic lesions, significantly improving diagnostic accuracy compared to conventional methods. In addition, recent studies highlight that integrating AI with multimodal imaging techniques such as CT, MRI, and EUS can achieve diagnostic accuracy exceeding 90% for early-stage pancreatic cancer detection, reinforcing the growing adoption of advanced imaging technologies.
The blood test segment is expected to grow at the fastest CAGR during the forecast period, driven by rising demand for early, non-invasive pancreatic cancer detection and ongoing technological advancements. Biomarkers such as CA 19-9 and carcinoembryonic antigen (CEA) remain widely used for diagnosis and monitoring. In addition, increasing adoption of liquid biopsy, genetic testing, and multi-omics approaches is enhancing diagnostic accuracy. The emergence of advanced blood-based assays is further supporting early-stage detection and expanding market growth.
Cancer Type Insights
The exocrine segment accounted for the largest market revenue share in 2025. The exocrine segment continues to dominate the pancreatic cancer diagnostics market, accounting for a significant share of revenue due to the high prevalence of exocrine malignancies. Factors such as increasing awareness, advancements in diagnostic technologies, and the need for early detection are supporting segment growth. According to Johns Hopkins University, exocrine cancers represent over 95% of pancreatic cancer cases, with pancreatic ductal adenocarcinoma accounting for nearly 90% of diagnoses. The high incidence of adenocarcinoma significantly drives diagnostic demand, thereby reinforcing the segment’s leading market position.
The endocrine segment is anticipated to grow at the fastest CAGR during the forecast period. Endocrine malignancies are less common than exocrine types and account for 8% of all pancreatic tumors . However, changes in lifestyle, inherited gene mutations, and the presence of comorbidities are expected to increase disease prevalence and drive segment growth.
End Use Insights
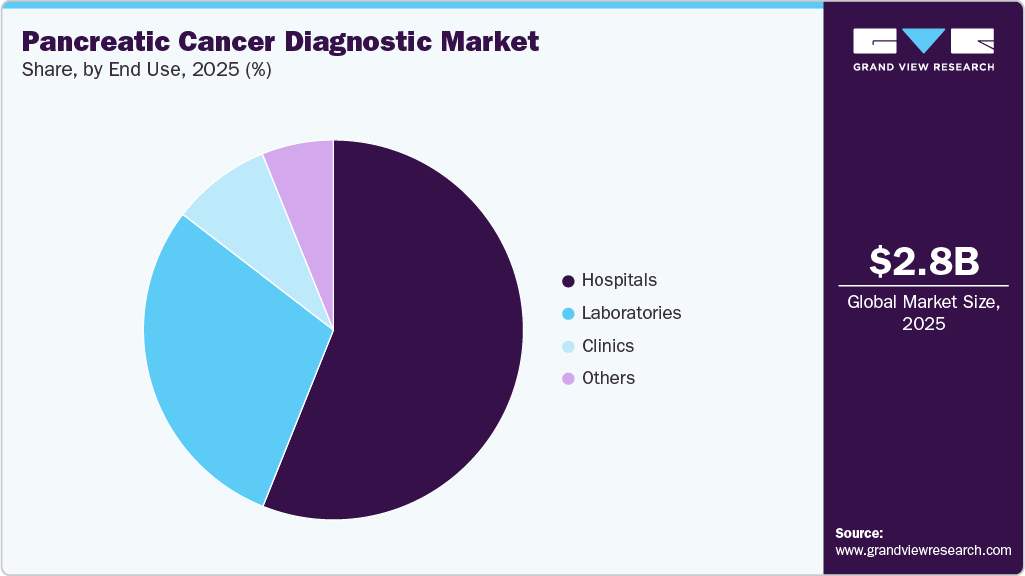
The hospitals segment led the market with the largest revenue share of 56.06% in 2025, driven by increasing patient inflow, expanding access to advanced diagnostic technologies, and rising focus on personalized medicine. The segment benefits from integrated care settings that enable early diagnosis, imaging, and biomarker testing under one roof. Strategic collaborations and expansion of oncology-focused hospital networks are further supporting growth. For instance, in 2026, Mayo Clinic expanded its precision oncology program, integrating advanced molecular diagnostics and AI-supported imaging for pancreatic cancer detection, thereby strengthening hospital-based diagnostic capabilities and improving patient outcom s.
 To learn more about this report, Download Free Sample Report
The laboratories segment is expected to witness at the fastest CAGR during the forecast period, driven by the rising disease burden and increasing demand for accurate diagnostic testing. High test volumes, advanced laboratory infrastructure, and adoption of molecular and genetic testing are supporting segment expansion. In addition, favorable reimbursement policies are enhancing accessibility to diagnostic services. For instance, according to the American Society of Clinical Oncology, a significant portion of genetic testing costs is covered by health insurance plans, encouraging wider adoption of laboratory-based diagnostics.
Regional Insights
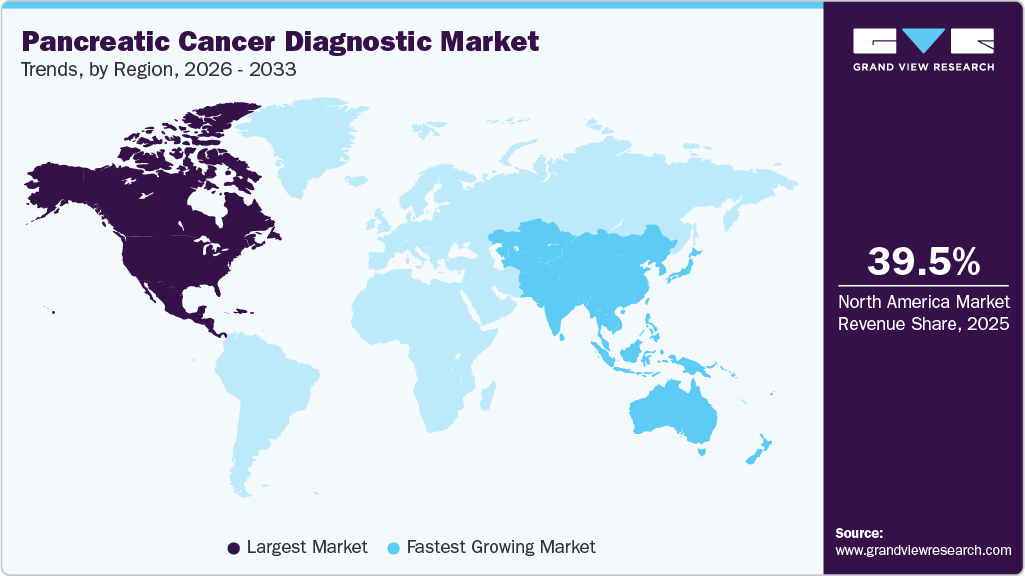
North America dominated the global pancreatic cancer diagnostic market with the largest revenue share of 39.5% in 2025. The regional growth is driven by a high disease burden, strong healthcare infrastructure, and early adoption of advanced diagnostic technologies. The region benefits from widespread availability of molecular diagnostics, liquid biopsy platforms, and AI-enabled imaging solutions.
 To learn more about this report, Download Free Sample Report
Favorable reimbursement policies and strong support from regulatory bodies such as the U.S. Food and Drug Administration further facilitate market growth. In addition, increasing investments in oncology research and growing participation in clinical trials are accelerating the development of innovative diagnostic tools. The presence of leading diagnostic companies and biotechnology firms, along with strong collaboration between academic institutions and industry players, continues to support technological advancements and the commercialization of early detection solutions across the region.
U.S. Pancreatic Cancer Diagnostic Market Trends
The pancreatic cancer diagnostic market in the U.S. accounted for the largest market revenue share in North America in 2025, attributed to high incidence rates of pancreatic cancer and significant healthcare spending. The country is characterized by the rapid adoption of advanced diagnostics, including biomarker-based assays, genetic testing, and liquid biopsy solutions. Support from organizations such as the National Cancer Institute and extensive funding for cancer research are driving innovation in early detection technologies. In addition, increasing awareness initiatives and patient advocacy programs are promoting early diagnosis. The U.S. also leads in clinical research and commercialization of multi-cancer early detection (MCED) tests, supported by a robust regulatory framework and strong presence of leading diagnostic and biotechnology companies.
Europe Pancreatic Cancer Diagnostic Market Trends
The pancreatic cancer diagnostic market in Europe holds a significant share, supported by well-established healthcare systems and increasing focus on early cancer detection. The region is witnessing growing adoption of molecular diagnostics and biomarker-based testing, particularly in Western European countries. Regulatory oversight from the European Medicines Agency and implementation of the In Vitro Diagnostic Regulation (IVDR) are shaping the market landscape by ensuring quality and safety standards. In addition, government-funded screening programs and rising investments in oncology research are contributing to market growth. Collaborative research initiatives across the European Union are further supporting innovation in diagnostic technologies, while increasing awareness about early diagnosis is driving demand for advanced testing solutions.
The UK pancreatic cancer diagnostic market is driven by a strong public healthcare infrastructure and increasing government focus on early cancer detection. The National Health Service plays a critical role in expanding access to diagnostic services and implementing early diagnosis strategies. National cancer plans emphasize timely detection and integration of advanced diagnostic technologies, including imaging and molecular testing. In addition, research initiatives supported by academic institutions and cancer charities are fostering innovation in biomarker discovery and early screening methods. Growing awareness campaigns and improved referral pathways are further enhancing early diagnosis rates, thereby supporting the adoption of pancreatic cancer diagnostic solutions across the country.
The pancreatic cancer diagnostic market in Germany represents a key market in Europe, supported by advanced healthcare infrastructure and high adoption of innovative diagnostic technologies. The country has a strong focus on precision medicine and molecular diagnostics, which is driving the use of biomarker-based tests for pancreatic cancer detection. Favorable reimbursement policies and well-established laboratory networks are facilitating access to advanced diagnostic services. In addition, Germany’s emphasis on research and development, supported by collaborations between academic institutions and diagnostic companies, is accelerating innovation. The presence of leading medical technology firms and increasing demand for early detection solutions are further contributing to the market growth in the country.
Asia Pacific Pancreatic Cancer Diagnostic Market Trends
The pancreatic cancer diagnostic market in the Asia Pacific is expected to witness at the fastest CAGR during the forecast period, driven by a large patient population, rising cancer incidence, and improving healthcare infrastructure. Increasing healthcare expenditure and government initiatives to enhance cancer screening programs are supporting market expansion. Countries across the region are adopting advanced diagnostic technologies, including molecular testing and imaging solutions, to improve early detection rates. In addition, growing awareness about cancer diagnosis and increasing investments by global and regional players are accelerating market growth. The expansion of private healthcare facilities and diagnostic laboratories is further improving access to advanced testing solutions across emerging economies.
The Japan pancreatic cancer diagnostic market is characterized by advanced healthcare infrastructure and high adoption of innovative diagnostic technologies. The country places strong emphasis on early detection and precision medicine, supported by government initiatives and research programs. Advanced imaging techniques and biomarker-based diagnostics are widely utilized in clinical practice. In addition, Japan’s aging population contributes to a higher incidence of pancreatic cancer, driving demand for diagnostic services. Strong collaboration between research institutions and healthcare providers is fostering innovation in early detection technologies, while favorable reimbursement policies support the adoption of advanced diagnostic solutions.
The pancreatic cancer diagnostic market in China is emerging as a high-growth, driven by a rapidly increasing cancer burden and ongoing healthcare reforms. Government initiatives to improve cancer screening and early detection are supporting market development. Investments in healthcare infrastructure and the expansion of diagnostic laboratories are enhancing access to advanced testing solutions. In addition, the country is witnessing increased adoption of molecular diagnostics and AI-based technologies in oncology. Growing participation of domestic and international companies in the Chinese diagnostics market is further accelerating innovation and commercialization of advanced pancreatic cancer diagnostic tools.
Latin America Pancreatic Cancer Diagnostic Market Trends
The pancreatic cancer diagnostic market in Latin America is experiencing lucrative growth, supported by improving healthcare infrastructure and increasing awareness of cancer diagnosis. Countries such as Brazil and Mexico are witnessing rising adoption of advanced diagnostic technologies, including imaging and biomarker-based tests. Government initiatives to strengthen cancer care and expand access to diagnostic services are driving market growth. However, challenges such as limited access to advanced technologies in rural areas and budget constraints continue to impact market expansion. Despite these challenges, increasing investments in healthcare and growing awareness are expected to drive demand for pancreatic cancer diagnostics in the region.
Middle East & Africa Pancreatic Cancer Diagnostic Market Trends
The pancreatic cancer diagnostic market in the Middle East & Africa is witnessing steady growth, driven by improving healthcare infrastructure and rising awareness about early cancer detection. Governments in the region are increasingly investing in healthcare development and cancer care programs, which are supporting the adoption of diagnostic technologies. The expansion of private healthcare providers and diagnostic centers is enhancing access to advanced testing solutions. However, limited access to specialized diagnostic facilities and a lack of awareness in certain areas remain key challenges. Despite this, ongoing healthcare reforms and increasing focus on early diagnosis are expected to create growth opportunities in the regional market.
Key Pancreatic Cancer Diagnostic Company Insights
Key players in the pancreatic cancer diagnostic industry are increasingly adopting strategies such as new product development, mergers and acquisitions, and strategic partnerships to strengthen their market position and expand global presence. Leading companies, including Illumina, Agilent Technologies, F. Hoffmann-La Roche, Thermo Fisher Scientific, and QIAGEN, continue to dominate the market through continuous investments in molecular diagnostics and precision medicine. These players are focusing on developing advanced solutions such as liquid biopsy, next-generation sequencing (NGS), and AI-enabled diagnostics to address the growing demand for early and accurate detection. In addition, ongoing portfolio expansion and technological innovation are enabling companies to maintain a competitive edge in the evolving global diagnostics landscape.
Key Pancreatic Cancer Diagnostic Companies:
The following key companies have been profiled for this study on the pancreatic cancer diagnostic market.
- Thermo Fisher Scientific, Inc.
- QIAGEN
- Illumina, Inc.
- F. Hoffmann-La Roche Ltd.
- BD
- Agilent Technologies, Inc.
- Myriad Genetics, Inc
- Koninklijke Philips N.V.
- Abbott
- Hitachi, Ltd
- Danaher
- Prestige Biopharma Ltd
- BioMarker Strategies
- ASURAGEN, INC
Recent Developments
-
In February 2026, ClearNote Health launched an enhanced version of its Avantect Pancreatic Cancer Test, a blood-based diagnostic solution demonstrating 82.6% sensitivity and 97.5% specificity. The test leverages a multiomic approach combined with machine learning algorithms to enable accurate and early detection of pancreatic cancer.
-
In February 2026, the U.S. Food and Drug Administration approved Optune Pax, a non-invasive device developed by Novocure, for the treatment of locally advanced pancreatic cancer. The device utilizes Tumor Treating Fields (TTFields), a novel technology that delivers electric fields to disrupt cancer cell division, highlighting advancements in innovative and non-invasive therapeutic approaches for pancreatic cancer management.
-
In March 2026, researchers at Konkuk University developed a rapid diagnostic test kit capable of detecting pancreatic cancer within 15 minutes using a single drop of blood, demonstrating advancements in point-of-care diagnostic consumables.
-
In November 2025, Azenta collaborated with the PRECEDE Consortium, a global initiative focused on early detection and prevention of pancreatic cancer. This partnership aims to advance biomarker research, genetic testing, and data-driven approaches to identify high-risk individuals, thereby supporting the development of innovative diagnostic strategies and improving early detection outcomes .
-
In November 2025, F. Hoffmann-La Roche entered into a strategic agreement with Freenome to commercialize blood-based multi-cancer early detection tests in international markets. The deal includes over USD 200 million in potential value and focuses on multi-omics and cfDNA-based diagnostics, which are highly relevant for early detection of pancreatic cancer.
Pancreatic Cancer Diagnostic Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.8 billion
Estimated Market size in 2026
USD 2.9 billion
Projected Market size by 2033
USD 5.1 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2021 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, test type, cancer type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; India; China; Japan; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; UAE; South Africa; Kuwait
Key companies profiled
Thermo Fisher Scientific, Inc.; QIAGEN; Illumina, Inc.; F. Hoffmann-La Roche Ltd.; Agilent Technologies, Inc.; Abbott; BD; Myriad Genetics, Inc.; Koninklijke Philips N.V.; Hitachi, Ltd; Danaher; Prestige Biopharma Ltd; BioMarker Strategies; ASURAGEN, INC
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pancreatic Cancer Diagnostic Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global pancreatic cancer diagnostic market report based on the product, test type, cancer type, end use, and regions.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Consumables
-
Services
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Imaging Test
-
CT Scan
-
MRI
-
Ultrasound
-
PET
-
Others
-
-
Biopsy
-
Blood Test
-
Liver Function Tests
-
Tumor Markers
-
Others
-
-
Others
-
-
Cancer Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Exocrine
-
Adenocarcinoma
-
Squamous Cell Carcinoma
-
Adenosquamous Carcinoma
-
Colloid Carcinoma
-
-
Endocrine
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
Increasing prevalence of pancreatic cancer, rise in awareness for early disease diagnosis, and advancements in molecular diagnostics are the major factors driving the pancreatic cancer diagnostic market growth over the forecast period.
The global pancreatic cancer diagnostic market size was valued at USD 2.8 billion in 2025 and is estimated at USD 2.9 billion for 2026.
The global pancreatic cancer diagnostic market is expected to grow at a CAGR of 6.8% from 2026 to 2033, reaching USD 5.1 billion by 2033.
The consumables segment is expected to dominate the pancreatic cancer diagnostic market with a share of 48.7% in 2025 due to the increasing adoption of novel tests, increased R&D investments, and rising launch of technologically advanced diagnostic kits and reagents.
Key players include Thermo Fisher Scientific, Inc.; QIAGEN; Illumina, Inc.; F. Hoffmann-La Roche Ltd.; Agilent Technologies, Inc.; Abbott; BD; Myriad Genetics, Inc.; Koninklijke Philips N.V.; Hitachi, Ltd; Danaher; Prestige Biopharma Ltd; BioMarker Strategies; ASURAGEN, INC.
North America held the largest share of 39.5% in 2025 and is expected to register a lucrative growth rate over the forecast period. It is attributable to the increasing incidence of disease, presence of leading market players, and rising initiatives from profit and non-profit organizations to promote early disease diagnosis.
Asia Pacific is the fastest-growing region over the forecast period.
The imaging test segment led with a 57.0% revenue share in 2025, while the blood test segment is the fastest-growing.
The exocrine segment held the largest revenue share in 2025, while endocrine is the fastest-growing type.
Hospitals segment held the largest share (over 56.0%) in 2025, while laboratories is the fastest-growing segment.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


