
- Home
- »
- Animal Health
- »
-
Pet Diabetes Care Market Size & Share Report, 2026-2033GVR Report cover

Pet Diabetes Care Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal (Dogs, Cats), By Solution (Treatment, Glucose Monitoring Devices), By Distribution Channel (Veterinary Hospitals & Clinics, Retail Pharmacies, E-commerce), By Region, And Segment Forecasts
Market Size, 2025
$2.3BMarket Estimate, 2026
$2.5BMarket Forecast, 2033
$4.6BCAGR, 2026–2033
9.4%Pet Diabetes Care Market Summary
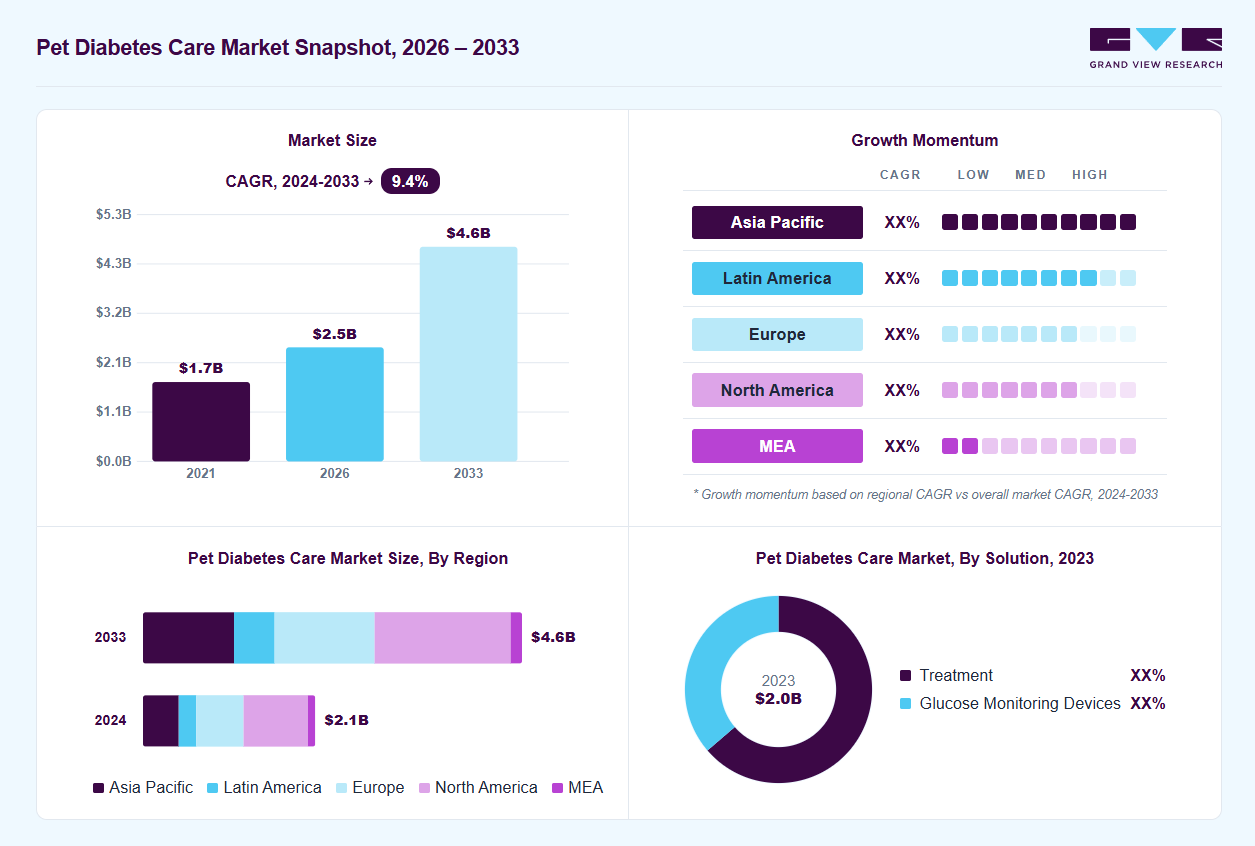
The global pet diabetes care market size was valued at USD 2.3 billion in 2025 and is projected to grow from USD 2.5 billion in 2026 to USD 4.6 billion by 2033, at a CAGR of 9.4% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 37.2% in 2025. The pet diabetes care industry’s growth is driven by the rising prevalence of diabetes among companion animals, particularly aging and obese pets.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal: Dogs segment held the largest share of 53.2% in 2025
- By solution: Treatment segment held the largest market share in 2025
- By distribution channel: Veterinary hospitals & clinics held the largest market share in 2025
Regional Highlights
- Largest regional market: North America (37.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest revenue share in 2025
Market Size & Forecast
- Market Size in 2025: USD 2.3 Billion
- Estimated Market Size in 2026: USD 2.5 Billion
- Projected Market Size by 2033: USD 4.6 Billion
- CAGR (2026-2033): 9.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing pet ownership and increasing adoption rates are expanding the population requiring long-term diabetes management.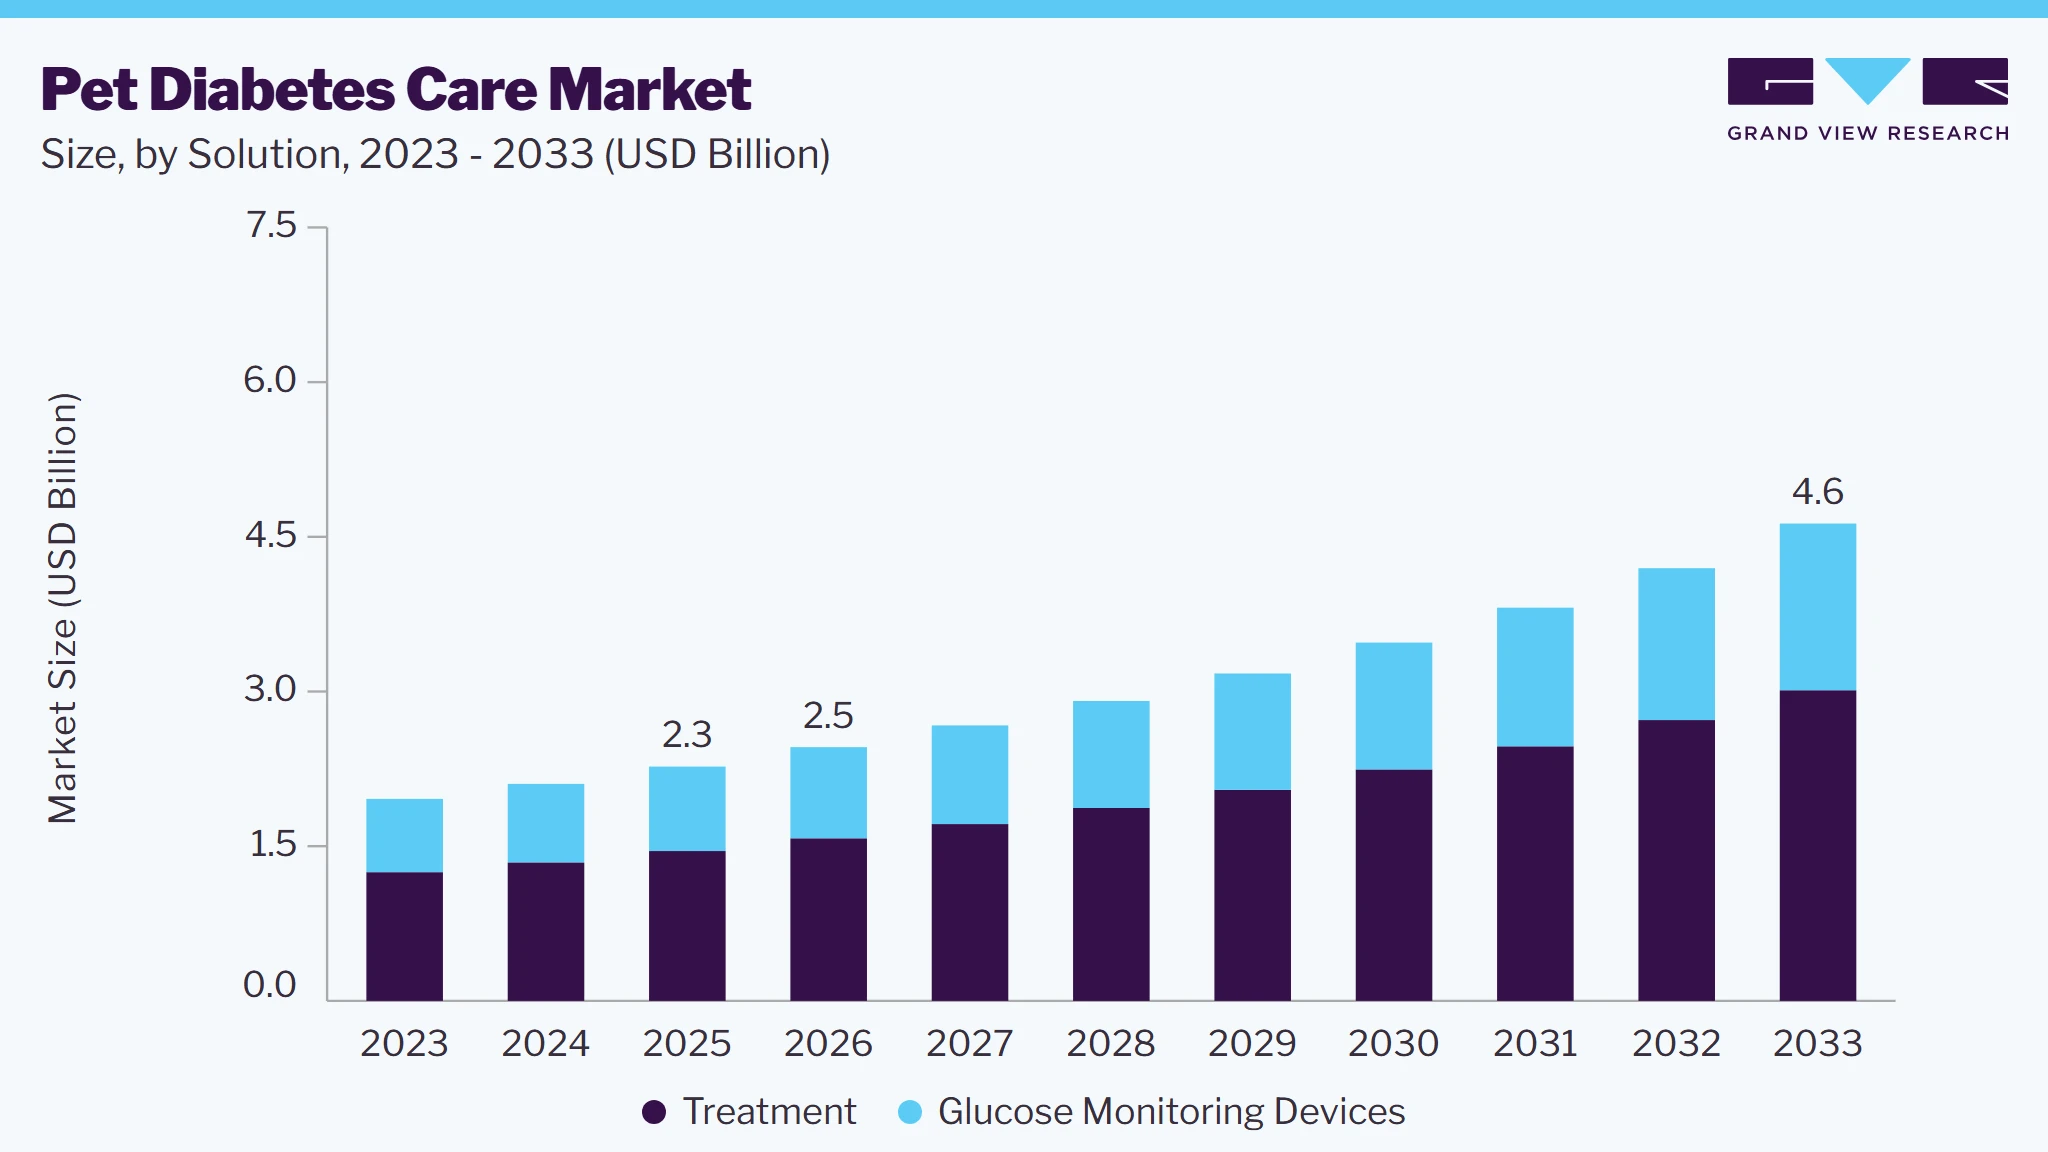 To learn more about this report, Download Free Sample Report
In addition, higher uptake of pet insurance is improving access to advanced diagnostics, glucose monitoring devices, and insulin therapies by reducing out-of-pocket expenses.
Market Dynamics
The pet diabetes care market is experiencing sustained growth due to the increasing incidence of diabetes in companion animals, coupled with expanding pet ownership, increasing animal adoption, and heightened awareness of long-term pet disease management. Advancements in glucose monitoring technologies, insulin delivery systems, and digital health solutions are improving disease management and encouraging early diagnosis. Furthermore, expanding pet insurance coverage and increasing expenditure on veterinary care are enhancing access to long-term diabetes treatment. However, the high cost of continuous monitoring and lifelong therapy, along with limited awareness in developing regions, may restrain market growth to some extent.
Moreover, the regulatory landscape for the pet diabetes care industry is evolving as veterinary authorities place greater emphasis on the safety, efficacy, and quality of diabetes therapeutics and diagnostic devices. Regulatory agencies continue to streamline approval pathways for veterinary pharmaceuticals, insulin formulations, glucose monitoring systems, and related medical devices while requiring stringent manufacturing and quality standards. Also, increasing harmonization of veterinary regulations across major markets and growing support for animal health innovation are encouraging product development, market expansion, and wider adoption of advanced diabetes care solutions.
The increasing prevalence of diabetes among companion animals is a major factor driving the growth of the pet diabetes care market. For instance, according to an article published by Oak Forest Veterinary Hospital, diabetes currently affects approximately 1 in 200 cats and 1 in every 200-500 dogs, with a growing number of cases reported in senior pets and in younger animals also. The rising incidence is closely associated with increasing pet obesity, sedentary lifestyles, and longer life expectancy, all of which elevate the risk of metabolic disorders. Since diabetes is a chronic condition that requires lifelong insulin therapy, regular blood glucose monitoring, prescription diets, and frequent veterinary consultations, its growing prevalence is significantly increasing demand for diabetes management products and services. Furthermore, greater awareness among pet owners regarding early symptoms such as excessive thirst, frequent urination, and unexplained weight loss is encouraging earlier diagnosis and timely intervention, contributing to improved treatment outcomes and sustained market growth.
 To learn more about this report, Download Free Sample Report
The high cost associated with the diagnosis and long-term management of pet diabetes remains a significant restraint for the pet diabetes care market. Effective disease management requires regular veterinary consultations, blood glucose testing, continuous glucose monitoring devices, insulin therapy, prescription diets, and periodic follow-up examinations, resulting in substantial recurring expenses for pet owners. These costs can be particularly burdensome in regions with limited pet insurance penetration or lower disposable incomes, leading to delayed diagnosis, inconsistent adherence to treatment, or discontinuation of therapy. Consequently, the financial burden associated with lifelong diabetes management limits the adoption of advanced diabetes care solutions and constrains overall market growth.
The expanding adoption of pet insurance presents a significant growth opportunity for the pet diabetes care market by improving affordability and access to long-term diabetes management. According to the latest North American Pet Health Insurance Association (NAPHIA) data, approximately 6.4 million pets in the U.S. were insured in 2024, representing an estimated 5-5.3 million pet owners with coverage. As diabetes requires lifelong insulin therapy, regular blood glucose monitoring, routine veterinary consultations, and specialized nutrition, broader insurance coverage can significantly reduce financial burden, encouraging pet owners to pursue timely diagnosis and continuous treatment. This trend is expected to support higher adoption of advanced glucose monitoring devices, insulin delivery products, and diabetes management services.
Despite this growth, pet insurance remains substantially underpenetrated, covering less than 5% of the estimated 135+ million dogs and cats in U.S. households. This large uninsured pet population represents considerable untapped market potential for diabetes care providers. Furthermore, the pet insurance industry has recorded an average annual growth rate of approximately 20% over the past five years, driven by increasing veterinary healthcare costs, rising awareness of insurance benefits, and the growing perception of pets as family members. As insurance providers expand their offerings and awareness continues to increase, the resulting improvement in access to comprehensive veterinary care is expected to create favorable opportunities for sustained market growth.
Market Concentration & Characteristics
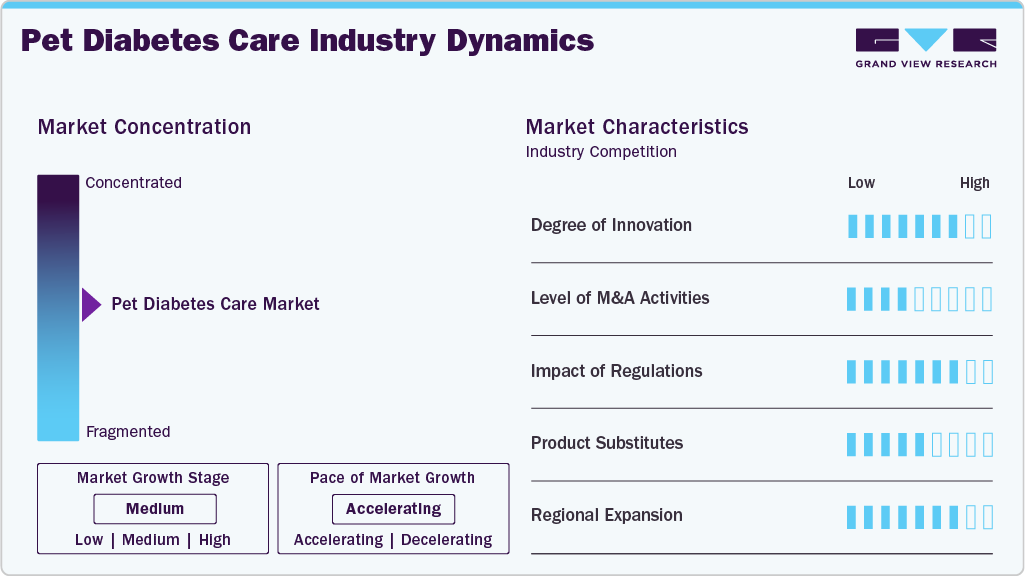
The pet diabetes care industry is positioned at a moderate level of market concentration, characterized by the presence of established animal health companies offering insulin therapies, glucose monitoring devices, and diabetes management solutions. Established players such as BD, Boehringer Ingelheim International GmbH, Merck Animal Health, Nova Biomedical, and Zoetis leverage their extensive product portfolios, strong distribution networks, and long-standing relationships with veterinary clinics to maintain a competitive market position. However, the presence of niche manufacturers offering specialized glucose monitoring devices and insulin delivery solutions contributes to a dynamic competitive environment.
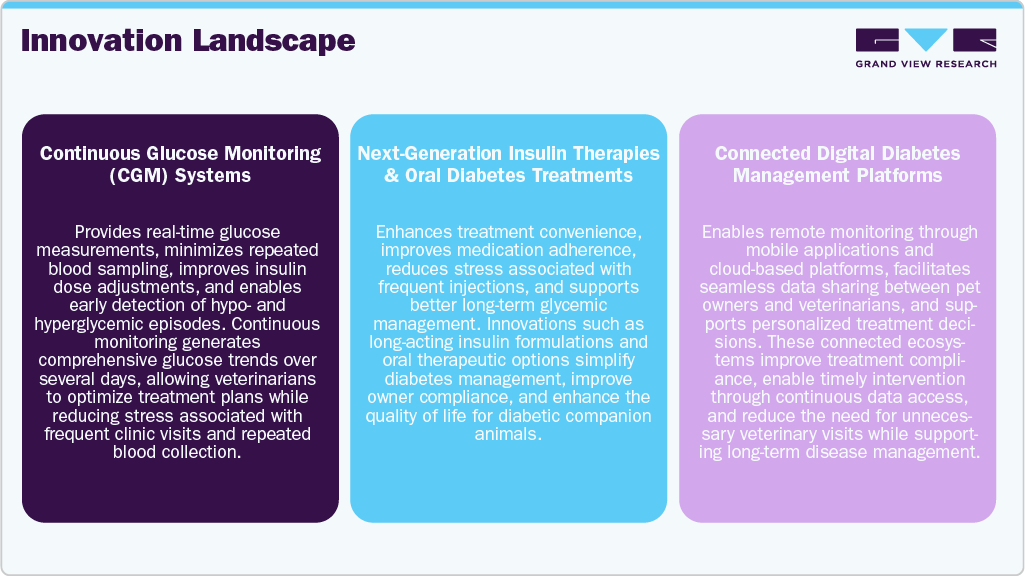
The industry demonstrates a high degree of innovation, driven by the adoption of advanced diabetes management technologies from human healthcare into veterinary medicine. Continuous glucose monitoring systems are becoming increasingly common for diabetic pets, while emerging innovations such as automated insulin delivery (AID) systems integrating CGMs, insulin pumps, and mobile applications demonstrate the sector’s shift toward personalized, real-time diabetes management. These advancements are expected to improve treatment precision, enhance disease monitoring, and support the future development of smart veterinary diabetes care solutions.
 To learn more about this report, Download Free Sample Report
The industry is witnessing moderate merger and acquisition activity, with leading animal health companies acquiring innovative veterinary technology firms and expanding their companion animal portfolios. These transactions strengthen product offerings, enhance technological capabilities, and broaden geographic reach.
The sector is influenced by stringent veterinary regulatory standards governing the approval, safety, and quality of diabetes therapeutics and diagnostic devices. Supportive regulatory pathways for veterinary innovations are facilitating the commercialization of advanced diabetes care products.
The threat of product substitutes is moderate, as diabetes requires continuous medical management through insulin therapy and glucose monitoring. Although dietary management and lifestyle modifications support treatment, they cannot replace prescribed diabetes medications and monitoring devices.
Companies are actively pursuing regional expansion by strengthening distribution networks, establishing strategic partnerships, and increasing their presence in emerging veterinary healthcare markets. Rising companion animal ownership and improving access to veterinary services are creating new growth opportunities across Asia Pacific, Latin America, and the Middle East.
Analyst Perspective
Advancements in veterinary diagnostics and digital health technologies are transforming the pet diabetes care market. Increasing adoption of continuous glucose monitoring (CGM) systems, digital health platforms, and advanced insulin delivery technologies is improving treatment outcomes and veterinary decision-making. Rising pet lifespans and obesity prevalence are driving long-term demand for diabetes care. Moreover, established animal health companies and emerging veterinary technology companies are expanding innovation in monitoring and treatment solutions. Growth will be further supported by increasing digitalization of pet healthcare and expanding access to advanced pet care, particularly in emerging markets.
Animal Insights
The dogs segment dominated the pet diabetes care market with a share of 53.2% in 2025, owing to the substantial canine population and high ownership rates. According to the APPA National Pet Owners Survey in 2025, 42.6% of U.S. households own dogs, representing approximately 56.3 million households and a total dog population of 87.3 million. The large dog population increases the number of animals at risk of developing chronic conditions such as diabetes, thereby expanding the patient pool requiring long-term disease management. Additionally, dog owners spend an average of USD 598 annually on veterinary care, considering a higher willingness to invest in advanced diagnostics, insulin therapy, routine glucose monitoring, and ongoing veterinary treatment.
The cats segment is expected to grow at the fastest CAGR of 10.8% in the coming years, driven by the increasing prevalence of obesity among companion cats, a major risk factor for the development of Type II diabetes. Sedentary indoor lifestyles, overfeeding, and reduced physical activity have contributed to a growing number of overweight cats, increasing the need for regular glucose monitoring, insulin therapy, and long-term diabetes management. This trend is expected to drive sustained demand for feline diabetes care products and services.
Solution Insights
The treatment segment dominated the pet diabetes care industry with a share of 63.9% in 2025, due to the lifelong nature of diabetes management in companion animals. Once diagnosed, diabetic pets require continuous insulin therapy to maintain blood glucose levels, creating consistent demand for veterinary insulin products. Additionally, the increasing adoption of advanced insulin delivery devices, such as insulin pens and syringes designed for accurate dosing and ease of administration, is improving treatment compliance among pet owners. Ongoing innovations in insulin formulations and delivery technologies are further supporting the growth of this segment.
The glucose monitoring devices segment is witnessing significant growth owing to the increasing adoption of continuous glucose monitoring technologies in veterinary diabetes management. For instance, the development of innovative solutions, such as the GluCurve Pet Continuous Glucose Monitor, scheduled for relaunch in Canada in early 2026 and the U.S. in the second quarter of 2026, enables real-time glucose monitoring and supports more accurate insulin dose adjustments. By providing continuous glucose data to both pet owners and veterinarians through connected mobile applications and online platforms, these technologies improve treatment precision, reduce complications, and enhance long-term disease management. The anticipated demand of up to 3 million units annually in both the U.S. and Europe further highlights the growing adoption of advanced diabetes care solutions, thereby driving demand for monitoring devices.
Distribution Channel Insights
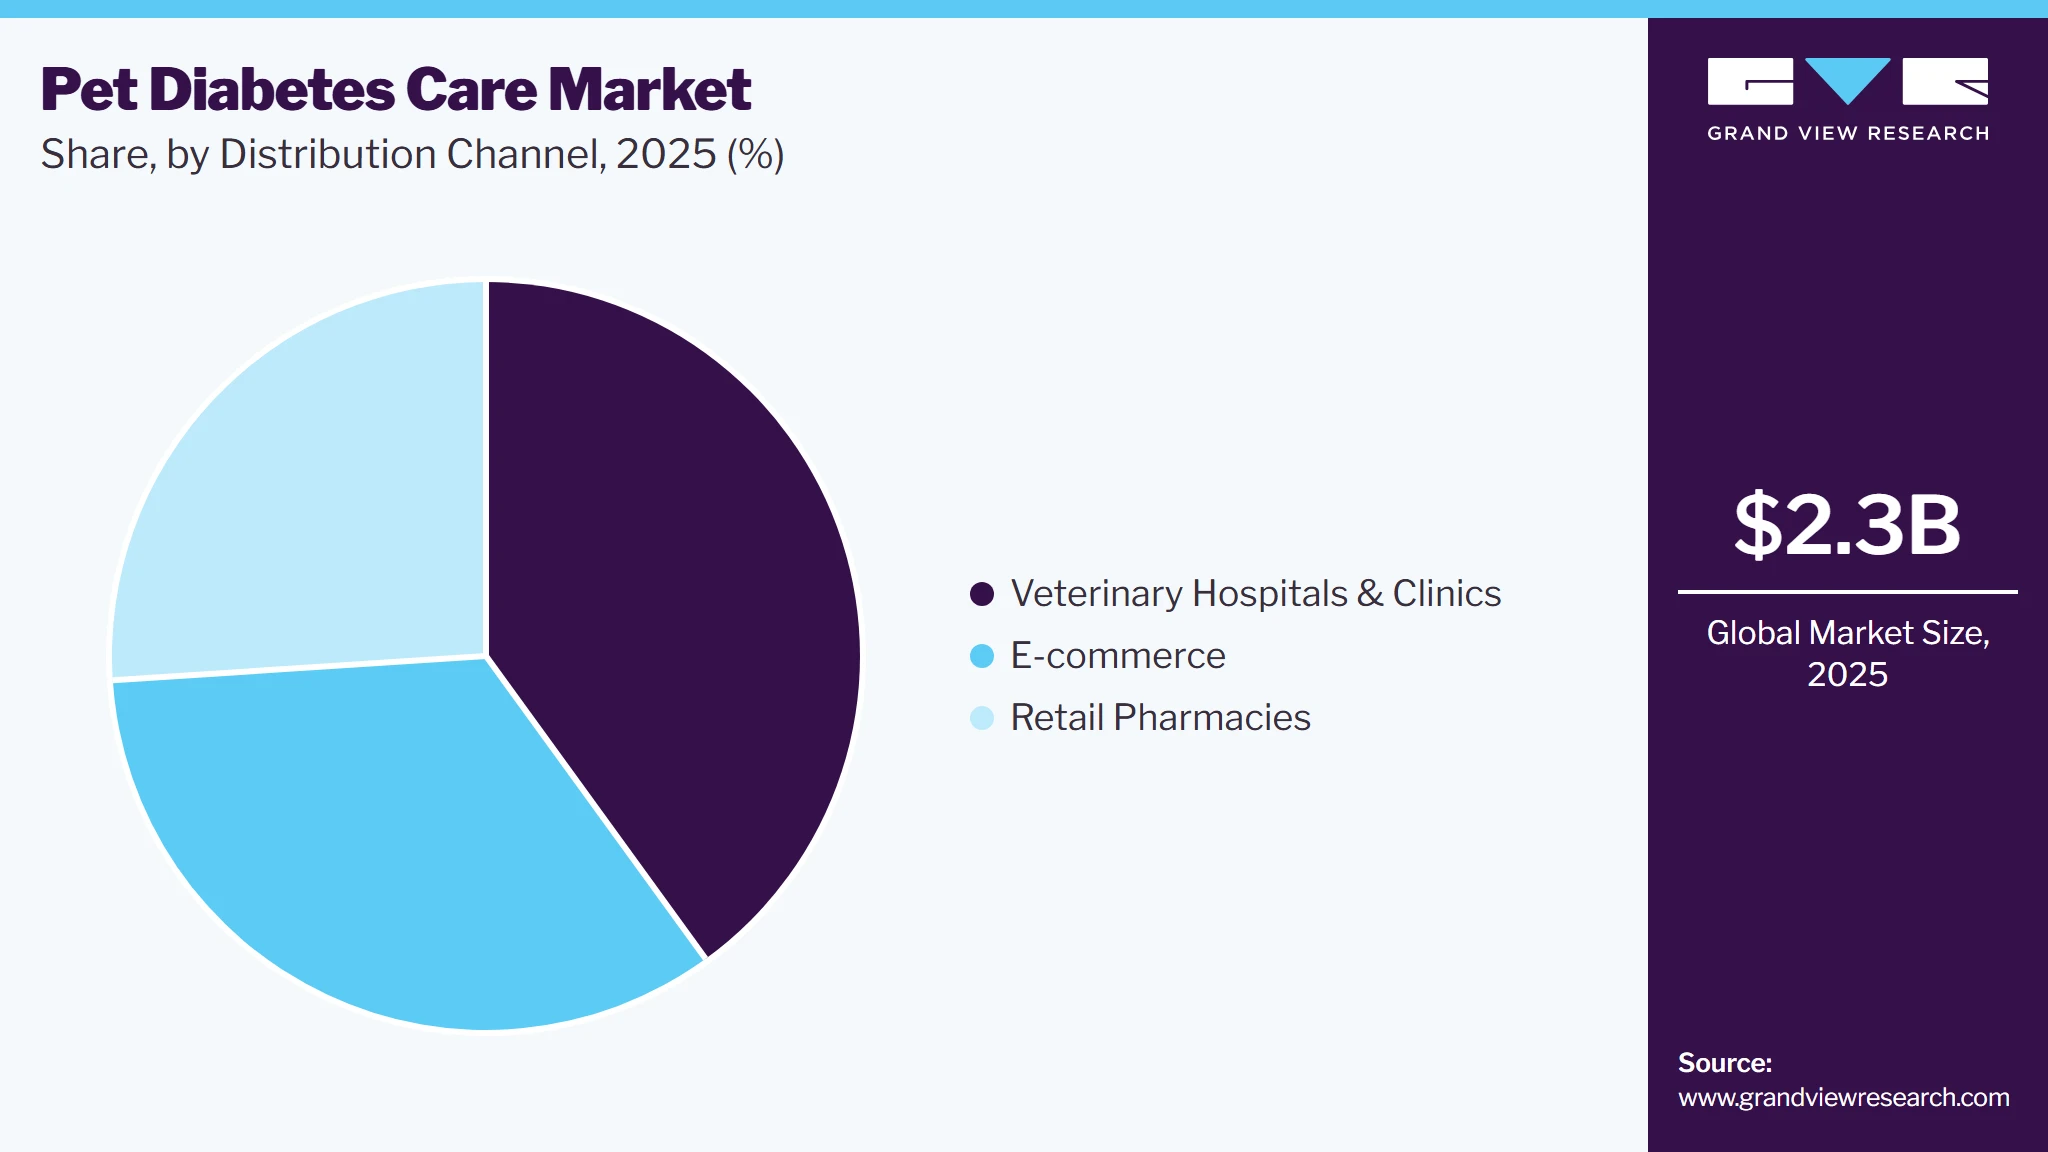
The veterinary hospitals & clinics segment accounted for the largest revenue share of 40.0% in 2025. This is due to their central role in the diagnosis, treatment, and long-term management of diabetes in companion animals. These facilities provide comprehensive diabetes care, including blood glucose testing, insulin prescription, treatment monitoring, dietary counseling, and regular follow-up visits. Their access to advanced diagnostic equipment and experienced veterinary professionals enables accurate diagnosis and personalized treatment plans, improving clinical outcomes. Furthermore, the growing number of companion animal visits for chronic disease management and the expansion of specialized veterinary services are strengthening the demand for diabetes care products and services through this channel.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is estimated to grow the fastest at a CAGR of 10.3%. This is owing to the increasing preference for convenient online purchasing of diabetes care products. Pet owners are increasingly using online platforms to purchase insulin, glucose monitoring devices, testing supplies, and prescription diets because of competitive pricing, home delivery, and subscription-based refill services. The growing availability of veterinary-approved products through digital pharmacies and pet healthcare platforms is improving accessibility, particularly in regions with limited specialty veterinary stores. In addition, the rapid expansion of online retail channels and increasing digital adoption among pet owners are supporting the sustained growth of the e-commerce segment.
Regional Insights
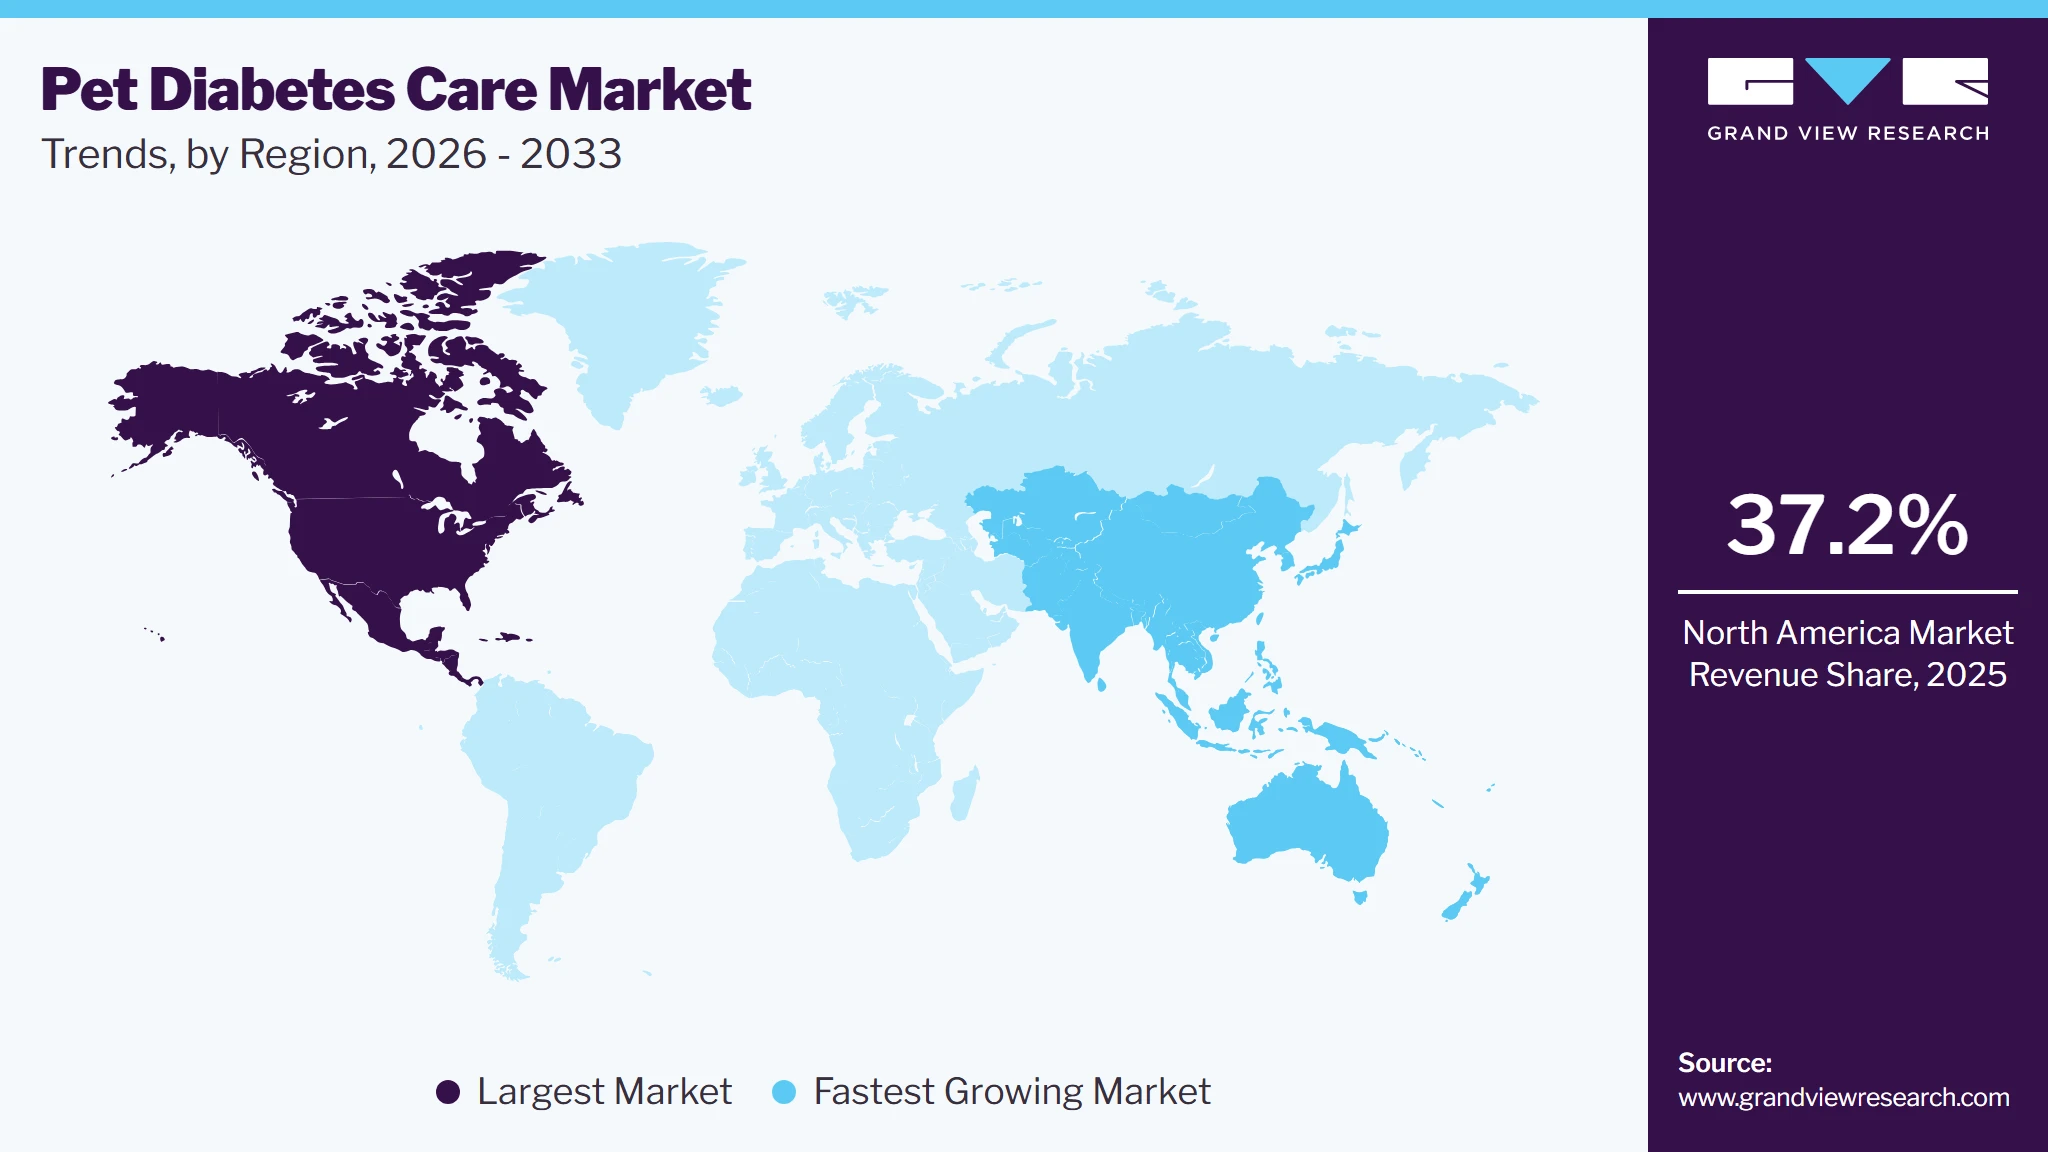
The North America pet diabetes care market held the largest share of 37.2% in 2025. The market is driven by the region's well-established veterinary healthcare infrastructure and high adoption of advanced diabetes management technologies. Strong pet insurance penetration enables greater access to insulin therapy, glucose monitoring devices, and long-term veterinary care. The presence of leading animal health companies, coupled with continuous product innovation, further supports market expansion. In addition, high awareness among pet owners regarding chronic disease management and preventive veterinary care contributes to early diagnosis and improved treatment compliance.
 To learn more about this report, Download Free Sample Report
U.S. Pet Diabetes Care Market Trends
The U.S. pet diabetes care industry accounted for the largest share of North America in 2025, driven by the country's expanding companion animal population and strong emphasis on preventive veterinary care. According to the American Veterinary Medical Association (AVMA), the number of pet-owning households increased from 71.5 million in 2016 to 77.5 million in 2025, with 58.6% of U.S. households owning at least one pet. Over the same period, the owned dog population rose to 87.3 million, while the cat population reached 76.3 million, expanding the population at risk of chronic diseases such as diabetes. Additionally, nearly 80% of dog owners and over 70% of cat owners consider their pets as family members, encouraging higher spending on routine veterinary care, early disease detection, and long-term diabetes management, thereby driving market growth.
The Canada pet diabetes care market is expected to grow at a significant CAGR during the forecast period, supported by increasing awareness of diabetes in companion animals and a strong focus on early diagnosis and long-term disease management. Diabetes is one of the most common endocrine disorders in dogs, with Type I diabetes being the predominant form, requiring lifelong insulin therapy and regular blood glucose monitoring. The need for continuous insulin administration, periodic veterinary consultations, and routine glucose testing drives sustained demand for diabetes therapeutics and monitoring devices. Furthermore, Canada's well-developed veterinary healthcare system and growing adoption of advanced diagnostic and treatment solutions continue to support market growth.
Europe Pet Diabetes Care Market Trends
The Europe pet diabetes care industry is supported by increasing expenditure on companion animal healthcare and a growing emphasis on preventive veterinary medicine. The region benefits from stringent animal welfare regulations that encourage routine health screening and timely management of chronic diseases. Rising demand for advanced veterinary diagnostics, coupled with expanding availability of specialized diabetes care products, is driving market growth. Furthermore, collaborations between veterinary clinics, research institutions, and animal health companies are accelerating the adoption of innovative diabetes management solutions.
The pet diabetes care market in the UK is expected to grow significantly over the forecast period, driven by the increasing prevalence of diabetes among companion animals and strong awareness of chronic disease management. Pet diabetes is estimated to affect approximately 1 in 175 pets in the U.K., highlighting the growing need for long-term veterinary care. Since most diabetic dogs require lifelong insulin therapy and many diabetic cats require continuous glucose monitoring, the demand for insulin products, monitoring devices, and prescription diets continues to increase. Furthermore, growing awareness among pet owners regarding early diagnosis, obesity management, and routine veterinary check-ups is supporting the adoption of advanced pet diabetes care solutions across the country.
The Germany pet diabetes care market held the largest share in 2025 in Europe, supported by the country's strong animal health industry and continuous product innovation. The European Commission's marketing authorization of SENVELGO (velagliflozin oral solution), developed by Germany-based Boehringer Ingelheim, marks a significant advancement in feline diabetes management. As the first once-daily oral treatment for cats with non-insulin-dependent diabetes mellitus, SENVELGO simplifies disease management by reducing the need for insulin injections and frequent glucose monitoring, improving treatment compliance among pet owners. The introduction of such innovative therapies, coupled with Germany's robust veterinary healthcare infrastructure and strong R&D capabilities, is accelerating the adoption of advanced pet diabetes care solutions and driving market growth.
Asia Pacific Pet Diabetes Care Market Trends
The Asia Pacific pet diabetes care industry is expected to grow at the fastest CAGR over the forecast period, driven by increasing companion animal ownership and rising disposable incomes in emerging economies. Expanding veterinary healthcare infrastructure and improved access to veterinary services are enhancing the diagnosis and treatment of chronic diseases in pets. Growing awareness of pet health, increasing urbanization, and the humanization of companion animals are encouraging greater spending on long-term diabetes management. Additionally, international animal health companies are expanding their regional footprint through strategic partnerships and distribution networks.
The pet diabetes care market in India is expected to grow at the fastest CAGR across the APAC region from 2026 to 2033. This is fueled by changing pet lifestyles, increasing urbanization, and growing awareness of companion animal health. Veterinary experts have reported a rise in diabetes among pet dogs, largely attributed to sedentary lifestyles, obesity, reduced physical activity, and increasing consumption of processed pet foods, particularly among urban pets. These lifestyle changes are increasing the incidence of metabolic disorders, prompting greater demand for early diagnosis, insulin therapy, glucose monitoring devices, and specialized diabetic nutrition. Furthermore, the expansion of veterinary healthcare services and rising expenditure on premium pet care are expected to support the continued market growth.
The market for pet diabetes care in Australia is witnessing notable growth driven by increasing awareness of diabetes in companion animals and greater emphasis on early diagnosis and disease management. According to veterinary experts, diabetes affects approximately 1 in 200 dogs and 1 in 230 cats, with obesity, aging, and breed predisposition identified as key risk factors. As awareness of symptoms such as excessive thirst, weight loss, and lethargy continues to improve, more pets are being diagnosed at earlier stages, increasing demand for blood glucose testing, insulin therapy, and long-term monitoring. Furthermore, the country's well-established veterinary healthcare system and rising focus on preventive pet care are supporting the adoption of advanced diabetes management solutions, driving market growth.
Latin America Pet Diabetes Care Market Trends
The pet diabetes care industry in Latin America is growing at a lucrative rate, owing to is driven by the gradual modernization of veterinary healthcare systems and increasing investment in companion animal health. Rising pet humanization trends are encouraging pet owners to seek advanced medical care for chronic conditions, including diabetes. The growing presence of multinational veterinary pharmaceutical companies and the wider availability of diabetes therapeutics are improving market accessibility. Moreover, expanding veterinary clinic networks and increasing awareness of early disease diagnosis are supporting steady market growth.
The Argentina pet diabetes care market is expected to witness steady growth over the forecast period, supported by the country's expanding companion animal population and increasing demand for specialized veterinary services. Argentina has one of the highest rates of pet ownership in Latin America, with dogs and cats playing an increasingly important role in urban households. This trend has encouraged veterinary clinics to expand their offerings for chronic disease management, including endocrine disorders such as diabetes. The growing availability of imported veterinary insulin formulations, prescription therapeutic diets, and point-of-care diagnostic equipment is improving treatment accessibility.
Middle East & Africa Pet Diabetes Care Market Trends
The MEA pet diabetes care industry is advancing, owing to improving veterinary healthcare infrastructure and increasing awareness of companion animal wellness. Rising investments in veterinary hospitals, specialty clinics, and animal healthcare services are expanding access to diabetes diagnosis and treatment. Growth in premium pet care spending, particularly in Gulf Cooperation Council (GCC) countries, is supporting the adoption of advanced diabetes management products. Furthermore, increasing participation of international animal health companies and expanding distribution channels are creating new opportunities for market development across the region.
The pet diabetes care market in South Africa is expected to grow at a considerable CAGR during the forecast period, driven by the increasing expansion of veterinary hospitals & clinics, veterinary practices, and improving access to companion animal healthcare in major metropolitan areas. The country has witnessed rising demand for advanced veterinary diagnostics as pet owners seek more comprehensive clinical evaluations for aging animals. Since diabetes is more frequently diagnosed in senior and overweight pets, the growing aging pet population is creating sustained demand for insulin therapy, blood glucose monitoring, and regular veterinary follow-up.
The UAE pet diabetes care market is anticipated to register healthy growth during the forecast period, supported by the rapid development of premium companion animal healthcare services and increasing expenditure on advanced veterinary treatments. The country's affluent pet-owning population is increasingly seeking high-quality medical care, including specialized endocrine disease management and continuous monitoring solutions.
Key Pet Diabetes Care Company Insights
The pet diabetes care market is characterized by moderate to high competition and is moderately fragmented, with the presence of established animal health companies, veterinary diagnostics providers, and specialized medical device manufacturers. Leading players such as Zoetis Inc., Merck Animal Health, Boehringer Ingelheim, IDEXX Laboratories, Elanco Animal Health, Virbac, and Trividia Health compete by expanding their diabetes treatment portfolios, developing advanced glucose monitoring technologies, and strengthening their veterinary distribution networks. For instance, Zoetis offers ProZinc (protamine zinc recombinant human insulin) for diabetic cats and dogs, while IDEXX Laboratories provides diagnostic solutions that support the early detection and long-term monitoring of diabetes in companion animals.
Key Pet Diabetes Care Companies
The following key companies have been profiled for this study of the pet diabetes care market.
-
Merck & Co., Inc.
-
Zoetis
-
BD
-
Boehringer Ingelheim International GmbH
-
Nova Biomedical
-
Allison Medical, Inc.
-
AccuBioTech Co., Ltd
-
i-SENS, Inc.
-
TaiDoc Technology Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merck & Co., Inc.; Zoetis; BD; Boehringer Ingelheim International GmbH; Nova Biomedical)
Established companies focus on expanding their companion animal diabetes portfolios through continuous product innovation, regulatory approvals, and geographic expansion. They invest in advanced insulin formulations, continuous glucose monitoring (CGM) technologies, insulin delivery devices, and digital diabetes management platforms. Strategic collaborations with veterinary hospitals, distributors, and research institutions, along with investments in R&D and manufacturing capabilities, help strengthen market presence and improve access to comprehensive diabetes care solutions.
These companies benefit from strong global brands, extensive veterinary distribution networks, broad product portfolios, and well-established relationships with veterinarians and animal healthcare providers. Their regulatory expertise, financial strength, advanced manufacturing capabilities, and ability to integrate diagnostics with treatment solutions enable high customer trust, product reliability, and sustained market leadership.
Established players often encounter high R&D and regulatory compliance costs associated with veterinary pharmaceuticals and medical devices. Long product development timelines, premium product pricing, and complex reimbursement and market access environments may limit adoption in price-sensitive markets. Additionally, large organizational structures can slow innovation compared with agile technology-focused competitors.
Emerging Players (Allison Medical, Inc.; AccuBioTech Co., Ltd.; i-SENS, Inc.; TaiDoc Technology Corporation)
Emerging companies emphasize affordable glucose monitoring technologies, portable diagnostic devices, and user-friendly diabetes management solutions for veterinary applications. They focus on adapting human diabetes technologies for companion animals, developing connected monitoring platforms, and expanding through partnerships with veterinary distributors, online retail channels, and regional animal healthcare providers. Their strategies prioritize innovation, rapid commercialization, and penetration into underserved and emerging markets.
Emerging players compete through technological agility, cost-effective product offerings, faster innovation cycles, and specialized expertise in glucose monitoring and digital health technologies. Their ability to introduce compact, connected, and easy-to-use monitoring systems allows them to respond quickly to evolving veterinary needs while building a strong presence in niche and regional markets.
Emerging companies generally have limited financial resources, smaller manufacturing capacities, and less established distribution networks than multinational competitors. Lower brand recognition, limited veterinary sales infrastructure, and dependence on third-party partnerships may restrict global expansion. They may also face challenges in obtaining regulatory approvals, scaling production, and competing against companies offering integrated diabetes treatment and diagnostic portfolios.
Recent Developments
-
In April 2025, Universal Biosensors (UBI) launched the consumer-configured PETRACKR Blood Glucose Monitoring System Starter Pack for at-home diabetes monitoring in dogs and cats. The starter pack includes a handheld glucose meter, test strips, lancets, a lancing device, quality control solution, and Bluetooth-enabled mobile app connectivity, enabling pet owners to monitor blood glucose levels remotely and share real-time data with veterinarians. The launch strengthens the adoption of home-based diabetes management and expands access to advanced glucose monitoring solutions for companion animals.
-
In December 2025, ALR Technologies SG Ltd. announced the successful completion of internal manufacturing testing for its GluCurve Pet Continuous Glucose Monitor (CGM) and confirmed its relaunch in the Canadian market for January 2026. Designed specifically for diabetic dogs and cats, the GluCurve system provides continuous glucose readings every three minutes for up to 14 days through a pet-friendly sensor, with data accessible via a mobile application and veterinary web portal for remote insulin dose management. The planned expansion into the U.S. and global markets is expected to strengthen the adoption of advanced continuous glucose monitoring solutions in veterinary diabetes care.
-
In January 2024, Boehringer Ingelheim’s SENVELGO (velagliflozin oral solution) received the S&P Global Animal Health Award for "Best New Product for Companion Animals." The oral treatment, specifically developed for diabetic cats, was recognized for introducing the first SGLT2 inhibitor in veterinary medicine and for securing regulatory approvals across the U.S., Canada, and Europe. This recognition highlights the growing innovation in feline diabetes management and supports the adoption of convenient, non-insulin therapeutic options in companion animal care.
Pet Diabetes Care Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.3 billion
Estimated market size in 2026
USD 2.5 billion
Projected market size by 2033
USD 4.6 billion
Growth rate
CAGR of 9.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Solution, animal, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait; Oman; Qatar
Key companies profiled
Merck & Co., Inc.; Zoetis; BD; Boehringer Ingelheim International GmbH; Nova Biomedical; Allison Medical, Inc.; AccuBioTech Co., Ltd; i-SENS, Inc.; TaiDoc Technology Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pet Diabetes Care Market Report Segmentation
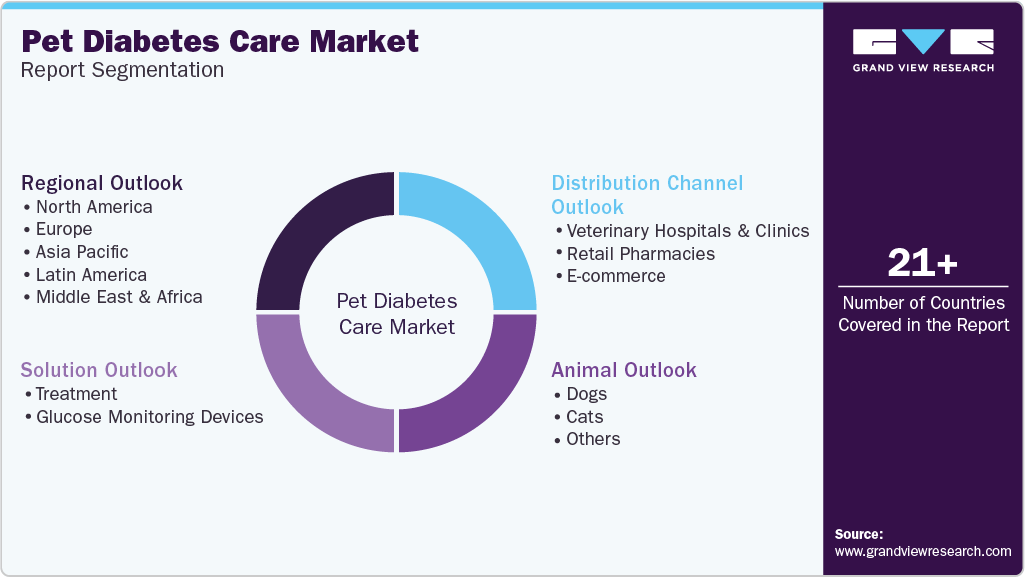
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pet diabetes care market report based on solution, animal, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Solution Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Treatment
-
Insulin Therapy
-
Insulin Delivery Devices
-
Other Treatments
-
-
Glucose Monitoring Devices
-
-
Animal Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Dogs
-
Cats
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Retail Pharmacies
-
E-commerce
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Sweden
-
Denmark
-
-
Asia Pacific
-
Japan
-
India
-
China
-
South Korea
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
-
Research Methodology
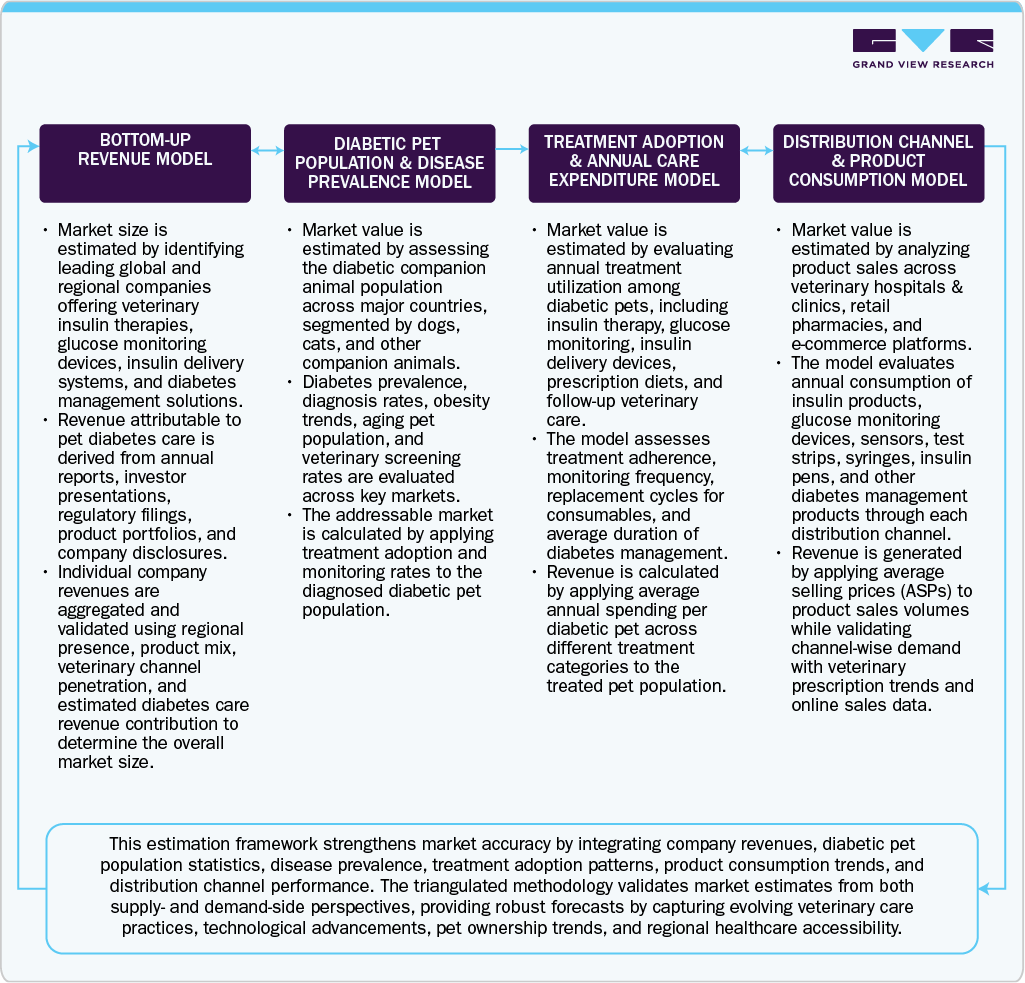
The pet diabetes care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pet diabetes care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Solution
Revenue capture definition
Treatment
This segment accounts for revenue generated from products and therapies used to manage diabetes in companion animals, including insulin medications, insulin administration devices, prescription therapeutic products, and supportive treatment options.
Glucose Monitoring Devices
Revenue in this segment is derived from devices and systems used to measure blood glucose levels in diabetic pets, including portable glucose meters, continuous glucose monitoring (CGM) systems, sensors, readers, and related monitoring accessories.
Insulin Therapy
This segment comprises revenue generated from veterinary and human insulin formulations prescribed for the treatment of diabetes in pets, including long-acting, intermediate-acting, and rapid-acting insulin products.
Insulin Delivery Devices
Revenue includes sales of products designed to administer insulin to diabetic animals, such as insulin syringes, insulin pens, pen needles, and other injection accessories.
Other Treatments
This segment includes revenue generated from complementary diabetes management products, including oral antidiabetic medications, prescription diabetic diets, nutritional supplements, and other supportive therapeutic solutions.
Segment - Animal
Revenue capture definition
Dogs
This segment represents revenue generated from diabetes diagnosis, monitoring, and treatment products specifically utilized for canine patients.
Cats
Revenue in this segment includes diabetes care products and solutions intended for feline patients, encompassing insulin therapy, glucose monitoring devices, and related disease management products.
Others
This segment comprises revenue generated from diabetes care products used for other companion animals, including rabbits, ferrets, guinea pigs, and other pets diagnosed with diabetes.
Segment - Distribution Channel
Revenue capture definition
Veterinary Hospitals & Clinics
This segment captures revenue generated through veterinary hospitals, specialty clinics, and animal healthcare centers that diagnose, prescribe, administer, and dispense diabetes care products and services.
Retail Pharmacies
Revenue includes sales of diabetes therapeutics, insulin products, glucose monitoring supplies, and related pet healthcare products distributed through retail pharmacies and veterinary pharmacy outlets.
E-commerce
This segment represents revenue generated through online sales channels, including digital pharmacies, pet healthcare platforms, manufacturer websites, and e-commerce marketplaces offering diabetes management products for companion animals.
Estimation Model
 To learn more about this report, Download Free Sample Report
Customization Table
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Disease Burden & Patient Pool Assessment
Developed a comprehensive assessment of the global diabetic companion animal population across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The analysis evaluated diabetes prevalence by animal type, obesity trends, aging pet population, diagnosis rates, treatment compliance, and veterinary healthcare accessibility. Identified high-potential countries based on disease burden, pet ownership, veterinary infrastructure, and reimbursement environment.
Enables stakeholders to identify high-growth geographies, estimate the addressable patient population, prioritize commercialization strategies, and optimize investments based on disease prevalence and treatment demand.
Treatment Landscape, Care Pathway & Industry Assessment
Conducted an end-to-end evaluation of the pet diabetes care ecosystem, covering insulin manufacturers, glucose monitoring device providers, insulin delivery device suppliers, veterinary hospitals & clinics, retail pharmacies, e-commerce platforms, and pet insurance providers. Assessed treatment pathways, technology adoption, pricing trends, reimbursement, and product accessibility across major markets.
Provides a holistic understanding of the diabetes care ecosystem, treatment adoption trends, value chain dynamics, and revenue opportunities, enabling informed strategic planning and portfolio expansion.
Competitive Intelligence & Product Portfolio Benchmarking
Performed detailed benchmarking of leading pet diabetes care companies based on product portfolio breadth, insulin offerings, glucose monitoring technologies, digital health capabilities, geographic footprint, distribution strategy, innovation pipeline, partnerships, regulatory approvals, and R&D investments. Compared established multinational companies with emerging technology providers to identify competitive positioning and market gaps.
Supports identification of competitive strengths, innovation opportunities, partnership prospects, product differentiation strategies, and long-term competitive positioning while helping stakeholders respond to evolving market dynamics.
Frequently Asked Questions About This Report
The global pet diabetes care market is expected to grow at a CAGR of 9.4% from 2026 to 2033, reaching USD 4.6 billion by 2033.
Some key players operating in the pet diabetes care market include Merck Animal Health, Zoetis, BD, Boehringer Ingelheim International GmbH, Trividia Health, Inc., Allison Medical, Inc., UltiMed, Inc., ACON Laboratories, Inc., i-SENS, Inc., TaiDoc Technology Corporation.
Key factors that are driving the pet diabetes care market growth include the increasing companion animal population and pet adoption, availability of pet diabetes care devices, the prevalence and rising risk factors of the disease, supportive awareness programs, and strategies implemented by key companies.
Asia Pacific is the fastest-growing region over the forecast period.
The dogs segment led with a 53.2% revenue share in 2025, while the cats is the fastest-growing segment
The treatment segment led with a 63.9% revenue share in 2025, while the glucose monitoring devices is the fastest-growing segment
The veterinary hospitals & clinics segment led with a 40.0% revenue share in 2025, while the e-commerce is the fastest-growing segment
The global pet diabetes care market size was valued at USD 2.3 billion in 2025 and is estimated at USD 2.5 billion in 2026.
North America dominated the pet diabetes care market with a share of 37.2% in 2024.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


