
- Home
- »
- Plastics, Polymers & Resins
- »
-
Plastics In Personal Protective Equipment Market Report, 2033GVR Report cover

Plastics In Personal Protective Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Polyethylene, Polypropylene, Polyurethane), By Application (Protective Clothing, Respiratory Protection, Protective Footwear), By Region, And Segment Forecasts
Market Size, 2025
$24.9BMarket Estimate, 2026
$29.3BMarket Forecast, 2033
$53.0BCAGR, 2026–2033
8.8%Plastics In PPE Market Size & Trends
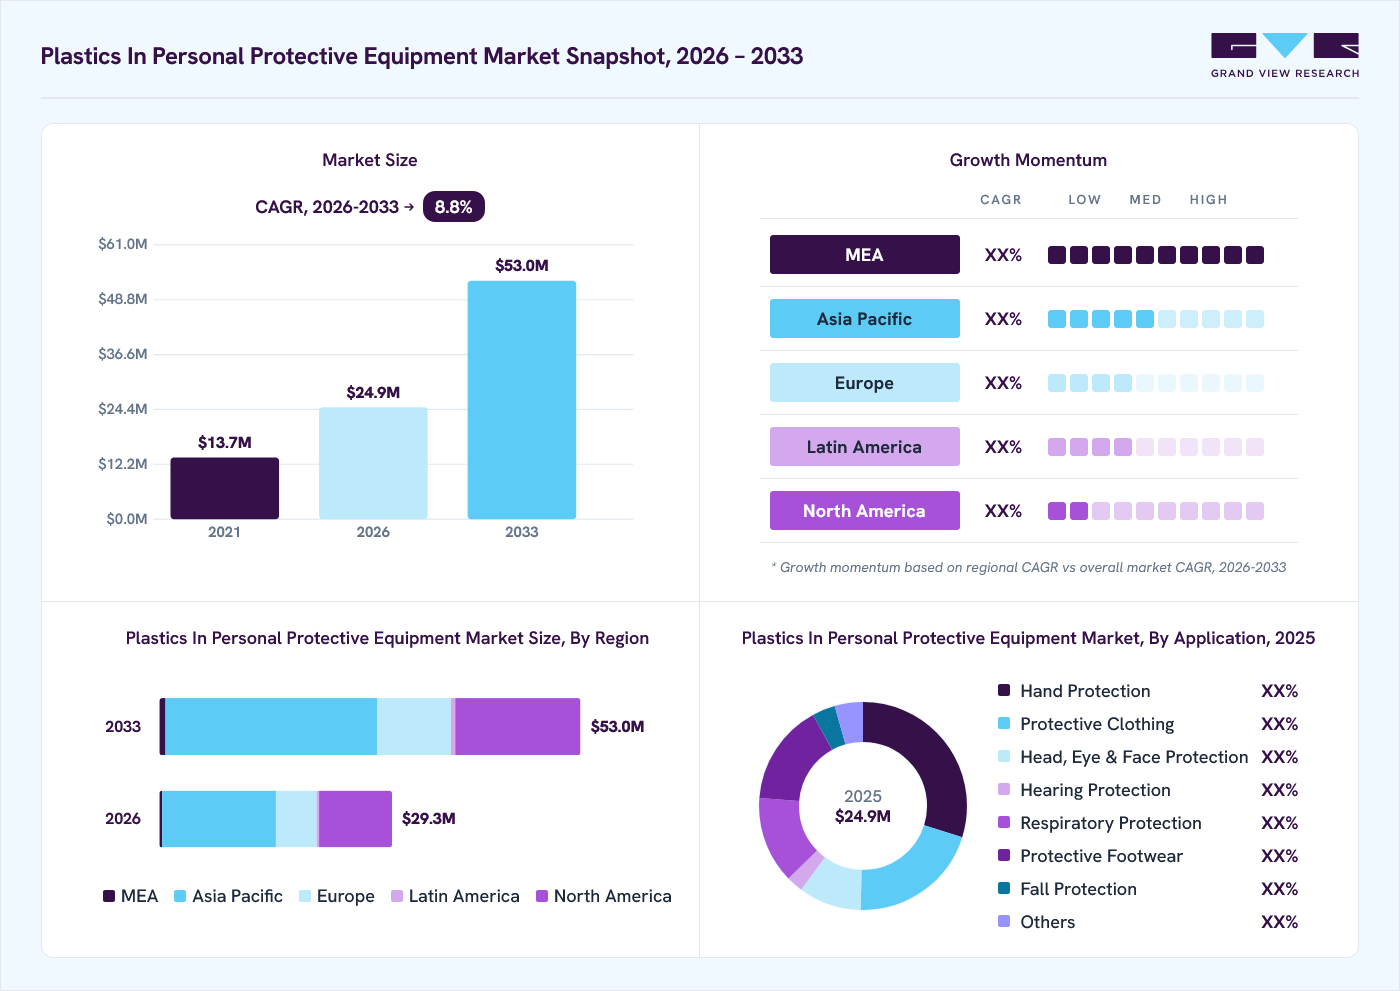
The global plastics in personal protective equipment (PPE) market size was valued at USD 24.9 billion in 2025 and is projected to grow from USD 29.3 billion in 2026 to USD 53.0 billion by 2033, growing at a CAGR of 8.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 48.7% in 2025. Constant technological advancements in raw materials, the increasing need for workplace safety and hygiene, and evolving regulatory standards by global authorities have helped drive market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Polyethylene (PE) segment held the largest revenue share of 24.4% in 2025.
- By application: Hand protection segment held the largest revenue share of 29.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (48.7% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (fastest CAGR, 2026-2033)
- By country: China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.9 Billion
- Estimated market size in 2026: USD 29.3 Billion
- Projected market size by 2033: USD 53.0 Billion
- CAGR (2026-2033): 8.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The variety of available plastics and their different features and benefits have led to their large-scale utilization in the personal protective equipment (PPE) sector. These solutions are used widely in areas such as construction, chemicals, oil & gas, and mining, where the risk of exposure to harmful gases or chemicals is high and thus requires the availability of protective accessories. The COVID-19 pandemic emerged as a major factor driving consumer awareness regarding protective equipment such as face masks and protective clothing, which boosted the use of plastics in the manufacturing process of PPE kits. As government mandates globally necessitated these solutions to prevent the spread of the virus, particularly outdoors, the plastics in the personal protective equipment industry witnessed significant expansion during this period. Increased focus on health security and preparedness has accelerated investments in manufacturing technologies that can produce large volumes of plastic-based solutions quickly and efficiently. PPE standards and regulations set by organizations such as the U.S. Food and Drug Administration (FDA), the Occupational Safety and Health Administration (OSHA), and the Centers for Disease Control and Prevention (CDC) require specific performance characteristics, for instance, barrier protection and fluid resistance, which plastics can meet effectively.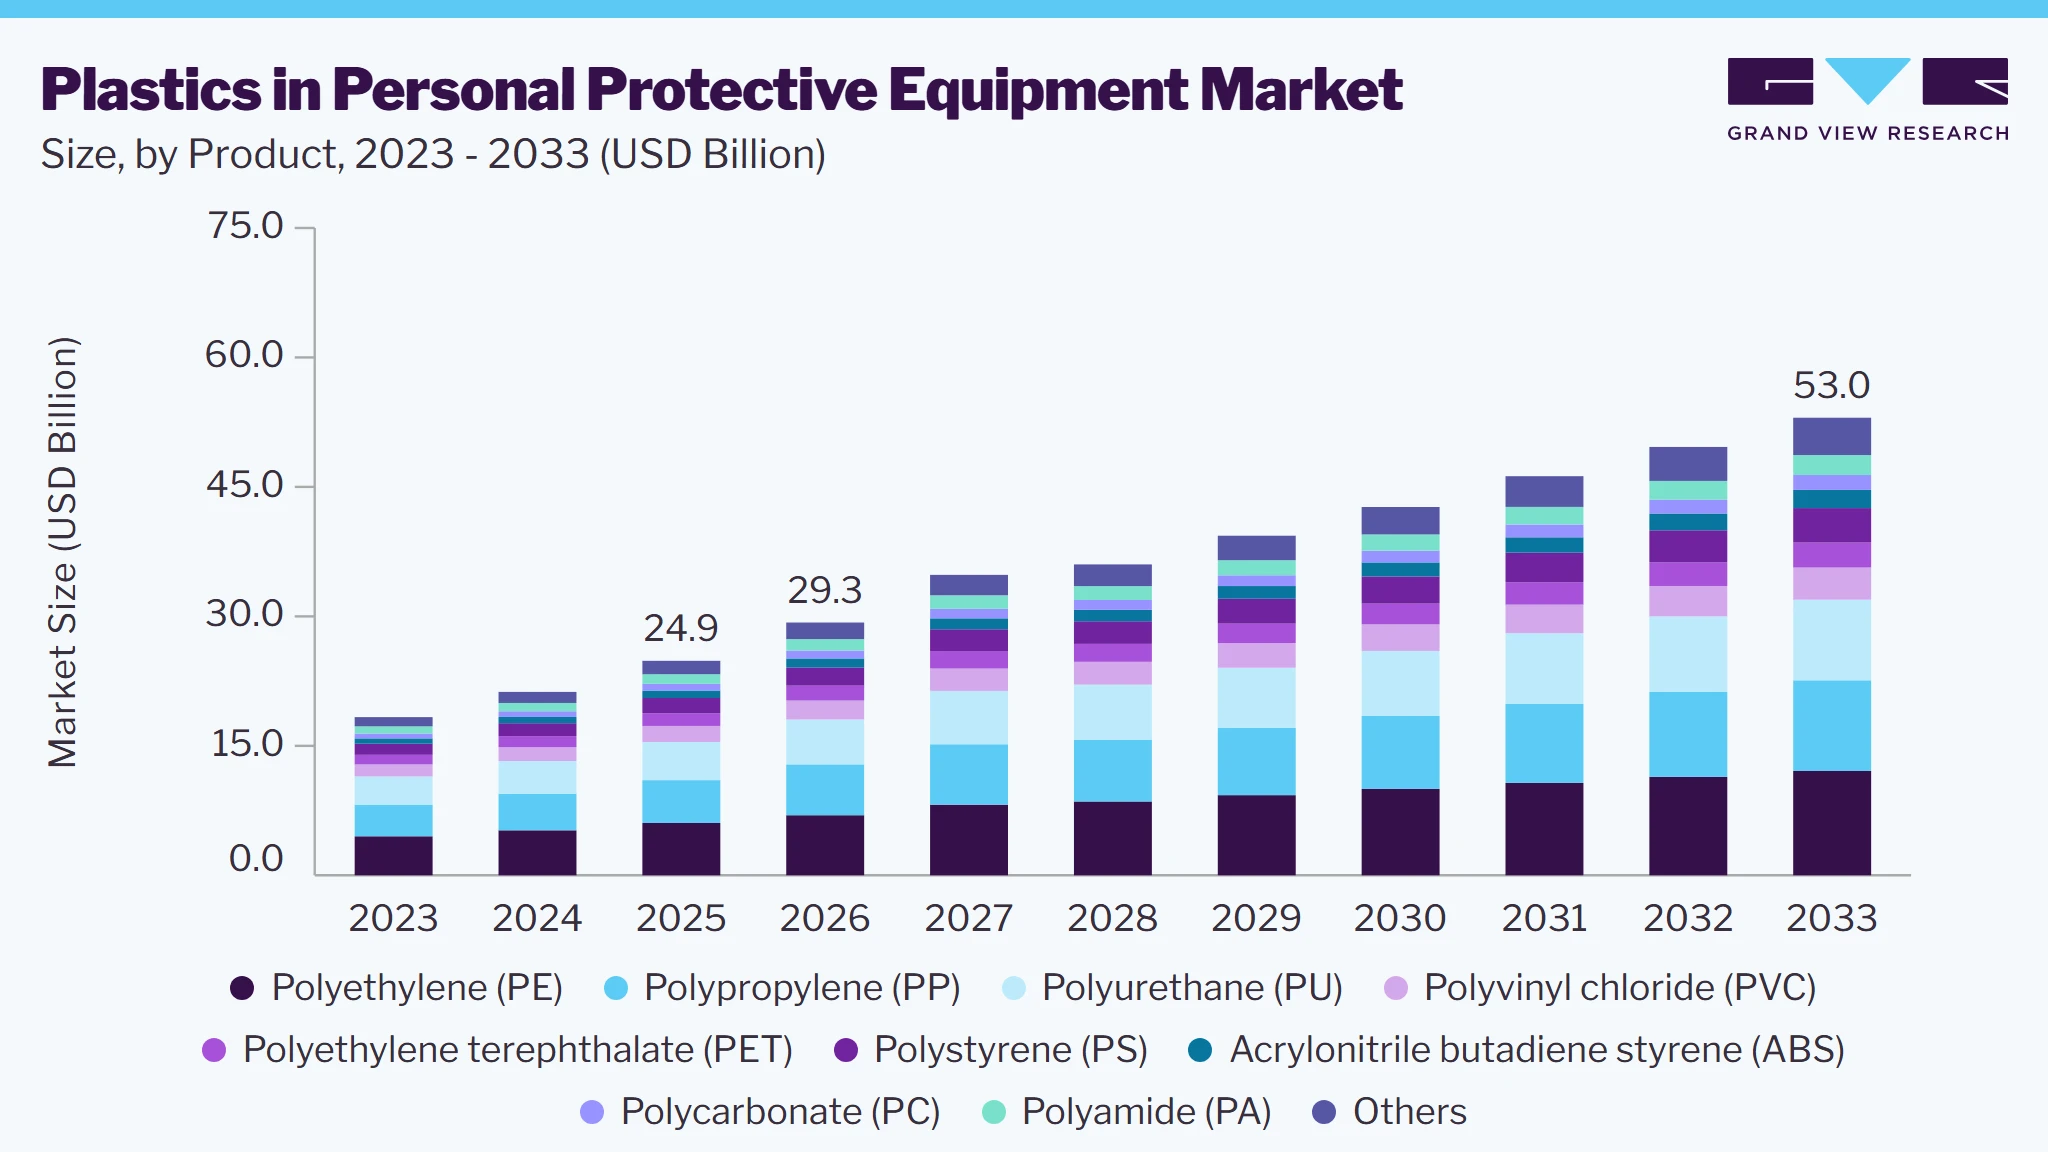 To learn more about this report, Download Free Sample Report
Plastics, particularly polymers such as polyethylene (PE), polypropylene (PP), and polyvinyl chloride (PVC), impart excellent barrier properties to PPE, protecting the wearer from common contaminants, chemicals, and biological hazards. These materials are highly durable and resistant to wear, making them ideal for use in items, including gloves, masks, face shields, and protective gowns that must withstand continuous physical and environmental stress. Using plastics as a base material allows for the integration of various functionalities in these products. For example, face shields can be made from polycarbonate or PET (polyethylene terephthalate) for clarity and impact resistance, while nitrile, latex, or vinyl gloves provide flexibility and tactile sensitivity. Moreover, certain plastic materials can be embedded with antimicrobial agents, enhancing their ability to resist the growth of harmful microorganisms, which is important in specific applications such as medical gowns and gloves.
The increasing focus on sustainability among global corporations and rising awareness regarding the issues presented by single-use and disposable plastic products has helped shape industry developments. The improper disposal of PPE can introduce hazardous pollutants into ecosystems, including microplastics that pose a substantial risk to marine life and human health. Transitioning from conventional plastics to bioplastics represents a promising avenue for sustainable production. Bioplastics, derived from renewable resources such as plant cellulose, offer reduced carbon footprints and better biodegradability compared to traditional plastics. Partnerships between research institutes and manufacturers are expected to aid innovations in the plastics in the personal protective equipment industry. For instance, in April 2022, British PPE manufacturer Globus Group announced a partnership with Imperial College Healthcare to recycle face masks into new medical solutions for the National Health Service (NHS).
Market Dynamics
The plastics in the personal protective equipment market are witnessing steady growth, driven by increasing investments in healthcare preparedness, stringent safety regulations, and rising demand for advanced protective solutions across medical, industrial, and hazardous work environments. High-performance plastics, primarily including polyethylene (PE), polypropylene (PP), polyvinyl chloride (PVC), polycarbonate (PC), and polyethylene terephthalate (PET), offer superior barrier protection, chemical resistance, impact strength, durability, and wearer comfort, accelerating their adoption in gloves, masks, face shields, and protective apparel. Furthermore, growing emphasis on sustainable materials, bioplastic innovations, recycling initiatives, and collaborative product development continues to support long-term global market expansion.
The plastics in the personal protective equipment market are experiencing steady growth, driven by increasing demand from healthcare systems, where infection prevention and patient safety remain critical priorities. Plastic-based personal protective equipment manufactured primarily from polypropylene is extensively utilized in disposable masks, isolation gowns, surgical drapes, and other medical protective products due to its lightweight properties, fluid resistance, high filtration efficiency, durability, and cost-effective large-scale production. These performance advantages continue to accelerate the adoption of plastic-based PPE across hospitals, dental clinics, diagnostic centers, and research laboratories worldwide.
Market growth is further supported by rising healthcare investments, expanding hospital infrastructure, and increasing emphasis on infection control protocols across public and private healthcare facilities. The growing volume of surgical procedures, diagnostic testing, emergency care services, and laboratory research has significantly increased the consumption of disposable protective products that ensure reliable barrier protection and regulatory compliance. As healthcare providers continue to prioritize hygiene, operational efficiency, and occupational safety, plastics in personal protective equipment are expected to witness sustained demand across global healthcare applications.
Fluctuating prices of petrochemical-based raw materials present a significant challenge for plastics in the personal protective equipment market. Manufacturers are increasingly exposed to volatile crude oil prices, rising production expenses, and higher procurement costs for essential polymers such as polypropylene, polyethylene, and polyvinyl chloride, affecting overall profitability and pricing stability. Additionally, supply chain disruptions, transportation constraints, and inconsistent raw material availability continue to create operational uncertainties. These factors increase manufacturing costs for PPE producers while placing pricing pressure on distributors and end-users, potentially limiting market growth and reducing procurement flexibility across healthcare and industrial sectors.
The rising focus on sustainability and circular economy practices offers a substantial opportunity for plastics within the personal protective equipment (PPE) sector. Due to increasing worries over plastic waste production, governments, healthcare organizations, and industrial firms are looking for eco-friendly alternatives to traditional single-use PPE. This shift is fostering innovation in recyclable, reusable, and bio-based materials, such as recyclable polypropylene (PP), bioplastics, and sophisticated polymer combinations. Producers are allocating resources to create environmentally friendly PPE items that uphold high protection standards while minimizing ecological footprint. The advancement of sustainable plastic-based PPE options is anticipated to generate new growth opportunities, especially in healthcare, industrial safety, and consumer protection applications.
Product Insights
Based on product, the polyethylene (PE) segment led the market with the largest revenue share of 24.4% in 2025. The demand for polyethylene (PE) has been influenced by various factors, including the material's unique properties, its versatility, and the evolving needs of industries and healthcare systems for protective accessories. Polyethylene is a widely used plastic in PPE due to its cost-effectiveness, durability, chemical resistance, and ease of processing. Moreover, it is a lightweight material, which results in items made from PE, such as gloves, gowns, and aprons being more comfortable for extended wear. Polyethylene is also resistant to fluids, making it an ideal material for creating protective barriers against bodily fluids, blood-borne pathogens, and other contaminants. Increasing sustainability concerns are expected to lead to the development of recyclable & bio-based polyethylene alternatives, aiding segment growth.
The polyester segment is expected to grow at the highest CAGR from 2026 to 2033. Increasing awareness regarding product benefits such as its durability, versatility, resistance to wear and tear, and ability to be easily engineered for specific protective properties have made it a preferred material in the plastics in PPE industry. These properties have made it a preferred material for protective equipment that needs to withstand heavy wear and repeated use, such as protective clothing, coveralls, gowns, and aprons. Polyester also offers good resistance to chemical exposure, making it suitable for use in environments where workers are exposed to harsh chemicals or biohazards. Innovations in bio-based polyester, such as materials produced from renewable sources (plant-based feedstocks such as sugarcane or corn), offer an eco-friendly alternative to conventional polyester made from petrochemical resources.
Application Insights
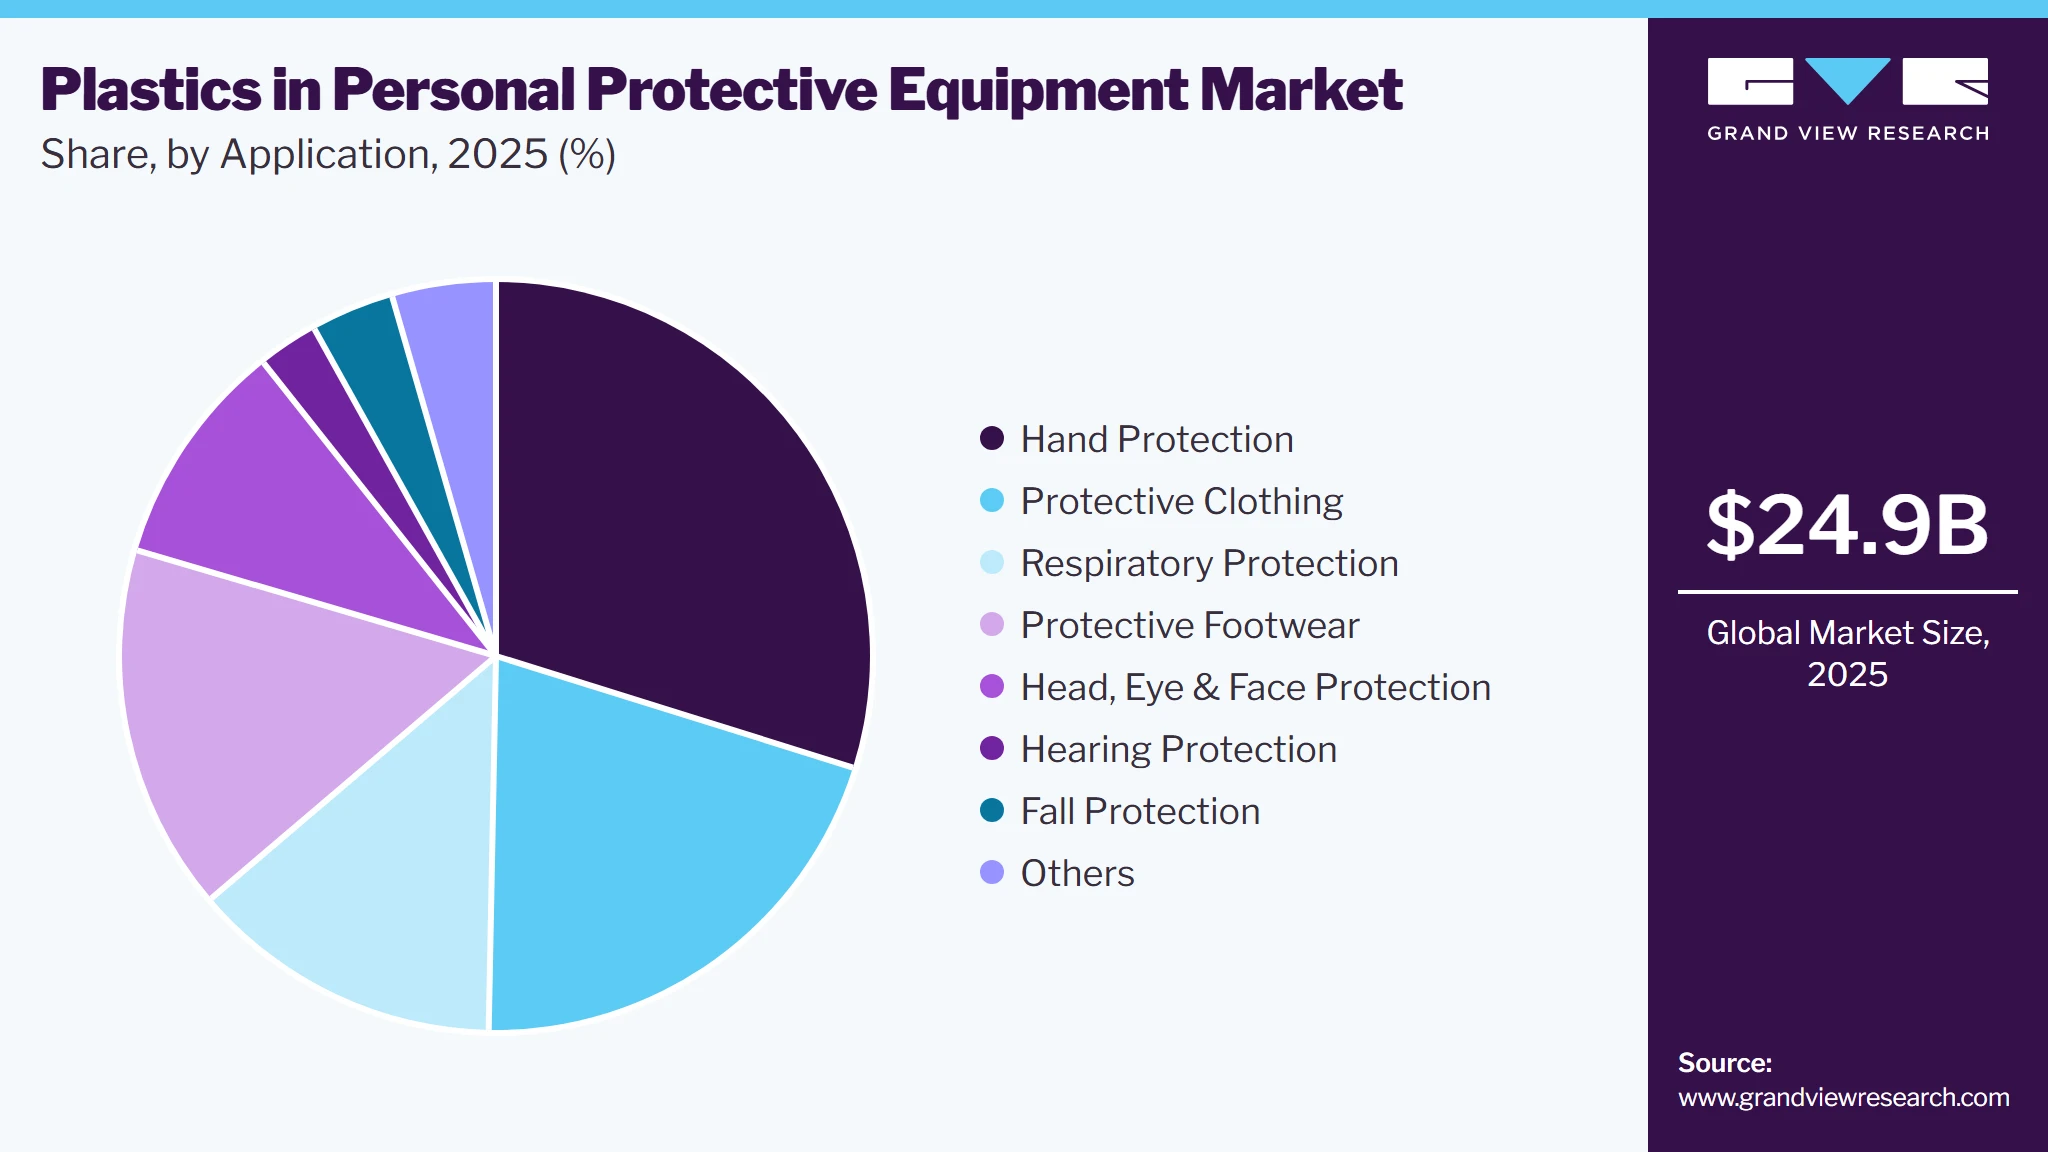
Based on application, the hand protection segment led the market with the largest revenue share of 29.8% in 2025. The demand for plastic-based PPE for hand protection, particularly gloves, has experienced significant growth due to healthcare requirements, industrial growth, safety regulations, and the increased importance of hygiene during the COVID-19 pandemic. For instance, latex, nitrile, and PVC gloves protect against pathogens, bacteria, and viruses, making them indispensable in medical institutions such as hospitals and clinics. Continued advancements in the food processing industry and the need to adhere to various food safety regulations have steadily increased the utilization of these protective accessories. Utilizing nanotechnology, self-disinfecting coatings, or reinforced materials has led to the development of high-performance gloves for intensive industrial and medical environments, aiding segment expansion.
 To learn more about this report, Download Free Sample Report
The respiratory protection segment is expected to grow at the highest CAGR during the forecast period in the plastics in personal protective equipment industry. Increasing sales of face masks and protective face shields among general consumers and their continued widespread use in industrial settings contribute to the extensive use of plastics in making respiratory protective equipment. Key plastics used in respiratory protection accessories include polypropylene (PP), polycarbonate (PC), polyethylene (PE), and polyvinyl chloride (PVC), which provide a balance of durability, comfort, and protection. High-risk industries such as construction, mining, chemicals, oil & gas, and pharmaceutical manufacturing have regulations requiring workers to wear these types of PPE to prevent inhalation of toxic chemicals, dust, fumes, and other airborne hazards. This has led to a steady demand for respiratory PPE, such as N95 respirators, half-mask respirators, and full-face respirators.
Regional Insights
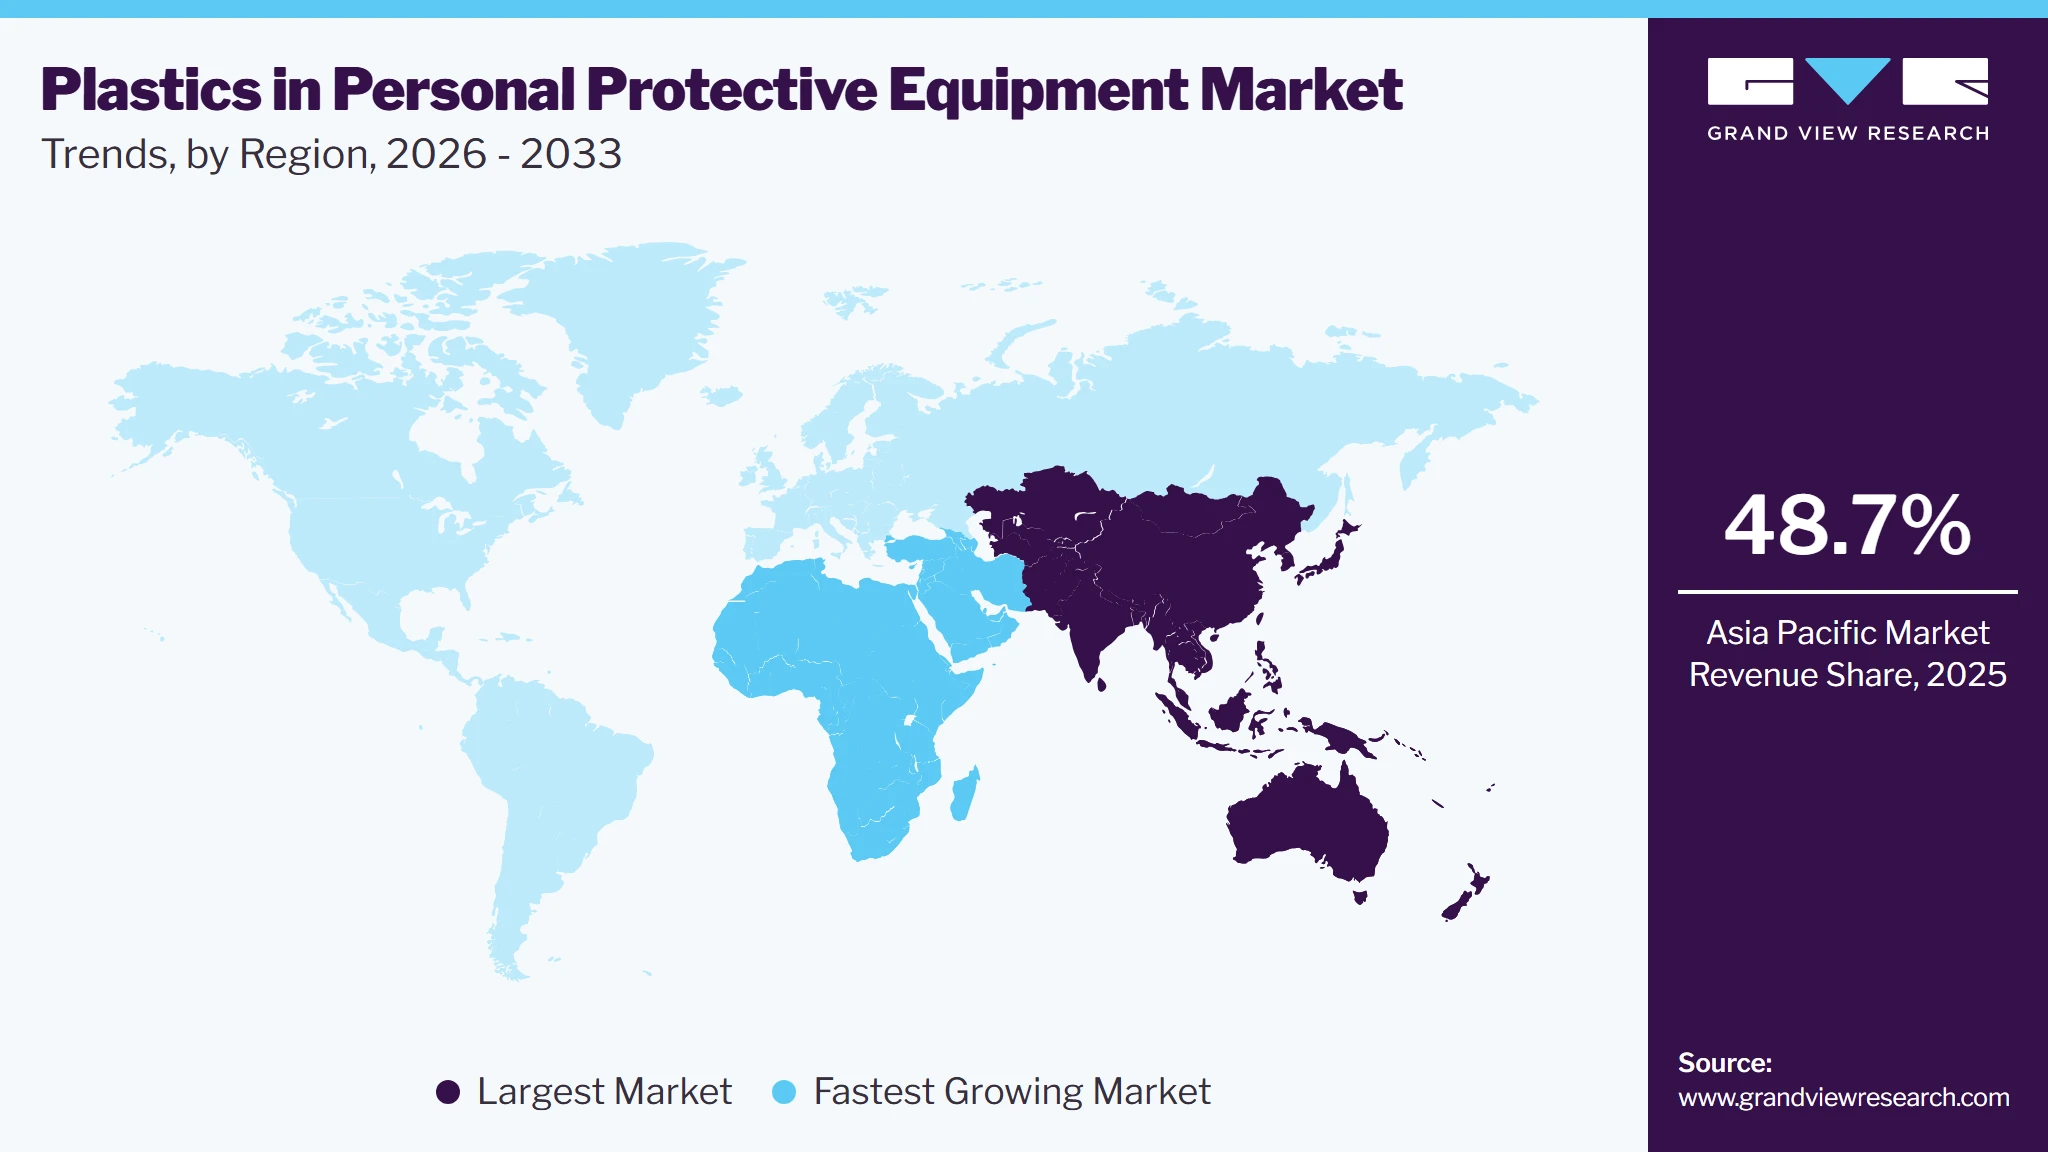
Asia Pacific dominated the plastics in personal protective equipment market with the largest revenue share of 48.7% in 2025. The steadily growing regional population and fast pace of industrialization in economies such as India, China, and South Korea have created a significant demand for PPE, leading to the expansion of the plastics industry. Moreover, many countries are facing the issue of severe air pollution, with cities such as New Delhi and Gurugram (India), Lahore (Pakistan), and Dhaka (Bangladesh) seeing consistently hazardous Air Quality Index (AQI) levels. As a result, consumers have been compelled to use face masks and respirators, creating growth opportunities for manufacturers to incorporate high-quality and durable plastics in their solutions.
 To learn more about this report, Download Free Sample Report
China Plastics in Personal Protective Equipment Market Trends
The plastics in personal protective equipment market in China accounted for the largest market revenue share in Asia Pacific in 2025 and is expected to maintain its position in the coming years. The demand for plastics in PPE has significantly increased in recent years, driven primarily by stringent regulations due to the COVID-19 pandemic, as the economy was one of the worst-affected regions globally. Moreover, the country's rapid industrialization and comprehensive government worker and public safety regulations have enabled industry advancements through product innovations. China is one of the leading global producers and consumers of PPE, thus playing a vital role in both domestic consumption and global supply chains.
North America Plastics in Personal Protective Equipment Market Trends
North America plastics in personal protective equipment market accounted for a substantial revenue share in the global industry in 2025. Plastics such as polyethylene (PE), polyvinyl chloride (PVC), polypropylene (PP), and polycarbonate are widely used in manufacturing various types of PPE due to their cost-effectiveness, performance, and ability to meet safety standards. Furthermore, an increasing push toward recycling and the use of bioplastics in PPE manufacturing have led to a range of innovative developments in this industry in the U.S. and Canada. Recycled plastics, such as recycled polyethylene (rPE) and recycled polypropylene (rPP), are being used to reduce the environmental impact of plastic-based PPE. The extensive use of 3D printing technology to produce large batches of personal protective equipment has further enabled market expansion in this region.
The U.S. plastics in personal protective equipment market accounted for the largest revenue share in the regional market in 2025. Advancements in the material sciences segment, stringent regulatory environment concerning worker safety, and constantly evolving manufacturing practices have resulted in a steady growth of this industry. The U.S. was one of the worst-affected economies during the pandemic, leading to large-scale production of PPE kits across states to protect both citizens and healthcare workers. In recent years, several states and federal agencies have adopted strategies to stockpile PPE for future emergencies. Plastics remain an essential requirement in these strategies due to their low cost and effective performance in protecting against contaminants. Regulatory bodies such as the OSHA and the CDC have set strict standards for PPE used in workplaces and healthcare settings, which has helped shape the market positively.
Middle East & Africa Plastics in Personal Protective Equipment Market Trends
The Middle East & Africa region is expected to grow at the fastest CAGR during the forecast period, aided by significant investments by regional governments in improving healthcare and industrial infrastructure. The growing importance of the healthcare sector has driven a strong demand for plastic-based medical PPE, such as surgical masks, gloves, and protective suits. The extensive presence of petrochemical and oil & gas facilities in this region has further boosted the utilization of protective gear and accessories such as chemical-resistant gloves, face shields, and coveralls. Polyethylene, polypropylene, and PVC are commonly used in these products due to their durability, chemical resistance, and affordability. The continued expansion of the construction sector due to the development of various high-rises and commercial complexes has driven the presence of plastic-based safety gear, such as helmets, safety goggles, gloves, and protective suits, in the market to ensure worker safety.
Saudi Arabia plastics in personal protective equipment market accounted for a substantial revenue share in the Middle East & Africa market in 2025, aided by increasing industrialization in the economy and initiation of various infrastructural projects. Saudi Arabia has been making significant investments in the healthcare segment, which aligns with its Vision 2030 goals to improve healthcare quality and increase the accessibility of healthcare services for its population. This has driven the demand for PPE, particularly solutions such as surgical masks, gloves, and protective clothing. Additionally, the fast pace of development of planned megaprojects such as Qiddiya and NEOM have boosted the construction industry and provided employment to several local and migrant workers. As a result, the need to ensure their safety and welfare has increased the demand for personal protective equipment such as safety goggles, gloves, helmets, and other fall protection equipment.
Key Plastics in Personal Protective Equipment Company Insights
Some major companies involved in the global plastics in personal protective equipment industry include BASF, SABIC, and Celanese Corporation, among others.
-
BASF is a multinational chemical producer that operates through six major segments, including materials, chemicals, industrial solutions, surface technologies, nutrition & care, and agricultural solutions. Through the materials segment, the company is involved in developing and manufacturing performance materials, polyamide raw materials, and monomers. BASF offers a range of products designed to make protective equipment; for instance, the Elastollan thermoplastic polyurethane (TPU) is used in safety footwear, such as the KAMU safety boots. Another notable offering is the Elastopan polyurethane that is used in various components of PPE, including protective gear that requires shock absorption and durability.
-
SABIC (Saudi Basic Industries Corporation) is a global chemical manufacturing company based in Riyadh, Saudi Arabia. The company manufactures and sells products through four major segments: petrochemicals, antinutrients, specialties, and metals. SABIC actively produces plastics for personal protective equipment (PPE), focusing on sustainability and incorporating innovative materials. For instance, it has developed specialized polypropylene melt-blown resins specifically for manufacturing face masks, with these materials complying with N95 standards.
Key Plastics In Personal Protective Equipment Companies
The following key companies have been profiled for this study on the plastics in personal protective equipment market.
-
BASF
-
SABIC
-
Evonik Industries AG
-
Sumitomo Chemical Co., Ltd.
-
Arkema
-
Celanese Corporation
-
Eastman Chemical Company
-
Chevron Phillips Chemical Company LLC
-
Exxon Mobil Corporation
-
Covestro AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF, SABIC, Exxon Mobil Corporation, Chevron Phillips Chemical Company LLC, Sumitomo Chemical Co., Ltd.)
- Broad portfolios of commodity and engineering plastics, including polypropylene (PP), polyethylene (PE), polycarbonate (PC), polyethylene terephthalate (PET), polyamide (PA), thermoplastic polyurethane (TPU), and other specialty polymers serving healthcare, construction, manufacturing, mining, oil & gas, pharmaceuticals, food processing, and industrial personal protective equipment applications.
- Strong emphasis on developing medical-grade, lightweight, high-impact, chemical-resistant, recyclable, and sustainable polymer solutions for disposable and reusable PPE.
- Continuous investments in polymer innovation, advanced resin manufacturing, production capacity expansion, circular economy initiatives, and strategic collaborations with PPE manufacturers, healthcare providers, industrial safety companies, and global distribution partners support market penetration, supply chain resilience, and long-term commercial growth.
- Extensive expertise in polymer science, specialty resin development, and high-volume manufacturing enables the commercialization of high-performance plastics offering superior impact resistance, chemical resistance, fluid barrier protection, durability, lightweight performance, optical clarity, and regulatory compliance.
- Strong research and development capabilities, vertically integrated petrochemical operations, global manufacturing networks, reliable raw material supply, and long-standing relationships with PPE manufacturers and medical device companies support recurring revenue generation and sustained customer retention.
- Advanced quality assurance systems, application development expertise, regulatory certifications, and globally recognized brands provide strong competitive differentiation across healthcare, industrial, and occupational safety markets.
- Dependence on petrochemical feedstocks exposes manufacturers to crude oil price volatility, raw material cost fluctuations, supply chain disruptions, geopolitical uncertainties, and energy cost inflation.
- Significant investments are required to meet increasingly stringent environmental regulations, develop bio-based and recyclable polymers, expand sustainable manufacturing capabilities, maintain regulatory compliance, and support continuous product innovation, resulting in elevated capital and operating expenditures.
- The market is further challenged by intense competition from regional polymer producers, growing customer preference for sustainable PPE materials, evolving circular economy requirements, and increasing adoption of biodegradable and renewable polymer alternatives, which may affect profitability and long-term market share.
Emerging Players (Arkema, Celanese Corporation, Eastman Chemical Company, Covestro AG, Evonik Industries AG)
- Focus on strengthening their position in the plastics in personal protective equipment market through development and commercialization of advanced engineering plastics, specialty polymers, and high-performance materials used in protective applications such as head, eye & face protection, respiratory protection, protective clothing, gloves, footwear, and industrial safety equipment.
- Emphasis is placed on expanding PPE-relevant product portfolios, improving impact resistance, chemical barrier properties, thermal stability, flexibility, and comfort-driven material performance.
- Strategic collaborations with PPE manufacturers, healthcare suppliers, industrial safety firms, and automotive and construction equipment producers support innovation and market penetration.
- Strong capabilities in specialty polymers and engineering materials, enabling the development of high-performance PPE solutions with enhanced durability, chemical resistance, lightweight properties, and user comfort.
- Competitive advantage is strengthened through advanced material science expertise, strong R&D investments, and the ability to deliver application-specific solutions for healthcare, industrial, and hazardous work environments.
- Their established global presence in specialty chemicals and materials innovation supports steady expansion into high-value PPE applications.
- Exposure to raw material price volatility, regulatory compliance pressures, and sustainability-driven material substitution trends may impact margins and operational stability.
- Dependence on cyclical end-use industries and competition from large integrated chemical and commodity polymer producers can limit market share expansion.
- Additionally, relatively lower penetration in mass PPE manufacturing segments compared to established polymer suppliers may restrict large-scale contract wins and volume-driven growth opportunities.
Recent Developments
-
In October 2023, SABIC announced its collaboration with INTELLINIUM, which involved the use of SABIC’S LNP STAT-LOY compound in PPE solutions that are ATEX-certified. LNP STAT-LOY addresses ATEX’s Intrinsic Safety electrical conductivity demands while offering a surface resistivity of 1 GΩ - 100 GΩ to adhere to ATEX directives. The compound further allows a high electrical signal transmission for embedded telecom technologies such as 4G NB-IoT, 4G LTE-M, LoRaWAN, GPS, Bluetooth, and Near Field Communication (NFC).
Plastics In Personal Protective Equipment Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 24.9 billion
Market size value in 2026
USD 29.3 billion
Revenue forecast in 2033
USD 53.0 billion
Growth rate
CAGR of 8.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, Italy, China, Japan, India, Brazil, Saudi Arabia
Key companies profiled
BASF; SABIC; Evonik Industries AG; Sumitomo Chemical Co., Ltd.; Arkema; Celanese Corporation; Eastman Chemical Company; Chevron Phillips Chemical Company LLC; Exxon Mobil Corporation; Covestro AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Plastics In Personal Protective Equipment Market Report Segmentation
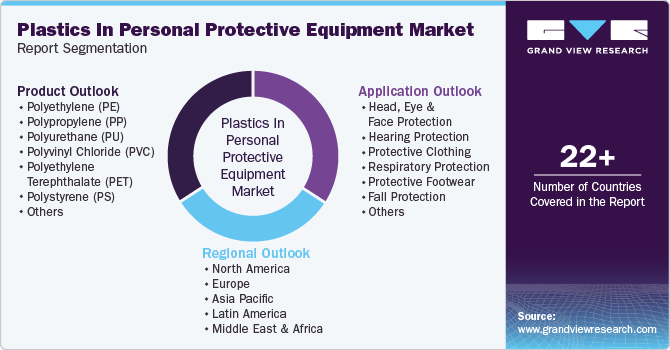
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global plastics in personal protective equipment market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyethylene (PE)
-
Polypropylene (PP)
-
Polyurethane (PU)
-
Polyvinyl Chloride (PVC)
-
Polyethylene Terephthalate (PET)
-
Polystyrene (PS)
-
Acrylonitrile Butadiene Styrene (ABS)
-
Polycarbonate (PC)
-
Polyamide (PA)
-
Polysulfone (PSU)
-
Polyphenylsulfone (PPSU)
-
Acrylic
-
Polyester
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Head, Eye & Face Protection
-
Hearing Protection
-
Protective Clothing
-
Respiratory Protection
-
Protective Footwear
-
Fall Protection
-
Hand Protection
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
MEA
-
Saudi Arabia
-
-
Research Methodology
The plastics in personal protective equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each plastics in personal protective equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Polyethylene (PE)
Revenue is captured through the production and sale of polyethylene-based plastics in personal protective equipment utilized in disposable gloves, isolation gowns, protective aprons, shoe covers, and medical packaging. Demand is driven by excellent chemical resistance, moisture barrier properties, lightweight characteristics, flexibility, and cost-effective large-scale manufacturing.
Polypropylene (PP)
Revenue is captured through the commercialization of polypropylene-based plastics in personal protective equipment used in surgical masks, respirators, protective gowns, face shields, disposable caps, and medical protective apparel. Growth is supported by high filtration efficiency, lightweight construction, fluid resistance, durability, and compatibility with melt-blown and spunbond nonwoven manufacturing processes.
Polyurethane (PU)
Revenue is captured through the supply of polyurethane-based plastics in personal protective equipment utilized in protective gloves, coated garments, footwear, respiratory components, and impact-resistant safety equipment. Demand is driven by superior flexibility, abrasion resistance, wearer comfort, tear strength, and long-term mechanical durability in demanding industrial and healthcare environments.
Polyvinyl Chloride (PVC)
Revenue is captured through the production and sale of PVC-based plastics in personal protective equipment used in disposable gloves, face shields, protective clothing, aprons, chemical-resistant garments, and medical accessories. Growth is supported by excellent chemical resistance, transparency, durability, waterproof performance, and cost-efficient processing for high-volume production.
Polyethylene Terephthalate (PET)
Revenue is captured through the commercialization of PET-based plastics in personal protective equipment utilized in face shields, protective visors, safety goggles, medical barriers, and transparent protective components. Demand is driven by outstanding optical clarity, impact resistance, dimensional stability, recyclability, and lightweight characteristics.
Polystyrene (PS)
Revenue is captured through the supply of polystyrene-based plastics in personal protective equipment used in protective face shield frames, medical accessories, disposable diagnostic components, and laboratory protective products. Growth is supported by lightweight properties, dimensional stability, ease of molding, and cost-effective manufacturing for disposable applications.
Acrylonitrile Butadiene Styrene (ABS)
Revenue is captured through the production and sale of ABS-based plastics in personal protective equipment utilized in reusable respirators, safety helmets, face shield frames, protective eyewear, and industrial safety equipment. Demand is driven by high impact resistance, structural rigidity, dimensional stability, durability, and ease of precision molding.
Polycarbonate (PC)
Revenue is captured through the commercialization of polycarbonate-based plastics in personal protective equipment used in face shields, safety goggles, protective eyewear, helmet visors, and reusable medical protective devices. Growth is supported by exceptional impact strength, optical transparency, heat resistance, and long-term durability under demanding operating conditions.
Polyamide (PA)
Revenue is captured through the supply of polyamide-based plastics in personal protective equipment utilized in safety helmets, respirator components, protective footwear, industrial fasteners, and structural PPE assemblies. Demand is driven by excellent mechanical strength, wear resistance, thermal stability, and superior performance in high-stress environments.
Polysulfone (PSU)
Revenue is captured through the production and sale of polysulfone-based plastics in personal protective equipment used in reusable medical devices, sterilizable face shields, respiratory equipment, and healthcare protective components. Growth is supported by high-temperature resistance, repeated sterilization capability, chemical resistance, and long-term dimensional stability.
Polyphenylsulfone (PPSU)
Revenue is captured through the commercialization of PPSU-based plastics in personal protective equipment utilized in premium reusable medical PPE, surgical protective equipment, respiratory systems, and sterilizable healthcare devices. Demand is driven by exceptional impact strength, high thermal stability, hydrolysis resistance, and compatibility with repeated sterilization cycles.
Acrylic
Revenue is captured through the supply of acrylic-based plastics in personal protective equipment used in protective barriers, sneeze guards, face shield components, medical partitions, and transparent safety enclosures. Growth is supported by superior optical clarity, weather resistance, lightweight construction, and ease of fabrication for protective applications.
Polyester
Revenue is captured through the production and sale of polyester-based plastics in personal protective equipment utilized in protective garments, reusable gowns, high-strength fabrics, industrial workwear, and coated protective textiles. Demand is driven by excellent tensile strength, abrasion resistance, dimensional stability, durability, and compatibility with advanced protective fabric technologies.
Others
Revenue is captured through the commercialization of specialty plastics in personal protective equipment utilized across healthcare, pharmaceutical, food processing, construction, chemical processing, mining, and industrial safety applications. Growth is supported by continuous material innovation, increasing demand for application-specific protective solutions, enhanced regulatory compliance, and expanding adoption of sustainable and high-performance polymer technologies.
Segment - Application
Revenue capture definition
Head, Eye & Face Protection
Revenue is captured through the production and sale of plastic-based personal protective equipment utilized in safety helmets, hard hats, face shields, safety goggles, and protective visors across construction, manufacturing, mining, healthcare, and industrial environments. Demand is driven by high impact resistance, optical clarity, lightweight characteristics, chemical resistance, UV protection, and compliance with workplace safety regulations.
Hearing Protection
Revenue is captured through the commercialization of plastic-based personal protective equipment used in earmuffs, earplugs, and hearing protection devices across manufacturing, construction, mining, aviation, and heavy industrial applications. Growth is supported by superior acoustic insulation, lightweight design, wearer comfort, durability, chemical resistance, and increasing occupational noise safety standards.
Protective Clothing
Revenue is captured through the production and sale of plastic-based personal protective equipment utilized in isolation gowns, coveralls, aprons, protective suits, and chemical-resistant garments across healthcare, pharmaceuticals, laboratories, chemical processing, and industrial facilities. Demand is driven by excellent fluid resistance, chemical protection, durability, lightweight construction, flexibility, and stringent infection control and workplace safety requirements.
Respiratory Protection
Revenue is captured through the supply of plastic-based personal protective equipment used in respirators, disposable masks, powered air-purifying respirators (PAPRs), and breathing apparatus across healthcare, construction, mining, oil & gas, and manufacturing industries. Growth is supported by high filtration efficiency, lightweight materials, chemical resistance, ergonomic design, and increasing emphasis on respiratory health and airborne hazard protection.
Protective Footwear
Revenue is captured through the commercialization of plastic-based personal protective equipment utilized in safety boots, overshoes, toe caps, and slip-resistant footwear across construction, manufacturing, mining, logistics, food processing, and healthcare applications. Demand is driven by impact resistance, chemical resistance, waterproof performance, lightweight properties, abrasion resistance, and compliance with occupational safety standards.
Fall Protection
Revenue is captured through the production and sale of plastic-based personal protective equipment used in safety harnesses, lanyards, connectors, helmet accessories, and fall arrest system components across construction, utilities, telecommunications, and industrial maintenance applications. Growth is supported by high mechanical strength, durability, weather resistance, lightweight construction, and increasing implementation of workplace fall prevention regulations.
Hand Protection
Revenue is captured through the utilization of plastic-based personal protective equipment in disposable gloves, chemical-resistant gloves, cut-resistant gloves, examination gloves, and industrial hand protection products across healthcare, food processing, pharmaceuticals, manufacturing, and chemical industries. Demand is driven by superior barrier protection, puncture resistance, flexibility, chemical resistance, tactile sensitivity, and increasing focus on worker safety and hygiene.
Others
Revenue is captured through the utilization of plastic-based personal protective equipment across protective sleeves, knee pads, arm guards, disposable accessories, emergency response equipment, and specialized industrial safety products. Growth is supported by expanding workplace safety initiatives, technological advancements in polymer materials, increasing regulatory compliance, and growing demand for application-specific protective solutions across diverse end-use industries.
Estimation Model
Layer Name
Key Question
Description
Top-Down Plastics in Personal Protective Equipment Demand Assessment Layer
What defines market boundaries?
This layer begins with global demand for plastic-based personal protective equipment used across healthcare, construction, manufacturing, mining, oil & gas, chemicals, pharmaceuticals, food processing, transportation, and other industrial sectors. Demand is filtered based on workforce size, occupational safety regulations, healthcare infrastructure expansion, industrial production, construction activity, infection prevention requirements, workplace hazard exposure, and increasing adoption of disposable and reusable protective equipment across major end-use industries.
Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across head, eye & face protection, hearing protection, protective clothing, respiratory protection, protective footwear, fall protection, hand protection, and other PPE applications. Market revenue is aligned with critical material performance requirements including impact resistance, chemical resistance, fluid barrier protection, lightweight characteristics, flexibility, durability, thermal stability, wearer comfort, optical clarity, and compliance with stringent occupational safety, healthcare, and industrial protection standards.
Product Material Conversion Layer
Who captures market revenue?
This layer converts application-level demand into plastics in personal protective equipment revenue by applying product material mix ratios across polypropylene (PP), polyethylene (PE), polyvinyl chloride (PVC), polyethylene terephthalate (PET), polycarbonate (PC), acrylonitrile butadiene styrene (ABS), thermoplastic polyurethane (TPU), and other engineering plastics. Revenue allocation considers material pricing, barrier performance, impact strength, chemical resistance, manufacturing complexity, product specifications, regulatory compliance, technological innovation, and supplier positioning across the global plastics in personal protective equipment value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific's leadership in manufacturing, healthcare infrastructure expansion, industrialization, and workforce growth; North America's strong demand driven by stringent workplace safety regulations, advanced healthcare systems, and high PPE consumption; and Europe's emphasis on worker protection, environmental sustainability, and regulatory compliance. It also evaluates emerging opportunities across Latin America, the Middle East, and Africa, supported by expanding healthcare investments, industrial development, mining activities, construction projects, and increasing adoption of plastic-based personal protective equipment across developing economies.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The Plastics in Personal Protective Equipment market was segmented across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, with further breakdown based on key demand centers such as healthcare infrastructure, industrial manufacturing hubs, construction activity, and chemical processing clusters. Regional consumption patterns were mapped against regulatory intensity, industrial safety standards, and adoption of advanced PPE materials.
Enables clear visibility of high-growth geographies and demand hotspots, supports region-specific strategy development, and helps identify localized regulatory and procurement dynamics influencing PPE material adoption.
Cross-segmentation
Demand was analyzed by integrating application segments (head, eye & face protection, respiratory protection, protective clothing, gloves, footwear, fall protection, and others) with products such as polypropylene, polyethylene, PVC, PET, and engineering plastics. Cross-segmentation also incorporated end-use industries, including healthcare, construction, oil & gas, manufacturing, and mining.
Provides a deeper understanding of intersectional demand drivers, identifies high-value product–application combinations, and supports targeted product positioning and portfolio optimization for PPE manufacturers.
Opportunity assessment
Growth opportunities were identified across sustainable bioplastics, antimicrobial polymers, recyclable PPE materials, and advanced engineering plastics for high-performance protective applications. Emerging demand from healthcare expansion, industrial safety regulations, and sustainable manufacturing initiatives was evaluated across global markets.
Highlights innovation-driven growth areas, supports R&D prioritization, and enables strategic investment decisions in next-generation PPE materials and sustainable product development.
Frequently Asked Questions About This Report
Based on application, the Hand Protection segment accounted for the largest share of 29.8% market size in 2025. Growing emphasis on occupational safety, hygiene compliance, and protection against chemical and biological hazards is driving the adoption of plastics in personal protective equipment in hand protection applications due to their ability to provide superior barrier resistance, chemical stability, flexibility, and durable mechanical performance.
The plastics in personal protective equipment market was valued at USD 24.9 billion in the year 2025 and is estimated at around USD 29.3 billion in 2026.
Some of the key players operating in the plastics in plastics in personal protective equipment market include BASF SE; SABIC; Evonik Industries AG; Sumitomo Chemical Co., Ltd.; Arkema; Celanese Corporation; Eastman Chemical Company; Chevron Phillips Chemical Company; Exxon Mobil Corporation; and Covestro AG.
The Asia Pacific Plastics in Personal Protective Equipment market accounted for the largest share of 48.7% market size in 2025.
China was the leading country in the Asia Pacific Plastics in Personal Protective Equipment market in 2025 and is expected to grow at a compound annual growth rate of 9.1%.
The respiratory protection segment, based on application, is expected to grow at a CAGR of 9.6% for the forecast period.
The plastics in personal protective equipment market is expected to grow at a compound annual growth rate of 8.8% from 2026 to 2033 to reach around USD 53.0 billion by 2033.
The Polyethylene (PE) led the plastics in personal protective equipment market in 2025 with a 24.4% share. Growing demand for lightweight, cost-efficient, and high-performance protective materials across healthcare, construction, manufacturing, chemical handling, and food processing industries is driving the adoption of polyethylene (PE) in the plastics in personal protective equipment market
Growing emphasis on workplace safety, continuous advancements in polymer technologies, and increasingly stringent regulatory standards are driving the growth of the plastics in personal protective equipment market.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


