
- Home
- »
- Electronic Devices
- »
-
Power Management System Market Size Report, 2026-2033GVR Report cover

Power Management System Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component, By Application (Load Shedding & Management, Power Control & Monitoring, Generator Control), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$7.8BMarket Estimate, 2026
$8.4BMarket Forecast, 2033
$14.8BCAGR, 2026–2033
8.4%Power Management System Market Summary
The global power management system market size was valued at USD 7.8 billion in 2025 and is projected to grow from USD 8.4 billion in 2026 to USD 14.8 billion by 2033, at a CAGR of 8.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 32.0% in 2025. Factors such as the increasing importance of energy efficiency across industries and growing environmental sustainability awareness drive the demand for power management systems. Moreover, the rising adoption of sustainable and renewable energy sources, such as solar and wind power, presents significant growth opportunities for the market as it requires advanced power management systems to integrate and manage fluctuating renewable energy inputs.
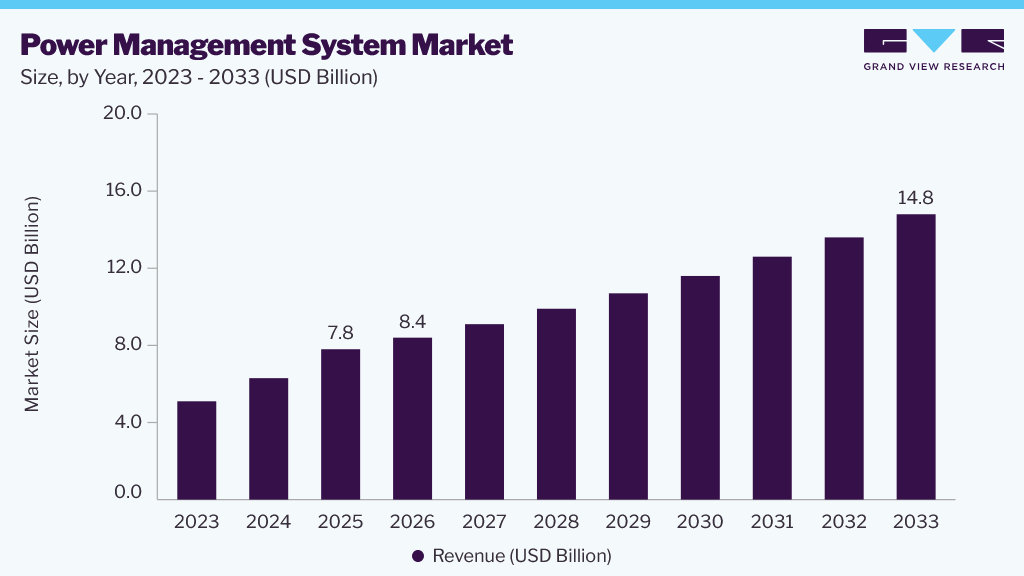 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The hardware segment held the largest market share of over 63.0% in 2025.
- By application: The load shedding & management segment held the largest market share in 2025.
- By end use: The oil & gas segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (32.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 7.8 Billion
- Estimated market size in 2026: USD 8.4 Billion
- Projected market size by 2033: USD 14.8 Billion
- CAGR (2026-2033): 8.4%
Prism AI by Grand View Research Free to tryAsk a question about the power management system marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Businesses and consumers are increasingly adopting solutions that optimize energy consumption, minimize waste, and reduce operational costs. At the same time, government regulations and policy initiatives promoting energy efficiency are accelerating the deployment of advanced power management systems across industrial, commercial, and utility applications. Modern power management systems leverage real-time monitoring, predictive analytics, and intelligent control capabilities to improve energy utilization, enhance operational reliability, and support sustainability objectives. According to the International Energy Agency (IEA), global investments in energy efficiency reached approximately USD 660 billion in 2024, representing an increase of nearly 50% since 2019. Furthermore, governments accounting for more than 70% of global energy demand have introduced or strengthened energy efficiency policies, creating a favorable environment for the adoption of advanced power management and energy optimization solutions.There is a growing expectation for an uninterrupted power supply to ensure the continuous operation of businesses and homes. However, severe storms, aging infrastructure, complex electrical distribution systems, and expanding distributed energy networks increase the risk of grid instability and power disruptions. To address such issues, IoT-enabled sensors, electrical meters, smart breakers, and other intelligent equipment are needed to continuously monitor electrical conditions. Combining digital technologies with power management systems enhances efficiency, reduces downtime, and enables rapid decision-making.
Analyst Perspective
The global power management system market is expected to witness steady growth, driven by the increasing demand for energy optimization, smart grid modernization, and the integration of renewable energy sources into power networks. Rising adoption of automation, Industrial IoT (IIoT), and digital monitoring solutions across industrial, commercial, and utility sectors is further accelerating market expansion. Organizations are increasingly investing in advanced power management systems equipped with real-time monitoring, predictive analytics, and intelligent control capabilities to improve energy efficiency, enhance grid reliability, minimize operational downtime, and optimize asset performance. In addition, supportive government initiatives promoting energy efficiency, grid resilience, and decarbonization are expected to create significant growth opportunities for the market over the forecast period.
Component Insights
The hardware segment led the market with the largest revenue share, over 63.0%, in 2025 and is expected to dominate the industry over the forecast period. The demand for power management systems is rising due to the growing adoption of automation across industries. Sensors, meters, and controllers are essential hardware components in automation systems. Governments worldwide are implementing regulations and initiatives to promote energy efficiency and reduce carbon emissions, increasing the demand for power management systems. Also, the hardware segment in the market is expected to grow due to the increasing adoption of automation in the industry, such as using Artificial Intelligence (AI), the Internet of Things (IoT), and cloud platforms.
The software segment is expected to witness the fastest CAGR during the forecast period. The software segment is expected to grow due to the adoption of automation in industry, IoT, and cloud platforms worldwide. Software in power management systems is used for various applications, such as performance monitoring, load profiling and scheduling, outage scheduling, maintenance and inspection, optimal power flow, automatic generation control and dispatch, data security, and others. The software can also be used for supervisory control and data acquisition (SCADA), advanced distribution management systems (ADMS), outage management systems (OMS), generation management systems (GMS), and other applications.
Application Insights
The load shedding & management segment held the largest revenue share in 2025. Load shedding and management in a power system involve various strategies and technologies that help balance the supply and demand of electricity. It is used during periods of high demand or when the system is unstable. The process includes temporarily disconnecting some loads from the grid to prevent a complete blackout and maintain system stability. Load shedding refers to reducing total electricity consumption for a specific site, while load shifting involves using the same amount of power at different times. Controlled brownouts are intentional reductions or power cuts to prevent supply failure. Load shifting helps integrate intermittent renewable energy sources by linking energy consumption to periods of high generation.
The European Union (EU) aims to reduce final energy consumption by at least 11.7% compared with the projected 2030 energy use. On July 25, 2023, the EU completed the legislative process to strengthen the Energy Efficiency Directive. The new legislation, with the updated binding target, was enforced in all EU countries on October 10, 2023. The goal of this target is to lower the EU's final energy consumption by 11.7% by the year 2030, as compared to the estimated energy usage for 2030, based on the 2020 reference scenario.
The power control & monitoring segment is expected to witness the fastest CAGR during the forecast period. Power control and monitoring involve a network of meters connected to the internet, providing real-time data on the facility's power system. It utilizes online software to identify potential problems in the electrical system. Power monitoring is growing due to the increasing focus on efficient power utilization and industrialization, as well as the need to maximize the reliability of the electricity infrastructure. The implementation of power monitoring systems has risen due to the increasing adoption of smart grid technologies and a focus on industrial development. Furthermore, the growing trend in digitalization and cloud computing has become a significant driver for commercial and industrial power monitoring and control.
End Use Insights
By end use, the oil & gas segment held the largest revenue share in 2025 and is projected to grow at a significant CAGR over the forecast period. The increased global demand for energy has led to a rise in oil exploration and production activities in remote and challenging environments. Power interruptions during these operations can result in significant financial losses, so the industry is prioritizing advanced power management solutions. These systems ensure a continuous power supply, incorporate emergency shutdown systems, adhere to regulatory standards, and reduce the environmental carbon footprint by integrating renewable energy sources. Adopting advanced technologies for monitoring, analytics, and optimizing energy usage further drives the industry's continued growth in the market.
According to the U.S. Energy Information Administration (EIA), the global oil demand is expected to rise by 3%-10% by 2030 and by 6%-42% by 2050, compared with 2022. The case of High Economic Growth shows the most significant increase in global oil demand, and global oil production is set to reach approximately 120 million barrels per day by 2050.
The IT & data centers segment is expected to witness the fastest CAGR during the forecast period. The demand for digital services, cloud computing, and data storage has led to the growth of the IT & Data centers segment in the power management market. Efficient power management systems are vital for data centers to ensure a reliable power supply, optimize energy usage, and reduce operational costs. Power management solutions are also essential in achieving energy efficiency, reducing carbon footprint, and meeting environmental standards. Adopting power management technologies is vital for companies striving to enhance their corporate social responsibility.
Regional Insights
The power management system industry in North America dominated the global market, accounting for around 32.0% of revenue in 2025. The regional market is driven by the widespread adoption of smart grid technologies, the rapid digitalization of power infrastructure, and the increasing deployment of IoT-enabled energy management solutions across the industrial, commercial, and utility sectors. Rising investments in grid modernization, data center infrastructure, and electrification projects are further accelerating demand for advanced power management systems. For instance, in September 2025, ABB announced an investment of approximately USD 110 million to expand its U.S. manufacturing and research & development capabilities for advanced electrification solutions. The investment will enhance the production of circuit breakers, switching devices, and power protection technologies for data centers, utilities, and industrial applications, strengthening the regional power management ecosystem.
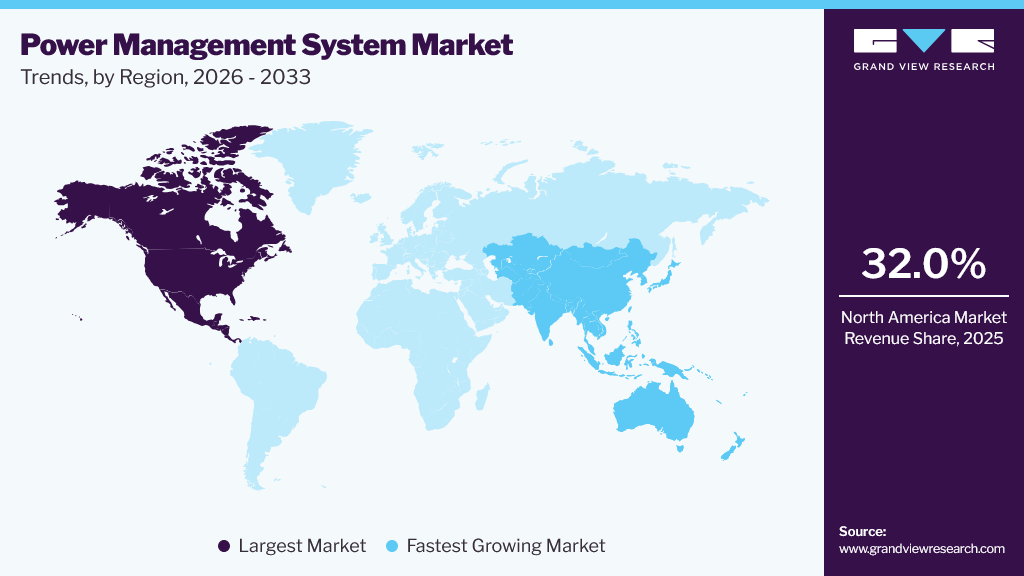 To learn more about this report, Download Free Sample Report
U.S. Power Management System Market Trends
The power management system industry in the U.S. accounted for the largest share of the North American market in 2025. Market growth is supported by the increasing emphasis on energy efficiency, grid resilience, and the modernization of aging electrical infrastructure. Rising electricity demand, expansion of renewable energy capacity, and growing investments in smart grid technologies are driving the adoption of intelligent power management solutions across utilities and industrial facilities. In addition, increasing concerns over climate change and the growing frequency of extreme weather events are encouraging investments in resilient power infrastructure, advanced monitoring systems, and distributed energy resources, further supporting the demand for power management systems across the country.
Europe Power Management System Market Trends
The power management system industry in Europe is driven by the rapid adoption of cloud computing. Increasing demand for cloud services is driving the expansion of data centers and accelerating the adoption of IoT-enabled and cloud-based power management platforms. As organizations continue to migrate their IT infrastructure to the cloud, the need for reliable, energy-efficient, and intelligent power management solutions is rising. Furthermore, the expansion of cloud infrastructure is creating opportunities for advanced power monitoring, energy optimization, and efficient power distribution, enabling data center operators to enhance operational efficiency, reduce energy consumption, and improve overall infrastructure reliability.
The power management system industry in the UK is expected to grow at a healthy CAGR over the forecast period. The UK's focus on electric vehicles (EVs) and the expanding EV market increased demand for power management systems. Smart power management is necessary to efficiently handle the rising electricity demand from the charging infrastructure for electric vehicles. The growth of the EV market is anticipated to create more opportunities for power management system manufacturers as the demand for energy management systems and efficient charging infrastructure is expected to grow.
Germany power management system industry dominated the global market in Europe. The growth of renewable energy sources is expected to drive the demand for power management systems, which can optimize energy consumption based on weather forecasts. Therefore, the reduction in energy consumption and the expansion of renewable energy sources in Germany are expected to drive the country's market growth. In January 2024, Germany announced plans to reduce energy consumption in the private and public sectors by 26.5% by 2030. Reducing energy consumption requires implementing energy-efficient solutions, including adopting power management systems. Moreover, the German government aims to increase the share of renewables in electricity generation to 65% by 2030, a target the requires expanding transmission and distribution infrastructure and improving taxation and market regulation.
Asia Pacific Power Management System Market Trends
The power management system industry in Asia Pacific is anticipated to grow at the fastest CAGR during the forecast period. The Asia Pacific market is growing due to the integration of advanced systems that handle the variability and intermittency associated with renewable energy sources such as solar and wind. There is an increasing investment in renewable energy sources across the region due to environmental concerns and to reduce dependence on fossil fuels.
China power management system industry dominated the regional market in 2025. China's Industrial Internet of Things (IIoT) significantly drives the market growth. The country's Industry 4.0 initiatives, centered on the digital transformation of manufacturing, rely heavily on IIoT technologies. Power management systems are essential to these initiatives, providing the infrastructure for efficient, intelligent energy management in smart factories.
The power management system industry in Japan is expected to grow steadily over the forecast period. The growth of the market in Japan is attributed to microgrid implementation, which enhances disaster resilience, given Japan's susceptibility to earthquakes and tsunamis. With its mountainous terrain and remote areas, Japan is exploring microgrid solutions to ensure a reliable power supply. Power management systems are integral to the effective operation of microgrids, optimizing energy flow and supporting decentralized energy generation in remote locations.
Middle East & Africa Power Management System Market Trends
The power management system industry in MEA is driven by the need for energy efficiency and grid resilience, which is driving investments in modernizing power distribution systems in the MEA region. With growing concerns about energy security, climate change, and natural disasters, there is a heightened focus on enhancing the efficiency, reliability, and resilience of power grids. Utilities are deploying advanced metering infrastructure (AMI), distribution automation systems, and grid monitoring technologies to optimize energy distribution, detect and respond to outages, and improve system reliability. Additionally, the adoption of distributed energy resources (DERs) such as rooftop solar panels, battery storage systems, and microgrids is decentralizing power generation and distribution, making power systems more resilient to disruptions and enabling greater energy independence for consumers and communities.
Saudi Arabia’s power management system industry is expected to grow at a significant CAGR over the forecast period. The development of smart cities and the adoption of smart grids significantly drive growth in the power management system market in Saudi Arabia. Power management systems play an essential role in the infrastructure of smart cities by ensuring that energy is used efficiently in smart buildings, transportation systems, and urban services. The country implemented a new smart-cities strategy to transform municipal and residential services into smart services through digital technologies and the Internet of Things (IoT).
Key Power Management System Company Insights
Some of the key players operating in the market include ABB, General Electric, Siemens, Eaton, Schneider Electric, Emerson Electric Co., OMRON Corporation, and others.
-
ABB's offerings include advanced grid automation technologies, substation automation solutions, SCADA systems for real-time monitoring and control, energy management systems for optimizing energy consumption, microgrid solutions for localized energy systems, digital substation technologies leveraging digital advancements, power quality solutions addressing voltage fluctuations and harmonics, as well as energy storage systems to integrate renewable sources and enhance grid stability.
-
Eaton offers a comprehensive set of solutions for efficient and reliable power management. Their portfolio includes electrical distribution and control systems; power quality solutions, including UPS systems and surge protection; backup power solutions with generators and transfer switches; and monitoring and management tools to optimize power usage. Eaton's capability extends to energy storage solutions, microgrid implementations for localized power systems, and smart grid technologies that enhance grid efficiency.
-
Emerson Electric Co. offers solutions for electrical distribution, monitoring, and energy management, contributing to enhanced efficiency and reliability in electrical systems. Emerson's portfolio extends to critical applications, including UPS systems, data center solutions encompassing precision cooling and power distribution units, and services to improve the reliability of electrical infrastructure.
-
OMRON Corporation provides equipment for monitoring electric power to aid in energy conservation, as well as sensing and control equipment for environmental monitoring in clean rooms. It includes advanced automation and control systems, such as programmable logic controllers (PLCs), human-machine interface (HMI) devices, and energy management solutions, which help optimize power consumption and improve overall efficiency.
Key Power Management System Companies
The following key companies have been profiled for this study on the power management system market:
-
ABB
-
General Electric
-
Siemens
-
Eaton
-
Schneider Electric
-
Emerson Electric Co.
-
MITSUBISHI HEAVY INDUSTRIES, LTD.
-
Rockwell Automation
-
Honeywell International Inc.
-
Fuji Electric Co., Ltd.
-
LARSEN & TOUBRO LIMITED.
-
OMRON Corporation
Recent Developments
-
In March 2026, Eaton Corporation plc completed the acquisition of Boyd Thermal to strengthen its data center solutions portfolio. By integrating Boyd Thermal's advanced liquid cooling technologies with Eaton's power management expertise, the acquisition enhances the company's ability to deliver energy-efficient, high-performance power infrastructure for AI-driven and hyperscale data centers.
-
In July 2026, VoltServer and Eaton Corporation plc formed a strategic partnership to advance next-generation power distribution solutions. The collaboration combines Eaton’s power management expertise with VoltServer’s Digital Electricity technology to develop more efficient and scalable power delivery systems.
-
In June 2025, Eaton Corporation plc and Siemens Energy announced a strategic partnership to accelerate data center deployment through integrated power generation and electrical infrastructure solutions. The collaboration focuses on delivering scalable power systems, grid-independent energy solutions, and advanced power management technologies to support the rapidly growing power requirements of AI and cloud computing facilities.
-
In January 2025, Chevron, Engine No. 1, and GE Vernova announced plans to develop up to 4 GW of dedicated power infrastructure for U.S. data centers. The initiative aims to provide reliable, scalable, and efficient power solutions to meet the increasing electricity demand driven by artificial intelligence, cloud computing, and digital transformation, supporting the adoption of advanced power management systems.
Power Management System Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.8 billion
Estimated market size in 2026
USD 8.4 billion
Projected market size by 2033
USD 14.8 billion
Growth rate
CAGR of 8.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, application, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Netherlands; China; India; Japan; Australia; South Korea; Brazil; Mexico; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
ABB; General Electric; Siemens; Eaton; Schneider Electric; Emerson Electric Co.; MITSUBISHI HEAVY INDUSTRIES, LTD.; Rockwell Automation; Honeywell International Inc.; Fuji Electric Co., Ltd.; LARSEN & TOUBRO LIMITED; OMRON Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Power Management System Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the power management system market report based on component, application, end use, and region:
- Component Outlook (Revenue, USD Billion, 2021 - 2033)
- Hardware
- Controllers
- Sensors
- Switches, Relays, & Gateways
- Others
- Software
- Supervisory Control & Data Acquisition (SCADA)
- Advanced Distribution Management Components (ADMS)
- Outage Management Component (OMS)
- Generation Management Components (GMS)
- Others
- Services
- Hardware
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Load Shedding & Management
- Power Control & Monitoring
- Generator Control
- Switching and Safety Management
- Power Simulator
- Energy Cost Accounting
- Data Historian
- Others
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Oil & Gas
- Marine
- Metal & Mining
- Chemical & Petrochemical
- IT & Data Centers
- Utilities
- Paper & Pulp
- Others
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- Italy
- France
- Spain
- Netherlands
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- UAE
- Saudi Arabia
- South Africa
- North America
Frequently Asked Questions About This Report
The hardware segment accounted for the largest revenue share of over 63.0% in 2025.
Key players in the market include ABB, General Electric, Siemens, Eaton, Schneider Electric, Emerson Electric Co., MITSUBISHI HEAVY INDUSTRIES, LTD., Rockwell Automation, Honeywell International Inc., Fuji Electric Co., Ltd., LARSEN & TOUBRO LIMITED, OMRON Corporation, and others.
The global power management system market size was valued at USD 7.8 billion in 2025 and is estimated at USD 8.4 billion for 2026.
The global power management system market is expected to grow at a CAGR of 8.4% from 2026 to 2033, reaching USD 14.8 billion.
North America dominated with approximately 32.0% revenue share in 2025.
About the Author(s)
Electronic Devices Research Team
Semiconductors & Electronics · Electronic DevicesThis report was authored by the electronic devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic devices segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


