
- Home
- »
- Consumer F&B
- »
-
Ready To Drink Coffee Market Size And Share Report, 2033GVR Report cover

Ready To Drink Coffee Market (2026 - 2033)
Size, Share & Trends Analysis Report By Packaging (Bottles, Cans, Cartons), By Nature (Conventional, Organic), By Distribution Channel (B2B, B2C), By Region (North America, APAC, Europe), And Segment Forecasts
Market Size, 2025
$31.4BMarket Estimate, 2026
$33.6BMarket Forecast, 2033
$49.0BCAGR, 2026–2033
5.6%Ready To Drink Coffee Market Summary
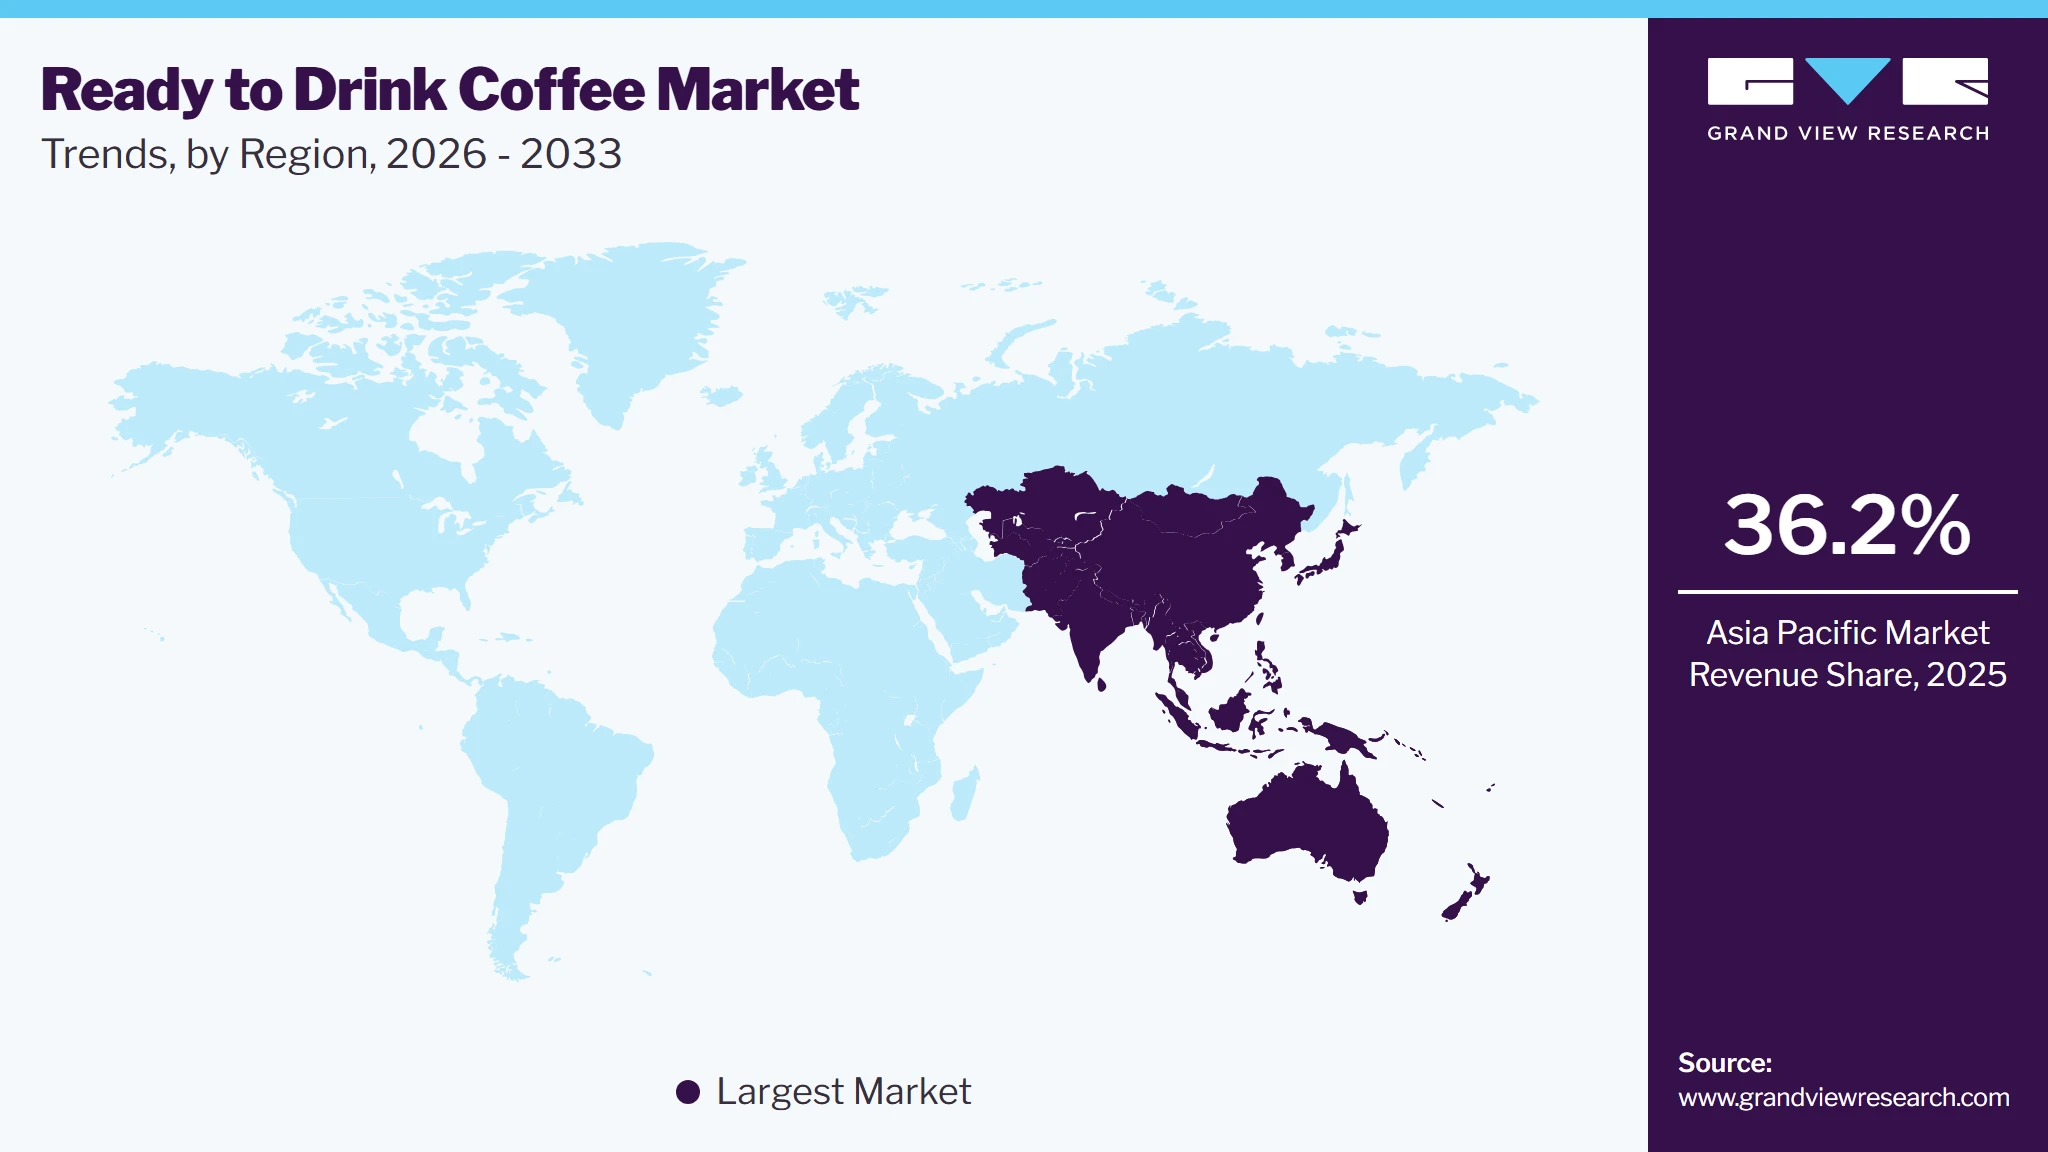
The global ready to drink coffee market size was valued at USD 31.4 billion in 2025 and is projected to grow from USD 33.6 billion in 2026 to USD 49.0 billion by 2033, at a CAGR of 5.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 36.2% in 2025. The market is expected to grow owing to factors such as increased adoption of coffee culture, lifestyle changes, busy schedules, which are increasing demand for ready-to-drink beverages, and a rise in health-conscious consumers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By packaging: Cans segment led the market with the largest revenue share of 43.4% in 2025.
- By nature: Conventional RTD coffee segment led the market with the largest revenue share of 95.5% in 2025.
- By distribution channel: B2C segment led the market with the largest revenue share of 79.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (36.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 31.4 Billion
- Estimated market size in 2026: USD 33.6 Billion
- Projected market size by 2033: USD 49.0 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, companies are constantly innovating the product by introducing new flavors to enhance its appeal to consumers across boundaries, which, in turn, are contributing to the market growth of RTD coffee. Lifestyle changes, busy routines, and increased Western influence contribute to the growth of the market. These factors have augmented coffee culture adoption, contributing to market growth. This augmented adoption of the culture and high demand for coffee encourages companies and brands to serve cold beverages that appeal to most consumers. This growth in demand is further fueled by the evolution of e-commerce and social media platforms, which are attracting young consumers to ready-to-drink coffee. Moreover, due to the health benefits of coffee, such as its rich source of antioxidants and low-calorie alternatives, the category has attracted a rising number of health-conscious consumers, which helps in the market growth of RTD coffee.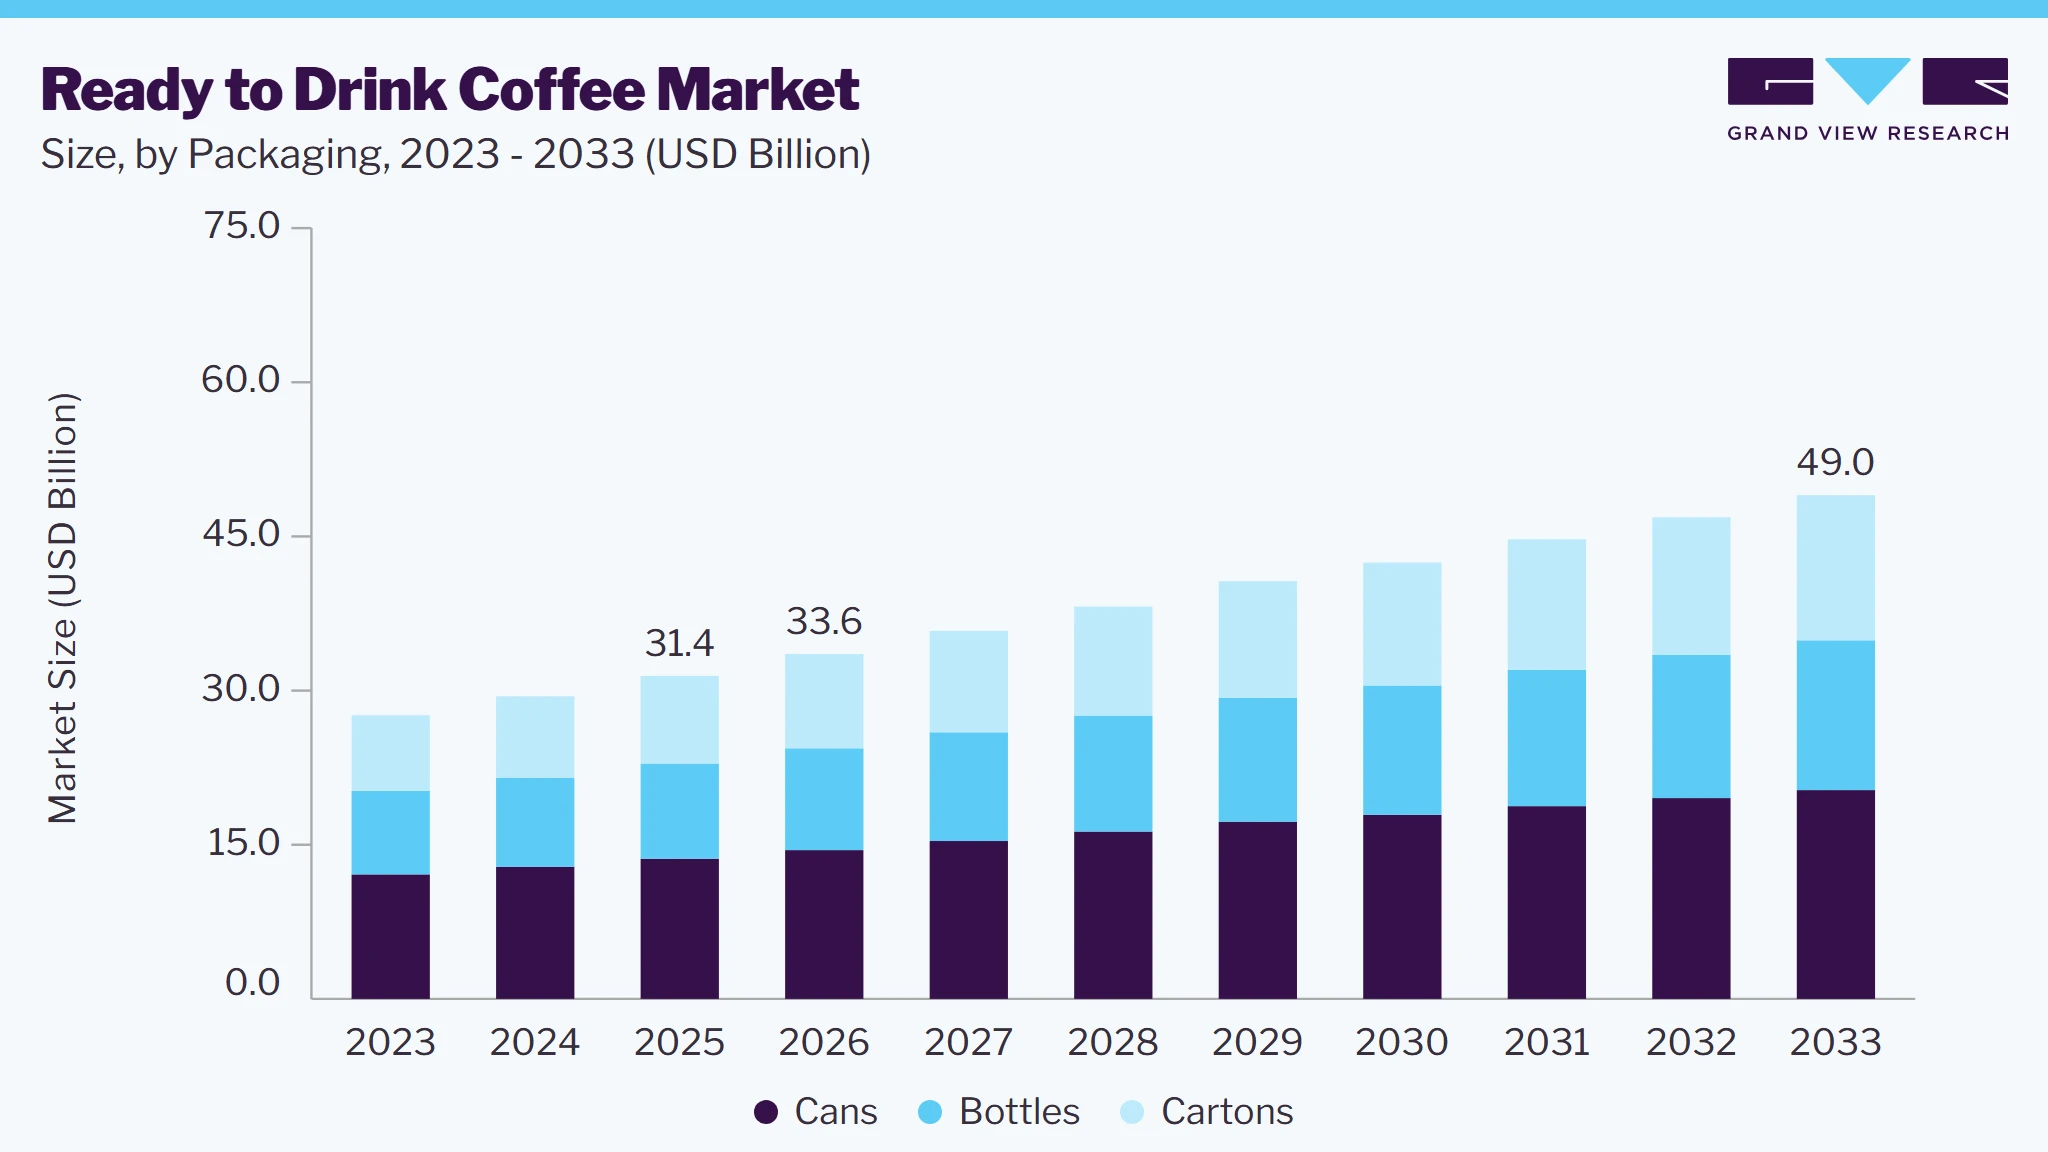 To learn more about this report, Download Free Sample Report
The increasing population of millennials and Gen Z is a significant factor in the market growth of RTD coffee. According to the Qureos data published in August 2024, the Gen Z population represents nearly 32% of the global population. To meet the evolving needs and demands of young consumers, the brands are introducing ready-to-drink beverages in the market. For instance, according to the BeverageDaily article published in January 2023, Gen Z consumers are inclined towards ready-to-drink coffee compared to traditional hot brew coffee. Such rising evolution, coupled with high coffee consumption, is expected to boost market growth.
The evolving lifestyles and busy routine lifestyles have given rise to health-conscious consumers. This rise in health awareness has created an opportunity for companies to formulate healthy alternatives to the beverage, resulting in higher coffee consumption daily. For instance, according to Levista data published in February 2024, over 2.25 billion people consume coffee as it improves productivity and focus. In addition, the antioxidant in coffee enhances its consumption; for instance, according to the MedicineNet, Inc. data published in March 2023, coffee aids colon digestion, reducing the hazardous impact of carcinogenic compounds on colon tissue. Thus, the lifestyle changes and health benefits of coffee make it a suitable alternative for health-conscious consumers.
The market growth is expected to rise owing to factors such as increased health-conscious consumers, lifestyle changes, and a growing population of young consumers, thereby augmenting the demand for RTD coffee. The rising demand for coffee is encouraging companies to innovate coffee into attractive choices. The RTD coffee is available in the market with a wide array of options, including classic coffee, French vanilla variant, hazelnut coffee, and salted caramel, to name a few. The key players in the category are innovating and launching attractive new products to enhance their appeal to consumers. For instance, in July 2024, Starbucks Corporation launched a new ready-to-drink protein drink imbibed with coffee, attracting health-conscious consumers. The drink is available in scrumptious flavors, including caffe latte, chocolate mocha, and caramel hazelnut. Such product innovations are expected to strengthen the market growth in the RTD coffee category.
Market Dynamics
The ready-to-drink (RTD) coffee market is experiencing steady growth, driven by increasing consumer demand for convenient, on-the-go beverage options and a growing preference for premium coffee products. Rising health consciousness has encouraged manufacturers to introduce low-sugar, organic, and functional RTD coffee variants enriched with protein, vitamins, and other nutritional ingredients. Continuous innovations in flavors, packaging, and cold brew formulations are helping brands attract a broader consumer base. Additionally, expanding retail distribution channels, including supermarkets, convenience stores, and e-commerce platforms, is enhancing product accessibility and supporting market expansion. Investments in product development and sustainable packaging solutions are further strengthening competition and creating long-term growth opportunities in the global RTD coffee market.
The rising demand for convenient, on-the-go beverage options is a key driver for the Ready-to-Drink (RTD) coffee market. Busy lifestyles, longer working hours, and increasing travel time have encouraged consumers to seek beverages that are easy to carry and consume without preparation. RTD coffee offers a quick and hassle-free solution, providing both refreshment and caffeine in a portable format. Its availability across retail stores, convenience outlets, and online channels further supports its growing popularity among consumers seeking convenience and flexibility. In March 2026, Starbucks launched its new Coffee & Protein ready-to-drink range, combining coffee with added protein, prebiotic fiber, vitamins, and minerals to cater to consumers seeking convenient wellness-focused beverages.
High product prices compared to traditional brewed coffee act as a restraint on the RTD coffee market. RTD coffee products often include costs related to packaging, processing, branding, and distribution, making them more expensive than freshly brewed coffee prepared at home or purchased from local cafés. Price-sensitive consumers may be reluctant to pay a premium for convenience, especially in markets with abundant low-cost coffee alternatives. This pricing gap can limit product adoption and reduce purchase frequency among budget-conscious consumers.
The RTD coffee market is experiencing strong growth opportunities as manufacturers expand their presence across supermarkets, convenience stores, vending machines, online retail platforms, and quick-commerce channels. Wider product availability is making RTD coffee more accessible to consumers seeking convenient and ready-to-consume beverages. The growing penetration of digital retail channels is also enabling brands to reach new customer segments and offer a broader range of products. Additionally, investments in innovative packaging, premium formulations, and functional coffee variants are enhancing consumer appeal and supporting market expansion.
Analyst Perspective
The ready-to-drink (RTD) coffee market is witnessing steady expansion, driven by increasing consumer preference for convenient, on-the-go beverage solutions that align with fast-paced urban lifestyles. Growing demand for functional beverages that offer energy, refreshment, and added health benefits is further supporting product adoption across diverse age groups. Rising interest in premium, low-sugar, and clean-label coffee variants is also reshaping consumption patterns, encouraging brands to innovate in flavor profiles and formulations. Additionally, the rapid expansion of retail distribution networks, e-commerce platforms, and quick-commerce channels is significantly enhancing product accessibility and supporting sustained market growth.
Packaging Insights
Based on packaging, the cans segment led the market with the largest revenue share of 43.4% in 2025. The segment growth is associated with factors such as the convenience of storage, enhancing the portability of the product, appealing to consumers with busy schedules requiring coffee on the go, and maintaining the freshness of the coffee in air-tight container packaging, in turn enhancing the shelf-life. In addition, it offers a sustainable alternative as aluminum cans can be recycled back to their original form, unlike plastics. Companies are encouraged to use aluminum cans to store RTD beverages. For instance, in March 2023, a new campaign called Canifesto was launched by RTD brands to promote the use of cans to store beverages, emphasizing the sustainable angle. Such growing instances are expected to boost market growth.
The carton RTD coffee is expected to grow at a CAGR of 7.0% from 2026 to 2033. The growth of the segment can be attributed to the benefits offered by the packaging style, as it offers portability, convenience, and cost-effectiveness. According to the data published by MTPak Coffee, the cartons are of a suitable packaging style for cold brew coffee as it reduces shipping costs and requires less packaging material. In addition, paper can be recycled which also proves a sustainable alternative to plastic packaging. Moreover, it proves advantageous for the companies to brand their product in attractive packaging, enhancing their appeal to the targeted consumers. The advantages the carton packaging provides also contribute to the growth of the market.
Nature Insights
Based on nature, the conventional RTD coffee segment led the market with the largest revenue share of 95.5% in 2025, driven by factors like convenience, affordability, and a wider range of flavors and formulations. Consumers, particularly in developing markets, are drawn to its lower price point and accessibility in mainstream retail outlets. Furthermore, innovative flavor combinations, energy-boosting additives, and collaborations with popular brands are constantly being introduced to cater to a broad spectrum of consumer preferences, solidifying its position as a readily available and satisfying caffeine source for immediate consumption. For instance, Monster Energy Company launched a new RTD cold brew coffee in June 2022, which is available in latte and sweet black flavors. In addition, price-conscious consumers prefer conventional coffee due to its easy availability, effective taste, and reasonable pricing.
Organic RTD coffee is expected to grow at a CAGR of 9.1% from 2026 to 2033. Organic cold brew coffee is made without synthetic raw materials and is free from chemicals such as pesticides and fertilizers. Health-conscious consumers are willing to pay a higher price for chemical-free products over conventional coffee products. Furthermore, organic RTD coffee is available with various organic certifications, which attract the attention of high-end consumers, and companies offer such products in the market to meet the rising demand. For instance, Blue Bottle Coffee, Inc. has made its RTD coffee available in an organic form with USDA certification to enhance its authenticity. Such rising demand from consumers coupled with health-conscious lifestyles are leading consumers to the market, which is expected to grow over the years.
Distribution Insights
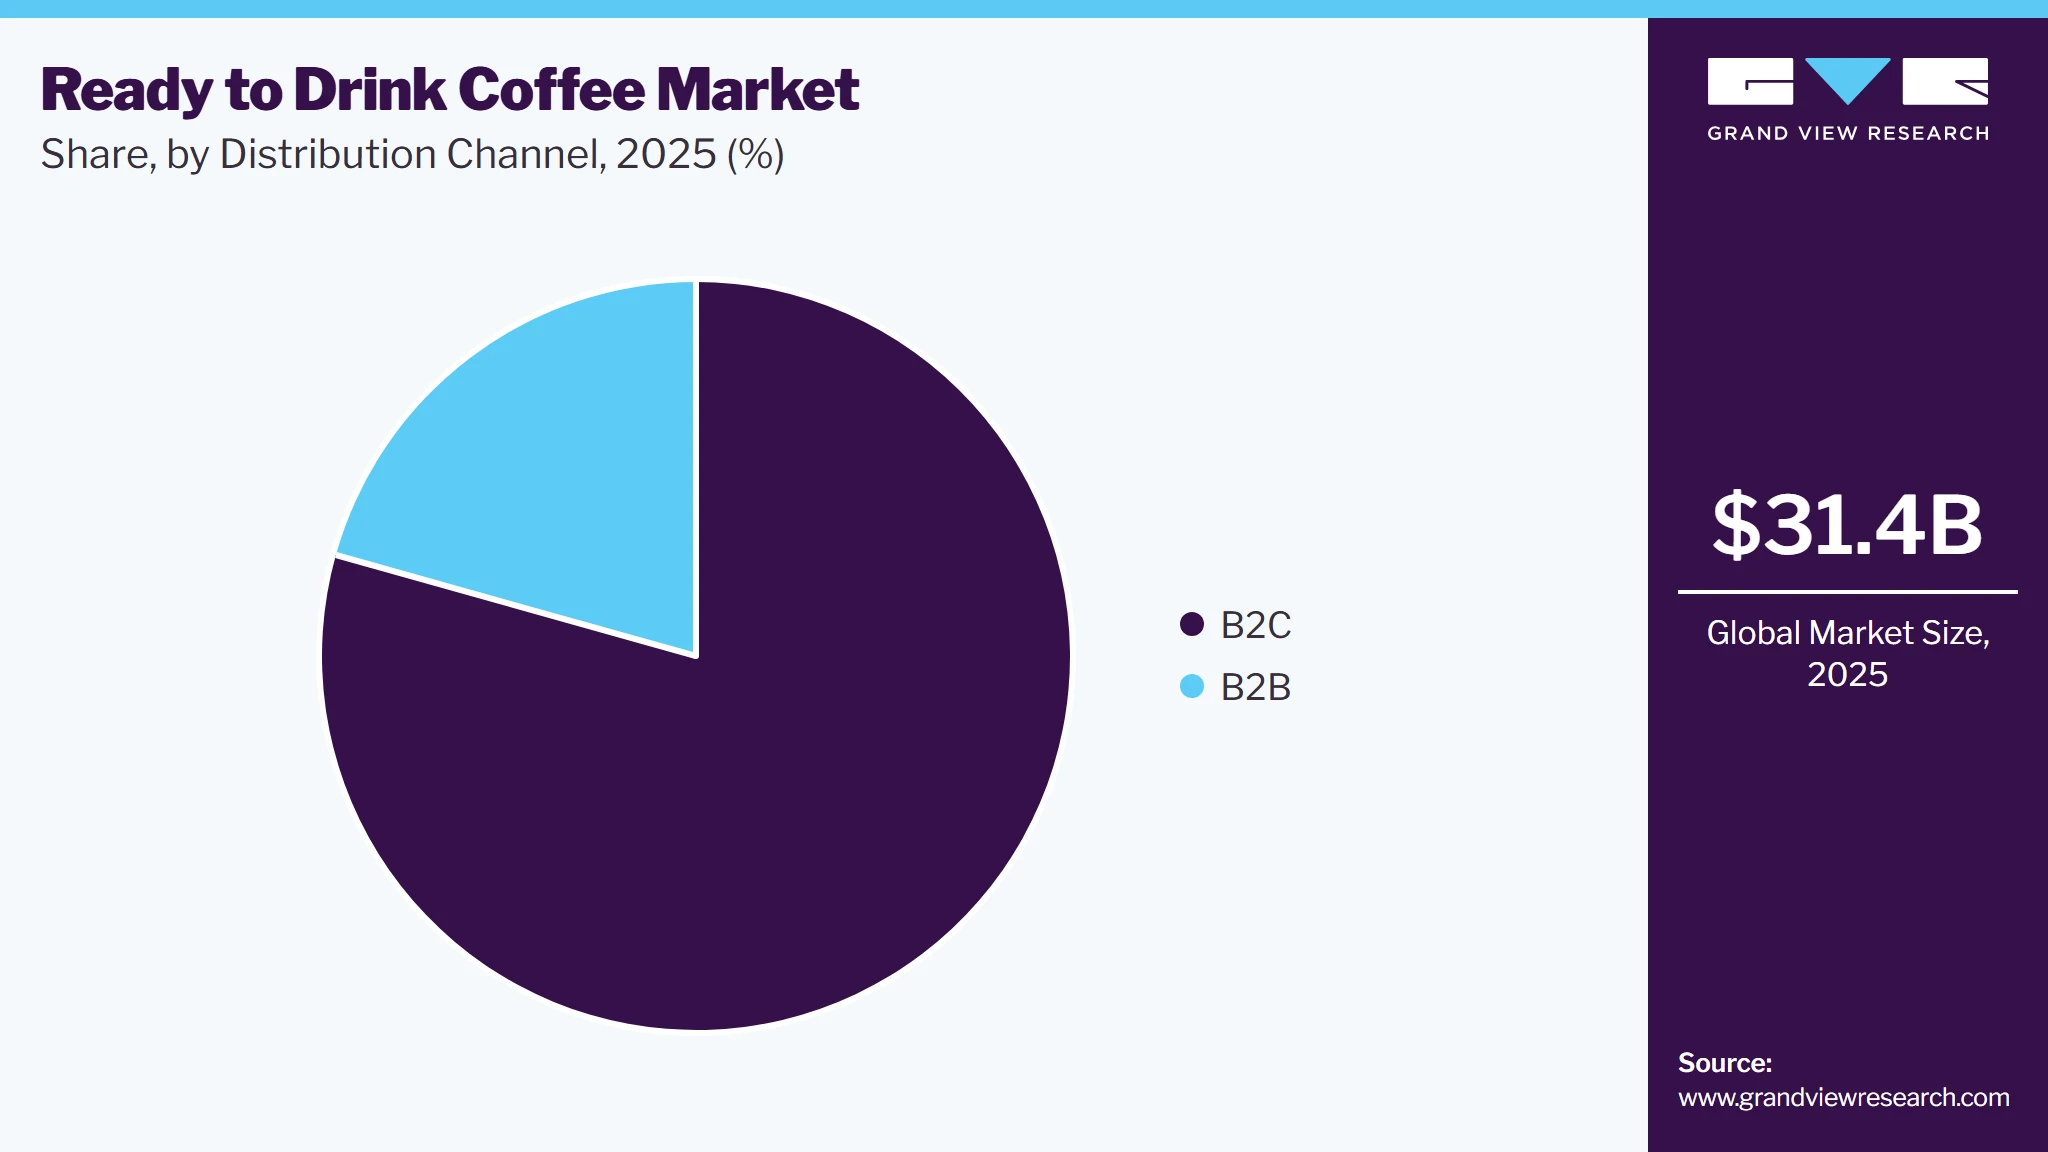
Based on the distribution channel, the B2C segment led the market with the largest revenue share of 79.4% in 2025. Supermarkets and hypermarkets offer a wide range of products in this category, allowing consumers to choose according to their preferences. These distribution channels perform well in terms of sales due to their wide range of products available in various brands, various flavored RTD coffee options, and different packaging styles. These advantages give consumers the edge in making quick decisions with attractive discounted pricing. The companies, looking at the rising demand in the category, are making their products available in supermarkets and hypermarkets. For instance, Bones Coffee Company announced the launch of RTD coffee cold brews in July 2024. These newly launched products will be available in five attractive variations and will also be available to consumers at Walmart. Such new product launches made available in supermarkets and hypermarkets are expected to boost market growth.
 To learn more about this report, Download Free Sample Report
The sales of RTD coffee through the B2B channel are expected to grow at a CAGR of 5.5% from 2026 to 2033. The offices and hotels & restaurants contribute to sales growth through B2B distribution channels. The commercial offices are equipped with vending machines through which employees can enjoy RTD coffee, which improves productivity and increases attention span. Furthermore, factors such as increased disposable income, rise in tourism, and lifestyle alterations, hotels & restaurants offer various RTD coffee options appealing to the consumers. The hotels & restaurants offer fancy options in the RTD coffee beverage range of products and are involved in making their presence in QSRs and hotels. For instance, Kings Coffee, in August 2022, made its mark in the RTD coffee space by planning for B2B collaborations with QSRs and hotels. Such rising instances are expected to boost market growth.
Regional Insights
The Ready To Drink (RTD) coffee industry in North America held over 27.29% of the global revenue in 2025. The high coffee culture's existence augments factors such as convenience and portability, high product innovations, and a wide range of RTD coffee beverages available, and the rising young consumer population, such as millennials and Gen Z, adds to the ripe market. The strong presence of key companies offering RTD coffee further offers market growth in the region. For instance, in June 2024, Westrock Coffee Company launched the largest RTD manufacturing unit in North America. The product launches and huge investments by the giant companies enhance the growth of the market.
U.S. RTD Coffee Market Trends
The ready-to-drink (RTD) coffee market in the U.S. held the largest share in the North America region in 2025. The market growth in the country can be attributed to the core coffee culture and high coffee consumption by Americans. In addition, the country hosts several cafes and restaurants offering the instant gush of energy to corporate employees, ready-to-drink beverage enthusiasts, and young consumers. For instance, according to the National Coffee Association of U.S.A., Inc. data published in April 2024, daily coffee consumption has risen by 37% since 2004. For instance, according to a report published by the National Coffee Association in September 2024, 21% of coffee consumers believed cold brew is a healthier kind compared to other coffee types. Furthermore, ready-to-drink coffee is now the third most popular coffee method among specialty coffee enthusiasts, rising by 83% since 2023, according to the SCA (Specialty Coffee Association) report published in June 2023.
Europe RTD Coffee Market Trends
The Europe RTD coffee industry is expected to grow at a CAGR of 6.7% from 2026 to 2033. The rising population of millennials and Gen Z consumers, increased tourism in the region coupled with several cafes with high adoption of coffee contribute to the growth of the market. The rising demand for RTD coffee is encouraging companies in the region to collaborate and acquire RTD's growing brand in the product category. For instance, Britvic plc, in July 2023, acquired the fastest-growing RTD coffee brand, Jimmy's Iced Coffee, to expand its portfolio. This acquisition will enable Britvic plc to enhance the growth of Jimmy’s Iced Coffee, utilizing its customer relationships and increasing efficiency through the supply chain. The higher activities of key players in the region are expected to accelerate the growth of the market.
Asia Pacific RTD Coffee Market Trends
Asia Pacific dominated the ready-to-drink (RTD) coffee market with the largest revenue share of 36.2% in 2025. The increased influence of Western trends, the evolution of internet connectivity that paved the way for the rise of social media, and the high adoption of coffee culture in the region contribute to the market growth. In addition, the warm and humid climate further accelerates the demand for cold brew and RTD cold coffee alternatives. The urbanization and smart city developments coupled with busy routine lifestyles add to the rising demand for RTD coffee in the region. Key companies are strategizing to make their presence in the RTD coffee category and serve the target consumers. For instance, Rage Coffee launched RTD coffee variants in March 2023 in delicious flavors, including mocha frappe, salted caramel, and hazelnut latte. Companies innovating and launching new products in the category enhance market growth.
 To learn more about this report, Download Free Sample Report
Key Ready To Drink Coffee Company Insights
The global ready-to-drink coffee industry is characterized by numerous well-established and emerging players. Manufacturers are continually introducing new products to capture consumer interest. This includes a variety of ready-to-drink coffee beverages such as classic, vanilla, hazelnut, and caramel coffee options. For instance, brands such as Ueshima Coffee Company, based in Japan, have launched two new RTD coffees in the UK market in iced latte and iced matcha latte variants. Moreover, the companies are embracing sustainability in product packaging and adopting aluminum cans as they are recyclable. In addition, various companies are strategizing to enter the lucrative space by launching new products, acquiring RTD coffee brands, and launching manufacturing facilities to accelerate market growth.
Key Ready To Drink Coffee Companies:
The following key companies have been profiled for this study on the ready to drink coffee market.
-
Nestlé
-
Starbucks Coffee Company
-
Sleepy Owl Coffee
-
Tata Consumer Products Limited
-
Kings Coffee
-
Rage Coffee
-
Costa
-
Tim Hortons
-
Blue Bottle Coffee, Inc.
-
Inspire Brands, Inc. (Dunkin’)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Nestlé S.A.; Starbucks Coffee Company; Tata Consumer Products Limited; Costa; Tim Hortons;)
- Large-scale production of RTD beverages, strong global distribution networks, diversified product portfolios, and continuous investment in premium and functional RTD coffee innovations.
- Strong brand equity, extensive retail and café presence, advanced product innovation capabilities, and strong supply chain and marketing power.
- High operational costs, intense competition in mature markets, and reliance on premium pricing strategies.
Emerging Players (Sleepy Owl Coffee; Kings Coffee; Rage Coffee)
- Direct-to-consumer models, digital-first marketing, niche targeting of young and urban consumers, and focus on innovative RTD coffee flavors and formats.
- Agility in product innovation, strong social media-driven branding, and ability to quickly adapt to changing consumer preferences.
- Limited global reach, smaller distribution networks, and lower economies of scale compared to established players.
Recent Developments
-
In April 2023, Chamberlain Coffee launched new products in the RTD coffee space by introducing plant-based RTD cold brew lattes and collaborating with Walmart.
-
In June 2023, Tata Consumer Products Limited introduced RTD cold coffee in three variants, including classic, mocha, and hazelnut. The new product launch will enable the company to offer the coffee experience to the target consumers.
-
In March 2023, The Coca‑Cola Company partnered with Inspire Brands, Inc. (Dunkin’) to expand the latter company's relationship into the RTD coffee line of products into cans packaging style. The RTD coffee product line includes various flavors parallel to their donuts, including brownie batter donuts, cake batter donuts, and coffee cake muffins.
Ready To Drink Coffee Market Report Scope
Report Attribute
Details
Market size in 2025
USD 31.4 billion
Estimated market size in 2026
USD 33.6 billion
Projected market size by 2033
USD 49.0 billion
Growth rate
CAGR of 5.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Packaging, nature, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; South Africa
Key companies profiled
Nestlé S.A.; Starbucks Coffee Company; Sleepy Owl Coffee; Tata Consumer Products Limited; Kings Coffee; Rage Coffee; Costa; Tim Hortons; Blue Bottle Coffee, Inc.; Inspire Brands, Inc. (Dunkin’)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Ready To Drink Coffee Market Report Segmentation
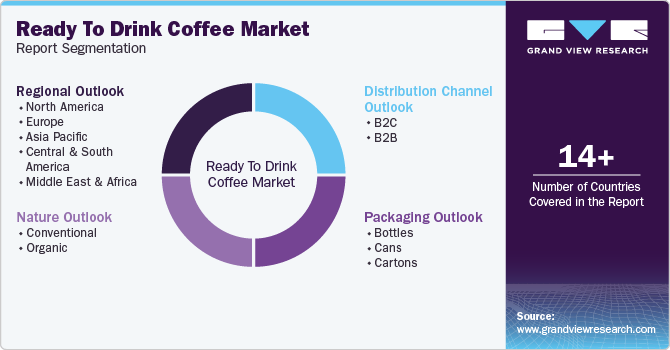
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ready to drink coffee market report based on packaging, nature, distribution channel, and region.
 To learn more about this report, Download Free Sample Report
-
Packaging Outlook (Revenue, USD Million, 2021 - 2033)
-
Bottles
-
Cans
-
Cartons
-
-
Nature Outlook (Revenue, USD Million, 2021 - 2033)
-
Conventional
-
Organic
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
B2C
-
Grocery Stores/Supermarkets
-
Hypermarkets
-
Convenience Stores
-
Online Retailers
-
Online Direct-to-Consumer (DTC)
-
Others
-
-
B2B
-
Cafes
-
Hotels & Restaurants
-
Offices
-
Bakeries and Coffee Shops
-
Others
-
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The ready to drink coffee market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each ready to drink coffee segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Nature
Revenue capture definition
Conventional
Conventional RTD coffee products are made using traditionally sourced coffee beans and standard production methods. They are widely available across retail channels and are preferred by consumers seeking affordable, convenient, and familiar coffee beverage options.
Organic
Organic RTD coffee products are produced using coffee beans grown without synthetic pesticides, fertilizers, or genetically modified ingredients. They appeal to health-conscious and environmentally aware consumers who prioritize natural ingredients and sustainable sourcing practices.
Estimation Model
Layer
Guiding Question
Description
Consumption Universe Layer
Who consumes ready to drink (RTD) coffee globally?
Represents the overall population of coffee consumers, including individuals who prefer convenient, ready‑to‑drink caffeine‑based beverages for energy, refreshment, and lifestyle consumption.
Access & Availability Layer
Who can access ready to drink (RTD) coffee?
Includes consumers who can purchase RTD coffee through supermarkets, convenience stores, vending machines, cafés, and expanding online and quick‑commerce platforms.
Purchase & Usage Layer
Who regularly purchases ready to drink (RTD) coffee?
Covers consumers who actively choose RTD coffee as part of their daily routine, especially for on‑the‑go consumption, work breaks, travel, and instant energy needs.
Revenue Conversion Layer
How is revenue generated from ready to drink coffee consumers?
Represents monetization through sales of RTD coffee across formats such as bottles, cans, and cartons, along with premium, low‑sugar, functional, and flavored variants.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
RTD Coffee Market Demand Drivers & Consumer Motivation
Examined rising demand for convenient, on-the-go coffee beverages driven by urban lifestyles, increasing work mobility, and preference for instant energy solutions among consumers.
Provides insight into how convenience-led consumption patterns and fast-paced routines are shaping sustained RTD coffee demand.
RTD Coffee Product Development & Formulation Trends
Analyzed innovation in RTD coffee formulations including cold brew variants, low-sugar and functional blends, dairy alternatives, and premium flavored offerings tailored to evolving taste preferences.
Identifies key innovation directions supporting product differentiation and alignment with health-conscious and premiumization trends.
RTD Coffee Competitive Landscape & Brand Positioning
Assessed strategies adopted by global and emerging RTD coffee brands, including premium branding, functional positioning, café-led ecosystems, and direct-to-consumer engagement models.
Provides understanding of how brand differentiation, lifestyle marketing, and innovation-led positioning are shaping competitive intensity in the RTD coffee market.
Frequently Asked Questions About This Report
The global ready-to-drink (RTD) coffee market size was valued at USD 31.4 billion in 2025 and is estimated at USD 33.6 billion for 2026.
The global ready-to-drink (RTD) coffee market is expected to grow at a CAGR of 5.6% from 2026 to 2033, reaching USD 49.0 billion by 2033
Asia Pacific dominated with a 36.2% revenue share in 2025.
The cans segment led with a 43.4% revenue share in 2025.
Conventional RTD coffee segment led the market with the largest revenue share of 95.5% in 2025.
Key players include Nestlé S.A., Starbucks Coffee Company, Sleepy Owl Coffee, Tata Consumer Products Limited, Kings Coffee, Rage Coffee, Costa, Tim Hortons, Blue Bottle Coffee, Inc., and Inspire Brands, Inc. (Dunkin’).
Key factors driving the ready-to-drink (RTD) coffee market include rising consumer demand for convenient, on-the-go beverages and increasing preference for coffee-based drinks.
B2C segment led the market with the largest revenue share of 79.4% in 2025.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


