
- Home
- »
- Plastics, Polymers & Resins
- »
-
Specialty Carbon Black Market Size, Share Report 2026-2033GVR Report cover

Specialty Carbon Black Market (2026 - 2033)
Size, Share & Trends Analysis Report By Grade (Conductive Carbon Black, Fiber Carbon Black, Food Contact Carbon Black), By Region (Asia Pacific, Europe, North America, Latin America), And Segment Forecasts
Market Size, 2025
$3.5BMarket Estimate, 2026
$3.8BMarket Forecast, 2033
$7.9BCAGR, 2026–2033
10.9%Specialty Carbon Black Market Summary
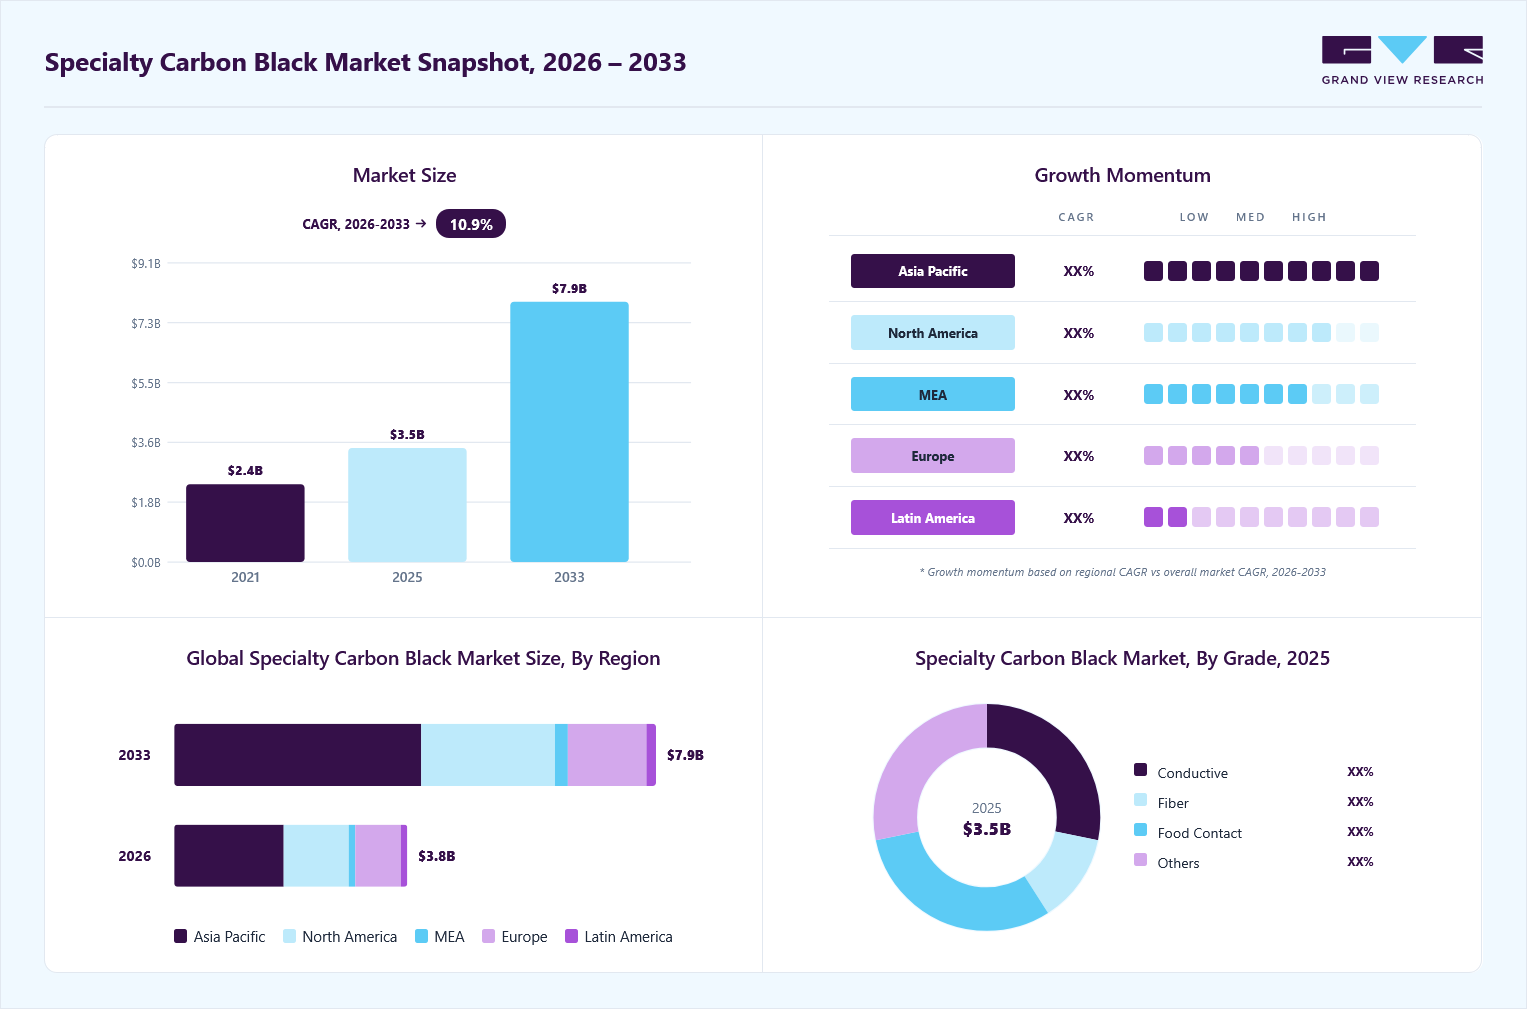
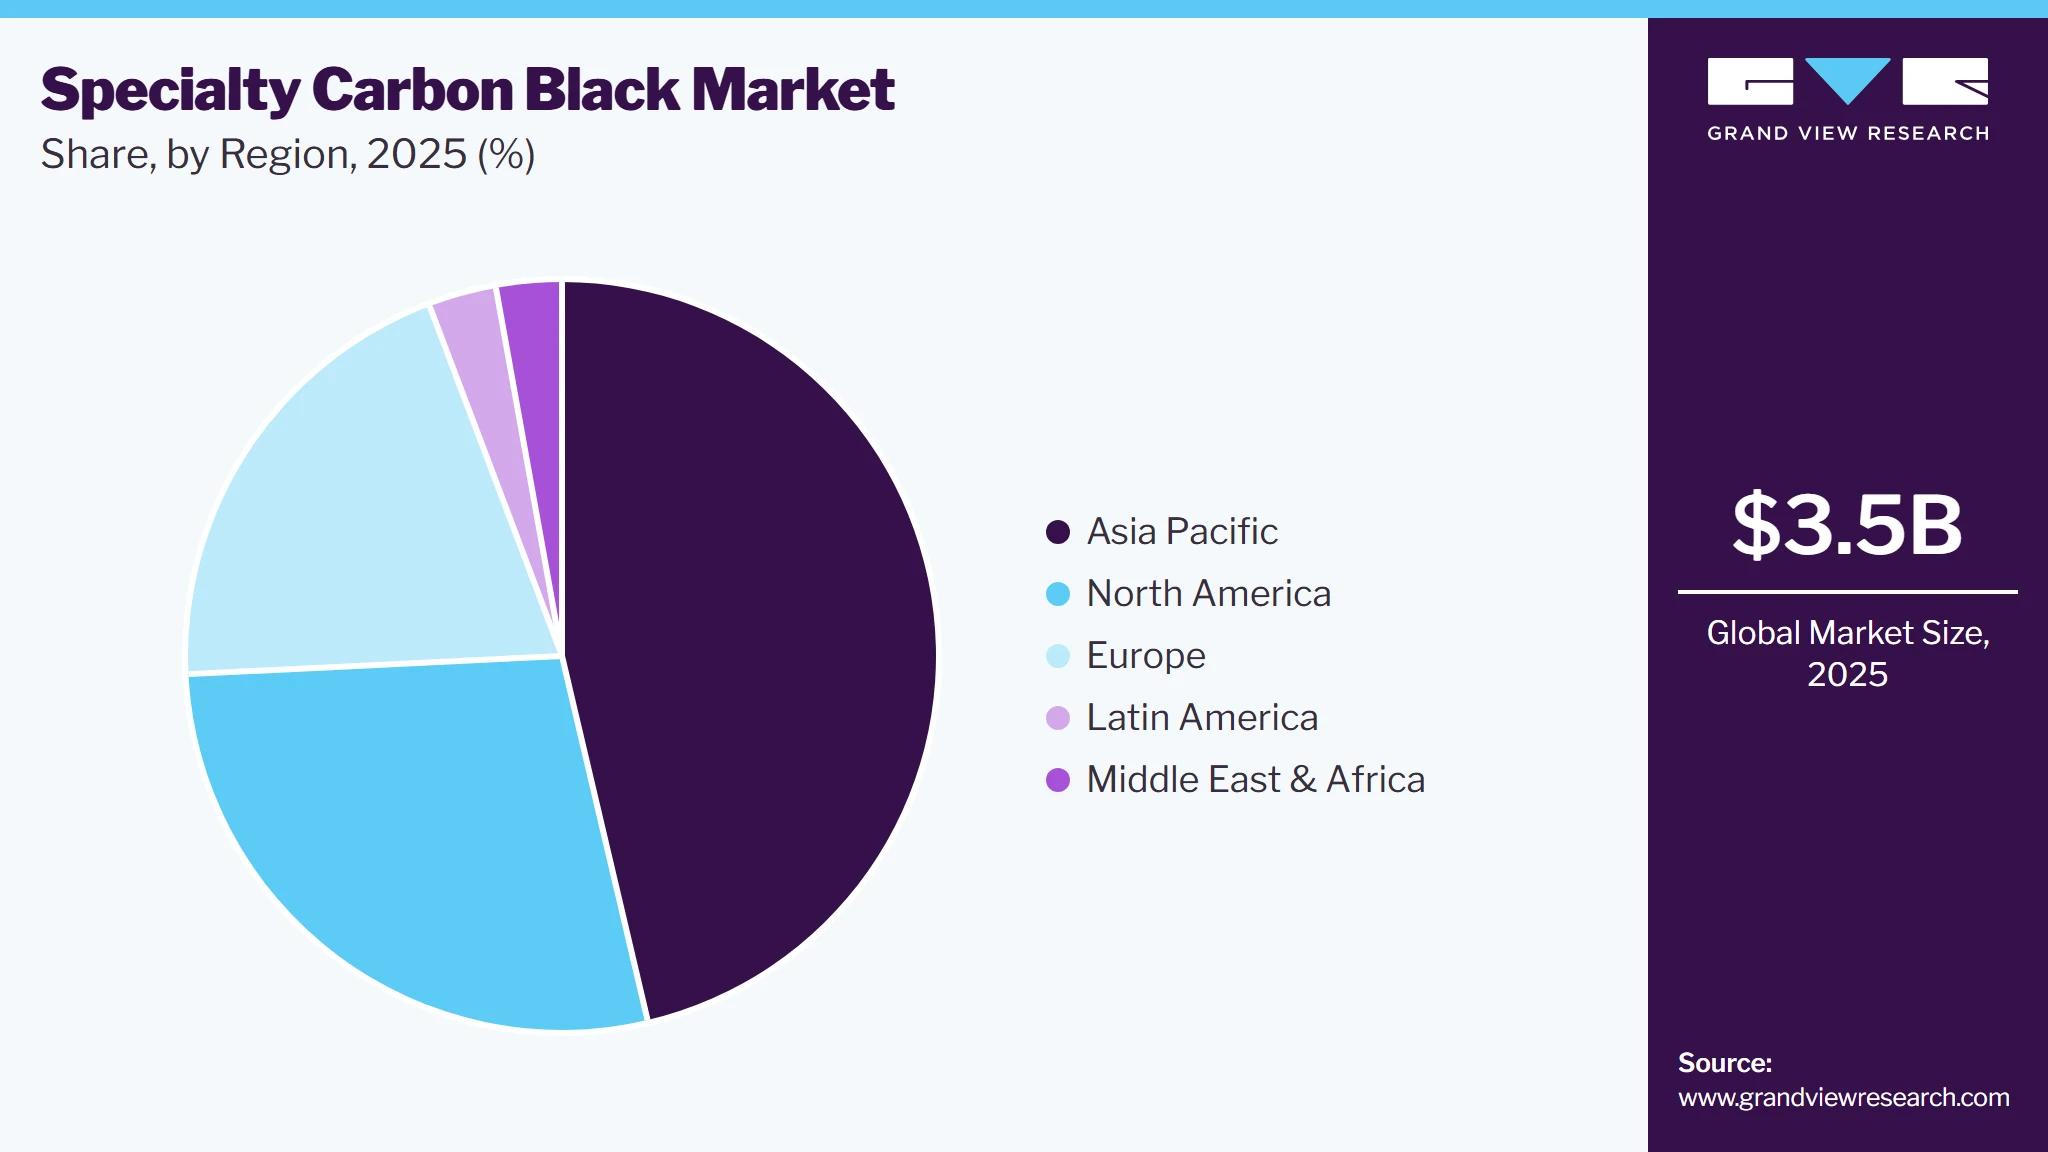
The global specialty carbon black market size was valued at USD 3.5 billion in 2025 and is projected to grow from USD 3.8 billion in 2026 to USD 7.9 billion by 2033, at a CAGR of 10.9% from 2026 to 2033. The Asia Pacific held the largest share of 46.3% of the global market in 2025. This is attributed to the surging demand for the product as reinforcing agents, especially in tires.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By grade: Food contact segment accounted for the largest share of 30.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.3% revenue share, 2025)
- By country: The China led the Asia Pacific market in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.5 Billion
- Estimated market size in 2026: USD 3.8 Billion
- Projected market size by 2033: USD 7.9 Billion
- CAGR (2026-2033): 10.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, the growing utilization of the product in agriculture mulch film, stretch wrap, refuse sacks, and industrial bags is anticipated to contribute to the market growth in the near future. Specialty carbon black is a highly versatile component for non-rubber applications. It imparts protection from UV degradation, color, electrical conductivity, and opacity. The selection of carbon black entirely depends on the product's requirements. It is mainly used in key plastic segments, including molding, film, pipe, fiber, and cable.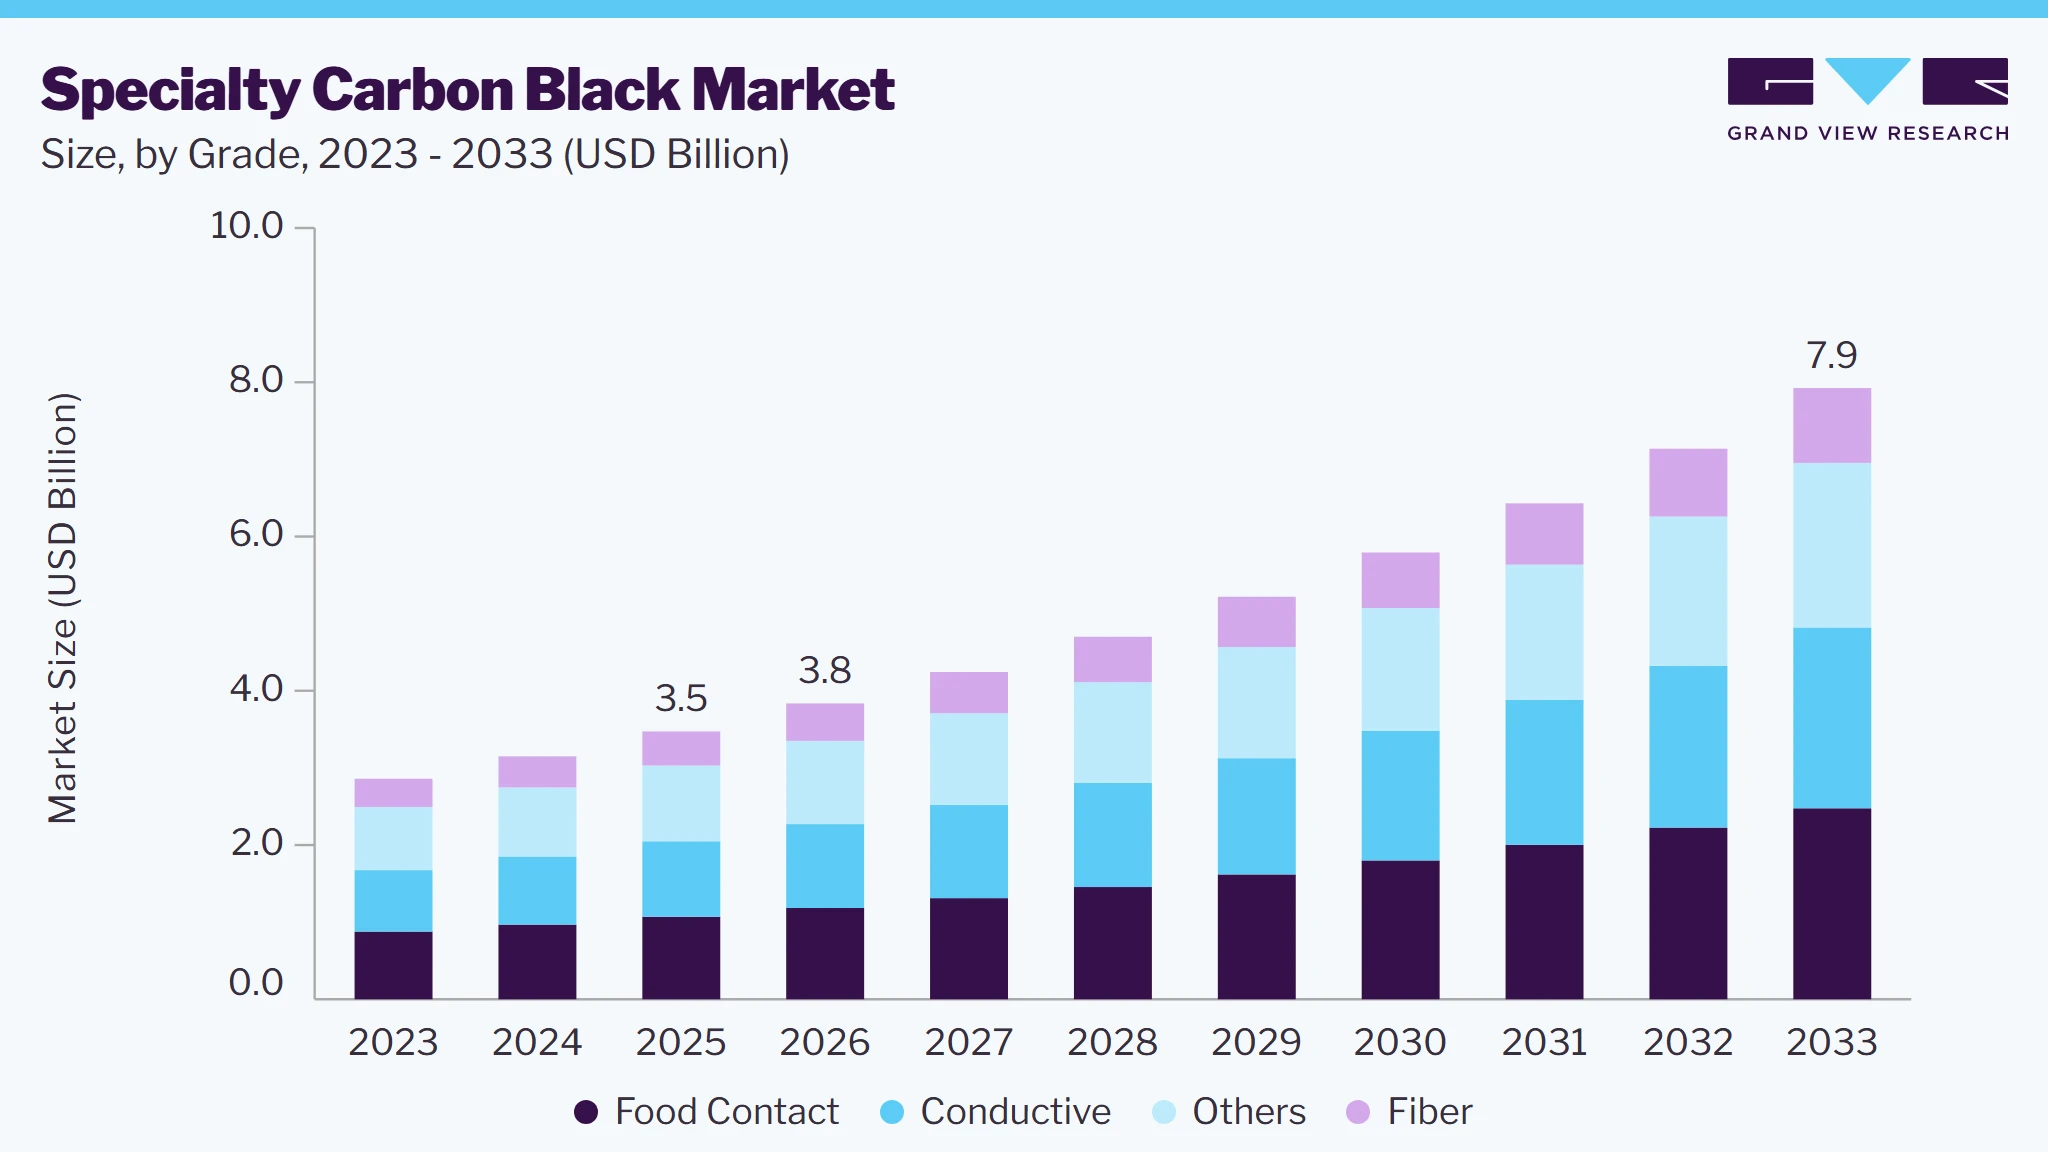 To learn more about this report, Download Free Sample Report
Specialty carbon black dynamics are heavily dependent on applications such as non-tire rubber, electrostatic discharge, packaging, paints and coatings, printing ink consumption, and regulations formulated for manufacturing technologies and raw materials. It provides enhanced viscosity, conductivity, UV protection, and sharp color.
The global transition towards electric vehicles is driving the market for specialty carbon black, which plays a critical role in lithium-ion battery technology, improving electrode conductivity and durability. For instance, nearly 300,000 new EVs were sold in the first quarter of 2025 in the U.S.
Rapid urbanization and infrastructure development, particularly in emerging economies such as India and China, propel the demand for specialty carbon black. Its application in automotive, electronics, consumer goods, and industrial parts aligns with the growing needs of expanding urban centers. This infrastructural boom offers significant growth prospects for the specialty carbon black market.
Market Dynamics
The specialty carbon black market is experiencing steady growth due to increasing demand from plastics, coatings, inks, batteries, and electronics industries. Specialty carbon black is widely used to enhance conductivity, UV protection, color performance, durability, and mechanical properties in a broad range of industrial applications. Growing production of high-performance plastics, rising consumption of conductive materials in electric vehicles (EVs) and lithium-ion batteries and increasing demand for premium black pigments in automotive coatings and printing inks are supporting market expansion. Technological advancements in conductive carbon materials and increasing investments in sustainable and low-emission manufacturing processes are further contributing to market growth.
The growing adoption of electric vehicles and energy storage systems is a major driver of the Specialty Carbon Black Market. Specialty carbon black serves as a critical conductive additive in lithium-ion batteries, improving electrical conductivity and enhancing battery performance. As global automakers accelerate EV production and governments promote vehicle electrification through incentives and emission regulations, demand for battery-grade specialty carbon black continues to increase.
The impact of this trend extends beyond the automotive sector into consumer electronics, industrial batteries, and renewable energy storage systems. Manufacturers are developing advanced conductive carbon black grades with improved dispersion characteristics and conductivity levels to meet evolving battery performance requirements. The rapid expansion of battery manufacturing capacity worldwide is expected to significantly strengthen demand for specialty carbon black over the coming years.
Fluctuations in feedstock prices and increasingly stringent environmental regulations present significant challenges for the specialty carbon black market. Specialty carbon black production relies heavily on petroleum-based feedstocks, making manufacturers vulnerable to changes in crude oil prices and supply chain disruptions. Rising energy costs and feedstock price volatility can directly affect production expenses and profit margins.
Governments across North America, Europe, and Asia are implementing stricter regulations related to carbon emissions, air quality, and industrial waste management. Compliance with these environmental standards often requires substantial investments in emission-control technologies and sustainable production processes. These factors can increase operational costs and create barriers for market expansion, particularly for smaller manufacturers with limited capital resources.
The increasing use of high-performance plastics and sustainable material solutions is creating substantial growth opportunities for the specialty carbon black market. Specialty carbon black is extensively utilized in engineering plastics, packaging materials, automotive components, and construction products to provide UV protection, conductivity, color consistency, and enhanced durability. Rising demand for lightweight and durable materials across various industries is driving the adoption of specialty carbon black formulations.
Opportunities are also emerging from the development of sustainable and circular economy initiatives. Manufacturers are investing in recovered carbon black technologies, low-carbon production methods, and environmentally friendly product innovations to meet growing sustainability requirements. As industries seek materials that combine high performance with improved environmental profiles, specialty carbon black producers can strengthen their market position through innovative product development and strategic partnerships across automotive, electronics, packaging, and industrial sectors.
Market Concentration & Characteristics
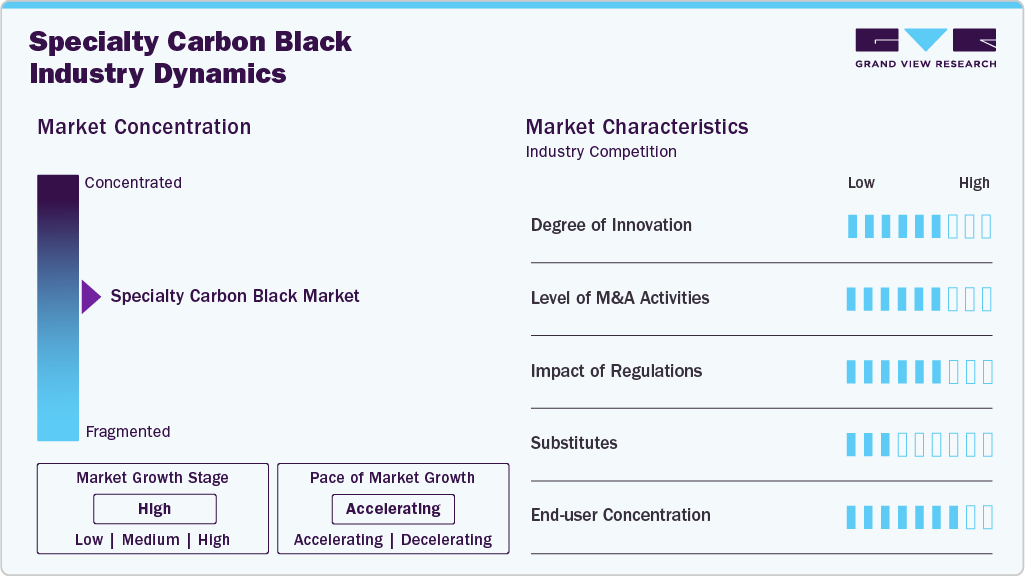
The market is concentrated, with a few companies accounting for a majority share of the global market. The market leaders are companies that have initially established a significant presence in the specialty carbon black industry. The companies have developed well-accepted product formulations and established a significant geographical presence.
 To learn more about this report, Download Free Sample Report
Emerging players in the market have integrated manufacturing and distribution along with a focus on product innovation. The companies have developed processes and formulated products to adopt the product differentiation strategy. These companies also work with end users to develop customized products.
Analyst Perspective
The specialty carbon black market is positioned for sustained growth, driven by increasing demand for high-performance materials across plastics, coatings, inks, electronics, and energy storage applications. Unlike carbon black commodity, specialty grades offer enhanced conductivity, UV protection, color performance, and dispersion characteristics, making them critical for advanced industrial and consumer applications. The rapid expansion of electric vehicle production and lithium-ion battery manufacturing is emerging as one of the most significant demand drivers, as conductive carbon black plays an essential role in improving battery efficiency and performance.
Grade Insights
The food contact segment accounted for the largest share of the specialty carbon black market, representing 30.9% of total revenue in 2025. Increasing packaging, films & sheets, and plastic molded goods usage in the food industry is expected to drive market growth over the forecast period. Food-grade products adhere to various requirements imposed by the FDA, The European Plastics Regulation, and the Japan Hygienic Olefin & Styrene Plastics Association (JHOSPA). Specialty carbon blacks are used for packaging a diverse range of products and thus have extensive applications across several end-use industries, including food and agriculture.
The conductive segment is expected to grow at the fastest CAGR of 11.6% over the forecast period. Conductive carbon blacks are used to manufacture cost-efficient electrically conductive plastic compounds, which are used in various processing methods and final applications. Several companies are investing in the production of conductive carbons. For instance, in February 2025, PCBL Chemical Ltd. formalized an agreement with Ningxia Jinhua Chemical Co. to commence the production of acetylene black within India. The inclusion of acetylene black in its product line will significantly augment PCBL's capabilities in the conductive sector.
Increasing demand from end-use industries such as automotive, architecture, and consumer goods is anticipated to fuel conductive carbon black demand in the paints & coatings industry. A growing manufacturing sector and strong economic growth are expected to drive conductive product consumption over the forecast period. Asia Pacific market is one of the largest manufacturers and consumers of polymers and is expected to fuel market growth over the next five years.
Regional Insights
North America held a significant position in the global specialty carbon black market in 2025. There is a substantial demand for conductive and food-grade products in North America due to the growth of the packaging and polymer industries. The region is also expected to benefit from a rapidly expanding automotive industry, where these products are mainly utilized as sealants for gaskets, liners in automobile dashboards, arm liners, instrument panels, and other components.
 To learn more about this report, Download Free Sample Report
U.S. Specialty Carbon Black Market Trends
The specialty carbon black market in the U.S. is anticipated to grow significantly during the forecast period. The U.S. is home to one of the largest automotive markets in the world. Major automakers have responded to new domestic cost advantages by shifting production from other countries to the U.S. A large consumer market, open investment policy, available infrastructure, a highly skilled workforce, and government incentives have made the U.S. a premier hub for the auto industry. The U.S. market is expected to benefit from a revitalized automotive sector.
In addition, there's a growing emphasis on sustainable carbon black solutions in North America, with companies such as Cabot introducing products with certified recycled content. In March 2024, the U.S.-based specialty chemical firm, Cabot Corporation, introduced PROPELE8, an engineered reinforcing carbon black. This product is formulated to improve the performance characteristics of elastomers, especially in rigorous applications such as tires and industrial rubber goods.
Europe Specialty Carbon Black Market Trends
Europe's specialty carbon black market is anticipated to grow rapidly during the forecast period. High demand from the polymer industry is expected to drive demand in Europe. Recovery of the automotive industry in the region in countries such as Germany, France, the UK, and Russia is anticipated to boost market growth over the forecast period. Demand for specialty carbon black in paints & coatings and inks is expected to increase in the near future.
Germany's specialty carbon black market is anticipated to grow at the fastest CAGR during the forecast period. The growth of key end-use industries such as the automotive and plastics industries drives the German market. Increasing demand for molded parts for consumer goods and the development of non-rubber automotive applications are anticipated to drive market growth in the country.
The UK specialty carbon black market is anticipated to grow at a CAGR of 11.4% during the forecast period. Polyester fiber was the largest application segment in the UK fiber carbon black market, with rising demand for luxury apparel, mattresses, and other fiber products. The country's market is largely mature and driven by innovation and cost differentiation. Packaging also emerged as the prominent application segment in the food industry, with a shift towards packaged food & beverages along with rising regulatory guidelines, which is further estimated to contribute to the market growth.
Asia Pacific Specialty Carbon Black Market Trends
Asia Pacific accounted for 46.3% of the Crop Rotation market revenue in 2025, making it the largest regional market. The growth in this region can be attributed to expanding end-use industries and growing consumer interest in recyclable & sustainable, yet luxurious and comfortable products. Increasing high-performance coatings demand from end-use industries such as marine, aerospace, decorative, wood, and industrial coatings is expected to drive regional market growth over the forecast period. Moreover, the presence of developing countries, including India and China, is anticipated to further drive the market growth due to the escalating industrial base in the Asia Pacific region. In January 2024, Birla Carbon announced greenfield expansions in the Asia Pacific region, aiming to increase its carbon black capacity by over 240 kilotons in India and Thailand.
China held the largest market in Asia Pacific in 2025, at a revenue share of 41.5%, owing to the expansion of key downstream sectors, including automotive, electronics, and construction. China's advantageous access to affordable raw materials and labor positions it as an economically efficient center for the production of specialty carbon black.
The India specialty carbon black market is expected to witness a significant expansion during the forecast period, due to the textile industry's growth and rising automotive sales in the country. Several large-scale players, such as Birla Carbon Company and Himadri mark the market. Increasing demand for food-grade carbon black from the packaged food industry is expected to drive market growth further over the forecast period. The growth of the polymer industry, coupled with increasing demand in the automotive and construction sectors, is anticipated to drive market growth in the country.
Latin America Specialty Carbon Black Market Trends
The specialty carbon black market in Latin America is anticipated to grow significantly during the forecast period. Latin America is expected to benefit from a rapidly expanding automotive industry, where these products are mainly utilized as non-rubber automotive components. Increasing consumer disposable income and rising living standards are also anticipated to foster demand for comfortable furniture and bedding, leading to an upsurge in fiber carbon black sales. In addition, increasing demand for food-grade carbon black from the packaged food industry is expected to further drive market growth over the forecast period.
The Brazil specialty carbon black market is driven by increasing demand from thermosetting application in end-use industries such as automotive, construction, consumer goods and blow-molded containers. The country is characterized by a rapidly growing industrial sector, which is expected to influence industry growth in the near future positively. Increasing specialty carbon black demand for semi-conductive cable compounds, which is used for smoothness, conductivity, and chemical cleanliness, is anticipated to drive demand over the forecast period.
Middle East & Africa Specialty Carbon Black Market Trends
Increasing construction spending in emerging economies such as Saudi Arabia, Qatar, UAE, and Oman is anticipated to drive market growth in the Middle East & Africa (MEA) region. Rapid urbanization in these developing countries has shifted consumer preference towards packaged food & beverages, thus generating huge demand for fiber grade specialty carbon black. Increasing demand from thermoplastic molding for various applications in end-use industries such as consumer goods and automotive is further anticipated to boost market growth. The growth of the textile sector, along with strong demand from the packaged food industry, is expected to drive market growth in the region.
Saudi Arabia's specialty carbon black market is expecting a surge in demand from the construction and automotive sectors. The growth of the industrial sector, along with rising automotive sales, is anticipated to drive industry growth in the country. In addition, rising packaged food consumption and textile industry growth are also expected to boost demand over the forecast period.
Key Specialty Carbon Black Company Insights
The market competition is highly dependent upon the product mix, number of sellers and location. As the products are application specific the product mix of any market player is expected to have a profound impact. Companies are tailoring their product portfolio to gain leadership in a specific application. The strategy helps the companies to enjoy higher margins while adopting the product differentiation strategy. Companies such as Orion and Cabot Carbon are working on strategies to achieve product leadership.
The number of sellers is considerably low, as the market comprises manufacturers with specialty offerings. Another major distinctive factor about the market is the presence of large-scale carbon black manufacturers that have the geographical and product expertise they have developed over the years by being in the business. The competition terms in the market are mainly dictated by these companies, and the rest of the companies try to exploit small pockets either by geographical expansion or new product development.
-
OMSK Carbon Group is a Russian carbon black company with manufacturing locations in Omsk and Volgograd. The company’s product portfolio comprises both OMCARB special grades for paint and polymer applications and commodity grades for rubber and tire product industries.
-
Tokai Carbon Co. Ltd. is a Japanese carbon black manufacturer. The company operates through its seven business segments: graphite electrodes, carbon black, fine carbon, smelting and lining, furnaces, friction materials, and anode materials. The company operates through its carbon black production plants based in Ishinomaki, Shonan, Chita, Shiga, Hofu, Kyusyu Wakamatsu and Tanoura.
Key Specialty Carbon Black Companies
The following key companies have been profiled for this study on the specialty carbon black market.
-
Omsk Carbon Group
-
Tokai Carbon Co., Ltd.
-
Atlas Organics Private Limited
-
Continental Carbon Company
-
Birla Carbon
-
Cabot Corporation
-
Oak Investment Partners
-
Himadri Specialty Chemical Ltd
-
Philips Carbon Black Limited
-
Orion S.A.
-
Ralson Carbon Black Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Cabot Corporation, Birla Carbon, Tokai Carbon Co., Ltd., Orion S.A., Phillips Carbon Black Limited, Continental Carbon Company)
- Focus on expanding specialty-grade and conductive carbon black portfolios for plastics, batteries, coatings, and electronics applications.
- Invest heavily in R&D, capacity expansions, sustainability initiatives, and long-term supply agreements with automotive, battery, and industrial customers.
- Strengthening market presence through global manufacturing networks and advanced product development.
- Extensive production capacities and well-established global distribution networks.
- Strong technical expertise in conductive, pigment, and high-performance carbon black grades.
- Ability to serve diverse end-use industries including automotive, electronics, packaging, coatings, and energy storage.
- High capital and operating costs are associated with environmental compliance and specialty-grade manufacturing.
- Larger organizational structures may slow response times to niche customer requirements and emerging application opportunities.
Emerging Players (Omsk Carbon Group, Himadri Specialty Chemical Ltd, Atlas Organics Private Limited, Ralson)
- Concentrate on niche specialty carbon black grades, customized formulations, and region-specific customer requirements.
- Expand through strategic partnerships, contract manufacturing, and targeted penetration into plastics, rubber, coatings, and battery applications.
- Focus on cost-efficient production and localized supply capabilities.
- Greater operational flexibility enables faster adaptation to customer-specific performance requirements.
- Competitive pricing strategies and strong relationships within regional markets.
- Ability to address specialized applications with tailored product offerings.
- Limited global footprint and smaller production capacities compared with multinational market leaders.
- Lower R&D budgets may constrain development of next-generation conductive and sustainable carbon black products.
- Greater exposure to raw material price fluctuations and regional demand cycles.
Recent Developments
-
In January 2025, Sumitomo Rubber Industries and Mitsubishi Chemical partnered to recycle carbon black from end-of-life tires. Sumitomo Rubber will provide tire materials to Mitsubishi Chemical for processing into sustainable carbon black, which will then be used in new tires, promoting a circular economy.
-
In January 2025, Tokai Carbon Co., Ltd, Kyushu University, Bridgestone Corporation, and Okayama University initiated a collaborative technology development project. The project focuses on secondary processing of recovered carbon black (rCB) extracted from polymeric materials, notably end-of-life tires.
-
In July 2024, Himadri Specialty Chemical Ltd, via its wholly-owned subsidiary Himadri Clean Energy Limited (HCEL), strategically acquired Himadri Green Technologies Innovation Limited. This acquisition is intended to broaden Himadri's operational footprint, aiming for business expansion and improved internal efficiency.
-
In January 2024, Birla Carbon announced Greenfield Expansions in the Asia Pacific region. The company shall expand its carbon black capacity by over 240 kilotons in the identified locations of India and Thailand
Specialty Carbon Black Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.5 billion
Estimated market size in 2026
USD 3.8 billion
Projected market size by 2033
USD 7.9 billion
Growth rate
CAGR of 10.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Grade, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Russia; China; Japan; India; South Korea; Southeast Asia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Omsk Carbon Group; Tokai Carbon Co., Ltd.; Atlas Organics Private Limited; Continental Carbon Company; Birla Carbon; Cabot Corporation; Oak Investment Partners; Himadri Specialty Chemical Ltd; Philips Carbon Black Limited; Orion S.A.; Ralson.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Specialty Carbon Black Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global specialty carbon black market report based on grade and region.
 To learn more about this report, Download Free Sample Report
-
Grade Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Conductive Carbon Black
-
Conductive Polymers
-
Paints & Coatings
-
Battery Electrodes
-
Printing Inks
-
Others
-
-
Fiber Carbon Black
-
Polyester Fiber
-
Pp Masterbatches
-
Nylon Textiles
-
Other Synthetic Fibers
-
-
Food Contact Carbon Black
-
Packaging
-
Film & Sheet
-
Consumer Molded Parts
-
Others
-
Other Carbon Black
-
-
-
Regional Outlook (Revenue, USD million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The specialty carbon black market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each specialty carbon black segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Grade
Revenue capture definition
Conductive
Revenue generated from specialty carbon black grades designed to provide electrical conductivity and electrostatic discharge (ESD) protection in applications such as lithium-ion batteries, conductive plastics, cables, electronic components, industrial packaging, and automotive systems. Market revenue is captured through sales of high-conductivity carbon black products used to enhance electrical performance and energy storage efficiency.
Fiber
Revenue generated from specialty carbon black grades utilized in synthetic fibers, nonwoven materials, technical textiles, and polymer fiber applications. These products provide coloration, UV protection, conductivity, and enhanced durability to fiber-based materials used across automotive, industrial, construction, and consumer applications.
Food Contact
Revenue generated from specialty carbon black grades that comply with food-contact regulations and are used in food packaging materials, food-processing equipment components, beverage closures, and other applications requiring regulatory-approved black pigmentation, UV resistance, and material protection. Revenue is captured through the supply of certified carbon black products meeting applicable food safety standards.
Others
Revenue generated from specialty carbon black grades used in a broad range of applications including coatings, printing inks, toners, sealants, adhesives, rubber goods, engineering plastics, construction materials, and specialty industrial products. This segment captures sales of customized and application-specific carbon black formulations that do not fall under the conductive, fiber, or food-contact categories.
Estimation Model
Layer Name
Key Question
Description
Carbon Black Production Layer
What forms is the supply base?
Identify global production capacity of specialty carbon black supported by feedstock availability, manufacturing technologies, furnace and specialty-grade production facilities, conductive carbon black capacity, pigment-grade manufacturing infrastructure, and regional production capabilities. This establishes the foundational supply base available for specialty carbon black applications worldwide.
End-Use Industry Adoption Layer
Where is specialty carbon black utilized?
Estimate the proportion of specialty carbon black consumed across plastics, coatings, inks & toners, batteries, electronics, automotive components, packaging materials, and other industrial applications based on performance requirements, conductivity needs, coloration demand, UV protection requirements, and industry adoption trends.
Consumption Intensity Layer
How much specialty carbon black is used?
Analyze application-specific loading rates, conductivity requirements, pigmentation intensity, polymer incorporation levels, formulation standards, manufacturing practices, and regional industrial production trends to determine annual specialty carbon black consumption across major end-use sectors.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of carbon black grades, conductive carbon black products, pigment black formulations, high-performance carbon additives, and customized specialty compounds supplied to plastics manufacturers, battery producers, coating companies, printing ink manufacturers, electronics suppliers, automotive component manufacturers, and industrial processors worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between specialty carbon black grades, end-use industries, and application areas. Analysis identifies consumption patterns, demand concentration, conductivity requirements, pigment utilization trends, and revenue contribution across intersecting segments such as conductive carbon black in batteries, pigment carbon black in coatings and inks, and UV-protection grades in plastics.
Supports product portfolio optimization and market prioritization by identifying the most attractive grade-application-industry combinations, enabling improved resource allocation, sales targeting, capacity planning, and strategic growth initiatives.
Competitive Benchmarking
Comparative evaluation of leading specialty carbon black manufacturers based on product portfolio breadth, conductive carbon black capabilities, manufacturing capacity, geographic presence, sustainability initiatives, battery-material expertise, customer relationships, production footprint, and strategic developments across key regional markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing deeper visibility into market positioning, technological strengths, differentiation strategies, innovation capabilities, and areas of competitive advantage.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with electric vehicle battery expansion, energy storage systems, conductive plastics, advanced electronics, high-performance coatings, sustainable materials, recovered carbon black technologies, and increasing demand for specialty additives across industrial applications.
Helps identify high-growth investment areas, emerging application opportunities, technology development priorities, and market expansion strategies, supporting long-term revenue growth and competitive positioning across the specialty carbon black value chain.
Frequently Asked Questions About This Report
The global specialty carbon black market size was valued at USD 3.5 billion in 2025 and is estimated at USD 3.8 billion for 2026.
The global specialty carbon black market is expected to grow at a CAGR of 10.9% from 2026 to 2033, reaching USD 7.9 billion by 2033.
Asia Pacific is the fastest-growing region over the forecast period.
The food contact segment led with a 30.9% revenue share in 2025, while the conductive segment is the fastest-growing.
Asia Pacific dominated with a 46.3%% revenue share in 2025.
Key players include Key players include Omsk Carbon Group; Tokai Carbon Co., Ltd.; Atlas Organics Private Limited; Continental Carbon Company; Birla Carbon; Cabot Corporation; Oak Investment Partners; Himadri Specialty Chemical Ltd; Philips Carbon Black Limited; Orion S.A.; Ralson.
Key factors include surging demand for the product as reinforcing agents, especially in tires.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


