
- Home
- »
- Next Generation Technologies
- »
-
Sports Technology Market Size & Share Report, 2026-2033GVR Report cover

Sports Technology Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Devices, Smart Stadium, Analytics & Statistics, Esports), By Sport (American Football/Rugby, Baseball, Basketball, Cricket, Golf, Ice Hockey), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$23.0BMarket Estimate, 2026
$28.1BMarket Forecast, 2033
$119.6BCAGR, 2026–2033
23.0%Sports Technology Market Summary
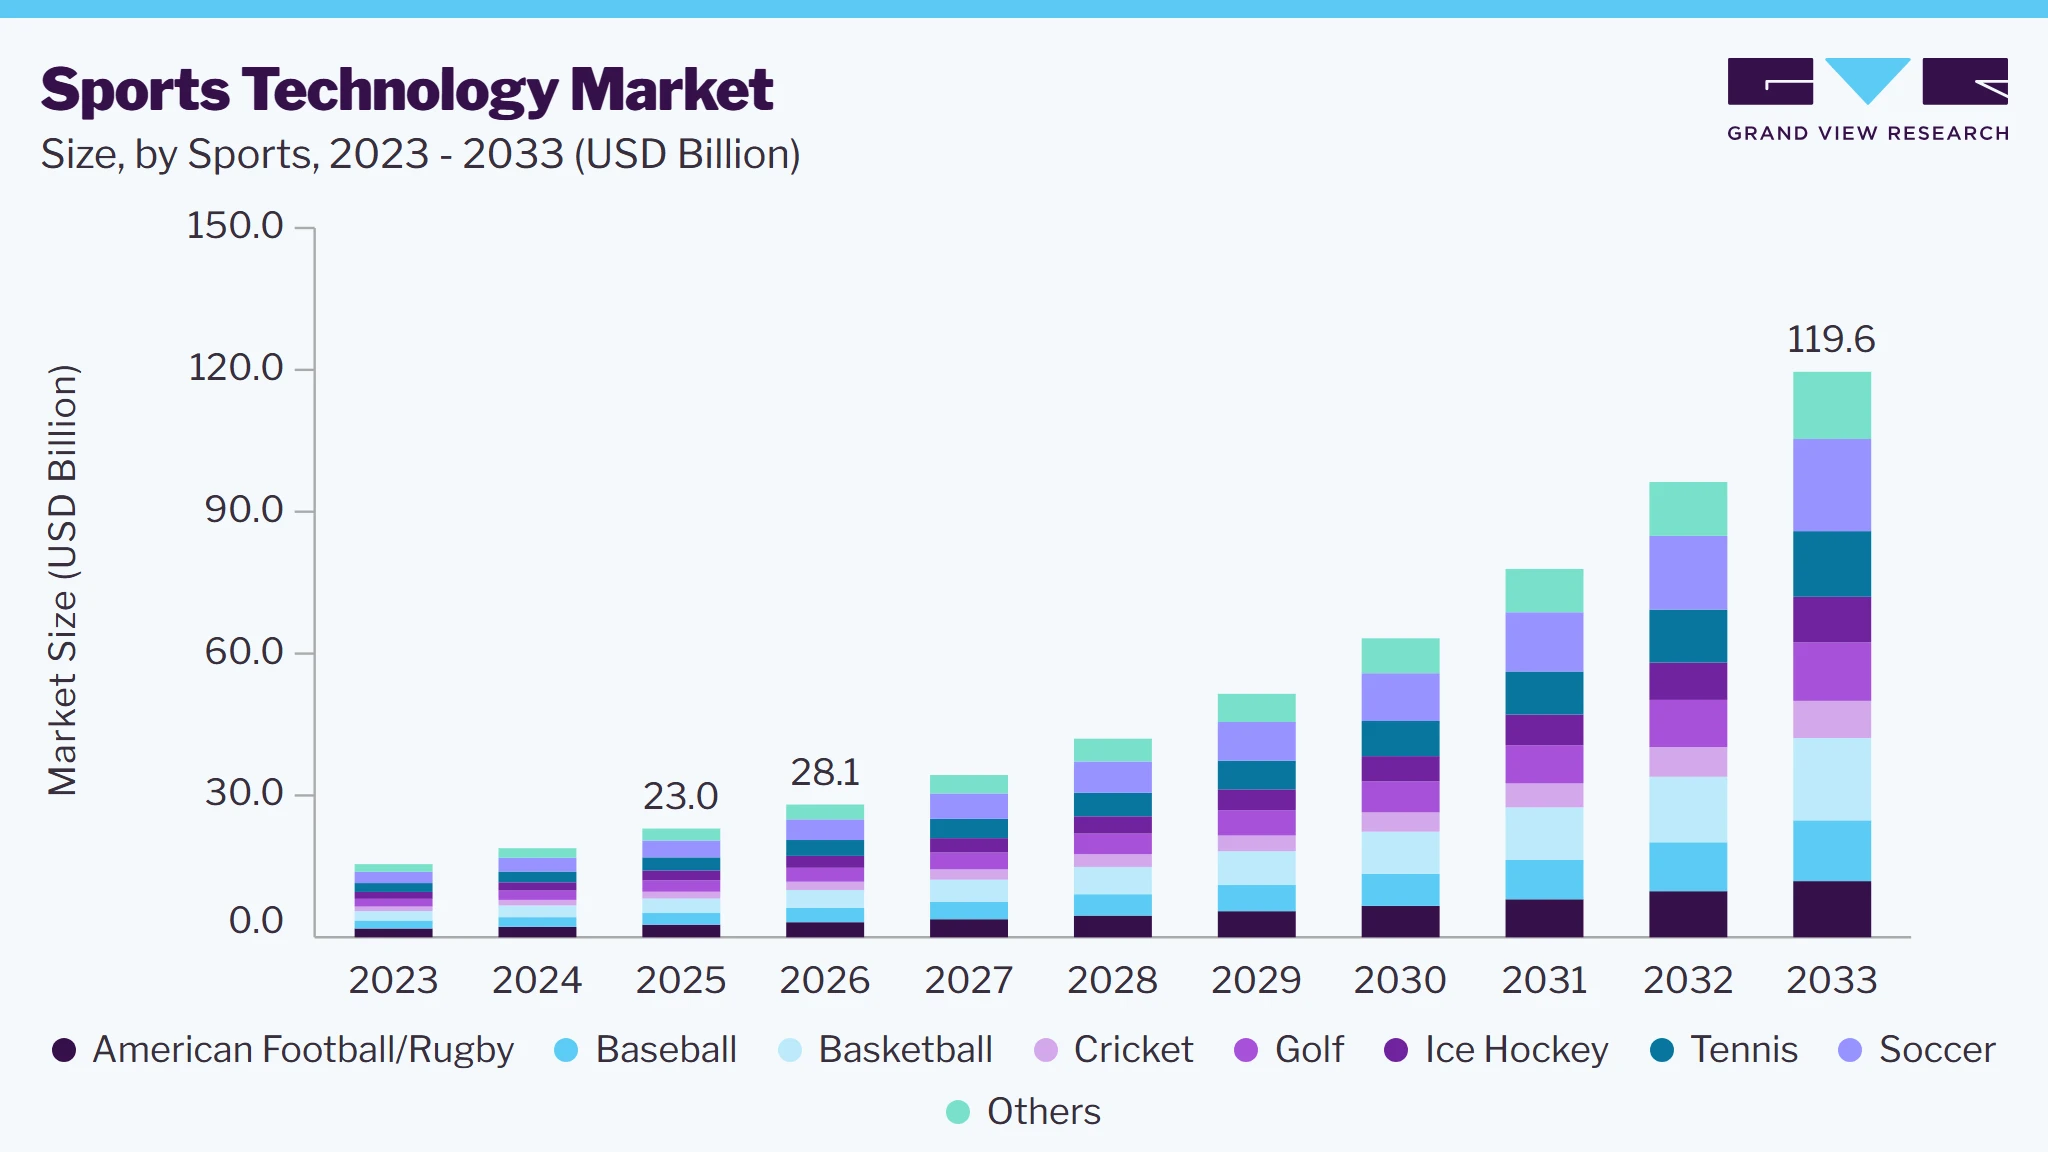
The global sports technology market size was valued at USD 23.0 billion in 2025 and is projected to grow from USD 28.1 billion in 2026 to USD 119.6 billion by 2033, at a CAGR of 23.0% from 2026 to 2033. Europe dominated the global market with the largest revenue share of 30.1% in 2025. The sports technology market is driven by the increasing adoption of data-driven performance analytics and AI-enabled training systems.
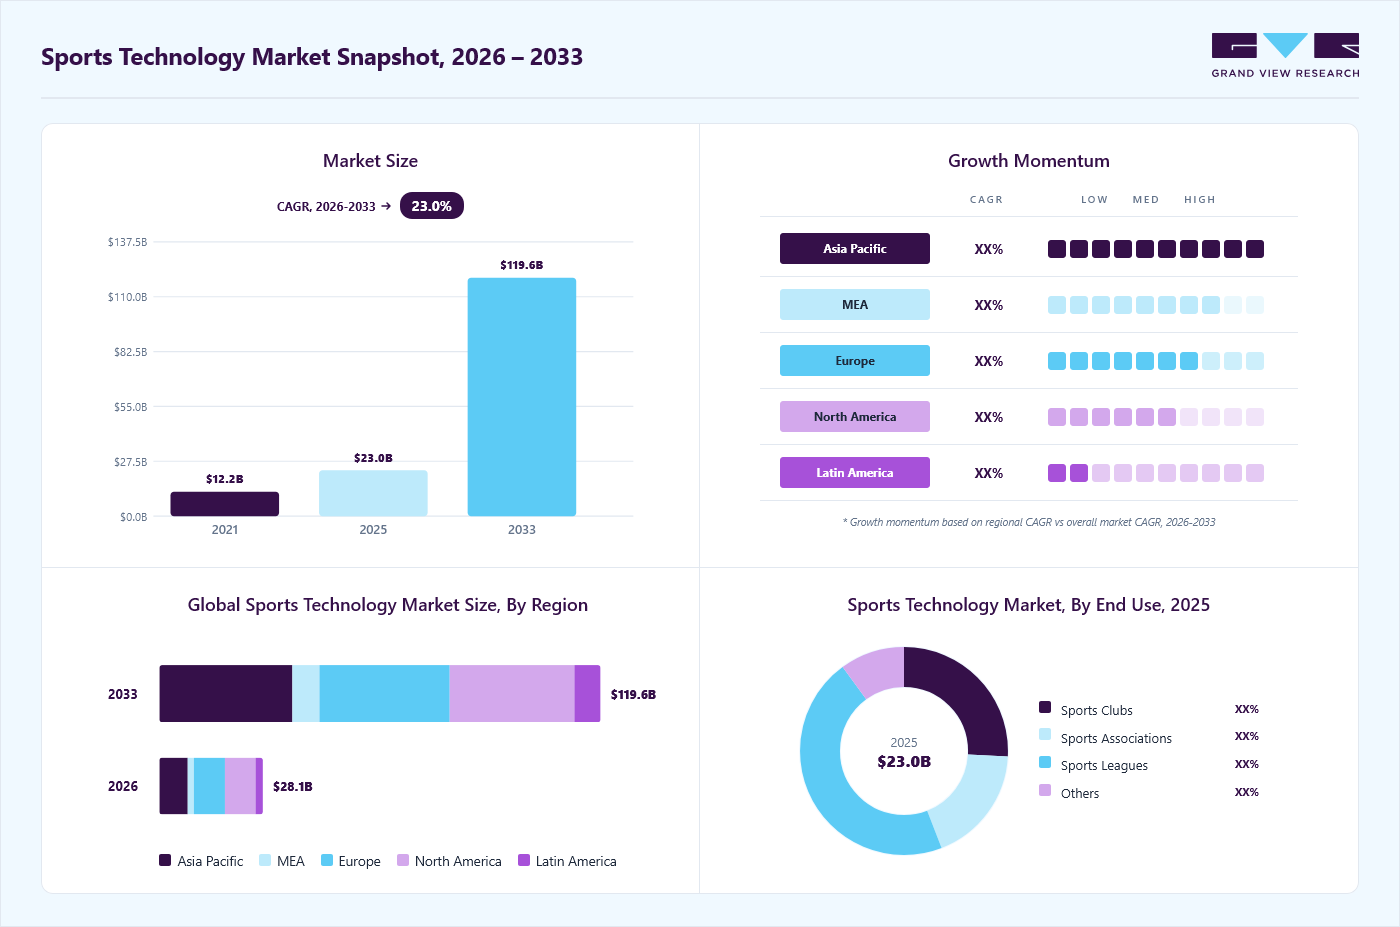 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The smart stadium segment dominated the market, with a share of 54.6% in 2025.
- By sports: The soccer segment accounted for the largest market share of 15.5% in 2025.
- By end use: The sports leagues segment held the largest market share in 2025.
Key Market Trends & Insights
- Largest regional market: Europe (30.1% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By Country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 23.0 Billion
- Estimated market size in 2026: USD 28.1 Billion
- Projected market size by 2033: USD 119.6 Billion
- CAGR (2026-2033): 23.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing integration of wearable devices and biometric sensors is enhancing real-time monitoring of physical parameters, improving coaching efficiency. The expansion of connected sports ecosystems, cloud-based platforms, and sensor-enabled tracking technologies is strengthening performance analysis, operational efficiency, and audience interaction across global sports applications.Immersive technologies, including virtual reality (VR) and augmented reality (AR), are revolutionizing the fan experience in the sports technology industry by offering innovative ways to engage with games. AR overlays provide real-time stats, player data, and interactive visuals during live matches, enriching the overall viewing experience. On the other hand, VR allows fans to witness games from a player’s perspective or virtually attend matches from the comfort of their own home, a trend gaining traction in the sports technology industry. These immersive solutions are also being implemented for athlete training, enabling players to simulate game scenarios in a controlled, virtual environment. The increasing demand for personalized, immersive experiences is propelling investments in VR and AR within the sports technology industry as more organizations look to enhance fan engagement and provide dynamic, interactive content.
 To learn more about this report, Download Free Sample Report
The sports technology industry is also being influenced by the integration of artificial intelligence (AI) to monitor athletes' health, fitness, and safety. AI-powered wearable devices, such as smartwatches and heart rate monitors, track players’ activity off the field, helping ensure safety during training and workouts. For example, NASCAR utilizes deep learning to analyze data patterns, which can be applied across various commercial sectors, including voice recognition and computer vision. In the sports technology industry, AI is proving essential in keeping track of player health while optimizing performance both on and off the field.
Wearable technology, including fitness trackers, smart apparel, and sensor-embedded equipment, is transforming the sports technology industry by allowing athletes to monitor and enhance their performance in real time. These devices provide essential data on heart rate, speed, movement, and energy use, enabling athletes and coaches to make more informed decisions. For example, in team sports like soccer and rugby, GPS trackers are used to analyze player positioning and workload, which helps reduce injury risks. In addition, advanced biosensors in the sports technology industry now allow tracking of hydration, fatigue, and recovery, further the adoption of wearable technology across both professional and amateur sports globally.
AI and machine learning are being widely used in the sports technology industry to analyze vast amounts of data and offer actionable insights. These technologies empower teams to predict player performance, create strategic game plans, and scout talent by analyzing gameplay footage. AI-powered video analytics, for example, can identify patterns and behaviors of opposing teams, providing a competitive advantage. Moreover, predictive algorithms in the sports technology industry are being used to assess injury risks by correlating player biomechanics with historical data, significantly improving the accuracy and efficiency of sports management and coaching.
Market Dynamics
Sports technology is witnessing rapid adoption across professional sports, fitness, and recreational ecosystems, offering advanced capabilities in performance tracking, athlete monitoring, and data-driven decision-making through AI, machine learning, wearable sensors, and computer vision-based analytics. These solutions enable teams and coaches to optimize training workloads, reduce injury risk, and enhance tactical strategies, thereby improving overall athletic performance and efficiency. The growing shift toward connected sports environments, smart stadiums, and immersive fan engagement platforms, coupled with rising investments in digital infrastructure, cloud-based analytics, and real-time broadcasting technologies, is expected to continue driving strong growth in the sports technology market.
The increasing adoption of advanced analytics, artificial intelligence, and machine learning solutions is significantly driving the transformation of modern sports ecosystems. Teams, leagues, and training organizations are leveraging real-time data insights to evaluate player performance, optimize training schedules, and enhance tactical decision-making. Wearable devices and sensor-based tracking systems further support continuous monitoring of athlete health and workload, enabling injury prevention and improved recovery management, thereby strengthening operational efficiency across competitive sports environments.
Data-centric platforms are also reshaping coaching methodologies by enabling predictive modeling of player outcomes and match strategies. Organizations are increasingly integrating video analytics and computer vision tools to assess gameplay patterns and identify performance gaps. This shift toward evidence-based decision-making is improving competitive outcomes while reducing reliance on traditional observational methods. As digital transformation deepens, analytics-driven systems are becoming essential for performance optimization across all levels of organized sports.
The deployment of advanced sports technologies requires significant investment in hardware, software platforms, and data infrastructure, which can limit adoption among smaller teams and grassroots organizations. High costs associated with wearable devices, smart stadium systems, and AI-enabled analytics platforms create financial constraints, particularly in developing regions. Additionally, ongoing maintenance, system integration, and skilled personnel requirements further increase operational expenses, thereby restricting widespread implementation across all levels of the sports ecosystem.
The complexity of integrating multiple technologies into existing sports frameworks also presents operational challenges. Many organizations struggle to manage the large volumes of data generated by sensors, cameras, and tracking systems due to limited technical expertise. Concerns related to cybersecurity, data privacy, and system interoperability further slow down adoption. These barriers collectively hinder seamless scalability and create disparities between well-funded professional teams and lower-tier sports institutions.
The increasing demand for immersive and interactive fan experiences is creating new opportunities for innovation in sports ecosystems. Technologies such as augmented reality, virtual reality, and AI-driven personalization are enabling fans to engage with live events in more dynamic and customized ways. Smart stadiums equipped with high-speed connectivity and real-time data platforms are enhancing in-venue experiences through instant replays, digital ticketing, and interactive content delivery systems.
Digital broadcasting platforms are evolving to incorporate advanced analytics and personalized viewing experiences, allowing fans to access tailored statistics and multi-angle coverage. Sports organizations are increasingly monetizing fan engagement through subscription-based models, digital content ecosystems, and interactive applications. This shift toward experience-driven consumption is opening new revenue channels while strengthening long-term audience loyalty across global sports environments.
Market Concentration & Characteristics
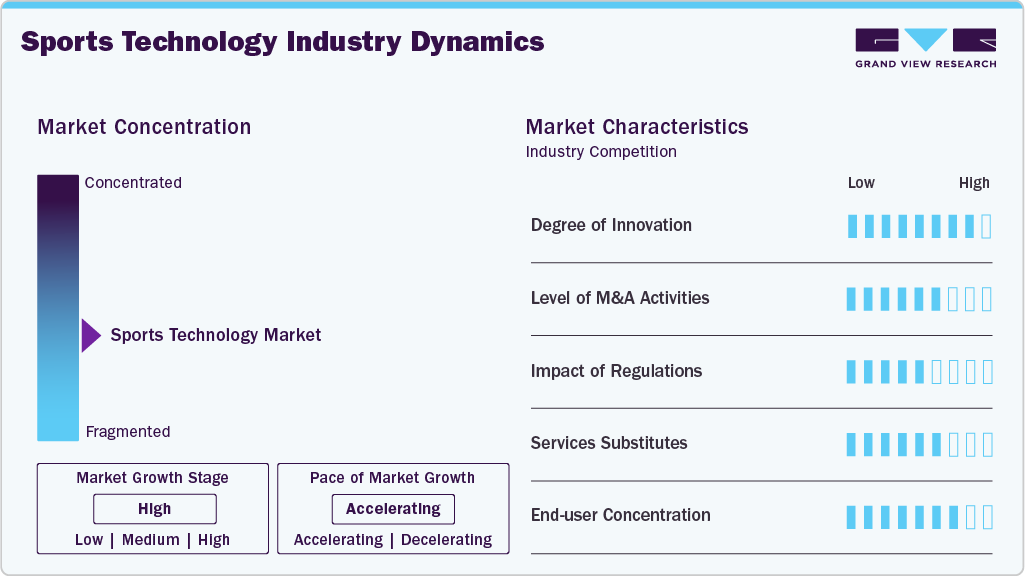
The sports technology market is moderately fragmented, comprising global technology companies, sports analytics providers, wearable device manufacturers, software developers, and a wide base of niche startups specializing in performance tracking, video analytics, and fan engagement solutions. The market is expanding due to rising adoption of data-driven performance optimization tools, increasing integration of wearable and sensor-based monitoring systems, and growing deployment of smart stadiums. Strategic collaborations between technology providers, sports organizations, and broadcasting networks are becoming increasingly common as stakeholders focus on improving athlete performance and fan experience. Continuous advancements in artificial intelligence, machine learning algorithms, computer vision systems, and cloud-based analytics platforms are emerging as key competitive strategies across the market.
 To learn more about this report, Download Free Sample Report
The market is characterized by a very high level of innovation, driven by rapid developments in real-time performance analytics, biometric tracking devices, immersive AR/VR-based fan engagement systems, and AI-powered coaching tools. The industry is witnessing moderate to high merger and acquisition activity as large technology firms acquire specialized analytics and wearable technology startups to strengthen ecosystem capabilities and expand product offerings. Competition from traditional coaching methods and legacy broadcasting systems remains moderate, but digital and data-driven solutions continue to gain strong adoption. Increasing investments in smart stadium infrastructure, connected sports ecosystems, and digital fan engagement platforms are expected to further strengthen demand across the sports technology market.
Analyst Perspective
The sports technology market is experiencing strong expansion driven by the increasing adoption of data-driven performance analytics, the rising use of wearable and sensor-based monitoring systems, and the growing integration of AI and machine learning across training and competition environments. The industry is benefiting from a shift toward connected sports ecosystems, where real-time performance tracking, injury prevention, and strategic decision-making are becoming central to team and athlete development. Continuous advancements in computer vision, cloud-based analytics platforms, and immersive fan engagement technologies are further accelerating digital transformation across professional sports leagues, training academies, and global sporting events.
Type Insights
Based on type, the smart stadium segment led the market with the largest revenue share of 54.6% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The integration of IoT (Internet of Things) technology is transforming smart stadiums by providing fans with real-time, interactive experiences. Mobile apps are playing a central role in this transformation, offering fans the ability to access personalized services such as seat upgrades, in-seat ordering, and live event updates. These technologies not only enhance the convenience of attending live events but also help teams and stadium operators better understand fan preferences. With data collected from IoT devices, teams can offer targeted promotions and customized experiences. This increased engagement boosts fan loyalty and drives new revenue streams for sports organizations.
The analytics & statistics segment is projected to register the fastest CAGR of over 29% from 2025 to 2030. The role of analytics extends beyond athletes to fan engagement, where data is used to personalize the fan experience. By collecting data from ticketing, mobile apps, and IoT devices, teams can understand fan behavior and preferences. This information is then used to offer customized experiences, such as personalized promotions, optimized seating arrangements, or curated content. Analytics also helps identify trends in fan interactions and predict future behaviors, enabling sports organizations to tailor marketing efforts and improve customer service. Ultimately, data-driven insights are enhancing how teams build stronger relationships with their fan base and boost loyalty.
Sports Insights
Based on sports, the soccer segment led the market with the largest revenue share of 15.5% in 2025. The integration of wearable technology in soccer is revolutionizing how athletes monitor their performance and health. Devices such as smart shirts, vests, and GPS trackers allow coaches and players to track metrics like heart rate, speed, distance covered, and player load during matches and training. These wearables provide real-time data that help in assessing player fitness and preventing injuries by identifying early signs of fatigue or strain. The data collected also informs training programs, making them more personalized and effective. As technology advances, there is a growing emphasis on wearables that can also monitor biomechanics, providing deeper insights into movement patterns and potential injury risks.
The basketball segment is anticipated to record the fastest CAGR from 2025 to 2030. The use of analytics and data-driven coaching is transforming how basketball teams evaluate players and develop strategies. Advanced statistical tools provide insights into player performance across a wide range of metrics, such as shooting efficiency, player movement, and defensive positioning. Coaches and front-office staff use this data to refine strategies, matchups, and in-game decisions to maximize team performance. Player tracking technology, such as cameras and motion sensors, enables teams to assess player positioning and movement both on and off the ball. By leveraging data analytics, teams can make more informed decisions, from drafting new players to fine-tuning their game plans for upcoming matches.
End Use Insights
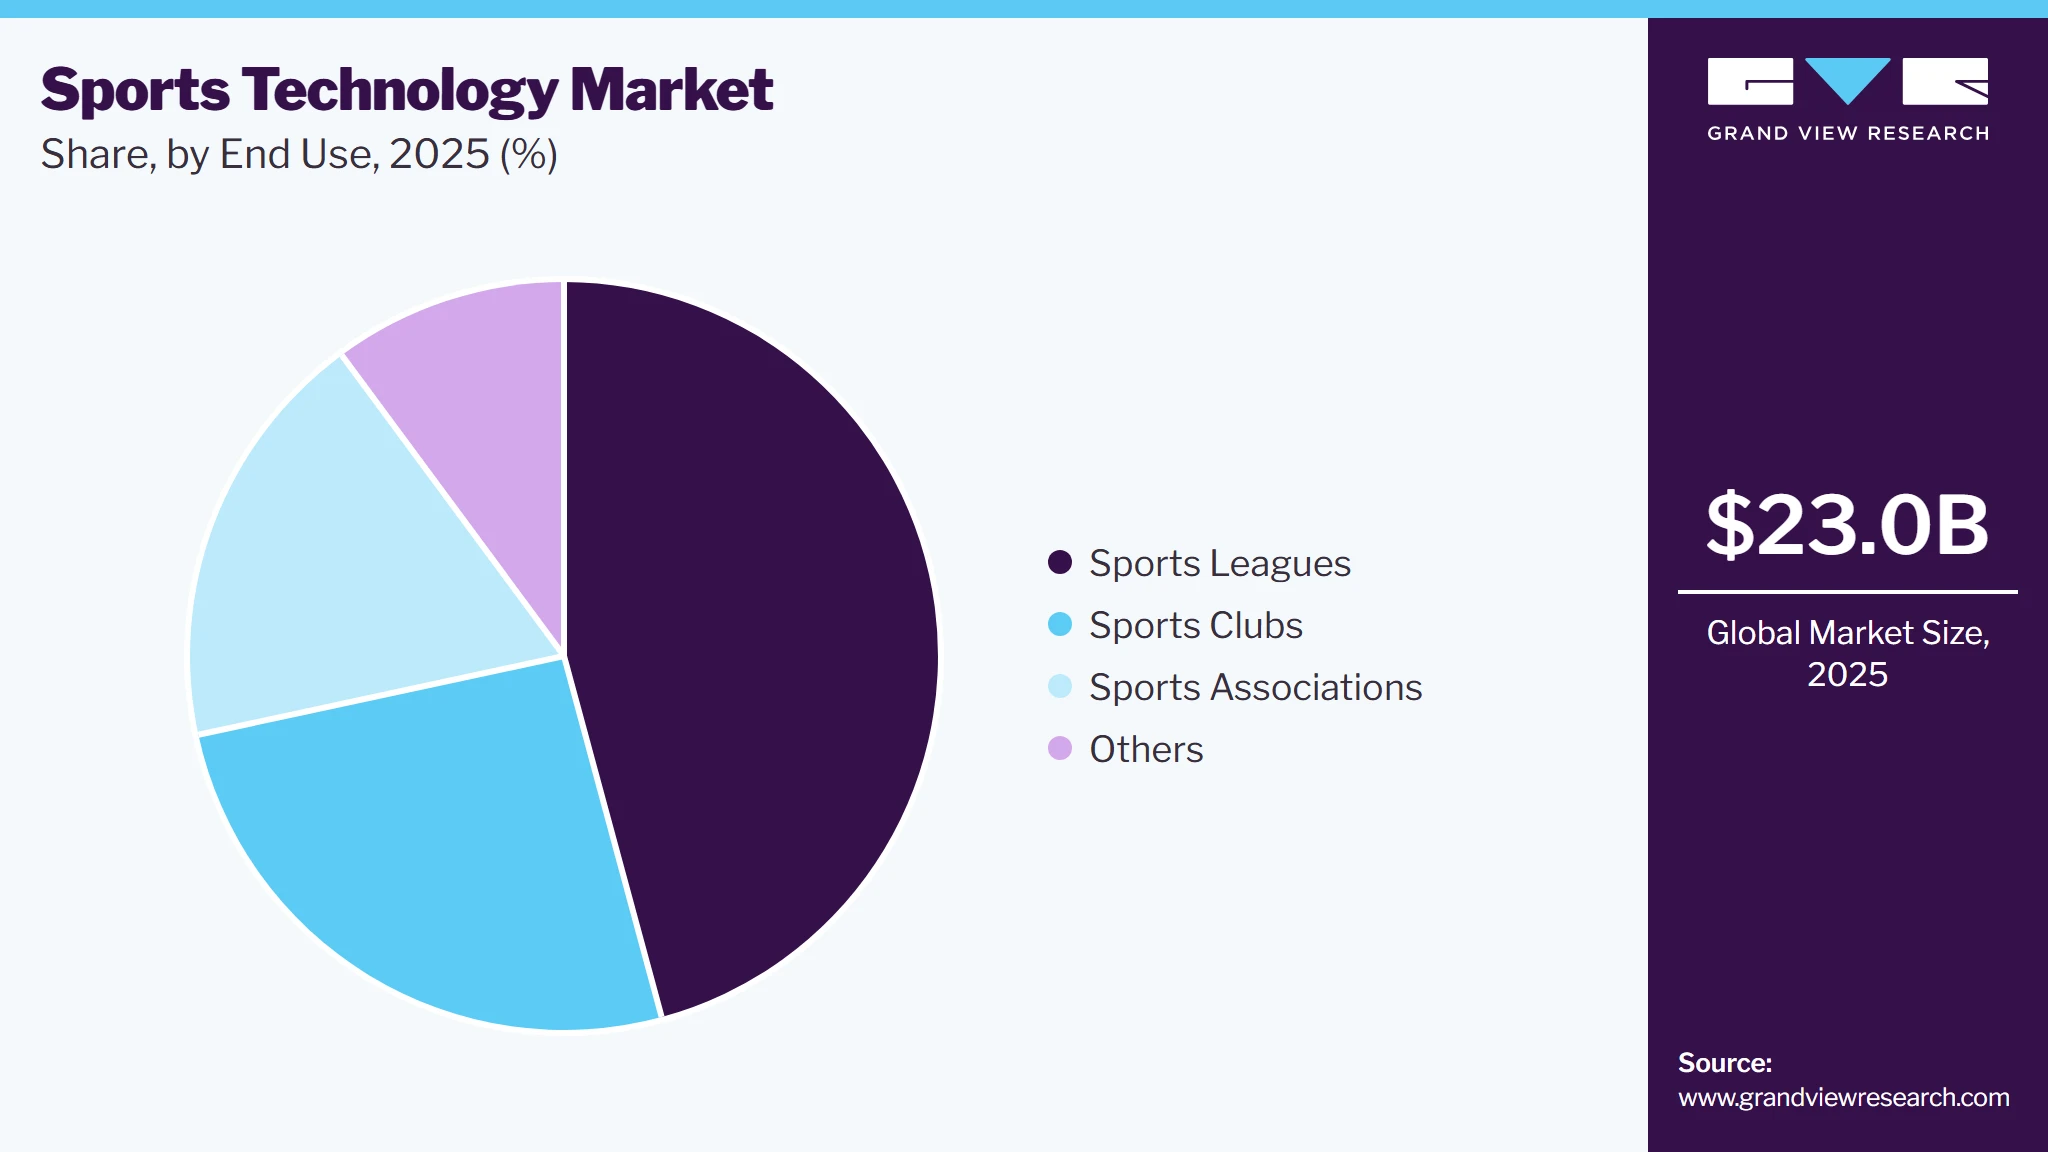
Based on end use, the sports leagues segment dominated the market with the largest revenue share of 45.8% in 2025, The growing acceptance of sports betting is reshaping how sports leagues operate, particularly in North America. With many leagues entering partnerships with betting platforms, they are creating new revenue streams while offering fans more ways to engage in their favorite sports. Legalized sports betting also brings in new data opportunities, as fan behavior and bet predictions are now tracked and analyzed for marketing and strategy. However, there are concerns about integrity and the potential for match-fixing, prompting leagues to establish tighter regulations and monitoring systems. As betting becomes more integrated into the sports ecosystem, leagues will need to balance revenue opportunities with maintaining the sport's integrity.
 To learn more about this report, Download Free Sample Report
The sports associations segment is anticipated to record the fastest CAGR from 2025 to 2030. Sports associations are embracing cutting-edge technology to enhance the sports experience for both athletes and fans. The use of data analytics, wearables, and advanced video analysis is helping associations improve player performance and make data-driven decisions in competitions. In addition, technology is enhancing fan engagement through virtual reality, augmented reality, and interactive apps that offer real-time statistics, live broadcasts, and unique content. Many associations are investing in digital platforms to engage fans in new ways, particularly as more events are streamed online. With technology continuing to evolve, sports associations are likely to continue integrating innovative solutions that improve both athletic performance and fan experience.
Regional Insights
The North America sports technology market held the largest global revenue share of over 28% in 2024. In North America, traditional sports like American football, basketball, and baseball have long dominated the market, but emerging sports are now gaining attention. Sports such as soccer, esports, and mixed martial arts (MMA) are becoming increasingly popular, with younger generations driving this shift. Major sports leagues like the NFL and NBA are expanding their reach by hosting international games, while soccer leagues like MLS are attracting top global talent and boosting their fanbase. Esports is also thriving, with big brands investing in sponsorships, tournaments, and gaming events. As sports diversification continues, North America is likely to become a hub for more niche sports and innovative fan experiences.
U.S. Sports Technology Market Trends
The sports technology market in the U.S. held the largest share in the North America region in 2025. In the U.S., sports are deeply woven into the fabric of culture, with major leagues like the NFL, NBA, MLB, and NHL leading the charge. The U.S. also stands as a global leader in sports entertainment, with events like the Super Bowl and the NBA Finals attracting massive audiences. With the integration of sports betting becoming more widespread, the U.S. is also seeing a significant shift in fan behavior, adding new layers to the sports experience. The rise of alternative sports such as soccer (MLS) and esports (through platforms like Twitch and the growth of leagues like the eMLS) is reshaping the American sports market.
Europe Sports Technology Market Trends
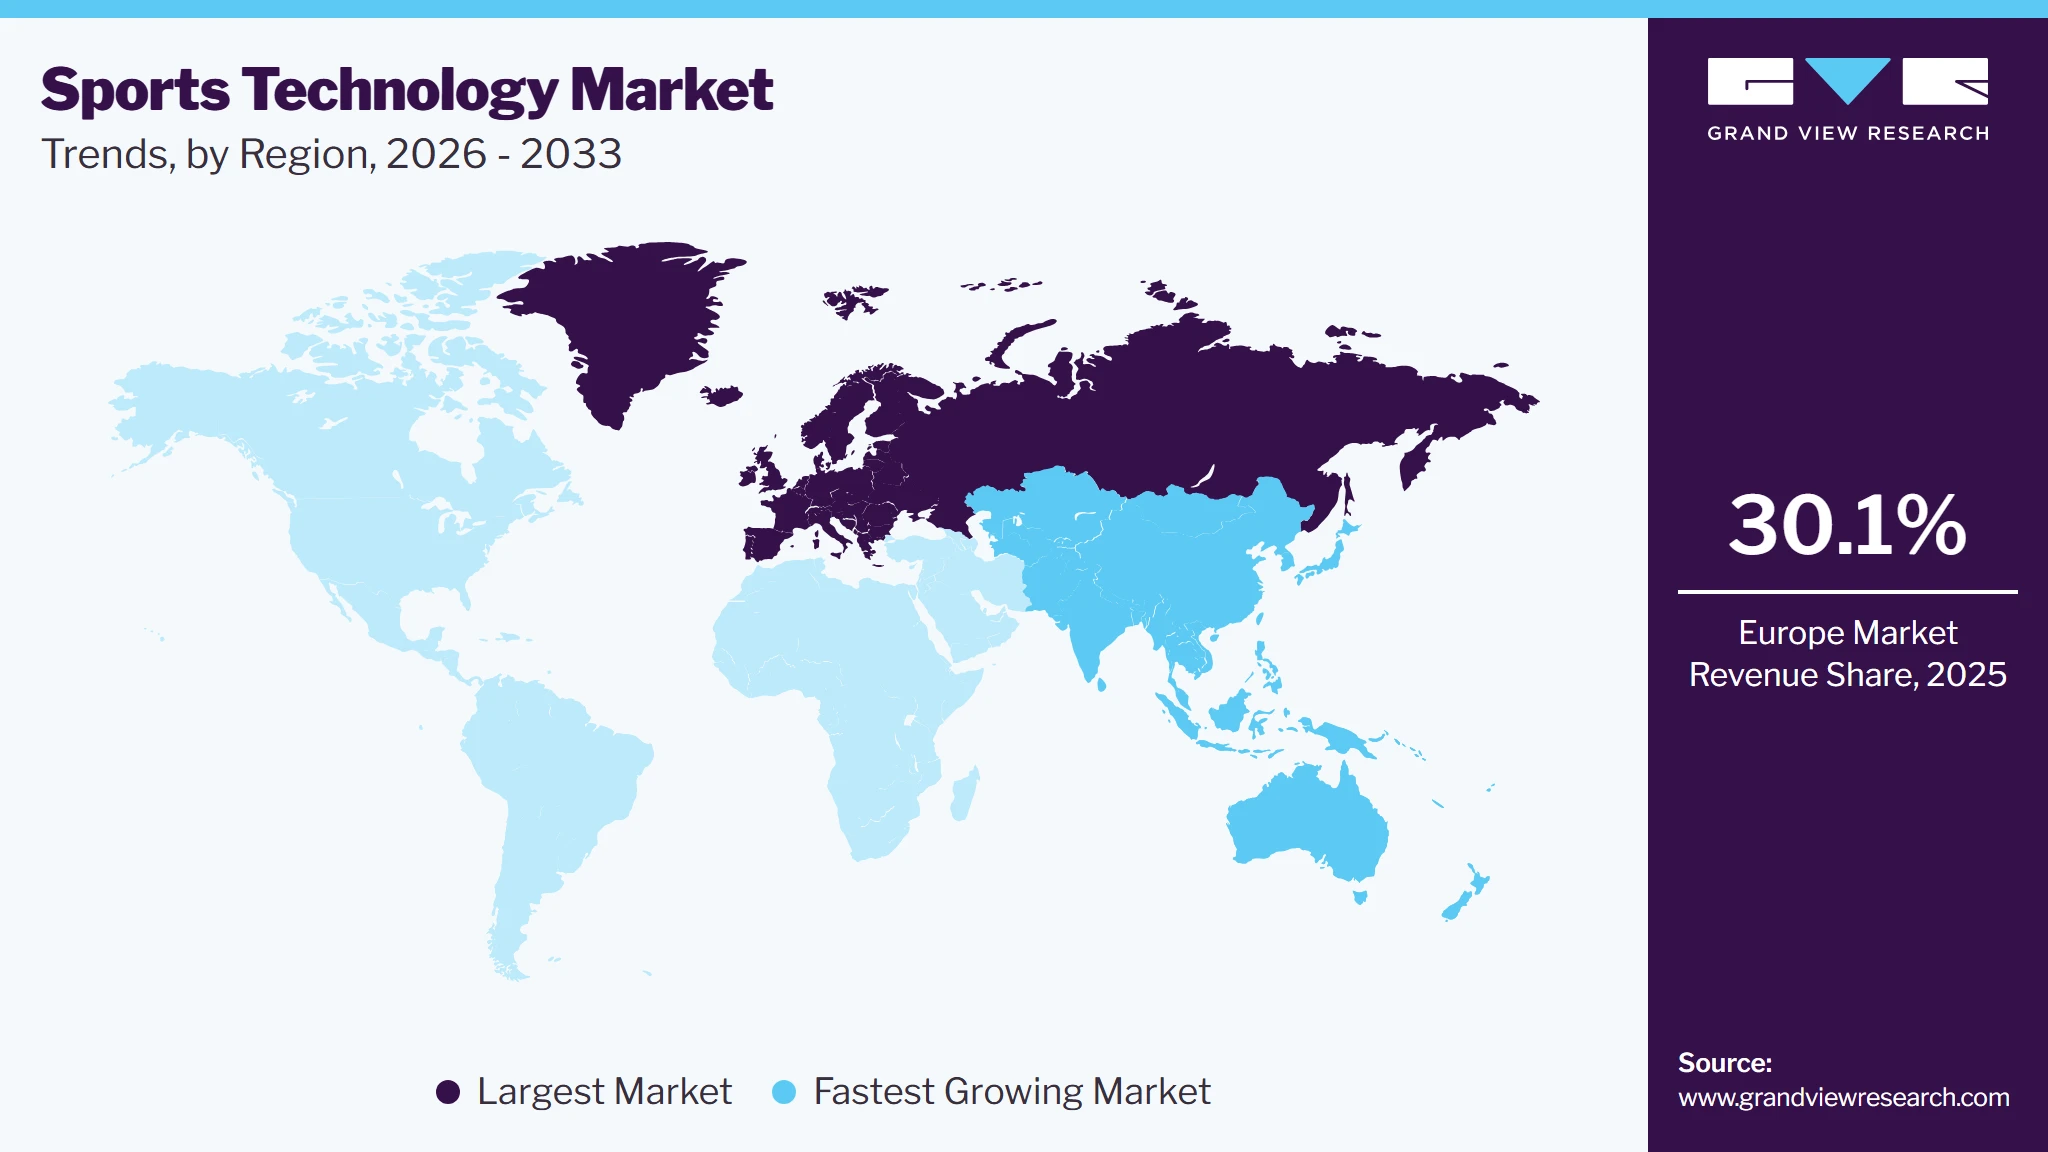
Europe dominated the sports technology market with the largest revenue share of 30.1% in 2025. Europe remains the heart of many of the world’s most prestigious traditional sports leagues, especially in soccer, rugby, and tennis. Countries like the UK, Spain, Italy, and Germany are home to some of the biggest soccer clubs, with global fanbases and immense commercial value through broadcasting rights and sponsorships. The UEFA Champions League, Premier League, and La Liga are just a few examples of high-profile European competitions that attract millions of fans worldwide. Moreover, Europe is also witnessing the rise of niche sports, including handball, motorsports, and cycling, as fan bases grow and tournaments become more accessible. The strong infrastructure, rich history, and competitive leagues will continue to solidify Europe's position as a dominant force in global sports.
 To learn more about this report, Download Free Sample Report
The UK sports technology industry is expected to grow rapidly in the coming years. The UK remains a key player in global sports, particularly through the world-renowned English Premier League, which attracts top talent and global viewership. Rugby and cricket are also integral parts of British culture, with iconic events like the Six Nations and the British Open. The UK continues to innovate in fan engagement and sports technology, ensuring its place as a leader in both traditional and emerging sports.
The Germany sports technology industry held a substantial market share in 2024. Germany is known for its excellence in football, with the Bundesliga offering highly competitive matches and Bayern Munich maintaining global prominence. The country is also a major player in motorsports, cycling, and Olympic disciplines, consistently excelling in international competitions. Germany's focus on sports science and advanced technology has played a key role in its continued success across various sporting arenas.
Asia-Pacific Sports Technology Market Trends
The Asia-Pacific sports technology industry is projected to grow at the fastest CAGR of over 24% from 2025 to 2030. The Asia Pacific region is experiencing a rapid transformation in the sports sector, driven by increased investment, infrastructure development, and an expanding middle class. Countries like China, Japan, and India are heavily investing in sports, with an emphasis on soccer, basketball, and cricket. The Chinese government has also set ambitious goals to turn China into a global sports powerhouse by 2030. The region is seeing a surge in fan engagement through digital platforms and the growing presence of international sports leagues and events. Esports is particularly booming in countries like South Korea and China, with large-scale competitions and sponsorships creating a million-dollar industry. As the Asia Pacific market continues to evolve, it will become an increasingly important player in the global sports landscape.
Japan sports technology industry blends tradition and modernity in its sports culture, with baseball and soccer being central to its sports scene. The Tokyo 2020 Olympics showcased Japan's ability to integrate cutting-edge technology, such as robotics and augmented reality, with sporting events. In addition, esports are rapidly growing, making Japan one of the largest esports markets in Asia and contributing to the country's evolving sports landscape.
China sports technology industry has been making significant investments in sports, with the government aiming to make the country a global sports leader by 2030. Soccer is a key focus, with the Chinese Super League attracting big-name players, and basketball is also immensely popular, particularly with the NBA's strong fanbase. The government's emphasis on building sports infrastructure and grassroots programs is helping to foster a sustainable sports culture for future generations.
Key Sports Technology Company Insights
Some of the key players operating in the market include IBM Corporation, and SAP SE, among others.
-
IBM Corporation has long been a leader in sports technology, specializing in artificial intelligence, data analytics, and cloud computing solutions for the sports industry. They have revolutionized fan engagement with their AI-powered platforms, like Watson, which enhances the sports viewing experience through predictive analytics and real-time data. IBM is also a key partner for major sports events like the US Open and Wimbledon, where they provide advanced data processing and analytics services. Their long-standing history in the tech space positions IBM as a trusted and innovative company in sports technology.
-
SAP SE is a mature leader in the sports technology industry, specializing in enterprise resource planning (ERP) solutions and data analytics tailored for sports organizations. SAP provides sports leagues, teams, and event organizers with tools to streamline operations, manage player performance, and enhance fan engagement. Their software solutions help sports businesses with everything from ticketing to merchandise sales, creating efficient, data-driven operations. As sports organizations increasingly rely on technology for decision-making, SAP continues to be a key player in optimizing the operational side of sports industries.
Some of the emerging market players in the sports technology industry include Dream Sports Group and Genius Sports Group, among others.
-
Dream Sports Group, the parent company of platforms like Dream11, has rapidly grown into a leading player in the fantasy sports and sports technology industry. Known for pioneering the fantasy sports ecosystem in India, it now focuses on expanding its offerings into mobile gaming, esports, and online betting. The company's AI-driven platform provides users with personalized fantasy sports experiences, leveraging data analytics to enhance player engagement. With a growing user base and investments in technology, Dream Sports is positioned to become a key player in the global fantasy sports sector.
-
Genius Sports Group has emerged as a trailblazer in the sports data and technology space, offering data-driven solutions for the sports industry. Specializing in real-time sports data and analytics, they provide sports leagues, betting operators, and media companies with comprehensive statistics and insights to enhance fan engagement and business operations. The company’s expertise extends to sports integrity, helping protect leagues and bookmakers from fraudulent activities. As sports betting continues to grow globally, Genius Sports is increasingly playing a central role in the modernization of the sports data ecosystem.
Key Sports Technology Companies
The following are the leading companies in the sports technology market.
-
Apple Inc.
-
Catapult Group
-
ChyronHego Corporation
-
Cisco Systems, Inc.
-
HCL Technologies Limited
-
IBM Corporation
-
Infosys Limited
-
Modern Times Group MTG
-
Oracle
-
Panasonic Corporation
-
SAP SE
-
Sony Corporation
-
Stats LLC
-
Telefonaktiebolaget LM Ericsson
-
Amazon Web Services Inc.
-
DELTATRE
-
Ernst & Young Global Limited
-
Genius Sports Group
-
Microsoft Corporation
-
SAS Institute Inc.
-
Sportradar AG
-
Synergy Sports
-
CBS Sports Digital
-
Draft Kings, Inc
-
Dream 11 (Sporta Technologies Pvt. Ltd.)
-
Dream Sports Group
-
FanDuel Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Microsoft Corporation, IBM Corporation, Cisco Systems, Inc.)
- Established players focus on expanding cloud-based sports analytics, AI platforms, and connected ecosystems globally.
- Invest heavily in scalable digital infrastructure, real-time data processing, and smart sports solutions.
- Strong global presence with advanced cloud, AI, and enterprise technology capabilities.
- Ability to deliver integrated, secure, and high-performance sports data and infrastructure solutions.
- Limited sports-specific specialization compared to dedicated niche analytics providers.
- Large enterprise structures may reduce agility and slow innovation cycles in sports applications.
Emerging Players (Catapult Group, Genius Sports Group, Synergy Sports)
- Focus on developing niche sports analytics platforms, wearable tech, and AI-driven insights.
- Invest in partnerships with leagues and clubs to integrate real-time performance data.
- High innovation agility enabling rapid deployment of advanced sports technology solutions.
- Strong specialization in analytics, tracking systems, and performance optimization tools.
- Limited global scale restricts large enterprise and league-level contract opportunities.
- Dependence on external funding may constrain long-term product development and expansion.
Recent Developments
-
In June 2023, Infosys Limited launched a mobile app aimed at enriching fan experiences at live sports events by integrating augmented reality. This innovation seeks to increase viewer interaction and satisfaction during games. The app focuses on enhancing engagement through immersive features and real-time content.
-
In May 2023, IBM Corporation formed a strategic partnership with a prominent sports league to leverage its cloud solutions for advanced game data analysis. The collaboration is intended to optimize team performance and improve fan engagement by delivering deeper insights. This move reflects IBM’s commitment to using technology to enhance the sports industry.
-
In April 2023, HCL introduced a cutting-edge AI-driven platform designed to enhance athlete performance analytics. By utilizing real-time data, the platform aims to optimize training processes and improve results. This innovation underscores HCL's focus on delivering technology solutions that support sports performance enhancement.
Sports Technology Market Report Scope
Report Attribute
Details
Market size in 2025
USD 23.0 billion
Estimated market size in 2026
USD 28.1 billion
Projected market size by 2033
USD 119.6 billion
Growth rate
CAGR of 23.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, sports, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico, U.K.; Germany; France; China; Australia; Japan; India; South Korea; Brazil; South Africa; Saudi Arabia; UAE
Key companies profiled
Apple, Inc.; Catapult Group; ChyronHego Corp.; Cisco Systems, Inc.; HCL Technologies Ltd.; IBM Corp.; Infosys Ltd.; Modern Times Group MTG; Oracle; Panasonic Corporation; SAP SE; Sony Corporation; Stats LLC; Telefonaktiebolaget LM Ericsson; Amazon Web Services Inc.; DELTATRE; Ernst & Young Global Limited; Genius Sports Group; Microsoft Corporation; SAS Institute Inc.; Sportradar AG; Synergy Sports; CBS Sports Digital; Draft Kings, Inc; Dream 11 (Sporta Technologies Pvt. Ltd.); Dream Sports Group; FanDuel Group.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sports Technology Market Report Segmentation
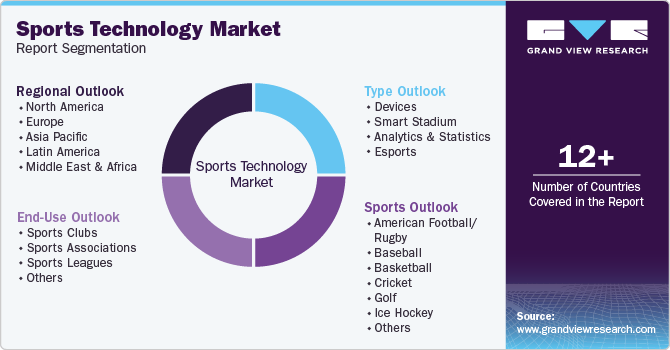
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest technology trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global sports technology market report based on type, sports, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Devices
-
Wearables
-
Digital Signage
-
Camera
-
-
Smart Stadium
-
Software
-
Stadium & Public Security
-
Building Automation
-
Event Management
-
Others
-
-
Services
-
-
Analytics & Statistics
-
On-field
-
Player & Team Analysis
-
Video Analysis
-
Performance Improvement
-
Refereeing Decisions
-
-
Health Assessment
-
-
Off-field
-
Fan Engagement
-
Content Platforms
-
Fan Experience
-
Fantasy Sports
-
-
Ticket Pricing
-
Others
-
-
-
Esports
-
Tickets & Merchandise
-
Sponsorship & Advertisement
-
Others
-
-
-
Sports Outlook (Revenue, USD Million, 2021 - 2033)
-
American Football/Rugby
-
Baseball
-
Basketball
-
Cricket
-
Golf
-
Ice Hockey
-
Tennis
-
Soccer
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Sports Clubs
-
Sports Associations
-
Sports Leagues
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The sports technology market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each sports technology segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Devices
Revenue is generated from wearable technologies, biometric sensors, GPS trackers, and motion-tracking equipment used for real-time monitoring of athlete performance. This segment is driven by increasing demand for injury prevention, workload management, and data-driven training optimization across professional and amateur sports environments.
Smart Stadium
Revenue is generated through integrated stadium technologies, including IoT-enabled infrastructure, digital ticketing systems, connected seating solutions, and real-time crowd management platforms. This segment is driven by the rising need for enhanced spectator experience, operational efficiency, and automated venue management systems.
Analytics & Statistics
Revenue is captured through advanced data analytics platforms that process player performance data, match statistics, predictive modeling, and video analysis. This segment is driven by increasing reliance on artificial intelligence and machine learning tools to improve coaching strategies and competitive decision-making.
Esports
Revenue is generated through digital gaming platforms, streaming infrastructure, tournament management systems, and real-time performance tracking tools. This segment is driven by the rapid expansion of competitive gaming ecosystems, rising global audience engagement, and monetization through digital content models.
Segment - Sports
Revenue capture definition
American Football/Rugby
Revenue is generated through performance-tracking systems, impact-monitoring devices, and tactical analysis platforms that enhance player safety and strategic gameplay. This segment is driven by high physical intensity requirements and strong adoption of analytics-based coaching systems.
Baseball
Revenue is captured through motion tracking, pitching analytics, and video-based performance evaluation systems. This segment is driven by the growing use of precision analytics to improve batting efficiency, pitching accuracy, and the development of game strategy.
Basketball
Revenue is generated through wearable tracking systems, shot analysis tools, and AI-driven performance evaluation platforms. This segment is driven by the increasing adoption of real-time analytics to optimize player positioning, endurance, and tactical execution.
Cricket
Revenue is generated through ball tracking systems, biomechanics analysis tools, and video-assisted decision platforms. This segment is driven by strong demand for data-driven insights in batting, bowling, and fielding performance optimization.
Golf
Revenue is captured through swing analysis systems, GPS-enabled tracking devices, and biomechanical assessment tools. This segment is driven by the growing focus on precision improvement, personalized coaching, and performance consistency.
Ice Hockey
Revenue is generated through player-tracking systems, collision-monitoring sensors, and real-time game analytics platforms. This segment is driven by high-speed gameplay dynamics and increasing focus on safety and tactical optimization.
Tennis
Revenue is captured through line-calling systems, shot tracking technologies, and AI-based match analytics platforms. This segment is driven by strong demand for accurate performance measurement and real-time decision-support systems.
Soccer
Revenue is generated through GPS tracking systems, video analytics platforms, and tactical performance tools used to optimize player and team performance. This segment is driven by global popularity and widespread adoption of data-driven coaching systems.
Others
Revenue is generated through niche sports applications that utilize wearable devices, tracking systems, and analytics platforms tailored to specific athletic requirements. This segment is driven by increasing digital adoption across emerging and less mainstream sports categories.
Segment - End Use
Revenue capture definition
Sports Clubs
Revenue is generated through adoption of performance analytics platforms, wearable tracking devices, and training optimization systems used to improve athlete development. This segment is driven by increasing focus on competitive advantage and injury prevention strategies.
Sports Associations
Revenue is captured through regulatory technology systems, officiating tools, and data governance platforms used to manage sports standards and compliance. This segment is driven by growing demand for standardized performance-monitoring and fair-play enforcement systems.
Sports Leagues
Revenue is generated through the large-scale deployment of analytics infrastructure, broadcasting technologies, and fan engagement platforms. This segment is driven by the high commercialization of sports events and increasing investments in digital transformation initiatives.
Others
Revenue is generated from educational institutions, fitness organizations, and recreational sports providers that adopt basic to advanced sports technology solutions. This segment is driven by rising awareness of fitness tracking and expanding grassroots sports participation.
Estimation Model
Layer Name
Key Question
Description
Industrial Base Layer
Who are the potential adopters?
Identifies the total addressable base, including professional sports teams, amateur clubs, training academies, fitness organizations, stadium operators, sports federations, and individual athletes that require performance optimization, analytics, and digital engagement solutions.
Technology Readiness Layer
Who can implement sports technology systems?
Adoption based on readiness factors such as digital infrastructure availability, data analytics maturity, IoT and wearable integration capability, cloud adoption, budget allocation for technology investments, and organizational willingness to transition toward data-driven sports ecosystems.
Deployment Layer
Who actively deploys sports technology solutions?
Applies adoption levels across end-use segments where sports technology is actively implemented, including performance-tracking systems, smart stadium infrastructure, video analytics platforms, and fan-engagement tools used by professional leagues, elite clubs, and major sporting events.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through hardware devices such as wearables and sensors, software subscriptions for analytics platforms, smart stadium infrastructure systems, esports platforms, broadcasting technologies, licensing agreements, and recurring revenue from cloud-based performance monitoring and fan engagement services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Athlete Performance Optimization, Training Design & Feasibility Assessment
Conducted detailed evaluation of performance analytics systems across professional teams, training academies, and individual athletes, integrating wearable sensors, GPS tracking, biometric monitoring, and AI-driven coaching platforms for workload management and injury prevention.
Enables data-driven training optimization, improves athlete performance efficiency, reduces injury risk, and enhances competitive decision-making outcomes.
Smart Stadium & Sports Infrastructure Integration Strategy
Assessed deployment of smart stadium technologies including IoT-enabled seating systems, real-time crowd analytics, digital ticketing platforms, and immersive fan engagement solutions integrated with high-speed connectivity and cloud-based infrastructure.
Enhances spectator experience, improves stadium operational efficiency, supports real-time engagement, and enables seamless digital event management.
Digital Sports Media, Esports & Fan Engagement Development
Evaluated integration of sports broadcasting technologies, esports platforms, AR/VR-based viewing systems, and AI-powered content personalization tools for global audiences and interactive fan ecosystems.
Enables immersive viewing experiences, increases fan engagement, supports monetization through digital platforms, and enhances accessibility of global sports content.
Frequently Asked Questions About This Report
Some key players operating in the sports technology market include Apple Inc.; Cisco Systems, Inc.; Telefonaktiebolaget LM Ericsson; Fitbit, Inc.; Fujitsu; Garmin Ltd.; IBM Corporation; Modern Times Group MTG; Panasonic Corporation; Samsung; SAP SE; and Sony Corporation.
Key factors that are driving the sports technology market are the significant improvements in audience engagement and upcoming sports events and growth including the growing number of sports leagues across the globe.
The Asia Pacific is the fastest-growing region over the forecast period.
The smart stadium segment led with a 54.6% revenue share in 2025, while the analytics & statistics is the fastest-growing segment.
The soccer segment led with a 15.5% revenue share in 2025.
The sports leagues segment led with a 45.8% revenue share in 2025.
The global sports technology market size was estimated at USD 23.0 billion in 2025 and is expected to reach USD 28.1 billion in 2026.
The global sports technology market is expected to grow at a compound annual growth rate of 23.0% from 2026 to 2033 to reach USD 119.6 billion by 2033.
Europe dominated the sports technology market with a share of nearly 30.1% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


