
- Home
- »
- Pharmaceuticals
- »
-
Systemic Lupus Erythematosus Market Size Report, 2033GVR Report cover

Systemic Lupus Erythematosus Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (Biologics, TNF Inhibitors, NSAID’s, Corticosteroids), By Route Of Administration, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.2BMarket Forecast, 2033
$5.3BCAGR, 2026–2033
7.3%Systemic Lupus Erythematosus Market Summary
The global systemic lupus erythematosus market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.2 billion in 2026 to USD 5.3 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of approximately 39.5% in 2025. Increasing new cases of autoimmune diseases, the growing prevalence of SLE worldwide, increasing awareness of the significance of early diagnosis, and expanding research and development in treatments for systemic lupus erythematosus (SLE) are key factors driving market growth.
Key Market Trends & Insights
- By drug class: The immunosuppressant segment accounted for the largest market share of over 35.0% in 2025.
- By route of administration: The oral route of administration segment held the largest market share in 2025.
- By distribution channel: The hospital pharmacy segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (39.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.2 Billion
- Projected market size by 2033: USD 5.3 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Emergence of innovative therapies related to severe autoimmune diseases, availability of drugs and treatments related to SLE, and enhanced healthcare infrastructure in numerous countries have fueled growth of this market in recent years. Increasing healthcare expenditure, particularly in developed countries, and rising collaborations between pharmaceutical companies and care providers are fostering the development of innovative therapies, thus propelling market growth. Moreover, the presence of regulatory agencies such as the Food and Drug Administration (FDA) and the European Medicines Agency (EMA) approving new drugs and therapies more frequently is expected to influence the growth of this market during the forecast period.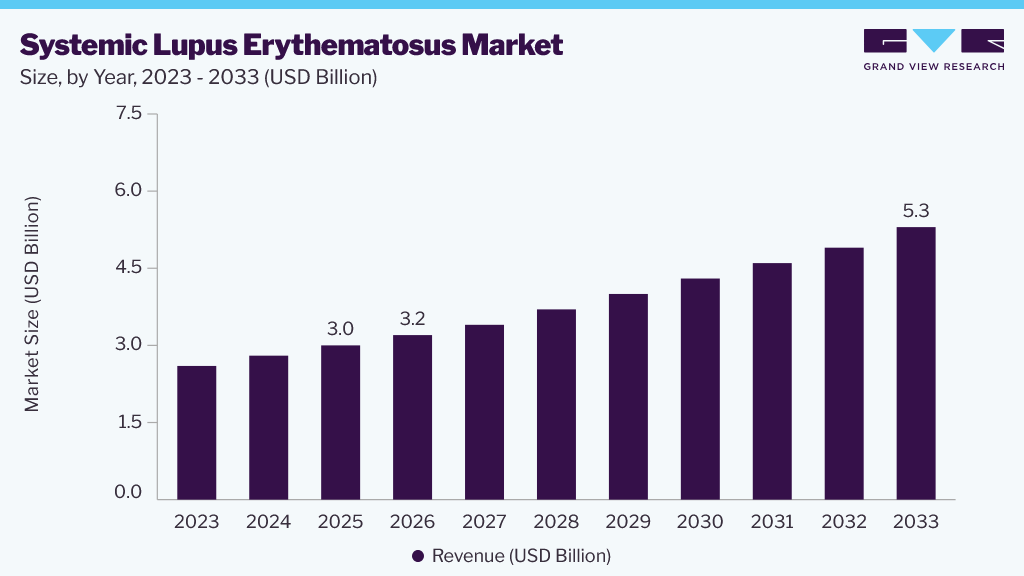 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The vast majority of individuals diagnosed with lupus are women, with over 90% of cases occurring in females. Lupus most often strikes during childbearing, typically between the ages of 15 and 44. Similarly, approximately 5 million people worldwide are believed to have lupus, which can cause inflammation and damage to various parts of the body.
Another key growth factor driving the SLE market is the development and approval of new, targeted therapies. Several biopharmaceutical companies are actively pursuing the development of new treatments for systemic lupus erythematosus (SLE). These efforts aim to improve patient outcomes by advancing various SLE research and management aspects. In March 2024, the FDA authorized Seattle Children's Hospital to initiate the first clinical trial in the U.S. utilizing CAR-T cell therapy for children under 18 and older with SLE.
Increasing healthcare expenditure, especially in developed countries, bolsters the adoption of advanced therapies. As governments and private insurers allocate more resources toward treating autoimmune diseases, patients have greater access to new and effective medications. In addition, strategic collaborations and partnerships between pharmaceutical companies, research institutions, and healthcare providers are fostering the development of innovative therapies. Growing awareness regarding the severity of SLE and the need for focused efforts to invent advanced therapies for it is expected to drive growth for this market during the forecast period. In May 2024, Exagen Inc. announced a campaign to raise awareness about lupus during Lupus Awareness Month.
Analyst Perspective
The systemic lupus erythematosus industry is entering a phase of sustained innovation, supported by increasing disease awareness, improved diagnostic capabilities, and a robust clinical development pipeline. Pharmaceutical companies are shifting toward targeted biologics and cell-based therapies that address the underlying immune dysfunction while improving long-term disease management. Regulatory support for novel treatment approvals and rising healthcare investments are accelerating patient access to advanced therapies across developed markets. In addition, collaborations among biotechnology firms, research institutions, and healthcare providers are strengthening therapeutic innovation. As personalized medicine gains momentum, the SLE market is expected to witness improved treatment outcomes, broader commercialization opportunities, and sustain long-term growth.
Drug Class Insights
The immunosuppressant segment led the market with the largest revenue share of over 35.0% in 2025. The segment is primarily driven by the effectiveness of the drug in managing the disease's symptoms. Immunosuppressive drugs are often prescribed for treating lupus, including methotrexate and azathioprine, which are widely used for their ability to effectively reduce inflammation and modulate the immune response. The growing use, increasing rate of diagnosis resulting from rising awareness, and growth in prevalence of SLE are expected to fuel growth of this segment during the forecast period.
For instance, in February 2025, Roche announced that detailed Phase III REGENCY study results for Gazyva (obinutuzumab) were published in the New England Journal of Medicine, demonstrating significantly improved complete renal response in patients with active lupus nephritis when Gazyva was administered in combination with standard immunosuppressive therapy, including mycophenolate mofetil (MMF) and corticosteroids. The study highlights the continued role of immunosuppressive agents as the foundation of systemic lupus erythematosus treatment, with emerging biologic therapies increasingly being used alongside these established medications to improve patient outcomes.
The biologics segment is anticipated to witness at the fastest CAGR from 2026 to 2033. One of the key factors driving the segment growth is the increasing awareness and understanding of the disease's underlying biology. Therapies such as belimumab and anifrolumab have shown high efficacy in treating patients with systemic lupus erythematosus (SLE). The growing demand for personalized medicine and the need for more effective treatments with fewer side effects are driving the adoption of biologics. In addition, the expansion of indications for existing biologics and the emergence of new biologic agents in the pipeline are expected to fuel market growth.
Route of Administration Insights
The oral route of administration segment accounted for the largest market revenue share in 2025. Growth of this segment is attributed to its convenience, ease of administration, and high patient compliance. Oral medications such as antimalarial hydroxychloroquine and corticosteroids have been the cornerstone of systemic lupus erythematosus treatment as they offer a convenient and non-invasive treatment option, allowing patients to manage their disease in the comfort of their own homes.
In addition, oral medications are often less expensive than biologics and other injectable treatments, making them a more accessible option for patients.
For instance, in November 2025, the American College of Rheumatology (ACR) released its updated clinical guidelines for the treatment of systemic lupus erythematosus (SLE), recommending the universal use of oral hydroxychloroquine for nearly all patients with SLE, alongside minimizing glucocorticoid exposure and introducing additional therapies when needed. The updated recommendations reinforce the continued importance of oral medications as the cornerstone of long-term SLE management due to their proven efficacy, ease of administration, and high patient adherence, supporting the dominance of the oral route of administration segment.
The subcutaneous segment is expected to grow at the fastest CAGR over the forecast period. Subcutaneous administration offers improved patient convenience, reduced administration costs, and enhanced treatment adherence. The route enables patients to self-administer therapy at home, reducing the need for frequent hospital or infusion center visits and improving overall treatment accessibility.
In addition, advancements in biologic therapies and the development of patient-friendly prefilled syringes and autoinjectors are encouraging the adoption of subcutaneous formulations. The growing preference for home-based care and the increasing availability of subcutaneous biologic therapies for systemic lupus erythematosus are expected to further drive the growth of this segment during the forecast period.
Distribution Channel Insights
The hospital pharmacy segment accounted for the largest market revenue share in 2025. The growth of this segment is attributed to its widespread presence and specialized care offerings. Hospital pharmacies are often equipped with advanced pharmacy information systems and offer various medications, including biologics and immunosuppressants. In addition, hospital pharmacies have trained professionals who provide patient education, counseling, and support as and when needed. Moreover, several health insurance plans cover hospital pharmacy costs, making medications more affordable.
For instance, in October 2025, GSK announced that Brazil's health regulator ANVISA approved Benlysta (belimumab) as the first biologic for pediatric patients with active lupus nephritis. As an intravenous biologic requiring administration and monitoring in specialized healthcare settings, the approval is expected to strengthen the role of hospital pharmacies in dispensing, preparing, and managing advanced SLE therapies while improving patient access to specialized treatment.
The online pharmacy segment is anticipated to grow at the fastest CAGR during the forecast period. The growing e-commerce sector, the rising demand for convenient and accessible healthcare services, and the adoption of digital technologies are the primary factors that drive the growth of this segment. Online pharmacies enable patients to conveniently order prescription medications, access home delivery services, and refill long-term prescriptions without the need for frequent visits to healthcare facilities.
In addition, increasing internet penetration, widespread smartphone adoption, and the expansion of telemedicine services are encouraging patients with chronic conditions such as systemic lupus erythematosus to utilize digital pharmacy platforms for improved treatment accessibility and medication adherence. The growing availability of secure online prescription management and digital healthcare services is expected to further support the growth of this segment during the forecast period.
Regional Insights
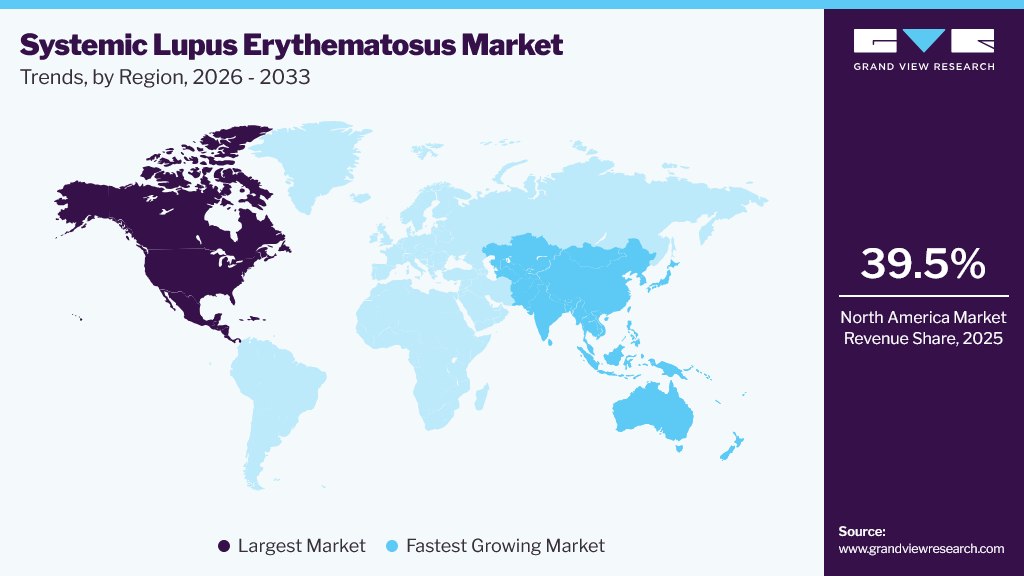
North America dominated the global systemic lupus erythematosus market with the largest revenue share of approximately 39.5% in 2025. The region's dominance is attributed to the high prevalence of systemic lupus erythematosus, robust healthcare infrastructure, and awareness about autoimmune disease. The region's large pharmaceutical industry, coupled with the presence of key players such as GlaxoSmithKline, Eli Lilly and Company, and AstraZeneca, has driven innovation and investment in the development of new therapies, solidifying North America's position as a leader in the systemic lupus erythematosus market. Furthermore, the well-established regulatory frameworks that streamline the approval and availability of new therapies further contribute to the region's growth. In December 2023, the FDA approved a phase 1 trial of CNTY-101 in patients with moderate to severe systemic lupus erythematosus.
 To learn more about this report, Download Free Sample Report
U.S. Systemic Lupus Erythematosus Market Trends
The systemic lupus erythematosus market in the U.S. accounted for the largest market revenue share in North America in 2025. The U.S. benefits from an advanced healthcare system with widespread access to specialized medical care, leading to high diagnosis rates and effective management of SLE. Strong pharmaceutical and biotechnology sectors, coupled with a supportive regulatory environment such as the FDA and the Lupus Foundation of America, facilitate the swift approval of new treatments, propelling the region’s growth.
Europe Systemic Lupus Erythematosus Market Trends
The systemic lupus erythematosus market in Europe held a significant share in 2025. The robust healthcare infrastructure, the increasing prevalence of SLE, and broad healthcare coverage are key factors driving the region’s growth. The region is home to numerous research institutions and pharmaceutical companies that contribute to developing and making available innovative SLE treatments.
Asia Pacific Systemic Lupus Erythematosus Market
The systemic lupus erythematosus market in the APAC is anticipated to grow at the fastest CAGR over the forecast period. Increasing SLE disease awareness and healthcare expenditure are the key factors expected to drive the region’s growth. SLE is more common among Asian populations, and China and India, being the most populous countries, naturally have a higher number of patients diagnosed with this autoimmune condition.
For instance, in December 2025, InnoCare Pharma announced that its Phase IIb clinical trial of orelabrutinib for systemic lupus erythematosus (SLE) successfully met its primary endpoint, while China's Center for Drug Evaluation (CDE) also approved the initiation of a Phase III registrational trial. The milestone underscores the rapid expansion of autoimmune disease research and innovative drug development across Asia Pacific, particularly in China, supporting the region's emergence as the fastest-growing market for systemic lupus erythematosus therapeutics.
Key Systemic Lupus Erythematosus Company Insights
Some of the key companies in the systemic lupus erythematosus industry include Novartis AG, GSK plc, F. Hoffmann-La Roche Ltd, Sanofi, Bristol-Myers Squibb Company, and others. To address the growing competition, the major market participants are adopting strategies such as enhanced focus on research and development, innovation-based new product launches, collaborations, and acquisitions of other organizations operating in similar businesses.
-
GSK plc, a global pharmaceuticals and biotechnology company, offers a diverse range of products across three different categories, including vaccines, specialty, and general medicines.
Key Systemic Lupus Erythematosus Companies
The following key companies have been profiled for this study on the systemic lupus erythematosus market.
-
Novartis AG
-
GSK plc.
-
F. Hoffmann-La Roche Ltd
-
Pfizer Inc.
-
Sanofi
-
Bristol-Myers Squibb Company
-
ImmuPharma PLC
-
Merck KgaA
-
AstraZeneca
-
UCB S.A.
Recent Developments
-
In June 2026, UCB announced positive topline results from its Phase 3 PHOENYCS GO trial evaluating dapirolizumab pegol (DZP) in patients with moderate-to-severe systemic lupus erythematosus (SLE). The study met its primary endpoint by demonstrating a statistically significant improvement in disease activity when added to standard-of-care treatment, reinforcing UCB's commitment to expanding innovative therapeutic options for SLE patients.
-
In June 2025, GSK announced that the U.S. Food and Drug Administration approved a 200 mg subcutaneous autoinjector of Benlysta (belimumab) for patients aged five years and older with active lupus nephritis. The approval expands at-home treatment options for pediatric lupus patients and strengthens GSK's leadership in the systemic lupus erythematosus treatment market by improving treatment accessibility and patient convenience.
Systemic Lupus Erythematosus Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.2 billion
Projected market size by 2033
USD 5.3 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug class, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; Australia; South Korea; India; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Novartis AG; GSK plc.; F. Hoffmann-La Roche Ltd; Pfizer Inc.; Sanofi; Bristol-Myers Squibb Company; ImmuPharma PLC; Merck KgaA; AstraZeneca; UCB S.A.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Systemic Lupus Erythematosus Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global systemic lupus erythematosus market report based on drug class, route of administration, distribution channel, and region:
- Drug Class Outlook (Revenue, USD Billion, 2021 - 2033)
- Biologics
- Saphnelo (Anifrolumab)
- Benlysta (Belimumab)
- Phase 3 Pipeline Products
- TNF Inhibitors
- NSAID’s
- Corticosteroids
- Antimalarials
- Immunosuppressants
- Other Drug Classes
- Biologics
- Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
- Oral
- Intravenous
- Subcutaneous
- Other Route of Administration
- Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacy
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


