
- Home
- »
- Consumer F&B
- »
-
Tea Market Size, Share And Trends Report, 2026-2033GVR Report cover

Tea Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Black, Green, Oolong, Herbal), By Distribution Channel (Supermarkets & Hypermarkets, Convenience Stores, Grocery Stores), By Region, And Segment Forecasts
Market Size, 2025
$69.5BMarket Estimate, 2026
$74.0BMarket Forecast, 2033
$115.2BCAGR, 2026–2033
6.5%Tea Market Summary
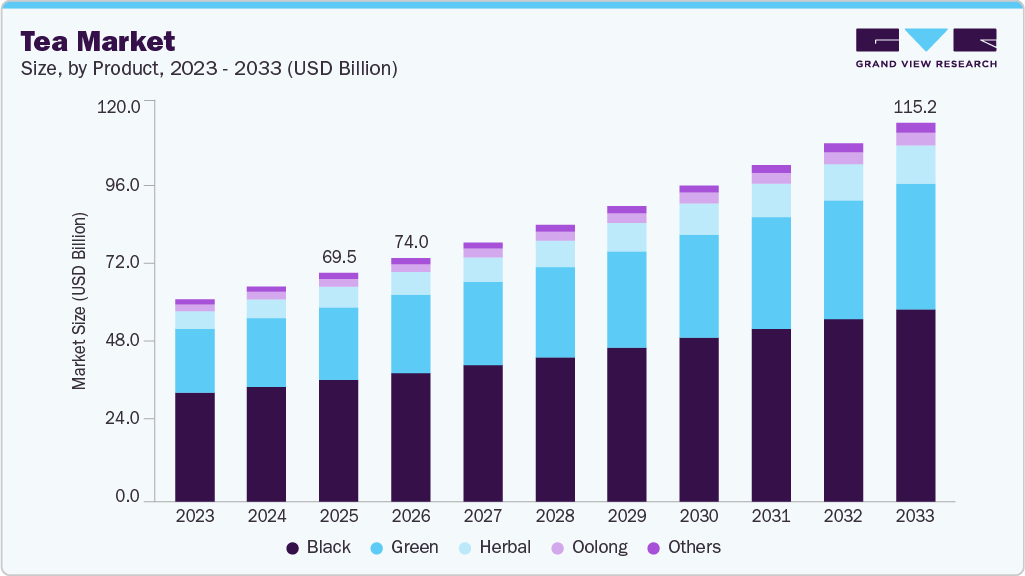
The global tea market size was valued at USD 69.5 billion in 2025 and is projected to grow from USD 74.0 billion in 2026 to USD 115.2 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 67.9% in 2025. The shift toward functional beverage drinks that provide health benefits beyond basic nutrition has significantly shaped the market.
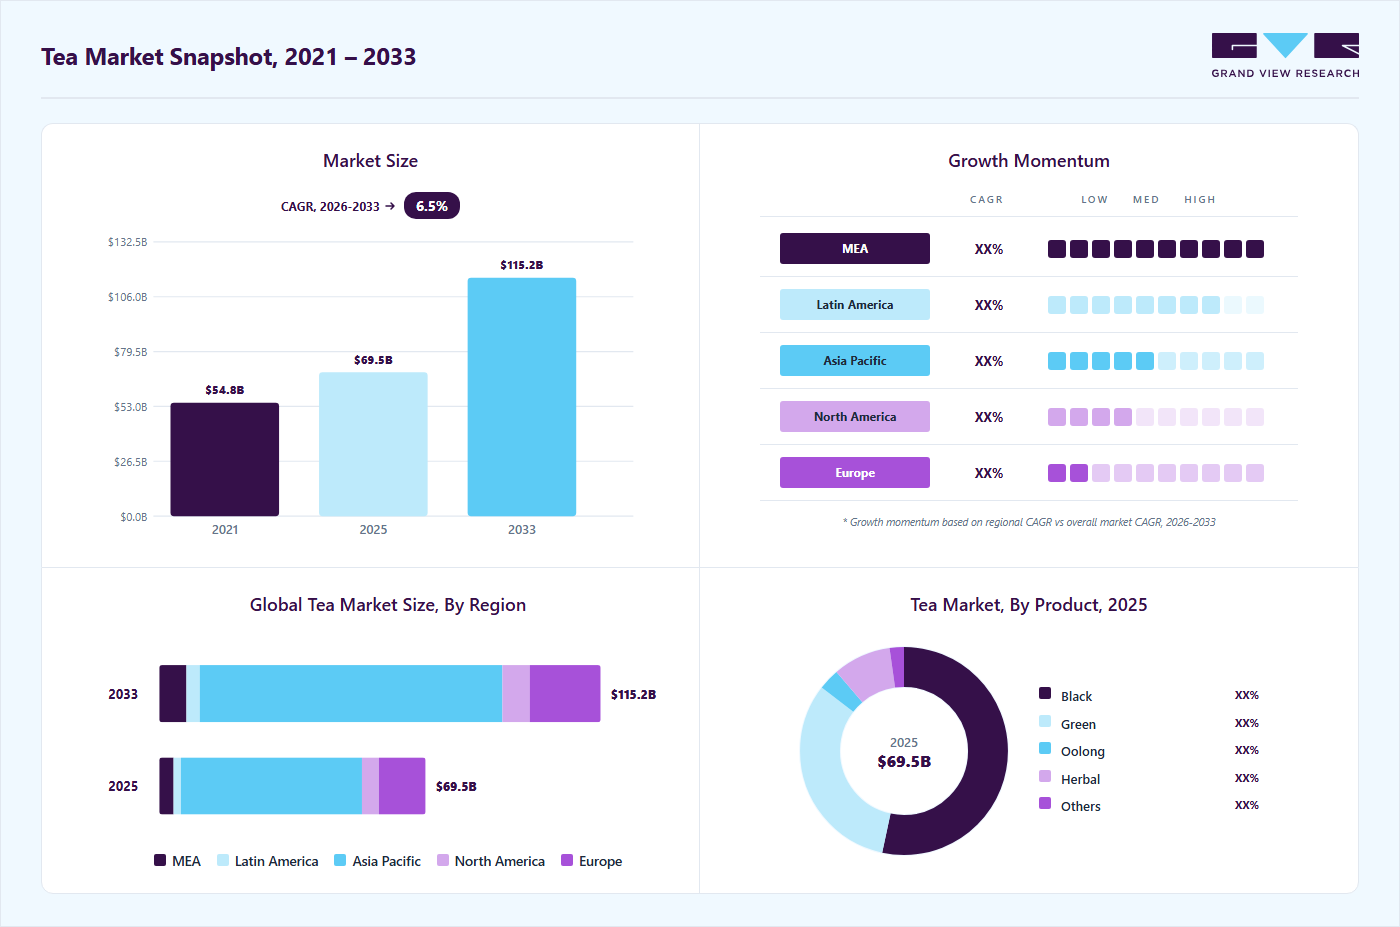 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Black tea segment led the market and accounted for a share of 53.3% in 2025.
- By distribution channel: Supermarkets & hypermarkets segment led the market and accounted for a share of 43.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (67.9% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (highest CAGR, 2026-2033)
- By country: India held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 69.5 Billion
- Estimated market size in 2026: USD 74.0 Billion
- Projected market size by 2033: USD 115.2 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumers are looking for drinks that can aid in detoxification, boost energy levels, or support weight management, which has led to a surge in demand for various types of tea. The industry is a dynamic and evolving market that caters to a diverse range of consumer preferences and cultural practices around the globe. As one of the most widely consumed beverages after water, tea has a rich history that spans thousands of years. Its appeal lies in its refreshing qualities and the variety of flavors and health benefits it offers. From traditional black and green teas to herbal blends and specialty infusions, the market encompasses a broad spectrum of products that attract casual drinkers and dedicated enthusiasts.The health and wellness trend significantly shapes consumer preferences in the market, with an increasing demand for functional teas catering to specific health benefits. Many consumers are turning to teas that claim to support immune function or provide stress relief as the pursuit of holistic health becomes a priority in daily life. This shift is closely tied to a broader cultural movement toward self-care and wellness, encouraging individuals to seek products that contribute positively to their physical and mental well-being. For instance, in September 2024, Traditional Medicinals, an organic botanical wellness company, introduced its new line of Stress Ease Teas, which includes Focus, Immune, and Tension Relief varieties. These teas utilize the benefits of adaptogens and nervines, medicinal herbs that aid the body’s response to occasional stress and support the nervous system. These certified organic teas provide natural and efficient remedies for individuals seeking equilibrium and strength in the rapidly moving modern environment.
 To learn more about this report, Download Free Sample Report
The tea industry has experienced significant growth in recent years, driven by innovation and flavor diversity. As consumer preferences evolve, brands are expanding their offerings to encompass a diverse array of flavors, blends, and formats. This diversification caters to a growing audience seeking not only traditional tea experiences but also unique and novel options. From fruit-infused teas to herbal blends and specialty cold brews, the market is becoming increasingly vibrant, allowing consumers to explore new taste profiles.
New tea formats, such as ready-to-drink (RTD) teas and tea pods or capsules, are also reshaping the industry by catering to consumer demands for convenience and quality. RTD teas are available in a wide range of flavors and are designed for on-the-go consumption, appealing to busy lifestyles. Many brands are focusing on premium ingredients and health benefits, making these products attractive to health-conscious consumers. In September 2024, Twinings introduced a new line of ready-to-drink sparkling teas designed to cater to the growing consumer demand for functional beverages that offer both refreshment and health benefits. This innovative range includes three distinct flavors: Refresh, featuring Juicy Raspberry Lemonade; Defence, with Zesty Orange and Passionfruit; and Boost, offering Zingy Lemon and Ginger.
Furthermore, the exploration of global tea traditions has led to a broader appreciation for diverse tea cultures. Brands are incorporating traditional practices and flavors from around the world, such as matcha from Japan or chai from India, thereby enriching their product lines. This not only enhances variety but also fosters a deeper connection with consumers who are increasingly interested in authentic and culturally rich experiences. Collectively, these trends in innovation and variety are driving the tea market forward, making it a dynamic and continually evolving market.
Market Dynamics
The rapid expansion of ready-to-drink (RTD) tea products and online retail channels is significantly driving growth in the global tea industry. Consumers are seeking convenient, healthy, and on-the-go beverage options, leading to strong demand for bottled, canned, and packaged RTD teas. Rising health awareness has also encouraged the consumption of low-sugar, organic, herbal, and functional RTD tea beverages containing antioxidants and natural ingredients. In addition, busy lifestyles and urbanization are accelerating the preference for convenient beverage formats among younger consumers. E-commerce platforms and quick-commerce delivery services are further enhancing product accessibility by enabling consumers to explore a wide variety of tea brands, flavors, and premium products from home. Manufacturers are continuously launching innovative RTD tea variants to strengthen consumer engagement and market presence. A recent example occurred in March 2026 when Lipton launched a new Peach Green Tea RTD beverage in Europe, targeting health-conscious consumers seeking refreshing, flavored tea options with natural ingredients and reduced sugar content.
Climate change and fluctuations in tea production remain major restraints affecting the global industry. Tea cultivation is highly dependent on stable climatic conditions, including appropriate rainfall, temperature, humidity, and soil quality. However, increasing global temperatures, irregular rainfall patterns, droughts, floods, and extreme weather events are negatively impacting tea yields and crop quality across major tea-producing countries such as India, China, Kenya, and Sri Lanka. Changes in weather conditions can reduce leaf quality, alter flavor profiles, and increase the spread of pests and plant diseases, thereby affecting overall tea production and profitability. In addition, climate-related disruptions often lead to supply shortages and price volatility in international tea markets. Small tea farmers are particularly vulnerable, as they face rising irrigation, labor, and crop management costs. These environmental challenges are forcing tea producers to invest in climate-resilient farming techniques and sustainable agricultural practices, increasing operational expenses and creating long-term uncertainty for the industry.
The market is witnessing increasing diversification as consumers shift toward beverages that deliver convenience, natural caffeine, and added health benefits. According to SPINS functional tea products featuring collagen grew by 84.0%, while vitamin C-positioned products increased by 58.0% in 2026, indicating strong momentum for benefit-led tea formulations. The growing presence of canned tea also positions the category as an alternative to conventional soft drinks and energy beverages. This trend creates opportunities for tea manufacturers to expand into RTD, canned, herbal, green, and fortified tea formats, while targeting applications such as energy, immunity, hydration, beauty, and general wellness.
Analyst Perspective
The industry is expanding beyond traditional black and green tea toward herbal, functional, specialty, and premium tea products, supported by changing consumption patterns and product innovation. Manufacturers are increasingly focusing on premiumization, convenient formats, distinctive blends, and natural ingredients to differentiate products and capture higher-value consumer segments. The expansion of ready-to-drink tea, tea bags, instant tea, and specialty blends is also creating opportunities across multiple consumption occasions. However, fluctuations in tea leaf prices, climatic conditions, supply-chain disruptions, and changing agricultural yields remain important challenges for producers and processors. Overall, product diversification, premium offerings, functional positioning, and innovation in convenient formats are expected to remain key growth areas.
Consumer Insights
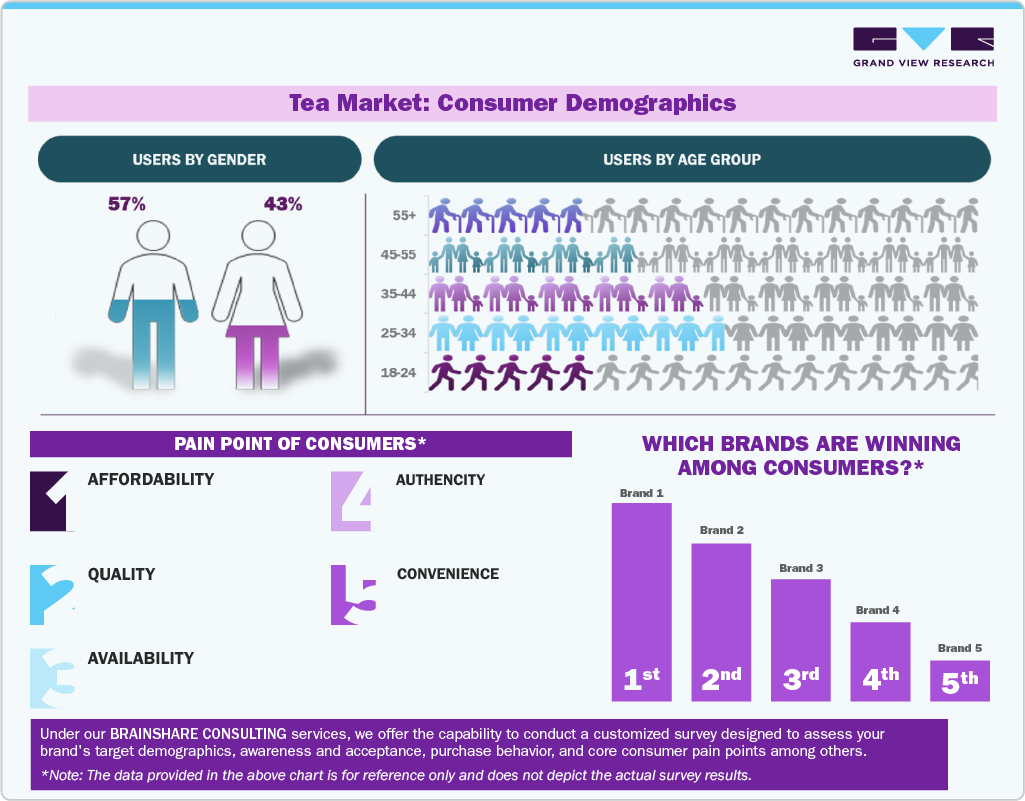
Consumer preferences are influenced by taste, aroma, quality, affordability, and perceived health benefits. Consumers seek products that align with their lifestyles, including green tea, herbal infusions, organic blends, and functional teas. Growing awareness of wellness and natural ingredients is encouraging interest in products associated with relaxation, digestion, and daily hydration. Convenience also plays an important role, supporting demand for tea bags, ready-to-drink tea, and easy-to-prepare blends. Additionally, consumers evaluate brand reputation, ingredient transparency, packaging, and product authenticity before purchasing. Price sensitivity and consistent product quality further influence brand selection and repeat purchases.
 To learn more about this report, Download Free Sample Report
Product Insights
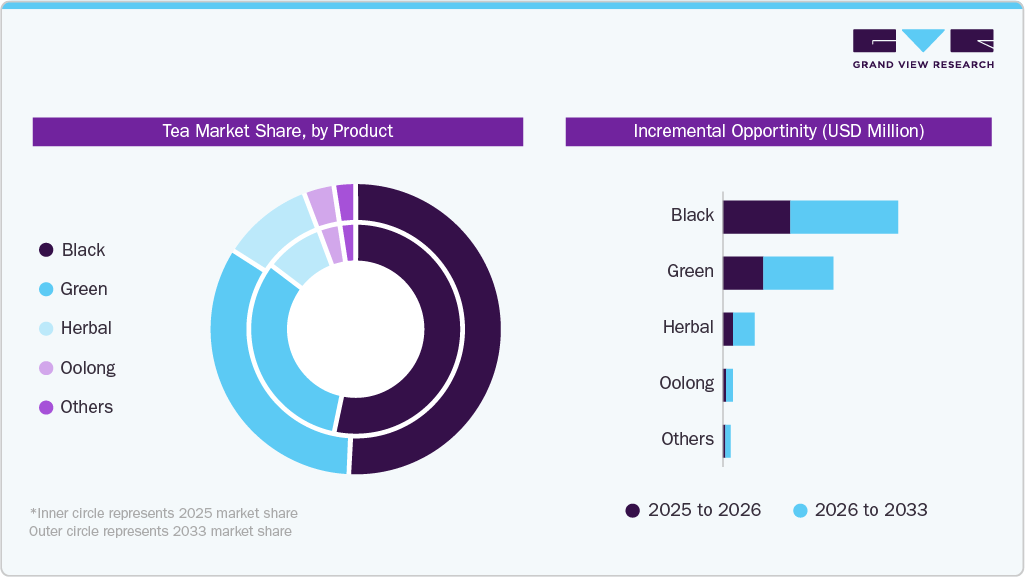
The black tea segment dominated the market with a share of 53.3% in 2025. Black tea, derived from the camellia sinensis plant, is preferred by a large population worldwide due to its strong flavor and high caffeine content. According to the World Tea Export Council, black tea is the most consumed tea in the world, accounting for approximately 75% of the total tea consumption. Its growth is driven by several benefits, such as antioxidant properties that protect from free radicals and reduce cell damage. Moreover, black tea contains flavonoids similar to those found in fruits, red wine, and dark chocolate, improving heart function. In addition, black tea lowers low-density lipoproteins cholesterol levels, thus dropping the risk of heart disease. These advantages are expected to drive increased demand and growth in the black tea market in the coming years.
 To learn more about this report, Download Free Sample Report
The herbal tea segment is expected to grow at a CAGR of 8.1% from 2026 to 2033, driven by a combination of demographic, lifestyle, and consumption trends. Factors such as the expanding working population, rising demand for convenient and ready-to-use beverage options, and the continued expansion of organized retail channels are supporting market growth. In addition, the increasing use of herbal tea and botanical extracts as natural ingredients in personal care and wellness products is further strengthening demand.
Distribution Channel Insights
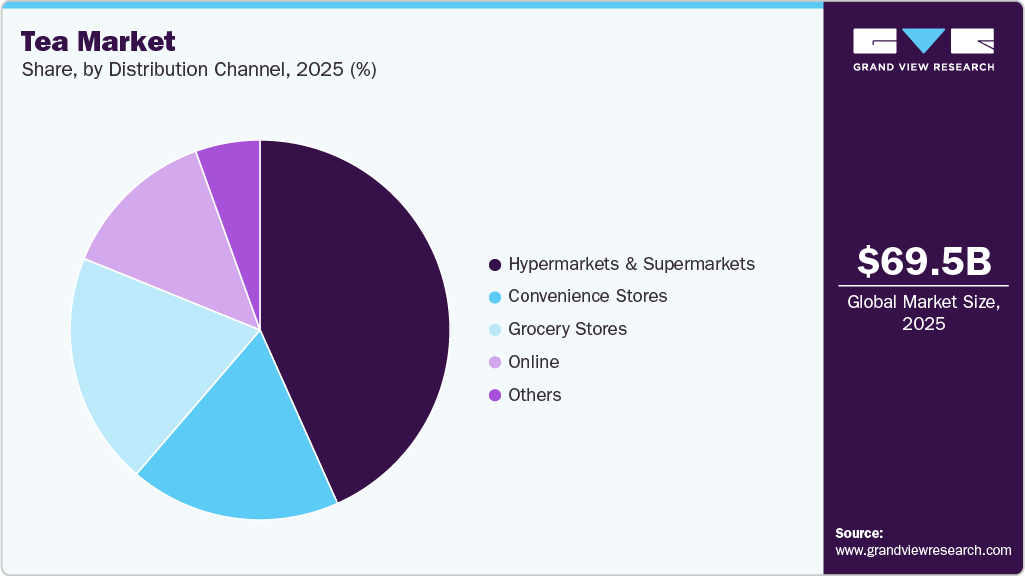
The supermarkets & hypermarkets segment accounted for a share of 43.3% in 2025. Supermarkets and hypermarkets are attractive outlets for consumers as they provide a centralized shopping experience, allowing buyers to pick up tea alongside other daily essentials. With dedicated tea sections, these stores often offer a wide range of tea options, from traditional black and green teas to premium, herbal, and specialty teas. This variety appeals to consumers seeking both popular and niche tea products in one place. Furthermore, the availability of loyalty programs, seasonal discounts, and promotional offers in these retail outlets drives foot traffic, increasing the volume of tea purchases.
 To learn more about this report, Download Free Sample Report
Sales of tea through the online distribution channel are expected to grow at a CAGR of 8.7% from 2026 to 2033. Consumers are turning to online platforms for convenience and accessibility, allowing them to browse a wide range of tea varieties and brands from the comfort of their homes. This trend is particularly pronounced among younger tech-savvy demographics who prefer the ease of ordering products online. Additionally, online channels provide a platform for tea producers, especially small and artisanal brands, to reach a broader audience beyond their local markets, expanding their customer base and boosting sales.
Regional Insights
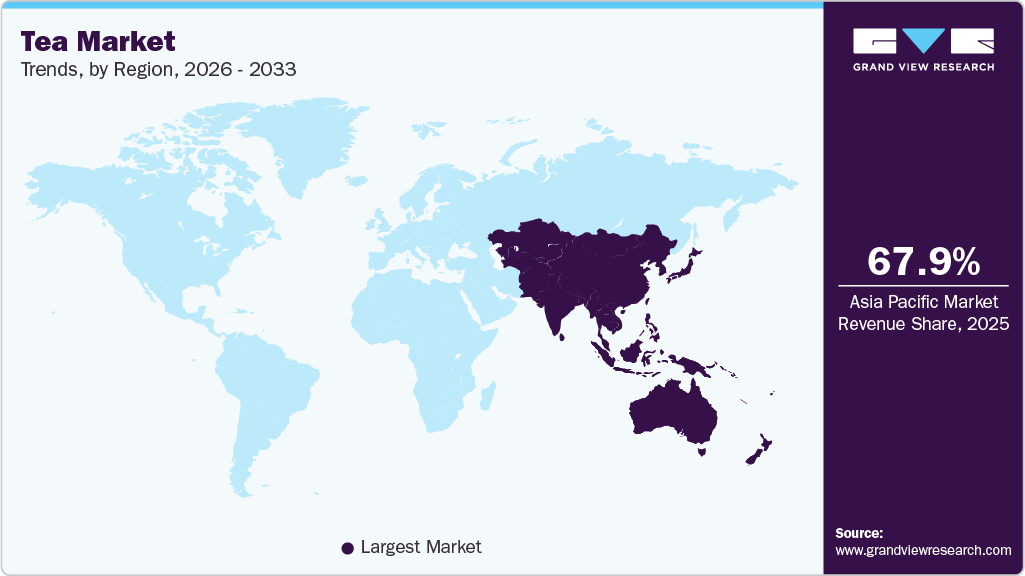
The tea market in Asia Pacific accounted for the largest share of 67.9% in 2025. Tea has a significant cultural and social value across many regions in Asia Pacific. Moreover, tea is often perceived as more beneficial than other drinks, attracting health-conscious individuals to choose tea over carbonated beverages. The increasing popularity of tea among millennials has led to a rising demand for flavored varieties like clove, pepper, cinnamon, masala, mixed fruit, and more, driving market growth in the Asia Pacific region.
 To learn more about this report, Download Free Sample Report
India Tea Market Trends
The India tea market accounted for a share of 25.7% of the Asia Pacific market in 2025. India has a strong tea-drinking culture, with black tea and milk-based tea being part of everyday consumption. The market is supported by widespread household consumption, established domestic production, and the popularity of regional and flavored teas. Demand is also expanding toward green, herbal, premium, and wellness-oriented teas, as consumers increasingly seek products associated with natural ingredients and health benefits.
North America Tea Market Trends
The North America tea market is expected to register a CAGR of 6.1% from 2026 to 2033. Rising awareness of the health benefits associated with tea such as antioxidant content, hydration support, and perceived benefits for digestion, metabolism, and stress management has positioned tea as a favorable alternative to sugar-sweetened carbonated drinks and high-calorie beverages. This trend is particularly strong among health-conscious and aging populations seeking natural and minimally processed products.
The tea market in the U.S. accounted for a share of 76.2% of the North America market in 2025. The U.S. market is primarily driven by black and iced tea, with iced tea holding particularly strong cultural relevance in the Southern states. In recent years, consumer interest has expanded toward green, herbal, specialty, and wellness-oriented teas, supported by growing demand for diverse flavors and health-focused beverages. The expansion of tea houses, specialty brands, and ready-to-drink formats is further broadening tea consumption and supporting market development.
Europe Tea Market Trends
The tea market in Europe is expected to register a CAGR of 5.4% from 2026 to 2033. The growing trend toward healthier beverage choices among European consumers is driven by increasing awareness of the health benefits associated with tea, such as antioxidants and potential weight management properties. Additionally, tea is perceived as a versatile drink that caters to a variety of tastes and preferences, including herbal and specialty teas that appeal to health-conscious and adventurous consumers alike. Moreover, European cultural diversity has led to a broader acceptance and integration of tea traditions from different regions, contributing to its popularity across various demographics.
Central & South America Tea Market Trends
The tea market in Central & South America is expected to register a CAGR of 7.7% from 2026 to 2033. The Central and South American market is supported by established tea consumption and production in countries such as Argentina and Brazil, while consumer preferences are gradually shifting toward more diversified tea offerings. Traditional black tea remains important, but demand is expanding toward herbal, green, specialty, flavored, and ready-to-drink teas. Growing awareness of the health benefits associated with tea, together with rising interest in natural and lower-sugar beverages, is encouraging manufacturers to introduce differentiated products. The expansion of modern retail, foodservice, and convenient packaged formats is further supporting market development and creating opportunities for both established tea companies and emerging brands across the region.
Middle East & Africa Tea Market Trends
The tea market in the Middle East & Africa is expected to register the highest CAGR of 8.3% from 2026 to 2033. The Middle East and Africa’s market is driven by high-frequency tea consumption, strong cultural preferences, and an established tea production and trading base. Black tea remains widely consumed across the region. The region's large young population, urbanization, expanding retail channels, and growing availability of branded tea products are providing opportunities for manufacturers to expand beyond traditional tea offerings and introduce convenient, differentiated, and value-added products.
Key Tea Company Insights
The presence of a few established players and new entrants characterizes the market. Many big players are increasing their focus on the growing trend of the tea market. Players in the market are diversifying their service offerings in order to maintain market share.
 To learn more about this report, Download Free Sample Report
Key Tea Companies:
The following key companies have been profiled for this study on the tea market.
-
Associated British Foods plc
-
Dilmah Ceylon Tea Company PLC.
-
Bigelow Tea
-
PepsiCo, Inc.
-
Bettys & Taylors of Harrogate Ltd
-
Starbucks Coffee Company
-
Unilever
-
Caraway Tea
-
Harris Freeman
-
The Republic of Tea
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Associated British Foods plc; Dilmah Ceylon Tea Company PLC; Bigelow Tea; PepsiCo, Inc.; Bettys & Taylors of Harrogate Ltd; Starbucks Coffee Company; Unilever; Harris Freeman)
- Strengthen branded tea portfolios, expand premium and specialty offerings, and leverage established retail and distribution networks.
- High brand recognition, extensive distribution, strong sourcing capabilities, and broad consumer reach.
- Mature portfolios may limit agility, while large-scale sourcing and operations increase exposure to commodity-price and climate-related risks.
Emerging Players (Caraway Tea; The Republic of Tea)
- Target premium, specialty, wellness, and digitally driven tea consumption through differentiated blends and direct-to-consumer channels.
- Strong niche positioning, digital-first distribution, premium product differentiation, and faster response to evolving consumer preferences.
- Smaller sourcing and distribution networks, lower mass-market penetration, and comparatively limited production and marketing scale.
Recent Developments
-
In October 2025, Tata Tea Agni introduced Tata Tea Agni Extra Josh, promoted as India’s first tea with added natural caffeine for extra energy to suit modern, fast-paced lifestyles, supported by TVCs that portray homemakers as energetic “superwomen” powered by this new strong tea variant, initially launched in select north India markets and positioned as an innovative extension of the brand’s existing “Josh Jagaye Har Roz” promise.
-
In July 2025, CHAGEE launched its popular Peach Oolong Milk Tea in Indonesia, featuring Fujian Golden Guanyin oolong tea blended with real peach juice and supported by in-store promotions, social media photo activities, and limited-edition merchandise like luggage tags, card holders, and tote bags across its Jakarta outlets.
Tea Market Report Scope
Report Attribute
Details
Market size in 2025
USD 69.5 billion
Estimated market size in 2026
USD 74.0 billion
Projected market size by 2033
USD 115.2 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; Spain; China; India; Japan; South Korea; Australia & New Zealand; Brazil; South Africa
Key companies profiled
Associated British Foods plc; Dilmah Ceylon Tea Company PLC.; Bigelow Tea; PepsiCo, Inc; Bettys & Taylors of Harrogate Ltd; Starbucks Coffee Company; Unilever; Caraway Tea; Harris Freeman; The Republic of Tea
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Tea Market Report Segmentation
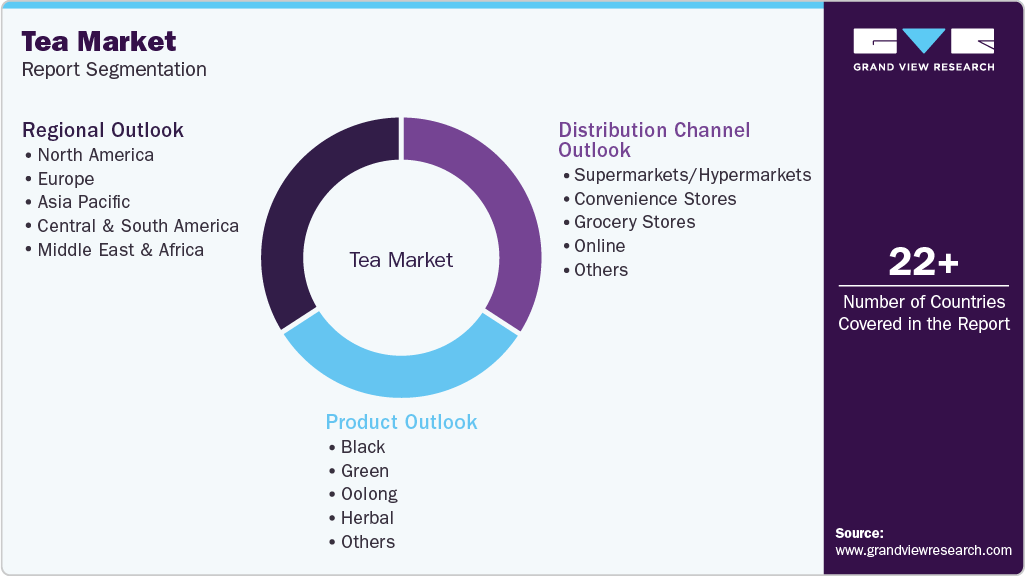
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global tea market report based on product, distribution channel and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Black
-
Green
-
Oolong
-
Herbal
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Supermarkets & Hypermarkets
-
Convenience Stores
-
Grocery Stores
-
Online
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa (MEA)
-
South Africa
-
-
Research Methodology
The tea market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each tea segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Black
This segment includes the sales of fully oxidized tea products characterized by their dark color, robust flavor, and relatively strong aroma, including loose-leaf, tea bags, and flavored black tea variants.
Green
This segment includes the sales of minimally oxidized tea products produced from tea leaves that are heat-treated to preserve their green color, fresh flavor, and naturally occurring compounds.
Oolong
This segment includes the sales of partially oxidized tea products positioned between green and black tea, offering a diverse range of flavors and aromas depending on the degree of oxidation and processing method.
Herbal
This segment includes the sales of caffeine-free infusions made primarily from herbs, flowers, fruits, spices, and other botanical ingredients, including chamomile, peppermint, hibiscus, and ginger-based products.
Others
This segment includes the sales of flavored tea, and other specialty or fermented tea varieties.
Estimation Model
Layer
Key Question
Description
Target Consumer Base
Who consumes tea products?
Demand is supported by consumers seeking daily refreshment, relaxation, cultural familiarity, wellness benefits, and convenient beverage options. Consumption is influenced by taste, tea variety, health positioning, and preparation convenience.
Consumer Need & Interest Layer
Where are they sold?
Tea products are distributed through supermarkets, hypermarkets, convenience stores, specialty tea shops, foodservice outlets, and e-commerce platforms, expanding accessibility across traditional and modern retail.
Purchasing & Usage Layer
How do brands differentiate?
Brands compete through premium tea varieties, herbal and functional blends, organic offerings, distinctive origins, ready-to-drink formats, convenient packaging, and wellness-focused formulations.
Revenue Realization Layer
How much revenue is generated?
Value is generated through premiumization, product variety, brand loyalty, convenience, functional positioning, and expansion across retail, foodservice, and digital channels.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Assess the tea market based on consumption patterns and consumer preferences
Evaluated tea consumption across black, green, herbal, specialty, and functional teas, considering taste, wellness, convenience, and purchasing behavior.
Helps identify high-potential consumer segments, product categories, and demand drivers.
Evaluate the competitive positioning of leading tea brands
Assessed players based on product portfolio, tea varieties, premium positioning, packaging, distribution, pricing, and brand presence.
Provides a structured competitive benchmark and highlights positioning and differentiation opportunities.
Identify emerging tea products and consumption opportunities
Evaluated developments in functional teas, premium blends, organic offerings, ready-to-drink tea, convenient formats, and novel flavor profiles.
Helps identify product innovation opportunities aligned with changing consumer preferences and consumption occasions.
Frequently Asked Questions About This Report
The global tea market size was estimated at USD 69.5 billion in 2025 and is expected to reach USD 74.0 billion in 2026.
The global tea market is expected to grow at a compound annual growth rate (CAGR) of 6.5% from 2026 to 2033 to reach USD 115.2 billion by 2033.
Key factors driving growth in the global tea market include rising health awareness, with consumers increasingly choosing tea for its antioxidants and functional benefits, along with a shift toward premium and specialty varieties. Expanding urbanization, innovative flavors, convenient ready-to-drink formats, and strong e-commerce penetration are further supporting market expansion.
Asia Pacific dominated with a 67.9% revenue share in 2025.
North America is expected to be the fastest-growing region over the forecast period.
The black tea segment led with a 53.3% revenue share in 2025.
Sales of tea through the supermarkets/hypermarkets held the largest revenue share in 2025.
The black tea market accounted for the largest share of 53.3% in 2025, driven by its widespread consumption, strong cultural preference in regions like Asia and Europe, and its affordability compared to specialty teas. Additionally, its versatility, longer shelf life, and growing demand for ready-to-drink beverages further supported its dominance.
Some key players operating in the global tea market include Associated British Foods plc, Dilmah Ceylon Tea Company PLC., Bigelow Tea, PepsiCo, Inc., Bettys & Taylors of Harrogate Ltd, Starbucks Coffee Company, Unilever, Caraway Tea, Harris Freeman, and The Republic of Tea.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


