
- Home
- »
- Advanced Interior Materials
- »
-
Textile-to-Textile Recycling Market Size Report, 2033GVR Report cover
![Textile-to-Textile Recycling Market (2026 - 2033)Report]()
Textile-to-Textile Recycling Market (2026 - 2033)
Size, Share & Trends Analysis Report By Fiber/Material Type (Polyester/PET, Cotton, Nylon/Polyamide, Cellulosic Fibers), By Recycling Technology (Mechanical Recycling), By End Use Application, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$5.4BCAGR, 2026–2033
14.4%Textile-to-Textile Recycling Market Summary
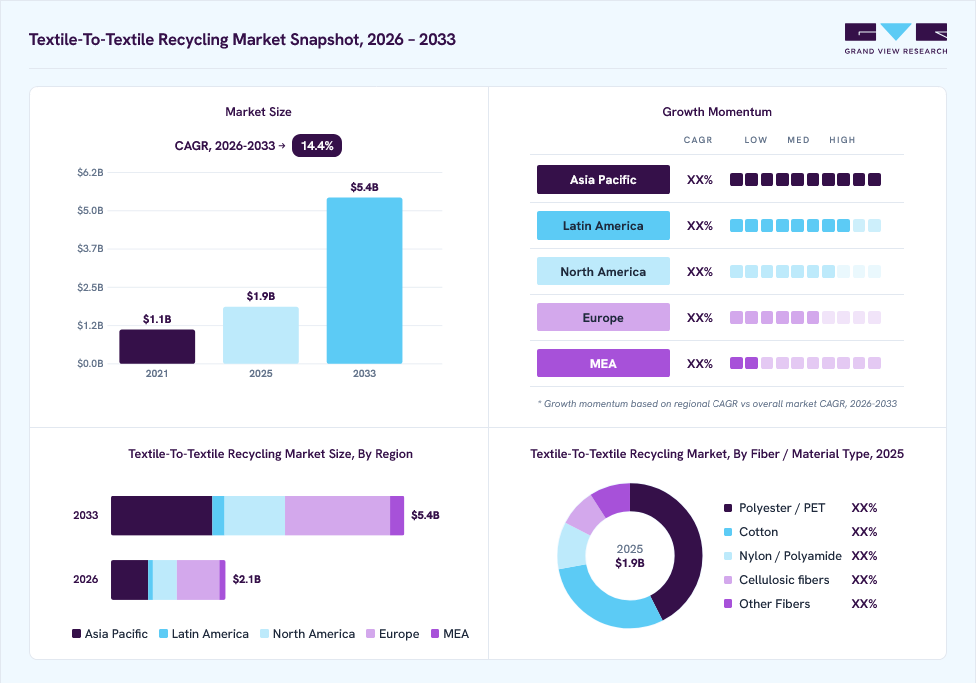
The global textile-to-textile recycling market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 5.4 billion by 2033, at a CAGR of 14.4% from 2026 to 2033. dominated the market, accounting for the largest revenue share of The market is gaining momentum as apparel manufacturers, brands, and textile producers increasingly shift from linear production models toward circular material systems.
Key Market Trends & Insights
- By fiber/material type: Polyester/PET segment held the highest revenue share of 42.5% in 2025.
- By recycling technology: Biological/enzymatic recycling segment is expected to grow at a CAGR of 15.5% over the forecast period.
- By end use: Apparel & fashion segment dominated the market with a revenue share of 49.8% in 2025.
Regional Highlights
- Largest regional market: Europe (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.1 Billion
- 2033 Projected Market Size: USD 5.4 Billion
- CAGR (2026-2033): 14.4%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask Prism AI
A cited answer in seconds
- Corpus30K studies, 1.2M points
- ScopeAll markets, not just this
- CitationTraced to report & table
- HonestySays "not covered" if so
- SpeedSeconds, not days
Technological development is increasingly shifting the market toward higher-value fiber recovery. Mechanical recycling remains commercially established for relatively clean and homogeneous textile waste, whereas chemical, enzymatic, dissolution, and depolymerization technologies are being developed to recover higher-quality fibers from polyester, cellulose, nylon, and blended textiles. Advanced sorting, automated fiber identification, decolorization, and digital traceability are also improving the quality and consistency of recovered feedstock.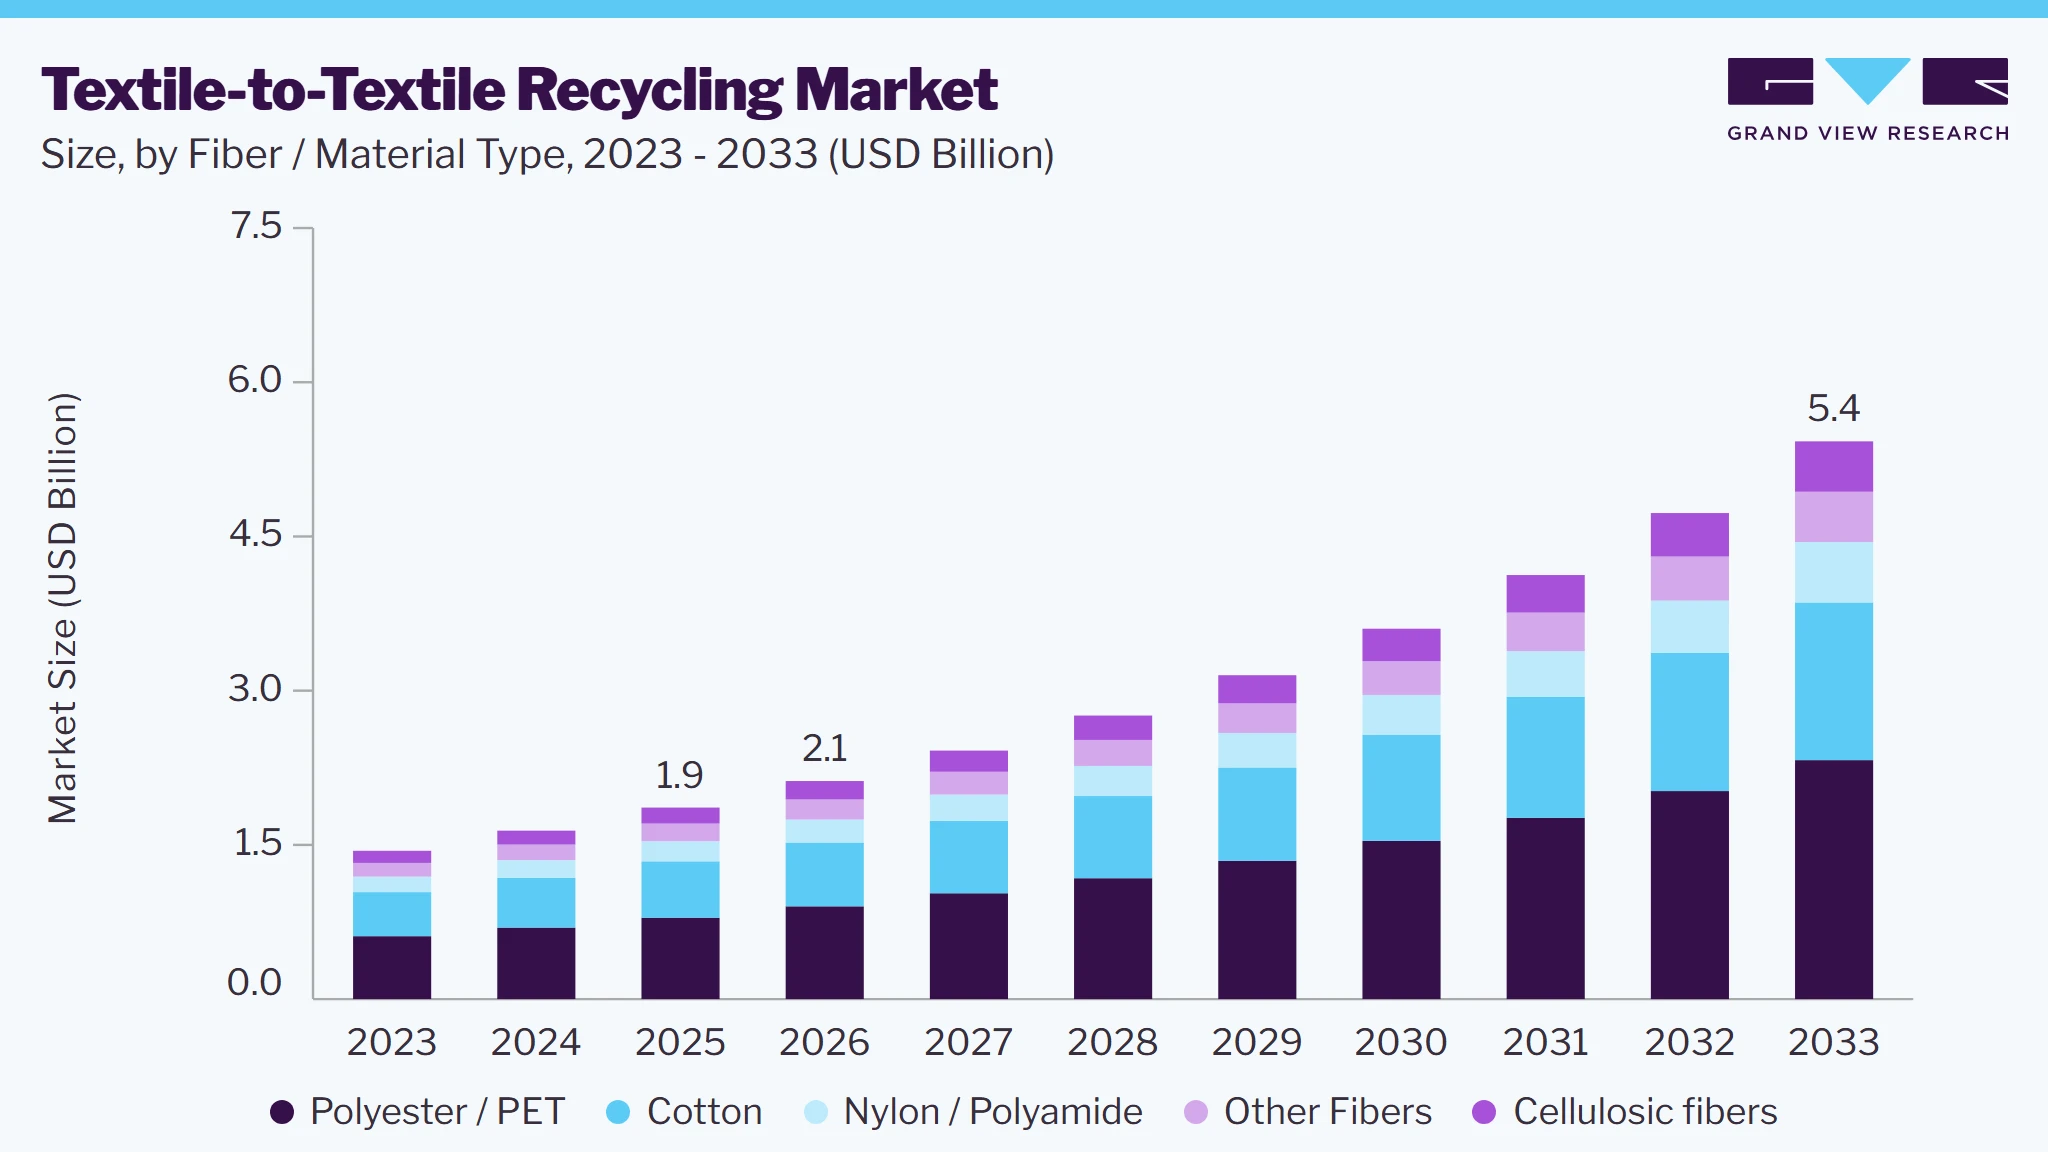
Market Dynamics
The textile-to-textile recycling market is undergoing a transition from conventional textile waste recovery to closed-loop recycling systems that return discarded fibers to textile manufacturing. Market development is influenced by the availability and quality of textile waste, recycling economics, technology maturity, brand sustainability commitments, regulatory requirements, and the ability of recyclers to produce fibers that meet textile-industry performance specifications. While mechanical recycling provides the current commercial foundation, chemical and biological technologies are expected to become increasingly important for the recovery of difficult-to-recycle blends and higher-quality fiber.
The increasing emphasis on circular fashion is a major driver for textile-to-textile recycling. Apparel brands and textile manufacturers are seeking to reduce dependence on virgin raw materials while improving the environmental profile of their products. Recycled fibers enable manufacturers to incorporate secondary raw materials into existing textile supply chains, particularly in apparel, sportswear, home textiles, and industrial textiles. Growing sustainability commitments are therefore encouraging brands to establish take-back programs, recycling partnerships, and closed-loop sourcing arrangements.
The availability of textile waste is also strengthening the underlying feedstock base. Pre-consumer waste generated by spinning, weaving, knitting, cutting, and garment manufacturing is relatively homogeneous and easier to process, while post-consumer garments represent a much larger but more complex resource. Improvements in collection and sorting infrastructure are gradually making post-consumer textiles more accessible to recyclers. India's textile-waste mapping initiatives similarly highlight the opportunity to strengthen recycling and circularity across both pre- and post-consumer waste streams.
A major restraint is the difficulty of obtaining consistent, high-quality textile waste suitable for fiber-to-fiber recycling. Post-consumer textiles can contain blended fibers, dyes, finishes, trims, elastane, coatings, and contaminants that complicate sorting and processing. Mechanical recycling can also shorten fibers and reduce material quality after repeated processing, limiting the proportion of recycled content that can be incorporated into premium textile applications. Chemical recycling can address some of these limitations but generally requires greater capital investment, sophisticated processing systems, and tighter control of feedstock composition.
The increasing development of chemical, enzymatic, and hybrid recycling technologies represents a significant opportunity for the market. Blended textiles such as cotton-polyester fabrics have historically been difficult to recycle into equivalent textile materials because the individual fibers must be separated or selectively recovered. Emerging dissolution, depolymerization, and enzymatic processes can potentially recover individual material components at higher quality, expanding the addressable waste stream for textile-to-textile applications. India's Ministry of Textiles has identified mechanical, thermo-mechanical, chemical, and thermo-chemical pathways and emphasizes the need for complementary technologies rather than dependence on a single recycling process.
Market Concentration & Characteristics
The textile-to-textile recycling market is moderately fragmented, with competition distributed across established mechanical recyclers, textile manufacturers, chemical recycling technology developers, fiber producers, startups, and vertically integrated apparel companies. Traditional recycling companies maintain an advantage in feedstock sourcing and processing infrastructure, while emerging technology companies are differentiating themselves through advanced chemical, enzymatic, and fiber-separation technologies. Strategic partnerships between recyclers, brands, textile manufacturers, and technology providers are becoming increasingly important because successful textile-to-textile recycling requires integration across collection, sorting, recycling, spinning, and downstream textile manufacturing.
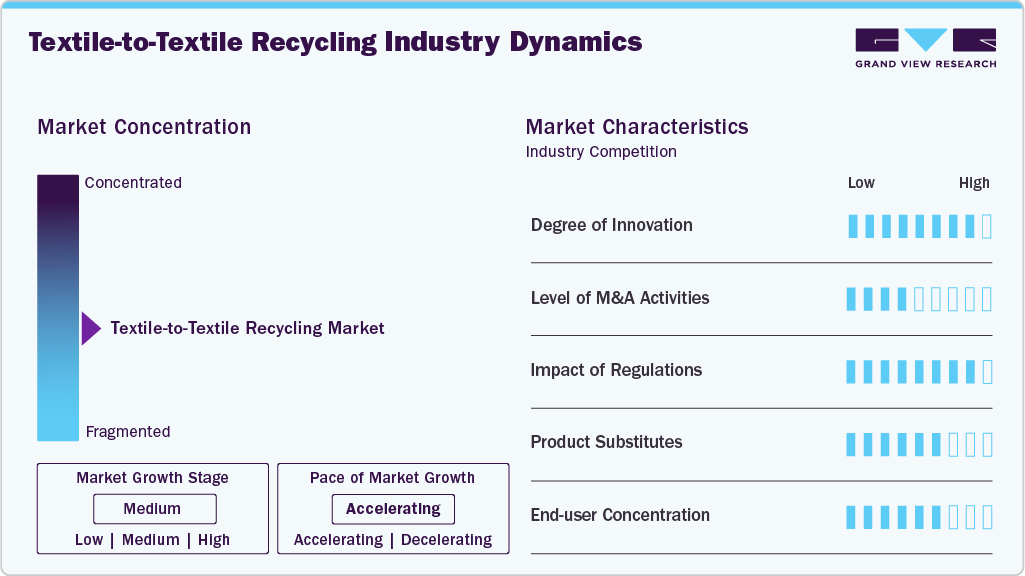
The threat of substitutes is moderate because textile-to-textile recycling competes with virgin fibers, downcycling, reuse, resale, upcycling, and alternative waste-to-value pathways. Virgin polyester, cotton, and other fibers remain widely available and offer established performance and supply consistency, while reuse and resale can retain greater product value without requiring fiber reprocessing. However, increasing regulatory pressure, sustainability requirements, and brand commitments are reducing the long-term attractiveness of virgin-material-intensive supply chains. Textile-to-textile recycling, therefore, has an advantage where manufacturers require recycled content while maintaining textile-grade material quality.
Fiber/Material Type Insights
The polyester/PET segment held the highest revenue share of 42.5% in 2025, driven by the extensive use of polyester in apparel, home textiles, and industrial applications, along with the established availability of polyester recycling technologies. The relatively high recyclability of PET established collection and processing infrastructure, and growing adoption of recycled polyester fibers by textile manufacturers and brands further support the segment's leading position.
The cellulosic fibers segment is expected to grow at a CAGR of 15.5% over the forecast period, as advances in regenerated cellulose recycling improve the ability to recover fibers from cotton-rich and other cellulose-based textile waste. Increasing development of dissolution-based recycling technologies, growing interest in recycled cellulose fibers, and investments in closed-loop production are expected to expand the use of recycled cellulosic materials across apparel and other textile applications.
Recycling Technology Insights
The mechanical recycling segment held the highest revenue share of 56.6% in 2025, due to its established commercial presence, relatively simple processing requirements, and broad applicability to pre-consumer and post-consumer textile waste. The technology requires comparatively lower processing complexity than advanced chemical and biological routes and is widely used for converting suitable textile waste into recycled fibers for yarn, apparel, home textiles, and other applications.
The biological/enzymatic recycling segment is expected to grow at a CAGR of 15.5% over the forecast period, as enzyme-based processes advance toward commercial-scale textile recycling. These technologies offer potential for selective separation and breakdown of textile materials while enabling recovery of valuable fiber components from complex waste streams. Continued technological development, pilot-scale validation, and investment in enzyme-based recycling are expected to support future adoption.
End Use Application Insights
The apparel & fashion segment held the highest revenue market share of 49.8% in 2025, supported by the large volume of textile fibers consumed in clothing and fashion products and the increasing incorporation of recycled fibers into apparel collections. Growing demand for recycled-content garments, brand commitments to circular materials, and established textile manufacturing supply chains are supporting the use of recycled fibers across clothing, sportswear, denim, and other fashion applications.
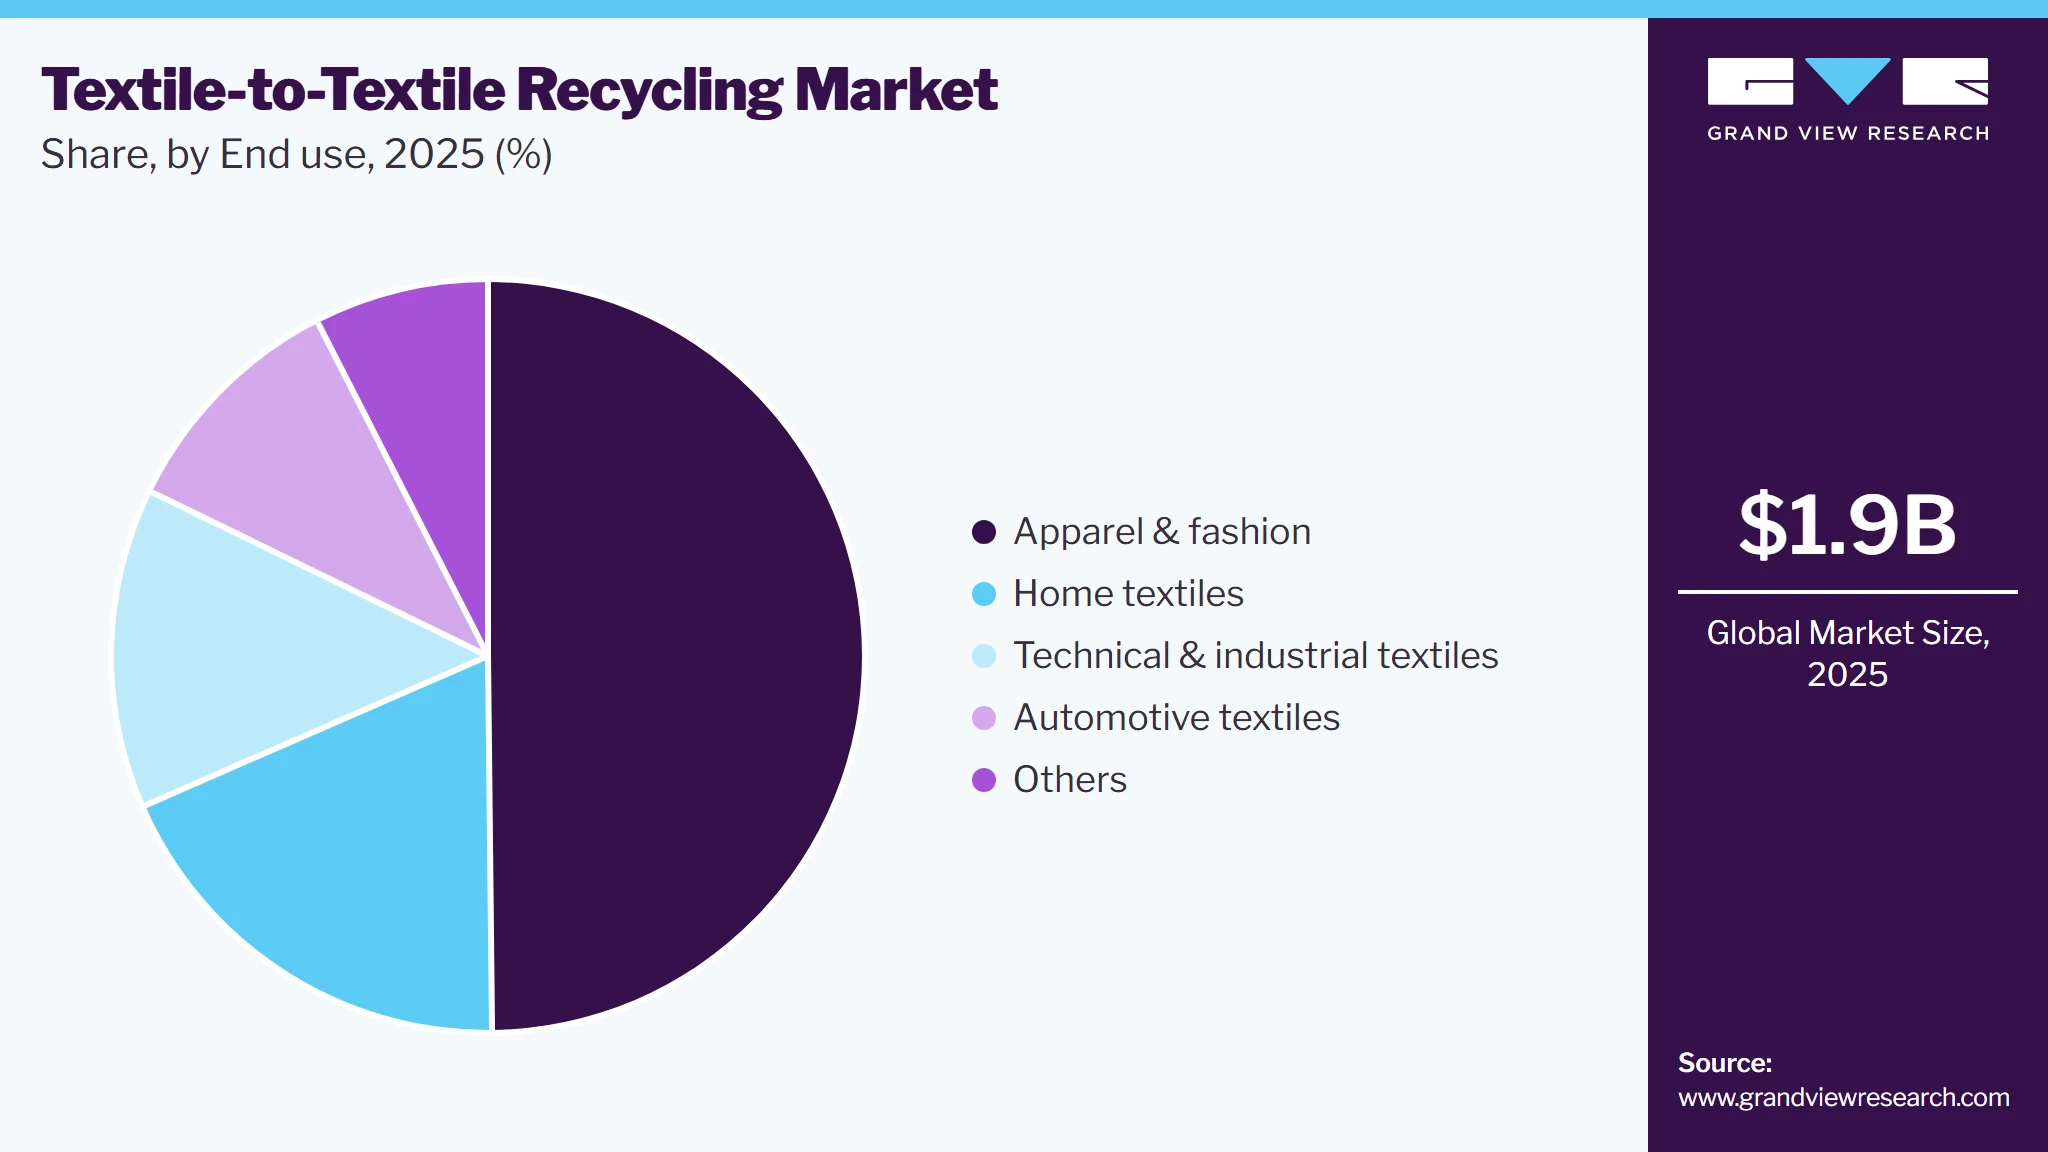
The technical & industrial textiles segment is expected to grow at a CAGR of 15.5% over the forecast period, as recycled fibers gain adoption in performance-oriented applications requiring durable and functional textile materials. The increasing use of recycled materials in automotive textiles, filtration, construction textiles, protective products, and other industrial applications, together with improvements in recycled fiber quality and performance, is expected to create additional demand among technical textile manufacturers.
Regional Insights
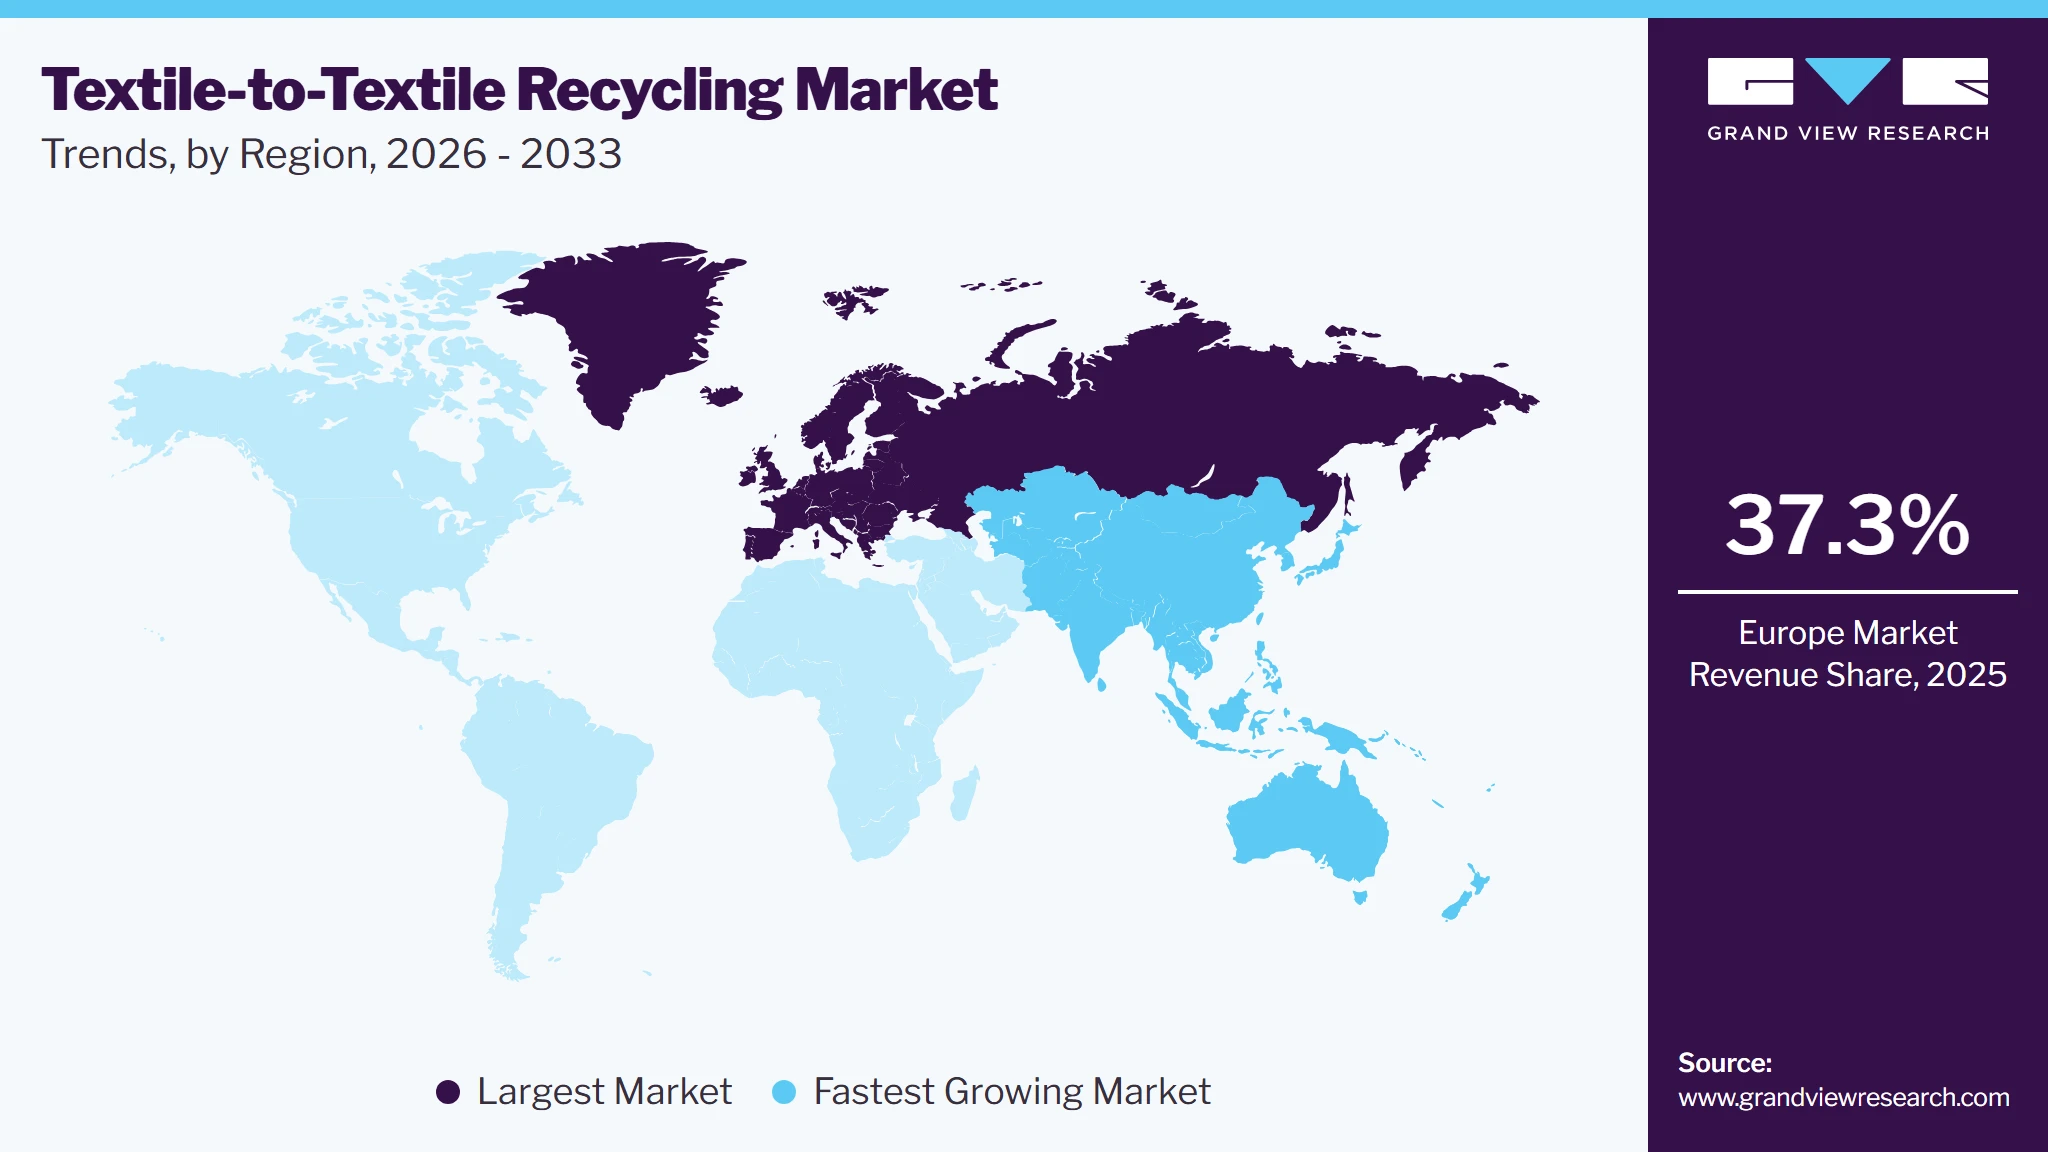
Europe dominated the global textile-to-textile recycling market and accounted for the largest revenue share, at 37.3%, in 2025, owing to its strong circular-economy policy framework, advanced textile industry, recycling infrastructure, and sustainability-oriented consumer market. Regulatory developments are strengthening requirements for separate collection, producer responsibility, recycling, eco-design, and traceability. The EU's revised Waste Framework Directive introduces harmonized extended producer responsibility requirements for textiles, while the Digital Product Passport is expected to improve traceability and facilitate recycling. These measures are creating favorable conditions for investment in textile sorting, fiber recovery, and closed-loop recycling.
Germany Textile-to-Textile Recycling Market Trends
Germany is an important European market because of its established waste-management infrastructure, advanced manufacturing capabilities, and strong focus on resource efficiency and circular production. Textile companies and recyclers are increasingly exploring automated sorting, fiber identification, and advanced recycling technologies. The country's industrial ecosystem also provides opportunities for collaboration between textile manufacturers, recycling companies, machinery suppliers, and technology developers.
Asia Pacific Textile-to-Textile Recycling Market Trends
Asia Pacific is a major growth region for textile-to-textile recycling because of its large textile manufacturing base, abundant production waste, and concentration of spinning, weaving, garment manufacturing, and fiber-processing capabilities. Countries such as China, India, Japan, South Korea, Bangladesh, and Vietnam are increasingly exploring mechanical and advanced recycling technologies.
The China textile-to-textile recycling market remains an important market because of its extensive textile manufacturing capacity, large synthetic-fiber industry, and established recycling infrastructure. The country's large polyester production base provides opportunities for closed-loop polyester recycling, while increasing environmental requirements are encouraging textile manufacturers to improve waste recovery and resource efficiency. Investment in chemical recycling and higher-quality regenerated fibers is expected to strengthen China's role in advanced textile-to-textile recycling.
North America Textile-to-Textile Recycling Market Trends
North America is experiencing increasing adoption of textile-to-textile recycling through brand-led take-back programs, recycling partnerships, and investment in advanced processing technologies. The region benefits from strong participation by apparel brands and retailers seeking recycled materials for sustainability targets. However, post-consumer collection, sorting infrastructure, and feedstock economics remain important challenges. Increasing interest in domestic recycling capacity and circular supply chains is expected to support market development.
The U.S. textile-to-textile recycling market is being driven by increasing corporate sustainability commitments, consumer interest in circular fashion, and investment in textile collection and recycling infrastructure. Apparel brands and technology companies are developing partnerships aimed at converting post-consumer garments into recycled fibers, while emerging technologies are targeting polyester, cotton, nylon, and blended textile waste. Greater emphasis on domestic textile recycling is also creating opportunities for localized collection-to-fiber supply chains.
Central and South America Textile-to-Textile Recycling Market Trends
Central and South America is an emerging market for textile-to-textile recycling, supported by growing textile consumption, increasing sustainability awareness, and the development of waste-management and circular-economy initiatives. Brazil and Mexico offer the strongest potential because of their large apparel and textile industries, while other countries are gradually developing collection, sorting, and recycling networks. Market growth is currently constrained by limited advanced recycling infrastructure and fragmented collection systems, creating opportunities for investment in organized textile recovery and recycling facilities.
Middle East & Africa Textile-to-Textile Recycling Market Trends
The Middle East & Africa market remains at an earlier stage of textile-to-textile recycling development but offers long-term potential as governments, brands, and textile manufacturers increasingly focus on waste reduction and resource efficiency. The region's growing apparel consumption, expanding textile manufacturing activities, and development of sustainability-oriented industrial projects can support demand for textile recovery solutions. Opportunities are particularly relevant for establishing collection and sorting infrastructure and developing recycling hubs capable of supplying recycled fibers to regional textile and apparel manufacturers.
Key Textile-to-Textile Recycling Company Insights
Some of the key players operating in the market include Lenzing AG and Birla Cellulose
-
Lenzing AG is an Austria-based specialty fiber producer focused on cellulose-based fibers for textile and nonwoven applications. The company develops regenerated fibers such as lyocell and viscose and has expanded its textile recycling capabilities through technologies such as REFIBRA, which incorporates recycled textile material into new fibers.
-
Birla Cellulose is the cellulosic fiber business of the Aditya Birla Group and a major producer of man-made cellulosic fibers. It operates multiple manufacturing sites and uses closed-loop technologies, while also developing recycled-fiber solutions through partnerships with textile recycling companies such as Circ.
CARBIOS and CIRC are some of the emerging market participants in the textile-to-textile recycling market.
-
CARBIOS is a France-based biotechnology company developing enzyme-based recycling technologies for plastics and textiles. Its PET biorecycling technology uses enzymatic depolymerization to recover polyester from textile waste and convert it into material suitable for producing new polyester fibers.
-
Circ is a U.S.-based textile-to-textile recycling company developing technology to separate polycotton blends into their core components, recovering cellulose and polyester building blocks for production of new recycled fibers. Its Circ materials include recycled polyester, lyocell, and viscose, with partnerships across the textile supply chain supporting commercialization.
Key Textile-to-Textile Recycling Companies
The following key companies have been profiled for this study on the textile-to-textile recycling market.
-
Lenzing AG
-
Birla Cellulose
-
Hyosung TNC
-
Unifi, Inc.
-
Aquafil S.p.A.
-
Circulose
-
CIRC
-
CARBIOS
-
Loop Industries, Inc.
-
Recover Textile Systems, S.L.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players Lenzing AG, Birla Cellulose, Hyosung TNC, Unifi, Inc., Aquafil S.p.A., Recover Textile Systems, S.L.
- Invest in established textile recycling, regenerated fiber, and recycled synthetic fiber capabilities to convert textile waste and other recovered materials into textile-grade fibers.
- Expand recycling capacity and market reach through partnerships with apparel brands, textile manufacturers, recyclers, and technology providers.
- Focus on improving recycled fiber quality, production efficiency, traceability, product performance, and integration with existing textile supply chains.
- Established manufacturing and fiber-production infrastructure supports commercial-scale deployment.
- Strong relationships with apparel brands, textile manufacturers, and downstream customers support market access and adoption.
- Diversified fiber portfolios and established recycling capabilities provide resilience across different feedstocks and end-use applications.
- High capital requirements for recycling infrastructure, capacity expansion, and process optimization.
- Established production systems can face challenges in adapting to highly variable post-consumer textile feedstocks and complex fiber blends.
- Dependence on consistent waste collection, feedstock quality, and cost-competitive recycled fiber supply can constrain expansion.
Emerging Players CIRC, CARBIOS, Loop Industries, Inc., Circulose
- Develop advanced textile-to-textile recycling technologies targeting cotton-rich textiles, polyester, blended fabrics, and other difficult-to-recycle textile waste.
- Scale commercial operations through strategic partnerships with fiber producers, apparel brands, textile manufacturers, and recycling companies.
- Prioritize improvements in fiber recovery, material quality, feedstock flexibility, process efficiency, and commercial-scale production.
- Specialized technologies address difficult-to-recycle textile streams and enable higher-value material recovery.
- Strong technology differentiation and partnerships with established fiber producers can accelerate commercialization and market access.
- Flexible business models and technology-focused operations allow faster development of new recycling pathways.
- Relatively smaller commercial footprint and production capacity compared with established fiber manufacturers.
- Dependence on financing, strategic partnerships, feedstock availability, and successful scale-up of recycling technologies.
- Challenges remain around processing costs, feedstock consistency, technology scalability, and achieving price competitiveness with virgin fibers.
Recent Developments
-
In June 2025, Circ entered a strategic partnership with Selenis to toll and polymerize thousands of metric tons of Circ recycled polyester at an industrial scale in Europe, supporting the commercialization of both recycled polyester and lyocell from textile waste.
-
In 2025, Loop launched Twist, its branded textile-to-textile PET made exclusively from textile waste and announced a strategic alliance with Hyosung TNC. It also secured land in Gujarat for its planned Infinite Loop India facility and signed an offtake agreement with Nike.
Textile-to-Textile Recycling Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 Billion
Estimated market size in 2026
USD 2.1 Billion
Projected market size by 2033
USD 5.4 Billion
Growth rate
CAGR of 14.4% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Fiber/material type, recycling technology, end-use application, and region
Regional scope
Global
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Saudi Arabia
Key companies profiled
Lenzing AG; Birla Cellulose; Hyosung TNC; Unifi, Inc.; Aquafil S.p.A.; Circulose; CIRC; CARBIOS; Loop Industries, Inc.; Recover Textile Systems, S.L.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Textile-to-Textile Recycling Market Report Segmentation
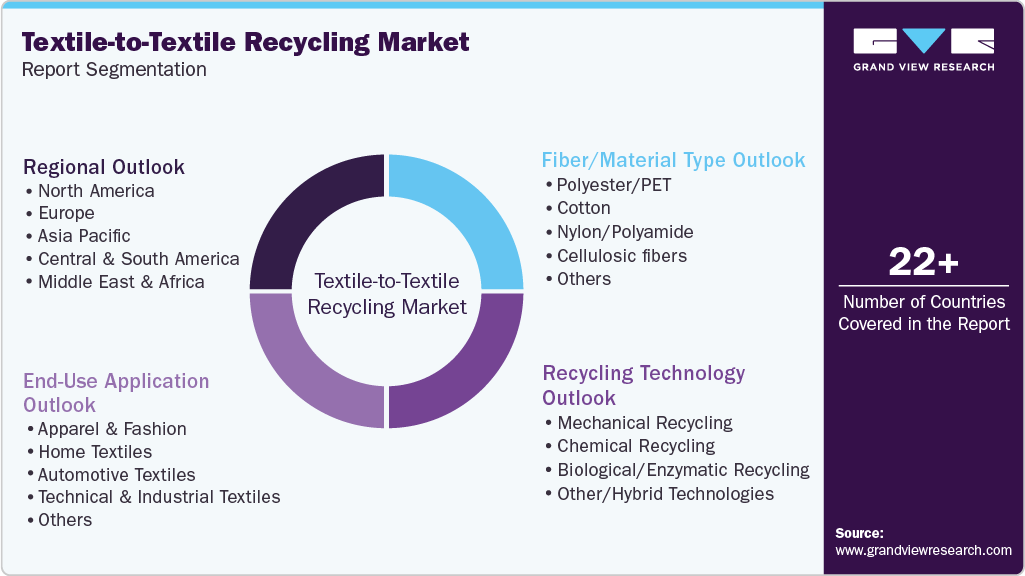
This report forecasts revenue growth at regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the textile-to-textile recycling market on the basis of fiber/material type, recycling technology, end-use application, and region:
-
Fiber/Material Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Polyester/PET
-
Cotton
-
Nylon/Polyamide
-
Cellulosic fibers
-
Others
-
-
Recycling Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Mechanical Recycling
-
Chemical Recycling
-
Biological/Enzymatic Recycling
-
Other/Hybrid Technologies
-
-
End Use Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Apparel & Fashion
-
Home Textiles
-
Automotive Textiles
-
Technical & Industrial Textiles
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central and South America
-
Brazil
-
-
Middle East and Africa
-
Saudi Arabia
-
-
Research Methodology
The textile-to-textile recycling market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each textile-to-textile recycling segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Fiber/Material Type
Revenue Capture Definition
Polyester / PET
Revenue generated from the sale of recycled polyester/PET textile fibers produced by processing pre-consumer and post-consumer polyester-containing textile waste, including discarded garments, fabric scraps, yarn waste, and polyester blends, through textile-to-textile recycling processes.
Cotton
Revenue generated from the sale of recycled cotton fibers produced by processing pre-consumer and post-consumer cotton-containing textile waste, including discarded garments, cutting waste, fabric scraps, yarn waste, and cotton blends, through textile-to-textile recycling processes.
Nylon / Polyamide
Revenue generated from the sale of recycled nylon/polyamide fibers produced by processing pre-consumer and post-consumer nylon/polyamide textile waste, including discarded garments, industrial textile waste, fabric scraps, yarn waste, and nylon-containing blends.
Cellulosic fibers
Revenue generated from the sale of regenerated or recycled cellulosic textile fibers produced from pre-consumer and post-consumer cellulose-based textile waste, including cotton-rich textiles, viscose, rayon, and other cellulosic materials processed through recycling technologies.
Others
Revenue generated from the sale of recycled textile fibers derived from other recyclable fiber materials not classified under polyester/PET, cotton, nylon/polyamide, or cellulosic fibers, including wool, acrylic, polypropylene, and other specialty textile fibers.
Segment - Recycling Technology
Revenue Capture Definition
Mechanical recycling
Revenue generated from the sale of textile fibers produced through mechanical processing of pre-consumer and post-consumer textile waste, including sorting, shredding, tearing, opening, carding, and re-spinning operations without chemically altering the polymer or fiber structure.
Chemical recycling
Revenue generated from the sale of recycled or regenerated textile fibers produced through chemical processes that dissolve, depolymerize, separate, or otherwise chemically process textile waste to recover fiber-forming materials for subsequent textile production.
Biological/enzymatic recycling
Revenue generated from the sale of recycled textile fibers or recovered fiber-forming materials produced using biological or enzymatic processes to selectively break down, separate, or recover components from pre-consumer and post-consumer textile waste for textile production.
Other/hybrid technologies
Revenue generated from the sale of recycled textile fibers produced using other or combined recycling technologies that integrate mechanical, chemical, thermal, biological, enzymatic, or other processing methods to recover usable textile materials from textile waste.
Segment - End-use Application
Revenue Capture Definition
Apparel & fashion
Revenue generated from the sale of recycled textile fibers used in apparel and fashion products, including clothing, sportswear, activewear, denim, footwear textiles, accessories, and other fashion-related textile products.
Home textiles
Revenue generated from the sale of recycled textile fibers used in home textile products, including bedding, towels, curtains, upholstery, carpets, rugs, cushions, and other household textile applications.
Automotive textiles
Revenue generated from the sale of recycled textile fibers used in automotive textile applications, including vehicle upholstery, seat fabrics, carpets, floor coverings, headliners, insulation, trunk liners, and other interior textile components.
Technical & industrial textiles
Revenue generated from the sale of recycled textile fibers used in technical and industrial textile applications, including filtration materials, geotextiles, protective textiles, construction textiles, industrial fabrics, and other performance-oriented textile products.
Others
Revenue generated from the sale of recycled textile fibers used in other applications not classified under apparel & fashion, home textiles, automotive textiles, or technical & industrial textiles, including institutional textiles, medical textiles, and other specialty applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Parent Market Analysis
What is the overall size and growth outlook of the global textile fibers, recycled fibers, textile recycling, textile waste management, and circular textile materials markets?
The estimation begins by evaluating the broader global textile fiber, recycled fiber, textile recycling, textile waste management, and sustainable textile materials markets. Global fiber production and consumption, textile and apparel manufacturing, textile waste generation, collection and sorting infrastructure, recycling capacity, recycled fiber production, and investments in circular textile materials are analyzed to establish the total addressable market relevant to textile-to-textile recycling.
02
Textile Waste-to-Fiber Recycling Penetration Analysis
What proportion of the overall textile recycling and recycled fiber market is represented by textile-to-textile recycling across different fiber types and recycling technologies?
This layer estimates the penetration of textile-to-textile recycling within the broader textile recycling and recycled fiber markets. Adoption is assessed across pre-consumer and post-consumer textile waste streams and major fiber types, including polyester/PET, cotton, nylon/polyamide, cellulosic fibers, and other materials. Penetration is further evaluated across mechanical, chemical, biological/enzymatic, and hybrid recycling technologies to determine the share of recycled fiber production originating from textile waste that is returned to textile applications.
03
Regional & End-use Demand Assessment
Which regions, fiber types, recycling technologies, and end-use industries contribute the highest demand for textile-to-textile recycled fibers?
Market demand is evaluated across major regions based on textile and apparel manufacturing capacity, textile waste generation, availability of recyclable feedstock, collection and sorting infrastructure, recycling capacity, sustainability regulations, recycled-content requirements, and circular-economy initiatives. Demand is further assessed across apparel & fashion, home textiles, automotive textiles, technical & industrial textiles, and other applications, while considering the adoption of recycled polyester/PET, cotton, nylon/polyamide, and cellulosic fibers.
04
Company Revenue Validation & Market Forecasting
How is the final market size validated and forecast across fiber types, recycling technologies, regions, and end-use applications?
Final estimates are validated using company revenues, textile recycling and fiber production capacities, processing volumes, recycled fiber output, waste collection volumes, feedstock availability, recycling technology deployment, product portfolios, manufacturing facilities, technology partnerships, investments, certifications, and announced capacity expansions. Bottom-up and top-down approaches are triangulated using company-level, fiber-level, technology-level, waste-stream, regional, and end-use data to generate reliable market estimates and forecasts for textile-to-textile recycling.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Textile Waste Feedstock Availability & Recycling Potential Assessment
Analyze the availability of pre-consumer and post-consumer textile waste, including collection channels, fiber composition, contamination levels, sorting requirements, geographic availability, and suitability for conversion into recycled textile fibers.
Helps assess feedstock availability and quality while identifying key raw-material constraints and opportunities affecting the scalability of textile-to-textile recycling.
Recycling Technology & Fiber Conversion Assessment
Evaluate mechanical, chemical, biological/enzymatic, and hybrid recycling technologies based on feedstock compatibility, processing requirements, technology maturity, fiber yield, quality, scalability, energy requirements, and commercialization status.
Helps recyclers, fiber producers, and technology developers identify suitable recycling routes and opportunities to improve fiber recovery, process efficiency, and commercial scalability.
Competitive Landscape & Capacity Benchmarking
Benchmark key textile-to-textile recyclers and technology providers based on recycling capacity, fiber production capacity, technology capabilities, geographic presence, product portfolio, partnerships, investments, and capacity expansion plans.
Provides a clear view of market positioning, competitive intensity, leading players, capacity distribution, and potential gaps for new investments or market entry.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


