
- Home
- »
- Consumer F&B
- »
-
UAE Premium Bottled Water Market Size Report, 2026-2033GVR Report cover

UAE Premium Bottled Water Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Still Water, Sparkling Water), By Price Point (Premium), By Packaging Type, By Distribution Channel, By Pack Size, By Pack Type (Single Pack, Multi Pack), And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.3BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
5.5%UAE Premium Bottled Water Market Summary
The UAE premium bottled water market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.3 billion in 2026 to USD 1.9 billion by 2033, at a CAGR of 5.5% from 2026 to 2033. The UAE’s hot and arid climate drives consistent hydration needs and supports strong demand for bottled water. Premium consumption is further reinforced by luxury tourism, upscale hospitality, high purchasing power, and rising wellness consciousness.
Key Market Trends & Insights
- By product: Still water segment held the largest market share of 83.6% in 2025.
- By price point: Premium segment held the largest market share of 70.5% in 2025.
- By packaging type: PET bottles segment held the largest market share of 71.7% in 2025.
- By distribution channel: Off-premise segment held the largest market share of 69.9% in 2025.
- By pack size: Upto 500 ml segment held the largest market share of 38.2% in 2025.
- By pack type: Multi pack segment held the largest market share of 50.4% in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.2 Billion
- Estimated market size in 2026: USD 1.3 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 5.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumers increasingly favor pure, mineral-rich, functional, and visually distinctive water products, while brands are differentiating through premium packaging, source provenance, enhanced hydration propositions, and sustainability-led formats. UAE consumers are increasingly viewing premium bottled water as more than a basic hydration product, with purity, quality, wellness, convenience, and premium presentation becoming important purchase considerations. The country’s hot and arid climate creates a sustained need for hydration, while high purchasing power and a strong luxury consumption culture support demand for differentiated water products. Consumers are increasingly interested in high-purity, mineral-rich, naturally sourced, and functional waters, particularly products that align with active lifestyles and wellness-oriented consumption.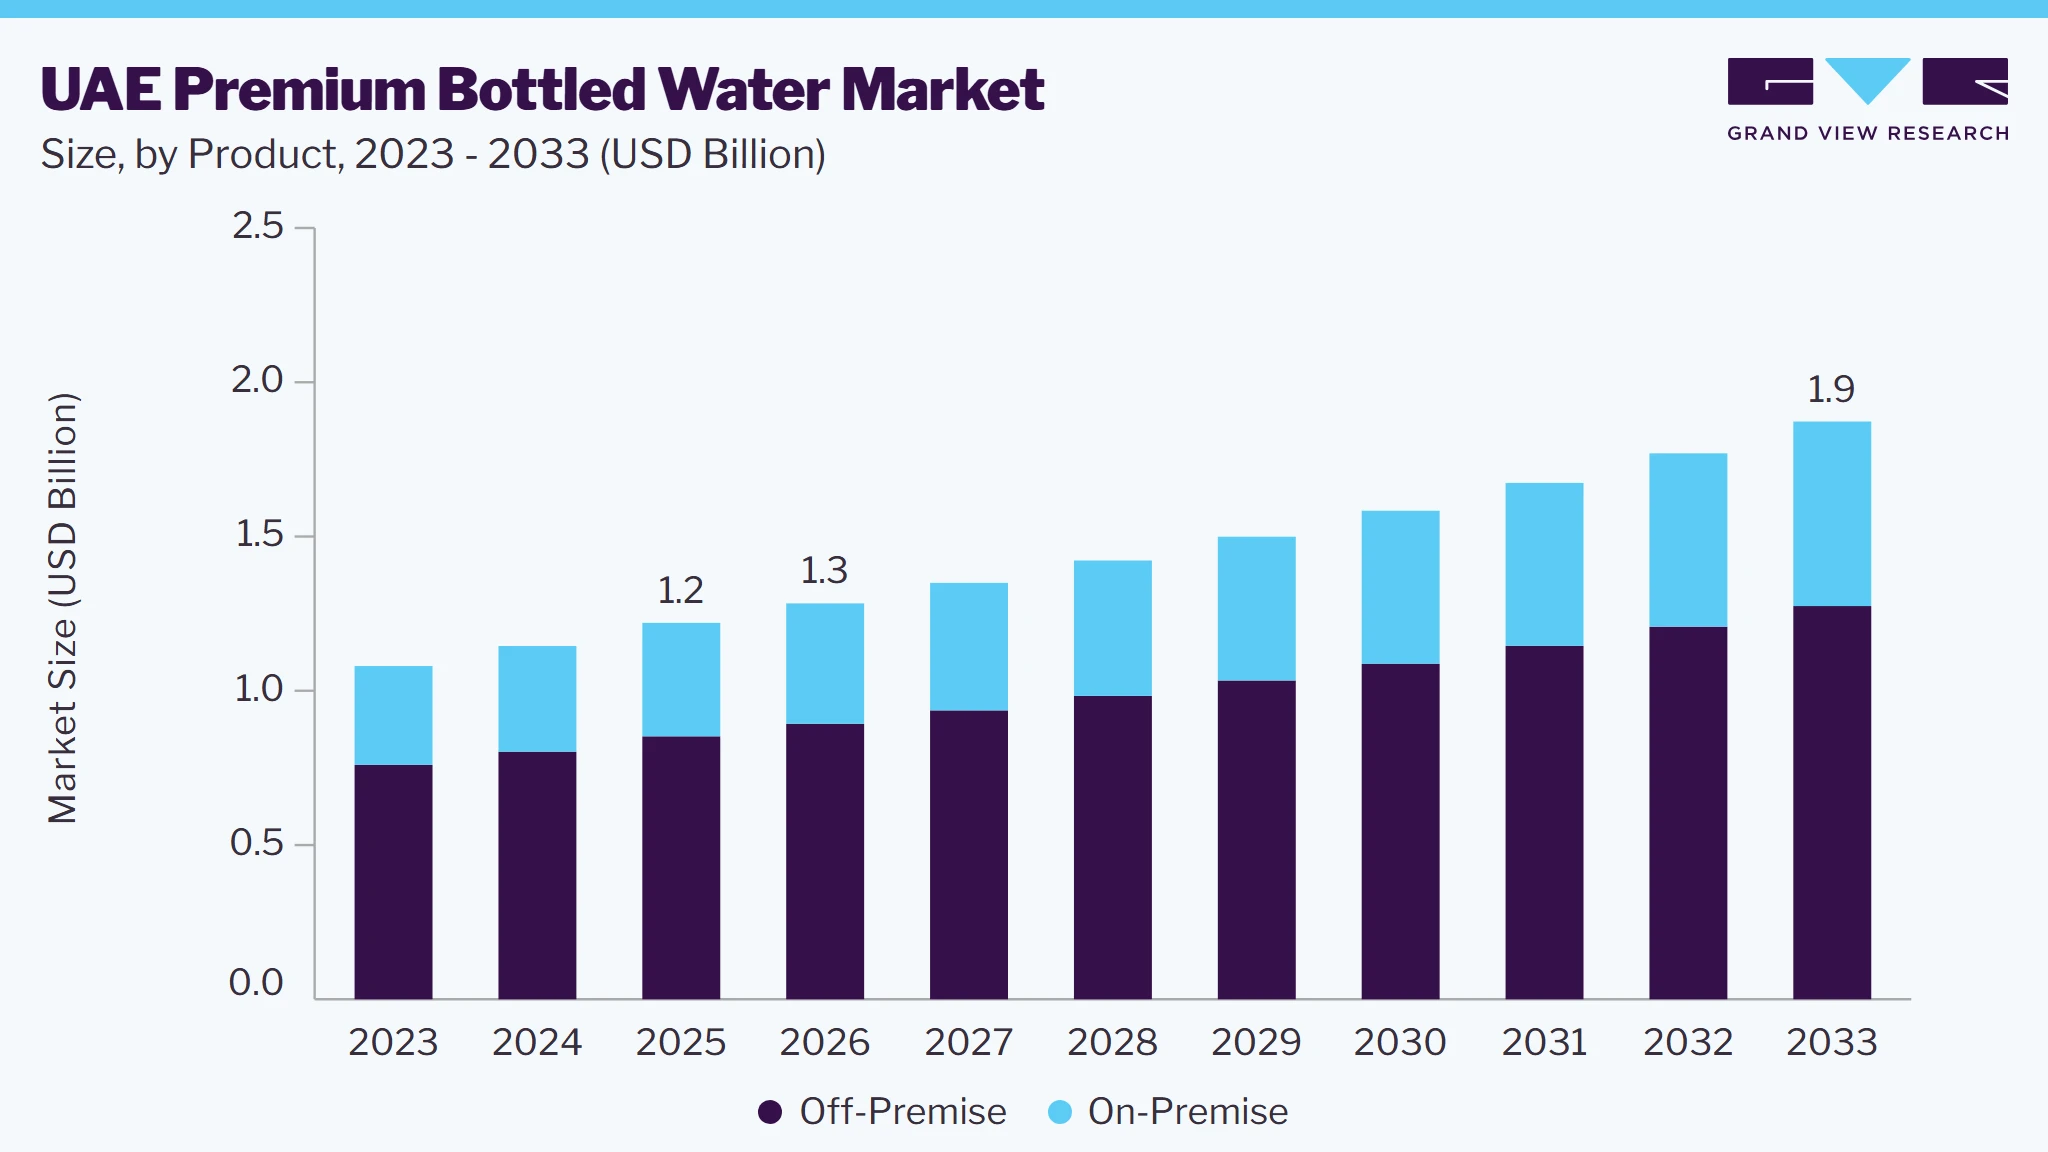 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
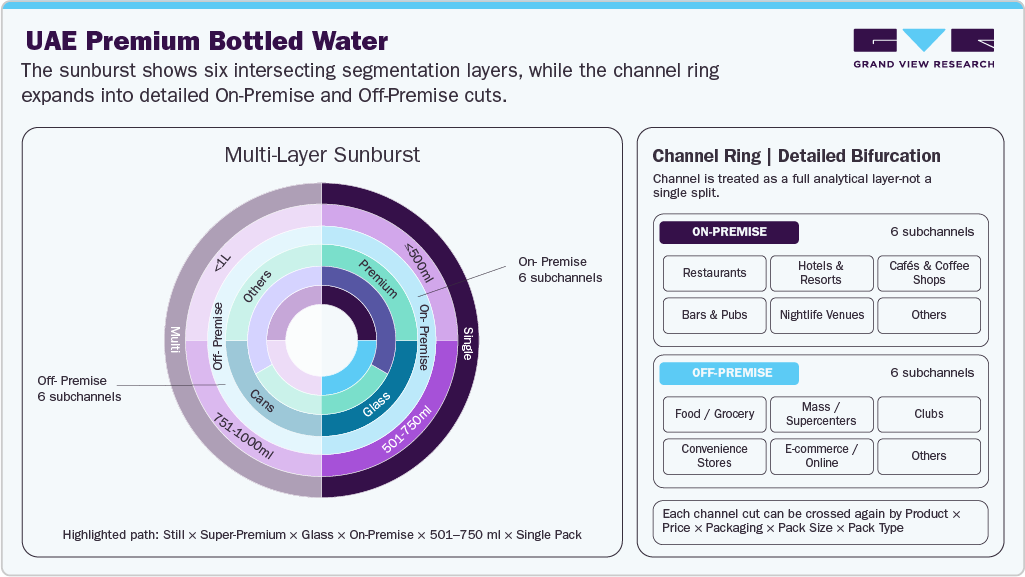
Demand is also reinforced by the UAE’s extensive hotel, restaurant, tourism, and luxury hospitality ecosystem, in which premium water enhances the overall dining and guest experience. For instance, in February 2025, BE WTR partnered with Rosewood Abu Dhabi to launch Abu Dhabi’s first fully circular automatic water bottling facility. The BiG 1500 system locally purifies, filters, and bottles still and sparkling water in reusable glass bottles, with each bottle designed to be refilled more than 300 times and the facility expected to eliminate 1.5 million single-use plastic bottles annually. This development highlights the growing convergence of premiumization and sustainability in the UAE water market. Brands are consequently placing greater emphasis on local sourcing, reusable packaging, environmental credentials, distinctive presentation, and premium hospitality partnerships, reflecting consumers’ evolving expectations for both product quality and responsible consumption.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The UAE premium bottled water industry is benefiting from advancements in water-generation technology and sustainable production practices, as increasing water scarcity encourages businesses to explore alternative sources and more resource-efficient solutions. Air-to-water systems are emerging as a differentiated approach that converts atmospheric moisture into drinking water through controlled purification and mineralization processes. For instance, in January 2025, Dubai-based A1RWATER commissioned a 90,000-square-foot facility at Dubai Industrial City equipped with 52 air-to-water generators capable of producing more than 100,000 liters of drinking water daily. The facility also integrates automated bottling and bottle-reuse capabilities, highlighting the potential for technology-enabled production, resource efficiency, and circularity to create differentiated premium bottled-water offerings in the UAE.
The UAE maintains stringent technical and conformity standards for bottled drinking water, requiring manufacturers and importers to meet defined requirements related to product quality, safety, packaging, labeling, and market compliance. UAE.S GSO 1025 establishes requirements for bottled drinking water, while UAE.S GSO 987 addresses natural mineral water. Compliance with these standards can increase testing, certification, packaging validation, and regulatory costs, particularly for premium brands introducing specialized mineral compositions, imported products, or differentiated product claims. These requirements may therefore raise market-entry barriers and extend commercialization timelines for new and smaller premium water brands.
The UAE premium bottled water industry offers opportunities for brands to strengthen differentiation through distinctive packaging, limited-edition collections, and culturally relevant product designs. Consumers in the UAE’s premium and hospitality segments are receptive to products that combine quality with strong visual appeal and a connection to local culture. For instance, in March 2025, Masafi unveiled limited-edition Ramadan packaging in collaboration with Emirati artist Mariam Abbas, incorporating UAE cultural symbols and heritage elements into its bottled-water packaging. The initiative demonstrates how bottled-water brands can use culturally relevant design, limited editions, and local artistic collaborations to strengthen brand differentiation and create greater consumer engagement during key occasions.
Analyst Perspective
The UAE premium bottled water market is evolving from basic hydration into a quality, wellness, and lifestyle-driven category, supported by the country’s hot climate, tourism, luxury hospitality, and growing health consciousness. Consumers increasingly assess premium water based on purity, mineral composition, source, taste, functional benefits, packaging, and sustainability, while convenience remains important for on-the-go and household consumption. Manufacturers are responding with natural mineral and functional waters, premium glass bottles, recycled PET, aluminum cans, reusable formats, local bottling, and direct-to-consumer delivery models. Premium water is also becoming part of the luxury dining and hospitality experience, encouraging brands to differentiate through distinctive bottle designs, provenance, and exclusive partnerships. At the same time, sustainability is moving from a brand differentiator toward a procurement consideration, particularly among hotels and restaurants seeking to reduce plastic waste and transportation-related impacts.
Consumer Insights
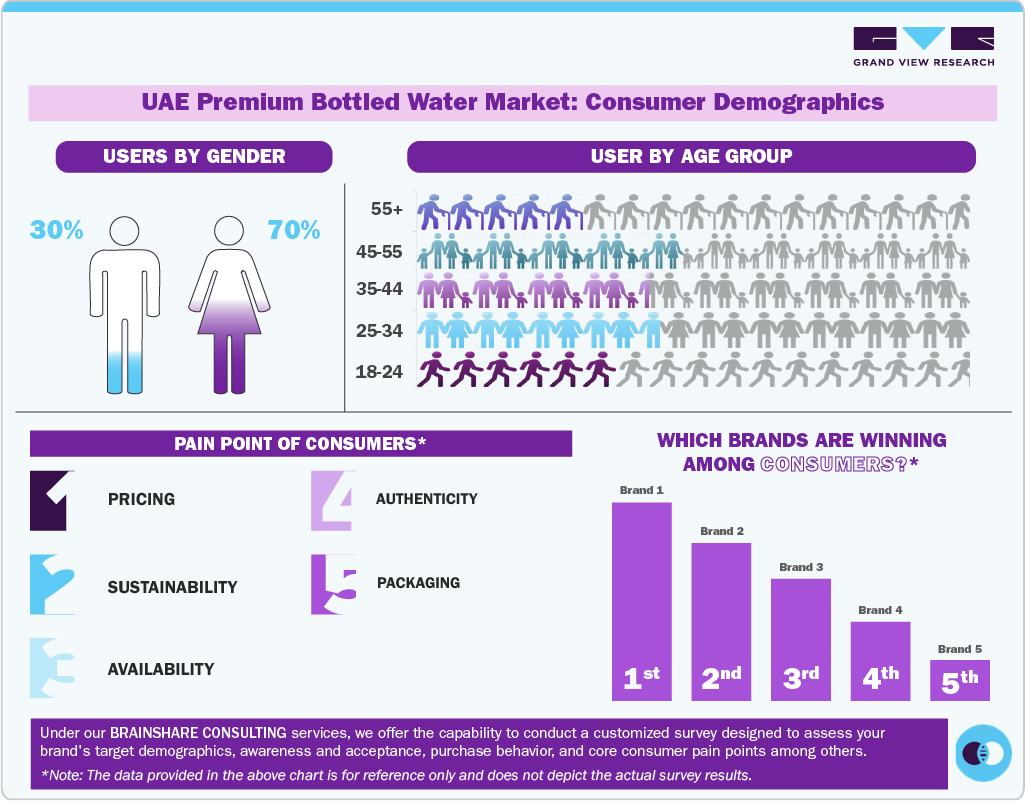
UAE consumers are increasingly evaluating premium bottled water based on quality, purity, sustainability, and the overall value of the product, rather than hydration alone. The country’s hot climate supports frequent water consumption, while rising wellness awareness is encouraging consumers to seek mineral-rich, naturally sourced, functional, and high-quality water options. Sustainability is also gaining importance, particularly among environmentally conscious consumers who are becoming more attentive to packaging materials, recyclability, local sourcing, and water provenance. For instance, a May 2026 survey commissioned by UAE premium water brand BE WTR found that 57% of UAE respondents considered sustainability important when choosing drinking water, while 66% cited better quality as a key reason for switching brands. This indicates that consumers increasingly associate premium water with both superior product attributes and responsible consumption. Convenience remains relevant across fitness, travel, workplaces, dining, and outdoor occasions, while premium water also carries strong lifestyle appeal through its presence in luxury hotels, restaurants, resorts, and wellness venues. As a result, UAE consumers are showing greater willingness to choose water brands that combine purity, functionality, premium presentation, environmental responsibility, and a credible source story, creating opportunities for brands to differentiate beyond conventional bottled-water offerings.
 To learn more about this report, Download Free Sample Report
Product Insights
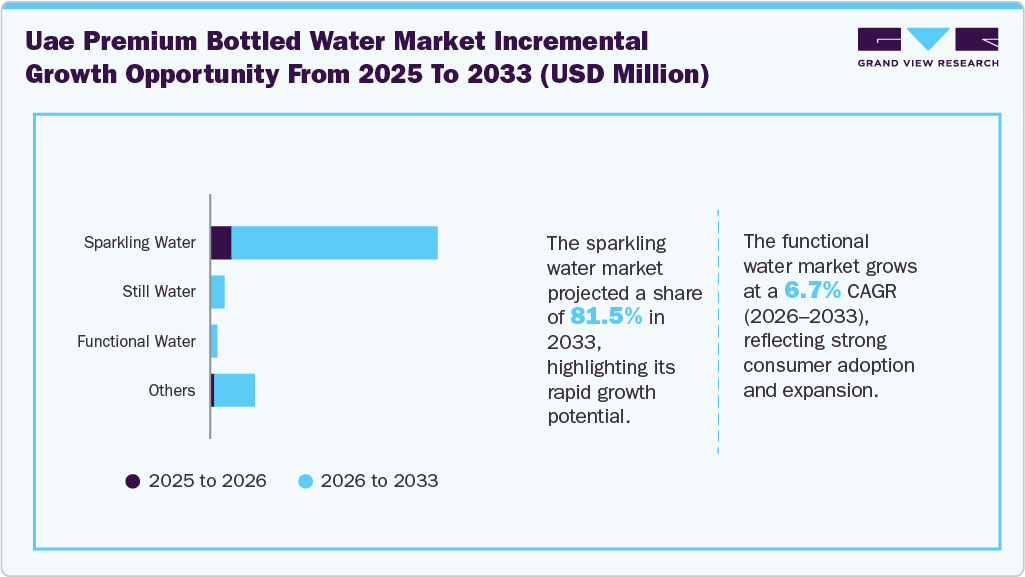
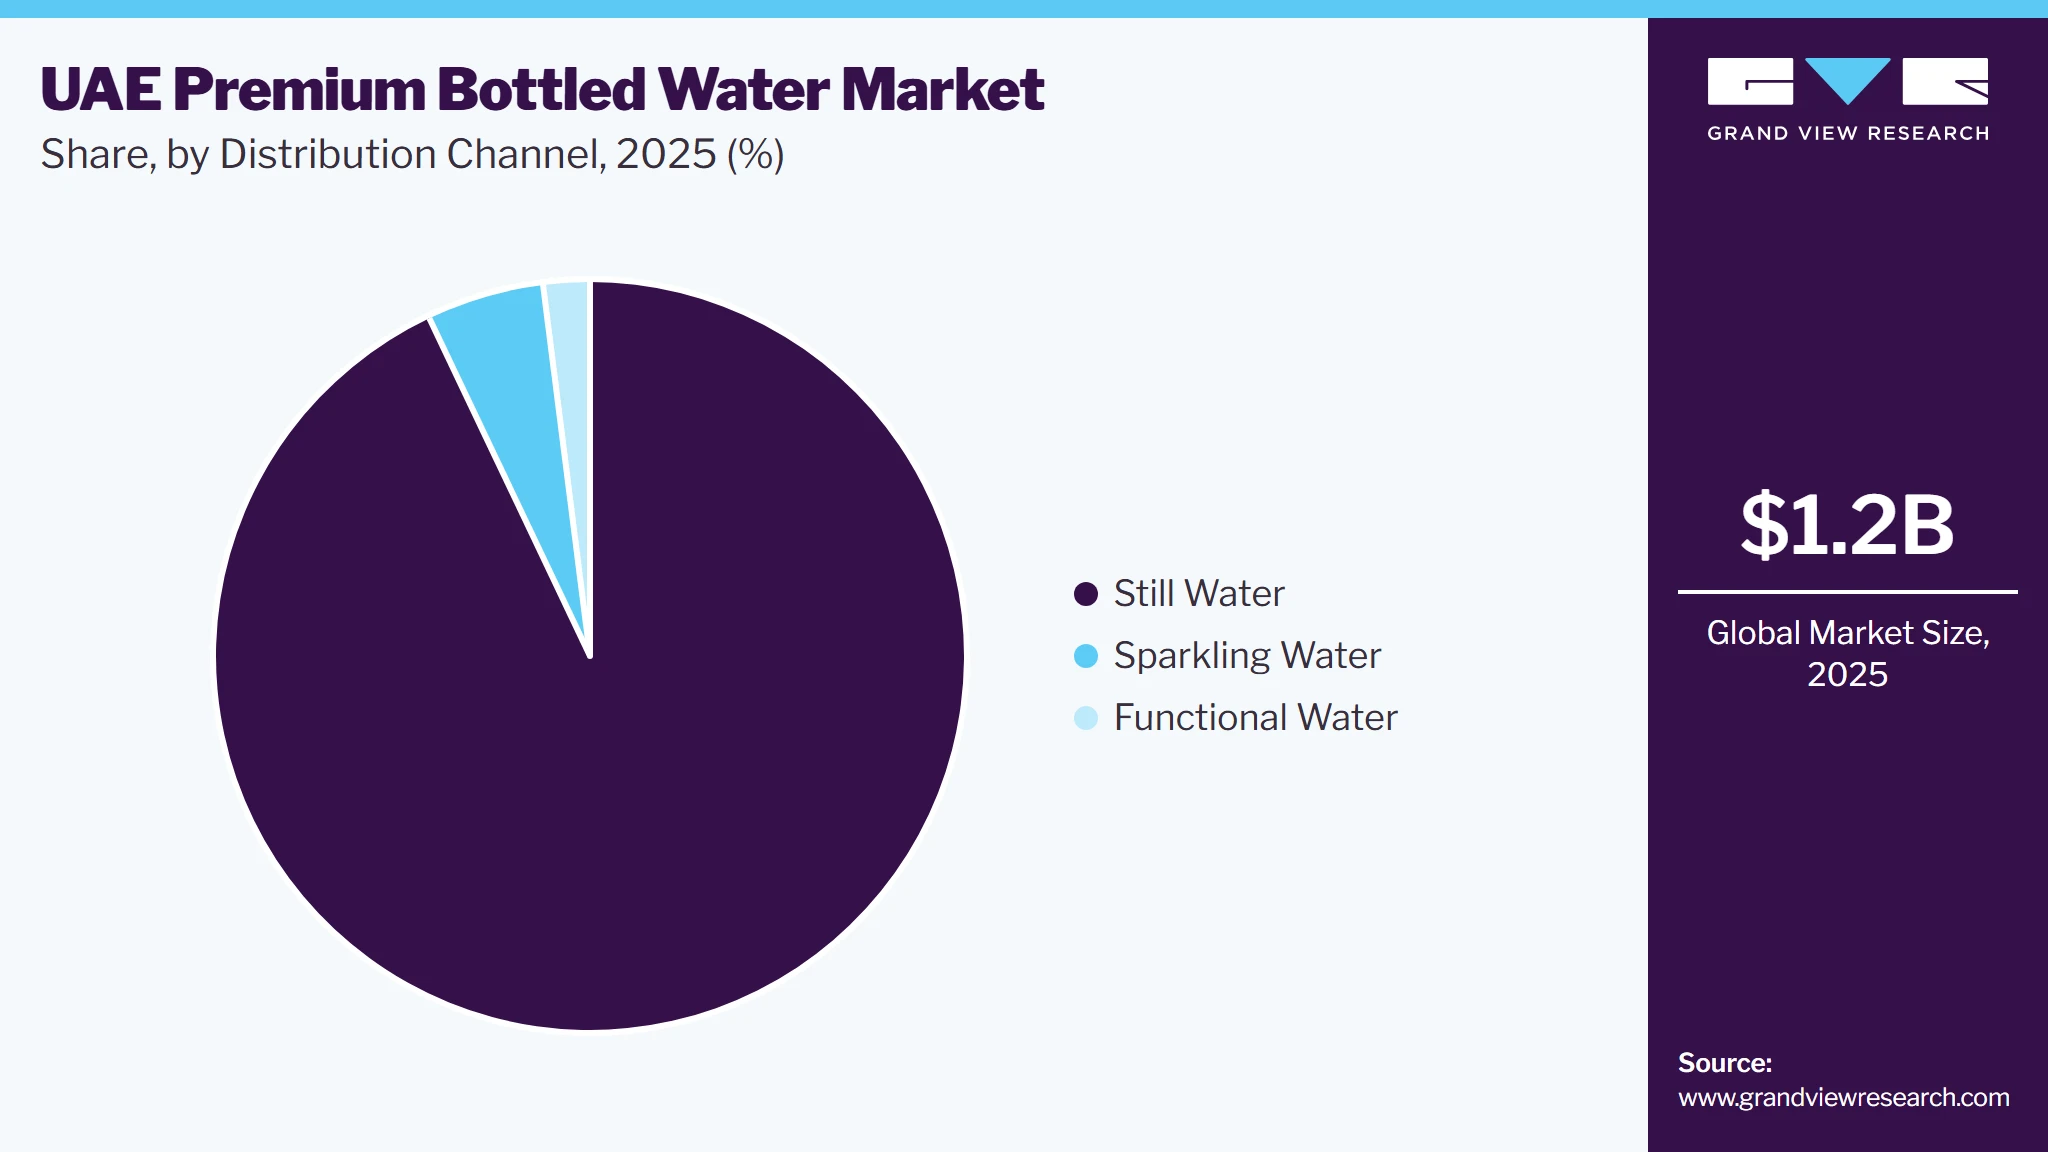
Still water accounted for the largest share of the UAE premium bottled water market, representing 83.6% of revenue in 2025. The segment’s leading position is supported by strong year-round hydration needs and widespread consumption across households, offices, retail outlets, restaurants, hotels, and other foodservice channels. Its suitability for regular consumption, particularly under the UAE’s hot climate, continues to reinforce consumer preference for non-carbonated water. Within the premium category, brands are creating differentiation through natural mineral composition, advanced purification, premium packaging, sustainable formats, and convenient pack sizes. For instance, in March 2025, Italian Food Masters introduced Lurisia Premium Natural Mineral Water in the UAE, offering still and sparkling variants across fine-dining restaurants, specialty coffee shops, gourmet retailers, and private-consumer channels. Sourced from the Monte Pigna springs in Italy, the still-water range emphasizes natural mineral characteristics and premium positioning, highlighting opportunities for differentiated imported brands within the UAE’s high-end water market.
 To learn more about this report, Download Free Sample Report
Functional water is projected to record the fastest CAGR of 6.7% from 2026 to 2033, driven by increasing consumer interest in health-oriented hydration, active lifestyles, and beverages offering benefits beyond basic hydration. UAE consumers are showing greater interest in products containing electrolytes, minerals, vitamins, and other functional ingredients, particularly for hydration during exercise and the country’s hot climate. Premium brands are leveraging these preferences to develop benefit-led water products with differentiated nutritional and wellness propositions, enabling higher-value positioning and attracting health- and fitness-conscious consumers.
Price Point Insights
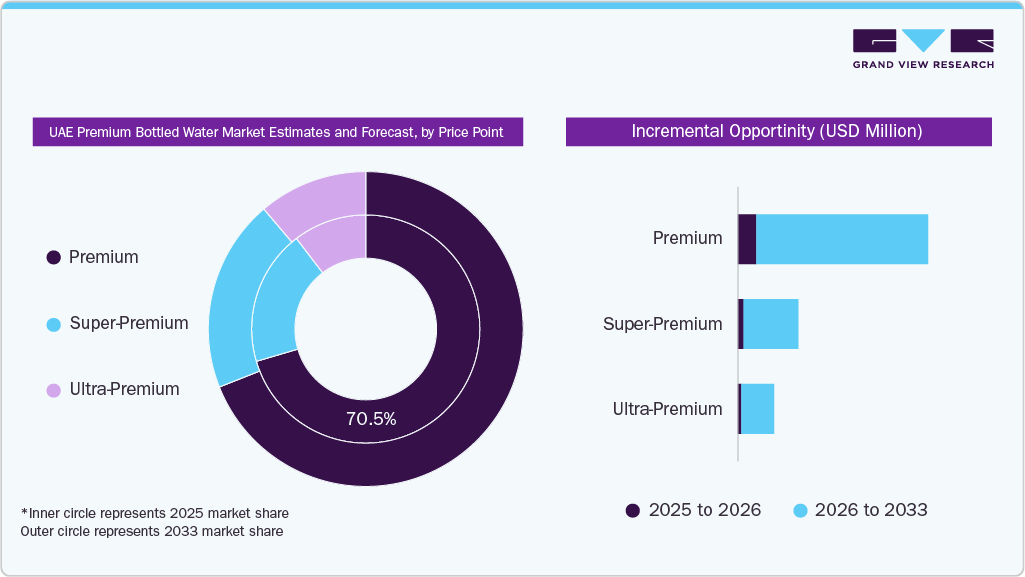
By price point, the premium bottled water accounted for the largest share, representing 70.5% of total revenue in 2025. Its strong position is supported by the UAE’s high-income consumer base, luxury-oriented consumption patterns, and well-established hospitality and tourism sectors. Consumers are increasingly willing to pay a premium for bottled water offering superior purity, distinctive mineral composition, natural or exclusive sourcing, sophisticated packaging, and sustainability credentials. Demand is particularly strong across luxury hotels, fine-dining restaurants, resorts, corporate settings, and premium retail, where bottled water is increasingly considered part of the overall consumption experience rather than a basic beverage. This premiumization trend encourages brands to differentiate through brand heritage, source provenance, innovative packaging, functional attributes, and exclusive hospitality partnerships, supporting continued value growth in the segment.
 To learn more about this report, Download Free Sample Report
The ultra-premium bottled water is projected to record the fastest CAGR of 6.5% from 2026 to 2033. The ultra-premium segment benefits from demand for exclusivity, distinctive water origins, luxury packaging, and elevated brand experiences, supported by the UAE’s affluent consumer base and strong luxury hospitality, fine-dining, tourism, and premium retail sectors. Brands are leveraging unique source stories, premium glass formats, limited-edition designs, and sustainability credentials to justify higher price points. For instance, in January 2026, Dubai-based DISANTINO Water was recognized by Luxury Lifestyle Awards as the “Best Luxury Ultra-Premium Natural Water in Dubai, UAE.” The brand offers 750 mL still and naturally effervescent mineral water in premium glass bottles, sourced from protected springs in Italy’s Central Apennines. Its exclusive positioning, distinctive mineral profile, and fine-dining-focused presentation highlight the potential for ultra-premium brands to differentiate through provenance, quality, and luxury appeal in the UAE market.
Packaging Type Insights
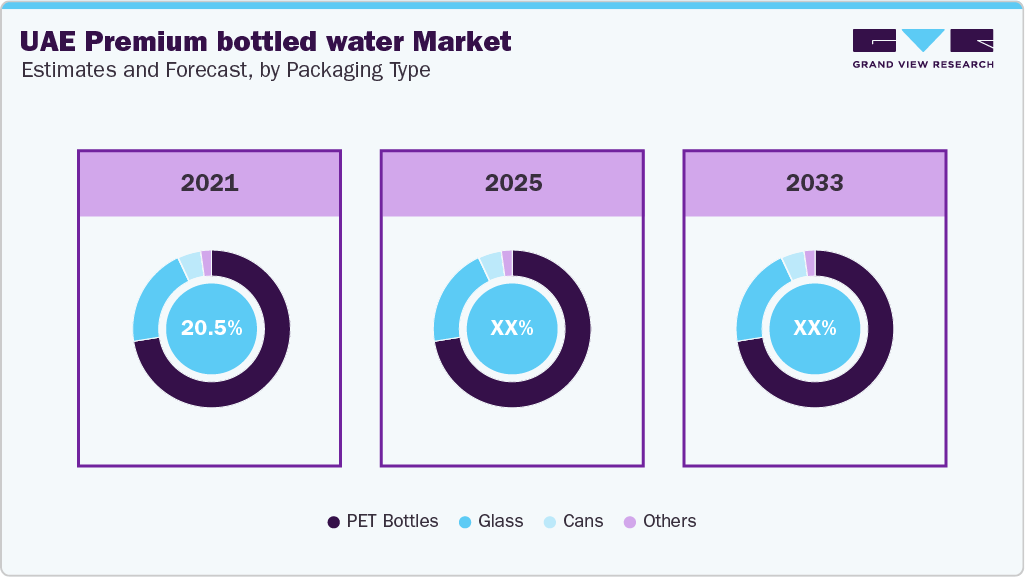
By packaging type, PET bottles held the largest share of the UAE premium bottled water industry, accounting for 71.7% of total revenue in 2025. Its strong position is supported by lightweight construction, durability, portability, affordability, and extensive distribution, making PET suitable for frequent hydration across retail, hospitality, fitness, workplaces, and on-the-go occasions. The growing use of recycled PET is also enabling premium brands to meet sustainability expectations while retaining the convenience and practicality of plastic packaging. For instance, in November 2025, VOSS strengthened its UAE offering with 250 mL Still Water bottles made from 100% recyclable PET, targeting wellness, hospitality, fashion, and cultural events. The launch highlights how premium water brands are leveraging compact PET formats, contemporary packaging, and recyclable materials to align convenience with evolving sustainability requirements in the UAE market.
 To learn more about this report, Download Free Sample Report
By packaging type, cans are projected to record the fastest CAGR of 7.2% from 2026 to 2033, The cans segment is gaining traction due to growing preference for portable, durable, and environmentally responsible packaging. Aluminum cans provide advantages in recyclability, convenience, and handling, making them suitable for on-the-go consumption across hospitality, fitness, events, travel, and premium retail. The format also offers brands an opportunity to establish a modern premium identity while reducing dependence on conventional plastic packaging. For instance, in 2025, UAE-based CANAMA launched PAANI, positioned as the UAE’s first premium resealable canned water, featuring a recyclable aluminum format designed for convenient consumption. The launch highlights the potential for canned water to emerge as a differentiated premium packaging format in the UAE, particularly among consumers seeking convenience combined with sustainability.
Distribution Channel Insights
The off-premise channels in the UAE premium bottled water market accounted for the largest share of 69.9% of the revenue in 2025. Its leading position is supported by widespread availability through supermarkets, convenience stores, e-commerce platforms, home-delivery services, and other retail outlets, enabling consumers to purchase premium water for regular household and personal consumption. The UAE’s high smartphone penetration and established online grocery ecosystem are also supporting digital purchasing and recurring delivery models. For instance, in May 2026, UAE premium water brand BE WTR launched a subscription-based home-delivery app in Dubai, enabling consumers to order locally bottled still and sparkling water in reusable glass bottles directly to their homes. The initiative highlights the growing role of direct-to-consumer distribution and subscription-based delivery in expanding premium water accessibility beyond hotels, restaurants, and other on-premise channels.
 To learn more about this report, Download Free Sample Report
The on-premise channel is projected to register the fastest CAGR of 6.3% from 2026 to 2033, supported by the UAE’s expanding luxury hospitality, tourism, fine-dining, and premium foodservice sectors. Premium bottled water is increasingly integrated into the overall dining and guest experience, with hotels and restaurants favoring products that offer high quality, distinctive sourcing, premium presentation, and sustainable packaging. The strong growth of upscale hospitality also creates opportunities for exclusive water partnerships and locally bottled solutions tailored to hotel and restaurant requirements. For instance, in February 2026, Armada UAE secured exclusive distribution of Evian still and sparkling water across all 15 Jumeirah hotels in the UAE and their 70 restaurants, significantly expanding the brand’s presence across the country’s luxury hospitality channel.
Pack Size Insights
By pack size, upto 500 ml of premium bottled water, representing 38.2% of revenue in 2025. The segment benefits from strong demand for single-serve bottles that are easy to carry, consume, and purchase, particularly across commuting, travel, fitness, workplaces, retail, and hospitality occasions. Compact formats are also well suited to the UAE’s hot climate, where consumers frequently purchase water for immediate consumption while travelling or engaging in outdoor activities. For instance, in 2025, UAE-based Ma Hawa offered its premium still water in a 330 ml format, providing a compact option for individual consumption across retail and lifestyle occasions. The availability of smaller premium formats highlights the importance of portability and convenience in driving demand within the UAE premium bottled water market.
The 501-750 ml of premium bottled water are projected to register the fastest CAGR of 5.6% from 2026 to 2033. Growth is supported by consumer preference for mid-sized formats that provide greater hydration capacity while remaining practical for individual consumption. These bottles are well suited to outdoor activities, travel, fitness, dining, hospitality, and extended periods away from home, offering a balance between portability and volume. Premium brands are responding by expanding into larger single-serve formats that combine functionality with elevated presentation. For instance, in January 2026, BE WTR introduced its 750 mL still water format in the UAE, offering locally produced water in premium glass bottles with a defined mineral profile. The launch reinforces the relevance of the 750 ml format across premium dining, hospitality, and household consumption, combining higher hydration volume with premium product experience.
Pack Type Insights
The premium bottled water in multi packs held the largest position in the UAE premium bottled water industry, representing 50.4% of revenue in 2025. Its leading position is supported by demand for convenient, cost-effective, and readily available water supplies for households, offices, hospitality venues, and group consumption occasions. Multipacks enable consumers and businesses to maintain sufficient bottled-water inventory while reducing the need for frequent individual purchases. The format is particularly relevant in the UAE’s hot climate, where high and recurring hydration needs encourage bulk purchasing. Premium brands are also expanding multipack offerings across modern retail and e-commerce channels, providing consumers with greater convenience while supporting repeat purchases and higher basket values.
The premium bottled water in single pack is projected to register a significant CAGR of 5.0% from 2026 to 2033. Growth is supported by increasing demand for convenient, portable, and individually portioned water across commuting, travel, fitness, dining, events, and other on-the-go occasions. Single packs also allow consumers to select premium water based on brand, source, mineral composition, and packaging, without committing to larger quantities. The format is particularly relevant in the UAE, where the hot climate and high mobility of consumers and tourists sustain demand for readily accessible hydration. Premium brands are therefore strengthening their presence through compact pack sizes, premium packaging, and targeted single-serve offerings, supporting wider adoption across retail and hospitality channels.
Key UAE Premium Bottled Water Company Insights
The UAE premium bottled water industry is competitive, with established multinational brands and emerging premium players competing across retail, foodservice, hospitality, and e-commerce channels. Companies are focusing on product innovation, portfolio expansion, sustainable packaging, strategic partnerships, digital marketing, and channel expansion to strengthen market positioning.
 To learn more about this report, Download Free Sample Report
Key UAE Premium Bottled Water Companies
-
Agthia Group PJSC
-
Masafi Co. LLC
-
Mai Dubai LLC
-
National Food Products Company (NFPC)
-
Danone S.A.
-
Nestlé S.A.
-
Coca-Cola Al Ahlia Beverages Company LLC
-
Ma Hawa
-
BE WTR
-
Marina Mineral Water Co. LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Agthia Group PJSC, Masafi Co. LLC, Mai Dubai LLC, National Food Products Company (NFPC), Danone S.A., Nestlé S.A., Coca-Cola Al Ahlia Beverages Company LLC)
- Expand premium portfolios through distinctive sources, premium packaging, sustainability initiatives, and broad retail and hospitality distribution.
- Strong brand recognition, established distribution, trusted sources, and premium positioning.
- Higher operating costs, regulatory pressures, and intense competition from private-label and specialist brands.
Emerging Players (Ma Hawa, BE WTR, Marina Mineral Water Co. LLC)
- Target niche opportunities through flexible production, specialist offerings, differentiated sourcing, and selected retail or hospitality channels.
- Greater flexibility, customer-focused solutions, and differentiated product propositions.
- Limited brand awareness, distribution reach, production scale, and marketing resources.
Recent Developments
-
In February 2026, Armada UAE secured exclusive distribution of Evian still and sparkling water across all 15 Jumeirah hotels in the UAE and their 70 restaurants, significantly expanding the brand’s presence across the country’s luxury hospitality channel.
-
In January 2026, BE WTR introduced its 750 mL still water format in the UAE, offering locally produced water in premium glass bottles with a defined mineral profile. The launch reinforces the relevance of the 750 mL format across premium dining, hospitality, and household consumption, combining higher hydration volume with premium product experience.
UAE Premium Bottled Water Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026
USD 1.3 billion
Projected market size by 2033
USD 1.9 billion
Growth Rate (Revenue)
CAGR of 5.5% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative (Revenue) units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, price point, packaging type distribution channel. Pack size, pack type
Country scope
UAE
Key companies profiled
Agthia Group PJSC; Masafi Co. LLC; Mai Dubai LLC; National Food Products Company (NFPC); Danone S.A.; Nestlé S.A.; Coca-Cola Al Ahlia Beverages Company LLC; Ma Hawa; BE WTR; Marina Mineral Water Co. LLC
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
UAE Premium Bottled Water Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the UAE premium bottled water market report on the basis of product, price point, packaging type distribution channel, Pack size, and pack type.
-
Product Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
Still Water
-
Sparkling Water
-
Functional Water
-
Others
-
-
Price Point Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
Premium
-
Super-Premium
-
Ultra-Premium
-
-
Packaging Type Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
PET Bottles
-
Glass
-
Cans
-
Others
-
-
Distribution Channel Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
On-Premise
-
Restaurants
-
Hotels & Resorts
-
Cafés & Coffee Shops
-
Bars & Pubs
-
Nightlife Venues
-
Others
-
-
Off-Premise
-
Food / Grocery
-
Mass (incl. supercenters)
-
Clubs
-
Convenience Stores
-
E-commerce / Online
-
Other
-
-
-
Pack Size Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
Upto 500 ml
-
501-750 ml
-
751-1000 ml
-
Above 1 Liter
-
-
Pack Type Outlook (Volume, Million Liters; Revenue, USD Million; 2021 - 2033)
-
Single Pack
-
Multi Pack
-
Research Methodology
The UAE premium bottled water market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each UAE premium bottled water segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Still Water
This segment includes the sales of premium still water, including natural spring water, mineral water, artesian water, and purified water without carbonation.
Sparkling Water
This segment includes the sales of premium sparkling water, including naturally sparkling and carbonated water products.
Functional Water
This segment includes the sales of premium water enhanced with functional ingredients, such as electrolytes, vitamins, minerals, antioxidants, and other nutrients intended to support hydration and wellness.
Others
This segment includes the sales of other premium bottled water products, including specialty water products differentiated by unique sourcing, processing, or formulation.
Estimation Model
Layer Name
Key Question
Description
Consumption Profile Layer
Who consumes premium bottled water?
Demand is supported by consumers seeking high-quality hydration, perceived purity, superior taste, natural mineral content, functional benefits, and premium experiences. Wellness awareness, convenience, and interest in sustainable consumption further influence purchasing preferences.
Market Reach Layer
Where are they sold?
Products reach consumers through retail, e-commerce, restaurants, hotels, foodservice, and specialty channels, with distribution breadth supporting market penetration.
Innovation & Differentiation Layer
How do brands differentiate?
Brands differentiate through source provenance, mineral composition, functional benefits, sparkling formats, premium bottle designs, and sustainable packaging.
Value Generation Layer
How does consumption convert into market value?
Revenue is generated through premium-priced product sales, supported by brand equity, differentiated offerings, packaging value, and consumer willingness to pay.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Understand premium bottled water consumer preferences and purchasing behavior
Developed a UAE-specific consumer assessment covering preferences for natural spring water, mineral content, source origin, purity, taste, packaging format, sustainability, and functional benefits. Evaluated purchasing behavior across supermarkets, convenience stores, specialty retailers, foodservice, and e-commerce.
Helps identify high-value consumer segments, key purchase drivers, and attributes that support premium pricing and brand differentiation in the UAE market.
Benchmark competitive positioning of leading premium bottled water brands
Assessed major UAE and international brands based on water source, product positioning, packaging, price tier, brand image, sustainability initiatives, distribution footprint, and product portfolio. Evaluated how brands differentiate through provenance, purity, functionality, and premium packaging.
Provides a structured competitive benchmark to identify positioning gaps, whitespace opportunities, and potential strategies for strengthening market presence
Identify emerging product categories and innovation opportunities
Evaluated emerging trends including still water, sparkling water, functional water and other premium water category. Assessed innovation around ingredients, packaging, sourcing, and consumer experience.
Supports identification of high-potential product opportunities and innovation pathways aligned with evolving UAE preferences for health, wellness, convenience, sustainability, and premium experiences.
Frequently Asked Questions About This Report
The upto 500 ml segment led with a 38.2% revenue share in 2025, while the 501–750 ml segment is the fastest-growing.
Off-premise channels accounted for the largest revenue share in 2025, while on-premise channels are expected to be the fastest-growing segment.
The UAE premium bottled water market size was valued at USD 1.2 billion in 2025 and is estimated at USD 1.3 billion for 2026.
The UAE premium bottled water market is expected to grow at a CAGR of 5.5% from 2026 to 2033, reaching USD 1.9 billion by 2033.
Premium consumption is further reinforced by luxury tourism, upscale hospitality, high purchasing power, and rising wellness consciousness.
Still water dominated the UAE premium bottled water market, accounting for 83.6% revenue share in 2025, while the functional water is expected to register the fastest growth during the forecast period.
Premium priced bottled water accounted for the largest revenue share in 2025, while ultra-premium priced bottled water are expected to be the fastest-growing segment.
PET bottles accounted for the largest revenue share in 2025, while cans are expected to be the fastest-growing segment.
The multi pack segment led with a 50.4% revenue share in 2025, and is the fastest-growing pack type.
Key players include Agthia Group PJSC; Masafi Co. LLC; Mai Dubai LLC; National Food Products Company (NFPC); Danone S.A.; Nestlé S.A.; Coca-Cola Al Ahlia Beverages Company LLC; Ma Hawa; BE WTR; Marina Mineral Water Co. LLC
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


