
- Home
- »
- Next Generation Technologies
- »
-
Unmanned Surface Vehicle Market Size, Share Report, 2033GVR Report cover

Unmanned Surface Vehicle Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Autonomous, Semi-autonomous), By Application (Defense, Commercial), By Size, By Region, And Segment Forecasts,
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.2BMarket Forecast, 2033
$5.0BCAGR, 2026–2033
12.9%Unmanned Surface Vehicle Market Summary
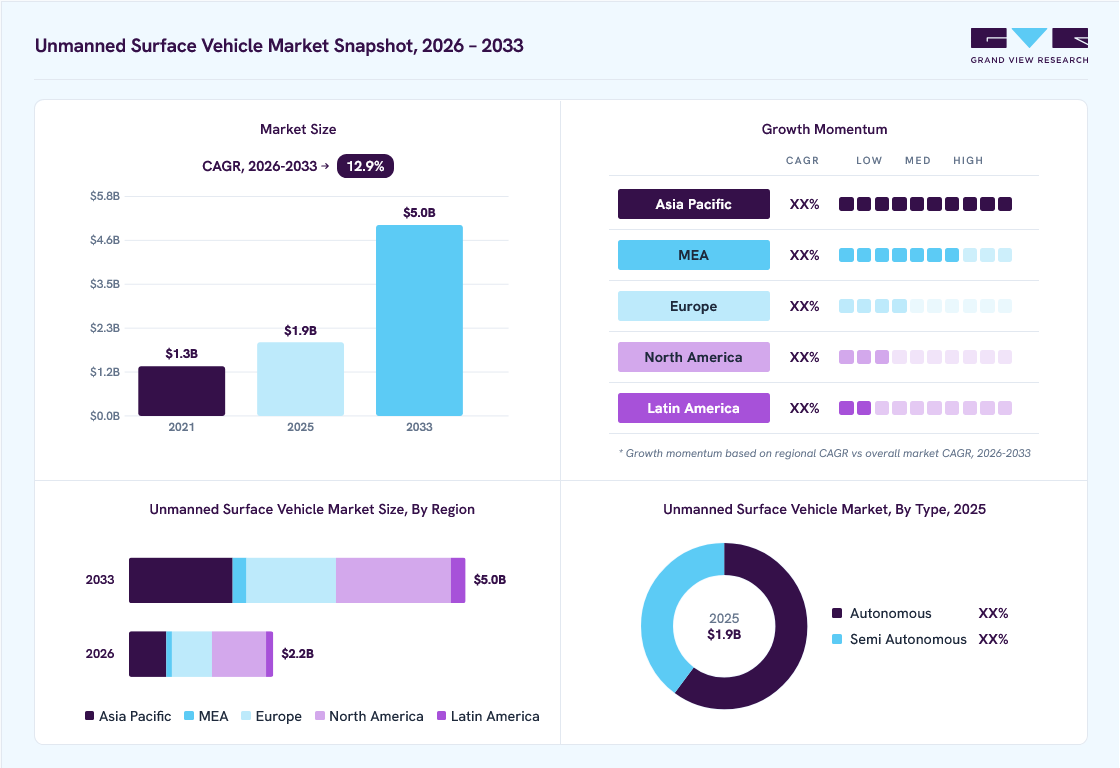
The global unmanned surface vehicle market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 5.0 billion by 2033, at a CAGR of 12.9% from 2026 to 2033. North America dominated the global market with the largest revenue share of 37.9% in 2025. The unmanned surface vehicle market is driven by the increasing adoption of autonomous maritime technologies, advanced sensors, satellite communications, and autonomous navigation systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The autonomous segment dominated the market with a share of 60.1% in 2025.
- By size: The medium segment accounted for the largest market share of 44.0% in 2025.
- By application: The defense segment held the largest market share of 68.9% in 2025.
Regional Highlights
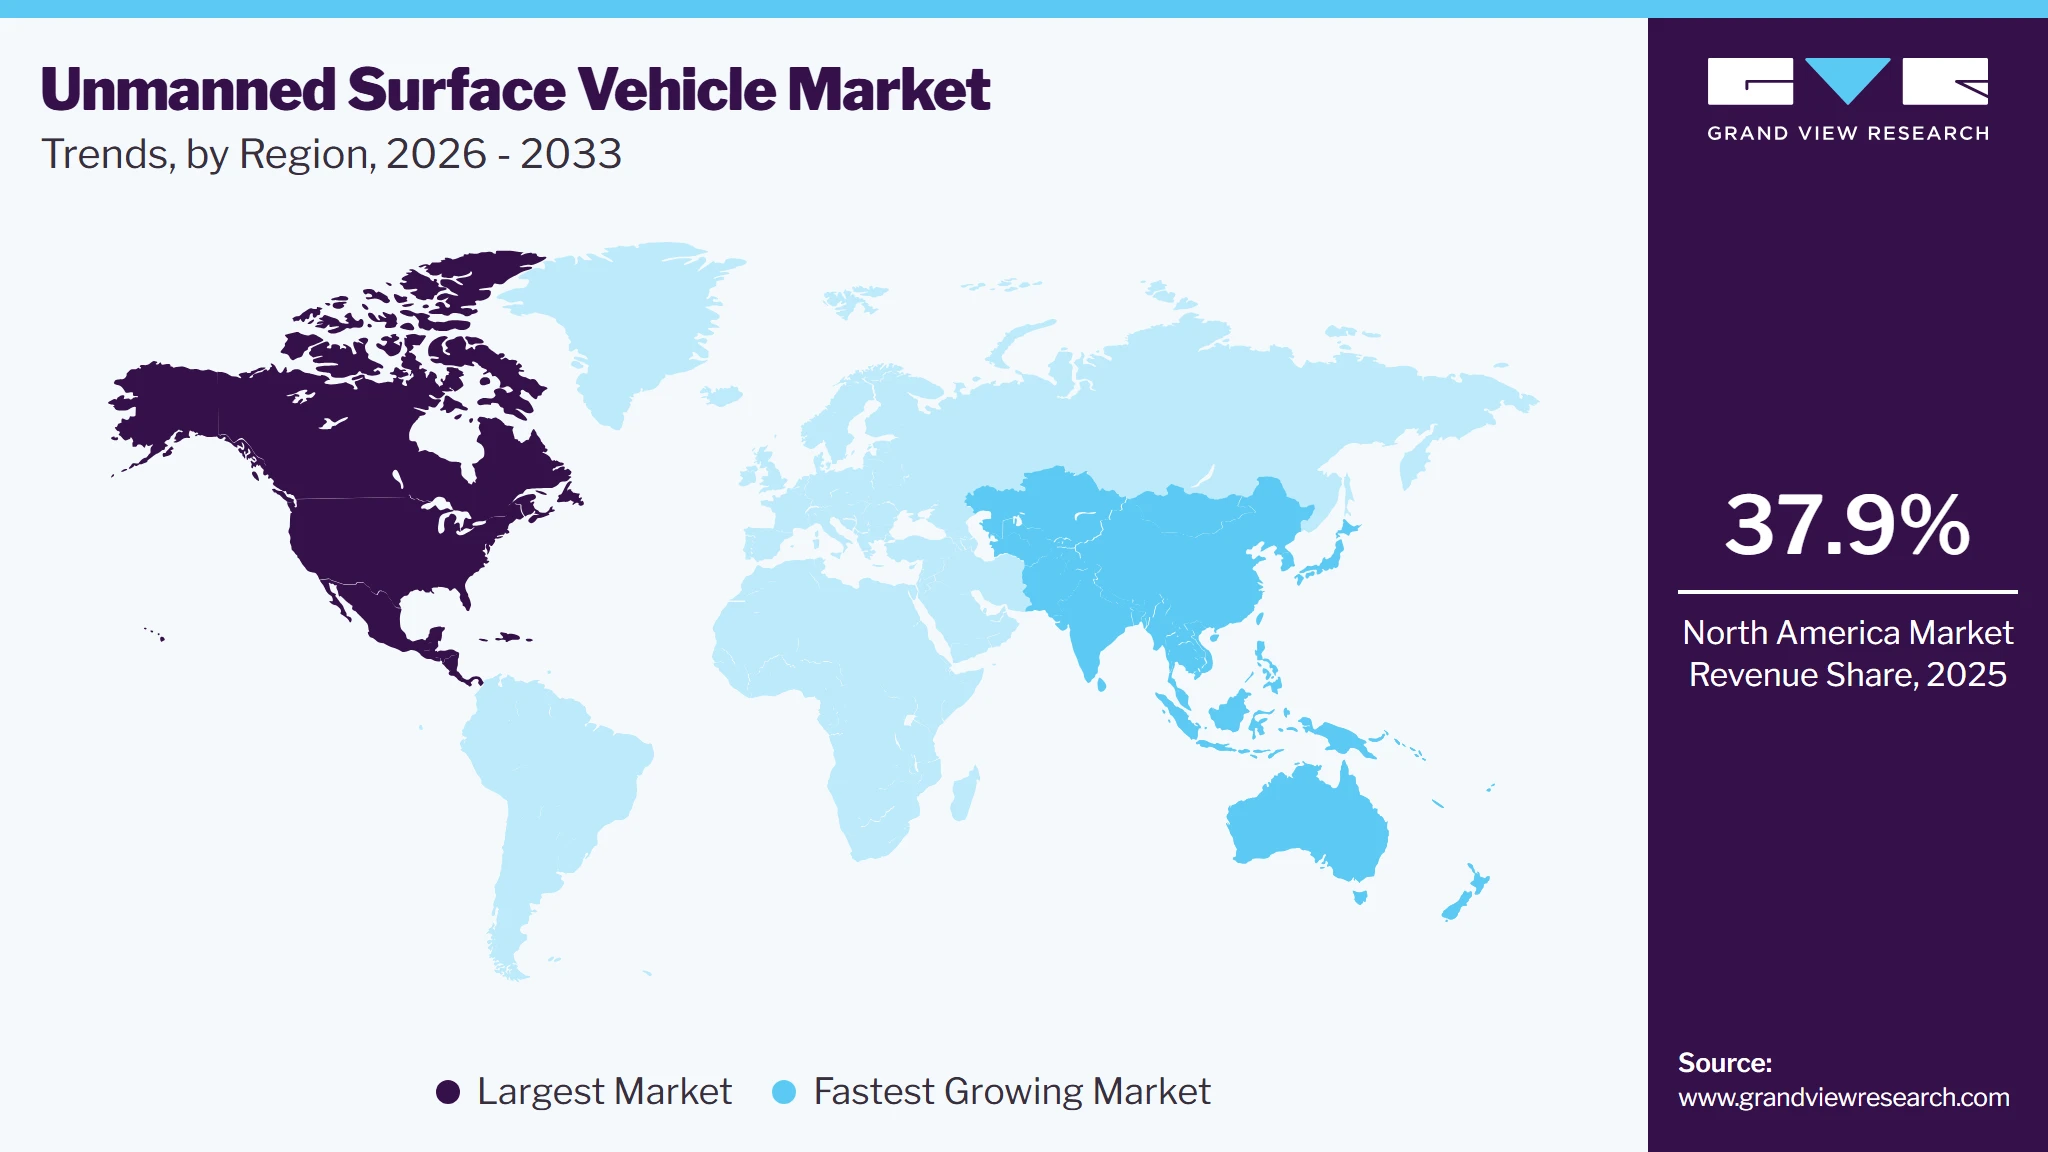
- Largest regional market: North America (37.9% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 5.0 Billion
- CAGR (2026-2033): 12.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding deployment of unmanned surface vehicles for naval surveillance, mine countermeasures, offshore oil and gas inspection, environmental monitoring, and maritime security is significantly accelerating market growth. The growing investments in autonomous maritime systems, smart ports, oceanographic research, and maritime border protection, along with advancements in hybrid and electric propulsion technologies, are improving vessel endurance, reducing operational costs, and creating substantial growth opportunities in the unmanned surface vehicle market.
The market is witnessing significant growth driven by the increasing adoption of defense and security applications. Navies and maritime security agencies are increasingly deploying unmanned surface vehicles (USV) for surveillance, reconnaissance, and countermeasures. The ability of USVs to operate in hazardous environments without risking human lives makes them an invaluable asset for modern naval operations, driving their demand.
 To learn more about this report, Download Free Sample Report
Technological advancements in autonomous navigation and control systems are propelling the USV market. Innovations in AI and machine learning have enhanced USVs' capabilities, enabling them to perform complex missions with minimal human intervention. These advancements are improving operational efficiency and reducing the cost of operations, making USVs more attractive to various end-users.
The use of USVs is expanding beyond defense to include commercial and scientific research applications. In the commercial sector, USVs are increasingly used for offshore oil and gas exploration, environmental monitoring, and marine data collection. Scientific researchers are leveraging USVs to study oceanography and marine ecosystems, benefiting from the vehicles' ability to cover vast areas and gather data in real-time.
Moreover, the need for enhanced maritime infrastructure and port security is driving the growth of the USV market. Ports and harbors are investing in USVs for tasks such as underwater inspection, pollution monitoring, and security patrols. USVs' ability to operate continuously and provide detailed real-time data makes them an essential tool for maintaining and securing maritime infrastructure.
USVs are increasingly being equipped with advanced sensor systems, including sonar, radar, and cameras, to enhance their functionality. These sensors enable USVs to perform a wide range of tasks, from underwater mapping to surface surveillance. The integration of these advanced sensors is driving the demand for USVs in various sectors, as they provide critical data for decision-making processes.
Market Dynamics
The unmanned surface vehicle market is experiencing strong growth due to increasing demand for autonomous maritime operations, autonomous navigation technologies, and marine sensing systems. Rising investments in naval modernization programs, offshore energy infrastructure, maritime border security, and oceanographic research are encouraging governments to deploy advanced unmanned surface vehicles. The expanding use of USVs for intelligence, surveillance, and reconnaissance, mine countermeasures operations, environmental monitoring, offshore asset inspection, and search-and-rescue missions is driving market adoption. Continuous innovations in satellite communications, real-time data analytics, and integrated command-and-control platforms are enhancing mission endurance, improving operational efficiency, and creating significant opportunities to expand the unmanned surface vehicle market.
Increasing geopolitical tensions, territorial disputes, piracy incidents, and illegal maritime activities are prompting defense agencies and coast guards to strengthen surveillance capabilities through autonomous platforms. Unmanned surface vehicles provide persistent intelligence, surveillance, reconnaissance, and patrol operations while minimizing risks to personnel. Their ability to operate continuously in challenging sea conditions makes them an asset for monitoring coastal waters, exclusive economic zones, and critical maritime infrastructure with greater operational efficiency.
Modern unmanned surface vehicles equipped with artificial intelligence, advanced radar, electro-optical sensors, sonar, and satellite communication systems enable real-time situational awareness and rapid threat detection. Governments are investing heavily in autonomous maritime fleets to enhance border protection, mine countermeasure missions, anti-submarine warfare support, and naval reconnaissance. These investments are accelerating technological innovation, expanding procurement programs, and increasing the adoption of unmanned surface vehicles across defense organizations worldwide.
The deployment of unmanned surface vehicles is constrained by evolving maritime regulations governing autonomous vessel operations, navigation safety, and liability. International maritime laws were primarily developed for crewed vessels, creating uncertainty regarding operational approval, collision responsibility, and compliance standards for autonomous systems. These regulatory challenges often delay commercial implementation, cross-border deployments, and certification processes for advanced unmanned maritime platforms.
The varying national regulations and the absence of globally harmonized standards complicate the integration of autonomous vessels into existing maritime traffic systems. Operators must satisfy stringent cybersecurity, communication reliability, and operational safety requirements before receiving authorization for routine deployments. The lengthy approval process increases development costs and slows fleet expansion, particularly for commercial operators seeking to deploy unmanned vessels across multiple international maritime jurisdictions.
The rapid expansion of offshore renewable energy installations, including wind farms and floating solar infrastructure, is creating substantial demand for autonomous maritime support operations. Unmanned surface vehicles provide cost-effective inspection, seabed mapping, environmental monitoring, cable route surveys, and maintenance support without exposing personnel to hazardous offshore conditions. Their ability to conduct frequent autonomous missions significantly improves operational efficiency while reducing vessel operating expenses.
Advancements in autonomous navigation, hybrid propulsion, high-resolution imaging, and remote communication technologies are enabling unmanned surface vehicles to perform longer-duration missions with greater accuracy. Energy developers and marine service providers are increasingly adopting these platforms for asset inspection, environmental compliance monitoring, and predictive maintenance activities. The continued expansion of offshore infrastructure is expected to create sustained demand for versatile autonomous vessels capable of supporting complex marine operations.
Market Concentration & Characteristics
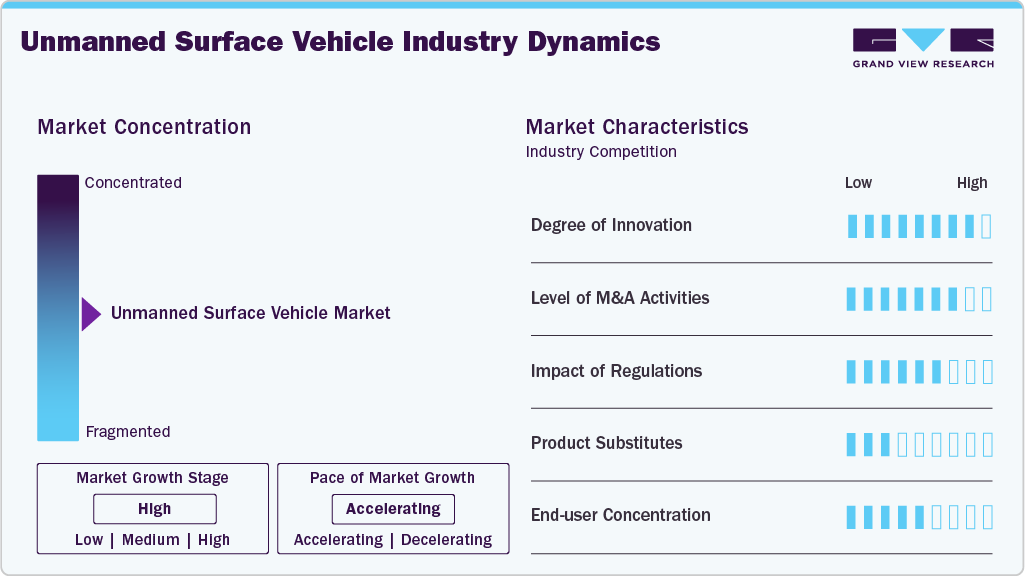
The unmanned surface vehicle market is moderately concentrated, with leading defense contractors, autonomous marine technology developers, shipbuilders, marine robotics companies, and maritime systems integrators competing across military, commercial, and scientific applications. The market is witnessing steady expansion driven by increasing investments in naval modernization, maritime surveillance, offshore energy operations, and autonomous marine technologies. Companies are focusing on artificial intelligence-enabled autonomous navigation, advanced sensor integration, hybrid and electric propulsion systems, and strategic partnerships to strengthen their product portfolios and expand their global presence. Vendors are also investing in next-generation communication systems, autonomous mission management software, multi-mission vessel platforms, and enhanced collision avoidance technologies to improve operational efficiency, mission endurance, and autonomous decision-making across diverse maritime environments.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high level of technological innovation, supported by continuous advancements in autonomous navigation algorithms, marine robotics, satellite communications, machine learning, and integrated sensor technologies. Merger and acquisition activity remains moderate, with established defense companies and maritime technology providers acquiring specialized autonomous systems developers and sensor technology companies to enhance their autonomous capabilities. The threat of substitutes remains low because conventional crewed vessels cannot provide the same level of operational endurance, reduced personnel risk, autonomous mission execution, and cost efficiency offered by unmanned surface vehicles. Regulatory impact remains high due to evolving standards for autonomous maritime navigation, maritime safety regulations, defense procurement policies, cybersecurity requirements, and international operational guidelines. Increasing investments in autonomous naval fleets, offshore infrastructure monitoring, maritime border security, environmental observation, and intelligent port operations are expected to further drive market growth.
Analyst Perspective
The unmanned surface vehicle market is experiencing strong momentum, driven by increasing investment in autonomous maritime technologies, naval modernization programs, and growing demand for cost-effective maritime surveillance and offshore operations. Continuous advancements in artificial intelligence, autonomous navigation systems, satellite communication, advanced sensors, and hybrid propulsion technologies are improving mission efficiency, operational endurance, and situational awareness across defense and commercial applications. Governments and private organizations increasingly prioritize autonomous maritime security, offshore infrastructure inspection, hydrographic surveying, environmental monitoring, and oceanographic research. Market participants are well-positioned to benefit from expanding deployment opportunities, thereby supporting sustained innovation and long-term revenue generation across the global unmanned surface vehicle ecosystem.
Type Insights
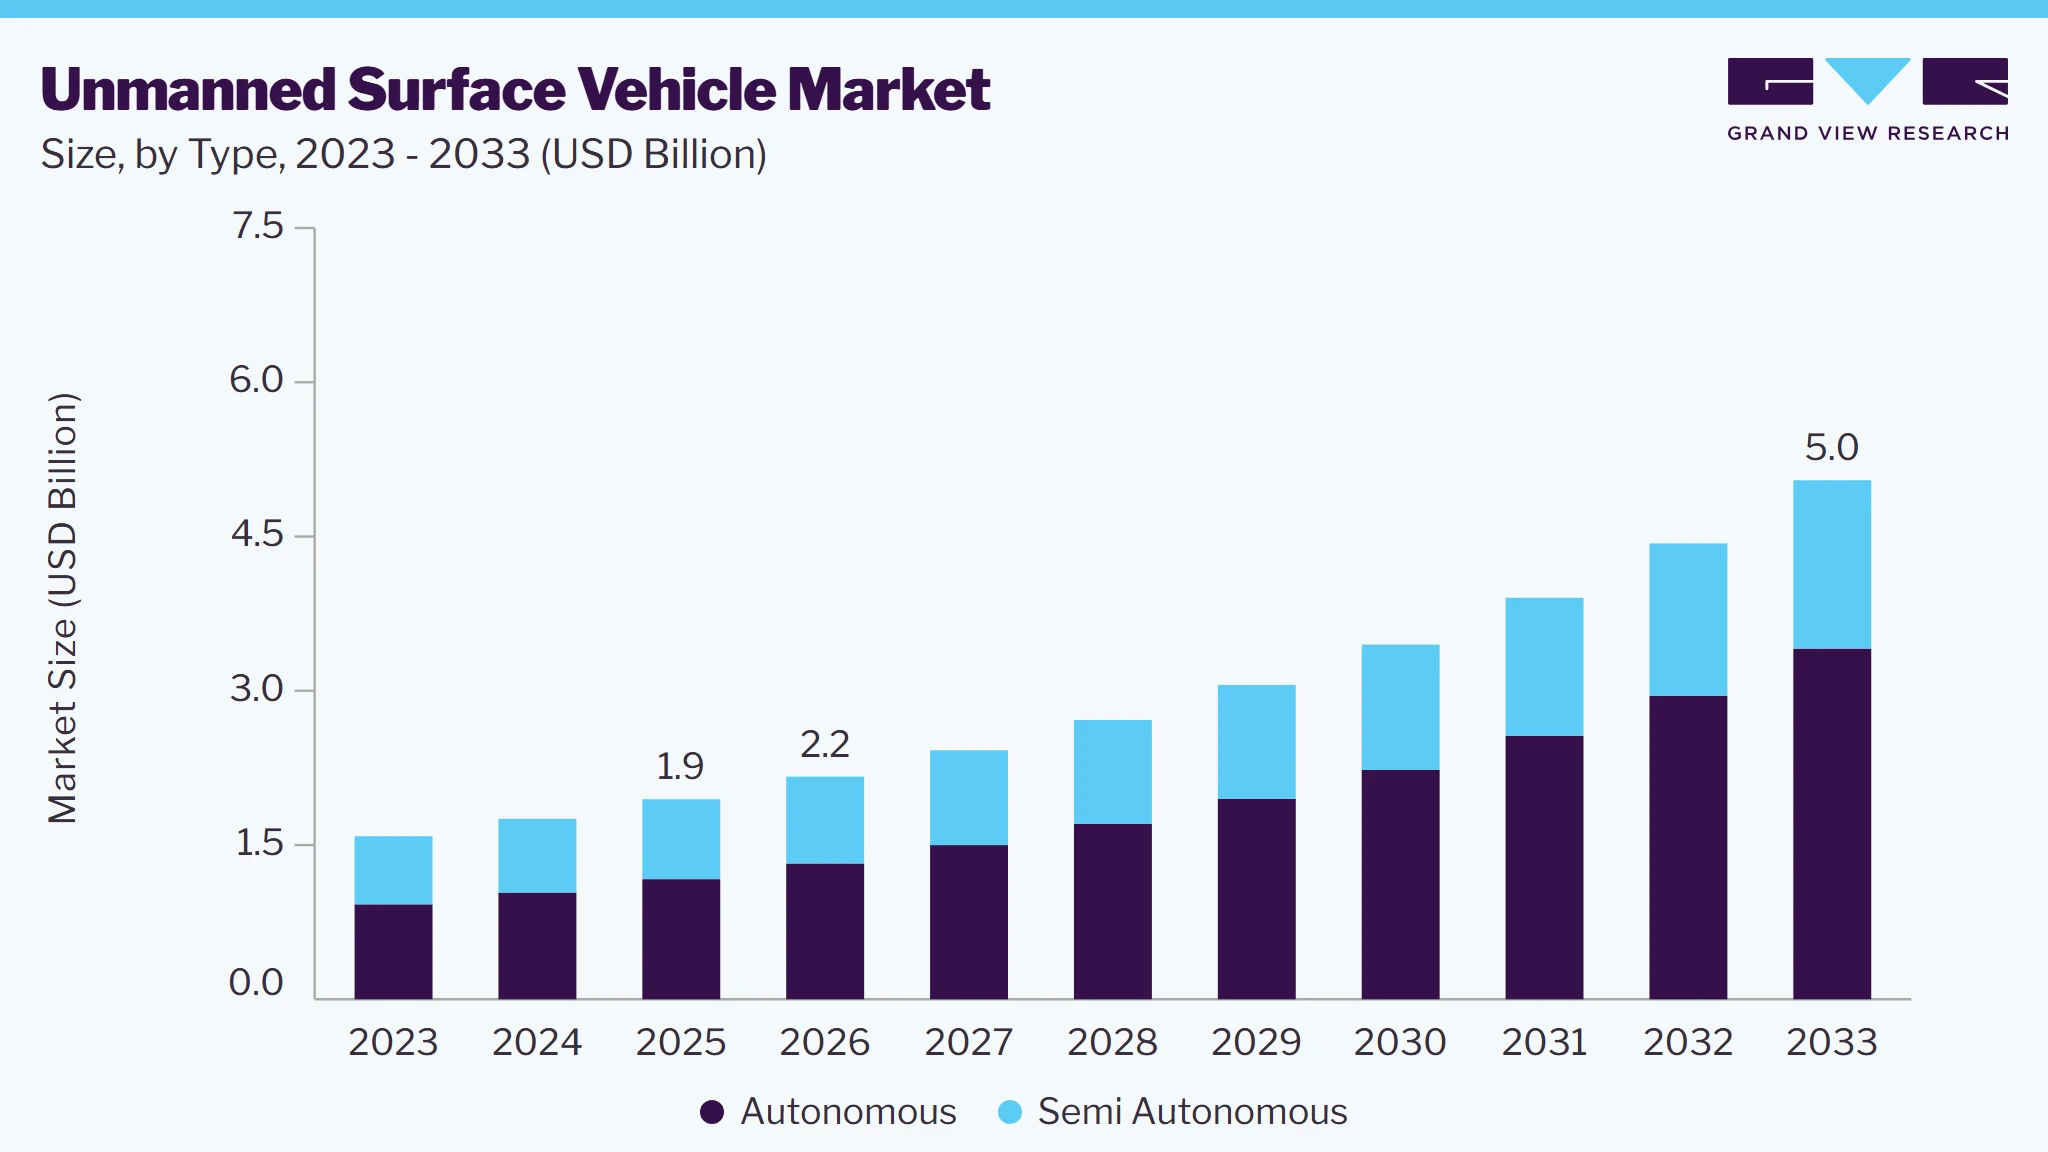
Based on type, the autonomous segment led the market with the largest revenue share of 60.1% in 2025 and is expected to grow at a considerable CAGR over the forecast period. This segment benefits from increased reliability and operational flexibility, combining autonomous capabilities with the option for manual control, which is particularly appealing in complex or uncertain environments. Semi-autonomous USVs are often preferred for applications requiring real-time human intervention, such as search and rescue missions or intricate survey tasks, driving their dominance in the market.
The autonomous segment is expected to record a significant CAGR of over 14% from 2024 to 2033, due to advancements in artificial intelligence, machine learning, and sensor technology. These improvements are enhancing the capabilities of autonomous USVs, making them more reliable and efficient for various applications, including environmental monitoring and defense operations. The growing demand for fully autonomous systems that can operate independently with minimal human intervention, coupled with reduced operational costs and increased operational efficiency, is driving the market growth.
Size Insights
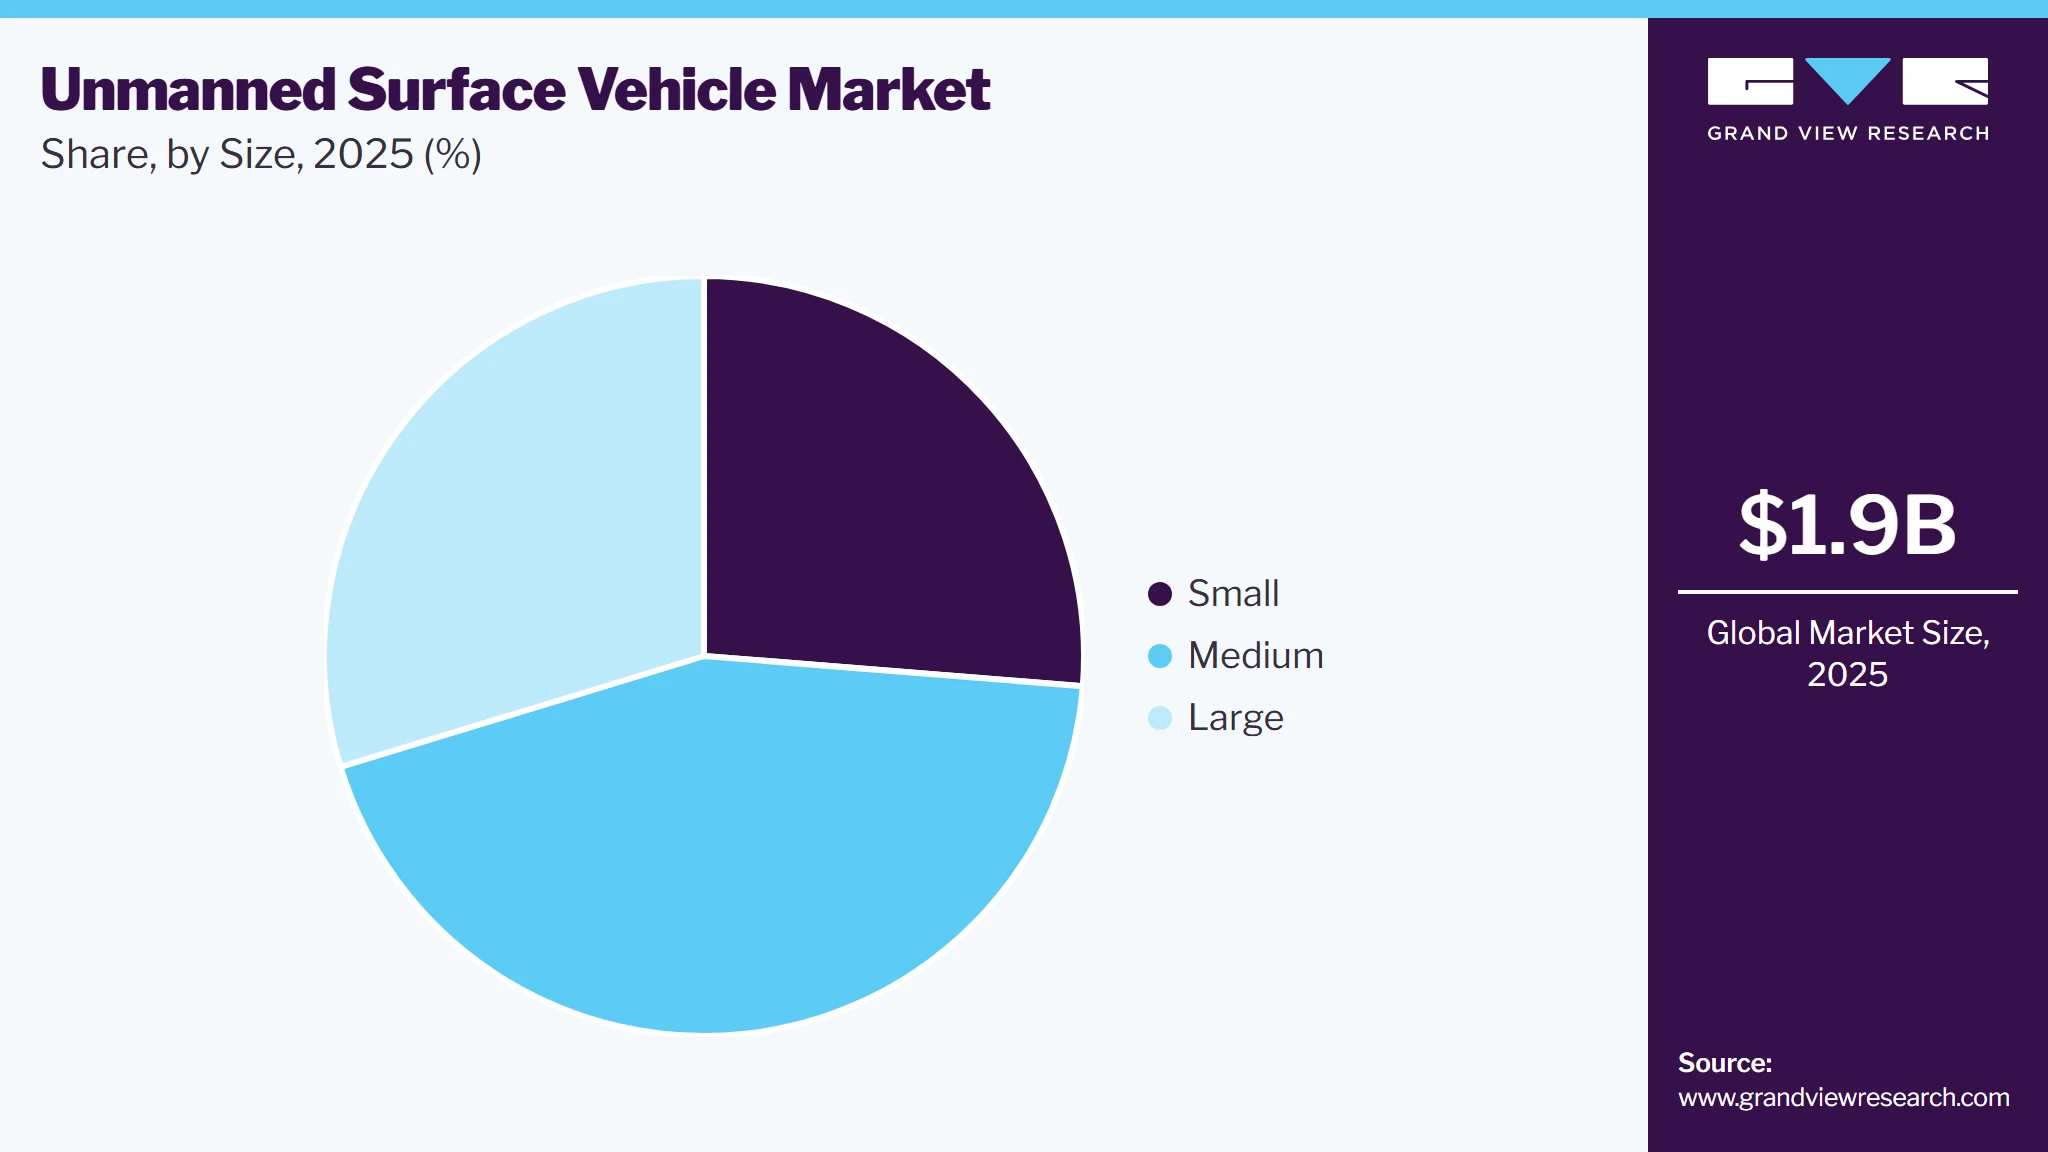
Based on size, the medium segment dominated the market with the largest revenue share of 44.0% in 2025. Medium-sized USVs offer an optimal mix of payload capacity, endurance, and maneuverability, making them ideal for tasks such as environmental monitoring, survey operations, and defense missions. Their adaptability to various operational needs, combined with cost-effective deployment and maintenance, has driven their dominance in the market.
The small size segment is expected to register the fastest CAGR from 2024 to 2033 due to its cost-effectiveness, ease of deployment, and suitability for niche applications. These compact USVs are increasingly used for tasks such as environmental monitoring, shallow-water surveys, and coastal inspections, where their smaller size allows for operation in restricted or challenging environments. Their lower operational costs and flexibility, combined with advances in technology that enhance their capabilities, are driving their rapid adoption and growth in the market.
Application Insights
Based on application, the defense segment accounted for the largest market share of 68.9% in 2025, owing to the increasing demand for advanced maritime security and surveillance solutions. USVs are used for a range of defense applications, including mine countermeasures, anti-submarine warfare, and border patrol, offering high operational efficiency and reduced risk to human personnel. Their ability to perform critical tasks autonomously or with minimal human intervention, along with advancements in technology, has made them a preferred choice for military operations, driving significant investment and revenue growth in this sector.
 To learn more about this report, Download Free Sample Report
The commercial segment is anticipated to register the fastest CAGR from 2024 to 2033, owing to increasing adoption in sectors such as environmental monitoring, logistics, and offshore operations. Advances in technology and growing demand for autonomous systems in commercial applications are driving this growth, as businesses seek to leverage USVs for enhanced operational capabilities and data accuracy in various maritime and coastal environments.
Regional Insights
North America dominated the unmanned surface vehicle market with the largest revenue share of 37.9% in 2025 due to the defense sector's increased investment in advanced maritime technologies and the rising need for autonomous surface vehicles for environmental monitoring and commercial applications. The region's strong technological infrastructure and supportive regulatory environment also contributed to this growth.
 To learn more about this report, Download Free Sample Report
U.S. Unmanned Surface Vehicle Market Trends
The unmanned surface vehicle market in the U.S. held the largest share in the North America region in 2025, driven by substantial defense spending on autonomous maritime systems and the integration of advanced technologies for coastal surveillance, naval operations, and environmental monitoring. In addition, the presence of major USV manufacturers and research institutions fosters innovation and market expansion.
Asia Pacific Unmanned Surface Vehicle Market Trends
The Unmanned Surface Vehicle (USV) market in Asia Pacific accounted for a significant revenue share of over 20% in 2023 due to increasing defense budgets, particularly in countries like China and India. The region's focus on enhancing maritime security, coupled with the rising adoption of autonomous technologies for commercial applications, is driving market expansion.
The India Unmanned Surface Vehicle (USV) market is anticipated to register the fastest CAGR from 2024 to 2033 due to increased defense spending and a strategic focus on maritime security. The government's investment in autonomous technologies for coastal surveillance and naval operations contributes to market growth.
The Unmanned Surface Vehicle (USV) market in China is projected to grow at a CAGR from 2024 to 2033, due to substantial investments in military modernization and the development of autonomous maritime systems. The country's focus on enhancing its naval capabilities and securing its extensive maritime borders supports the demand for advanced USVs.
The Japan Unmanned Surface Vehicle (USV) market is projected to grow at a CAGR from 2024 to 2033, due to its technological advancements in robotics and autonomous systems. The country's emphasis on maritime research, environmental monitoring, and commercial shipping applications drives the demand for USVs.
Europe Unmanned Surface Vehicle Market Trends
The Unmanned Surface Vehicle (USV) market in the Europe region is anticipated to register a CAGR of around 10% from 2024 to 2033 due to increased funding for maritime research and development projects and a strong focus on environmental sustainability and maritime security. European countries are also investing in autonomous technologies to enhance their naval capabilities and support commercial maritime activities.
The UK Unmanned Surface Vehicle (USV) market is projected to grow at a CAGR from 2024 to 2033, due to increased government funding for autonomous systems in defense and commercial sectors. The UK's strategic focus on enhancing its naval capabilities and improving maritime security through advanced technologies supports this growth.
The Unmanned Surface Vehicle (USV) market in Germany is anticipated to record a CAGR from 2024 to 2033, owing to its strong engineering and manufacturing capabilities, as well as significant investments in maritime research and innovation. The country's emphasis on environmental protection and advanced technological solutions for maritime applications also boosts market growth.
Middle East and Africa (MEA) Unmanned Surface Vehicle Market Trends
The Unmanned Surface Vehicle (USV) market in the Middle East and Africa (MEA) region is anticipated to grow at the fastest CAGR of around 11% from 2024 to 2033 due to rising investments in maritime security and oil & gas exploration. Countries in the region are adopting USVs for border surveillance, environmental monitoring, and commercial applications to enhance their maritime capabilities.
The Saudi Arabia Unmanned Surface Vehicle (USV) market accounted for a considerable revenue share in 2023 due to the increased investment in defense and maritime security. The country's focus on protecting its maritime borders and securing its oil and gas infrastructure drives the demand for advanced USVs.
Key Unmanned Surface Vehicle Company Insights
Some of the key players operating in the market are L3Harris Technologies, Inc. and Kongsberg Gruppen ASA, among others.
-
L3Harris Technologies, Inc. is an aerospace and defense technology company known for delivering innovative solutions in communication, avionics, surveillance, and electronic warfare. Headquartered in Melbourne, Florida, L3Harris operates across various sectors, including defense, civil government, and commercial markets. The company specializes in providing advanced technology and mission-critical solutions that support military and security operations worldwide.
-
Kongsberg Gruppen ASA is a Norwegian technology company renowned for its expertise in delivering advanced systems and solutions across the defense, maritime, and aerospace sectors. Kongsberg's offerings include high-technology products and services such as defense systems, remote weapon stations, digital solutions for the maritime industry, and aerospace systems. The company provides state-of-the-art autonomous and remotely operated systems designed for naval and commercial applications.
Liquid Robotics and Fugro are some of the emerging market participants in the Unmanned Surface Vehicle (USV) industry.
-
Liquid Robotics is an American company that specializes in the design and manufacture of autonomous ocean robots, particularly its flagship product, the Wave Glider. The company focuses on providing persistent ocean data collection and observation through unmanned surface vehicles (USVs). In the USV market, Liquid Robotics is a significant player, especially in areas like environmental monitoring, defense, and offshore energy, offering innovative solutions that provide real-time data collection and surveillance across vast oceanic regions.
-
Fugro is a Dutch multinational company that specializes in geotechnical, survey, subsea, and geosciences services, primarily for the oil and gas, infrastructure, and renewable energy sectors. Fugro is known for providing high-quality data collection and analysis to better understand the earth's surface and subsurface. In the Unmanned Surface Vehicle (USV) industry, Fugro plays a crucial role, utilizing USVs for a wide range of applications such as hydrographic surveying, environmental monitoring, and offshore construction support.
Key Unmanned Surface Vehicle Companies:
The following key companies have been profiled for this study on the unmanned surface vehicle market.
-
ECA Group
-
Elbit Systems Ltd.
-
Fugro
-
Kongsberg Gruppen ASA
-
L3Harris Technologies, Inc.
-
Liquid Robotics
-
Saab AB
-
Teledyne Technologies Incorporated
-
Textron Systems Corporation
-
Thales Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Elbit Systems Ltd., Kongsberg Gruppen ASA, L3Harris Technologies, Inc.)
Expand autonomous maritime platforms through strategic defense partnerships and advanced navigation technology integration.
Invest in AI-enabled unmanned vessels supporting multi-mission naval and commercial maritime operations globally.
Strong defense relationships and proven autonomous maritime technologies strengthen long-term competitive market positioning.
Reliable unmanned surface vehicles offer advanced sensors, extended endurance, and superior operational performance.
Reliance on lengthy defense procurement cycles delays commercialization and broader market expansion.
Large organizational structures reduce flexibility in adopting rapidly evolving autonomous maritime innovations.
Emerging Players (Liquid Robotics, Textron Systems Corporation, Fugro)
Emerging players focus on developing cost-effective autonomous vessels with AI-driven navigation and modular mission payloads.
Expand market presence through technology partnerships, pilot projects, and commercial maritime application deployments.
Agile product development enables rapid innovation in autonomous navigation and marine robotics technologies.
Specialized unmanned surface vehicles address niche maritime missions with flexible and customizable platform designs.
Limited financial resources restrict large-scale manufacturing capacity and global commercial market expansion.
A smaller customer base and limited field deployments reduce credibility in major defense procurement programs.
Recent Developments
-
In April 2024, L3Harris Technologies, Inc. teamed up with Performance Marine to showcase Unmanned Surface Vehicle (USV) capabilities at the eighth Doha International Maritime Defense Exhibition and Conference (DIMDEX). Known for featuring the latest in maritime and defense technologies, DIMDEX served as the perfect venue for unveiling 'Suhail,' the first autonomous USV constructed in Doha. This partnership underscored their cutting-edge innovations and emphasized the growing importance of autonomous systems in maritime defense.
-
In May 2024, Kongsberg Maritime opened a new facility in Kochi, India, as part of its strategic plan to strengthen customer support and lay the groundwork for future assembly of its waterjet products. The facility is poised for further expansion and investment to enable the assembly and overhaul of Kongsberg Maritime’s Kamewa waterjets.
-
In June 2023, the Thales Unmanned Surface Vessel (USV) Apollo successfully concluded a demanding series of autonomous mine countermeasure (MCM) trials, setting the stage for autonomous mine-hunting operations in the Royal Navy and the broader industry. The Thales-built Royal Navy Motor Boat (RNMB) Apollo completed a series of open water assurance tests.
Unmanned Surface Vehicle Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Market size value in 2026
USD 2.2 billion
Revenue forecast in 2033
USD 5.0 billion
Growth rate
CAGR of 12.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, size, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
ECA Group; Elbit Systems Ltd.; Fugro; Kongsberg Gruppen ASA; L3Harris Technologies, Inc.; Liquid Robotics; Saab AB; Teledyne Technologies Incorporated; Textron Systems Corporation; Thales Group
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Unmanned Surface Vehicle Market Report Segmentation
This report forecasts and estimates revenue growth at the global, regional, and country levels along with analyzing the latest market trends and opportunities in each one of the sub-segments from 2021 to 2033. For this study, Grand View Research has further segmented the global unmanned surface vehicle market report based on type, size, application, and region.
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Autonomous
-
Semi-autonomous
-
-
Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Small
-
Medium
-
Large
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Defense
-
ISR
-
Mine Countermeasures
-
Anti-ship Warfare
-
Communication Gateway
-
Others
-
-
Commercial
-
Weather and Environment Monitoring
-
Hydrographic Survey
-
Infrastructure Monitoring and Inspection
-
Others
-
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The unmanned surface vehicle market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each unmanned surface vehicle segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Autonomous
Revenue is derived from fully autonomous unmanned surface vehicles that execute missions with minimal or no human intervention, autonomous navigation systems, and mission management software. Demand is supported by increasing adoption across naval operations, hydrographic surveys, environmental monitoring, and offshore inspection activities that require continuous autonomous performance.
Semi-autonomous
Revenue originates from unmanned surface vehicles that perform predefined tasks autonomously while remaining under partial human supervision or remote operator control. Adoption is increasing due to their enhanced safety and suitability for surveillance, search-and-rescue, offshore support, and scientific research missions where operator oversight is essential.
Segment - Size
Revenue capture definition
Small
Revenue is generated from compact unmanned surface vehicles designed for short-range missions, inland waterways, harbor surveillance, environmental monitoring, and rapid hydrographic surveys. Market demand is fueled by their portability, lower deployment costs, ease of transportation, and ability to operate efficiently in confined or shallow-water environments.
Medium
Revenue is obtained from medium-sized unmanned surface vehicles developed for extended maritime missions, offshore inspection, coastal security, oceanographic research, and infrastructure monitoring. Adoption is increasing due to their balanced payload capacity, operational endurance, and capability to accommodate multiple navigation, communication, and sensing technologies.
Large
Revenue is contributed by large vehicles engineered for long-endurance naval operations, deep-sea surveillance, anti-submarine warfare support, and offshore logistics. Demand is driven by their high payload capacity, extended operational range, superior sea-keeping capability, and ability to integrate advanced mission systems.
Segment - Application
Revenue capture definition
Defense
Revenue is generated from unmanned surface vehicles deployed for intelligence, surveillance, and reconnaissance, as well as border security missions. This segment is supported by increasing defense modernization programs, naval fleet automation, and investments in autonomous maritime security technologies.
Commercial
Revenue is generated by unmanned surface vehicles used for offshore energy inspection, hydrographic surveying, environmental monitoring, and infrastructure inspection. Demand is supported by growing requirements for cost-efficient autonomous marine operations, improved data collection capabilities, and reduced operational risks in commercial maritime activities.
Estimation Model
Layer Name
Key Question
Description
Maritime Demand Layer
Who are the potential adopters?
Identifies the primary customer base for unmanned surface vehicles, including naval forces, coast guards, offshore energy companies, port authorities, research institutions, environmental agencies, and commercial marine operators requiring autonomous maritime surveillance, inspection, monitoring, and data collection capabilities.
Autonomous Maritime Enablement Layer
Who can deploy Unmanned Surface Vehicles?
Adoption depends on the availability of autonomous navigation systems, satellite communication, GNSS positioning, AI-enabled control systems, marine sensors, cloud connectivity, and supporting maritime infrastructure that enables reliable, safe, and efficient autonomous vessel operations.
Mission Deployment Layer
Where are Unmanned Surface Vehicles actively utilized?
Deployment occurs across defense patrols, coastal surveillance, offshore energy facilities, hydrographic surveying, environmental monitoring, oceanographic research, port security, search-and-rescue missions, fisheries management, and maritime infrastructure inspection, all of which require autonomous surface operations.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through unmanned surface vehicle sales, autonomous navigation software, onboard sensors, propulsion systems, payload integration, maintenance services, operator training, fleet management platforms, software upgrades, and long-term defense and commercial service contracts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Naval Surveillance & Autonomous Mission Capability Assessment
Conducted detailed assessment of autonomous naval surveillance platforms, integrating AI-based navigation, radar, sonar, satellite communication, and mission management systems to evaluate operational effectiveness, maritime domain awareness, and fleet deployment strategies across defense operations.
Improves maritime surveillance, enhances mission efficiency, strengthens border security, and supports autonomous naval operations.
Offshore Infrastructure Inspection & Marine Asset Monitoring Strategy
Evaluated deployment of unmanned surface vehicles for offshore energy infrastructure inspection, subsea asset monitoring, hydrographic surveying, and predictive maintenance by integrating advanced sensors, autonomous navigation, and real-time communication technologies.
Reduces inspection costs, improves asset reliability, enhances operational safety, and supports offshore infrastructure management.
Autonomous Maritime Technology Integration & Fleet Modernization Analysis
Assessed integration of artificial intelligence, autonomous navigation, hybrid propulsion, collision avoidance systems, and secure communication technologies into unmanned surface vehicle fleets to optimize mission performance, endurance, interoperability, and operational readiness across maritime applications.
Enhances autonomous capabilities, improves fleet readiness, increases operational endurance, and supports maritime modernization initiatives.
Frequently Asked Questions About This Report
The global unmanned surface vehicle market is expected to grow at a CAGR of 12.9% from 2026 to 2033, reaching USD 5.0 billion by 2033.
The global unmanned surface vehicle market size was valued at USD 1.9 billion in 2025 and is estimated at USD 2.2 billion in 2026.
North America dominated the global market with the largest revenue share of 37.9% in 2025.
Key factors that are driving the unmanned surface vehicle market growth include the increasing adoption in defense and security applications. Navies and maritime security agencies are increasingly deploying USVs for surveillance, reconnaissance, and countermeasures.
Key players include ECA Group; Elbit Systems Ltd.; Fugro; Kongsberg Gruppen ASA; L3Harris Technologies, Inc.; Liquid Robotics; Saab AB; Teledyne Technologies Incorporated; Textron Systems Corporation; Thales Group
Asia Pacific is the fastest-growing region over the forecast period.
The autonomous segment led the market with the largest revenue share of 60.1% in 2025 and is the fastest-growing segment.
The defense segment dominated the market with a share of 68.9% in 2025.
The medium segment accounted for the largest share, with 44.0% of revenue in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


