
- Home
- »
- Animal Health
- »
-
Veterinary Bone Grafts And Substitutes Market Report, 2033GVR Report cover

Veterinary Bone Grafts And Substitutes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Autografts, Allografts, Xenografts), By Animal Type, By Form, By Application, By Material, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$271.3MMarket Estimate, 2026
$291.2MMarket Forecast, 2033
$533.8MCAGR, 2026–2033
9.0%Veterinary Bone Grafts And Substitutes Market Summary
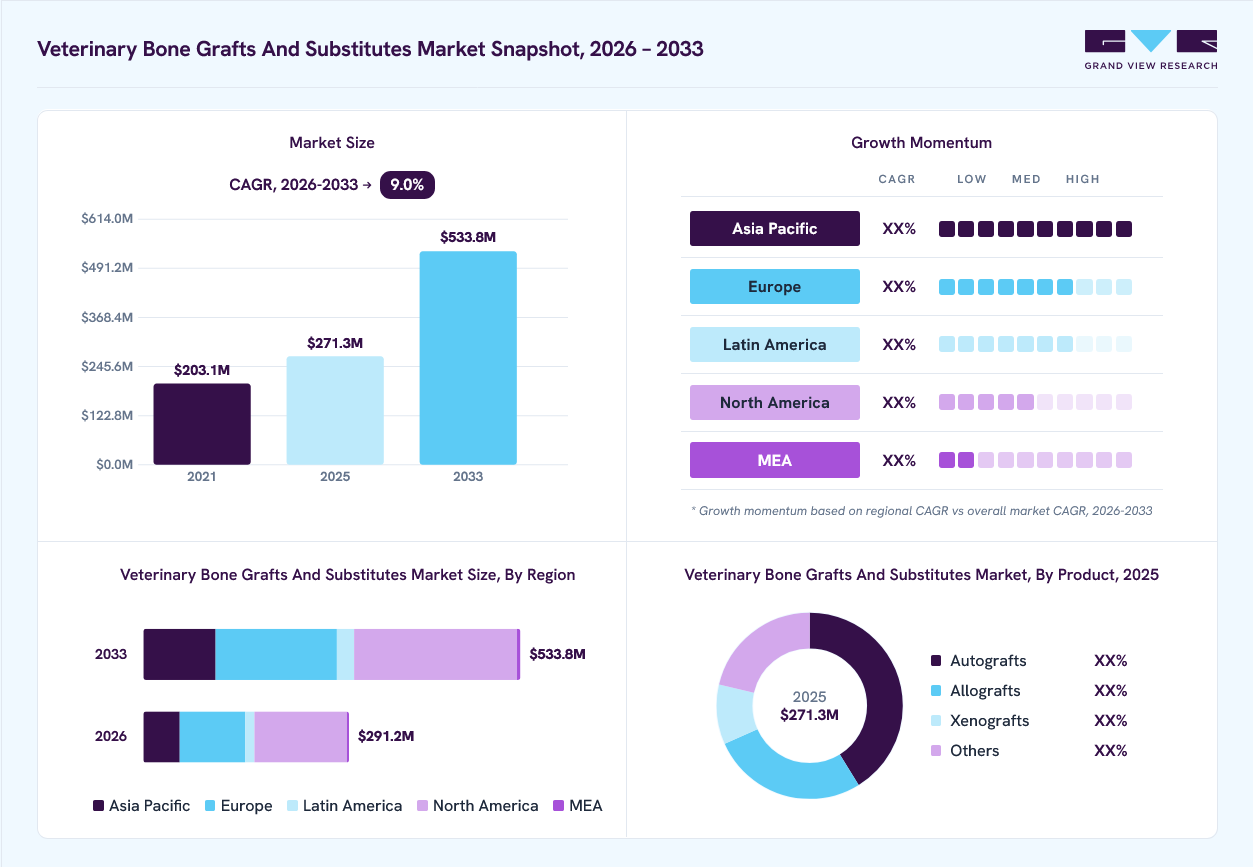
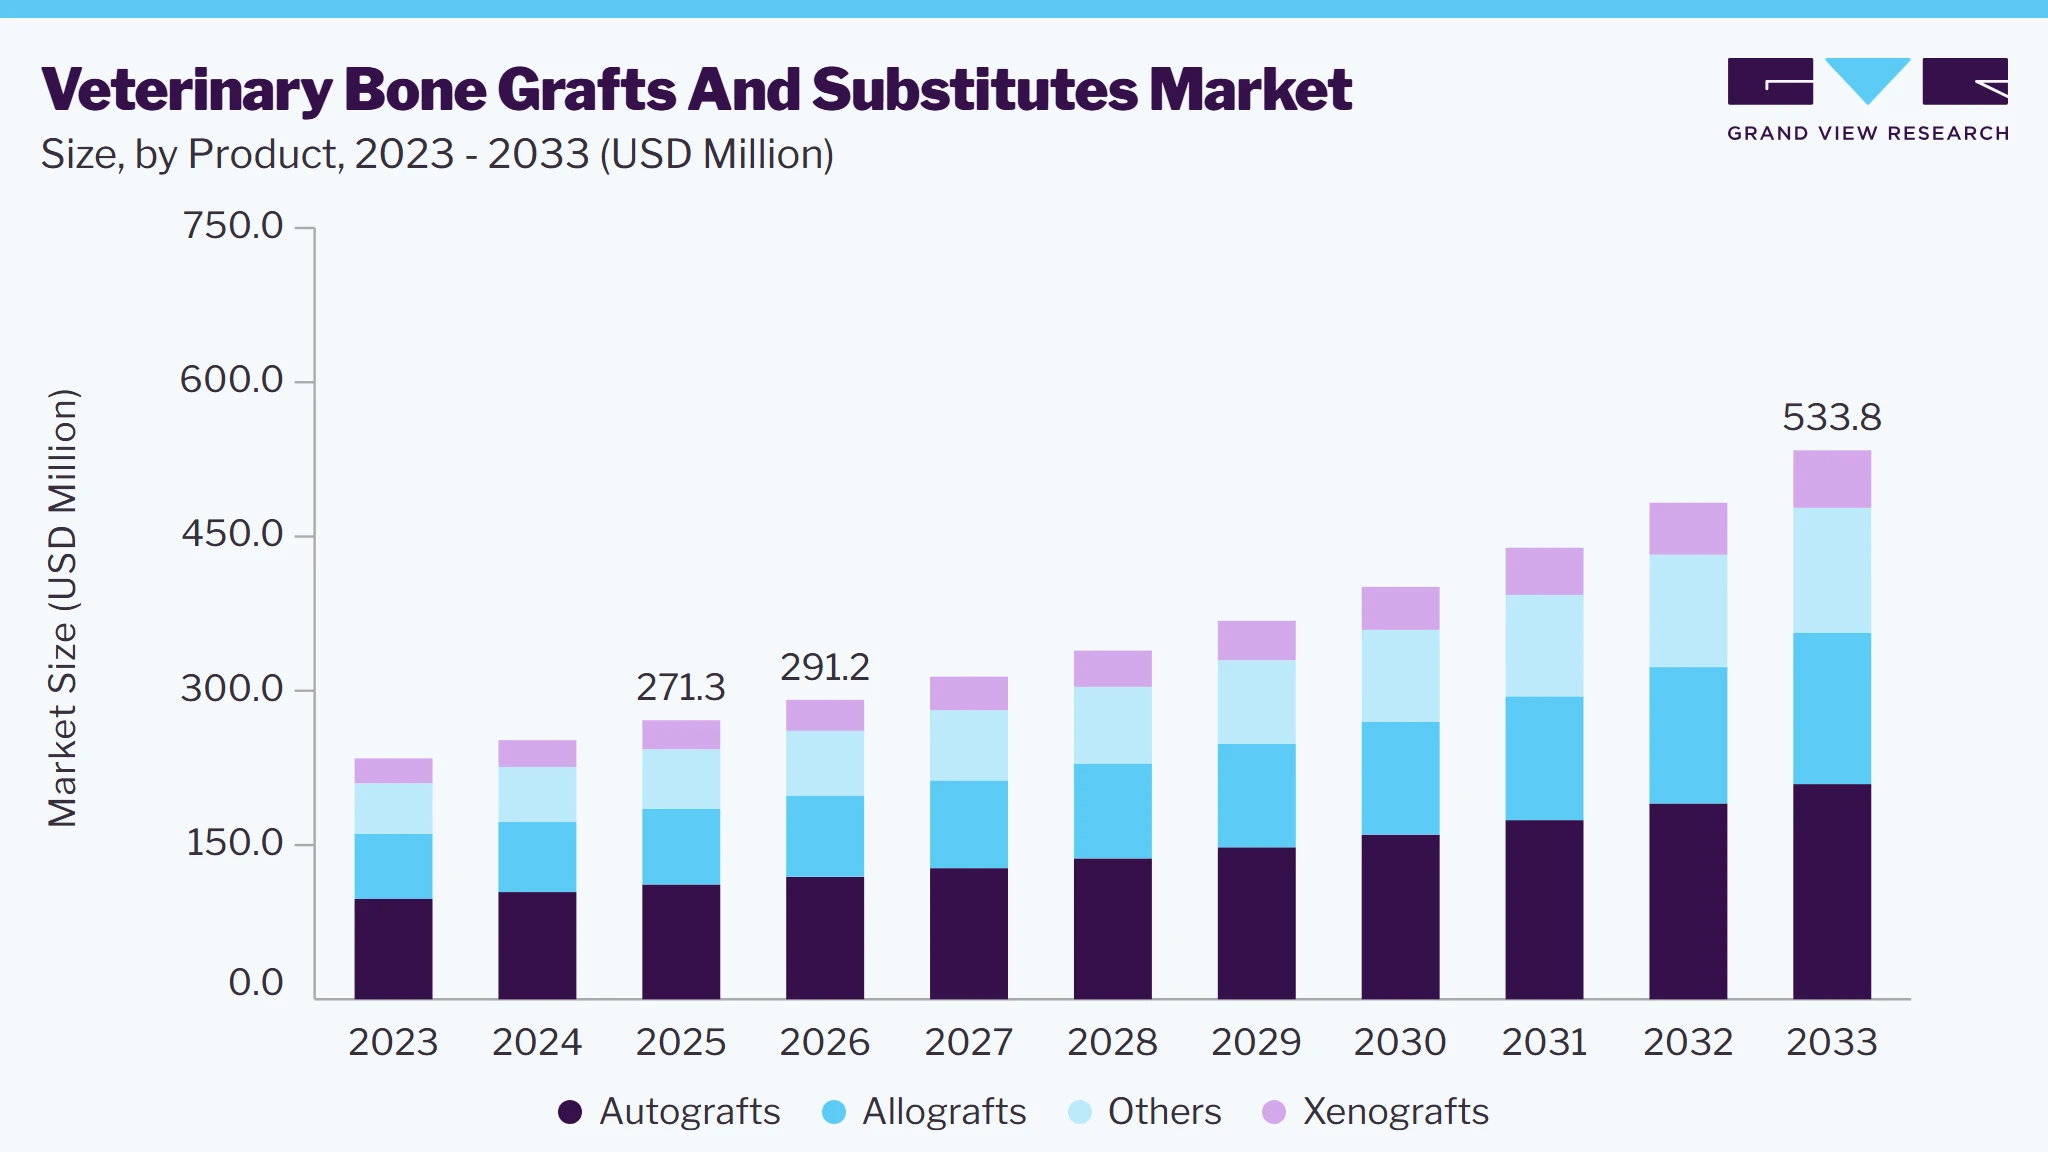
The global veterinary bone grafts and substitutes market size was valued at USD 271.3 million in 2025 and is projected to grow from USD 291.2 million in 2026 to USD 533.8 million by 2033, at a CAGR of 9.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 45.2% in 2025. The increasing demand for advanced orthopedic solutions, rising pet ownership, growing awareness of veterinary surgical options, and increasing product launches are expected to drive market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Autografts segment led the market with the largest revenue share of 41.1% in 2025.
- By application: Orthopedic segment led the market with the largest revenue share of 41.4% in 2025.
- By animal: Dogs segment led the market with the largest revenue share of 56.6% in 2025.
- By form: Injectables segment led the market with the largest revenue share of 34.8% in 2025.
Regional Highlights
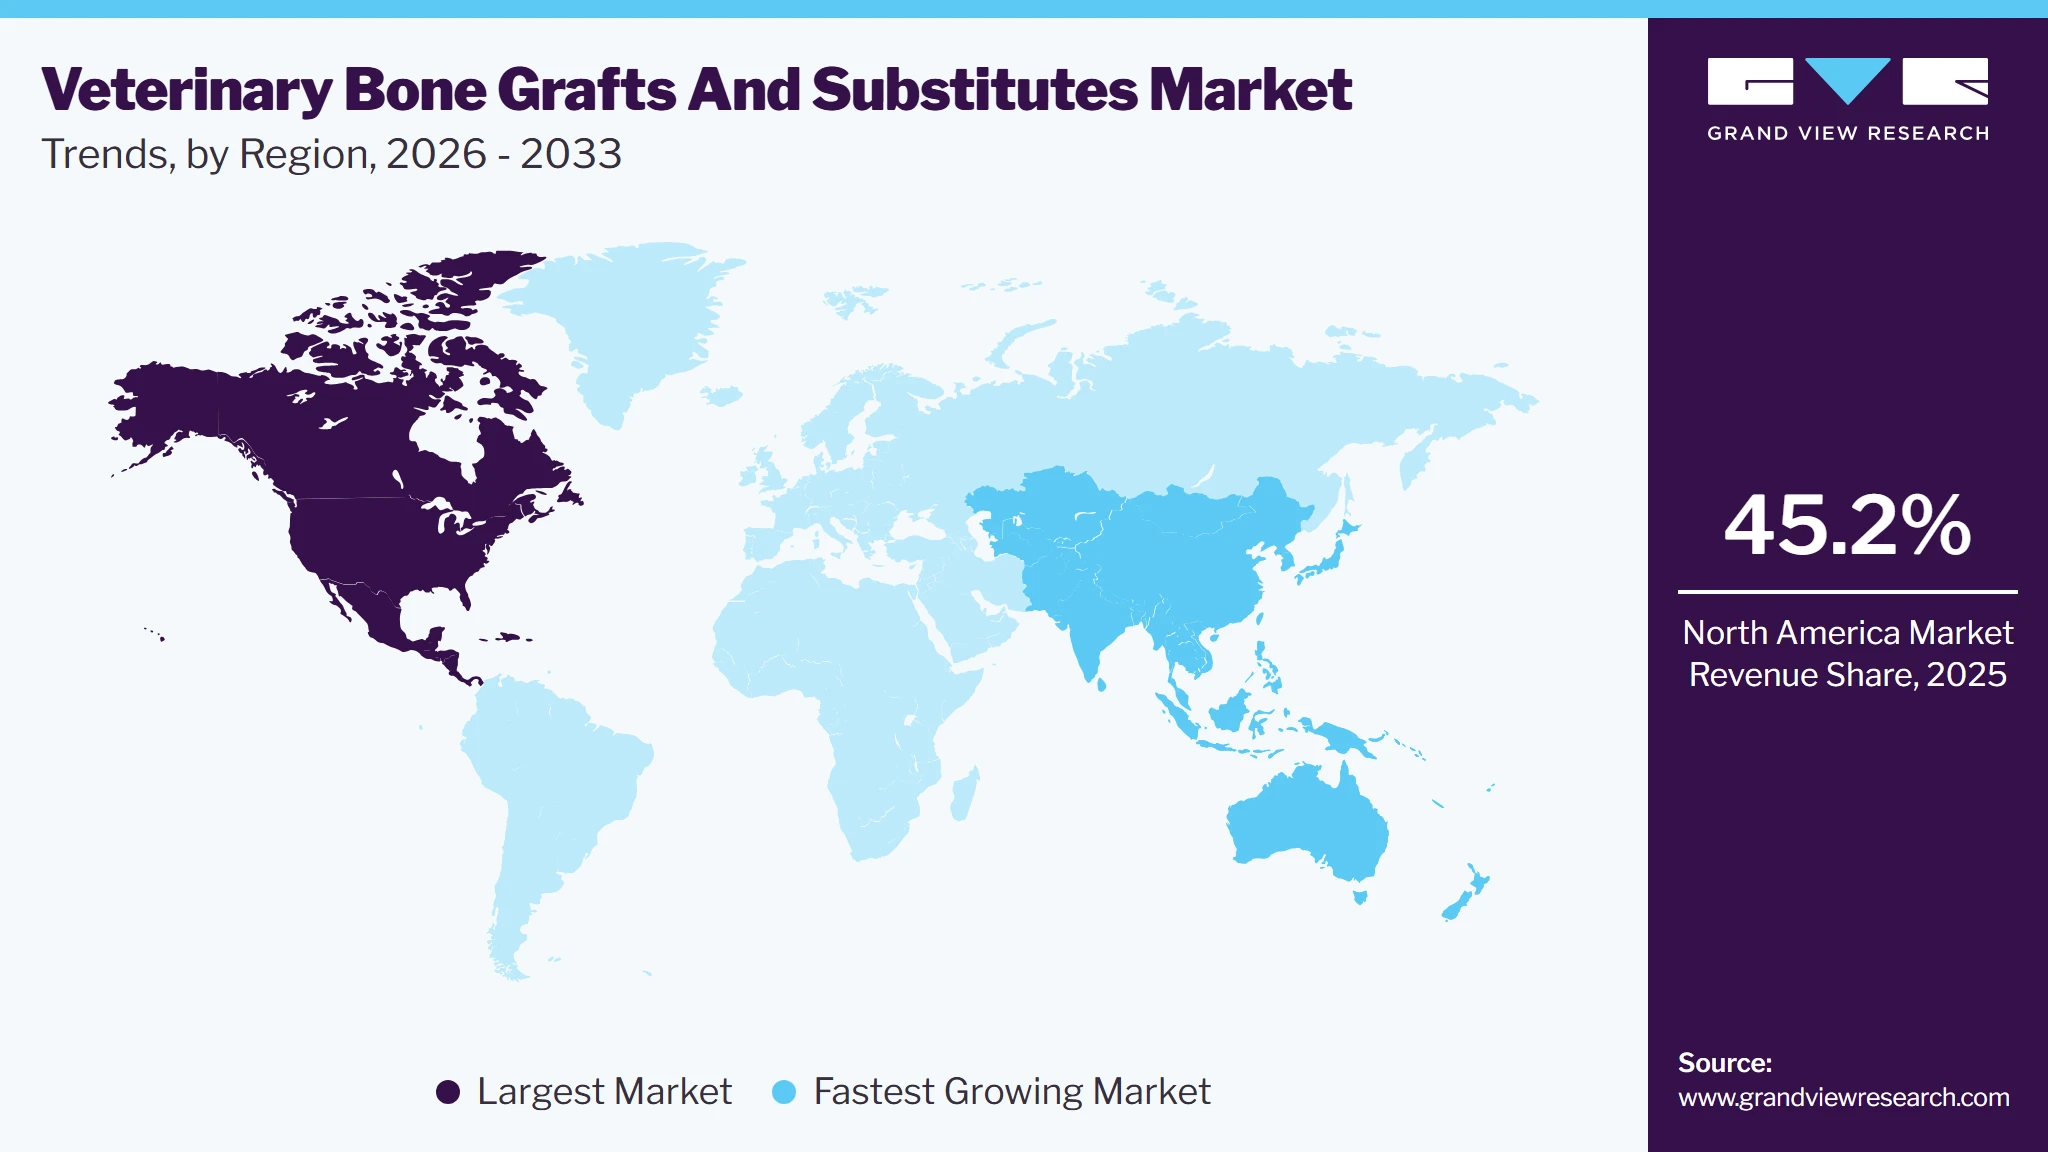
- Largest regional market: North America (45.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 271.3 Million
- Estimated market size in 2026: USD 291.2 Million
- Projected market size by 2033: USD 533.8 Million
- CAGR (2026-2033): 9.0%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary bone grafts and substitutes marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →For instance, in May 2024, Biomendex introduced the patented biodegradable Adaptos bone substitute, designed for orthopedic and dental applications. This innovative product has been successfully utilized in over 1,000 surgeries, primarily on small animals like dogs and cats.
 To learn more about this report, Download Free Sample Report
Furthermore, increasing supportive initiatives and growing awareness about veterinary bone grafts and substitutes drive market growth. Additionally, increased educational programs, such as TheraVet's Osteosarcoma Program and rising outreach efforts at veterinary conferences, boost awareness of innovative treatments like BIOCERA-VET OSTEOSARCOMA RTU. These initiatives are expanding the adoption of advanced bone grafts and substitutes by demonstrating their benefits, including minimally invasive options and improved outcomes for conditions like osteosarcoma. This increase in awareness is leading to a rise in market demand and accelerating the development and distribution of these products. For instance, in June 2023, TheraVet reported a 300% increase in centers participating in its Osteosarcoma Program within six months, highlighting growing interest and adoption of its BIOCERA-VET OSTEOSARCOMA RTU solution. This minimally invasive treatment option is positioned as a viable alternative to traditional limb amputation or invasive surgeries, addressing a significant medical need for canine osteosarcoma. The program's success is further evidenced by a 33% increase in participating centers since its official launch and a threefold rise in web traffic to its dedicated information site.
The advancements in graft technologies and ongoing clinical research are also expected to contribute to market growth. Options like allografts, autografts, and recombinant bone growth factors such as Bone Morphogenetic Protein-2 (rhBMP-2) are crucial in treating mandibular defects. rhBMP-2, a human recombinant protein that promotes new bone formation, has seen increased clinical use since its initial veterinary application in 2004. In addition, the US FDA released draft guidance for dental bone grafting device manufacturers on March 2024, Titled “Animal Studies for Dental Bone Grafting Material Devices - Premarket Notification (510(k)) Submissions,” which outlines the necessary conditions under which preclinical studies are required and offers recommendations to meet regulatory requirements for these Class II devices. Ongoing studies at leading institutions and recent product launches, such as Zoetis's TruScient for the European market, highlight the expanding availability and adoption of innovative bone grafting solutions, further driving market growth.
Market Dynamics
The market is experiencing steady growth, driven by increasing demand for advanced orthopedic solutions, rising companion animal ownership, and greater awareness of minimally invasive and regenerative veterinary treatments. In addition, the growing prevalence of fractures, cranial cruciate ligament injuries, osteoarthritis, dental disorders, and bone tumors has increased the adoption of bone graft materials across veterinary hospitals and specialty clinics. The market is advancing due to continuous product launches featuring synthetic biomaterials, injectable grafts, bioactive ceramics, and tissue-engineered substitutes are expanding treatment options, improving surgical outcomes and recovery times. For instance, in February 2026, Biomendex received FDA 510(k) clearance for its Adaptos Fuse Bone Graft, enabling U.S. commercialization. This technology, previously validated in over 2,700 veterinary orthopedic and dental procedures, highlighted successful translation of veterinary regenerative innovations into broader bone regeneration applications.
In addition, increasing investments in veterinary orthopedic research, regenerative medicine, and advanced surgical infrastructure are supporting market expansion. Furthermore, the growing willingness of pet owners to spend on specialized surgical procedures, coupled with expanding veterinary referral networks and improved access to advanced diagnostic imaging, is accelerating product utilization. Moreover, collaborations between manufacturers, veterinary universities, and research institutes are fostering innovation, enabling the commercialization of next-generation bone regeneration technologies and creating sustained growth opportunities for the global veterinary bone grafts and substitutes market.
The rising demand for advanced orthopedic solutions is a key driver of the market. The increasing incidences of fractures, cranial cruciate ligament injuries, osteoarthritis, spinal disorders, and bone tumors in companion animals that have significantly increased the need for effective bone regeneration products. As pets live longer and remain more active, veterinarians are performing a growing number of complex orthopedic and reconstructive procedures that require bone grafts to accelerate healing and restore skeletal function. For instance, in July 2026, Bristol Vet Specialists successfully implanted a custom titanium-polyurethane "bionic joint" in a dog with osteochondritis dissecans, using CT-based planning and 3D-printed surgical guides, the procedure restored mobility and reduced pain, highlighting advances in personalized veterinary orthopedic implants.
In addition, veterinary specialty hospitals are adopting these advanced solutions to improve surgical outcomes, reduce recovery time, and enhance patient mobility. Furthermore, growing investments in veterinary orthopedic surgery, regenerative medicine, and minimally invasive procedures, coupled with increasing willingness among pet owners to pursue advanced treatments, continue to strengthen demand for innovative bone graft and substitute products worldwide.
The high cost of advanced bone graft procedures remains a significant restraint for the market. Some of the premium synthetic grafts, bioactive ceramics, injectable biomaterials, and customized regenerative implants substantially increase the overall cost of orthopedic and reconstructive surgeries. In addition to product expenses, advanced imaging, specialized surgical equipment, and trained veterinary orthopedic surgeons, elevate treatment costs.
Moreover, pet owners, particularly in regions with limited pet insurance coverage, may hesitate to pursue these procedures due to affordability concerns. However, cost sensitivity is especially evident for elective orthopedic and dental interventions, where conservative treatments are often preferred. Furthermore, smaller veterinary clinics may delay adoption of advanced bone graft technologies because of budget constraints and lower surgical volumes, limiting broader market penetration despite the proven clinical benefits of regenerative bone substitutes.
The growing development of bioactive and regenerative bone graft technologies presents a significant opportunity for the market. Some of the research institutions are integrating natural bioactive compounds with advanced biomaterials in large numbers to improve implant performance and accelerate bone healing. For instance, in April 2026, researchers at Washington State University demonstrated that a turmeric and ginger extract coating on titanium bone implants significantly enhanced bone regeneration, approximately doubling bone bonding within six weeks while eliminating over 90% of bacteria on implant surfaces and substantially reducing osteosarcoma-related cancer cells. Such innovations highlight the potential of multifunctional bone graft substitutes that simultaneously promote osseointegration, reduce infection risks, and support postoperative recovery. As regenerative medicine, bioactive coatings, and advanced biomaterials continue to evolve, veterinary manufacturers have opportunities to commercialize next-generation bone graft products that improve clinical outcomes, expand orthopedic treatment options, and strengthen adoption across specialty veterinary hospitals and referral centers.
Market Concentration & Characteristics
The veterinary bone grafts and substitutes market is highly concentrated. The market is in a medium growth stage, and the rate of expansion is rapidly increasing. Rapid advancements in veterinary bone surgical procedures, as well as the introduction of innovative products by key manufacturers, are key market drivers. Market concentration is impacted by the rate of technical improvements. Companies invest in R&D to introduce novel products with improved features and efficacy can gain a competitive advantage and expand their market penetration.
The veterinary bone grafts and substitutes market is characterized by a high degree of innovation driven by the need for advanced solutions in orthopedic care for animals. Innovations include the development of products with enhanced osteoconductive and osteo-integrative properties. For Instance, in May 2023, TheraVet launched BIOCERA-VET Combo-Clean, a bone substitute that provides sustained local antibiotic delivery for up to 30 days, making it highly effective in preventing and managing bone infections. Combined with the seven most commonly used antibiotics, this product offers unique osteoconductive and osteo-integrative properties, enhancing its use in orthopedic surgeries. Additionally, ready-to-use injectable bone cement and customized grafts designed for specific animal breeds and types of fractures are becoming more common, reflecting the market's focus on improving treatment outcomes and reducing recovery times.
 To learn more about this report, Download Free Sample Report
The level of collaborations and partnership activities in the market is high, reflecting a strategic focus on expanding market reach and enhancing product availability. Key collaborations often involve distribution agreements with established veterinary product companies. For instance, in November 2023, Biomendex and Prevett Oy entered into a partnership to distribute AdaptosVet bone graft material in Finland. Prevett now offers this product through its wholesale system, allowing Finnish veterinary clinics and hospitals to easily order AdaptosVet directly from their webshop.
Regulations significantly impact the market by ensuring product safety, efficacy, and quality through rigorous approval processes and adherence to manufacturing standards. Compliance with these regulations can increase market entry barriers and development costs and enhance product credibility and trust among veterinary professionals. Ultimately, robust regulatory frameworks drive market growth by advancing innovation and ensuring high standards of care.
Product launches in the market significantly impact market dynamics by introducing innovative solutions that address specific orthopedic needs. New products often drive market growth by enhancing treatment options, improving surgical outcomes, and increasing competition. They also stimulate interest among veterinary professionals and can lead to broader adoption of advanced technologies in clinical practice. For Instance, In March 2024, TheraVet launched BIOCERA-VET Equine as an innovative treatment in dental applications and oral/maxillofacial surgery in horses. The product has an exclusive property needed for minimally invasive cementoplasty.
Regional expansion is a key growth strategy in the market, allowing companies to tap into new and emerging markets. Companies can significantly boost their market presence by entering regions with high pet ownership and increasing demand for advanced veterinary care. For Instance, in February 2023, TheraVet signed an exclusive distribution agreement with Vetpharma to distribute its BIOCERA-VET product line across 24 countries, including Scandinavia, Brazil, South Africa, Australia, and Japan. This agreement marks a significant expansion, making BIOCERA-VET available on all continents and tapping into high-potential markets where the demand for advanced animal healthcare solutions is growing.
Analyst Perspective
The sector is propelled by rising incidences of orthopedic conditions, traumatic fractures, and congenital bone defects in companion animals and livestock. In addition, growing pet ownership, increased spending on advanced veterinary care, and rising owner willingness to pursue surgical interventions rather than euthanasia are key demand drivers. Some of the advances such as in synthetic substitutes, allografts, xenografts, and demineralized bone matrices are improving osteointegration outcomes while reducing donor-site morbidity associated with traditional autografts.
Furthermore, veterinary hospitals and specialty orthopedic clinics are adopting these products, supported by growing referral networks and board-certified veterinary surgeons. In addition, rising cases of hip dysplasia, periodontal bone loss, and sports-related injuries in performance animals are expanding application scope beyond companion animals into equine and livestock segments. Moreover, competitive dynamics are intensifying as manufacturers focus on product innovation, resorbable scaffolds, and growth-factor-enhanced substitutes. In addition, strategic collaborations between biomaterial developers and veterinary institutions, alongside expanding distribution in emerging economies, are expected to accelerate market penetration and long-term growth prospects.
Product Insights
Based on product, the autografts segment led the market with the largest revenue share of 41.1% in 2025. Autografts are highly and commonly used in veterinary bone surgeries because they perfectly match the recipient's tissue, minimizing the risk of immune rejection. They are harvested from the same animal, ensuring compatibility and promoting faster healing. Additionally, autografts contain live bone cells and growth factors that enhance bone regeneration and integration, making them highly effective for repairing fractures, bone defects, and other orthopedic conditions. This natural compatibility and biological activity make autografts a preferred choice for many veterinarians.
Others segment is expected to grow at fastest CAGR of 7.34% during forecast period. It includes synthetic bone graft substitutes, growth factor-based grafts, and antibiotic-loaded bone graft substitutes. Synthetic bone grafts and substitutes, particularly those made from materials like tricalcium phosphate (TCP) and hydroxyapatite, have gained popularity in recent years. These synthetic options are favored due to their biocompatibility, ease of availability, and lower risk of disease transmission compared to allografts and autografts. Additionally, they provide a scaffold that promotes natural bone growth and healing, making them a popular choice for treating fractures, bone defects, and orthopedic conditions in various animals.
Animal Type Insights
Based on animal, the dogs segment led the market with the largest revenue share of 56.6% in 2025. The increasing prevalence of orthopedic injuries in dogs participating in agility competitions is expected to be one of the key factors driving the market due to the growing need for specialized care. For instance, according to a February 2024 Frontiers in Veterinary Science publication, orthopedic injuries (32.9%) were the most common health complication among dogs participating in the Yukon Quest International Sled Dog Race. The data further suggests that these injuries were the most common reason for participant dogs withdrawing (75%) from the competition. As more dogs engage in these activities, the demand for veterinary orthopedic services such as bone graft and substitute surgeries increases.
Cats segment is expected to be fastest-growing segment with the highest CAGR of 7.76% over the forecast period. Globally, the second-most popular pet choice is cats. According to the American Pet Products Association report from 2024, approximately 40 million U.S. households own cats, and cat ownership increased among younger generations, especially millennials. Moreover, advancements in treatment options, including minimally invasive techniques and novel bone grafts and substitutes, contribute to the evolving landscape of the market. As pet owners increasingly seek advanced care for their cats, the market will likely continue growing and adapting to meet the specific needs of feline orthopedic patients.
Form Insights
Based on form, the injectables segment led the market with the largest revenue share of 34.8% in 2025. In the veterinary bone grafts and substitutes market, injectable forms are increasingly popular due to their minimally invasive nature, which reduces surgical trauma and post-operative recovery time. Injectable bone grafts allow for precise application to irregular bone defects, enhancing the integration and healing process. This form also minimizes the risk of infection and provides ease of use for veterinarians, making it a preferred option for treating bone injuries and defects in animals. The ability to fill complex bone cavities and adapt to various surgical needs drives the demand for injectable veterinary bone grafts and substitutes.
Pellets segment is estimated to grow at the highest CAGR of 7.4% over the forecast period. Pellet forms are gaining popularity due to their ease of handling and precise placement. Pellets provide controlled delivery and consistent dosing of graft material, enhancing application accuracy in bone defects. They offer better adaptability to the shape and size of the defect, leading to improved integration and healing. Additionally, pellet form can be easily packed into irregular spaces and allows for straightforward manipulation during surgery, making it a favored choice in veterinary orthopedic and dental procedures.
Application Insights
Based on application, the orthopedic segment led the market with the largest revenue share of 41.4% in 2025. Veterinary bone grafts and substitutes are commonly used in orthopedic treatments compared to other indications due to their critical role in addressing fractures, bone defects, and joint problems, which are prevalent in animals. These materials provide structural support and facilitate bone healing, making them essential for repairing traumatic injuries, degenerative conditions, and congenital deformities. This segment is advancing due to rising collaborations between universities and companies in research. For instance, in March 2026, EpiBone collaborated with Cornell University, demonstrating that its tissue-engineered osteochondral grafts (EB-OC) achieved cartilage and bone repair outcomes comparable or superior to fresh allografts, highlighting scalable, donor-independent regenerative solutions for advanced orthopedic applications.
 To learn more about this report, Download Free Sample Report
Dental segment is expected to grow at the fastest CAGR over the forecast period. Veterinary bone grafts and substitutes are gaining popularity in veterinary dentistry due to their effectiveness in treating periodontal disease, jaw fractures, and bone defects caused by dental extractions or tumors. These materials help regenerate bone and provide structural support, improving the stability and function of the jaw. For example, bone grafts are increasingly used in treating mandibular defects in dogs, allowing for better outcomes in dental surgeries and enhancing the overall health and quality of life of the animals. This growing application in dentistry highlights the versatility and importance of bone grafts in veterinary care.
Material Insights
Based on material, the tricalcium phosphate (TCP) segment led the market with the largest revenue share of 40.3% in 2025. The demand for Tricalcium Phosphate (TCP) based veterinary bone grafts and substitutes is higher due to TCP's excellent biocompatibility and osteoconductive properties, which promote natural bone regeneration. TCP is resorbable and thus gradually dissolves and is replaced by new bone, making it ideal for healing fractures and defects. Its ability to support the growth of new bone tissue while minimizing the risk of immune reactions or complications makes TCP-based grafts a preferred choice in veterinary surgeries. Additionally, TCP's versatility allows it to be used in various forms, such as granules, blocks, or putty, catering to different surgical needs.
Bioglass segment is expected to be fastest-growing segment with the highest CAGR of 7.76% over the forecast period. Bioglass-based veterinary bone grafts and substitutes are rapidly gaining popularity in veterinary surgeries due to their unique ability to bond directly with bone and support bone regeneration. Bioglass stimulates cellular activity that enhances healing and provides a scaffold for new bone growth. Its bioactive properties encourage the formation of a strong bone-implant interface, reducing healing time and improving surgical outcomes. Additionally, bioglass is resorbable, allowing it to integrate seamlessly with the host bone, making it an effective and reliable option for treating fractures and bone defects in animals.
End-use Insights
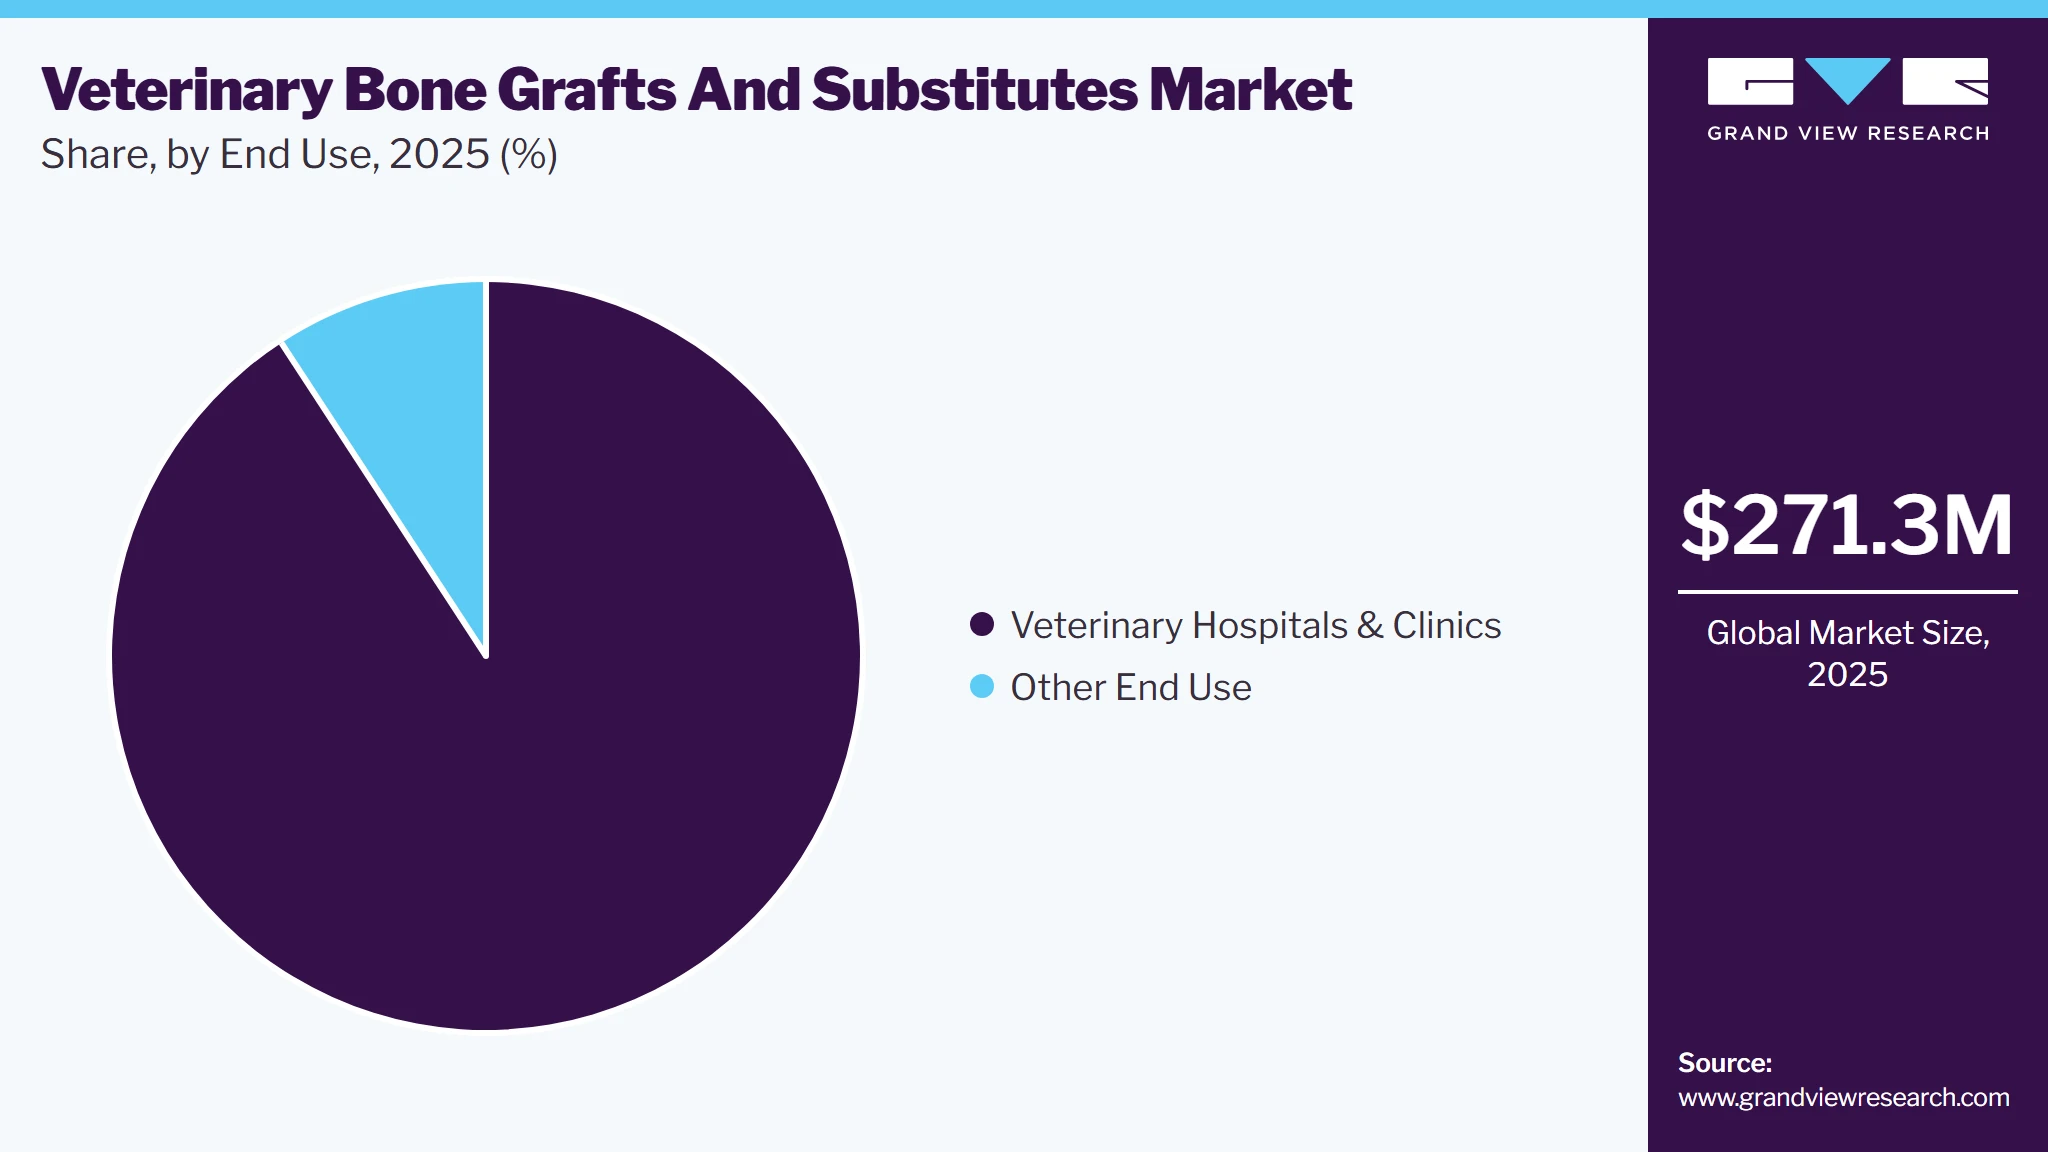
Based on end use, the veterinary hospitals & clinics segment led the market with the largest revenue share of 90.8% in 2025. This growth is attributed to the extensive use of these products for a wide range of orthopedic procedures. These facilities often handle complex cases requiring advanced bone grafting techniques, making them key users of these technologies. Additionally, the high volume of surgeries performed in these settings, combined with their access to the latest technologies and expertise, drives demand for bone grafts and substitutes, solidifying their dominant market position.
Hospitals and clinics also report the largest footfall of patients making these a preferred choice of care for pet parents. Furthermore, the growing need to increase clinic revenue is expected to propel the segment in the near future. By expanding service lines to include orthopedic surgeries, clinics can access new revenue streams, increasing weekly revenue by about USD 40,000 to 80,000, as estimated by Vimian.
Regional Insights
North America dominated the veterinary bone grafts and substitutes market with the largest revenue share of 45.2% in 2025. Key players in the market are engaging in strategic initiatives, such as product launches, collaborations, and acquisitions, to strengthen their market presence in North America, propelling market growth. For instance, in March 2024, Movora acquired Veterinary Transplant Services (VTS), a leader in veterinary grafts and tissue, enhancing its offerings in the market. This acquisition is expected to expand Movora’s portfolio with VTS’s unique graft materials, supporting advanced healing solutions and continuing education for veterinary professionals.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Bone Grafts & Substitutes Market Trends
The veterinary bone grafts and substitutes market in the U.S. held the largest share in the North America region in 2025, driven by the expansion of veterinary facilities and increasing demand for advanced orthopedic solutions, including bone grafts and substitutes. For instance, in April 2024, UC Davis Veterinary Medical Teaching Hospital launched the Advanced Veterinary Surgery Center, a cutting-edge facility dedicated to orthopedic procedures. The center features 25 rooms and three advanced operating rooms to address the increased demand for orthopedic surgeries and expand training for future specialists.
Europe Veterinary Bone Grafts & Substitutes Market Trends
European veterinary bone grafts & substitutes market is influenced by several trends, driven by increasing pet ownership and awareness of advanced veterinary care, advancements in bone graft technologies, and rising demand for innovative orthopedic solutions. Additionally, the expansion of distribution networks and collaborations with local partners enhance market access and product availability across diverse regions in Europe.
Similarly, increased canine & feline population and pet care expenditure fuel market growth. For instance, the number of pet owners is growing, with 166 million out of Europe's 352 million pets being owned by 50% of European households. However, steady growth in the dog population is expected to propel the demand for related products and services, driving the market. Chronic conditions, such as joint disorders, fractures, and trauma, which require surgical interventions, fuel the market. According to findings of the Royal Veterinary College, trauma injuries and obesity are one of the most common disorders affecting cats. While joint diseases, obesity, and limb lameness commonly affect dogs.
Germany held the largest share in the European veterinary bone grafts & substitutes market in 2024. In Germany, the rise in the pet dog population, prevalence of pet obesity, expenditure on pet health, well-equipped pet health infrastructure, and technological advancements have put pressure on players to innovate new veterinary bone grafts & substitutes for pet surgery, benefiting their health. This factor has led companies to shift their focus to product innovations. In addition, growing pet health concerns, rising product offerings by companies, and well-established veterinary care facilities are expected to boost the number of orthopedic surgeries performed in the country. For instance, in January 2024, TheraVet launched BIOCERA-VET products in Germany. To support this launch, the company mentioned attending the Leipzig Veterinary Congress. The TheraVet and AWEX (Wallonia Export & Investment Agency) participated in this event, which was dedicated to animal health. Therefore, growing product offerings of key companies will likely drive the market.
UK is anticipated to grow at a constant rate due to an increase in partnerships between key players to expand distribution networks and improve product accessibility for veterinary clinics across the UK. For instance, in September 2023, Biomendex entered into collaboration with N2 (UK) Ltd to distribute AdaptosVet in the UK and Northern Ireland. By collaborating with established distributors like N2 (UK) Ltd, companies can utilize thier existing networks and market presence to enhance product availability and reach a broader customer base.
Asia Pacific Veterinary Bone Grafts & Substitutes Market Trends
The Asia Pacific veterinary bone grafts & substitutes market is expanding rapidly, driven by factors such as rising number of orthopedic issues in animals, including osteosarcoma and arthritis, is fueling demand for bone grafts and substitutes to aid in effective treatment and recover. Canine osteosarcoma is a common and aggressive bone cancer affecting dogs in the Asia-Pacific region. Estimates suggest that it accounts for approximately 85% of all primary bone tumors in dogs. Bone grafts and substitutes are increasingly used in limb-sparing surgeries for canine osteosarcoma, allowing for more effective treatment options that preserve the limb and improve quality of life. Veterinary bone grafts are often used in conjunction with chemotherapy or radiotherapy, providing a comprehensive approach to managing osteosarcoma and addressing the limitations of traditional treatments.
The veterinary bone grafts & substitutes market in India is witnessing notable growth due to the increasing incidence of arthritis in dogs and the need for advanced veterinary bone grafting procedures. According to a Times of India article from July 2023, dogs with arthritis often have degenerative joint disease, which results in joint stiffness, discomfort, and inflammation. Although it typically affects older dogs, it can also affect younger dogs for various reasons, including genetics, trauma, or illnesses. The common belief is that arthritis primarily affects older dogs, yet hip dysplasia, which causes malformed hip or femur joints, can cause arthritic changes in dogs as young as 6 months. Veterinary bone grafts and substitutes provide critical solutions in managing this condition by supporting joint repair and enhancing healing processes. It also provide necessary support and stability to affected bones and joints, particularly in complex cases of arthritis.
Latin America Veterinary Bone Grafts & Substitutes Market Trends
Growing pet ownership and expenditure in Latin America drive demand for advanced veterinary treatments, including bone grafts and substitutes. For instance, Mexico and Argentina are experiencing rising rates of pet adoption, leading to increased veterinary care needs. Furthermore, companies are expanding their distribution networks in Latin America to meet the growing demand. For instance, partnerships between global suppliers and local distributors are increasing the availability of advanced bone graft products in the region. For example, according to the 2023 annual report of TheraVet, the company’s products, such as BIOCERA-VET, are available through regional distributors or veterinary networks in Latin American countries.
The Brazil veterinary bone grafts and substitutes market is expanding due to increased awareness and demand for advanced veterinary orthopedic treatments, particularly for managing conditions like osteoarthritis and fractures in pets. Additionally, rising pet ownership and higher expenditure on pet health are fueling the demand for specialized veterinary treatments, including bone grafts and substitutes. There are roughly 59.4 million pet dogs in Brazil and 28.1 million cats. Moreover, the country has approximately 36 million small dogs & pups at home—more per capita than any other country in the world. This is because of Brazil’s rapidly growing middle-class population. Furthermore, according to an article published by PetFood Industry in June 2023, 52% of Brazilian households own a dog, whereas 23% own a cat.
Middle East & Africa Veterinary Bone Grafts & Substitutes Market Trends
The Middle East & Africa veterinary bone grafts & substitutes market is witnessing significant growth, driven by increased bone-related disorders, such as fractures and osteoarthritis in pets, which drive demand for bone grafts and substitutes. Similarly, the development of new veterinary clinics and hospitals across the region presents opportunities for market growth. Improved facilities can support advanced procedures requiring bone grafts and substitutes. For instance, in South Africa, the rise in orthopedic surgeries for pets and the expansion of veterinary hospitals in urban areas are creating significant demand for advanced bone grafts and substitutes. Similarly, in the UAE, increasing investments in veterinary care infrastructure are expected to boost the market for these products, reflecting a broader trend of growth across the region.
Urbanization in Saudi Arabia significantly contributes to the growth of the market. As cities expand and the population of pet owners increases, there is a rising demand for advanced veterinary care. This urban growth drives the establishment of more veterinary clinics and specialized animal hospitals equipped to perform complex procedures, including bone graft surgeries. The increase in urban pet ownership also leads to a higher incidence of bone-related issues in pets, further boosting the need for innovative treatments such as bone grafts and substitutes. Additionally, urban areas tend to have better access to advanced medical technologies and higher awareness of sophisticated veterinary options, supporting the market's expansion.
Key Veterinary Bone Grafts And Substitutes Company Insights
Key players in the veterinary bone grafts & substitutes market are actively engaged in highly competitive market dynamics. These companies emphasize R&D and introduce new products to enhance their market presence. Furthermore, increasing distribution agreements among key players significantly drives the growth of the veterinary bone grafts and substitutes market. These partnerships enhance the availability and accessibility of advanced bone graft products, allowing companies to enter new markets and reach a broader customer base quickly. For instance, TheraVet's agreement with Alcyon Italia to distribute BIOCERA-VET products in Italy has boosted its market presence, demonstrating how such collaborations can lead to greater market penetration and increased sales of veterinary orthopedic solutions.
Key Veterinary Bone Grafts And Substitutes Companies:
The following key companies have been profiled for this study on the veterinary bone grafts and substitutes market.
-
Movora (Vimian Group AB)
-
TheraVet SA
-
Biomendex
-
Integra LifeSciences Corporation.
-
Progenica Therapeutics, LLC
-
BioChange
-
Nutramax Laboratories Veterinary Sciences, Inc.
-
RITA LEIBINGER GmbH & Co. KG
-
VETEREGEN
-
AlphaLogix, LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Mova (Mivin Group, AB Ther, SA and others)
Mature players focus on expanding regenerative biomaterial portfolios, investing in R&D for bioactive and synthetic graft substitutes, strengthening collaborations with veterinary hospitals and universities, securing regulatory approvals, and expanding distribution networks globally. They also emphasize clinician education, evidence-based product validation, acquisitions of innovative biomaterial companies, and continuous product innovation to address orthopedic, dental, and oncology applications while improving long-term customer loyalty.
Established companies benefit from extensive product portfolios, proven clinical performance, strong brand recognition, robust regulatory compliance, global distribution capabilities, and long-standing relationships with veterinary surgeons. Their financial strength enables continuous innovation, and market maturity, gaining increased investments in regenerative technologies, allowing them to deliver reliable solutions with consistent availability, comprehensive technical support, and superior clinical outcomes across diverse veterinary applications.
Mature players often face slower innovation cycles due to complex regulatory processes and organizational structures. Premium pricing may restrict adoption among cost-sensitive veterinarians, while maintaining broad product portfolios increases operational costs.
Emerging Players (VET... AlphaLoc, LLC and regional pet brands)
Emerging players focus on developing bioactive synthetic grafts, injectable materials, and species-specific regenerative solutions while collaborating with veterinary hospitals, universities, and distributors. They emphasize clinical validation, cost-effective manufacturing, digital veterinary education, and regulatory compliance. Strategic partnerships with orthopedic specialists and emerging biomaterial suppliers, 3D-printed scaffolds, and minimally invasive surgical applications help strengthen commercialization and expand market penetration.
Emerging companies differentiate themselves through innovative biomaterials, customizable formulations, regenerative technologies, and competitive pricing. Faster product development, flexibility in addressing niche veterinary applications, and often advanced manufacturing technologies enable quick commercialization. Strong collaborations with research institutes and adoption of tissue engineering, functionalized agents, and injectable substitutes position them as innovative alternatives to established manufacturers.
Emerging companies often face limited brand recognition, restricted distribution networks, and constrained financial resources compared with established competitors. High regulatory requirements, lengthy clinical validation, limited access to funding, and lower marketing capabilities can delay commercialization
Recent Developments
-
In May 2024, TheraVet unveiled plans to launch a range of products for horses by 2027. These products will include BIOCERA-VET OSTEO, with enhanced osteo inductive properties; NUTRA-VET, a range of nutraceuticals; and VISCO-VET Equine, a regenerating gel currently being developed by the company to treat osteoarticular diseases as well as tendon and ligament injuries.
-
In January 2024, Biomendex and Jorgensen Laboratories (Jorvet) entered a collaboration agreement to distribute AdaptosVet across the U.S., Canada, and Mexico.
-
In January 2024, TheraVet signed a partnership agreement with Alcyon Italia to distribute its BIOCERA-VET line of bone substitutes in Italy, using Alcyon’s extensive network and expertise in orthopedic distribution. This collaboration includes the promotion of 13 BIOCERA-VET products, supported by clinical trials and educational initiatives aimed at Italian veterinarians.
Veterinary Bone Grafts And Substitutes Market Report Scope
Report Attribute
Details
Market size in 2025
USD 271.3 million
Estimated market size in 2026
USD 291.2 million
Projected market size by 2033
USD 533.8 million
Growth rate
CAGR of 9.0% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, animal, form, application, material, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Movora (Vimian Group AB); TheraVet SA; Biomendex; Integra LifeSciences Corporation.; Progenica Therapeutics, LLC; BioChange; Nutramax Laboratories Veterinary Sciences; Inc.; RITA LEIBINGER GmbH & Co. KG; VETEREGEN; AlphaLogix, LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Bone Grafts And Substitutes Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary bone grafts and substitutes market report based on product, animal type, form, application, material, end-use, and region.
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Autografts
-
Allografts
-
Xenografts
-
Others
-
-
Animal Type Outlook (Revenue, USD Million; 2021 - 2033)
-
Dogs
-
Cats
-
Horses
-
Others
-
-
Form Outlook (Revenue, USD Million; 2021 - 2033)
-
Powders
-
Putty
-
Pellets
-
Injectables
-
Others
-
-
Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Orthopedic
-
Dental
-
Ocular
-
Osteosarcoma
-
Others
-
-
Material Outlook (Revenue, USD Million; 2021 - 2033)
-
Tricalcium Phosphate (TCP)
-
Ceramic
-
Bioglass
-
Others
-
-
End-Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Other End Use
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of Latin America
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
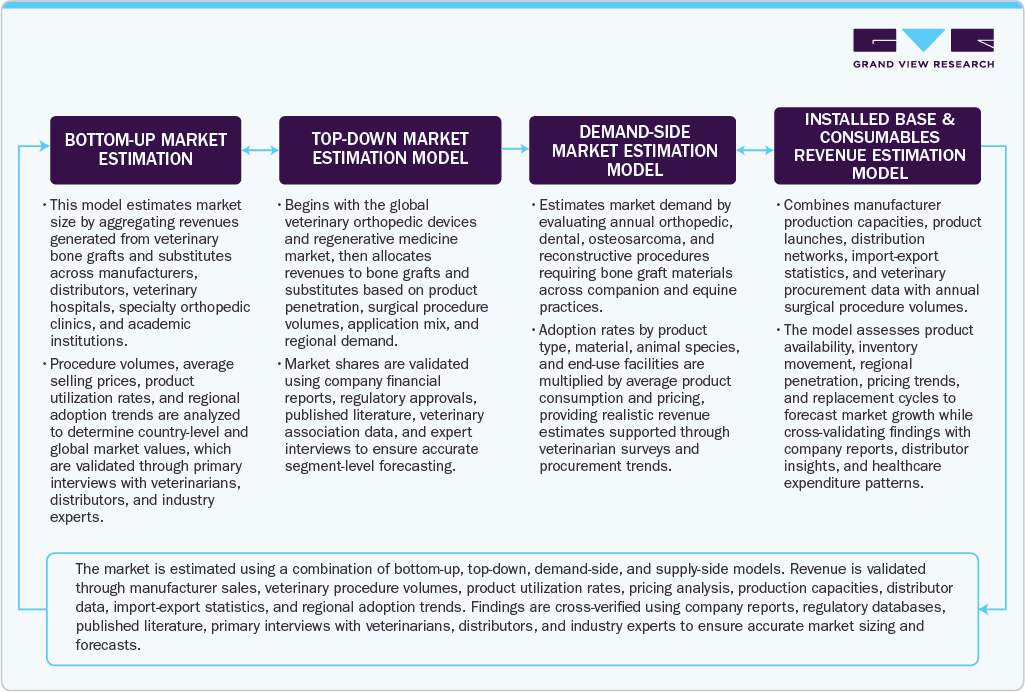
The veterinary bone grafts and substitutes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary bone grafts and substitutes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Autografts
Autografts utilize bone harvested from the same animal to repair skeletal defects. They provide superior osteogenic, osteoconductive, and osteoinductive properties while minimizing immune rejection and disease transmission risks.
Allografts
Allografts involve donor bone obtained from another animal of the same species. They provide structural support and osteoconductive properties while avoiding donor-site morbidity associated with autograft harvesting procedures.
Xenografts
Xenografts are bone graft materials derived from different animal species, commonly bovine or porcine sources. They provide scaffold support for bone regeneration after extensive processing ensures biocompatibility and safety.
Others
Includes synthetic bone substitutes, demineralized bone matrix, composite grafts, growth factor-enhanced biomaterials, and bioengineered scaffolds designed to promote bone healing in diverse veterinary orthopedic and reconstructive procedures.
Autografts
Autografts utilize bone harvested from the same animal to repair skeletal defects. They provide superior osteogenic, osteoconductive, and osteoinductive properties while minimizing immune rejection and disease transmission risks.
Segment - Animal
Revenue Capture Definition
Dogs
Dogs represent the largest animal segment due to high incidence of fractures, cranial cruciate ligament injuries, orthopedic surgeries, dental procedures, and increasing adoption of advanced regenerative bone grafting techniques worldwide.
Cats
Cats require bone grafts primarily for fracture repair, maxillofacial reconstruction, orthopedic trauma, and dental surgeries. Growing companion animal healthcare expenditure supports increased utilization of advanced graft materials and substitutes.
Horses
Horses utilize bone grafts for treating orthopedic injuries, joint disorders, stress fractures, and performance-related skeletal defects. Equine sports medicine increasingly adopts regenerative biomaterials to accelerate healing and restore mobility.
Other Animals
Includes livestock, rabbits, birds, exotic pets, and wildlife requiring bone grafts for trauma management, orthopedic reconstruction, and skeletal defect repair in specialized veterinary practices and zoological healthcare facilities.
Segment - Form
Revenue Capture Definition
Powders
Powder formulations consist of finely processed graft materials suitable for filling irregular bone defects. They provide excellent adaptability, promote bone regeneration, and are commonly combined with biological fluids during surgery.
Putty
Putty bone grafts offer moldable consistency for easy application into complex bone defects. Their handling characteristics improve surgical convenience while maintaining graft stability and supporting new bone formation effectively.
Pellets
Pellet bone grafts are preformed granules providing structural support and controlled placement within bone defects. They maintain defect space while encouraging gradual integration and regeneration during orthopedic healing processes.
Injectables
Injectable bone graft substitutes are minimally invasive formulations delivered through syringes into bone defects. They enhance surgical precision, reduce procedure time, and improve access to anatomically challenging treatment sites.
Others
Includes blocks, strips, sponges, gels, membranes, and customized scaffold formats developed for specific orthopedic, dental, and reconstructive procedures requiring specialized graft delivery and structural support characteristics.
Segment - Application
Revenue Capture Definition
Orthopedic
Orthopedic applications include fracture repair, joint reconstruction, spinal fusion, corrective osteotomies, and treatment of bone defects. This segment accounts for the largest demand for veterinary bone graft substitutes globally.
Dental
Dental applications involve alveolar bone regeneration, periodontal defect repair, tooth extraction sites, and maxillofacial reconstruction. Bone grafts improve implant stability, jaw integrity, and long-term oral health outcomes.
Ocular
Ocular applications include orbital reconstruction and repair of craniofacial defects affecting eye structures following trauma, tumor removal, or congenital abnormalities requiring supportive bone regeneration and structural restoration procedures.
Osteosarcoma
Bone grafts support reconstruction following osteosarcoma tumor resection by restoring skeletal integrity, promoting healing, and improving postoperative function alongside limb-sparing surgeries and comprehensive veterinary oncology treatment strategies.
Other Application
Includes reconstructive surgery, craniofacial repair, congenital defect correction, trauma management, and regenerative medicine procedures requiring bone replacement materials to restore skeletal function and improve patient recovery outcomes.
Segment - Material
Revenue Capture Definition
Tricalcium Phosphate (TCP)
Tricalcium phosphate is a biodegradable ceramic biomaterial offering excellent osteoconductivity. It gradually resorbs as natural bone regenerates, making it widely used for veterinary orthopedic and dental bone defect repair.
Ceramic
Ceramic bone substitutes provide high compressive strength, biocompatibility, and osteoconductive properties. They are commonly used for structural bone support in orthopedic and reconstructive veterinary surgeries requiring durable graft materials.
Bioglass
Bioglass is a bioactive material that bonds directly with bone tissue while stimulating cellular activity and mineralization. It promotes faster regeneration and improved healing in veterinary skeletal reconstruction procedures.
Others
Includes hydroxyapatite, collagen composites, polymer-based biomaterials, bioactive composites, and emerging regenerative materials engineered to enhance bone formation, mechanical stability, and long-term integration in veterinary patients.
Segment - End-Use
Revenue Capture Definition
Veterinary Hospitals & Clinics
Veterinary hospitals and clinics represent the primary end users, performing orthopedic, dental, oncology, and reconstructive surgeries requiring bone graft materials, advanced imaging, specialized surgical expertise, and postoperative rehabilitation services.
Other End Use
Includes academic veterinary institutions, research laboratories, specialty rehabilitation centers, wildlife hospitals, and referral facilities utilizing bone graft substitutes for clinical research, advanced treatments, and experimental regenerative medicine applications.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Strategic forecasting and investment opportunity analysis
Provided customized forecasting models using bottom-up, top-down, demand- and supply-side methodologies. Integrated the potential demand, growth, and investment scenarios to evaluate future market opportunities through 2033.
Strengthened strategic planning by delivering reliable revenue forecasts, investment prioritization, capacity planning, risk assessment, and evidence-based business development strategies, enabling the client to capitalize on emerging opportunities in the veterinary bone grafts and substitutes market.
Regional market opportunity and regulatory assessment
Delivered country-level evaluation covering North America, Europe, Asia Pacific, Latin America, and the Middle East. Included regulatory pathways, veterinary healthcare infrastructure, reimbursement environment, import dependency, distributor landscape, and regional adoption of advanced bone graft technologies.
Assisted in prioritizing expansion markets, optimizing regional launch strategies, minimizing regulatory risks, and identifying countries with favorable infrastructure, growing orthopedic procedure volumes, and higher commercial potential.
Competitive intelligence and market landscape analysis
Developed an extensive competitive assessment covering established manufacturers, emerging biomaterial companies, distributor networks, pricing strategies, product portfolios, mergers, collaborations, and market expansion strategies. Included SWOT benchmarking and innovation comparison across leading bone graft providers.
Helped benchmark competitive positioning, identify market gaps, evaluate acquisition or partnership opportunities, and develop effective commercialization strategies. Supported strategic decision-making for market entry, pricing optimization, and long-term competitive differentiation.
Frequently Asked Questions About This Report
The global veterinary bone grafts and substitutes market size was valued at USD 271.3 million in 2025 and is estimated at USD 291.2 million in 2026.
The global veterinary bone grafts and substitutes market is expected to grow at a CAGR of 9.0% from 2026 to 2033, reaching USD 533.8 million by 2033.
North America dominated with a revenue share of 45.2% in 2025.
Some key players operating in the veterinary bone grafts & substitutes market include Movora (Vimian Group AB); TheraVet SA; Biomendex; Integra LifeSciences Corporation.; Progenica Therapeutics, LLC; BioChange; Nutramax Laboratories Veterinary Sciences; Inc.; RITA LEIBINGER GmbH & Co. KG; VETEREGEN; AlphaLogix, LLC
Key factors that are driving the market growth include increasing demand for advanced orthopedic solutions, rising pet ownership, growing awareness of veterinary surgical options, increasing product launches, and an increase in supportive initiatives.
Asia Pacific is the fastest-growing region over the forecast period.
Based on product, the autografts segment led the market with the largest revenue share of 41.1% in 2025.
Based on animal, the dogs segment led the market with the largest revenue share of 56.6% in 2025.
Based on form, the injectables segment led the market with the largest revenue share of 34.8% in 2025.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


