
- Home
- »
- Animal Health
- »
-
Veterinary Ophthalmic Drugs Market Size Report, 2033GVR Report cover

Veterinary Ophthalmic Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal (Canine, Feline, Equine, Bovine), By Drug (Antibiotics, NSAIDs, Corticosteroids, Lubricants / Artificial Tears), By Indication, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.2BMarket Forecast, 2033
$3.6BCAGR, 2026–2033
7.1%Veterinary Ophthalmic Drugs Market Summary
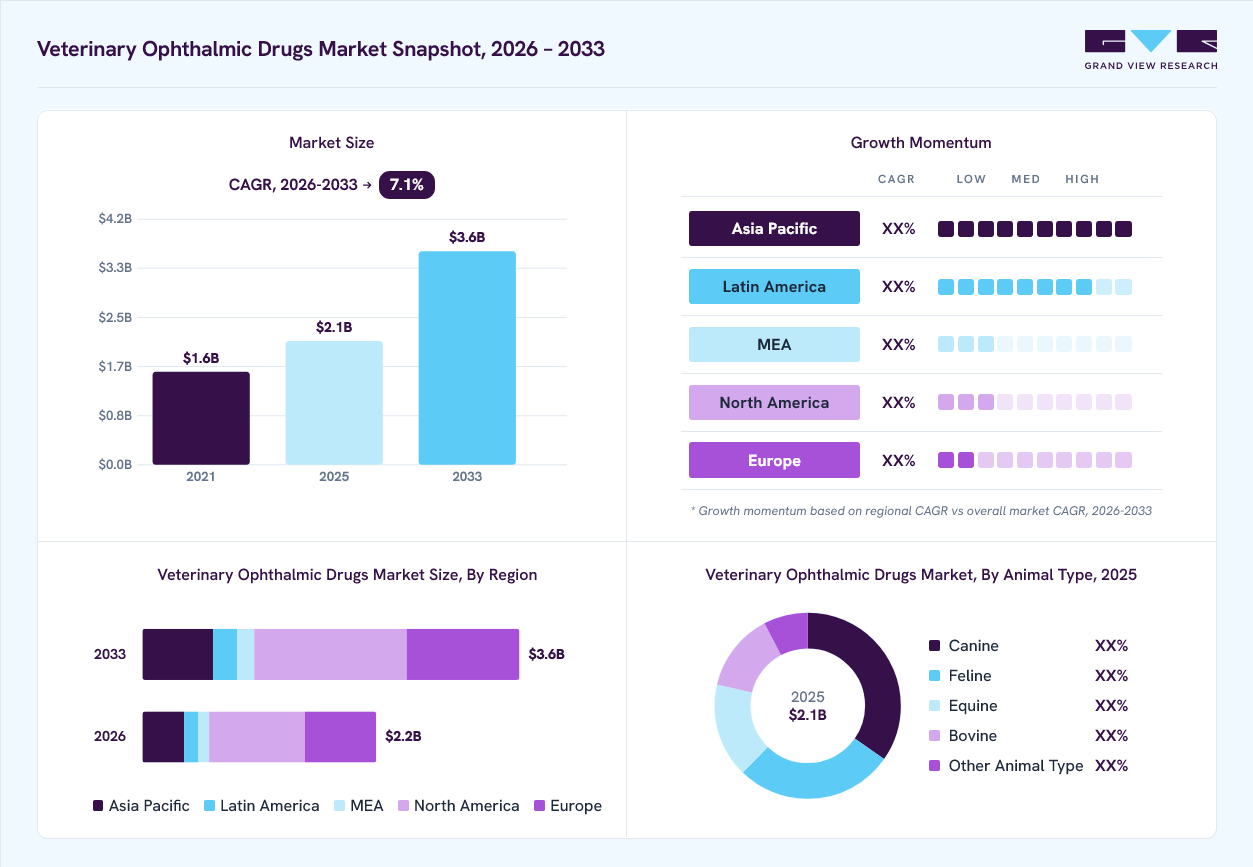
The global veterinary ophthalmic drugs market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 3.6 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.1% in 2025. Some of the factors driving the market growth are advancements in ophthalmic drug-delivery technologies, rising development of long-acting ophthalmic therapies, increasing focus on antimicrobial stewardship & evidence-based use, and growing clinical demand for treatment of complex ocular diseases.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug: Lubricants / artificial tears segment led the market with the largest revenue share of 26.0% in 2025.
- By animal type: Canine segment led the market with the largest revenue share of 34.7% in 2025.
- By indication: Uveitis segment led the market with the largest revenue share of 18.2% in 2025.
- By distribution channel: Veterinary hospitals & clinics segment led the market with the largest revenue share of 38.3% in 2025.
Regional Highlights
- Largest regional market: North America (41.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 3.6 Billion
- CAGR (2026-2033): 7.1%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary ophthalmic drugs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Advances in drug delivery technology are driving market growth. Advanced technologies such as artificial intelligence are improving corneal drug delivery by modeling how formulation variables affect ocular absorption and retention. A February 2026 review from the University of Illinois Chicago, published in MDPI, reported that machine learning predicts particle size, release kinetics, corneal permeability, and irritation risk before laboratory validation. These models operate in closed-loop systems that refine formulations using experimental feedback. The approach reduces development time, supports safer carrier design, and enables smart platforms such as peptide carriers and drug-releasing contact lenses. This shift is creating growth opportunities for precision-based ophthalmic therapies with sustained release profiles. To learn more about this report, Download Free Sample Report
Furthermore, an April 2025 study conducted at the Hebrew University of Jerusalem reported that eyedrops formulated with cross-linked hyaluronic acid achieved superior ocular bioavailability than conventional carriers. Dogs treated with XHA-based drops recorded 2.4 times higher exposure to cefazolin and 4.2 times higher exposure to chloramphenicol compared with polyvinyl alcohol formulations. Higher drug exposure and prolonged retention on the corneal surface reduce dosing frequency and improve treatment adherence among pet owners. Lower administration burden increases the acceptance of premium ophthalmic therapies in clinical practice.
Moreover, an April 2025 article published on Drugs.com confirmed that hyaluronic acid carriers extend antibiotic residence time on canine ocular tissue and may reduce the risk of antimicrobial resistance. The report noted that hyaluronic acid supports epithelial healing and exhibits mild antimicrobial activity. Veterinary pharmaceutical companies are responding by developing combination products that integrate antibiotics with advanced viscoelastic carriers. These platforms create opportunities for antifungal therapies, immunomodulators, and anti-glaucoma agents that benefit from sustained ocular exposure.
Drug delivery innovation has emerged as the most decisive market growth. Artificial intelligence-led formulation design and advanced carriers such as cross-linked hyaluronic acid are increasing ocular drug exposure and extending therapeutic duration beyond conventional drops. Veterinary clinics are prioritizing products that achieve measurable clinical improvement with fewer daily doses and lower resistance risk. Manufacturers are directing capital toward differentiated delivery platforms that command premium pricing and strengthen brand positioning against generics. This technology-centered shift is accelerating demand in chronic indications such as keratoconjunctivitis sicca and glaucoma and is shaping the long-term expansion trajectory of the sector.
Key Insights from the Improved Canine Eyedrops Research Study
Insight
Explanation / Implication
Hyaluronic acid improves retention
Cross-linked HA keeps antibiotics on the eye longer and increases contact time.
Higher drug exposure levels
Cefazolin exposure rose about 2.4× and chloramphenicol about 4.2× with HA-based drops.
Reduced dosing needs
Longer retention allows fewer applications and improves caregiver compliance.
Lower resistance risk
Better drug persistence supports more stable dosing and may slow resistance development.
HA supports healing
Hyaluronic acid helps hydration, tissue repair, and may provide antibacterial action.
Better tear-film stability
The formulation improves lubrication, which supports recovery in many eye conditions.
Relevance to human therapies
Canine eye structure is similar to that of humans, so findings may guide human drug-delivery advances.
Tested for safety first
Initial work was done in healthy dogs, and trials in diseased eyes are planned.
Uses common ophthalmic antibiotics
The study used antibiotics already standard in veterinary care, improving practical value.
Dogs as strong research models
Dog eye anatomy makes them suitable for testing ophthalmic delivery systems.
Market Dynamics
The veterinary ophthalmic drugs market is experiencing steady growth, driven by the increasing prevalence of ocular disorders in companion animals, rising pet ownership, and growing expenditure on advanced veterinary care. The expanding geriatric pet population and the higher incidence of conditions such as dry eye, glaucoma, cataracts, corneal ulcers, and conjunctivitis are increasing the demand for ophthalmic therapeutics, including anti-infectives, anti-inflammatory drugs, lubricants, and combination formulations. Furthermore, advancements in veterinary ophthalmic diagnostics, the expansion of specialty veterinary clinics, increasing pet insurance coverage, and greater awareness among pet owners regarding early diagnosis and treatment are supporting wider adoption of ophthalmic drugs across both developed and emerging markets.
The market is also being shaped by an evolving regulatory landscape focused on product quality, safety, and animal welfare. Regulatory authorities are strengthening approval requirements for veterinary ophthalmic pharmaceuticals by emphasizing clinical efficacy, manufacturing quality, pharmacovigilance, and appropriate labeling standards. Also, the introduction of generic ophthalmic drugs, harmonization of regulatory frameworks across several regions, and government initiatives aimed at improving veterinary healthcare access are enhancing product availability and affordability. However, manufacturers must continue to invest in regulatory compliance, quality assurance, and post-market surveillance to meet evolving standards and maintain market competitiveness.
The rising geriatric pet population is a significant driver of the veterinary ophthalmic drugs market, as aging animals are more susceptible to chronic ocular disorders requiring long-term medical management. According to American Veterinary Medical Association, more than half of all owned dogs in the U.S. are classified as seniors, while only 8% of dogs were under one year of age in 2024, indicating a clear shift toward an aging canine population. Senior dogs are at a substantially higher risk of developing age-related eye conditions such as cataracts, glaucoma, keratoconjunctivitis sicca (dry eye), retinal degeneration, and chronic corneal diseases, which often require prolonged treatment with anti-inflammatory agents, lubricants, antibiotics, and intraocular pressure-lowering medications. Additionally, senior dogs typically require biannual veterinary examinations instead of annual visits, enabling earlier detection and continuous monitoring of ophthalmic diseases. As pet owners increasingly invest in advanced healthcare to improve the quality of life of aging companion animals, demand for veterinary ophthalmic therapeutics is expected to increase steadily, supporting long-term market growth.The veterinary ophthalmic drugs market is constrained by the limited availability of veterinary ophthalmologists and specialized eye care facilities, particularly in developing countries and rural regions. Although the incidence of ocular disorders such as cataracts, glaucoma, corneal ulcers, keratoconjunctivitis sicca, and retinal diseases is increasing, access to specialized veterinary ophthalmic care remains uneven. Many general veterinary clinics lack trained ophthalmologists as well as advanced diagnostic equipment, including slit-lamp biomicroscopes, tonometers, indirect ophthalmoscopes, and ocular imaging systems required for accurate diagnosis and disease monitoring. Consequently, ocular conditions are often identified at advanced stages, resulting in delayed treatment initiation, reduced therapeutic effectiveness, and, in severe cases, irreversible vision loss.The increasing expenditure on pet healthcare presents a significant growth opportunity for the veterinary ophthalmic drugs market. For instance, according to the American Pet Products Association (APPA), U.S. spending on veterinary care and product sales is projected to increase from USD 41.0 billion in 2025 to USD 42.4 billion in 2026, while total pet industry expenditures are expected to rise from USD 158 billion to USD 165 billion during the same period. This sustained increase in pet healthcare spending reflects pet owners' growing willingness to invest in specialized veterinary treatments, including ophthalmic diagnostics and prescription eye medications. As awareness of chronic ocular disorders and the importance of early intervention continues to improve, veterinary clinics are increasingly adopting advanced ophthalmic therapeutics, such as anti-inflammatory agents, lubricants, antibiotics, and glaucoma medications. The growing preference for premium veterinary care, coupled with higher investments in specialty services, is expected to create substantial opportunities for manufacturers to expand their ophthalmic drug portfolios and strengthen their presence in both developed and emerging veterinary markets.Market Concentration & Characteristics
The veterinary ophthalmic drugs industry exhibits moderate concentration, dominated by leading companies such as Merck & Co., Dechra Pharmaceuticals, Virbac, and Zoetis, which maintain extensive portfolios and global distribution networks. At the same time, specialized ophthalmic manufacturers, compounding pharmacies, and veterinary clinic-driven innovators contribute to a diverse competitive environment. Emerging players in AI-driven drug delivery, cross-linked hyaluronic acid carriers, and sustained-release platforms further broaden competition, keeping the industry balanced while promoting technology-led innovation.
The veterinary ophthalmic drugs industry shows a strong innovation trajectory, driven by AI-based diagnostics, tele-ophthalmology, and sustained-release drug delivery platforms. Advanced carriers, including cross-linked hyaluronic acid and peptide-based systems, improve ocular drug retention and healing, while next-generation imaging tools enable earlier detection and precision care. These technologies enhance treatment outcomes and support the adoption of premium therapies, supporting industry growth.
 To learn more about this report, Download Free Sample Report
M&A activity is increasing as leading animal health companies acquire specialized ophthalmic technology developers to expand capabilities and portfolios. The acquisition of SentrX by Dômes Pharma illustrates strategic consolidation around advanced biomaterials and sustained-release drug-delivery systems. These deals strengthen competitive positioning, accelerate innovation pipelines, and extend industry reach.
Regulatory frameworks influence industry dynamics by enforcing standards for drug safety, efficacy, and manufacturing quality. Alignment with human ophthalmology regulations supports faster adoption of advanced therapies, while regional differences in approval pathways may delay industry entry. Compliance requirements enhance product credibility and shape development costs and timelines.
Substitution pressure is moderate, with some human ophthalmic drugs and general medications repurposed for veterinary use. Rising demand for species-specific formulations and targeted delivery systems is reducing reliance on these substitutes. The shift toward dedicated veterinary solutions enhances industry differentiation and lowers substitution risks.
Human pharmaceutical companies are increasingly entering veterinary ophthalmology by adapting advanced ocular drug-delivery technologies and biomaterials for animal use. Leveraging strong R&D in human eye care, they efficiently repurpose sustained-release systems and specialty formulations for pets. Many establish veterinary subsidiaries or partnerships to streamline industry entry, introducing higher-quality, innovation-driven products that elevate therapeutic standards and accelerate innovation in veterinary eye care.
Analyst Perspective
The veterinary ophthalmic drugs market is expected to maintain robust growth over the forecast period, supported by continuous innovation in ophthalmic formulations and the increasing integration of advanced diagnostics into routine veterinary practice. Pharmaceutical companies are focusing on the development of long-acting eye drops, preservative-free formulations, combination therapies, and targeted drug delivery systems to improve treatment efficacy, patient compliance, and clinical outcomes. In addition, the growing adoption of teleconsultation services and digital diagnostic technologies is enabling earlier identification and monitoring of ocular diseases, creating new opportunities for manufacturers to expand their product portfolios and strengthen their market presence.
However, market expansion is likely to face challenges associated with treatment adherence, product accessibility, and pricing pressures. Many ophthalmic disorders require prolonged or lifelong therapy with frequent administration of topical medications, which can reduce owner compliance and affect treatment outcomes. In addition, increasing competition from generic ophthalmic drugs is placing pressure on product pricing and margins, requiring manufacturers to differentiate through innovation and clinical evidence. Companies that invest in novel formulations, strategic collaborations with specialty veterinary clinics, and veterinarian education programs will be better positioned to address these challenges and capitalize on the growing demand for advanced veterinary eye care.
Animal Insights
Based on animal type, the canine segment led the market with the largest revenue share of 34.7% in 2025, driven by high disease prevalence in dogs, routine screening at clinics, and strong owner awareness of visible eye symptoms. Chronic dry eye, corneal ulcers, and age-linked degeneration need repeat therapy, so drug use remains steady throughout the year. Many dogs stay on lubricants, antibiotics, and anti-inflammatory drops for extended periods. Clinics invest in better diagnostics for canine eye care, and this raises treatment rates. These patterns keep demand broad across urban and rural regions.
The feline segment is emerging as the fastest-growing category in the market, fueled by rising cases linked to herpesvirus, allergy-driven irritation, and tear film instability. Cats often present subtle symptoms, so clinics rely on imaging and staining tools to raise detection. Owners act early when discharge or redness appears, and this boosts more treatment starts. Many cats live indoors, and this increases exposure to irritants that trigger eye problems. Chronic flare-ups need repeat therapy, so growth remains strong. More cat-specific formulations also help improve compliance.
Indication Insights
Based on indication, the uveitis segment led the market with the largest revenue share of 18.2% in 2025, driven by its links to trauma, immune disease, and systemic infections that affect many animal species. Recurrence is common, so patients come back for prolonged care. Clinics rely on steroids, antibiotics, and immune-acting drops to control inflammation. Many cases appear suddenly with pain or cloudiness, so vets begin treatment right away. Imaging helps reveal deeper inflammation that was once missed. These factors keep uveitis a high-volume condition across practices.
Conjunctivitis is emerging as the fastest-growing segment in the market, fueled by allergies, viral exposure, and irritants in homes and outdoor spaces. It is simple to identify, so case numbers rise as clinics screen pets more often. Treatment relies on antibiotics, lubricants, and anti-inflammatory drops that owners find easy to use. Sudden redness and discharge drive quick visits, and this supports early intervention. Recurrence in young and adult pets raises follow-up prescribing. These traits create strong growth across general practices.
Distribution Channel Insights
Based on distribution channel, veterinary hospitals & clinics segment led the market with the largest revenue share of 38.3% in 2025, because they manage examinations, imaging, procedures, and follow-up plans. Eye disorders often require direct evaluation, so most prescriptions originate in clinics. Specialists support complex surgeries and use advanced drugs that raise total volume. Clinics maintain full stock for immediate treatment. Repeat appointments keep drug flow consistent throughout the year. This setting remains the primary point of care for most pet owners.
 To learn more about this report, Download Free Sample Report
E-commerce is the fastest-growing market segment over the forecast period, driven by strong demand for easy refills and home delivery for chronic therapies. Online platforms offer a wide range of approved products with clear pricing. Auto-refill programs support pets with recurring dry eye or infection-linked conditions. Digital pharmacies expand access for owners in smaller towns. Simple ordering improves adherence to long-term treatment plans. These factors keep online sales rising across regions.
Drug Insights
Based on drug, the lubricants / artificial tears segment led the market with the largest revenue share of 26.0% in 2025 and is also expected to exhibit the fastest CAGR over the forecast period. This dominance is driven by their use in dry eye, irritation, and postoperative care across many species. These products are safe for long-term use, so they carry high refill rates in clinics. Older animals and flat-faced breeds need regular lubrication for comfort. Clinics hold a wide mix of gels, ointments, and extended-relief drops to support varied cases. These drugs play a significant role in healing after eye surgery. This broad and daily use keeps the category dominant across markets.
Other drugs (anesthetics, antifungals, anti-glaucoma, etc.) segment is the second-fastest growing over the forecast period, fueled by a steady rise in complex infections, fungal disease, and pressure-linked disorders. Corneal injuries also bolster the use of anesthetics and targeted antifungals. Glaucoma cases in dogs and cats often need lifelong pressure control. Early diagnosis improves as clinics adopt newer imaging tools. These conditions create long treatment cycles with high clinical dependency. Growth remains strong because these therapies support both routine and advanced care.
Regional Insights
North America dominated the veterinary ophthalmic drugs market with the largest revenue share of 41.1% in 2025, driven by strong pet ownership, high awareness of ocular disorders, and advanced veterinary infrastructure. The region benefits from the rapid adoption of specialty ophthalmic therapeutics, including anti-infectives, anti-inflammatories, and tear-replacement formulations. The growing prevalence of conditions such as keratoconjunctivitis sicca, cataracts, and glaucoma continues to stimulate product demand. Expanding pet insurance coverage further supports treatment accessibility. Increasing emphasis on early diagnosis and the availability of board-certified veterinary ophthalmologists also drives market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Ophthalmic Drugs Market Trends
The veterinary ophthalmic drugs market in the U.S. held the largest share in the North America region in 2025. The veterinary ophthalmic drugs market in the U.S. is evolving with rising demand for targeted ocular therapies, increasing chronic ocular disease burden, and heightened focus on companion animal wellness. Growth is supported by strong investments in specialty clinics and advanced diagnostic tools such as slit-lamp biomicroscopy and tonometry. Manufacturers are expanding portfolios with improved formulations, longer-acting drops, and combination therapies. Pet parents’ willingness to spend on premium care continues to elevate treatment uptake. Regulatory clarity and faster approval pathways for ophthalmic generics also shape market progression.
Europe Veterinary Ophthalmic Drugs Market Trends
The veterinary ophthalmic drugs market in Europe is expanding, fueled by high veterinary care standards, increasing treatment rates for ocular infections, and widespread adoption of companion animals. Strong regulatory emphasis on product quality and safety enhances trust in ophthalmic therapeutics. Demand is rising for anti-inflammatory agents and ocular lubricants, particularly for aging pets and brachycephalic breeds. Growth in veterinary insurance penetration across Western Europe further supports market performance. Expansion of cross-border distribution networks is also streamlining product availability.
The UK veterinary ophthalmic drugs market is gaining momentum, driven by the rising prevalence of hereditary ocular disorders, strong clinical expertise, and active adoption of advanced treatment regimens. Increased awareness of pet eye health is prompting earlier diagnosis and intervention. The presence of leading veterinary ophthalmology practices contributes to higher procedural volumes. Growth in pet insurance coverage supports the affordability of long-term therapies. Market demand is also boosted by an expanding aging pet population requiring chronic ophthalmic management.
Asia Pacific Veterinary Ophthalmic Drugs Market Trends
The veterinary ophthalmic drugs market in the Asia Pacific is the fastest-growing region over the forecast period, driven by rising pet ownership, expanding urban veterinary networks, and increasing awareness regarding ocular diseases. Countries such as China, Japan, and South Korea are witnessing significant growth in specialized care adoption. Manufacturers are broadening distribution across emerging markets to address previously underserved demand. Economic growth and rising disposable incomes support higher spending on companion animal therapeutics. The increasing incidence of infections and trauma-related ocular disorders further accelerates market uptake.
India veterinary ophthalmic drugs market is expanding, driven by rising companion animal adoption, growing veterinary infrastructure, and increased recognition of ocular conditions. Market growth is supported by more veterinarians adopting modern ophthalmic diagnostics and therapeutics in urban regions. Demand for antibiotics, lubricants, and anti-inflammatory formulations is increasing steadily. The growing presence of multinational and domestic brands is improving market accessibility. Educational initiatives by veterinary associations are also enhancing clinical management capabilities.
Latin America Veterinary Ophthalmic Drugs Market Trends
The veterinary ophthalmic drugs market in Latin America is growing, driven by improving veterinary healthcare access, rising awareness of pet eye diseases, and expanding pet care spending in key markets. Increased penetration of private veterinary clinics is enhancing the availability of ophthalmic treatments. The market is also benefiting from improvements in supply chain and distribution networks. The growing demand for anti-infective and supportive ocular therapies is particularly notable. Increasing adoption of premium pet care services is further propelling market growth.
Brazil veterinary ophthalmic drugs market is expanding, driven by strong pet population growth, increased clinical adoption of ophthalmic diagnostics, and rising awareness of early eye disease management. Demand for antibiotics, lubricants, and anti-inflammatory drops is growing rapidly. High prevalence of ocular infections among dogs in tropical climates also supports market demand. Improved access to specialty veterinary care is enabling faster adoption of advanced products. Growing investments by domestic and international manufacturers are strengthening market competitiveness.
Middle East & Africa Veterinary Ophthalmic Drugs Market Trends
The veterinary ophthalmic drugs market in the MEA is gaining traction, fueled by growing demand for companion animal care, increasing establishment of specialized clinics, and rising focus on preventive ophthalmology. Countries like the UAE and Saudi Arabia are witnessing significant adoption of advanced formulations. Higher disposable incomes are contributing to a greater willingness to invest in premium ocular treatments. Market penetration is improving due to the expansion of international veterinary brands. Rising awareness of breed-specific ocular issues is further driving demand.
South Africa veterinary ophthalmic drugs market is expanding, driven by rising pet care expenditure, growing recognition of ocular disorders, and improving availability of specialty veterinary services. Increased uptake of treatments for infections, corneal injuries, and chronic inflammatory conditions is supporting growth. Veterinary associations are promoting awareness of preventive ophthalmic care among pet owners. Distribution of ophthalmic therapeutics is improving through retail and clinic-based channels. Growth is further supported by increasing demand for advanced diagnostic procedures.
The veterinary ophthalmic drugs market in Saudi Arabia is expanding, driven by rising demand for companion animal services, strong investments in veterinary infrastructure, and growing adoption of specialized ophthalmic treatments. Increased pet ownership among urban households is stimulating demand for ocular care products. Clinics are increasingly equipped with advanced diagnostics, leading to better detection of chronic diseases. Government support for the veterinary sector development is improving product accessibility. Rising preference for premium and imported drugs further boosts market growth.
Key Veterinary Ophthalmic Drugs Company Insights
The market is moderately concentrated, with Merck & Co., Zoetis, Dechra Pharmaceuticals, and Virbac holding leading positions through broad portfolios and global reach. Specialty ophthalmic manufacturers, compounding pharmacies, and technology-driven entrants capture smaller but growing shares, supporting innovation and limiting market consolidation. Companies investing in sustained-release carriers, AI-assisted diagnostics, and human-pharma crossovers are gaining a competitive advantage, while regulatory compliance and strategic M&A further influence market positioning and growth.
Key Veterinary Ophthalmic Drugs Companies:
The following key companies have been profiled for this study on the veterinary ophthalmic drugs market.
- Merck & Co. Inc.
- Zoetis
- Dechra Pharmaceuticals
- Virbac
- Ceva Santé Animale
- Elanco
- Bausch & Lomb
- Sandoz
- Norbrook Laboratories
- I-Med Animal Health
- Dômes Pharma, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players(Merck & Co. Inc.; Zoetis; Dechra Pharmaceuticals; Virbac; Ceva Santé Animale; Elanco; Bausch & Lomb; Sandoz)
- Leading companies emphasize expanding their veterinary ophthalmology portfolios through anti-infectives, corticosteroids, lubricants, NSAIDs, and combination therapies. They strengthen their market position by investing in ophthalmic R&D, strategic acquisitions, collaborations with veterinary hospitals, regulatory approvals, specialty product launches, and global distribution expansion while enhancing veterinarian education programs and digital engagement initiatives.
- Established vendors benefit from diversified animal health portfolios, extensive regulatory expertise, well-established relationships with veterinary hospitals and distributors, broad geographic presence, and strong financial resources. Their ability to continuously introduce innovative formulations, leverage global manufacturing capabilities, and maintain robust brand recognition enables sustained market leadership.
- Large companies often face lengthy product development cycles, stringent regulatory requirements, increasing competition from generic ophthalmic drugs, pricing pressure from veterinary purchasing groups, and high costs associated with clinical studies and product commercialization. Managing portfolio differentiation while maintaining profitability remains a significant challenge.
Emerging Players(I-Med Animal Health; Dômes Pharma, Inc.; regional veterinary ophthalmic drug manufacturers)
- Emerging companies primarily focus on niche ophthalmic therapies, preservative-free formulations, specialized lubricants, and cost-effective eye care solutions. They expand through regional partnerships, contract manufacturing, online veterinary pharmacies, distributor collaborations, and targeted product launches addressing unmet clinical needs in companion animals.
- These companies compete through product specialization, faster innovation cycles, flexible manufacturing capabilities, competitive pricing, and the ability to address underserved regional markets. Their focused product development enables quicker response to changing clinical requirements and evolving veterinary treatment practices.
- Emerging manufacturers generally have limited commercial reach, lower brand visibility, restricted R&D budgets, smaller sales networks, and fewer regulatory resources than multinational competitors. Scaling manufacturing capacity, expanding international approvals, and establishing veterinarian confidence remain key barriers to broader market penetration.
Recent Developments
-
In January 2026, Dômes Pharma partnered with the International Society of Veterinary Ophthalmology (ISVO) to sponsor the Dômes Pharma‑ISVO Travel Scholarship, funding three travel awards in 2026 to support emerging veterinary ophthalmologists’ training at centers of excellence.
-
In January 2026, Hagyard Equine Medical Institute announced expansion plans for its equine‑only ophthalmology services beyond central Kentucky, starting in 2026, to address a shortage of board‑certified equine ophthalmologists and reduce long wait times for specialized eye care for horses. The expansion will increase access to advanced diagnostics and surgical treatments for a wide range of equine ocular conditions and support growth in specialist equine eye care.
-
In October 2025, Tata 1mg launched a new pet medicines and supplements service, leveraging its existing pharmacy app and delivery infrastructure to reach 22,000 pincodes across India. It plans to serve prescription-led pet care, food, and grooming needs without building a separate app.
Veterinary Ophthalmic Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.2 billion
Projected market size by 2033
USD 3.6 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug, animal type, indication, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Merck & Co. Inc.; Zoetis; Dechra Pharmaceuticals; Virbac; Ceva Santé Animale; Elanco; Bausch & Lomb; Sandoz; Norbrook Laboratories; I-Med Animal Health; Dômes Pharma, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Ophthalmic Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary ophthalmic drugs market report based on animal, drug, indication, distribution channel, and region
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Canine
-
Feline
-
Equine
-
Bovine
-
Others
-
-
Drug Outlook (Revenue, USD Million, 2021 - 2033)
-
Antibiotics
-
NSAIDs
-
Corticosteroids
-
Lubricants / Artificial Tears
-
Analgesics / Pain Relievers
-
Others Drugs
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Eyelid Abnormalities
-
Cataract
-
Glaucoma
-
Retinal Complications
-
Uveitis
-
Conjunctivitis
-
Corneal Complications
-
Other Indications
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Specialty Stores
-
E-Commerce
-
Other Distribution Channels
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
India
-
China
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
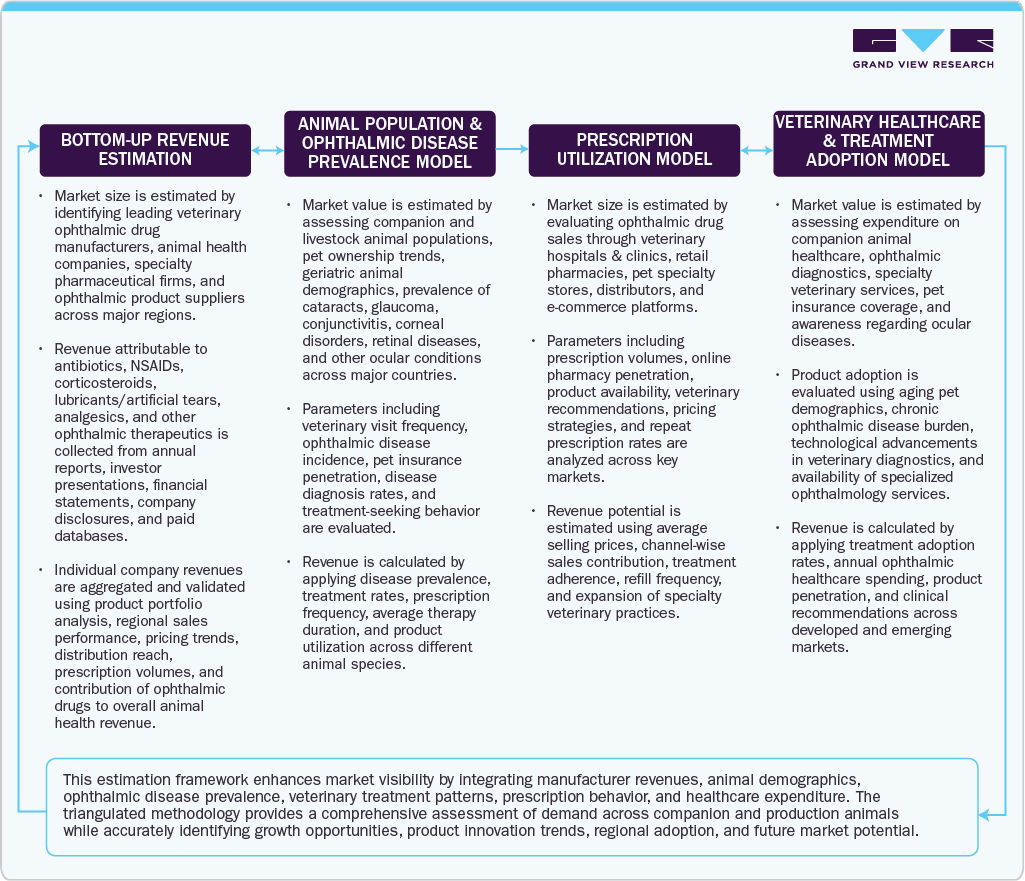
The veterinary ophthalmic drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary ophthalmic drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug
Revenue Capture Definition
Antibiotics
Revenue derived from ophthalmic antibiotic formulations prescribed for the treatment and prevention of bacterial eye infections in animals.
NSAIDs
Revenue earned from non-steroidal anti-inflammatory ophthalmic drugs used to reduce ocular inflammation, pain, and postoperative complications in veterinary patients.
Corticosteroids
Revenue generated from corticosteroid-based ophthalmic medications utilized for managing inflammatory and immune-mediated eye conditions in animals.
Lubricants / Artificial Tears
Revenue contributed by ophthalmic lubricants and artificial tear products used to relieve dry eye syndrome and maintain ocular surface health in animals.
Analgesics / Pain Relievers
Revenue generated from ophthalmic pain-relieving medications administered to alleviate ocular discomfort associated with eye diseases, trauma, or surgical procedures.
Other Drugs
Revenue derived from other veterinary ophthalmic therapeutics, including antivirals, antifungals, immunomodulators, mydriatics, and combination formulations used in ocular disease management.
Segment - Animal Type
Revenue Capture Definition
Canine
Revenue earned from ophthalmic drugs prescribed for the treatment of ocular diseases affecting dogs.
Feline
Revenue generated from veterinary ophthalmic therapeutics used in the management of eye disorders in cats.
Equine
Revenue derived from ophthalmic medications administered for the treatment of ocular diseases and injuries in horses.
Bovine
Revenue contributed by veterinary ophthalmic drugs used for preventing and treating eye conditions in cattle.
Other Animal Type
Revenue generated from ophthalmic therapeutics used in birds, small mammals, livestock species, exotic animals, and other animals not included in the above categories.
Segment - Indication
Revenue Capture Definition
Eyelid Abnormalities
Revenue derived from ophthalmic drugs used in the management of eyelid disorders such as entropion, ectropion, blepharitis, and related conditions.
Cataract
Revenue earned from ophthalmic medications prescribed for the management of cataract-associated complications and perioperative eye care.
Glaucoma
Revenue generated from ophthalmic therapeutics used to reduce intraocular pressure and manage glaucoma in animals.
Retinal Complications
Revenue contributed by ophthalmic drugs utilized in the treatment and supportive management of retinal diseases and associated vision disorders.
Uveitis
Revenue generated from ophthalmic medications used to control inflammation of the uveal tract and prevent vision-threatening complications.
Conjunctivitis
Revenue derived from ophthalmic drugs indicated for the treatment of bacterial, viral, allergic, and inflammatory conjunctivitis in animals.
Corneal Complications
Revenue earned from ophthalmic therapeutics used to treat corneal ulcers, keratitis, corneal injuries, and other corneal disorders.
Others
Revenue generated from ophthalmic drugs used for the management of other ocular diseases and conditions not included in the above indications.
Segment - Distribution Channel
Revenue Capture Definition
Veterinary Hospitals & Clinics
Revenue derived from ophthalmic drugs dispensed and administered through veterinary hospitals, specialty eye clinics, and general veterinary practices.
Pet Specialty Stores
Revenue earned from veterinary ophthalmic products sold through pet specialty retail outlets offering prescription and over-the-counter eye care products.
E-Commerce
Revenue generated from online sales of veterinary ophthalmic drugs through digital pharmacies, e-commerce platforms, and manufacturer-owned websites.
Others
Revenue contributed by ophthalmic drugs distributed through wholesalers, distributors, agricultural supply stores, and other alternative sales channels.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Veterinary Ophthalmic Treatment Landscape & Market Assessment
Conducted a comprehensive assessment of the veterinary ophthalmic ecosystem by evaluating pharmaceutical manufacturers, specialty veterinary clinics, ophthalmic drug portfolios, distribution channels, regulatory environment, and disease burden across companion and production animals. Assessed drug classes, treatment protocols, diagnosis rates, pricing dynamics, reimbursement trends, and regional adoption patterns.
Provides actionable insights into market size, growth drivers, treatment trends, competitive positioning, and investment opportunities, enabling stakeholders to identify high-growth therapeutic segments and regional expansion strategies.
Competitive Product Benchmarking & Innovation Assessment
Performed benchmarking of leading veterinary ophthalmic drug manufacturers based on product portfolio breadth, formulation innovation, regulatory approvals, clinical efficacy, pricing strategy, distribution reach, partnerships, and commercialization initiatives. Evaluated competitive differentiation across antibiotics, corticosteroids, NSAIDs, lubricants, and combination therapies.
Enables companies to compare competitive positioning, identify product portfolio gaps, evaluate innovation strategies, strengthen commercialization plans, and uncover licensing, partnership, or acquisition opportunities.
Disease Burden & Commercial Opportunity Analysis
Evaluated commercial opportunities by assessing prevalence of ocular disorders, aging pet demographics, treatment adoption, specialty veterinary infrastructure, pet healthcare expenditure, and prescription trends. Identified high-potential therapeutic indications and recommended market entry and expansion strategies based on regional demand and clinical adoption.
Supports strategic decision-making for product development, market prioritization, portfolio expansion, and resource allocation by identifying attractive disease segments and emerging revenue opportunities.
Frequently Asked Questions About This Report
The lubricants/artificial tears segment led with a 26.0% revenue share in 2025.
Canine held the largest revenue share 34.7% in 2025.
Uveitis held the largest share 18.2% in 2025 and conjunctivitis is the fastest-growing market.
Asia Pacific is the fastest-growing region over the forecast period.
The global veterinary ophthalmic drugs market size was valued at USD 2.1 billion in 2025 and is expected to reach USD 2.2 billion in 2026.
The global veterinary ophthalmic drugs market is expected to grow at a compound annual growth rate of 7.1% from 2026 to 2033 to reach USD 3.6 billion by 2033.
North America dominated with a 41.1% revenue share in 2025.
Some key players operating in the veterinary ophthalmic drugs market include Merck & Co. Inc., Zoetis, Dechra Pharmaceuticals, Virbac, Ceva Santé Animale, Elanco, Bausch & Lomb, Sandoz, Norbrook Laboratories, I-Med Animal Health, and Dômes Pharma, Inc.
Some of the factors driving the market growth are advancements in ophthalmic drug-delivery technologies, rising development of long-acting ophthalmic therapies, increasing focus on antimicrobial stewardship & evidence-based use, and growing clinical demand for treatment of complex ocular diseases.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


