
- Home
- »
- Sustainable Energy
- »
-
Voluntary Carbon Credit Market Size Report, 2026-2033GVR Report cover

Voluntary Carbon Credit Market (2026 - 2033)
Size, Share & Trends Analysis Report By Project (Renewable Energy, Energy Efficiency), By Application (Industrial, Energy), By End-use (Private Companies, Government Agencies), By Region, And Segment Forecasts
Market Size, 2025
$5.3BMarket Estimate, 2026
$7.4BMarket Forecast, 2033
$52.4BCAGR, 2026–2033
32.2%Voluntary Carbon Credit Market Summary
The global voluntary carbon credit market size was valued at USD 5.3 billion in 2025 and is projected to grow from USD 7.4 billion in 2026 to USD 52.4 billion by 2033, at a CAGR of 32.2% from 2026 to 2033. The market in North America dominated with a revenue share of 37.0% in 2025. The market growth is driven by companies pledging to achieve net-zero emissions and the need for offsets to compensate for emissions that cannot be fully eliminated.
Key Market Trends & Insights
- By end use: Private companies segment held the largest market share of 62.1% in 2025.
- By project: Renewable energy segment held the largest market share of 39.1% in 2025.
- By application: Industrial segment held the largest market share of 32.2% in 2025.
Regional Highlights
- Largest regional market: North America (37.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.3 Billion
- Estimated market size in 2026: USD 7.4 Billion
- Projected market size by 2033: USD 52.4 Billion
- CAGR (2026-2033): 32.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is expected to shift from focusing on reducing emissions to removing them altogether, with removal credits expected to account for 35% of the market by 2030. The growth of the voluntary carbon market is also driven by the increasing importance of carbon credits in achieving sustainability goals, with companies and governments recognizing the need for credible incentives for emissions reductions. The market is expected to continue to evolve, with the focus on quality and verifiability of credits becoming increasingly important.
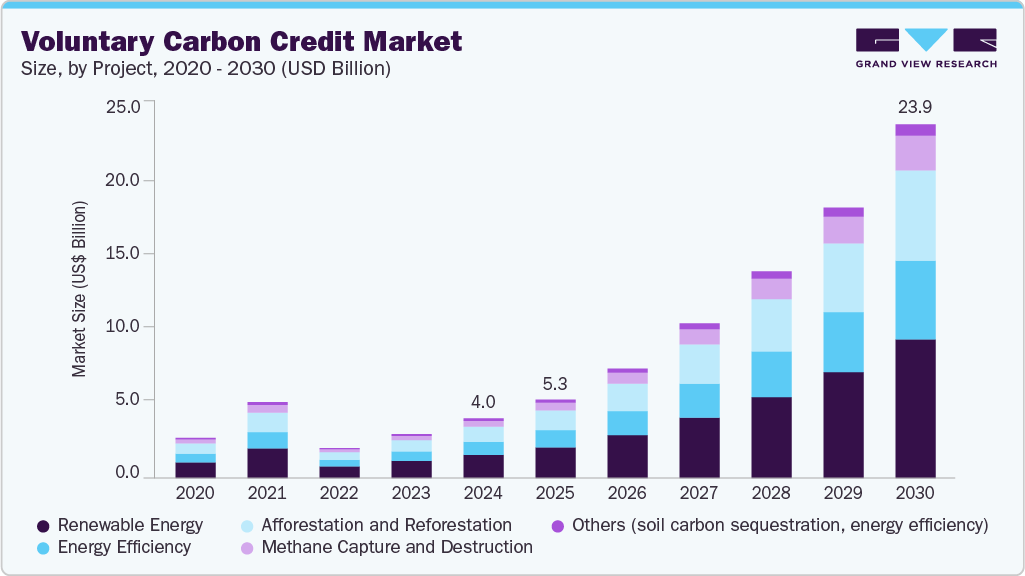 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Corporate net-zero commitments are a major driver of the growth in the voluntary carbon credit market. As companies pledge to achieve net-zero emissions, they are increasingly turning to the voluntary carbon market to offset the emissions they cannot fully eliminate through their own decarbonization efforts.This surge in demand is driven by the urgency for companies to act on climate change and demonstrate their commitment to sustainability. The voluntary carbon market provides a mechanism for companies to compensate for their residual emissions and contribute to global emissions reduction efforts.
The voluntary carbon credit market offers several opportunities for companies and individuals to reduce their carbon footprint and contribute to a more sustainable future. The market allows for the purchase and sale of carbon credits, which represent the reduction or removal of one tonne of carbon dioxide or its equivalent from the atmosphere.Key opportunities in the voluntary carbon credit market include the development of new carbon offset projects, the growth of carbon trading platforms, and the increasing adoption of carbon credits by companies and governments.
Market Dynamics
The voluntary carbon credit market is primarily driven by the increasing adoption of corporate sustainability initiatives and net-zero emission commitments across industries. Voluntary carbon credits enable organizations to offset unavoidable greenhouse gas emissions by supporting projects that reduce, remove, or avoid carbon emissions, including reforestation, renewable energy, soil carbon sequestration, and carbon capture initiatives. Growing pressure from investors, consumers, and regulatory bodies to improve environmental performance, coupled with the expansion of ESG programs, rising participation from financial institutions, and advancements in carbon monitoring and verification technologies, is supporting market growth and driving demand for high-quality carbon credits worldwide.
The increasing adoption of net-zero emission targets and corporate sustainability strategies remains a key growth driver for the voluntary carbon credit market. Organizations across industries are increasingly utilizing carbon credits to offset residual emissions while pursuing long-term decarbonization goals. Growing pressure from investors, consumers, and regulatory stakeholders to demonstrate measurable climate action is accelerating participation in voluntary carbon markets and supporting demand for verified carbon offset projects.
Furthermore, the expansion of ESG reporting frameworks and sustainability disclosure requirements is encouraging companies to integrate carbon offsetting into broader environmental strategies. Businesses are increasingly seeking high-quality carbon credits to enhance climate credentials, strengthen corporate reputation, and meet sustainability commitments, which continues to drive market growth worldwide.
Despite favorable growth prospects, concerns surrounding the quality, additionality, permanence, and verification of carbon credit continue to pose challenges for market participants. Variations in project standards and carbon accounting methodologies can create uncertainty regarding the environmental impact of certain credits, while increasing scrutiny from regulators, investors, and environmental organizations may affect buyer confidence and limit broader market adoption.
The growing preference for high-integrity carbon removal projects, including afforestation, reforestation, biochar, and direct air capture initiatives, presents significant growth opportunities for the voluntary carbon credit market. In addition, advancements in digital monitoring, reporting, and verification technologies are improving transparency and credibility across carbon markets, enabling more efficient transactions and creating new avenues for market expansion over the forecast period.
Market Concentration & Characteristics
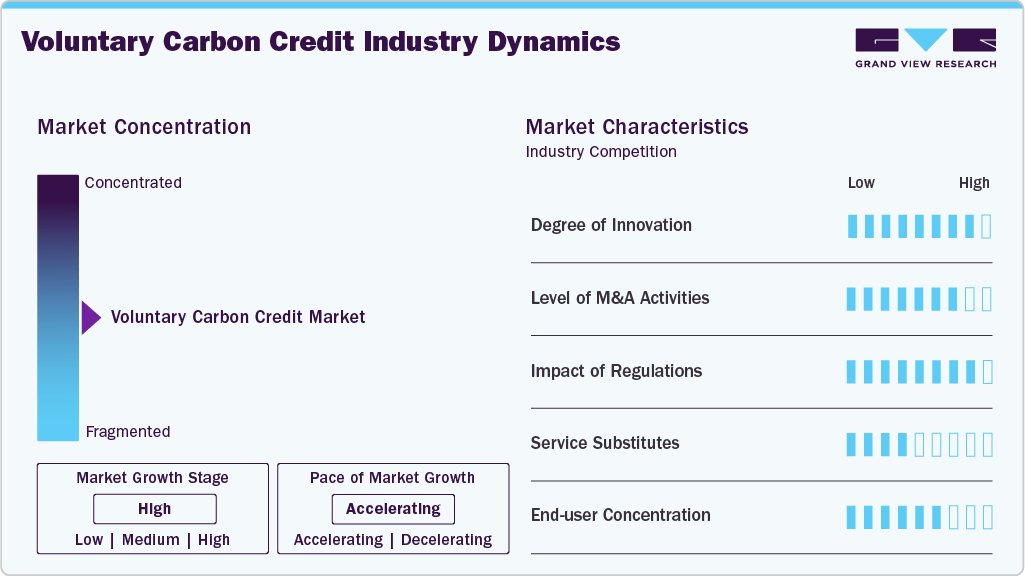
The voluntary carbon credit market is moderately fragmented, with a combination of global carbon registries, climate advisory firms, project developers, trading platforms, and sustainability solution providers competing. The market is witnessing growth driven by rising corporate net-zero commitments, expanding ESG disclosure requirements, and increasing investments in climate mitigation initiatives worldwide. Strategic partnerships and collaborations are becoming common as companies aim to strengthen carbon project portfolios, expand geographic reach, and enhance digital monitoring. Continuous investments in blockchain-enabled traceability systems, AI-powered carbon accounting platforms, and high-integrity carbon removal projects are becoming competitive strategies within the voluntary carbon credit market.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by growing adoption of engineered carbon removal technologies, satellite-based environmental monitoring, and blockchain-integrated carbon trading platforms. The industry is experiencing moderately high merger and acquisition activities as climate technology firms, registries, and sustainability consultancies pursue portfolio expansion. Competition from substitute decarbonization approaches remains moderate, as organizations continue relying on voluntary offsets for unavoidable emissions across hard-to-abate sectors. Increasing investments in nature-based solutions, direct air capture technologies, and community-driven sustainability projects are expected to continue supporting the accelerating growth trajectory of the voluntary carbon credit market.
Analyst Perspective
The voluntary carbon credit market is experiencing strong growth, driven by rising corporate net-zero commitments, expanding ESG initiatives, and increasing demand for carbon offset solutions across industries. Rising pressure from investors, consumers, and regulatory stakeholders is encouraging organizations to invest in carbon credit generated from renewable energy, afforestation and reforestation, methane capture, and other carbon reduction and removal projects. While concerns regarding credit quality, transparency, and evolving verification standards remain key challenges, advancements in monitoring, reporting, and verification technologies are improving market credibility and transaction efficiency. The growing demand for high-integrity carbon removal projects and the increasing participation of financial institutions are creating new opportunities across the carbon value chain. In the coming years, companies that can provide high-quality carbon credits, strengthen project verification capabilities, and expand access to scalable carbon-reduction and removal projects are expected to improve their competitive position in the market.
Project Insights
The renewable energy segment led the market with the largest revenue share of 39.1% in 2025. Based on the project, the voluntary carbon credit market has been segmented into Renewable Energy, Energy Efficiency, Afforestation and Reforestation, Methane Capture and Destruction, and Others (soil carbon sequestration, energy efficiency).
Renewable energy dominated the voluntary carbon credit market with a revenue share of over 39.09% in 2024. This growth is driven by the increasing pressure on companies to reduce their carbon footprint and meet the ambitions of the Paris Agreement. Renewable energy projects, such as solar and wind farms, are a key area of focus for carbon credits, as they help support the cost of developing clean energy sources and make them more affordable. Carbon credits can also provide additional revenue streams for project developers, promoting the adoption of clean energy technologies.
Methane capture and destruction is expected to grow at a significant CAGR of 31.6% during the forecast period. The demand for voluntary carbon credits in Methane Capture and Destruction projects is significant, driven by the urgent need to reduce greenhouse gas emissions. Methane, a potent greenhouse gas, is produced and emitted by various sources, including landfills, agricultural activities, and coal mining.
Application Insights
Based on Application, the voluntary carbon credit market is segmented into industrial, household devices, energy, agriculture, and others. The industrial segment accounted for the highest revenue share of 32.2% in 2025. Industrial companies are increasingly looking to offset their emissions through carbon credits, which represent the reduction or removal of one tonne of carbon dioxide or its equivalent from the atmosphere. The demand for carbon credits in industrial applications is driven by the need to reduce emissions from various industrial processes, such as energy consumption, transportation, and manufacturing.
Household Devices is expected to grow at a significant CAGR of 32.5% in the coming years. Energy applications are a key driver of voluntary carbon credit market growth. Companies are investing in renewable energy projects like wind and solar farms that generate credits, while others purchase credits to offset emissions from traditional energy sources. This trend fuels both clean energy development and emissions reduction efforts.
End Use Insights
Based on end use, the voluntary carbon credit market is segmented into government agencies, non-governmental organizations (NGOs), private companies, and individuals. Private Companies dominated the voluntary carbon credit market and accounted for a share of over 62.1% in 2025. The private companies in the voluntary carbon credit market are driven by several factors. Firstly, the growing demand for corporate sustainability initiatives and net-zero targets is a significant driver. Companies are looking to offset their emissions through high-quality credits that align with their environmental and social goals. Secondly, the increasing adoption of carbon credits by governments and regulatory bodies is also driving the market.
The individual segment emerged as fastest-growing segment with a CAGR of 34.7%. Individuals can participate by purchasing carbon credits to offset their flights, energy consumption, or other activities that generate significant emissions. This can be done through various platforms, such as carbon offset programs offered by airlines or companies. The market is driven by the desire to reduce carbon emissions and support sustainable projects, with many individuals seeking to make a positive impact on the environment.
Regional Insights
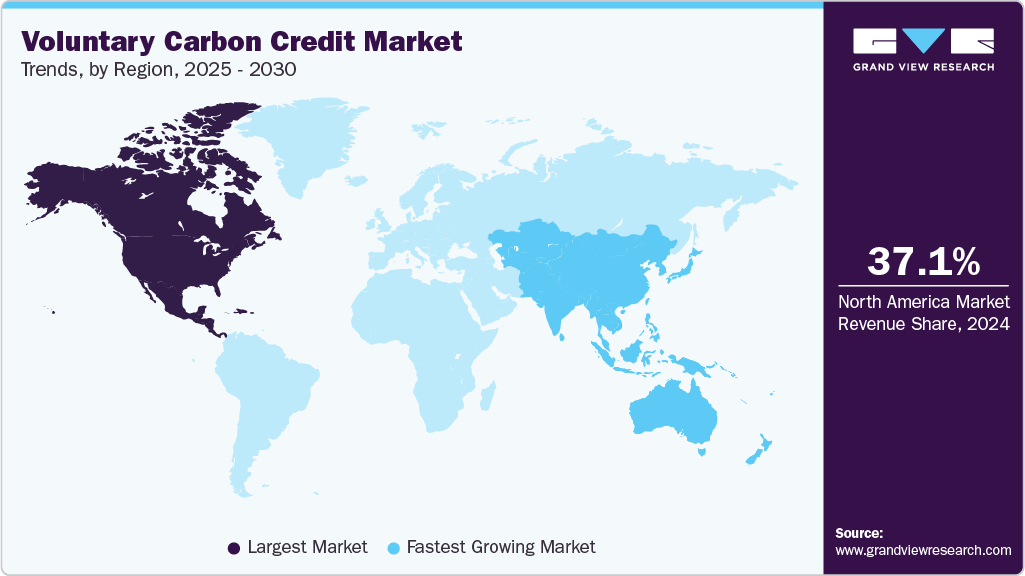
North America dominated the voluntary carbon credit market with the largest revenue share of 37.0% in 2025. The North America market is experiencing significant growth, driven by increasing demand for carbon offsetting and the need for companies to meet their sustainability goals.
 To learn more about this report, Download Free Sample Report
U.S. Voluntary Carbon Credit Market Trends
The voluntary carbon credit market in the U.S. held the largest share in North America region in 2025. The surge in demand is largely attributed to companies and individuals seeking to reduce their carbon footprint and contribute to climate change mitigation efforts.
The voluntary carbon credit market in Canada is expected to grow at the fastest CAGR of 35.4%. The demand for carbon credits in Canada's voluntary carbon market (VCM) has grown significantly, driven by increasing corporate and individual demand for carbon offsetting.
Europe Voluntary Carbon Credit Market Trends
The European voluntary carbon credit market has seen significant growth, driven by strong demand from corporate buyers seeking high-quality credits.
The voluntary carbon credit market in Germany accounted for largest share of over 27.2% in 2025. The market is driven by strong demand from German corporates seeking to offset their emissions and meet their sustainability goals.
Spain voluntary carbon credit market is expected to progress with a CAGR of 36.8% over the forecast period. The Spanish voluntary carbon credit market is growing, driven by increasing demand from corporations and government initiatives. Nature-based credits, particularly forestry and land-use projects, are in high demand due to their ability to sequester carbon and offer co-benefits like biodiversity conservation and ecosystem restoration.
Asia Pacific Voluntary Carbon Credit Market Trends
The voluntary carbon credit market in Asia Pacific is expected to grow at the highest CAGR over the forecast period. The voluntary carbon credit market in Asia Pacific is driven by government initiatives and corporate sustainability goals, with forestry and land-use projects emerging as pivotal players in carbon sequestration and ecological benefits.
China voluntary carbon credit market is projected to grow at a significant rate. The market aims to supplement China's compulsory Emissions Trading Scheme (ETS) and support the country's goal of peaking carbon emissions by 2030 and achieving net-zero emissions by 2060.
The voluntary carbon credit market in India held a significant share in 2025, accounting for a share of over 15.0%. India's voluntary carbon credit market is expected to grow significantly, driven by increasing corporate demand for sustainability initiatives and favorable government policies.
Central & South America Voluntary Carbon Credit Market Trends
The voluntary carbon credit market in Brazil accounted for the largest share of 49.3% in 2025 in the region. The Central & South America voluntary carbon credit market is projected to grow at a significant rate over the forecast period. The market is expected to emerge as a significant player in the global carbon credit market, driven by increasing demand and favorable policies.
The voluntary carbon credit market in Brazil accounted for the largest share of 49.4% in 2024 in the region. The country is a leader in this market due to its vast forests and renewable energy projects.
Middle East & Africa Voluntary Carbon Credit Market Trends
The Middle East & Africa voluntary carbon credit marketis expected to grow at a significant rate. The Middle East and Africa's voluntary carbon market is on the rise, fueled by initiatives like the UAE's $450 million commitment to African credits and the first-ever regional auction in Saudi Arabia.
Key Voluntary Carbon Credit Company Insights
The voluntary carbon credit market is becoming increasingly competitive, with leading players like South Pole, Verra, and Gold Standard differentiating themselves through high-integrity projects, robust certification standards, and transparent reporting to meet growing corporate demand for credible offsets. Emerging competitors are leveraging innovative technologies like blockchain (e.g., Toucan, KlimaDAO) and AI-driven monitoring to enhance traceability and reduce risks of double-counting, while nature-based solutions (e.g., reforestation, REDD+) and engineered removals (e.g., DAC, biochar) dominate premium-priced segments.
Key Voluntary Carbon Credit Companies:
The following key companies have been profiled for this study on the voluntary carbon credit market.
-
Ecosecurities
-
BioCarbon Partners
-
BURN Manufacturing
-
Biofílica Ambipar
-
Indus Delta Capital Limited
-
Terrasos
-
EKI Energy Services Ltd. (formerly EnKing International)
-
3Degrees
-
Climate Impact Partners
-
EcoAct
-
AB Verra
-
Puro.earth
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., South Pole, 3Degrees, Inc., Climate Impact Partners, EcoAct SAS, EcoSecurities Group Limited)
- Focus on large-scale carbon credit origination, project development, brokerage, and climate advisory services supported by global project portfolios and corporate customer networks.
- Emphasize high-quality carbon credits, project verification, sustainability consulting, and long-term partnerships with corporations pursuing net-zero and ESG objectives.
- Benefit from established market credibility, diversified carbon credit portfolios, strong relationships with project developers, and extensive global customer bases.
- Broad geographic presence and technical expertise support access to premium carbon projects and large-scale transaction opportunities.
- Face increasing scrutiny regarding carbon credit quality, transparency, and project integrity across voluntary carbon markets.
- Profitability may be affected by fluctuations in carbon credit prices, evolving regulatory frameworks, and changing corporate sustainability spending patterns.
Emerging & Specialized Players (e.g., EKI Energy Services Ltd., Xpansiv Limited, ClimeCo LLC, BioCarbon Partners Group Ltd., Carbon Direct, Inc.)
- Focus on specialized carbon market solutions, digital trading platforms, nature-based carbon projects, carbon asset management, and science-based decarbonization services.
- Emphasize technological innovation, project-specific expertise, advanced carbon analytics, and targeted market expansion strategies.
- Benefit from operational agility, specialized service offerings, and the ability to address evolving customer requirements across carbon removal, nature-based solutions, and environmental commodity markets.
- Flexible business models support faster innovation, technology adoption, and responsiveness to emerging market opportunities.
- Limited scale, project portfolios, and geographic reach compared to larger industry participants.
- Expansion often requires significant investments in project development, technology infrastructure, carbon credit sourcing, and customer acquisition capabilities.
Recent Developments
- In April 2025, Microsoft secured a major agreement with BTG Pactual TIG for 8 million carbon removal credits, the largest deal of its kind. The company also boosted its soil carbon efforts by buying 40,000 verified credits from Indigo Ag. Both actions support Microsoft's target to become carbon negative by 2030.
-
In June 2024, RVCMC hosted Nairobi's largest voluntary carbon credit auction, selling over 2.2 million tonnes. The credits were sourced from 18 regional projects focused on emission reductions and removals. Key buyers included Aramco, ENOWA, and Saudi Electricity Company.
-
In April 2024, Saudi PIF-backed RVCMC partnered with Xpansiv to launch a new carbon credit exchange platform. The move aims to improve transparency and direct climate finance to underserved regions.
Voluntary Carbon Credit Market Report Scope
Report Attribute
Details
Market definition
The global Voluntary Carbon Credit Market refers to the revenue generated from the trading and sale of carbon credit created through projects that reduce, remove, or avoid greenhouse gas emissions. These credits are purchased voluntarily by corporations and other organizations to offset emissions and support sustainability and climate goals.
Market size in 2025
USD 5.3 billion
Estimated market size in 2026
USD 7.4 billion
Projected market size by 2033
USD 52.4 billion
Growth rate
CAGR of 32.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Project, application, end-use, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, France, UK, Italy, Spain, Netherlands, China, India, Japan, South Korea, Australia, Indonesia, Malaysia, Brazil, Argentina, Saudi Arabia, South Africa, UAE
Key companies profiled
South Pole, 3Degrees, Inc., Climate Impact Partners, EcoAct SAS, EcoSecurities Group Limited, EKI Energy Services Ltd., Xpansiv Limited, ClimeCo LLC, BioCarbon Partners Group Ltd., Carbon Direct, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Voluntary Carbon Credit Market Report Segmentation
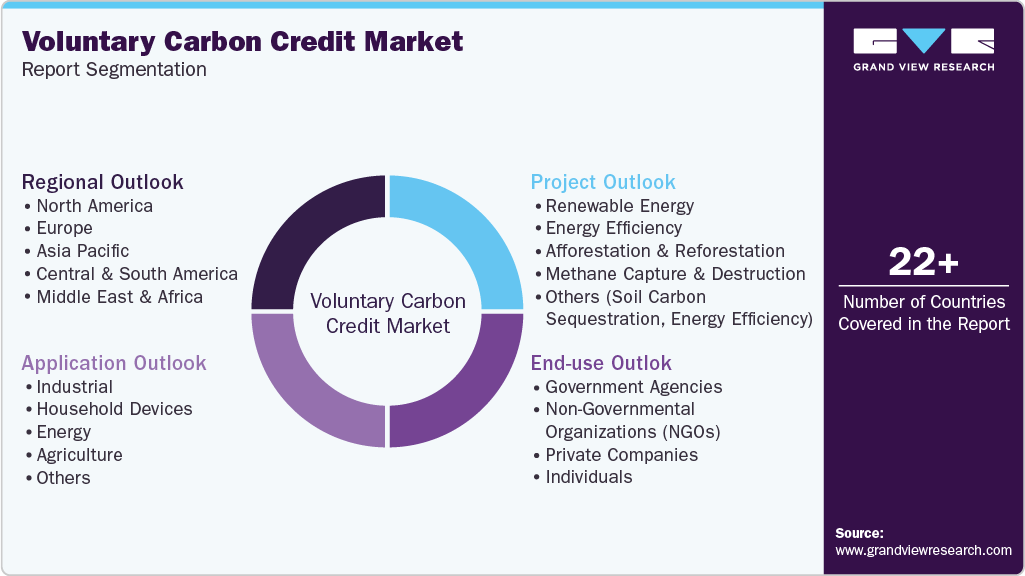
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global voluntary carbon credit market report based on project, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Project Outlook (Volume, Million Tons; Revenue, USD Million, 2021 - 2033)
-
Renewable Energy
-
Energy Efficiency
-
Afforestation and Reforestation
-
Methane Capture and Destruction
-
Others (soil carbon sequestration, energy efficiency)
-
-
Application Outlook (Volume, Million Tons; Revenue, USD Million, 2021 - 2033)
-
Industrial
-
Household Devices
-
Energy
-
Agriculture
-
Others
-
-
End Use Outlook (Volume, Million Tons; Revenue, USD Million, 2021 - 2033)
-
Government Agencies
-
Non-Governmental Organizations (NGOs)
-
Private Companies
-
Individuals
-
-
Regional Outlook (Volume, Million Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
Netherlands
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Indonesia
-
Malaysia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The voluntary carbon credit market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each voluntary carbon credit segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Project
Revenue Capture Definition
Renewable Energy
This segment includes carbon credits generated by renewable energy projects, such as wind, solar, hydropower, geothermal, and biomass facilities, that reduce or avoid greenhouse gas emissions by replacing fossil-fuel-based energy generation. Market revenue is attributed to the issuance, certification, brokerage, and sale of carbon credits generated through these projects.
Energy Efficiency
Energy efficiency projects generate carbon credits by reducing energy consumption across industrial facilities, commercial buildings, transportation systems, and infrastructure. Revenue is generated through carbon credit generation, verification, trading, and associated carbon management services linked to energy-saving initiatives.
Afforestation and Reforestation
This segment includes carbon credits generated from afforestation, Reforestation, and forest conservation projects that remove carbon dioxide from the atmosphere through biological sequestration. Revenue is derived from carbon credit issuance, project development, verification, trading, and related ecosystem restoration activities.
Methane Capture and Destruction
Methane capture and destruction projects generate carbon credits by preventing methane emissions from landfills, wastewater treatment facilities, agricultural operations, coal mines, and industrial sites. Market revenue is attributed to carbon credit creation, certification, sales, and project implementation activities.
Others (soil carbon sequestration, energy efficiency)
This segment includes carbon credits generated from blue carbon, soil carbon sequestration, biochar, direct air capture, cookstoves, and other emerging carbon reduction and removal projects. Revenue is generated through project development, carbon credit issuance, verification, trading, and associated environmental services.
Application
Revenue Capture Definition
Industrial
The industrial segment utilizes voluntary carbon credits to offset emissions generated from manufacturing, mining, construction, chemicals, and other industrial operations. Revenue capture includes the purchase, retirement, brokerage, and management of carbon credits used to support corporate decarbonization initiatives.
Household Devices
This segment includes the use of carbon credits from household-level emission-reduction projects, such as improved cookstoves, clean heating systems, and energy-efficient appliances. Revenue is generated through carbon credit issuance, certification, and transactions linked to household-emission-reduction programs.
Energy
The energy segment utilizes voluntary carbon credits to offset emissions from power generation, fuel consumption, and energy-intensive operations. Revenue is attributed to carbon credit procurement, trading activities, and sustainability programs implemented by energy producers and consumers.
Agriculture
Agricultural carbon credits are generated through sustainable farming practices, soil carbon sequestration, livestock methane reduction, and land management initiatives. Revenue capture includes project development, carbon credit verification, trading, and the implementation of agricultural emission-reduction programs.
Others
This segment includes transportation, waste management, commercial buildings, and other applications that utilize voluntary carbon credits to offset greenhouse gas emissions. Revenue is generated through carbon credit transactions, environmental programs, and related carbon management activities.
End-use
Revenue Capture Definition
Government Agencies
Government agencies purchase and retire voluntary carbon credits to support climate action programs, carbon neutrality goals, environmental initiatives, and public sustainability commitments. Revenue is generated through the procurement of carbon credits and related carbon management activities.
Non-Governmental Organizations (NGOs)
NGOs utilize voluntary carbon credits to support environmental conservation, climate mitigation, and sustainability projects. Revenue capture includes carbon credit purchases, project financing, and participation in voluntary carbon market activities.
Private Companies
Private companies represent the largest end-use segment, using voluntary carbon credits to offset residual emissions, meet net-zero commitments, comply with ESG objectives, and enhance sustainability performance. Revenue is generated through carbon credit purchases, trading, retirement, and carbon management services.
Individuals
Individuals purchase voluntary carbon credits to offset their personal carbon footprints from travel, energy consumption, and lifestyle activities. Revenue is attributed to retail carbon credit transactions, carbon offset programs, and consumer-focused sustainability initiatives.
Estimation Model
Layer Name
Key Question
Description
Carbon Emissions & Offset Demand Base Layer
What forms the demand base?
Identify global demand for voluntary carbon credits across organizations seeking to offset greenhouse gas emissions and achieve sustainability objectives. Assess emissions generated by corporations, institutions, governments, and individuals, along with net-zero commitments, ESG initiatives, and climate action programs to establish the addressable market opportunity.
Carbon Credit Project Supply Layer
Where are carbon credits generated and supplied?
Estimate the supply of carbon credits generated from renewable energy, afforestation and reforestation, energy efficiency, methane capture, and other carbon reduction or removal projects across key regions. Analyze project development activity, certification standards, registry issuance, and carbon credit availability to assess market supply dynamics.
Carbon Credit Adoption Layer
How extensively are voluntary carbon credits utilized?
Analyze the adoption of voluntary carbon credits across industrial, energy, agriculture, household, and other applications. Evaluate corporate sustainability strategies, carbon neutrality goals, ESG reporting requirements, and climate commitments influencing carbon credit procurement and retirement activities.
Revenue Layer
How is market revenue generated?
Expenditures on voluntary carbon credit purchases, brokerage services, carbon trading activities, and related carbon management solutions quantify market revenue. Carbon credit transaction volumes, average credit prices, project quality, and demand from end-use organizations drive the overall market value.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Voluntary Carbon Credit Competitive Landscape Assessment
Detailed competitive landscape analysis covering carbon credit project developers, carbon asset managers, climate solutions providers, carbon marketplaces, and trading platforms. The study profiled key market participants based on geographic presence, project portfolio, carbon credit origination capabilities, project types, customer base, strategic partnerships, technology adoption, and investments in carbon reduction and removal initiatives.
Enabled evaluation of competitive positioning, project development capabilities, carbon credit sourcing strategies, customer engagement models, and market participation across the voluntary carbon credit value chain.
Project & Application Assessment
Evaluation of global voluntary carbon credit demand across renewable energy, energy efficiency, afforestation and reforestation, methane capture, and other carbon reduction and removal projects. Included assessment of carbon credit applications across industrial, energy, agriculture, household, and other sectors, along with project development trends, verification standards, adoption patterns, regulatory considerations, and regional market dynamics.
Highlighted project development trends, carbon credit adoption patterns, and regional demand opportunities. Supported strategic planning, project portfolio optimization, market entry evaluation, and investment prioritization decisions.
Opportunity Assessment
Identification of high-growth opportunities associated with carbon removal technologies, nature-based solutions, digital carbon marketplaces, and increasing corporate demand for high-integrity carbon credits. Assessed emerging opportunities arising from net-zero commitments, ESG initiatives, advancements in monitoring and verification technologies, and growing investments in climate mitigation projects worldwide.
Enabled prioritization of high-value growth opportunities and emerging carbon credit segments. Supported long-term business planning, project development strategies, investment decisions, and expansion initiatives aligned with evolving sustainability and decarbonization requirements.
Frequently Asked Questions About This Report
The voluntary carbon credit market size was valued at USD 5.3 billion in 2025 and is expected to reach USD 7.4 billion in 2026.
The voluntary carbon credit market is expected to grow at a compound annual growth rate of 32.2% from 2026 to 2033 to reach USD 52.4 billion by 2033.
Based on end-use, private companies accounted for largest revenue share of 62.1% in 2025, while individuals are anticipated to register the fastest CAGR over the forecast period.
The key players operating in the voluntary carbon credit market include South Pole, 3Degrees, Inc., Climate Impact Partners, EcoAct SAS, EcoSecurities Group Limited, EKI Energy Services Ltd., Xpansiv Limited, ClimeCo LLC, BioCarbon Partners Group Ltd., and Carbon Direct, Inc.
North America dominated the market with revenue share of 37.0% in 2025.
The U.S. dominated the North America market with a revenue share of 81.3% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 33.5% over the forecast period.
Based on applications, industrial accounted for largest revenue share of 32.2% in 2025.
The global voluntary carbon credit market is primarily driven by increasing corporate net-zero commitments and growing demand for carbon offset solutions. Rising ESG initiatives, sustainability reporting requirements, and investments in carbon reduction and removal projects are further supporting market growth.
About the Author(s)
Sustainable Energy Research Team
Energy & Power · Sustainable EnergyThis report was authored by the sustainable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the sustainable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


