
- Home
- »
- Plastics, Polymers & Resins
- »
-
Water Soluble Packaging Market Size & Share Report, 2033GVR Report cover

Water Soluble Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report by Material (Polymers, Fibers, Surfactants), By Product (Bags, Pouches), By Solubility Type, By End-use (Household Products, Agriculture, Medical, Retail), By Region, And Segment Forecasts
Market Size, 2025
$3.6BMarket Estimate, 2026
$3.8BMarket Forecast, 2033
$5.7BCAGR, 2026–2033
5.9%Water Soluble Packaging Market Summary
The global water soluble packaging market size was valued at USD 3.6 billion in 2025 and is projected to grow from USD 3.8 billion in 2026 to USD 5.7 billion by 2033, at a CAGR of 5.9% from 2026 to 2033. North America market dominated, with a revenue share of 32.4% in 2025. Soluble packaging is designed to dissolve in water, making it a sustainable alternative to traditional packaging materials such as plastic, glass, and metal.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Polymers segment led the market with the largest revenue share of 65.99% in 2025.
- By product: Bags segment led the market with the largest revenue share of 46.92% in 2025.
- By solubility type: Hot water segment led the market with the largest revenue share of 59.57%in 2025.
- By end-use: Household products segment led the market with the largest revenue share of 23.44% in 2025.
Regional Highlights
- Largest regional market: North America (32.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.6 Billion
- Estimated market size in 2026: USD 3.8 Billion
- Projected market size by 2033: USD 5.7 Billion
- CAGR (2026-2033): 5.9%
Prism AI by Grand View Research Free to tryAsk a question about the water soluble packaging marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The growth of the water-soluble packaging market is attributed to rising environmental concerns and a shift in consumer demand for sustainable packaging solutions. This packaging is convenient to use for consumers, easily dissolvable, and contributes minimally to environmental pollution. The U.S. federal government has implemented several regulations on plastic packaging, which is creating growth opportunities for water soluble packaging industry. For instance, the U.S. Environmental Protection Agency (EPA) has established regulations for the disposal of plastic waste, and the Food and Drug Administration (FDA) has established regulations regarding the use of plastics in consumer goods which further fuels the market growth for water-soluble packaging solutions.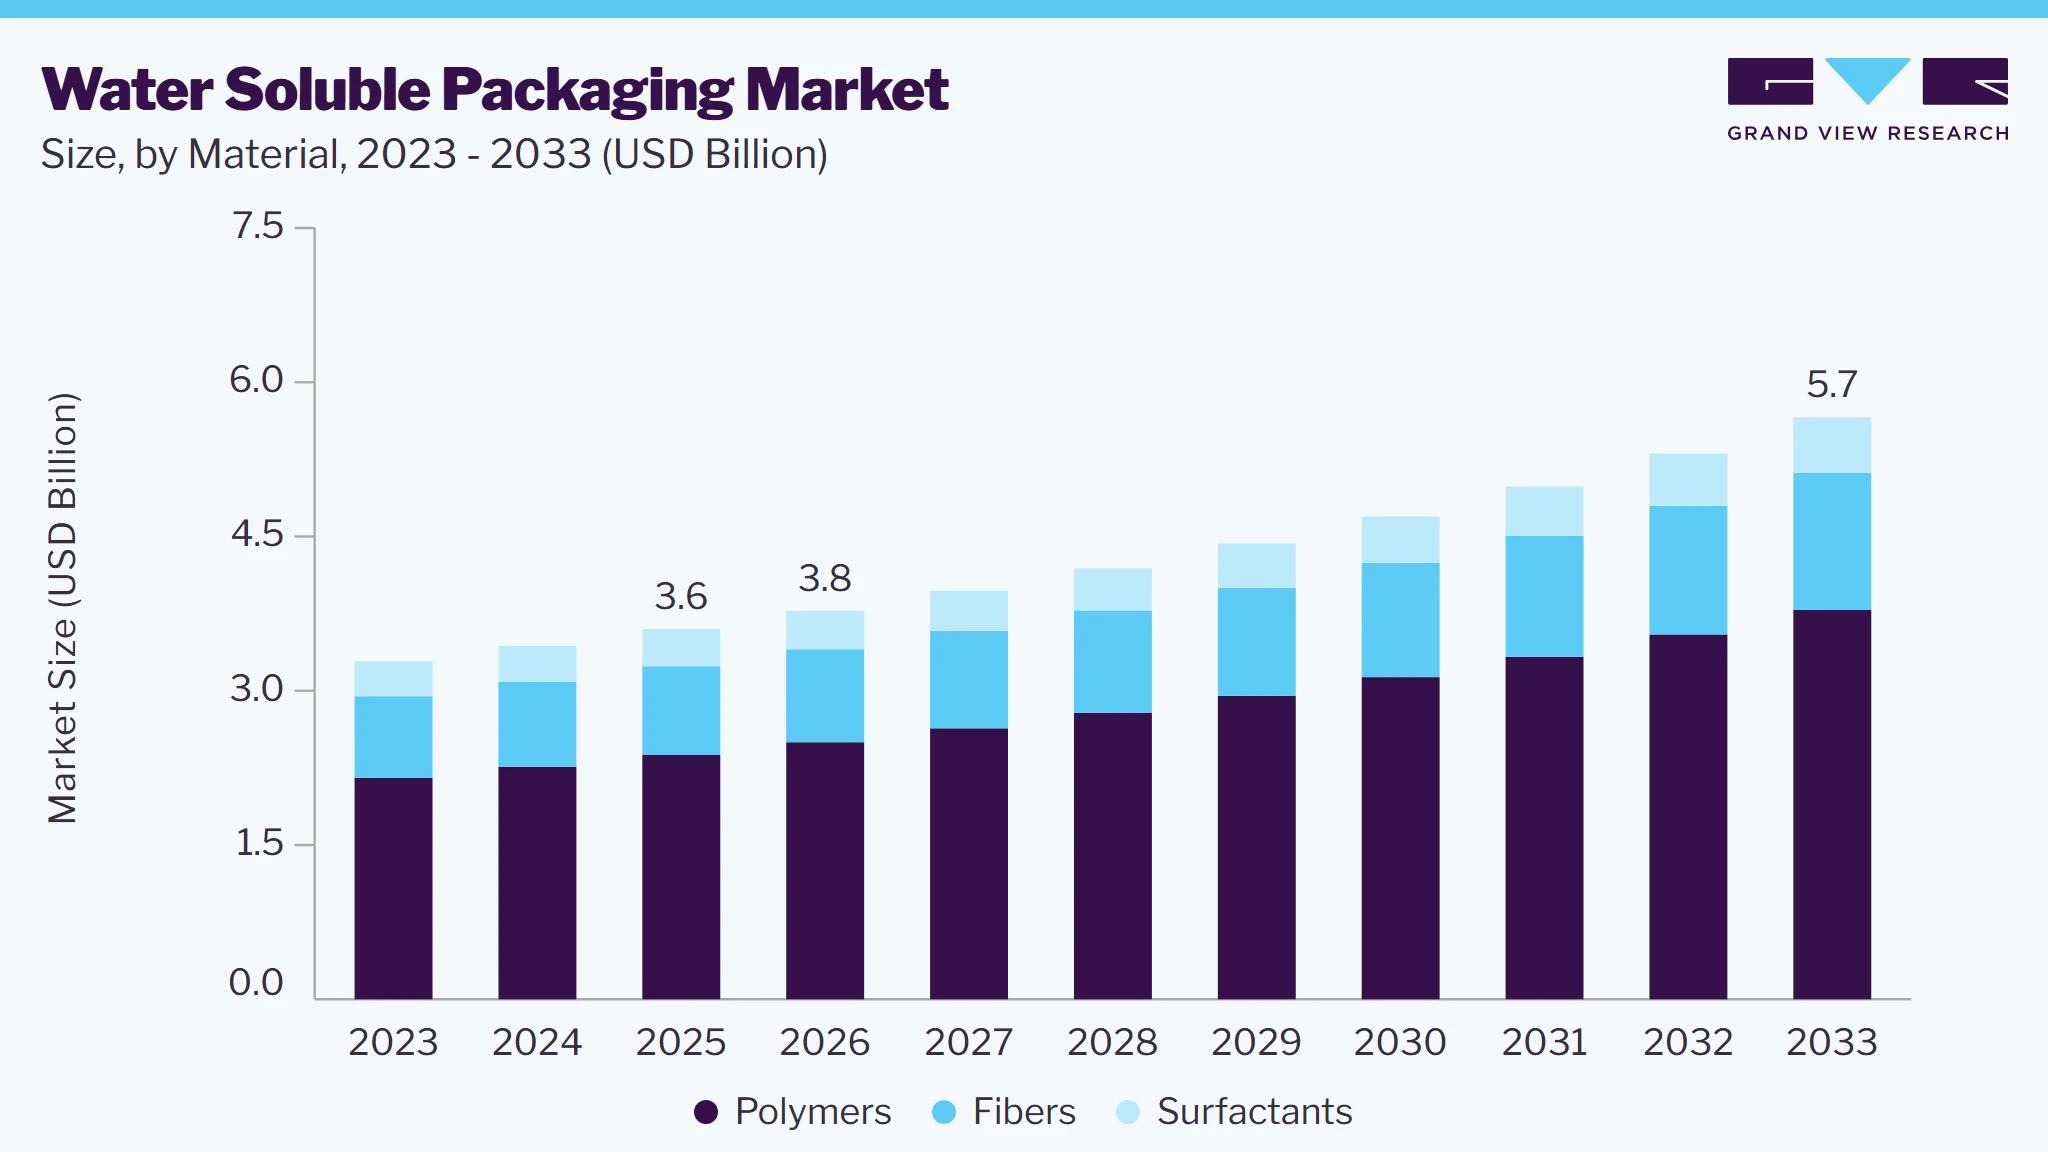 To learn more about this report, Download Free Sample Report
The U.S. market houses a significant number of water soluble packaging manufacturers such as MonoSol (a Kuraray Division), U.S. Non Wovens, Mondi, and Smart Solve Industries, which supports the water soluble packaging demand in the country. Growing awareness regarding the benefits offered by water soluble packaging solutions is driving their adoption by end-users in the U.S. For instance, Saie, a health and beauty brand, uses water soluble packaging for its products.
Stringent government regulations on plastic ban have also positively impacted the water-soluble packaging industry growth. For instance, the draft European Union regulation published by the UK government has set a target to achieve zero avoidable plastic waste by 2042. This initiative by the government has further led to increased demand for sustainable packaging solutions such as water-soluble packaging.
Market Dynamics
The Water Soluble Packaging market is witnessing significant growth, driven by increasing demand for sustainable packaging solutions, stringent regulations on single-use plastics, and the growing adoption of convenient unit-dose packaging across multiple industries. Water soluble packaging, primarily manufactured from polyvinyl alcohol (PVOH) and other biodegradable polymers, dissolves completely in water, minimizing packaging waste and improving product handling. Industries such as detergents, agrochemicals, pharmaceuticals, personal care, and household cleaning products are increasingly utilizing water soluble films and pouches to enhance safety, reduce product wastage, and support sustainability goals. Furthermore, continuous advancements in biodegradable film technologies, improved moisture resistance, and enhanced dissolution performance are expanding application areas and accelerating the adoption of water soluble packaging worldwide.
The increasing emphasis on reducing plastic waste and improving consumer convenience is a major driver of the water soluble packaging market. Governments and regulatory agencies worldwide are introducing stricter environmental policies that encourage the adoption of biodegradable and environmentally friendly packaging materials. Water soluble packaging provides an effective alternative to conventional plastic packaging by eliminating packaging waste after use while offering precise product dosing for detergents, agrochemicals, and pharmaceutical formulations. Its ability to improve handling safety, reduce direct contact with hazardous substances, and minimize product wastage has significantly increased its adoption across industrial and consumer applications.
In addition to regulatory support, changing consumer lifestyles and the growing demand for convenient packaging formats are further fueling market expansion. The rising popularity of detergent pods, water treatment chemicals, and unit-dose pharmaceutical products has encouraged manufacturers to invest in advanced water soluble film technologies that provide improved strength, controlled dissolution rates, and enhanced compatibility with a wide range of formulations. As industries continue to prioritize sustainability, operational efficiency, and user convenience, demand for water soluble packaging is expected to grow steadily across global markets.
One of the major restraints affecting the water soluble packaging market is the relatively high production cost of water soluble films compared to conventional plastic packaging materials. Specialized raw materials such as polyvinyl alcohol (PVOH), advanced manufacturing processes, and strict quality control requirements increase production expenses. Additionally, water soluble packaging is highly sensitive to humidity and moisture during storage and transportation, requiring controlled environmental conditions and specialized packaging systems to maintain product integrity. These factors can limit adoption in cost-sensitive industries and regions with challenging climatic conditions.
The expanding use of water soluble packaging in healthcare, agriculture, and specialty chemical applications presents significant growth opportunities for the water soluble packaging market. Pharmaceutical manufacturers are increasingly adopting water soluble packaging for unit-dose medications and medical products to improve hygiene and dosing accuracy, while agrochemical companies are utilizing dissolvable packaging to reduce worker exposure to hazardous chemicals and improve application safety. Continuous innovation in biodegradable polymer formulations, high-barrier water soluble films, and customized packaging solutions is expected to broaden application areas, creating substantial long-term growth opportunities for market participants.
Market Concentration & Characteristics
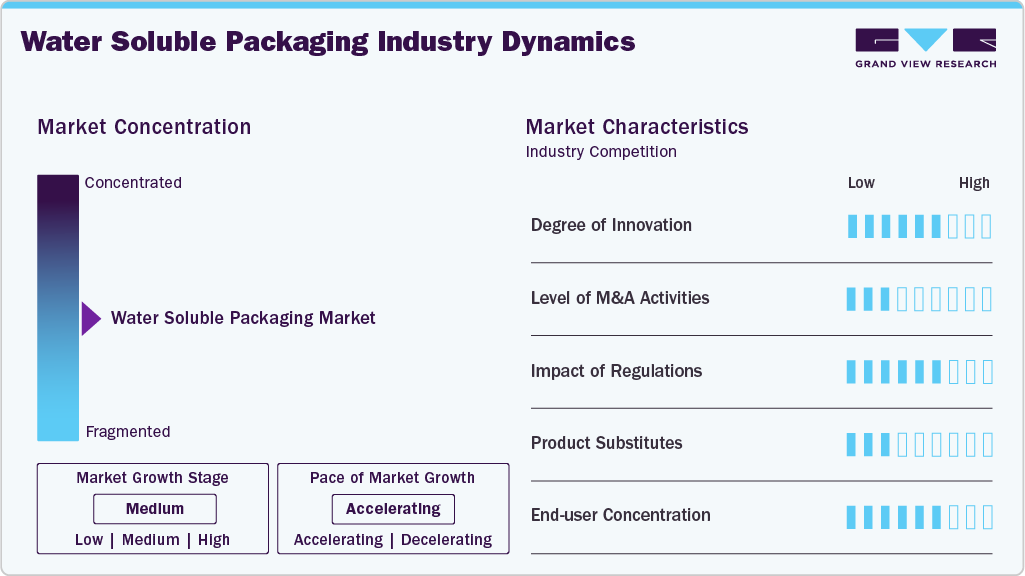
The water-soluble packaging market is moderately concentrated, with several companies contributing to the overall market share and product innovation. The market is also characterized by several small-scale start-ups, which encourage further innovation in product development. The market is experiencing a moderate growth rate. However, it is expected to gain higher growth rates over the next few decades.
The water soluble packaging market has been witnessing growing innovation, especially in the incorporation of sustainable materials such as polymers, surfactants, and fibers derived from natural sources. Brands are developing packaging that is highly soluble and offers extra-strength catering to varied applications, including retail, medical, and chemical industries. Water soluble packaging improvements also reflect ongoing innovations and consistent investments in their R&D.
 To learn more about this report, Download Free Sample Report
Environmental regulations significantly influence water-soluble packaging solutions and the responsible sourcing of materials. Governments across North America and European countries have implemented recycled-content mandates and single-use plastic restrictions. These laws are pushing brands toward water soluble and compostable alternatives. Compliance has become a key driver of R&D and product positioning. Regulatory impact is high and continues to shape future market offerings.
Water soluble packaging manufacturers are actively expanding product lines to address the issues of waste generated from traditional packaging. Eco-friendly alternatives, including compostable and water-soluble packaging, are gaining traction. Companies are also offering customized packaging solutions for various end-use sectors. Product expansion is healthy and driven by environmental and consumer demands.
Companies from different verticals are incorporating water-soluble packaging as a part of their environmental efforts. Brands including Procter & Gamble, Unilever, and Reckitt Benckiser Group are using water soluble pods for their homecare products including detergents, shampoos, bath soaps and gels, among others. Companies are also making strategic alliances to develop and customize packaging for their products.
Analyst Perspective
The water-soluble packaging market has evolved from a niche packaging solution primarily used for detergent and agrochemical applications into a rapidly expanding segment of the sustainable packaging industry. Growing concerns over plastic pollution, stricter environmental regulations, and increasing demand for convenient, unit-dose packaging have accelerated adoption across household care, healthcare, agriculture, and industrial sectors. Advances in water-soluble polymer technologies have further improved product strength, dissolution performance, and application versatility. Looking ahead, the market is expected to experience strong growth, supported by increasing investments in biodegradable packaging solutions, expanding adoption in pharmaceutical and personal care applications, and continuous innovation in high-performance, eco-friendly materials, positioning water-soluble packaging as a key contributor to the future of sustainable packaging.
Material Insights
Based on materials, water-soluble packaging is segmented into polymer, surfactants and fibers. Among these, the polymers segment led the market with the largest revenue share of 65.99% in 2025. Polyvinyl alcohol is popularly used as a water-soluble packaging material due to its strong film-forming properties and excellent water solubility. These polymers are compatible with a wider range of product ingredients, including aggressive chemicals, enzymes, and other active ingredients having applications in household, medical, agriculture, and personal care sectors.
The fiber segment is expected to advance at a substantial CAGR of 5.2% during the forecast period. Natural fiber materials are derived from plant sources including wood pulp, while, synthetic fibres are derived from grains such as corn and wheat, which are further used in the production of fiber-based water-soluble packaging solutions. For instance, water soluble paper is an example of fiber-based packing product that helps in lowering the environmental impact compared to conventional plastic packaging solutions. Such products helps in driving the demand for fiber-based water soluble packaging market.
Product Insights
Based on products, the water-soluble packaging market is segmented into bags, pouches, and pods & capsules. Among these, the bags segment led the market with the largest revenue share of 46.92% in 2025 and is expected to maintain its dominance during the forecast period. This is due to its extensive adoption in the medical packaging sector, especially for infected laundry bags and disposable consumables. The convenience and easy application of water-soluble bags make them a preferred choice for both manufacturers and consumers. For instance, a study in April 2024 revealed that over 92% of hospital laundry staff have been in contact with contaminated linen, underscoring the significant infection risks in healthcare settings. To mitigate this, many hospitals have adopted water-soluble laundry bags, which can be placed directly into washing machines, reducing direct handling of soiled linens and enhancing infection control measures. Additionally, increasing regulatory emphasis on hospital hygiene standards is driving the procurement of safer and more sustainable packaging solutions. As a result, demand for water-soluble medical bags is expected to continue rising, particularly across hospitals, nursing homes, and emergency care facilities.
The pouches segment is anticipated to grow at a considerable CAGR over the forecast period. The water-soluble pouches are commonly used for single-dose packaging of items such as laundry detergents, agricultural chemicals, industrial cleaning agents, and personal care products including bath additives. Designed to completely dissolve in water without leaving waste, they offer a sustainable and user-friendly alternative to conventional plastic packaging. Increasing demand for biodegradable, pre-measured packaging across industries such as home care, agriculture, and personal care is expected to fuel continued growth of this segment over the coming years.
Solubility Insights
Based on solubility type, the hot water segment led the market with the largest revenue share of 59.57%in 2025. The ability to dissolve the packaging quickly and easily in hot water temperatures ranging typically between 60°C to 80°C eliminates the need for measuring, handling, and disposing of traditional packaging materials. This is a major factor driving the demand for this segment.
Cold-water soluble packaging offers greater energy efficiency by dissolving quickly at temperatures below 20°C, eliminating the need for hot or warm water. Growing environmental awareness and the push for eco-friendly packaging solutions are driving increased demand for water-soluble packaging, which in turn is expected to encourage the market for cold-water soluble options. For instance, in 2021, Emballator introduced rigid containers made from PVOH that dissolve in cold water. These containers can be tailored to meet specific customer needs, providing an innovative and sustainable alternative for packaging dry products while helping reduce plastic waste.
End-use Insights
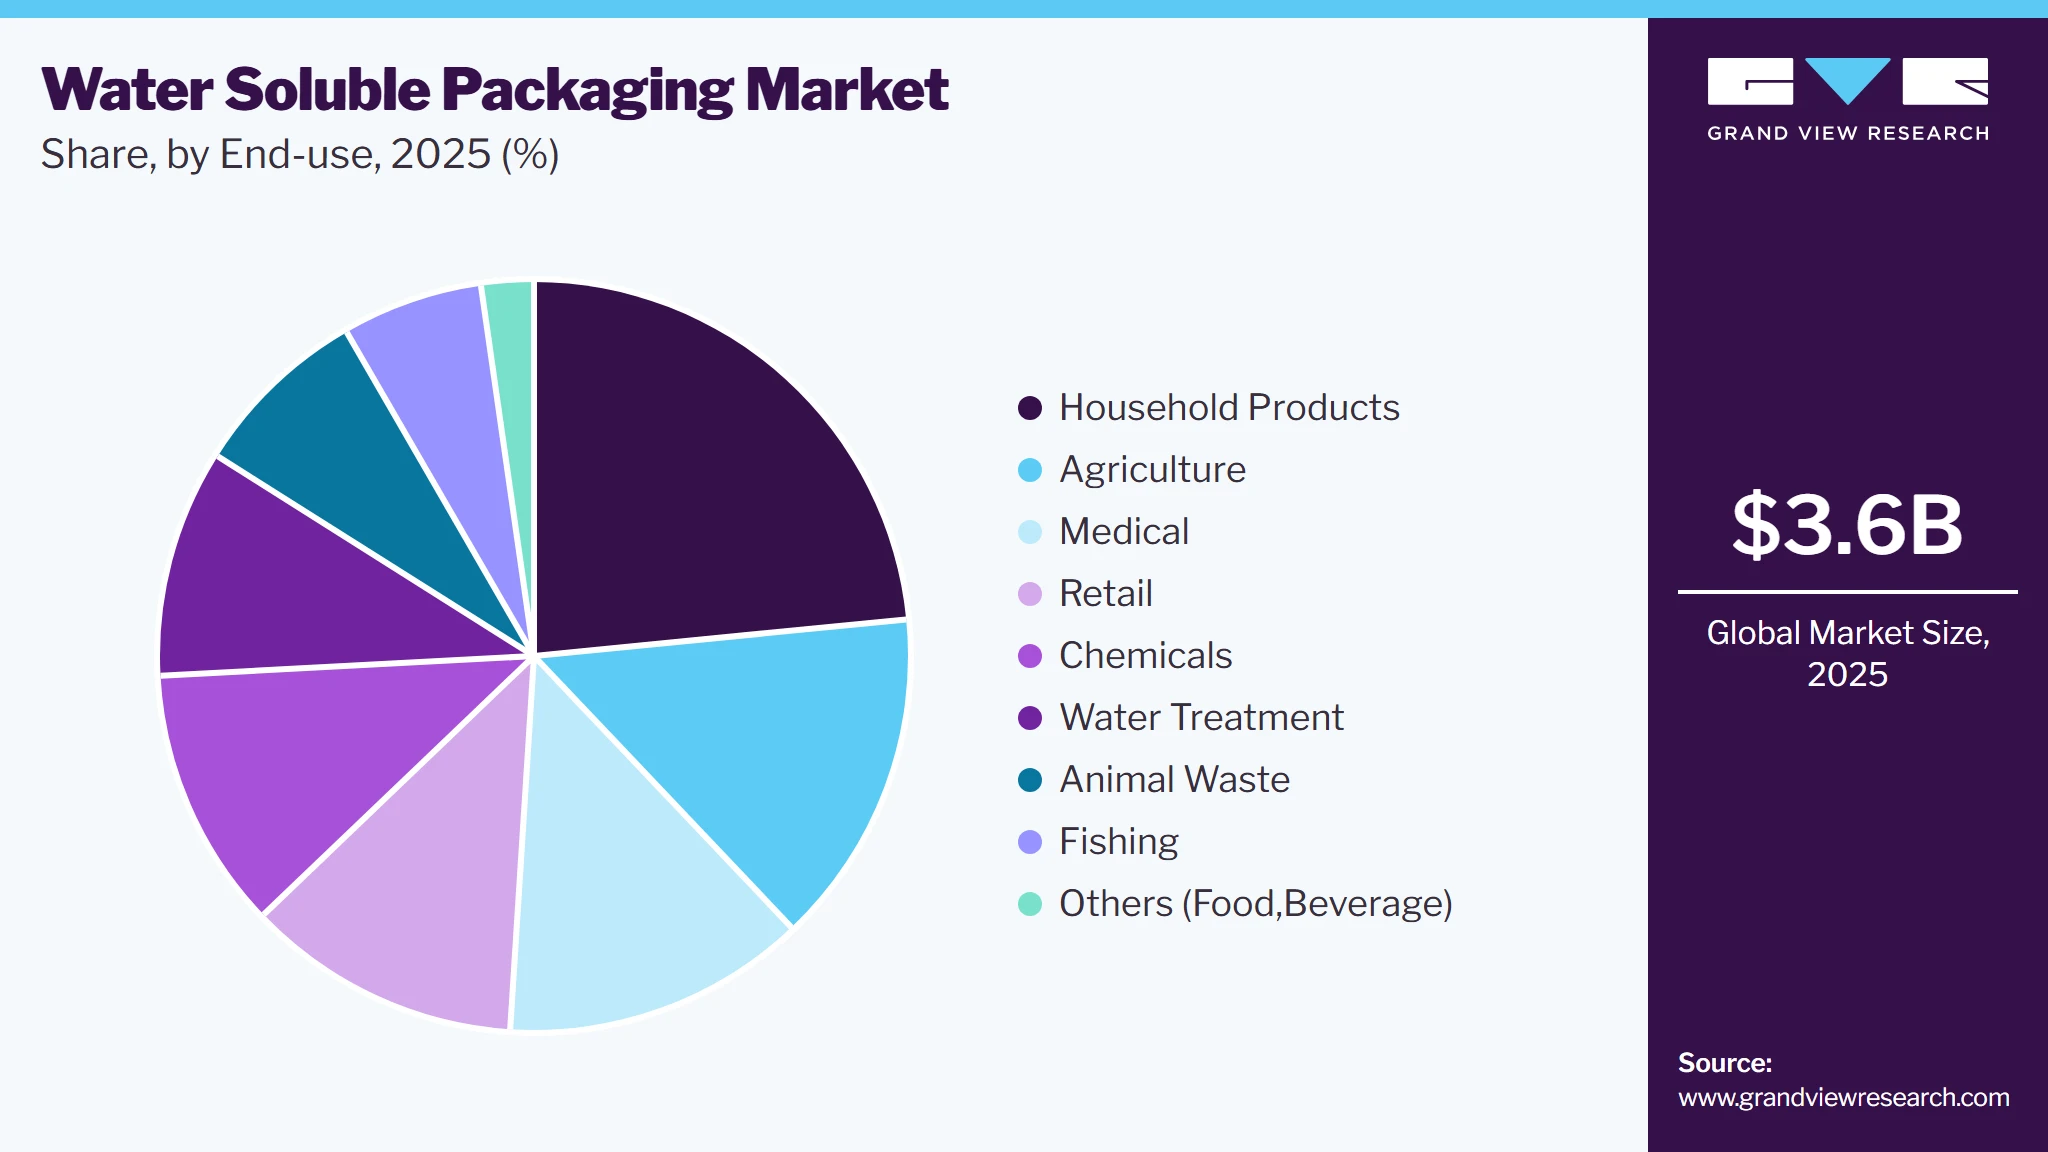
Based on end-use, household products segment led the market with the largest revenue share of 23.44% in 2025, owing to the wide application of water-soluble packaging in laundry detergent pods and other household cleaning products, such as drain cleaner pods, glass cleaner pods, and toilet blocks. Many companies started to provide household products in such water soluble packaging. For instance, Unimasses Group, a global household cleaning products manufacturer, offers a wide range of laundry detergent in Water-soluble packaging. Such packaging provides a convenient and efficient way of dispensing cleaning products without the need for measuring or handling bulky containers. Such innovations in household product packaging are fuelling the demand for this segment.
 To learn more about this report, Download Free Sample Report
The consumption of water soluble packaging in the agriculture industry is expected to grow at the fastest during the forecast period of 2025 to 2030. Water soluble packaging solutions are used in packaging fertilizers and pesticides, which helps to reduce waste and minimize its environmental impact. Furthermore, water-soluble packaging is widely used in hospitals, healthcare centres, and nursing homes, in the form of laundry bags. These water-soluble laundry bags are used to wash the contaminated and infected laundry of patients without the risk of infection, as these bags are dissolvable in water when they are put together in a washing machine along with laundry.
In the retail sector, water-soluble packaging is used in garment bags, grocery bags, and other consumer goods packaging. The personal care industry is adopting this packaging solution to eliminate plastic packaging usage due to stringent government regulations on plastic ban and plastic waste management For instance, the Government of Canada introduced the Single-Use Plastics Prohibition Regulations, which came into effect in December 2022. These regulations aim to eliminate specific categories of single-use plastic items such as checkout bags, cutlery, stirring sticks, and food service ware by regulating their manufacture, import, and sale. This measure is part of Canada’s broader strategy to achieve zero plastic waste by 2030. Such proactive government initiatives are encouraging industries to adopt sustainable alternatives including water-soluble packaging.
The chemical industry is expected to expand at a significant rate during the forecast period, on account of the fast-growing trend of fabric dyeing. Dye pods have gained popularity among the younger generation due to their convenience and ease of use. These pods are simply dropped in water along with the fabric and they dissolve and release the color into the water, eliminating the packaging waste.
Regional Insights
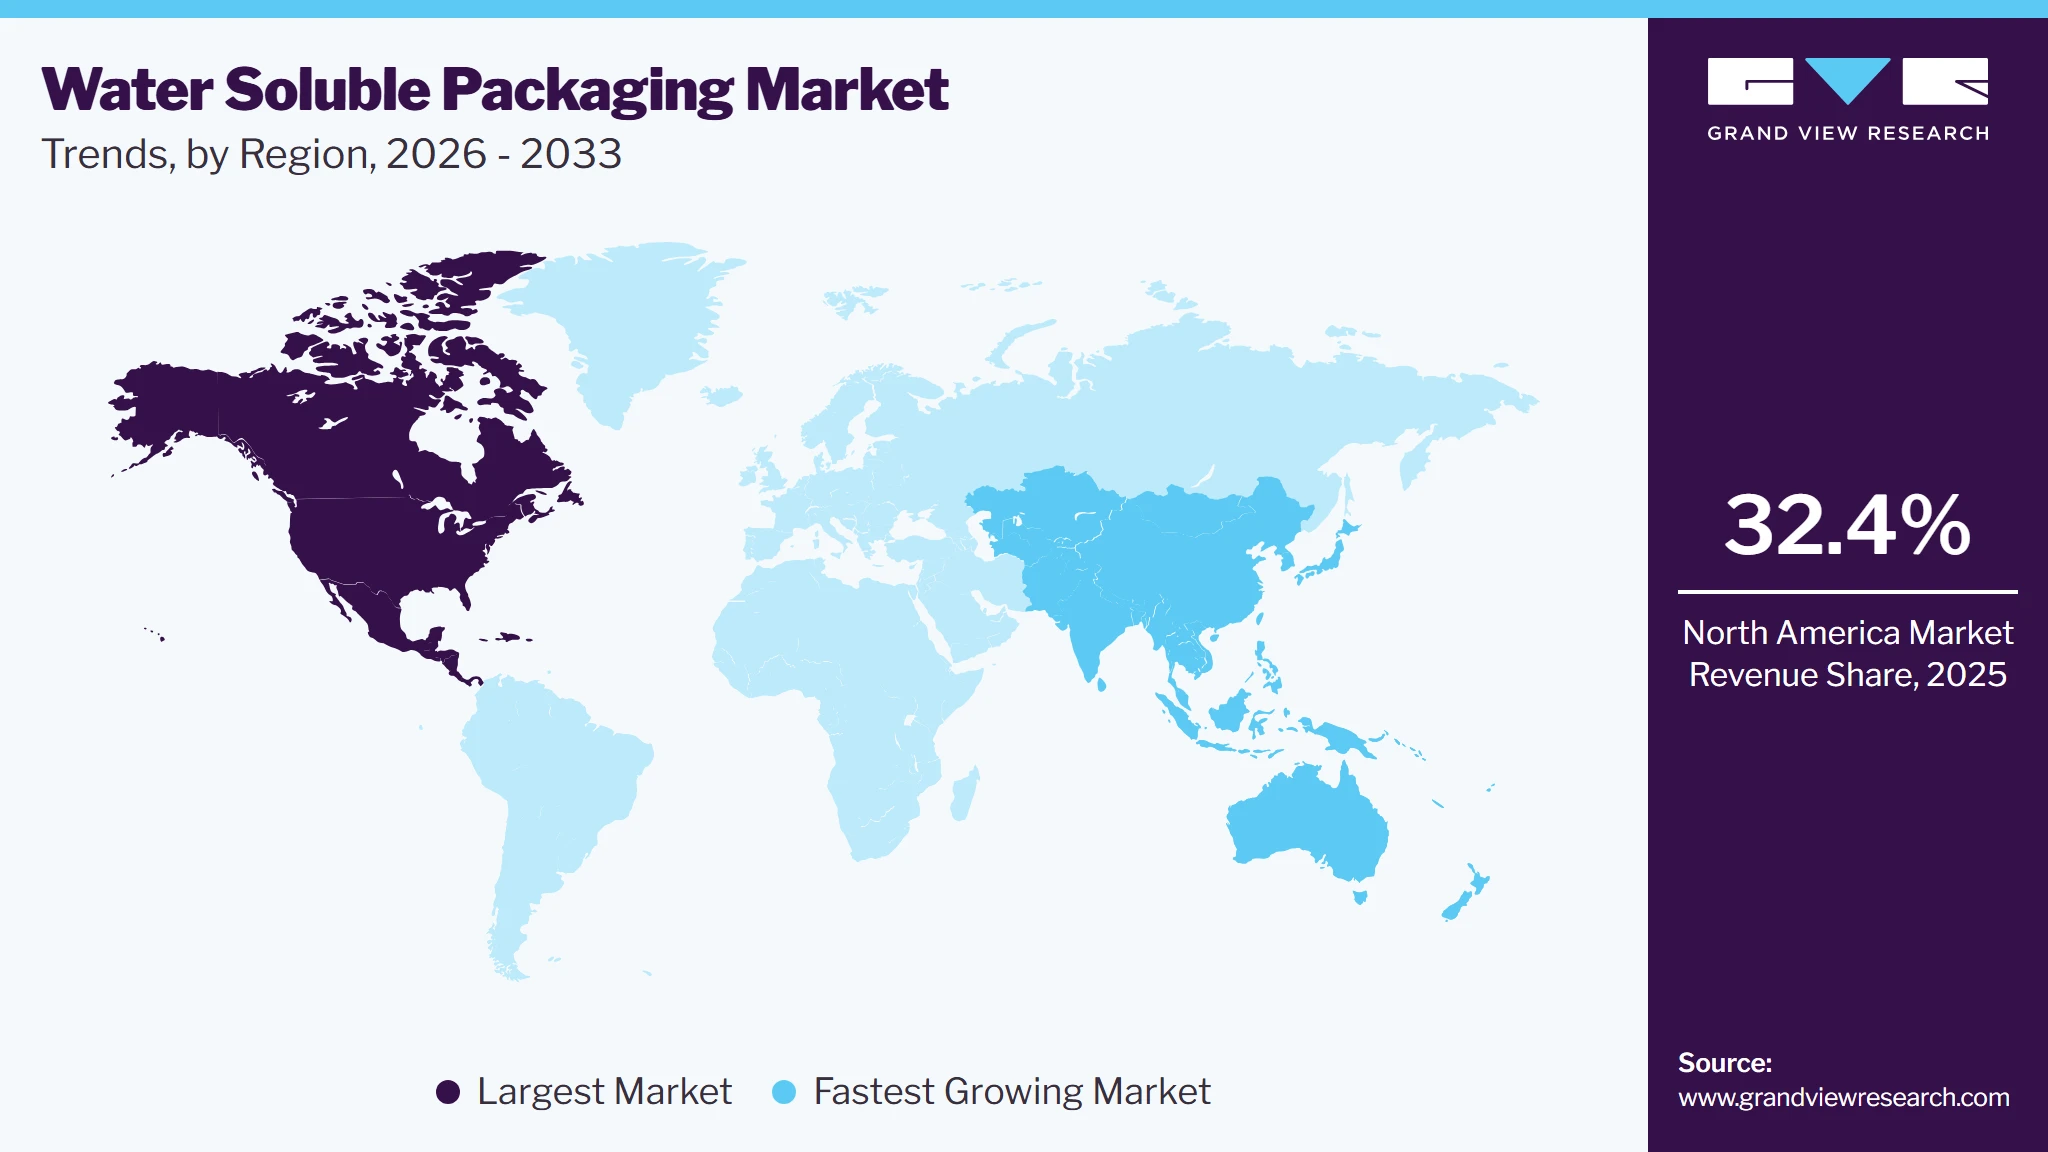
North America dominated the water soluble packaging market with the largest revenue share of 32.4% in 2025 in the water-soluble packaging market. This is owing to the increasing demand for environmental-friendly packaging solutions from various regional end-user industries including household products, healthcare, and food & beverages. In addition, the stringent government regulations and the rising awareness among consumers about the negative environmental impact of traditional packaging materials are driving the demand for such packaging solutions in North America.
 To learn more about this report, Download Free Sample Report
U.S. Water Soluble Packaging Market Trends
The Water Soluble packaging market in U.S. held the largest share in the North America region in 2025. This growth is primarily driven by rising demand from the household sector for cleaning pods and capsules, particularly for laundry and dishwashers. These products offer convenience and safety, with formulations designed to minimize skin contact with harmful chemicals. Additionally, the increasing adoption of dishwashers and washing machines has bolstered the market for water-soluble detergents and dishwasher pods.
Beyond household use, the expanding U.S. healthcare sector is also fueling demand. For instance, in 2023, National Health Expenditure (NHE) grew by 7.5% to $4.9 trillion, accounting for 17.6% of the country’s GDP, with spending reaching $14,570 per person. Medicare spending rose by 8.1% to $1,029.8 billion (21% of total NHE), while Medicaid spending increased by 7.9% to $871.7 billion (18% of total NHE). This substantial growth in healthcare spending drives the demand for hygienic, sustainable packaging solutions-such as water-soluble laundry bags used in hospitals and care facilities to safely handle contaminated materials without direct contact. As a result, the healthcare sector is a significant contributor to the rising demand for water-soluble packaging in the U.S.
Europe Water Soluble Packaging Market Trends
Europe accounted for a significant market share in 2024 due to the increased product demand from the household segment and stringent government regulation pertaining to environmental protection. The trend of independent living in the region has led to hectic and busy schedules of consumers, giving rise to an increased demand for products that are convenient and easy to use. Consumer buying such products has a positive impact on the water-soluble packaging market due to the growing demand for cleaning pods. Moreover, stringent government regulations on plastic bans and a growing emphasis on sustainable packaging is driving the market demand for these solutions in the region. For instance, in December 2024, the European Council approved the Packaging and Packaging Waste Regulation, which mandates that all packaging must be recyclable or reusable by 2030. This regulation is pushing industries to adopt innovative, eco-friendly materials such as water-soluble films, further accelerating market growth.
Asia Pacific Water Soluble Packaging Market Trends
Asia Pacific is poised to expand at the fastest CAGR of 6.4% through 2030 in the market for water-soluble packaging, owing to the rising demand for sustainable packaging solutions in the region. Countries such as China, India, South Korea, and Japan are major contributors to the market growth, owing to the high demand for laundry detergents and personal care products. Moreover, the ban on plastic packaging in various countries is fueling regional market growth.
China accounted for the largest market share in 2024 in the Asia Pacific region. This is attributed to the rapidly growing end-user industries and increased consumer awareness about sustainable packaging solutions. The Chinese government has been implementing certain regulations to reduce plastic packaging usage in the country, which is positively impacting the demand for sustainable packaging solutions. For instance, China's National Development and Reform Commission (NDRC), in collaboration with the Ministry of Ecology and Environment, has outlined a comprehensive plan to reduce single-use plastic consumption by 2025. This initiative is part of the 14th Five-Year Plan (2021-2025) aimed at controlling plastic pollution.
Key Water Soluble Packaging Company Insights
Key players in the Water Soluble Packaging Market include Kuraray, Lithey Inc., Mondi Group, SEKISUI CHEMICAL CO., LTD., Mitsubishi Chemical Corporation, Soltec Development, Soluble Technology Limited, Aquapak Polymers Ltd., Rovi Packaging, S.A., INVISIBLE COMPANY, AICELLO CORPORATION, Medanos Claros HK Limited, Cortec Corporation, Acedag Ltd, Changzhou Haoteng Environmental Protection New Material Technology Co., Ltd., Green Master Packaging, Guangdong Proudly New Material Technology Corp., Solupak, EOS Plast Srl, and Solubag.
-
Kuraray Co., Ltd. is a global leader in water-soluble films under the brand "Eval and Poval", known for their high-quality polyvinyl alcohol (PVA) materials used in packaging detergents, agrochemicals, and pharmaceuticals. The company focuses on innovation and sustainability in polymer science.
-
SEKISUI CHEMICAL CO., LTD. manufactures water-soluble and biodegradable films used in a variety of household and industrial applications. The company is recognized for its environmental stewardship and consistent R&D in advanced functional materials.
Key Water Soluble Packaging Companies:
The following key companies have been profiled for this study on the water soluble packaging market.
-
Kuraray
-
Lithey Inc.
-
Mondi Group
-
SEKISUI CHEMICAL CO., LTD.
-
Mitsubishi Chemical Corporation
-
Soltec Development
-
Soluble Technology Limited
-
Aquapak Polymers Ltd.
-
Rovi Packaging, S.A.
-
INVISIBLE COMPANY
-
AICELLO CORPORATION
-
Medanos Claros HK Limited
-
Cortec Corporation
-
Acedag Ltd
-
Changzhou Haoteng Environmental Protection New Material Technology Co., Ltd.
-
Green Master Packaging
-
Guangdong Proudly New Material Technology Corp.
-
Solupak
-
EOS Plast Srl
-
Solubag
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Kuraray; Mondi Group; SEKISUI CHEMICAL CO., LTD.; Mitsubishi Chemical Corporation; AICELLO CORPORATION; Cortec Corporation)
- Focus on expanding water soluble packaging portfolios through high-performance water-soluble films, bags, pouches, pods, and specialty packaging solutions for household products, agrochemicals, pharmaceuticals, healthcare, chemicals, and industrial applications. Invest in advanced polymer technologies, biodegradable material innovation, sustainable manufacturing processes, and global production capabilities while strengthening strategic partnerships with FMCG companies, detergent manufacturers, and agrochemical producers.
- Strong global manufacturing footprint, advanced polymer research capabilities, diversified product portfolios, and extensive distribution networks support large-scale commercial supply. Continuous investments in R&D, sustainable material innovation, regulatory compliance, and high-performance water-soluble film technologies strengthen their competitive position across global markets.
- High investment requirements for specialty polymer development, manufacturing technology, and regulatory compliance increase operational costs. Dependence on specialty raw materials, fluctuating polymer prices, and stringent environmental and product safety standards may impact profitability and production flexibility.
Emerging Players (Lithey Inc.; Soltec Development; Soluble Technology Limited; Aquapak Polymers Ltd.; Rovi Packaging, S.A.; INVISIBLE COMPANY; Medanos Claros HK Limited; Acedag Ltd; Changzhou Haoteng Environmental Protection New Material Technology Co., Ltd.; Green Master Packaging; Guangdong Proudly New Material Technology Corp.; Solupak; EOS Plast Srl; Solubag)
- Focus on developing innovative and customized water soluble packaging solutions for niche applications across household products, agriculture, medical, retail, water treatment, and specialty chemicals. Expand market presence through sustainable product development, flexible manufacturing, application-specific packaging formats, and regional distribution partnerships while investing in biodegradable materials and next-generation water-soluble film technologies.
- Greater operational flexibility enables rapid product innovation, customized packaging solutions, and faster response to evolving customer requirements. Strong focus on sustainability, emerging biodegradable technologies, and niche market applications helps these companies differentiate themselves and build long-term relationships with regional customers.
- Limited production capacity, smaller international presence, and comparatively lower financial resources restrict participation in large global supply contracts. Lower brand recognition, limited distribution networks, and comparatively lower investment in large-scale manufacturing, automation, and advanced R&D may reduce competitiveness against established multinational water soluble packaging manufacturers.
Recent Developments
-
In October 2024, Solubag secured Series A funding worth USD 4.5 million led by Exit Ventures, with participation from Between the Coasts Ventures, Landon Ainge, and others. This investment was made with an aim to accelerate the development and commercialization of Solubag's patented water-soluble materials designed to replace single-use plastics.
-
In October 2024, British packaging firm Mondi plc announced the €634 million acquisition of Schumacher Packaging’s assets in Germany, Benelux, and the UK.
Water Soluble Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.6 billion
Estimated market size in 2026
USD 3.8 billion
Projected market size by 2033
USD 5.7 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, product, solubility type end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Kuraray, Lithey Inc., Mondi Group, SEKISUI CHEMICAL CO., LTD., Mitsubishi Chemical Corporation, Soltec Development, Soluble Technology Limited, Aquapak Polymers Ltd., Rovi Packaging, S.A., INVISIBLE COMPANY, AICELLO CORPORATION, Medanos Claros HK Limited, Cortec Corporation, Acedag Ltd, Changzhou Haoteng Environmental Protection New Material Technology Co., Ltd., Green Master Packaging, Guangdong Proudly New Material Technology Corp., Solupak, EOS Plast Srl, Solubag
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Water Soluble Packaging Market Report Segmentation
This report forecasts volume and revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global water soluble packaging Market report based on based on material, product, solubility type, end-use, and region:
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Polymers
-
Surfactants
-
Fibers
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Bags
-
Pouches
-
Pods & Capsules
-
-
Solubility Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Cold Water
-
Hot Water
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Household Products
-
Agriculture
-
Medical
-
Retail
-
Chemicals
-
Water Treatment
-
Animal Waste
-
Fishing
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Southeast Asia
-
-
Central & South America
-
Brazil
-
Chile
-
-
Middle East & Africa
-
Saudi Arabia
-
United Arab Emirates
-
South Africa
-
-
Research Methodology
The water soluble packaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each water soluble packaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Material
Revenue capture definition
Polymers
Revenue generated from water soluble packaging products manufactured using water-soluble polymers, primarily polyvinyl alcohol (PVOH/PVA) and other biodegradable polymer materials. Includes water soluble films, pouches, sachets, laundry detergent pods, agrochemical packaging, pharmaceutical unit-dose packaging, and specialty dissolvable packaging solutions.
Fibers
Revenue generated from water soluble packaging products manufactured using water-dispersible and biodegradable fiber-based materials. Includes fiber-reinforced dissolvable packaging, specialty paper-based water soluble packaging, protective packaging, and sustainable packaging solutions used across consumer goods, healthcare, and industrial applications.
Surfactants
Revenue generated from water soluble packaging products manufactured using surfactant-based and specialty dissolvable material formulations designed to enhance dissolution performance and product compatibility. Includes water soluble films, sachets, pouches, and unit-dose packaging used for detergents, cleaning products, personal care products, water treatment chemicals, and other specialty applications requiring rapid and controlled dissolution.
Segment - Product
Revenue capture definition
Bags
Revenue generated from water soluble bags manufactured using dissolvable polymer materials for the safe storage, handling, and transportation of powders, chemicals, laundry products, medical waste, and other industrial materials. Includes biodegradable and water-dissolvable bags designed to minimize direct product contact and eliminate packaging waste after use.
Pouches
Revenue generated from water soluble pouches used for unit-dose packaging of detergents, agrochemicals, pharmaceuticals, personal care products, and specialty chemicals. Includes single-dose and multi-compartment dissolvable pouches that provide accurate dosing, improved product safety, and enhanced user convenience.
Pods & Capsules
Revenue generated from water soluble pods and capsules designed for pre-measured applications in laundry detergents, dishwashing products, cleaning agents, pharmaceuticals, and water treatment chemicals. Includes dissolvable pods and capsules that offer controlled product release, reduced product wastage, and improved handling efficiency across household and industrial applications.
Segment - Solubility Type
Revenue capture definition
Hot Water
Revenue generated from hot water-soluble packaging designed to dissolve at elevated water temperatures. Includes water soluble films, bags, pouches, pods, and capsules used for detergents, industrial chemicals, textile processing, healthcare, and specialty applications where controlled dissolution in hot water is required.
Cold Water
Revenue generated from cold water-soluble packaging designed to dissolve efficiently at ambient or low water temperatures. Includes water soluble films, pouches, bags, pods, and capsules used for laundry detergents, dishwashing products, agrochemicals, pharmaceuticals, personal care products, and other consumer and industrial applications requiring rapid dissolution without the need for heated water.
Segment - End-Use
Revenue capture definition
Household Products
Revenue generated from water soluble packaging products used for household cleaning and consumer products. Includes water soluble bags, pouches, pods, and capsules for laundry detergents, dishwashing detergents, surface cleaners, disinfectants, and other home care products designed for convenient unit-dose applications.
Agriculture
Revenue generated from water soluble packaging products used in agricultural applications. Includes dissolvable bags and pouches for pesticides, herbicides, fungicides, fertilizers, plant nutrients, and other agrochemicals that improve handling safety, reduce operator exposure, and minimize packaging waste.
Medical
Revenue generated from water soluble packaging products used in medical and healthcare applications. Includes dissolvable bags, pouches, films, and unit-dose packaging for pharmaceuticals, hospital laundry, infection control products, medical waste disposal, and healthcare chemicals that enhance hygiene and reduce contamination risks.
Retail
Revenue generated from water soluble packaging products supplied to the retail sector. Includes dissolvable packaging for consumer goods, personal care products, household products, and specialty retail items requiring sustainable, convenient, and single-dose packaging solutions.
Chemicals
Revenue generated from water soluble packaging products used for industrial and specialty chemicals. Includes dissolvable bags, pouches, and films for powders, additives, pigments, cleaning agents, and hazardous chemicals that improve product handling, dosing accuracy, and workplace safety.
Water Treatment
Revenue generated from water soluble packaging products used in water treatment applications. Includes dissolvable packaging for water purification chemicals, disinfectants, coagulants, and treatment additives used in municipal, industrial, and commercial water treatment facilities.
Animal Waste
Revenue generated from water soluble packaging products used for animal waste management. Includes dissolvable bags and liners designed for hygienic collection, handling, and disposal of pet waste, livestock waste, and veterinary applications while reducing environmental impact.
Fishing
Revenue generated from water soluble packaging products used in the fishing and aquaculture industry. Includes dissolvable bags, bait bags, and packaging for fishing baits, attractants, and aquaculture products that dissolve in water without leaving packaging residue.
Others (Food, Beverage)
Revenue generated from water soluble packaging products used in food, beverage, and other specialty applications. Includes dissolvable films, edible or water-soluble sachets, ingredient packaging, beverage additives, and customized packaging solutions designed for convenience, portion control, and sustainable packaging requirements.
Estimation Model
Layer Name
Key Question
Description
End-use Industry Demand Base Layer
What forms the demand base?
Identify the global demand generated by end-use industries including household products, agriculture, healthcare, chemicals, water treatment, retail, animal waste management, fishing, and food & beverage that require safe, convenient, and sustainable packaging solutions. This layer establishes the total addressable market based on detergent consumption, agrochemical usage, pharmaceutical production, specialty chemical demand, packaged consumer goods, and increasing adoption of environmentally friendly packaging across developed and emerging economies.
Water Soluble Packaging Adoption Layer
Where is water soluble packaging utilized?
Estimate the adoption of water soluble packaging across major end-use industries, including household products, agriculture, medical, chemicals, water treatment, retail, animal waste management, fishing, and food & beverage. Assess the penetration of water soluble bags, pouches, pods & capsules based on product safety requirements, unit-dose packaging demand, handling convenience, regulatory compliance, sustainability initiatives, and the need to minimize user exposure to hazardous substances.
Packaging Consumption Intensity Layer
How much water soluble packaging is utilized?
Analyze the volume of water soluble packaging consumed based on product production volumes, unit-dose consumption patterns, packaging frequency, formulation compatibility, and application-specific requirements. Packaging utilization is influenced by consumer demand for convenient dosing, growth in detergent pods, agrochemical packaging requirements, pharmaceutical unit-dose products, advancements in water soluble film technology, and increasing preference for biodegradable packaging materials.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of water soluble packaging products manufactured using polymers, fibers, surfactants, and other specialty dissolvable materials. Revenue is generated from sales of bags, pouches, pods & capsules with hot water and cold water solubility across household products, agriculture, healthcare, chemicals, water treatment, retail, animal waste management, fishing, food & beverage, and other industrial applications seeking sustainable, safe, and convenient packaging solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pricing Analysis
Comprehensive pricing analysis of water-soluble packaging products across material types, packaging formats, end-use industries, and major regional markets. Includes raw material cost trends, manufacturing cost structure, pricing variations by application, and competitive price benchmarking.
Supports pricing optimization, procurement planning, supplier evaluation, cost competitiveness analysis, and informed decision-making for product positioning and long-term sourcing strategies.
Trade Assessment
Detailed assessment of the global trade landscape for water-soluble packaging, including import-export trends, key exporting and importing countries, supply chain analysis, tariff and regulatory impact, and raw material sourcing patterns.
Helps identify trade opportunities, evaluate supply chain risks, optimize sourcing strategies, support market expansion decisions, and improve resilience against regional trade disruptions.
Opportunity Assessment
In-depth analysis of emerging growth opportunities across applications, end-use industries, and regional markets. Includes evaluation of high-growth sectors such as household detergents, agrochemicals, pharmaceuticals, personal care, and industrial chemicals, along with technological innovations and sustainability-driven market trends.
Enables identification of untapped revenue opportunities, supports investment prioritization, facilitates strategic product development, and assists stakeholders in capitalizing on evolving market trends and future growth potential.
Frequently Asked Questions About This Report
The global water-soluble packaging market was valued at USD 3.6 billion in 2025 and is estimated to reach USD 3.8 billion in 2026.
North America market dominated, with a revenue share of 32.4% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Hot water segment led the market with the largest revenue share of 59.57%in 2025.
Polymers segment led the market with the largest revenue share of 65.99% in 2025.
Bags segment led the market with the largest revenue share of 46.92% in 2025.
Key players in the water-soluble packaging market include Kuraray Co., Ltd., Sekisui Chemical Co., Ltd., Mitsubishi Chemical Group, Arrow Greentech Ltd., Mondi plc, Aicello Corporation, Cortec Corporation, Aquapak Polymers Ltd., Amtrex Nature Care Pvt. Ltd., and Changzhou Water Soluble Co., Ltd.
The global water-soluble packaging market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 5.7 billion by 2033.
The water-soluble packaging market is primarily driven by increasing demand for sustainable and biodegradable packaging, stringent regulations on plastic waste, rising adoption of unit-dose packaging in detergents and agrochemicals, expanding pharmaceutical and healthcare applications, and continuous advancements in water-soluble polymer technologies.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


