
- Home
- »
- Next Generation Technologies
- »
-
Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Market Report, 2033GVR Report cover

Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Chipset (Wi-Fi 6, Wi-Fi 6E, Wi-Fi 7), By Device (WLAN Infrastructure Devices, Consumer Devices, Wireless Cameras), By Application, By Region, And Segment Forecasts
Market Size, 2025
$43.8BMarket Estimate, 2026
$51.6BMarket Forecast, 2033
$141.2BCAGR, 2026–2033
15.5%Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Market Summary
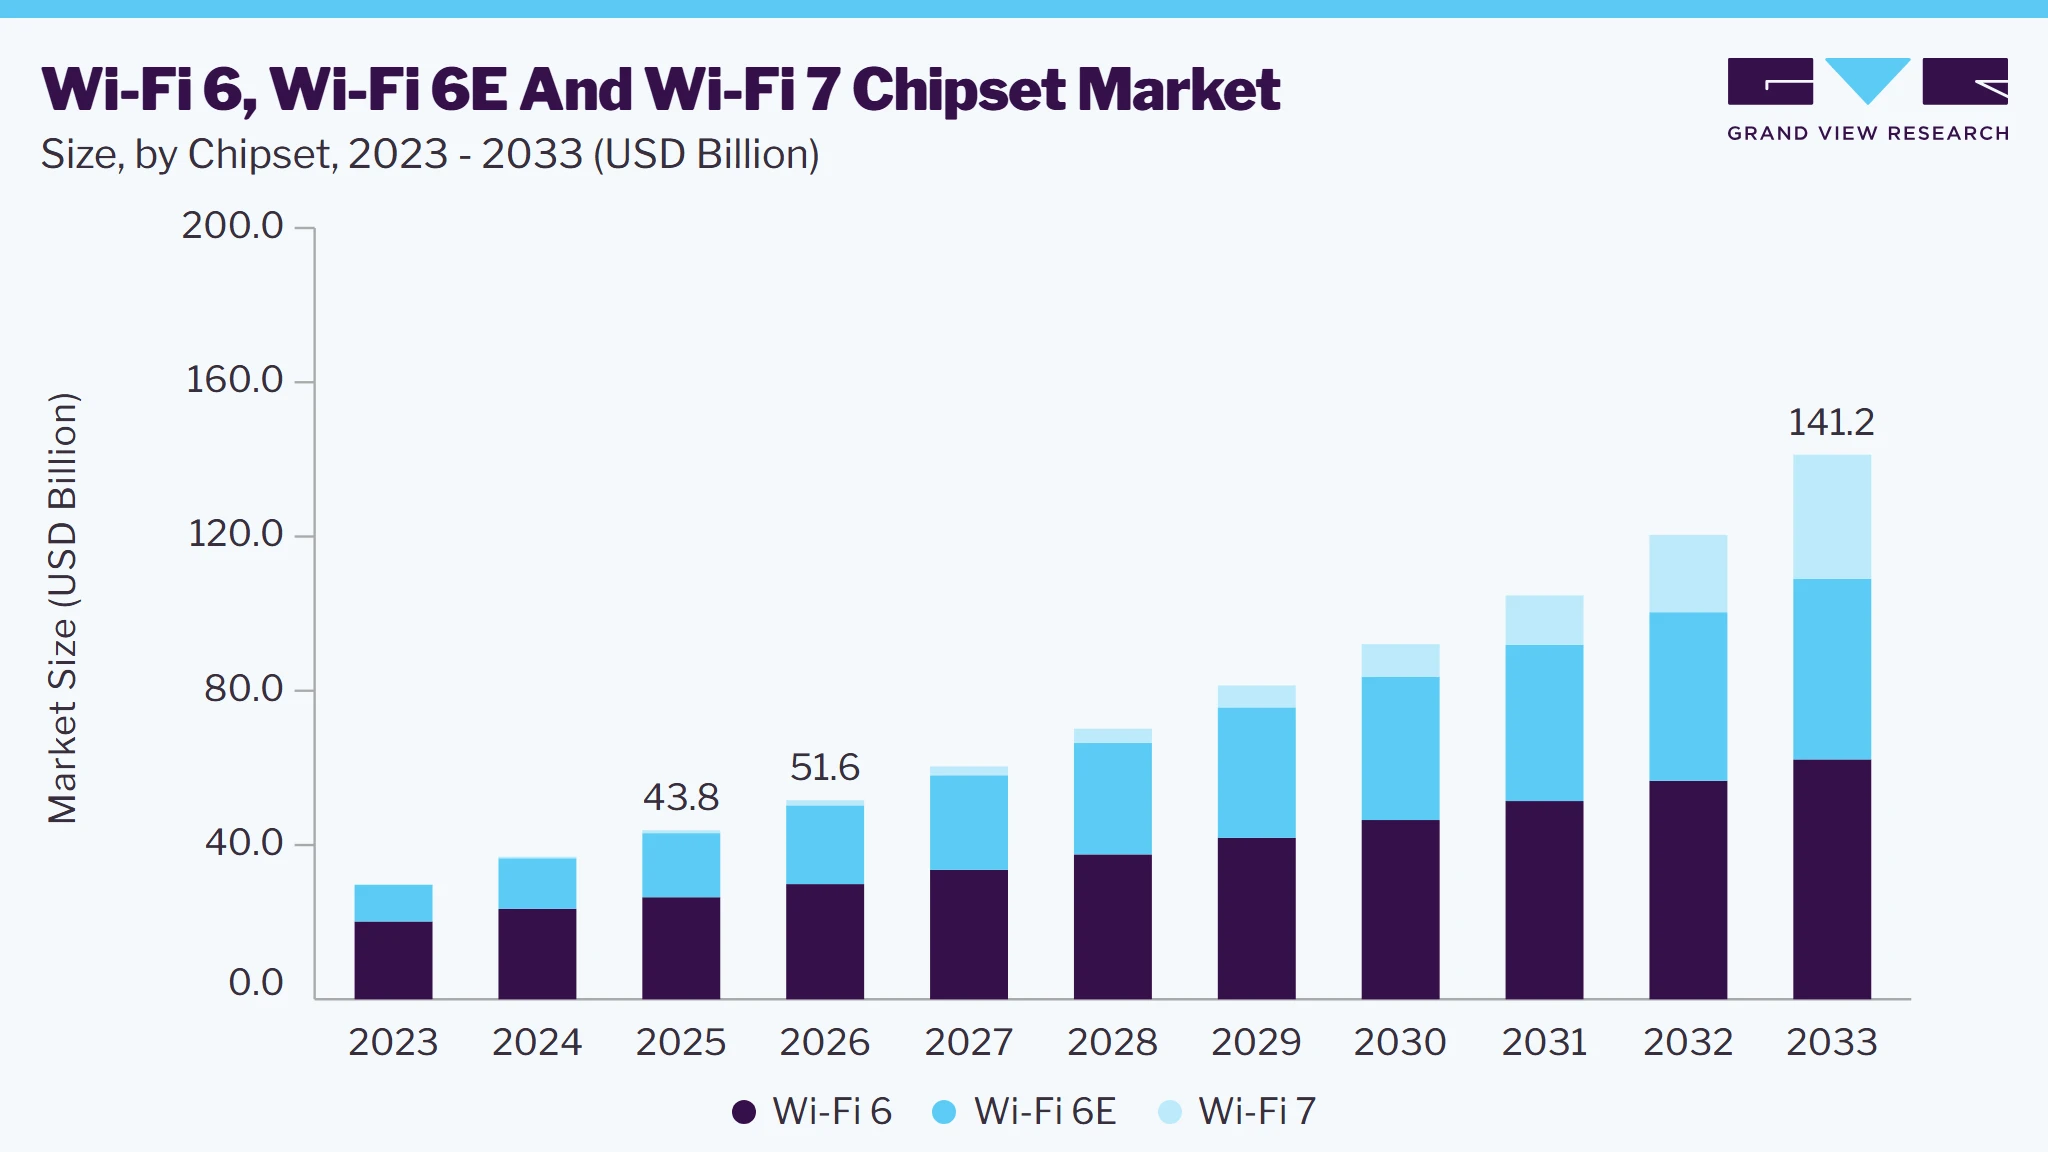
The global Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 chipset market size was valued at USD 43.8 billion in 2025 and is projected to grow from USD 51.6 billion in 2026 to USD 141.2 billion by 2033, at a CAGR of 15.5% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 37.7% in 2025. The growing need for enhanced networks, low latency, and high-bandwidth communications across enterprises is estimated to drive the Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 chipset industry during the forecast period.
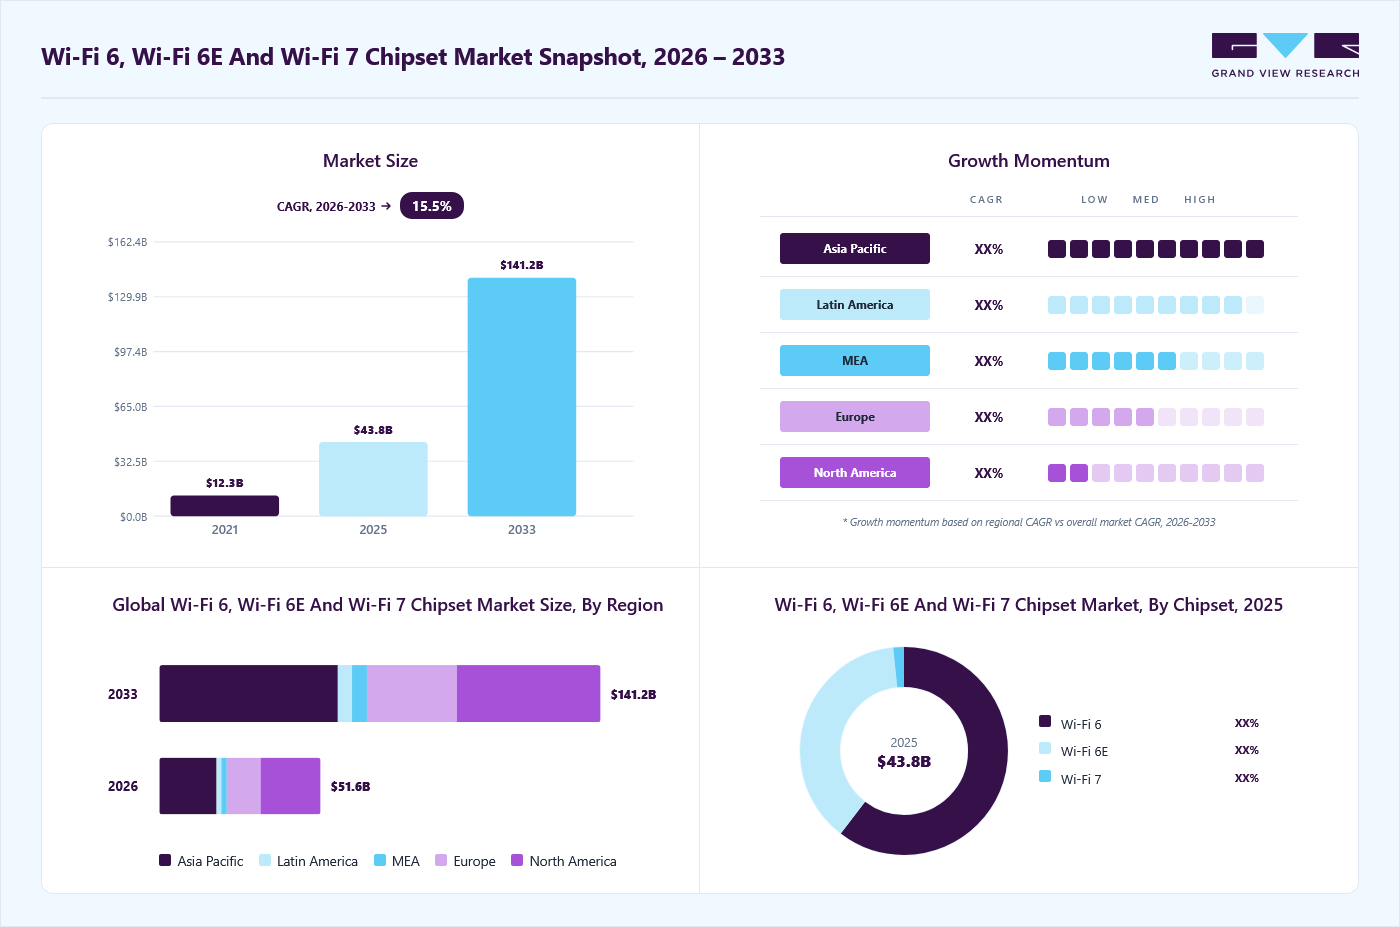 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By chipset: Wi-Fi 6 segment held the largest market share of 60.4% in 2025.
- By device: WLAN infrastructure devices segment held the largest market share of 39.4% in 2025.
- By application: Commercial segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (37.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 43.8 billion
- Estimated market size in 2026: USD 51.6 billion
- Projected market size by 2033: USD 141.2 billion
- CAGR (2026-2033): 15.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The significantly increasing data traffic has accelerated the need for superior network connectivity across several verticals, such as corporate and industrial. Thus, it is expected to boost the installations of wi-fi 6 and 6E devices and subsequently increase the demand for their chipsets in the next seven years.In 2020, Broadcom Inc. unveiled BCM4389, the world debut of the Wi-Fi 6E customer device. The device expands the level to accommodate the about-to-be-workable 6 GHz band alongside broader 160 MHz channel bandwidths, doubling the speeds and cutting latency in half compared to the previous device. The BCM4389 offers real-world rates of over 2 Gbps and up to 5 times better battery consumption, making it an excellent choice for future Augmented Reality/ Virtual Reality (AR/VR) devices and flagship smartphones. The benefits of the new chipset technology over the legacy wireless standard are expected to push its adoption significantly in the upcoming years.
 To learn more about this report, Download Free Sample Report
Manufacturing factories are evolving significantly to improve their operational efficiency. The adoption of modern devices such as Augmented Reality/Virtual Reality (AR/VR), wireless cameras, and collaborative robots is gaining momentum across the manufacturing industries. The operation of these devices seamlessly requires enhanced wireless network connectivity. Thus, it is expected to boost the adoption of Wi-Fi 6 and 6E devices and their components over the next seven years. Moreover, globally, rising trends of e-learning across universities and schools need unified network connectivity to deliver uninterrupted services. Thus, it is estimated to propel the global Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset industry growth over the coming years.
Regulatory trends in the market are evolving to accommodate the growing demand for faster and more efficient wireless technologies. Regulatory bodies worldwide, including the Federal Communications Commission (FCC) in the U.S. and the European Telecommunications Standards Institute (ETSI), are increasingly allocating more spectrum for unlicensed use in the 6 GHz band to support the expansion of Wi-Fi 6E and Wi-Fi 7. These regulatory changes are crucial in enabling broader deployment of next-gen Wi-Fi technologies and ensuring minimal interference in high-traffic environments. Additionally, governments are working to standardize technical specifications for Wi-Fi 6 and Wi-Fi 7, fostering global interoperability and providing a clear framework for chipset manufacturers.
Market Dynamics
The Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market is experiencing accelerated momentum driven by rising data traffic, proliferation of connected devices, and enterprise-grade wireless performance requirements. Network densification, cloud-native applications, and latency-sensitive use cases such as immersive media, industrial automation, and connected mobility are reshaping chipset demand. Regulatory approvals for extended spectrum bands, coupled with OEM migration toward next-generation WLAN standards, continue to redefine competitive intensity and technology roadmaps across consumer, commercial, and industrial segments.
The exponential growth of smartphones, IoT endpoints, smart home systems, and enterprise devices has placed significant pressure on legacy Wi-Fi standards. Conventional WLAN architecture faces challenges related to congestion, inefficient spectrum utilization, and degraded performance in dense environments such as offices, campuses, and public venues. As digital services increasingly rely on uninterrupted, low-latency connectivity, network performance has become a critical infrastructure requirement rather than a value-added feature.
Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipsets address these challenges through technologies such as OFDMA, MU-MIMO, wider channel bandwidths, and multi-link operation. These enhancements significantly improve spectral efficiency, reduce latency, and support simultaneous device connectivity. As a result, OEMs and network operators are accelerating chipset integration, directly supporting volume growth across infrastructure and end-device categories.
The adoption of Wi-Fi 6E and Wi-Fi 7 chipsets is constrained by higher silicon complexity, more demanding RF front-end requirements, and higher BOM costs. For price-sensitive consumer electronics and emerging markets, these cost premiums limit near-term mass adoption, particularly in mid-range and entry-level devices. In addition, backward compatibility and certification requirements add to development and deployment timelines.
Downstream impacts are most visible in cost-conscious regions across Asia, Latin America, and parts of Africa, where device replacement cycles remain longer. Small and mid-sized enterprises also delay infrastructure upgrades due to capital expenditure constraints. These factors collectively moderate short-term penetration of advanced Wi-Fi standards despite strong underlying demand fundamentals.
Enterprise digital transformation, Industry 4.0 initiatives, and private wireless deployments are creating a strong opportunity for advanced Wi-Fi chipsets. Manufacturing plants, logistics hubs, healthcare facilities, and smart campuses require deterministic performance, ultra-low latency, and high device density support. Regulatory expansion of the 6 GHz band further enhances deployment feasibility.
Wi-Fi 7 chipset vendors targeting industrial IoT, private enterprise networks, and premium infrastructure equipment are well positioned to capture this opportunity. Infrastructure-focused OEMs and chipset suppliers with strong ecosystem partnerships, advanced security features, and long-term support capabilities are expected to benefit disproportionately from enterprise and industrial adoption.
Analyst Perspective
The Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market is transitioning from consumer-led adoption toward enterprise and industrial-driven growth. Spectrum expansion, device densification, and latency-sensitive workloads are accelerating technology upgrades. Vendors are prioritizing premium performance, security, and multi-band capabilities to differentiate offerings. Investment activity is increasingly focused on Wi-Fi 7 development, industrial-grade Wi-Fi 6s, and ecosystem partnerships, indicating a structurally stronger long-term market trajectory.
Chipset Insights
Based on chipset, the Wi-Fi 6 segment led the market with the largest revenue share of 60.4% in 2025. The significant growth is attributed to the growing demand for high-performance network connectivity, allowing multi-users access simultaneously at constant bandwidth capacity. This segment is expected to witness considerable growth due to the high bandwidth needs of the mass population, where it needs to handle network congestion due to heavy network load. Rapidly growing demand for modern devices with the supporting capability of new wireless frequency bands such as 2.4GHz, 5GHz, and 6GHz is further expected to accelerate the adoption of Wi-Fi 6 chipsets. Additionally, offering BSS coloring features in the chipset technology would enhance the network reliability in a very dense ecosystem by enabling frames from the neighbor’s network. These frames assist in minimizing network interference from other networks and boosting network speed. It is anticipated to witness to a massive demand across residential, commercial, and industrial applications.
The Wi-Fi 7 segment is anticipated to register fastest growth over the forecast period. Wi-Fi 7 is the upgraded version of Wi-Fi 6E, with some enhanced technologies. The IEEE standard name of Wi-Fi 7 is 802.11be. It operates on a wide range of radio frequencies, such as 2.4GHz, 5GHz, and 6GHz. The maximum link rate that it offers is 40,000 Mbit/s. The Multiple Input Multiple Output (MIMO) enhancement and 16 spatial streams increase the video streaming quality and resolution. Wi-Fi 7 has a Hybrid Automatic Repeat Request (HARQ), which helps multiple link adaptation. The Wi-Fi 7 uses the modulation scheme known as 4K QAM, which increases the throughput value. It comes with flexible channel utilization, which reduces the interference in the signal and further enhances connectivity. Wi-Fi 7 offers wireless interface capacity up to 33Gbps and a threshold over 10Gbps throughputs.
Device Insights
Based on device, the WLAN infrastructure devices segment led the market with the largest revenue share of 39.4% in 2025. It is attributed to the soaring demand for chipsets to assemble into next-generation routers, gateways, repeaters, and extenders. A robust surge in the need for enhanced bandwidth capacity across enterprise customers is expected to ascend the global deployment of Wi-Fi 6 access points/routers. Furthermore, a high focus on providing superior client services and experience through fueling network bandwidth capacity is estimated to increase the adoption of next-generation WLAN infrastructure. Subsequently, it is likely to increase the Wi-Fi 6, 6E, and 7 chipsets demand for these WLAN devices.
The drone segment is anticipated to register a significant CAGR over the forecast period. The segment growth is driven by increasing demand for high-speed, reliable wireless connectivity in applications such as aerial imaging, delivery services, and industrial inspections. Wi-Fi 6 and 6E chipsets enhancing drones' ability to transmit large data volumes in real-time, offering lower latency and higher bandwidth to support advanced features like live-streaming, high-resolution video, and remote control. With the introduction of Wi-Fi 7, drones are expected to benefit from even faster data transfer rates, enabling smoother operation in complex environments, more efficient use of available spectrum, and improved overall performance.
Application Insights
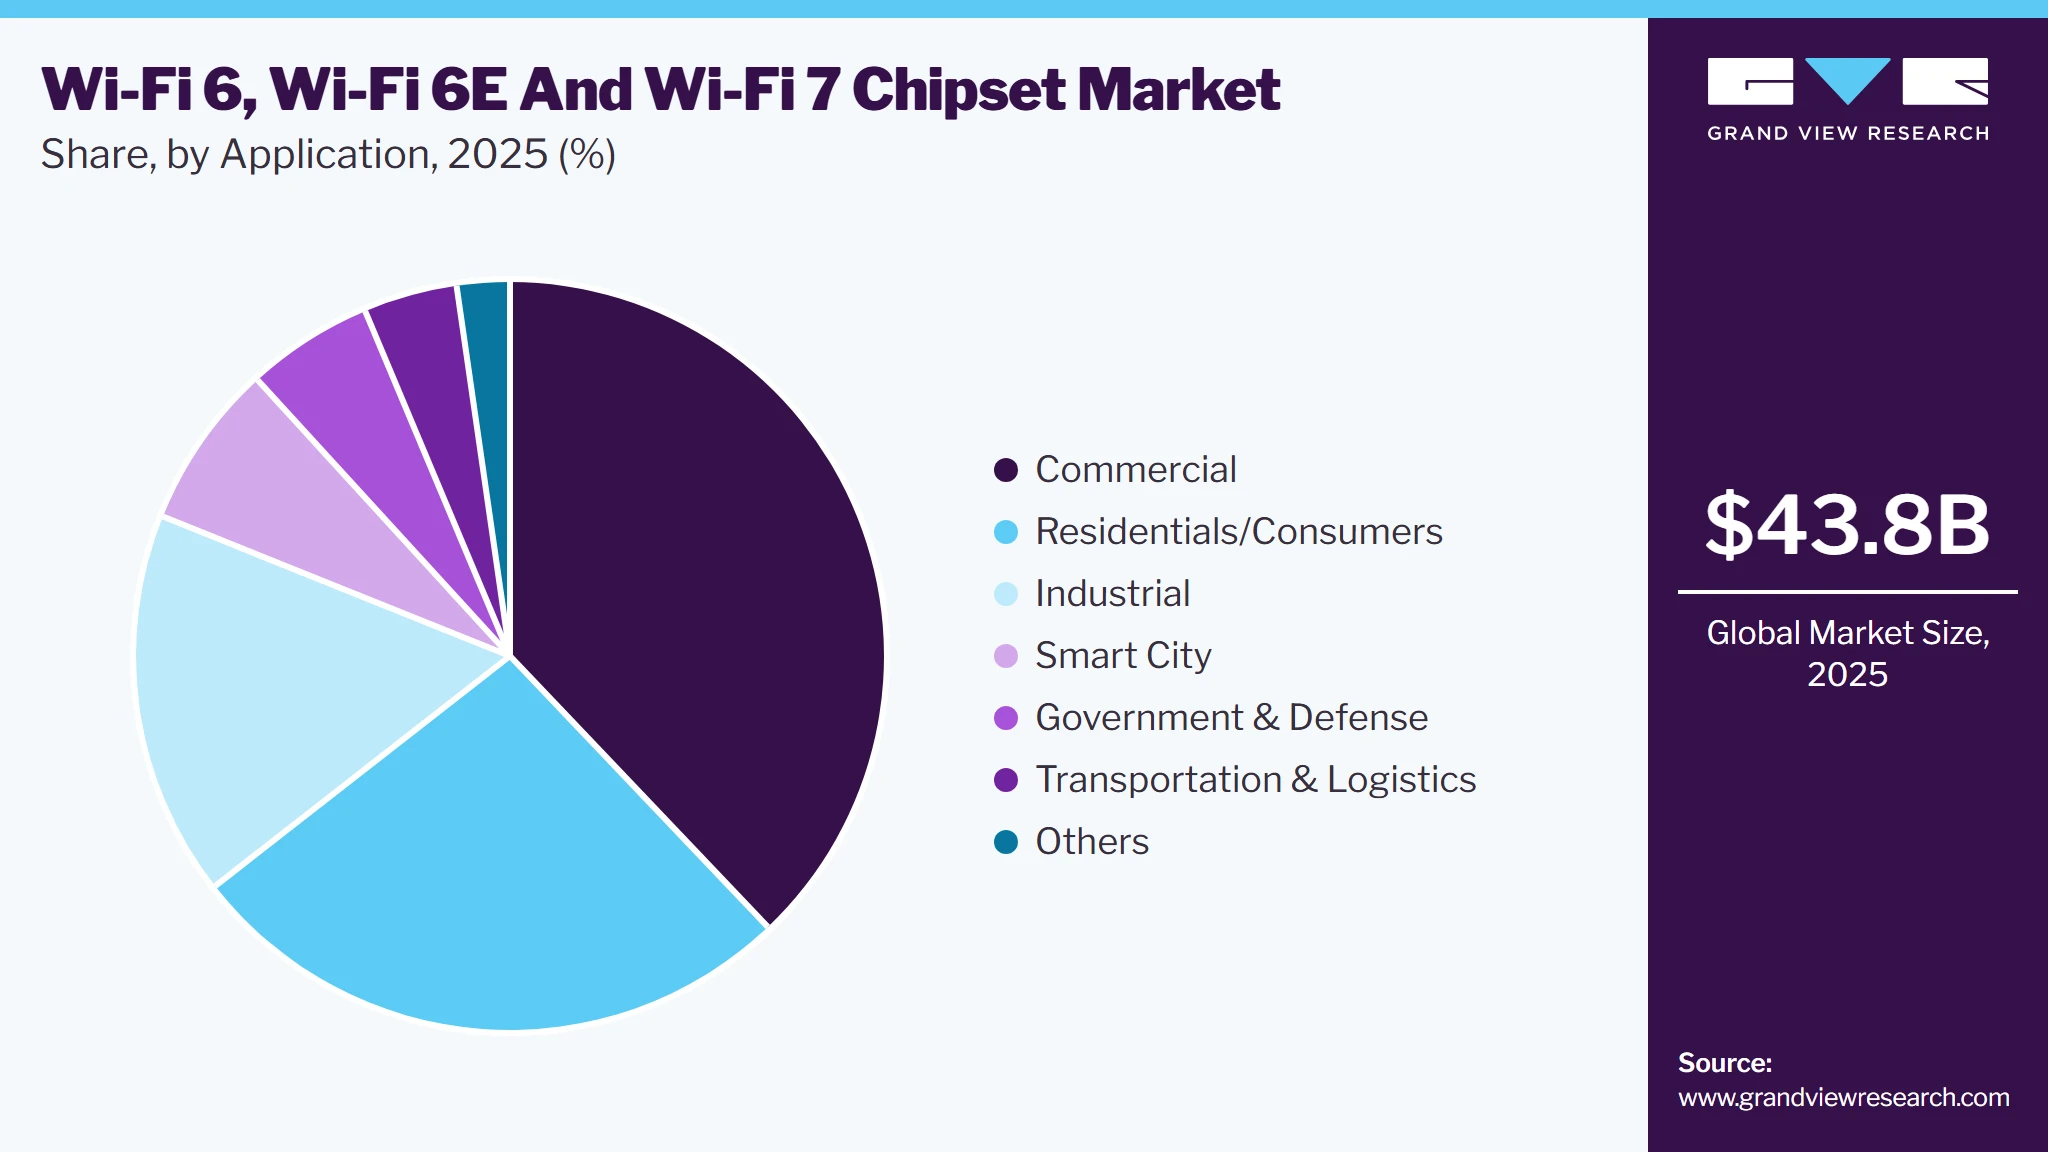
Based on application, the commercial segment led the market with the largest revenue share of 37.9% in 2025. This high growth is attributed to the rapidly increasing demand for superior wireless connectivity across corporate offices. Nowadays, corporate employees are collaborating with their clients and co-workers through video meetings, learning via streaming videos, and hosting numerous cloud applications. This requires high-speed internet connectivity and thereby raises the adoption of Wi-Fi routers and wifi-6, 6E, & 7 enabled end-user devices such as laptops. Resultantly, it is expected to increase the demand for chipsets over the forecast period.
 To learn more about this report, Download Free Sample Report
The industrial segment is anticipated to register the fastest CAGR over the forecast period. The growth can be attributed to the increasing adoption of smart manufacturing, industrial automation, and real-time data processing. Wi-Fi 6 and 6E chipsets offer enhanced connectivity, greater bandwidth, and reduced latency, enabling seamless communication between machines, sensors, and control systems in complex industrial environments. These advancements are particularly valuable in applications such as predictive maintenance, asset tracking, and process optimization.
Regional Insights
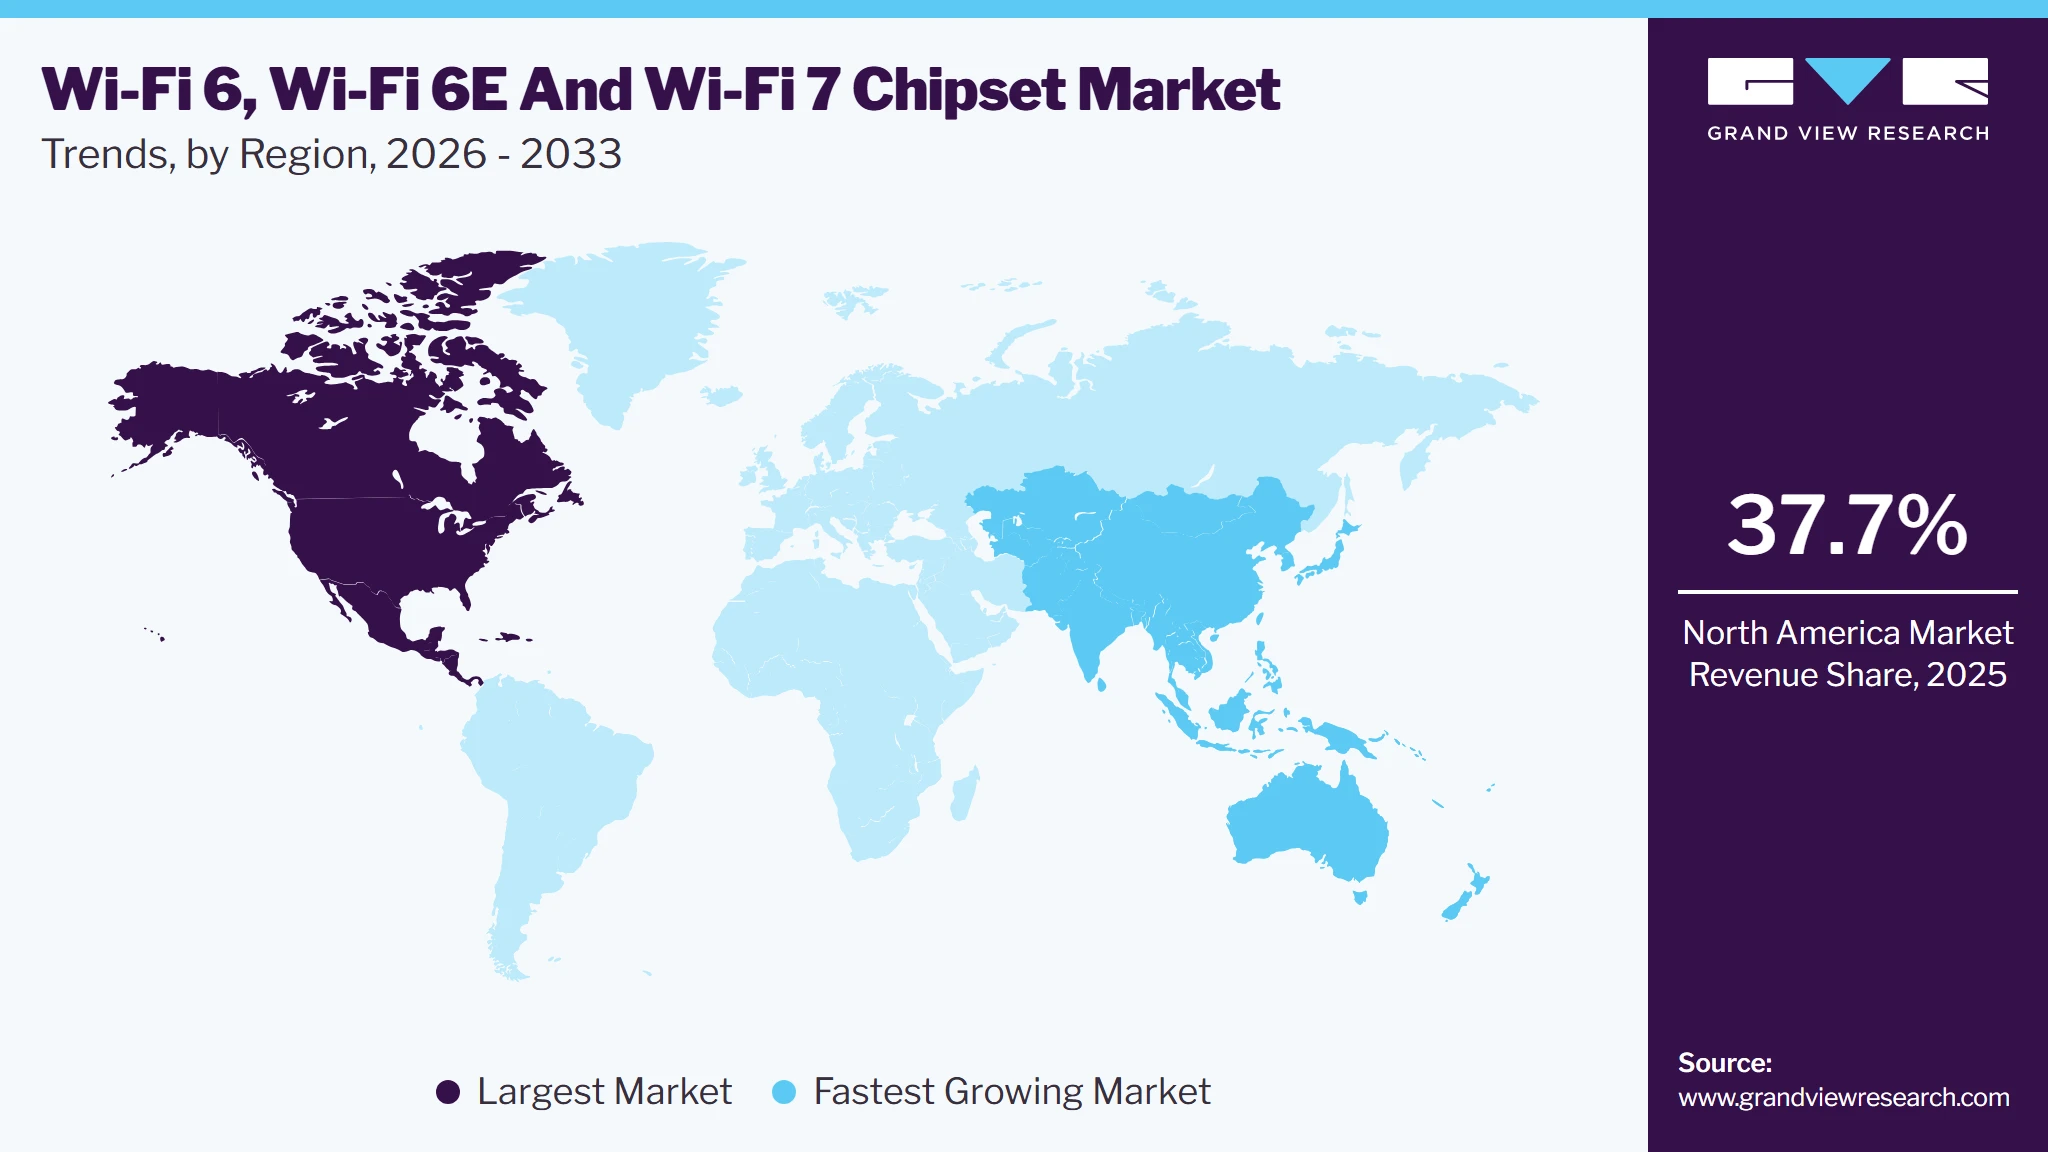
North America dominated the global Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset market with the largest revenue share of 37.7% in 2025. The market is experiencing significant growth, driven by increasing demand for faster, more reliable internet connections across consumer, enterprise, and industrial sectors. As businesses and consumers upgrade their networks to support high-bandwidth applications like video streaming , gaming, and IoT devices, the adoption of Wi-Fi 6 and Wi-Fi 6E technologies is accelerating, offering enhanced performance and reduced latency through wider channels and better spectrum utilization. The emerging Wi-Fi 7 standard, promising even faster speeds and lower latency, is poised to further drive innovation in the chipset market. With strong investments from leading chipset manufacturers and growing infrastructure deployment, the region is poised for a dynamic evolution in wireless connectivity technologies, with Wi-Fi 7 expected to play a key role in future-proofing networks for the next generation of digital services.
 To learn more about this report, Download Free Sample Report
U.S. Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Industry Trends
The Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset market in the U.S. held the largest share in the North America region in 2025. The U.S. Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market is driven by strong demand for faster and more reliable wireless connectivity across sectors like smart homes, enterprise, and healthcare. Wi-Fi 6 and Wi-Fi 6E are widely adopted in devices such as smartphones, routers, and laptops, offering improved speed and efficiency. With the rise of connected devices, Wi-Fi 7 is expected to further enhance performance, providing faster speeds and ultra-low latency for emerging applications. Intense competition among chipset manufacturers, along with ongoing R&D investment, is shaping the market's growth.
Europe Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 Chipset Market Trends
The increasing demand for the high-speed internet and seamless connectivity grows across both consumer and enterprise segments. The widespread adoption of Wi-Fi 6 and Wi-Fi 6E technologies is driven by the region's focus on improving broadband infrastructure and enabling efficient data transfer for applications such as smart cities, IoT, and remote work. As European businesses and consumers increasingly adopt next-gen networking solutions, Wi-Fi 7 is expected to become a key enabler for advanced use cases, including immersive technologies like AR/VR. The market is supported by EU regulations that promote the allocation of spectrum for Wi-Fi advancements, and leading chipset manufacturers are investing heavily in R&D to meet the region’s demand for cutting-edge wireless solutions.
The UK market is expanding as demand for fast, reliable wireless connectivity grows across sectors like retail, education, and healthcare. Adoption of Wi-Fi 6 and 6E is fueled by the need for supporting more devices and high-bandwidth applications. With government initiatives promoting digital transformation, Wi-Fi 7 is expected to enhance future technologies such as smart homes and autonomous vehicles. The market is boosted by R&D investments and new public Wi-Fi network rollouts, positioning the UK as a leader in wireless innovation.
The Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market in Germany is growing rapidly, driven by the country's strong digital infrastructure and high demand for reliable wireless connectivity in industries such as automotive, healthcare, and smart homes. Germany's emphasis on Industry 4.0 and the increasing adoption of IoT devices are pushing the need for faster and more efficient Wi-Fi networks. The transition to Wi-Fi 6 and 6E is enabling higher speeds and lower latency, while the anticipated arrival of Wi-Fi 7 will further bolster Germany’s position as a leader in technological innovation.
Asia Pacific Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 Chipset Market Trends
The Asia Pacific market is expected to grow at the highest CAGR over the forecast period, driven by the region's increasing adoption of digital technologies across industries like healthcare, education, and smart homes. Wi-Fi 6 and 6E adoption is particularly strong in countries such as South Korea, where smart city initiatives and high-speed internet requirements are key drivers. With the growing need for faster, more reliable networks, Wi-Fi 7 is expected to further enhance connectivity and fuel the region’s tech advancements, from consumer electronics to industrial applications.
China’s Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market is experiencing exponential growth, fueled by the country’s massive digital transformation, including the expansion of smart cities and 5G networks. With a focus on supporting IoT devices, autonomous vehicles, and AI applications, China is adopting Wi-Fi 6 and 6E technologies to handle the growing demand for data-heavy applications. The introduction of Wi-Fi 7 is expected to provide even faster speeds and greater network efficiency, catering to China’s ambitious tech initiatives and global connectivity goals.
The Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market in India is on the rise, driven by rapid urbanization, increased smartphone penetration, and a growing demand for digital services. The adoption of Wi-Fi 6 and 6E is gaining traction in urban areas, particularly for applications in education, healthcare, and e-commerce. With the government’s push towards a Digital India and greater internet accessibility, Wi-Fi 7 is expected to play a key role in boosting connectivity and enabling next-gen services like smart cities and IoT infrastructure.
Japan's Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market is advancing as the country continues to lead in technology innovation and smart infrastructure development. The shift towards Wi-Fi 6 and 6E is spurred by the growing demand for high-performance connectivity in sectors like manufacturing, robotics, and entertainment. With the upcoming rollouts of Wi-Fi 7, Japan aims to further improve its digital landscape, facilitating applications such as 8K video streaming, autonomous systems, and enhanced industrial automation.
Key Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Company Insights
Some of the key companies in the Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset industry include Broadcom Inc., Qualcomm Technologies, Inc., Intel Corporation, and others. The companies are consistently pushing the boundaries of wireless technology with new chipset releases. The rollout of Wi-Fi 6E and the anticipated transition to Wi-Fi 7 has intensified the race, as companies strive to develop next-generation chipsets that can handle increased spectrum, faster speeds, and ultra-low latency required by future digital services.
-
Broadcom Inc. is a leading global technology company that designs, develops, and supplies a broad range of semiconductor and infrastructure software solutions. The company operates across diverse sectors, including data center, networking, broadband, wireless communications, and enterprise software. Its extensive product portfolio includes broadband modems, network switches, wireless chips, optical sensors, and memory solutions. Broadcom is also a prominent provider of connectivity solutions, including Wi-Fi, Bluetooth, and 5G technology, catering to industries such as telecommunications, automotive, and consumer electronics.
-
Qualcomm Technologies Inc. is a leader in wireless technology and semiconductors, specializing in the design and development of mobile communications and connectivity solutions. The company operates across diverse sectors, including mobile, automotive, IoT, networking, and computing. Qualcomm’s extensive product portfolio includes advanced chipsets for smartphones, 5G infrastructure, automotive solutions, Wi-Fi technology, and IoT devices.
Key Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Companies:
The following key companies have been profiled for this study on the wi-fi 6, wi-fi 6E And wi-fi 7 chipset market.
-
Broadcom Inc.
-
Qualcomm Technologies, Inc.
-
ON Semiconductor Connectivity Solutions, Inc.
-
Intel Corporation
-
Celeno
-
MediaTek Inc.
-
Texas Instruments Incorporated
-
Cypress Semiconductor Corporation
-
STMICROELECTRONICS N.V.
-
NXP SEMICONDUCTORS N.V.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Broadcom Inc., Qualcomm Technologies, Inc., Intel Corporation, MediaTek Inc., Texas Instruments Incorporated)
- These players are focused on broad portfolio development across consumer, enterprise, and infrastructure-grade Wi-Fi chipsets; continuous investment in next-generation standards; deep OEM and ecosystem partnerships
- Strong IP ownership, advanced silicon integration capabilities, global customer base, and early adoption of Wi-Fi 6E and Wi-Fi 7 standards
- High R&D and fabrication costs; longer product qualification cycles for niche and industrial deployments
Emerging Players (Celeno, ON Semiconductor Connectivity Solutions, Inc.)
- These players are focused product strategies targeting specific performance gaps; emphasis on power efficiency, interference mitigation, and cost-optimized designs
- Agile innovation, differentiated PHY/MAC technologies, and targeted positioning in residential and industrial segments
- Limited scale, narrower product portfolios, and lower pricing leverage compared to established competitors
Recent Developments
-
In October 2024, Silicon Labs launched the SiWx917 Wi-Fi 6 chipset platform, specifically designed for IoT applications. This ultra-low power chipset offers up to two years of battery life, making it ideal for a wide array of IoT use cases in both residential and industrial sectors. Targeted home applications include HVAC systems, smart locks, cameras, sensors, and appliances, while its industrial applications support predictive maintenance, smart meters, asset tracking, and other sensor-driven solutions.
-
In September 2023, Intel Corporation introduced two new networking chipsets, the Wi-Fi 7 BE200 and BE202, based on the IEEE 802.11be (Wi-Fi 7) specification. The Wi-Fi 7 standard offers data rates up to 40 Gbit/s, with the BE200 chipset utilizing 2x2 TX/RX streams across the 2.4 GHz, 5 GHz, and 6 GHz frequency bands to enhance connectivity and performance.
Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 Chipset Market Report Scope
Report Attribute
Details
Market size in 2025
USD 43.8 billion
Estimated market size in 2026
USD 51.6 billion
Projected market size by 2033
USD 141.2 billion
Growth rate
CAGR of 15.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Chipset, device, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Broadcom Inc.; Qualcomm Technologies, Inc.; ON Semiconductor Connectivity Solutions, Inc.; Intel Corporation; Celeno; MediaTek Inc.; Texas Instruments Incorporated; Cypress Semiconductor Corporation; STMICROELECTRONICS N.V.; NXP SEMICONDUCTORS N.V.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 Chipset Market Report Segmentation
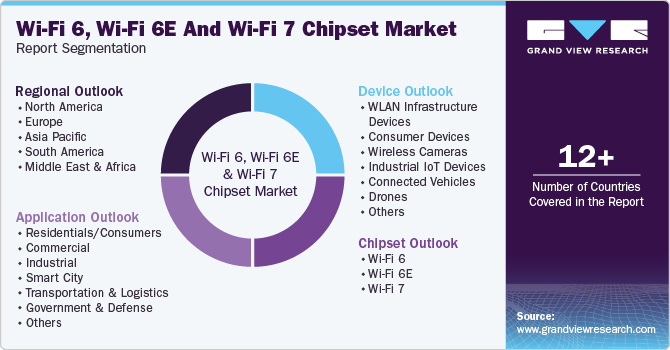
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset market report based on chipset, device, application, and region.
 To learn more about this report, Download Free Sample Report
-
Chipset Outlook (Revenue, USD Million; 2021 - 2033)
-
Wi-Fi 6
-
Wi-Fi 6E
-
Wi-Fi 7
-
-
Device Outlook (Revenue, USD Million; 2021 - 2033)
-
WLAN Infrastructure Devices
-
Consumer Devices
-
Smartphones/Tablets
-
Desktops/Laptops
-
AR/VR and Wearables
-
Smart Home Devices
-
Others
-
-
Wireless Cameras
-
Industrial IoT Devices
-
Connected Vehicles
-
Drones
-
Others
-
-
Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Residentials/Consumers
-
Commercial
-
Enterprises/Corporates
-
Airports
-
Stadiums
-
Malls/Shops
-
Hospitals
-
Hotels & Restaurants
-
Educational Campuses
-
Others
-
-
Industrial
-
Smart Manufacturing
-
Energy & Utility
-
Oil & Gas and Mining
-
-
Smart City
-
Transportation & Logistics
-
Government & Defense
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
South America
-
Brazil
-
-
Middle East & Africa
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Research Methodology
The Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Wi-Fi 6, Wi-Fi 6E And Wi-Fi 7 chipset segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Chipset
Revenue capture definition
Wi-Fi 6
Revenue generated from the sale of Wi-Fi 6 (IEEE 802.11ax) chipsets supplied to OEMs, ODMs, and device manufacturers for integration into WLAN infrastructure equipment, consumer electronics, industrial devices, connected vehicles, and other Wi-Fi-enabled products.
Wi-Fi 6E
Revenue generated from the sale of Wi-Fi 6E chipsets supporting operation in the 6 GHz band, supplied for integration into enterprise networking equipment, premium consumer devices, industrial systems, and other products requiring enhanced spectrum availability and reduced interference.
Wi-Fi 7
Revenue generated from the sale of Wi-Fi 7 (IEEE 802.11be) chipsets integrated into next-generation WLAN infrastructure, consumer devices, industrial equipment, automotive systems, and other applications requiring ultra-high throughput, low latency, and advanced wireless performance.
Segment - Device
Revenue capture definition
WLAN Infrastructure Devices
Revenue generated from Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipsets sold for integration into routers, gateways, mesh systems, access points, WLAN controllers, and other wireless networking infrastructure equipment.
Consumer Devices
Revenue generated from Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipsets integrated into consumer electronic devices used for personal connectivity, entertainment, communication, and smart living applications such as:
- Smartphones/Tablets: Revenue generated from Wi-Fi chipsets integrated into smartphones and tablets to provide wireless internet connectivity, content streaming, gaming, and application access.
- Desktops/Laptops: Revenue generated from Wi-Fi chipsets embedded in desktop PCs, notebooks, and laptop computers to enable wireless networking and internet connectivity.
- AR/VR and Wearables:Revenue generated from Wi-Fi chipsets supplied for AR/VR headsets, smart glasses, smartwatches, fitness trackers, and other wearable devices requiring high-bandwidth and low-latency connectivity.
- Smart Home Devices: Revenue generated from Wi-Fi chipsets integrated into smart speakers, connected appliances, thermostats, security systems, lighting products, and other home automation devices.
- Others:Revenue generated from Wi-Fi chipsets embedded in gaming consoles, smart TVs, set-top boxes, printers, media streaming devices, and other connected consumer electronics.
Wireless Cameras
Revenue generated from Wi-Fi chipsets integrated into residential and commercial surveillance cameras, video monitoring systems, and related imaging devices.
Industrial IoT Devices
Revenue generated from Wi-Fi chipsets supplied for industrial sensors, gateways, machine controllers, robotics, and connected factory equipment used in industrial environments.
Connected Vehicles
Revenue generated from Wi-Fi chipsets integrated into passenger and commercial vehicles for infotainment systems, diagnostics, software updates, telematics, and in-vehicle connectivity applications.
Drones
Revenue generated from Wi-Fi chipsets embedded in commercial, industrial, and consumer drones to support wireless control, navigation, video transmission, and data communication.
Others
Revenue generated from Wi-Fi chipsets integrated into specialized or emerging connected devices not classified under the above categories.
Segment - Application
Revenue capture definition
Residential / Consumers
Revenue generated from Wi-Fi chipsets integrated into devices and networking equipment deployed in residential environments for broadband access, entertainment, gaming, and smart home connectivity.
Commercial
The segment Represents Wi-Fi chipset revenues attributable to networking infrastructure and connected devices deployed across commercial establishments, public venues, and business environments.
- Enterprises / Corporates: Consists of Wi-Fi chipset revenues derived from enterprise-grade access points, routers, gateways, PCs, and connected devices used within corporate offices and business facilities.
- Airports: Covers Wi-Fi chipset revenues associated with wireless networking infrastructure and connected systems deployed within airport facilities for passenger connectivity, operational communications, and digital services.
- Stadiums: Represents Wi-Fi chipset revenues linked to high-density wireless infrastructure and connected systems installed in sports arenas, event venues, and entertainment facilities.
- Malls/Shops: Includes Wi-Fi chipset revenues attributable to retail networking infrastructure, point-of-sale systems, customer connectivity platforms, digital signage, and other connected retail applications.
- Hospitals: Consists of Wi-Fi chipset revenues associated with healthcare networking infrastructure, connected medical devices, patient monitoring systems, and digital healthcare applications.
- Hotels & Restaurants: Covers Wi-Fi chipset revenues derived from hospitality networking equipment and connected systems supporting guest connectivity and operational services.
- Educational Campuses: Represents Wi-Fi chipset revenues attributable to campus-wide networking infrastructure, connected educational devices, research networks, and digital learning environments.
- Others: Others segments include additional commercial environments such as offices in mixed-use buildings, convention centers, co-working spaces, entertainment venues, and service facilities that deploy Wi-Fi networks to support employee operations, customer connectivity, and digital service delivery beyond core commercial categories.
Industrial
Comprises Wi-Fi chipset revenues linked to industrial networking infrastructure, connected machinery, automation systems, and Industrial IoT deployments.
- Smart Manufacturing: Consists of Wi-Fi chipset revenues attributable to factory automation systems, robotics, machine-to-machine communications, industrial gateways, and connected production equipment.
- Energy & Utility: Covers Wi-Fi chipset revenues associated with smart grid infrastructure, utility monitoring systems, metering equipment, and operational communication networks.
- Oil & Gas and Mining: Represents Wi-Fi chipset revenues linked to ruggedized networking equipment, monitoring systems, connected assets, and industrial communications deployed in oil, gas, and mining operations.
Smart City
Includes Wi-Fi chipset revenues attributable to connected urban infrastructure such as surveillance systems, traffic management solutions, public Wi-Fi networks, and municipal IoT deployments.
Transportation & Logistics
Consists of Wi-Fi chipset revenues associated with warehouses, fleet management systems, ports, transportation hubs, logistics infrastructure, and asset tracking applications.
Government & Defense
Covers Wi-Fi chipset revenues linked to government communication networks, public safety systems, defense infrastructure, and mission-critical wireless deployments.
Others
Includes Wi-Fi chipset revenues associated with niche, emerging, or specialized application areas not categorized under the above segments.
Estimation Model
Layer Name
Key Question
Description
End-Use Demand Layer
Where is Wi-Fi connectivity demand generated?
Assesses device-level and infrastructure demand across consumer, enterprise, and industrial applications adopting Wi-Fi 6, 6E, and 7 standards.
Device Penetration Layer
Which devices integrate advanced Wi-Fi chipsets?
Evaluates penetration rates of Wi-Fi standards across routers, smartphones, PCs, and industrial equipment.
Chipset ASP Layer
What is the value captured per integration?
Analyzes average selling prices across chipset generations based on performance tier and integration complexity.
Supplier Revenue Layer
How is revenue distributed among vendors?
Aggregates chipset shipments and ASPs to derive vendor-level and market-level revenues.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 Chipset Market Opportunity Assessment
Evaluated regional demand drivers and spectrum availability
Assessed enterprise and consumer adoption patterns by geography
Identified regions with accelerated transition to Wi-Fi 6E and Wi-Fi 7
Highlighted region-specific growth pockets
Supported regional expansion and localization strategies
Improved investment prioritization by geography
Cross-Segmentation Analysis for the Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 Chipset Market
Delivered cross-sectional analysis offering adoption across device categories and application areas
Benchmarked demand intensity across consumer, enterprise, and industrial segments
Assessed segment-level technology migration patterns
Identified high-potential device and application combinations
Supported targeted product positioning
Enhanced segment-wise resource allocation decisions
Competitive Benchmarking and Strategic Positioning
Benchmarked competitors across technology readiness and portfolio breadth
Compared innovation focus and ecosystem alignment
Evaluated relative strengths in Wi-Fi 6, 6E, and 7 deployments
Identified competitive white spaces
Supported differentiation and roadmap alignment
Enabled data-driven competitive strategy formulation
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The Wi-Fi 6 segment dominated the market, with a revenue share of 60.4% in 2025.
North America dominated the Wi-Fi 6, Wi-Fi 6E and Wi-Fi 7 chipset market with the largest revenue share of 37.7% in 2025. The market is experiencing significant growth, driven by increasing demand for faster, more reliable internet connections across consumer, enterprise, and industrial sectors.
The global Wi-Fi 6, Wi-Fi 6e and Wi-Fi 7 chipset market size was valued at USD 43.8 billion in 2025 and is estimated at USD 51.6 billion for 2026.
The global Wi-Fi 6, Wi-Fi 6e and Wi-Fi 7 chipset market is expected to grow at a CAGR of 15.5% from 2026 to 2033, reaching USD 141.2 billion by 2033.
Some key players operating in the Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset market include Broadcom Inc.; Qualcomm Technologies, Inc.; ON Semiconductor Connectivity Solutions, Inc.; Intel Corporation; Celeno; MediaTek Inc.; Texas Instruments Incorporated; Cypress Semiconductor Corporation; STMICROELECTRONICS N.V.; NXP SEMICONDUCTORS N.V.
The growing need for enhanced network performance, low-latency, and high-bandwidth communications across enterprises is estimated to drive the Wi-Fi 6, Wi-Fi 6E, and Wi-Fi 7 chipset industry during the forecast period.
The WLAN infrastructure devices segment held the largest market share of 39.4% in 2025, while Industrial IoT devices is the fastest-growing segment.
The commercial segment held the largest revenue share of 37.9% in 2025, while industrial is the fastest-growing segment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


