
- Home
- »
- Alcohol & Tobacco
- »
-
Wine Market Size, Share & Trends, Industry Report, 2033GVR Report cover

Wine Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Table Wine, Dessert Wine, Sparkling Wine), By Distribution Channel (On-Trade And Off-Trade), By Region (North America, Europe, APAC, MEA, Central & South America), And Segment Forecasts
Market Size, 2025
$549.6BMarket Estimate, 2026
$589.8BMarket Forecast, 2033
$1,082.0BCAGR, 2026–2033
9.1%Wine Market Summary
The global Wine market size was valued at USD 549.6 billion in 2025 and is projected to grow from USD 589.8 billion in 2026 to USD 1082.0 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. Europe dominated the global market, with a revenue share of 44.5% in 2025. The growth of the premium wine market is attributed to the increasing popularity of premium and super-premium wines, particularly among younger consumers in emerging markets.
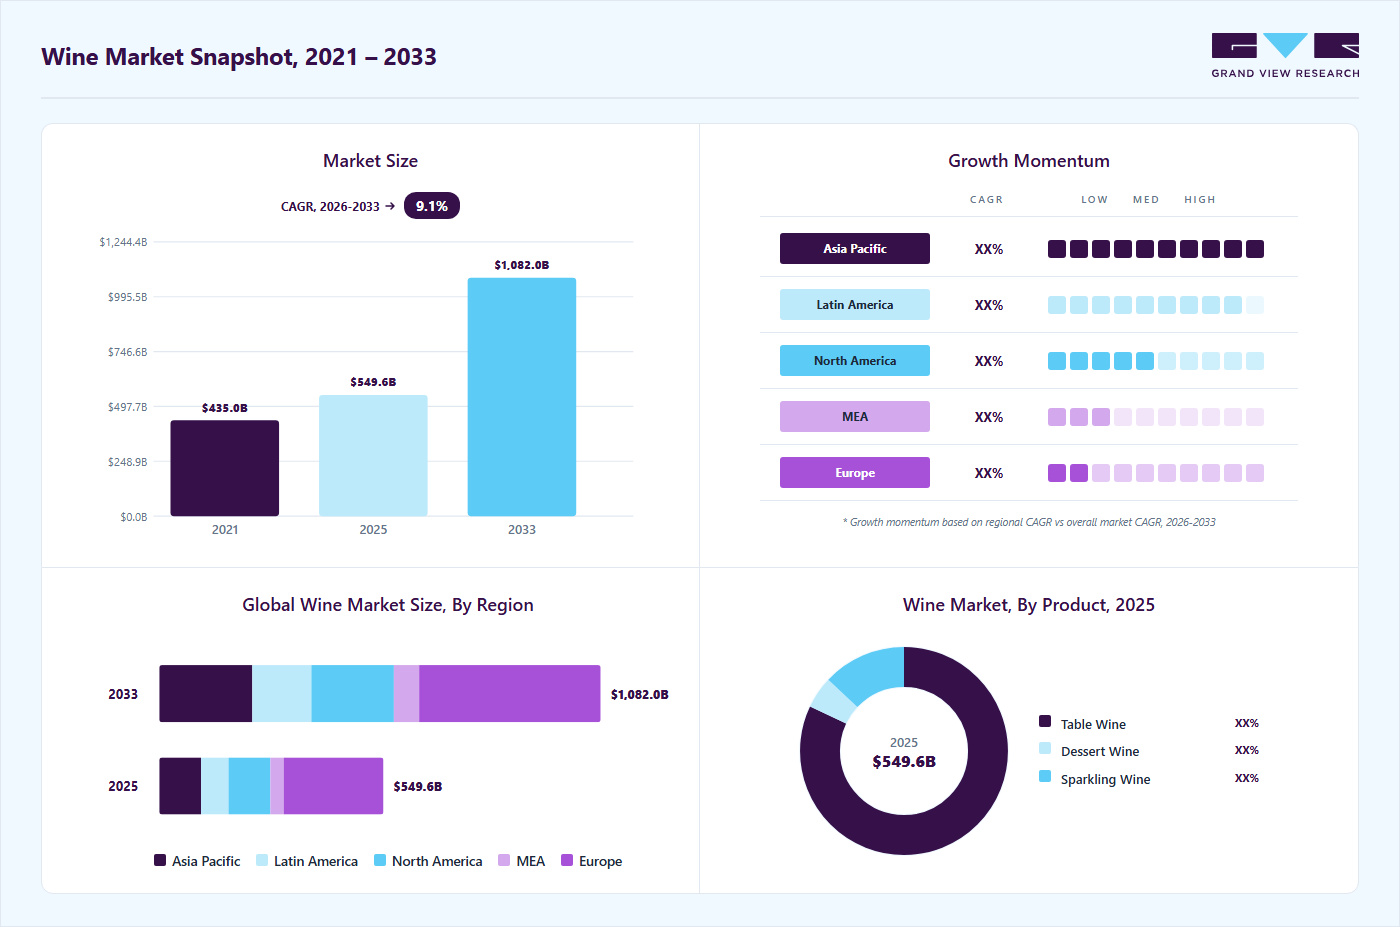 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Table wine segment led the market and accounted for a share of 81.9% in 2025.
- By distribution channel: Off-trade segment led the market and accounted for a share of 77.5% in 2025.
Regional Highlights
- Largest regional market: Europe (44.5% revenue share, 2025)
- Germany held the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 549.6 Billion
- Estimated market size in 2026: USD 589.8 Billion
- Projected market size by 2033: USD 1082.0 Billion
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These consumers are seeking higher-quality, more sophisticated wines and are willing to pay a premium for them. The global wine market is being reshaped by a convergence of premium‑centric, sustainability‑focused, and digitally‑enabled trends that together fuel robust demand growth. Consumers in mature markets are gravitating toward “premiumization,” willing to pay higher prices for provenance‑rich, single‑vineyard or organic wines, while younger drinkers prioritize low‑alcohol, natural, and carbon‑neutral offerings, prompting producers to expand biodynamic and low‑intervention portfolios. Moreover, the expanding middle class in emerging economies, particularly in the Asia-Pacific, is contributing significantly to increased wine consumption. Rising disposable incomes allow more people to explore and enjoy wine as a lifestyle choice, driving the growth of the luxury wine market. Increased tourism and globalization also play a role, exposing individuals to different wine cultures and varieties.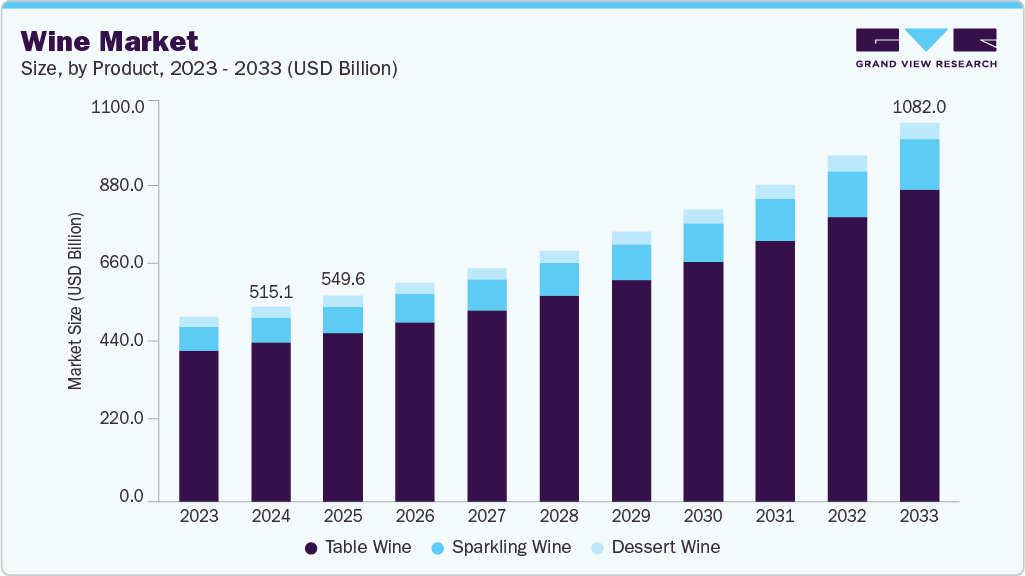 To learn more about this report, Download Free Sample Report
Moreover, the perception of wine as a sophisticated, health-conscious beverage is fueling demand, particularly when consumed in moderation. Finally, strategic marketing and promotional efforts by wine producers, focusing on education and storytelling, are effectively attracting new consumers and solidifying the loyalty of existing ones. For instance, in September 2025, the distribution of premium wine brands from Bogle Family Wine Collection was expanded across California through Southern Glazer’s Wine & Spirits, resulting in increased retail penetration and supply chain efficiency.
Another significant trend is the growing demand for sustainable and organically produced wines, reflecting a broader consumer focus on environmental consciousness and health, driving the growth of the organic wine market. Rosé wine continues its upward trajectory, driven by its refreshing character and versatility, making it a popular choice for a range of occasions. Furthermore, e-commerce and online wine subscriptions are rapidly expanding, creating new avenues for wine producers to reach consumers directly and personalize their offerings in the wine & spirits industry. In February 2025, a new 2024 Rosé was launched through a collaboration between Valdemar Estates and VITAL Wines, and healthcare funding for vineyard workers was supported as part of the brand’s ESG-driven premium wine strategy.
Emerging markets, particularly in the Asia Pacific, are also contributing to the growth of the wine industry. Countries such as China, India, and South Korea are seeing increased wine consumption due to rising disposable incomes, urbanization, and greater exposure to Western drinking habits. At the same time, sustainability and environmental consciousness are shaping purchasing decisions, leading to a higher demand for organic, natural, and sustainably produced wines. Wineries adopting eco-friendly practices, such as organic farming, recyclable packaging, and renewable energy use, are gaining favor among environmentally conscious consumers. This is driving the growth of the natural wine market.
There has been an increase in preference for sparkling wines. American wine preferences reflect a strong inclination toward smoother, fruitier wines, suggesting a widespread appreciation for balanced, approachable flavors. Semi-sweet and sweet wines also enjoy notable popularity, indicating a preference for wines with a touch of sweetness that appeal to a broad audience.
Meanwhile, dry and savory wines maintain a steady following, likely appealing to those who appreciate more structured, complex profiles. Tannic wines, which have a bold and intense character, appear to have a more niche appeal. These preferences highlight the diverse palates of American consumers and the evolving trends shaping the natural wine market. In April 2025, Target launched its Collective Good wine range, including table wine varietals such as Cabernet Sauvignon and Pinot Grigio packaged in sustainable paper bottles, expanding eco-friendly table wine offerings across nearly 1,200 retail stores.
Innovation in wine varieties and packaging formats is further driving the growth of the sparkling wine market. The wine industry has seen a rise in sparkling wines, fruit-infused wines, and alternative packaging options such as canned wine, boxed wine, and single-serve bottles. This diversification appeals to a broader audience, making wine consumption more convenient and adaptable to different lifestyles.
Wine tourism has also become a major growth driver, with destinations like France, Italy, Spain, the U.S., and Australia attracting visitors eager for immersive vineyard experiences. These experiences not only boost local economies but also encourage global wine sales as travelers bring back their newly discovered favorites. This is expected to create opportunities in the Australian wine market, the Chinese wine market, and the U.S. wine market, among others. In April 2025, a major acquisition agreement was announced by The Wine Group to acquire multiple premium wine brands, vineyards, and production assets from Constellation Brands, and portfolio diversification and production scale expansion were strategically strengthened.
Consumer Insights
Globally, millennials account for approximately 30% of total wine consumption, making them the largest generational consumer segment and surpassing baby boomers in premium wine market share. Millennials account for approximately 30.0% of wine consumption in the United States, while Gen Z represents only about 9% of total consumers, highlighting a slower adoption rate among younger legal-age drinkers. Approximately 66.0% of households in the United States purchase wine, demonstrating high household penetration and stable consumer demand in mature markets.
Women represent approximately 42% of global wine consumers and account for approximately 42% of wine volume purchases, indicating strong participation and growing influence in premium wine purchasing decisions. The average age of global wine consumers is approximately 39 years, reflecting strong consumption among working-age adults with stable disposable incomes.
 To learn more about this report, Download Free Sample Report
Over the years, the global vineyard landscape has evolved significantly, driven by the increasing demand for wine across various regions. As wine consumption continues to rise, particularly in emerging markets, vineyard expansion has become necessary to meet the growing demand. Many countries with a deep-rooted winemaking tradition, such as France, Italy, and Spain, continue to dominate the global vineyard area. Meanwhile, regions such as the United States, Argentina, Australia, and China have also expanded their vineyard plantings to meet the demand of both domestic and international markets.
Some of the world's most renowned vineyards include Château Margaux in France, Bodega Catena Zapata in Argentina, Penfolds Magill Estate in Australia, and Napa Valley's Opus One in the U.S. These vineyards, known for their high-quality production, reflect the ongoing expansion and adaptation of the global wine industry to evolving consumer preferences and non-alcoholic wine market trends.
Wine has recently gained traction and is one of the fastest-growing beverages in the wine and spirits market, especially in the U.S. and the UK. With the rapid expansion of social media, winemakers are continually adopting and integrating it to market wine. The canned wine market is transforming owing to technological innovations. However, consumers between the ages of 18 and 27 prefer beer over wine, owing to which winemakers are using social media to increase their market presence and audience, driving the growth of the non-alcoholic wine market. Tourism and travel have also led the a rise in demand for locally produced wines. Chile and Italy are very well known for their wines and consumers travel to these countries for their food and wines. Another trend is the adoption of wine in a can, which is driving the growth of the canned wine market.
Europe is the most established wine market, with most of Europe’s wine production concentrated in the southern part of the region, where consumers prefer local wine over foreign wine. However, countries such as the UK, the Netherlands, Austria, Germany, and Belgium can offer significant growth opportunities for the luxury wine market. These countries have insufficient domestic wine production, and the consumers are more open to foreign wines. The Eastern European organic wine market is relatively small, but wine consumption in this part of the region is increasing, and also providing further growth opportunities for wine producers. This is expected to drive growth in the sparkling wine market in Europe in the coming years.
However, European wine consumption has been declining over the past few years. This trend is influenced by factors such as changing consumer preferences, economic conditions, and health awareness. Major wine-consuming countries such as France, Italy, and Germany have seen decreases in per capita consumption. Despite this, there is growing interest in premium and sustainable wines, which has helped maintain some stability in the wine industry.
 To learn more about this report, Download Free Sample Report
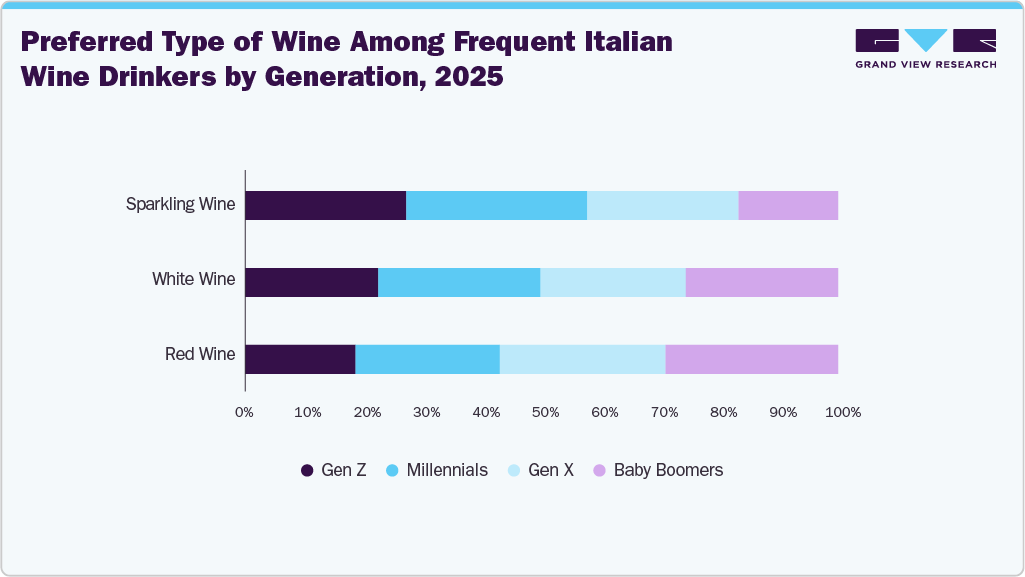
According the a report published by Amfori, Italy is one of the world’s oldest winemaking countries. The country boasts an enormous wealth of expertise, diversity (more than 2,000 grape varieties and vintages), and some of the finest wines in the world. There is a generational variation in the types of wine preferred by frequent Italian wine drinkers, reflecting distinct tastes and consumption habits. Younger generations, especially Gen Z and Millennials, favor sparkling wines for social occasions, while Millennials and Gen X show strong interest in white wine for its versatility. Red wine remains a classic choice, particularly among Baby Boomers, who appreciate its depth and tradition. These preferences reflect the evolving wine culture in Italy, blending heritage with modern trends.
Product Insights
The table wine market held the largest share of more than 81.9% in the global wine market in 2025. The market for table wine is growing due to rising consumer preference for casual, affordable wine for everyday consumption. Growing wine culture, particularly among millennials and young adults, along with increased social drinking occasions, has driven demand. Moreover, the expansion of online wine retail, improved accessibility, and the popularity of food-and-wine pairings have contributed to market growth. The trend toward organic and sustainably produced wines is also attracting health-conscious consumers, further fueling demand.
 To learn more about this report, Download Free Sample Report
The sparkling wine market is projected to register the fastest CAGR of 9.3% from 2026 to 2033. The market for sparkling wine is increasing due to rising consumer preference for celebratory and casual drinking occasions. Growing demand for premium and diverse sparkling wine varieties, including Prosecco, Champagne, and Cava, has expanded the market. Additionally, younger consumers are embracing sparkling wine for its refreshing taste and lower alcohol content. The rise of e-commerce and direct-to-consumer sales has further boosted accessibility, while the trend toward food pairings and mixology has increased its appeal in the hospitality sector. In September 2025, Dry Creek Vineyard launched a limited-production Sparkling Chenin Blanc, expanding its premium sparkling portfolio and capitalizing on rising consumer interest in aromatic, refreshing sparkling wines.
Distribution Channel Insights
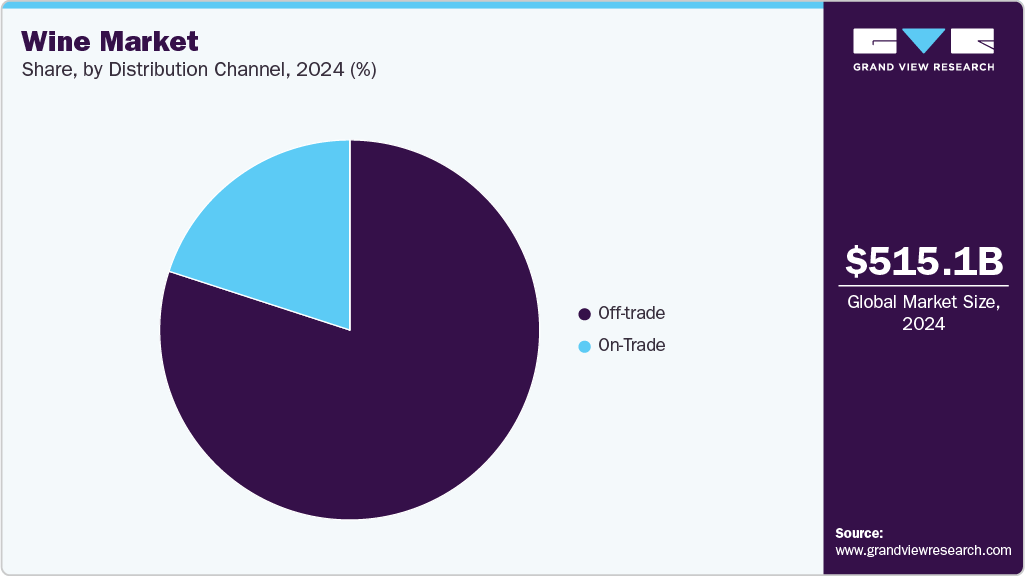
The sales of wine through off-trade channel accounted for the largest revenue share of 77.5% in 2025. The off-trade distribution channel of wine includes retail outlets, supermarkets, and hypermarkets. The expansion of large retail chains such as Walmart, Tesco, and Carrefour has strengthened the shelf visibility and accessibility of wine products. Retailers have increasingly introduced private-label wines, offering competitive pricing and improving margins, thereby driving volume sales. Consumers prefer purchasing wine through off-trade channels due to promotional pricing, bulk discounts, and bundled offers. Supermarkets provide price transparency and comparative shopping advantages, which support higher household penetration rates.
The growth of online alcohol platforms and digital grocery services has accelerated off-trade penetration. Companies such as Amazon and regional online alcohol retailers have expanded direct-to-consumer wine sales, enabling convenience-driven purchasing and subscription models.
 To learn more about this report, Download Free Sample Report
The on-trade distribution channel is expected to experience the fastest CAGR, at 9.8%, from 2026 to 2033. The on-trade distribution channel includes outlets such as clubs, hotels, bars, restaurants, and coffee shops. The global hospitality and tourism recovery has led to higher footfall in hotels and restaurants, driving wine sales through experiential consumption. Premium sparkling wines and champagne are frequently consumed in celebratory and luxury settings. International tourist inflows contribute significantly to wine sales in hospitality venues, particularly in wine-producing regions such as France, Italy, and Spain, where wine tourism enhances on-trade consumption.
Expansion of urban bars and lounges in emerging markets has accelerated demand for wine by the glass offerings. Sparkling wines and rosé wines have particularly benefited from lifestyle-driven consumption trends. Advanced preservation technologies (e.g., nitrogen-based systems) enable restaurants to serve premium wines by the glass, increasing accessibility and trial consumption among consumers.
Regional Insights
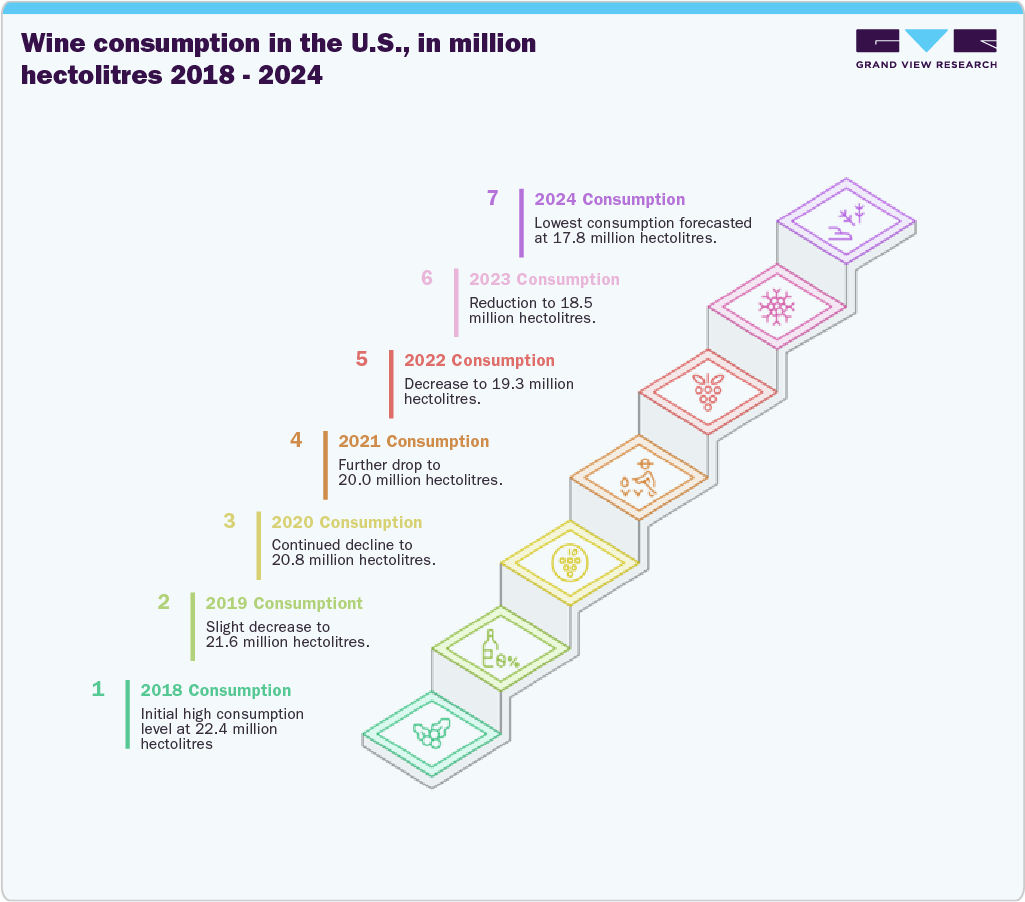
The North America wine market is expected to grow at a CAGR of 9.1% from 2026 to 2033. The wine market in the Americas has exhibited diverse trends. According to the Wine Institute and the International Organization of Vine and Wine (OIV), U.S. per-capita wine consumption declined from 2.94 gallons in 2022 to approximately 2.68 gallons in 2023, with preliminary estimates for 2024-2025 indicating stagnation at historically low levels. Total U.S. wine consumption volume fell by 2.6% in 2023 and another 1-2% estimated in 2024, reflecting structural demand shifts. A major driver is demographic change. Mexico’s wine consumption increased to approximately 1.3 liters per capita in 2024, up from about 0.9 liters in 2018. Domestic wine production increased by over 12% between 2021 and 2024, supported by government investment and expanding vineyard area in Baja California.
 To learn more about this report, Download Free Sample Report
U.S. Wine Market Trends
The winemarket in the U.S. is expected to grow at a CAGR of 9.0% from 2026 to 2033. Wine sales have surged across the U.S. owing to innovation in its flavor, color, and packaging. Beyond the classic wines, niche markets and emerging wine regions are gaining prominence. Regions such as the Willamette Valley in Oregon, the Finger Lakes in New York, the Santa Rita Hills in California, and the Columbia Valley are carving out niches with their distinct offerings. Indigenous grape varieties, innovative winemaking techniques, and unique terroirs are captivating adventurous palates. According to the Silicon Valley Bank 2025 State of the Wine Industry Report:
-
Consumers aged 21-34 reduced wine consumption frequency by more than 20% since 2021.
-
Gen Z consumers increasingly prefer spirits, ready-to-drink cocktails, and low-alcohol alternatives, thereby weakening demand for traditional wine.
Europe Wine Market Trends
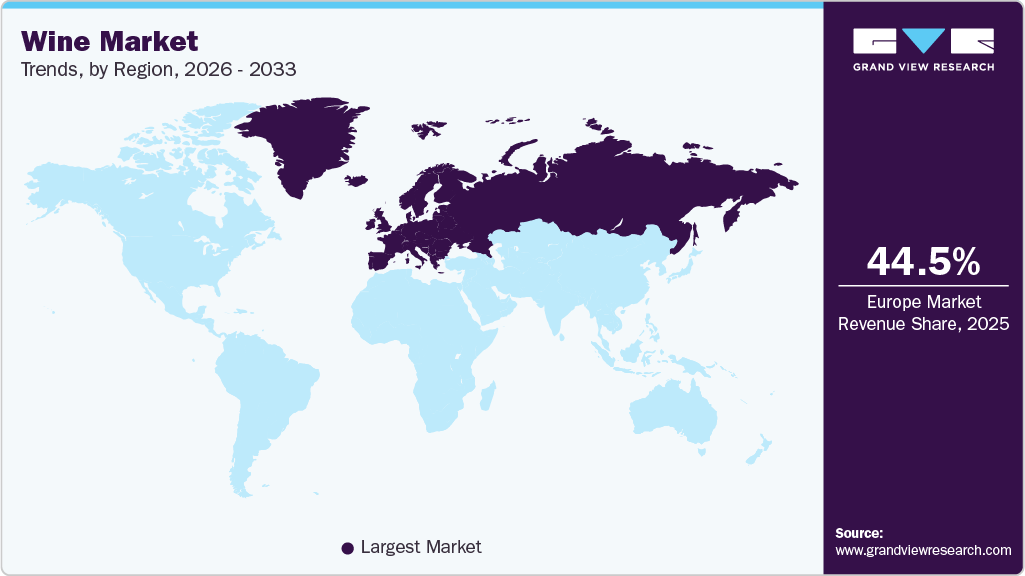
The wine market in Europe accounted for a revenue share of 44.5% of the global revenue in 2025. Europe is the most established wine market, with several countries, such as Portugal, Italy, and France, having the highest per capita annual wine consumption. According to the OIV’s 2024 World Vine and Wine Sector Report, EU member states consumed about 103.6 million hectolitres of wine in 2024, representing approximately 48% of global wine consumption, which was 2.8% lower than in 2023 and more than 5% below the five-year average. This consumption trend reflects ongoing declines in traditional European markets, including reductions in France, Italy, and Germany, as part of structural shifts in drinking habits and the impact of competitive beverages on demand. Countries such as Germany and the UK are the largest importers of wine, while wine production is much lower than consumption.
 To learn more about this report, Download Free Sample Report
The wine market in France is expected to develop at the fastest CAGR of 8.6% during the projected period. A large majority of French wine consumers also associate wine with values of tradition and sophistication, and consume a familiar drink. Increasingly, consumers also associate wine with relaxing occasions and see the drink as refreshing. These factors are expected to create an optimistic outlook for the French wine market in the upcoming years. Wine tourism in France is currently experiencing considerable growth. An increasing number of wine tourism enthusiasts are exploring the rich wine-growing heritage of France, traveling through outstanding landscapes, learning about the timeless know-how safeguarded by passionate winegrowers, and enjoying a host of new tastes.
Asia Pacific Wine Market Trends
The Asia Pacific wine market is expected to grow at a CAGR of 10.7% from 2026 to 2033. China, Japan, and South Korea are among the region’s key wine markets, supported by a large consumer base and rising disposable incomes. The region also offers opportunities for wine producers through expanding distribution channels and demand for diverse wine varieties. China remains an important market for imported wine, although demand has faced recent headwinds. According to Wine Australia, Australian wine exports to mainland China declined by 17% in value to A$755 million in 2025, following the initial rebound after import tariffs were removed in 2024. Meanwhile, Singapore, Thailand, and Malaysia recorded growth in the value of Australian wine exports in 2025, highlighting opportunities for market diversification across the Asia-Pacific. These developments underscore the importance of adapting product portfolios and distribution strategies to changing consumer preferences and market conditions.
India wine market is projected to grow at a CAGR of 14.8% over the forecast period. The large young population, increasing urbanization, and the perception of wine as a ‘status symbol are factors expected to drive the market in India. The growing acceptance and preference for wine among the upper and middle classes are also boosting the market. The largest exporters of wine to India are Australia, Spain, France, and Italy, which together contribute to almost 75% of the country’s wine imports. Secondary exporters include Chile, South Africa, and Argentina. The European Union previously supplied over half of India’s wine imports, but over the past two years, Australia has surpassed it by offering more competitive prices and lower logistical costs.
Key Wine Company Insights
The global wine market is fragmented, with several global and regional competitors operating in the market. These companies are investing heavily in acquisitions and promotions to grow their client base and brand loyalty. Furthermore, these firms are leveraging emerging technologies such as blockchain and artificial intelligence to improve consumer experience and streamline supply chain activities.
 To learn more about this report, Download Free Sample Report
Key Wine Companies:
The following key companies have been profiled for this study on the wine market.
- E. & J. Gallo Winery
- Constellation Brands, Inc.
- The Wine Group
- Treasury Wine Estates
- Viña Concha y Toro
- Castel Freres
- Accolade Wines
- Pernod Ricard
- Asahi Group Holdings, Ltd.
- Beijing Yanjing Beer Group Co.
Recent Developments
- In October 2025, House Wine launched its Red Table Wine in a 1-liter bottle, offering a fruit-forward blend of Merlot, Cabernet Sauvignon, and Syrah. The larger format provides 33% more wine than a standard 750 ml bottle and is positioned around value, versatility, and sharing occasions. The launch expanded the brand’s everyday wine portfolio with a larger-format offering targeting casual dining and social gatherings.
-
In July 2025, Pasqua Wines, proud ambassador of Amarone della Valpolicella and Veneto wines, was chosen by renowned and trailblazing Washington State winemaker Charles Smith as the exclusive international distributor for a selection of wines from the acclaimed House of Smith portfolio.
-
In February 2025, VITAL Wines, the non-profit winery dedicated to improving equity in healthcare access for vineyard workers and their families, proudly announces the release of VITAL x Valdemar Estates 2024 Rosé.
-
In January 2025, Alliance Wine launched its first comprehensive Burgundy En Primeur campaign, integrating wines from the newly acquired H2Vin portfolio. This campaign features nearly 350 wines from over 30 top Burgundy producers, showcasing the combined strength and depth of the two businesses. The campaign is part of a broader trend in the wine trade, with other companies such as Thorman Hunt and Flint Wines also launching their own primeur offerings around the same time.
-
In June 2024, Searcys, Great Britain's oldest caterer, launched a new English Sparkling Wine. The new vintage was harvested in 2016, bottled in 2017, and aged on lees for over six and a half years. Produced by Surrey's Greyfriars vineyard, it features vibrant apple and citrus flavors with toasty aromas.
Wine Market Report Scope
Report Attribute
Details
Market size in 2025
USD 549.6 billion
Estimated market size in 2026
USD 589.8 billion
Projected market size by 2033
USD 1,082.0 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million/Billion, volume in million liters and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; Brazil; Argentina; South Africa
Key companies profiled
E. & J. Gallo Winery; Constellation Brands, Inc.; The Wine Group; Treasury Wine Estates; Viña Concha y Toro; Castel Frères; Accolade Wines; Pernod Ricard; Asahi Group Holdings Ltd; Beijing Yanjing Beer Group Co.
Customization scope
Free report customization (equivalent to 8 analyst-working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options.
Global Wine Market Report Segmentation
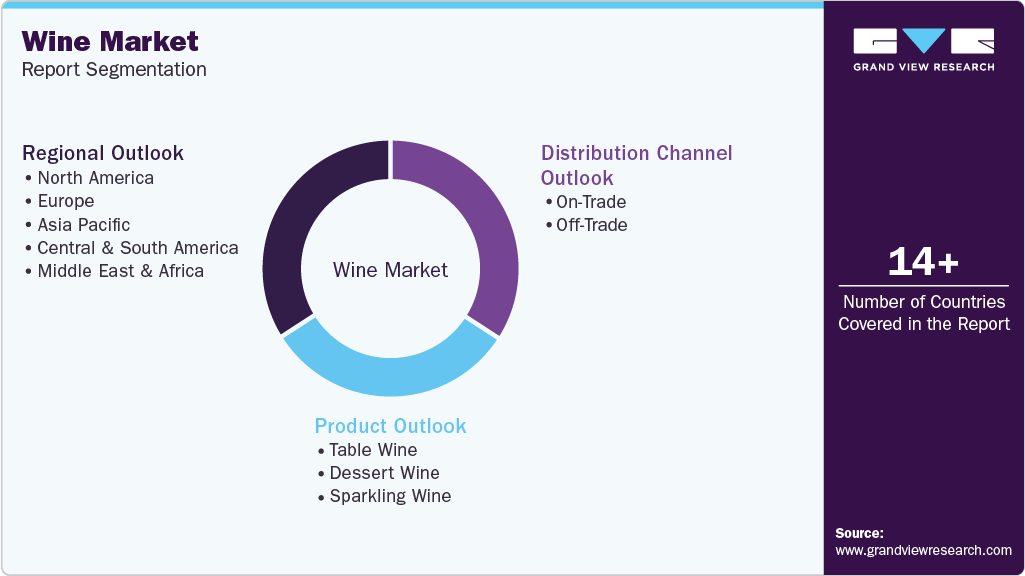
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wine market report based on product, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; Volume, Million Liters, 2021 - 2033)
-
Table Wine
-
Dessert Wine
-
Sparkling Wine
-
-
Distribution Channel Outlook (Revenue, USD Million; Volume, Million Liters, 2021 - 2033)
-
On-Trade
-
Off-Trade
-
-
Regional Outlook (Revenue, USD Million; Volume, Million Liters, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
-
Frequently Asked Questions About This Report
By distribution channel, the off-trade segment led the market, accounting for 77.5% in 2025.
The global wine market was estimated at USD 549.6 billion in 2025 and is expected to reach USD 589.8 billion in 2026.
Europe dominated with a 44.5% revenue share in 2025.
The global wine market is expected to grow at a compound annual growth rate of 9.1% from 2026 to 2033 to reach USD 1,082.0 billion by 2033.
The table wine segment held the largest revenue share of 81.9% in 2025, while the sparkling wine is the fastest-growing segment.
Some of the key market players in the wine market are E. & J. Gallo Winery, Constellation Brands, Inc., The Wine Group, Treasury Wine Estates, Viña Concha y Toro, Castel Frères, Accolade Wines, Pernod Ricard, Asahi Group Holdings, Ltd., and Beijing Yanjing Beer Group Co.
About the Author(s)
Alcohol & Tobacco Research Team
Consumer Goods · Alcohol & TobaccoThis report was authored by the alcohol & tobacco research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the alcohol & tobacco segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


