
- Home
- »
- Plastics, Polymers & Resins
- »
-
Wood Adhesives Market Size, Share & Growth Report, 2033GVR Report cover

Wood Adhesives Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Urea-Formaldehyde, Soy-based, Isocyanates, Polyurethane), By Application, By Substrate (Plywood, Oriented Strand Board, Medium-density Fiberboard) By Region, And Segment Forecasts
Market Size, 2025
$8.3BMarket Estimate, 2026
$9.0BMarket Forecast, 2033
$15.6BCAGR, 2026–2033
8.6%Wood Adhesives Market Size & Trends
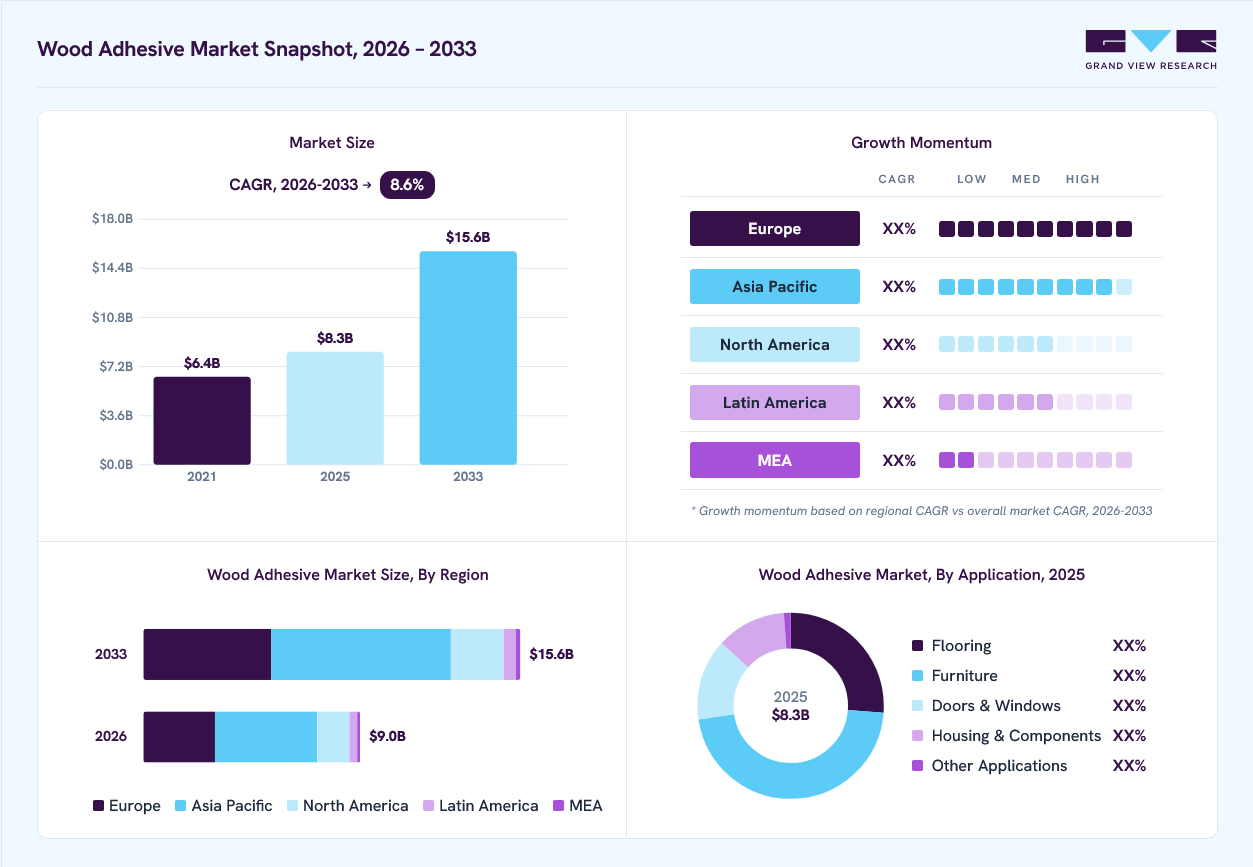
The global wood adhesives market size was valued at USD 8.3 billion in 2025 and is projected to grow from USD 9.0 billion in 2026 to USD 15.6 billion by 2033, at a CAGR of 8.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 47.0% in 2025. Growing global engineered wood-based panel production is a significant factor driving the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Urea-formaldehyde dominated the product type segment at a revenue share of 32.8% in 2025.
- By application: Furniture segment held the largest share of 46.4% in 2025.
- By substrate: Plywood projected for the largest market share of 27.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (47.0% revenue share in 2025)
- By Country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.3 Billion
- Estimated market size in 2026: USD 9.0 Billion
- Projected market size by 2033: USD 15.6 Billion
- CAGR (2026-2033): 8.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Engineered wood-based panels such as plywood, oriented strand board, and particle board consume a significant volume of adhesives during their manufacturing process. For instance, plywood is produced by binding veneers with adhesive. The market is anticipated to grow over the forecast period owing to the increasing demand for eco-friendly and green furniture. Rising concerns among people regarding the abatement of trees and global warming have led to a surge in the use of engineered wood-based panels. Rapid urbanization coupled with an increase in disposable income has contributed to a higher demand for engineered wood furniture. This is estimated to be a significant factor in influencing product demand.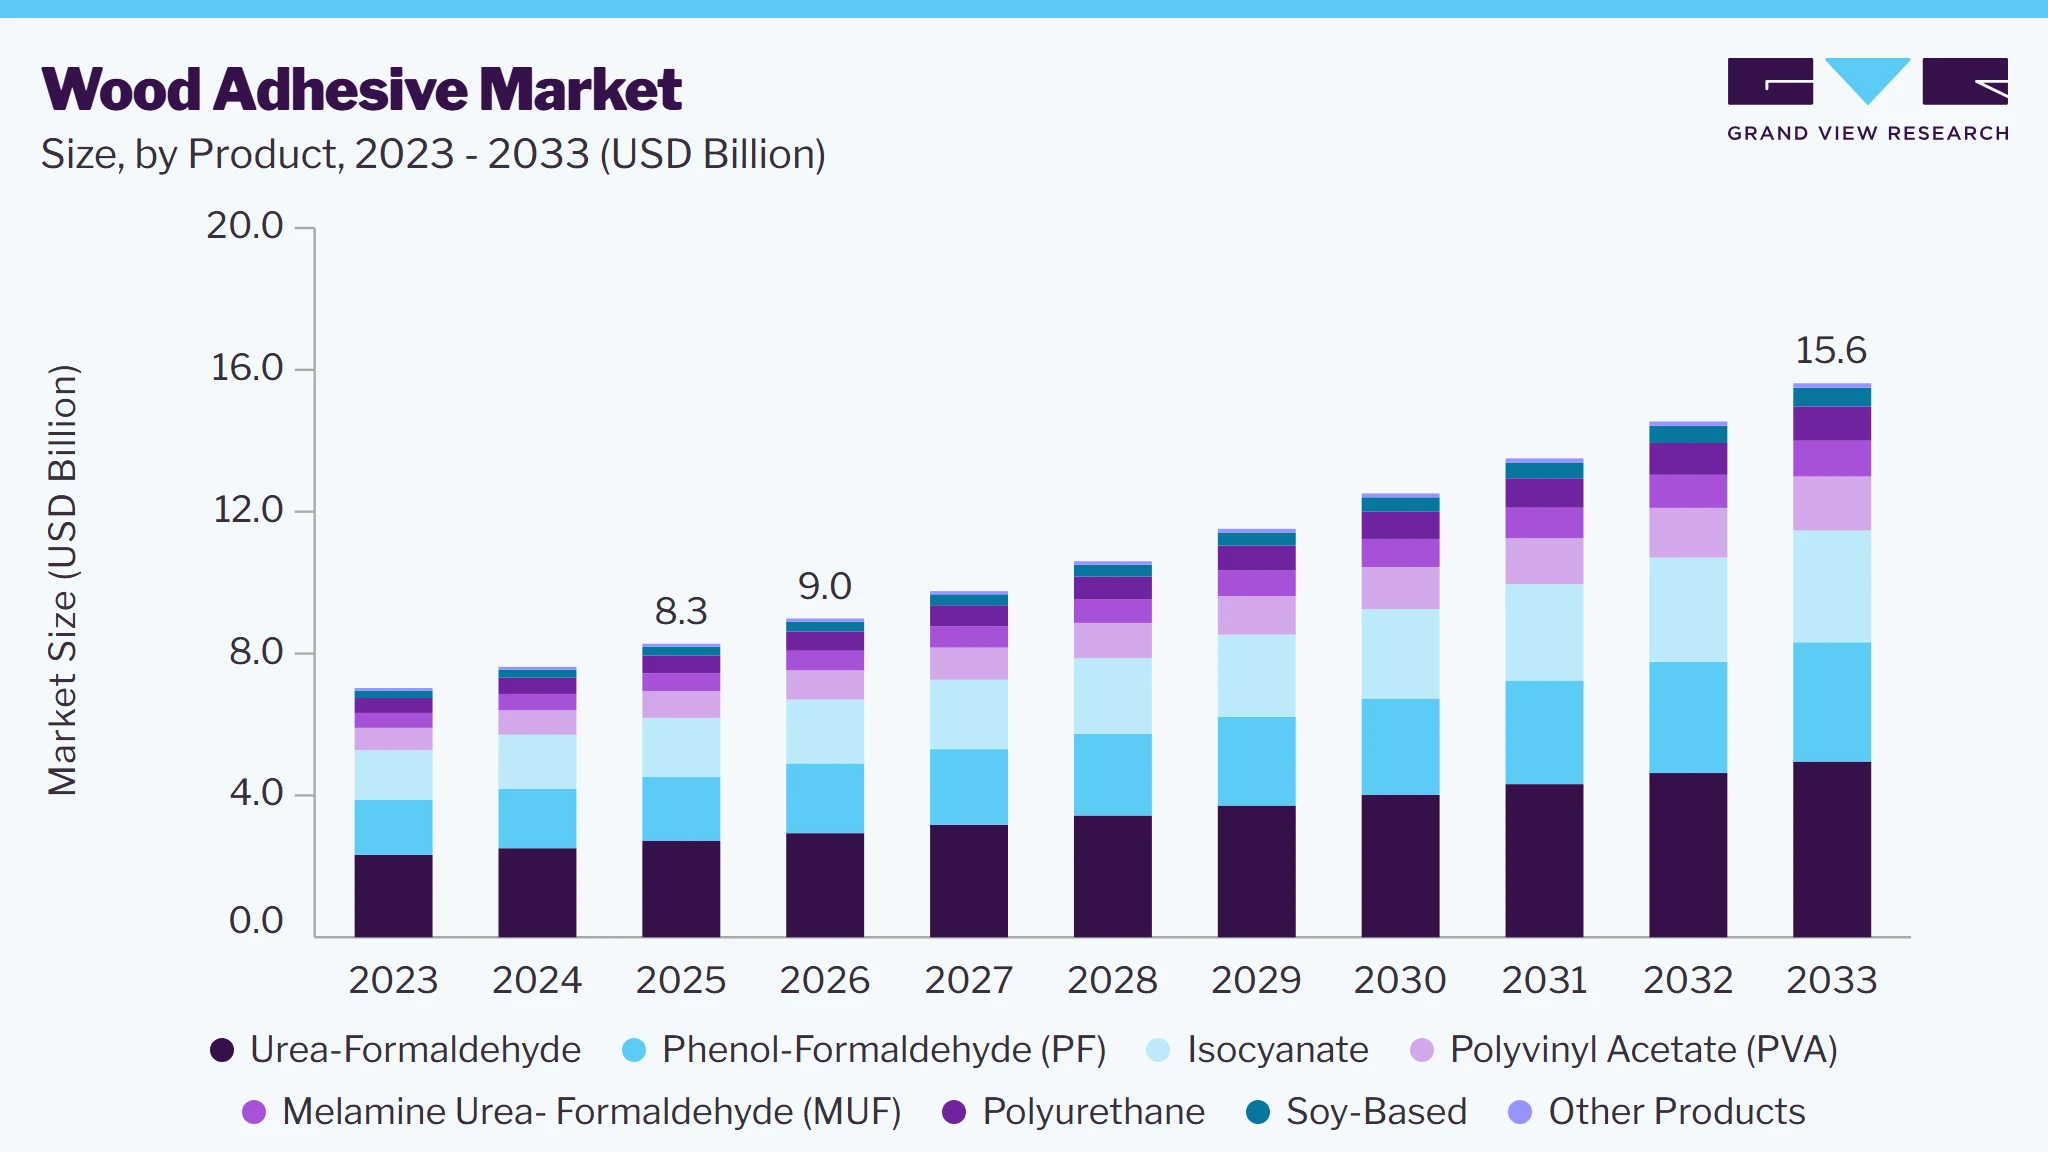 To learn more about this report, Download Free Sample Report
Wood panel manufacturers, especially in Asia Pacific, rely on in-house production capabilities to produce adhesives for their products. Adhesive production is considered to be a part of wood-based panel manufacturing in the woodworking industry. However, most small to medium panel manufacturers do not have adequate adhesive production and quality control capabilities. Adhesive formulation and monitoring of quality is solely dependent on the operator’s knowledge, skill, and experience.
The market is characterized by the presence of a stringent regulatory framework associated with the emission levels of formaldehyde during wood-based panel manufacturing. This is expected to open new growth avenues for soy-based, polyurethane, and polyvinyl acetate adhesives over the next seven years.
Growing refurbishment and renovation activities coupled with increasing number of constructions is anticipated to boost market growth. Moreover, government initiatives towards sustainable construction have resulted in an increased need for engineered wood and wood products in the form of furniture for use in both residential as well as commercial applications, which is expected to augment demand for the market across the forecast period.
Remodeling and renovation activities on account of rising living standards are expected to contribute to the demand for furniture. The growing service sector in emerging economies has led to the development of office spaces and corporate buildings, which have consequently impacted the demand for wood furniture’s, which is expected to drive the market growth.
Furthermore, rising concerns among people regarding the abatement of trees and global warming have led to a surge in the use of engineered wood panels. The manufacturing of engineered wood panels such as oriented strand board, plywood, and particle board requires a significant volume of adhesives. For instance, plywood is produced by applying adhesive resin to veneers. As a result, the growing demand for wood panels is likely to boost demand for wood adhesives.
In addition, rising awareness regarding environmental degradation, growing customer base, and enhanced & consistent R&D activities are anticipated to grow the bio-based wood adhesives demand. In addition, according to the World Agricultural Production Outlook, global production of soy (soybean) was 391.17 million metric tons, which represented a 10% increase in the production. To sum up, abundant raw material availability of bio-based adhesives such as starch, soy and corn are expected to positively influence the market growth over the forecast period.
However, volatile organic compound (VOC) emissions resulting from commercial and industrial use of adhesives pose both environmental and health risks. In order to regulate such industrial emissions, several countries have set guidelines to restrict the amount of gaseous emission during the use of adhesives. Thus, stringent government regulations prevalent in the industry is expected to restrict the market growth across the forecast period.
For instance, in the U.S., the Environmental Protection Agency states that manufacturers and suppliers of adhesives and sealants must comply with the established volatile organic compound standards. Moreover, European adhesives industry also complies with the regulations under Registration, Evaluation, Authorization and Restriction of Chemicals (REACH). These environmental regulations restrict the growth of adhesives market as the violation of such government-defined regulations can result in heavy penalties and losses.
Market Dynamics
The wood adhesives market is witnessing steady growth driven by the expanding construction, furniture, and woodworking industries, along with increasing demand for engineered wood products. Wood adhesives play a vital role in bonding materials such as plywood, particleboard, medium-density fiberboard (MDF), laminated veneer lumber (LVL), and other engineered wood products, ensuring durability, strength, and moisture resistance. Rising urbanization, infrastructure development, and growing residential and commercial construction activities are fueling the demand for high-performance wood adhesives. Additionally, the increasing preference for sustainable and low-VOC adhesive formulations is creating new opportunities for market expansion.
The rapid growth of the construction and furniture sectors is a key driver of the wood adhesives market. Increasing investments in residential, commercial, and infrastructure projects have significantly boosted the demand for engineered wood panels, flooring, doors, cabinets, and furniture, all of which rely on advanced adhesive technologies for superior bonding performance.
The rising popularity of modular furniture, ready-to-assemble products, and customized interior solutions has further accelerated the adoption of wood adhesives. Moreover, continuous innovations in adhesive formulations offering enhanced bonding strength, water resistance, heat resistance, and faster curing are supporting manufacturers in meeting evolving industry requirements. As urbanization and housing development continue to expand globally, demand for wood adhesives is expected to remain strong throughout the forecast period.
Volatility in the prices of petrochemical-based raw materials such as resins, formaldehyde, and other chemical intermediates presents a significant challenge for the wood adhesives market. Supply chain disruptions, fluctuations in crude oil prices, and geopolitical uncertainties can increase manufacturing costs and affect profit margins for adhesive producers.
Additionally, stringent environmental regulations regarding volatile organic compound (VOC) emissions and formaldehyde content are creating compliance challenges for manufacturers. The transition toward environmentally friendly adhesive formulations requires continuous investments in research, product development, and regulatory compliance, increasing operational expenses. These factors may hinder market growth, particularly in cost-sensitive regions.
The growing focus on sustainability and green building practices is creating significant opportunities for the wood adhesives market. Increasing consumer awareness and stricter environmental standards are driving demand for bio-based, formaldehyde-free, and low-VOC wood adhesives that minimize environmental and health impacts while delivering high bonding performance.
Advancements in adhesive technologies are enabling the development of innovative products derived from renewable raw materials such as soy protein, lignin, starch, and other bio-based feedstocks. These sustainable adhesives offer reduced emissions, improved indoor air quality, and compliance with green building certifications. Furthermore, the increasing use of engineered wood products in sustainable construction and the growing adoption of eco-friendly furniture manufacturing are expected to create substantial growth opportunities for companies investing in next-generation wood adhesive technologies.
Analyst Perspective
The global wood adhesives market is positioned for steady growth, driven by expanding construction activities, increasing furniture manufacturing, and rising demand for engineered wood products across residential and commercial sectors. Urea-formaldehyde (UF) adhesives remain the most widely used product type due to their cost-effectiveness, strong bonding performance, and extensive application in plywood, particleboard, and medium-density fiberboard (MDF). Furthermore, the growing adoption of modular furniture, sustainable building materials, and low-VOC, formaldehyde-free adhesive technologies is accelerating market demand. Continuous advancements in bio-based adhesive formulations and increasing investments in environmentally friendly wood bonding solutions are expected to further support market expansion across both developed and emerging economies.
Substrate Insights
Plywood projected for the largest market share of 27.0% in 2025. Increasing demand for plywood in construction and furniture industries, especially in Asia Pacific, is expected to have a favorable impact on the wood adhesive market growth over the forecast period.
Plywood is manufactured by gluing multiple thin layers of veneer wood. Superior properties such as high strength, moisture resistance, impact resistance, chemical resistance, fire resistance, and durability offered by the product are expected to drive the market over the forecast period. It can also be used as an insulating material for wall cladding, ceilings, roofing, and flooring.
Oriented strand board (OSB) is yet another significant segment for the product. The logs are sliced into strands of a specific size and assembled in wet bins until they get ready to be dried. The dried strands are mixed with adhesive to construct the board and a minimal amount of wax to improve the resistance to water absorption and moisture. Increasing demand for oriented strand board (OSB) as an alternative to plywood and solid boards, especially in North America and Europe, is projected to drive the demand for the product in OSB over the forecast period.
Medium-density fiberboard (MDF) finds extensive application scope in the construction and furniture industries. Rising demand for wood furniture, flooring, and cabinetry is expected to drive the market over the forecast period. The rapid growth of the residential and commercial building & construction sector in Asia Pacific is expected to have a positive impact on the segment growth over the forecast period.
Product Insights
Urea-formaldehyde dominated the product type segment at a revenue share of 32.8% in 2025. This is attributed to its wide utilization as a non-transparent thermosetting resin for wood. It exhibits superior properties includes high tensile strength and flexural modulus. Fillers and extenders are added to the resin to control flow, viscosity, and resin penetration in wood. They are widely used in the manufacturing of interior grade plywood and particleboard. A major drawback of UF adhesives is their poor water resistance.
The melamine urea-formaldehyde (MUF) resins possess superior water-resistance properties as compared to other resins. A recent trend indicates the development of MUF resin adhesives for finger jointing of sawmill waste timbers and also for manufacturing flooring tiles from bamboo and bamboo laminates. These resins are the popular choice for exterior and semi-exterior panels.
Isocyanates exhibit excellent resistance to moisture and are used to bond agricultural cellulosic wastes such as bagasse and straw. The most commonly used isocyanates are methylene diphenyl diisocyanate (MDI) and toluene diisocyanate (TDI). However, the product causes irritation of skin, eyes, and respiratory tract when used in high concentrations.
Application Insights
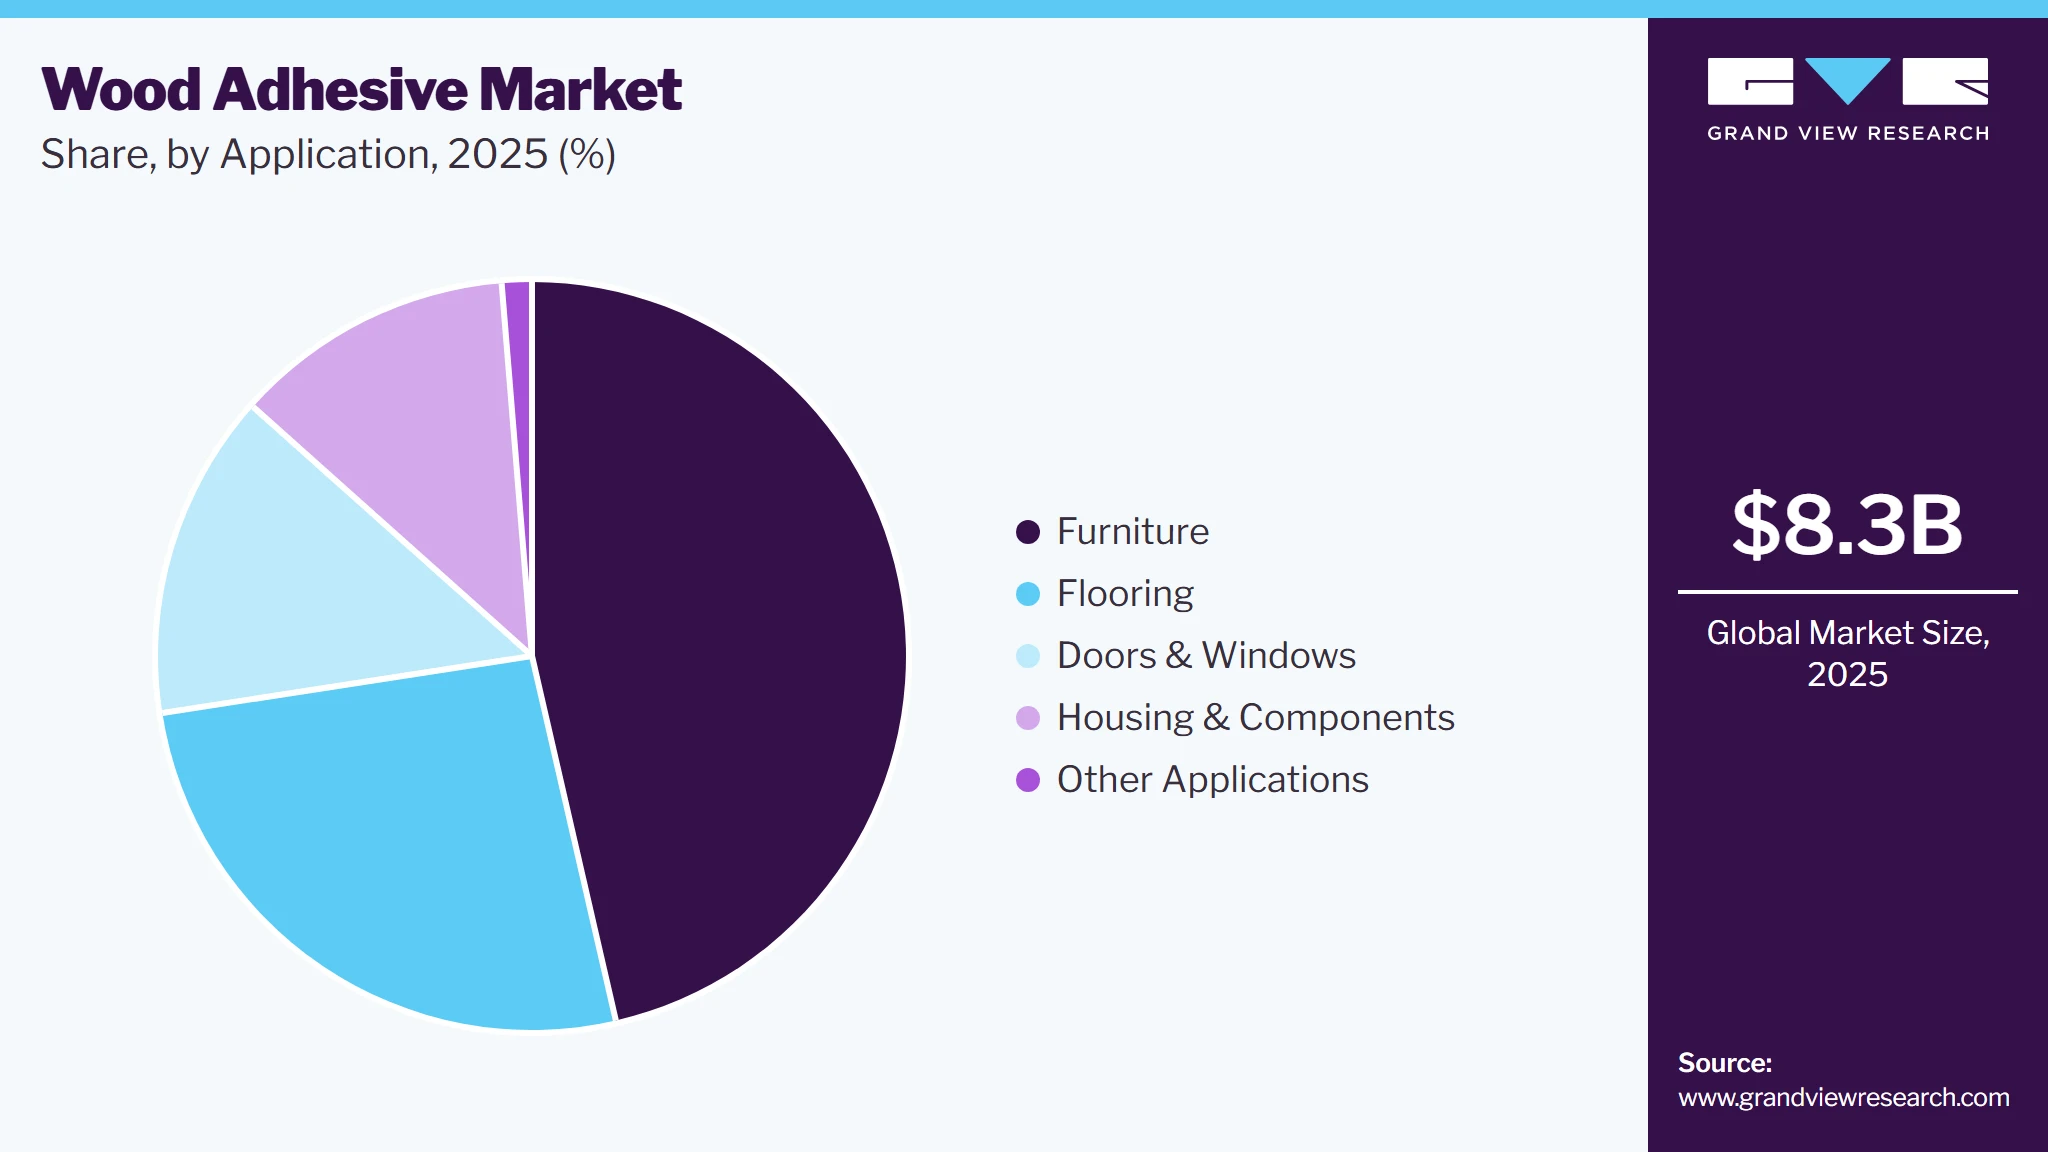
Furniture segment held the largest share of 46.4% in 2025. This is attributed to growing utilization of wood-based panels as they are lightweight, well finished, and durable as compared to traditional wood. Unlike glass, these panels can be used to manufacture sturdy and durable interior decoration items which are expected to have a positive impact on the segment growth over the next seven years.
 To learn more about this report, Download Free Sample Report
Flooring application is poised to observe the fastest growth with a CAGR, from 2023 to 2030. Increasing per capita disposable income coupled with the growing demand for residential space is anticipated to fuel the demand for flooring. Plywood floors enable customers to achieve enhanced aesthetics at a lower cost. An increasing number of restoration & refurbishment projects in developed economies are likely to augment the demand for wooden flooring, thereby propelling the adhesives market growth.
Wood adhesives are increasingly being applied on residential and commercial doors & windows for waterproofing and enhancing the overall texture & appeal. The product is also used during the manufacturing of window films as it enhances the UV filtration of the films.
Housing components including studs, joists, rafters, sheathing, and siding are made from wood. Increasing demand for residential space owing to rapid urbanization along with higher living standards is expected to drive market growth significantly over the forecast period. New residential & commercial construction activities are also propelling the demand for engineered housing components to ensure energy sustainability, attractiveness, and efficiency.
Regional Insights
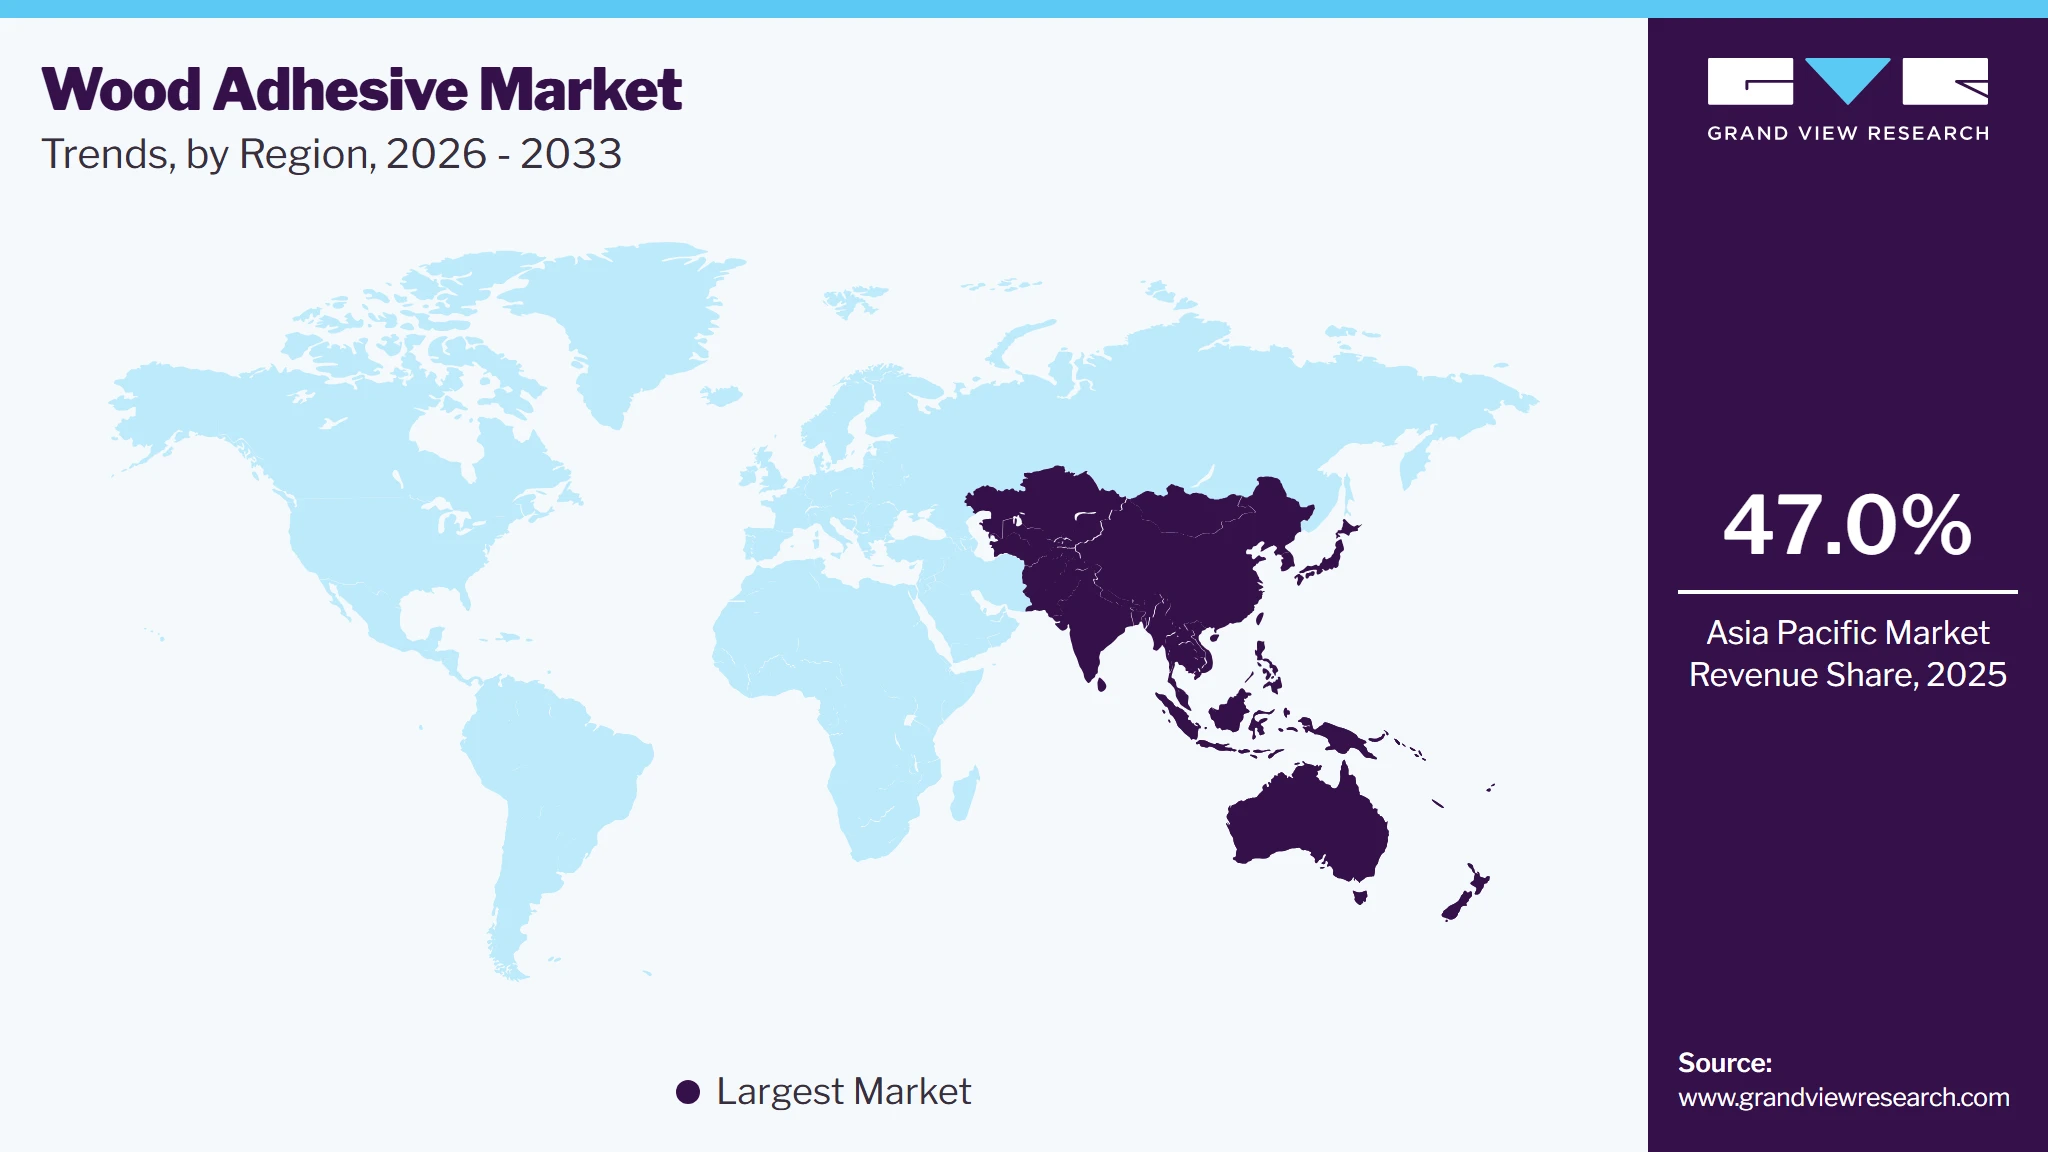
Asia Pacific accounted for 47.0% of the wood adhesives market revenue in 2025, making it the largest regional market. This is attributed to exponential rise in population in the Asia Pacific countries, coupled with the high demand for affordable housing, and government schemes promoting basic amenities such as food & shelter have led to the expansion of construction industry in the region.
 To learn more about this report, Download Free Sample Report
China Wood Adhesives Market Trends
China held the highest market revenue share in Asia Pacific in 2025. The wood- panel industry in China has a high economic importance, since it is one of the largest producers of wood-based panels in the world. The well-established wood panel industry in the region coupled with the steady supply of wood products is anticipated to further boost the wood adhesives market growth.
Europe Wood Adhesives Market Trends
Germany is one of the largest producers of wood adhesives in Europe. The wood adhesives market has witnessed rapid growth over past few years owing to robust demand from furniture and construction industry. Robust economic development has substantially profited the furniture industry and has resulted in increased private consumption.
However, the macroeconomic insecurity in context to European debt crisis is likely to hamper the growth of numerous industrial sectors in Germany, including furniture and housing construction, which in turn is expected to negatively impact the market over the forecast period.
Key Wood Adhesives Company Insights
The global market is fragmented with the presence of numerous global and regional players. The market is characterized by the presence of key companies such as HB Fuller, Henkel AG & Co., KGaA, Bostik SA, and 3M and other small to medium regional players.
The global players face intense competition from each other as well as from the regional players who have strong distribution networks and good knowledge about suppliers & regulations. For instance, in January 2023, Sika AG has recently introduced MB EZ Rapid, a high-performance single-component adhesive substrate consolidator and rapid-drying moisture barrier designed specifically for both residential and commercial floor covering installations. In addition, companies in the market compete on the basis of quality offered and the technology used for the manufacturing of the product.
Key Wood Adhesives Companies
The following key companies have been profiled for this study on the wood adhesives market.
-
DuPont
-
H.B. Fuller Company
-
Henkel AG & Co., KGaA
-
Bostik S.A.
-
3M
-
Sika AG
-
Ashland, Inc.
-
Pidilite Industries Ltd.
-
Jubiulant Industries Ltd.
-
Akzo Nobel N.V.
-
Franklin Adhesives & Polymers
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Henkel AG & Co. KGaA; 3M Company; H.B. Fuller; Sika AG; Ashland Inc.; Bostik S.A.; AkzoNobel N.V.; DowDuPont Inc.)
- Expand production capacity for high-performance wood adhesives serving furniture, construction, flooring, and engineered wood applications.
- Invest in R&D to develop low-VOC, formaldehyde-free, and bio-based adhesive technologies that comply with evolving environmental regulations.
- Strengthening global presence through acquisitions, strategic partnerships, and expansion of manufacturing facilities.
- Enhance product portfolios with advanced adhesive solutions offering improved bonding strength, durability, moisture resistance, and faster curing times.
- Strong global manufacturing footprint and well-established distribution networks.
- Extensive R&D capabilities supporting continuous product innovation.
- Broad product portfolios cater to multiple industrial and construction sectors.
- Strong relationships with OEMs, furniture manufacturers, and engineered wood producers, supported by recognized global brands.
- Exposure to fluctuations in petrochemical raw material prices and supply chain disruptions.
- High compliance costs associated with stringent VOC and formaldehyde emission regulations.
- Large operational structures may reduce flexibility in responding to niche market demands.
- Intense competition from regional manufacturers offering lower-cost alternatives.
Emerging & Regional Players (Pidilite Industries Ltd.; Jubilant Industries Ltd.; Franklin Adhesives & Polymers)
- Focus on expanding regional market share through cost-effective adhesive solutions for furniture, plywood, laminates, and woodworking industries.
- Develop customized adhesive formulations tailored to local customer requirements and substrate applications.
- Increase investments in environmentally friendly and water-based adhesive technologies.
- Expand dealer networks, technical support services, and partnerships with furniture and panel manufacturers.
- Strong understanding of regional market dynamics and customer preferences.
- Greater operational flexibility and quicker response to changing customer requirements.
- Competitive pricing strategies supported by localized manufacturing.
- Strong presence in rapidly growing construction and furniture markets.
- More limited international presence and distribution compared with multinational competitors.
- Lower R&D budgets may slow the commercialization of advanced adhesive technologies.
- Greater dependence on regional demand and local economic conditions.
- Increasing competition from global adhesive manufacturers expanding into emerging markets.
Wood Adhesives Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 8.3 billion
Market size value in 2026
USD 9.0 billion
Revenue forecast in 2033
USD 15.6 billion
Growth rate
CAGR of 8.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, substrate, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan, Brazil; Saudi Arabia
Key companies profiled
Henkel AG & Co. KGaA; 3M Company; H.B. Fuller; Sika AG; Ashland Inc.; Bostik S.A.; Pidilite Industries Ltd.; Jubilant Industries Ltd.; AkzoNobel N.V.; Franklin Adhesives & Polymers.; DowDuPont Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wood Adhesives Market Report Segmentation
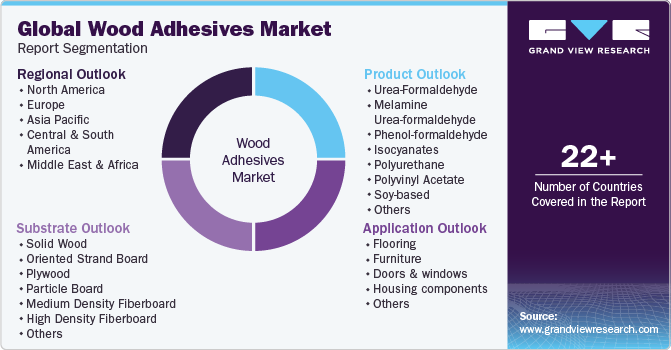
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wood adhesives market report based on product, application, substrate, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; Volume, Kilotons; 2021 - 2033)
-
Urea-formaldehyde (UF)
-
Melamine Urea-formaldehyde (MUF)
-
Phenol-formaldehyde (PF)
-
Isocyanates
-
Polyurethane
-
Polyvinyl Acetate (PVA)
-
Soy-based
-
Others
-
-
Application Outlook (Revenue, USD Million; Volume, Kilotons; 2021 - 2033)
-
Flooring
-
Furniture
-
Doors & Windows
-
Housing Components
-
Others
-
-
Substrate Outlook (Revenue, USD Million; Volume, Kilotons; 2021 - 2033)
-
Solid Wood
-
Oriented Strand Board (OSB)
-
Plywood
-
Particle Board (PB)
-
Medium-density Fiberboard (MDF)
-
High-density Fiberboard (HDF)
-
Others
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilotons; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The wood adhesives market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wood adhesives segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Urea-Formaldehyde
Revenue is generated from adhesives used in interior wood products such as particleboard, MDF, plywood, furniture, and cabinetry due to their cost-effectiveness and strong bonding performance.
Melamine Urea- Formaldehyde (MUF)
Includes earnings from moisture-resistant adhesive formulations utilized in flooring, kitchen furniture, laminated panels, and semi-exterior wood applications.
Phenol-Formaldehyde (PF)
Market revenue covers high-performance structural adhesives supplied for exterior-grade plywood, OSB, laminated beams, and construction materials requiring superior weather resistance.
Isocyanate
Captures sales from isocyanate-based bonding systems used in engineered wood products, structural panels, and moisture-resistant composite materials.
Polyurethane
Revenue comprises adhesive solutions designed for premium furniture, flooring, doors, windows, and specialty woodworking applications requiring flexibility and durability.
Polyvinyl Acetate (PVA)
Represents income from water-based adhesives widely used in woodworking, furniture assembly, paper lamination, and general interior bonding applications.
Soy-Based
Encompasses revenues from bio-based wood adhesives manufactured for environmentally friendly furniture, plywood, and engineered wood products with reduced formaldehyde emissions.
Other Products
Covers sales of acrylic, epoxy, EVA, hot-melt, and other specialty adhesive formulations serving niche wood bonding applications.
Segment - Application
Revenue capture definition
Flooring
Revenue is derived from adhesives used in the manufacturing and installation of hardwood, engineered wood, laminate, and parquet flooring systems.
Furniture
Accounts for adhesive sales supporting the production of residential, commercial, and office furniture, including cabinets, tables, chairs, and shelving units.
Doors & Windows
Includes revenues associated with bonding wood components used in the fabrication of interior and exterior doors, window frames, and related architectural products.
Housing & Components
Captures income from adhesives supplied for structural wood assemblies, wall panels, roofing systems, prefabricated housing, and other building components.
Other Applications
Encompasses revenues from adhesives utilized in packaging, decorative wood products, handicrafts, marine woodwork, and other specialized applications.
Segment - Application
Revenue capture definition
Solid Wood
Reflects sales of adhesives formulated for bonding natural timber in furniture manufacturing, joinery, doors, flooring, and structural wood applications.
Oriented Strand Board (OSB)
Covers revenue generated from adhesives used in the production of OSB panels for construction, roofing, flooring, and wall sheathing.
Plywood
Represents earnings from adhesive systems employed in plywood manufacturing across residential, commercial, industrial, and marine applications.
Particle Board (PB)
Includes revenue from bonding agents used in particle board production for furniture, cabinetry, shelving, and interior construction materials.
Medium-Density Fiberboard (MDF)
Accounts for adhesive sales supporting MDF manufacturing for furniture, molding, interior paneling, and decorative applications.
High-Density Fiberboard (HDF)
Revenue is captured from adhesive formulations utilized in high-density fiberboard production for laminate flooring, furniture components, and engineered wood products.
Other Substrates
Encompasses sales from adhesives used with laminated veneer lumber (LVL), cross-laminated timber (CLT), veneer, bamboo, cork, and other wood-based substrates.
Estimation Model
Layer Name
Key Question
Description
Wood Adhesives Production Layer
What forms is the supply base?
Identify global wood adhesive production capacity based on the availability of raw materials such as synthetic and bio-based resins, curing agents, additives, fillers, and solvents, along with resin synthesis technologies, formulation capabilities, manufacturing infrastructure, quality standards, and production facilities. This layer establishes the global supply base serving construction, furniture, flooring, packaging, and engineered wood industries.
Application Adoption Layer
Where are Wood Adhesives utilized?
Estimate the proportion of wood adhesives consumed across furniture manufacturing, flooring, doors & windows, housing components, engineered wood products, and other industrial applications based on production volumes, end-use demand, technological advancements, and regional manufacturing trends.
Consumption Intensity Layer
How much Wood Adhesives are used?
Analyze adhesive consumption across plywood, particleboard, MDF, HDF, OSB, solid wood, and other wood substrates by evaluating production output, adhesive loading rates, manufacturing processes, and industry demand to determine annual wood adhesive consumption across major end-use industries and geographic regions.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of wood adhesives, including urea-formaldehyde (UF), melamine urea-formaldehyde (MUF), phenol-formaldehyde (PF), polyurethane, polyvinyl acetate (PVA), isocyanate, soy-based, and other specialty adhesive formulations supplied to furniture manufacturers, engineered wood producers, construction companies, flooring manufacturers, and woodworking industries worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between product types, applications, and substrate types in the wood adhesives market. The analysis identifies adhesive usage intensity, bonding requirements, performance characteristics, curing technologies, and revenue contribution across intersecting segments, such as polyurethane adhesives for flooring, urea-formaldehyde adhesives for particleboard and MDF, and phenol-formaldehyde adhesives for exterior-grade plywood and structural panels.
Supports product portfolio optimization and market prioritization by identifying the most attractive product–application–substrate combinations, enabling improved resource allocation, sales targeting, product innovation, and long-term growth planning across the wood adhesives value chain.
Competitive Benchmarking
Comparative evaluation of leading wood adhesive manufacturers based on product portfolio breadth, adhesive technologies, manufacturing capacity, raw material sourcing, geographic footprint, sustainability initiatives, innovation capabilities, customer base, distribution network, and strategic developments across major regional markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing greater visibility into market positioning, technological strengths, differentiation strategies, operational efficiency, and competitive advantages.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with bio-based and low-VOC adhesives, formaldehyde-free technologies, sustainable construction, engineered wood products, modular furniture manufacturing, green building initiatives, and advanced adhesive formulations for high-performance wood applications across global markets.
Helps identify high-growth investment areas, emerging application opportunities, product development priorities, sustainability initiatives, and market expansion strategies, supporting long-term revenue growth and stronger competitive positioning throughout the wood adhesives value chain.
Frequently Asked Questions About This Report
The global wood adhesives market was estimated at USD 8.3 billion in 2025 and is projected to reach USD 9.0 billion by 2026.
The global wood adhesives market is expected to grow at a compound annual growth rate of 8.6% from 2024 to 2030 to reach USD 15.6 billion by 2033.
Some key players operating in the wood adhesives market include Henkel AG & Co., KGaA, H.B. Fuller, 3M, Bostik S.A., Sika AG, Pidilite Industries Ltd., Ashland, Inc., Jubilant Industries Ltd., and AkzoNobel N.V., among others.
Key factors that are driving the market growth include increasing demand for wood based panels, and rising awareness regarding bio based wood adhesives.
Asia Pacific dominated the global wood adhesives market in 2025, accounting for 47.0% of total revenue, driven by its large furniture manufacturing base, expanding construction sector, and strong production of engineered wood products, particularly in China, India, and Southeast Asia.
The furniture segment led the market with a 46.4% revenue share in 2025, supported by rising demand for residential and commercial furniture, increasing urbanization, and growing adoption of modular and ready-to-assemble furniture.
Plywood emerged as the leading substrate segment, capturing 27.0% of the global market in 2025, owing to its extensive use in furniture, flooring, cabinetry, interior decoration, and construction applications.
The soy-based wood adhesives segment is projected to register the fastest CAGR of 10.0% during the forecast period, driven by increasing demand for bio-based, low-VOC, and formaldehyde-free adhesive solutions that support sustainable manufacturing and green building initiatives.
Urea-formaldehyde dominated the wood adhesives market with a share of over 32.8% in 2025. These adhesives are widely used in the production of wood-based panels and are gaining wide popularity owing to their good performance and high reactivity.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


