
- Home
- »
- HVAC & Construction
- »
-
Furniture Market Size, Share And Trends Report, 2026-2033GVR Report cover

Furniture Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Bedroom Furniture, Storage Furniture, Seating Furniture), By Material (Metal, Wood, Plastic, Glass), By Application (Residential, Commercial), By Region, And Segment Forecasts
Market Size, 2025
$786.1BMarket Estimate, 2026
$831.6BMarket Forecast, 2033
$1,334.1BCAGR, 2026–2033
7.0%Furniture Market Summary
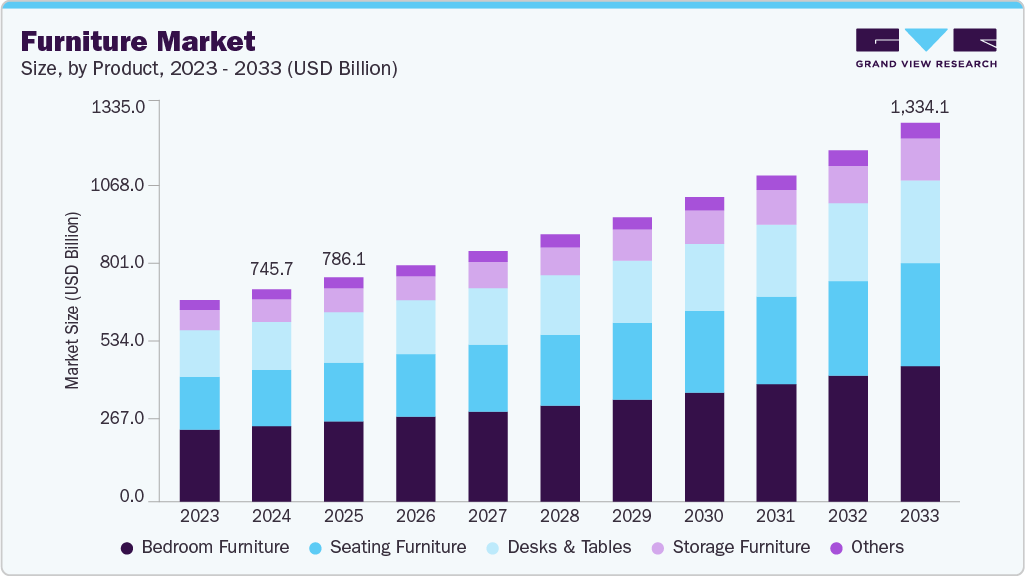
The global furniture market size was valued at USD 786.1 billion in 2025 and is projected to grow from USD 831.6 billion in 2026 to USD 1,334.1 billion by 2033, at a CAGR of 7.0% from 2026 to 2033. Asia Pacific dominated the global market, with a revenue share of 38.5% in 2025. Market growth is driven by increasing residential and commercial construction, rising consumer spending on home interiors, and growing demand for space-efficient, multifunctional, and customizable furniture.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Bedroom furniture segment held the largest market share of 35.7% in 2025.
- By material: Wood segment held the largest market share of 39.8% in 2025.
- By application: Residential segment held the largest market share of 61.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.5% share in 2025)
- Fastest growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By Country: China is anticipated to grow at a CAGR of 8.2% from 2026 to 2033.
Market Size & Forecast
- Market size in 2025: USD 786.1 Billion
- Estimated market size in 2026: USD 831.6 Billion
- Projected market size by 2033: USD 1,334.1 Billion
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The adoption of sustainable materials, e-commerce channels, and smart furniture solutions is further reshaping purchasing patterns and expanding market opportunities. The continued expansion of residential, commercial, and institutional infrastructure is creating a broad demand base for furniture across both developed and emerging markets. New housing developments, hospitals, hotels, community centers, educational facilities, government buildings, and commercial spaces require furniture across multiple categories, including bedroom furniture, seating, storage units, tables, and specialized healthcare furnishings. This relationship is particularly relevant in markets where urbanization, rising housing supply, and large-scale infrastructure investment are increasing the number of newly furnished spaces.
 To learn more about this report, Download Free Sample Report
Government-led housing & urban development programs are also creating a high demand for a variety of furniture products. Saudi Arabia, for example, is using housing and real estate development as part of its broader economic diversification strategy under Vision 2030. The country's Housing Program targets a 70% homeownership rate among Saudi families by 2030, while the government continues to expand residential supply and support infrastructure. In its 2025 annual report, Saudi Arabia stated that homeownership among Saudi families had risen from 47.0% in 2016 to more than 60.0% in 2025.
The scale of ongoing development is also evident from recent project activity. In the first half of 2025, Saudi Arabia's Ministry of Municipalities and Housing announced approximately 26,000 housing units through off-plan projects, alongside more than 5,200 residential plots. Such developments are expected to generate downstream opportunities for furniture manufacturers and suppliers as residential units, hospitality properties, offices, and community facilities progress from construction to fit-out and occupancy.
Alongside construction activity, regulatory and institutional procurement requirements are shaping product specifications, particularly in healthcare and other high-use environments. Furniture supplied to hospitals and healthcare facilities must increasingly address durability, cleanability, infection-control requirements, and resistance to chemicals and stains. These requirements are encouraging manufacturers to move beyond conventional aesthetics and incorporate antimicrobial finishes, easy-clean surfaces, durable laminates, stain-resistant materials, and designs that minimize dust and microbial accumulation. As a result, institutional furniture is increasingly being designed around a combination of hygiene, durability, safety, and lifecycle performance, creating opportunities for manufacturers capable of meeting increasingly stringent technical specifications.
Market Dynamics
The global furniture market continues to expand, driven by steady urbanization, rising disposable income, and expanding residential construction across Asia Pacific. Growth is primarily anchored by the residential segment, particularly bedroom and living room furnishings, while office and commercial sectors are accelerating due to corporate hybrid-work reconfigurations. Fluctuating prices for core inputs-such as timber, metals, polyurethane foam, and specialty textiles-coupled with unpredictable energy, logistics, and ocean freight expenses, continue to squeeze operating margins for global manufacturers.
Expansion of residential construction and housing supply remains a major driver of the global furniture market. Population growth, urbanization, household formation, and government-backed housing programs are increasing the number of newly occupied homes requiring bedroom, living room, dining, and storage furniture. This trend is particularly evident in emerging economies, where housing development is increasingly linked to infrastructure investment and economic diversification.
Saudi Arabia’s FY2026 Budget Statement reported that over 107,000 housing units and developed lands were provided during 2025, while the country continues to target a 70% homeownership rate by 2030. Such additions generate downstream furniture demand as newly completed properties transition from construction to occupancy. Renovation, replacement, and household upgrading further support sales, enabling manufacturers and retailers to benefit from sustained residential investment and changing consumer preferences.
Volatility in the cost of raw materials and production remains a significant restraint on the global furniture market, particularly for manufacturers dependent on wood, metal, foam, plastics, adhesives, finishes, and energy-intensive production. Furniture producers often operate in competitive pricing environments, limiting their ability to fully pass higher material, labor, logistics, and energy costs on to consumers without affecting demand. Wood remains particularly important to furniture manufacturing, making procurement conditions, sustainability requirements, and supply-chain disruptions relevant to production economics.
Manufacturers are responding through greater use of engineered wood, recycled inputs, localized sourcing, and material-efficient designs. However, these strategies can require additional investment in sourcing, production capabilities, and certification. Persistent cost uncertainty may therefore pressure operating margins, influence product specifications, delay capacity investments, and encourage manufacturers to optimize supply chains and redesign products around material availability and cost efficiency.
Integration of technology and multifunctionality is creating new opportunities for furniture manufacturers to move beyond conventional products and capture higher-value demand. Consumers, particularly in urban households, are increasingly seeking furniture that combines storage, lighting, charging, connectivity, and space efficiency. Smart beds, adjustable desks, modular seating, and tables incorporating charging or lighting features are gaining relevance as living spaces become more compact and digitally enabled.
Current industry trends point to growing interest in smart and connected furniture, as well as modular and space-saving designs. This shift enables manufacturers to differentiate through functionality rather than relying solely on materials and aesthetics. It also supports premiumization, as consumers may pay more for products that consolidate multiple functions or integrate technology into everyday routines. Advances in sensors, LED systems, wireless charging, and connected-home ecosystems could further broaden this opportunity.
Analyst Perspective
The furniture market is being shaped by urbanization, new housing supply, institutional and healthcare projects, sustainability, and technology integration rather than residential construction alone. Within this environment, LED bedside tables occupy a distinct position at the intersection of furniture and smart-home products. Integrated LED lighting, charging functionality, space efficiency, and contemporary design are enabling manufacturers to develop higher-value multifunctional furniture. Sustainability is also influencing material and manufacturing choices, with growing interest in recycled, recyclable, renewable, and responsibly sourced materials. Product longevity, repairability, recyclability, lower-impact manufacturing, and transparent sourcing are becoming increasingly relevant, particularly across premium residential, hospitality, commercial, and institutional segments.
Brand Share Analysis
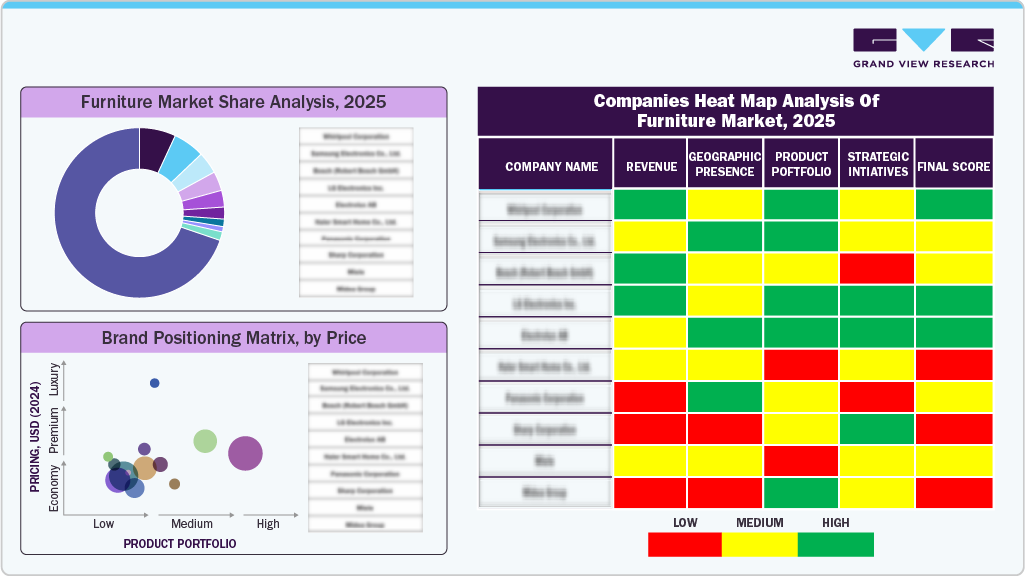
The furniture market is highly fragmented yet increasingly competitive, comprising large multinational manufacturers, regional players, vertically integrated retailers, and specialized niche brands. Established companies benefit from economies of scale, global sourcing capabilities, and extensive distribution networks, while smaller, design-led players compete by differentiating in aesthetics, craftsmanship, customization, and sustainability credentials. Price competition remains pronounced in mass-market segments, whereas premium and luxury tiers are driven by brand equity, design innovation, and material quality.
 To learn more about this report, Download Free Sample Report
Competition in the furniture market is further shaped by ongoing shifts in consumer preferences, the expansion of omnichannel retail, and supply chain optimization efforts. Leading players are investing in product portfolio diversification, digital visualization tools, and direct-to-consumer platforms to enhance customer engagement and improve margins. At the same time, private labels and digitally native brands are intensifying competitive pressure by offering design-forward products at competitive price points. As a result, the competitive landscape continues to evolve toward greater emphasis on brand positioning, operational efficiency, and responsiveness to changing lifestyle and interior design trends.
Consumer Insights & Surveys
 To learn more about this report, Download Free Sample Report
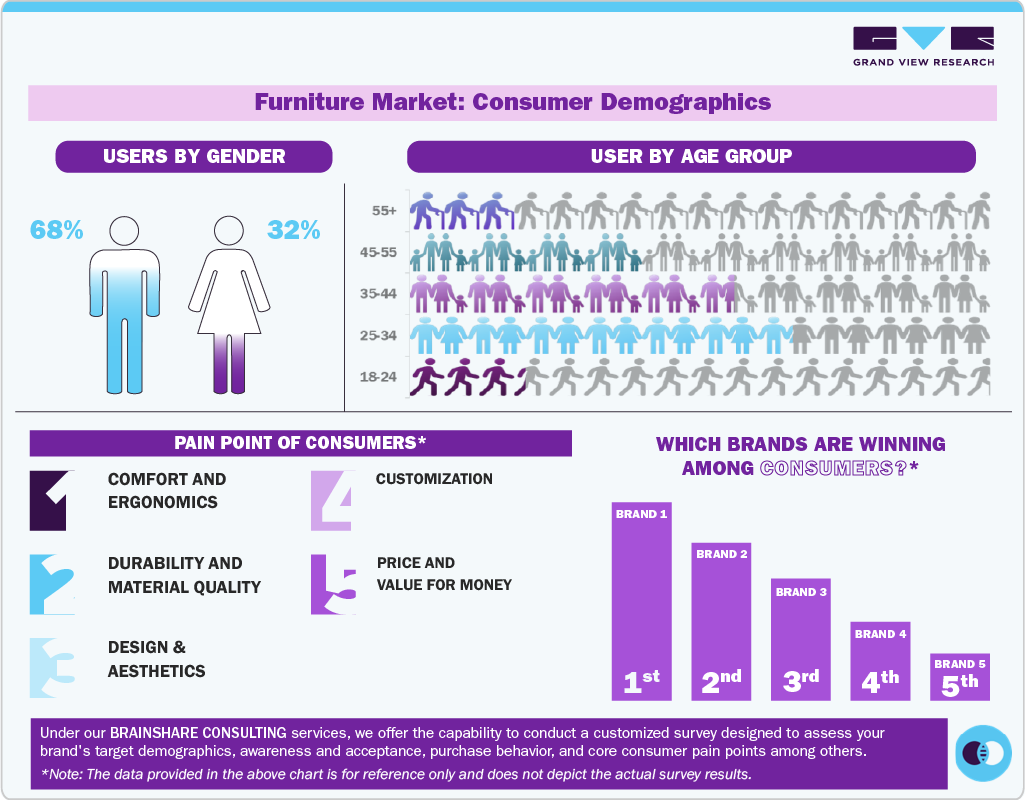
According to a Consumer Insights Now (CIN) survey conducted in late June and early July 2023 among nearly 1,900 U.S. consumers, affordability and product quality emerged as the leading considerations in furniture purchasing decisions. 29% of respondents identified staying within budget as an important final purchase factor, while 28% prioritized product quality, followed by furniture style at 16% and discounts or sales at 11%. Consumers also placed considerable emphasis on product-specific information before purchasing: 64% considered furniture size and dimensions, 48% fabric details, 46% warranty information, 42% reviews and recommendations, and 40% expected product lifespan. Digital channels played an important role in the research process, with 50% of consumers beginning their furniture search on retailer websites and 43% consulting online reviews. The findings indicate that consumers evaluate furniture through a combination of value, durability, design, product specifications, and purchase confidence, while digital channels increasingly support product discovery and evaluation.
Product Insights
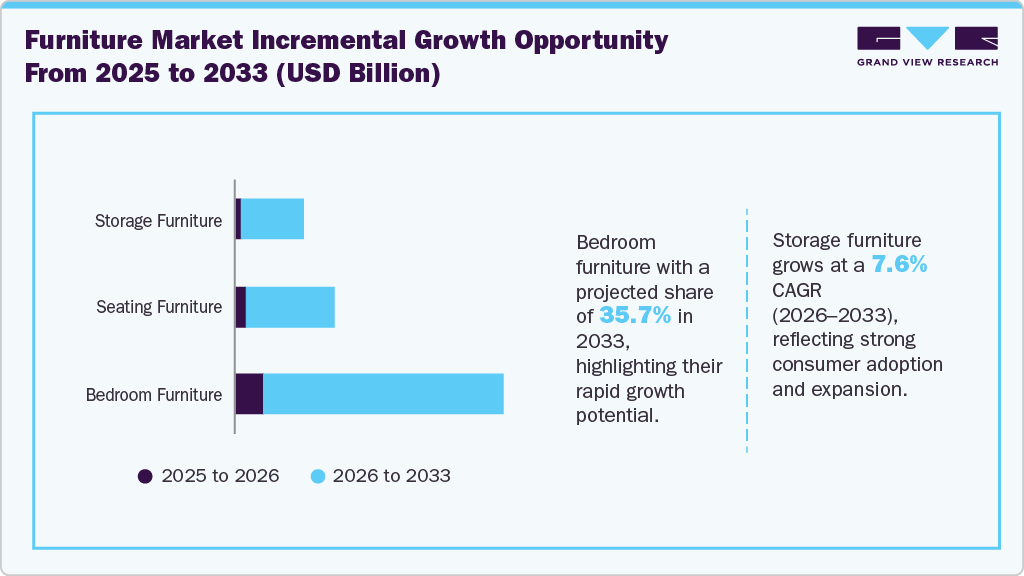
Bedroom furniture accounted for 35.7% of the global furniture market in 2025, supported by continued urbanization, residential construction, and the expansion of rental housing. The growing number of households, particularly in urban areas, is sustaining demand for beds, wardrobes, dressers, nightstands, and other bedroom furnishings. Consumers are placing greater emphasis on comfort, aesthetics, functionality, and customization, encouraging manufacturers to offer designs that accommodate diverse lifestyles and room sizes. Minimalist interiors and space-efficient layouts are further supporting demand for compact and multifunctional bedroom furniture.
Within this category, beds are benefiting from the growing preference for premium, technology-enabled products. Advancements in home-furnishing technology have encouraged the integration of features such as adjustable mechanisms, built-in lighting, charging ports, storage, and smart controls. In parallel, growing interest in contemporary bedroom aesthetics and home renovation is encouraging consumers to upgrade beds as part of broader bedroom makeovers, supporting segment growth over the forecast period.
 To learn more about this report, Download Free Sample Report
Demand for storage furniture is projected to grow at a CAGR of 7.6% from 2026 to 2033, driven by urbanization, smaller residential spaces, and evolving household lifestyles. Wardrobes, dressers, cabinets, shelves, TV stands, drawers, and chests are increasingly used to maximize available space while maintaining organized, visually appealing interiors. The expansion of apartments and rental housing is particularly supporting demand for compact, multifunctional, and modular storage solutions that can adapt to different room configurations. In addition, greater consumer spending on home improvement and interior upgrades has encouraged purchases of storage furniture as a relatively accessible way to refresh living spaces without undertaking major renovations. Product development is also evolving toward technology-enabled solutions, including integrated lighting, charging features, and smart entertainment storage. At the same time, rising environmental awareness is encouraging interest in durable, recyclable, sustainably sourced, and adaptable storage products, further broadening consumer choice.
Material Insights
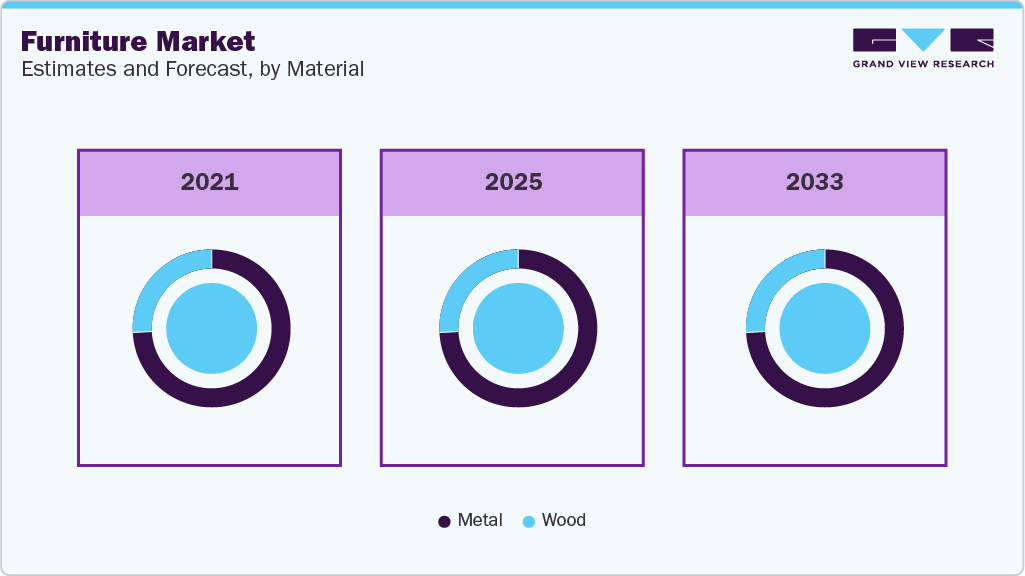
In terms of revenue, the wood segment accounted for 39.8% of the global furniture industry in 2025, maintaining its position as the dominant material category. Wood remains widely used across furniture applications owing to its availability, versatility, durability, and ability to accommodate diverse designs and finishes. The material is used in products ranging from beds and wardrobes to tables, seating, and storage units. Furniture manufacturing also relies on engineered wood products, including plywood, fiberboard, and particleboard, which offer alternatives to solid timber while enabling cost-effective, flexible product designs.
 To learn more about this report, Download Free Sample Report
The plastic segment is projected to grow at the fastest CAGR of 7.7% from 2026 to 2033. The growth of this segment is supported by rising demand for lightweight, affordable, and contemporary furniture, particularly among cost-conscious consumers and urban households. Advances in high-performance plastics and improved manufacturing technologies are also enabling manufacturers to develop durable, aesthetically diverse, and increasingly functional plastic furniture products.
Application Insights
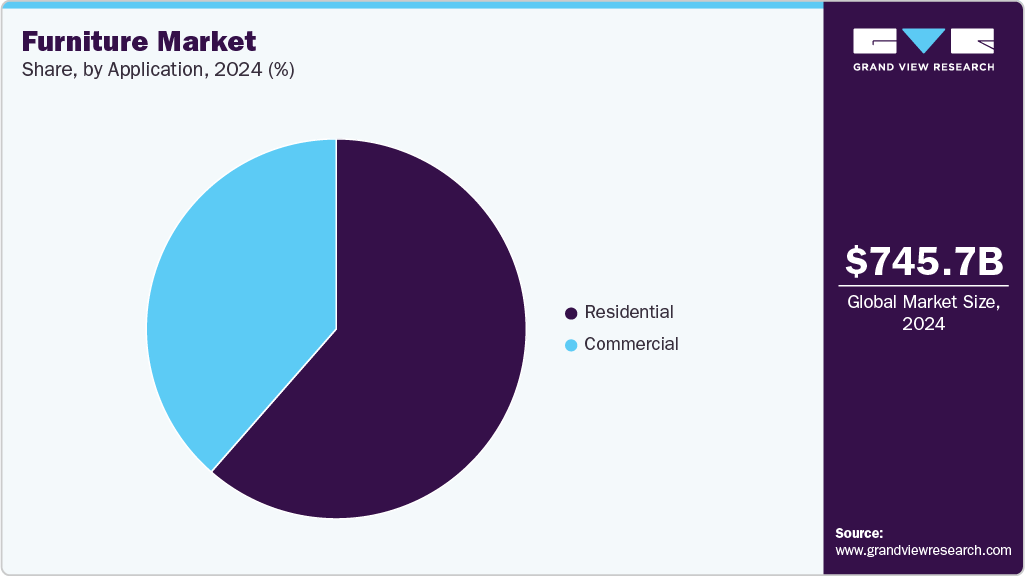
The residential segment accounted for the largest revenue share of 61.3% in 2025 and is projected to expand at a CAGR of 6.8% from 2026 to 2033. Growth is being supported by rising household formation, urbanization, residential construction, and increasing expenditure on living room and bedroom furnishings. Government-led housing and urban development initiatives, particularly across emerging economies, are further expanding the number of residential spaces requiring furniture. In India, for example, the Ministry of Housing and Urban Affairs oversees policies and programs related to urban development and housing infrastructure, supporting the broader expansion of urban residential environments.
 To learn more about this report, Download Free Sample Report
The commercial segment is projected to grow at the fastest CAGR of 7.3% from 2026 to 2033, driven by furniture requirements across offices, hotels, restaurants, cafés, and other commercial establishments. Expansion of office infrastructure, hospitality facilities, and experience-oriented commercial spaces is increasing demand for furniture that combines functionality, durability, aesthetics, and space efficiency.
Regional Insights
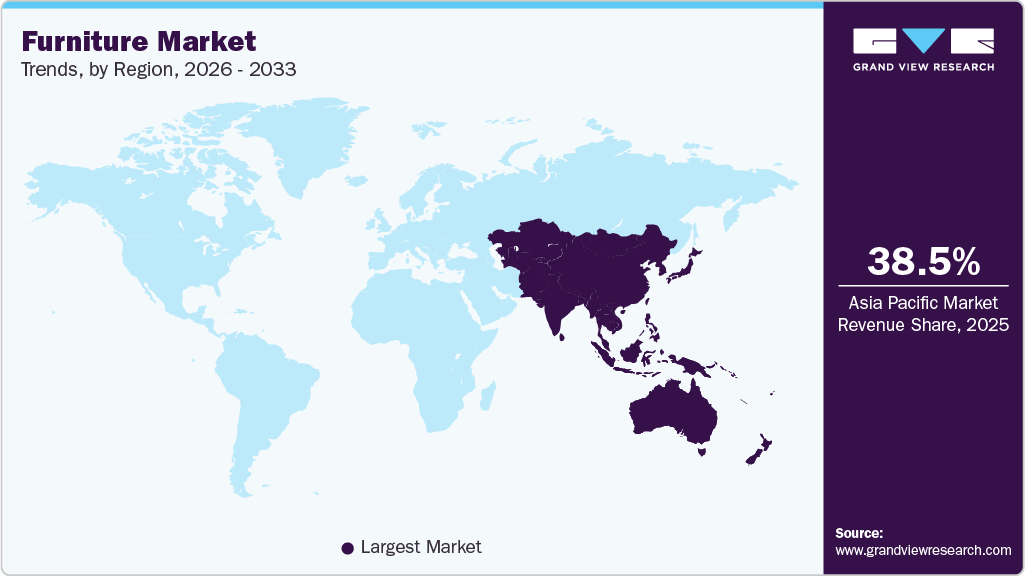
The Asia Pacific dominated the global furniture market, accounting for 38.5% of revenue in 2025, and is expected to grow at the fastest CAGR over the forecast period. The region’s strong position is supported by rising disposable incomes, expanding middle- and upper-income consumer groups, and increasing expenditure on home furnishing and interior upgrades. Demand remains particularly strong for living room furniture, followed by bedroom, kitchen, and dining products, as consumers invest in improving both the functionality and aesthetics of residential spaces. In addition, robust real estate development and government-backed housing initiatives are expanding the number of newly constructed and furnished residential units across major markets. Rapid urbanization and the expansion of the IT and services sectors are also influencing furniture demand by supporting household formation, office development, and migration toward urban centers. Together, these factors are creating sustained demand for residential, commercial, and hospitality furniture and are expected to support the region’s market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
The China furniture market is anticipated to grow at a CAGR of 8.2% from 2026 to 2033. Growth is being supported by premiumization, rising disposable incomes, and greater consumer focus on lifestyle quality. Urban households are increasingly seeking aesthetically refined, space-efficient, and multifunctional furniture suited to smaller living spaces. At the same time, domestic manufacturers are strengthening design capabilities, branding, and product innovation to capture evolving consumer preferences. The integration of online and offline retail channels is further improving product accessibility and expanding market reach.
North America Furniture Market Trends
The North America furniture industry is anticipated to showcase a CAGR of 6.5% from 2026 to 2033. The regional market is expanding on the back of structural shifts in housing patterns, including suburbanization, homeownership, and continued residential construction. In the U.S., the homeownership rate stood at 65.0% in the second quarter of 2026, supporting a large installed base for furniture replacement and upgrades. Demand is supported by strong replacement cycles, higher spending on home improvement, and sustained interest in multifunctional furniture solutions. Digitally enabled retail models and flexible financing options are improving purchase accessibility. The region also benefits from advanced logistics infrastructure supporting faster delivery timelines.
The furniture market in the U.S. is expected to grow at a CAGR of 6.9% from 2026 to 2033. The U.S. market’s growth is driven by lifestyle-driven consumption and a strong focus on personalization and customization. There is a growing consumer preference for comfort, modular design, and adaptability for combined living and working environments. The competitive environment is being reshaped by direct-to-consumer brands and omnichannel strategies. Innovation in materials and the integration of smart furniture are gaining momentum.
Middle East & Africa Furniture Market Trends
The Middle East & Africa furniture industry is expected to grow at the second-fastest CAGR of 7.0% from 2026 to 2033. The growth is driven by rapid infrastructure and tourism development, particularly in Saudi Arabia and the UAE, where governments are investing in hospitality, residential, commercial, and entertainment projects to diversify their economies.
Saudi Arabia recorded 123 million tourists in 2025, including more than 30 million international visitors, while tourism spending reached USD 81 billion, according to the 2025 Vision 2030 Annual Report. Similarly, Dubai welcomed a record 19.59 million international overnight visitors in 2025, up 5% from 2024, while its hotel inventory reached 154,264 rooms across 827 establishments by year-end. These developments are expected to strengthen demand for residential, hospitality, office, and outdoor furniture across the region as new properties transition into furnishing and operational phases.
Europe Furniture Market Trends
The furniture industry in Europe is expected to showcase a CAGR of 6.8% from 2026 to 2033. The market is expanding due to infrastructure development, hospitality investments, and urban population growth. Demand is particularly strong in premium and contract furniture segments. Rapid real estate development supports large-scale furnishing requirements. Imported furniture continues to play a significant role alongside emerging local manufacturers.
The UK furniture market is growing as consumer spending on home renovations and interior upgrades increases. Design-led purchasing behavior and strong demand for premium home furnishings are notable trends. Sustainability and ethical sourcing are influencing brand preference. Online channels play a critical role in product discovery and sales.
Key Furniture Company Insights
The market is characterized by the presence of a few established players and new entrants. Many big players are increasing their focus on the changing furniture trends. Players in the market are diversifying their service offerings to maintain market share.
-
IKEA is a Swedish-founded multinational company known for its affordable, flat-pack, ready-to-assemble furniture, home accessories, and kitchen appliances. Established in 1943 by Ingvar Kamprad, IKEA has grown into one of the world’s largest furniture retailers, operating in over 50 countries. The brand is recognized for its minimalist Scandinavian design, cost-effective manufacturing, and sustainable practices.
-
Restoration Hardware is a high-end American home furnishings company that offers luxury furniture, lighting, textiles, and décor. Founded in 1979 and headquartered in Corte Madera, California, RH is known for its upscale, timeless aesthetic that blends classic and modern design. RH targets affluent consumers and emphasizes quality craftsmanship, exclusivity, and a lifestyle-oriented brand image.
Key Furniture Companies:
The following key companies have been profiled for this study on the furniture market.
-
Jason Furniture (HangZhou) Co., Ltd
Recent Developments
-
In April 2026, IKEA announced a strategic expansion of its brick-and-mortar retail footprint in North America, detailing plans to launch 10 full-format stores across major U.S. metropolitan hubs, alongside expanding its urban "Plan & Order" studio concepts.
-
In February 2026, Ashley Furniture Industries expanded its global retail network by opening specialized Ashley Sleep showrooms across emerging Asian and Latin American markets, reinforcing its position as a leading global manufacturer and distributor.
-
In January 2026, Williams-Sonoma, Inc. announced plans to open 20 retail locations during FY26. The expansion will primarily focus on open-air lifestyle centers for its West Elm and Pottery Barn banners.
-
In April 2025, Italian design house Paola Lenti introduced “Alma,” a groundbreaking outdoor seating collection developed in collaboration with Argentine designer Francisco Gomez Paz. The range includes an armchair, two-seater, and three-seater sofas, all engineered through generative algorithms and CNC-machined stainless-steel frames, complemented by an elastic mesh that eliminates traditional padding. Importantly, Alma’s cushions use biodegradable, recycled polyester fiber, presenting an eco-friendly, polyurethane-free alternative that underscores the brand’s commitment to sustainability.
-
In December 2024, RH opened its largest Gallery, Newport Beach, a 97,000-square-foot, four-level design and retail destination at Fashion Island in California. This flagship space exemplifies RH's evolution from a traditional luxury furniture retailer to a fully immersive lifestyle brand. The Gallery features an expansive showcase of RH Interiors, Modern, Outdoor, Baby & Child, and TEEN collections and a curated selection of antiques.
-
In November 2024, RH opened RH Raleigh, The Gallery at North Hills, a 60,000 sq ft, three-level immersive luxury hub in Raleigh’s North Hills district. The flagship venue blends expansive RH Interiors and contemporary, Modern, and Outdoor collections with rare antiques and global artifacts, all set within a striking glass‑and‑steel structure featuring courtyards edged with Japanese boxwoods and European-style landscaping.
-
In February 2024, La-Z-Boy Inc. announced a significant investment in its presence at the industry’s major trade shows by extending leases for its High Point Market and Las Vegas Market showrooms and planning substantial renovations. The upgrades include a modern, high-tech redesign of its La‑Z‑Boy flagship showroom and the England Furniture space in High Point, aimed at enhancing presentation, comfort, and style ahead of High Point Market in April 2024.
Furniture Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 786.1 billion
Estimated market size in 2026
USD 831.6 billion
Projected market size by 2033
USD 1,334.1 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, material, application, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; South Africa; Australia & New Zealand
Key companies profiled
IKEA; Ashley Furniture Industries Inc.; RH (Restoration Hardware); Williams-Sonoma, Inc.; La-Z-Boy Inc.; Raymour & Flanigan; Oppein Home Group Inc.; Jason Furniture (HangZhou) Co., Ltd; Steelcase Inc.
Customization
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Furniture Market Report Segmentation
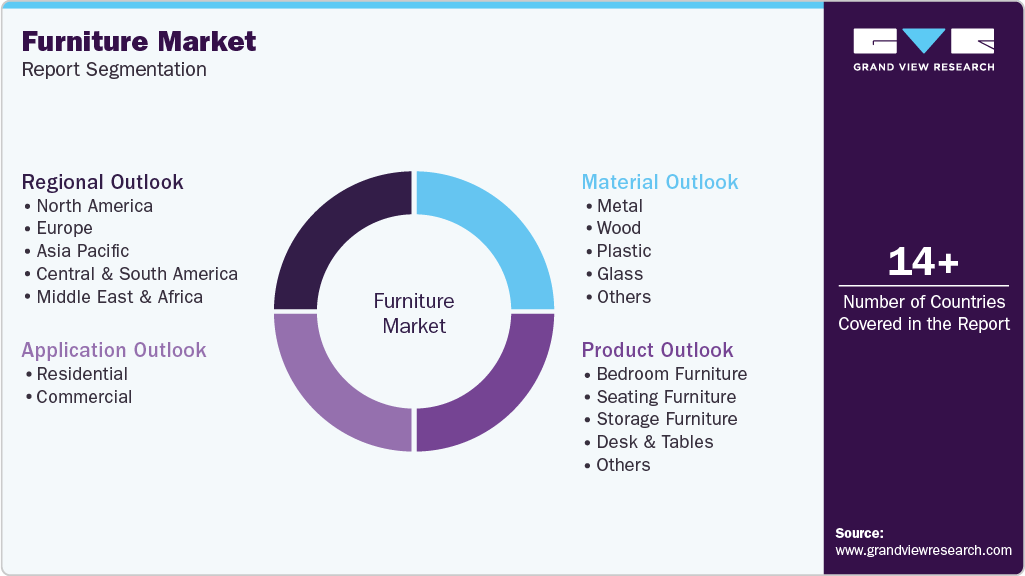
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the furniture market report by product, material, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Bedroom Furniture
-
Mattresses
-
Beds
-
Nightstands
-
-
Seating furniture
-
Chairs
-
Sofa & Couches
-
Others (lounges & recliners, etc.)
-
-
Storage furniture
-
Wardrobes & Dressers
-
Cabinets & Shelves
-
TV Stands/Entertainment Units
-
Others (Drawers, Chests, etc.)
-
-
Desk and Tables
-
Others
-
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Metal
-
Wood
-
Plastic
-
Glass
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia & New Zealand
-
-
Central & South America
-
Brazil
-
-
Middle East and Africa (MEA)
-
South Africa
-
-
Frequently Asked Questions About This Report
The global furniture market was estimated at USD 786.1 billion in 2025 and is expected to reach USD 831.6 billion in 2026.
The furniture market is driven by rising demand for home furnishings, expansion in the real estate sector, and evolving consumer preferences for modular, sustainable, and tech-enabled furniture solutions.
The Asia Pacific dominated the furniture market with a share of 38% in 2025. This growth can be attributed to the increasing disposable income of the upper and middle-class population. Moreover, the increasing demand for living room furniture, followed by bedroom and kitchen, and dining furniture is projected to accelerate the market growth.
Key players in the furniture market include IKEA, Ashley Furniture Industries Inc., RH (Restoration Hardware), Williams-Sonoma, Inc., La-Z-Boy Inc., Raymour & Flanigan, Oppein Home Group Inc., Jason Furniture (HangZhou) Co., Ltd, and Steelcase Inc.
Bedroom furniture segment led with a share of 35.7% in 2025, while storage furniture is expected to grow fastest.
Wood segment led with a market share of about 39.8% in 2025, while plastic segment is expected to grow fastest.
Residential segment led with a market share of 61.3% in 2025, while commercial segment is expected to grow fastest.
The global furniture market is expected to grow at a compound annual growth rate of 7.0% from 2026 to 2033 to reach USD 1,334.1 billion by 2033.
About the Author(s)
HVAC & Construction Research Team
Technology · HVAC & ConstructionThis report was authored by the hvac & construction research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the hvac & construction segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


