
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Wood Coatings Market Size And Share Report, 2026-2033GVR Report cover

Wood Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin Type (Polyurethane, Acrylic, Nitrocellulose, Unsaturated Polyester), By Technology (Solvent Borne, Waterborne, Powder Coating, Radiation Cured), By Application, By Region, And Segment Forecasts
Market Size, 2025
$12.4BMarket Estimate, 2026
$13.0BMarket Forecast, 2033
$18.7BCAGR, 2026–2033
5.3%Wood Coatings Market Summary
The global wood coatings market size was valued at USD 12.4 billion in 2025 and is projected to grow from USD 13.0 billion in 2026 to USD 18.7 billion in 2033, at a CAGR of 5.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 45.5% in 2025. The market for wood coatings is primarily driven by rising demand for furniture and wood-based products, as well as by consumers' preference for aesthetically appealing, durable finishes.
Key Market Trends & Insights
- By resin type: The polyurethane segment dominated the global market, accounting for more than 45.5% of revenue in 2025.
- By applications: The furniture segment dominated the global market, accounting for over 55.5% of revenue in 2025.
- By technology: The solvent-borne segment held the largest share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.5% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 12.4 Billion
- Estimated market size in 2026: USD 13.0 Billion
- Projected market size by 2033: USD 18.7 Billion
- CAGR (2026 - 2033): 5.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Factors such as global population growth and the housing market's recovery have increased demand for furniture products, including beds, chairs, shelves, tables, and cabinets. Furthermore, increasing interest in interior design and decoration across residential spaces, hotels, and corporate offices is driving furniture demand, thereby supporting market growth. Wood coatings are widely used to enhance the appearance and protect wooden products. These coatings provide decorative finishes and protective barriers against environmental factors, including UV radiation, temperature fluctuations, moisture, and abrasion, helping preserve the quality, durability, and longevity of wood surfaces. In addition, wood coatings reduce the risk of warping, rotting, decay, and other forms of wear and tear, making them particularly important for outdoor applications such as fences, decks, and other exposed wooden structures.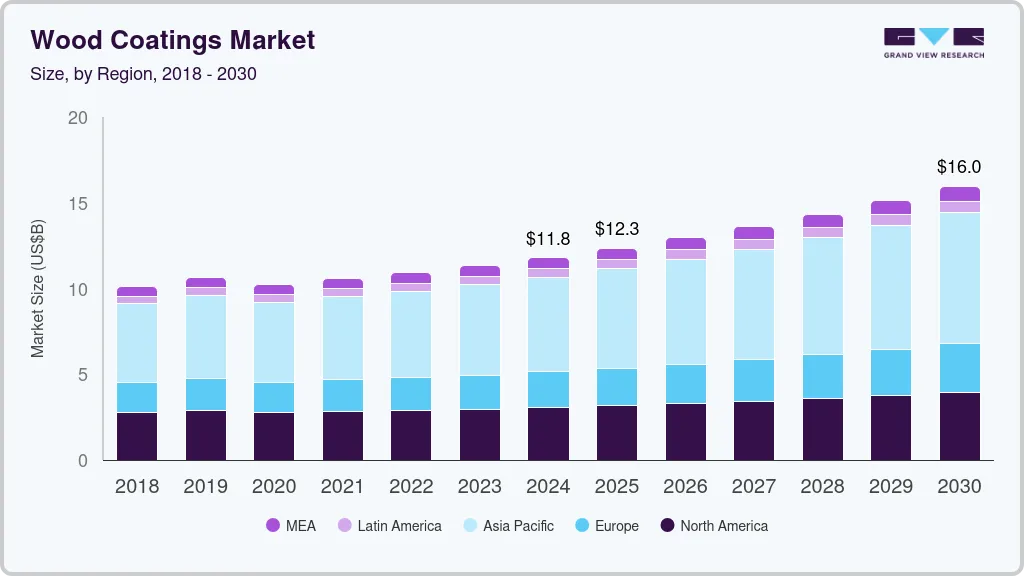 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
Growth in global furniture manufacturing is driving demand for wood coatings across residential, commercial, and institutional applications. Increased production of wooden furniture requires protective and decorative coatings, including stains, varnishes, primers, sealers, and topcoats, to improve durability, appearance, moisture resistance, and surface protection. The rising demand for modular furniture, ready-to-assemble products, and customized interior furnishings is encouraging manufacturers to expand production capacity and invest in advanced finishing technologies. In addition, rapid urbanization, rising residential construction activity, and increasing consumer spending on home improvement and interior décor products are driving furniture consumption worldwide. As furniture manufacturers continue to increase output, demand for industrial wood coatings used in furniture finishing and wood surface treatment is expected to rise.
For instance, in February 2025, AkzoNobel’s Sikkens Wood Coatings business introduced a waterborne wood coating, RUBBOL WF 3350, containing 20% bio-based content. Such initiatives support the advancement of sustainable wood coating technologies and the adoption of bio-based formulations across end-use industries.
Stringent environmental regulations are a significant market restraint, requiring manufacturers to comply with strict limits on volatile organic compound (VOC) emissions and hazardous chemicals, as well as sustainability standards. These requirements reduce formulation flexibility and increase production complexity. As a result, coating producers must invest in research and development to transition toward low-VOC, water-based, and bio-based formulations while maintaining product performance and durability, thereby increasing development and production costs. Regulatory pressure continues to increase across major markets, particularly in Europe and North America, where environmental standards governing emissions, chemical usage, and product sustainability are becoming more stringent. Compliance with these regulations often requires reformulation, additional testing, certification, and process modifications, which can increase operational costs and extend product development timelines for wood coating manufacturers.
The development of bio-based wood coatings presents a significant market opportunity. This trend is driven by increasing demand for sustainable materials and environmentally responsible coating solutions. Manufacturers such as Sherwin-Williams, AkzoNobel, PPG Industries, Axalta Coating Systems, and Nippon Paint Holdings are focusing on plant-derived resins and bio-based formulations to reduce dependence on fossil-based inputs while maintaining coating performance and durability. In addition, growing sustainability commitments across the furniture, construction, and wood processing industries are driving the adoption of low-emission and renewable coating technologies. These trends are expected to create growth opportunities for manufacturers through the development of innovative bio-based coating technologies and sustainable product portfolios.
Analyst Perspective
The market is transitioning toward high-performance, environmentally responsible coating solutions, driven by evolving regulatory requirements and changing consumer preferences. The increasing demand for aesthetically appealing, durable wood products across furniture, construction, and interior applications continues to support market expansion. Manufacturers are focusing on developing advanced coating technologies that offer enhanced protection, improved finish quality, and lower environmental impact. In addition, growing adoption of waterborne and bio-based formulations is reshaping product development strategies across the industry. Ongoing investments in sustainable coating technologies and innovation in wood finishing solutions are expected to create new growth opportunities for market participants over the forecast period.
Resin Type Insights
The polyurethane segment dominated the global market, accounting for more than 45.5% of revenue in 2025. The segment's dominance is attributed to the widespread use of polyurethane coatings across furniture, flooring, cabinetry, and interior wood applications. Polyurethane coatings provide excellent durability, abrasion resistance, chemical resistance, and UV protection while maintaining surface appearance over extended periods. Their ability to deliver high-performance protective finishes and long service life has supported their adoption across residential and commercial wood products.
The nitrocellulose segment is expected to grow at a high CAGR during the forecast period. Nitrocellulose is one of the most widely used resins in the wood coatings industry due to its fast drying, ease of application, and cost-effectiveness. Resin is commonly used in furniture and interior wood-finishing applications where efficient production cycles and aesthetic appearance are important. In addition, nitrocellulose coatings offer good repairability, allowing localized surface repairs without extensive refinishing. Their favorable balance of performance, processing efficiency, and affordability continues to support adoption across furniture manufacturing and wood processing applications.
Application Insights
The furniture segment led the market, accounting for over 55.5% of revenue in 2025. The segment benefits from evolving consumer preferences toward premium interiors, customized furniture, and aesthetically finished wood products. Manufacturers increasingly use wood coatings to improve surface appearance, maintain color consistency, and protect furniture from daily wear and tear. The growing emphasis on product quality and visual appeal in residential and commercial furniture continues to drive the adoption of advanced wood-coating solutions.
The flooring and decking segment is expected to grow rapidly during the forecast period. Wood flooring and decking surfaces are exposed to continuous foot traffic, moisture, temperature variations, and outdoor environmental conditions. As a result, demand for coatings that provide abrasion resistance, weather protection, and long-term surface durability is increasing. The expansion of outdoor recreational spaces, hospitality projects, and premium residential developments is further driving the adoption of wood coatings for flooring and decking applications.
Technology Insights
The solvent-borne segment accounted for the largest revenue share in 2025. Solvent-borne coatings are very popular in the paints and coatings industry. Solvent-borne coatings are easy to apply and have been traditionally thought to provide a better finish. Solvent-borne coatings often provide superior performance characteristics compared to water-based coatings. They offer excellent durability, adhesion, and resistance to wear, chemicals, and environmental factors. In addition, they typically offer faster drying times compared to waterborne coatings. This rapid drying enables quicker turnaround times in manufacturing and construction, reducing labor and energy costs. Solvent-borne coatings are known for their ability to withstand harsh environmental conditions, such as exposure to extreme temperatures, UV radiation, and moisture.
However, the release of VOCs during the application of solvent-borne coatings has led to increased focus on developing and adopting environmentally friendly, low-VOC alternatives such as water-borne and powder coatings. This shift towards eco-friendly options may pose potential challenges to the future growth of solvent-borne coatings in the industry.
The waterborne segment is expected to grow rapidly during the forecast period. Waterborne coatings contain lower levels of VOCs and are considered more environmentally friendly than solvent-borne coatings. In addition, they have a milder odor, creating a more pleasant working environment for applicators and helping reduce indoor air pollution. Waterborne coatings contain fewer hazardous chemicals and offer improved safety during handling and storage due to their lower flammability. These advantages, coupled with increasing environmental regulations and sustainability requirements, support the adoption of waterborne coatings across various wood coating applications.
Regional Insights
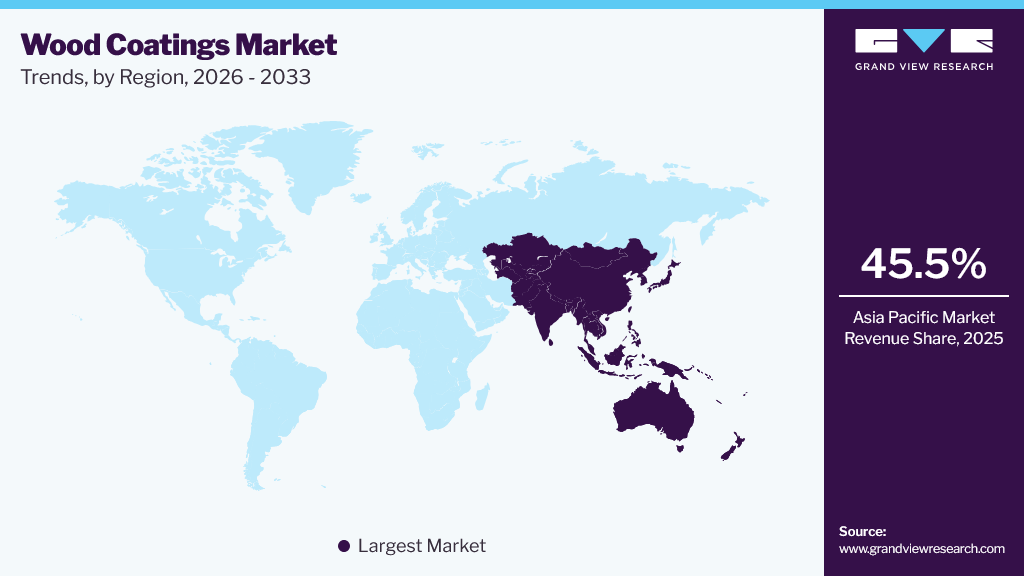
Asia Pacific dominated the wood coatings market, accounting for over 45.5% of revenue in 2025. Rising production of furniture, cabinetry, flooring, and other wood-based products is contributing to higher demand for wood coatings across the region. Growth in residential construction activities and increasing preference for aesthetically finished wood products are further supporting the adoption of wood coating solutions in major markets such as China, India, Vietnam, and Indonesia.
 To learn more about this report, Download Free Sample Report
In addition, rising investments by furniture manufacturers are supporting demand for wood finishing and protective coating solutions. For instance, in January 2026, IKEA announced plans to more than double its investment in India to over USD 2.2 billion over the next five years while expanding local production and sourcing capabilities. The expansion reflects continued growth in furniture manufacturing and consumption across the region, supporting demand for wood coatings used in furniture and interior wood applications.
North America Wood Coatings Market Trends
The wood coatings market in North America is shifting toward waterborne and low-emission technologies as manufacturers move away from solvent-based systems to comply with increasingly stringent environmental regulations. U.S. Environmental Protection Agency (EPA) requirements to reduce VOC emissions are prompting producers to develop low-VOC formulations for furniture, cabinetry, and interior wood applications. For instance, in January 2024, Sherwin-Williams launched SHER-WOOD EA Hydroplus, a waterborne wood coating designed for cabinetry, furniture, and building product applications. The coating offers low VOC content, improved flow and leveling characteristics, and enhanced film hardness, supporting production efficiency while helping manufacturers meet evolving environmental requirements.
U.S. Wood Coatings Market Trends
The U.S. wood coatings market is supported by strong demand from the furniture, cabinetry, flooring, and building products industries. Growth is driven by rising renovation and remodeling activity, increased spending on home improvement projects, and sustained demand for aesthetically appealing, durable wood finishes. In addition, the presence of a large manufacturing base and an established wood processing industry continues to support the consumption of wood coatings across residential and commercial applications.
Europe Wood Coatings Market Trends
The wood coatings market in Europe is characterized by strong demand from the furniture, construction, and interior wood products industries, particularly across Germany, Italy, France, and the UK. Market growth is supported by the region’s well-established furniture manufacturing base and by increasing demand for high-quality wood for residential and commercial applications. In addition, growing emphasis on sustainable construction practices and environmentally responsible coating solutions is encouraging the adoption of advanced wood coating technologies across the region.
Middle East & Africa Wood Coatings Market Trends
The wood coatings market in MEA is supported by growing infrastructure development, luxury real estate projects, and demand for premium interior wood applications. Countries such as the UAE, Saudi Arabia, Qatar, and South Africa are investing in residential, hospitality, and commercial construction projects that use wooden doors, cabinetry, panels, and decorative wood furnishings. For instance, in January 2026, UAE-based interior fit-out company ME FITOUT completed the interior works for the 25-story Reem Eleven residential tower in Abu Dhabi. The project included customized wooden doors, custom wardrobes, kitchen units, decorative wall cladding, and interior wood panel installations. Such projects increase demand for wood coatings used to finish and protect premium interior wood products.
Key Wood Coatings Company Insights
The market is highly competitive, with global manufacturers competing through product innovation, strategic partnerships, acquisitions, and capacity expansion initiatives. Companies are increasingly focusing on sustainable coating technologies, including waterborne, UV-cured, and low-VOC formulations, to strengthen their product portfolios and market presence across furniture, flooring, and architectural wood applications.
Key Wood Coatings Companies
The following key companies have been profiled for this study on the wood coatings market.
-
The Sherwin-Williams Company
-
PPG Industries, Inc.
-
Akzo Nobel N.V.
-
Nippon Paint Holdings Co., Ltd.
-
RPM International Inc.
-
Diamond Paints
-
KANSAI HELIOS
-
BASF SE
-
Axalta Coating Systems, LLC
-
Asian Paints
- Eastman Chemical Company
Recent Developments
-
In January 2026, ICRO Coatings announced a global partnership with Kansai Nerolac Paints to strengthen collaboration in wood coating solutions, with a focus on the Indian market. The partnership combines ICRO Coatings’ expertise in wood coatings and finishes with Kansai Nerolac Paints’ market presence and distribution network in India. Such developments highlight efforts to expand the availability of advanced wood coating solutions and strengthen market penetration in the Indian wood coatings industry.
-
In June 2026, Teknovace and Remmers Gruppe SE entered a strategic partnership valued at approximately USD 35 million, under which Remmers Gruppe SE will acquire a 50.0% stake in Teknovace in phased transactions. The agreement focuses on expanding manufacturing capacity in India and establishing facilities for UV coatings, resins, and construction chemicals, as well as a global R&D center. This partnership is expected to strengthen production capabilities and support growth in industrial and wood coatings applications.
-
In February 2025, Gemini Industries acquired Diamond Vogel's Industrial Wood business unit. This acquisition represents a strategic milestone to advance quality, innovation, and service in the wood coatings industry. The transaction strengthens Gemini Industries' presence in the industrial wood coatings segment and reflects ongoing industry consolidation.
Wood Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.4 billion
Estimated market size in 2026
USD 13.0 billion
Projected market size by 2033
USD 18.7 billion
Growth rate
CAGR of 5.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin type, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Turkey; Netherlands; China; Australia; Japan; South Korea; Thailand; South Korea; Indonesia; Malaysia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
The Sherwin-Williams Company; PPG Industries, Inc.; Akzo Nobel N.V.; Nippon Paint Holdings Co., Ltd.; RPM International Inc.; Diamond Paints; KANSAI HELIOS; BASF SE; Axalta Coating Systems, LLC; Asian Paints; Eastman Chemical Company
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Wood Coatings Market Report Segmentation
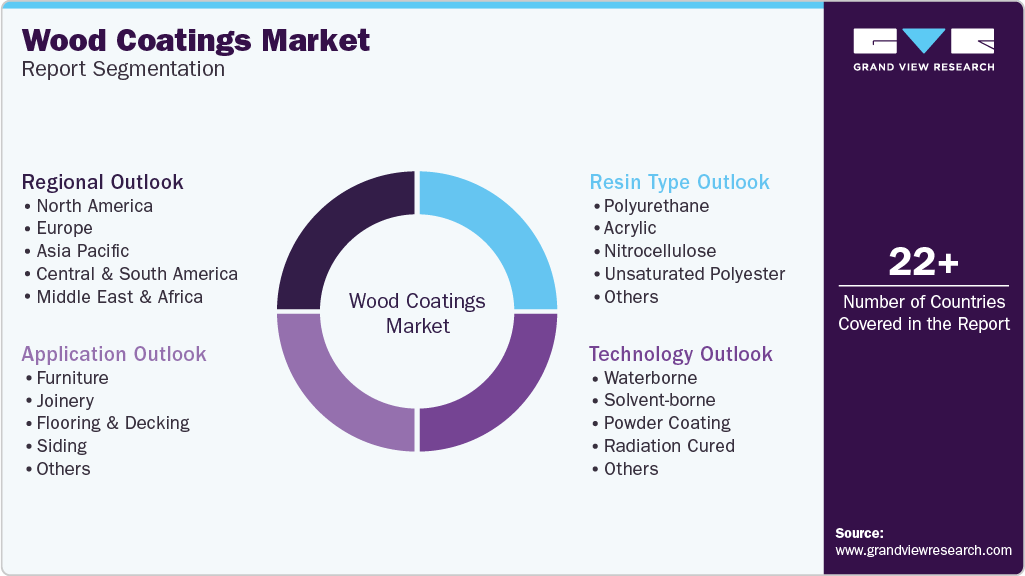
This report forecasts regional and country-level revenue growth and provides an analysis of the latest industry trends and opportunities in each sub segment from 2021 to 2033. For this study, Grand View Research has segmented the global wood coatings market report based on resin type, technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Resin Type Outlook (Volume in Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Polyurethane
-
Acrylic
-
Nitrocellulose
-
Unsaturated Polyester
-
Others
-
-
Technology Outlook (Volume in Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Waterborne
-
Solvent-borne
-
Powder Coating
-
Radiation Cured
-
Others
-
-
Application Outlook (Volume in Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
Furniture
-
Joinery
-
Flooring & Decking
-
Siding
-
Others
-
-
Regional Outlook (Volume in Kilo Tons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Turkey
-
Netherlands
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
Indonesia
-
Malaysia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Frequently Asked Questions About This Report
The global wood coatings market size was valued at USD 12.4 billion in 2025 and is estimated at USD 13.0 billion for 2026.
The global wood coatings market is expected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 18.7 billion.
Key players include The Sherwin-Williams Company; PPG Industries, Inc.; Akzo Nobel N.V.; Nippon Paint Holdings Co., Ltd.; RPM International Inc.; Diamond Paints; KANSAI HELIOS; BASF SE; Axalta Coating Systems, LLC; Asian Paints; Eastman Chemical Company
Asia Pacific dominated with a 45.5% revenue share in 2025.
Furniture dominated the wood coatings market with a share of 55.5% in 2025.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


