
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Zero Friction Coatings Market Size And Share Report, 2033GVR Report cover

Zero Friction Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By product (Polytetrafluoroethylene, Molybdenum Disulfide), By Formulation, By End-use (Aerospace, Energy), By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.6BCAGR, 2026–2033
5.5%Zero Friction Coatings Market Summary
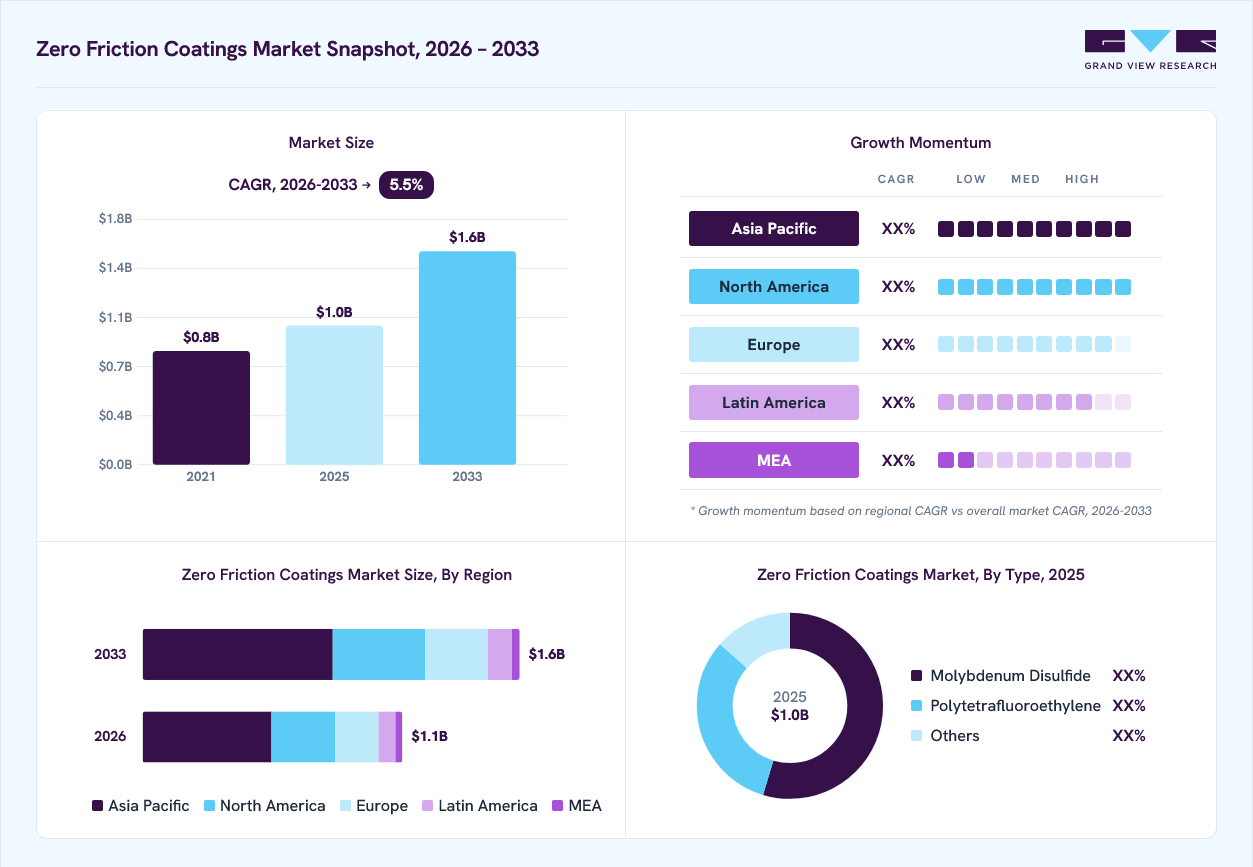
The global zero friction coatings market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.6 billion by 2033, at a CAGR of 5.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 49.5% in 2025. The growing demand for zero friction coatings is attributed to their lubricating and corrosion protection properties, which increase the wear life of components across industries such as automotive, energy, and aerospace.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Molybdenum disulfide segment held the largest revenue share of 54.6% in 2025.
- By formulation: Solvent-based coatings segment held the largest revenue share of 41.4% in 2025.
- By end-use: Automobile & transportation segment held the largest share of 37.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (49.5% revenue share, 2025)
- By country: China held the largest share of the Asia Pacific market in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.6 Billion
- CAGR (2026-2033): 5.5%
Prism AI by Grand View Research Free to tryAsk a question about the zero friction coatings marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Low friction coatings can also avoid noises thus making them suitable for use on any kind of material. The product improves performance, safety, and reliability by extending lubrication intervals, controlling wear and friction, preventing component failures, and reducing operating and production costs these coatings are generally applied at 10-20 µm dry film thickness. Zero friction coatings are applied either by dipping, spraying or using paint drums and centrifuges depending on the nature of the component being treated.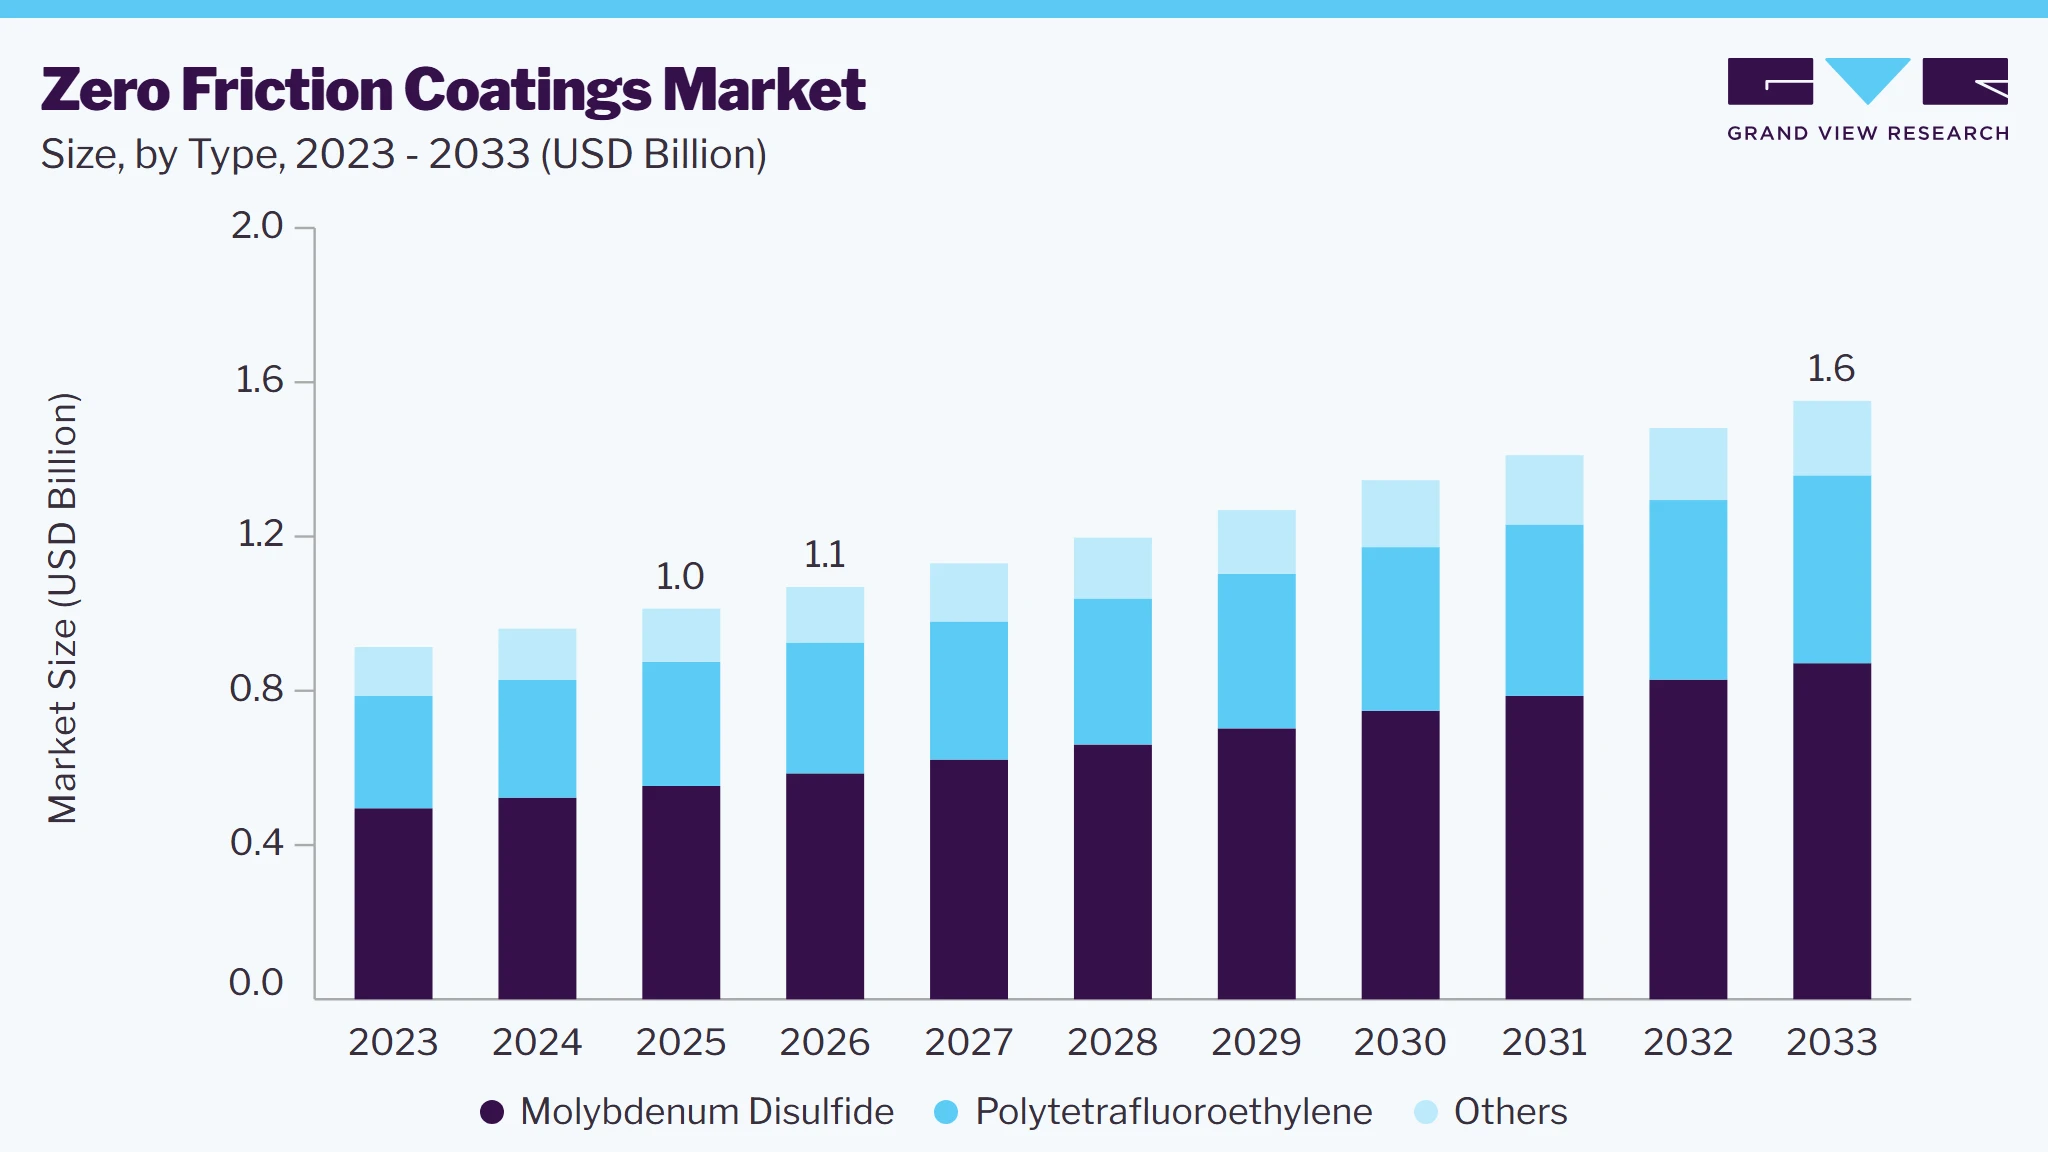 To learn more about this report, Download Free Sample Report
The method of making a zero-friction coating on the metal surface includes various steps such as forming an encapsulated powder that has grains made from a core of solid lubricants that includes at least MoS2 & graphite and a thin shell of fusable soft metal like copper, zinc, nickel, or others. Further, coating of uniform thickness of about 25-175 microns is then formed.
Market Dynamics
The zero friction coatings market is growing due to increasing demand for improved efficiency, reduced energy consumption, and longer service life of mechanical components across automotive, aerospace, industrial machinery, and electronics sectors. Manufacturers are adopting these coatings to minimize wear, reduce maintenance requirements, and enhance equipment performance under demanding operating conditions. The rising use of electric vehicles, precision machinery, and advanced manufacturing systems is creating demand for low friction solutions that improve reliability and operational efficiency. Growing focus on sustainable technologies and cost reduction is encouraging industries to replace traditional lubrication methods with advanced coating solutions.
Industries are increasingly adopting zero friction coatings to improve the energy efficiency of machines and reduce losses caused by mechanical friction. Friction between moving components results in energy wastage, heat generation, and faster wear, increasing operational expenses. By applying low friction coatings, manufacturers can enhance component performance, reduce power consumption, and extend equipment lifespan. This benefit is encouraging adoption across automotive engines, industrial equipment, aerospace systems, and manufacturing machinery.
The growing requirement for durable and efficient components in high performance applications is increasing the use of advanced coating technologies. Companies are focusing on improving productivity while lowering maintenance costs, which creates demand for coatings that provide better wear resistance and smoother operation. This shift toward efficient mechanical systems is contributing to market expansion.
The high cost associated with manufacturing and applying zero friction coatings restricts their adoption in several price sensitive industries. These coatings often require specialized materials, advanced deposition processes, and skilled technical expertise, which increase overall production expenses. Small and medium sized manufacturers may find it difficult to justify the additional investment compared with conventional lubrication methods or standard surface treatments. The requirement for specific application conditions and equipment also increases implementation costs. As a result, industries with limited budgets may continue using traditional solutions, reducing the penetration of zero friction coatings in certain market segments.
The increasing adoption of electric vehicles creates significant opportunities for zero friction coating manufacturers due to the need for efficient and durable components. EV systems require solutions that improve energy efficiency, reduce component wear, and support longer operating life. Zero friction coatings can be applied to bearings, gears, motors, and other moving parts to minimize friction losses and enhance vehicle performance. Manufacturers developing coatings specifically designed for electric mobility applications can capture growing demand from automotive companies. The expansion of EV production worldwide encourages innovation in lightweight and high performance materials, creating opportunities for advanced coating providers to develop specialized solutions for next generation transportation systems.
Analyst Perspective
The zero friction coatings market is experiencing steady growth as industries seek solutions that improve component efficiency, reduce energy losses, and extend equipment lifespan. Increasing adoption in automotive, aerospace, and industrial machinery applications is creating demand for advanced low friction surface technologies. Growth opportunities are emerging from electric vehicle components, renewable energy equipment, and precision engineering systems requiring enhanced durability. Manufacturers are focusing on customized coating formulations and application technologies to address specific performance requirements. Rising emphasis on maintenance reduction and operational efficiency will continue supporting market expansion.
Product Insights
Based on product, the molybdenum disulfide segment accounted for the largest share of the zero friction coatings market, representing 54.6% of total revenue in 2025. The growth is attributed to properties such as high load carrying capacity and excellent adhesion. MoS2 is a dry film lubricant that prevents galling, fretting, and seizing to extend the wear life when operating at temperatures in the range of -350°F and +500°F. The coefficient of friction of this type of coating is 0.07. MoS2 coating solution is used for critical equipment and parts and is widely used in corrosion management as it is unreactive to most corrosive agents.
The polytetrafluoroethylene (PTFE) was the second-largest segment and accounted for a revenue share of over 31.8% in 2025 and is predicted to witness a CAGR of 5.3% in the coming years. The growth is attributed to its properties such as high dielectric strength, heat tolerance, non-sticks, and chemical resistance. The temperature tolerance of PTFE ranges from -518°F to 599°F thus making it suitable for use in bakeware applications. The carbon-fluorine bonds of PTFE are extremely flexible and non-reactive which makes it an excellent electrical insulator. These coatings find applications in the medical field in the manufacturing of medications, in the tech sector for producing high-tech parts and tools, and in other industrial applications.
Formulation Insights
The solvent-based coatings segment accounted for the largest revenue share of 41.4% in 2025. The growth is attributed to the less susceptibility of these coatings to environmental conditions including humidity and temperature during the curing phase.
The water-based coating was the second-largest segment and accounted for a revenue share of over 36.4% in 2025 and is predicted to witness a CAGR of 6.0% in the coming years. The growth is attributed to low volatile organic compound (VOC) content, resilience against accelerated aging exposures, and the ability to be pigmented. It also shows lower friction along with extended weathering.
End-use Insights
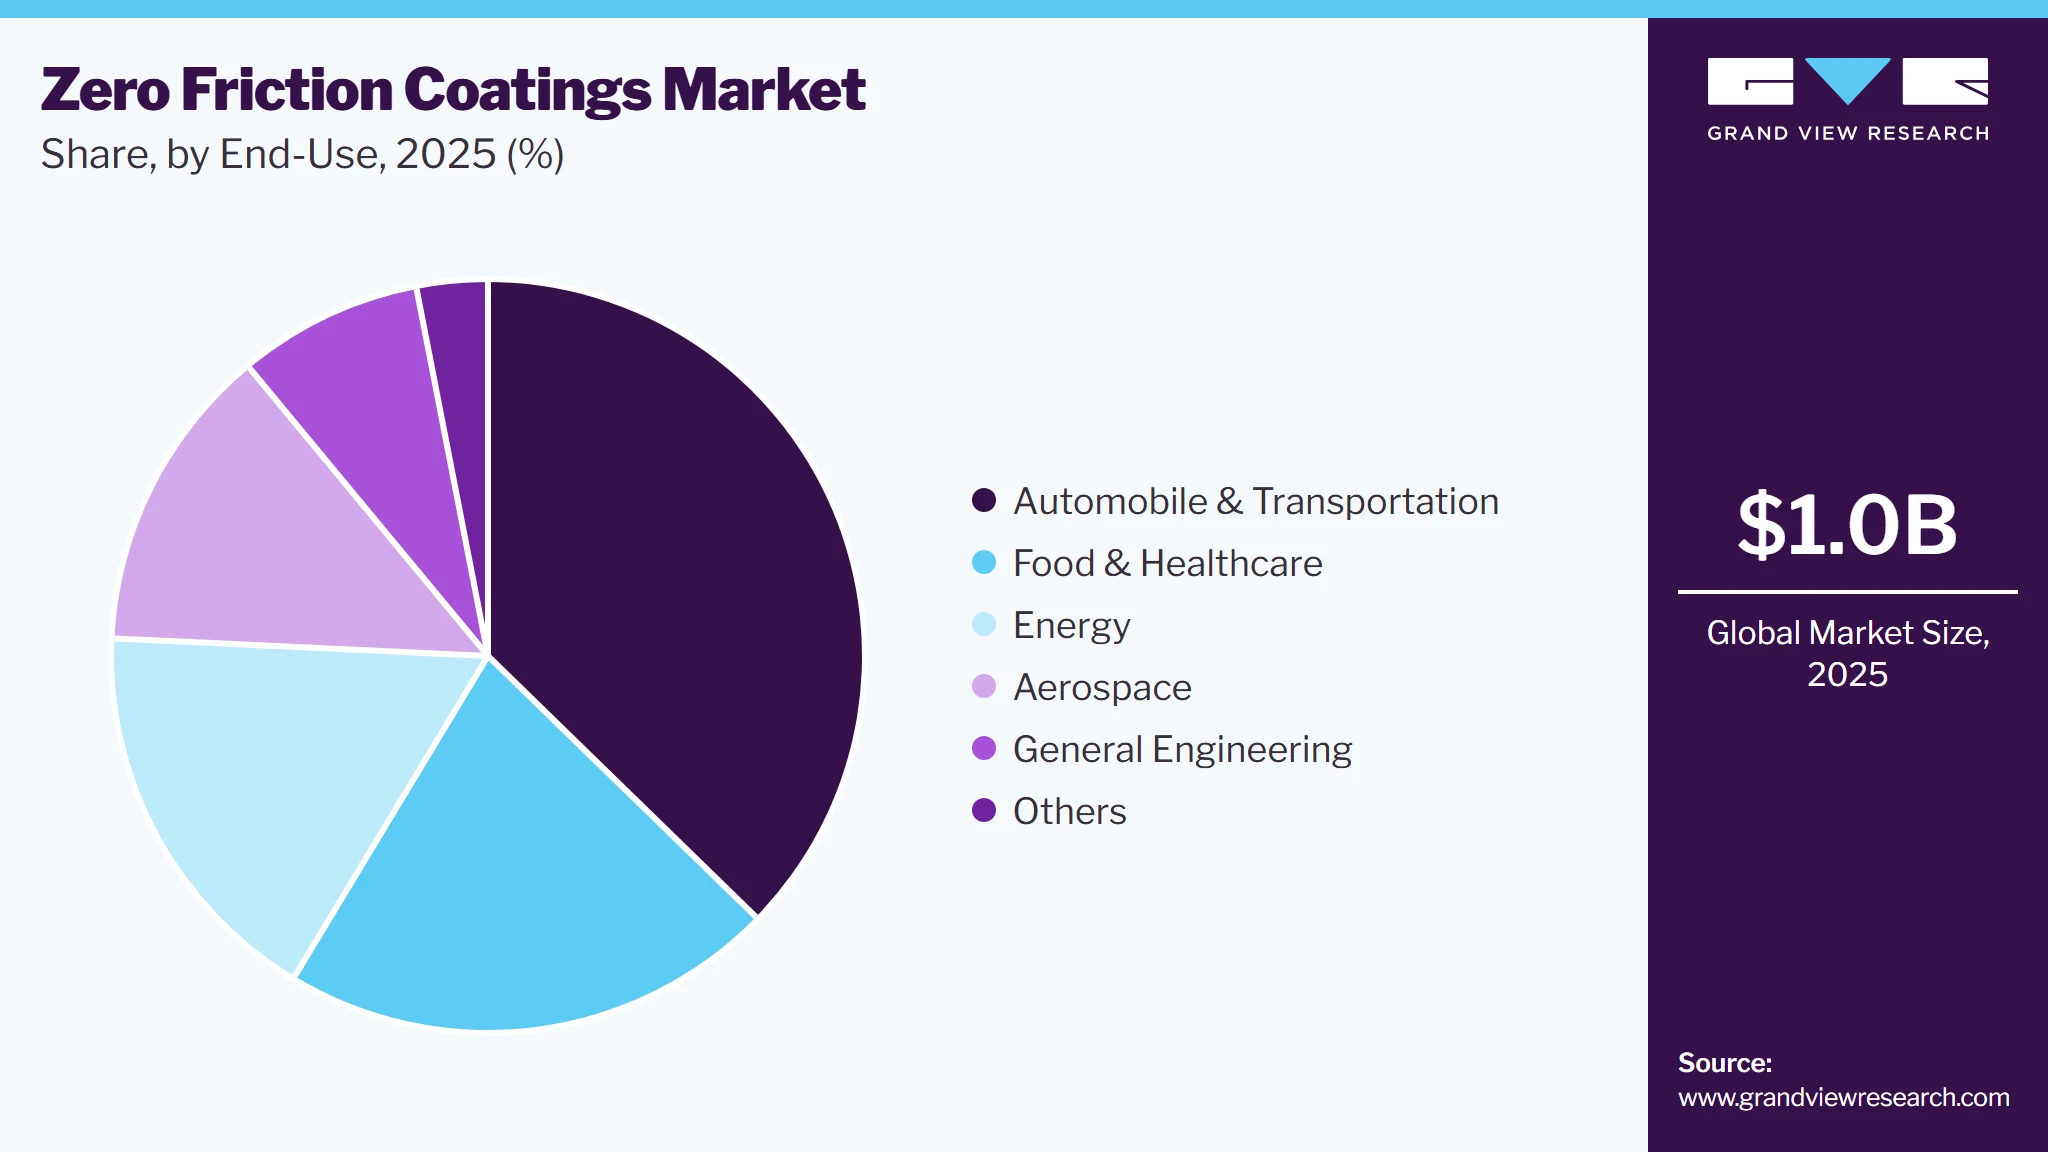
The automobile & transportation segment accounted for the largest share of the zero friction coatings market, representing 37.3% of total revenue in 2025. This is attributed to their ability to reduce noise making them ideal for automotive applications where they are used to reduce cabin noise which is a priority in cars these days. The growing sales of automobiles across the globe coupled with the rising adoption of electric vehicles is anticipated to drive the growth of the automotive industry which in turn is likely to have a positive impact on the zero friction coatings market.
 To learn more about this report, Download Free Sample Report
The food and healthcare was the second-largest segment and accounted for a revenue share of over 21.4% in 2025. The growth is attributed due to increased need of coatings for parts used on food packaging and processing equipment for providing non-stick, wear resistant, and non-wetting surfaces. In healthcare sector, low friction coatings are used in analytical and surgical instrumentation, autoclave and sterilization equipment, and packaging of pharmaceutical products.
The energy segment accounted for a revenue share of 17.1% in 2025 and is expected to witness a CAGR of 5.6% in the predicted years. The growth is attributed to the exposure of materials to extremely harsh environments in the oil and gas industry. Properties of the product including temperature resistance, corrosion resistance, UV protection, chemical protection, and others are likely to foster its demand in the energy sector over the forecast period.
Regional Insights
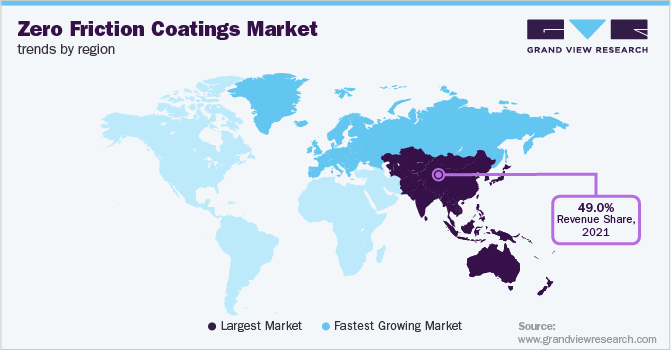
Asia Pacific accounted for 49.5% of the zero friction coatings market revenue in 2025, making it the largest regional market. The growth is attributed to the presence of automotive manufacturing industries in the countries such as Japan, South Korea, and China. The Association of Southeast Asian Nations is the seventh largest automotive manufacturing hub across the world and produced around 3.5 million vehicles in 2021. The region has a presence of some of the leading automotive manufacturers including Honda, Toyota, Ford, BMW, and others. The growing automobile industry in the region is predicted to fuel the demand for zero friction coatings in the predicted years.
 To learn more about this report, Download Free Sample Report
According to the International Trade Administration, China maintained a leading position in the Asia Pacific zero friction coatings market. The motor vehicle imports of the country have decreased from 1,246,800 in 2017 to 927,632 in 2020. This is likely to foster the domestic production of vehicles thereby having a positive impact on the market in the coming years.
Europe accounted for a revenue share of 16.7% in 2025 and is predicted to witness a CAGR of 5.4% over the forecast period. According to the European Automobile Manufacturers Association, the commercial production of vehicles in Europe grew by 4.9% in 2021 despite supply chain constraints. The U.K. was a leading country in the exports of commercial vehicles from the region in 2021 accounting for a market share of around 29.5%. The automotive sector contributes around 7% of the GDP of the European Union. The growing automobile sector in the country is expected to bolster the demand for zero friction coatings in the region in the near future. Some of the leading automotive manufacturers in the region include Volkswagen, Daimler, BMW, Stellantis.
Key Companies & Market Share Insights
Major manufacturers are engaged in adopting several strategies including joint ventures, business expansions, and new product launches to increase their market presence. For instance, In June 2020, Poeton launched a new low friction coating named Apticote 480A having a remarkably low coefficient of friction with a 75.0% reduction as compared to their previous offerings.
Key Zero Friction Coatings Companies
The following key companies have been profiled for this study on the zero friction coatings market.
-
Archroma
-
BASF SE
-
BioTex Malaysia
-
Dow
-
Ethox Chemicals LLC
-
Evonik Industries AG
-
Fibro Chem LLC
-
German Chemicals Ltd.
-
Govi N.V.
-
Huntsman International LLC
-
Kemira Oyj
-
Kiri Industries Ltd.
-
LANXESS
-
OMNOVA Solutions Inc.
-
Omya United Chemicals
-
Organic Dyes and Pigments
-
Resil Chemicals Pvt. Ltd.
-
Solvay S.A.
-
The Lubrizol Corporation.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Endura Coatings, DuPont, VITRACOAT, Poeton Industries, Carl Bechem GmbH, IKV Tribology Ltd.)
- These companies focus on developing specialized low friction coating solutions for automotive, aerospace, and industrial applications.
- They expand through product innovation, application expertise, technical support, and partnerships with component manufacturers requiring advanced surface treatments.
Category
Operating Strategies
Competitive Edge
Weakness
Emerging Players (ASV Multichemie Private Limited, GMM Coatings Private Limited, AFT Fluorotec Ltd., Master Bond Inc., Sandwell UK Ltd., Whitmore Manufacturing)
- These companies focus on expanding their presence through specialized coating solutions, regional customer support, and application specific products.
- They target industries requiring friction reduction, wear protection, and improved component durability.
- These companies focus on expanding their presence through specialized coating solutions, regional customer support, and application specific products.
- They target industries requiring friction reduction, wear protection, and improved component durability.
- These companies focus on expanding their presence through specialized coating solutions, regional customer support, and application specific products.
- They target industries requiring friction reduction, wear protection, and improved component durability.
Zero Friction Coatings Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.0 billion
Market size value in 2026
USD 1.1 billion
Revenue forecast in 2033
USD 1.6 billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, formulation, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa;
Key companies profiled
AB Enzymes, Archroma, BASF SE, BioTex Malaysia, Dow, Ethox Chemicals, LLC, Evonik Industries AG, Fibro Chem, LLC, German Chemicals Ltd., Govi N.V., Huntsman International LLC, Kemira Oyj, Kiri Industries Ltd., LANXESS, OMNOVA Solutions Inc., Omya United Chemicals, Organic Dyes and Pigments, Resil Chemicals Pvt. Ltd., Solvay S.A., The Lubrizol Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Zero Friction Coatings Market Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global zero friction coatings market report on the basis of type, formulation, end-use, and region:
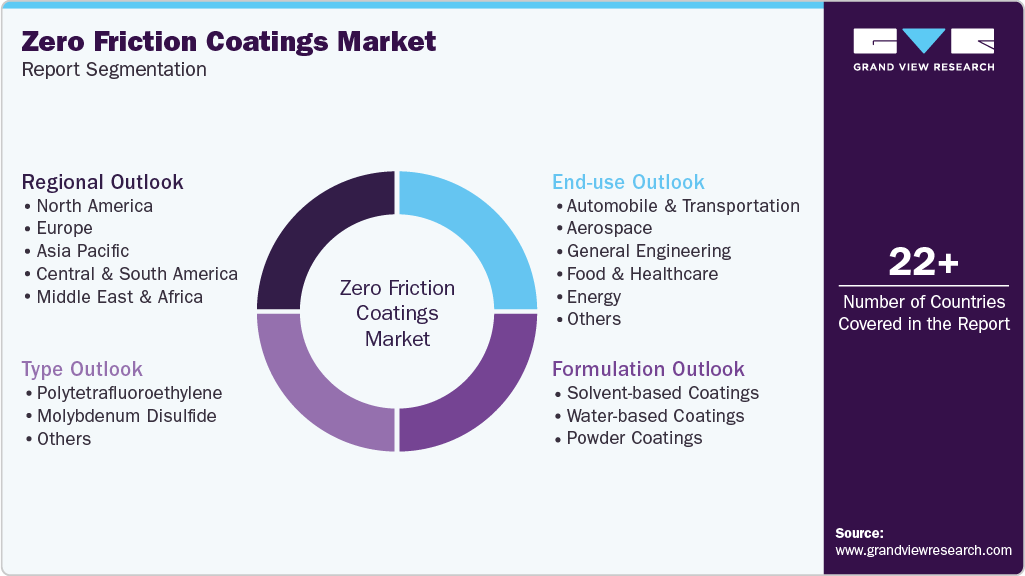 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polytetrafluoroethylene
-
Molybdenum Disulfide
-
Others
-
-
Formulation Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Solvent-based Coatings
-
Water-based Coatings
-
Powder Coatings
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automobile & Transportation
-
Aerospace
-
General Engineering
-
Food & Healthcare
-
Energy
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Russia
-
Netherlands
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Indonesia
-
Thailand
-
-
Central & South America
-
Brazil
-
Argentina
-
Colombia
-
-
Middle East & Africa
-
Turkey
-
South Africa
-
Morocco
-
-
Research Methodology
The zero friction coatings market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each zero friction coatings segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Polytetrafluoroethylene
Revenue is captured through the sale of PTFE based zero friction coatings used to provide low friction, non stick, and chemical resistant properties to industrial components. Manufacturers generate income through supply to automotive, aerospace, food processing, and engineering industries where PTFE coatings improve component performance, reduce wear, and enhance operational efficiency in demanding applications.
Molybdenum Disulfide
Revenue is generated through the supply of molybdenum disulfide based coatings designed for high load, high temperature, and dry lubrication applications. Coating manufacturers capture value through demand from aerospace, automotive, and industrial machinery sectors requiring enhanced wear resistance, reduced friction, and reliable performance under extreme operating conditions.
Other Products
Revenue is generated through the sale of alternative low friction coating materials, including diamond like carbon, graphite, ceramic based, and nanocomposite coatings. Manufacturers capture revenue by supplying specialized solutions for applications requiring improved durability, surface protection, and friction reduction across industrial, electronics, energy, and transportation sectors.
Segment - Formulation
Revenue Capture Definition
Solvent based Coatings
Revenue is captured through the sale of solvent based zero friction coating formulations used for applications requiring strong adhesion, fast drying properties, and high performance surface protection. Manufacturers generate income by supplying these coatings to industries such as automotive, aerospace, and heavy machinery where durability and resistance to harsh operating conditions are required.
Water based Coatings
Revenue is generated through the supply of water based low friction coatings developed for applications requiring reduced volatile organic compound emissions and improved environmental compatibility. Coating providers capture value through adoption in industries seeking sustainable coating solutions while maintaining friction reduction, wear resistance, and improved component efficiency.
Powder Coatings
Revenue is generated through sales of powder based friction reducing coatings applied to industrial components requiring durable and uniform surface protection. Manufacturers capture revenue from applications where high wear resistance, reduced maintenance requirements, and long lasting performance are important, particularly in machinery, transportation, and engineering sectors.
Segment - End Use
Revenue Capture Definition
Automobile & Transportation
Revenue is captured through the supply of zero friction coatings for automotive and transportation components such as engines, bearings, transmissions, and electric vehicle parts. Manufacturers generate income by supporting vehicle producers and component suppliers seeking improved efficiency, reduced wear, and longer service life of moving components.
Aerospace
Revenue is generated through sales of advanced low friction coatings used in aircraft engines, actuators, bearings, and other aerospace components. Coating manufacturers capture value by providing high performance solutions that operate under extreme temperatures, pressure conditions, and demanding aerospace reliability requirements.
General Engineering
Revenue is captured through the supply of friction reducing coatings for industrial machinery, equipment parts, gears, pumps, and mechanical systems. Manufacturers generate revenue from industries requiring improved operational efficiency, lower maintenance frequency, and enhanced durability of components exposed to continuous movement and heavy usage.
Food & Healthcare
Revenue is generated through coatings supplied for food processing equipment, medical devices, and healthcare components requiring smooth movement, corrosion resistance, and hygienic performance. Manufacturers capture value by providing specialized coatings that improve equipment reliability while meeting strict industry performance requirements.
Energy
Revenue is captured through sales of zero friction coatings used in renewable energy systems, power generation equipment, turbines, and other energy related machinery. Manufacturers generate income by helping operators reduce friction losses, improve equipment efficiency, and extend the operational life of critical components.
Other End Use
Revenue is generated through supply of zero friction coatings across additional applications including electronics, semiconductor equipment, marine systems, and specialized industrial sectors. Manufacturers capture revenue by providing customized coating solutions that improve surface performance, reduce friction, and enhance reliability in niche applications.
Estimation Model
Layer Name
Key Question
Content
Industrial Component Base Layer
What forms the demand base?
Identify the global installed base and production volumes of mechanical components, automotive parts, aerospace systems, industrial machinery, energy equipment, and precision components that require friction reduction solutions. This layer establishes the total addressable component base where zero friction coatings can be applied to improve efficiency, durability, and operational performance.
Coating Adoption Layer
Where are zero friction coatings consumed?
Estimate the adoption and application penetration of zero friction coatings across major industries including automotive and transportation, aerospace, general engineering, energy, food processing, healthcare, and electronics. Demand is assessed based on component requirements, operating conditions, performance expectations, and replacement of conventional lubrication or surface treatment methods.
Coating Consumption Intensity Layer
How much coating is used?
Analyze average coating consumption rates based on component surface area, coating thickness, application frequency, material type, and performance requirements. Consumption intensity varies depending on coating formulation, such as PTFE, molybdenum disulfide, DLC, and ceramic based coatings, along with end use conditions including temperature, pressure, and wear exposure.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of zero friction coating materials, formulations, application services, and customized coating solutions. Revenue is generated from recurring demand by automotive manufacturers, aerospace companies, industrial equipment producers, energy operators, and specialized engineering industries requiring improved efficiency, reduced maintenance, and extended component life.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Expanded regional analysis covering additional countries such as South Korea, Brazil, and Mexico, including their adoption trends, industrial application landscape, and demand potential for zero friction coatings across automotive, electronics, aerospace, and engineering sectors.
Provides deeper visibility into emerging regional markets and helps identify countries with increasing demand potential for advanced coating solutions beyond commonly assessed markets.
Competitive Benchmarking
Detailed comparison of zero friction coating manufacturers based on product portfolio, coating technologies, application expertise, end use penetration, innovation focus, and strategic positioning across industries such as automotive, aerospace, and industrial machinery.
Supports evaluation of competitive positioning, technology differentiation, and supplier capabilities to understand market dynamics and identify potential strategic partnerships.
Opportunity Assessment
Assessment of future opportunities arising from electric vehicle adoption, expansion of renewable energy equipment, semiconductor manufacturing growth, and increasing demand for high performance components requiring reduced friction and improved durability.
Helps identify high growth application areas and enables stakeholders to align investment strategies with emerging demand trends and evolving industrial requirements.
Frequently Asked Questions About This Report
The molybdenum disulfide segment accounted for the largest share of the zero friction coatings market, representing 54.6% of total revenue in 2025. This growth was driven by its superior lubricating properties and widespread industrial adoption across automotive, aerospace, and manufacturing applications globally.
The solvent-based coatings segment accounted for the largest revenue share of 41.4% in 2025. due to its excellent performance, durability, easy application, and strong demand across various industrial sectors requiring efficient friction reduction solutions.
The automobile & transportation segment accounted for the largest share of the zero friction coatings market, representing 37.3% of total revenue in 2025. This dominance reflects increasing vehicle production, demand for efficiency, and adoption of advanced coatings for improved performance and durability worldwide.
The China market accounted for the largest share of the zero friction coatings market in 2025, driven by its extensive manufacturing base, expanding automotive and industrial machinery sectors, strong demand for high-performance coatings, and increasing adoption of advanced friction-reducing technologies.
The global zero friction coatings market is expected to grow at a compound annual growth rate of 5.5% from 2026 to 2033 to reach USD 1.6 billion by 2033.
Asia Pacific accounted for 49.5% of the zero friction coatings market revenue in 2025, making it the largest regional market.. This is attributable to the presence of automotive manufacturing industries in the countries such as Japan, South Korea, and China.
The global zero friction coatings market size was USD 1.0 billion in 2025 and is estimated at USD 1.1 billion in 2026.
Some key players operating in the zero friction coatings market include Endura Coatings, DuPont, VITRACOAT , Poeton, Bechem, ASV Multichemie Private Limited, GMM Coatings Private Limited, and IKV Tribology Ltd.
Key factors that are driving the market growth include the growing demand for zero friction coatings owing to their lubricating and corrosion protection properties which increases the wear life of a component.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


