
- Home
- »
- Automotive & Transportation
- »
-
Automotive Aftermarket Size And Share Report, 2026-2033GVR Report cover

Automotive Aftermarket (2026 - 2033)
Industry Size, Share & Trends Analysis Report By Replacement Part (Tire, Battery, Brake Parts, Filters, Body Parts, Wheels, Turbochargers), By Distribution Channel, By Service Channel, By Certification, By Region, And Segment Forecasts
Market Size, 2025
$489.5BMarket Estimate, 2026
$509.8BMarket Forecast, 2033
$643.8BCAGR, 2026–2033
3.4%Automotive Aftermarket Industry Summary
The global automotive aftermarket industry size was estimated at USD 489.5 billion in 2025 and is projected to grow from USD 509.8 billion in 2026 to USD 643.8 billion by 2033, growing at a CAGR of 3.4% from 2026 to 2033. Asia Pacific dominated the automotive aftermarket industry with the largest revenue share of 29.4% in 2025. The global automotive aftermarket is witnessing significant digital transformation as connected vehicle technologies become more widely adopted.
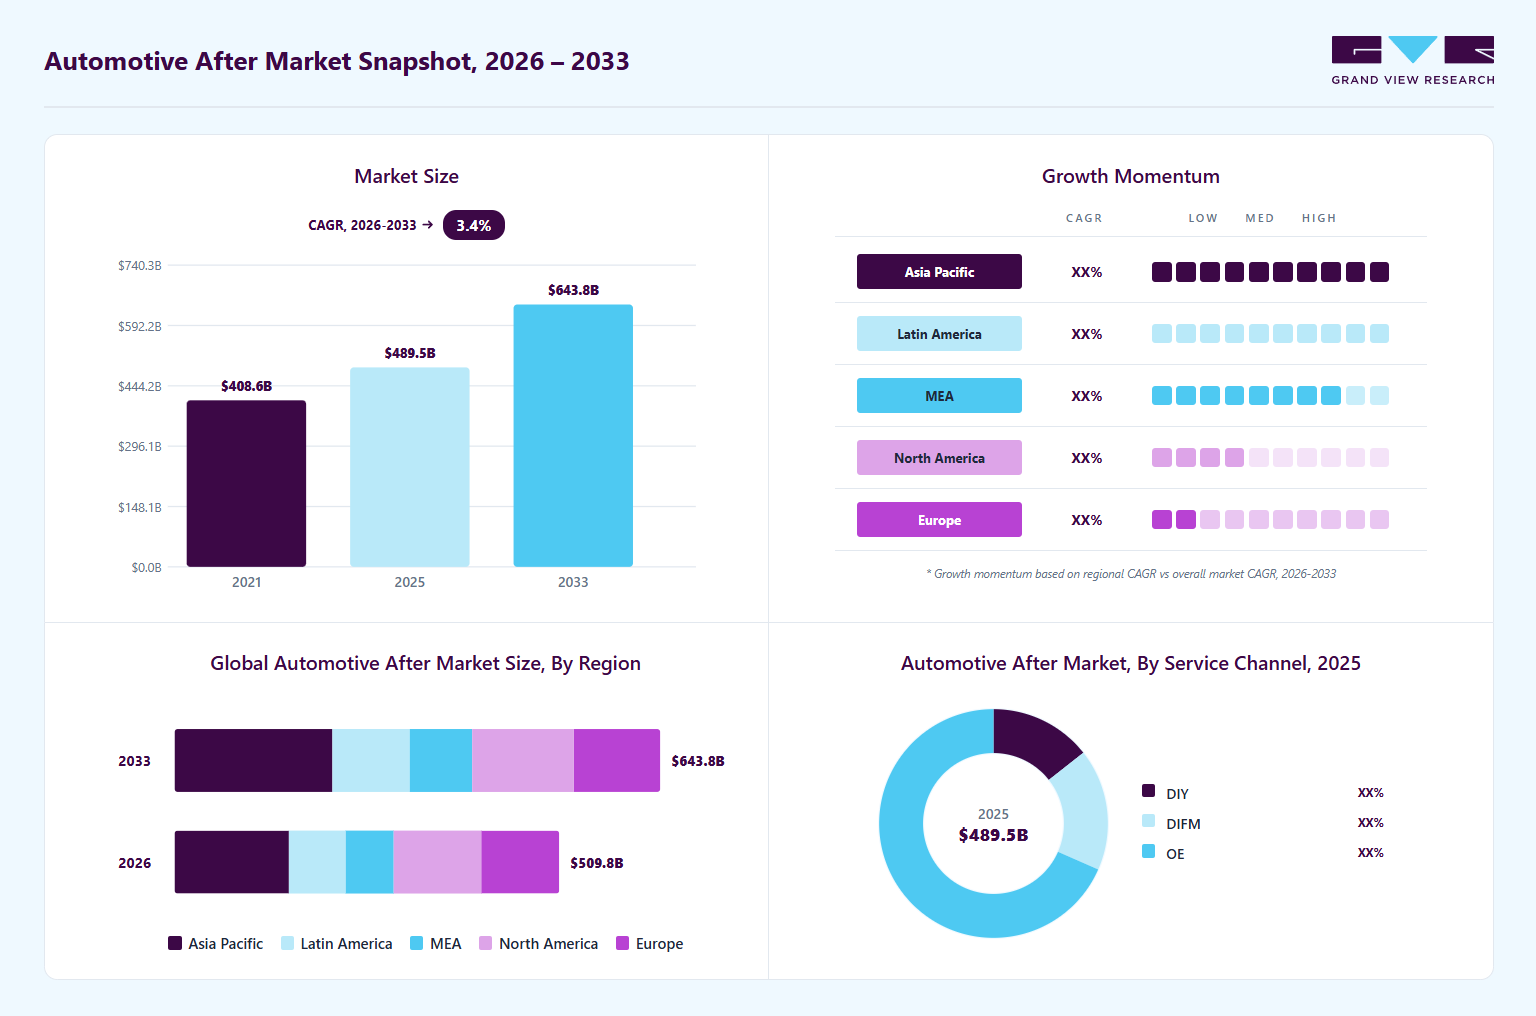 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By replacement part: Tire segment held a significant 23.2% revenue share in 2025.
- By distribution channel: Retailers segment held the largest revenue share in 2025.
- By service channel: OE (Delegating to OEMs) segment held the largest market share of 68.4% in 2025.
- By certification: Genuine segment held the largest market share of 51.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (29.4% revenue share, 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 489.5 Billion
- Estimated market size in 2026: USD 509.8 Billion
- Projected market size by 2033: USD 643.8 Billion
- CAGR (2026-2033): 3.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advanced telematics and vehicle diagnostics systems are enabling predictive maintenance and real-time monitoring of vehicle performance. These technologies help vehicle owners identify maintenance needs earlier, improving service efficiency and reducing downtime. Regional regulatory authorities, such as the Japanese Automobile Sports Muffler Association (JASMA) and the U.S. Environmental Protection Agency, monitor the established standards and environmental impacts associated with the functioning of automotive components. For instance, the noise emission levels associated with the modern-day automotive resonators and mufflers in automotive exhaust systems. Digitization of component delivery sales & services, along with the advent of an online portal distributing aftermarket components in synchrony with the global auto-part supplier groups, is expected to draw huge investments from key companies. For instance, the leading market component suppliers, such as US Auto Parts Network, Inc. and CarParts.com, are expected to drive the global demand for aftermarket during the forthcoming years.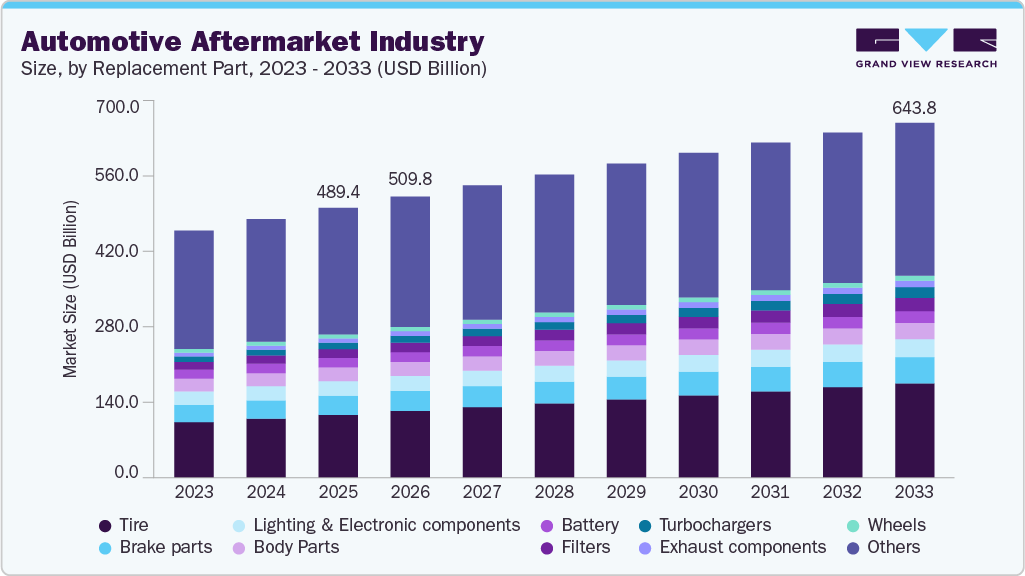 To learn more about this report, Download Free Sample Report
Due to the aforementioned trade gateways, online aftermarket business arcades have high potential in developing countries. Additionally, growing online sales of automotive components are estimated to deliver significant demand for the market. Companies are now shifting to the digital platform owing to the smoother experience for the customers. In January 2020, Continental AG announced its online portal, which will feature a comprehensive portfolio of its services and information about its products for the market.
The value chain of the market comprises two primary segments: automotive replacement part suppliers and service enablers. These prime industry segments are exchanging value through the automotive sectors at several intermittent stages. Access to an elaborative component assortment coupled with the simplicity of transactions, delivered through the digitalization of the global automotive component sales, is destined to resolve the obtainability issues, thereby driving the automobile aftermarket industry. The ensuing digitalization is anticipated to have a significant impact on the industry, as a growing number of people are inclined toward Internet-of-Things (IoT) and digitization trends.
Furthermore, the technological improvements in propulsion have created numerous opportunities in the market. However, issues related to high R&D expenditure are expected to hinder market growth during the forecast period. Automobile manufacturers face specific constraints when conducting their manufacturing processes. Production cost is one of these constraints. Some automotive replacement parts, such as aftermarket filters, however, offer the opportunity to choose a part that suits the conditions in which a vehicle operates.
Market Dynamics
The automotive aftermarket industry is supported by the increasing age of vehicles, which drives demand for replacement parts and repair services. Growing digitalization is improving customer access to products through online sales channels. The industry faces challenges from counterfeit components and fluctuating raw material costs. Rising vehicle complexity is increasing the need for specialized maintenance and diagnostic services. The transition toward electric vehicles is creating new opportunities while altering demand for traditional aftermarket products.
The expansion of e-commerce channels is reshaping the automotive aftermarket industry by providing consumers, repair shops, and fleet operators with convenient access to a broad range of replacement parts, accessories, and maintenance products. Online platforms allow customers to compare prices, evaluate product specifications, read reviews, and identify compatible parts for specific vehicle models. This improved accessibility reduces the time required to source components and enables customers to make more informed purchasing decisions.
The growing adoption of digital marketplaces is helping aftermarket manufacturers, distributors, and retailers reach a larger customer base beyond traditional brick-and-mortar networks. Enhanced inventory visibility, vehicle-specific search tools, and faster delivery options are improving the overall purchasing experience. As online channels continue to gain popularity, they are supporting higher sales volumes and expanding the availability of automotive aftermarket products across both developed and emerging markets.
The presence of counterfeit and low-quality automotive parts remains a major restraint for the automotive aftermarket industry. These products are often sold at significantly lower prices than genuine components, making them attractive to cost-sensitive consumers and independent repair shops. Authorized manufacturers and distributors face pricing pressure and revenue losses, particularly in regions where regulatory enforcement is limited.
Counterfeit parts frequently fail to meet required quality, safety, and performance standards, increasing the risk of vehicle malfunctions and higher maintenance costs. The use of such components can damage critical vehicle systems, leading to safety concerns and reduced customer satisfaction. The growing circulation of counterfeit products also weakens consumer trust in the aftermarket ecosystem, creating challenges for reputable suppliers seeking to maintain brand credibility and long-term customer loyalty.
The increasing adoption of electric vehicles is creating significant opportunities for the automotive aftermarket industry. As the global EV fleet expands, demand is growing for specialized aftermarket products and services, including battery diagnostics, battery replacement, thermal management components, charging equipment, and software-related maintenance solutions. This shift is encouraging aftermarket participants to diversify their product portfolios and develop capabilities tailored to electric mobility.
In addition, the growing need for EV-specific repair and maintenance services is creating new revenue streams for service providers and parts suppliers. Independent workshops and aftermarket companies are investing in technician training, diagnostic tools, and advanced equipment to support the evolving requirements of electric vehicles. As EV adoption continues to accelerate, the aftermarket industry is expected to benefit from emerging opportunities across both component sales and service offerings.
Market Concentration & Characteristics
The automotive aftermarket industry is moderately fragmented, with many manufacturers, distributors, retailers, and service providers operating across global markets. While several multinational companies maintain strong positions in specific product categories, no single participant dominates the overall industry. The market includes thousands of independent repair shops and regional parts suppliers. Product diversity across tires, batteries, filters, lubricants, brakes, and accessories supports competition among numerous vendors. E-commerce platforms have further lowered barriers to market participation for smaller suppliers. Regional vehicle parc differences also encourage the presence of local aftermarket businesses. These factors place the industry toward the fragmented side of the concentration spectrum.
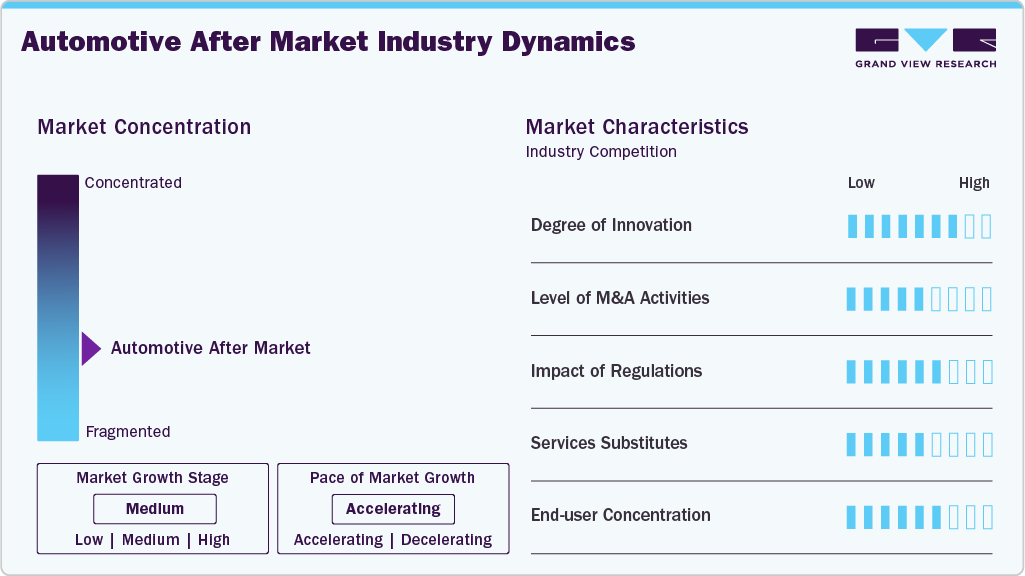 To learn more about this report, Download Free Sample Report
The industry is benefiting from the growing global vehicle population and increasing average vehicle age. Older vehicles require more frequent maintenance, repairs, and component replacements. Digital sales channels are improving product accessibility and expanding customer reach. Demand for premium replacement parts and vehicle upgrades continues to increase. Growth in electric and connected vehicles is creating new aftermarket opportunities. Fleet operators are also investing more in maintenance to maximize vehicle uptime. These factors are supporting an accelerating growth trajectory for the industry.
Analyst Perspective
The automotive aftermarket industry is expected to maintain steady growth, supported by the expanding global vehicle parc and increasing average vehicle age. Demand for replacement parts and maintenance services is likely to remain strong as consumers seek to extend vehicle lifespans and reduce ownership costs. Digital sales channels and e-commerce platforms are improving product accessibility and strengthening distribution efficiency. The transition toward electric and connected vehicles is creating new opportunities in batteries, electronics, diagnostics, and software-related services. While counterfeit parts and pricing pressures remain challenges, investments in technology, product innovation, and service capabilities are expected to support long-term market expansion.
Replacement Parts Insights
Based on replacement part, the tire segment led the market with the significant revenue share of 23.2% in 2025. The tire segment is anticipated to dominate the market in terms of size over the forecast period. It is expected to remain the dominant segment on account of the low replacement cycle of tires as compared to the other component counterparts. The aftermarket replacement part suppliers comprise various accessory suppliers, lubricant suppliers, tire suppliers, and other component replacement suppliers.
Furthermore, the industry value chain comprises service enablers such as repairing services providers and entertainment service providers. The automobile industry is observing an increase in the demand for hybrid electric cars that would eventually throttle the demand for exhaust parts and specific tools for these specialized cars. This curb can be attributed to the increased prices of petrol and automobiles with petrol engines. Growth in the disposable proceeds of patrons in developing nations, such as China and Brazil, is expected to have a positive impact on the growth rate of the market.
The growing demand for locomotives is projected to trigger the demand for automobile component sales. Rigid regulatory standards of car safety across the globe are anticipated to drive market economies. The modern age production technology, such as 3D printing of automotive parts, is being extensively deployed by major companies in the industry to optimize their production costs, with 3D printing enabling efficient fabrication performance and reduction of emission toxicity.
Distribution Channel Insights
Based on distribution channel, the retailers segment led the market with the largest revenue share of 54.0% in 2025. The retail segment is anticipated to continue dominating from 2026 to 2033. The wholesale & distribution segment is expected to witness relatively fast growth in terms of revenue from 2026 to 2033. Automotive aftermarket economies are important parts of the overall automotive manufacturing & maintenance scheme, as automotive components need to be replaced on time to maintain the overall performance of the vehicle.
The increasing influence of technological advancement is transforming the market towards digitization. The aftermarket is going online, and the marketplace is transforming. Parts and services are being sold online. Every player in the value chain, including Original Equipment Manufacturers (OEMs), Original Equipment Suppliers (OESs), wholesalers, insurers, and workshops, is responding to the growing online aftermarket trend. Advanced technology usage in auto parts fabrication, the surge in consumer and passenger automobile production, and the digitalization of automotive repair & maintenance services are the few factors expected to impel the market growth.
Service Channel Insights
Based on service channel, the OE (Delegating to OEMs) segment led the market with the largest revenue share of 68.4% in 2025. The OE segment is anticipated to dominate the aftermarket arena in terms of size by 2033. The DIY segment is expected to register relatively rapid growth in terms of revenue over the forecast period. DIY customers possess the technical knowledge and interest in maintaining, repairing, and upgrading their cars independently. DIFM customers purchase parts online but have them installed by a professional workshop.
The aftermarket service channel comprises members such as raw material suppliers, tier 1 distributors, automobile exhaust hubs/manufacturing units, and aftermarket units comprising jobbers and ultimately the repair shops. Repair centers are the important stakeholders in the service channel. The industry is witnessing a trend of strategic alliances and collaborations between collision repair centers and leading auto insurance companies to gain a competitive edge and capture a significant share of the market. For instance, Utica Mutual Insurance Company, State Farm Mutual Automobile Insurance Company, and Progressive Casualty Insurance Company have tie-ups with certified automotive repair shops across all the states in the U.S.
Certification Insights
Based on certification, the genuine parts segment led the market with the largest revenue share of 51.0% in 2025. The genuine parts segment is anticipated to continue dominating over the forecast period. The uncertified segment is expected to experience relatively rapid revenue growth from 2026 to 2033. Counterfeit parts are illegal, have not been tested or certified, and do not come with a warranty. Genuine parts are manufactured by car manufacturers or by OEMs, also known as subcontractors. Genuine replacement parts offer greater assurance of quality, are more diverse, easier to find, and come with a warranty. The downside of these parts is that they are expensive and must be purchased from dealers.
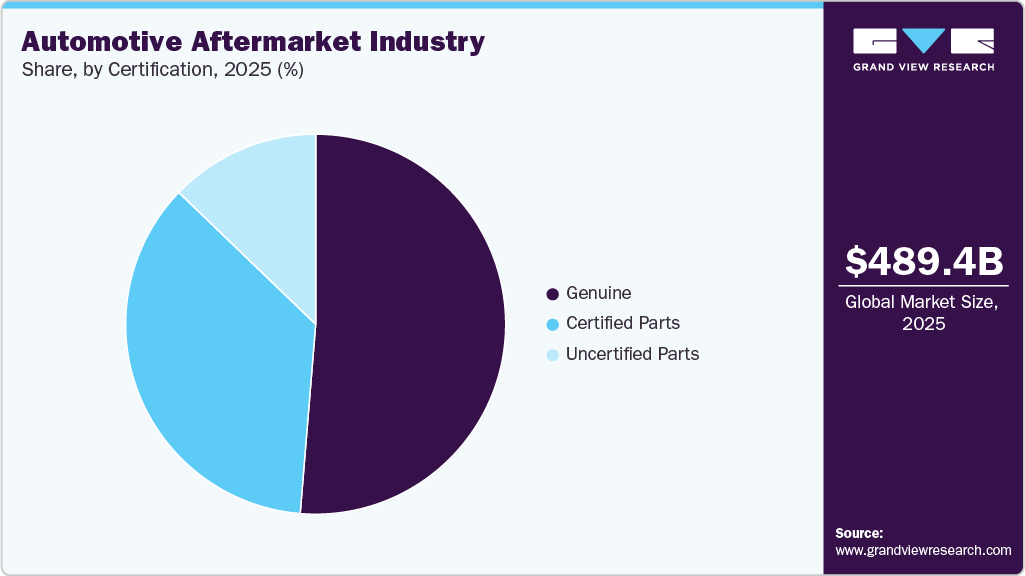 To learn more about this report, Download Free Sample Report
Certified automotive parts are tested and inspected by certified organizations. The Certified Automotive Parts Association (CAPA) is a non-profit organization that was incorporated in 1987. CAPA offers test programs to verify and guarantee the quality and suitability of automotive replacement parts. It was the brainchild of automotive insurance companies and was formed to ensure the quality of replacement parts used by collision repair shops. Certified parts are cost-effective alternatives to genuine, more expensive parts. At the same time, uncertified parts can be used as an alternative to the original automotive parts. Car makers do not approve uncertified parts. However, the low cost of uncertified parts creates significant growth opportunities for the segment in the coming years.
Regional Insights
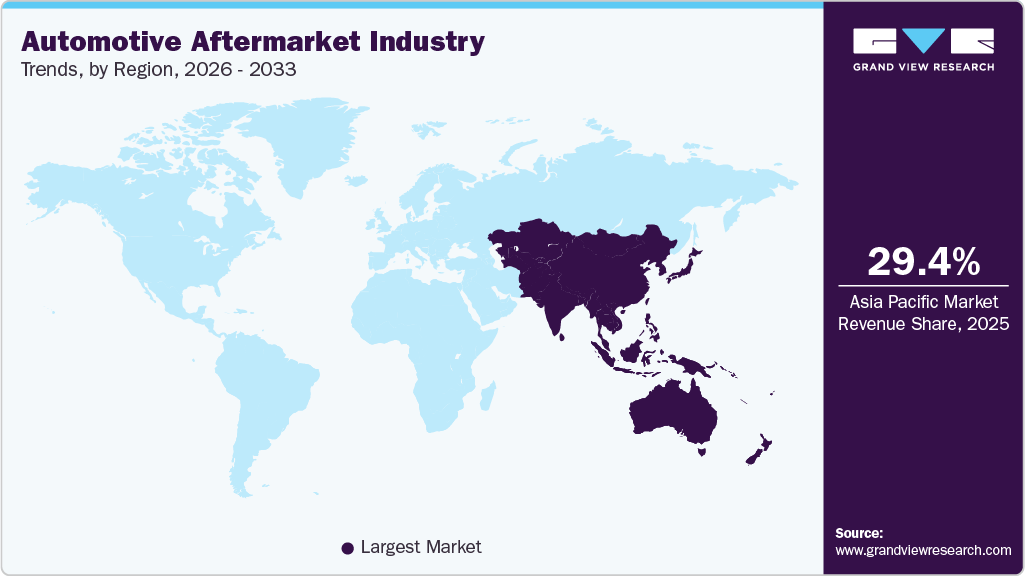
Asia Pacific dominated the automotive aftermarket industry with the largest revenue share of 29.4% in 2025. Asia Pacific is expected to continue leading from 2026 to 2033. The digitalization of automotive component delivery services is seen as a key driver of regional car sales, alongside the adoption of advanced technologies in auto parts production and rising output and sales of consumer and passenger vehicles.
 To learn more about this report, Download Free Sample Report
The automotive aftermarket industry in the China held the largest share in the Asia Pacific region in 2025. E-commerce has been booming in China, and the automotive aftermarket is no exception. Online platforms and marketplaces have gained popularity, offering a wide range of automotive products and services. Consumers in China increasingly turn to online channels for convenience, competitive pricing, and access to a vast selection of aftermarket parts and accessories.
North America Automotive Aftermarket Industry Trends
The North America automotive aftermarket is anticipated to grow at a CAGR of 2.2% from 2026 to 2033. Additionally, there is a growing trend of vehicle customization in the region, where owners modify their vehicles to reflect their unique tastes and preferences. This includes aftermarket upgrades such as performance parts, aesthetic enhancements, audio systems, lighting modifications, and more.
The automotive aftermarket industry in the U.S. held the largest share in the North America region in 2025. The U.S. automotive aftermarket has seen a significant expansion of e-commerce channels. Online retailers and marketplaces have gained popularity due to the convenience of purchasing parts and accessories online. E-commerce offers a wide range of products, competitive pricing, and simplified shopping experiences.
Europe Automotive Aftermarket Industry Trends
The Europe automotive aftermarket is expected to reach USD 115.75 billion by 2033. Europe is at the forefront of automotive technology, which has significantly influenced the aftermarket sector. The integration of advanced technologies in vehicles, such as ADAS, electric and hybrid systems, and connectivity features, has created opportunities for aftermarket solutions and retrofits to meet the changing needs of European vehicle owners.
The automotive aftermarket in the UK is placing an increased focus on skills development and training programs. With the advancement of vehicle technologies, there is a growing need for qualified technicians and professionals who can diagnose, repair, and maintain modern vehicles. Training initiatives are being introduced to upskill the workforce and ensure they remain updated with the latest advancements. These trends reflect the unique factors shaping the growth of the automotive aftermarket in the UK.
Key Automotive Aftermarket Company Insights
Key automotive aftermarket companies include 3M Company, Continental AG, Denso Corporation, Robert Bosch GmbH, and ZF Friedrichshafen AG.
-
3M India Limited, a subsidiary of the U.S.-based 3M Company, leverages science and innovation to address practical challenges and enhance daily life. The company operates across the Safety & Industrial, Transportation & Electronics, Healthcare, and Consumer markets in India and internationally. Its product portfolio includes adhesives, abrasives, medical supplies, safety equipment, and consumer goods, distributed through direct sales, trade channels, and e-commerce. With manufacturing facilities and an R&D center in India, 3M India is committed to sustainable development, operational excellence, and long-term value creation for stakeholders.
-
Continental AG is a German multinational automotive technology and tire company founded in 1871 and headquartered in Hanover, Germany. It is one of the world’s leading tire manufacturers and automotive suppliers, offering sustainable, safe, and convenient mobility solutions to automotive manufacturers, industrial customers, and end-users globally. Continental’s product portfolio includes tires, brake systems, vehicle electronics, safety systems, and technical components that support modern mobility and transport. With a long history of innovation and a presence in over 50 countries, the company focuses on technological leadership, quality, and sustainable growth in the automotive sector.
Key Automotive Aftermarket Companies
The following key companies have been profiled for this study on the automotive aftermarket.
-
3M Company
-
Continental AG
-
Cooper Tire & Rubber Company
-
PHINIA Inc.
-
Denso Corporation
-
DRiV Incorporated (Tenneco)
-
HELLA KGaA Hueck & Co.
-
Robert Bosch GmbH
-
Valeo Group
-
ZF Friedrichshafen AG
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: 3M Company, Valeo Group, Continental AG
- Focus on product portfolio expansion, global distribution network strengthening, technology innovation, and strategic acquisitions to maintain market share and profitability.
- Strong brand recognition, extensive distribution networks, broad product portfolios, advanced R&D capabilities, and long-standing customer relationships.
- High operating costs, complex supply chains, slower decision-making processes, and dependence on established product lines.
Emerging Players: Denso Corporation, PHINIA Inc.
- Focus on niche product offerings, competitive pricing, regional expansion, digital sales channels, and partnerships with distributors and service providers to gain market presence and scale operations.
- Greater flexibility, competitive pricing, niche product specialization, faster innovation cycles, and strong regional market focus.
- Limited brand recognition, smaller distribution networks, lower financial resources, and restricted geographic presence.
Recent Developments
-
In August 2024, Delphi, a brand of PHINIA Inc., significantly expanded its product offerings by launching over 2,000 new parts in the first half of 2024, covering a total of 632 million vehicles globally. This includes enhancements in key categories such as Braking, Steering and Suspension, and Sensors, with a notable 35.0% increase in first-to-market launches compared to the previous year. The company also introduced advanced diagnostic software and expanded its coverage of electric vehicle models, reinforcing its commitment to keeping vehicles on the road longer and more efficiently.
-
In June 2023, Continental released the UltraContact NXT series tire, which is distinguished by its high share of sustainable material usage. The tire comprises up to 65% of recycled, renewable, and ISCC PLUS mass balance-certified materials. The tires will be made available in 19 sizes.
-
In April 2023, ZF Aftermarket announced an expansion of its range of offerings for the Indian passenger car market with the introduction of three newly manufactured TRW products in India, comprising shock absorbers, brake pads, and brake discs. The company emphasizes that a crucial aspect of the independent aftermarket is the repair of brakes for passenger vehicles.
Automotive Aftermarket Industry Report Scope
Report Attribute
Details
Market size in 2025
USD 489.5 billion
Estimated Market size in 2026
USD 509.8 billion
Projected Market size by 2033
USD 643.8 billion
Growth rate
CAGR of 3.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Replacement parts, distribution channel, service channel, certification, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; Australia; South Korea; Brazil; KSA; UAE; South Africa
Key companies profiled
3M Company, Continental AG, Cooper Tire & Rubber Company, PHINIA Inc., Denso Corporation, DRiV Incorporated (Tenneco), HELLA KGaA Hueck & Co., Robert Bosch GmbH, Valeo Group, ZF Friedrichshafen AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Aftermarket Industry Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the industry trends in each of the segments from 2021 to 2033. For this study, Grand View Research has segmented the automotive aftermarket industry report based on replacement part, distribution channel, service channel, certification, and region:
-
Replacement Parts Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tire
-
Battery
-
Brake Parts
-
Filters
-
Body parts
-
Lighting & Electronic Components
-
Wheels
-
Exhaust components
-
Turbochargers
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retailers
-
OEMs
-
Repair Shops
-
-
Wholesalers & Distributors
-
-
Service Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
DIY (Do it Yourself)
-
DIFM (Do it for Me)
-
OE (Delegating to OEMs)
-
-
Certification Outlook (Revenue, USD Billion, 2021 - 2033)
-
Genuine Parts
-
Certified Parts
-
Uncertified Parts
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The automotive aftermarket industry figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive aftermarket segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Replacement Parts
Revenue capture definition
Tire
Revenue is generated from the replacement of worn, damaged, or performance-upgrade tires for passenger and commercial vehicles through retail outlets, service centers, and online channels.
Battery
Revenue is captured through the sale and replacement of automotive batteries that have reached the end of their operational life or require upgrades for improved vehicle performance.
Brake Parts
Revenue comes from the replacement of brake pads, brake discs, drums, calipers, and related braking components due to wear, safety requirements, and maintenance schedules.
Filters
Revenue is derived from the periodic replacement of air filters, oil filters, fuel filters, and cabin filters required to maintain vehicle efficiency and performance.
Body Parts
Revenue is generated from the replacement of damaged exterior and structural components, including bumpers, fenders, doors, hoods, mirrors, and panels following accidents or wear.
Lighting & Electronic Components
Revenue is captured through the replacement and upgrade of lighting systems, sensors, control modules, infotainment components, switches, and other electronic vehicle parts.
Wheels
Revenue comes from the replacement and upgrade of vehicle wheels due to damage, wear, aesthetic preferences, or performance enhancement requirements.
Exhaust Components
Revenue is generated from the replacement of mufflers, catalytic converters, pipes, and other exhaust system components that deteriorate over time or fail regulatory inspections.
Turbochargers
Revenue is derived from the replacement and servicing of turbochargers that experience performance degradation, mechanical failure, or require upgrades for improved engine efficiency.
Others
Revenue is captured from the replacement, repair, and upgrade of automotive components not covered under the major categories, including accessories, gearboxes, suspension parts, steering components, and other aftermarket products.
Segment - Distribution Channel
Revenue capture definition
Retailers
Revenue is captured from direct sales of aftermarket parts, accessories, and maintenance products to vehicle owners, repair shops, and fleet operators through physical stores and online platforms.
Wholesalers & Distributors
Revenue is captured from the bulk distribution and sale of aftermarket parts and components to retailers, service centers, workshops, and other channel partners within the automotive supply chain.
Segment - Service Channel
Revenue capture definition
DIY (Do It Yourself)
Revenue is captured through direct purchases of aftermarket parts, accessories, and repair tools by vehicle owners for self-maintenance and repairs.
DIFM (Do It For Me)
Revenue is derived from labor charges and component sales associated with maintenance, repair, and replacement services performed by independent workshops and service centers.
OE (Delegating to OEMs)
Revenue is generated from manufacturer-approved replacement parts and servicing solutions delivered through authorized dealership networks.
Segment - Certification
Revenue capture definition
Genuine Parts
Revenue is captured from the sale of OEM-manufactured or OEM-approved replacement components distributed through authorized channels.
Certified Parts
Revenue is generated from replacement components produced by third-party manufacturers that meet recognized quality, safety, and performance standards.
Uncertified Parts
Revenue is derived from the sale of aftermarket components that do not carry OEM approval or recognized third-party quality certifications.
Estimation Model
Layer Name
Key Question
Description
Vehicle Parc Layer
Which vehicles create demand for aftermarket products and services?
Identify the total population of passenger cars, light commercial vehicles, heavy commercial vehicles, and other vehicles in operation. This layer establishes the addressable vehicle base requiring maintenance, repair, and replacement components throughout the vehicle lifecycle.
Serviceable Vehicle Layer
Which vehicles actively consume aftermarket products?
Filter the vehicle parc based on vehicle age, mileage, usage intensity, and maintenance frequency. Vehicles beyond the warranty period and those requiring regular servicing form the primary demand base for aftermarket products and services.
Replacement Demand Layer
What aftermarket components and services are purchased?
Estimate demand for replacement parts such as tires, batteries, brake parts, filters, body parts, lighting & electronic components, wheels, exhaust components, turbochargers, and other aftermarket products. Replacement cycles, failure rates, and maintenance schedules determine demand volumes.
Revenue Capture Layer
How is revenue generated across the aftermarket ecosystem?
Calculate revenue generated through the sale and installation of aftermarket parts across DIY, DIFM, and OE channels, including retailers, wholesalers, distributors, service centers, and authorized dealerships. This layer converts replacement demand into total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Entry & Expansion Assessment
Regional aftermarket demand sizing and growth forecasting
Vehicle parc and replacement cycle analysis
Distribution channel and service network assessment
Competitive landscape and regulatory evaluation
Identified high-growth regional opportunities
Supported market entry and expansion strategies
Highlighted key competitive and regulatory risks
Enabled data-driven investment and resource allocation decisions
Partner & Distribution Study
Wholesaler, distributor, retailer, and workshop network analysis
Channel performance and market coverage benchmarking
Margin structure and profitability assessment
Route-to-market effectiveness evaluation
Optimized distribution and channel strategies
Identified gaps in market coverage and partner networks
Improved channel partner selection and engagement
Enhanced market penetration and revenue growth planning
Product Positioning & Competitive Intelligence
Aftermarket product portfolio benchmarking
Pricing and value proposition assessment
Brand perception and customer preference analysis
Competitor strategy and market share evaluation
Improved product differentiation and positioning
Supported pricing optimization initiatives
Identified unmet customer requirements
Strengthened competitive advantage and market presence.
Frequently Asked Questions About This Report
The global automotive aftermarket industry size was estimated at USD 489.5 billion in 2025 and is expected to reach USD 509.8 billion in 2026.
The global automotive aftermarket industry is expected to grow at a compound annual growth rate of 3.4% from 2026 to 2033 to reach USD 643.8 billion by 2033.
Asia Pacific is the fastest-growing region over the forecast period.
Some key players operating in the automotive aftermarket industry include 3M Company, Continental AG, Cooper Tire & Rubber Company, PHINIA Inc., Denso Corporation, DRiV Incorporated (Tenneco), HELLA KGaA Hueck & Co., Robert Bosch GmbH, Valeo Group, ZF Friedrichshafen AG
The retailers segment dominated the automotive aftermarket industry, accounting for around 54.0% in 2025.
Key factors driving the automotive aftermarket industry growth include the expanding vehicle fleet, increasing vehicle age, and rising demand for maintenance and replacement parts.
The tire segment captured a prominent 23.2% revenue share in 2025. .
The OE (Delegating to OEMs) segment dominated the automotive aftermarket industry in terms of market size, with a share of 68.4% in 2025, while DIY (Do It Yourself) is the fastest-growing segment.
Asia Pacific dominated the automotive aftermarket industry with a share of 29.4% in 2025. This is attributable to strong manufacturing activity, increasing automation adoption, and growing investments in AI-driven technologies.
Automotive After Market By Country
- U.S. Automotive Aftermarket
- Canada Automotive Aftermarket
- Mexico - North America Automotive Aftermarket
- Germany Automotive Aftermarket
- France Automotive Aftermarket
- Japan Automotive Aftermarket
- China Automotive Aftermarket
- India Automotive Aftermarket
- Brazil Automotive Aftermarket
- U.K. Automotive Aftermarket
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


