
- Home
- »
- Advanced Interior Materials
- »
-
Airflow And Zone Controls Equipment Market Report, 2033GVR Report cover

Airflow And Zone Controls Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Dampers, Variable Air Volume), By Operation (Manual, Automatic), By Application, By Deployment, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$5.6BMarket Estimate, 2026
$5.8BMarket Forecast, 2033
$8.7BCAGR, 2026–2033
6.0%Airflow And Zone Controls Equipment Market Summary
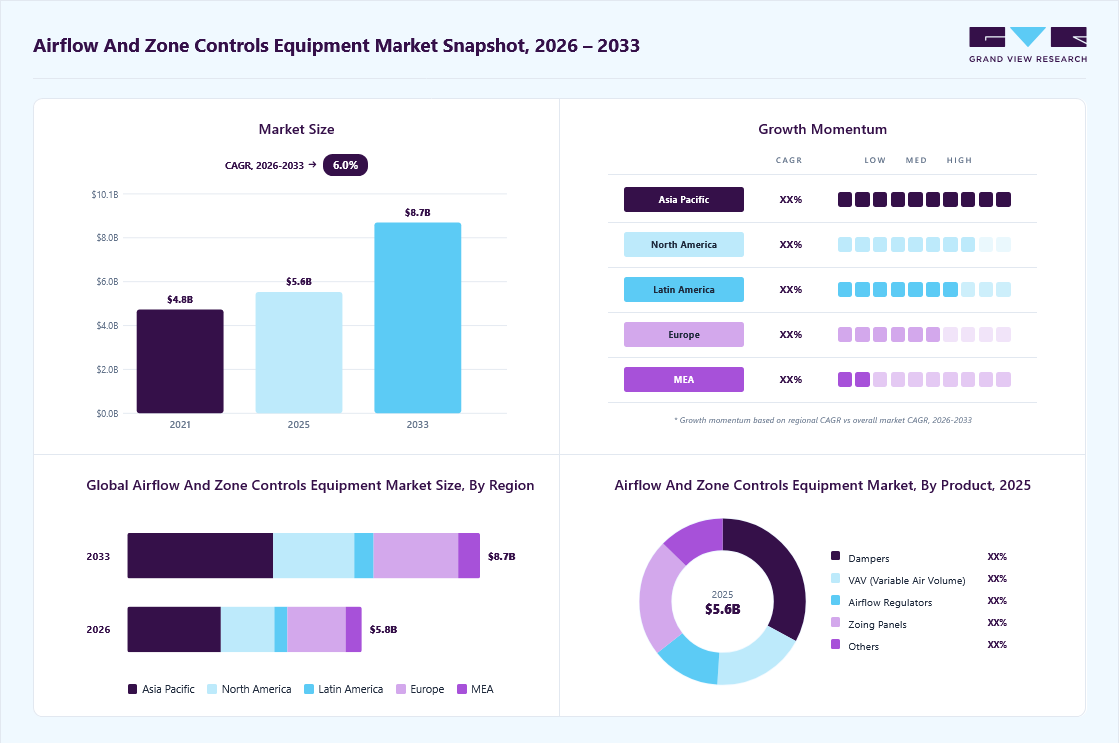
The airflow and zone controls equipment market size was valued at USD 5.6 billion in 2025 and is projected to grow from USD 5.8 billion in 2026 to USD 8.7 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. Asia Pacific dominated the airflow and zone controls equipment market with the largest revenue share of 39.5% in 2025. The industry is evolving with a strong shift toward smart, automated systems. Increased adoption of IoT-based devices allows real-time monitoring and precise control, improving energy efficiency and user comfort.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Dampers segment held the largest market share of 32.8% in 2025.
- By application: Commercial segment held the largest market share of 48.4% in 2025.
- By operation: Manual segment held the largest market share of 66.8% in 2025.
- By deployment: New installation segment held the largest market share of 67.4% in 2025.
Regional Highlights
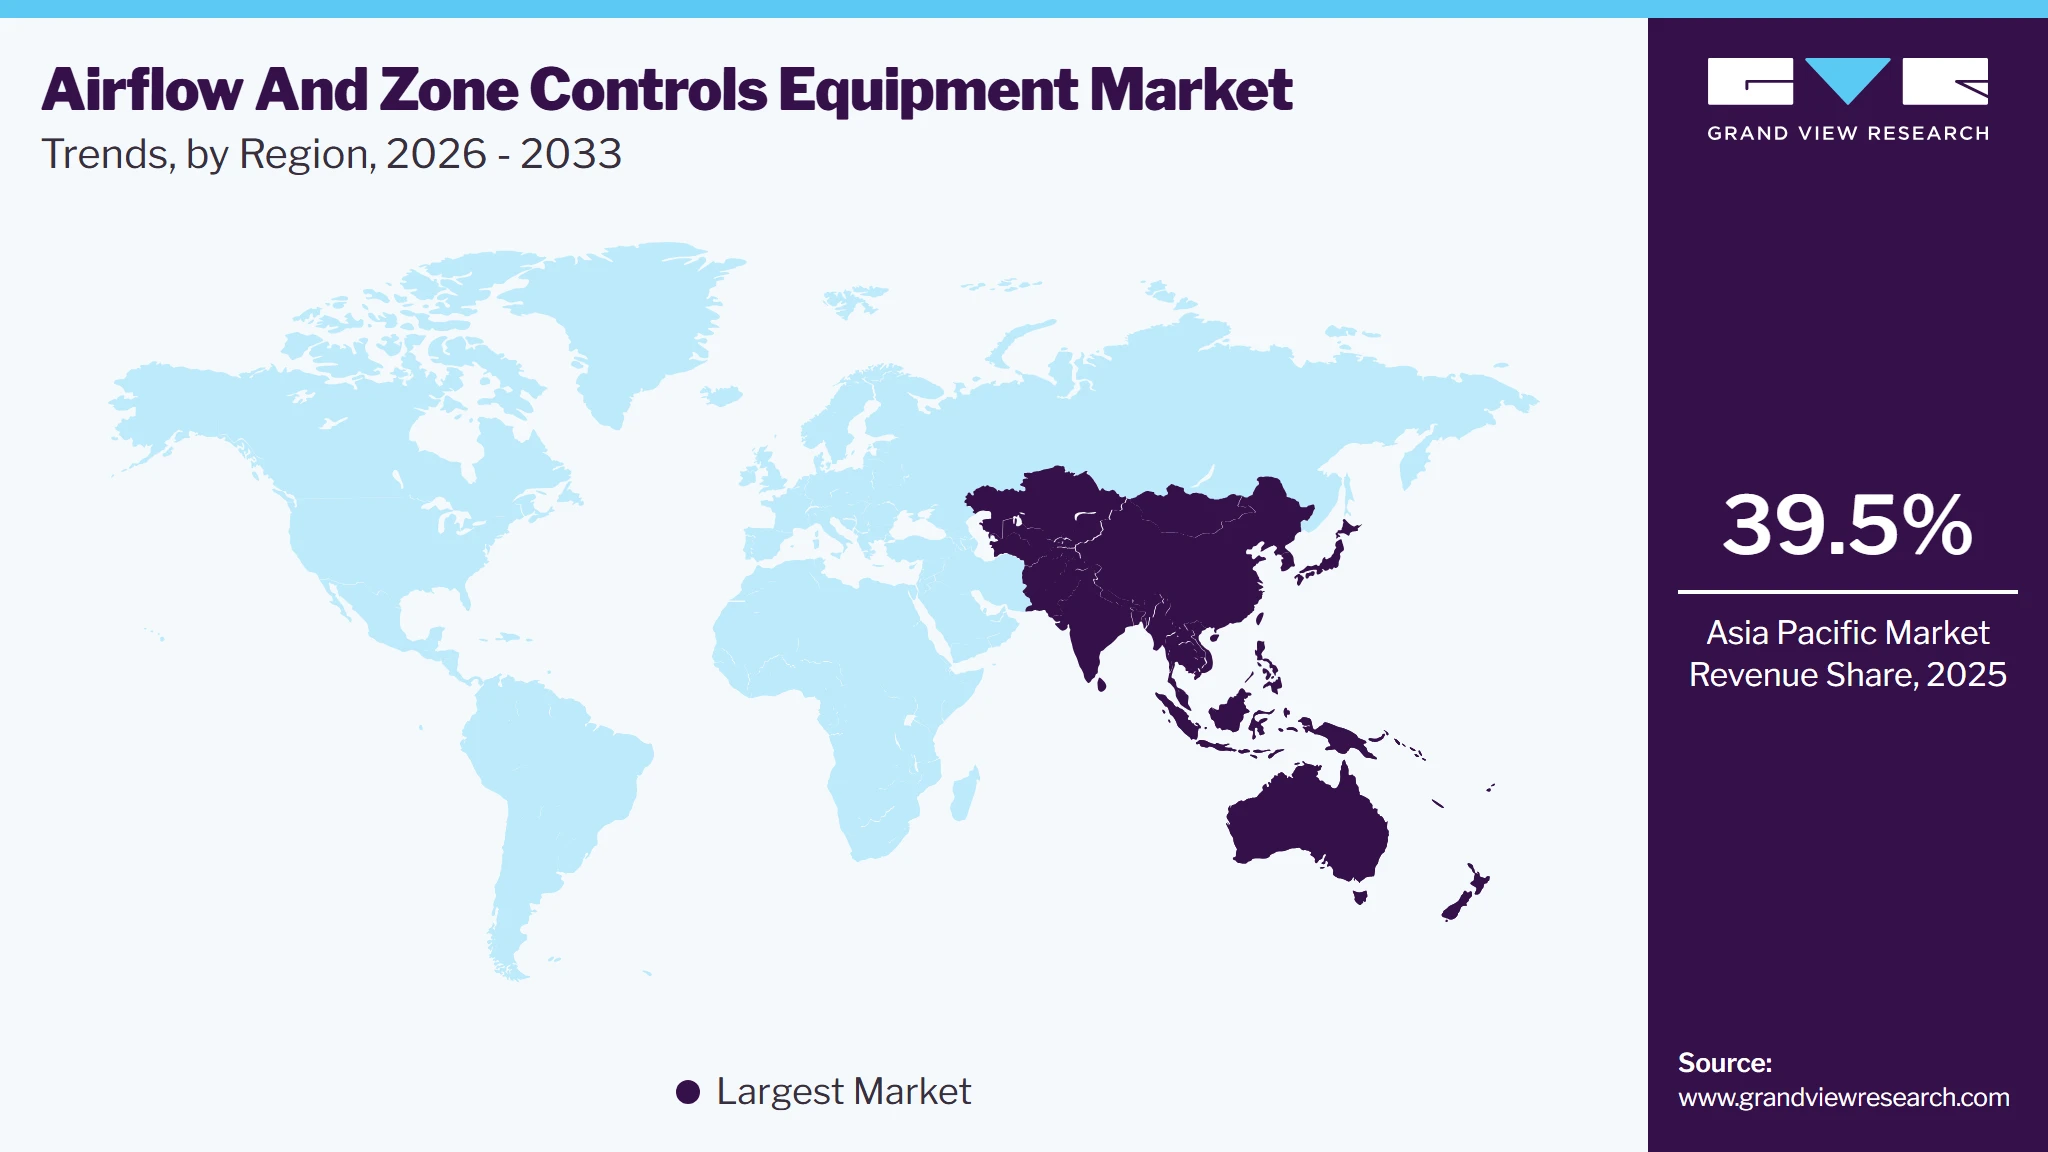
- Largest regional market: Asia Pacific (39.5% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 5.6 Billion
- Estimated market size in 2026: USD 5.8 Billion
- Projected market size by 2033: USD 8.7 Billion
- CAGR (2026-2033): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the airflow and zone controls equipment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Furthermore, the demand for energy-efficient solutions is driven by stricter building codes and sustainability goals, particularly in commercial and industrial sectors.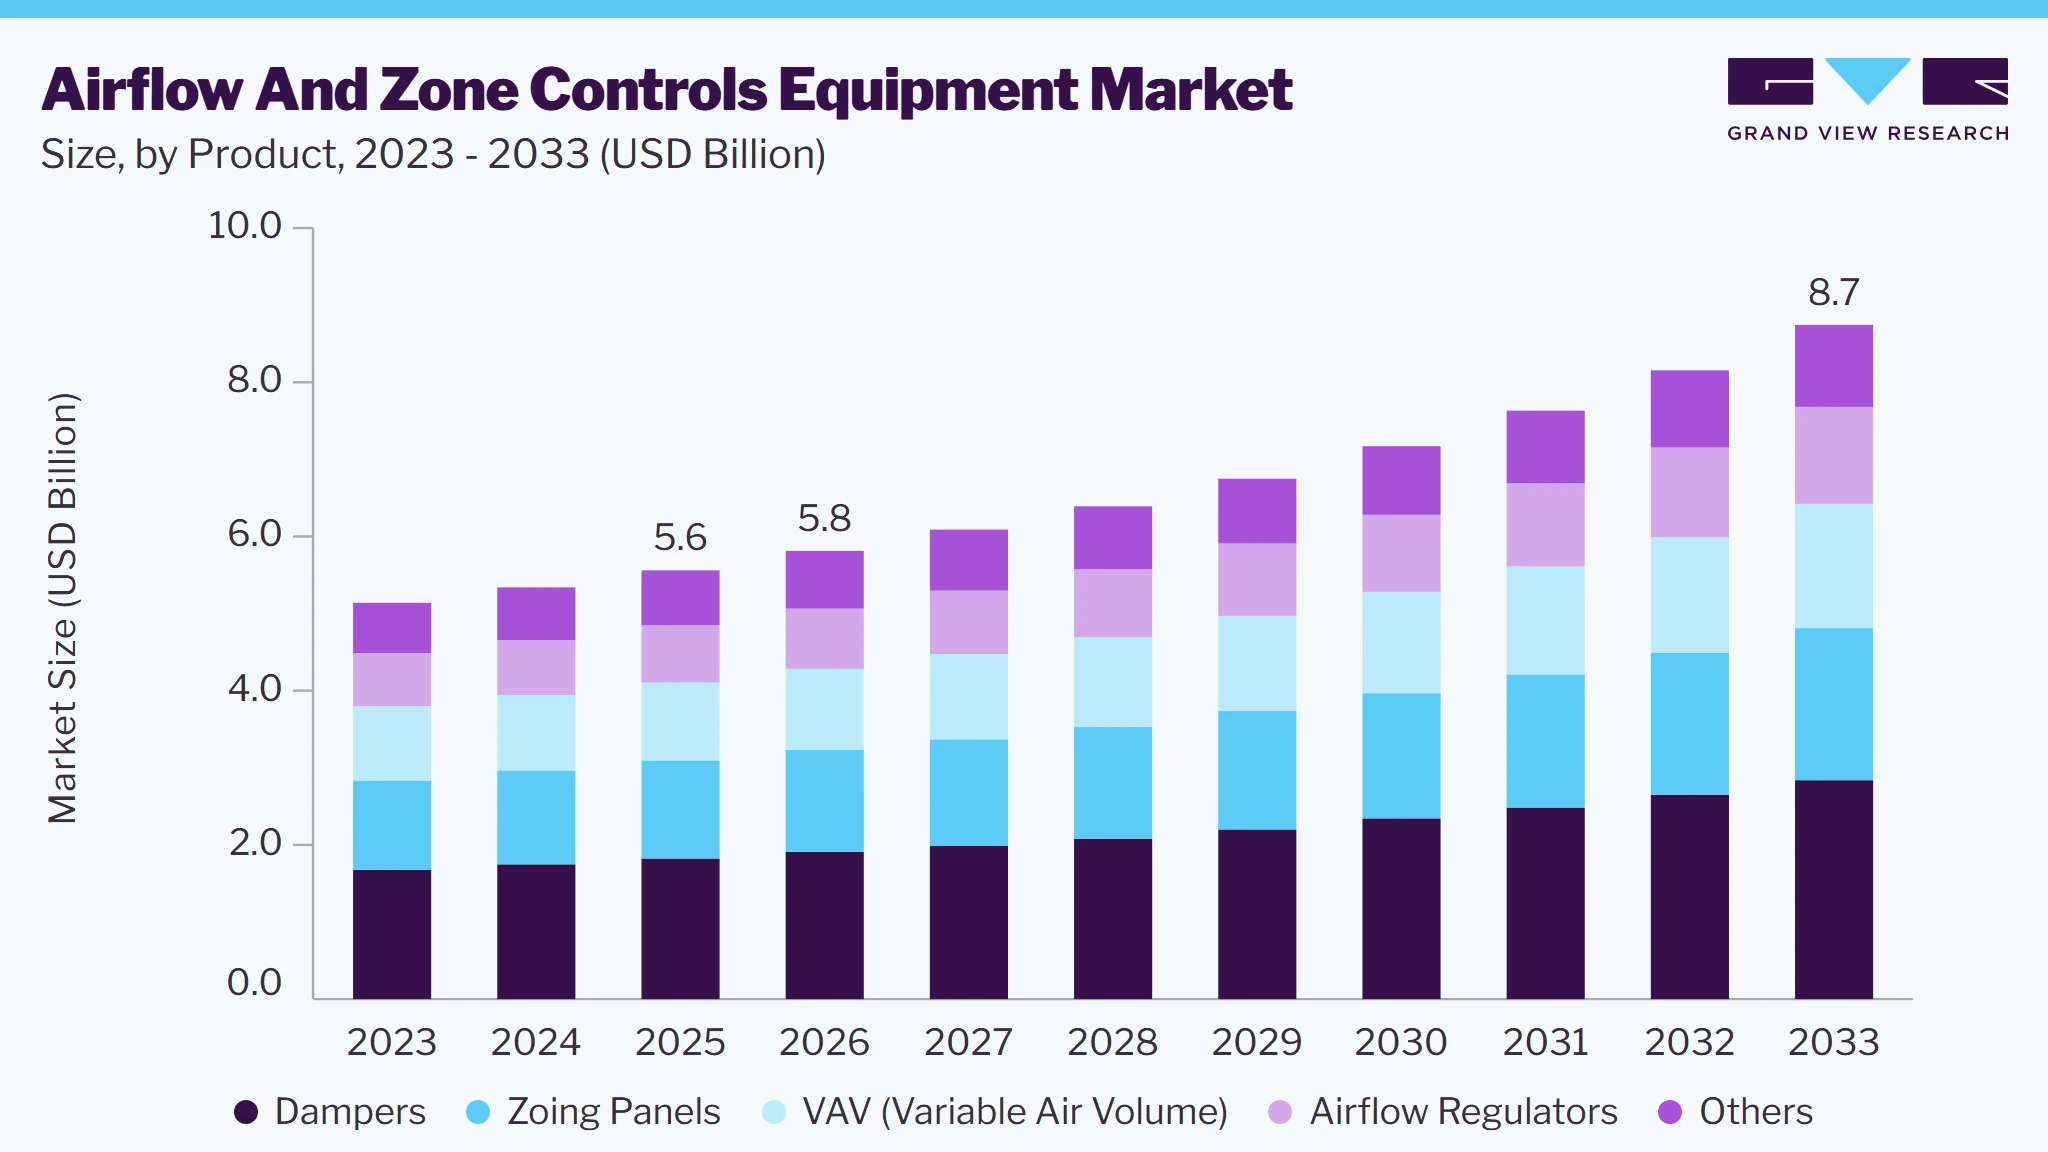 To learn more about this report, Download Free Sample Report
There is also a rise in the use of advanced zoning systems that allow better regulation of airflow in multi-zone environments, catering to the varying needs of different areas within a building. Additionally, the integration of airflow and zone control technologies with HVAC systems is gaining traction, ensuring seamless operation and optimized performance. Moreover, increased awareness of indoor air quality (IAQ) is another key factor, prompting the use of advanced filtration and ventilation systems. Lastly, the growing focus on retrofit and upgrade projects, especially in existing buildings aiming for energy savings and improved performance, is fueling market growth.
Market Dynamics
The airflow and zone controls equipment market is predominantly driven by the global imperative for energy efficiency, the accelerating adoption of intelligent building automation systems, and increasingly stringent regulatory standards for indoor environmental quality. The integration of IoT-enabled sensing, artificial intelligence, and predictive analytics has further catalyzed demand by enabling real-time adaptive control, remote diagnostics, and optimized thermal comfort across residential, commercial, and institutional applications. However, market growth is moderated by substantial capital expenditures, retrofitting complexities in aging infrastructure, and persistent interoperability challenges arising from fragmented communication protocols across diverse manufacturer platforms.
The airflow and zone controls equipment market is predominantly driven by the proliferation of stringent building energy codes and indoor air quality regulations, which mandate reduced HVAC energy consumption and prescribed ventilation rates across residential, commercial, and institutional sectors. Compliance frameworks including LEED, BREEAM, and WELL certifications further compel building owners to deploy advanced zoning solutions capable of precise temperature modulation, demand-based ventilation, and dynamic airflow allocation, positioning these systems as indispensable for achieving regulatory adherence and sustainability targets.
The expansion of commercial real estate and residential construction activities, particularly in developing economies, continues to generate substantial demand for airflow and zone controls equipment, as new facilities must integrate modern HVAC infrastructure from the design phase. Additionally, post-pandemic health awareness has intensified focus on indoor environmental quality, accelerating adoption of zone control systems equipped with IoT-enabled sensors and AI-driven analytics that facilitate real-time monitoring, predictive maintenance, and adaptive control, thereby enhancing occupant well-being and operational efficiency.
High installation and capital costs remain a significant restraint for the airflow and zone controls equipment market, as these systems require considerable upfront investment for sensors, dampers, controllers, actuators, ductwork modifications, and integration with existing HVAC infrastructure. These financial barriers are particularly challenging for small-scale residential projects and budget-constrained institutional facilities, often delaying adoption or encouraging consideration of lower-cost manual alternatives that compromise energy efficiency and comfort outcomes.
Interoperability challenges arising from fragmented communication protocols across diverse manufacturer platforms present a persistent barrier to market growth, complicating system integration and limiting deployment flexibility in multi-vendor environments. Furthermore, the inherent technical complexity of zoning systems necessitates specialized expertise for proper design, installation, and commissioning, creating a skills gap that constrains market penetration, particularly in regions with limited access to trained HVAC professionals and inadequate technical support infrastructure.
The integration of digital monitoring and automation technologies presents a significant opportunity for the airflow and zone controls equipment market, with advanced sensors, real-time performance analytics, predictive maintenance algorithms, and AI-driven adaptive controls enabling operators to optimize thermal comfort, minimize energy waste, and reduce operational expenditures. As building owners increasingly adopt smart building frameworks and Industrial Internet of Things (IIoT) solutions, demand for digitally enabled zone control systems is expected to accelerate, creating avenues for value-added service offerings and recurring revenue streams.
The global transition toward decentralized energy generation, microgrid architectures, and net-zero energy buildings creates substantial opportunities for manufacturers to develop specialized zoning solutions tailored to variable thermal loads and renewable energy integration. The emergence of passive house standards and demand-response programs further amplifies this potential, as these high-performance structures require precise, energy-optimized zoning systems to achieve ambitious efficiency targets while maintaining occupant comfort and air quality, positioning zone controls as integral components of sustainable building design.
Analyst Perspective
The airflow and zone controls equipment market is witnessing steady growth as building owners and facility managers increasingly prioritize energy efficiency, indoor air quality, and occupant comfort. The adoption of smart HVAC systems, connected building management platforms, and demand-controlled ventilation is driving the integration of advanced airflow and zoning solutions across residential, commercial, and industrial buildings. In addition, stricter energy efficiency regulations and green building standards are encouraging the replacement of conventional HVAC control systems with intelligent, automated equipment that optimizes airflow while reducing energy consumption. As investments in smart buildings and HVAC modernization continue to accelerate, manufacturers offering integrated, IoT-enabled, and energy-efficient airflow and zone control solutions are expected to benefit from sustained long-term demand.
Market Concentration & Characteristics
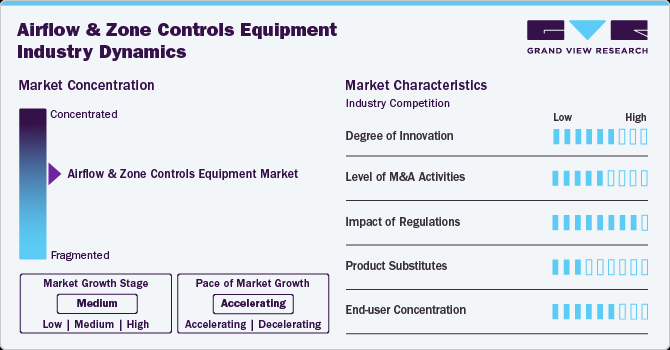
The industry is moderately concentrated, with a few large players dominating the market while smaller companies cater to niche segments. Leading manufacturers have significant market share due to their strong technological innovations, product quality, and brand recognition. However, there is still room for new entrants, especially those offering specialized or localized solutions. Over time, mergers and acquisitions have led to increased consolidation as companies seek to expand their product portfolios and regional reach.
One of the key characteristics of the market is the strong focus on technological advancements. Companies are increasingly developing IoT-integrated systems that allow for remote monitoring and control, providing enhanced energy management capabilities. Smart features like real-time data analysis, adaptive airflow, and integration with building automation systems (BAS) are becoming essential for staying competitive. These innovations are transforming how HVAC systems are managed and optimized.
 To learn more about this report, Download Free Sample Report
Energy efficiency and sustainability are core drivers of the industry, with regulations becoming stricter globally. Government incentives and green building certifications, such as LEED, have pushed the demand for energy-saving equipment that improves building performance. Companies are responding by designing products that not only save energy but also contribute to reducing carbon footprints, making them attractive to environmentally conscious consumers and businesses.
The market is highly influenced by the construction industry, particularly in the commercial and industrial sectors. With rapid urbanization and an increase in new building projects, the demand for advanced airflow and zone control equipment is on the rise. Additionally, the growing trend of smart cities and sustainable infrastructure projects is creating new opportunities for the industry. As buildings become more complex, so does the need for advanced and customizable airflow solutions to meet diverse requirements.
Drivers, Opportunities & Restraints
The growing emphasis on energy efficiency and sustainability in both residential and commercial buildings is a major driver for the airflow and zone controls equipment market. With stricter energy regulations and the increasing adoption of green building standards like LEED, there is a rising demand for advanced HVAC systems that can optimize air distribution and minimize energy consumption. Additionally, the integration of IoT technology into these systems is enhancing real-time control and monitoring, further boosting their popularity.
One key restraint for the industry is the high initial cost of advanced systems and retrofitting existing buildings. Many businesses and homeowners may hesitate to invest in these technologies due to the perceived high upfront costs, especially when upgrading older HVAC systems. Additionally, the complexity of installation and maintenance can deter adoption, particularly in regions with limited technical expertise.
A significant opportunity for the industry lies in the increasing demand for smart, connected HVAC systems in emerging markets. As urbanization accelerates and the construction industry grows in regions like Asia-Pacific and Latin America, there is a substantial market for energy-efficient, automated systems. Furthermore, the rising awareness about indoor air quality (IAQ) presents an opportunity for businesses to develop and market advanced air filtration and ventilation solutions to meet consumer demand for healthier indoor environments.
Product Insights
Based on product, the dampers segment led the market with the largest revenue share of 32.8% in 2025. The demand for dampers in airflow and zone control equipment is increasing as buildings and HVAC systems prioritize energy efficiency and precise airflow management. Modern dampers are now being integrated with smart technologies, allowing for automated and real-time control of airflow. This shift toward smart dampers enhances system performance by adapting to changing conditions and ensuring optimal air distribution, which is critical in both residential and commercial spaces aiming for sustainability and energy savings.
Airflow regulators are gaining traction due to their ability to maintain consistent air distribution and pressure throughout HVAC systems, optimizing performance. As building designs become more complex, particularly in multi-zone environments, these regulators help balance airflow across various zones, ensuring uniform comfort and energy efficiency. The trend is moving toward advanced, digitally controlled regulators that provide real-time monitoring and integration with building automation systems, further improving operational efficiency and reducing energy costs.
Operation Insights
Based on operation, the manual segment led the market with the largest revenue share of 66.8% in 2025. While manual airflow and zone control equipment are still in use, their demand is steadily declining as building owners and operators seek more efficient, automated solutions. Manual systems often require continuous adjustments, leading to higher energy consumption and inconsistent comfort levels. However, they remain popular in smaller or older buildings where budget constraints or lack of advanced infrastructure make automated systems less feasible.
The demand for automatic airflow and zone control systems is rapidly increasing due to the growing preference for energy efficiency and convenience. Automated systems offer real-time adjustments based on occupancy, temperature, and air quality, improving both comfort and energy savings. Integration with smart building technologies and IoT devices further enhances the functionality of these systems, making them the preferred choice for modern, sustainable buildings seeking optimized HVAC performance and cost-effective operation.
Application Insights
Based on application, the commercial segment led the market with the largest revenue share of 48.4% in 2025. In commercial applications, the demand for advanced airflow and zone control equipment is driven by the need for energy-efficient, customizable HVAC systems that meet the diverse needs of large buildings. Commercial spaces are increasingly adopting smart, automated systems that provide precise control over air distribution, ensuring both comfort and optimal energy usage.
In residential applications, the trend toward airflow and zone control equipment is growing due to increasing consumer interest in energy-efficient solutions that enhance comfort and reduce utility costs. Smart home integration, allowing homeowners to control airflow and temperature through smartphones or voice assistants, is becoming more common.
Deployment Insights
Based on deployment, the new installation segment led the market with the largest revenue share of 67.4% in 2025. The demand for new installations of airflow and zone control equipment is on the rise, driven by rapid urbanization, increased commercial construction, and the growing focus on energy-efficient, sustainable buildings. As new residential and commercial properties are built, there is a clear shift toward integrating advanced, smart airflow systems to optimize energy consumption and improve indoor air quality.
The replacement market for airflow and zone control equipment is also expanding, as older HVAC systems are upgraded to meet higher energy efficiency standards and improve system performance. Existing buildings, especially those in commercial sectors, are replacing outdated manual or less efficient systems with more advanced, automated solutions.
Distribution Channel Insights
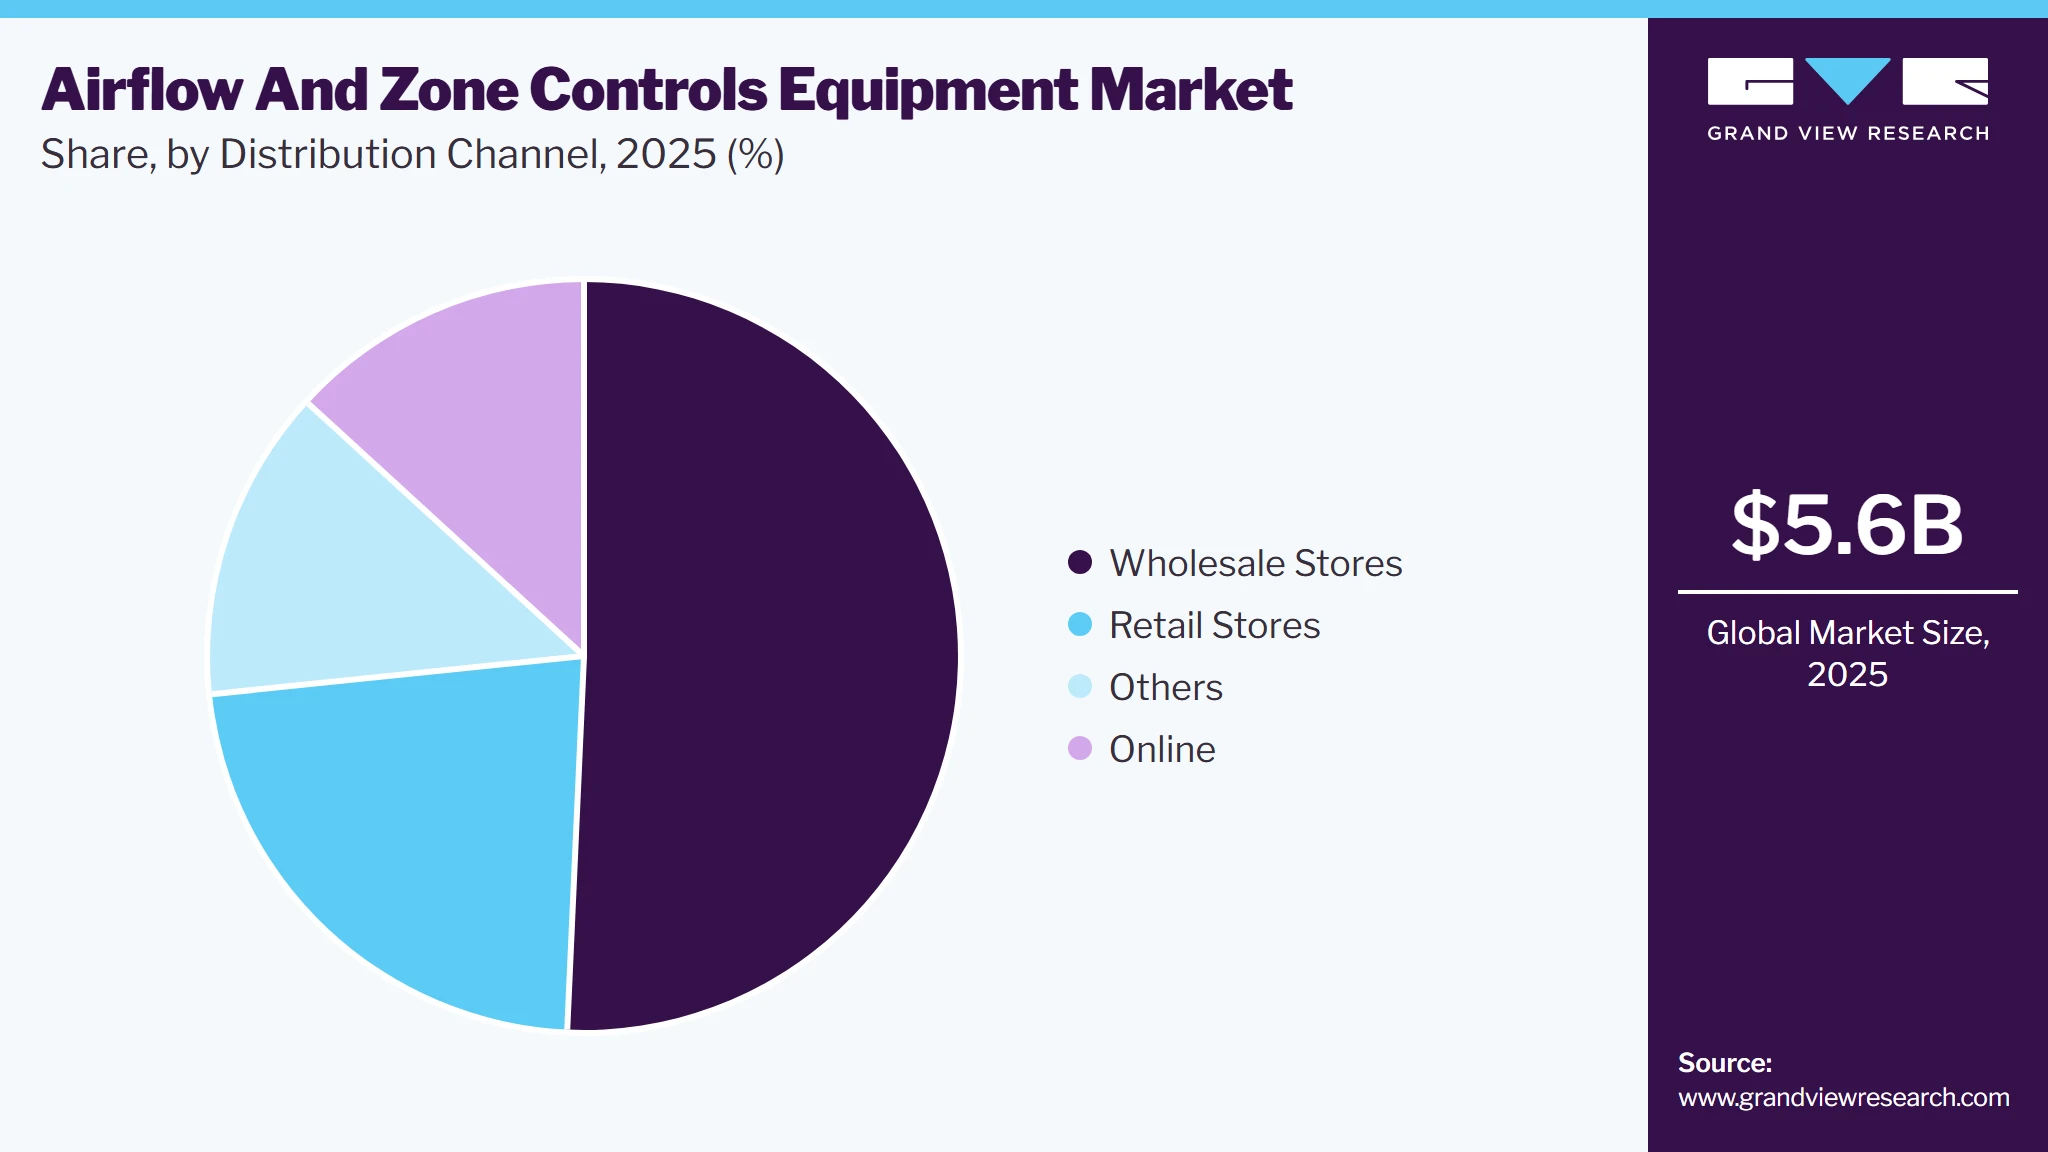
Based on distribution channel, the wholesale stores segment led the market with the largest revenue share of 50.7% in 2025. Wholesale stores play a significant role in the airflow and zone controls equipment market, particularly for large-scale commercial projects and bulk purchases. These stores offer a wide range of HVAC equipment and parts, including advanced zone control systems, at competitive prices. They serve as a primary distribution channel for contractors, engineers, and businesses looking to source equipment in bulk, ensuring quick access to necessary components for new installations and replacements.
 To learn more about this report, Download Free Sample Report
The online distribution channel for airflow and zone control equipment is rapidly expanding, driven by the growing preference for digital shopping and the convenience it offers. Online platforms enable customers-ranging from contractors to homeowners-to access a broader range of products, compare prices, and read reviews, often with delivery options to their location. As smart home and IoT solutions become more mainstream, the online market is particularly attractive for consumers seeking easy-to-install, smart airflow systems that can be controlled via apps or voice assistants.
Regional Insights
North America airflow and zone controls equipment market is expanding rapidly, driven by the increasing demand for energy-efficient solutions and building regulations focused on sustainability. The U.S. and Canada are at the forefront of adopting advanced airflow control systems, with notable growth in both residential and commercial sectors.
U.S. Airflow And Zone Controls Equipment Market Trends
The airflow and zone controls equipment market in the U.S. is expected to grow at a CAGR of 5.1% from 2025 to 2030. The demand for airflow and zone control systems is rising as energy-efficient construction practices and green building certifications become more prevalent. The need for precise airflow control is especially significant in regions with extreme climates, where efficient heating and cooling are essential for energy savings.
Canada airflow and zone controls equipment market is expected to grow at a CAGR of 5.9% from 2025 to 2030. The market’s growth is driven by stringent energy efficiency standards and a strong desire to reduce heating costs, particularly in colder regions. To meet energy codes and maintain optimal indoor air quality, Canadian residential and commercial buildings are increasingly incorporating advanced airflow and zone control systems.
Europe Airflow And Zone Controls Equipment Market Trends
The airflow & zone controls equipment market in Europe is bolstered by strong regulatory efforts promoting energy-efficient building practices and environmental sustainability. Northern European countries, in particular, are leading the adoption of advanced airflow control systems in both residential and commercial buildings.
Germany airflow and zone controls equipment market held 32.4% share in the European market in 2024. The demand for advanced airflow systems is driven by the country’s robust green building initiatives and energy efficiency policies. Airflow & zone control equipment are especially sought after in both new constructions and renovation projects as Germany strives to meet its sustainability objectives.
The airflow and zone controls equipment market in the UK is driven by a national push to improve energy efficiency in both homes and commercial properties. Strict energy regulations, including those from the government, encourage the use of advanced zone control systems to help meet energy conservation targets.
Asia Pacific Airflow And Zone Controls Equipment Market Trends
Asia Pacific dominated the airflow and zone controls equipment market with the largest revenue share of 39.5% in 2025. Urbanization, rapid construction activity, and growing awareness of energy efficiency are driving significant demand for advanced airflow control systems. Countries like China and India are increasingly seeking energy-efficient solutions for both residential and commercial buildings.
 To learn more about this report, Download Free Sample Report
The airflow and zone controls equipment market in China held the largest share in the Asia Pacific region in 2025. The growing demand for energy-efficient buildings and reduced carbon emissions aligns with China’s broader efforts to enhance energy efficiency in the construction sector. The rising middle class and urbanization are contributing to the demand for modern, sustainable airflow systems in both residential homes and commercial spaces.
The airflow and zone controls equipment market in the India is expected to grow at a CAGR of 5.9% from 2025 to 2030. With rapid urbanization and a booming construction sector, there is a rising demand for systems that improve air quality and reduce energy consumption. As urban air quality becomes a growing concern, Indian consumers and businesses are increasingly adopting advanced airflow control solutions for both residential and commercial buildings.
Middle East & Africa Airflow And Zone Controls Equipment Market Trends
The airflow and zone controls equipment market in the Middle East and Africa is driven by urbanization, increased construction activity, and a need for energy-efficient technologies. In countries like Saudi Arabia, high energy costs are spurring the adoption of advanced airflow systems to reduce cooling and heating costs.
Saudi Arabia airflow and zone controls equipment market is making significant investments in sustainable building practices, driving the demand for airflow and zone control systems in both residential and commercial buildings. The country’s extreme climate makes energy-efficient ventilation systems essential for managing indoor air quality and reducing cooling costs.
Latin America Airflow And Zone Controls Equipment Market Trends
The airflow and zone controls equipment market in Latin America is gradually expanding, propelled by growing construction activities and rising awareness of sustainable building practices. Countries like Brazil are seeing increased demand for energy-efficient solutions in both new residential and commercial developments, boosting the adoption of advanced airflow control systems.
Brazil airflow and zone controls equipment market is expanding as the country’s construction industry grows and energy efficiency standards become more stringent. With a rising focus on sustainable building practices and energy conservation, Brazil is increasingly adopting advanced airflow systems to enhance indoor air quality and reduce energy consumption in both residential and commercial buildings.
Key Airflow And Zone Controls Equipment Company Insights
Some of the key players operating in the market include Carrier, Daikin Industries, Ltd., among others.
-
Carrier is a leading global provider of heating, ventilation, and air conditioning (HVAC) solutions. Founded in 1902 by Willis H. Carrier, the company has a long history of innovation and industry leadership, particularly in the development of modern air conditioning systems. Carrier offers a wide range of products for residential, commercial, and industrial applications.
-
Daikin Industries, Ltd., established in 1924 and headquartered in Osaka, Japan, is a global leader in the HVAC industry. The company specializes in the design, manufacture, and distribution of air conditioning systems, refrigerants, and other energy-efficient climate control solutions. Daikin is renowned for its innovation in sustainable technologies, offering a wide range of products, including residential, commercial, and industrial HVAC systems, heat pumps, air purifiers, and air handling units.
Key Airflow And Zone Controls Equipment Companies:
The following key companies have been profiled for this study on the airflow and zone controls equipment market.
- Panasonic Corporation
- Carrier
- Broan-NuTone, LLC
- Zehnder America
- Daikin Industries, Ltd.
- Greenheck Fan Corporation
- Ruskin
- Aldes Group (American Aldes Ventilation Corporation)
- Trane Technologies
- RenewAire
- S&P USA Ventilation Systems, LLC
- Zonex Systems
- Arzel Zoning
- AprilAire
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Johnson Controls; Carrier; Daikin Industries, Ltd.; Trane Technologies; Greenheck Fan Corporation; Ruskin; Panasonic Corporation.)
- Focus on integrated HVAC ecosystems encompassing airflow management, zoning controls, ventilation equipment, and building automation platforms.
- Strengthen market position through continuous product innovation, digital connectivity, and long-term relationships with OEMs, contractors, and facility owners.
- Expand capabilities through energy management solutions, retrofit projects, and intelligent building technologies.
- Strong global brand recognition supported by extensive distribution channels and established installed bases.
- Comprehensive product portfolios spanning dampers, actuators, VAV systems, thermostats, sensors, and control platforms.
- Significant engineering expertise and financial resources enable sustained R&D investment and participation in large-scale commercial projects.
- Premium pricing structures may limit competitiveness in price-sensitive applications.
- Larger organizational frameworks can result in longer product development cycles and reduced operational flexibility.
- Revenue exposure to fluctuations in commercial construction activity and capital expenditure trends across end-use sectors.
Emerging & Regional Players (e.g., Zonex Systems; Arzel Zoning; AprilAire; RenewAire; Zehnder America; Aldes Group; S&P USA Ventilation Systems, LLC; Broan-NuTone, LLC)
- Concentrate on specialized airflow management, zoning technologies, and indoor air quality solutions tailored to residential and light commercial applications.
- Emphasize application-specific product development, flexible manufacturing, and targeted regional expansion strategies.
- Leverage partnerships with HVAC contractors, distributors, and channel partners to strengthen market penetration.
- Strong specialization in niche applications and the ability to deliver customized solutions with shorter response times.
- Competitive pricing structures support penetration in regional and retrofit markets.
- Greater operational agility facilitates faster product innovation and adaptation to evolving customer requirements.
- Limited global presence, smaller service networks, and lower financial resources can restrict participation in large multinational projects.
- Market visibility and customer reach are often narrower compared with established industry leaders.
- Limited geographic reach and service capabilities constrain participation in multinational projects.
- Comparatively smaller financial resources restrict large-scale acquisitions and extensive research investments.
- Lower brand visibility and narrower distribution networks compared with diversified global HVAC equipment manufacturers.
Recent Developments
-
In December 2024, Honeywell's Phoenix Controls launched the Critical Spaces Control Platform, designed to enhance safety and operational efficiency in critical environments. This advanced platform utilizes automation to manage airflow through a specialized venturi valve, ensuring optimal ventilation in settings such as hospitals, laboratories, cleanrooms, and research facilities, where precise environmental control is essential.
Airflow And Zone Controls Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.6 billion
Estimated market size in 2026
USD 5.8 billion
Projected market size by 2033
USD 8.7 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, operation, application, deployment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Panasonic Corporation; Carrier; Broan-NuTone, LLC; Zehnder America; Daikin Industries, Ltd.; Greenheck Fan Corporation; Ruskin; Aldes Group (American Aldes Ventilation Corporation); Trane Technologies; RenewAire; S&P USA Ventilation Systems, LLC; Zonex Systems; Arzel Zoning; AprilAire; Johnson Controls
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Airflow And Zone Controls Equipment Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global airflow and zone controls equipment market on the basis of product, operation, application, deployment, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Dampers
-
VAV (Variable Air Volume)
-
Airflow Regulators
-
Zoning Panels
-
Others
-
-
Operation Outlook (Revenue, USD Million, 2021 - 2033)
-
Manual
-
Automatic
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Commercial
-
Residential
-
Industrial
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
New Installation
-
Replacement
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online
-
Retail Stores
-
Wholesale Stores
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The airflow and zone controls equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each airflow and zone controls equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Dampers
This segment captures revenue generated from the sale of airflow control devices designed to regulate, isolate, or direct the flow of air within HVAC ductwork.
Variable Air Volume (VAV)
This segment captures revenue from the sale of VAV boxes and terminal units that modulate airflow to maintain setpoint temperatures in specific zones.
Airflow Regulators
This segment captures revenue from the sale of devices specifically designed to maintain a constant or pre-set airflow rate irrespective of pressure fluctuations within the duct system.
Zoning Panels
This segment captures revenue from the sale of centralized control panels that act as the interface between the HVAC system and multiple zone sensors and dampers.
Others
This segment captures revenue from all other airflow and zone control products not explicitly classified above. This includes, but is not limited to, zone thermostats, room sensors, wireless communication modules, system controllers, and auxiliary accessories required for complete system integration, connectivity, and user interface.
Segment - Operation
Revenue Capture Definition
Manual
This segment captures revenue from the sale of airflow and zone control equipment that requires physical human intervention for adjustment and operation, without integrated sensing or automated logic.
Automatic
This segment captures revenue from the sale of airflow and zone controls equipment that incorporates electronic sensing, actuators, and control logic to adjust airflow and zoning automatically in response to setpoints, schedules, or environmental conditions. T
Segment - Application
Revenue Capture Definition
Commercial
This segment captures revenue from airflow and zone controls equipment deployed in non-industrial, professionally managed buildings, including office complexes, retail spaces, hotels, hospitals, educational institutions, and government facilities.
Residential
This segment captures revenue from equipment installed in single-family homes, townhouses, apartment complexes, and other dwellings intended for private habitation.
Industrial
This segment captures revenue from equipment deployed in manufacturing plants, processing facilities, warehouses, power generation stations, and other industrial settings.
Segment - Deployment
Revenue Capture Definition
New Installation
This segment captures revenue from airflow and zone controls equipment sold as part of new construction or complete HVAC system replacement projects.
Replacement
This segment captures revenue from equipment sold to upgrade, repair, or exchange existing airflow and zone control components within an operational system.
Segment - Distribution Channel
Revenue Capture Definition
Online
This segment captures revenue from the sale of airflow and zone controls equipment through web-based platforms, including manufacturer-direct e-commerce sites, online industrial distributors, and third-party marketplaces.
Retail Stores
This segment captures revenue from equipment sold through physical retail outlets, including specialty HVAC suppliers, home improvement stores, and electrical supply showrooms.
Wholesale Stores
This segment captures revenue from the sale of airflow and zone control equipment through wholesale distributors and authorized dealer networks that serve the B2B market.
Others
This segment captures revenue from all other distribution channels not classified above. This includes sales through direct manufacturer contracts (e.g., OEM supply agreements, direct to large commercial projects), sales to government bodies, sales through installation and maintenance service providers, and any emerging channels that do not fit the primary categories of online, retail, or wholesale.
Estimation Model
Layer Name
Key Question
Description
HVAC Equipment Demand Layer
Where are airflow and zone control systems required?
Analyze demand across residential, commercial, institutional, and industrial buildings. Assess HVAC installations in offices, hospitals, hotels, educational institutions, retail facilities, data centers, and manufacturing plants to establish the addressable demand for airflow and zone control equipment.
Building Construction & HVAC Investment Layer
Where is new equipment demand being created?
Evaluate investments in new building construction, HVAC retrofits, smart building projects, and energy-efficiency upgrades. Assess greenfield developments, commercial renovations, and building automation initiatives that generate demand for airflow dampers, zone control systems, and related HVAC control equipment.
Technology Penetration Layer
What share of applicable facilities deploys airflow and zone control equipment?
Estimate penetration by building type, HVAC configuration, application, and geography. Account for adoption of smart HVAC controls, building management systems, and demand-controlled ventilation technologies, while considering competition from conventional fixed-airflow systems.
Revenue Realization Layer
How much market revenue is generated?
Estimate annual shipments of airflow and zone control equipment by product type, application, and region. Quantify revenues generated exclusively from the sale of new airflow and zone control equipment supplied to HVAC OEMs, contractors, system integrators, and building owners.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked leading airflow and zone controls equipment manufacturers based on product portfolio strength, financial performance, technology capabilities, application focus, geographic footprint, and strategic positioning, while distinguishing established and specialized market participants.
Provided a comprehensive understanding of the competitive landscape, enabling the client to evaluate market positioning, identify differentiation opportunities, and monitor competitive intensity more effectively
Regional Segmentation
Refined regional analysis by evaluating commercial construction activity, HVAC penetration rates, energy efficiency regulations, smart building adoption, indoor air quality requirements, and retrofit investments across North America, Europe, Asia Pacific, Middle East & Africa, and Latin America.
Enabled identification of high-growth regional markets, regulatory drivers, and investment priorities, supporting market expansion and strategic entry decisions.
Opportunity assessment
Assessed emerging growth opportunities across commercial buildings, residential developments, industrial facilities, retrofit installations, indoor air quality applications, and smart HVAC and building automation solutions.
Helped prioritize the most attractive revenue pockets and investment areas by identifying segments with strong future demand and favorable adoption trends.
Frequently Asked Questions About This Report
Asia Pacific dominated the airflow and zone controls equipment market with the largest revenue share of 39.5% in 2025.
The commercial segment led the market with the largest revenue share of 48.4% in 2025.
The new installation segment accounted for the largest revenue share of 67.4% in 2025.
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by rapid urbanization, increasing commercial construction, and growing investments in smart and energy-efficient buildings.
The global airflow and zone controls equipment market size was valued at USD 5.6 billion in 2025 and is estimated at USD 5.8 billion for 2026.
The dampers segment led the market with the largest revenue share of 32.8% in 2025.
Some of the key players operating in the airflow & zone controls equipment market include Panasonic Corporation, Carrier, Broan-NuTone, LLC, Zehnder America, Daikin Industries, Ltd., Greenheck Fan Corporation, Ruskin, Aldes Group (American Aldes Ventilation Corporation), Trane Technologies, RenewAire, S&P USA Ventilation Systems, LLC, Zonex Systems, Arzel Zoning, AprilAire, Johnson Controls.
The airflow & zone controls equipment market is evolving with a strong shift towards smart, automated systems. Increased adoption of IoT-based devices allows real-time monitoring and precise control, improving energy efficiency and user comfort.
The global airflow and zone controls equipment market is expected to grow at a CAGR of 6.0% from 2026 to 2033, reaching USD 8.7 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


