
- Home
- »
- Next Generation Technologies
- »
-
AI In Aerospace And Defense Market Size Report 2026-2033GVR Report cover

AI In Aerospace And Defense Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Hardware, Software), By Deployment Type, By Platform, By Technology, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$26.8BMarket Estimate, 2026
$29.3BMarket Forecast, 2033
$57.1BCAGR, 2026–2033
9.9%AI in Aerospace And Defense Market Summary
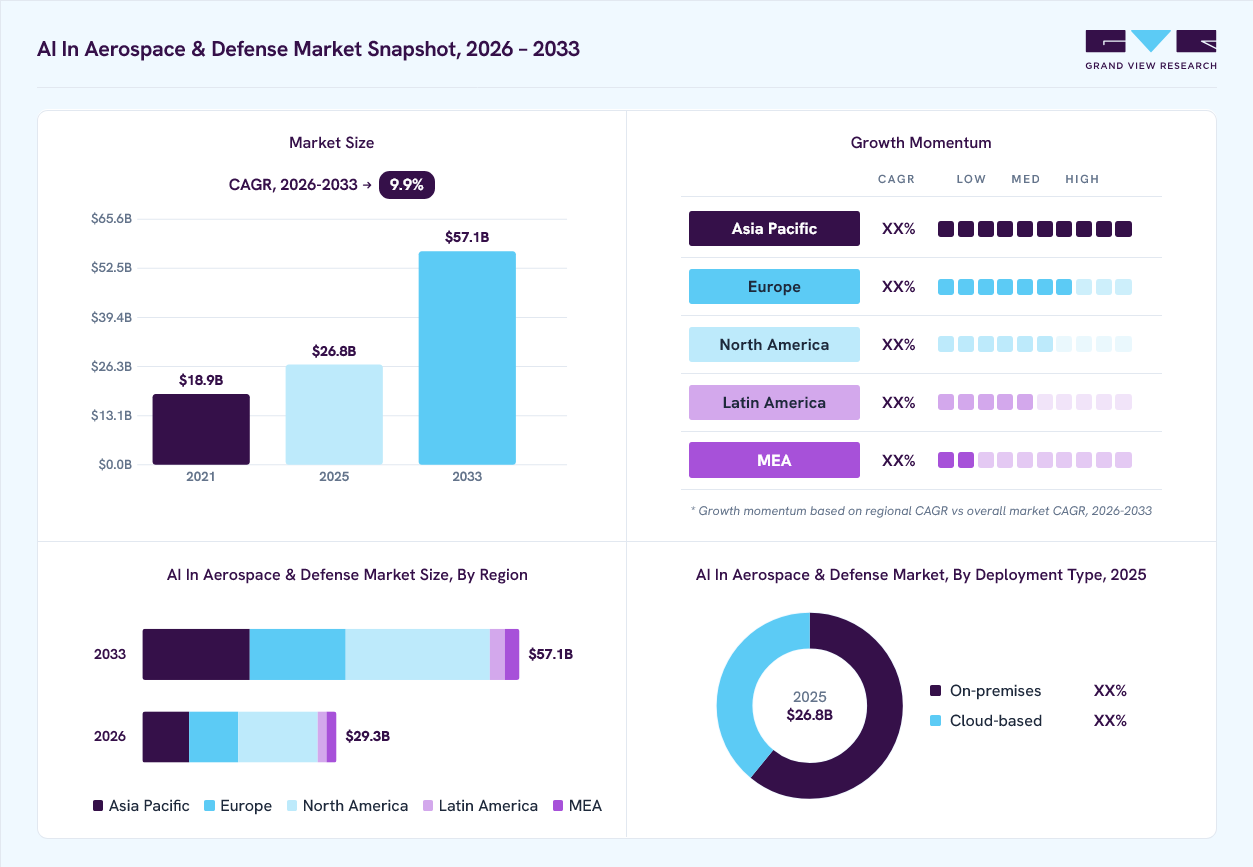
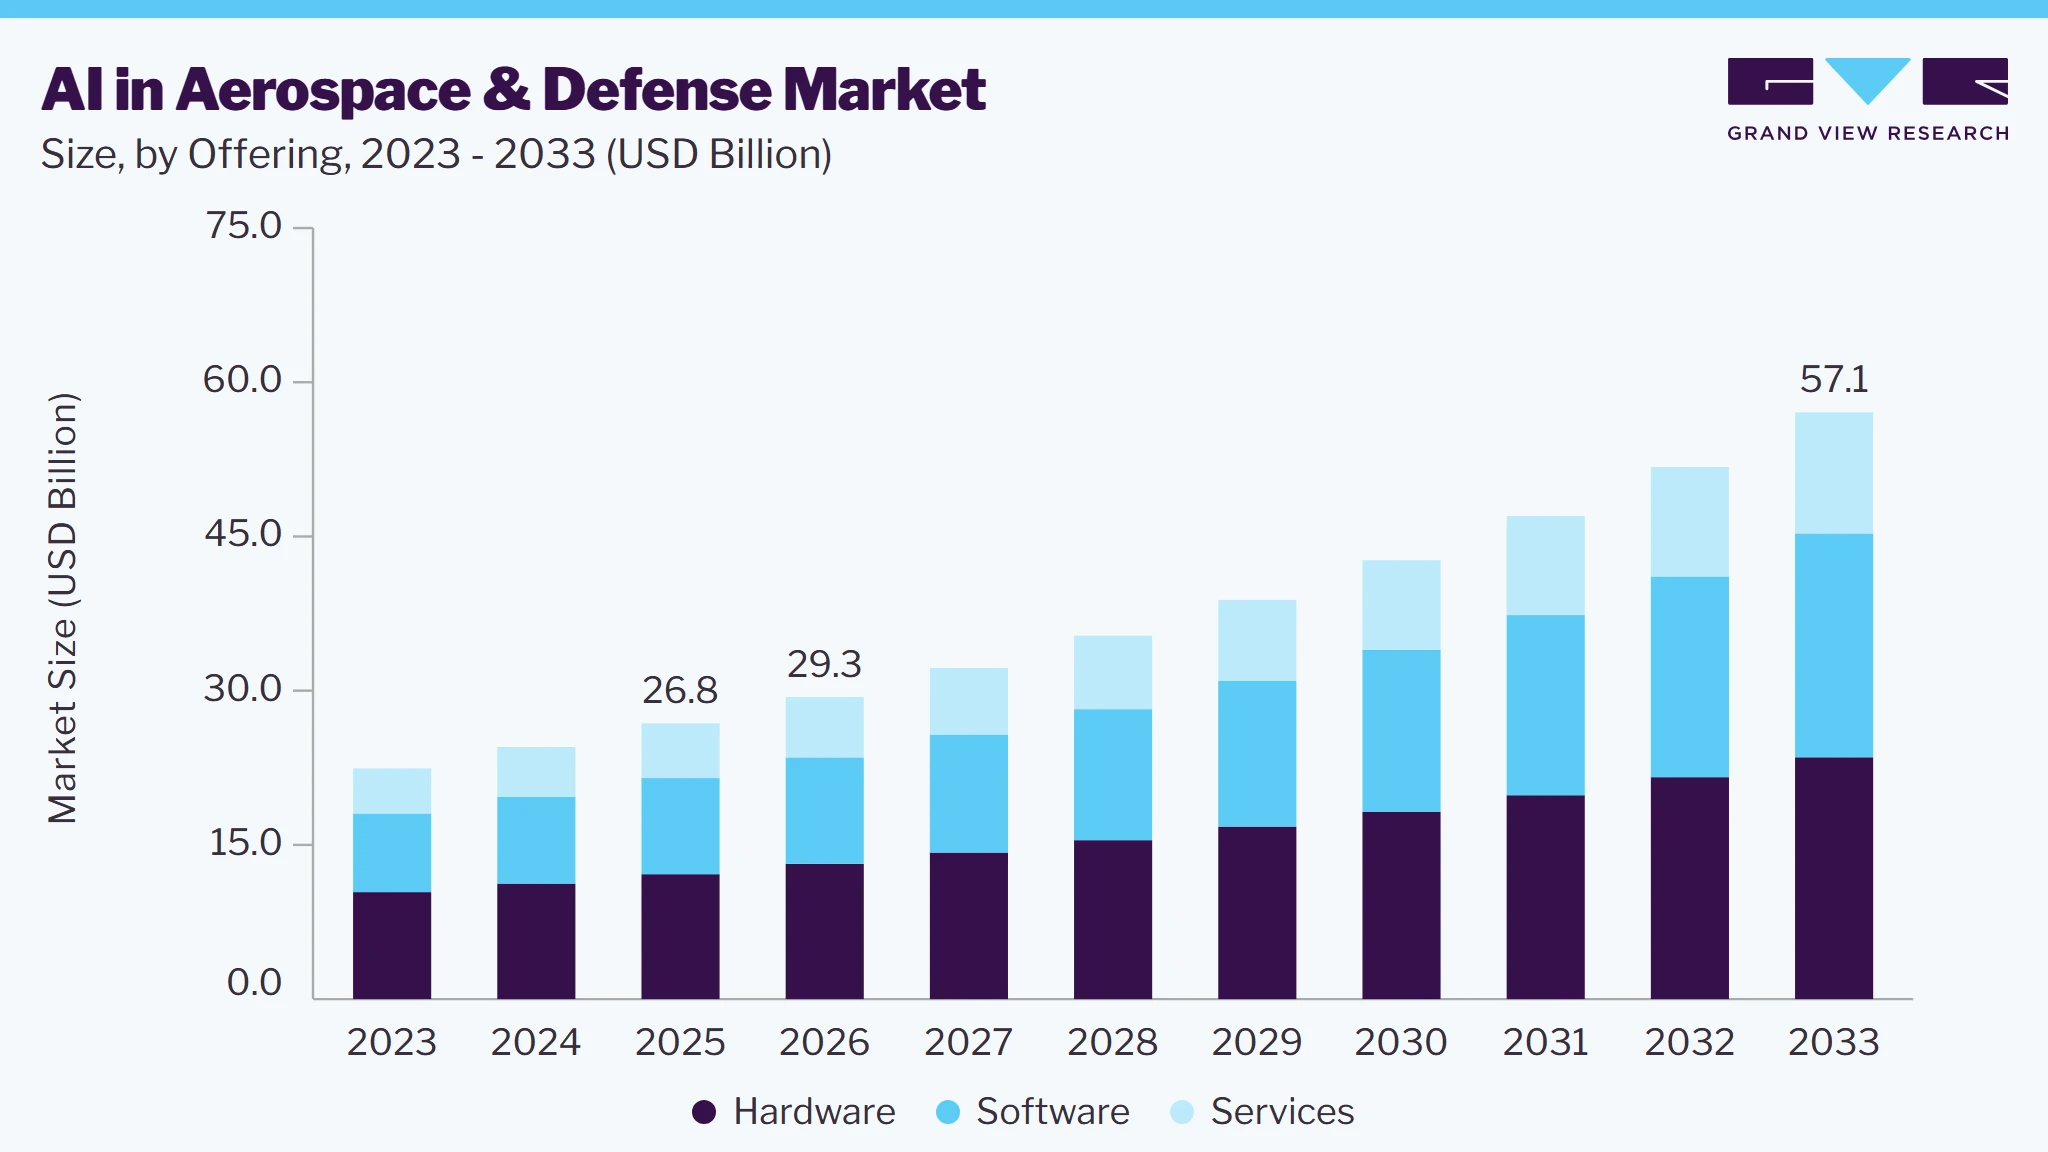
The global AI in aerospace and defense market size was valued at USD 26.8 billion in 2025 and is projected to grow from USD 29.3 billion in 2026 to USD 57.1 billion by 2033, at a CAGR of 9.9% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 41.4% in 2025. The market is driven by the increasing adoption of artificial intelligence for autonomous systems, the growing integration of machine learning, computer vision, and edge computing into defense platforms, and the rising demand for real-time decision intelligence across military and aerospace operations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: Hardware segment dominated the market, with a share of 42.6% in 2025.
- By deployment type: On-premises segment accounted for the largest market share of 55.5% in 2025.
- By platform: Airborne development segment dominated the market in 2025.
- By technology: Machine learning segment held the largest market share in 2025.
- By application: Surveillance and monitoring development segment dominated the market in 2025.
- By end use: Government & law enforcement segment accounted for the largest market share in 2025.
Regional Highlights
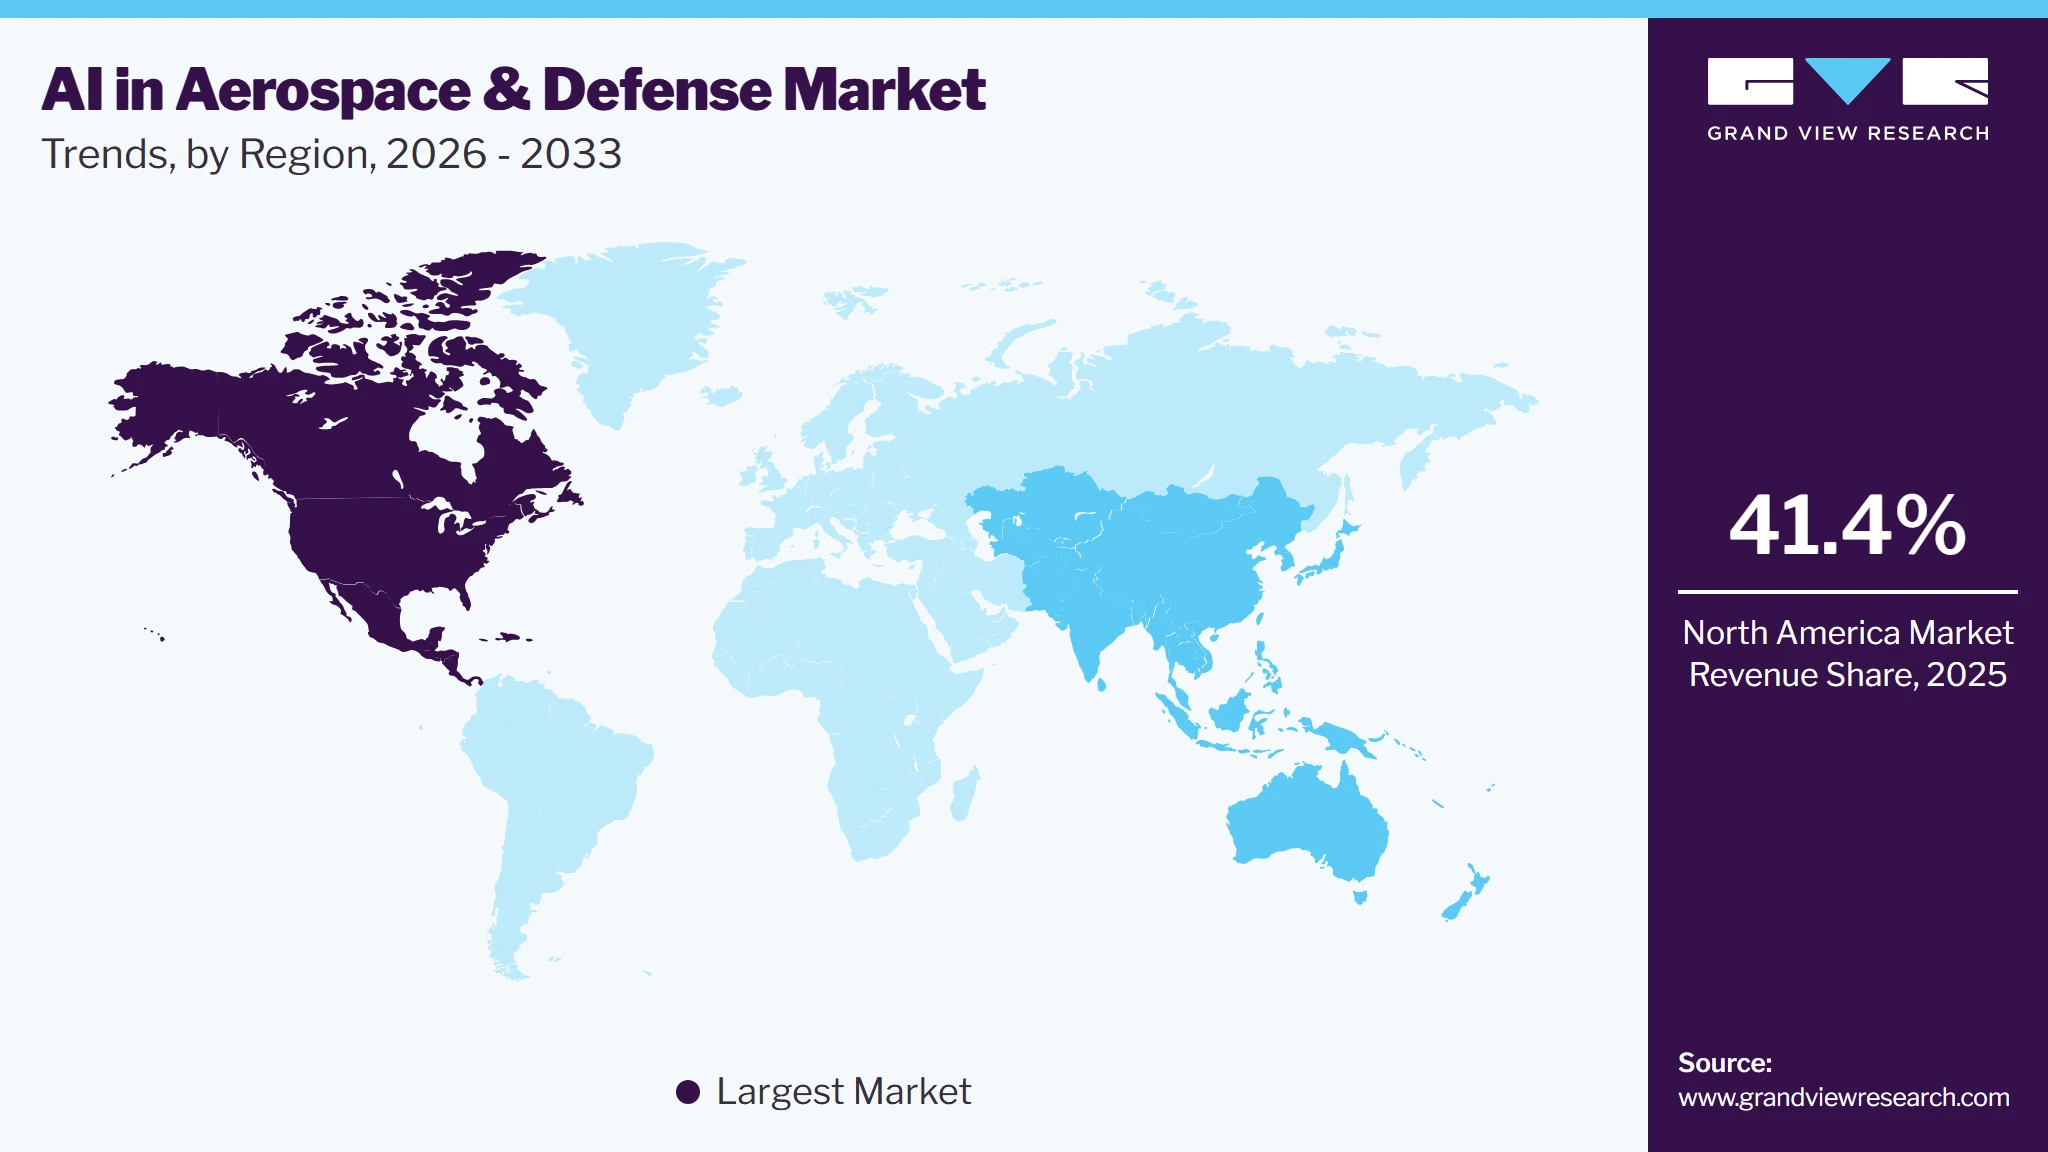
- Largest regional market: North America (41.4% revenue share, 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 12.6%, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 26.8 Billion
- Estimated market size in 2026: USD 29.3 Billion
- Projected market size by 2033: USD 57.1 Billion
- CAGR (2026-2033): 9.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding deployment of AI-powered unmanned aerial vehicles (UAVs), autonomous combat systems, predictive maintenance solutions, intelligent surveillance, cybersecurity platforms, and mission planning applications is significantly accelerating the adoption of AI technologies across the aerospace and defense sector. The increasing use of AI-enabled data fusion, target recognition, and command-and-control systems is enhancing operational efficiency, improving situational awareness, and enabling faster, more informed decision-making, thereby creating growth opportunities in the market.
Predictive maintenance powered by AI reduces unexpected equipment failures and downtime by forecasting when components need service before they break down. In addition, AI enhances decision-making by providing actionable insights through data analytics, streamlining operations, reducing costs, and improving resource allocation. AI-driven systems analyze data from various sources to optimize maintenance schedules, manage supply chains, and improve logistics. Multiple governments have been investing in developing and enhancing the capacity of forces to counter global threats, accelerating military modernization, and including advanced technologies. AI advancements in surveillance and threat detection revolutionize aerospace and defense operations by processing and analyzing vast amounts of data from sensors, satellites, and other sources in real time. AI systems use machine learning algorithms to detect and identify potential threats with high accuracy, reducing false alarms and improving overall situational awareness. These systems can integrate data from diverse sources to provide comprehensive and timely intelligence, enabling more effective monitoring of borders, airspace, and strategic locations. Enhanced threat detection capabilities lead to quicker, more precise responses, improving national security and defense readiness while better protecting assets and personnel.
 To learn more about this report, Download Free Sample Report
In aerospace and defense, AI-driven design tools and simulations are transforming the development and manufacturing processes. AI algorithms enhance the design phase by providing more accurate simulations and predictions, leading to innovative solutions and reduced design errors. AI-powered generative design tools can explore a broader range of design possibilities, optimizing for performance, weight, and cost. In addition, Artificial Intelligence (AI) helps create detailed digital twins of systems, enabling extensive virtual testing and validation before physical prototypes are built. This approach accelerates the innovation cycle, improves product reliability, and lowers production costs, contributing to more efficient and cost-effective development processes. For instance, in October 2025, Lockheed Martin partnered with Google Public Sector to integrate its AI Factory with Google's advanced generative AI, including the Gemini models. Such developments are likely to strengthen the growth potential of this industry.
Market Dynamics
The AI in aerospace and defense market is experiencing significant growth owing to the increasing emphasis on intelligent defense modernization, the rapid evolution of autonomous mission capabilities, and the growing need for data-driven operational superiority across military and aerospace environments. Rising defense expenditures, increasing investments in AI-enabled command, control, communications, computers, intelligence, surveillance, and reconnaissance (C4ISR) systems, and the modernization of next-generation air, land, sea, and space platforms are encouraging governments and defense organizations to integrate advanced AI technologies into critical missions. The expanding adoption of AI for autonomous navigation, predictive maintenance, electronic warfare, battlefield intelligence, logistics optimization, and cyber defense is broadening market penetration across defense ecosystems. Continuous advancements in generative AI, edge AI, digital twin technology, sensor fusion, explainable AI, and human-machine teaming are enabling faster threat assessment, enhancing mission effectiveness, improving asset readiness, and strengthening operational resilience, thereby creating substantial opportunities for long-term market growth.
Governments worldwide are substantially increasing investments in defense modernization programs to strengthen national security, improve operational readiness, and enhance mission effectiveness. Artificial intelligence is becoming a strategic technology within next-generation defense platforms by enabling autonomous mission execution, real-time battlefield intelligence, predictive analytics, and faster command decision-making. Military organizations are integrating AI across air, land, naval, and space systems to improve operational precision while reducing reliance on manual processes.
The growing deployment of AI-powered surveillance systems, autonomous unmanned platforms, predictive maintenance solutions, and intelligent command-and-control architectures is transforming defense capabilities. AI enables rapid analysis of large volumes of sensor, radar, satellite, and intelligence data, allowing forces to identify threats more accurately and respond more quickly. Continuous investments in AI-enabled defense technologies are accelerating procurement programs while improving mission efficiency, situational awareness, and asset availability across modern military operations.
The deployment of artificial intelligence in defense applications faces significant challenges due to evolving regulatory frameworks, ethical considerations, and stringent military certification requirements. Governments require AI systems to demonstrate transparency, reliability, cybersecurity resilience, and compliance with national defense policies before operational deployment. These extensive validation procedures increase implementation timelines and complicate the integration of AI into mission-critical defense environments.
Defense organizations must also address concerns regarding autonomous decision-making, accountability, data security, and interoperability with legacy military systems. Sensitive defense data requires secure processing environments, while AI models must perform reliably under unpredictable battlefield conditions. Meeting these technical, legal, and operational requirements often demands extensive testing, continuous monitoring, and specialized infrastructure, slowing the widespread implementation of advanced AI capabilities.
The increasing adoption of edge AI across defense platforms is creating significant opportunities for intelligent mission execution in environments where communication latency or network disruption limits cloud connectivity. Processing data directly on aircraft, naval vessels, satellites, autonomous vehicles, and battlefield devices enables immediate analysis of mission-critical information without depending on centralized computing infrastructure.
Advancements in compact AI processors, sensor fusion technologies, secure edge computing, and low-power hardware are making real-time autonomous operations increasingly practical across defense applications. Edge intelligence supports faster threat detection, autonomous navigation, electronic warfare, predictive maintenance, and tactical decision support while improving operational resilience in contested environments. Defense organizations prioritize distributed operations, edge AI is becoming a foundational capability for future military systems.
Market Concentration & Characteristics
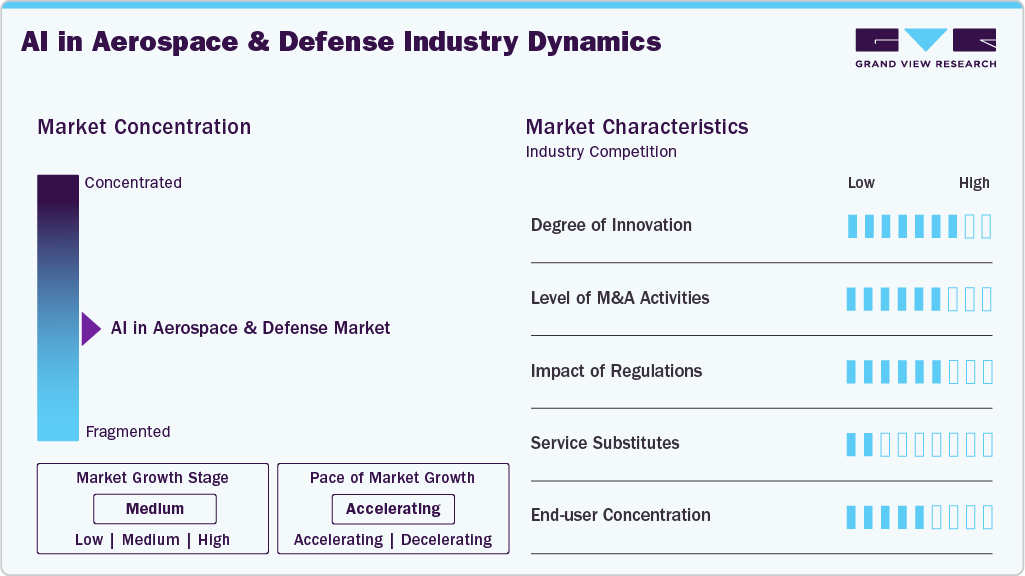
The AI in aerospace and defense market is moderately concentrated, with leading defense contractors, aerospace manufacturers, AI technology providers, and autonomous systems developers competing across intelligence, surveillance, mission planning, cybersecurity, and predictive maintenance applications. Rising defense modernization initiatives, increasing military investments in autonomous capabilities, and the growing need for real-time decision intelligence are driving market expansion. Companies are strengthening their competitive positions through strategic partnerships, acquisitions, AI-enabled platform development, and continuous investments in advanced defense technologies.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by rapid advancements in machine learning, edge AI, computer vision, sensor fusion, and autonomous mission technologies. Merger and acquisition activity remains moderately high as companies expand AI expertise and strengthen defense technology portfolios. Regulatory impact is significant due to stringent defense procurement policies, cybersecurity requirements, AI governance standards, and export controls. The threat of substitutes remains low because conventional defense systems cannot match AI-enabled operational speed, accuracy, and decision intelligence.
Analyst Perspective
The AI in aerospace and defense market is witnessing significant expansion, driven by increasing defense modernization initiatives, rapid advancements in artificial intelligence technologies, and the growing adoption of autonomous systems, intelligent surveillance, and predictive analytics across military and aerospace operations. The expanding implementation of edge AI, machine learning, computer vision, digital twins, and AI-enabled command-and-control platforms is improving mission planning, operational efficiency, asset readiness, and threat detection. The governments and defense organizations increasingly prioritize autonomous capabilities, real-time decision intelligence, and secure AI-driven operations. Technology providers are positioned to capitalize on emerging opportunities, thereby reinforcing long-term market expansion and sustainable revenue generation across the global aerospace and defense ecosystem.
Offering Insights
Based on offering, the hardware segment led the market with the largest revenue share of 42.6% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The market is driven by the increasing demand for advanced computing and processing power necessary for AI applications. Enhanced hardware capabilities are crucial for running complex algorithms, managing large datasets, and performing real-time data analysis. As AI technologies evolve, they require more powerful processors, specialized GPUs, and high-performance computing systems. This demand is further fueled by advancements in sensor technologies, which are integral for data collection and integration into AI systems. In addition, the push for more robust, reliable hardware that withstands harsh aerospace and defense environments contributes to the growth of this segment.
The software segment is expected to register the fastest CAGR from 2026 to 2033. The market is growing due to the increasing deployment of AI-driven applications for mission-critical tasks. Software advancements include sophisticated algorithms for data analytics, machine learning, and predictive maintenance, which enhance operational efficiency and decision-making. Innovations in software also facilitate the development of customized solutions tailored to specific defense and aerospace needs, such as advanced simulation tools and automated systems. The need for scalable, flexible software that can integrate with existing systems while addressing evolving challenges drives continued investment and growth in this segment. For instance, in June 2025, C3 AI, an AI technology solutions company, announced a new task order from the United States Air Force (USAF) Rapid Sustainment Office (RSO) to expand the deployment of its AI-powered predictive maintenance system. Such developments are key to the growth of this market.
Deployment Type Insights
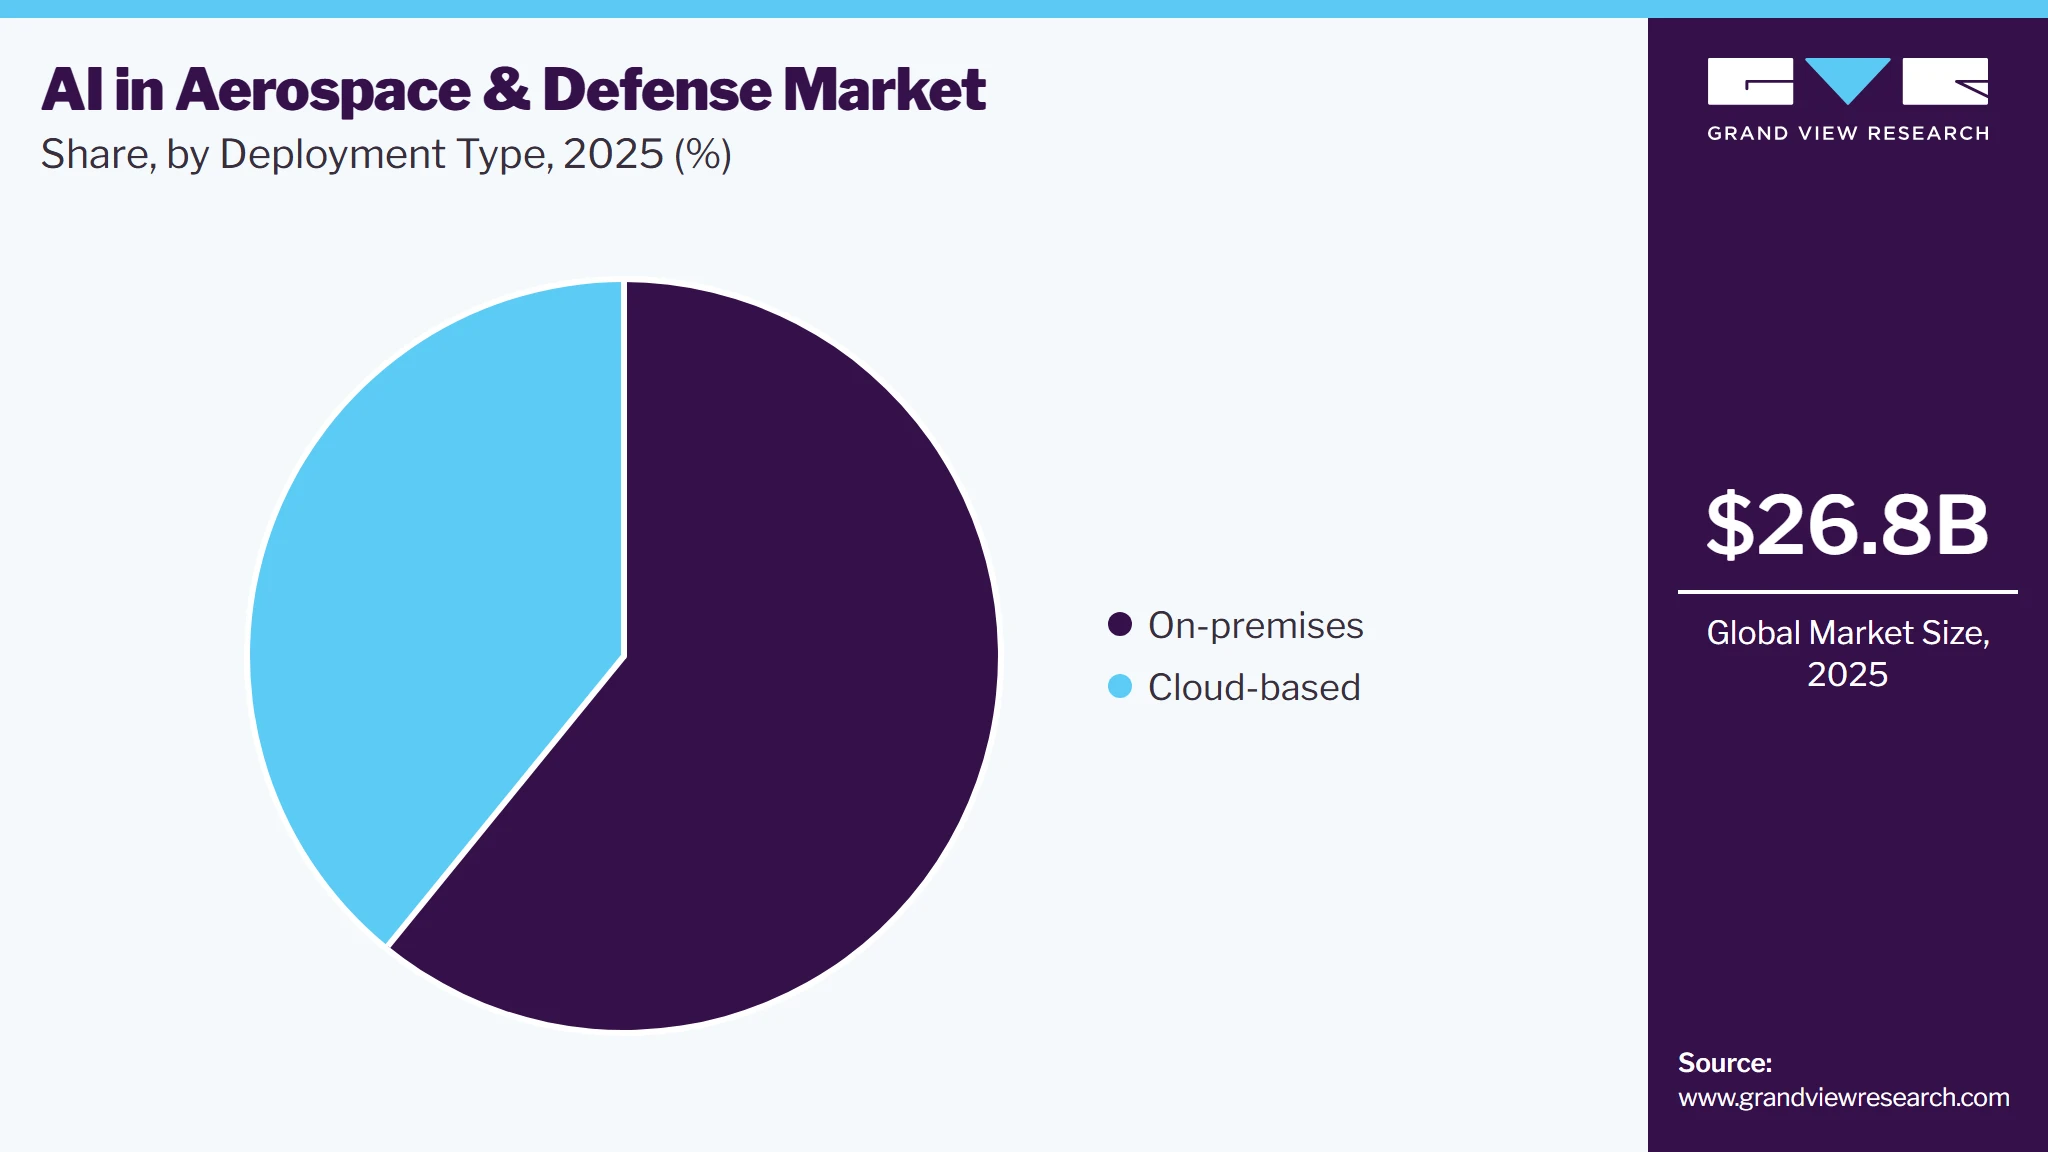
Based on deployment type, the on-premises segment dominated the market with the largest revenue share of 55.5% in 2025. The market is growing due to the need for secure, controlled environments in which sensitive data and applications can be managed with high confidentiality. On-premises solutions offer robust security measures and strict regulatory compliance, making them ideal for handling classified and mission-critical information. In addition, the preference for on-premises systems arises from the desire for greater control over hardware, software, and data management. The ability to customize and integrate these systems within existing infrastructure further supports the growth of on-premises AI solutions in the aerospace and defense sectors.
 To learn more about this report, Download Free Sample Report
The cloud-based segment is expected to register the fastest CAGR from 2026 to 2033. The market is growing rapidly as organizations seek scalable and flexible solutions to manage and analyze vast amounts of data. Cloud-based AI platforms offer significant advantages, including cost-effectiveness, ease of deployment, and the ability to rapidly scale resources based on demand. These platforms facilitate collaboration and data sharing among distributed teams, enhance computational power, and support advanced analytics and machine learning. The increasing adoption of cloud services also enables real-time data processing and access to cutting-edge AI technologies without substantial on-premises infrastructure investments. In February 2026, Oracle announced that it had received a task order from the United States Air Force (USAF) for Oracle Cloud Infrastructure (OCI) services. Associated with the Air Force Cloud One program, this partnership includes Department of War (DoW) cloud modernization and access to Oracle AI Database 26ai on OCI. These developments signify the growth opportunity for the cloud segment.
Platform Type Insights
Based on platform, the airborne segment led the market with the largest revenue share of 37.5% in 2025. The market is driven by the growing use of AI technologies in aviation and military aircraft to enhance operational capabilities and safety. AI-powered systems improve navigation, collision avoidance, and autonomous flight management, providing greater efficiency and precision. The integration of advanced sensors and real-time data analysis supports enhanced situational awareness and decision-making for pilots and defense operators. As aerospace and defense organizations seek to modernize their fleets and develop next-generation aircraft, the demand for AI-driven airborne systems continues to rise, fostering growth in this segment.
The space segment is expected to register the fastest CAGR from 2026 to 2033. The market benefits from the increasing application of AI in satellite operations, space exploration, and space-based monitoring systems. AI technologies enable more efficient data processing, real-time image analysis, and autonomous spacecraft operations. The ability to handle vast amounts of space-derived data, enhance mission planning, and improve satellite communication is driving growth in this segment. As space missions become more complex and ambitious, the demand for advanced AI solutions to support satellite management, space exploration, and in-orbit operations continues to expand, fueling growth in the space sector.
Technology Insights
Based on technology, the machine learning development segment dominated the market with a revenue share of 30.6% in 2025. The market is driven by the ability to analyze complex datasets and make data-driven predictions. Machine learning algorithms improve various applications, including predictive maintenance, threat detection, and automated decision-making. The technology’s ability to adapt and learn from new data allows for continuous improvement in system performance and accuracy. As aerospace and defense organizations seek to leverage machine learning for advanced analytics, pattern recognition, and autonomous systems, the demand for machine learning solutions is increasing, supporting expansion in this segment.
Computer vision is expected to register the fastest CAGR from 2026 to 2033. The market is growing due to its ability to provide advanced image and video analysis capabilities. Computer vision technologies enable real-time processing of visual data from cameras, satellites, and drones, enhancing surveillance, reconnaissance, and target identification. Applications such as facial recognition, object detection, and autonomous vehicle navigation benefit from the accuracy and efficiency of computer vision. As the need for precise visual data analysis and automation in aerospace and defense operations increases, the demand for computer vision solutions continues to rise, driving growth in this segment.
Application Insights
Based on application, the surveillance and monitoring segment accounted for the largest market share of 21.8% in 2025. The market is expanding due to the critical need for enhanced security and situational awareness. AI-driven surveillance systems provide advanced capabilities for real-time monitoring, threat detection, and data analysis. These systems leverage AI to analyze video feeds, sensor data, and other inputs to identify potential threats and anomalies with high accuracy. The growing emphasis on national security, border protection, and intelligence gathering drives demand for sophisticated surveillance and monitoring solutions, contributing to the segment’s growth.
Navigation & guidance systems are expected to register the fastest CAGR from 2026 to 2033. The market growth benefits from advancements in AI technologies that improve accuracy and reliability. AI-enhanced navigation systems support precise positioning, route optimization, and autonomous navigation for aircraft, spacecraft, and military vehicles. Guidance systems leverage AI for real-time adjustments, threat avoidance, and mission planning. The integration of AI into these systems enhances performance, reduces errors, and supports complex operational scenarios. As aerospace and defense organizations seek to enhance their navigation and guidance capabilities, the demand for AI-driven solutions in this segment continues to grow.
End Use Insights
Based on end use, the government & law enforcement development segment dominated the market with a revenue share of 52.0% in 2025. The market is growing due to the increasing adoption of AI technologies for public safety and security. AI solutions support various applications, including surveillance, crime prediction, and intelligence analysis. The ability to process large volumes of data and provide actionable insights enhances law enforcement agencies' effectiveness in preventing and responding to threats. In addition, AI-driven tools assist in managing critical infrastructure and emergency response. As governments and law enforcement agencies seek to leverage advanced technologies to improve security, demand for AI solutions in this segment is rising.
The commercial segment is expected to grow at a significant CAGR from 2026 to 2033. The market is driven by the increasing use of AI technologies in commercial aviation and related industries. AI applications enhance operational efficiency, safety, and customer experience in commercial airlines through predictive maintenance, flight optimization, and automated systems. In addition, it supports advanced analytics for market forecasting, route planning, and passenger services. The growing focus on improving operational performance and competitive advantage in the commercial aerospace sector fuels the demand for AI-driven solutions, contributing to the expansion of this segment.
Regional Insights
North America dominated the AI in aerospace and defense market with the largest revenue share of 41.4% in 2025. The market is driven by significant investment in research and development, technological innovation, and the presence of major defense contractors and aerospace companies. The region benefits from a strong technological infrastructure, extensive government funding, and a high demand for advanced AI solutions to enhance national security and operational efficiency. In addition, collaboration between private and public sectors accelerates the development and adoption of cutting-edge AI technologies. The focus on modernization and the integration of AI in military and aerospace systems further fuels growth in this region. Partnerships and collaborations among companies in the commercial sector also contribute significantly to the growth potential of this regional industry. In April 2026, CoLab AI Inc. announced a collaboration with Bombardier Inc. to deploy advanced AI solutions to support various processes in business jet manufacturing, including design-stage development.
 To learn more about this report, Download Free Sample Report
U.S. AI in Aerospace and Defense Market Trends
The AI in aerospace and defense market in the U.S. held the largest share in the North America region in 2025. The market has been experiencing growth owing to its substantial defense budget, technological leadership, and extensive research initiatives. The U.S. government and military invest heavily in AI technologies to enhance operational capabilities, security, and efficiency. The presence of major technology firms, defense contractors, and innovative startups contributes to rapid advancements in AI applications. In addition, strategic partnerships, public-private collaborations, and a focus on maintaining technological superiority drive the widespread adoption and development of AI solutions in various aerospace and defense sectors.
Asia Pacific AI in Aerospace and Defense Market Trends
The AI in aerospace and defense industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The market is driven by increasing defense expenditures, rapid technological advancements, and growing regional security concerns. Countries in APAC are investing in modernizing their aerospace and defense capabilities, with a focus on integrating AI technologies for improved operational efficiency, surveillance, and threat detection. The region's expanding defense budgets and strategic initiatives to enhance national security are driving rising demand for AI solutions. In addition, collaborations with global technology providers and local innovation hubs are further propelling growth in this market segment.
Japan AI in aerospace and defense market is estimated to grow significantly from 2026 to 2033. The market is fueled by its strong technological base, significant government investment in defense innovation, and a focus on enhancing national security. The country is actively integrating AI into its aerospace and defense systems to improve operational efficiency, precision, and safety. Japan's emphasis on advanced research, particularly in robotics and autonomous systems, drives the development of cutting-edge AI applications. Furthermore, strategic partnerships with international defense and technology firms contribute to the advancement and adoption of AI technologies in Japan's defense sector.
The AI in aerospace and defense market in India is estimated to record a notable CAGR from 2026 to 2033. The market is driven by its expanding defense budget, strategic focus on modernization, and increasing emphasis on technological innovation. The Indian government is investing in AI technologies to enhance defense capabilities, improve surveillance, and streamline operations. Initiatives such as "Make in India" and public-private partnerships support the development and deployment of AI solutions in aerospace and defense. In addition, India's growing technology sector and emphasis on research and development contribute to the advancement and integration of AI technologies in the country's defense and aerospace systems.
China AI in aerospace and defense market had the largest revenue share in 2025. The market is driven by its substantial investment in defense modernization, technological advancements, and strategic focus on enhancing national security. The Chinese government prioritizes integrating AI technologies into its aerospace and defense systems to improve operational efficiency, surveillance, and threat detection. China's growing defense budget and ambitious research initiatives support the development and deployment of advanced AI solutions. In addition, partnerships with global technology providers and investments in domestic innovation contribute to the expansion of AI applications in China's defense sector.
Key AI in Aerospace and Defense Company Insights
Some of the key players operating in the market include Deutsche Telekom AG, General Electric Co., and Honeywell International Inc.
-
Deutsche Telekom AG focuses on leveraging its robust telecommunications infrastructure to drive AI innovation in aerospace and defense. The company invests in developing advanced network solutions, enhancing cybersecurity, and integrating AI-driven IoT applications. Strategic partnerships and collaborations with defense contractors and aerospace firms support its growth, while continuous advancements in 5G technology enable more reliable and efficient AI solutions for critical defense and aerospace operations.
-
General Electric Co. focuses on digital transformation and predictive maintenance. GE invests in AI technologies to enhance its aviation and defense systems, improve operational efficiency, and reduce downtime. The company leverages its strong industrial expertise and research capabilities to develop advanced AI solutions for real-time data analytics and automation, supporting its position as a leader in smart infrastructure and aerospace technology.
Indra Sistemas SA, Iris Automation Inc., and SparkCognition Inc. are some of the emerging market participants.
-
Indra Sistemas SA emphasizes growth in AI for aerospace and defense through innovation in IT and defense solutions. The company invests in developing AI-powered systems for surveillance, navigation, and command-and-control applications. Strategic collaborations with global defense and aerospace firms enhance its market presence, while a focus on digital transformation and smart technology integration positions Indra as a key player in providing cutting-edge AI solutions tailored to defense and aerospace needs.
-
Iris Automation Inc. drives growth by specializing in AI-driven collision avoidance systems for unmanned aerial vehicles (UAVs). The company focuses on advancing its AI technologies to improve the safety and navigation of autonomous flights. By forming strategic partnerships with aerospace and defense organizations, Iris Automation expands its market reach and integrates its solutions into various UAV applications. Continuous innovation in computer vision and machine learning supports the growth and adoption of these technologies in the aerospace and defense sectors.
Key AI in Aerospace and Defense Companies
The following key companies have been profiled for this study on the AI in aerospace and defense market.
-
Deutsche Telekom AG
-
General Electric Company
-
Honeywell International Inc.
-
Indra
-
Infosys Limited
-
Intel Corporation
-
International Business Machines Corporation
-
Iris Automation Inc.
-
Lockheed Martin Corporation
-
Microsoft
-
Northrop Grumman.
-
NVIDIA Corporation
-
RTX
-
Avathon, Inc.
-
Thales
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Deutsche Telekom AG, General Electric Co., and Honeywell International Inc.)
- Focus on expanding AI-enabled defense platforms through strategic collaborations across aerospace, software, and government sectors.
- Invest heavily in autonomous systems, mission intelligence, predictive maintenance, and secure AI research.
- Strong defense portfolios, global government contracts, and advanced AI integration strengthen competitive positioning.
- Extensive aerospace expertise enables secure, mission-critical AI solutions across multi-domain defense operations.
- Dependence on lengthy defense procurement cycles delays the commercialization of next-generation AI capabilities.
- Complex organizational structures reduce agility in the face of emerging AI-focused defense technology competitors.
Emerging Players (Indra Sistemas SA, Iris Automation Inc., SparkCognition Inc.)
- Emerging players focus on developing specialized AI applications for autonomous missions, surveillance, and defense intelligence platforms.
- Invest aggressively in AI innovation through defense partnerships, pilot programs, and technology validation projects.
- Agile development enables the rapid deployment of advanced AI solutions to meet evolving defense requirements.
- Specialized AI expertise supports innovative autonomous systems, analytics, and mission-focused software capabilities.
- Limited financial resources restrict large-scale deployments and participation in long-term defense programs.
- A smaller customer base reduces competitiveness against established defense contractors with global government relationships.
Recent Developments
-
In June 2026, Accenture announced it had entered into agreements to acquire 100% stakes in runZero and NetRise, as well as a majority stake in Dragos, to deliver improved critical infrastructure defense through enhanced capabilities of an exclusive end-to-end platform.
-
In June 2026, Saab AB (publ), a Swedish aerospace and defense organization, announced its latest strategic investment of nearly USD 12.7 million for 10.0% of equity stake in Comand AI. This investment in a parish-based company specialized in battlefield AI technology has brought its AI-native planning solutions and other technical competencies into Saab’s R&D ecosystem.
-
In May 2026, Airbus partnered with the European AI company Mistral AI to further its commitment to deploying trustworthy and ethical AI technology across Airbus operations and processes.
-
In June 2025, Helsing, one of the prominent European defense technology companies, announced it had signed a binding agreement to acquire Grob Aircraft SE, a company focused on developing advanced technologies for aerial warfare.
AI in Aerospace and Defense Market Report Scope
Report Attribute
Details
Market size in 2025
USD 26.8 billion
Estimated market size in 2026
USD 29.3 billion
Projected market size by 2033
USD 57.1 billion
Growth rate
CAGR of 9.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, deployment type, platform, technology, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
Deutsche Telekom AG, General Electric Co., Honeywell International Inc., Indra Sistemas SA, Infosys Ltd., Intel Corporation, International Business Machines Corporation, Iris Automation Inc., Lockheed Martin Corporation, Microsoft Corporation, Northrop Grumman Corporation, NVIDIA Corporation, Raytheon Technologies Corporation, SparkCognition Inc., Thales Group
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global AI in Aerospace and Defense Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global AI in aerospace and defense market report based on offering, deployment type, platform, technology, application, end use, region:
-
Offering Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Processors
-
Memory Devices
-
Network Devices
-
-
Software
-
AI Solutions
-
AI Platforms
-
-
Services
-
Deployment & Integration
-
Support & Maintenance
-
-
-
Deployment Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud-based
-
On-premises
-
-
Platform Outlook (Revenue, USD Billion, 2021 - 2033)
-
Land
-
Naval
-
Airborne
-
Space
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Machine Learning
-
Natural Language Processing (NLP)
-
Computer Vision
-
Context-Aware Computing
-
Robotics
-
Big Data Analytics
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Predictive Maintenance
-
Surveillance & Monitoring
-
Mission Systems
-
Cybersecurity
-
Data Analytics
-
Autonomous Systems
-
Navigation & Guidance Systems
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Commercial
-
Government & Law Enforcement
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The AI in aerospace and defense market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each AI in aerospace and defense segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Offering
Revenue capture definition
Hardware
Revenue is generated through AI-enabled hardware, including processors, sensors, edge computing devices, avionics, radar systems, cameras, and embedded computing platforms used in defense and aerospace operations. This segment is driven by increasing deployment of autonomous platforms, intelligent surveillance systems, and high-performance computing infrastructure.
Software
Revenue is captured by AI software platforms supporting mission planning, predictive analytics, autonomous operations, cybersecurity, computer vision, and data intelligence. This segment is driven by rising demand for real-time decision support, intelligent automation, and advanced battlefield analytics.
Services
Revenue is generated from consulting, system integration, deployment, maintenance, training, and managed AI services for aerospace and defense organizations. This segment is fueled by growing requirements for seamless AI implementation, lifecycle support, and continuous technology optimization.
Segment - Deployment Type
Revenue capture definition
Cloud-based
Revenue is captured through cloud-hosted AI platforms that enable centralized data processing, analytics, simulation, and collaborative mission planning. This segment is driven by increasing adoption of secure cloud infrastructure, scalable computing resources, and remote operational management.
On-premises
Revenue is generated through AI solutions deployed within secure military and aerospace facilities to ensure complete data control and operational security. This segment is driven by stringent cybersecurity requirements, classified mission environments, and regulatory compliance.
Segment - Platform
Revenue capture definition
Land
Revenue is captured through AI applications deployed in armored vehicles, ground combat systems, autonomous robots, and battlefield surveillance platforms. This segment is driven by the increasing modernization of land defense systems and autonomous ground operations.
Naval
Revenue is generated through AI-powered systems supporting naval vessels, submarines, maritime surveillance, autonomous surface vehicles, and underwater operations. This segment is driven by growing investments in maritime security, fleet modernization, and intelligent naval missions.
Airborne
Revenue is captured through AI solutions integrated into military aircraft, helicopters, unmanned aerial vehicles (UAVs), and airborne surveillance platforms. This segment is propelled by increasing demand for autonomous flight, mission intelligence, and predictive aircraft maintenance.
Space
Revenue is generated by AI technologies supporting satellites, space surveillance, orbital operations, and space-based intelligence systems. This segment is driven by rising investments in military space programs, satellite autonomy, and space situational awareness.
Segment - Technology
Revenue capture definition
Machine Learning
Revenue is captured through machine learning algorithms that enable predictive analytics, autonomous decision-making, target recognition, and operational optimization. This segment is driven by increasing demand for intelligent data processing and adaptive defense capabilities.
Natural Language Processing (NLP)
Revenue is generated through AI systems capable of processing voice commands, multilingual communications, intelligence reports, and automated documentation. This segment is driven by growing requirements for efficient information analysis and mission communication.
Computer Vision
Revenue is captured through AI-powered image and video analysis for surveillance, target identification, facial recognition, and object detection. This segment is driven by increasing deployment of intelligent monitoring systems and autonomous reconnaissance platforms.
Context-Aware Computing
Revenue is generated through AI systems that analyze environmental, operational, and mission-specific conditions to support adaptive decision-making. This segment is driven by growing demand for intelligent situational awareness and dynamic mission execution.
Robotics
Revenue is generated by autonomous robotic platforms that perform reconnaissance, logistics, bomb disposal, inspection, and combat support operations. This segment is driven by the increasing adoption of unmanned systems in hazardous and high-risk environments.
Big Data Analytics
Revenue is generated through AI platforms that process massive volumes of operational, sensor, radar, satellite, and intelligence data to generate actionable insights. This segment is fueled by increasing demand for faster intelligence processing and mission planning.
Segment - Application
Revenue capture definition
Predictive Maintenance
Revenue is captured through AI solutions that monitor equipment health, predict component failures, and optimize maintenance schedules for defense assets. This segment is driven by increasing focus on improving asset availability, reducing downtime, and lowering maintenance costs.
Surveillance & Monitoring
Revenue is generated through AI-powered surveillance platforms that support real-time threat detection, border security, intelligence gathering, and infrastructure monitoring. This segment is driven by growing security concerns and demand for continuous situational awareness.
Mission Systems
Revenue is captured through AI-enabled mission planning, battlefield management, command-and-control, and tactical decision support solutions. This segment is driven by the increasing adoption of intelligent mission automation and operational coordination technologies.
Cybersecurity
Revenue is generated through AI-based cybersecurity solutions that detect cyber threats, monitor network activity, and automate incident response across defense systems. This segment is driven by rising cyberwarfare risks and evolving digital security requirements.
Data Analytics
Revenue is captured through AI platforms that analyze operational, intelligence, and mission data to improve planning, forecasting, and strategic decision-making. This segment is propelled by rising demand for data-driven military operations and operational efficiency.
Autonomous Systems
Revenue is generated by AI-enabled autonomous aircraft, vehicles, drones, marine systems, and robotic platforms capable of executing missions independently. This segment is driven by increasing investments in unmanned operations and next-generation defense technologies.
Navigation & Guidance Systems
Revenue is captured through AI-powered navigation, route optimization, target tracking, and precision guidance technologies. This segment is driven by growing demand for accurate navigation, autonomous mobility, and precision military operations.
Others
Revenue is generated through specialized AI applications, including logistics optimization, electronic warfare, training simulations, digital twins, resource planning, and intelligence support. This segment is driven by the expansion of AI adoption across diverse aerospace and defense functions.
Segment - End Use
Revenue capture definition
Commercial
Revenue is captured through AI solutions deployed by commercial aerospace companies for aircraft operations, predictive maintenance, manufacturing automation, air traffic management, and operational analytics. This segment is driven by increasing digital transformation and automation across commercial aviation.
Government & Law Enforcement
Revenue is generated through AI platforms supporting military organizations, border security agencies, intelligence services, public safety departments, and law enforcement authorities. This segment is fueled by rising investments in national security, surveillance, emergency response, and defense modernization initiatives.
Estimation Model
Layer Name
Key Question
Description
AI Defense Adoption Layer
Who are the potential adopters?
Identifies the primary organizations adopting AI technologies, including defense ministries, armed forces, intelligence agencies, aerospace manufacturers, homeland security organizations, border protection authorities, law enforcement agencies, and commercial aerospace companies seeking autonomous operations, surveillance, predictive maintenance, and mission intelligence capabilities.
AI Technology Enablement Layer
Who can deploy AI solutions?
Deployment depends on the availability of secure computing infrastructure, edge AI processors, cloud platforms, advanced sensors, high-performance computing, satellite communications, cybersecurity frameworks, machine learning models, and defense-grade data ecosystems supporting mission-critical AI applications across aerospace and defense operations.
Mission Application Layer
Where are AI solutions actively utilized?
AI is deployed across military aircraft, naval vessels, autonomous ground vehicles, satellites, command centers, border surveillance systems, cybersecurity operations, predictive maintenance facilities, intelligence analysis platforms, logistics networks, mission planning systems, and autonomous defense platforms supporting multi-domain operations.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through AI software platforms, intelligent defense hardware, autonomous systems, predictive maintenance solutions, cybersecurity platforms, mission planning software, system integration services, consulting, cloud-based AI solutions, maintenance contracts, and recurring revenue from software licensing and managed services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Autonomous Defense Systems Deployment & Mission Intelligence Assessment
Conducted detailed evaluation of AI-enabled autonomous aerial, naval, and ground defense platforms, integrating computer vision, sensor fusion, mission planning algorithms, and autonomous navigation technologies to optimize mission execution and operational effectiveness.
Improves mission accuracy, enhances autonomous operations, strengthens situational awareness, and supports faster tactical decision-making.
AI-Enabled Predictive Maintenance & Fleet Readiness Optimization
Assessed implementation of AI-powered predictive maintenance solutions across military aircraft, naval fleets, and ground vehicles, integrating machine learning, digital twins, condition monitoring, and asset performance analytics to improve equipment reliability and maintenance efficiency.
Reduces maintenance costs, improves asset availability, increases operational readiness, and supports lifecycle optimization strategies.
Intelligent Surveillance, Threat Detection & Command Decision Framework
Evaluated deployment of AI-driven surveillance platforms, real-time threat detection systems, intelligent command-and-control solutions, and multi-source intelligence analytics to strengthen battlefield awareness, accelerate response capabilities, and improve operational coordination across defense missions.
Enhances threat detection, improves command efficiency, strengthens intelligence capabilities, and enables real-time operational coordination.
Frequently Asked Questions About This Report
The global AI in aerospace and defense market size was valued at USD 26.9 billion in 2025 and is estimated at USD 29.6 billion for 2026
The global AI in aerospace and defense market is expected to grow at a CAGR of 9.9% from 2026 to 2033, reaching USD 57.1 billion by 2033.
North America dominated with a 41.4% revenue share in 2025.
Key players in the market include Deutsche Telekom AG, General Electric Company, Honeywell International Inc., Indra, Infosys Limited, Intel Corporation, International Business Machines Corporation, Iris Automation Inc., Lockheed Martin Corporation, Microsoft, Northrop Grumman, NVIDIA Corporation, RTX, Avathon, Inc., Thales, and others.
Key factors that are driving AI in aerospace & defense market growth include increased demand for AI-driven systems to analyze data from various sources to optimize maintenance schedules, manage supply chains, and improve logistics coupled with increased government investments and defense budgets.
Asia Pacific is the fastest-growing region over the forecast period.
The hardware segment dominated with a 42.6% revenue share in 2025 while software segment is expected to be the fastest-growing market.
The on-premises segment dominated the market with a share of 55.5% in 2025.The market is growing due to the need for secure, controlled environments in which sensitive data and applications can be managed with high confidentiality.
The government & law enforcement segment accounted for the largest share, with 52.0% of revenue in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


