
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Heat Shield Market Size Report, 2026-2033GVR Report cover

Automotive Heat Shield Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Single Shell, Double Shell), By Application (Exhaust System, Turbocharger, Engine Compartment), By Material, By Vehicle Type, By Region, And Segment Forecasts
Market Size, 2025
$13.8BMarket Estimate, 2026
$14.5BMarket Forecast, 2033
$20.4BCAGR, 2026–2033
5.7%Automotive Heat Shield Market Summary
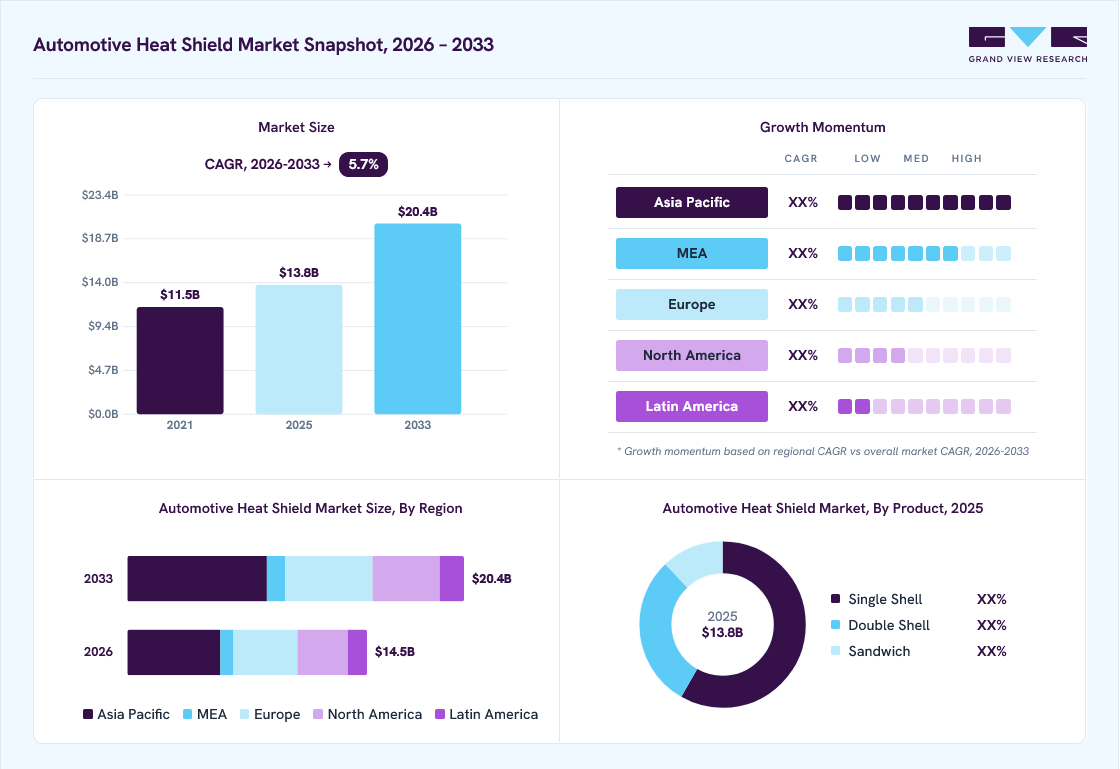
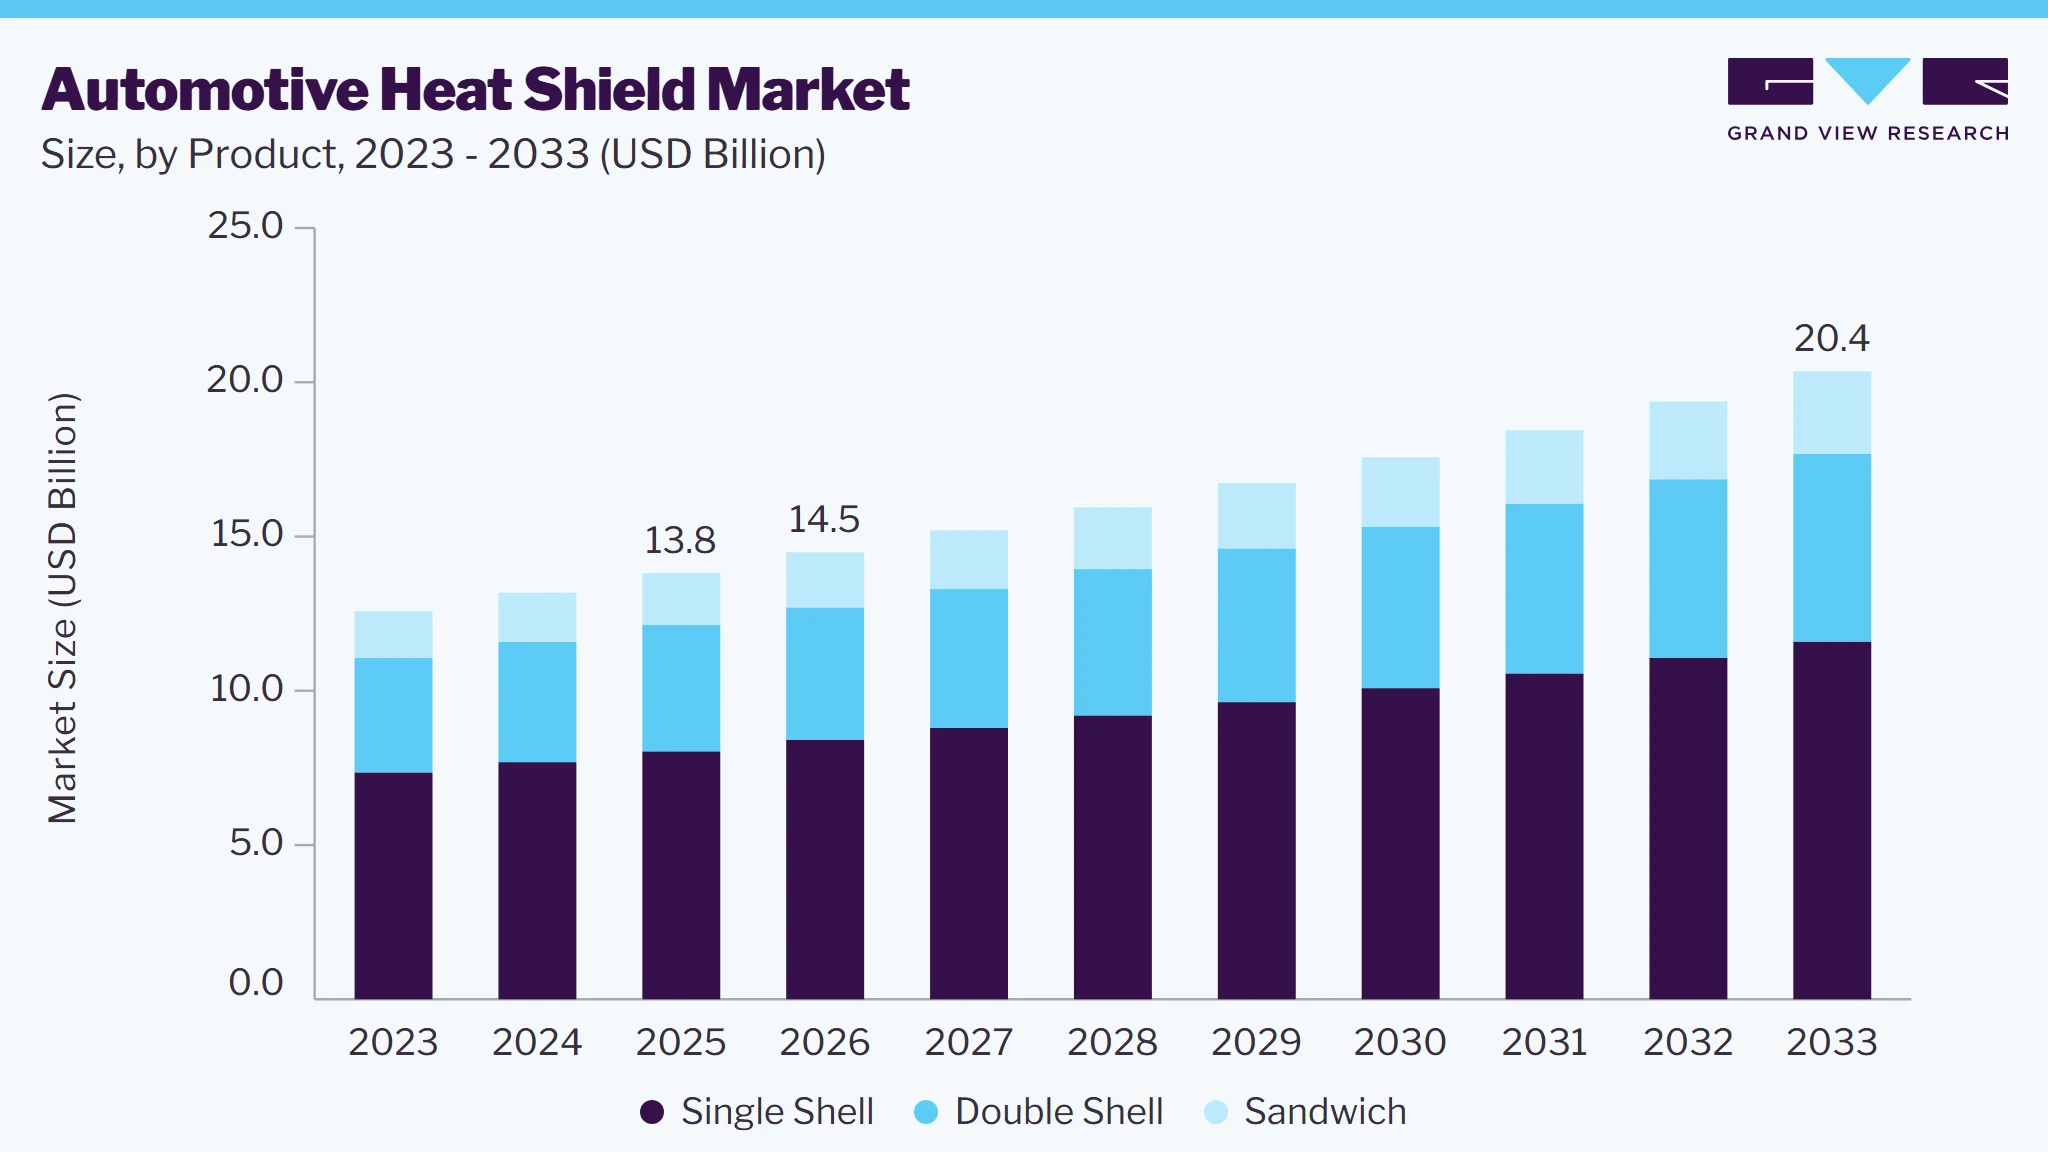
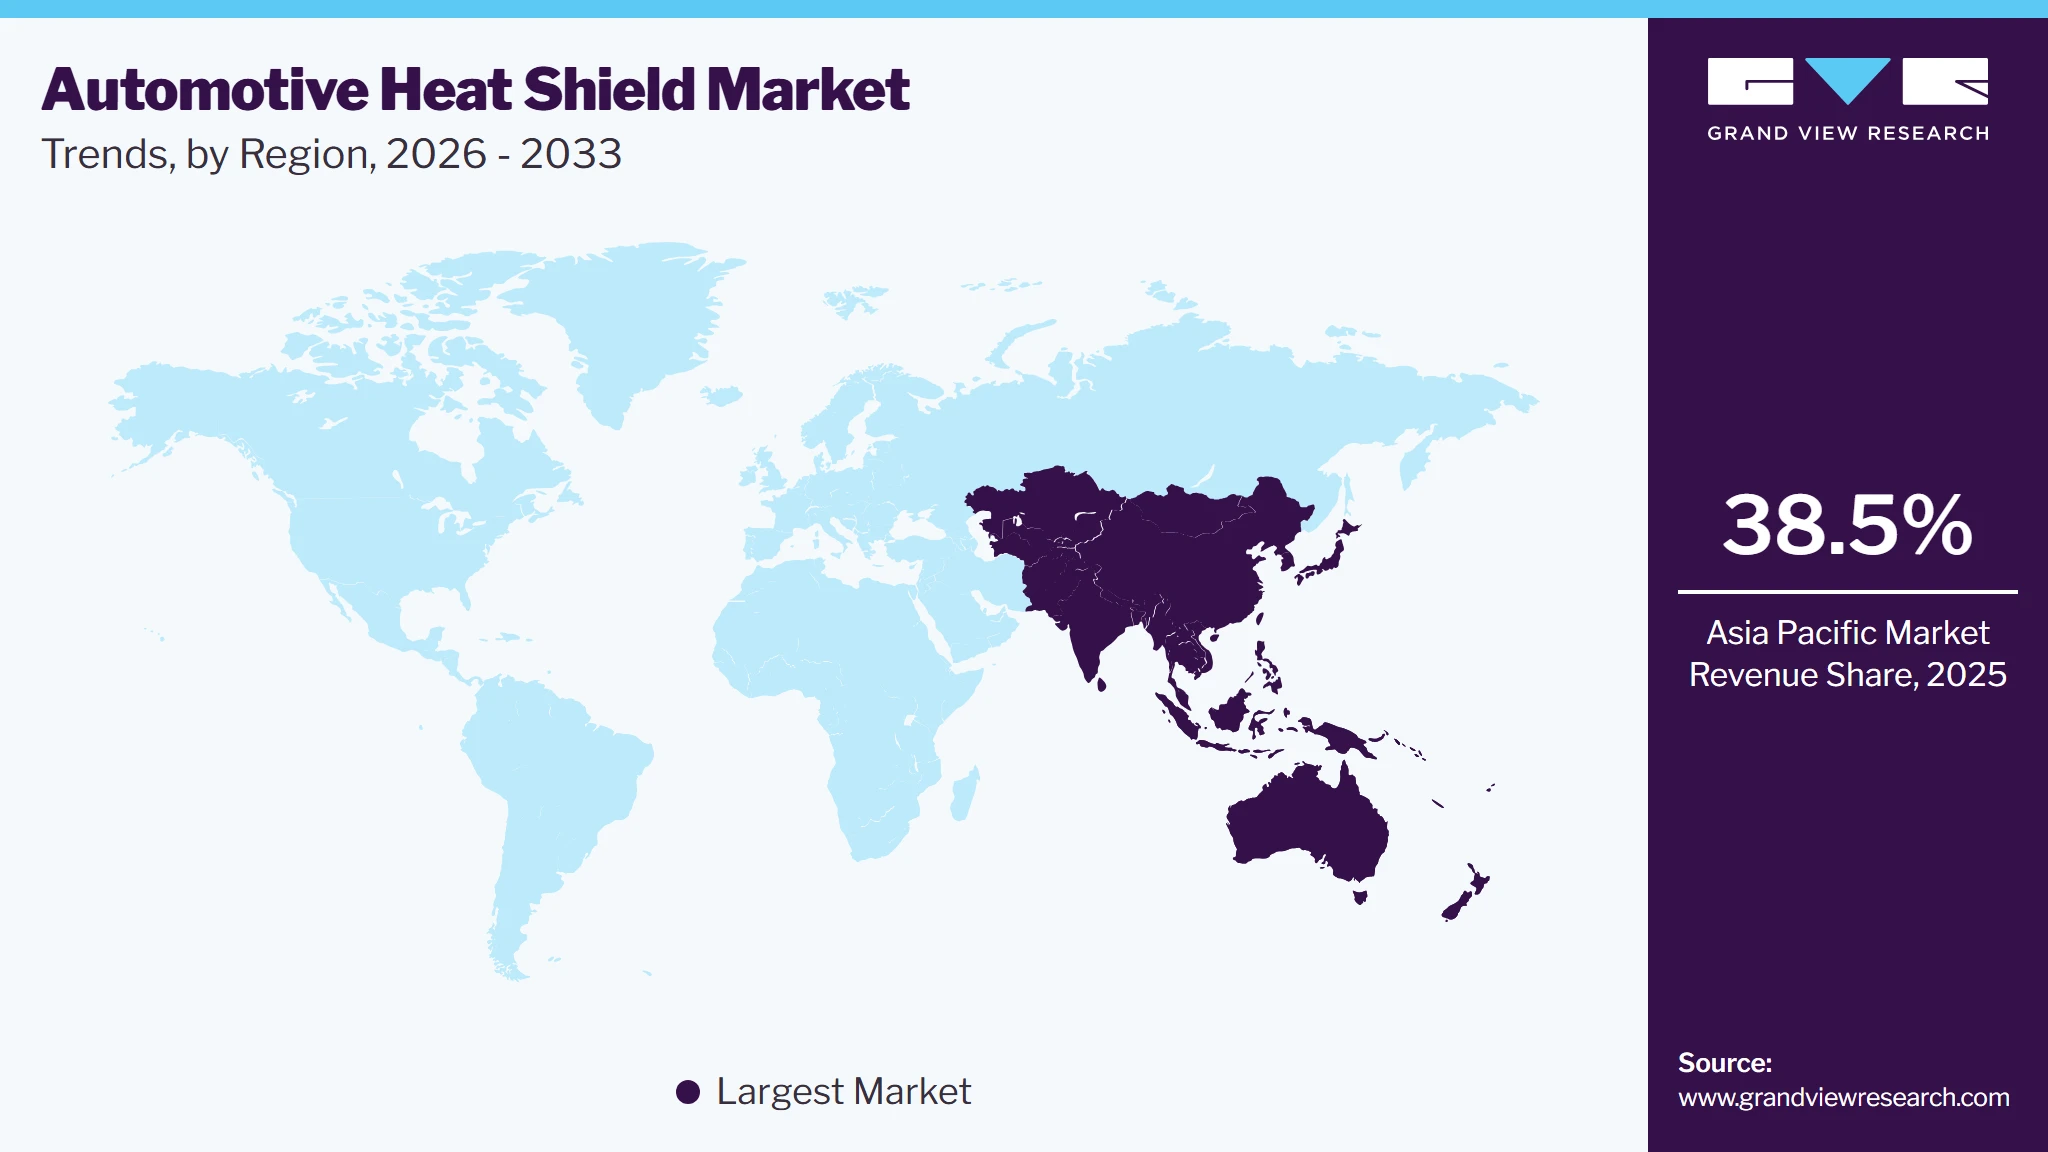
The global automotive heat shield market size was valued at USD 13.8 billion in 2025 and is projected to grow from USD 14.5 billion in 2026 to USD 20.4 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 38.5% in 2025. The market is experiencing notable growth, driven by a combination of regulatory, technological, and demand-driven factors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Single shell segment dominated the market, with a revenue share of 58.2% in 2025.
- By application: Engine compartment segment held the largest market share of 30.9% in 2025.
- By material: Metallic segment held the largest revenue share of 85.2% in 2025.
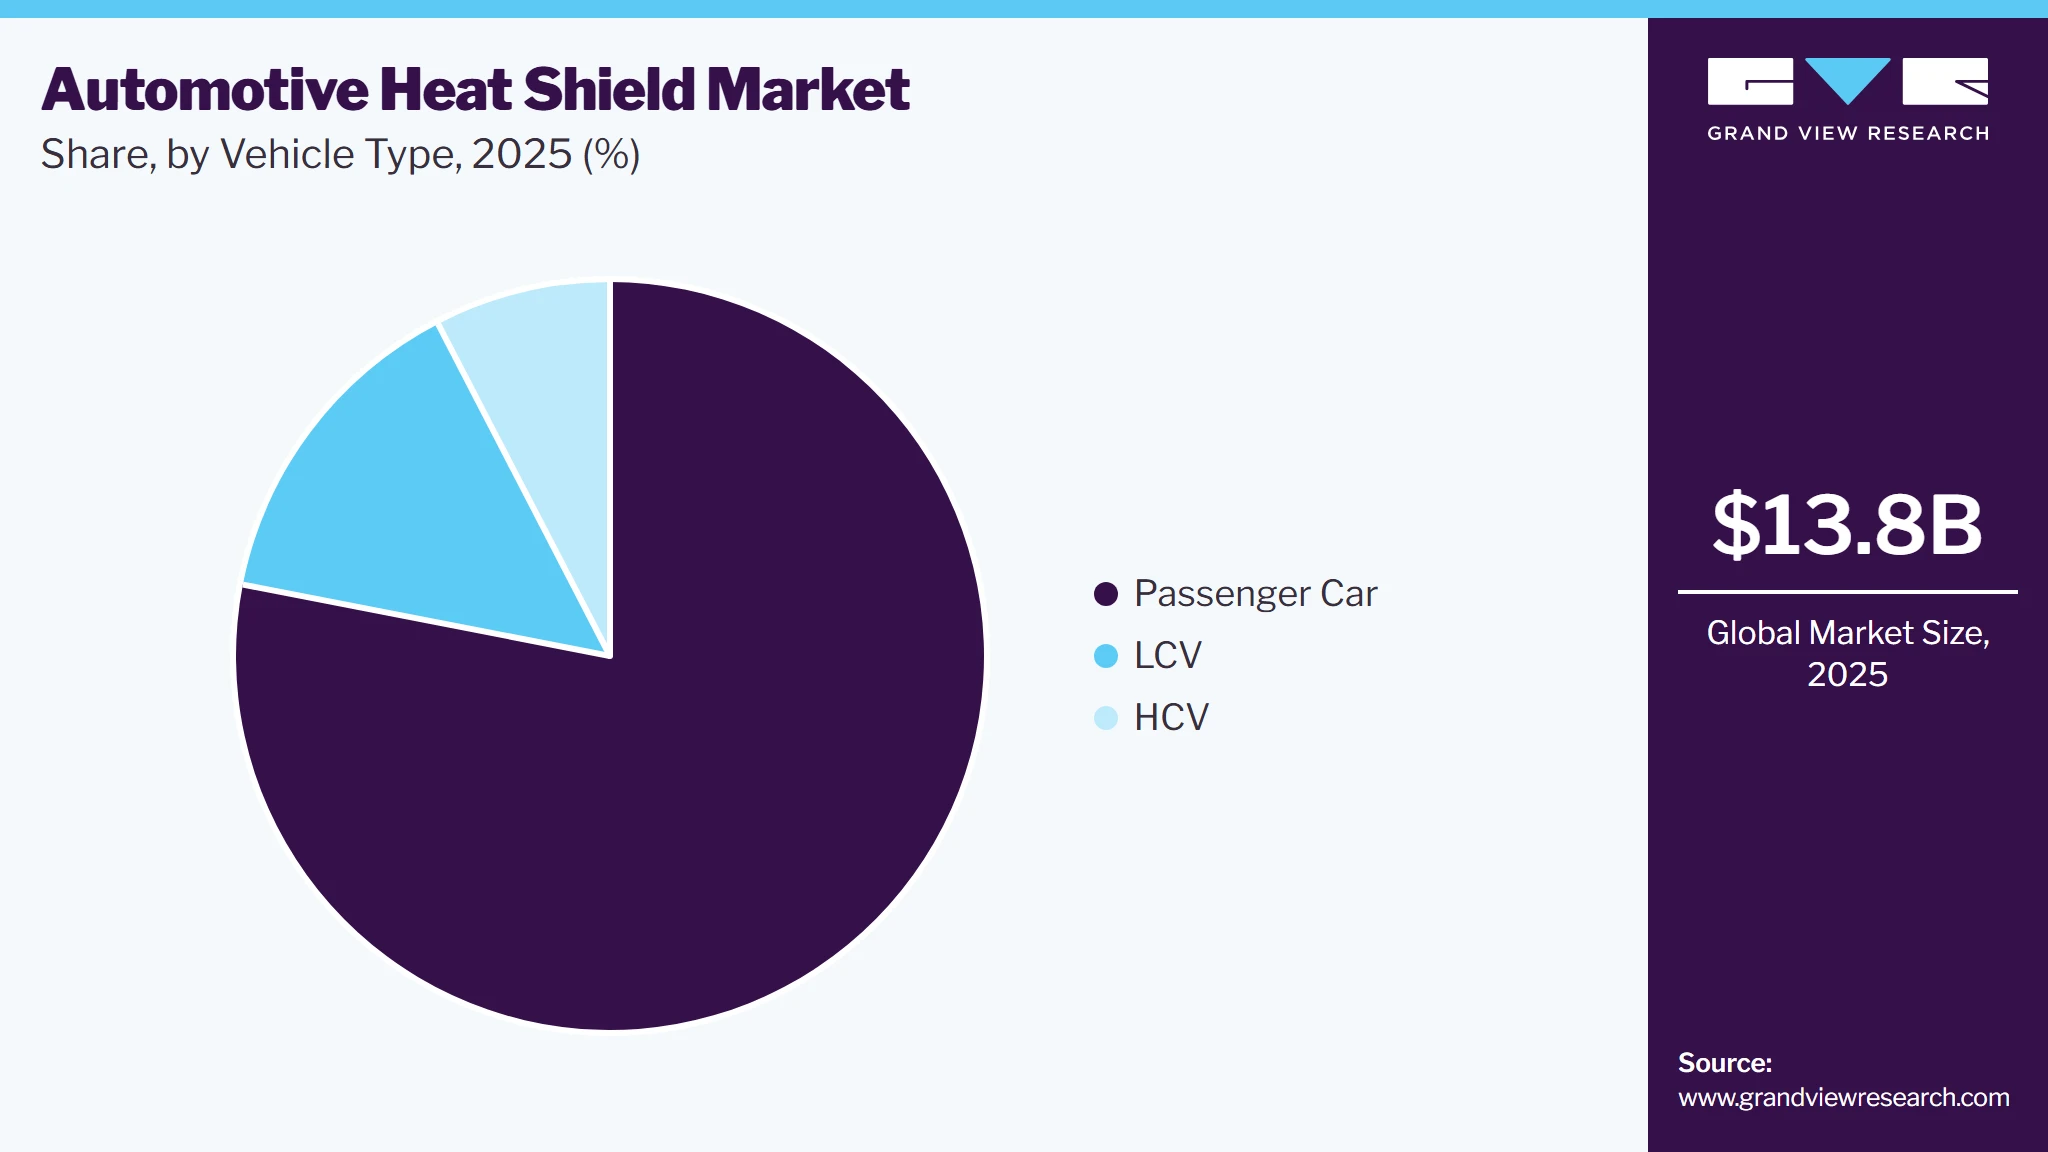
- By vehicle type: Passenger car segment accounted for the largest revenue share of 78.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.5% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 13.8 Billion
- Estimated market size in 2026: USD 14.5 Billion
- Projected market size by 2033: USD 20.4 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A major driver is the increasing implementation of stringent emission standards across many regions, particularly Europe, North America, and Asia. These regulations aim to reduce the environmental impact of vehicles by controlling emissions and improving fuel efficiency. Heat shields play a critical role in enabling vehicles to meet these standards by insulating engine components and exhaust systems, which helps reduce heat build-up, improves fuel efficiency, and minimizes harmful emissions.Another significant driver is the rising demand for electric and hybrid vehicles. As the automotive industry shifts toward electrification, the need for advanced heat management solutions becomes more pressing. Electric vehicle (EV) components, such as batteries, electric motors, and power electronics, generate considerable heat during operation. Effective thermal management is essential to ensure these components' safety, efficiency, and longevity. Consequently, heat shields designed specifically for EV applications are in higher demand, pushing manufacturers to innovate and develop specialized solutions for this rapidly growing segment.
 To learn more about this report, Download Free Sample Report
Moreover, advancements in lightweight materials and heat-resistant composites further propel the market. Automotive manufacturers increasingly focus on reducing vehicle weight to enhance fuel efficiency and performance. Modern heat shield materials, such as aluminum and composites, offer the necessary thermal resistance while being lightweight, helping manufacturers meet fuel economy standards without compromising on vehicle safety or performance. This trend is particularly prominent in the high-performance and luxury vehicle segments, where heat management is crucial for optimizing engine output and overall vehicle performance.
Market Dynamics
The automotive heat shield market is shaped by evolving vehicle design requirements, stricter emission regulations, and the growing need for advanced thermal management across passenger and commercial vehicles. Automakers are integrating lightweight metallic and composite heat shield materials to improve fuel efficiency while protecting critical powertrains, exhaust, battery, and electronic components from excessive heat. The expansion of hybrid and battery electric vehicles is broadening application areas, as effective thermal insulation plays an important role in maintaining battery performance, passenger comfort, and component durability. Continuous advancements in material engineering, including multilayer structures and high-temperature insulation solutions, are enabling manufacturers to meet demanding performance standards without adding significant vehicle weight. At the same time, fluctuations in raw material costs and increasing pressure to optimize manufacturing expenses present challenges for suppliers.
Stringent emission regulations and fuel efficiency targets across global automotive markets are increasing the demand for effective thermal management solutions. Automotive heat shields help reduce heat transfer from exhaust systems, turbochargers, engines, and other high-temperature components, protecting surrounding parts while improving overall vehicle performance and durability. The growing adoption of downsized turbocharged engines, hybrid powertrains, and battery electric vehicles has further expanded the need for advanced heat shielding solutions capable of managing higher operating temperatures and safeguarding sensitive electronic and battery systems.
Fluctuations in the prices of aluminum, stainless steel, and advanced insulating materials create cost uncertainties for heat shield manufacturers. In addition, modern vehicle architecture requires compact, lightweight, and customized heat shield designs that fit increasingly complex engine compartments and electrified powertrains. These design and manufacturing requirements increase engineering effort, tooling costs, and production complexity, particularly for suppliers serving multiple vehicle platforms with varying thermal management specifications.
The growing production of electric and hybrid vehicles presents significant opportunities for automotive heat shield manufacturers. Thermal protection is becoming increasingly important for battery packs, power electronics, electric motors, and charging systems to maintain operational efficiency and component reliability. At the same time, advancements in lightweight composites, multilayer insulation materials, and high-performance thermal barriers are enabling the development of heat shields that reduce vehicle weight while delivering superior heat resistance.
Analyst Perspective
The automotive heat shield market is growing steadily as vehicle manufacturers place greater emphasis on thermal management, fuel efficiency, passenger safety, and component durability. Increasing integration of turbocharged engines, stricter vehicle emission standards, and the need to protect temperature-sensitive components are driving demand for advanced heat shielding solutions across conventional, hybrid, and electric vehicles. In electric vehicles, heat shields play an important role in managing thermal loads around battery packs, power electronics, and electric drivetrains, supporting system reliability and operational safety. Manufacturers are focusing on lightweight materials such as aluminum, stainless steel, and advanced composites to reduce vehicle weight while maintaining high thermal insulation performance and corrosion resistance. As automotive production continues to evolve toward electrification and higher-performance powertrains, suppliers offering innovative, lightweight, and application-specific heat shield solutions are expected to benefit from sustained long-term market growth.
Material Insights
Based on material, the metallic segment led the market with the largest revenue share of 85.2% in 2025. This segment is driven by its superior heat resistance and durability compared to non-metallic alternatives. Metallic heat shields, often made from aluminum or steel, offer exceptional thermal conductivity and can withstand high-temperature environments commonly found in automotive engines and exhaust systems. This robustness ensures longer product life, reducing the need for frequent replacements, which appeals to manufacturers focused on reducing maintenance costs and improving vehicle longevity.
The non-metallic segment is expected to grow at the fastest CAGR of 5.4% over the forecast period. This segment of the market is experiencing significant growth, driven by increasing demand for lightweight materials in vehicle manufacturing. Automotive manufacturers aim to improve fuel efficiency and reduce emissions.
Application Insights
Based on application, the engine compartment segment led the market with the largest revenue share of 30.9% in 2025. This segment is driven by the increasing demand for improved vehicle performance and enhanced thermal management systems. As automotive manufacturers strive to deliver higher engine efficiency and power output, engines tend to generate more heat, necessitating efficient heat shields to protect sensitive components and improve engine performance.
Turbocharger is expected to grow at the fastest CAGR of 6.1% over the forecast period. Turbochargers play a crucial role in improving engine efficiency by compressing air, allowing smaller engines to produce more power. This process, however, generates intense heat, making heat shields essential for protecting nearby components from thermal damage and ensuring optimal performance. As more automakers incorporate turbochargers into a broader range of vehicle models, the need for reliable and effective heat shields continues to grow.
Vehicle Type Insights
Based on vehicle type, the passenger car segment led the market with the largest revenue share of 78.1% in 2025, driven by the growing consumer demand for enhanced vehicle comfort and cabin temperature control. Heat shields help protect the cabin from engine and exhaust heat, contributing to a more comfortable driving experience. With consumers prioritizing comfort and safety in their vehicle choices, automakers are integrating more robust thermal insulation measures. Advanced heat shielding technology, capable of isolating heat in high temperature zones, meets these requirements, driving the adoption of heat shields in passenger cars across both premium and economy models.
 To learn more about this report, Download Free Sample Report
HCV is expected to grow significantly at a CAGR of 4.7% over the forecast period. The Heavy Commercial Vehicles (HCV) segment in the market is witnessing growth driven by increasing regulatory pressure for emissions reduction and advancements in engine technology. As regulatory bodies worldwide continue to impose stringent standards to limit exhaust emissions, there is a rising demand for heat shields that effectively manage engine and exhaust system temperatures in HCVs.
Product Insights
Based on product, the single shell segment led the market with the largest revenue share of 58.2% in 2025. The single shell segment in the market is driven by factors such as its cost-effectiveness and straightforward design, making it an attractive option for vehicle manufacturers. This segment offers sufficient thermal protection for various automotive components, especially in situations where moderate heat insulation is required. The rising demand for lightweight materials to improve fuel efficiency also boosts the popularity of single-shell heat shields, as they are typically lighter than multi-layer alternatives. In addition, single-shell heat shields are easier to install and require minimal maintenance, appealing to automakers focused on reducing production costs and improving assembly line efficiency.
The sandwich segment is expected to grow at the fastest CAGR of 5.9% over the forecast period. The driving force behind the adoption of sandwich heat shields is their enhanced durability and performance under extreme conditions. These heat shields are designed to withstand high temperatures and harsh environments, ensuring prolonged protection for critical components such as exhaust systems, turbochargers, and engine parts.
Regional Insights
Asia Pacific dominated the automotive heat shield market with the largest revenue share of 38.5% in 2025. The automotive heat shield market in Asia Pacific is witnessing significant growth, driven by the rapid expansion of the automotive industry in countries like China, India, and Japan, fueling demand. With increased production and sales of passenger and commercial vehicles, the need for high-performance, reliable heat shields is growing to protect vehicle components from the intense heat generated by engines and exhaust systems. This is especially relevant as Asia-Pacific automakers focus on producing vehicles with higher fuel efficiency and performance, making effective heat management crucial.
 To learn more about this report, Download Free Sample Report
China Automotive Heat Shield Market Trends
The automotive heat shield market in China held the largest share in the Asia Pacific region in 2025. The automotive heat shield market in China is the world's largest, with substantial domestic and export vehicle production growth. As vehicle manufacturing continues to rise, there is a growing need for automotive heat shields to protect components from excessive heat generated by engines and exhaust systems. The expansion of electric vehicles (EVs) and hybrid vehicles in China further contributes to the demand for heat shields, as these vehicles also require thermal management solutions.
Central & South America Automotive Heat Shield Market Trends
The automotive heat shield market in CSA is expected to grow significantly over the forecast period. With the growing focus on reducing emissions and improving fuel efficiency, there is an increasing demand for heat shields that help optimize vehicle performance. Heat shields control exhaust heat, contributing to improving engine efficiency and reducing the vehicle's carbon footprint. Furthermore, the growing implementation of stringent emission regulations and fuel economy standards in countries such as Brazil is driving the adoption of these components in vehicles to meet compliance.
North America Automotive Heat Shield Market Trends
The automotive heat shield market in North America is growing due to the increase in electric and hybrid vehicle production. As these vehicles often operate at higher temperatures due to high-powered batteries and advanced electric drivetrains, heat shields are increasingly used to protect these critical components. The push towards electrification in the automotive sector, driven by both consumer demand and governmental policies, directly impacts the demand for heat shields that can withstand higher levels of heat generated in EVs and hybrid vehicles.
The U.S. automotive heat shield market has stringent government regulations to reduce vehicle emissions and enhance safety. The Environmental Protection Agency (EPA) and the National Highway Traffic Safety Administration (NHTSA) enforce regulations that require automakers to reduce vehicle environmental impact. Heat shields are crucial in protecting sensitive components from high temperatures and emissions. This has increased demand for advanced vehicle heat shield solutions to comply with these regulations.
Europe Automotive Heat Shield Market Trends
The automotive heat shield market in Europe is growing due to the demand for lightweight materials, and more advanced design capabilities in the automotive sector drive innovation in heat shield technologies. Heat shields must withstand high temperatures and contribute to vehicle weight reduction, a key factor for improving fuel economy. The use of lightweight materials such as aluminum, advanced composites, and ceramic coatings in manufacturing heat shields is gaining traction. These innovations are especially critical as electric vehicles (EVs) and hybrid vehicles, which require enhanced thermal management, become more popular in Europe.
Key Automotive Heat Shield Company Insights
Some key players operating in the market include DuPont, Dana Incorporated, and Others.
-
DuPont is a global company in advanced materials and chemicals, offering a range of solutions for the market. The company provides high-performance materials designed to withstand extreme temperatures, including its proprietary offerings like Kevlar and Nomex, used in automotive heat shielding applications to protect critical components from heat damage. DuPont’s heat-resistant solutions help enhance vehicle durability and safety by reducing heat transfer in areas such as exhaust systems, engine compartments, and underbody components.
-
Dana Incorporated offers a wide range of products, including advanced heat shields designed to protect critical components from excessive heat. Dana's product offerings include solutions for exhaust systems, underbody protection, and engine compartments, all engineered to enhance vehicle performance, fuel efficiency, and safety.
Key Automotive Heat Shield Companies
The following key companies have been profiled for this study on the automotive heat shield market.
-
DuPont
-
Dana Limited.
-
Zircotec Ltd
-
Morgan Advanced Materials
-
Autoneum
-
ElringKlinger AG
-
Lydall, Inc.
-
Tenneco Inc.
-
CARCOUSTICS
-
UGN Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Autoneum Holding AG, ElringKlinger AG, Tenneco Inc., UGN Inc., CARCOUSTICS International GmbH, Dana Incorporated)
- Focus on long-term supply agreements with global automotive OEMs while expanding production of metallic and lightweight automotive heat shields.
- Invest in advanced heat shield materials, manufacturing technologies, and product development for ICE, hybrid, and electric vehicles.
- Extensive automotive heat shield manufacturing capabilities and long-standing OEM relationships.
- Strong engineering expertise in lightweight, high-temperature shielding solutions supported by global manufacturing facilities.
- High dependence on automotive production volumes and OEM sourcing cycles.
- Significant investments required for material innovation, manufacturing expansion, and compliance with evolving emission and vehicle performance standards.
Emerging & Regional Players (e.g., Autoneum Holding AG, ElringKlinger AG, Tenneco Inc., UGN Inc., CARCOUSTICS International GmbH, Dana Incorporated)
- Focus on long-term supply agreements with global automotive OEMs while expanding production of metallic and lightweight automotive heat shields.
- Invest in advanced heat shield materials, manufacturing technologies, and product development for ICE, hybrid, and electric vehicles.
- Greater flexibility in developing customized automotive heat shield products for specific vehicle platforms.
- Strong expertise in specialized heat shielding materials and rapid product development for regional automotive markets.
- Limited manufacturing capacity and global market reach compared with established Tier-1 suppliers.
- Greater reliance on regional OEM contracts and comparatively lower investment capacity for large-scale expansion.
Recent Development
-
In April 2023, Autoneum completed the acquisition of Borgers Automotive. This development has led to Autoneum's operational scope now encompassing 67 production facilities across the globe, with a workforce of approximately 16,100 individuals spanning 24 different countries. By integrating the well-established German company into its operations, Autoneum has taken another significant step in fortifying its position as a worldwide leader in sustainable solutions for vehicle acoustic and thermal management
Automotive Heat Shield Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.8 billion
Estimated market size in 2026
USD 14.5 billion
Projected market size by 2033
USD 20.4 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, material, vehicle type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Spain; China; India; Japan; Brazil; Saudi Arabia
Key companies profiled
Autoneum Holding AG; ElringKlinger AG; Tenneco Inc.; UGN Inc.; CARCOUSTICS International GmbH; Zircotec Ltd; Dana Incorporated; Progress-Werk Oberkirch AG (PWO); Nippon Tokushu Toryo Co., Ltd. (Nittoku); Haberkorn GmbH.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Heat Shield Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive heat shield market based on product, material, application, vehicle type, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Single Shell
-
Double Shell
-
Sandwich
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Exhaust System
-
Turbocharger
-
Under Bonnet
-
Engine Compartment
-
Under Chassis
-
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Metallic
-
Non-metallic
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Car
-
Light Commercial Vehicle (LCV)
-
Heavy Commercial Vehicle (HCV)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The automotive heat shield market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive heat shield segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Single Shell
The segment captures revenue generated from the sale of single-shell automotive heat shields manufactured using metallic or composite materials. Revenue includes products supplied to OEMs and the aftermarket for thermal protection across vehicle platforms.
Double Shell
The segment captures revenue generated from the sale of double-shell automotive heat shields featuring dual-layer construction for enhanced thermal insulation. Revenue includes products supplied to OEMs and aftermarket customers.
Sandwich
The segment captures revenue generated from the sale of sandwich-type automotive heat shields incorporating multiple layers of metallic and insulating materials. Revenue includes products designed for advanced thermal management requirements.
Segment - Application
Revenue Capture Definition
Exhaust System
The segment captures revenue generated from the sale of automotive heat shields designed for exhaust system components. Revenue includes shielding products supplied for exhaust pipes, catalytic converters, mufflers, and related assemblies.
Turbocharger
The segment captures revenue generated from the sale of automotive heat shields engineered for turbocharger systems. Revenue includes products that provide thermal insulation for high-temperature turbocharger assemblies.
Under Bonnet
The segment captures revenue generated from the sale of automotive heat shields designed for under-bonnet thermal protection. Revenue includes products supplied to shield components located beneath the vehicle hood.
Engine Compartment
The segment captures revenue generated from the sale of automotive heat shields designed for engine compartment thermal management. Revenue includes products supplied to protect surrounding vehicle components from engine heat.
Under Chassis
The segment captures revenue generated from the sale of automotive heat shields designed for under-chassis installations. Revenue includes products supplied to provide thermal insulation for vehicle floor and underbody structures.
Segment - Material
Revenue Capture Definition
Metallic
The segment captures revenue generated from the sale of metallic automotive heat shields manufactured using aluminum, stainless steel, and other heat-resistant alloys. Revenue includes products supplied across passenger and commercial vehicle platforms.
Non-metallic
The segment captures revenue generated from the sale of non-metallic automotive heat shields manufactured using advanced insulation materials, fibers, and composites. Revenue includes lightweight thermal shielding products supplied to vehicle manufacturers.
Segment - Vehicle Type
Revenue Capture Definition
Passenger Car
The segment captures revenue generated from the sale of automotive heat shields supplied for passenger cars. Revenue includes thermal shielding products sold for internal combustion, hybrid, and battery electric passenger vehicles.
Light Commercial Vehicle (LCV)
The segment captures revenue generated from the sale of automotive heat shields supplied for light commercial vehicles. Revenue includes products designed for vans, pickups, and other light-duty commercial vehicle platforms.
Heavy Commercial Vehicle (HCV)
The segment captures revenue generated from the sale of automotive heat shields supplied for heavy commercial vehicles. Revenue includes products designed for trucks, buses, and other heavy-duty vehicle platforms requiring high-temperature protection.
Estimation Model
Layer Name
Key Question
Description
Vehicle Production & Thermal Management Demand Layer
Where are automotive heat shields required?
Analyze demand across passenger cars, light commercial vehicles, heavy commercial vehicles, and off-highway vehicles. Assess vehicle production volumes, engine configurations, exhaust system architecture, turbocharger adoption, battery thermal management requirements, and emission control systems to establish the addressable demand for automotive heat shields.
Automotive Manufacturing & Regulatory Compliance Layer
Where is new product demand being created?
Evaluate vehicle production trends, investments in automotive manufacturing, electrification, and tightening fuel efficiency and emission regulations. Assess OEM production capacity, platform launches, hybrid and electric vehicle production, and replacement of conventional thermal insulation materials that drive procurement of new automotive heat shields.
Product Adoption Layer
Which automotive heat shield technologies are being deployed?
Segment demand by product type, material, vehicle type, application, and sales channel. Apply adoption rates based on operating temperature, weight reduction requirements, thermal insulation performance, corrosion resistance, noise reduction, and durability.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of automotive heat shields by product type, vehicle type, application, and region. Quantify revenues generated exclusively from the sale of new automotive heat shields supplied to OEMs and the aftermarket.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
A competitive benchmarking analysis was conducted by evaluating established automotive heat shield manufacturers based on product portfolio, thermal management technologies, material expertise, manufacturing footprint, OEM partnerships, strategic initiatives, financial strength, and competitive positioning within the automotive heat shield market.
This benchmarking enabled stakeholders to evaluate competitive capabilities, identify product and technology differentiation opportunities, understand evolving supplier strategies, and develop informed market positioning and growth plans across the automotive heat shield value chain.
Regional Segmentation
A comprehensive regional analysis was provided across key markets, highlighting vehicle production trends, automotive manufacturing ecosystems, emission regulations, adoption of lightweight thermal management solutions, and regional demand for automotive heat shields. The assessment also evaluated the contribution of major countries to regional market performance.
The regional insights helped stakeholders identify high-growth markets, optimize regional expansion strategies, strengthen OEM engagement, allocate investments efficiently, and align product offerings with region-specific regulatory requirements and automotive manufacturing trends.
Opportunity Assessment
A detailed opportunity assessment was conducted by evaluating advancements in lightweight materials, thermal insulation technologies, electric and hybrid vehicle production, evolving emission standards, and increasing demand for advanced thermal management systems. The analysis identified high-growth opportunities across battery thermal protection, exhaust system insulation, turbocharger heat shielding, and next-generation vehicle platforms to support strategic decision-making.
This assessment enabled stakeholders to prioritize high-growth investment areas, strengthen product innovation strategies, expand their presence in electric and hybrid vehicle applications, and capitalize on emerging opportunities driven by advanced thermal management requirements and evolving automotive technologies.
Frequently Asked Questions About This Report
Asia Pacific dominated the automotive heat shield market with the largest revenue share of 38.5% in 2025.
The global automotive heat shield market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 20.4 billion by 2033.
Metallic segment held the largest revenue share of 85.2% in 2025.
Some of the key players operating in the automotive heat shield market include DuPont, Dana Incorporated, Zircotec, Morgan Advanced Materials, Autoneum, ElringKlinger AG, Lydall Inc., Tenneco Inc., Carcoustics, and UGN Inc.
Key factors that are driving the automotive heat shield market are rising product utilization in the production of electric vehicles, lightweight and fuel-efficient passenger cars, and commercial vehicles.
The global automotive heat shield market size was valued at USD 13.8 billion in 2025 and is estimated at USD 14.5 billion in 2026.
Based on product, the single shell segment led the market with the largest revenue share of 58.2% in 2025 while sandwich segment is expected to be the fastest-growing market.
Engine compartment segment dominated the market with the largest revenue share of 30.9% in 2025 and turbocharger segment is second fastest growing market
Based on vehicle type, the passenger car segment led the market with the largest revenue share of 78.1% in 2025, driven by the growing consumer demand for enhanced vehicle comfort and cabin temperature control.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


